
- Home
- »
- Advanced Interior Materials
- »
-
Battery Anode Materials Market Size Report, 2026-2033GVR Report cover

Battery Anode Materials Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Lithium, Silicon, Graphite), By Application (Consumer Electronics, Automotive, Industrial, Telecommunication), By Region, And Segment Forecasts
Market Size, 2025
$7.4BMarket Estimate, 2026
$8.0BMarket Forecast, 2033
$14.3BCAGR, 2026–2033
7.6%Battery Anode Materials Market Summary
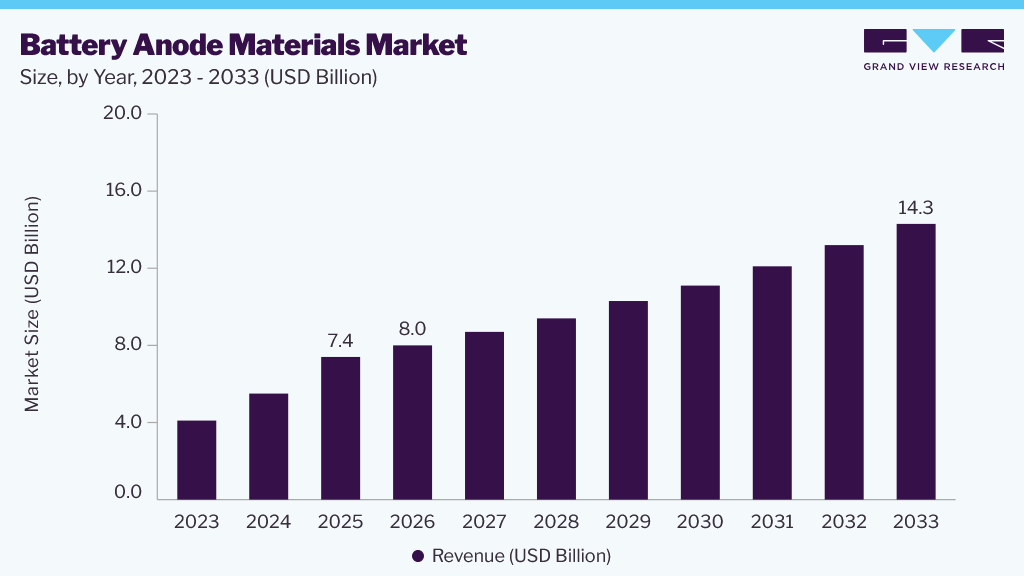
The global battery anode materialsmarket size was valued at USD 7.4 billion in 2025 and is projected to grow from USD 8.0 billion in 2026 to USD 14.3 billion in 2033, at a CAGR of 7.6% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 35.5% in 2025. The surge in electric vehicles (EVs) and the need for modern energy storage solutions have amplified the demand for high-performance batteries.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: The graphite segment held the largest market share of around 81.0% in 2025.
- By application: The consumer electronics segment held the largest market share of around 41.0% in 2025.
Regional Highlights
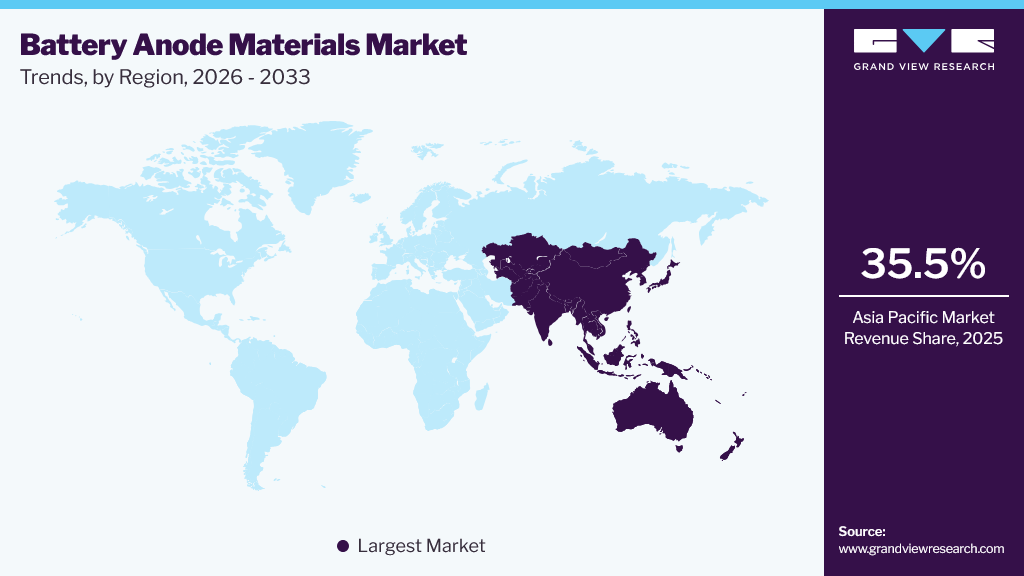
- Largest regional market: Asia Pacific (35.5% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 7.4 Billion
- Estimated market size in 2026: USD 8.0 Billion
- Projected market size by 2033: USD 14.3 Billion
- CAGR (2026-2033): 7.6%
Prism AI by Grand View Research Free to tryAsk a question about the battery anode materials marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Lithium-ion batteries dominate the EV market and rely on anode materials such as graphite, silicon, and other carbon-based materials to store and release energy efficiently. Hence, with the growing electric vehicles market, the demand for battery anode materials is also expected to grow rapidly.The growing inclination towards renewable energy sources, such as solar and wind, necessitates efficient energy storage solutions to address intermittency. Battery storage systems are crucial for storing excess energy generated during peak production periods and supplying it during low production or high-demand periods, thereby stabilizing the grid. This requires a significant increase in the production of battery materials, including anode materials.
Furthermore, advancements in technology and materials science are driving the development of next-generation batteries with higher energy densities, faster charging, and longer lifespans. These advancements often depend on novel anode materials that can store more energy per unit volume or weight, such as silicon-based or lithium-metal anodes.
With depleting reserves of fossil fuels and their increasing prices, the demand for electric vehicles has gone up. These vehicles are almost soundless and offer higher fuel efficiency than vehicles running on fossil fuels. The growing market for electric vehicles (EVs) is a significant driver behind the increasing demand for battery anode materials. As the automotive industry undergoes a monumental shift towards electrification to reduce greenhouse gas emissions and combat climate change, demand for high-performance batteries that power EVs efficiently and reliably is rising.
Moreover, the rise of portable electronic devices such as smartphones, tablets, and laptops, along with the growing Internet of Things (IoT) market and increasing adoption of electric vehicles, has led to rising demand for batteries with higher energy densities and longer cycle lives. As a result, manufacturers are continuously seeking improvements in anode materials to meet evolving performance requirements across consumer electronics and EV applications. For instance, in November 2025, Umicore announced a strategic partnership with HS Hyosung Advanced Materials to accelerate the industrialization and commercialization of silicon-carbon composite anode materials for EV lithium-ion batteries. This joint venture is expected to scale Umicore's silicon anode technology to an industrial demonstration plant by the end of 2026, thereby supporting the growing demand for higher-energy-density EV batteries.
Analyst Perspective
The global battery anode materials market is poised for steady growth, driven by the rapid adoption of electric vehicles (EVs), the increasing deployment of renewable energy storage systems, and the rising demand for consumer electronics that require high-performance rechargeable batteries. Graphite currently dominates the market due to its established commercial viability and widespread use in lithium-ion batteries. However, growing demand for higher energy density, faster charging, and longethe expansion of battery manufacturingthe development of next-generation anode materials. Technological advancements in silicon-based, lithium-metal, and hard carbon anode materials are supporting market growth by improving charging speed, energy density, and battery performance.
Material Insights
The graphite segment led the market and accounted for around 81.0% of the global revenue in 2025. It is expected to grow steadily from 2026 to 2033. Graphite remains the most widely used anode material in battery manufacturing due to its high electrical conductivity, cost-effectiveness, stable cycling performance, and proven safety in lithium-ion batteries. Both natural and synthetic graphite are extensively used in rechargeable battery production, making graphite the industry standard for anode materials. The growing production of battery cells for electric vehicles, energy storage systems, and consumer electronics is expected to drive strong demand for graphite-based anode materials over the forecast period. Despite the emergence of silicon-based alternatives, graphite continues to dominate the market owing to its established commercial viability and large-scale adoption across lithium-ion battery manufacturing. For instance, in January 2025, General Motors entered into a long-term supply agreement with Vianode to provide synthetic graphite anode materials for electric vehicle batteries, highlighting growing investments in securing graphite supply chains for next-generation battery production.
The lithium segment is expected to grow at the fastest CAGR from 2026 to 2033. The electrification of transportation, particularly the surge in EV adoption, is a primary driver behind the increasing demand for lithium-ion batteries. EV manufacturers rely heavily on lithium-ion batteries for their energy storage needs due to their high energy density, long cycle life, and relatively lightweight properties. As the automotive industry moves away from internal combustion engines towards electric powertrains, the demand for lithium-ion batteries and, consequently, lithium is expected to grow rapidly. Furthermore, lithium-based anode materials are gaining significant traction due to their exceptionally high theoretical energy density, which enables the development of batteries with longer driving ranges and improved energy storage capacity. This makes them particularly attractive for next-generation electric vehicles and high-performance energy storage applications. In addition, growing investments in solid-state battery technologies are expected to further accelerate segment growth, as lithium metal anodes are considered critical to achieving higher energy density, faster charging, and improved battery performance in next-generation battery systems.
Application Insights
The consumer electronics segment dominated the industry with the highest revenue share of approximately 41.0% in 2025. The segment is expected to witness steady growth over the forecast period. Rising demand for smartphones, laptops, tablets, wearables, and other portable electronic devices is driving the adoption of lithium-ion batteries globally. The growing middle-income population and rising disposable incomes are further supporting demand for consumer electronics worldwide. In addition, the rapid expansion of the consumer electronics industry, coupled with increasing adoption of advanced smart devices among younger consumers, is expected to drive demand for battery anode materials. Manufacturers are increasingly focusing on advanced anode materials to improve battery life, charging speed, and energy density in compact devices. For instance, in January 2025, TDK announced its plan to roll out next-generation silicon-anode batteries for mobile devices, including smartphones, to better handle AI-related power demands and offer higher energy density than conventional graphite-anode batteries. The company plans to begin mass production of these batteries in 2025, reflecting growing demand for advanced battery anode materials in consumer electronics applications.
The automotive sector is expected to grow at the fastest CAGR over the forecast period. The global automotive sector is undergoing a significant transformation, primarily driven by the rapid electrification of transportation and the increasing adoption of electric vehicles (EVs) in both emerging and developed economies. Moreover, the increasing penetration of electric vehicles in the automotive industry is expected to propel demand for battery anode materials further. The rapid expansion of EV battery manufacturing capacity and the establishment of battery gigafactories worldwide are expected to significantly increase demand for anode materials, particularly graphite, silicon-based materials, and other advanced battery materials. In addition, rising demand for batteries with longer driving range, faster charging capabilities, and improved energy density is accelerating the adoption of high-performance anode materials in automotive battery applications. Supportive government policies, subsidies, and investments in EV infrastructure are further contributing to segment growth over the forecast period.
Regional Insights
The battery anode materials industry in North America is growing due to the diverse and robust manufacturing sector encompassing industries such as automotive, aerospace, consumer electronics, and telecommunications. These industries rely heavily on batteries and battery materials for energy storage, further driving demand for battery anode materials. In addition, increasing investments in domestic battery manufacturing, battery gigafactory expansion, and supply chain localization initiatives across the U.S. and Canada are expected to further accelerate market growth. Supportive government policies, including incentives for electric-vehicle production and battery-material processing, are also contributing to rising demand for battery anode materials in the region.
 To learn more about this report, Download Free Sample Report
U.S. Battery Anode Materials Market Trends
The U.S. battery anode materials is growing due to rising demand for automotive components and consumer electronics, including laptops, smartphones, and other portable devices. The increasing adoption of electric vehicles is a major driver of demand for battery anode materials in the country. As consumers and governments increasingly prioritize sustainability and seek to reduce dependence on fossil fuels, demand for lithium-ion batteries continues to rise significantly. These batteries rely on anode materials such as graphite, silicon, and other advanced materials to deliver high energy density, fast charging, and improved performance. In addition, rising investments in domestic battery manufacturing and supply chain localization are further supporting market growth in the U.S. For instance, in September 2025, Sila announced the commencement of operations at its Moses Lake, Washington, facility. This facility aims to manufacture Titan Silicon anode material for applications such as electric vehicles, consumer electronics, drones, and other battery-powered devices. The company states that the plant initially supports 2–5 GWh of battery capacity and will expand further in the future.
Asia Pacific Battery Anode Materials Market Trends
Asia Pacific battery anode materials industry dominated the global market, accounting for approximately 35.5% of global revenue in 2025, and is expected to maintain this trend over the forecast period. This can be attributed to the growing industrialization and population in this region. The rapid industrialization has resulted in several automotive and their component manufacturers setting up their production facilities in the Asia Pacific region due to the availability of inexpensive labor and raw materials. This is expected to further drive industry demand for battery anode materials in the global marketplace.
The China battery anode materials industry dominated the Asia Pacific region, accounting for around 43.5% of overall revenue. It is growing due to several automotive and consumer electronics manufacturing companies investing in China to establish production facilities, driven by factors such as low labor costs, a robust business environment, low customs & taxes, and limited regulatory compliance. This has resulted in a well-established manufacturing sector in China, with production facilities across several industries, including consumer electronics, automotive and its components, and telecommunications. This, in turn, has increased the demand for battery anode materials in China.
The battery anode materials industry in India is driven by favorable government policies to boost the growth of various industries under its Make in India scheme. For instance, the launch of the Automotive Mission Plan (AMP) 2026 aims at establishing the country as a global manufacturing hub for automotive and its components. This is expected to propel the demand for battery anode materials in India at a significant CAGR over the coming years.
Europe Battery Anode Materials Market Trends
The battery anode materials industry in Europe accounted for a significant share of the global market in 2025. This region comprises many developed economies, which have established markets for several industries including automotive, aerospace & defense, and telecommunication which positively influences the industry demand for battery anode materials in this region. Moreover, the rapid adoption of electric vehicles and stringent emission reduction targets across major European economies are significantly driving demand for lithium-ion batteries and advanced battery materials. Government initiatives aimed at accelerating transportation electrification are further supporting market growth. In addition, increasing investments in battery gigafactories and regional battery supply chain localization across countries such as Germany, France, Sweden, and Hungary are expected to further boost demand for battery anode materials. The growing focus on sustainable battery production and reduced dependence on imported battery materials is also contributing to market expansion in Europe.
The Germany battery anode materials industry is growing due to the country’s well-developed automotive sector. Germany is one of Europe’s leading automotive manufacturing hubs, with several major automotive manufacturers actively investing in electric vehicle production and next-generation battery technologies. This is expected to drive significant demand for battery anode materials from 2026 to 2033. For instance, in July 2025, BMW announced the start of series production preparations for its sixth-generation high-voltage batteries, which power the Neue Klasse electric vehicles beginning at the end of 2025. The company is developing batteries and pilot production activities at its facilities in Parsdorf, Hallbergmoos, and Munich, Germany. These batteries have lithium-ion cells which contain graphite- and silicon-based anode materials. Such new projects drive demand for battery anode materials in Germany.
Middle East & Africa Battery Anode Materials Market Trends
The battery anode materials industry in the Middle East & Africa is expected to grow at a significant rate over the years, owing to the automotive, energy, and consumer electronics industries in the region that are key consumers of the product. Moreover, increasing investments in renewable energy projects and grid-scale energy storage systems across countries such as Saudi Arabia, the UAE, and South Africa are expected to drive demand for advanced battery technologies and battery anode materials. The growing focus on clean energy transition and power infrastructure modernization is further supporting regional market growth. In addition, rising government initiatives to promote electric mobility, sustainable transportation, and industrial diversification are contributing to increased adoption of lithium-ion batteries, thereby boosting demand for battery anode materials across the region.
The Saudi Arabia battery anode materials industry is experiencing rapid growth due to various factors, including the country's economic diversification efforts, infrastructure development projects, and an expanding manufacturing sector. The combination of economic diversification efforts, an expanding manufacturing sector, population growth, and government initiatives is expected to propel demand for anode materials across industries.
Central & South America Battery Anode Materials Market Trends
The battery anode materials industry in Central & South America is experiencing growth driven by several key factors that contribute to the region’s economic development, along with industrialization and urbanization. Several automotive companies are investing in setting up their production facilities due to inexpensive labor and the availability of raw materials in the region. This is expected to trigger the demand for battery anode materials in this region over the forecast period.
The Brazil battery anode materials industry’s growth is driven by large-scale industrialization and strategic investment by manufacturing companies in Brazil. Hence, Brazil's escalating manufacturing sector is also contributing to the growth of the battery anode materials industry. Moreover, increasing adoption of electric vehicles and growing investments in renewable energy storage systems are expected to further drive demand for lithium-ion batteries and advanced battery materials in Brazil. The rising focus on clean energy transition and electrification is supporting long-term market growth in the country.
Key Battery Anode Materials Company Insights
Mergers and acquisitions contribute significantly to market expansion, which enables companies to strengthen their technological capabilities, expand production capacity, and broaden their geographic presence. In the battery anode materials industry, mergers and acquisitions enable companies to secure critical raw material sources, expand manufacturing capacity, and accelerate the commercialization of advanced anode technologies such as silicon-carbon materials.
Some of the key players operating in the market are SGL Carbon and Nippon Carbon
-
SGL Carbon is a publicly traded company with a broad shareholder structure. The company operates through three core business units, including Graphite Solutions, Process Technology, and Fiber Composites. The company has a strong global presence with sales and production operations across North America, Asia, and Europe. SGL Carbon currently operates 29 sites globally and maintains a service network spanning more than 80 countries.
-
Nippon Carbon is involved in the production and sale of carbon products. This company primarily offers carbon fiber products, carbon specialties, artificial graphite electrodes, silicon carbide continuous fibers, and battery materials.
JFE Chemical Corporation and M2Graphite are some of the emerging participants in the market.
-
JFE Chemical Corporation operates in several product categories, including chemical products, battery materials, fine chemicals, and inorganic materials. In battery materials, this company produces hard carbon, natural graphite anodes, and MCMB graphite anodes.
-
M2Graphite is a graphite-focused materials company engaged in the development and supply of high-quality graphite materials for advanced industrial applications. The company primarily focuses on producing and processing graphite products suitable for battery applications, energy storage systems, and other high-performance industrial uses. Its offerings support industries including electric vehicles, battery materials, renewable energy, and advanced manufacturing.
Key Battery Anode Materials Companies
The following key companies have been profiled for this study on the battery anode materials market.
-
SGL Carbon
-
Nippon Carbon Co Ltd
-
M2Graphite
-
JFE Chemical Corporation
-
Resonac Holdings Corporation.
-
KUREHA CORPORATION
-
Shanshan Holdings
-
POSCO FUTURE M
-
Jiangxi Shenchao New Energy Technology Co., Ltd.
-
Mitsubishi Chemical Group Corporation.
Recent Developments
-
In May 2026, POSCO Future M announced that it secured mass-production technology for silicon anode materials, which is a next-generation anode technology capable of delivering significantly higher energy density and faster charging than conventional graphite anodes. It is targeting commercial production and plans to start supplying by 2028, addressing the growing demand for premium EVs and advanced battery technologies.
-
In June 2026, Graphite One announced that it advanced its Ohio active anode materials facility by executing a key engineering contract, supporting a planned 25,000 tonnes-per-year capacity for synthetic graphite anode material and strengthening North America’s domestic battery supply chain.
Battery Anode Materials Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.4 billion
Estimated market size in 2026
USD 8.0 billion
Projected market size by 2033
USD 14.3 billion
Growth rate
CAGR of 7.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, application, region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; China; India; Japan; Brazil; Saudi Arabia
Key companies profiled
SGL Carbon; Nippon Carbon Co Ltd; M2Graphite; JFE Chemical Corporation; Resonac Holdings Corporation; KUREHA CORPORATION; Shanshan Holdings; POSCO FUTURE M; Jiangxi Shenchao New Energy Technology Co., Ltd.; Mitsubishi Chemical Group Corporation.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Battery Anode Materials Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global battery anode materialsmarket report based on material, application, and region:
- Material Outlook (Revenue, USD Billion, 2021 - 2033)
- Lithium
- Silicon
- Graphite
- Others
- Application Outlook (Revenue, USD Billion, 2021 - 2033)
- Consumer Electronics
- Automotive
- Industrial
- Telecommunication
- Others
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Asia Pacific
- China
- India
- Japan
- Central & South America
- Brazil
- Middle East & Africa
- Saudi Arabia
- North America
Frequently Asked Questions About This Report
Key players in the market include SGL Carbon, Nippon Carbon Co., Ltd., M2Graphite, JFE Chemical Corporation, Resonac Holdings Corporation, KUREHA CORPORATION, Shanshan Holdings, POSCO FUTURE M, Jiangxi Shenchao New Energy Technology Co., Ltd., Mitsubishi Chemical Group Corporation, and others.
The graphite segment accounted for the largest revenue share of approximately 81.0% in 2025.
The global battery anode materials market size was valued at USD 7.4 billion in 2025 and is estimated at USD 8.0 billion for 2026.
The global battery anode materials market is expected to grow at a CAGR of 7.6% from 2026 to 2033, reaching USD 14.3 billion.
Asia Pacific dominated with an approximately 35.5% revenue share in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


