
- Home
- »
- Semiconductors
- »
-
Battery Sensor Market Size And Share Report, 2026-2033GVR Report cover
![Battery Sensor Market (2026 - 2033)Report]()
Battery Sensor Market (2026 - 2033)
Size, Share & Trends Analysis Report By Voltage (12V, 24V, 48V), By Communication (LIN, CAN), By Vehicle Category (Passenger Car, Light Commercial Vehicle, Heavy Commercial Vehicle), By Vehicle Type, By Region, And Segment Forecasts
Market Size, 2025
$4.2BMarket Estimate, 2026
$4.7BMarket Forecast, 2033
$9.9BCAGR, 2026–2033
11.2%Battery Sensor Market Summary
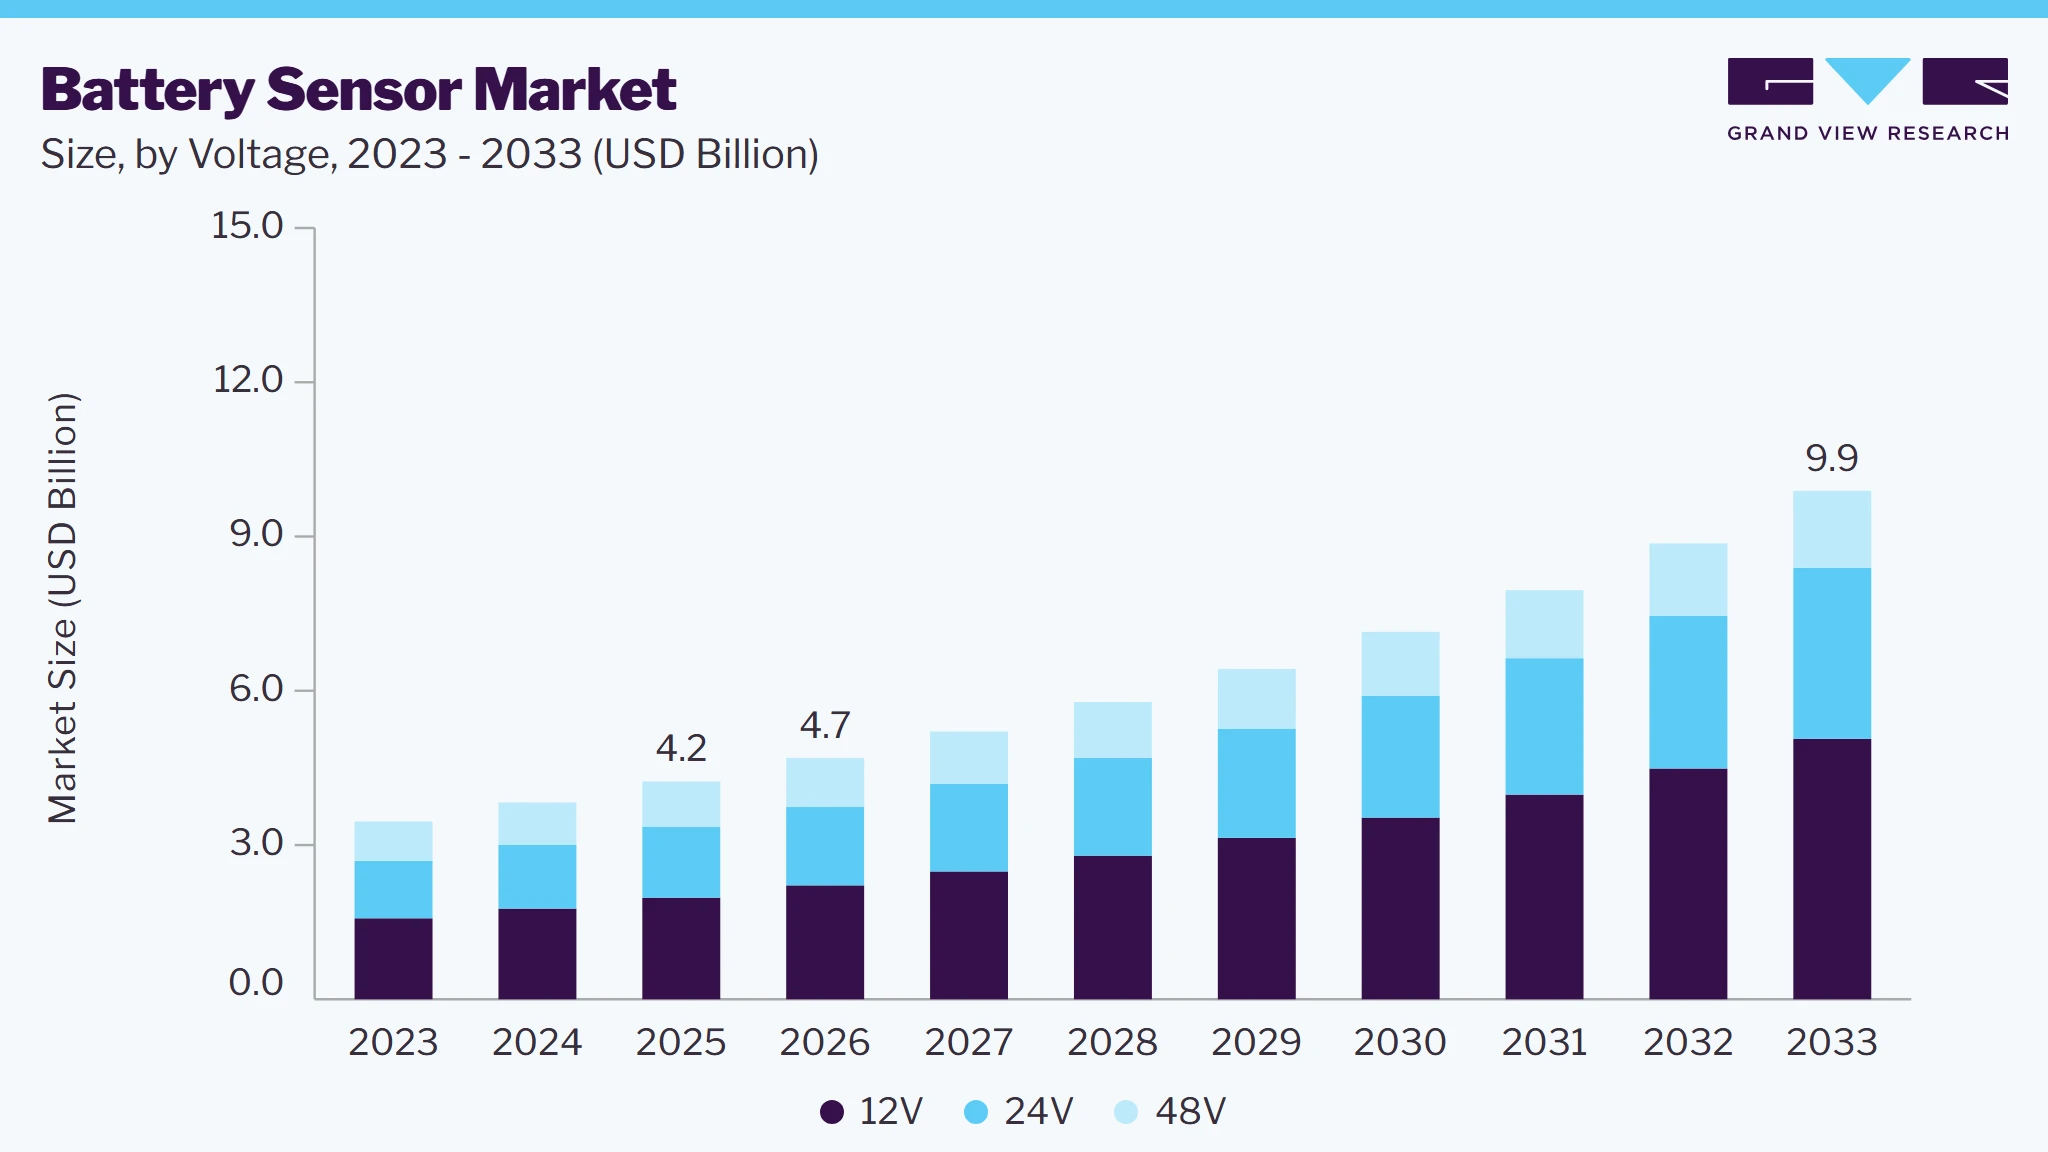
The global battery sensor market size was valued at USD 4.2 billion in 2025 and is projected to grow from USD 4.7 billion in 2026 to USD 9.9 billion by 2033, at a CAGR of 11.2% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 45.7% in 2025. The market consists of battery sensors that are used for monitoring the electric vehicle battery in the automotive industry.

Key Market Trends & Insights
- By voltage: 12V segment dominated the market, with a revenue share of 46.6% in 2025.
- By communication: Controller area network segment held the largest market share of 48.0% in 2025.
- By vehicle category: Passenger car segment held the largest revenue share in 2025.
- By vehicle type: BEV segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (45.7% revenue share, 2025)
- By country: The India is the fastest growing country in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.2 Billion
- Estimated market size in 2026: USD 4.7 Billion
- Projected market size by 2033: USD 9.9 Billion
- CAGR (2026-2033): 45.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These sensors monitor and measure battery performance in order to help protect the vehicle and its components. Focus on battery safety and efficiency, evolving battery technology, and increasing adoption of electric vehicles are some of the key factors driving the battery sensor market’s growth.Battery sensors enhance safety and efficiency by precisely measuring current, voltage, temperature, and calculate the battery's state of charge and function. They prevent issues like deep discharge, support CO2-saving technologies, and ensure a reliable power supply to critical vehicle systems. By maximizing battery life and supporting advanced vehicle features like predictive diagnostics, these sensors are crucial for vehicle electrification and automation. This functionality drives the growing adoption of battery sensors, contributing significantly to the market's growth.
In November 2023, United Safety & Survivability Corporation, an advanced safety solution provider, announced the launch of its latest innovation, a Lithium-Ion Battery Failure Detection System. This solution has the capability to detect battery failure at an early stage, which significantly increases battery safety. Such innovations are crucial for the growing adoption of electric vehicles, which rely on precise monitoring for optimal performance. With these technological advances, the demand for advanced battery sensors is rising, thus fueling the battery sensor market's growth.
The surging demand for electric vehicles (EVs) is fueling the need for advanced battery sensors, which are vital for ensuring optimal performance and longevity. These sensors offer real-time insights into vital metrics, ensuring efficient battery management and early detection of potential issues. The necessity for reliable battery management systems grows as EV adoption accelerates due to environmental and economic benefits. This heightened demand for efficient and safe battery operations is driving significant growth in the battery sensor market.
Despite the market's promising growth, one factor restraining the battery sensor market's growth is the high cost of advanced battery sensors, which can deter widespread adoption, especially in cost-sensitive markets. However, to overcome this challenge, industry players are investing in research and development to innovate and reduce production costs. Moreover, companies are also forming strategic partnerships to leverage shared resources and expertise, aiming to make advanced battery sensors more affordable. These efforts are expected to enhance market accessibility and support the continued growth of the battery sensor market.
Market Dynamics
Advancements in battery technologies, electric mobility, energy storage systems, and smart battery management systems (BMS) are significantly driving the demand for high-performance battery sensors capable of monitoring voltage, current, temperature, pressure, and state-of-charge parameters with greater accuracy and reliability. The integration of artificial intelligence, IoT connectivity, wireless monitoring, and predictive diagnostics enhances battery safety, operational efficiency, lifespan, and real-time performance optimization across electric vehicles, consumer electronics, industrial equipment, and grid-scale energy storage applications. However, high development and integration costs, stringent safety and performance standards, sensor calibration complexities, and challenges associated with operating under harsh environmental conditions increase deployment expenses and limit adoption among cost-sensitive end users. Meanwhile, the rapid expansion of electric vehicle production, growing investments in renewable energy storage infrastructure, increasing emphasis on battery safety regulations, and the emergence of next-generation solid-state and high-energy-density batteries are creating opportunities for manufacturers to develop intelligent, miniaturized, highly accurate, and energy-efficient battery sensor solutions tailored to evolving electrification and energy transition requirements.
The rapid growth of electric vehicle (EV) production and the increasing deployment of advanced battery management systems (BMS) are significantly driving demand for battery sensors across automotive, energy storage, industrial equipment, and consumer electronics applications. Modern battery sensors capable of accurately monitoring voltage, current, temperature, pressure, and state-of-charge parameters enable enhanced battery safety, optimized energy utilization, improved charging efficiency, and extended battery lifespan. These intelligent sensing solutions play a critical role in preventing thermal runaway, ensuring reliable battery operation, and supporting the performance requirements of high-energy-density lithium-ion and next-generation battery chemistries.
The market is also witnessing growing integration of artificial intelligence, predictive diagnostics, wireless communication technologies, and IoT-enabled monitoring platforms. AI-driven analytics facilitate real-time battery health assessment, predictive maintenance, fault detection, and performance optimization, helping battery manufacturers and end users reduce downtime, improve operational reliability, and lower lifecycle costs. Additionally, increasing investments in renewable energy storage systems, stringent battery safety regulations, and the ongoing transition toward vehicle electrification are accelerating the adoption of highly accurate, miniaturized, and energy-efficient battery sensor solutions tailored to evolving electrification and energy management requirements.
The deployment of battery sensor solutions requires significant investment in sensor technologies, battery management systems (BMS), data acquisition modules, communication interfaces, and advanced diagnostic software. The high costs associated with sensor development, precision calibration, testing, certification, and integration often limit adoption among cost-sensitive end users, particularly in consumer electronics, industrial equipment, and entry-level electric vehicle segments. Additionally, manufacturers must invest in compliance with stringent safety standards, functional validation processes, and reliability testing under varying operating conditions, further increasing overall development and implementation costs.
The market also faces challenges related to complex integration and interoperability requirements. Battery sensors must operate seamlessly with battery management systems, thermal management units, charging infrastructure, power electronics, and vehicle or energy management platforms. Ensuring compatibility across diverse battery chemistries, cell configurations, communication protocols, and end-use applications often requires specialized engineering expertise, extended validation cycles, and additional integration efforts. Moreover, maintaining sensor accuracy and reliable performance under harsh environmental conditions, such as extreme temperatures, vibration, and high-voltage environments, can increase system complexity and deployment timelines, potentially affecting product commercialization and large-scale adoption.
The rapid expansion of electric mobility, renewable energy integration, and stationary energy storage systems is creating significant opportunities for battery sensor manufacturers worldwide. Increasing electric vehicle production, growing investments in grid-scale battery storage projects, and rising demand for reliable power backup solutions are driving the adoption of advanced battery monitoring technologies. Battery sensors play a critical role in ensuring operational safety, optimizing charging and discharging cycles, extending battery lifespan, and improving overall energy efficiency, making them an essential component of modern electrification infrastructure.
The market is also benefiting from the emergence of next-generation battery technologies, including solid-state, lithium-sulfur, and high-energy-density lithium-ion batteries, across automotive, aerospace, consumer electronics, and industrial applications. As battery systems become more sophisticated and energy-dense, manufacturers and end users are increasingly adopting intelligent sensing solutions equipped with real-time diagnostics, predictive analytics, and wireless communication capabilities to enhance battery performance and mitigate safety risks such as overheating and thermal runaway. This trend is generating substantial opportunities for companies to develop highly accurate, miniaturized, energy-efficient, and application-specific battery sensor solutions tailored to evolving energy storage and electrification requirements.
Analyst Perspective
The battery sensor market is expanding rapidly due to rising EV adoption, advanced BMS, and growing renewable energy storage deployment. Automotive OEMs and energy storage providers are increasingly using battery sensors to improve safety, charging efficiency, energy utilization, and battery lifespan. Advancements in AI, IoT, semiconductor integration, and predictive diagnostics are enhancing real-time battery monitoring and performance optimization. Despite challenges such as high integration costs, stringent safety requirements, and lengthy qualification cycles, continued investments in electrification, renewable energy, and next-generation battery technologies are expected to drive steady market growth.
Voltage Insights
Based on voltage, the 12V segment led the market with the largest revenue share of 46.6% in 2025 and is expected to retain its dominance over the forecast period. The 12V battery sensor segment is experiencing growth due to its low cost and essential role in technologies like regenerative braking and start/stop systems. The continuous rise in vehicle production and stringent emission norms aimed at reducing CO2 emissions are further driving demand. As automotive manufacturers focus on enhancing fuel efficiency and meeting regulatory standards, the adoption of 12V battery sensors is increasing, thus significantly contributing to the 12V segment’s growth.
The 24V segment is expected to register significant growth from 2026 to 2033. This growth is driven by the increasing adoption of electric commercial vehicles and buses, which typically use 24V electrical systems. These vehicles require robust battery sensors to monitor and optimize performance, ensuring reliable operation over extended periods. As cities and governments worldwide prioritize sustainable transport solutions, the demand for electric buses and commercial vehicles is rising, further boosting the need for advanced 24V battery sensors, thus contributing to the segment’s growth.
Communication Insights
Based on communication, the controller area network (CAN) segment led the market with the largest revenue share of 58.0% in 2025. The segment’s growth is driven by its ability to support high-speed communication and robust data transmission capabilities. CAN technology facilitates real-time monitoring of critical battery parameters such as voltage, current, and temperature in electric vehicles (EVs), ensuring efficient operation and safety. As automakers increasingly integrate advanced electronic control systems in vehicles, the demand for CAN-based battery sensors is expanding.
The local interconnect network (LIN) segment is expected to grow significantly from 2026 to 2033. The LIN segment is witnessing growth primarily due to its cost-effectiveness and suitability for less demanding communication tasks within automotive systems. LIN technology provides reliable communication for monitoring secondary battery parameters and supporting basic functionalities in EVs, such as peripheral device control. As vehicle manufacturers seek to optimize costs while ensuring reliable performance, the demand for LIN-based batteries is expected to grow.
Vehicle Category Insights
Based on vehicle category, the Passenger Car segment led the market with the largest revenue share of 88.7% in 2025. The growing consumer preference for hybrid and electric passenger cars is driving the demand for battery sensors within this segment. Battery sensors are crucial for managing power efficiently and ensuring optimal battery health. As automakers focus on extending driving ranges and improving charging times for passenger cars, the demand for advanced sensors capable of real-time monitoring and predictive maintenance is expected to rise further, driving the adoption of battery sensors in passenger cars.
The light commercial vehicle segment is expected to register the highest CAGR from 2026 to 2033. Light commercial vehicles are used in various applications such as urban delivery fleets, small-scale logistics, and school transport, among others. In light commercial vehicles, battery sensors are used to maintain fleet uptime and optimize energy consumption in these vehicles. Key market players are focusing on developing scalable sensor solutions that cater to the unique requirements of these light commercial vehicles, including integration capabilities and cost-effectiveness.
Vehicle Type Insights
Based on vehicle type, the BEV segment led the market with the largest revenue share of 72.1% in 2025. The segment is experiencing rapid growth within the battery sensor market, driven by increasing global adoption of fully electric vehicles. BEVs rely heavily on advanced battery sensors to optimize performance, monitor health metrics, and ensure safety. As consumers and governments prioritize zero-emission transportation solutions, the demand for precise and reliable battery monitoring systems is escalating, thereby contributing to the BEV segment’s growth.
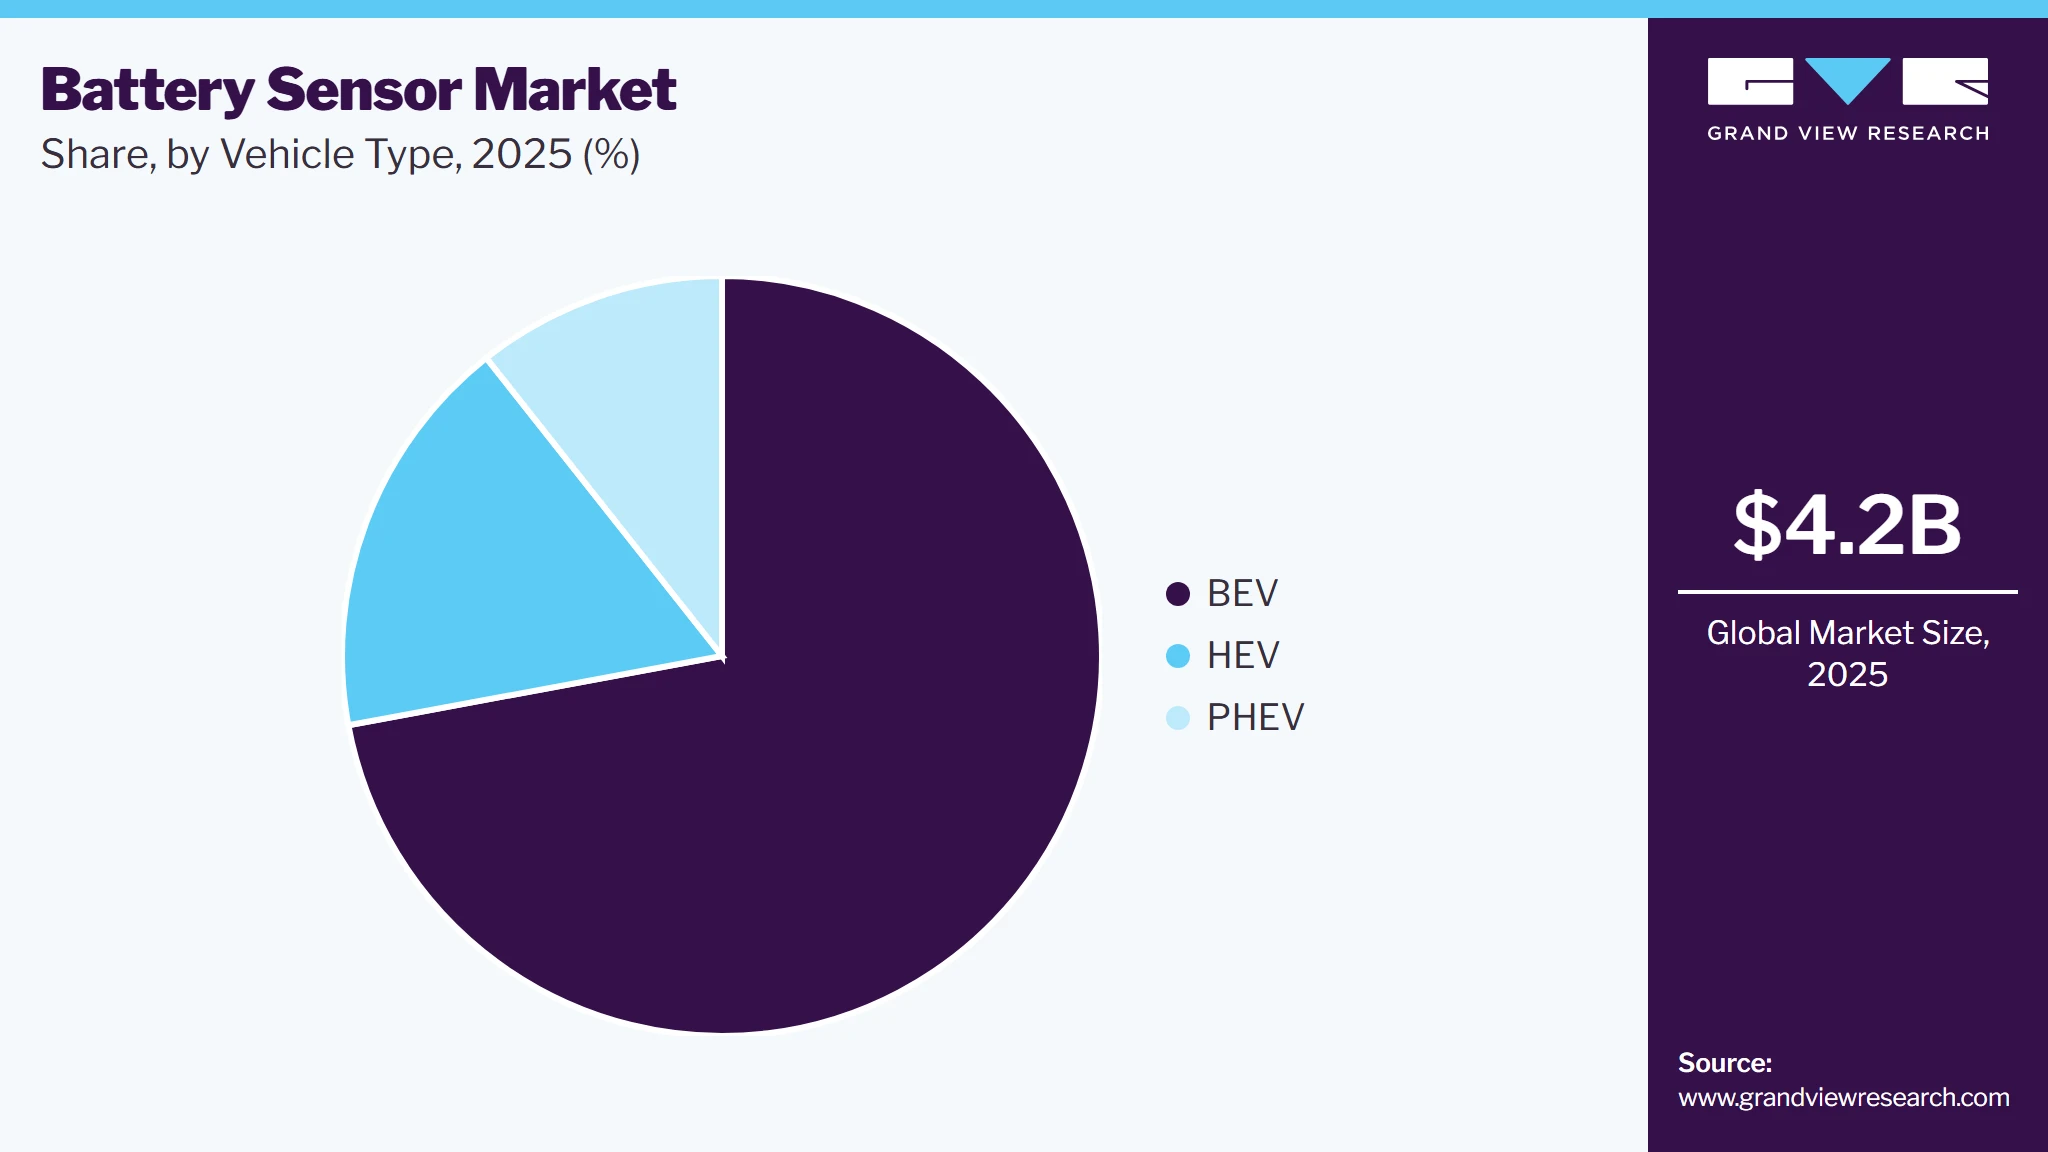
The HEV segment is expected to register significant growth from 2026 to 2033. The growing popularity of vehicles combining internal combustion engines with electric propulsion is driving the demand for battery sensors in HEV vehicles. HEVs require sophisticated battery sensors to efficiently manage energy flows between the engine, battery, and electric motor. As automotive manufacturers continue to enhance hybrid technology for improved fuel efficiency and reduced emissions, the demand for advanced battery sensors that can optimize hybrid system performance is increasing.
Regional Insights
North America battery sensor market is poised for significant growth from 2026 to 2033. The North America battery sensor market is expanding due to increasing investments in electric vehicle (EV) infrastructure and stringent emission regulations. With the U.S. and Canada at the forefront, the region sees rising demand for advanced battery sensors to support EV adoption.
U.S. Battery Sensor Market Trends
Battery sensor market in the U.S. is anticipated to register significant growth from 2026 to 2033. The market is growing amidst rapid EV adoption and supportive federal policies incentivizing clean energy initiatives. With growing technological advancements in battery sensors, the U.S. is poised for significant growth over the forecast period.
Europe Battery Sensor Market Trends
Battery sensor market in Europe is poised for significant growth from 2026 to 2033. The market is witnessing substantial growth propelled by ambitious CO2 reduction targets. Countries such as Germany, France, and Norway lead in EV adoption, creating a strong demand for high-performance battery sensors in the region.
Asia Pacific Battery Sensor Market Trends
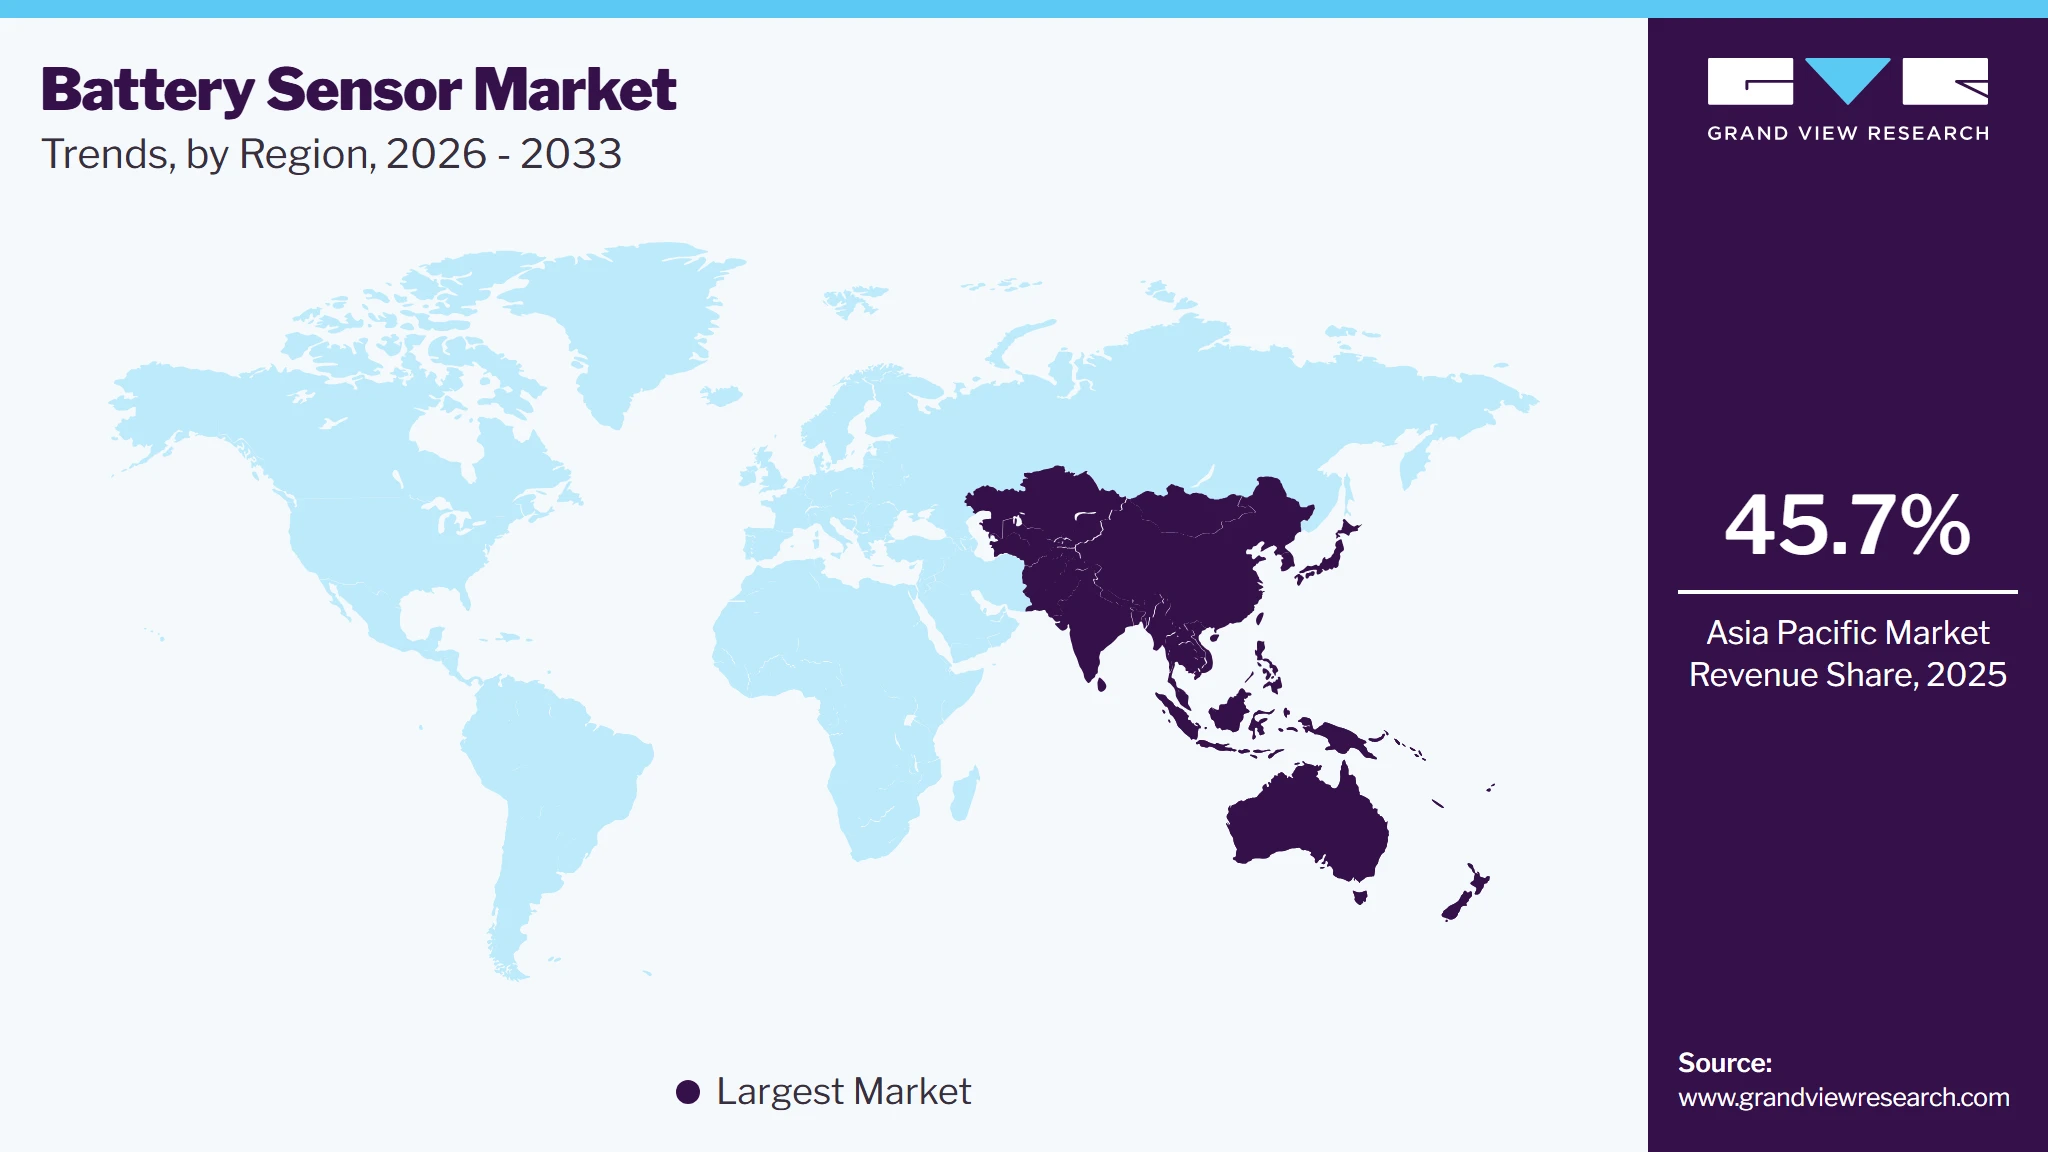
Battery sensor market in APAC dominated the global market and accounted for 45.7% in 2025. The regional market is experiencing rapid expansion driven by the region's dominance in electric vehicle production and increasing investments in sustainable mobility solutions. Manufacturers in the region are focusing on developing cost-effective and reliable battery sensor technologies to cater to diverse market needs and capitalize on the accelerating shift toward electric mobility.
India Battery Sensor Market Trends
India is the fastest growing country in the Aisa Pacific battery sensor market. Rapid EV adoption is increasing demand for battery sensors, as electric two-wheelers, three-wheelers, passenger vehicles and buses require continuous monitoring of voltage, current and temperature for safe and efficient battery operation. Government-supported EV manufacturing and adoption programs are further strengthening this demand. Also, increasing BMS sophistication and predictive battery monitoring is shifting the market from basic sensing toward integrated, high-accuracy sensors capable of supporting SoC, SoH, thermal monitoring and predictive diagnostics. This trend will particularly benefit suppliers of integrated battery-monitoring ICs, current sensors, cell-voltage sensors and temperature sensors.
Key Battery Sensor Company Insights
The battery sensor market is characterized by a few key players striving to innovate and capture market share. Major companies are focusing on developing and launching advanced sensor technologies in order to enhance their product portfolio offerings.
One such example is the launch of new sensors by Continental AG to protect the battery of electrified vehicles. In May 2022, Continental AG announced the launch of its two new sensors for electrified vehicles, namely the Battery Impact Detection (BID) system and the Current Sensor Module (CSM). Both of these solutions are aimed at focusing on protecting the battery and/or battery parameter retention. Such initiatives are harnessing innovation in the battery sensor market.
Key Battery Sensor Companies:
The following key companies have been profiled for this study on the battery sensor market.
- Continental AG
- Robert Bosch GmbH
- Furukawa Electric Co., Ltd.
- NXP Semiconductors
- Vishay Intertechnology, Inc.
- Inomatic GmbH
- Texas Instruments Incorporated
- HELLA
- TE Connectivity
- Battery Watering Technologies.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Continental AG; Robert Bosch GmbH; NXP Semiconductors; Texas Instruments Incorporated; TE Connectivity; HELLA; Vishay Intertechnology Inc.)
- Focus on developing high-precision battery sensors, battery management systems (BMS), current sensing technologies, and intelligent battery monitoring solutions for electrified vehicles.
- Continuous investments in sensor miniaturization, semiconductor technologies, AI-enabled diagnostics, functional safety capabilities, and advanced communication interfaces such as CAN and LIN.
- Strong global manufacturing footprint, extensive R&D capabilities, diversified product portfolios, and established relationships with leading automotive OEMs and battery suppliers.
- Proven expertise in automotive-grade electronics, functional safety compliance, and large-scale production capabilities.
- Robust after-sales support, technical expertise, and ability to provide integrated sensing and battery management solutions.
- High R&D expenditures and significant investments required to meet evolving battery technologies and stringent automotive safety standards.
- Longer product qualification and commercialization cycles due to extensive validation, certification, and OEM approval requirements.
- Exposure to fluctuations in automotive production volumes and semiconductor supply chain constraints.
Emerging Players (Furukawa Electric Co., Ltd.; Inomatic GmbH; Battery Watering Technologies)
- Focus on specialized battery sensing technologies, customized monitoring systems, battery maintenance solutions, and application-specific designs for automotive, industrial, and energy storage applications.
- Emphasize flexible engineering capabilities, niche product development, and tailored solutions to address specific customer requirements.
- Greater agility in product development and ability to address customer-specific battery monitoring requirements.
- Faster response to emerging battery technologies, evolving regulatory standards, and niche market opportunities.
- Limited global presence, smaller production capacities, and lower financial resources compared with established industry leaders.
- Dependence on a narrower customer base and product portfolio.
Battery Sensor Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.2 billion
Estimated Market size in 2026
USD 4.7 billion
Projected Market size by 2033
USD 9.9 billion
Growth rate
CAGR of 11.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Voltage, communication, vehicle category, vehicle type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; China; Japan; India; Australia; South Korea; Australia; Brazil; Kingdom of Kingdom of Saudi Arabia (KSA); UAE; South Africa
Key companies profiled
Continental AG; Robert Bosch GmbH; Furukawa Electric Co., Ltd.; NXP Semiconductors; Vishay Intertechnology Inc.; Inomatic GmbH; Texas Instruments Incorporated; HELLA; TE Connectivity; Battery Watering Technologies.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Battery Sensor Market Report Segmentation
The report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global battery sensor market report based on voltage, communication, vehicle category, vehicle type, and region.
-
Voltage Outlook (Revenue, USD Million, 2021 - 2033)
-
12V
-
24V
-
48V
-
-
Communication Outlook (Revenue, USD Million, 2021 - 2033)
-
Local Interconnect Network (LIN)
-
Controller Area Network (CAN)
-
-
Vehicle Category Outlook (Revenue, USD Million, 2021 - 2033)
-
Passenger Car
-
Light Commercial Vehicle
-
Heavy Commercial Vehicle
-
-
Vehicle Type Outlook (Revenue, USD Million, 2021 - 2033)
-
BEV
-
HEV
-
PHEV
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
UAE
-
Kingdom of Saudi Arabia (KSA)
-
South Africa
-
-
Research Methodology
The battery sensor market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each battery Sensor segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Voltage
Revenue Capture Definition
12V
This segment captures revenue generated from battery sensors designed for 12V battery systems predominantly used in passenger cars equipped with internal combustion engines, mild hybrid systems, and auxiliary power applications. These sensors monitor battery voltage, current, temperature, and state-of-health to optimize energy management, improve fuel efficiency, and support start-stop functionalities.
24V
This segment includes revenue derived from battery sensors deployed in 24V electrical architectures commonly found in light commercial vehicles, medium-duty trucks, buses, and industrial vehicles. These sensors enable real-time battery monitoring, enhance power management, support vehicle electrification initiatives, and ensure reliable operation under demanding duty cycles.
48V
This segment captures revenue generated from battery sensors integrated into 48V battery systems utilized in mild hybrid electric vehicles, advanced automotive electrical platforms, and emerging electrified mobility applications. These solutions facilitate efficient energy recuperation, improved battery performance, enhanced fuel economy, and compliance with increasingly stringent emission regulations.
Segment- Communication
Revenue Capture Definition
Local Interconnect Network (LIN)
This segment captures revenue generated from battery sensors utilizing LIN communication protocols for cost-effective and reliable data exchange between battery management components and vehicle electronic control units. These sensors are widely adopted in passenger vehicles and entry-level electrification platforms where simplified network architecture and lower implementation costs are prioritized.
Controller Area Network (CAN)
This segment includes revenue derived from battery sensors employing CAN communication protocols to enable high-speed, robust, and real-time transmission of battery performance data. These solutions are extensively used in electric vehicles, hybrid vehicles, commercial vehicles, and advanced battery management systems requiring seamless integration with powertrain, charging, and energy management systems.
Segment- Vehicle Category
Revenue Capture Definition
Passenger Car
This segment captures revenue generated from battery sensors deployed in passenger cars to support battery monitoring, energy optimization, start-stop systems, electrified powertrains, and onboard energy management functions. Increasing adoption of electric and hybrid passenger vehicles continues to drive demand for advanced sensing technologies in this segment.
Light Commercial Vehicle (LCV)
This segment includes revenue derived from battery sensors utilized in light commercial vehicles such as delivery vans, pickup trucks, and utility vehicles. These sensors enhance battery reliability, optimize power consumption, support electrification initiatives, and ensure uninterrupted operation in logistics, fleet management, and urban mobility applications.
Heavy Commercial Vehicle (HCV)
This segment captures revenue generated from battery sensors integrated into heavy-duty trucks, buses, construction equipment, and specialized industrial vehicles. These solutions enable continuous battery diagnostics, improve fleet efficiency, support high-power electrical systems, and ensure dependable performance under harsh operating environments and long-duty cycles.
Segment- Vehicle Type
Revenue Capture Definition
BEV
This segment captures revenue generated from battery sensors used in battery electric vehicles (BEVs). These sensors provide continuous monitoring of voltage, current, temperature, and battery health parameters to maximize driving range, enhance charging efficiency, improve safety, and support advanced battery management systems for high-capacity traction batteries.
HEV
This segment includes revenue derived from battery sensors deployed in hybrid electric vehicles (HEVs), where they facilitate efficient energy flow management between internal combustion engines and electric propulsion systems. These sensors contribute to improved fuel economy, optimized regenerative braking, and extended battery life.
PHEV
This segment captures revenue generated from battery sensors integrated into plug-in hybrid electric vehicles (PHEVs). These solutions support real-time battery diagnostics, charging management, state-of-charge estimation, and thermal monitoring, enabling seamless transitions between electric and conventional power modes while ensuring battery safety and performance optimization.
Estimation Model
Layer Name
Key Question
Description
Installed Vehicle and Battery Base Layer
Where are battery sensors used and what drives demand?
Establish the total potential demand base by identifying battery sensor deployment across passenger cars, light commercial vehicles, heavy commercial vehicles, battery electric vehicles (BEVs), hybrid electric vehicles (HEVs), plug-in hybrid electric vehicles (PHEVs), and other electrified mobility platforms equipped with battery management systems requiring real-time battery monitoring and diagnostics.
Addressable Battery Monitoring Market Layer
Which vehicle platforms can realistically adopt battery sensor solutions?
Refine the total vehicle and battery base into the realistically serviceable market by considering factors such as vehicle electrification rates, battery architecture (12V, 24V, and 48V), battery management system integration, communication protocol compatibility (LIN and CAN), regulatory requirements, OEM adoption trends, and regional penetration of advanced battery monitoring technologies.
Battery Sensor Procurement Layer
Who is actively purchasing, integrating, or upgrading battery sensor systems?
Estimate annual demand generation by analyzing vehicle production volumes, electrification initiatives, new model launches, battery management system upgrades, replacement demand, advancements in battery technologies, investments in electric mobility, and increasing adoption of battery health monitoring solutions by automotive OEMs, battery manufacturers, and Tier-1 suppliers.
Revenue Layer
How is revenue generated from battery sensor sales?
Revenue is generated through the sale of battery sensors across various voltage architectures (12V, 24V, and 48V), communication protocols (LIN and CAN), vehicle categories, and vehicle types. Market revenue is calculated by considering unit shipments, sensor specifications, sensing capabilities, communication features, OEM and aftermarket demand, regional pricing variations, and value chain margins across sensor manufacturers, battery management system providers, automotive suppliers, and vehicle manufacturers.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Battery Sensor Market Assessment
Structured evaluation of market dynamics including key drivers, restraints, opportunities, and industry trends across the battery sensor value chain.
Assessment of technology evolution across battery management systems (BMS), intelligent sensing technologies, AI-enabled battery diagnostics, wireless monitoring, and IoT-integrated energy management platforms.
Clear visibility into market growth drivers, technology adoption trends, and commercialization barriers.
Strategic input for market entry, expansion planning, and investment decisions.
End-Use and Application Insights
Analysis of demand distribution across passenger cars, light commercial vehicles, heavy commercial vehicles, BEVs, HEVs, PHEVs, and stationary energy storage applications.
Evaluation of evolving industry requirements related to battery safety, state-of-charge estimation, predictive maintenance, thermal management, and electrification initiatives.
Identification of high-growth and high-value application segments.
Support for targeted product development, customer prioritization, and go-to-market strategies.
Technology and Competitive Landscape Review
Benchmarking of key battery sensor technologies, including 12V, 24V, and 48V architectures, as well as LIN- and CAN-based communication systems.
Analysis of major players' innovation strategies, sensing capabilities, semiconductor integration expertise, product differentiation, and regional market presence.
Competitive intelligence for technology positioning and portfolio optimization.
Guidance for R&D prioritization, partnership evaluation, and long-term growth planning.
Frequently Asked Questions About This Report
The global battery sensor market size was estimated at USD 4.2 billion in 2025 and is expected to reach USD 4.7 billion in 2026.
Some key players operating in the battery sensor market include Continental AG, Robert Bosch GmbH, FURUKAWA ELECTRIC CO., LTD., NXP Semiconductors, Vishay Intertechnology, Inc., inomatic GmbH, Texas Instruments Incorporated, HELLA, TE Connectivity, and Battery Watering Technologies.
Key factors that are driving the market growth include vehicle electrification and the growing adoption of renewable energy storage systems.
The global battery sensor market is expected to grow at a compound annual growth rate of 11.2% from 2026 to 2033 to reach USD 9.9 billion by 2033.
Asia Pacific dominated the battery sensor market with a share of 45.7% in 2025. The regional market is experiencing rapid expansion driven by the region's dominance in electric vehicle production and increasing investments in sustainable mobility solutions.
About the Author(s)
Semiconductors Research Team
Semiconductors & Electronics · SemiconductorsThis report was authored by the semiconductors research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the semiconductors segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


