
- Home
- »
- Automotive & Transportation
- »
-
Battery Swapping Charging Infrastructure Market Report, 2033GVR Report cover
![Battery Swapping Charging Infrastructure Market (2026 - 2033)Report]()
Battery Swapping Charging Infrastructure Market (2026 - 2033)
Size, Share & Trends Analysis Report By Vehicle Type (Two-wheeler, Three-wheeler, Passenger Vehicle, Commercial Vehicle), By Service Type (Pay-per-use, Subscription), By Region, And Segment Forecasts
Market Size, 2025
$280.8MMarket Estimate, 2026
$333.6MMarket Forecast, 2033
$1,882.8MCAGR, 2026–2033
28.0%Market Size & Trends
The global battery swapping charging infrastructure market size was valued at USD 280.8 million in 2025 and is projected to grow from USD 333.6 million in 2026 to USD 1,882.8 million by 2033, at a CAGR of 28.0% from 2026 to 2033. Asia Pacific dominated the global market with the largest revenue share of 30.9% in 2025. Battery swapping charging infrastructure allows electric vehicle users to replace their discharged batteries with charged batteries at the swap stations. Consumers are charged for these batteries on a pay-per-use or subscription basis. Reduced charging time, reduced upfront costs of buying an electric vehicle, increasing demand for public charging infrastructure, and favorable government subsidies are driving the installation of battery swapping charging infrastructure, thereby driving the market’s growth.

Key Market Trends & Insights
- By vehicle type: Two-Wheeler segment dominated the market, with a revenue share of 31.2% in 2025
- By service type: Pay-per-Use segment held the largest market share in 2025
Regional Highlights
- Largest regional market: Asia Pacific (30.9% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 280.8 Million
- Estimated market size in 2026: USD 333.6 Million
- Projected market size by 2033: USD 1,882.8 Million
- CAGR (2026-2033): 28.0%
Additionally, battery swapping charging infrastructure of battery-as-a-service allows customers to lease batteries, which reduces their overall upfront cost of purchasing the battery. Batteries account for about 30-40% of the overall EV cost, and leasing them can reduce this cost considerably for consumers. The time and cost-saving capabilities of battery swapping charging infrastructure are expected to play a crucial role in their adoption, driving the market’s growth.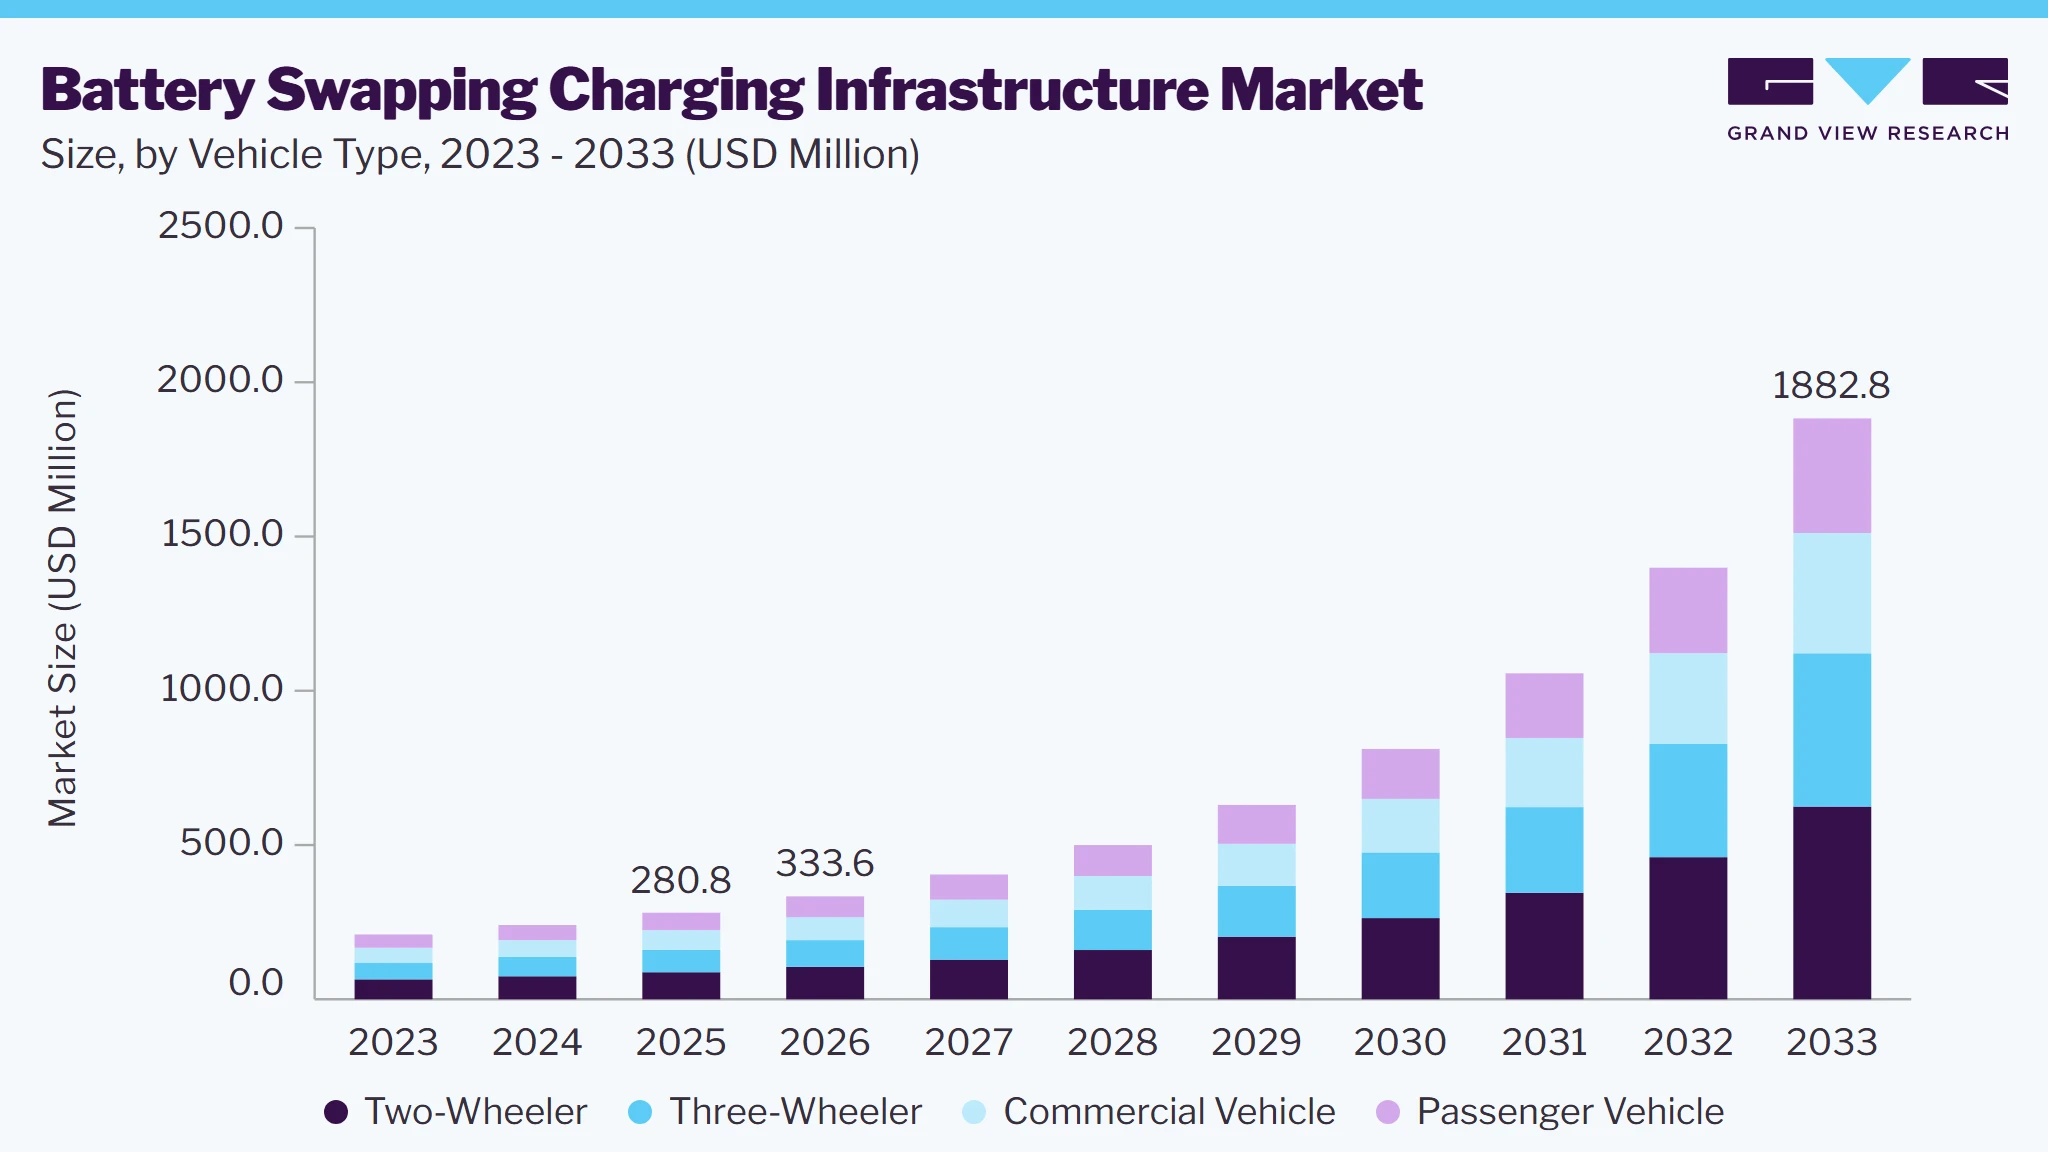
Governments worldwide are working toward bridging the gap between electric vehicle demand and public charging infrastructure. Government initiatives are crucial in the electric vehicle market to solve these disparities and kick-start market growth. Governments worldwide are drafting policies to address key technical, regulatory, institutional, and financial challenges in the electric vehicle market. For instance, in April 2022, the Indian government introduced a policy for electric vehicle battery-swapping that aims to catalyze the rapid adoption of EVs by promoting the adoption of battery swapping technology, which ensures minimal downtime, lower upfront costs, and lower space requirements. Such initiatives are fostering the growth of battery swapping charging infrastructure industry.
A well-established network of battery swapping charging infrastructure could be instrumental in driving the adoption of electric vehicles. However, the market faces a few roadblocks that need to be tackled by the authorities and key market players. For instance, standardization of EV Lithium-Ion battery packs remains a constraint for the market, and battery disposal is yet another issue for environmental pollution. However, with battery swapping charging infrastructure, the burden of removing and recycling batteries will reduce as the responsibilities for safe battery disposal and recycling will shift to private players, which is expected to drive the adoption of battery swapping charging infrastructure over the forecast period.
Market Dynamics
The battery swapping charging infrastructure market is shaped by accelerating electric vehicle (EV) adoption, urban mobility electrification, and increasing policy emphasis on reducing charging downtime and grid stress. The market is influenced by macro trends such as rapid electrification of two- and three-wheelers, the expansion of dense urban logistics, and the need for scalable, standardized energy delivery models. Technological forces include modular battery architectures, automated swapping stations, and software enabled asset management platforms. Moreover, the market is moving toward service oriented infrastructure models that prioritize uptime, fleet efficiency, and cost predictability over conventional plug-in charging approaches.
The primary driver of battery swapping infrastructure is the operational limitations of conventional charging, particularly long charging times and vehicle downtime. This challenge is most acute in high-utilization segments such as shared mobility, last-mile delivery, and urban commercial fleets, where vehicle idle time directly impacts revenue generation. As EV penetration increases in densely populated cities, charging congestion and grid capacity constraints further intensify the need for alternative refueling solutions. These structural inefficiencies create a strong demand for faster, repeatable energy replenishment models.
Battery swapping infrastructure addresses this driver by enabling near instant energy replacement, thereby significantly improving vehicle utilization rates. Swapping stations decouple charging time from vehicle operation, allowing batteries to be charged off-board under optimized conditions. This model supports fleet scalability, reduces peak-load pressure on urban grids, and enables standardized energy-as-a-service offerings. As a result, battery swapping accelerates EV adoption in commercial and shared-use applications, directly supporting market growth.
A key restraint affecting the market is the lack of standardized battery form factors, chemistries, and interfaces across vehicle manufacturers. Proprietary battery designs limit interoperability, restricting the scalability of swapping networks and increasing infrastructure complexity. This fragmentation raises capital requirements for station operators, who must support multiple battery types, and discourages cross-brand participation. The restraint significantly impacts network economics and slows ecosystem wide adoption.
Downstream, this restraint disproportionately affects passenger vehicles and multi-OEM markets, where design differentiation is highest. Geographies with fragmented EV manufacturing bases face slower rollout of swapping networks due to coordination challenges. In contrast, markets dominated by standardized two- and three-wheelers experience faster adoption. Moreover, the lack of standardization slows market expansion by limiting network density, utilization rates, and return on investment.
The emergence of Battery-as-a-Service business models presents a significant opportunity for the market. BaaS is enabled by declining battery costs, digital fleet management platforms, and regulatory support for service-based EV ownership. By separating battery ownership from the vehicle, BaaS reduces upfront vehicle costs and improves affordability. This model aligns well with battery swapping infrastructure, which requires centralized battery ownership and lifecycle control.
The growth potential is strongest in commercial fleets, shared mobility operators, and urban logistics providers, where predictable operating costs are critical. Vendors offering integrated hardware, software, and energy services are best positioned to capture this opportunity. Segments such as two-wheelers, three-wheelers, and light commercial vehicles are expected to drive early revenue capture, while passenger vehicle adoption is likely to follow in markets with strong OEM participation.
Analyst Perspective
The battery swapping charging infrastructure market is transitioning from pilot deployments to commercially scalable networks, driven by fleet electrification and urban mobility needs. Two- and three-wheelers currently anchor demand, while commercial fleets are emerging as high-value adopters. Technological advancements in automated swapping, battery health analytics, and energy management software are reshaping infrastructure efficiency. Investment activity is increasingly focused on integrated BaaS platforms rather than standalone hardware. Competitive dynamics are shifting toward ecosystem-led strategies involving OEMs, energy providers, and mobility operators.
Vehicle Type Insights
Based on vehicle type, the two-wheeler segment led the market with the largest revenue share of 31.2% in 2025. The cost-effectiveness offered by the battery swapping technology drives the growth of the industry. Battery swapping eliminates the need for owning a battery, reducing the upfront cost of electric two-wheelers. Many battery-as-a-service (BaaS) models enable users to pay for battery usage rather than purchase, making electric two-wheelers more affordable. This cost-effective approach has accelerated adoption in price-sensitive markets, particularly in developing countries.
The three-wheeler segment is expected to grow at a significant CAGR during the forecast period. The rapid growth of e-commerce and the increasing demand for efficient last-mile delivery solutions drive the adoption of electric three-wheelers. These vehicles are widely used for transporting goods and passengers in urban areas. Battery swapping offers a practical solution for maintaining high operational efficiency in these applications, as vehicles can stay on the road longer without needing to pause for extended charging periods.
Service Type Insights
Based on service type, the pay-per-use segment led the market with the largest revenue share of 59.2% in 2025. The pay-per-use or pay-as-you-go service allows the separation of battery from the vehicle and enables users to buy electric vehicles at a lower upfront cost. It allows electric vehicles to be financially viable for the first time. Moreover, the pay-per-use model addresses key EV adoption issues such as high upfront costs, long refueling time, and range anxiety. The pay-per-use segment is powered by smart batteries, quick interchange stations, smart networks, and plug-and-play docks. The technological innovations and viable economic options provided by the pay-per-use payment model are driving the segment’s growth in the battery swapping charging infrastructure industry.
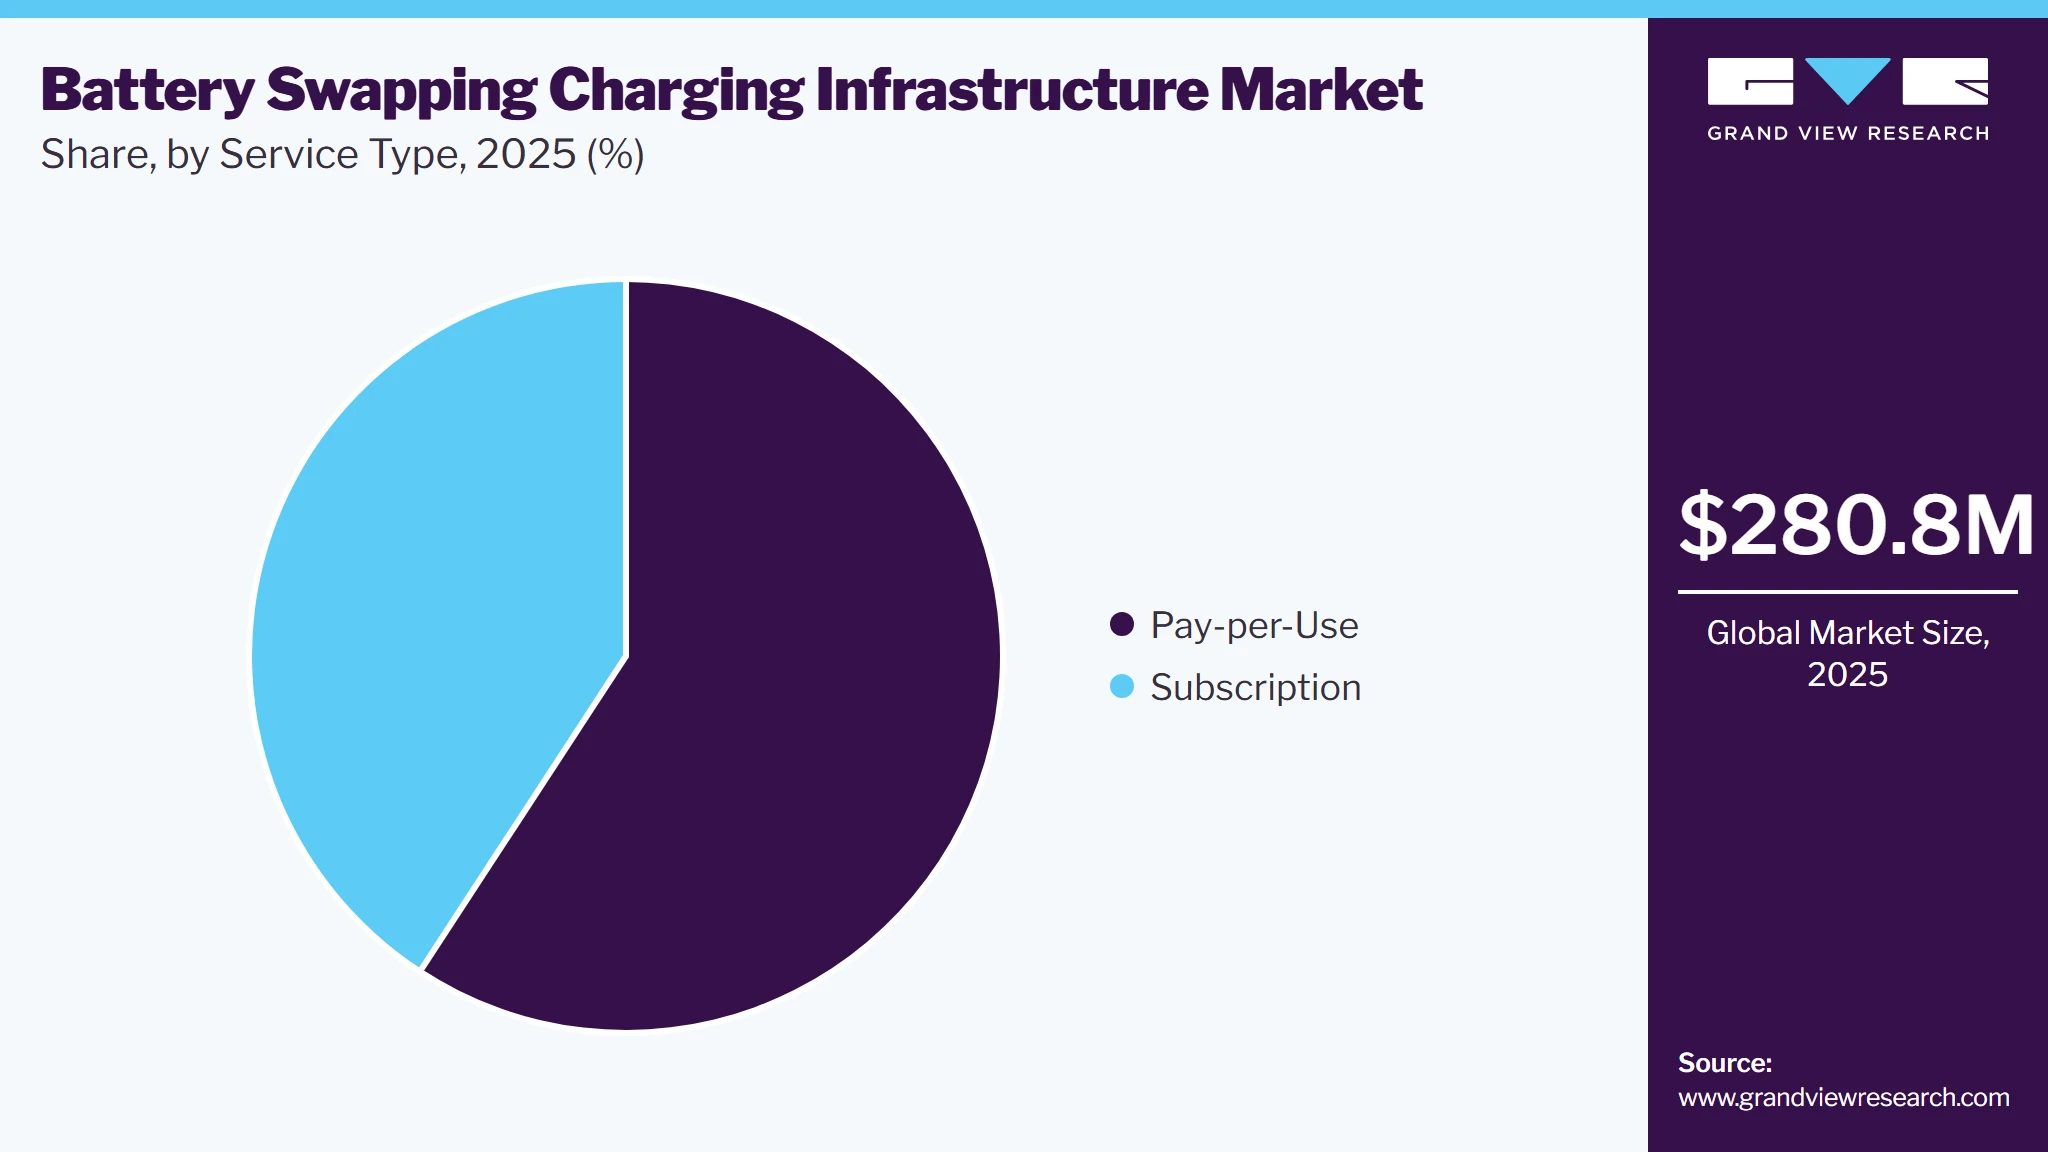
The subscription segment is expected to register the fastest CAGR during the forecast period. The subscription service segment allows electric vehicle users to subscribe to battery-as-a-service and opt for battery swapping at the swap station at pre-determined subscription prices. Governments across the globe are taking initiatives to increase the adoption of subscription battery-swapping charging infrastructure. For instance, in August 2022, the South Korean government announced that it would revise the law to allow battery subscription services for electric vehicles, reducing the upfront cost of electric vehicles by almost one-third. Such initiatives are expected to drive the segment's growth over the forecast period.
Regional Insights
North America battery swapping charging infrastructure industry held a significant share in 2024. Supportive government policies and incentives promoting EV adoption are indirectly driving the growth of battery swapping infrastructure. Federal and state governments in the U.S. and Canada are investing heavily in EV-related infrastructure development, including subsidies for battery technologies and grants for innovative charging solutions. Programs aimed at reducing greenhouse gas emissions and improving urban air quality further accelerate the demand for efficient charging alternatives like battery swapping and drive the growth of the battery swapping charging infrastructure industry.
U.S. Battery Swapping Charging Infrastructure Market Trends
The battery swapping charging infrastructure market in the U.S. held a dominant position in 2024 due to the growth of shared mobility services, such as ride-hailing and car-sharing platforms. It is boosting the need for efficient charging solutions. Battery swapping is particularly beneficial for these services as it enables quick turnarounds and ensures high fleet utilization.
Europe Battery Swapping Charging Infrastructure Market Trends
The battery swapping charging infrastructure market in Europe was identified as a lucrative region in 2024. The presence of stringent regulations and aggressive targets for reducing greenhouse gas emissions drives the growth of the industry. These regulatory measures have accelerated the shift to EVs, creating a need for robust charging infrastructure. Battery swapping aligns with these goals by promoting faster and more sustainable EV adoption, particularly in commercial and public transportation sectors.
The UK battery swapping charging infrastructure industry is expected to grow rapidly in the coming years due to the government mandates to phase out internal combustion engine (ICE) and incentives for EV buyers. While plug-in charging is prevalent, battery swapping is gaining traction as it addresses two critical EV challenges: range anxiety and long charging durations.
The battery swapping charging infrastructure market in Germany held a substantial market share in 2024, owing to the presence of the automotive industry in the country. Automakers and battery technology companies are collaborating to develop standardized battery packs and modular systems that support interoperability. This focus on innovation ensures the scalability and efficiency of battery swapping solutions and drives the growth of the industry.
Asia Pacific Battery Swapping Charging Infrastructure Market Trends
Asia Pacific dominated the global battery swapping charging infrastructure market with the largest revenue share of 30.9% in 2025. The growing EV adoption in the region, particularly in markets such as China, India, and Southeast Asia, is fueling the growth of the industry. In addition, the growth is fueled by government incentives, increasing consumer awareness about sustainable transportation, and the need to reduce dependency on fossil fuels. The battery swapping charging infrastructure market in the China held the largest share in the Asia Pacific region in 2025.

Japan battery swapping charging infrastructure market is expected to grow rapidly over the forecast period. Japan's densely populated urban areas and efficient public transport systems present an ideal environment for battery swapping, especially for commercial vehicles. Fleets involved in last-mile delivery, public transportation, and ride-hailing services benefit significantly from reduced charging downtime and operational costs enabled by battery swapping technology.
The battery swapping charging infrastructure market in China held a substantial market share in 2024 owing to rapid urbanization has increased demand for sustainable and efficient mobility solutions. Battery swapping stations, which require less space than traditional charging infrastructure, are particularly well-suited for densely populated urban centers. They also help mitigate grid strain by enabling pre-charged batteries to be swapped during non-peak hours, reducing energy demand spikes.
Key Battery Swapping Charging Infrastructure Company Insights
Some of the key companies in the battery swapping charging infrastructure market include NIO Inc., SUN Mobility Private Ltd., BYD Co. Ltd., Gogoro Inc., and others. Organizations are focusing on increasing customer base to gain a competitive edge in the industry. Therefore, key players are taking several strategic initiatives, such as mergers and acquisitions, and partnerships with other major companies.
-
NIO Inc. is a Chinese multinational automobile manufacturer specializing in the design and development of premium electric vehicles (EVs). It offers battery-swapping technology, which allows users to exchange depleted batteries for fully charged ones in a matter of minutes, enhancing convenience and reducing range anxiety. The company operates over 1,300 battery swap stations across China and has plans to expand internationally.
-
Gogoro Inc. is a battery-swapping technology company customized for urban electric scooters, mopeds, and motorcycles. The company operates the Gogoro Energy Network, a modular battery-swapping infrastructure that allows riders to quickly exchange depleted batteries at designated GoStations for a subscription fee. In addition to its operations in Taiwan, Gogoro is expanding internationally with initiatives in countries such as India and Indonesia, aiming to promote sustainable urban mobility solutions globally.
Key Battery Swapping Charging Infrastructure Companies
The following key companies have been profiled for this study on the battery swapping charging infrastructure market.
-
NIO Inc.
-
Gogoro Inc.
-
Leo Motors Inc.
-
Yadea Technology Group Co., Ltd.
-
SUN Mobility Private Ltd.
-
BYD Co. Ltd.
-
BattSwap Inc.
-
Kwang Yang Motor Co. Ltd. (KYMCO)
-
Panasonic Corp.
-
Lithion Power Pvt. Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (NIO Inc., Gogoro Inc., BYD Co. Ltd., Kwang Yang Motor Co. Ltd.)
- These players are focused on large-scale network deployment, OEM integration, and proprietary swapping ecosystems
- These players have strong capital bases, technology ownership, and brand-backed vehicle compatibility
- High capital intensity and limited cross-brand interoperability
Emerging Players (SUN Mobility Private Ltd., Lithion Power Pvt. Ltd., BattSwap Inc.)
- These players are focused on localized deployments, fleet partnerships, and modular platforms
- Agility, regional market understanding, and service-led models
- Limited scale, funding constraints, and dependence on standardization progress
Recent Developments
-
In December 2024, SUN Mobility launched modular battery-swapping technology designed for heavy electric vehicles (HEVs). The solution was showcased during a workshop in Chennai, attended by over 100 private bus operators from Tamil Nadu. Technology aims to address significant challenges faced by commercial fleet operators, such as high initial costs, inadequate charging infrastructure, and prolonged downtime associated with traditional charging methods.
-
In November 2024, Honda Power Pack Energy India Private Ltd (HEID) announced an ambitious plan to establish 500 battery-swapping stations across three major Indian cities, including Bengaluru, Delhi, and Mumbai, by March 2026. This initiative is part of the launch of Honda's e:Swap service, which aims to enhance the accessibility and convenience of electric two-wheelers, particularly the newly introduced Honda Activae.
Battery Swapping Charging Infrastructure Market Report Scope
Report Attribute
Details
Market size in 2025
USD 280.8 million
Estimated market size in 2026
USD 333.6 million
Projected market size by 2033
USD 1,882.8 million
Growth rate
CAGR of 28.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Vehicle type, service type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
NIO Inc.; Gogoro Inc.; Leo Motors Inc.; Yadea Technology Group Co.,Ltd.; SUN Mobility Private Ltd.; BYD Co. Ltd.; BattSwap Inc.; Kwang Yang Motor Co. Ltd. (KYMCO); Panasonic Corp.; Lithion Power Pvt. Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Battery Swapping Charging Infrastructure Market Report Segmentation
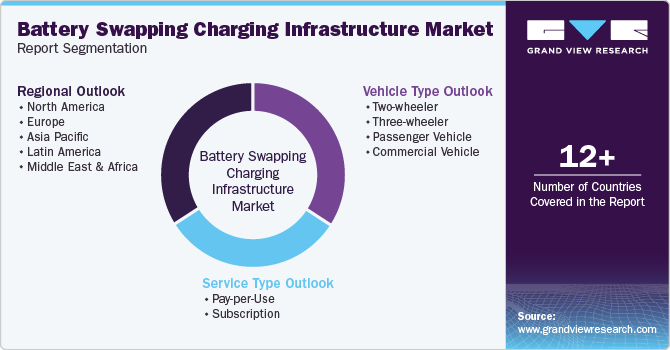
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global battery swapping charging infrastructure market report based on vehicle type, service type, and region.
-
Vehicle Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Two-wheeler
-
Three-wheeler
-
Passenger Vehicle
-
Commercial Vehicle
-
-
Service Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Pay-per-Use
-
Subscription
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Netherlands
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
Research Methodology
The battery swapping charging infrastructure market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each battery swapping charging infrastructure segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Vehicle Type
Revenue capture definition
Two-Wheeler
Revenue from battery swapping fees, subscription plans, and battery leasing services associated with electric scooters and motorcycles.
Three-Wheeler
Revenue generated through swap transactions, fleet contracts, and service agreements for electric autorickshaws and cargo three-wheelers.
Passenger Vehicle
Revenue from BaaS subscriptions, swap station access fees, and integrated mobility service contracts for electric cars.
Commercial Vehicle
Revenue from long-term fleet agreements, high-frequency swapping services, and energy management solutions for delivery vans and logistics vehicles.
Segment – Service Type
Revenue capture definition
Pay-per-Use
Revenue earned through one-time or variable charges for each battery swap, typically including energy cost, infrastructure usage fees, and service margins, with billing based on actual swap frequency without long-term customer commitment.
Subscription
Recurring revenue generated through fixed-period plans (monthly, quarterly, or annual) that provide users with bundled swap entitlements or unlimited swaps, often combined with battery leasing, maintenance, and software services under predictable, contract-based pricing models.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Vehicle Base Assessment
How many EVs are compatible with swapping?
This layer evaluates the installed and active base of EVs designed or retrofitted for battery swapping. It considers vehicle type distribution, fleet concentration, and OEM participation. Compatibility rates directly influence addressable infrastructure demand.
02
Infrastructure Density Mapping
How many swapping stations are required?
This layer estimates optimal station density based on vehicle utilization rates, urban traffic patterns, and average daily swaps. It accounts for geographic clustering and fleet operating zones.
03
Service Monetization
How is revenue generated per vehicle?
This layer of models’ revenue streams from pay-per-use swaps, subscriptions, and fleet contracts. Pricing structures and swap frequency assumptions are key inputs.
04
Ecosystem Scaling
How does the market scale over time?
This layer captures expansion dynamics, including network effects, standardization progress, and regulatory support. It reflects how utilization rates improve as ecosystems mature.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Battery Swapping Charging Infrastructure Market Opportunity Assessment
Country/region-wise market sizing and forecasts
Analysis of demand, adoption trends, and regulatory landscape
Identification of high-growth regions and investment hotspots
Identified region-specific growth opportunities
Supported expansion and go-to-market strategy
Enabled informed regional investment decisions
Cross-Segmentation Analysis for the Battery Swapping Charging Infrastructure Market
Criss-cross market analysis by vehicle type and service type
Demand and adoption assessment across key segments
Segment attractiveness and growth potential benchmarking
Identified high-potential market segments
Supported targeted product positioning and marketing strategy
Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the Battery Swapping Charging Infrastructure Market
Benchmarking of key competitors across products, pricing, partnerships, and innovation
Comparative assessment of market share, capabilities, and strategies
Analysis of competitive strengths, gaps, and differentiation areas
Identified competitive white spaces and growth gaps
Supported strategic positioning and differentiation
Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
The global battery swapping charging infrastructure market size was estimated at USD 280.8 million in 2025 and is expected to reach USD 333.6 million in 2026.
The global battery swapping charging infrastructure market is expected to grow at a compound annual growth rate of 28.0% from 2026 to 2033, reaching USD 1,882.8 million by 2033.
Some key players operating in the battery swapping charging infrastructure market include NIO Inc.; Gogoro Inc.; Leo Motors Inc.; Yadea Technology Group Co.,Ltd.; SUN Mobility Private Ltd.; BYD Co. Ltd.; BattSwap Inc.; Kwang Yang Motor Co. Ltd. (KYMCO); Panasonic Corp.; Lithion Power Pvt. Ltd.
Asia Pacific dominated the market with the largest revenue share of 30.9% in 2025. The growing EV adoption in the region, particularly in markets such as China, India, and Southeast Asia, is fueling the growth of the industry.
Pay-per-Use segment held the largest market share in 2025, while subscription is the fastest growing segment.
The China held the largest market share in 2025.
The battery swapping charging infrastructure market is driven by the growing need to minimize electric vehicle downtime by enabling faster energy replenishment compared to conventional charging methods.
Two-Wheeler segment dominated the market, with a revenue share of 31.2% in 2025. The cost-effectiveness offered by the battery swapping technology drives the growth of the industry.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs — add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


