
- Home
- »
- Petrochemicals
- »
-
Benzene Market Size, Share & Growth Report, 2026-2033GVR Report cover

Benzene Market (2026 - 2033)
Size, Share & Trends Analysis Report Derivative By End-use, By Production Process (Catalytic Reforming), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$54.3BMarket Estimate, 2026
$57.6BMarket Forecast, 2033
$93.0BCAGR, 2026–2033
7.1%Benzene Market Summary
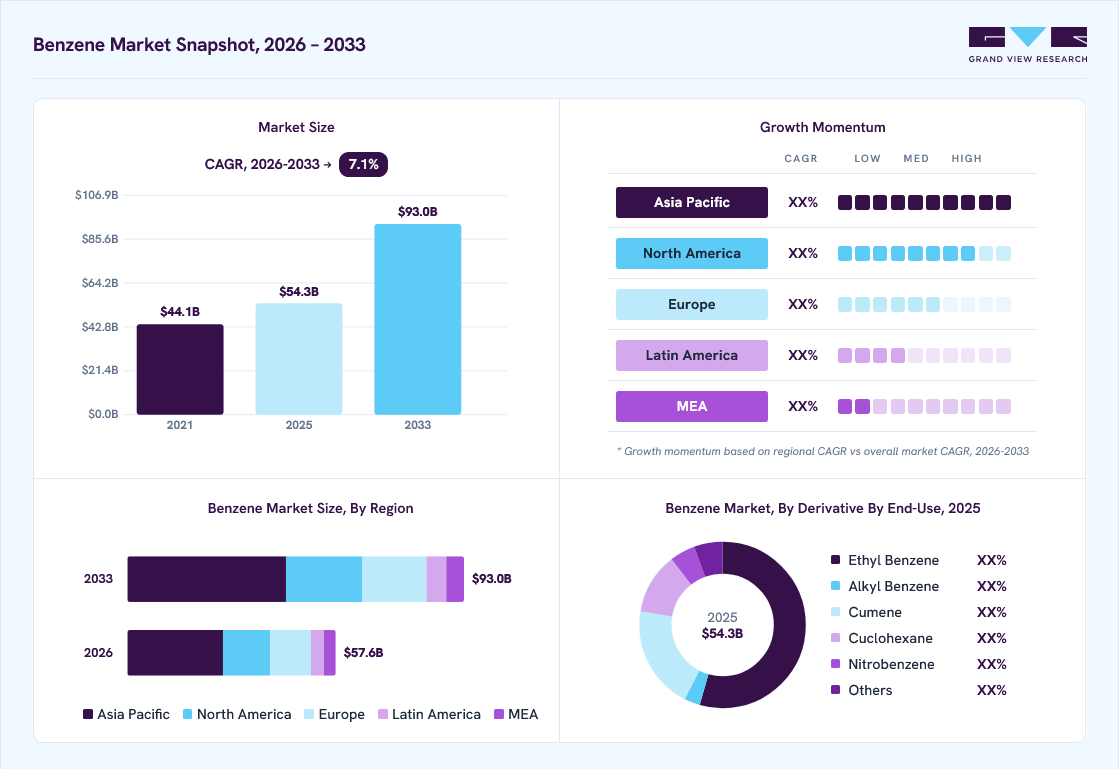
The global benzene market size was valued at USD 54.3 billion in 2025 and is projected to grow from USD 57.6 billion in 2026 to USD 93.0 billion by 2033, at a CAGR of 7.1% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 45.7% in 2025. The increasing demand for styrene in various end-use industries such as packaging, automotive, electronics, and others is acting as a major driving force for the continuously increasing demand for benzene.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By derivative by end-use: Ethyl benzene segment held the largest market share of 54.4% in 2025.
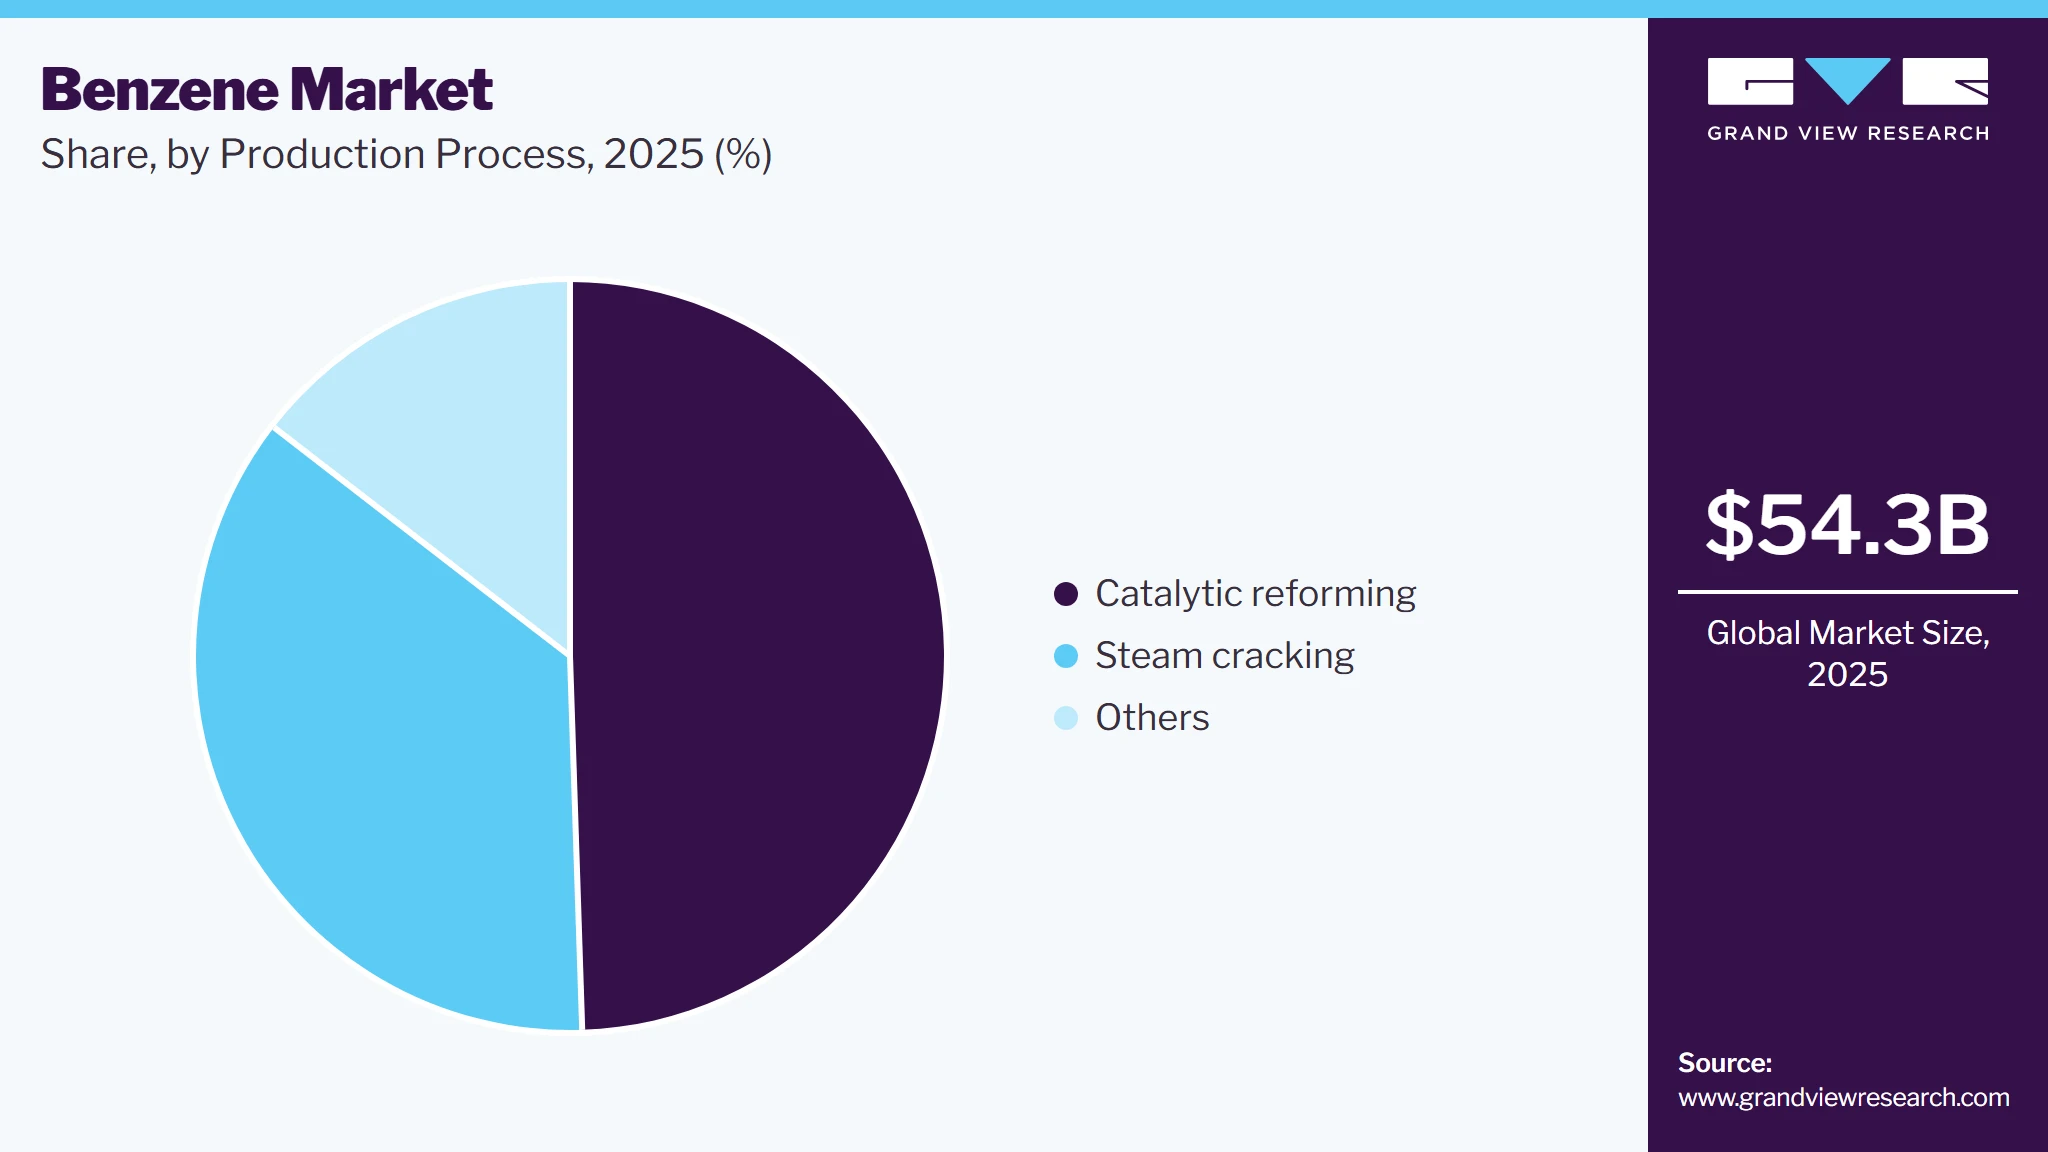
- By production process: Catalytic reforming segment held the largest market share of 49.5% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (45.7% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 54.3 Billion
- Estimated market size in 2026: USD 57.6 Billion
- Projected market size by 2033: USD 93.0 Billion
- CAGR (2026-2033): 7.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Styrene, produced from benzene’s derivative ethylbenzene, is used in a wide range of industries. The majority of the product goes into the production of polystyrene, which due to its flexibility, resilience, moisture resistance, and lightweight is used in the packaging industry.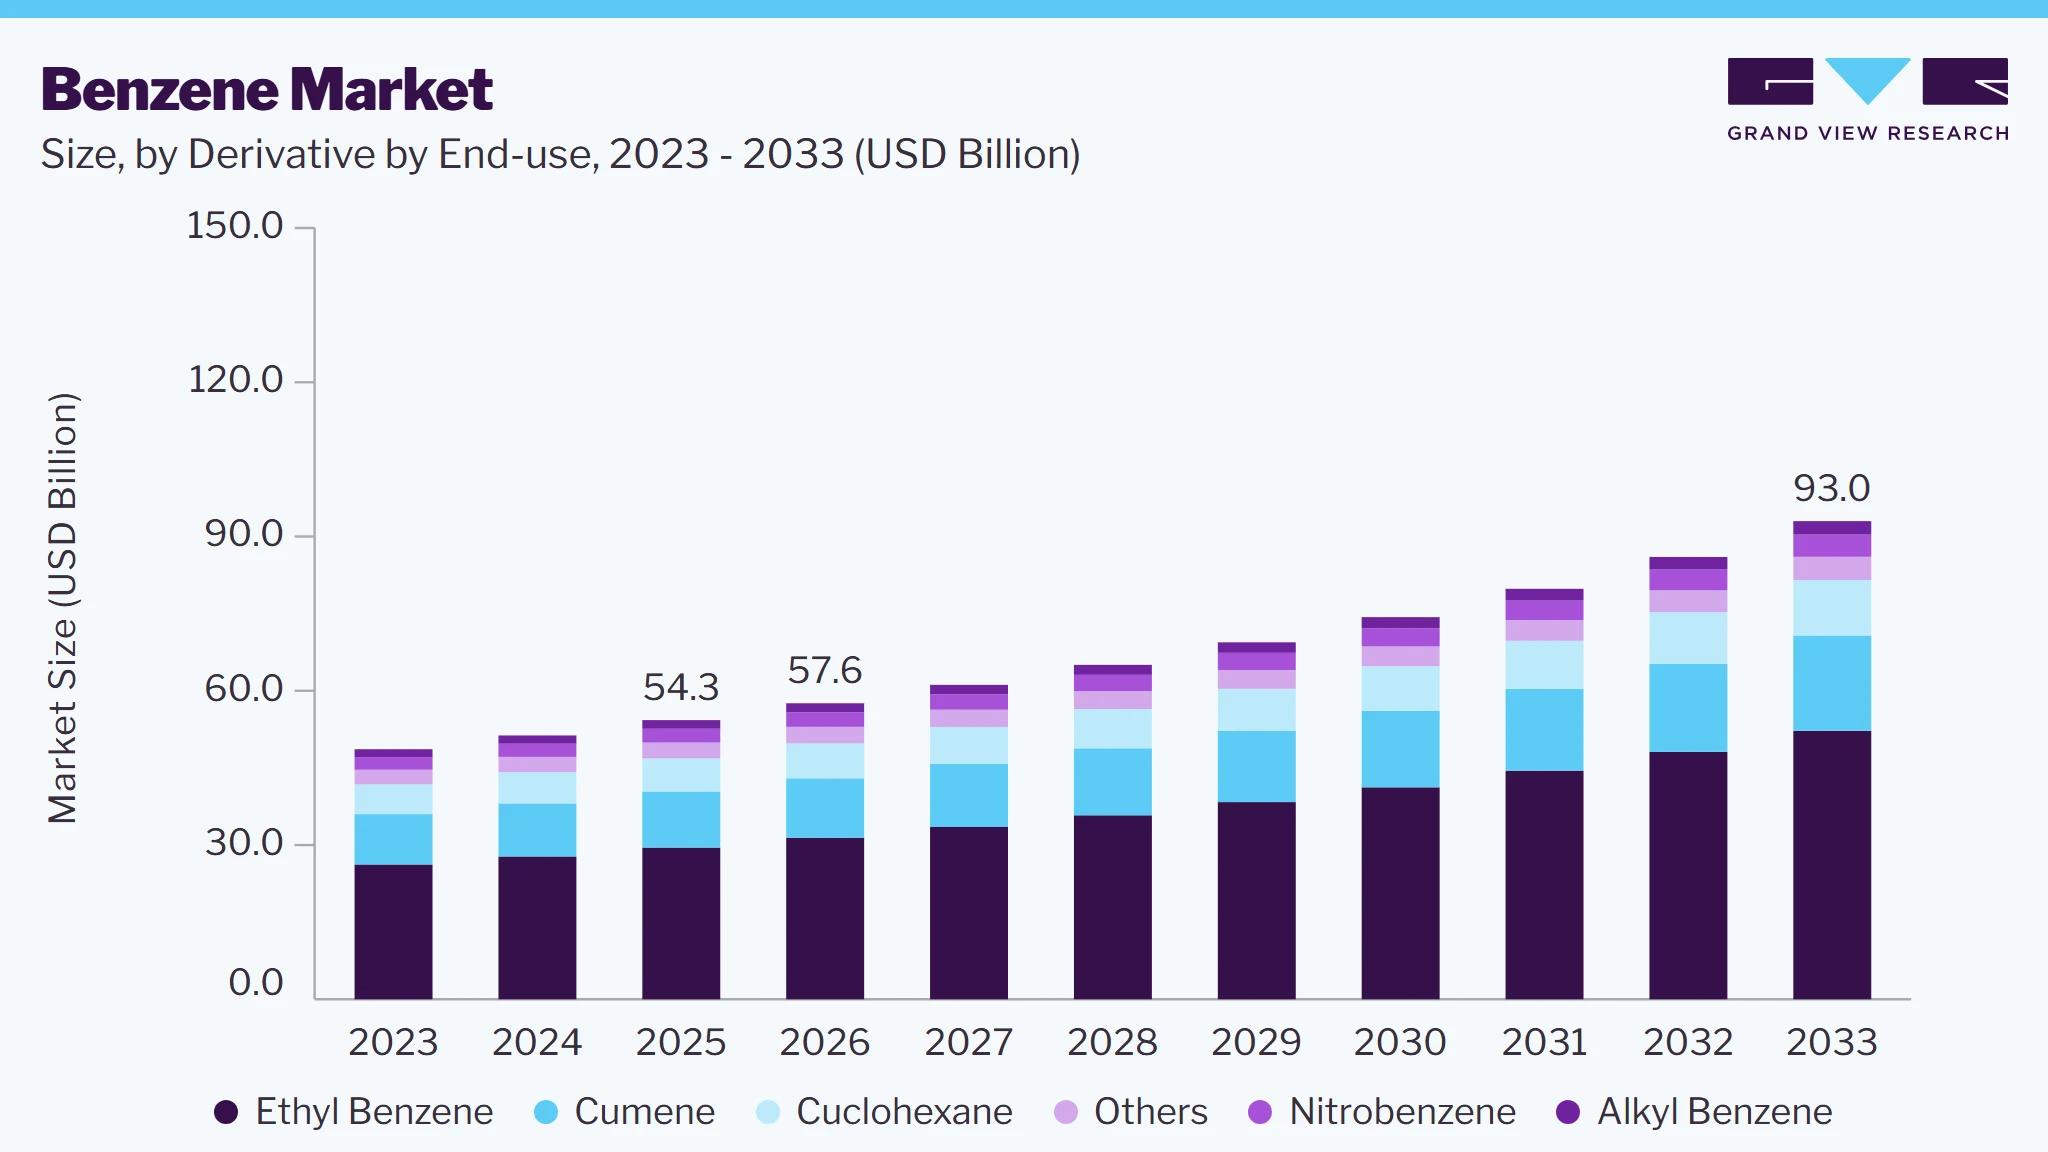 To learn more about this report, Download Free Sample Report
The automotive industry is increasing continuously with the introduction of a new range of electric vehicles has also resulted in an increase in demand for benzene as styrene is used in the production of tires and several body parts of both diesel or gasoline-powered vehicles and electric vehicles.
According to Niti Aayog, India is among the fastest-growing country in the automotive sector witnessing a compounded annual growth rate of 4% from 2011 to 2020. Additionally, according to the National Bureau of Statistics of China in 2020, tire production in the country reached to 807.47 million. Thus, this increasing demand for automobiles in different countries is resulting in an increase in demand for benzene.
 To learn more about this report, Download Free Sample Report
The U.S. is the largest consumer of benzene in North America. The market for the product is expected to grow significantly over the forecast period owing to the increasing demand from expanding petrochemical sector. Benzene is used as a feedstock in the petrochemical industry for the production of different chemicals such as resin, plastic, synthetic fibers, and nylon by using different methods such as steam cracking or catalytic reforming of crude oil.
According to the International Energy Agency (IEA) in 2018, the U.S. is home to around 40% of petrochemical production. Thus, the increasing petrochemical industry in the U.S. and North America as a whole as well as the availability of crude oil is acting as a driving factor for increasing the demand for benzene in the region.
Market Dynamics
The benzene market is witnessing steady growth, driven by increasing demand from the petrochemical, automotive, construction, pharmaceutical, and chemical industries. Benzene serves as a critical feedstock to produce styrene, phenol, cyclohexane, aniline, alkylbenzene, and other specialty chemicals. Rising demand for plastics, synthetic fibers, detergents, coatings, and performance materials is supporting market expansion. Additionally, growing industrialization, infrastructure development, and investments in chemical manufacturing capacity across emerging economies are contributing to the long-term growth of the benzene market.
The increasing consumption of benzene-derived chemicals such as styrene, phenol, and cyclohexane is a major driver for market growth. Styrene-based products, including polystyrene, ABS resins, and styrene-butadiene rubber, are witnessing strong demand from packaging, automotive components, electronics, and construction applications. Similarly, phenol derivatives are widely used in resins, adhesives, and coatings. Expanding automotive production, rising demand for lightweight materials, and growth in consumer goods manufacturing are accelerating the consumption of benzene-based intermediates globally.
Stringent environmental and occupational safety regulations related to benzene handling and emissions are creating challenges for market participants. Benzene is classified as a hazardous chemical due to its potential health risks, leading to strict compliance requirements across production facilities. Regulatory pressure to reduce emissions, improve workplace safety, and adopt cleaner production processes may increase operational costs for manufacturers. Fluctuations in crude oil prices and feedstock availability can impact benzene production costs and market profitability.
Expanding chemical manufacturing capabilities in emerging economies are creating significant growth opportunities for the benzene market. Increasing investments in petrochemical complexes, particularly across Asia-Pacific, the Middle East, and Latin America, are expected to strengthen benzene production and consumption. Rising demand for specialty chemicals, high-performance polymers, pharmaceuticals, and advanced materials is opening new application areas for benzene derivatives. Advancements in production technologies, including improved recovery processes and integration with refinery operations, are expected to enhance supply efficiency and support future market growth.
Analyst Perspective
The global benzene market is positioned for steady growth, driven by rising demand from the petrochemical, automotive, construction, packaging, and consumer goods industries. Benzene is a key feedstock to produce ethylbenzene, cumene, cyclohexane, linear alkylbenzene, nitrobenzene, and other chemical intermediates. The ethylbenzene segment remains the largest application area, supported by its extensive use in the production of styrene monomers, which is further utilized in polystyrene, ABS resins, synthetic rubber, and insulation materials. Additionally, increasing demand for plastics, synthetic fibers, detergents, engineering polymers, and polyurethane products, coupled with expanding petrochemical capacity and industrialization in emerging economies, continues to support the long-term growth of the benzene market.
Derivative By End-use Insights
Ethyl benzene segment dominated the product segment with a market share of 54.4% in 2025. This is attributed to its application in several growing end-use industries such as automobile, plastic, rubber, electronics, and others. Ethyl benzene is used for the production of a majority of styrene that finds its usage in the manufacturing of rubber tires, plastic packaging, several automobile parts (instrumental panels, knobs, trim, energy absorbing door panels, and sound dampening foam), and electronic equipment. Thus, all these factors contribute to the increasing demand for ethylbenzene.
Cumene is another fastest-growing derivative which accounted for the second-largest revenue share followed by ethylbenzene. This is attributed to its major application in end-use industries such as pharmaceutical, packaging, automobile, paints & coatings, and others with pharmaceuticals capturing the major share. Phenol and acetone produced from Cumene are used in pharmaceutical products as a solvent in fillers, to sterilize medical equipment, and as a disinfectant in antiseptics.
Production Process Insights
The catalytic reforming segment dominated the market with the largest revenue share of 49.5% in 2025. This is attributed to an increase in the usage of low octane straight run naphtha containing the naphthenes for the production of low-sulfur fuel used in gasoline and high-octane aromatic benzene. Additionally, catalytic reforming provides hydrogen which is further used for producing clean fuels by hydroprocessing units.
 To learn more about this report, Download Free Sample Report
Steam cracking is another production process capturing the second largest market share followed by catalytic reforming. This method is used as it uses naphtha or gas oil fraction as a feedstock along with some hydrocarbons such as propane and butane. It cuts out the expensive process of distillation needed and produces a wider range of products. However, it is not suitable for bulk production.
Regional Insights
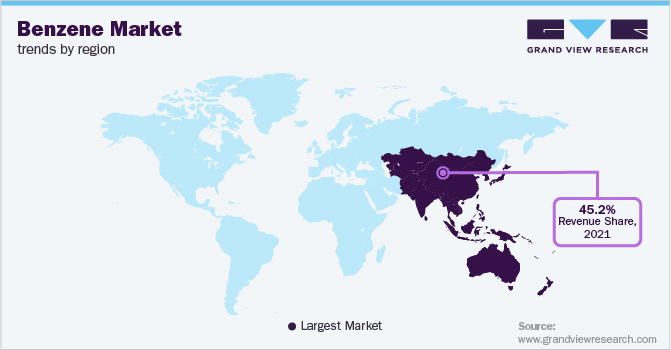
Asia Pacific accounted for 45.7% of the benzene market revenue in 2025, making it the largest regional market. This is attributed to the expanding end-use industries such as the chemical industry, packaging, automobile, pharmaceutical, and others in the region. According to International Institute for Sustainable Development (IISD) in 2021, the chemical industry in the Asia Pacific accounted for around 45% of global chemical manufacturing and 7% of global GDP.
 To learn more about this report, Download Free Sample Report
The major consumers and producers of benzene in the Asia Pacific are China, India, South Korea, and Japan. China is among the major consumer of benzene with imports amounting to USD 2,785,449 thousand whereas, South Korea accounted for major export amounting to USD 2,254,945 thousand in 2021. The increase in demand and import in China is due to the increasing usage of benzene in construction and automobile products such as paints, flooring, fiberglass, adhesives, tires, and others. According to the National Bureau of Statistics in China in 2021, the construction output of China accounted for around USD 4,091 Billion. Thus, the increasing end-use industries in the country are further driving the demand for the product.
North America is also expected to witness growth during the forecast period due to the increasing packaging, petrochemical, and pharmaceutical industries which are the major end users of the product. According to the U.S. Department of Health & Human Services, benzene is widely used and ranked among the top 20 chemicals for production volume in the country.
Europe is also anticipated to witness growth but at a relatively slower rate compared to North America and Asia Pacific due to tightening government regulations for use of benzene or its derivatives in consumer goods. For instance, the regulations imposed by the European Chemicals Agency (ECHA) and other organizations prohibiting the marketing and use of benzene in case it is present in mixtures or other substances at or above a concentration of 0.1% by weight are acting as a restraining factor in the growth of benzene in the region.
Key Companies & Market Share Insights
The market is highly competitive with the presence of some major industry players dominating the market. The market is characterized by the adoption of various strategic initiatives such as increasing production capacity, and technology partnerships to gain a competitive edge. For instance, companies such as Hengyi Petrochemical, in 2021, announced to set up a naphtha cracker that will add 80,000 TPA benzene capacity along with other products. This expansion will result in strengthening the position of the company.
Key Benzene Companies
The following key companies have been profiled for this study on the benzene market.
-
Dow
-
INEOS Group
-
LyondellBasell Industries Holdings B.V.
-
BASF SE
-
Royal Dutch Shell Plc
-
Reliance Industries Limited
-
Chevron Phillips Chemical Company LLC
-
China Petrochemical Corporation
-
Marathon Petroleum Corporation
-
LG Chem
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (ExxonMobil Corporation; INEOS Group; LyondellBasell Industries Holdings B.V.; BASF SE; Shell plc; Reliance Industries Limited; Chevron Phillips Chemical Company LLC; China Petrochemical Corporation; Marathon Petroleum Corporation; LG Chem)
- Expand integrated refinery and petrochemical capacities to increase benzene production.
- Invest in catalytic reforming, steam cracking, and process efficiency technologies.
- Secure long-term feedstock supply and downstream integration with styrene, phenol, cyclohexane, and LAB production.
- Strengthening global distribution through strategic partnerships, capacity expansions, and acquisitions.
- Vertically integrated operations ensure reliable feedstock availability and cost advantages.
- Large-scale production facilities with advanced refining and petrochemical technologies.
- Strong global distribution networks and long-term customer relationships.
- Robust financial resources supporting capacity expansion and sustainability initiatives.
- High dependence on crude oil and naphtha price fluctuations.
- Stringent environmental regulations and carbon reduction requirements increase compliance costs.
- Capital-intensive operations require significant ongoing investments.
- Exposure to cyclical demand from automotive, construction, and petrochemical industries.
Emerging & Regional Players (Rain Carbon Inc.; Epsilon Carbon Private Limited; JFE Chemical Corporation; Koppers Inc.; PCC Rokita SA; Química del Nalón S.A.; CARBOTECH; DEZA a.s.; Dong-Suh Chemical Ind. Co., Ltd.)
- Focus on regional supply of industrial-grade benzene and niche derivative markets.
- Improve cost competitiveness through efficient production and localized supply chains.
- Expand partnerships with regional chemical manufacturers and distributors.
- Invest in product quality enhancements and specialty-grade offerings.
- Greater flexibility in serving regional customers and customized requirements.
- Competitive pricing is supported by localized operations.
- Faster response to changing regional demand.
- Strong relationships with local downstream industries.
- Limited production capacity relative to global integrated producers.
- Smaller international distribution networks.
- Lower investment capability for major technology upgrades and capacity expansions.
- Greater vulnerability to feedstock supply disruptions and regional market volatility.
Benzene Market Report Scope
Report Attribute
Details
Market size in 2025
USD 54.3 billion
Estimated market size in 2026
USD 57.6 billion
Projected market size by 2033
USD 93.0 billion
Growth rate
CAGR of 7.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in Kilotons, Revenue in USD Billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Derivative by end-use, production process, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; Italy; Spain; Netherland; Belgium; China; India; Japan; Thailand; South Korea; Malaysia; Brazil; Argentina; South Africa; Saudi Arabia
Key companies profiled
Dow, INEOS Group; LyondellBasell Industries Holdings B.V.; BASF SE; Royal Dutch Shell Plc; Reliance Industries Limited; Chevron Phillips Chemical Company LLC; China Petrochemical Corporation; Marathon Petroleum Corporation; LG Chem
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Benzene Market Report Segmentation
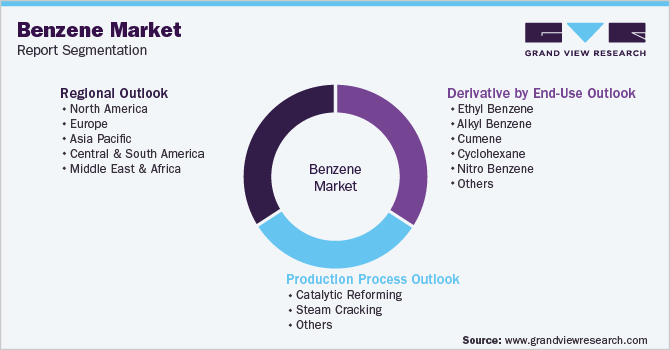
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global benzene market report based on derivative by end-use, production process, and region:
 To learn more about this report, Download Free Sample Report
-
Derivative by End-Use (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Ethyl Benzene
-
Packaging
-
Automobile
-
Others (ink & paints, agriculture, pharmaceutical)
-
-
Alkyl Benzene
-
Personal care (Surfactants)
-
Others (paint industry, ink solvent, agriculture herbicide)
-
-
Cumene
-
Pharmaceutical
-
Cosmetics
-
Automobile
-
Packaging
-
Paints & Coatings
-
Others (electronics, agriculture, cleaners, solvents)
-
-
Cyclohexane
-
Textile
-
Automobile
-
Thermoplastic
-
Others (solvent, paint & coatings)
-
-
Nitro Benzene
-
Agriculture
-
Pharmaceuticals
-
Others (rubber, paint, dyes, leather)
-
-
Others (Maleic Anhydride, Methylbenzoate)
-
Food additive
-
Surfactant
-
Personal care
-
Others (agriculture, paints & coatings, pharmaceutical)
-
-
-
Production Process (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Catalytic reforming
-
Steam cracking
-
Others (Toluene hydrodealkylation, Toluene disproportionation)
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
Netherland
-
Belgium
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Thailand
-
South Korea
-
Malaysia
-
-
Central and South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
-
Research Methodology
The benzene market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each benzene segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Derivative by End-use
Revenue capture definition
Ethyl Benzene
Captures revenue generated from benzene used in the production of ethylbenzene, a key intermediate for manufacturing styrene monomer used in polystyrene, ABS resins, synthetic rubber, and insulation materials.
Alkyl Benzene
Represents revenue from benzene consumed in the production of linear alkylbenzene (LAB), primarily used in the manufacture of biodegradable household and industrial detergents and surfactants.
Cumene
Accounts for revenue associated with benzene utilized in cumene production, which serves as the primary feedstock for manufacturing phenol and acetone used in resins, plastics, adhesives, and coatings.
Cyclohexane
Captures revenue generated from benzene used in cyclohexane production for manufacturing caprolactam and adipic acid, key intermediates in nylon 6 and nylon 6,6 production.
Nitrobenzene
Includes revenue from benzene consumed in the production of nitrobenzene, which is further processed into aniline for polyurethane foams, rubber chemicals, dyes, and pharmaceutical intermediates.
Others
Represents revenue generated from benzene used in the production of chlorobenzene, maleic anhydride, solvents, specialty intermediates, and other downstream petrochemical products.
Segment - Production Process
Revenue capture definition
Catalytic dehydrogenation
Accounts for revenue generated from benzene produced through catalytic reforming of petroleum naphtha, the primary commercial process supplying high-purity benzene for downstream petrochemical applications.
Steam cracking
Reflects revenue from benzene recovered as a co-product during steam cracking for ethylene production and subsequently supplied to manufacturers of styrene, phenol, cyclohexane, and other derivatives.
Others
Measures revenue derived from benzene produced through alternative processes such as toluene hydrodealkylation, toluene disproportionation, and coal tar extraction for use in various industrial and chemical applications.
Estimation Model
Layer Name
Key Question
Description
Benzene Production Layer
What forms is the supply base?
Identify the global production capacity of benzene from catalytic reforming, steam cracking, toluene hydrodealkylation, and coal tar processing by evaluating feedstock availability, refinery and petrochemical capacities, production technologies, purity grades, and manufacturing facilities. This layer establishes the global supply base for downstream petrochemical and industrial applications.
Application Adoption Layer
Where are benzene utilized?
Estimate the distribution of benzene consumption across major derivatives including ethylbenzene, cumene, cyclohexane, linear alkylbenzene, nitrobenzene, chlorobenzene, and other specialty chemicals by analyzing downstream manufacturing demand and regional production patterns.
Consumption Intensity Layer
How much benzene is consumed?
Assess benzene consumption across end-use industries by evaluating production volumes of plastics, synthetic fibers, detergents, automotive components, construction materials, pharmaceuticals, and specialty chemicals to estimate annual benzene demand across major regional markets.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the sale of benzene of various purity grades to manufacturers of styrene, phenol, acetone, nylon intermediates, detergents, rubber chemicals, pharmaceuticals, coatings, and other petrochemical products through direct contracts, distributors, and integrated chemical supply chains.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
Detailed cross-segmentation assessment evaluating the relationship between derivative (Ethyl Benzene, Alkyl Benzene, Cumene, Cyclohexane, Nitrobenzene, and Others) and production process (Catalytic Reforming, Steam Cracking, and Others). The analysis identifies production trends, derivative demand patterns, feedstock utilization, and revenue contribution across each production process-derivative combination.
Supports production planning and portfolio optimization by identifying the most profitable production process-derivative combinations, enabling better capacity allocation, investment decisions, and supply chain strategies.
Competitive Benchmarking
Comparative evaluation of leading benzene manufacturers based on derivative portfolio, benzene production capacity, production technologies, feedstock integration, refinery and petrochemical integration, geographic presence, sustainability initiatives, and recent strategic developments across major regional markets.
Assists competitive intelligence and strategic decision-making by providing insights into market positioning, operational strengths, technological capabilities, and competitive advantages.
Opportunity Assessment
Comprehensive assessment of emerging opportunities across high-growth benzene derivatives (ethylbenzene, cumene, cyclohexane, and linear alkylbenzene), expanding petrochemical capacity, refinery integration projects, and increasing demand from plastics, synthetic fibers, detergents, automotive, and specialty chemical industries across key regional markets.
Helps identify high-growth derivatives, production technologies, and regional investment opportunities, supporting capacity expansion, product development, market entry strategies, and long-term revenue growth.
Frequently Asked Questions About This Report
Asia Pacific dominated the benzene market with a 45.7% share in 2025, driven by its large petrochemical manufacturing base, expanding downstream chemical industry, and strong demand from the plastics, automotive, and construction sectors.
Catalytic reforming dominated the market with a 49.5% share in 2025, owing to its widespread adoption in petroleum refineries for efficient, large-scale benzene production with high product purity.
Asia Pacific is expected to register the fastest growth during the forecast period, supported by expanding refinery and petrochemical investments, increasing downstream chemical production, and government-led industrial diversification initiatives.
Manufacturers are investing in energy-efficient refining technologies, emission reduction measures, carbon capture solutions, and improved process integration to lower the environmental footprint of benzene production while complying with increasingly stringent environmental regulations.
The global benzene market size was valued at USD 54.3 billion in 2025 and is estimated at USD 57.6 billion for 2026.
Some of the major players in the market include Dow, INEOS Group, LyondellBasell Industries Holdings B.V., BASF SE, Royal Dutch Shell Plc, Reliance Industries Limited, Chevron Phillips Chemical Company LLC, China Petrochemical Corporation, Marathon Petroleum Corporation, LG Chem
The increasing demand of styrene in various end-use industries such as packaging, automotive, electronics, and others is acting as a major driving force for the continuously increasing demand of benzene
The global benzene market is expected to grow at a CAGR of 7.1% from 2026 to 2033, reaching USD 93.0 billion by 2033.
The ethyl benzene segment dominated the global benzene market with a share of more than 54.4% in 2025.
About the Author(s)
Petrochemicals Research Team
Bulk Chemicals · PetrochemicalsThis report was authored by the petrochemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the petrochemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


