
- Home
- »
- Renewable Chemicals
- »
-
Bio-acetic Acid Market Size, Share & Trends Report, 2033GVR Report cover

Bio-acetic Acid Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Vinyl Acetate Monomer, Acetic Anhydride, Acetate Esters, Ethanol, Purified Terephthalic Acid), By Region (North America, Europe, Asia Pacific, Central & South America), And Segment Forecasts
Market Size, 2025
$237.6MMarket Estimate, 2026
$251.2MMarket Forecast, 2033
$385.1MCAGR, 2026–2033
6.3%Bio-acetic Acid Market Summary
The global bio-acetic acid market size was valued at USD 237.6 million in 2025 and is projected to grow from USD 251.2 million in 2026 to USD 385.1 million by 2033, at a CAGR of 6.3% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 46.9% in 2025. The growth is attributed to rising demand for eco-friendly, sustainable alternatives to traditional petrochemical-based products.
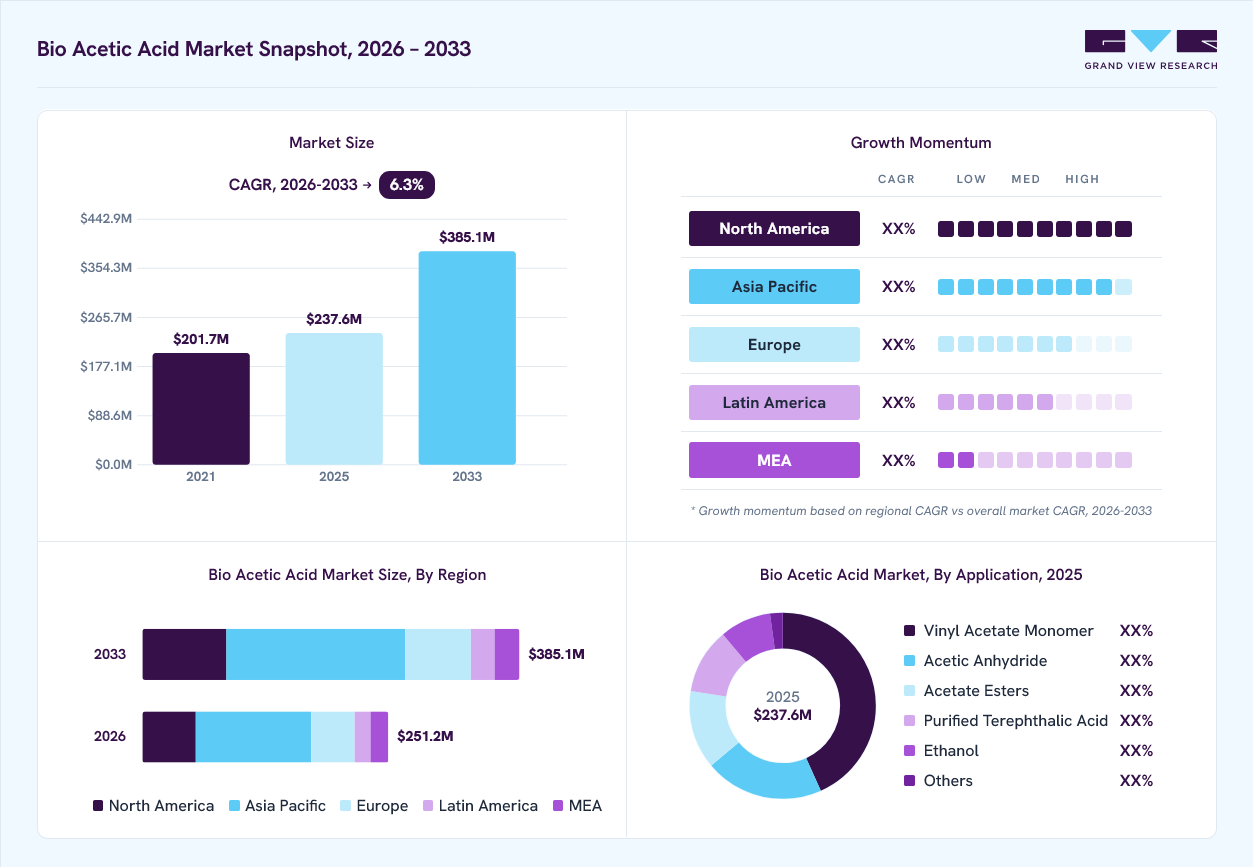 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Vinyl acetate monomer held a dominant position, contributing 43.2% of total revenue in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (46.9% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 237.6 Million
- Estimated market size in 2026: USD 251.2 Million
- Projected market size by 2033: USD 385.1 Million
- CAGR (2026-2033): 6.3%
Prism AI by Grand View Research Free to tryAsk a question about the bio-acetic acid marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Bio-acetic acid is a renewable alternative to petroleum-based acetic acid, used in a wide range of applications, including polymer production, textiles, and solvents. The growing awareness and focus on reducing the carbon footprint and environmental impact of various industries have led to a shift towards sustainable and eco-friendly production processes, driving demand for bio-based products such as bio-acetic acid.The growing focus on product safety, regulatory compliance, and clean-label formulations is driving the use of bio-based chemicals across the food, pharmaceutical, personal care, and specialty chemical industries. Bio-acetic acid and its byproducts, like acetate esters and acetic anhydride, are becoming popular as sustainable alternatives to traditional petrochemical ingredients. Manufacturers are investing more in green chemistry technologies to reduce environmental harm while improving production efficiency and product quality. This trend is driven by rising consumer interest in naturally sourced ingredients and by stricter sustainability goals across industries. For instance, in February 2025, thyssenkrupp Uhde and Novonesis launched a new enzymatic esterification technology to produce bio-based esters for food, personal care, and technical applications. This technology aims to cut energy use and improve product quality, reflecting the industry’s growing commitment to sustainable acetate production. These advancements are likely to create new growth opportunities for bio-acetic acid manufacturers by broadening the use of renewable acetate-based chemicals in different sectors.
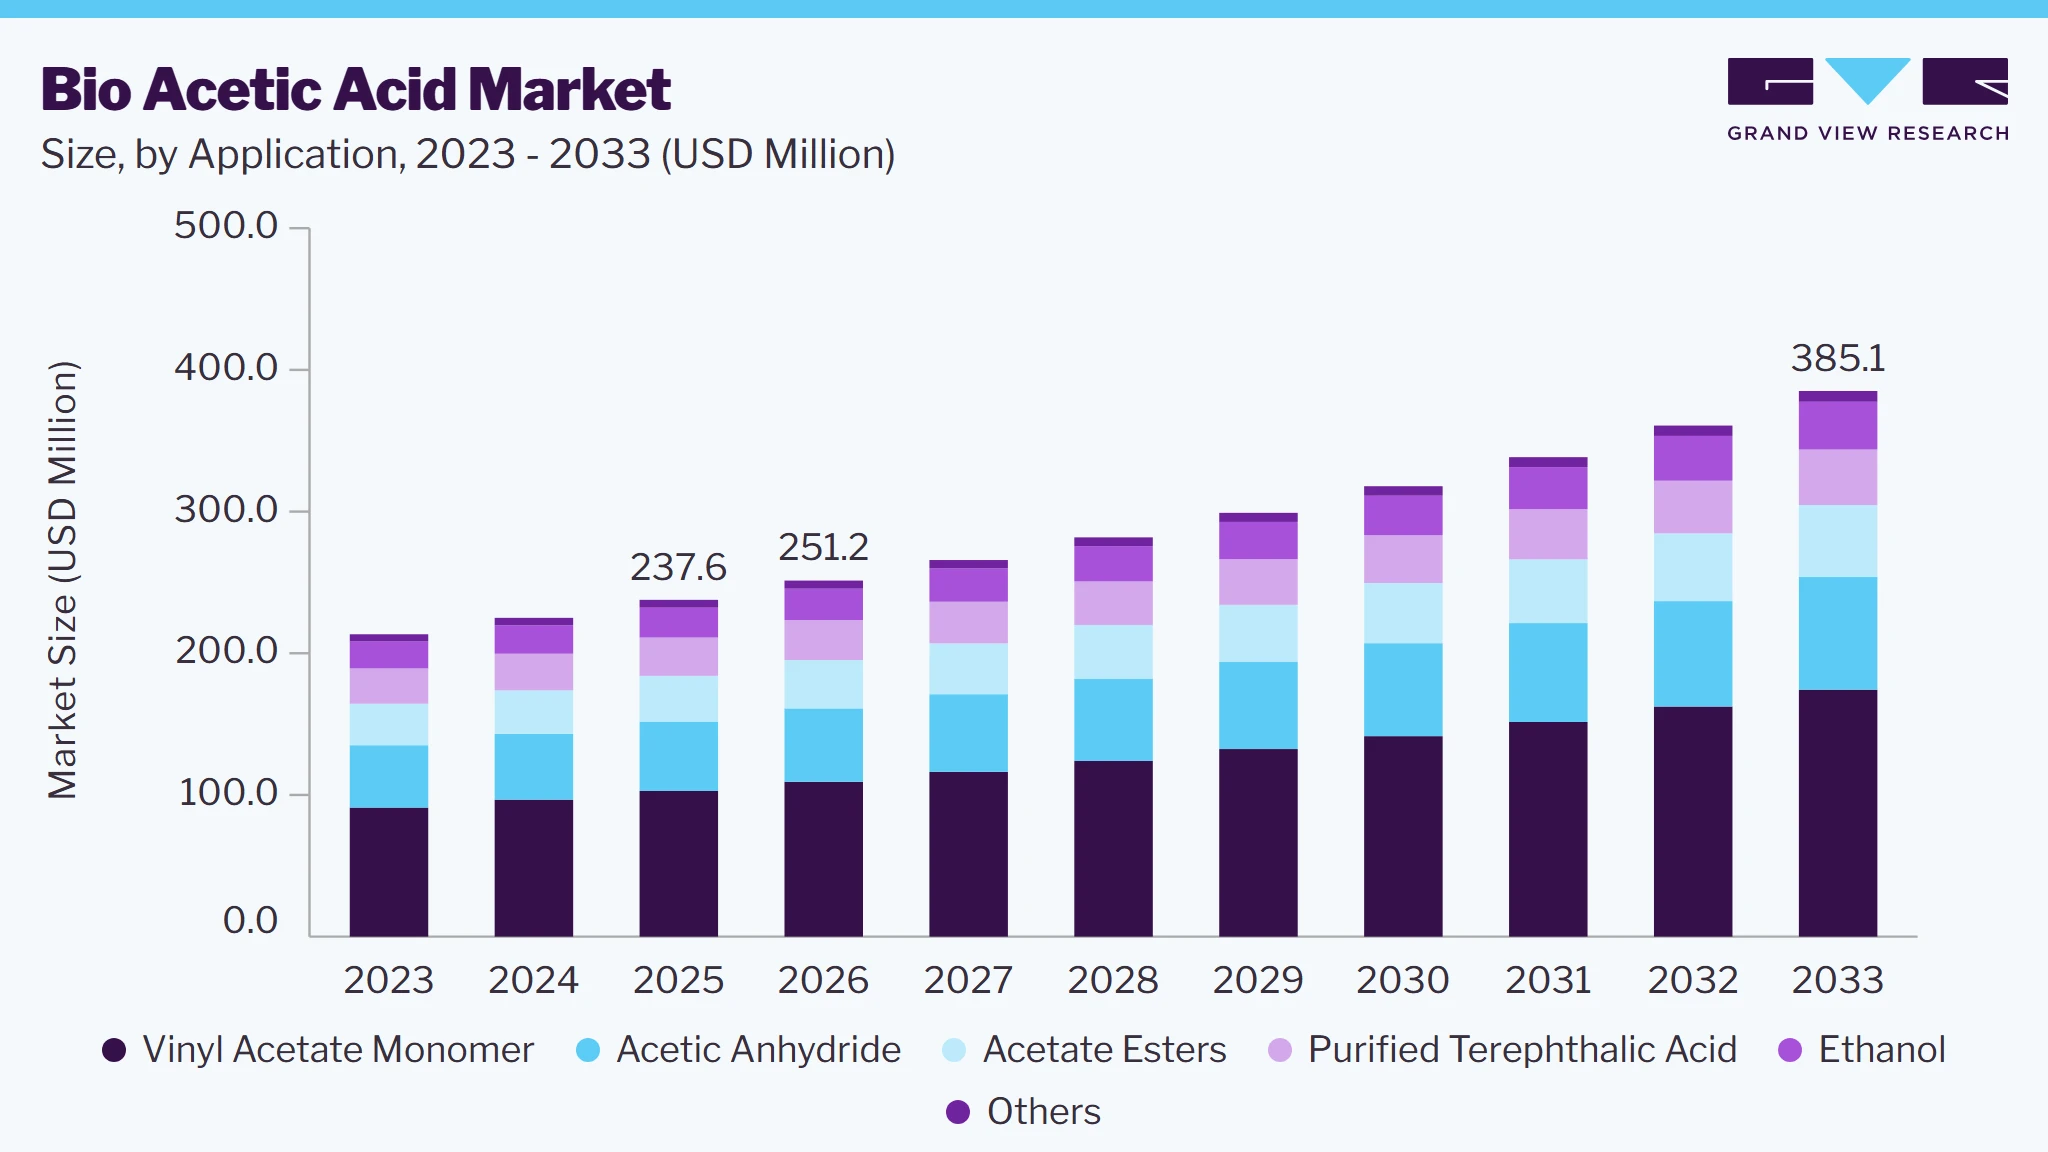 To learn more about this report, Download Free Sample Report
In addition, it is used to create polyvinyl alcohol (PVOH), which is used in coatings and adhesives due to its film-forming properties Thus, the rising demand for automobiles and construction in the U.S. is likely to propel the demand for paints & coatings in the country over the forecast period which in turn will drive the demand for bio-acetic acid used in the production of Vinyl Acetate Monomers (VAM).
Market Dynamics
The global bio-acetic acid market is experiencing steady growth as industries increasingly shift toward renewable and low-carbon chemical solutions to meet sustainability targets and evolving environmental regulations. Rising demand from downstream applications such as vinyl acetate monomer, acetate esters, and acetic anhydride is encouraging manufacturers to integrate bio-based feedstocks into their production processes. Advances in fermentation technologies, biomass utilization, and process optimization are improving production efficiency and enhancing the commercial viability of bio-acetic acid. In addition, growing investments in biorefineries and circular economy initiatives are supporting capacity expansion and product innovation across the value chain. However, the market continues to face challenges related to higher production costs, limited large-scale manufacturing infrastructure, and fluctuations in the availability of renewable feedstocks compared to conventional petrochemical routes.
The increasing global emphasis on sustainability is a major factor driving the bio-acetic acid market. Governments, manufacturers, and end-use industries are actively adopting renewable raw materials to reduce greenhouse gas emissions and lessen dependence on fossil fuel-derived chemicals. As environmental regulations become more stringent and corporate sustainability commitments gain momentum, bio-acetic acid is emerging as a preferred alternative in applications such as vinyl acetate monomer, acetate esters, and acetic anhydride. Its renewable origin aligns with evolving regulatory frameworks and supports manufacturers in achieving their environmental, social, and governance (ESG) objectives.
Consumer preference for environmentally responsible products is encouraging downstream industries to incorporate bio-based ingredients into their manufacturing processes. Sectors such as packaging, paints and coatings, adhesives, textiles, and pharmaceuticals are increasingly seeking sustainable chemical inputs without compromising product performance. This transition is accelerating investments in bio-based production technologies and expanding commercial opportunities for bio-acetic acid producers across both developed and emerging markets.
The widespread adoption of bio-acetic acid is constrained by its relatively high production costs compared to conventional petrochemical-based acetic acid. Manufacturing bio-acetic acid requires advanced fermentation technologies, specialized processing equipment, and consistent supplies of renewable feedstocks, all of which increase capital and operational expenditures. In addition, feedstock collection, transportation, and preprocessing can be complex and costly, particularly in regions where biomass supply chains are still underdeveloped. These factors reduce price competitiveness and limit adoption in cost-sensitive industrial applications where conventional acetic acid remains more economical.
The growing investment in integrated biorefineries presents a significant opportunity for the bio-acetic acid market. Governments and private organizations are supporting projects that convert agricultural residues, forestry waste, and other renewable biomass into high-value chemicals. These facilities improve feedstock utilization while enabling the production of multiple bio-based products, enhancing overall economic viability. As biorefinery infrastructure expands globally, bio-acetic acid manufacturers are expected to benefit from improved production efficiencies, diversified feedstock availability, and stronger supply chain resilience.
The increasing adoption of circular bioeconomy strategies is creating favorable conditions for market growth. Industries are focusing on resource efficiency, waste valorization, and carbon reduction through renewable chemical production, encouraging the commercialization of bio-acetic acid. Strategic collaborations between biotechnology companies, chemical manufacturers, and research institutions are accelerating innovation in fermentation processes and biomass conversion technologies. These developments are expected to lower production costs over time and open new application areas, strengthening the long-term growth potential of the market.
Analyst Perspective
The bio-acetic acid market is poised for sustained growth as industries increasingly transition toward renewable and low-carbon chemical alternatives. Advancements in fermentation technologies and expanding biorefinery investments are improving production efficiency and supporting commercial scalability. Demand is expected to remain strongest from vinyl acetate monomer, acetate esters, and acetic anhydride applications, driven by sustainability initiatives across packaging, coatings, and specialty chemicals. While higher production costs and limited large-scale manufacturing continue to restrain widespread adoption, ongoing technological innovation and supportive regulatory policies are expected to narrow the cost gap with petrochemical-based acetic acid.
Application Insights
By application, vinyl acetate monomer held a dominant position, contributing 43.2% of total revenue in 2025. This growth is attributed to its wide use in the production of adhesives, films, textiles, paints, coatings, and other end-use products. VAM is utilized as a key raw material in the manufacturing of several prominent polymers and resins. It is also used to develop high-performance emulsions and adhesives, which find applications in the automotive, construction, and packaged food industries. Increasing demand for VAM and its derivatives is expected to positively impact market growth during the forecast period.
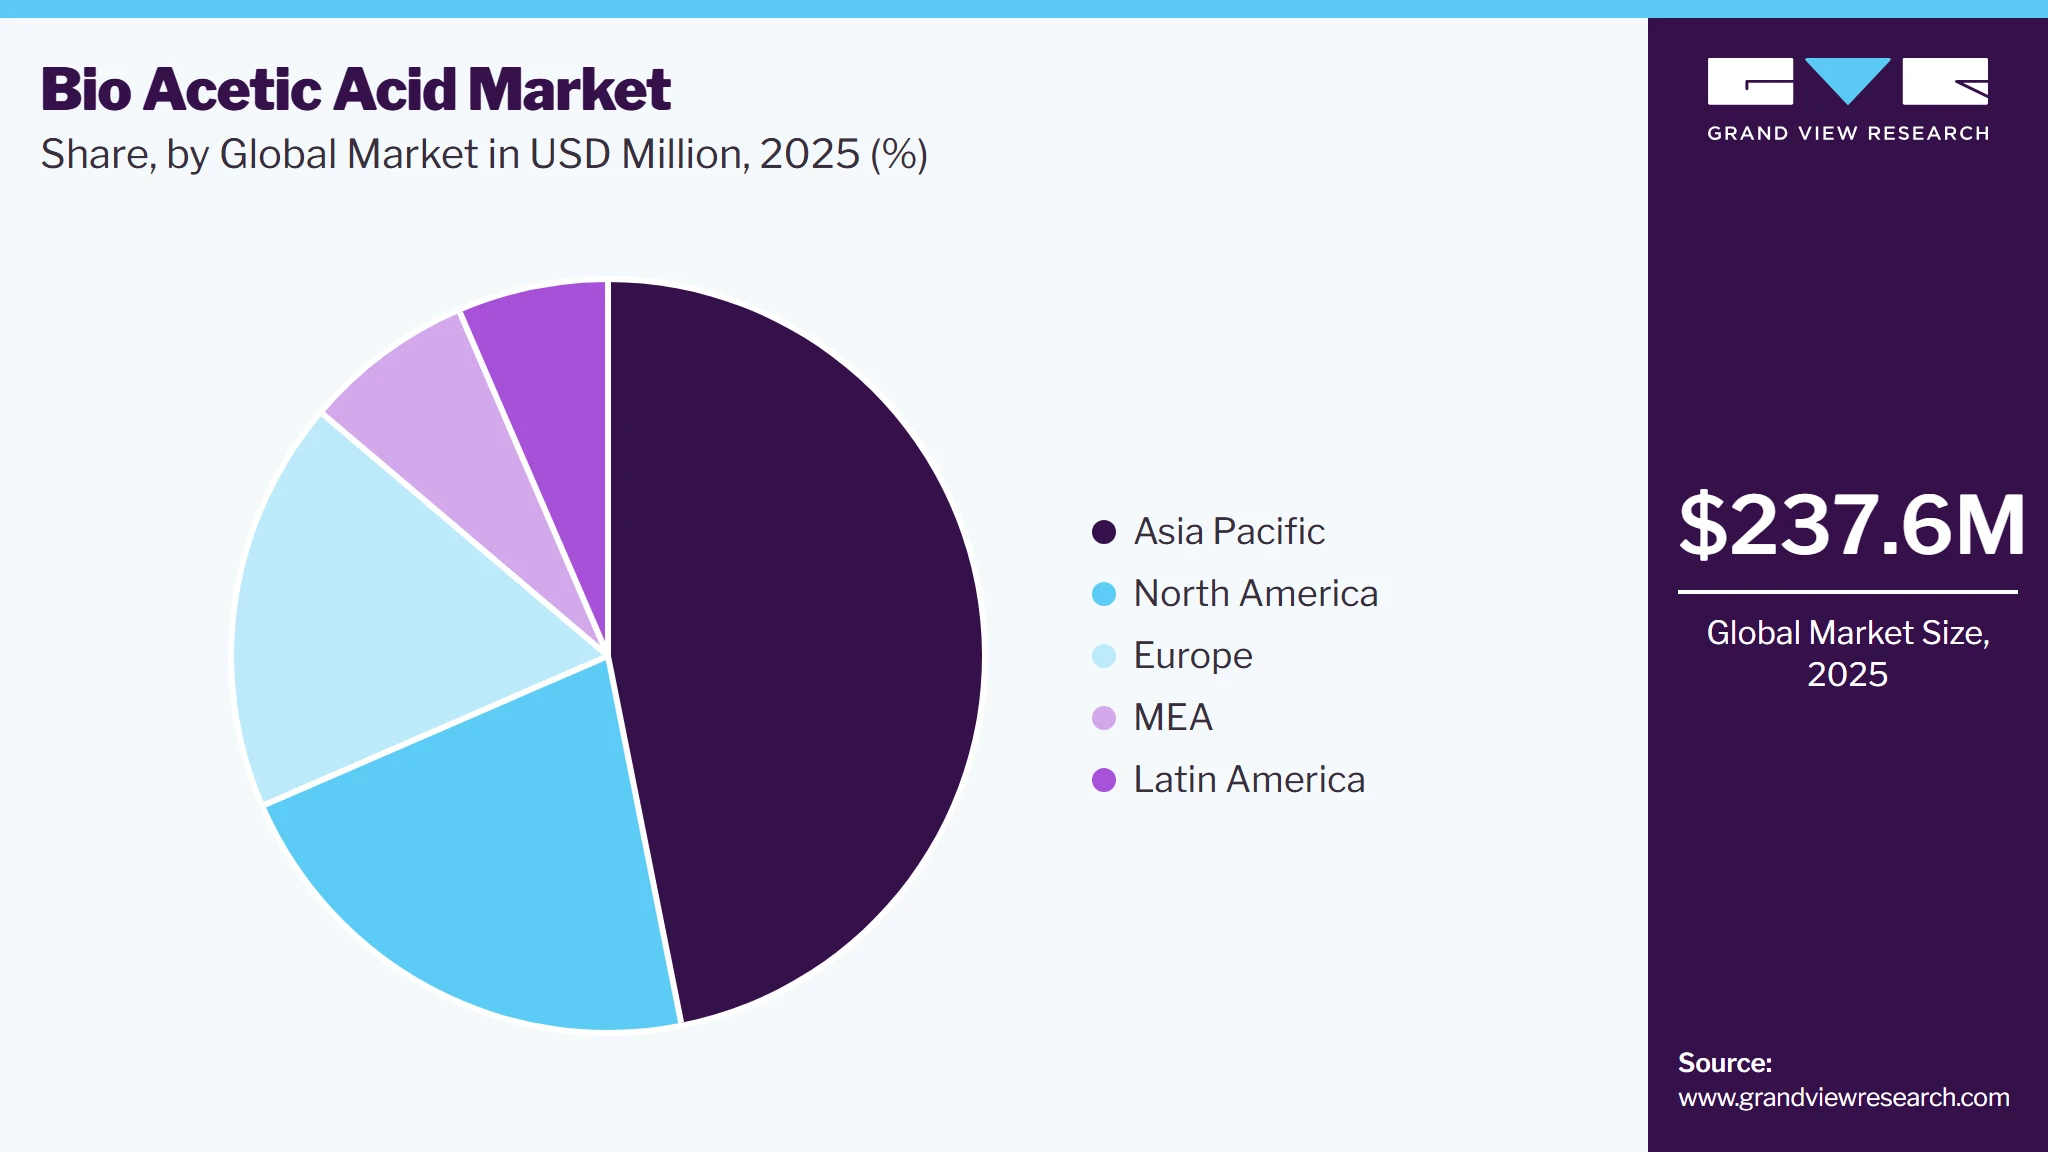 To learn more about this report, Download Free Sample Report
Acetic anhydride is another segment expected to grow significantly over the forecast period. It is a chemical intermediate used in the production of pharmaceutical products, tetraacetylethylenediamine (TAED), and cellulose acetate, among others. The wide use of acetic anhydride in producing drugs, such as aspirin, paracetamol, acetyl-p-aminophenol, acetylcholine hydrochloride, sulfa drugs, cortisone, and acetanilide, among others, coupled with the growing demand for cellulose acetate from the packaging industry, is expected to be a major driver contributing to the growth of the segment.
In addition, the growing demand for clear masks, face shields, food, and e-commerce packaging has driven increased demand for purified terephthalic acid, dimethyl terephthalate, and polyethylene terephthalate. This has led to the segment's growth, and advancements in production technologies are expected to offer lucrative opportunities for the segment in the future.
Regional Insights
Asia Pacific dominated the bio-acetic acid market with the highest revenue share of 46.9% in 2025. This growth was driven by rapid industrialization, increased manufacturing activities, and strong demand from end-use industries, including automotive, packaging, paints and coatings, plastics, food and beverages, and chemicals. The region's strong automotive sector plays a crucial role in this growth, as bio-acetic acid and its derivatives are commonly used in making coatings, adhesives, and specialty materials for vehicle production. Major automobile manufacturers such as Toyota, Kia, Nissan, and Hyundai are present in the region. In addition, growing consumer purchasing power and a rising population further boost industrial demand. According to the International Organization of Motor Vehicle Manufacturers, vehicle production in the Asia Pacific region rose by 7.6% in 2025 to about 59.2 million units, accounting for more than 61% of global vehicle output. This increase is driving demand for coatings, plastics, and other downstream products that use acetic acid derivatives, thereby supporting market growth.
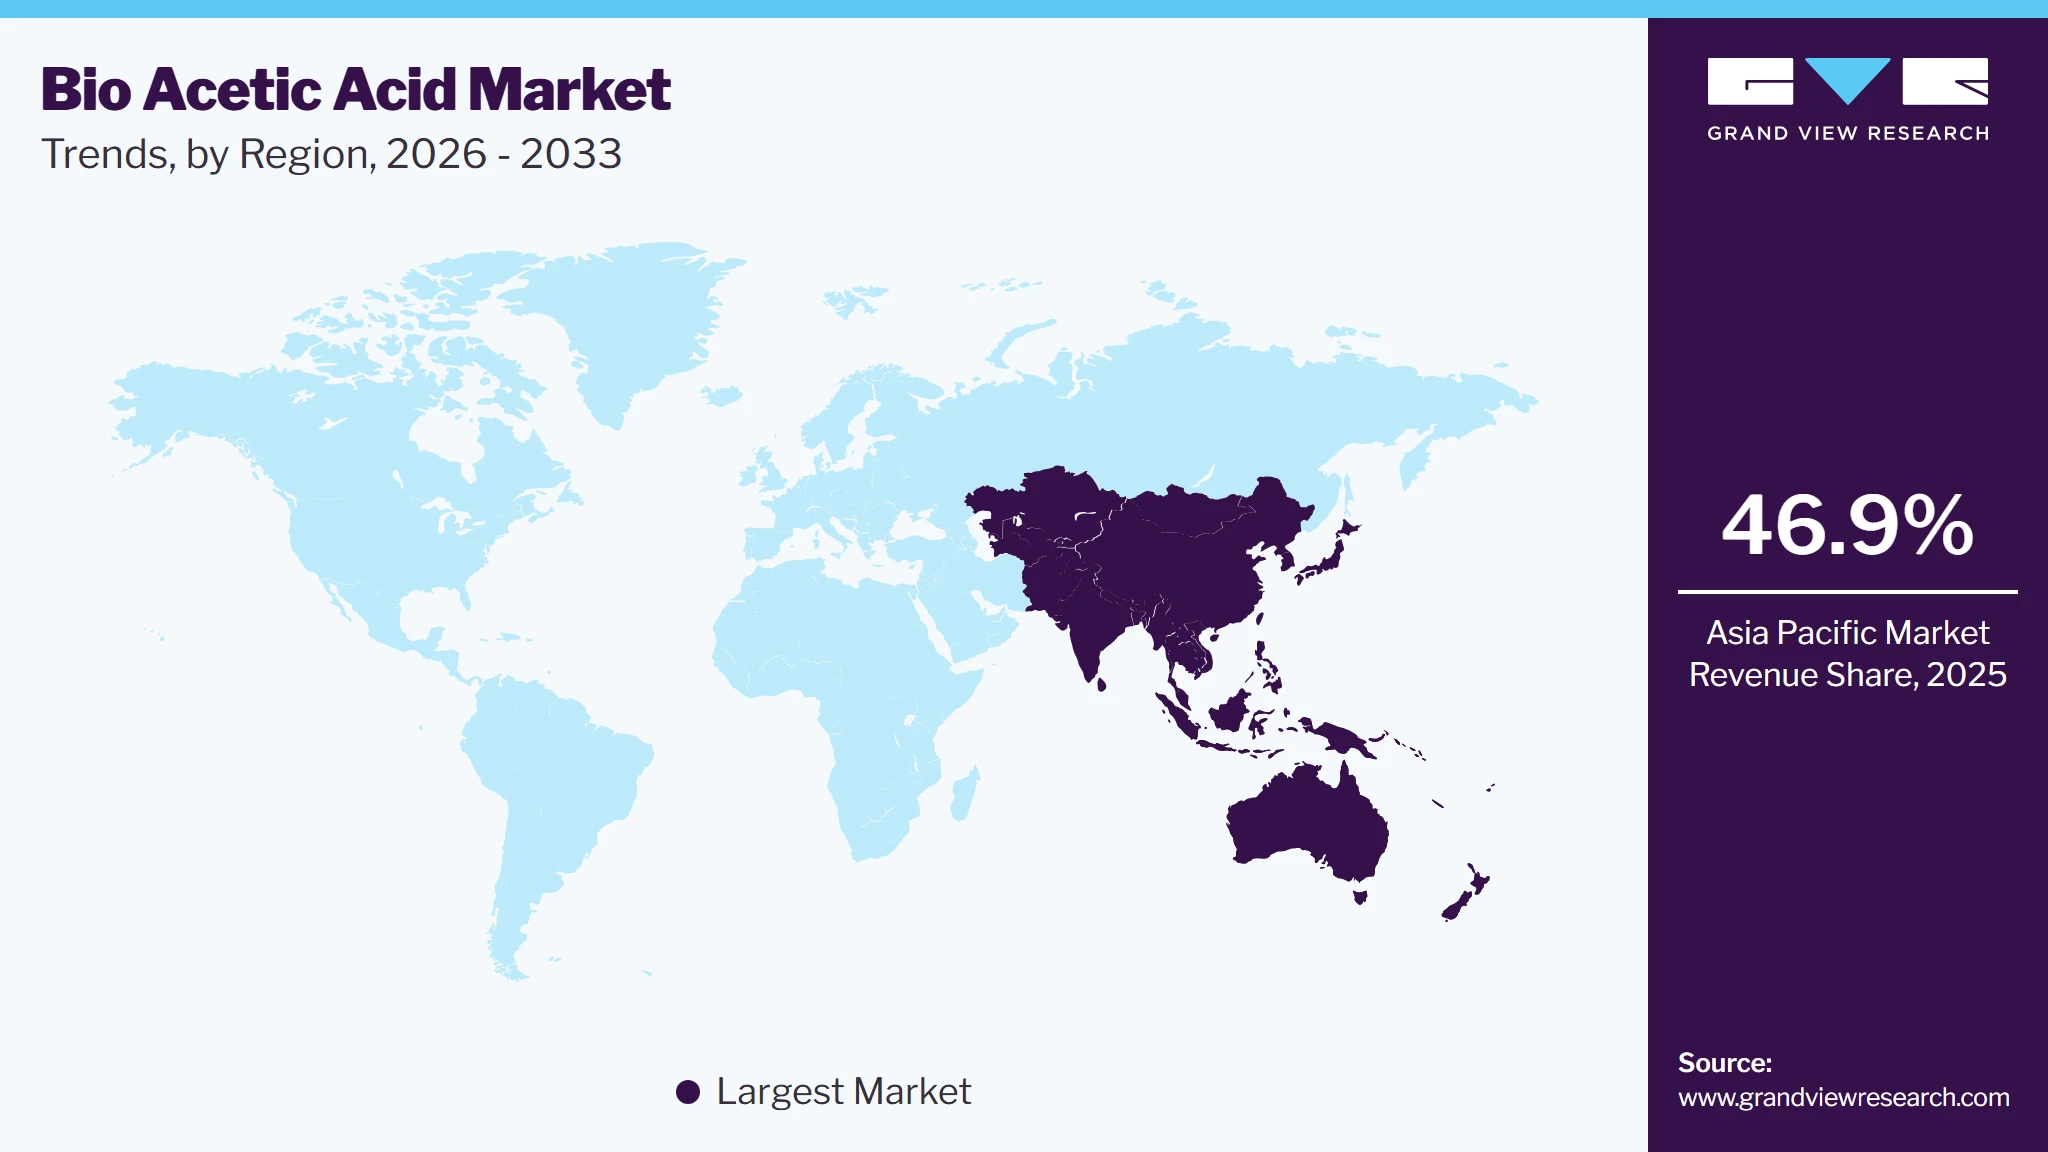 To learn more about this report, Download Free Sample Report
China Bio-acetic Acid Market Trends
China accounted for 61.6% of the Asia Pacific bio-acetic acid market in 2025.
North America Bio-acetic Acid Market
The bio-acetic acid market in North America is also witnessing significant growth, driven by increasing demand for vinyl acetate monomers from the packaging and food & beverage industries. In addition, bio-acetic acid is an essential raw material used in the production of personal care products such as shampoos, creams, conditioners, and more, as a pH regulator and preservative. In addition, the growing investment in bio-refineries and biomanufacturing technologies is driving market growth in the region. Governments, research institutions, and private companies in the U.S. and Canada are investing in developing sustainable production processes that use renewable feedstocks such as agricultural residues, biomass, and bioethanol. These investments improve production efficiency, cut dependence on fossil-based raw materials, and support the commercialization of bio-based chemicals.
Key Bio-acetic Acid Company Insights
The market is characterized by high competition, driven by a large number of large- and small-scale manufacturers and suppliers. Enterprises in product manufacturing use various methods to address the growing market demand. Such methods aim to expand their global reach, while also optimizing distribution costs to potential consumers. Companies are observed to undertake mergers and acquisitions, joint ventures, and expansion activities to take advantage of opportunities in the global market. The players are actively pursuing technological innovations and new product launches to strengthen their market position.
-
In January 2026, Kemvera made strides in bringing its bio-acetic acid and bio-ethyl acetate production process to market by completing the process design package (FEL 1) for a planned commercial facility with a capacity of 50,000 metric tons per year. The company has also built a pre-commercial demonstration reactor with a capacity of 500 metric tons per year and set up a pilot unit capable of producing 20 metric tons per year to test continuous operations. These milestones represent important steps toward scaling its unique catalytic platform, which turns bio-based feedstocks, including corn ethanol, into affordable bio-acetic acid.
Key Bio-acetic Acid Companies
The following key companies have been profiled for this study on the bio-acetic acid market:
-
AFYREN SAS
-
Celanese Corporation
-
Eastman Chemical Company
-
Godavari Biorefineries Limited
-
Jubilant Ingrevia Limited
-
LanzaTech Global, Inc.
-
Lenzing AG
-
SEKAB BioFuels & Chemicals AB
-
Wacker Chemie AG
-
ZeaChem, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Cargill, Inc., Novozymes A/S, GODAVARI BIOREFINARIES LTD, Airedale Chemicals, Sucroal SA)
- Invest in large-scale biorefinery facilities to enhance production efficiency and ensure consistent supply.
- Establish long-term renewable feedstock sourcing agreements to strengthen supply chain stability.
- Diversify product portfolios by offering multiple bio-based chemicals alongside bio-acetic acid.
- Expand geographically through strategic partnerships while maintaining compliance with regional sustainability regulations.
- Possess extensive manufacturing infrastructure capable of high-volume production.
- Benefit from well-established customer relationships across diverse end-use industries.
- Strong financial capabilities support continuous R&D, technology upgrades, and capacity expansion.
- Global distribution networks and recognized brand presence facilitate wider market penetration.
- High capital and operating costs associated with large-scale manufacturing facilities.
- Legacy production systems may require substantial investment for modernization.
- Slower organizational decision-making can delay technology adoption and innovation.
- Greater exposure to raw material price volatility and evolving environmental regulations.
Emerging Players (LanzaTech, Afyren SAS, Bio-Corn Products EPZ Ltd., BTG Bioliquids)
- Develop advanced fermentation and biomass conversion technologies to improve process efficiency.
- Form strategic collaborations with technology providers, research organizations, and industrial partners.
- Target high-value niche applications where demand for sustainable chemicals is increasing.
- Scale production gradually develops through pilot and demonstration plants before commercial expansion.
- Proprietary technologies offer differentiated and sustainable production pathways.
- Agile organizational structures enable rapid innovation and market responsiveness.
- Strong alignment with circular economy initiatives and low-carbon manufacturing trends.
- Ability to capitalize on government incentives supporting bio-based chemical production.
- Limited commercial-scale production capacity compared to established competitors.
- Financial constraints can slow capacity expansion and global market entry.
- Lower brand recognition reduces competitiveness in large industrial procurement contracts.
- Dependence on external funding and strategic partnerships may create commercialization risks.
Bio-acetic Acid Market Report Scope
Report Attribute
Details
Market size in 2025
USD 237.6 million
Estimated market size in 2026
USD 251.2 million
Projected market size by 2033
USD 385.1 million
Growth rate
CAGR of 6.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/million, Volume in Kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; India; Japan; South Korea; Brazil; Argentina; Saudi Arabia; Qatar; Egypt; South Africa
Key companies profiled
AFYREN SAS; Celanese Corporation; Eastman Chemical Company; Godavari Biorefineries Limited; Jubilant Ingrevia Limited; LanzaTech Global, Inc.; Lenzing AG; SEKAB BioFuels & Chemicals AB; Wacker Chemie AG; ZeaChem, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Bio-acetic Acid Market Report Segmentation
This report forecasts revenue growth at the regional and country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global bio-acetic acid market report based on application and region:
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Vinyl Acetate Monomer
-
Acetic Anhydride
-
Acetate Esters
-
Purified Terephthalic Acid
-
Ethanol
-
Other Applications
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
Qatar
-
Egypt
-
South Africa
-
-
Research Methodology
The Bio-acetic acid market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Bio-acetic acid segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Application
Revenue capture definition
Vinyl Acetate Monomer
Revenue generation is led using bio-acetic acid in vinyl acetate monomer production for adhesives, paints, coatings, construction materials, and packaging films. Consistent consumption across these high-volume industries secures a substantial share of market earnings.
Acetic Anhydride
Value realization is supported by bio-acetic acid serving as a key feedstock for acetic anhydride used in pharmaceuticals, cellulose acetate, agrochemicals, and specialty chemicals. Rising demand for sustainable chemical intermediates strengthens commercial returns.
Acetate Esters
Income potential is derived from the production of bio-based acetate esters used as environmentally friendly solvents in coatings, inks, adhesives, cleaning agents, and personal care products. Growing preference for low-VOC formulations enhances segment expansion.
Purified Terephthalic Acid
Market proceeds are driven by the application of bio-acetic acid as a process solvent in purified terephthalic acid manufacturing, supporting polyester fibers, PET packaging, and beverage containers. Increasing demand for sustainable packaging contributes to long-term revenue growth
Ethanol
Commercial gains originate from integrated biorefinery operations where bio-acetic acid functions as an intermediate or co-product in renewable ethanol production. Advancements in biomass conversion technologies improve operational efficiency and profitability.
Other Applications
Sales growth is generated through utilization in food preservation, textile processing, rubber manufacturing, water treatment, laboratory chemicals, and specialty formulations. Expanding adoption across niche industrial applications broadens the market's revenue base.
Estimation Model
Layer Name
Key Question
Description
Raw Material & Production Layer
What forms the supply base?
Examine the production of bio-acetic acid from renewable feedstocks such as agricultural residues, sugarcane, corn, lignocellulosic biomass, and other organic materials through fermentation and biochemical conversion technologies. Assess feedstock availability, microbial fermentation processes, purification methods, biorefinery integration, production capacities, regional manufacturing hubs, and supply chain capabilities that support the commercialization of sustainable acetic acid.
Application Adoption Layer
Where is bio-acetic acid consumed?
Evaluate the adoption of bio-acetic acid across major applications including vinyl acetate monomer, acetic anhydride, acetate esters, purified terephthalic acid, ethanol production, and specialty chemicals. Demand is driven by increasing preference for renewable raw materials, sustainability initiatives, low-carbon manufacturing practices, and expanding use of bio-based chemicals in packaging, coatings, pharmaceuticals, textiles, and consumer products.
Consumption Intensity Layer
How much bio-acetic acid is utilized?
Quantify bio-acetic acid consumption by analyzing production volumes, process integration, feedstock conversion efficiencies, and application-specific utilization rates across downstream industries. The assessment covers chemical intermediates, solvent manufacturing, polymer production, biofuel processing, pharmaceutical synthesis, and specialty chemical formulations to estimate regional and global demand patterns.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the commercial supply of bio-acetic acid to manufacturers seeking renewable alternatives for chemical synthesis and industrial processing. Financial performance is influenced by production scale, feedstock economics, technology advancements, long-term supply agreements, regulatory support for bio-based chemicals, sustainability-driven procurement strategies, product quality, and expanding demand from downstream industries adopting low-carbon manufacturing solutions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The study provides detailed country-level analysis across major bio-acetic acid production and consumption markets. It evaluates renewable feedstock availability, biorefinery infrastructure, production capacities, regulatory frameworks, trade dynamics, downstream application demand, and growth prospects across vinyl acetate monomer, acetate esters, acetic anhydride, purified terephthalic acid, ethanol, and specialty chemicals.
Supports strategic market expansion by identifying high-potential regions, assessing regional supply-demand dynamics, evaluating feedstock accessibility, and highlighting investment opportunities in emerging bio-based chemical hubs.
Competitive Benchmarking
The study presents an in-depth competitive benchmarking assessment of leading bio-acetic acid manufacturers based on production capabilities, technology platforms, feedstock sourcing strategies, product portfolio, geographic footprint, sustainability initiatives, strategic partnerships, innovation pipeline, and recent business developments.
Helps stakeholders evaluate competitor positioning, identify technological differentiators, benchmark operational capabilities, uncover collaboration opportunities, and strengthen long-term competitive strategies.
Opportunity Assessment
The study analyzes emerging opportunities across renewable chemicals, sustainable packaging, adhesives, coatings, pharmaceuticals, textiles, food ingredients, and integrated biorefineries. It further evaluates the impact of advances in fermentation technologies, circular bioeconomy initiatives, government incentives, and increasing adoption of low-carbon manufacturing practices.
Assists organizations in identifying high-growth applications, prioritizing investment areas, accelerating innovation initiatives, expanding into new end-use sectors, and capitalizing on the global transition toward sustainable chemical production.
Frequently Asked Questions About This Report
The global bio-acetic acid market is expected to grow at a CAGR of 6.3% from 2026 to 2033, reaching USD 385.1 million by 2033.
Asia Pacific dominated with a 46.9% revenue share in 2025.
Vinyl Acetate Monomer (VAM) dominated the bio-acetic acid market with a share of 43.2% in 2025.
The global bio-acetic acid market size was valued at USD 237.6 million in 2025 and is estimated at USD 251.2 million for 2026.
Key players include Lenzing AFYREN SAS; Celanese Corporation; Eastman Chemical Company; Godavari Biorefineries Limited; Jubilant Ingrevia Limited; LanzaTech Global, Inc.; Lenzing AG; SEKAB BioFuels & Chemicals AB; Wacker Chemie AG; ZeaChem, Inc.
The growth is attributed to rising demand for eco-friendly, sustainable alternatives to traditional petrochemical-based products.
About the Author(s)
Renewable Chemicals Research Team
Specialty & Chemicals · Renewable ChemicalsThis report was authored by the renewable chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable chemicals segment of the specialty & chemicals industry. All findings are based on proprietary specialty & chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


