
- Home
- »
- Clothing, Footwear & Accessories
- »
-
Blank Apparel Market Size, Share, Trends Report, 2026-2033GVR Report cover

Blank Apparel Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (T-Shirts & Tanks, Hoodies/ Sweatshirts, Shirts, Bottoms), By Distribution Channel (B2B, B2C), By Region (North America, Europe, Asia Pacific), And Segment Forecasts
Market Size, 2025
$15.9BMarket Estimate, 2026
$16.6BMarket Forecast, 2033
$24.0BCAGR, 2026–2033
5.4%Blank Apparel Market Summary
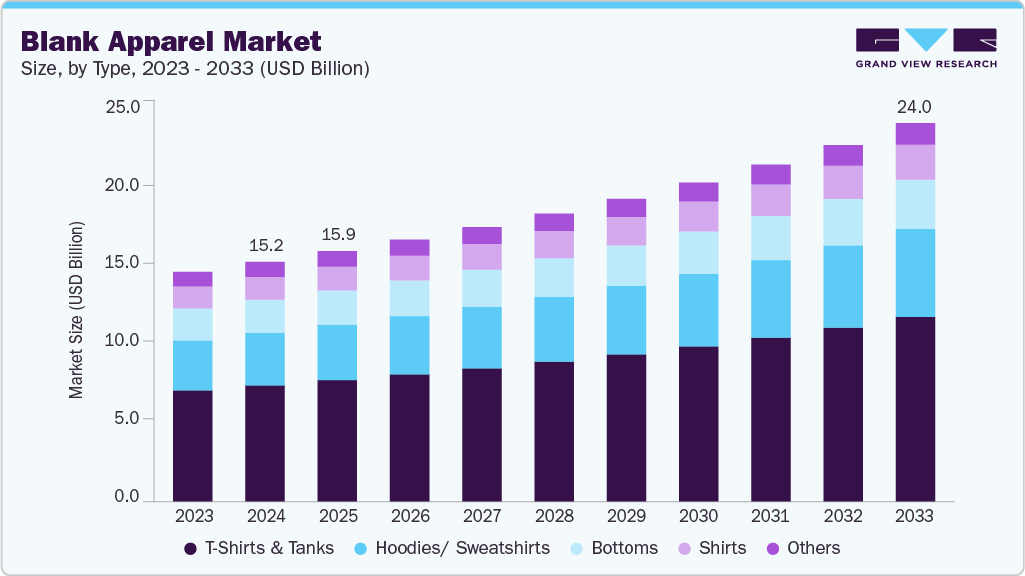
The global blank apparel market size was valued at USD 15.9 billion in 2025 and is projected to grow from USD 16.6 billion in 2026 to USD 24.0 billion by 2033, at a CAGR of 5.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 44.8% in 2025. A key trend in the blank apparel market is the rapid rise of print-on-demand and customization, where consumers and small brands want unique, personalized clothing instead of mass-produced designs.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: T-Shirts & tanks segment dominated the market, with a revenue share of 48.4% in 2025.
- By distribution channel: Business to business (B2B) segment held the largest market share of 96.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (44.8% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 15.9 Billion
- Estimated market size in 2026: USD 16.6 Billion
- Projected market size by 2033: USD 24.0 Billion
- CAGR (2026-2033): 5.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
This trend is fueled by the growth of e-commerce platforms such as Etsy, Shopify, and Amazon Merch, making it easy for startups and creators to build micro-brands using blank t-shirts, hoodies, and caps as their base products. Increasing sports participation is driving the demand for blank apparel. As more people engage in sports, fitness, and active lifestyles, there is a growing need for versatile clothing such as t-shirts, hoodies, and activewear that can be easily customized or branded. Athletes, sports enthusiasts, and casual consumers increasingly prefer plain apparel that can serve as a foundation for team kits, fan gear, or personalized sportswear, contributing to steady growth in the market.Rise in collaborations with universities, leagues, and clubs is creating new opportunities and driving market growth. Apparel brands are increasingly partnering with colleges and universities to produce team merchandise and promotional clothing for students, alumni, and fans. Similarly, partnerships with professional sports leagues and clubs enable brands to produce licensed fan apparel and merchandise. These collaborations expand the market for blank apparel, as plain products provide the flexibility required for branding, logos, and event-specific designs.
 To learn more about this report, Download Free Sample Report
For instance, in May 2023, Sports and lifestyle brand PlayR announced its global merchandise partnership with four teams of the Indian Premier League (IPL): Mumbai Indians, Chennai Super Kings, Punjab Kings, and Rajasthan Royals. This collaboration provides PlayR with exclusive rights to sell a wide range of high-quality apparel, accessories, equipment, and lifestyle products to fans.
Industries such as retail, hospitality, healthcare, and technology rely on uniforms to maintain a professional, cohesive appearance and ensure brand consistency and safety. Blank apparel provides a versatile base for customized uniforms, allowing businesses to add logos, embroidery, or prints to reflect their unique identity. For instance, in February 2024, National Windscreens partnered with Workwear Express to provide over 600 technicians with practical, durable uniforms, sourcing blank apparel as the base. This increasing trend of providing apparel and uniforms with logos and company names is expected to drive the demand for blank apparel and the overall market during the forecast period.
Market Dynamics
The blank apparel market is experiencing strong growth due to rising demand from customization, print-on-demand (POD), promotional merchandise, corporate branding, and independent fashion businesses. Blank garments serve as the foundational product for screen printing, embroidery, heat transfer, sublimation, and direct-to-garment (DTG) printing applications, making them a critical component of the broader apparel decoration ecosystem. The rapid expansion of e-commerce-based custom apparel platforms, creator-led merchandise brands, and small-batch production models has significantly increased demand for high-quality blank t-shirts, hoodies, sweatshirts, polos, and activewear. Additionally, improvements in fabric quality, color consistency, and inventory management capabilities are supporting market expansion across both developed and emerging economies.
The accelerating adoption of print-on-demand and customized apparel services is a primary growth driver for the blank apparel market. Entrepreneurs, e-commerce sellers, influencers, sports organizations, educational institutions, and corporate buyers increasingly rely on blank garments as the base product for personalized apparel production. The expansion of digital printing technologies, including DTG and DTF (Direct-to-Film) printing, has reduced minimum order requirements and enabled cost-effective short production runs, making customized apparel more accessible than ever before.
Furthermore, the growing popularity of creator merchandise, event-based apparel, corporate promotional wear, and team uniforms continues to generate substantial demand for blank apparel. The rise of online marketplaces and fulfillment platforms has further simplified the process of sourcing, decorating, and distributing customized garments, driving consistent consumption of blank apparel across multiple end-use sectors.
Fluctuations in cotton and textile raw material prices remain a significant challenge for blank apparel manufacturers and distributors. Cotton, which represents a major input cost for many blank garments, is highly susceptible to weather conditions, crop yields, water availability, geopolitical disruptions, and trade policies. Sudden increases in raw material costs can compress margins, particularly in a market where large-volume buyers often negotiate aggressively on price.
Additionally, the blank apparel industry relies heavily on efficient global sourcing, textile manufacturing, and distribution networks to maintain inventory availability across multiple sizes, colors, and product styles. Disruptions in textile production hubs, freight networks, or labor-intensive manufacturing operations can lead to inventory shortages, extended lead times, and fulfillment challenges for customization businesses that depend on rapid order turnaround.
Growing demand for sustainable apparel is creating substantial opportunities within the blank apparel market. Apparel decorators, corporate buyers, and fashion brands are increasingly seeking blank garments made from organic cotton, recycled fibers, regenerative agriculture-based materials, and low-impact dyes to meet evolving sustainability goals and consumer expectations. As environmental transparency becomes a key purchasing criterion, suppliers offering certified sustainable blank apparel are gaining competitive advantages.
In addition, demand is shifting toward premium blanks that provide superior fit, heavier fabric weights, enhanced durability, and retail-quality aesthetics suitable for fashion brands and premium merchandise programs. The continued growth of independent clothing labels, creator-led brands, and high-quality print-on-demand offerings is expected to increase demand for premium blank apparel products that deliver both customization flexibility and elevated consumer appeal, creating new value-generation opportunities across the market.
Analyst Perspective
The blank apparel market is benefiting from the structural shift toward on-demand apparel production and customization, particularly across print-on-demand, promotional merchandise, and independent fashion brands. Unlike traditional apparel segments, demand is increasingly influenced by decoration compatibility, fabric quality, and inventory availability rather than brand-driven consumer marketing. Premium blank apparel manufacturers are gaining share as creators, e-commerce sellers, and corporate buyers seek retail-quality garments suitable for DTG printing, embroidery, and customization. Sustainability is also emerging as a key differentiator, with demand rising for organic cotton and ethically sourced products. Additionally, nearshoring strategies and shorter production cycles are becoming critical as buyers prioritize supply chain reliability and faster fulfillment over purely low-cost sourcing.
Consumer Insights
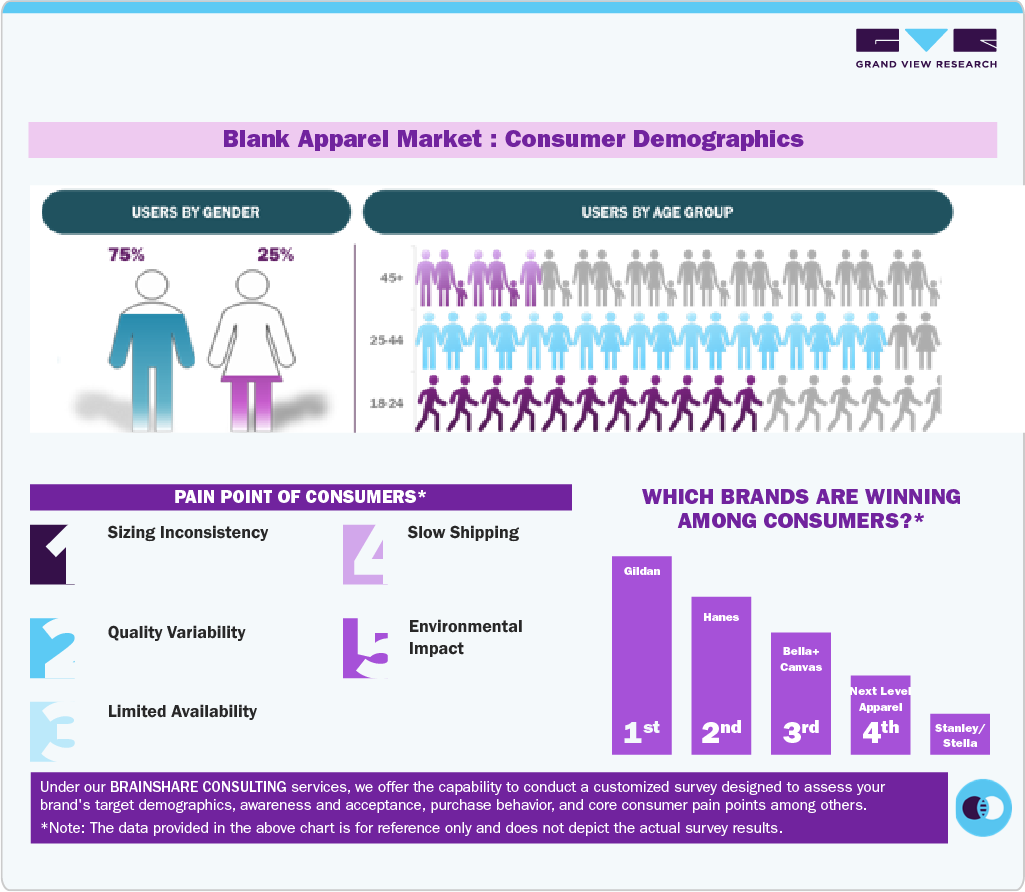
The global blank apparel market is predominantly male-driven, with men accounting for 75% of users and women 25%. This strong male skew highlights the demand for blank apparel in industries such as sports, promotional wear, and casual basics, which often cater more to male consumers. The data also suggests notable opportunities for growth by expanding female-focused styles and fits.
 To learn more about this report, Download Free Sample Report
Age distribution in the market shows active participation from younger and middle-aged consumers. The largest user group is aged 25-44, followed by a significant share of 18-24-year-olds, while those aged 45 and above make up a smaller portion. These insights underscore that younger demographics are key customers, likely influenced by the popularity of streetwear, e-commerce, and customizable basics.
Key consumer pain points in the blank apparel market are sizing inconsistency, quality variability, and limited availability-areas that brands must address to build loyalty and repeat purchase. Secondary issues include slow shipping and environmental impact, which increasingly inform buyer decisions, particularly among younger consumers who value convenience and sustainability.
Among brands, Gildan holds the leading position, followed by Hanes, BELLA+CANVAS, Next Level Apparel, and Stanley/Stella. These brands are recognized for balancing quality, availability, and pricing, which resonate strongly with market needs and help them maintain competitive advantage.
Type Insights
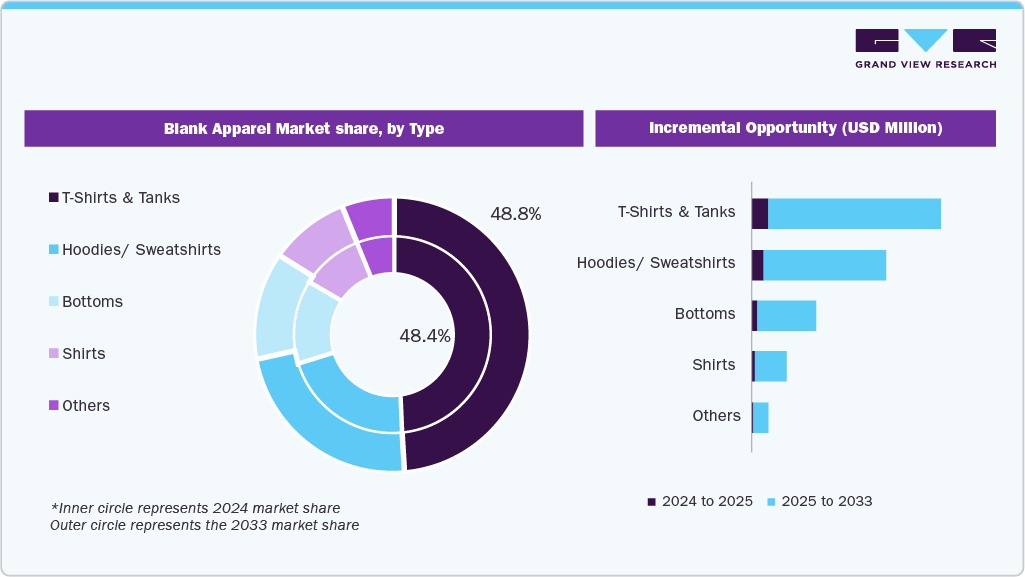
Based on types, the t-shirts & tanks segment led the market with the largest revenue share of 48.4% in 2025 and is expected to grow at the fastest CAGR over the forecast period. T-shirts and tanks represent the largest segment of the blank apparel market due to their versatility, affordability, and widespread use across printing, promotional, corporate branding, sportswear, and fashion applications. These garments serve as the preferred base products for screen printing, embroidery, direct-to-garment (DTG) printing, and custom apparel production because of their simple design and broad consumer appeal. Growing demand for personalized clothing, merchandise for events and businesses, and print-on-demand services continues to drive sales of blank t-shirts and tanks globally. Additionally, the increasing popularity of casual wear and athleisure trends, coupled with rising e-commerce penetration and small-batch apparel customization, is expected to support the segment’s strong growth throughout the forecast period.
 To learn more about this report, Download Free Sample Report
Hoodies/ Sweatshirts are anticipated to grow at a CAGR of 6.0% from 2025 to 2033. The widespread appeal of streetwear fashion has been fueled by the growing influence of social media, where style-conscious Millennials and Gen Z consumers showcase their outfit choices and share the latest trends. As these younger generations become the driving force behind consumer demand, the popularity of blank hoodies and sweatshirts has witnessed a surge in recent years. These clothing types are easily integrated into the streetwear aesthetic.
Distribution Channel Insights
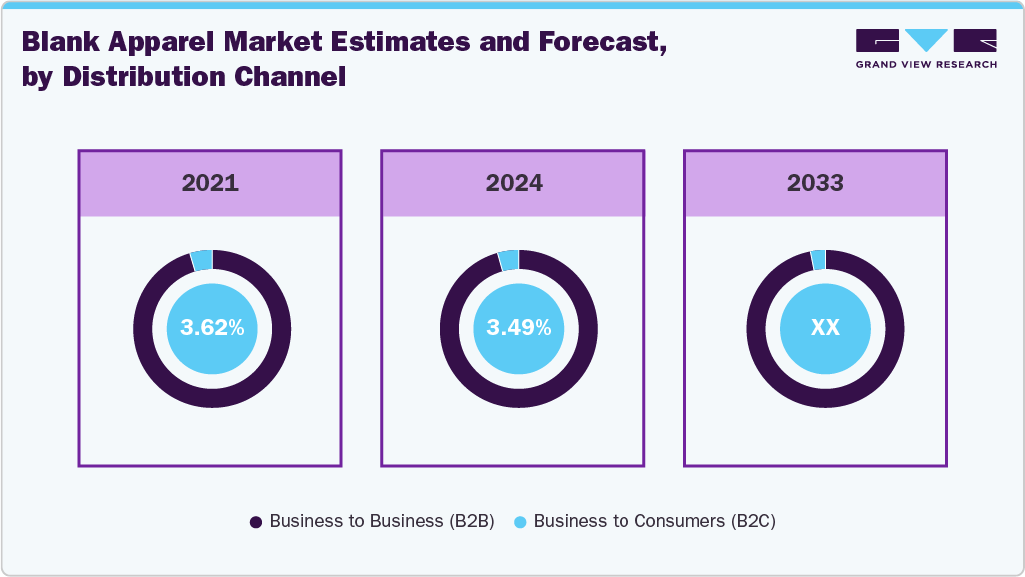
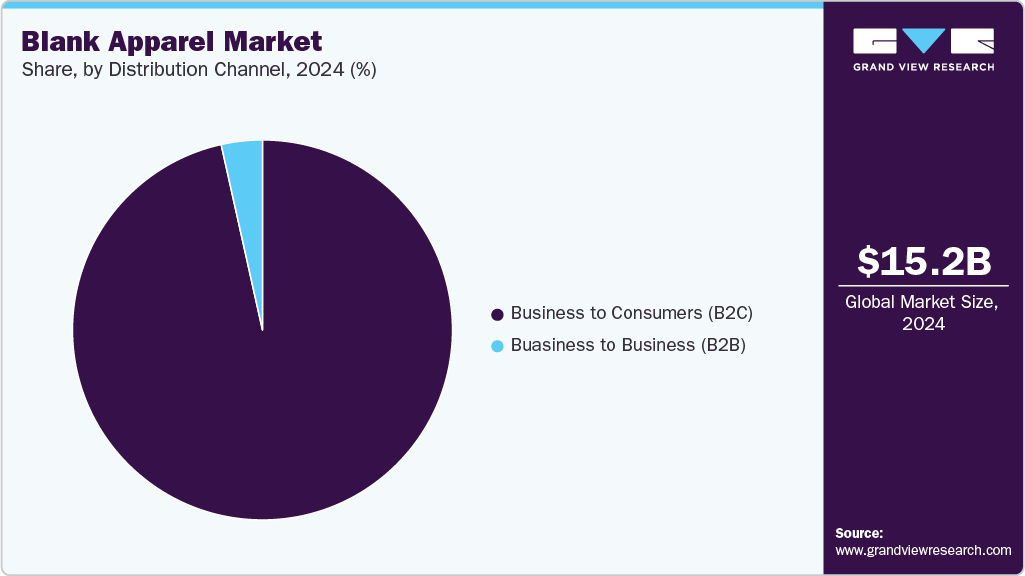
Based on distribution channel, the business to business (B2B) segment led the market with the largest revenue share of 96.6% in 2025, as the majority of products are purchased in bulk by apparel decorators, promotional product companies, corporate buyers, sports organizations, educational institutions, and fashion brands. Blank garments serve as foundational inventory for customization and branding activities, making wholesale procurement the preferred purchasing model across the industry. Large-volume orders enable businesses to achieve cost efficiencies while ensuring consistent product quality and availability. Furthermore, the rapid expansion of custom printing services, promotional marketing campaigns, company uniform programs, and print-on-demand business models has strengthened demand through B2B distribution channels. The established network of wholesalers, distributors, and apparel suppliers continues to reinforce the segment’s dominant position within the global blank apparel market.
 To learn more about this report, Download Free Sample Report
For instance, in September 2023, American Apparel, a North American clothing retailer acquired by Gildan Activewear, Inc., announced a multi-year partnership with Live Nation, the global leader in live entertainment, as the official printwear supplier at select Live Nation festivals in the U.S. This partnership provided the company with an exceptional opportunity to collaborate with artists and designers to create timeless t-shirt memories for attendees.
 To learn more about this report, Download Free Sample Report
The sale of blank apparel to Business to Consumers (B2C) is expected to grow at a CAGR of 3.6% from 2025 to 2033. The growing DIY culture and the trend toward personalization are key factors driving the sales of blank apparel through the business-to-consumer distribution channel. Consumers are increasingly seeking ways to express their creativity and individuality by customizing their clothing items, including t-shirts, hoodies, and other apparel.
Regional Insights
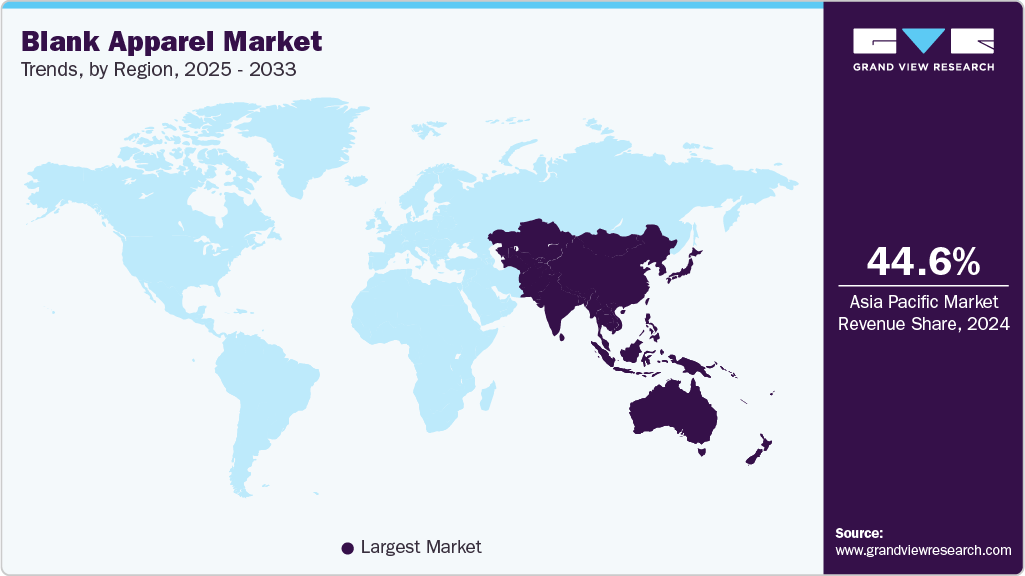
Asia Pacific dominated the blank apparel market with the largest revenue share of 44.8% in 2025, due to its strong textile and garment manufacturing ecosystem, cost-competitive production capabilities, and growing demand for customized apparel across both domestic and export markets. Countries across the region serve as major sourcing hubs for blank garments used in screen printing, embroidery, promotional products, and private-label apparel production. The expansion of e-commerce platforms, rising disposable incomes, increasing popularity of personalized fashion, and growing adoption of print-on-demand business models have further accelerated market growth. Additionally, the presence of large-scale apparel manufacturers, integrated supply chains, and abundant raw material availability continues to strengthen the region’s leadership in the global blank apparel market.
 To learn more about this report, Download Free Sample Report
China Blank Apparel Market Trends
The blank apparel market in the China held the largest share of about 40.9% in the Asia Pacific region in 2025, owing to its extensive textile manufacturing infrastructure, large production capacity, and well-established export-oriented apparel industry. The country is a key supplier of blank t-shirts, sweatshirts, polos, and other apparel products to global distributors, decorators, and fashion brands. Strong domestic demand for customized clothing, promotional merchandise, and private-label apparel further supports market growth. In addition, continuous investments in automated manufacturing technologies, efficient supply chain networks, and large-scale fabric production capabilities enable Chinese manufacturers to maintain competitive pricing and consistent product quality, reinforcing the country's dominant position within the regional blank apparel market.
North America Blank Apparel Market Trends
The North America blank apparel market is projected to grow at a CAGR of 5.0% from 2025 to 2033. Innovations in printing and embroidery technologies have made it more efficient and cost-effective to customize blank apparel. These advancements enable high-quality customization options, catering to the increasing demand for personalized clothing in the region. In March 2023, Mimaki USA unveiled the TxF150-75, its inaugural direct-to-film (DTF) printing system, alongside the PHT50 heat transfer pigment ink designed for DTF applications. This innovative printer targets the textile and apparel printing industry.
The U.S. blank apparel market is expected to witness a significant CAGR from 2025 to 2033. Partnerships play a crucial role in fueling innovation, expanding product offerings, and meeting consumer demands in the U.S. blank apparel market. Collaborations between manufacturers, fashion brands, and customization service providers enable the development of unique and personalized clothing options that resonate with modern consumers. For instance, in February 2023, Next Level Apparel announced a strategic partnership with GK Global to supply nearshore fabric. This collaboration between Next Level Apparel, a provider of high-quality blank apparel, and GK Global, a diverse global textiles company, represents a significant step toward sourcing 100% U.S.-grown cotton for the company’s complete clothing range.
Key Blank Apparel Company Insights
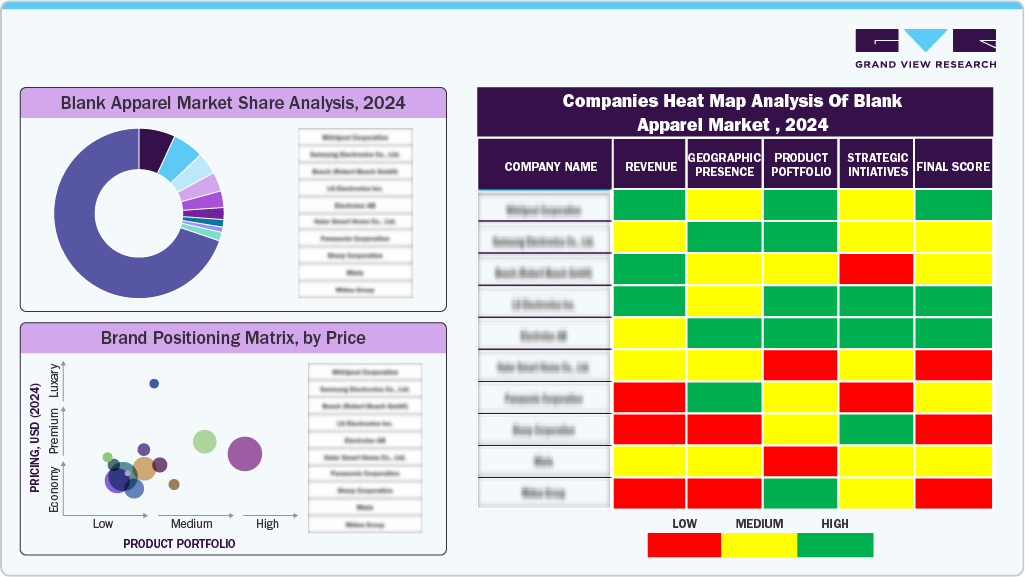
The global blank apparel market features Established players such as Gildan and BELLA+CANVAS lead the mid-tier segment by combining large-scale production, sustainable practices, and dependable fit, appealing to print-on-demand and promotional clients. In the premium bracket, brands such as Stanley/Stella, AS Colour, and Next Level Apparel attract design-conscious consumers with ethically sourced fabrics and elevated craftsmanship aimed at streetwear and lifestyle markets. Meanwhile, challengers including LANE SEVEN APPAREL, Independent Trading Company, SpectraUSA, Soffe Apparel (Delta Apparel, Inc.), and Los Angeles Apparel Inc. focus on innovation, affordability, and niche appeal-ranging from athletic blanks and fleecewear to made-in-USA craftsmanship and boutique designs. Together, these diverse players strengthen the market by serving both B2B and B2C channels, contributing to a dynamic ecosystem that blends quality, versatility, and sustainability in global blank apparel.
 To learn more about this report, Download Free Sample Report
Key Blank Apparel Companies
The following key companies have been profiled for this study on the blank apparel market.
-
BELLA+CANVAS
-
SpectraUSA
-
Gildan
-
Soffe Apparel, Inc. (Delta Apparel, Inc.)
-
Los Angeles Apparel Inc.
-
LANE SEVEN APPAREL
-
AS Colour
-
Independent Trading Company
-
Stanley/Stella
-
Next Level Apparel
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Gildan; BELLA+CANVAS; AS Colour; Stanley/Stella; Next Level Apparel)
- Expand vertically integrated manufacturing and sourcing capabilities to ensure cost efficiency, quality consistency, and reliable supply for decorators, print-on-demand providers, and apparel brands.
- Invest in sustainable materials, ethical production practices, premium fabric innovation, and global distribution networks while strengthening partnerships with wholesalers, screen printers, embroiderers, and e-commerce fulfillment providers.
- Strong brand recognition among apparel decorators and private-label customers, supported by large-scale production capabilities and extensive product portfolios.
- Established global distribution networks, supply chain efficiencies, and the ability to offer consistent quality, color ranges, and inventory availability across multiple markets.
- High exposure to fluctuations in cotton prices, labor costs, trade policies, and supply chain disruptions.
- Large-scale operations can reduce flexibility in responding quickly to emerging fashion trends, niche customer demands, and customized product requirements.
Emerging & Specialized Players (SpectraUSA; Soffe Apparel, Inc. (Delta Apparel, Inc.); Los Angeles Apparel Inc.; LANE SEVEN APPAREL; Independent Trading Company)
- Focus on premium blanks, fashion-forward silhouettes, heavyweight fabrics, made-in-USA offerings, and specialized products targeting streetwear brands, independent designers, and premium print-on-demand businesses.
- Leverage product differentiation, faster design-to-market cycles, and strong relationships with niche apparel decorators and boutique clothing brands to capture higher-margin opportunities.
- Greater agility in responding to evolving consumer preferences for oversized fits, premium fabrics, sustainable sourcing, and fashion-oriented blank apparel.
- Ability to differentiate through specialized product offerings, regional manufacturing capabilities, and strong positioning within high-growth streetwear and creator-commerce segments.
- Smaller production scale and distribution reach compared to industry leaders, resulting in lower purchasing power and inventory flexibility.
- Greater vulnerability to economic downturns, demand fluctuations, and competitive pricing pressure from large vertically integrated manufacturers with global sourcing advantages.
Recent Developments
-
In February 2024, Lane Seven Apparel took a major leap toward direct-to-consumer (DTC) sales with the debut of its e-commerce retail platform. The brand's new retail line enables it to establish a direct connection with the end consumer. The retail collection featured a variety of unisex pieces crafted from high-quality fabrics, such as three-end fleece, signature vintage, and 100% combed ringspun cotton, with prices ranging from USD 18 to USD 42.
-
In January 2024, Stanley/Stella took a step toward sustainability with the launch of its Spring/Summer 2024 collection. The collection not only brings innovation to popular styles but also revitalizes its women's t-shirt line. With a focus on lightweight materials and attention to detail, this collection was developed to offer even better quality and options for printing or embroidery.
Blank Apparel Market Report Scope
Report Attribute
Details
Market size in 2025
USD 15.9 billion
Estimated market size in 2026
USD 16.6 billion
Projected market size by 2033
USD 24.0 billion
Growth rate
CAGR of 5.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Australia & New Zealand; Brazil; South Africa
Key companies profiled
BELLA+CANVAS; SpectraUSA; Gildan; Soffe Apparel, Inc. (Delta Apparel, Inc.); Los Angeles Apparel Inc.; LANE SEVEN APPAREL; AS Colour; Independent Trading Company; Stanley/Stella; Next Level Apparel
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Blank Apparel Market Report Segmentation
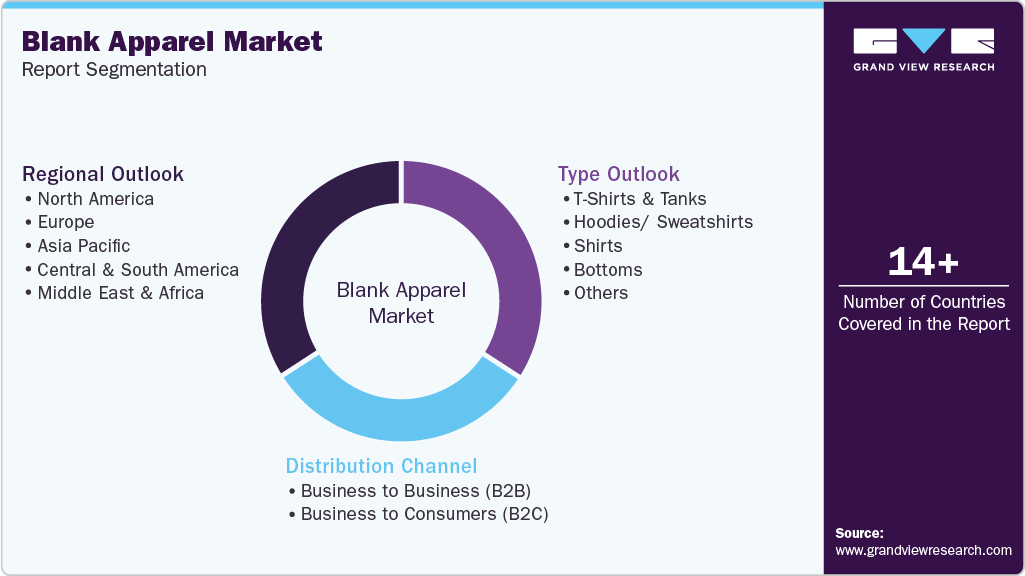
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global blank apparel market report on the basis of type, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
T-Shirts & Tanks
-
Hoodies/ Sweatshirts
-
Shirts
-
Bottoms
-
Others
-
-
Distribution Channel (Revenue, USD Million, 2021 - 2033)
-
Business to Business (B2B)
-
Business to Consumers (B2C)
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
-
Research Methodology
The blank apparel market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each blank apparel segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment -Type
Revenue capture definition
T-Shirts & Tanks
This segment covers blank short-sleeve and long-sleeve t-shirts, tank tops, sleeveless shirts, crew necks, V-necks, and performance tees sold without decorative prints or branding. The scope includes apparel supplied for customization, promotional use, retail resale, corporate merchandising, uniforms, and private-label applications across various fabric compositions and fit categories.
Hoodies/Sweatshirts
This segment includes blank hooded sweatshirts, pullovers, zip-up hoodies, crewneck sweatshirts, fleece tops, and performance outerwear designed for customization and resale. The scope covers lightweight, midweight, and heavyweight variants supplied to printers, embroiderers, promotional product companies, retailers, and fashion brands across multiple material blends and construction styles.
Shirts
This segment encompasses blank woven and knit shirts including polo shirts, button-down shirts, oxford shirts, work shirts, and casual shirts supplied without logos or graphics. The scope includes products intended for uniforms, corporate branding, hospitality applications, promotional programs, and private-label retail channels across different fabrics, sleeve lengths, and fit profiles.
Bottoms
This segment covers blank apparel bottoms such as sweatpants, joggers, shorts, leggings, track pants, lounge pants, and workwear bottoms offered for decoration or resale. The scope includes products supplied across activewear, casualwear, promotional apparel, uniform programs, and private-label collections with various fabric weights, performance features, and fit specifications.
Others
This segment includes blank apparel products not categorized under primary garment types, such as jackets, vests, thermals, bodysuits, aprons, and specialty apparel items. The scope covers products supplied for customization, corporate branding, promotional campaigns, workwear, and retail distribution across a broad range of materials, designs, and end-use applications.
Segment - Distribution Channel
Revenue capture definition
Business to Business (B2B)
This segment covers sales of blank apparel to organizations, distributors, wholesalers, decorators, screen printers, embroidery service providers, promotional product companies, educational institutions, and corporate buyers. The scope includes bulk procurement, contract supply agreements, wholesale transactions, and private-label sourcing conducted through manufacturer-direct and intermediary distribution networks.
Business to Consumers (B2C)
This segment includes direct sales of blank apparel to individual consumers through e-commerce platforms, brand-owned websites, retail stores, marketplaces, and specialty apparel outlets. The scope covers single-unit and small-volume purchases for personal use, DIY customization, crafting, casual wear, and independent resale activities across online and offline retail channels.
Estimation Model
Layer Title
Guiding Question
Description
Customizable Apparel Demand Layer
Who requires apparel that serves as a blank canvas?
Start with global demand from promotional merchandise companies, print-on-demand businesses, corporate branding programs, educational institutions, sports teams, workforce providers, event organizers, and emerging apparel brands. Apply apparel customization and branded merchandise demand indicators to identify the potential user base for blank garments.
Distribution & Manufacturing Accessibility Layer
Who can be supplied through wholesale apparel channels?
Filter the eligible demand base using wholesale distribution coverage, garment manufacturing capacity, print-service accessibility, e-commerce penetration, and regional sourcing ecosystems. This derives the addressable market accessible through blank apparel manufacturers, distributors, and fulfillment partners.
Purchase & Replenishment Layer
Who actively purchases blank apparel products?
Apply purchase frequency, inventory replenishment rates, merchandise program activity, print-on-demand volumes, and private-label apparel demand. Account for recurring purchases from screen printers, promotional product companies, corporate buyers, and apparel startups to estimate active demand.
Monetisation Layer
How much revenue is generated?
Multiply annual unit demand by blended ASPs across T-shirts & Tanks, Hoodies/Sweatshirts, Shirts, Bottoms, and other blank apparel categories. Include revenue generated from premium fabrics, sustainable materials, heavyweight garments, and private-label programs to estimate total market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Print-on-Demand (POD), Custom Decoration & End-Market Demand Mapping
Comprehensive analysis of blank apparel demand across key customization end markets including print-on-demand businesses, screen printers, embroidery service providers, promotional product distributors, corporate merchandise suppliers, sports teams, educational institutions, and creator-led apparel brands. The study maps demand across T-shirts & tanks, hoodies/sweatshirts, shirts, and bottoms while identifying the preferred garment categories for each end-user segment.
Identifies which product categories benefit most from customization spending and where future volume growth is concentrated. Helps manufacturers understand how demand is shifting from traditional promotional apparel toward creator merchandise, e-commerce POD platforms, influencer brands, and small-batch apparel businesses. Highlights the increasing importance of decoration compatibility, print quality, and fabric consistency in purchasing decisions.
Brand Positioning & Competitive Benchmarking Across the Blank Apparel Ecosystem
Detailed benchmarking of major blank apparel suppliers including Gildan, BELLA+CANVAS, Next Level Apparel, Stanley/Stella, AS Colour, Lane Seven Apparel, SpectraUSA, and others. The assessment evaluates competitive positioning across product quality, sustainability credentials, fabric innovation, color assortment, inventory depth, decoration friendliness, pricing strategy, and regional distribution networks.
Helps distinguish volume-driven manufacturers from premium fashion-oriented blank apparel providers. Reveals how brands compete through consistency, sustainable sourcing, eco-friendly materials, and fulfillment capabilities rather than solely on price. Also identifies competitive whitespace in premium POD-ready garments and sustainable blank apparel categories.
B2B Channel Structure & Distributor Opportunity Assessment
Analysis of the complete B2B supply chain including manufacturers, apparel wholesalers, decorators, contract printers, promotional product distributors, and corporate uniform suppliers. The study evaluates channel margins, inventory strategies, fulfillment models, and regional distributor concentration.
Provides visibility into where value is created across the blank apparel supply chain. Helps identify the most important distributors and partners for manufacturers and fulfillment operations, how inventory availability and fulfillment speed influence customer selection. Particularly relevant given the dominance of B2B sales within the industry.
Frequently Asked Questions About This Report
Asia Pacific dominated the market with a 44.8% revenue share in 2025.
The business-to-business (B2B) segment held the largest revenue share of 96.6% in 2025.
The t-shirts & tanks segment led the market with a 48.4% revenue share in 2025
The global blank apparel market is expected to grow at a CAGR of 5.4% from 2025 to 2033, reaching USD 24.0 billion by 2033.
Key players include BELLA+CANVAS, Gildan, AS Colour, Stanley/Stella, Next Level Apparel, Lane Seven Apparel, Independent Trading Company, Los Angeles Apparel, SpectraUSA, and Soffe Apparel, Inc..
Key factors include growing demand from the custom printing and apparel decoration industry, increasing adoption of private-label clothing by brands and retailers, expansion of e-commerce merchandise businesses, rising popularity of print-on-demand services, and growing demand for sustainable and ethically sourced blank garments.
The global blank apparel market size was valued at USD 15.9 billion in 2025 and is estimated at USD 16.6 billion in 2026.
About the Author(s)
Clothing, Footwear & Accessories Research Team
Consumer Goods · Clothing, Footwear & AccessoriesThis report was authored by the clothing, footwear & accessories research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clothing, footwear & accessories segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


