
- Home
- »
- Petrochemicals
- »
-
Carbon Black Feedstock Market Size & Share Report, 2033GVR Report cover

Carbon Black Feedstock Market (2026 - 2033)
Size, Share & Trends Analysis Report By Source (Clarified Slurry Oil, Coal Tar Oil, Ethylene Cracker Residue), By Product (High BMCI Type, General Type), By Region (North America, Europe, Asia Pacific), And By Segment Forecasts
Market Size, 2025
$8.0BMarket Estimate, 2026
$8.3BMarket Forecast, 2033
$11.3BCAGR, 2026–2033
4.4%Carbon Black Feedstock Market Summary
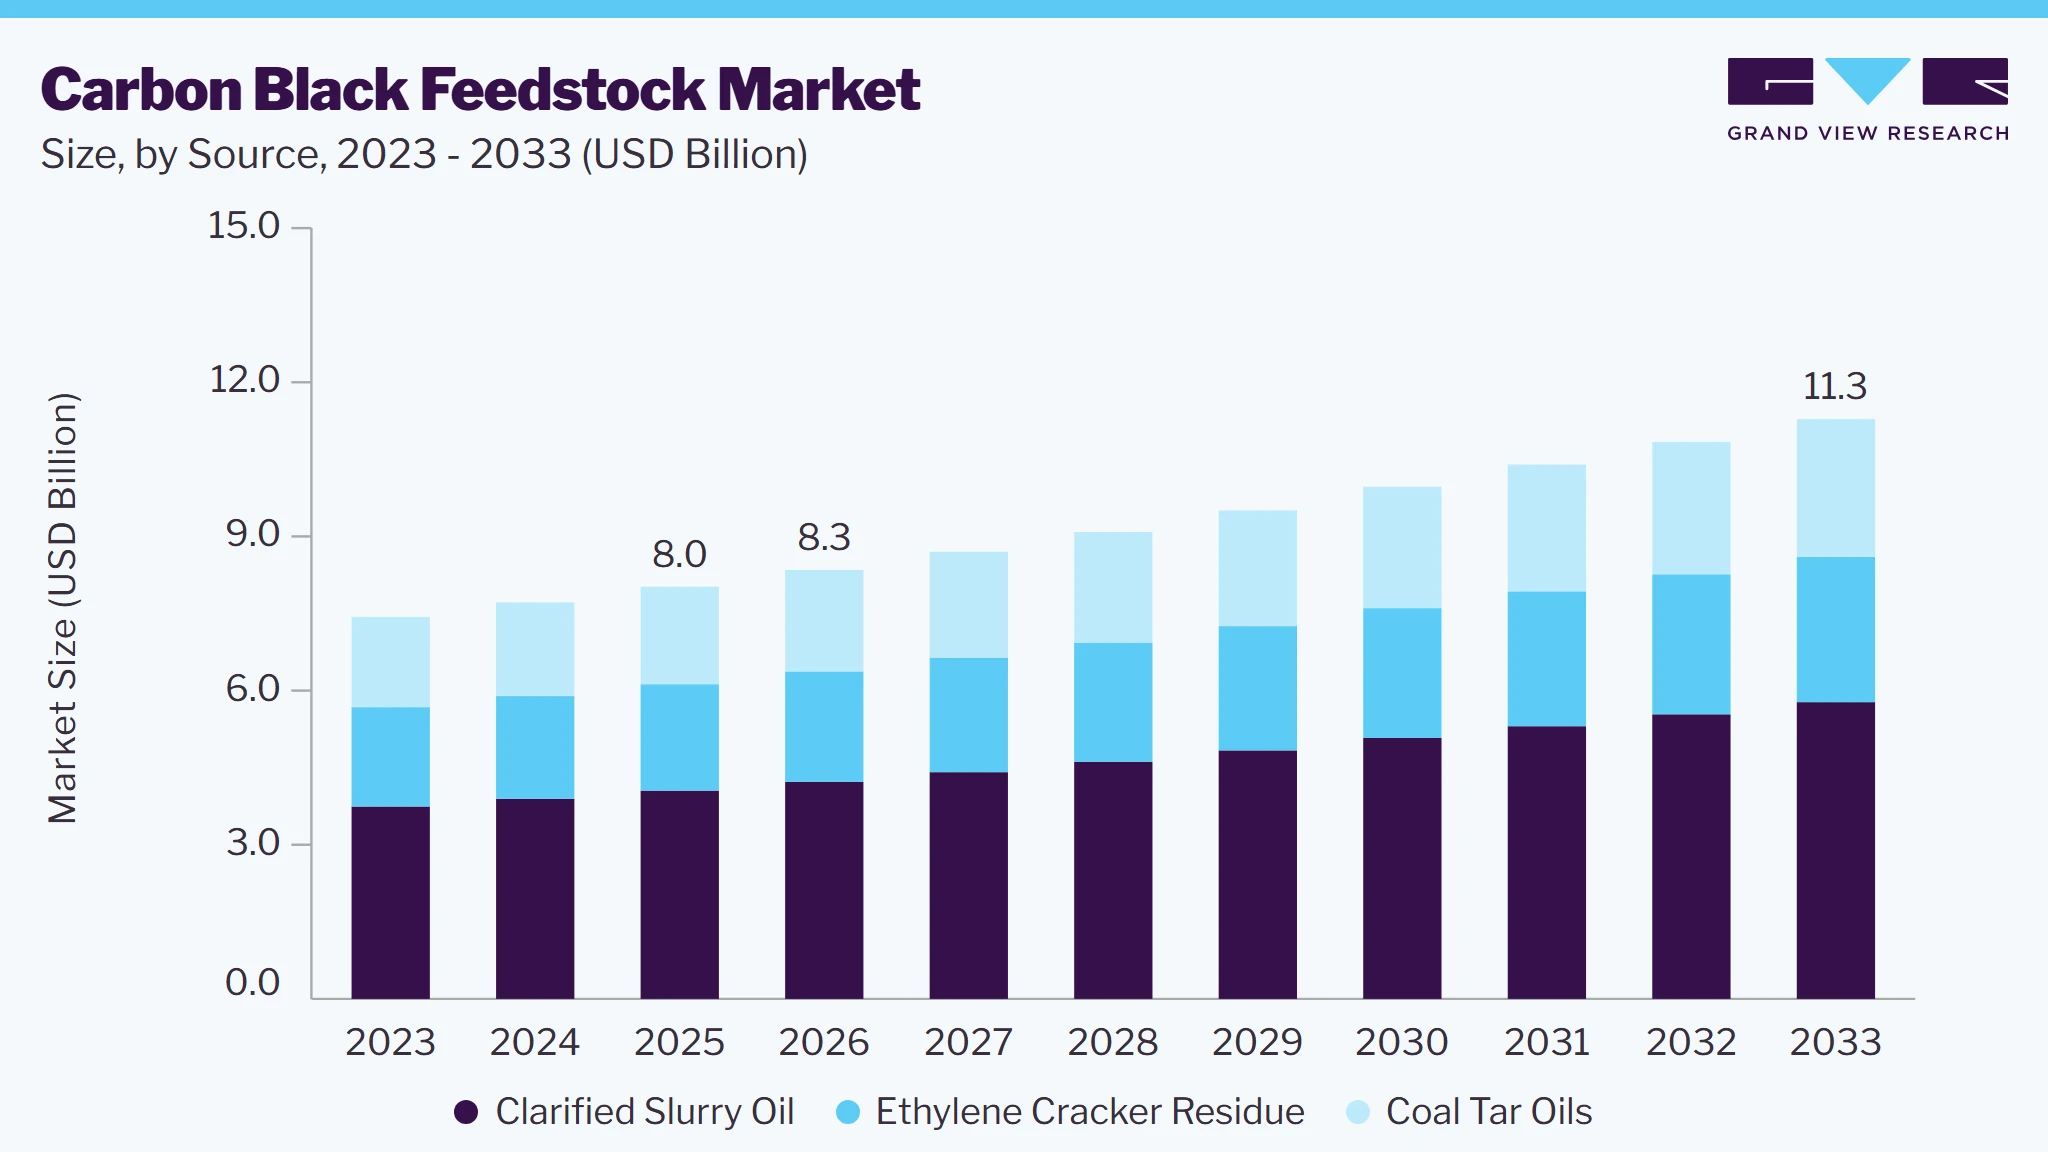
The global carbon black feedstock market size was valued at USD 8.0 billion in 2025 and is projected to grow from USD 8.3 billion in 2026 to USD 11.3 billion by 2033, at a CAGR of 4.4% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 43.1% in 2025. The market is primarily driven by the growing demand for carbon black, a key component in various industries.
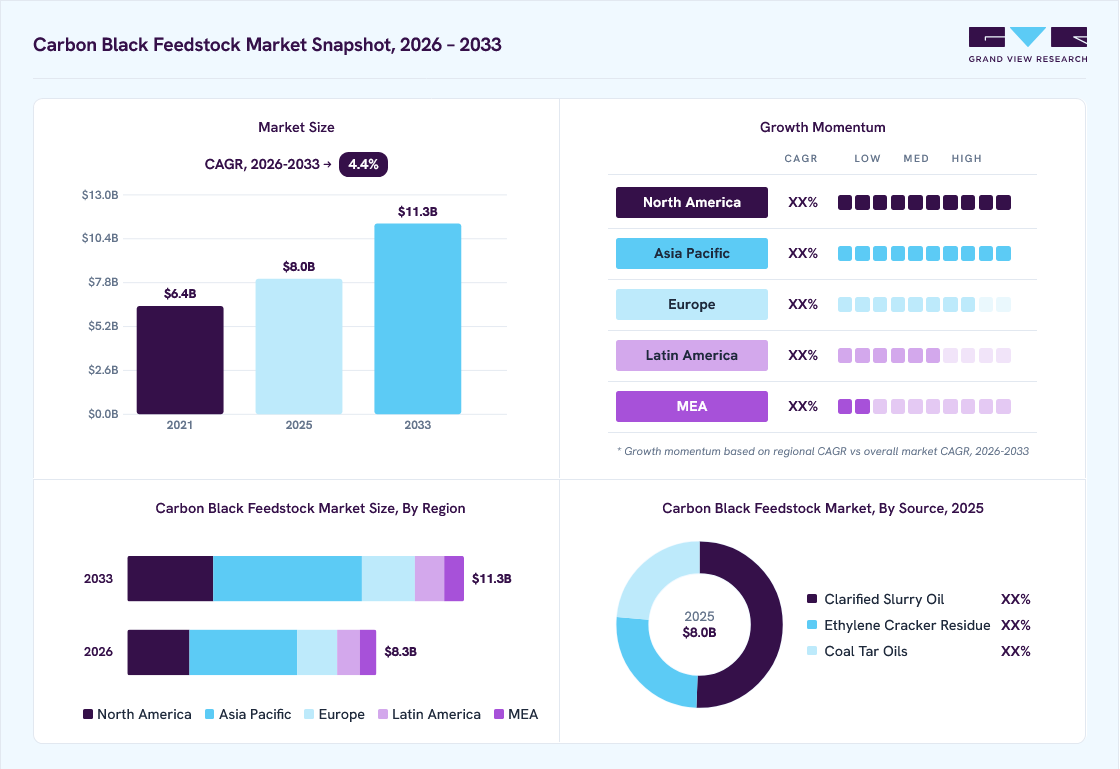 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By source: Clarified slurry oil segment held the largest market share of 50.5% in 2025.
- By product: General type segment held the largest market share of 55.4% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (43.1% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 8.0 Billion
- Estimated market size in 2026: USD 8.3 Billion
- Projected market size by 2033: USD 11.3 Billion
- CAGR (2026-2033): 4.4%
Prism AI by Grand View Research Free to tryAsk a question about the carbon black feedstock marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The increasing production of tires, plastics, rubber, and other products that require carbon black is a significant factor driving the market.In addition, the shift towards electric vehicles is expected to positively impact the carbon black feedstock market. While electric vehicles require fewer tires, they often incorporate carbon black in their batteries and other components, which could offset the decline in tire demand. Furthermore, the increasing focus on sustainability and the development of carbon black from renewable sources are also contributing to the growth of the market.
 To learn more about this report, Download Free Sample Report
The increasing production of tires, plastics, rubber, and other products that require carbon black is a major driver. While electric vehicles require fewer tires, they often incorporate carbon black in their batteries and other components. Government regulations related to emissions and environmental standards can impact the use of carbon black.
Market Dynamics
The carbon black feedstock market is being shaped by evolving refinery operations, increasing demand for high-performance carbon black, and changing environmental regulations governing heavy aromatic oils. Growth in the tire, automotive, industrial rubber, and specialty chemicals industries continues to support demand for premium feedstocks with consistent composition and high aromatic content. Refiners are also optimizing the utilization of by-products such as clarified slurry oil and ethylene cracker residue, improving feedstock availability while enhancing overall refinery economics. At the same time, investments in carbon black production capacity across emerging economies are strengthening long-term consumption of feedstock materials. However, the market faces challenges from fluctuating crude oil prices, tightening emission standards, and growing pressure to reduce the environmental footprint of conventional petroleum-derived feedstocks. Manufacturers are increasingly focusing on process efficiency, supply chain resilience, and the development of lower-emission production technologies to remain competitive.
The steady expansion of the global tire and industrial rubber industries remains a primary driver for the carbon black feedstock market. Carbon black is an essential reinforcing material used in the production of tires, conveyor belts, hoses, seals, and various molded rubber products, making the availability of high-quality feedstocks critical for manufacturers. As vehicle production, freight transportation, mining, and industrial manufacturing continue to expand, the consumption of carbon black increases correspondingly. This trend has encouraged refiners and feedstock suppliers to strengthen production capabilities for clarified slurry oil, ethylene cracker residue, and coal tar oils to ensure a reliable supply of aromatic-rich raw materials required for carbon black manufacturing.
Manufacturers are increasingly prioritizing feedstocks with higher aromaticity and stable chemical composition to improve carbon black yield, production efficiency, and product quality. The expansion of carbon black production facilities, coupled with strategic supply agreements between refiners and carbon black manufacturers, continues to reinforce demand for specialized feedstocks, creating sustained growth opportunities throughout the value chain.
The carbon black feedstock market is restrained by its strong dependence on refinery operations and the variable availability of petroleum-derived feedstocks. Key raw materials such as clarified slurry oil, ethylene cracker residue, and coal tar oils are generated as by-products of refining and petrochemical processes, making their supply directly influenced by refinery throughput, production strategies, and maintenance schedules. Variations in crude oil processing, operational disruptions, or changing demand for refined petroleum products can reduce feedstock availability and create supply imbalances. These fluctuations often result in unpredictable raw material costs, making procurement planning more complex for carbon black manufacturers. As a result, producers may face increased production expenses, pressure on profit margins, and challenges in maintaining consistent manufacturing operations. To address these issues, companies are increasingly emphasizing diversified sourcing strategies, long-term supplier partnerships, and improved inventory planning to enhance supply security and minimize operational risks.
An important opportunity for the carbon black feedstock market lies in the increasing integration of refining and petrochemical operations aimed at maximizing the commercial value of refinery by-products. Feedstocks such as clarified slurry oil and ethylene cracker residue were traditionally considered secondary refinery streams, but advances in refining technologies have enabled their efficient conversion into valuable raw materials for carbon black production. This shift allows refiners to improve resource utilization, diversify revenue streams, and reduce waste while meeting the growing requirements of downstream carbon black manufacturers.
Companies are investing in advanced processing technologies, logistics infrastructure, and long-term supply partnerships to improve feedstock consistency and operational efficiency. As carbon black producers seek secure and cost-effective sources of raw materials, closer collaboration with integrated refining and petrochemical facilities is expected to create significant commercial opportunities, strengthen supply chain resilience, and support sustainable growth across the global market.
Analyst Perspective
The carbon black feedstock market is supported by sustained demand from the tire, industrial rubber, and specialty chemicals industries. Refinery integration and the efficient utilization of aromatic by-products are improving feedstock availability and strengthening supply chain economics. At the same time, manufacturers are investing in higher-quality feedstocks and process optimization to enhance carbon black yield and production efficiency. While crude oil price fluctuations and evolving environmental regulations remain key challenges, the market is adapting through improved sourcing strategies and technological advancements. Overall, long-term demand for high-performance carbon black is expected to create stable growth opportunities for feedstock suppliers across both established and emerging markets.
Source Insights
By source, clarified slurry oil held a dominant position, contributing 50.5% of total revenue in 2025. The market is segmented into clarified slurry oil, ethylene cracker residue, and coal tar oils. Clarified slurry oil (CSO) is a byproduct of the sugar industry that can produce carbon black as a feedstock. CSO is a dark, viscous liquid that is rich in hydrocarbons. After a clarification process to remove impurities, it can be processed into carbon black, a valuable material used in various industries.
Coal tar oil is another potential feedstock for carbon black production. It is a byproduct of the coal tar distillation process and is rich in aromatic hydrocarbons. Its high carbon content makes it suitable for carbon black production. The use of coal tar oil as a carbon black feedstock is well-established, with proven production processes in place.
Ethylene cracker residue (ECR) is a byproduct of ethylene production. It is a complex mixture of hydrocarbons that can be used as a feedstock for carbon black production. ECR's high carbon content makes it suitable for this purpose. Finding a valuable use for this byproduct can help reduce the petrochemical industry's environmental impact.
Product Insights
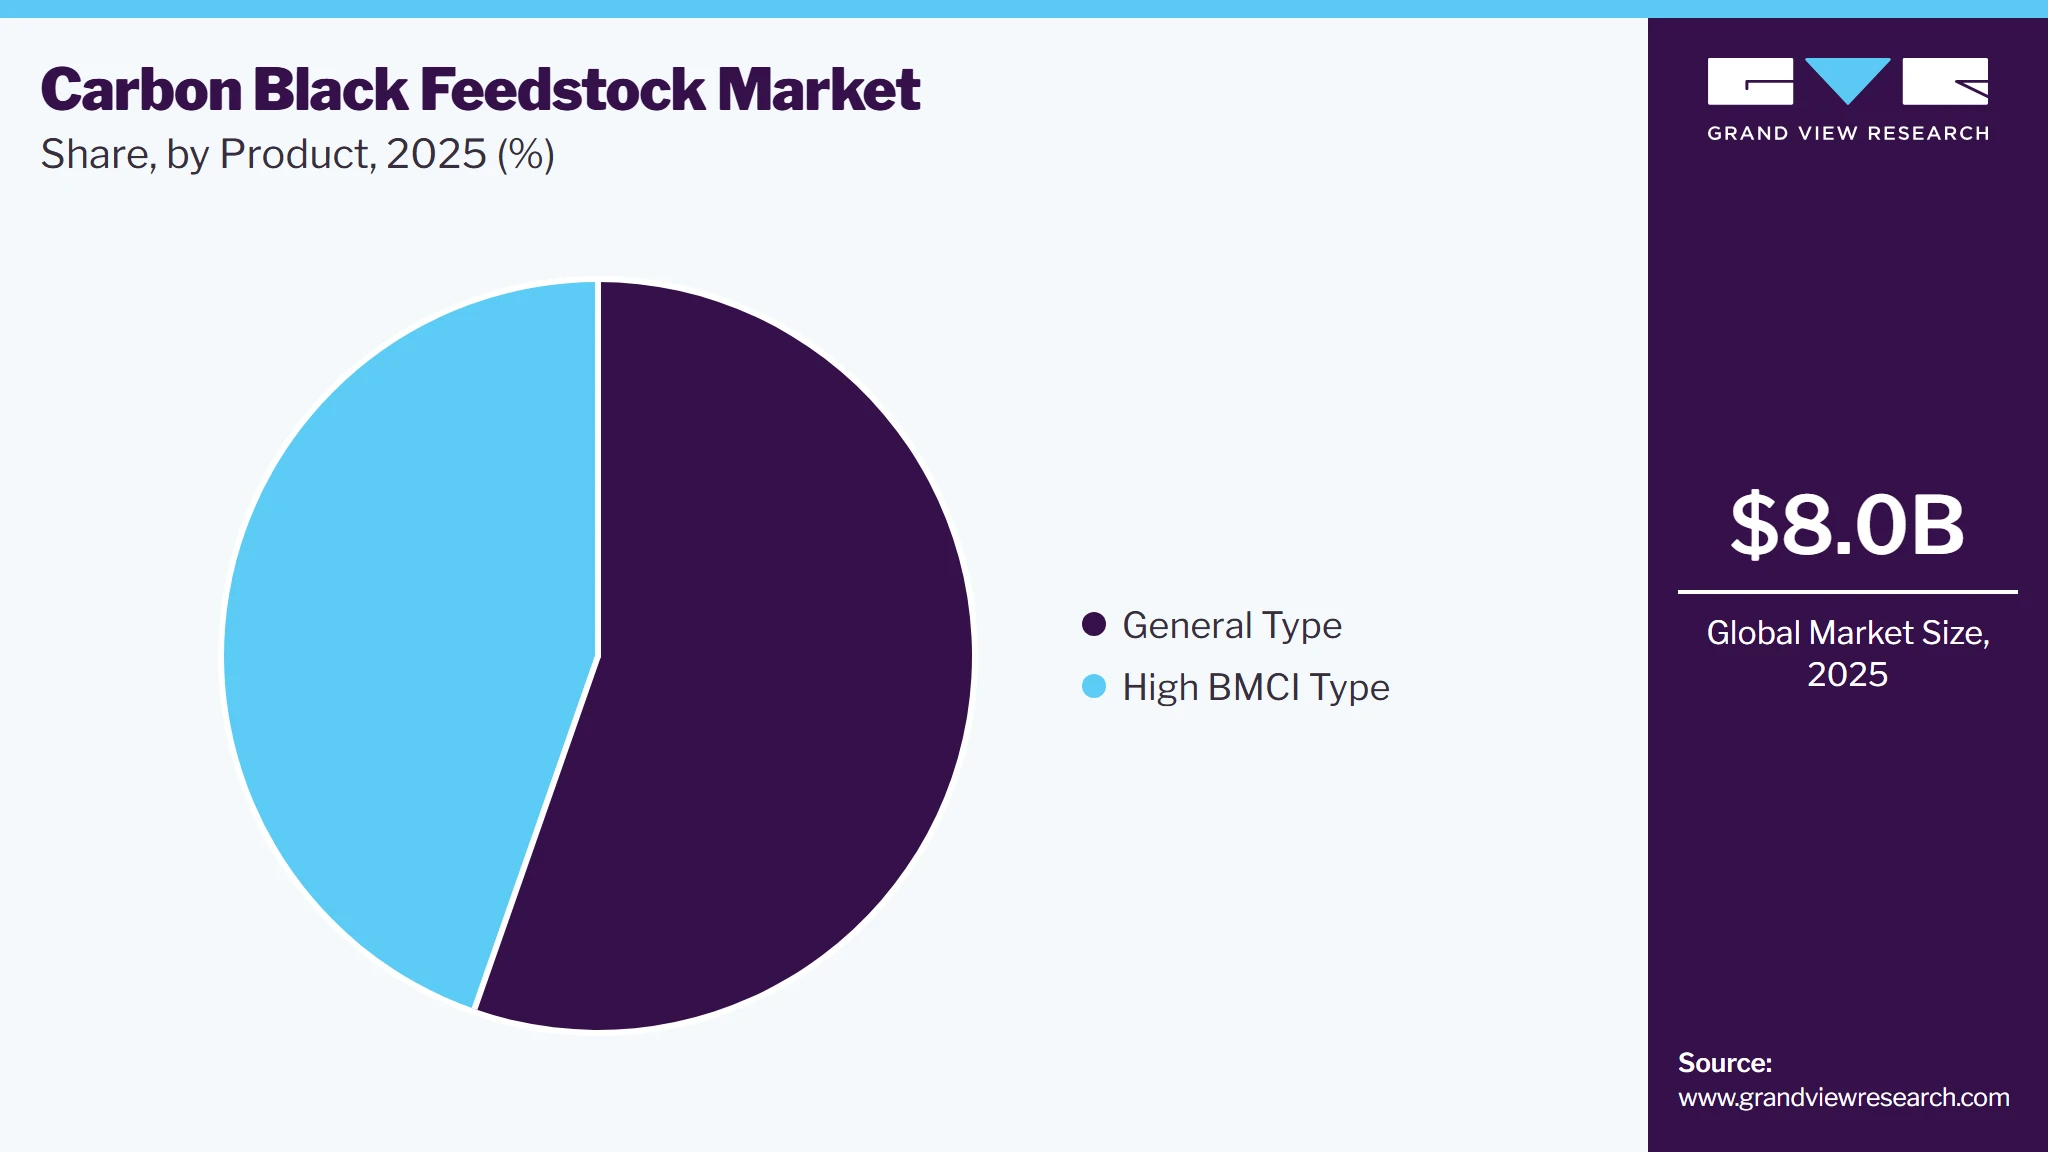
Based on product, the general type accounted for the highest market share, representing 55.4% of total revenue in 2025. General type carbon black is a broad category that encompasses various types of carbon black with a wide range of properties. It is used in various applications, including tires, plastics, rubber, and inks. It is used as a filler and reinforcement material in plastics, such as polyethylene and polypropylene. It is also used to improve rubber products' strength, durability, and abrasion resistance.
 To learn more about this report, Download Free Sample Report
High BMCI type carbon black is a type of carbon black characterized by its high black modulus (BMCI). This property indicates its ability to reinforce rubber compounds, making it a valuable material for applications requiring high strength, durability, and abrasion resistance.
Regional Insights
The key driver influencing the carbon black feedstock market in North America is the growing demand for carbon black itself. This demand is primarily fueled by the region's robust automotive industry, which is a major consumer of carbon black for tire production. Additionally, the plastics and rubber industries in North America also contribute significantly to the demand for carbon black.
U.S. Carbon Black Feedstock Market Trends
The demand for carbon black feedstock in the U.S. has been steadily increasing due to the expanding automotive industry, particularly the production of electric vehicles (EVs). EVs require more carbon black than traditional gasoline powered vehicles due to their larger battery capacity and need for reinforced tires.
Asia Pacific Carbon Black Feedstock Market Trends
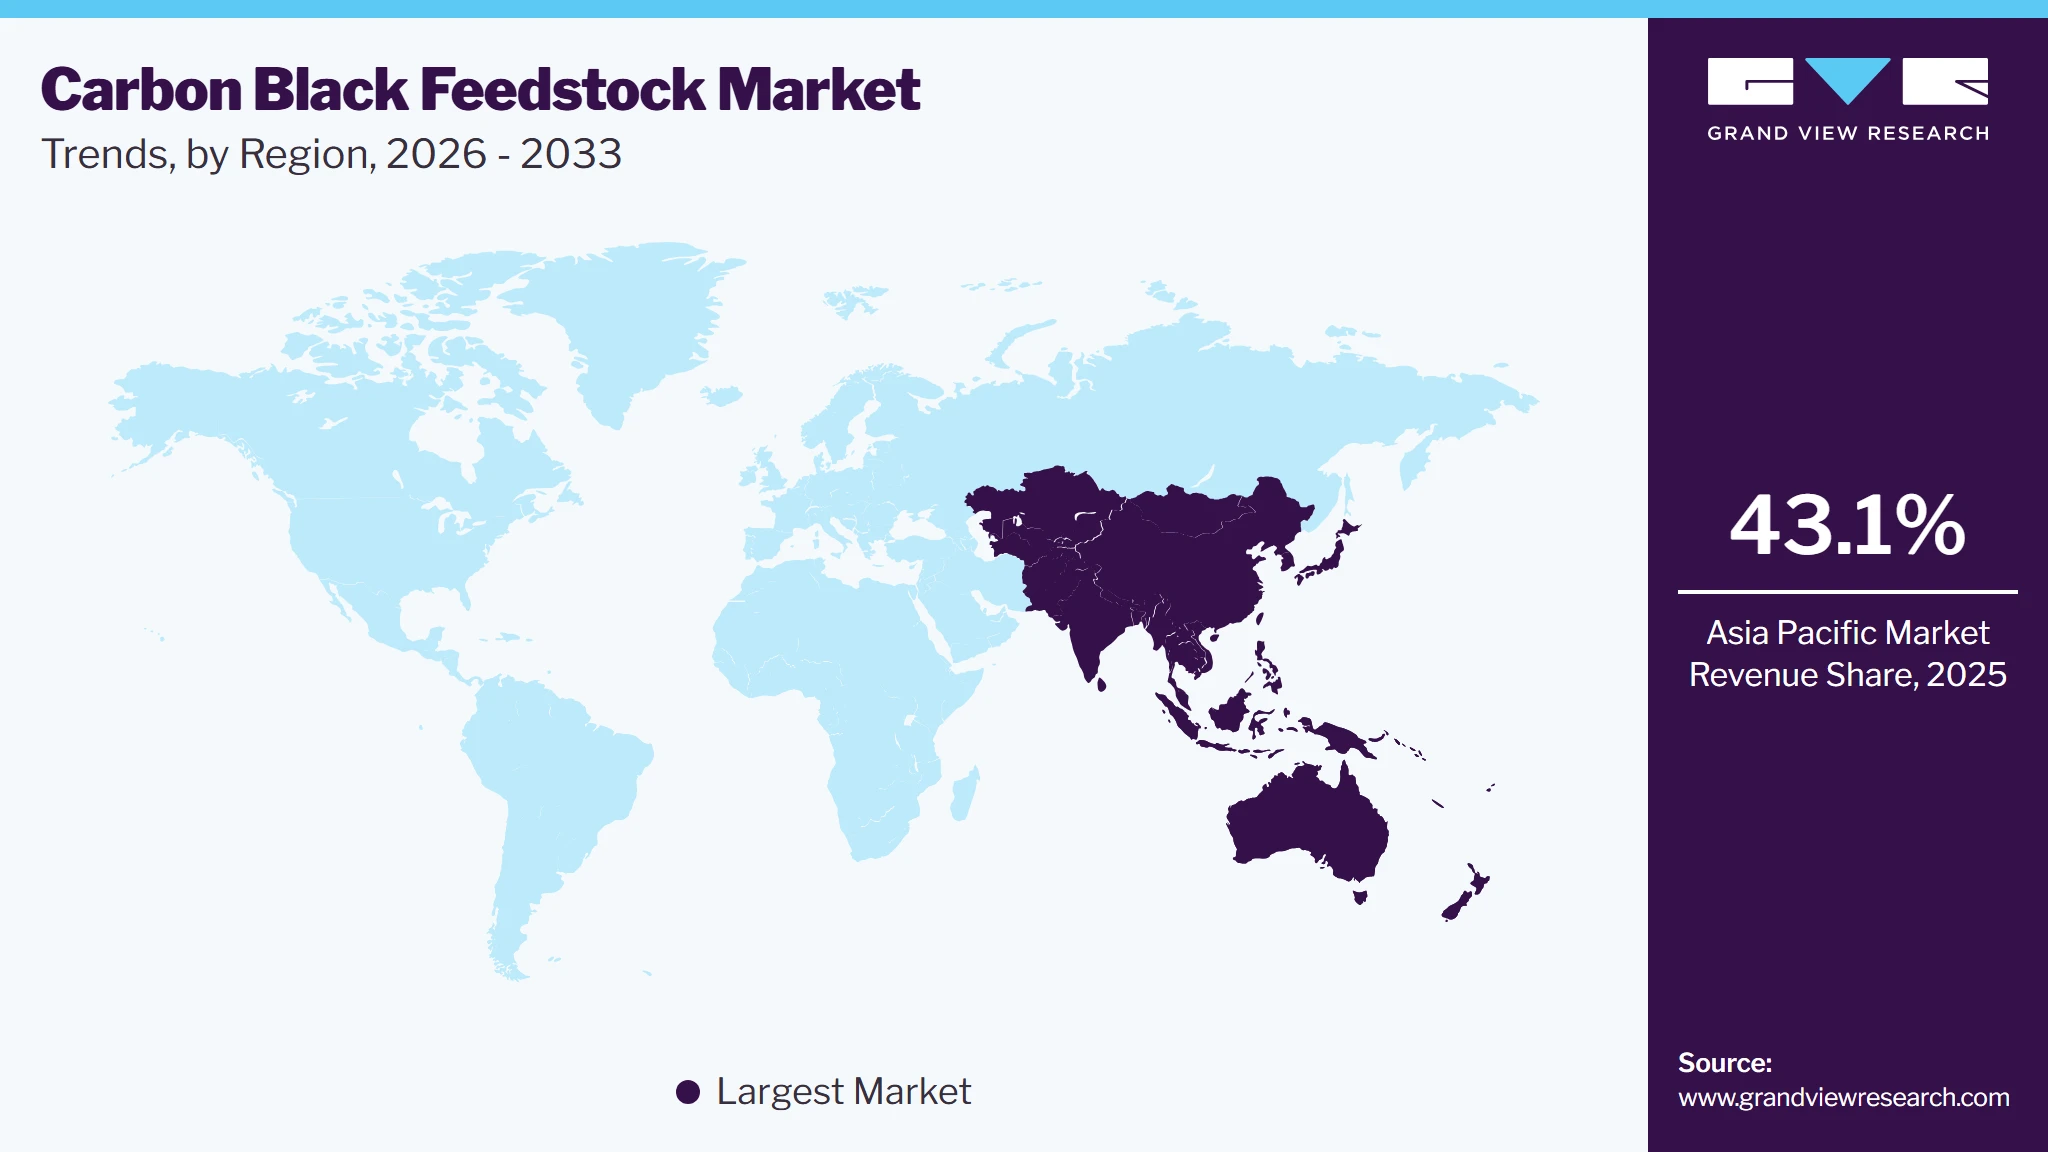
Asia Pacific dominated the carbon black feedstock market with the highest revenue share of 43.1% in 2025, and is expected to grow at a significant rate from 2024 to 2030. The Asia-Pacific region is home to some of the world's largest automotive markets, and the demand for cars and other vehicles is driving the demand for carbon black used in tires and other components. The region is experiencing rapid industrialization, leading to increased demand for products that require carbon black, such as tires, plastics, rubber, and inks.
 To learn more about this report, Download Free Sample Report
Europe Carbon Black Feedstock Market Trends
Europe is a major automotive market, and the demand for cars and other vehicles drives the demand for carbon black used in tires and other components. The plastics and rubber industries in Europe are also major consumers of carbon black, used as a reinforcement material and pigment. European Union regulations regarding emissions and product safety have influenced the use of carbon black in various applications, driving demand for specific types of carbon black.
Central & South America Carbon Black Feedstock Market Trends
The key driver influencing the carbon black feedstock market in Central and South America is the rapid industrialization and economic growth in the region. As these countries develop and modernize, there is a surge in demand for various products that require carbon black, such as tires, plastics, rubber, and inks.
Key Carbon Black Feedstock Company Insights
Some key players operating in the market are Dow and BASF SE
-
Dow is a global materials science company that produces a wide range of products used in various industries. Founded in 1897, Dow is one of the world's largest chemical companies. Dow offers solutions for a wide range of industries, including automotive, construction, electronics, and energy.
-
BASF SE is a German multinational chemical company. It is one of the world's largest chemical producers, offering a wide range of products and solutions across various industries.The company is committed to sustainability and has implemented various initiatives to reduce its environmental impact.
Haldia Petrochemicals Ltd (HPL) and Arham Petrochem Private Limited are some emerging participants in the market.
-
Haldia Petrochemicals Ltd. (HPL) is a joint venture between the Indian Government and a consortium of global petrochemical companies. It is a major petrochemical complex located in Haldia, West Bengal, India. HPL is one of the largest petrochemical complexes in India and a significant contributor to the country's petrochemical industry. It plays a crucial role in meeting the domestic demand for petrochemical products and also exports to international markets.
-
Arham Petrochem Private Limited is an Indian petrochemical company that specializes in the production and distribution of various petrochemical products. While I couldn't find specific details about their operations and products, based on their name, it's likely that they are involved in the petrochemical industry.
Key Carbon Black Feedstock Companies:
The following key companies have been profiled for this study on the carbon black feedstock market.
- Dow
- Arham Petrochem Private Limited
- Haldia Petrochemicals Ltd (HPL)
- Jalan Carbons & Chemicals (P) Ltd.
- Shell
- BASF
- Aramco
- Sherwin-Williams Company
- Epsilon Carbon Private Limited
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Indian Oil Corporation Ltd, Dow, Haldia Petrochemicals Ltd (HPL), Shell, BASF SE, Aramco, Sherwin-Williams Company)
- Operate integrated refining and petrochemical value chains to ensure secure feedstock availability.
- Invest in process optimization, capacity expansion, and advanced production technologies.
- Establish long-term supply contracts with carbon black manufacturers and industrial customers.
- Expand global distribution networks while strengthening sustainability and operational efficiency initiatives.
- Strong brand recognition and established relationships across global energy and chemical markets.
- Large-scale manufacturing capacity with diversified feedstock portfolios.
- Robust financial resources supporting technology upgrades and business expansion.
- Extensive supply chain and logistics capabilities ensuring reliable product availability.
- Large organizational structures can slow strategic decision-making and operational adjustments.
- High capital expenditure requirements for refinery modernization and regulatory compliance.
- Greater exposure to global crude oil price volatility and geopolitical risks.
- Complex international operations increased supply chain and compliance management challenges.
Emerging Players (Arham Petrochem Private Limited, Jalan Carbons & Chemicals (P) Ltd., Epsilon Carbon Private Limited)
- Focus on niche product offerings and customized feedstock solutions for regional customers.
- Increase production capabilities through targeted investments in processing and storage infrastructure.
- Build strategic partnerships with domestic refiners and downstream carbon black producers.
- Strengthen market presence by offering competitive pricing and responsive customer service.
- Greater operational flexibility to address changing customer requirements.
- Faster decision-making and ability to capitalize on regional market opportunities.
- Specialized expertise in selected feedstock grades and domestic supply networks.
- Lean operating structures that enable competitive pricing in targeted markets.
- Limited production capacity compared with multinational competitors.
- Lower investment capability for advanced technologies and large-scale expansion projects.
- Heavy dependence on regional demand and domestic refinery feedstock availability.
- Smaller distribution networks and lower global brand visibility can restrict international market penetration.
Recent Developments
-
In May 2022, Sabic introduced five carbon black grades in ASTM 2 and 3 series (N220, N326, N330, N339 and N375) in GCC. Sabic’s high reinforcing grades are used by the rubber industry for various end-product applications like tires, molded rubber goods, conveyor belts, rubber sheeting and other industrial rubber products to enhance their durability.
Carbon Black Feedstock Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.0 billion
Estimated market size in 2026
USD 8.3 billion
Projected market size by 2033
USD 11.3 billion
Growth rate
CAGR of 4.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million, Volume in Kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Source, product, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK, Germany; France; Italy; Spain; China; India; Japan; South Korea; Brazil; Argentina; South Africa; Saudi Arabia
Key companies profiled
Indian Oil Corporation Ltd; Dow; Arham Petrochem Private Limited; Haldia Petrochemicals Ltd (HPL); Jalan Carbons & Chemicals (P) Ltd.; Shell; BASF SE; Aramco; Sherwin-Williams Company; Epsilon Carbon Private Limited
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Carbon Black Feedstock Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the industry trends in each of the segments from 2021 to 2033. For this study, Grand View Research has segmented the global carbon black feedstock market based on the source, product, and region:
 To learn more about this report, Download Free Sample Report
-
Source Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Clarified Slurry Oil
-
Ethylene Cracker Residue
-
Coal Tar Oils
-
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
High BMCI Type
-
General Type
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The carbon black feedstock market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each carbon black feedstock segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Source
Revenue capture definition
Clarified Slurry Oil
Revenue growth is driven by its extensive use as a high-aromatic feedstock for carbon black manufacturing, offering consistent quality, favorable carbon yield, and reliable availability from refinery operations.
Ethylene Cracker Residue
Market expansion is supported by increasing utilization of aromatic-rich residue streams that enhance carbon black production efficiency while improving the value realization of petrochemical by-products.
Coal Tar Oils
Commercial demand is reinforced by their high aromatic content and suitability for producing specialty carbon black grades used in tires, rubber goods, inks, coatings, and conductive applications.
Product
Revenue capture definition
High BMCI Type
Revenue generation is supported by rising demand for premium feedstocks with elevated aromaticity that deliver superior carbon black yield, process efficiency, and consistent product performance for high-specification applications.
General Type
Business growth is fueled by broad adoption in standard carbon black manufacturing, where cost-effective feedstocks provide dependable performance for a wide range of industrial rubber and non-rubber applications.
Estimation Model
Layer Name
Key Question
Description
Raw Material & Production Layer
What forms the supply base?
Assess global carbon black feedstock production based on the availability of clarified slurry oil, ethylene cracker residue, coal tar oils, and other aromatic refinery streams. Evaluate refinery integration, feedstock recovery, processing technologies, quality optimization, storage, logistics, and distribution while analyzing raw material sourcing strategies, production economics, manufacturing capacity, and key refining hubs shaping global supply.
Application Adoption Layer
Where is carbon black feedstock consumed?
Examine the utilization of carbon black feedstock across major carbon black manufacturing applications serving tire production, industrial rubber goods, plastics, inks, coatings, batteries, and specialty chemicals. Market adoption is influenced by increasing demand for high-performance carbon black, growth in automotive and industrial manufacturing, and the need for feedstocks with consistent aromatic composition and processing efficiency.
Consumption Intensity Layer
How much carbon black feedstock is utilized?
Analyze consumption patterns by evaluating feedstock requirements across different carbon black production facilities and process technologies. The assessment considers production capacity, carbon black grade mix, feedstock conversion efficiency, refinery output, downstream manufacturing demand, and regional industrial activity to estimate overall market consumption.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the commercial supply of clarified slurry oil, ethylene cracker residue, coal tar oils, and other aromatic feedstocks to carbon black manufacturers. Commercial growth is supported by expanding tire and rubber production, increasing investments in refining and petrochemical integration, demand for premium high-BMCI feedstocks, technological improvements in feedstock processing, and long-term supply agreements that enhance value chain efficiency and supply reliability.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The study delivers detailed country-level analysis across major carbon black feedstock production and consumption markets. It evaluates refinery capacity, availability of clarified slurry oil, ethylene cracker residue and coal tar oils, feedstock supply chains, import-export dynamics, pricing trends, regulatory frameworks, refinery integration, and downstream demand from carbon black manufacturing industries.
Enables stakeholders to identify high-potential regional markets, evaluate feedstock availability, optimize procurement strategies, understand regulatory landscapes, and prioritize investments based on refinery output, industrial demand, and supply chain efficiency.
Competitive Benchmarking
The report provides a comprehensive benchmarking assessment of leading carbon black feedstock suppliers, covering product portfolios, production capabilities, refinery integration, geographic footprint, distribution networks, research and development initiatives, sustainability practices, operational strengths, and recent strategic developments.
Helps businesses evaluate competitive positioning, identify technology gaps, benchmark innovation capabilities, support strategic collaborations, and strengthen long-term market expansion and product differentiation strategies.
Opportunity Assessment
The study evaluates emerging growth opportunities across premium high-BMCI feedstocks, refinery and petrochemical integration, carbon black capacity expansion, circular economy initiatives, recovered carbon black value chains, feedstock quality enhancement technologies, and supply chain optimization. It also examines opportunities arising from increasing demand for high-performance carbon black and investments in advanced refining infrastructure.
Assists companies in identifying attractive growth segments, aligning product development with industry requirements, optimizing capital allocation, enhancing supply chain resilience, and strengthening long-term competitive advantage through innovation and strategic partnerships.
Frequently Asked Questions About This Report
By source, clarified slurry oil held a dominant position, contributing 50.5% of total revenue in 2025. Its high aromatic content, consistent quality, and widespread availability from refinery operations make it the preferred feedstock for producing high-yield, performance-oriented carbon black across diverse industrial applications.
Based on product, the general type accounted for the highest market share, representing 55.4% of total revenue in 2025, due to its broad applicability, cost-effectiveness, and widespread use in the production of standard-grade carbon black across tire, rubber, plastics, and industrial manufacturing applications.
High BMCI Type is the fastest growing product segment with a CAGR of 4.7% in the forecast period. Its rapid growth is driven by increasing demand for high-aromatic feedstocks that improve carbon black yield, enhance production efficiency, and support the manufacture of premium-grade carbon black for tire, industrial rubber, and specialty applications.
Clarified Slurry Oil is the fastest growing source segment with a CAGR of 4.6% in the forecast period. Its growth is driven by its high aromatic content, consistent quality, and widespread availability from refinery operations, making it the preferred feedstock for producing high-performance carbon black with improved process efficiency and yield.
The carbon black feedstock market is primarily driven by rising demand from the tire and industrial rubber industries, where carbon black is widely used as a reinforcing material. Increasing refinery integration, expanding petrochemical production, and growing investments in carbon black manufacturing capacity are enhancing the availability and utilization of aromatic-rich feedstocks such as clarified slurry oil and ethylene cracker residue.
Asia Pacific dominated the carbon black feedstock market with the highest revenue share of 43.1% in 2025. Rapid expansion of tire manufacturing, strong refining capacity, and increasing carbon black production across China, India, Japan, and South Korea continue to reinforce the region's leadership in global feedstock consumption.
The global carbon black feedstock market size was valued at USD 8.0 billion in 2025 and is estimated at USD 8.3 billion for 2026.
The global carbon black feedstock market is expected to grow at a CAGR of 4.4% from 2026 to 2033, reaching USD 11.3 billion by 2033.
Some key players operating in the carbon black feedstock market include Indian Oil Corporation Ltd; Dow; Arham Petrochem Private Limited; Haldia Petrochemicals Ltd (HPL); Jalan Carbons & Chemicals (P) Ltd.; Shell; BASF SE; Aramco; Sherwin-Williams Company; Epsilon Carbon Private Limited and others.
About the Author(s)
Petrochemicals Research Team
Bulk Chemicals · PetrochemicalsThis report was authored by the petrochemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the petrochemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


