
- Home
- »
- Plastics, Polymers & Resins
- »
-
CO2-based Plastics Market Size And Share Report, 2033GVR Report cover

CO2-based Plastics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (Polycarbonates, Polyurethanes), By Application (Packaging, Automotive Components, Electronic Components, Textile Processing), By Region, And Segment Forecasts
Market Size, 2025
$3.3BMarket Estimate, 2026
$3.7BMarket Forecast, 2033
$6.2BCAGR, 2026–2033
7.8%CO2-based Plastics Market Summary
The CO2-based plastics market size was valued at USD 3.3 billion in 2025 and is projected to grow from USD 3.7 billion in 2026 to USD 6.2 billion by 2033, at a CAGR of 7.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 42.1% in 2025. Increasing investments in carbon capture and utilization (CCU) technologies are driving growth in the CO₂-based plastics market by improving the commercial viability of carbon-derived polymers.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Polycarbonates CO2-based plastics segment led the market with the largest revenue share of 61.2% in 2025.
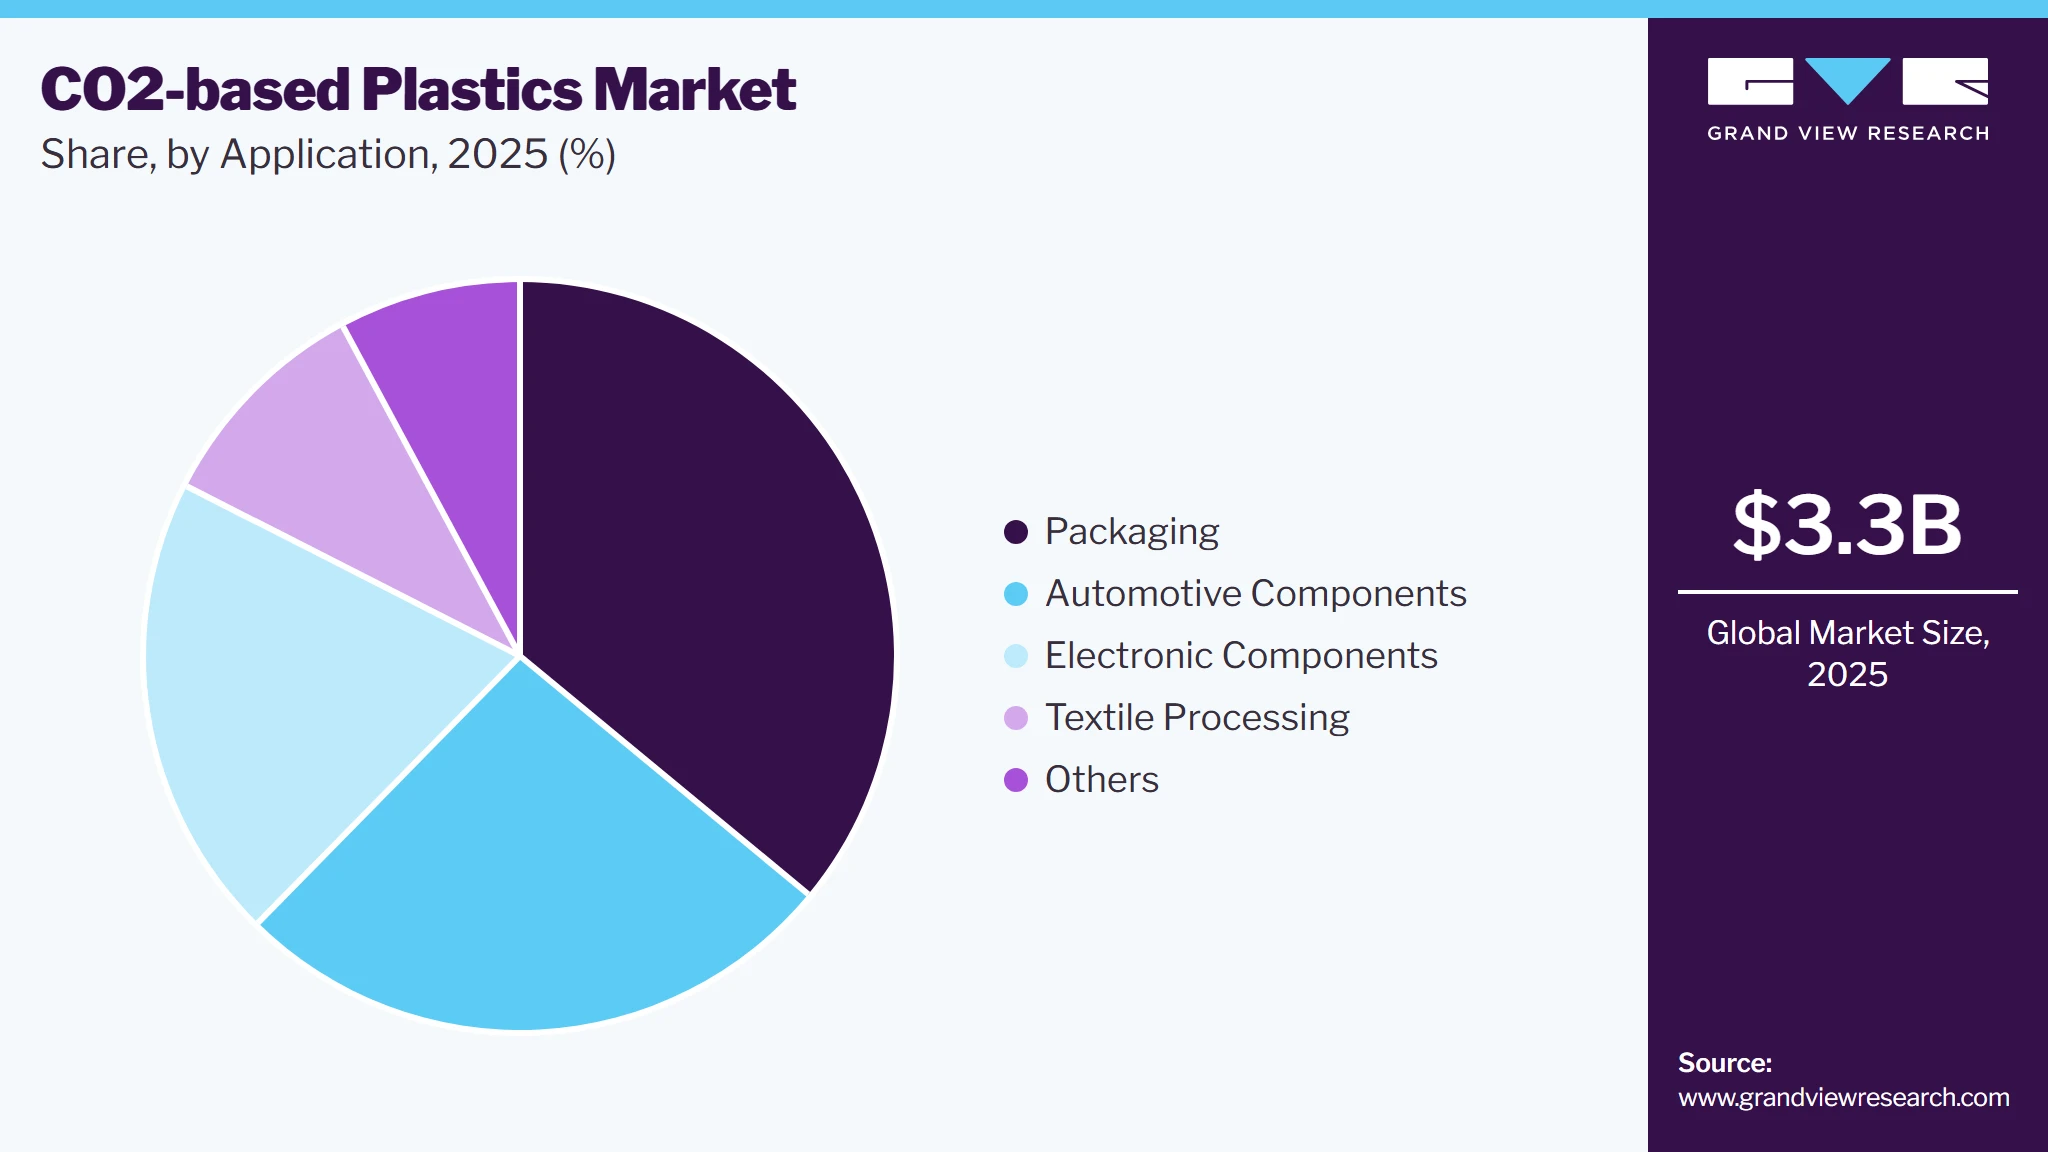
- By application: Packaging segment led the market with the largest revenue share of 36.0% in 2025.
Regional Highlights
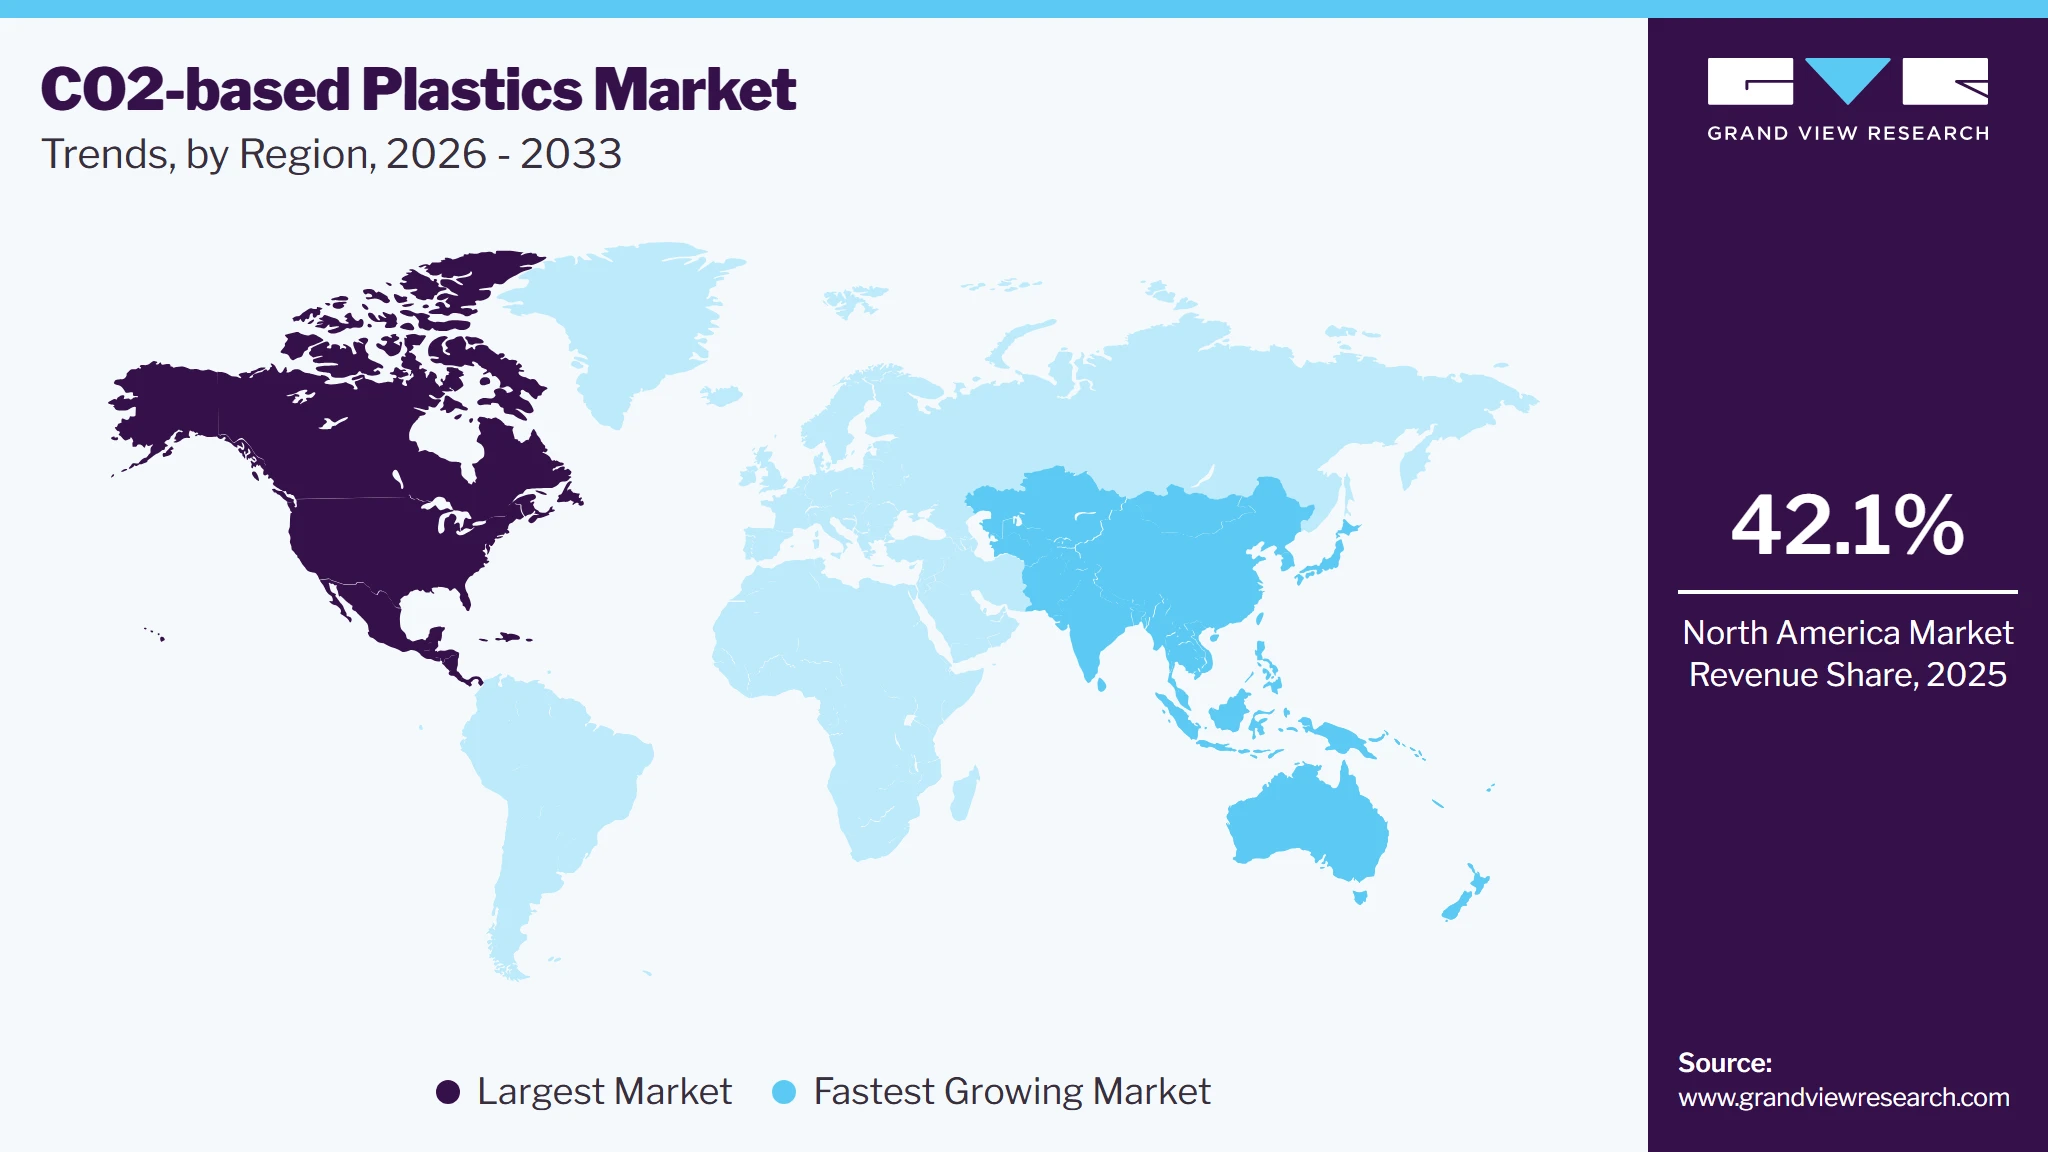
- Largest regional market: North America (42.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.3 Billion
- Estimated market size in 2026: USD 3.7 Billion
- Projected market size by 2033: USD 6.2 Billion
- CAGR (2026-2033): 7.8%
Prism AI by Grand View Research Free to tryAsk a question about the CO2-based plastics marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Rising funding from governments and private organizations supports advances in catalyst development, electrochemical conversion, and scalable polymerization technologies, enabling efficient production of polycarbonates and polyols. Growing industry collaborations, favorable regulatory support, and expanding adoption of circular economy practices are further accelerating the use of CO₂-based plastics as sustainable alternatives to conventional polymers. Governments and private sector players are funding research to enhance efficiency, reduce costs, and scale up production. The CO₂-based plastics market is witnessing a significant trend toward the expansion of carbon utilization technologies, driven by advancements in catalysis, electrochemical conversion, and biotechnological pathways. Companies are investing heavily in the development of efficient catalysts that facilitate the conversion of CO₂ into valuable polymer precursors, such as polycarbonates and polyols. This trend is further reinforced by collaborations between petrochemical giants and cleantech startups, aiming to commercialize scalable carbon capture and utilization (CCU) solutions.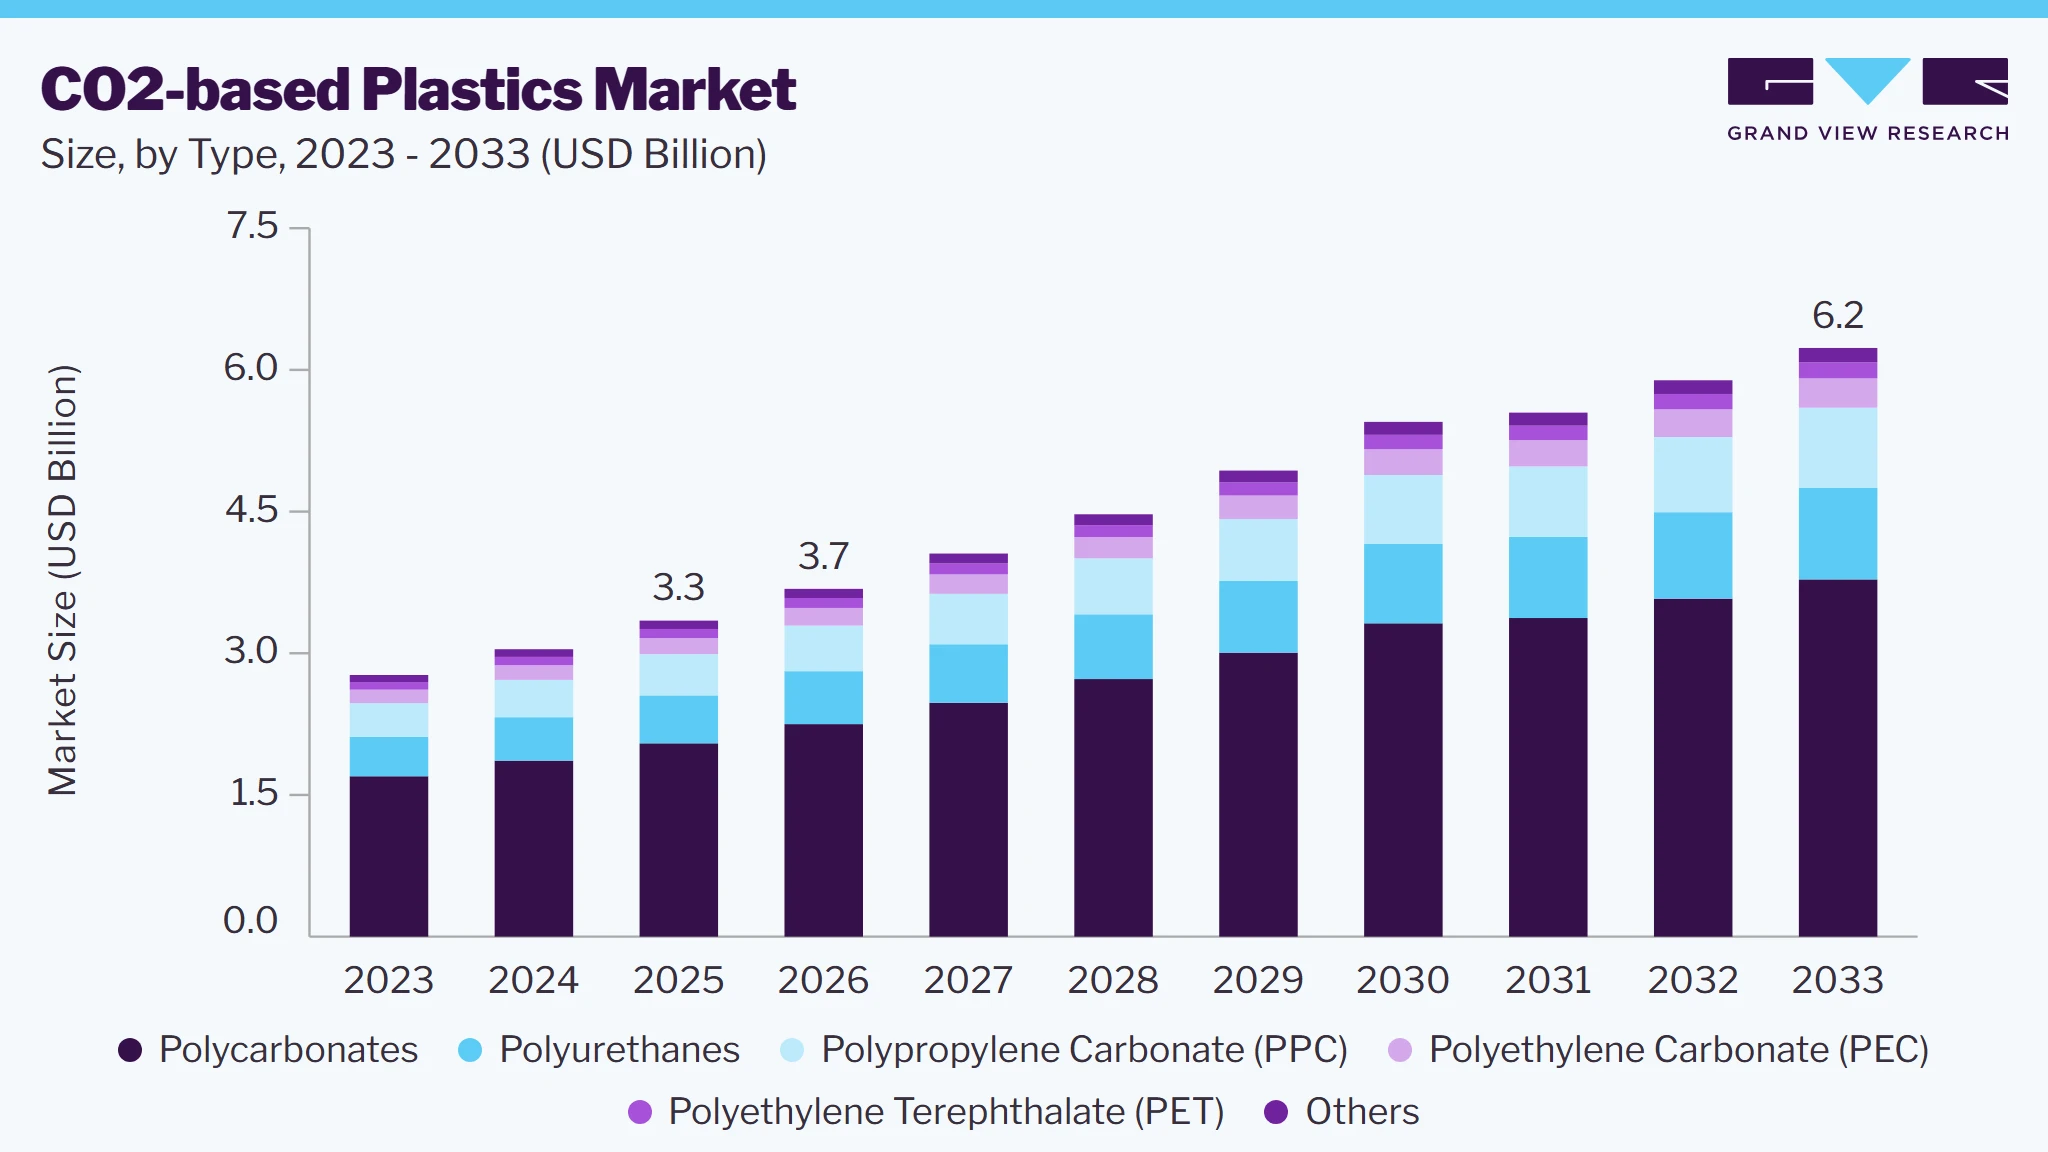 To learn more about this report, Download Free Sample Report
The integration of CO₂-derived materials into circular economy models is gaining traction, as major industries seek to align with global carbon neutrality commitments. The growing body of regulatory support and patent filings for CO₂-based polymerization processes underscores the accelerating momentum of this trend, positioning CO₂-based plastics as a key player in the sustainable materials landscape.
Market Dynamics
The CO2-based plastics market is advancing on the back of commercial interest in carbon utilization, with demand centered on polycarbonates and polyurethanes that can convert captured CO2 into performance-grade resins. Packaging remains the most active end-use, supported by demand for lighter, lower-carbon materials in films, containers, and branded consumer packaging. Demand is also concentrated in North America and Europe, where policy support, CCU investment, and sustainability-led procurement are strongest. The commercial structure is still partnership-driven, with producers relying on catalyst development, pilot scaling, and downstream brand collaborations to move from specialty volumes toward broader industrial adoption.
Packaging buyers are pushing CO2-based plastics into commercial relevance because brand owners now treat material choice as part of carbon disclosure, circularity, and product differentiation. This is most visible in rigid packs, films, and cosmetic containers, where CO2-derived polycarbonates and polyurethanes can support sustainability targets without fully abandoning the performance standards required for consumer packaging. The market benefits from the fact that packaging already dominates revenue within the application mix, giving suppliers a clear commercialization channel.
A second growth lever is the increasing willingness of large material users to trial carbon capture and utilization pathways through co-development programs. CO2-based polymer projects are moving forward where resin developers, catalyst specialists, and brand owners can align on technical validation and pilot output. That structure favors suppliers able to show conversion efficiency, application fit, and a credible path to scale. As a result, the market is being pulled by both sustainability procurement and the need for differentiated, lower-carbon material portfolios.
The main restraint is the cost structure of CO2 polymerization, which still depends on advanced catalysts, tightly controlled reaction conditions, and energy-intensive processing. This makes CO2-based plastics less competitive in price-sensitive applications where conventional fossil-based polymers already benefit from mature supply chains and scale economics. In addition, CO2 capture, transport, and utilization infrastructure remains uneven across regions, which limits consistent feedstock access and slows project bankability. Until process economics improve and scale lowers unit cost, commercial penetration will remain concentrated in premium, sustainability-led applications rather than mainstream volume categories.
Automotive components represent a strong expansion opportunity because OEMs are under pressure to reduce embodied carbon while maintaining lightweighting and durability targets. CO2-based polyurethanes and polycarbonates can fit interior parts, trims, and structural applications where sustainability now influences material selection. Suppliers that combine application validation with stable feedstock access can position these resins as credible substitutes in value-added vehicle programs.
Analyst Perspective
The CO2-based plastics market is moving from a pilot-led sustainability theme toward a more selective commercialization phase, where material performance, processing efficiency, and downstream qualification will matter more than carbon narrative alone. Packaging will remain the primary demand anchor, while automotive interiors and electronic components will create higher-value opportunities for resins that can meet technical and regulatory requirements. Over the next 5 to 10 years, the market is likely to shift from innovation-led experimentation to application-led value creation, especially for polycarbonates and polyurethanes. Winners will be those that combine catalyst IP, access to reliable CO2 utilization pathways, strong partnerships with converters and brand owners, and the ability to prove consistency at scale. The main risks remain high production cost, infrastructure gaps, and competition from lower-cost conventional resins, which will keep profitability tied to process efficiency and commercial integration.
Product Type Insights
Polycarbonates dominated the CO₂-based plastics market across the type segmentation in terms of revenue, accounting for a market share of 61.2% in 2024. The CO₂-based polycarbonate segment is gaining momentum as advancements in catalytic processes and polymerization techniques enhance the material’s performance, making it a viable alternative to traditional fossil-based polycarbonates. Researchers are developing highly efficient zinc- and cobalt-based catalysts that enable the direct incorporation of CO₂ into polycarbonate chains, reducing dependency on petroleum-derived bisphenol A (BPA). These innovations are particularly attractive in high-performance applications such as automotive components, optical storage media, and medical devices, where sustainability and durability are key considerations. Additionally, with regulatory agencies imposing restrictions on BPA-containing plastics, the shift toward non-toxic, CO₂-derived polycarbonates is accelerating, positioning this segment for strong growth in the coming years.
CO₂-based polyurethanes are witnessing a surge in demand, largely fueled by the increasing adoption of sustainable polyols in the construction and automotive industries. Leading manufacturers are utilizing CO₂ as a feedstock to produce high-performance polyols, reducing reliance on petrochemical-based raw materials while improving the carbon footprint of polyurethane foams. The construction sector, in particular, is driving demand due to the growing preference for energy-efficient insulation materials, where CO₂-based rigid polyurethane foams offer superior thermal performance and sustainability benefits. Likewise, the automotive industry is integrating CO₂-polyurethane foams into seating, dashboards, and interior components, as manufacturers strive to meet stricter emission regulations and lightweighting targets. This dual-sector demand is creating strong market traction for CO₂-derived polyurethanes as an eco-friendly alternative to conventional polyurethane formulations.
Application Insights
Packaging dominated the CO₂-based plastics market across the recycling process segmentation in terms of revenue, accounting for a market share of 35.8% in 2024. The growing emphasis on corporate sustainability commitments is driving the demand for CO₂-based plastics in packaging applications, as major global brands seek carbon-neutral alternatives to traditional fossil-fuel-derived materials. Leading consumer goods companies, particularly in the food & beverage and personal care sectors, are increasingly partnering with material innovators to integrate CO₂-derived polymers into their packaging portfolios. These initiatives align with ambitious net-zero goals, as well as evolving regulatory frameworks such as the EU Green Deal and Extended Producer Responsibility (EPR) laws, which mandate sustainable material adoption. Additionally, advancements in CO₂-polycarbonate and CO₂-polyurethane packaging technologies are enabling the development of durable, lightweight, and recyclable solutions, further strengthening the market potential of CO₂-based plastics in the packaging sector.
 To learn more about this report, Download Free Sample Report
The demand for CO₂-based plastics in electronic components is rising as manufacturers prioritize sustainability alongside high-performance material characteristics. With the consumer electronics industry under growing scrutiny for its environmental impact, companies are turning to CO₂-derived polycarbonates and polyurethanes to develop durable, heat-resistant, and lightweight materials for electronic casings, connectors, and circuit boards. Furthermore, the rise of electric vehicles (EVs) and smart devices is amplifying the need for advanced polymers with excellent electrical insulation properties, where CO₂-based polycarbonates offer a compelling alternative to conventional materials. As technology firms ramp up their commitments to carbon reduction and circular economy initiatives, the adoption of CO₂-derived plastics in electronics is expected to witness sustained growth, driven by both regulatory compliance and industry-wide sustainability initiatives.
Regional Insights
North America CO₂-based plastics market dominated the globally and accounted for largest revenue share of 42.1% in 2024. The North American CO₂-based plastics market is experiencing strong momentum due to government-backed incentives and policy frameworks that support carbon capture and utilization (CCU) technologies. The U.S. Inflation Reduction Act (IRA) and Canada’s Clean Fuel Regulations provide significant tax credits and funding for companies investing in CCU-based polymer production, making CO₂-derived plastics more commercially viable. Additionally, the 45Q tax credit in the U.S. incentivizes large-scale carbon capture projects, indirectly boosting the supply of industrial CO₂ feedstock for polymer manufacturing. This regulatory push is encouraging collaborations between chemical manufacturers and clean energy firms, accelerating the development of cost-effective CO₂-derived materials. With policymakers further tightening emissions standards, the market is poised to benefit from sustained financial support and legislative backing, reinforcing the region’s position as a leader in CO₂-based polymer innovation.
 To learn more about this report, Download Free Sample Report
The rapid expansion of private sector investments is another key driver for CO₂-based plastics in North America. Major chemical companies, venture capital firms, and sustainability-focused funds are injecting capital into startups and established players working on carbon-negative polymer technologies. Strategic investments from industry giants such as LanzaTech, Covestro, and Newlight Technologies are driving commercialization efforts, while partnerships with consumer goods companies are facilitating real-world applications of CO₂-derived plastics.
U.S. CO₂-based Plastics Market Trends
In the U.S., the expansion of industrial carbon capture infrastructure is playing a crucial role in accelerating the CO₂-based plastics market. Major energy and chemical companies are investing in large-scale direct air capture (DAC) and point-source carbon capture technologies, which are creating a stable and cost-effective supply of CO₂ feedstock for polymer manufacturers. The Department of Energy (DOE) has allocated substantial funding toward carbon capture projects, with initiatives like Project Bison and the Houston Carbon Capture Hub aiming to commercialize CO₂ utilization at an industrial scale. This infrastructure development is directly benefiting CO₂-based polymer production, as manufacturers gain reliable access to high-purity CO₂ streams for polycarbonates, polyurethanes, and biodegradable plastics. As carbon capture technology matures and costs decline, the U.S. is well-positioned to lead the global shift toward large-scale CO₂-based plastic manufacturing.
Europe CO₂-based Plastics Market Trends
Europe’s CO₂-based plastics market is being propelled by some of the world’s most stringent carbon neutrality regulations, making sustainable material adoption a top priority for industries. The European Green Deal, coupled with the Fit for 55 legislative package, has established aggressive carbon reduction targets, compelling manufacturers to explore alternative, low-carbon feedstocks such as CO₂-derived polymers. The Emissions Trading System (ETS) is further pressuring high-emission industries, including petrochemicals and packaging, to invest in sustainable material innovation to offset regulatory costs.
Asia Pacific CO₂-based Plastics Market Trends
Asia Pacific is witnessing a sharp rise in demand for CO₂-based plastics due to the region’s expanding manufacturing and automotive industries, which are under growing pressure to reduce emissions. Countries like China, Japan, and South Korea have launched aggressive carbon neutrality goals, with China’s “Dual Carbon” initiative and Japan’s Green Growth Strategy pushing industrial sectors to adopt low-carbon materials. The automotive industry, in particular, is emerging as a key driver, with leading automakers such as Toyota, Hyundai, and BYD integrating sustainable plastics into vehicle interiors and lightweight components.
Key CO₂-based Plastics Company Insights
The CO₂-based Plastics Market is highly competitive, with several key players dominating the landscape. Major companies include LG Chem, LanzaTech, Newlight Technologies, Fortum Recycling & Waste, NatureWorks, Covestro AG, and Avantium. The CO₂-based plastics market is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their product types.
Key CO₂-based Plastics Companies
The following key companies have been profiled for this study on the CO₂-based plastics market.
-
LG Chem
-
LanzaTech
-
Newlight Technologies
-
Fortum Recycling & Waste
-
NatureWorks
-
Covestro AG
-
Avantium
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (LG Chem, Covestro AG, NatureWorks, Fortum Recycling & Waste)
- Scale pilot programs into a validated commercial supply.
- Use partnerships with converters and brand owners to secure offtake.
- Focus on application-led qualification in packaging and durable goods.
- Stronger balance sheets and broader industrial reach.
- Better access to downstream customers and process integration.
- More credible scale-up capability and manufacturing discipline.
- High exposure to capex intensity and long validation cycles.
- Sustainability claims must be supported by measurable performance.
- Larger organizations can move more slowly in niche applications.
Emerging Players (LanzaTech, Newlight Technologies, Avantium)
- Target high-growth niches with differentiated CO2 conversion pathways.
- Rely on partnerships, pilots, and licensing-oriented commercialization.
- Build market presence through technology proof and selective customer wins.
- Higher innovation intensity and faster product iteration.
- Stronger focus on carbon-utilization storytelling and material differentiation.
- Ability to serve early adopters seeking low-carbon materials.
- Smaller commercial scale and narrower manufacturing footprint.
- Greater dependence on external funding, partners, and pilot success.
- More exposed to scale-up, cost, and adoption risk.
Recent Developments
-
In March 2024, LG Chem presented eco-friendly plastic materials derived from carbon dioxide at Cosmoprof Bologna 2024, a major beauty industry expo. They showcased cosmetic containers made from Poly Ethylene Carbonate (PEC), a next-generation plastic produced using captured carbon dioxide, in collaboration with COSMAX. LG Chem has developed proprietary catalysts, achieving high productivity in CO2-based plastic production.
-
In June 2023, Avantium and SCGC, a chemicals company in Asia, partnered to develop CO2-based polymers. The partnership involved scaling up production of polylactic-co-glycolic acid (PLGA) to a pilot plant with a capacity of 10 tonnes per annum.
CO₂-based Plastics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.3 billion
Estimated market size in 2026
USD 3.7 billion
Projected market size by 2033
USD 6.2 billion
Growth rate
CAGR of 7.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, region
RegioFinal scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain, China; India; Japan; South Korea, Australia Brazil; Argentina, Saudi Arabia, South Africa
Key companies profiled
LG Chem; LanzaTech; Newlight Technologies; Fortum Recycling & Waste; NatureWorks; Covestro AG; and Avantium
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase-addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global CO₂-based Plastics Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented CO₂-based plastics market report based on product type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Polycarbonates
-
Polyurethanes
-
Polypropylene Carbonate (PPC)
-
Polyethylene Carbonate (PEC)
-
Polyethylene Terephthalate (PET)
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Packaging
-
Films
-
Bottles
-
Containers
-
Trays
-
Others
-
-
Automotive Components
-
Interior Components
-
Structural Parts
-
Construction Materials
-
Pipes
-
Panels
-
Insulation
-
Others
-
-
Electronic Components
-
Casings
-
Connectors
-
Circuit Boards
-
Others
-
-
Textile Processing
-
Fibers
-
Non-Woven Fabrics
-
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The CO2-based plastics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each CO2-based plastics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Polycarbonates
Revenue is captured through sales of CO2-derived polycarbonate resin grades, compound formulations, and application-specific material supply for packaging, automotive, and electronic use cases where performance and sustainability are both monetized.
Polyurethanes
Revenue is captured through CO2-based polyurethane raw materials, polyol intermediates, and finished resin systems sold into foam, insulation, and interior component applications with sustainability-led material substitution.
Polypropylene Carbonate (PPC)
Revenue is captured through specialty polymer supply, blending grades, and niche performance materials used where lower-temperature processability and carbon-derived content support premium applications.
Polyethylene Carbonate (PEC)
Revenue is captured through resin sales, specialty compounding, and downstream packaging or cosmetic container applications where PEC is commercialized as a lower-carbon specialty polymer.
Polyethylene Terephthalate (PET)
Revenue is captured through CO2-enabled PET-related formulations, pilot-scale material output, and application development revenues where producers target existing PET value chains with carbon utilization chemistry.
Others
Revenue is captured through residual specialty products, experimental CO2 polymers, pre-commercial formulations, and custom material development that do not fit the core resin families.
Segment - Application
Revenue capture definition
Automotive Components
Revenue is captured through resin sales into interior trims, seating foams, lightweight parts, structural panels, and insulation material programs led by OEM and Tier 1 qualification cycles.
Electronic Components
Revenue is captured through high-performance polymer supply for casings, connectors, heat-resistant housings, and insulation parts where sustainability is paired with electrical and thermal performance requirements.
Packaging
Revenue is captured through resin and compound sales for films, bottles, containers, trays, and cosmetic packs where branded packaging owners pay for lower-carbon material content.
Textile Processing
Revenue is captured through specialty polymer inputs for textile auxiliaries, coatings, fiber processing aids, and low-carbon material layers used in performance and branded textile applications.
Others
Revenue is captured through specialty industrial, construction, consumer goods, and pilot-market applications that remain outside the primary commercial channels but still absorb technical resin output.
Estimation Model
Layer Name
Key Question
Description
Demand Mapping
Where does demand originate?
This layer anchors revenue by identifying end-use pull from packaging, automotive, electronics, and textile processing, where CO2-based polymers can realistically convert into sales.
Type Allocation
Which resin drives revenue?
This layer splits demand across polycarbonates, polyurethanes, PPC, PEC, PET, and others to reflect resin-specific commercialization intensity and price realization.
Regional Weighting
Which regions lead adoption?
This layer assigns market share by region because adoption is concentrated in North America and Europe, while policy-led scale-up remains uneven across countries.
Supply Validation
Can supply meet demand?
This layer checks company programs, pilot capacity, and partnership activity to confirm which volumes are commercially deliverable rather than only technically announced.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional outlook
Added a region-led framing aligned with the report scope, emphasizing North America and Europe as the strongest commercialization zones for CO2-based plastics.
Improves investor-facing clarity on where demand is most likely to convert into revenue.
Segment coverage
Expanded the type and application split into commercially grounded revenue definitions for each reported sub-segment.
Helps align market sizing assumptions with real end-use monetization logic.
Company benchmarking
Built a relative company classification into mature and emerging players with strategy, edge, and weakness assessment.
Supports competitive positioning and partner-screening decisions in one view.
Frequently Asked Questions About This Report
The North America CO2-based plastics market accounted for the largest share of 42.1% market size in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The key players in the CO2-based plastics market are LG Chem, LanzaTech, Newlight Technologies, Fortum Recycling & Waste, NatureWorks, Covestro AG, and Avantium.
Based on application, the packaging segment accounted for the largest share of 36.0% market size in 2025. Growing demand from food and beverage, consumer goods, healthcare, e-commerce, and personal care industries, coupled with advances in CO₂-based polymerization and sustainable packaging technologies, is accelerating the adoption of CO₂-based plastics for lightweight, recyclable, and lower-carbon packaging applications.
The CO2-based plastics market was estimated at around USD 3.3 billion in 2025 and is expected to reach around USD 3.7 billion in 2026.
The CO2-based plastics market is expected to grow at a compound annual growth rate of 7.8% from 2026 to 2033 to reach around USD 6.2 billion by 2033.
The polycarbonates CO2-based plastics industry led the CO2-based plastics product type market in 2025 with a 61.2% share. Growing demand from automotive, electronics, packaging, construction, and consumer goods industries, coupled with advances in CO₂-based polymerization and catalyst technologies, is accelerating the adoption of polycarbonates for durable, lightweight, high-performance, and sustainable engineering plastic applications.
Increasing investments in carbon capture and utilization (CCU) technologies are driving growth in the CO₂-based plastics market by improving the commercial viability of carbon-derived polymers. Rising funding from governments and private organizations supports advances in catalyst development, electrochemical conversion, and scalable polymerization technologies, enabling efficient production of polycarbonates and polyols. Growing industry collaborations, favorable regulatory support, and expanding adoption of circular economy practices are further accelerating the use of CO₂-based plastics as sustainable alternatives to conventional polymers.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


