
- Home
- »
- Plastics, Polymers & Resins
- »
-
Construction Elastomers Market Size Report, 2026-2033GVR Report cover

Construction Elastomers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (Styrene Block Copolymers, Thermoplastic Polyurethane, Styrene Butadiene, Ethylene Propylene Diene Monomer, Natural Rubber), By Application, By Region, And Segment Forecasts
Market Size, 2025
$5.9BMarket Estimate, 2026
$6.2BMarket Forecast, 2033
$9.6BCAGR, 2026–2033
6.4%Construction Elastomers Market Summary
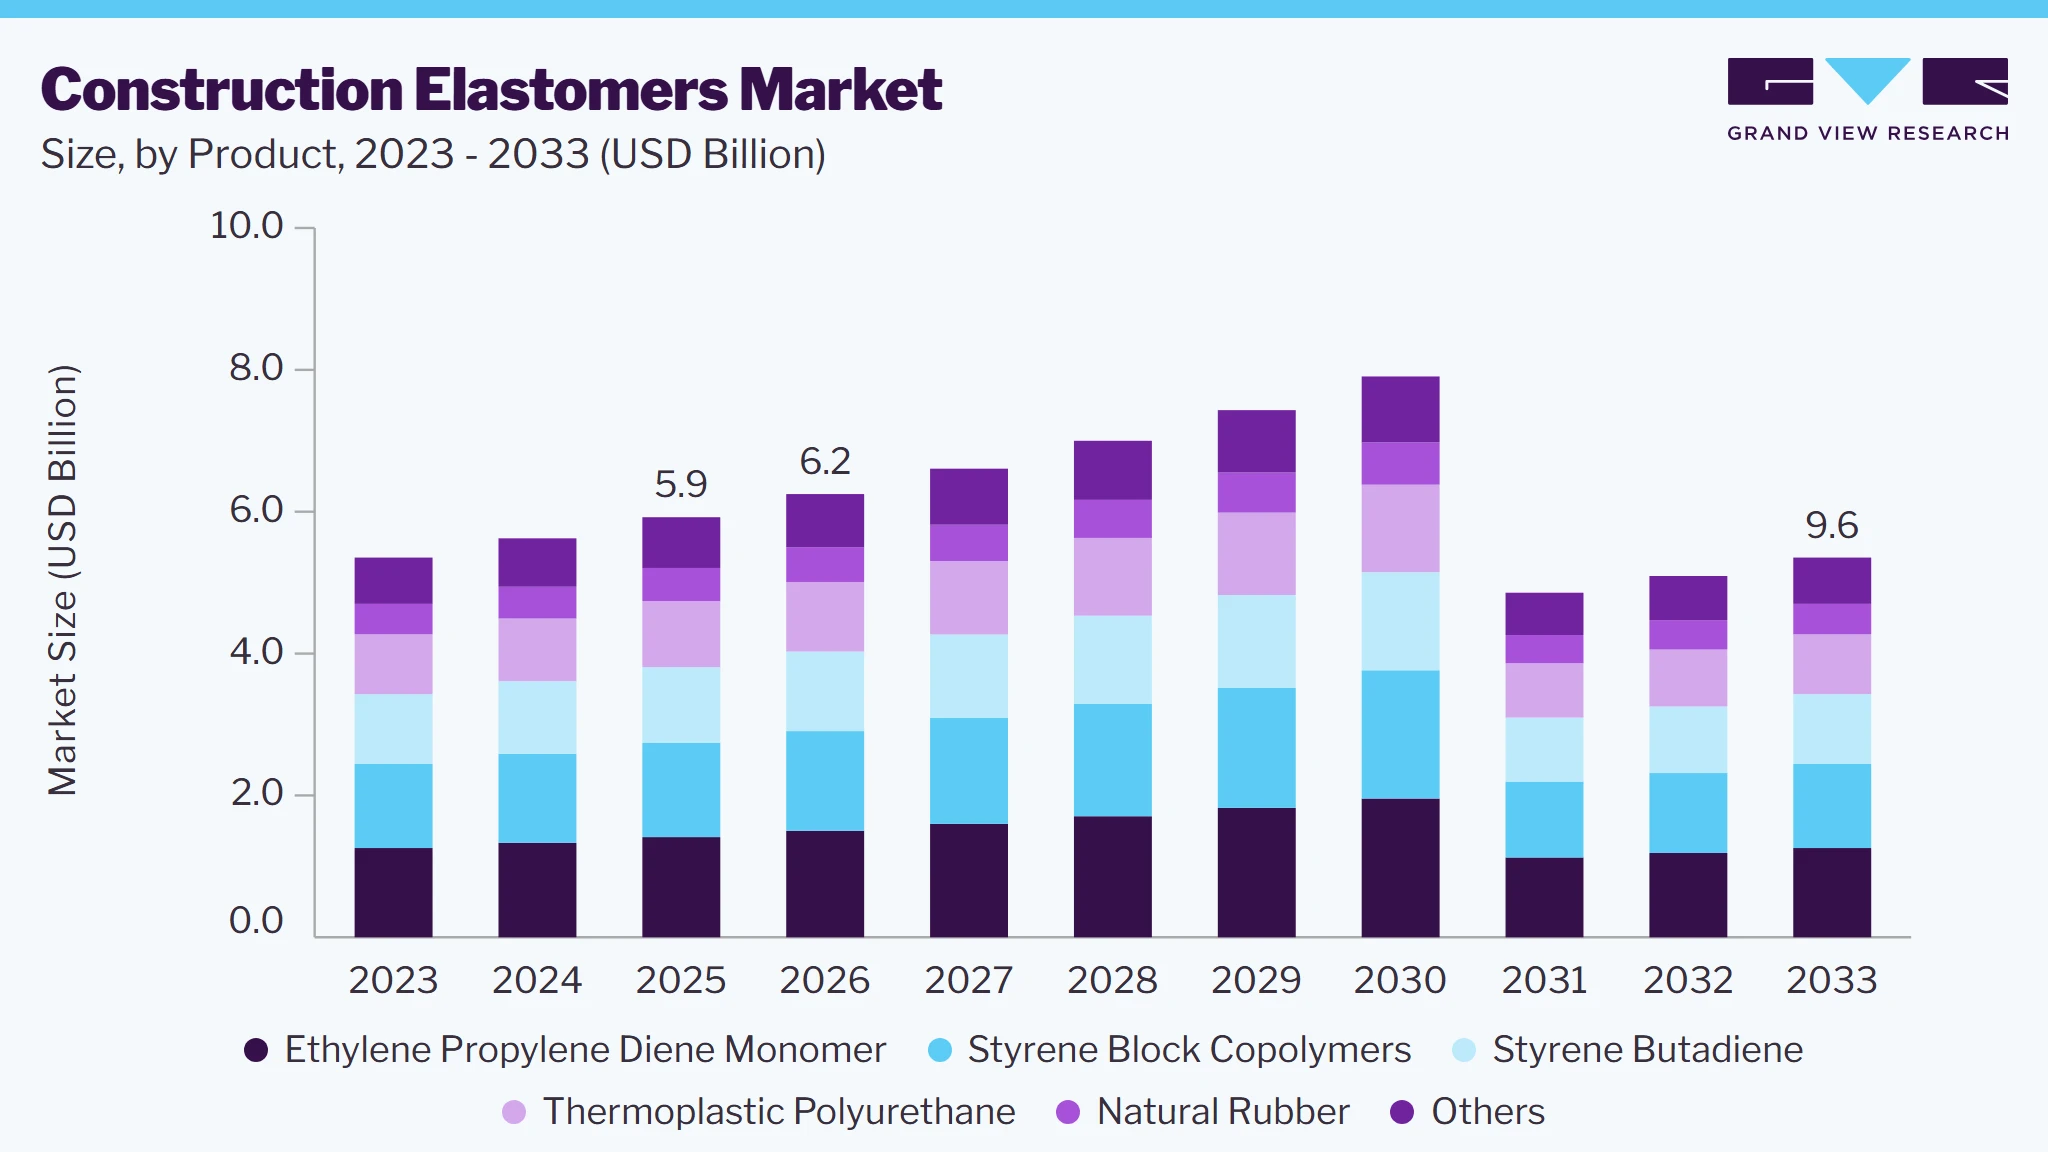
The global construction elastomers market size was valued at USD 5.9 billion in 2025 and is projected to grow from USD 6.2 billion in 2026 to USD 9.6 billion by 2033, at a CAGR of 6.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 49.5% in 2025. Growing demand from construction, infrastructure, packaging, healthcare, and consumer goods industries, together with tightening environmental regulations and increasing preference for recyclable, high-performance PVC formulations, is accelerating construction elastomers adoption.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Styrene block copolymers construction elastomers segment led the market with the largest revenue share of 22.4% in 2025.
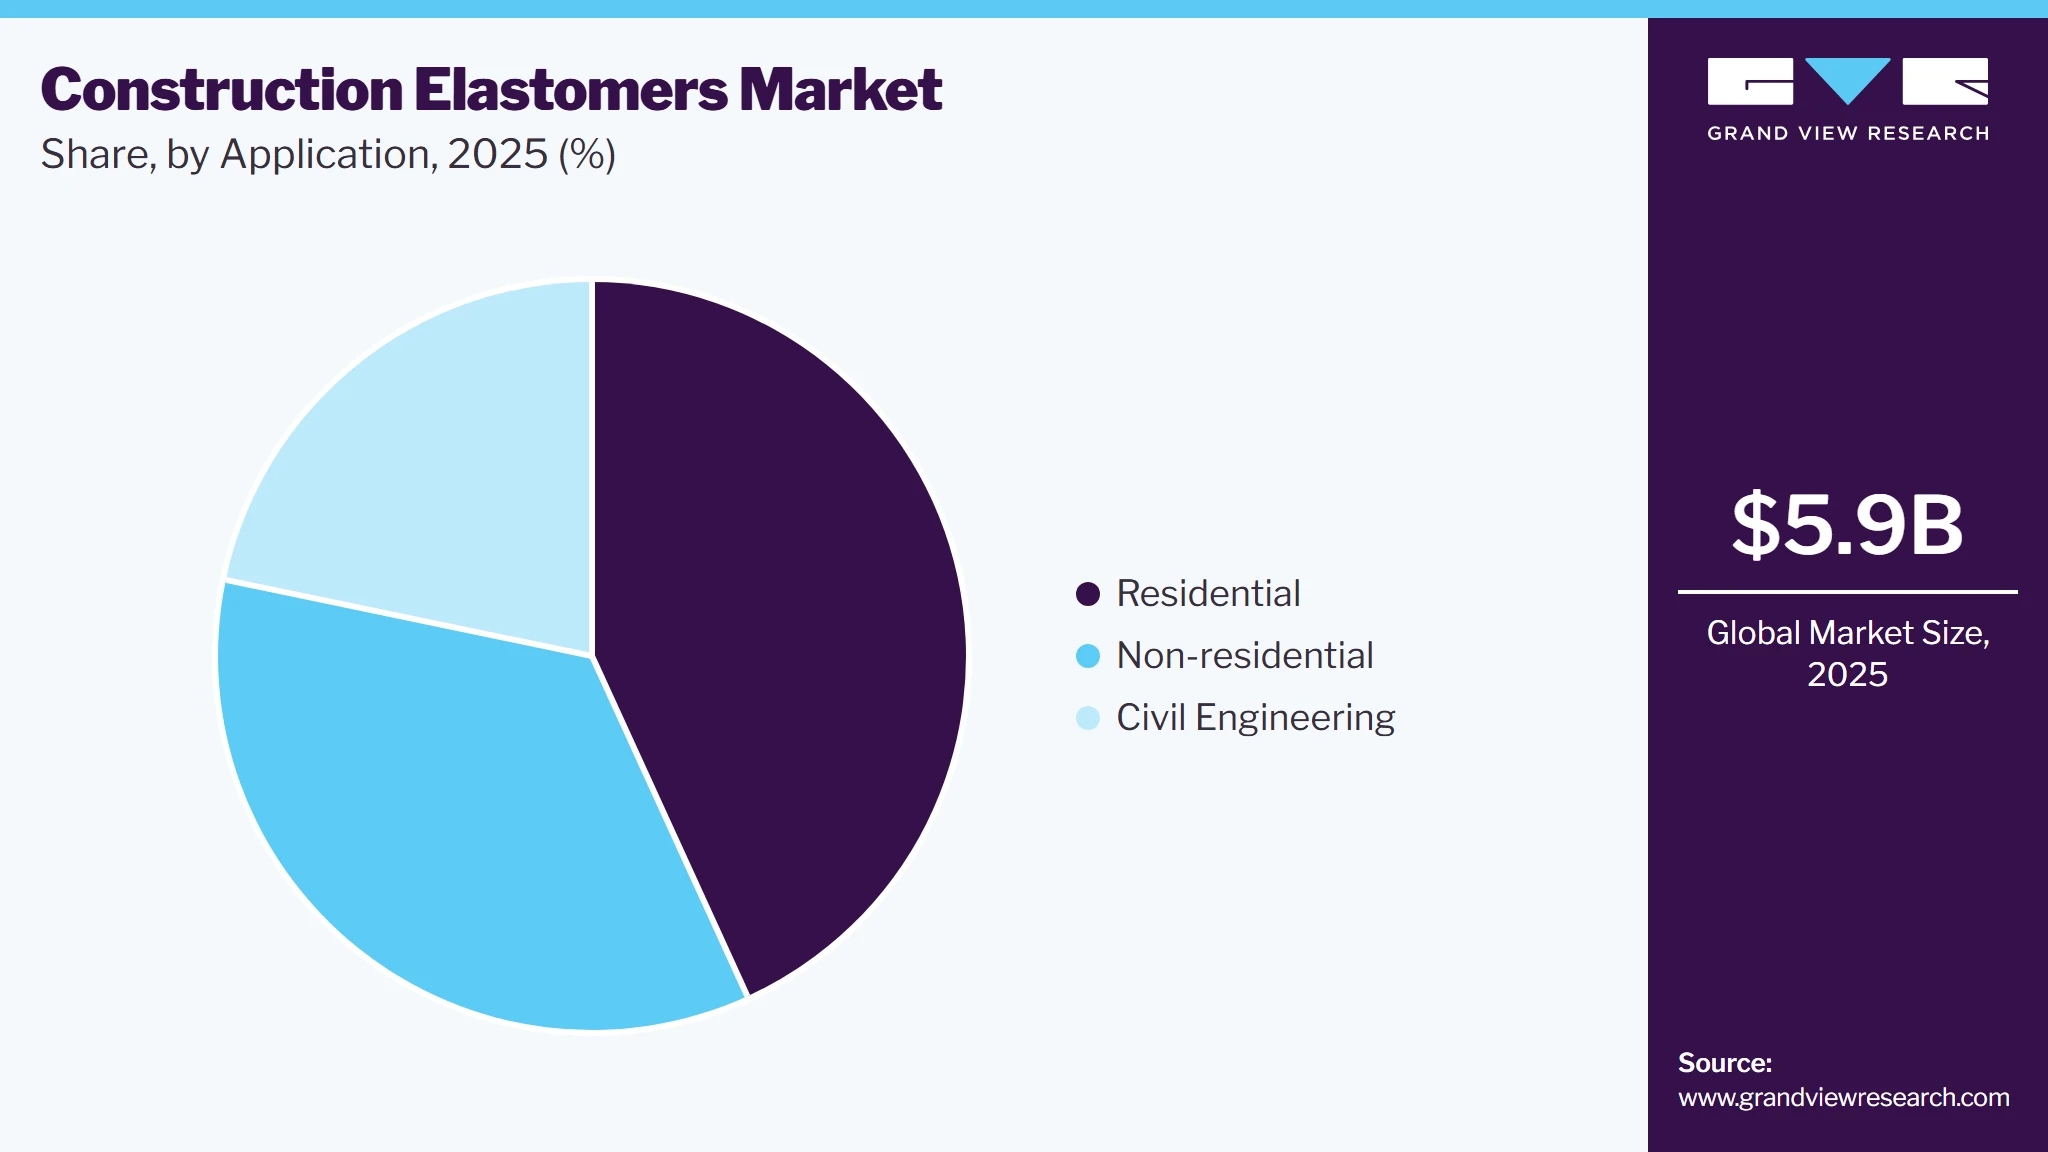
- By application: Residential construction elastomers segment led the market with the largest revenue share of 43.2% in 2025.
Regional Highlights
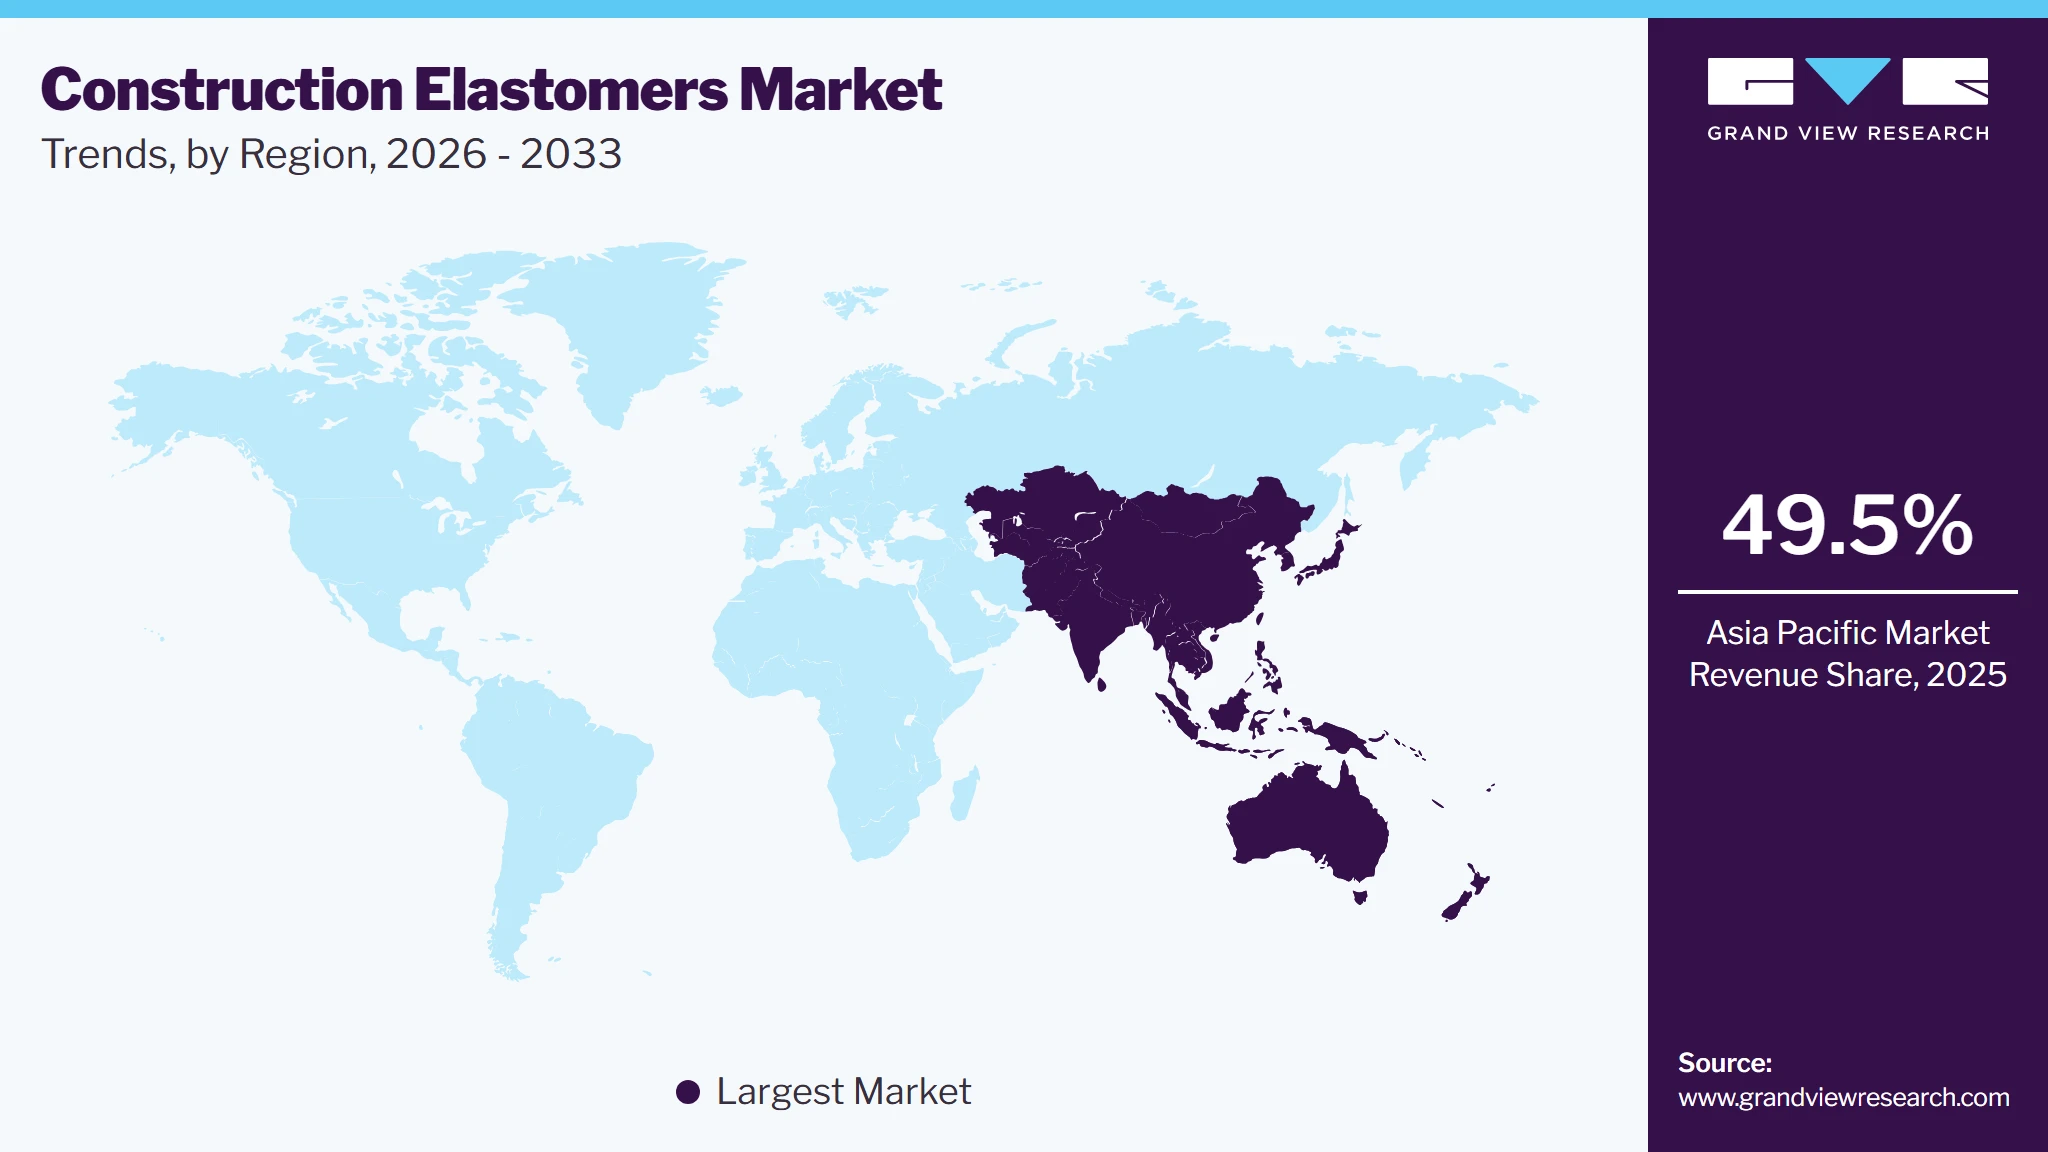
- Largest regional market: Asia Pacific (49.5% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.9 Billion
- Estimated market size in 2026: USD 6.2 Billion
- Projected market size by 2033: USD 9.6 Billion
- CAGR (2026-2033): 6.4%
Prism AI by Grand View Research Free to tryAsk a question about the construction elastomers marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The market is driven by increasing infrastructure development, rising demand for durable and flexible materials, and growing adoption of eco-friendly elastomers. Continuous advancements in stabilizer, plasticizer, and processing aid technologies, expanding sustainable additive portfolios, and rising investments in recyclable and low-emission PVC solutions are further strengthening demand for durable, weather-resistant, and application-specific PVC products across developed and emerging markets.
Additionally, advancements in polymer technology and government investments in smart city projects further fuel market growth. The rapid urbanization and industrialization in developing economies, particularly in Asia-Pacific and Latin America is contributing to the market growth. Governments worldwide are investing heavily in residential, commercial, and industrial construction, which directly boosts the demand for elastomers in applications such as sealants, adhesives, roofing membranes, and insulation materials. For example, China's Belt and Road Initiative (BRI) and India’s Smart Cities Mission have significantly increased the consumption of construction elastomers in recent years.
 To learn more about this report, Download Free Sample Report
Additionally, the rising demand for sustainable and energy-efficient materials is accelerating the demand for construction elastomers, thus boosting market growth. With stringent environmental regulations and growing consumer awareness, there is a shift toward eco-friendly and recyclable elastomers, such as thermoplastic elastomers (TPEs). These materials offer superior durability, flexibility, and resistance to extreme temperatures, making them ideal for green building applications. The adoption of LEED (Leadership in Energy and Environmental Design) certification and other sustainability standards has further fueled the demand for elastomers in energy-efficient windows, weatherproofing materials, and noise-reducing components.
Technological advancements in elastomer production have also played a crucial role in driving market expansion. Innovations in polymer chemistry have led to the development of high-performance elastomers with enhanced mechanical strength, weather resistance, and UV stability. Companies such as BASF and Dow are continuously investing in R&D to introduce new formulations that improve the lifespan of construction materials. For example, silicone-based elastomers are now widely used in modern infrastructure projects due to their excellent flexibility and water resistance, making them ideal for structural glazing and waterproofing systems.
Furthermore, the growing adoption of prefabricated and modular construction techniques has increased the reliance on elastomer-based products. Prefabricated buildings require high-performance gaskets, adhesives, and flexible joints that can withstand mechanical stress and varying climatic conditions. Elastomers provide superior sealing properties, ensuring long-term durability and reducing maintenance costs. In regions such as North America and Europe, where labor shortages and cost concerns are pushing the industry toward off-site construction, the demand for elastomers continues to surge.
Market Dynamics
Construction elastomers are supported by sustained demand from sealing, waterproofing, insulation, roofing, flooring, and vibration control applications across residential, non-residential, and civil engineering projects. Demand remains highly concentrated in Asia Pacific, where urbanization, infrastructure buildout, and large housing pipelines create the strongest consumption base. EPDM leads the product mix, while residential remains the largest application. The commercial structure is split between global formulators with broad portfolios and regional suppliers that compete on price, specification support, and project delivery. Sustainability, energy efficiency, and weather-resistant performance are increasingly shaping product selection and procurement.
The strongest demand driver is the rising specification of high-performance elastomers in energy-efficient building envelopes. Governments and developers are prioritizing airtightness, thermal insulation, and moisture control, which increases usage in roofing membranes, windows, facades, sealants, and expansion joints. Elastomers offer flexibility, UV stability, and long service life, which makes them suitable for modern construction systems that must reduce maintenance costs while improving building performance. LEED-aligned projects and other green building programs are reinforcing this shift, especially in developed markets where compliance standards are strict and material selection is performance-led.
This driver is also supported by infrastructure programs and the rapid expansion of residential construction in emerging economies. Asia Pacific, particularly China and India, continues to generate large-scale demand for elastomers in housing, commercial complexes, transport corridors, and industrial facilities. Civil engineering work such as bridges, tunnels, and seismic isolation systems requires durable elastomeric materials that can absorb movement and protect structural integrity. As construction moves toward longer lifecycle assets and more resilient design standards, elastomers are becoming a core material category rather than a secondary finishing input.
The market faces a structural restraint from raw material volatility and specification-heavy procurement. Construction elastomers depend on petrochemical inputs and face cost swings that can compress margins when project pricing is fixed in advance. At the same time, buyers often qualify products through long testing and compliance cycles, which slows adoption of new formulations and favors incumbent suppliers. Global leaders can absorb these pressures more effectively, while smaller regional players remain exposed to price competition and uneven project timing. This keeps the market commercially disciplined and limits rapid margin expansion.
A clear opportunity lies in eco-friendly elastomers for low-carbon construction, retrofit programs, and prefabricated building systems. Growing demand for recyclable, durable, and weather-resistant materials is creating room for premium formulations in roofing, waterproofing, and high-performance sealing. Suppliers that combine sustainability claims with proven field performance can win specification-led contracts, especially in green-certified projects and urban infrastructure upgrades.
Analyst Perspective
The construction elastomers market is moving from a volume-led materials market toward a more value-led, specification-driven category shaped by durability, energy efficiency, and sustainability. Over the next 5 to 10 years, demand will be strongest in roofing, sealing, waterproofing, expansion joints, and civil infrastructure, especially in the Asia Pacific and other fast-urbanizing regions. Product differentiation will depend less on commodity supply and more on formulation performance, regulatory compliance, low-VOC profiles, recyclability, and proven field life. Market leaders are likely to strengthen their position through integrated production, application support, regional manufacturing, and partnerships with contractors and building-system suppliers. At the same time, margin pressure will remain visible because of petrochemical feedstock volatility, cost-sensitive procurement, and the need to qualify products through demanding standards. The most resilient companies will be those that combine technical depth with local market access and sustainability-ready portfolios.
Product Type Insights
Based on product type, the styrene block copolymers construction elastomers segment led the market with the largest revenue share of 22.4% in 2025 and is projected to grow at the fastest CAGR of 6.7% during the forecast period. It is a synthetic rubber known for its excellent weather resistance, thermal stability, and flexibility. It is widely used in roofing membranes, window and door seals, expansion joints, and waterproofing applications. EPDM is particularly valued for its ability to withstand extreme weather conditions and UV radiation, making it a preferred choice for outdoor construction applications.
Styrene Butadiene (SB) elastomers are synthetic rubbers that provide high resilience, heat resistance, and wear resistance. In construction, SB elastomers are primarily used in asphalt modification, adhesives, and waterproof coatings. They enhance the durability and flexibility of asphalt pavements and roofing materials, making them an essential component in infrastructure projects. The rising demand for high-performance asphalt in road construction and repair activities is a major factor propelling SB elastomer demand.
Application Insights
Based on application, the residential construction elastomers segment led the market with the largest revenue share of 43.2% in 2025 and is projected to grow at the fastest CAGR of 6.6% during the forecast period. In the residential sector, construction elastomers are widely used for sealing, insulation, roofing, flooring, and structural applications. Common elastomers such as silicone, polyurethane, and thermoplastic elastomers (TPEs) contribute to energy efficiency, noise reduction, and long-lasting performance in residential buildings. The growth of construction elastomers in the residential sector is primarily driven by increasing urbanization, rising disposable income, and growing demand for energy-efficient housing.
 To learn more about this report, Download Free Sample Report
The non-residential segment, which includes commercial buildings, offices, industrial facilities, and public infrastructure, extensively utilizes construction elastomers for structural reinforcement, sealing, flooring, and roofing applications. The demand for construction elastomers in the non-residential segment is driven by rapid industrialization, commercial expansion, and the need for durable, high-performance materials in modern infrastructure.
In civil engineering applications, construction elastomers play a crucial role in bridge expansion joints, tunnel linings, pavement materials, and structural reinforcements. Their elasticity, weather resistance, and shock-absorbing properties make them ideal for ensuring structural stability and long-term durability in large-scale infrastructure projects.
Region Insights
Asia Pacific dominated the construction elastomers market with the largest revenue share of 49.5% in 2025 and is anticipated to grow at the fastest CAGR of 6.3% over the forecast period. This positive outlook is due to its unprecedented urbanization and infrastructure development. Countries such as China, India, and Indonesia are undergoing massive construction booms, with new residential complexes, commercial buildings, and infrastructure projects requiring large quantities of elastomers for sealing, insulation, and vibration dampening applications. Moreover, Japan and South Korea contribute significantly through their focus on earthquake-resistant construction technologies, where specialized elastomers play a crucial role in seismic isolation systems.
 To learn more about this report, Download Free Sample Report
The construction elastomers market in China accounted for the largest market revenue share in the Asia Pacific in 2025. Construction elastomers market in China is experiencing robust growth primarily due to its massive infrastructure development and continued urbanization. Additionally, China's investment in earthquake-resistant structures has specifically increased the use of specialty elastomers that provide crucial vibration isolation and structural flexibility. The rapid adoption of prefabricated construction methods in China has created unique opportunities for elastomer applications. In cities like Shenzhen, where entire buildings are assembled from factory-built components, specially formulated elastomers are critical for creating weather-tight, durable joints between prefab elements.
North America Construction Elastomers Market Trends
North America’s growth in the global construction elastomers market is primarily due to its robust construction industry, stringent building codes, and emphasis on sustainable, energy-efficient construction solutions. Substantial infrastructure investment programs and the adoption of advanced building technologies that require high-performance elastomeric materials reinforce the region's growth. Moreover, the renovation and retrofitting market in North America also contribute significantly to elastomer demand.
The U.S. construction elastomers market growth is majorly driven by its ongoing infrastructure revitalization efforts. Besides, the stringent building codes and sustainability initiatives in the U.S. have further accelerated the adoption of construction elastomers. Projects seeking LEED certification often incorporate elastomeric materials for their energy efficiency contributions through improved insulation and air sealing properties. Major infrastructure projects like the new Hudson River tunnel and the ongoing rehabilitation of aging bridges nationwide rely heavily on specialized elastomers for waterproofing, vibration control, and structural flexibility.
Europe Construction Elastomers Market Trends
Construction elastomers market in Europe is growing primarily due to the region’s stringent building codes and environmental regulations. Countries such as Germany, France, and the UK have implemented regulations that specifically favor materials with superior thermal insulation properties and weather resistance, driving demand for advanced elastomers in building envelopes and structural components. The European commitment to sustainable building practices has further accelerated elastomer adoption. Projects such as the Bosco Verticale in Milan and the Edge Olympic in Amsterdam showcase the integration of high-performance elastomeric materials in green building design.
The construction elastomers market in Germany is primarily driven by its robust construction sector, stringent building regulations, and focus on energy efficiency. The German government's implementation of energy-efficient building codes, such as the Energy Saving Ordinance (EnEV), has spurred innovation in construction materials, including elastomers.
Key Construction Elastomers Company Insights
The global construction elastomers market is highly competitive, driven by key players such as BASF, Dow, Arkema, DuPont, and Covestro AG. These companies focus on product innovation, strategic partnerships, and mergers & acquisitions to strengthen their market presence. Market share distribution is influenced by technological advancements, raw material availability, and regulatory compliance. Smaller regional players compete by offering cost-effective and specialized solutions, while global leaders maintain their edge through extensive R&D and diversified product portfolios.
-
In August 2023, Covestro AG started production at its new polyurethane elastomers systems plant in Shanghai, China. This investment, in the double-digit USD million range, is part of a series of investments in the company's Elastomers raw materials business worldwide.
-
In September 2022, Lion Elastomers, a synthetic rubber manufacturer, invested USD 22.0 million to expand its Geismar plant in Ascension Parish, Louisiana. The expansion project included the construction of a new multi-level production building housing two new finishing lines. The expansion project is expected to strengthen Lion Elastomers' manufacturing position and enhance quality and service for EPDM (Ethylene Propylene Diene Monomer) consumers.
Key Construction Elastomers Companies
The following are the leading companies in the construction elastomers market.
-
Arkema
-
BASF
-
Dow
-
Covestro
-
Huntsman International LLC
-
Teknor Apex Company
-
Lubrizol Corporation
-
Shanghai Sinopec Mitsui Elastomers
-
Mitsubishi Chemical Company
-
DuPont
-
SIBUR
-
Evonik Industries AG
-
Motherson
- Dynasol Elastomers
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players ( Arkema, BASF, Dow, Covestro, Huntsman International LLC, Lubrizol Corporation, Shanghai Sinopec Mitsui Elastomers, Mitsubishi Chemical Company, DuPont, SIBUR, Evonik Industries AG, Dynasol Elastomers)
Focus on integrated elastomer platforms, broad product portfolios, and cross-selling across adhesives, sealants, roofing, and engineered materials.
Use R&D, application testing, and technical service to secure specification-led contracts with builders, contractors, and system suppliers.
Expand through partnerships, capacity upgrades, and regional manufacturing footprints close to major construction demand centers.
Strong brand recognition and long-established customer relationships across construction and materials value chains.
Better ability to absorb raw material volatility, compliance costs, and tender-based pricing pressure.
Wider technology base for high-performance, weather-resistant, and sustainability-oriented elastomer formulations.
Slower product refresh cycles compared with more focused specialty suppliers.
Higher operating complexity from large portfolios and geographically distributed businesses.
Greater exposure to commoditization in standard construction-grade materials.
Emerging Players (Teknor Apex Company, Motherson)
Target narrower application windows where customization, service speed, or regional responsiveness matter more than scale.
Build traction through selected compounding, private-label supply, and project-linked partnerships.
Compete on agility, short lead times, and application-specific formulations.
Faster response to localized customer requirements and changing project specifications.
Greater flexibility in product development and niche positioning.
Lower organizational inertia, which supports quicker commercial decisions.
Limited scale compared with global leaders.
Weaker bargaining power in raw materials and distribution.
Higher dependency on a smaller set of projects, customers, or regional markets.
Construction Elastomers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.9 billion
Estimated market size in 2026
USD 6.2 billion
Projected market size by 2033
USD 9.6 billion
Growth rate
CAGR of 6.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, application, region
RegioFinal scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, France, Italy, UK, China, Japan, India, Australia, Brazil, Argentina, Colombia, Saudi Arabia, UAE, and South Africa
Key companies profiled
Arkema; BASF; Dow; Covestro; Huntsman International LLC; Teknor Apex Company; Lubrizol Corporation; Shanghai Sinopec Mitsui Elastomers; Mitsubishi Chemical Company; DuPont; SIBUR; Evonik Industries AG; Motherson; Dynasol Elastomers
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase-addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Construction Elastomers Market Report Segmentation
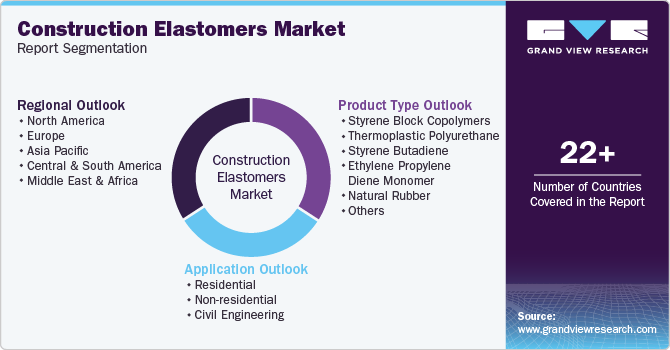
This report forecasts revenue growth at a global level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global construction elastomers market report based on product type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Type Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Styrene Block Copolymers
-
Thermoplastic Polyurethane
-
Styrene Butadiene
-
Ethylene Propylene Diene Monomer
-
Natural Rubber
-
Others
-
-
Application Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Residential
-
Non-residential
-
Civil Engineering
-
-
Region Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The construction elastomers market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each construction elastomers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue capture definition
Styrene Block Copolymers
Revenue is captured through sales of SBC compounds used in sealants, roofing membranes, adhesives, and modified construction materials, with value realized through formulation performance and project-grade supply.
Thermoplastic Polyurethane
Revenue is generated through premium-grade TPU sales for waterproofing membranes, glazing systems, cable protection, flooring layers, and high-flexibility sealing applications where durability and finish quality support higher pricing.
Styrene Butadiene
Revenue is captured through supply into concrete modification, asphalt modification, sealants, adhesives, and patching compounds, with volume driven by repair works, infrastructure maintenance, and cost-sensitive construction formulations.
Ethylene Propylene Diene Monomer
Revenue is earned from roofing sheets, expansion joints, weather seals, facade systems, and waterproofing products, with strong capture in large projects that require long-life and weather-resistant elastomeric performance.
Natural Rubber
Revenue is captured through vibration pads, bridge bearings, structural support elements, and general construction rubber goods, where demand remains tied to fabricated components and project-specific civil engineering needs.
Others
This segment captures revenue from silicone, chloroprene, nitrile, and specialty blends used in niche construction applications, custom compounding, and engineered sealing systems outside the core product categories.
Segment - Application
Revenue capture definition
Residential
Revenue is generated from elastomer use in roofing, sealing, flooring, windows, insulation, and renovation applications, with strong demand from housing starts, repair activity, and energy-efficiency upgrades.
Non-residential
Revenue is captured through supply into offices, commercial buildings, industrial facilities, hospitals, and data centers, where buyers require higher-performance sealing, waterproofing, flooring, and fire-resistant solutions.
Civil Engineering
Revenue is realized through bridge joints, tunnel linings, pavement systems, bearings, and infrastructure waterproofing, with procurement often tied to long-duration public works and maintenance contracts.
Estimation Model
Layer Name
Key Question
Description
Top-Down Market Layer
Why establish market baseline?
This layer anchors total market value to regional construction activity, infrastructure spending, and elastomer intensity across major end-use sectors.
Product Split Layer
Why analyze product mix?
This layer distributes demand across SBC, TPU, styrene butadiene, EPDM, natural rubber, and others based on formulation use and pricing.
Application Allocation Layer
Why assess end-use demand?
This layer allocates revenue across residential, non-residential, and civil engineering projects, reflecting specification depth and installation intensity
Regional Validation Layer
Why compare regional demand?
This layer refines estimates by geography, capturing Asia Pacific volume leadership, developed market compliance demand, and project mix differences.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Country-level analysis
Expanded the regional scope to include country-level demand patterns, project pipelines, and construction regulations across key markets.
Improves target-market selection and regional prioritization.
Company benchmarking
Added a comparative view of major suppliers by scale, integration, product breadth, and construction market positioning.
Helps identify leaders, challengers, and white spaces.
Sustainability view
Added a focused assessment of low-VOC, recyclable, and energy-efficient elastomer demand in modern construction.
Strengthens insight on premium segments and future demand shifts.
Frequently Asked Questions About This Report
The Asia Pacific Construction Elastomers market accounted for the largest share of 49.5% market size in 2025.
India was the leading Construction Elastomers market and is expected to grow at a compound annual growth rate of 7.1%.
Based on application, the residential segment accounted for the largest share of 43.2% market size in 2025. Growing demand for new housing developments, residential renovations, and energy-efficient buildings, increasing investments in urban housing infrastructure, and rising preference for durable, low-maintenance construction materials, together with advances in high-performance elastomer formulations and sustainable polymer technologies, are accelerating construction elastomers adoption for roofing membranes, sealants, waterproofing systems, window and door seals, insulation, flooring, and long-life residential building applications.
The non-residential segment, based on application, is expected to grow at a CAGR of 6.0% for the forecast period.
The styrene block copolymers construction elastomers industry led the construction elastomers product type market in 2025 with a 22.4% share. Growing demand for sealants, adhesives, roofing membranes, waterproofing systems, expansion joints, and flexible building components, coupled with increasing adoption of energy-efficient construction practices, rising preference for recyclable thermoplastic materials, and advances in polymer modification technologies, is accelerating styrene block copolymer adoption for durable, flexible, weather-resistant, and high-performance construction elastomer applications across residential, non-residential, and civil engineering projects.
The global construction elastomers market was estimated at around USD 5.9 billion in the year 2025 and is expected to reach around USD 6.2 billion in 2026.
The global construction elastomers market is expected to grow at a compound annual growth rate of 6.4% from 2026 to 2033 to reach around USD 9.6 billion by 2033.
The key players in the construction elastomers market include Arkema, BASF, Dow, Covestro, Huntsman International LLC, Teknor Apex Company, Lubrizol Corporation, Shanghai Sinopec Mitsui Elastomers, Mitsubishi Chemical Company, DuPont, SIBUR, Evonik Industries AG, Motherson, and Dynasol Elastomers.
The construction elastomers market is driven by rapid urbanization, infrastructure development, and the growing demand for durable, flexible, and energy-efficient materials. Additionally, advancements in polymer technology and increasing government initiatives for sustainable construction further fuel market growth.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


