
- Home
- »
- Communications Infrastructure
- »
-
Data Center As A Service Market Size Report, 2026 - 2033GVR Report cover

Data Center As A Service Market (2026 - 2033)
Size, Share & Trends Analysis Report By Infrastructure (Servers, Storage, Networking), By Enterprise Size (Large Enterprises, SMEs), By Vertical (IT & Telecom, Healthcare, Retail, BFSI), By Region, And Segment Forecasts
Market Size, 2025
$136.6BMarket Estimate, 2026
$162.9BMarket Forecast, 2033
$607.1BCAGR, 2026–2033
20.7%Data Center As A Service Market Summary
The global data center as a service market size was valued at USD 136.6 billion in 2025 and is projected to grow from USD 162.9 billion in 2026 to USD 607.1 billion in 2033, at a CAGR of 20.7% from 2026 to 2033. The market in North America dominated with a revenue share of 36.3% in 2025. North America's widespread adoption of cloud computing is accelerating demand for data center as a service solutions.
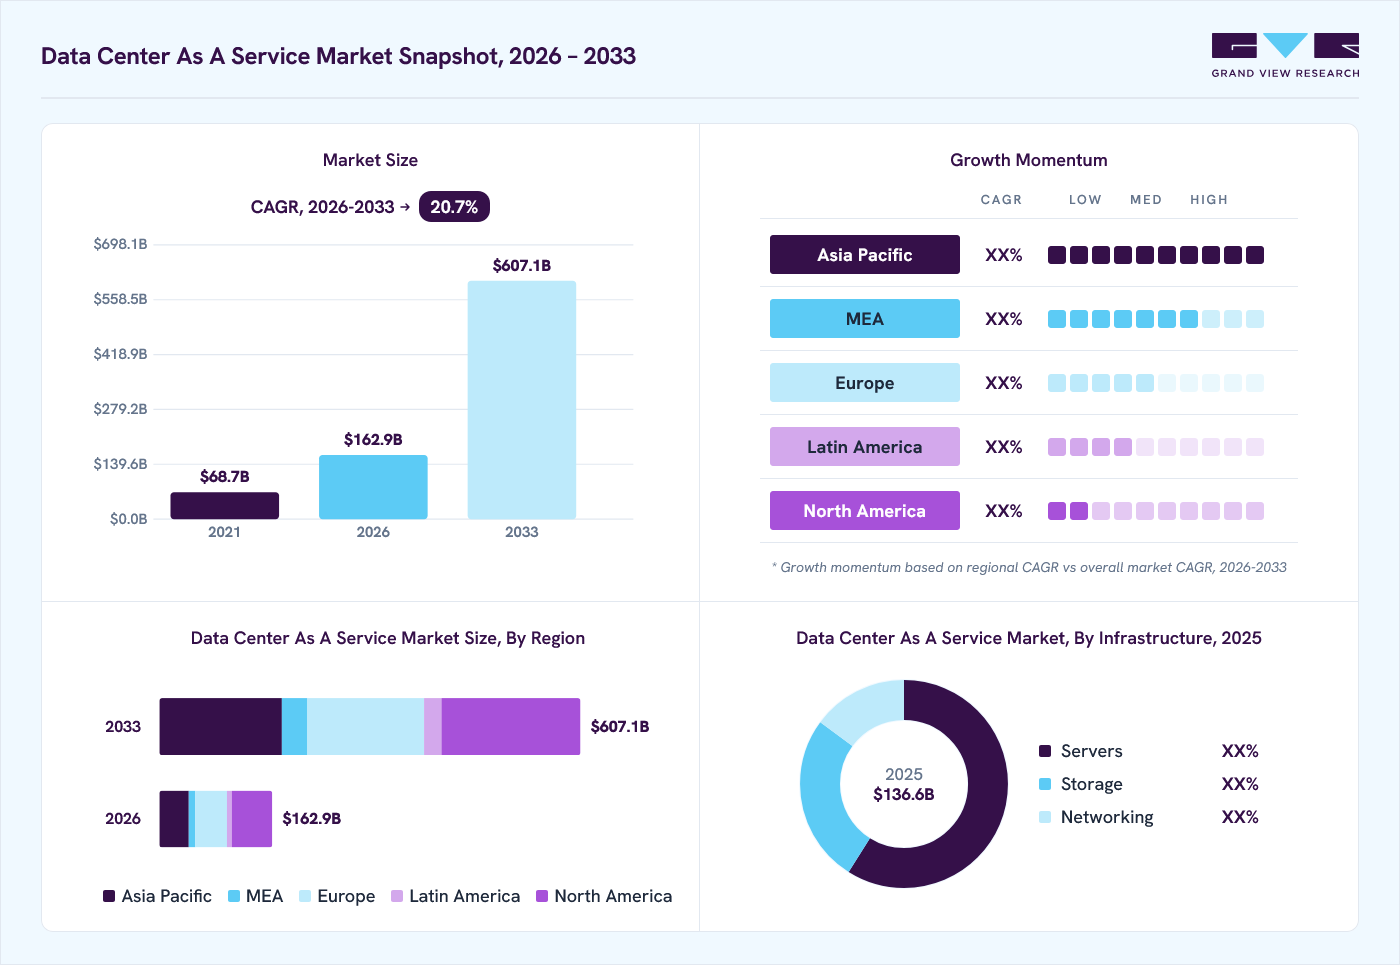 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By infrastructure: Servers segment dominated the market, with a revenue share of 58.9% in 2025.
- By Enterprises size: Large Enterprises segment held the largest market share of 55.8% in 2025.
- By vertical: IT & Telecom segment held the largest revenue share of 24.7% in 2025.
Regional Highlights
- Largest regional market: North America (36.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 136.6 Billion
- Estimated market size in 2026: USD 162.9 Billion
- Projected market size by 2033: USD 607.1 Billion
- CAGR (2026-2033): 20.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Enterprises are shifting from traditional on-premises infrastructure to cloud and hybrid environments to gain scalability, flexibility, and cost efficiency driving sustained growth in consumption-based data center services. The application of artificial intelligence in data centers is growing exponentially, owing to benefits such as greater efficiency in temperature management and predictive maintenance in data centers. For instance, DeepMind AI reduced Google’s data center cooling by 40% and improved energy efficiency by reducing overall emissions. Cloud helps in delivering a diverse set of applications, managing data, and restoring and creating backups and offers the ideal storage capacity. Furthermore, significant cost savings associated with the use of cloud-based platforms are prompting commercial establishments as well as government agencies to migrate to cloud storage and opt for cloud-based platforms, which is subsequently expected to drive the demand for data centers.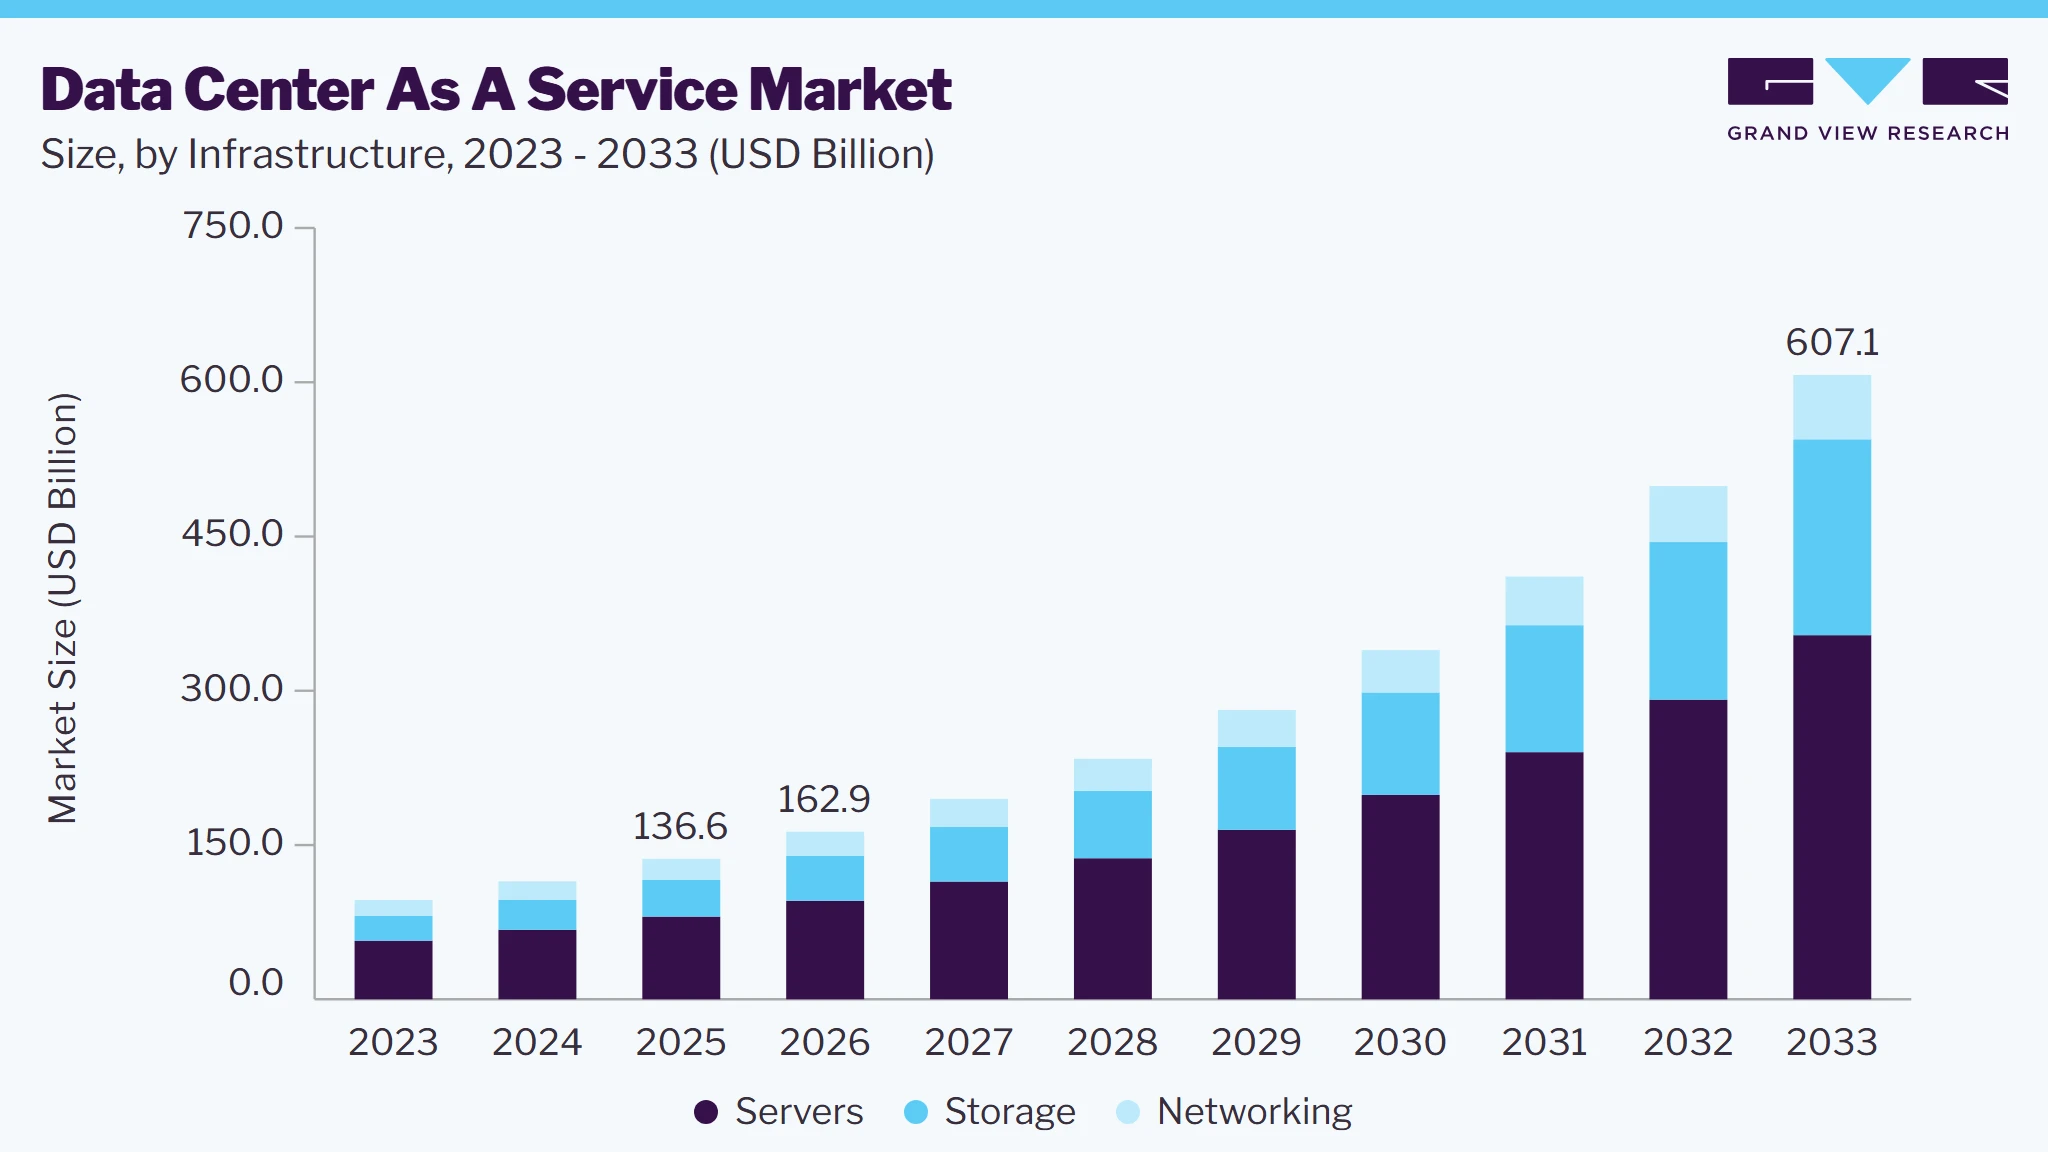 To learn more about this report, Download Free Sample Report
The rising dependency on data is increasing in day-to-day business operations and financial transactions. Modern data centers are emerging as an economic warehouse facility for the digitally connected world. These data centers are more than storage facilities; they offer advanced technological analysis, scaling, networking, storage, security, and computing facilities for platforms and applications. Governments and companies worldwide rely on data centers to store sensitive data related to operational and proprietary assets in a centralized and secure digital environment.
In addition, the rising need for enhanced disaster recovery and business continuity solutions also fuels the demand for the DCaaS industry. With increasing reliance on digital systems, businesses are highly vulnerable to disruptions caused by natural disasters, cyberattacks, or system failures. DCaaS providers offer redundancy, failover capabilities, and geographically dispersed data centers, ensuring uninterrupted access to critical data and applications. This resilience is a major selling point for enterprises looking to safeguard their operations against unforeseen events.
Advancements in networking technologies, such as 5G and software-defined networking (SDN), are further accelerating the growth of the DCaaS market. These technologies enable faster and more reliable connections between data centers and end-users, enhancing the overall performance of DCaaS solutions. With 5G facilitating low-latency and high-bandwidth connectivity, the adoption of edge computing is also increasing, driving demand for localized DCaaS offerings that support real-time data processing closer to the source.
Furthermore, the expansion of the DCaaS market is supported by increasing regulatory requirements and compliance needs. Many industries like finance, healthcare, and government operate under strict data privacy and security regulations. DCaaS providers offer advanced security measures, data encryption, and compliance certifications, ensuring that businesses can meet regulatory standards without the complexity of managing these requirements internally.
Market Dynamics
The data center as a service (DCaaS) market is witnessing strong growth as organizations increasingly seek scalable, flexible, and cost-efficient infrastructure solutions to support digital transformation initiatives. DCaaS enables enterprises to access computing, storage, networking, security, and disaster recovery capabilities through subscription-based or consumption-driven models, eliminating the need for significant upfront capital investments in data center infrastructure. The rapid adoption of cloud computing, artificial intelligence (AI), big data analytics, Internet of Things (IoT), and high-performance computing workloads is driving demand for agile and scalable data center services. Additionally, the growing prevalence of hybrid and multi-cloud environments, increasing focus on business continuity and disaster recovery, and rising data sovereignty and regulatory compliance requirements are encouraging organizations to leverage DCaaS offerings. The expansion of hyperscale data centers, edge computing deployments, and 5G networks is further accelerating market growth by creating demand for distributed, low-latency infrastructure. As enterprises continue to modernize IT operations and prioritize operational efficiency, demand for advanced data center as a service solutions is expected to grow steadily across industries worldwide.
The increasing adoption of cloud computing, artificial intelligence (AI), big data analytics, and hybrid IT environments is a major driver for the data center as a service (DCaaS) market. Organizations are modernizing their IT infrastructure to support data-intensive workloads while reducing capital expenditures and improving operational flexibility. DCaaS enables businesses to rapidly scale computing, storage, networking, and security resources on demand without investing in physical infrastructure. Furthermore, the growing use of AI applications, high-performance computing, and multi-cloud strategies is accelerating demand for flexible, consumption-based data center services across enterprises worldwide.
Data security, regulatory compliance requirements, and concerns regarding vendor dependency remain significant restraints for the DCaaS market. Organizations handling sensitive financial, healthcare, government, and customer data often face strict regulations related to data sovereignty, privacy, and cybersecurity. Migrating critical workloads to third-party infrastructure can raise concerns about data protection, compliance management, service availability, and operational control. Additionally, long-term reliance on a single service provider may create vendor lock-in challenges, making workload migration and infrastructure flexibility more complex for enterprises.
The rapid expansion of edge computing, 5G networks, and AI-driven workloads presents a significant opportunity for the DCaaS market. Enterprises increasingly require distributed, low-latency infrastructure capable of supporting real-time analytics, autonomous systems, industrial IoT, smart city applications, and AI model deployment. DCaaS providers are investing in edge data centers, GPU-enabled infrastructure, and AI-ready platforms to meet these evolving requirements. Furthermore, growing investments in digital transformation, hyperscale data center expansion, and industry-specific cloud solutions are creating substantial opportunities for DCaaS providers to deliver scalable, high-performance infrastructure services across global markets.
Analyst Perspective
The Data Center-as-a-Service (DCaaS) market is expanding rapidly as organizations adopt cloud computing, AI, hybrid and multi-cloud environments, edge computing, and digital transformation initiatives. DCaaS provides scalable, on-demand infrastructure services that help enterprises reduce IT complexity, optimize costs, and improve operational agility. Leading providers are differentiating themselves through AI-ready infrastructure, high-performance computing, advanced cybersecurity, automation, energy-efficient operations, and hybrid cloud integration. Growing adoption across industries such as BFSI, healthcare, manufacturing, retail, government, and telecommunications, along with rising data volumes and regulatory requirements, is expected to drive sustained long-term market growth.
Infrastructure Insights
Based on infrastructure, the servers segment led the market with the largest revenue share of 58.9% in 2025 and is expected to grow at the significant CAGR over the forecast period. Academic institutions, defense agencies, and government agencies are aggressively adopting new, innovative solutions based on the latest digital technologies, such as artificial intelligence (AI), internet of things (IoT), and machine learning (ML), thereby driving the need for sophisticated, hyper-converged IT infrastructure comprising high-performance computing servers to run complex software-defined solutions and process large volumes of data. The strong emphasis on maintaining a pool of servers to ensure adequate processing power to process large volumes of data bodes well for the segment's growth over the forecast period. In April 2021, Alibaba, a multinational technology company based in China, expanded its Zhongdu Grassland project data center in Zhangbei County, China. The latest expansion involved 10 data center buildings with over 200,000 server cabinets. The expansion fell under the company’s plans to expand to over 1 billion servers. Such developments are expected to contribute to the segment's growth over the forecast period.
The storage segment is anticipated to grow significantly with a CAGR of 23.4% over the forecast period. The rising volumes of computing data across the globe are also driving the demand for storage systems to ensure quick access to the data. Several countries focus on establishing virtual data storage systems to reduce their reliance on overseas organizations and strengthen data security. Infrastructure software enables the digital storage system to control, monitor, secure, and manage data without excessive operational costs. These are the primary factors expected to drive the data center as a service market demand.
Enterprise Size Insights
Based on organization size, large enterprises segment led the market with the largest revenue share of 55.8% in 2025. Favorable government regulations to encourage the establishment of data centers and the aggressive investments made by large companies in hosting private data centers are expected to open new opportunities for the segment's growth in the data center-as-a-service industry. For instance, in March 2022, Macquarie Telecom Group launched its data center at Macquarie Park Data Centre Campus in the North Zone of Sydney, Australia. The company also announced plans to construct data centers in the Northern area. Similarly, in April 2022, Kasi Cloud Ltd. embarked on building data centers and establishing digital infrastructure platforms in Lagos, Nigeria. The company has been looking forward to establishing a digital storage ecosystem and providing data virtualization services across Africa.
The SME segment is expected to grow significantly with a CAGR of over 22.7% over the forecast period. The growing reliance of SMEs on digital tools and cloud-based applications drives the segment growth. As businesses adopt Software-as-a-Service (SaaS) platforms, e-commerce solutions, and customer relationship management (CRM) systems, their data processing and storage needs are escalating. DCaaS solutions offer the scalability and reliability necessary to support these workloads, allowing SMEs to focus on core business activities without being constrained by IT infrastructure limitations.
Verticals Insights
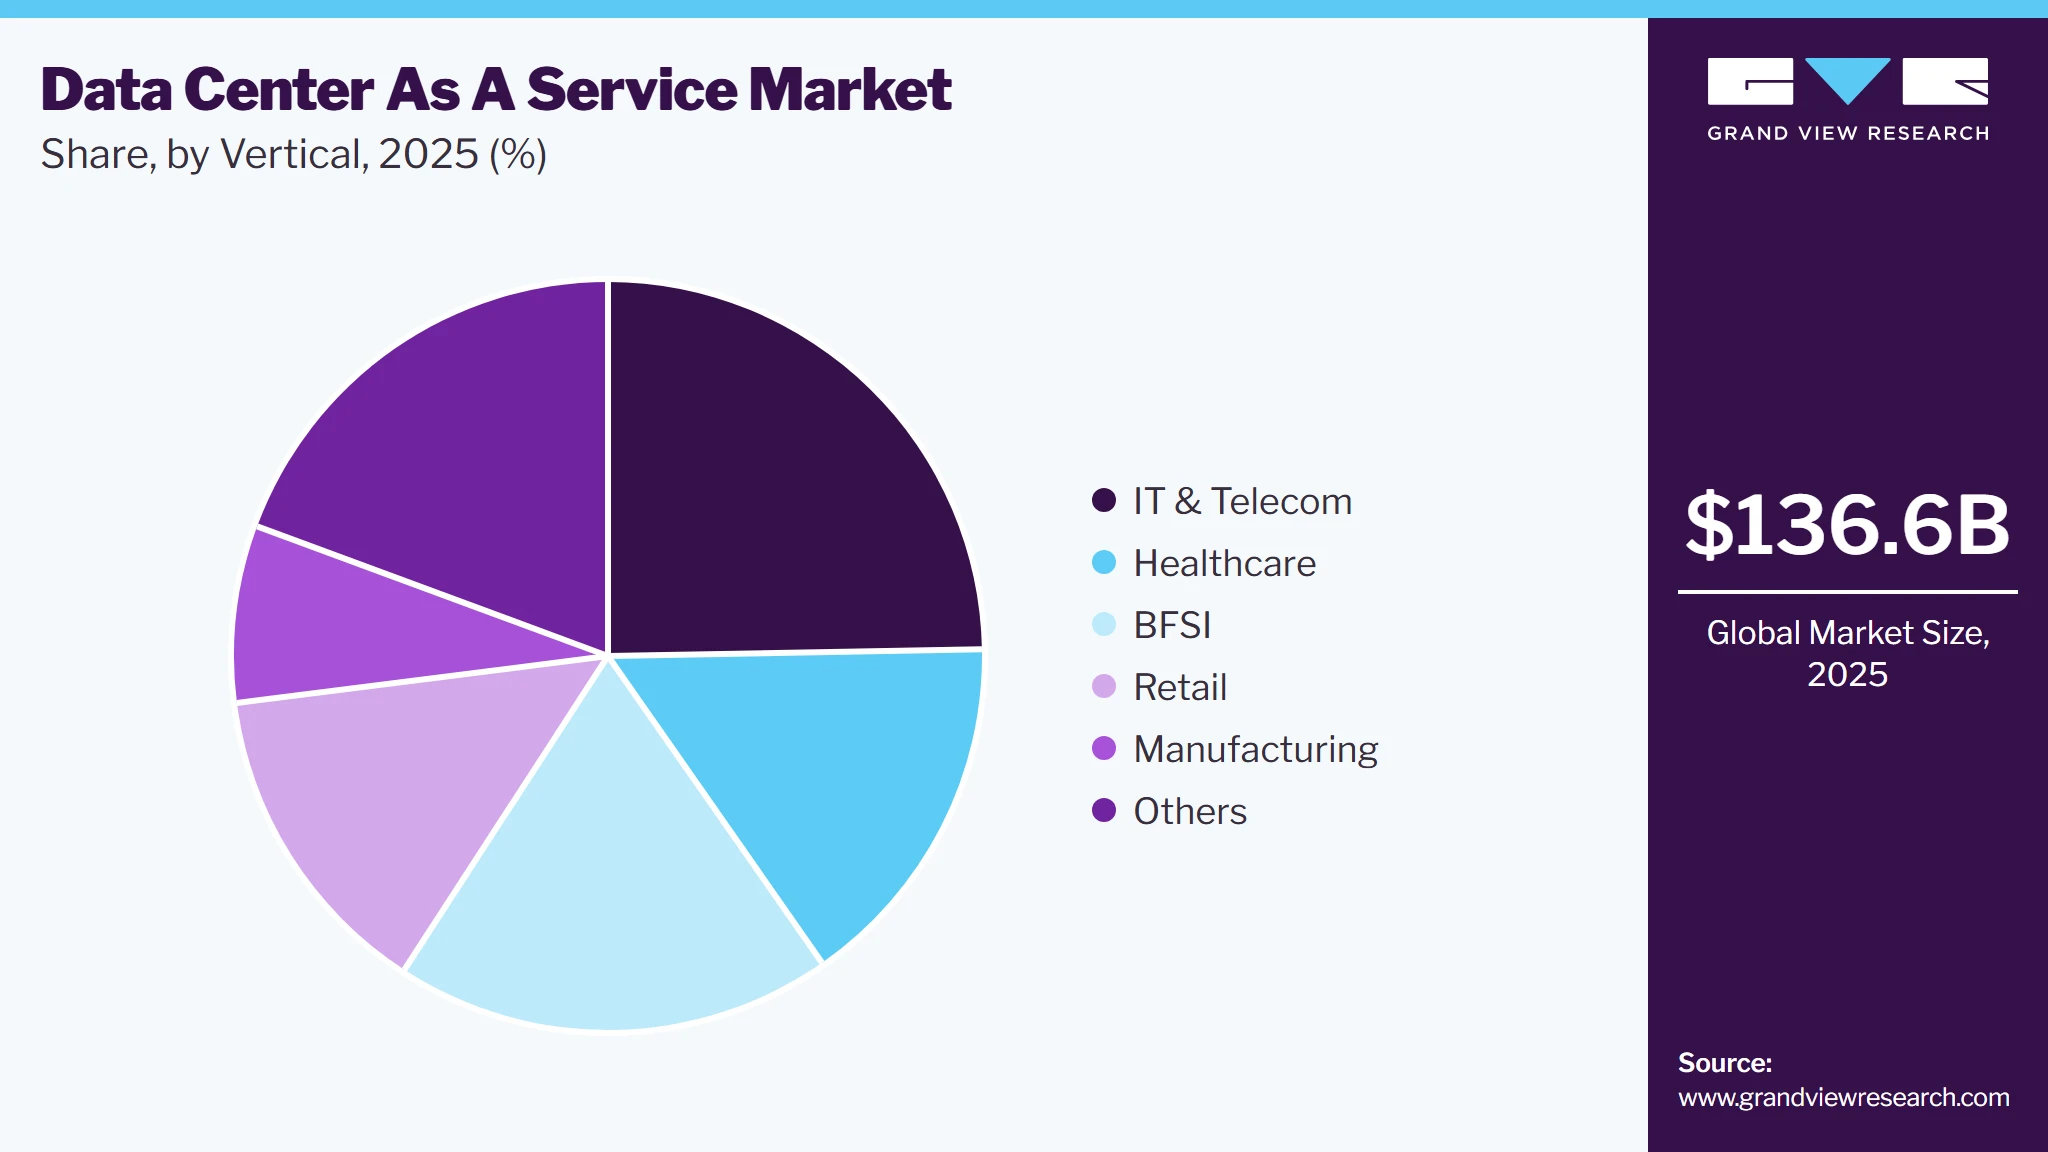
Based on vertical, IT & Telecom segment led the market with the largest revenue share of 24.8% in 2025. The IT & telecommunications industry is evolving rapidly in line with the changing data processing and latency needs and the advances in the latest technologies, such as IoT, 5G, virtual reality (VR), and augmented reality (AR). Telecommunications companies are particularly managing their infrastructure needs by establishing their own data centers using a private cloud for both core and non-core networking operations. The rollout of 5G networks is another critical factor propelling DCaaS adoption in the telecom sector. 5G technology requires a distributed network of edge data centers to ensure low latency, high-speed connectivity, and seamless service delivery. Telecom providers leverage DCaaS offerings to build and maintain these edge data centers efficiently, reducing operational complexities and capital expenditure while ensuring rapid deployment in diverse geographical regions.
 To learn more about this report, Download Free Sample Report
The increasing digitalization of healthcare operations and the rising need for robust IT infrastructure drive the segment growth. Healthcare providers, including hospitals, clinics, and research institutions, are rapidly adopting DCaaS solutions to manage the growing volume of electronic health records (EHRs), imaging data, and patient information. With the surge in telemedicine and remote patient monitoring, healthcare organizations require scalable and secure data storage and computing solutions to ensure seamless access and real-time processing of critical information. DCaaS offers the flexibility to scale resources based on demand, enabling healthcare institutions to optimize costs while maintaining high levels of efficiency and data accessibility.
Regional Insights
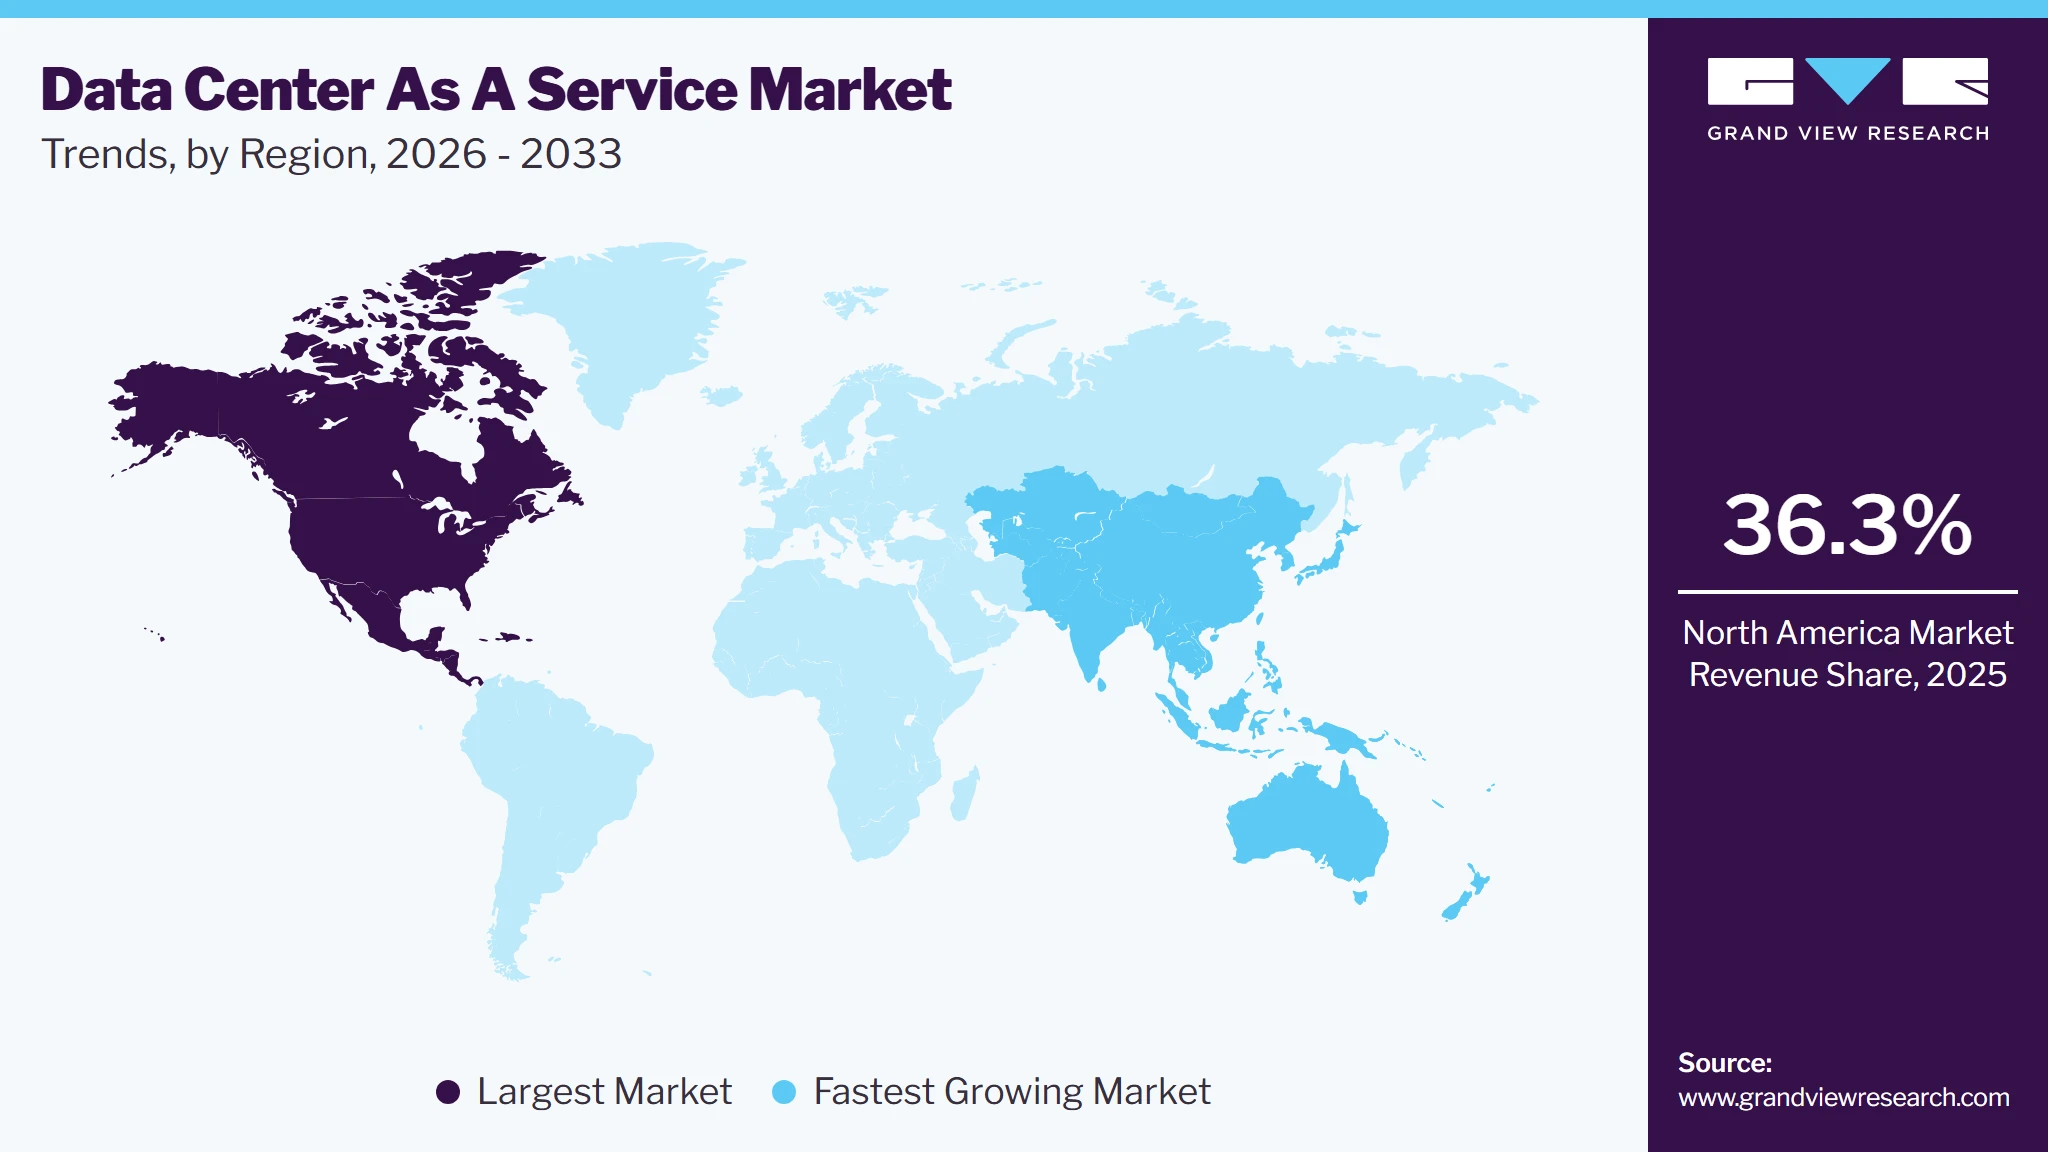
North America dominated the data center as-a-service market with the largest revenue share of 36.3% in 2025. The rise of edge computing is propelling the North American DCaaS industry. With the proliferation of Internet of Things (IoT) devices and the demand for real-time data processing, edge computing is becoming a critical infrastructure of IT strategies. DCaaS providers increasingly incorporate edge capabilities into their offerings, allowing businesses to process data closer to the source and reduce latency. This is particularly beneficial for industries such as autonomous vehicles, smart cities, and industrial automation, where real-time data analysis is essential for operational success. The integration of edge computing with DCaaS is reshaping how organizations manage data and drive innovation.
 To learn more about this report, Download Free Sample Report
U.S. Data Center As A Service Market Trends
The data center as-a-service market in the U.S. held the largest share in the North America region in 2025. The demand for data center as-a-service in the U.S. is experiencing significant growth. E-commerce and digital platforms drive the growth of DCaaS in the U.S. The explosive growth of online shopping and the shift toward digital-first customer engagement strategies have increased the demand for scalable IT infrastructure. DCaaS solutions enable e-commerce businesses to handle surges in traffic during peak seasons, ensure smooth transaction processing, and maintain a seamless user experience. By providing the ability to scale resources dynamically, DCaaS supports the operational agility that e-commerce companies require to thrive in a competitive landscape.
Asia Pacific Data Center As A Service Market Trends
Asia Pacific data center as-a-service market is expected to achieve the fastest CAGR of 22.6% during the forecast. The demand for data center development and infrastructure is growing in Asia Pacific owing to the large data volumes generated by extensive telecom networks, a large e-commerce customer base, and numerous service providers in the region, resulting in high server traffic flows. For instance, in February 2021, Linode LLC announced its plan to expand its services for its faster-growing customer base in APAC by adding a new GPU instance to its data center facility in Singapore. The new capability offers low-latency features for near-real-time data analysis, image processing, AI, video transcoding, and other data and processing applications. Furthermore, the growing number of startups and SMEs in the region is expected to fuel the adoption of data centers as a service.
Bottom of Form Key Data Center As A Service Company Insights
Some key players operating in the market include IBM Corporation, Microsoft Corporation, and Hewlett Packard Enterprise Development LP, among others.
-
IBM Corporation is a global technology company. IBM’s DCaaS solution is designed to provide enterprises with scalable, secure, and efficient data center infrastructure without the need to manage on-premise facilities. IBM’s DCaaS leverages its hybrid cloud expertise to offer flexible and cost-effective options for businesses looking to optimize their IT operations. IBM operates a vast network of global data centers, providing localized solutions that meet regional compliance and latency requirements. Through strategic partnerships with organizations like VMware, Red Hat, and SAP, IBM enhances the capabilities of its DCaaS offerings, ensuring compatibility with diverse enterprise ecosystems.
DigitalOcean, LLC and Linode are some of the emerging market participants in the target market.
-
DigitalOcean, LLC is a cloud infrastructure provider that specializes in offering simple, cost-effective cloud services tailored to developers, startups, and small- to medium-sized enterprises (SMEs). DigitalOcean’s DCaaS model provides businesses with reliable, high-performance infrastructure that eliminates the need for on-premise data centers. This service is designed to meet the needs of developers and SMEs looking for accessible and affordable data solutions. With data centers strategically located around the globe, DigitalOcean ensures fast and reliable access to its services for users worldwide. The company continuously invests in expanding its global footprint to meet the growing demand for cloud services. Its presence in emerging markets positions it to capture new growth opportunities in regions with increasing digital adoption.
Key Data Center As A Service Companies:
The following key companies have been profiled for this study on the data center as a service market.
- IBM Corporation
- Microsoft
- Hewlett Packard Enterprise Development LP
- Dell Technologies, Inc.
- Alibaba
- DigitalOcean, LLC
- Linode
- Equinix
- Huawei Technologies Co., Ltd.
- Amazon.com, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Amazon Web Services (AWS), Microsoft Azure, Google Cloud, IBM, Oracle Cloud Infrastructure, Alibaba Cloud, Equinix, Digital Realty)
- Established players focus on delivering comprehensive DCaaS offerings that include compute, storage, networking, security, backup, disaster recovery, AI infrastructure, and hybrid cloud services. Their strategies emphasize continuous expansion of hyperscale data center capacity, AI-ready infrastructure, edge computing deployments, and multi-cloud management capabilities.
- These providers benefit from extensive global data center footprints, massive capital resources, advanced cloud platforms, strong brand recognition, mature service portfolios, and large enterprise customer bases. Their ability to offer integrated cloud, AI, analytics, security, and infrastructure services enables them to support complex digital transformation initiatives across industries.
- High infrastructure and energy costs, increasing regulatory scrutiny, data sovereignty requirements, and significant capital expenditure commitments can impact profitability. They also face challenges related to power availability, data center capacity constraints, and customer concerns regarding vendor lock-in and workload portability.
Emerging Players (Equinix, Digital Realty, NTT Global Data Centers, Iron Mountain Data Centers, CyrusOne)
- Emerging players focus on specialized DCaaS offerings such as AI cloud infrastructure, GPU-as-a-Service, edge computing, developer-focused cloud platforms, and cost-effective infrastructure solutions. Many emphasize simplified deployment, flexible pricing models, industry-specific services, and regional cloud infrastructure expansion to target SMEs, startups, AI developers, and mid-sized enterprises.
- These companies offer greater agility, faster service innovation, competitive pricing, and specialized infrastructure tailored to specific workloads such as AI training, edge computing, content delivery, and cloud-native applications. Their focused business models enable quicker response to evolving customer requirements and emerging technology trends.
- Limited global infrastructure footprints, lower financial resources, and smaller customer ecosystems may restrict their ability to compete with hyperscale providers. Dependence on leased facilities, narrower service portfolios, and lower brand visibility can impact large enterprise adoption and long-term market expansion.
Recent Developments
-
In November 2024, Nokia signed a five-year agreement to supply Microsoft Azure with data center switches and routers, enhancing the scalability and reliability of Azure's global data centers. This partnership will extend Nokia's reach to more than 30 countries, strengthening its role as a crucial supplier for Microsoft's worldwide cloud infrastructure. Additionally, the collaboration advances the companies' joint efforts on open-source SONiC, highlighting Nokia's innovation in expanding SONiC's capabilities, including support for chassis-based solutions designed for high-capacity network roles in data centers.
-
In August 2024, Hewlett Packard Enterprise Development LP launched a new managed data center hosting service in the UAE, collaborating with Khazna Data Centers, a prominent provider of advanced hyperscale solutions. This service aligns with the UAE's national artificial intelligence (AI) strategy, encompassing various AI initiatives with top regional institutions. The offering grants access to a data center designed for end-to-end high-performance computing technologies, specifically built for AI, covering computing, software, networking, and direct liquid cooling.
Data Center As A Service Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 136.6 billion
Market size value in 2026
USD 162.9 billion
Revenue forecast in 2033
USD 607.1 billion
Growth rate
CAGR 20.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Infrastructure, enterprise size, vertical, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
IBM Corporation; Amazon.com, Inc.; Microsoft; Hewlett Packard Enterprise Development LP; Dell Technologies, Inc.; Alibaba; DigitalOcean, LLC; Linode; Equinix; Huawei Technologies Co., Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Data Center As A Service Market Report Segmentation
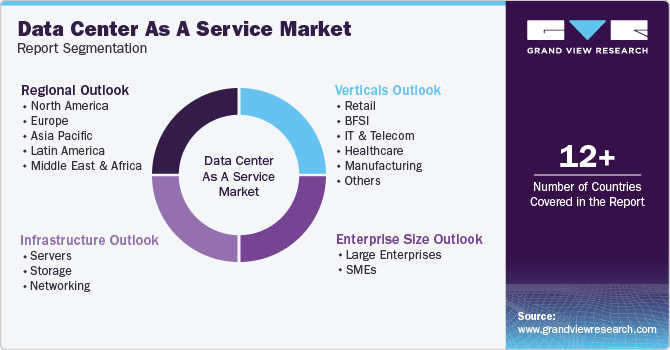
This report forecasts revenue growths at global, regional, as well as at country levels and offers qualitative and quantitative analysis of the market trends for each of the segments and sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global data center as a service market report based on infrastructure, enterprise size, verticals, and region:
 To learn more about this report, Download Free Sample Report
-
Infrastructure Outlook (Revenue, USD Billion,2021 - 2033)
-
Servers
-
Storage
-
Networking
-
-
Enterprise Size Outlook (Revenue, USD Billion, 2021 - 2033)
-
Large Enterprises
-
SMEs
-
-
Verticals Outlook (Revenue, USD Billion, 2021 - 2033)
-
Retail
-
BFSI
-
IT & Telecom
-
Healthcare
-
Manufacturing
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The data center as a service market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each data center as a service segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Infrastructure
Revenue capture definition
Servers
Servers refer to the computing resources provided through the DCaaS model, including physical and virtual servers that support application hosting, data processing, database management, artificial intelligence workloads, and enterprise computing requirements. DCaaS providers offer scalable server capacity on a pay-per-use or subscription basis, enabling organizations to increase or decrease computing resources according to workload demands.
Storage
Storage encompasses the data storage infrastructure delivered through DCaaS, including block, file, and object storage solutions used for data retention, backup, disaster recovery, archiving, and analytics. These services allow enterprises to securely store and manage growing volumes of structured and unstructured data without investing in on-premises storage infrastructure.
Networking
Networking includes the connectivity infrastructure and services that enable communication between servers, storage systems, cloud platforms, applications, and end users. DCaaS networking services typically include routers, switches, firewalls, load balancers, software-defined networking (SDN), and interconnection services that ensure secure, reliable, and high-performance data transmission.
Segment - Enterprise Size
Revenue capture definition
Large Enterprises
The Large enterprises segment, with respect to the number of employees, typically comprises organizations employing more than 1,000 employees for multinational corporations.
Small and Medium-Sized Enterprises
(SMEs)
The SMEs segment, with respect to the number of employees, generally includes organizations employing between 10 and 999 employees.
Segment - Vertical
Revenue capture definition
Retail
The retail segment includes e-commerce companies, retailers, supermarkets, and consumer goods businesses that utilize DCaaS solutions to support online transactions, customer analytics, inventory management, digital commerce platforms, and omnichannel operations. DCaaS helps retailers manage fluctuating workloads and improve customer experiences.
BFSI
The BFSI segment comprises banks, insurance companies, investment firms, payment service providers, and financial institutions that use DCaaS for secure transaction processing, digital banking, fraud detection, risk management, regulatory compliance, and business continuity. High security, reliability, and scalability are critical requirements within this sector.
IT & Telecom
The IT and telecommunications segment includes software companies, cloud service providers, managed service providers, internet companies, and telecommunications operators. These organizations rely on DCaaS to support cloud applications, network services, data processing, content delivery, AI workloads, and large-scale digital infrastructure deployments.
Healthcare
The healthcare segment includes hospitals, clinics, healthcare providers, pharmaceutical companies, biotechnology firms, and medical research organizations. DCaaS solutions support electronic health records (EHRs), telemedicine platforms, medical imaging, healthcare analytics, and regulatory compliance while ensuring data security and availability.
Manufacturing
The manufacturing segment consists of industrial enterprises utilizing DCaaS to support smart factory operations, industrial automation, predictive maintenance, supply chain management, digital twins, and Industrial Internet of Things (IIoT) applications. DCaaS enables manufacturers to process large volumes of operational and production data efficiently.
Others
The others segment includes government agencies, educational institutions, energy and utilities companies, transportation providers, media and entertainment organizations, and other industries that leverage DCaaS solutions for digital services, data management, application hosting, business continuity, and operational modernization.
Estimation Model
Layer
Question
Analysis
Enterprise Infrastructure Demand Layer
Who requires Data Center as-a-Service solutions?
Identify end-user organizations requiring scalable IT infrastructure, including BFSI, IT & Telecom, healthcare, retail, manufacturing, government, education, and digital-native enterprises. Assess the volume of organizations undergoing cloud migration, digital transformation, AI adoption, and data-intensive operations to establish the total addressable market for DCaaS solutions.
Technology Adoption & Cloud Readiness Layer
Which organizations can deploy DCaaS solutions?
Evaluate enterprise readiness for cloud, hybrid cloud, multi-cloud, AI, big data analytics, disaster recovery, and edge computing deployments. Analyze factors such as IT modernization initiatives, regulatory requirements, cybersecurity needs, workload scalability requirements, and cloud adoption maturity to determine potential DCaaS deployment opportunities.
Infrastructure Investment & Digital Transformation Layer
Who actively invests in DCaaS solutions?
Analyze investments by enterprises, hyperscale cloud providers, colocation operators, managed service providers, government agencies, and large digital businesses. Assess growth in cloud spending, AI infrastructure investments, data center outsourcing trends, digital transformation programs, and business continuity initiatives to identify active adopters of DCaaS services.
Monetization Layer
How much revenue is generated?
Quantify revenue generated from server-as-a-service, storage-as-a-service, networking-as-a-service, managed infrastructure services, disaster recovery services, hybrid cloud services, and colocation-integrated DCaaS offerings. Evaluate recurring revenues from subscription-based and consumption-based pricing models across enterprise segments and industry verticals.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Data Center Infrastructure & Cloud Adoption Assessment
Analyzed regional data center capacity, cloud adoption rates, hyperscale investments, colocation expansion, power availability, connectivity infrastructure, regulatory environments, and digital transformation initiatives across Latin America, and the Middle East & Africa.
Helps investors, cloud providers, colocation operators, and infrastructure vendors identify attractive growth markets, optimize expansion strategies, strengthen infrastructure planning, and capitalize on emerging digital economy opportunities.
Competitive Benchmarking & Service Innovation Assessment
Assessed service portfolios, cloud and hybrid infrastructure capabilities, AI and HPC offerings, edge computing strategies, sustainability initiatives, security frameworks, pricing models, and go-to-market approaches of leading and emerging DCaaS providers globally.
Helps stakeholders benchmark competitors, identify differentiation opportunities, evaluate partnership or acquisition prospects, and develop effective market positioning strategies.
Data Center Sustainability & Energy Efficiency Assessment
Evaluated renewable energy adoption, power utilization effectiveness (PUE) improvements, liquid cooling technologies, carbon reduction initiatives, and sustainability strategies implemented by major data center operators and cloud providers.
Helps stakeholders align infrastructure investments with ESG goals, optimize operational efficiency, meet regulatory requirements, and enhance competitive positioning in sustainability-focused markets.
Frequently Asked Questions About This Report
The servers segment led with a 58.9% revenue share in 2025, while storage segment is the fastest-growing segment.
The large enterprises segment led with a 55.8% revenue share in 2025, while SMEs segment is the fastest-growing segment.
The IT & Telecom segment held the largest share (over 24.0%) in 2025, while healthcare segment is the fastest-growing segment.
Some key players operating in the data center as a service market include Amazon.com, Inc., Microsoft Corporation, IBM, Hewlett Packard Enterprise Development LP, Alibaba, Huawei Technologies Co., Ltd., and Dell Technologies, Inc. among others.
The global data center as a service market size was valued at USD 136.6 billion in 2025 and is estimated at USD 162.9 billion in 2026.
Key factors that are driving the market growth include the high data center ownership cost, proliferation of connected devices, and the emerging Metaverse concept.
North America dominated with 36.3% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The global data center as a service market is expected to grow at a CAGR of 20.7% from 2026 to 2033 to reach USD 607.1 billion by 2033.
About the Author(s)
Communications Infrastructure Research Team
Technology · Communications InfrastructureThis report was authored by the communications infrastructure research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the communications infrastructure segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


