
- Home
- »
- Healthcare IT
- »
-
Digital Health For Obesity Market Size Report, 2026-2033GVR Report cover

Digital Health For Obesity Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Hardware, Software, Services), By End-use (Patients, Providers, Payers), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$70.1BMarket Estimate, 2026
$85.5BMarket Forecast, 2033
$392.9BCAGR, 2026–2033
24.3%Digital Health For Obesity Market Summary
The global digital health for obesity market size was valued at USD 70.1 billion in 2025 and is projected to grow from USD 85.5 billion in 2026 to USD 392.9 billion by 2033, growing at a CAGR of 24.3% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 37.1% in 2025. Increasing smartphone penetration, growing lifestyle changes, including sedentary habits and unhealthy dietary choices, increasing prevalence of chronic diseases, rising healthcare expenditure, and increasing accessibility of virtual care are driving the adoption of digital health technologies in addressing obesity.
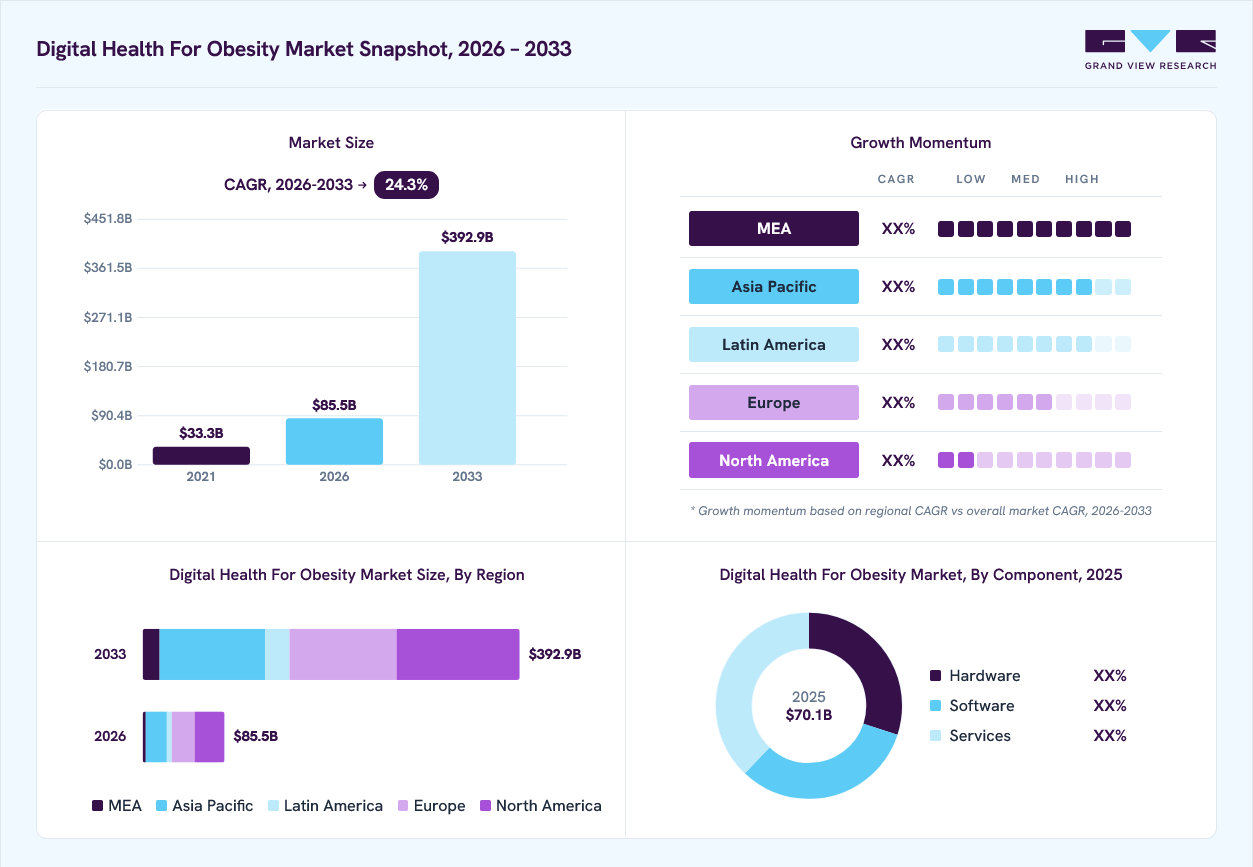 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Services segment held the largest revenue share of 38.0% in 2025.
- By end use: Patients segment held the largest revenue share of 34.8% in 2025.
Regional Highlights
- Largest regional market: North America (37.1% revenue share, 2025)
- Fastest-growing regional market: Middle East & Africa (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 70.1 Billion
- Estimated market size in 2026: USD 85.5 Billion
- Projected market size by 2033: USD 392.9 Billion
- CAGR (2026-2033): 24.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The increasing penetration of smartphones worldwide, coupled with the availability of mobile health apps, has contributed to the rising adoption of mHealth apps among consumers. According to Boston Technology, 52% of smartphone users have health-based mobile applications. In addition, the availability of low or no-cost applications is increasing the adoption of mobile apps. Over 90% of mHealth applications are free of cost. Healthcare professionals also use mHealth applications for treating patients. As per Boston Technology, 80% of physicians use smartphones and health-based applications. They are increasingly showing interest in mHealth apps and are recommending them to their patients. Almost half of the physicians use mHealth apps to correspond with patients. As per IMS Health data, the 30-day retention rate for prescribed mHealth apps is approximately 59%, and 76% for fitness apps.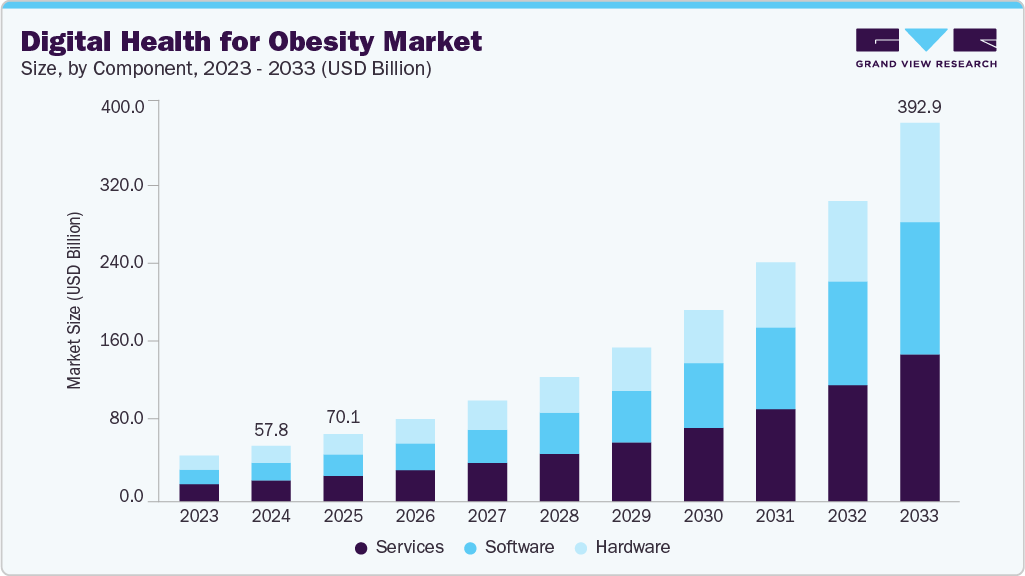 To learn more about this report, Download Free Sample Report
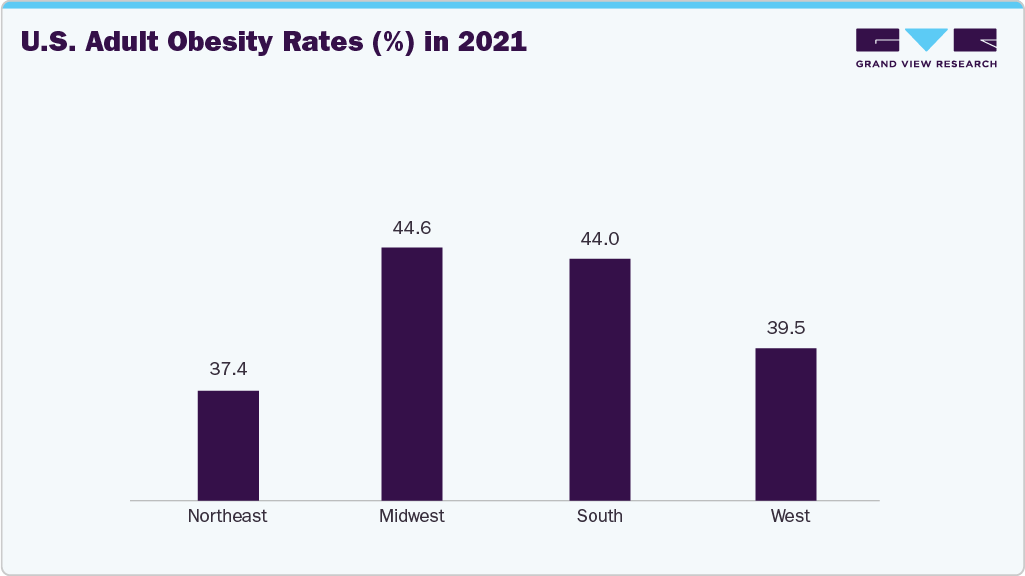
The rising incidence of obesity is expected to increase the prevalence of other chronic diseases. For instance, according to the World Atlas 2023 report, the prevalence of obesity among children and adolescents in the Americas is expected to increase from 2020 to 2035. Boys are likely to see an increase from 20% to 33%.
Furthermore, obesity is also expected to increase among men and women during the same 15-year period, with almost half of all adults (47% to 49%) predicted to be affected by obesity by 2035. Additionally, as per the Johns Hopkins University study, the risk of heart failure increased by 32% in the study for every five-point increase in body mass index (BMI). The increasing focus on preventive care is escalating the demand for digital health solutions.
Obesity is a major health issue for over 1 billion individuals across the world, including adults, adolescents, and children; as per the report of WHO, approximately 167 million people will be obese by 2025. The number of people affected by this problem is increasing, which is concerning as it is linked to serious health conditions such as type 2 diabetes and cardiovascular diseases.
Digital health tools have become essential in managing dietary habits and nutrition, offering personalized solutions to combat obesity and promote healthier lifestyles. For instance, mobile apps such as MyFitnessPal and Noom Coach use AI to provide personalized dietary guidance through individualized meal plans. At the same time, wearable technology such as Fitbit and Apple Watch helps track and monitor nutrition and physical activity. Online platforms such as Coursera and Udemy offer nutrition courses, and social media groups provide supportive communities for those dealing with weight management. These digital health solutions and fitness apps that use machine learning and AI to offer personalized fitness plans and diet guidance are expected to drive the market's growth as they offer advantages over traditional fitness methods.
Fitness apps utilize machine learning, artificial intelligence, and other technologies to offer personalized fitness plans to their customers. They also offer personalized diet charts, no equipment workout routines, track footsteps, monitor diet, and provide personalized health and fitness coaches. Such offerings and advantages over brick-and-mortar are expected to increase the market's growth potential. For instance, HealthifyMe offers calorie tracking, nutrition guidance, and personalized diet plans to support healthy eating habits for its users. In addition, wearable technology is a growing and widely utilized technology by customers. Health and fitness apps exhibit the highest retention rates, as 96.0% of users utilize only one of these apps.
 To learn more about this report, Download Free Sample Report
Studies have shown the effectiveness of digital health interventions in promoting healthy eating habits and weight management. A 2021 review published in the journal Obesity Reviews found that digital interventions led to an average weight loss of 2.1 kg (4.6 lbs) compared to control groups. Moreover, the National Health Interview Survey (NHIS) conducted by the Centers for Disease Control and Prevention (CDC) in the U.S. found that among adults who used a mobile health app to track their health in 2020, 41.4% reported using an app to track their weight, and 36.4% reported using an app to track their food intake.
GLP-1 drugs
GLP-1 drugs have become essential in the field of obesity treatment, as many digital health companies are transforming obesity care by incorporating therapies such as Wegovy, Ozempic, and Mounjaro into their virtual weight-loss programs. Services offered by platforms, including Ro, Found, Form Health, Sequence (associated with WeightWatchers), and Calibrate, provide access to prescription-based GLP-1 therapies along with supportive features such as coaching, dietary guidance, and telehealth monitoring. These GLP-1 medications are recognized as breakthrough therapies for obesity and are often central to subscription-based digital care models, highlighting their importance in effectively managing weight and improving health outcomes.
GLP1 drugs available on Digital platforms:
Drug Name (Brand)
Main Use
Provider
Rybelsus (Semaglutide)
Type 2 Diabetes
Novo Nordisk
Mounjaro (Tirzepatide)
Type 2 Diabetes, Weight Management
Eli Lilly and Company
Pendulum GLP-1 Probiotic
Gut health, Appetite control
Hebron Nutrition
In the new Metabolic Tech Stack, GLP-1 drugs are now paired with digital health tools to form a holistic obesity treatment model:
Layer
Component
Description
Bio Layer
GLP-1s
The pharmacological base triggering metabolic shifts.
Data Layer
Wearables + Apps
Continuous feedback loops: weight, activity, glucose, mood.
Behavioral Layer
Digital CBT + Coaching
Real-time nudges, habits, motivation, and accountability.
AI Layer
Predictive Engines
Personalized dosage, progress tracking, dropout prevention.
GLP-1's Role in Medical Obesity Treatment Vs Lifestyle-Only Solutions
Aspect
Lifestyle-Only Programs
GLP-1-Integrated Programs
Mechanism
Behavior change: diet, exercise, CBT
Pharmacological: appetite suppression, glucose control
Weight Loss (% body weight)
3-5% (on average)
10-20% (with semaglutide, tirzepatide)
Time to Results
Slow (months)
Rapid (within weeks)
Target Users
Overweight/motivated
Clinically obese/metabolically compromised
Sustainability
High dropout, rebound risk
Higher if paired with behavioral tools
Patient Acquisition Costs and Outcomes For GLP-1-Integrated Vs Non-GLP-1 Programs
Metric
App-Based Program
GLP-1-Integrated Program
Cost Per Acquisition
USD 50-150 (mostly digital ads)
USD 300-800 (due to physician involvement, screening, compliance risk)
Conversion Rate
5-10% (downloads to paying)
15-30% (qualified leads to onboarded patients)
Customer Attrition Risk
High (monthly subscriptions, low retention)
Medium (longer onboarding, but more clinical stickiness)
The obesity care market is transitioning to more effective solutions that include GLP-1 medications, which, when combined with digital tools, yield better weight loss outcomes. Despite higher patient acquisition costs, these programs demonstrate better retention and clinical results, marking a new standard in obesity treatment.
Market Dynamics
The digital health for obesity market is growing rapidly due to the increasing adoption of GLP-1 weight loss therapies and integrated digital care programs that support long-term weight management. Digital platforms help patients improve medication adherence, monitor progress, and receive personalized coaching and behavioral support. However, concerns about data privacy, cybersecurity, and long-term user engagement continue to hinder market growth. Furthermore, the integration of artificial intelligence and advanced analytics is creating new opportunities by enabling personalized interventions and real-time health insights. These factors are expected to accelerate the adoption of digital obesity management solutions across healthcare systems globally.
The growing adoption of GLP-1 receptor agonists for weight management is emerging as a key driver for the digital health for obesity market. The strong clinical efficacy demonstrated by GLP-1 therapies in promoting significant weight loss has increased awareness of obesity as a chronic disease requiring long-term management. As more patients adopt these therapies, the demand for digital health solutions that support medication adherence, lifestyle modification, nutrition tracking, and continuous monitoring is increasing. Digital platforms help patients manage their treatment journey more effectively while enabling healthcare providers to deliver personalized care remotely.
Furthermore, the integration of digital care programs with GLP-1 therapies is creating a more comprehensive approach to obesity management. These platforms provide personalized coaching, behavioral support, progress tracking, and real-time health insights, helping improve patient engagement and long-term outcomes. For instance, Noom Med combines prescription GLP-1 weight-loss medications with AI-powered coaching, nutrition guidance, and digital tracking tools, enabling users to achieve sustainable weight management through a holistic, personalized care model.
Data privacy and security is a key challenges in the digital health for the obesity market, as these platforms handle large volumes of sensitive health information. Obesity management applications, wearable devices, telehealth platforms, and remote monitoring solutions collect data on body weight, dietary habits, physical activity, medical history, and behavioral patterns. Compliance with evolving regulations such as HIPAA, GDPR, and other regional privacy laws requires significant investment in cybersecurity and data governance.
In addition, maintaining long-term patient engagement remains a major challenge for digital health providers. While many users initially adopt weight management apps, maintaining long-term patient engagement is another significant challenge for digital health providers. Although many users enthusiastically begin using weight management applications and wearable devices, sustaining participation over time is difficult. Declining motivation limited behavioral change, lack of personalized support, and user fatigue often reduce platform usage and lead to program discontinuation.
Integrating artificial intelligence and advanced analytics into digital obesity management platforms offers significant market growth potential. Unlike traditional programs that use generalized recommendations, AI-powered solutions analyze individual health data, lifestyle habits, dietary preferences, activity levels, and behavioral patterns to deliver personalized interventions. These technologies support more effective weight management through customized nutrition plans, real-time health insights, predictive risk assessments, and adaptive coaching that adjusts to user progress. As healthcare providers prioritize precision medicine and personalized care, demand for intelligent obesity management solutions is expected to rise. According to a survey by the American Medical Association, approximately 66% of physicians reported using AI in some capacity in 2024, up from 38% in 2023, reflecting the increasing acceptance and impact of AI-driven healthcare solutions.
Moreover, AI-driven platforms can enhance patient engagement and long-term adherence by enabling continuous health monitoring. Advanced algorithms analyze user data to identify weight-related risk patterns and recommend timely interventions, helping improve health outcomes and support sustainable weight management. For instance, Noom leverages AI and behavioral psychology to deliver personalized weight-management programs, while HealthifyMe uses its AI-powered nutrition assistant to provide customized diet and fitness recommendations tailored to individual users' needs.
Market Concentration & Characteristics
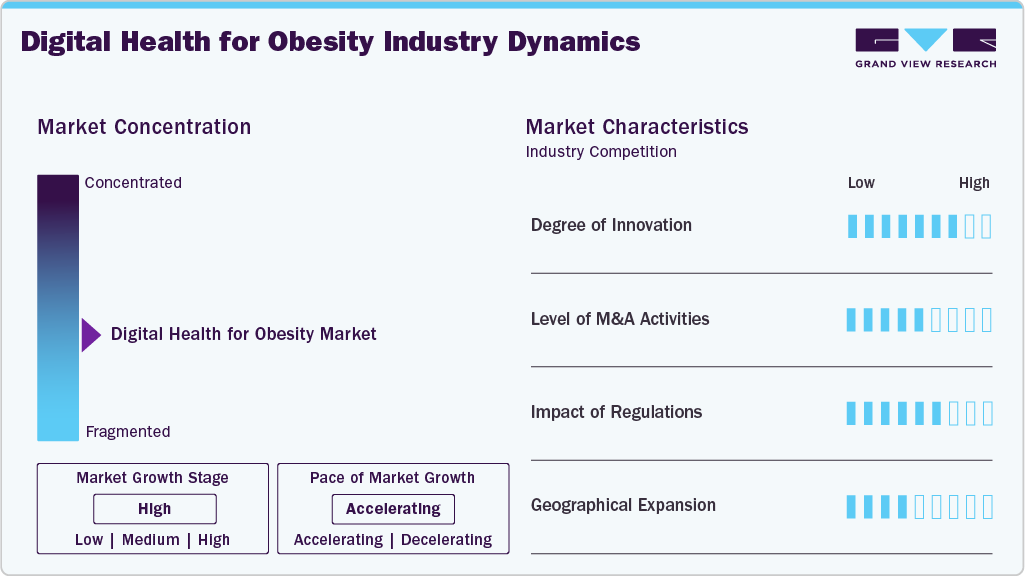
Degree of innovation in the digital health for obesity market is high. With various tools such as wearables, apps, telemedicine, and precision health, people can now choose personalized, data-driven approaches to healthy lifestyles. And with technological advancements, there is still more potential for transformative solutions in the fight against obesity. For instance, smart wearables such as fitness trackers and smartwatches equipped with advanced sensors and algorithms have revolutionized how individuals monitor their physical activity and health. These devices provide real-time data on steps taken, calories burned, and even sleep patterns. This information helps users and healthcare professionals track progress and tailor interventions for weight management.
The level of merger and acquisition (M&A) activities in the digital health for obesity market has been notable, reflecting a dynamic landscape with a focus on enhancing technological capabilities and expanding service portfolios. Recent M&A activities have seen established players acquiring startups with advanced AI algorithms for personalized weight management, aiming to strengthen their digital health offerings. For instance, in March 2023, WW International, Inc. finalized a definitive agreement to purchase Weekend Health, Inc., operating under the name Sequence. Sequence is a subscription-based telehealth platform that grants users access to healthcare professionals specializing in chronic weight management.
 To learn more about this report, Download Free Sample Report
The impact of regulations in the digital health for obesity market is moderate. Stringent FDA approval processes shape the entry of technologies, emphasizing safety and efficacy. Data privacy regulations, notably HIPAA, demand robust protection measures, while reimbursement policies influence adoption. Interoperability standards, ethical considerations, and global regulatory variations further shape the landscape, collectively affecting the development, acceptance, and market viability of digital health solutions tailored for obesity management. The ongoing collaboration between regulatory bodies, industry stakeholders, and healthcare professionals is crucial for fostering innovation while maintaining high safety and efficacy standards.
Several market players are adopting geographical expansion strategies to strengthen their positions in the market. This involves entering new regions or countries to tap into untapped markets and broaden their global footprint. For instance, in September 2023, Novo Nordisk, a Danish pharmaceutical company, launched Wegovy, a weight-loss medication, in the UK as part of its strategic expansion plan into new markets. However, the company is facing supply shortages due to high demand, and it expects these shortages to persist for several years.
Analyst Perspective
The increasing prevalence of obesity, growing adoption of connected health technologies, and heightened focus on preventive healthcare are driving demand for scalable and cost-effective obesity management solutions, including mobile health applications, wearable devices, telehealth platforms, and digital therapeutics. This shift is transforming obesity care from episodic treatment approaches toward continuous, data-driven patient engagement. In addition, advancements in artificial intelligence, behavioral coaching, and remote patient monitoring are enabling more personalized and effective weight management programs, while expanding reimbursement support and increasing awareness of obesity-related health risks are expected to foster continued innovation, investment, and market growth opportunities for both established and emerging digital health providers.
Component Insights
Based on component, the services segment led the market with the largest revenue share of 38.0% in 2025. This growth can be attributed to the growing demand for installation, maintenance, training, and other services. Furthermore, the growing demand for advanced software solutions and platforms such as Electronic Medical Records (EMRs) & Electronic Health Records (EHRs) and the increasing need for upgradation and training required to run these software solutions contribute to the growth of the services segment. Key players provide a wide array of pre- & post-installation services, project planning, training, implementation, and resource allocation & optimization.The software segment is expected to register the fastest CAGR over the forecast period, owing to the rapid adoption of software systems amongst patients, providers, insurance payers, and healthcare facilities. Increasing healthcare expenditures and the rising trend of healthcare digitalization are contributing to the growth of the software segment.
End-use Insights
Based on end use, the patients segment led the market with the largest revenue share of 34.8% in 2025. The growth is attributed to the rising shift towards patient-centered care and the growing demand for individuals to manage their personal health. Furthermore, companies are transforming the healthcare industry by introducing virtual consultations and patient-care devices to regain movement or monitor & track several health parameters.
 To learn more about this report, Download Free Sample Report
The provider segment accounted for a significant market share in the end-use segment, driven by the increased adoption of innovative technologies such as digital therapeutics and telemedicine. Healthcare providers are widely & readily utilizing digital solutions to offer personalized treatment plans, remote consultations, and evidence-based therapies beyond traditional care. Integrating digital tools enables providers to provide more personalized and accessible care, contributing to improved patient outcomes.
Regional Insights
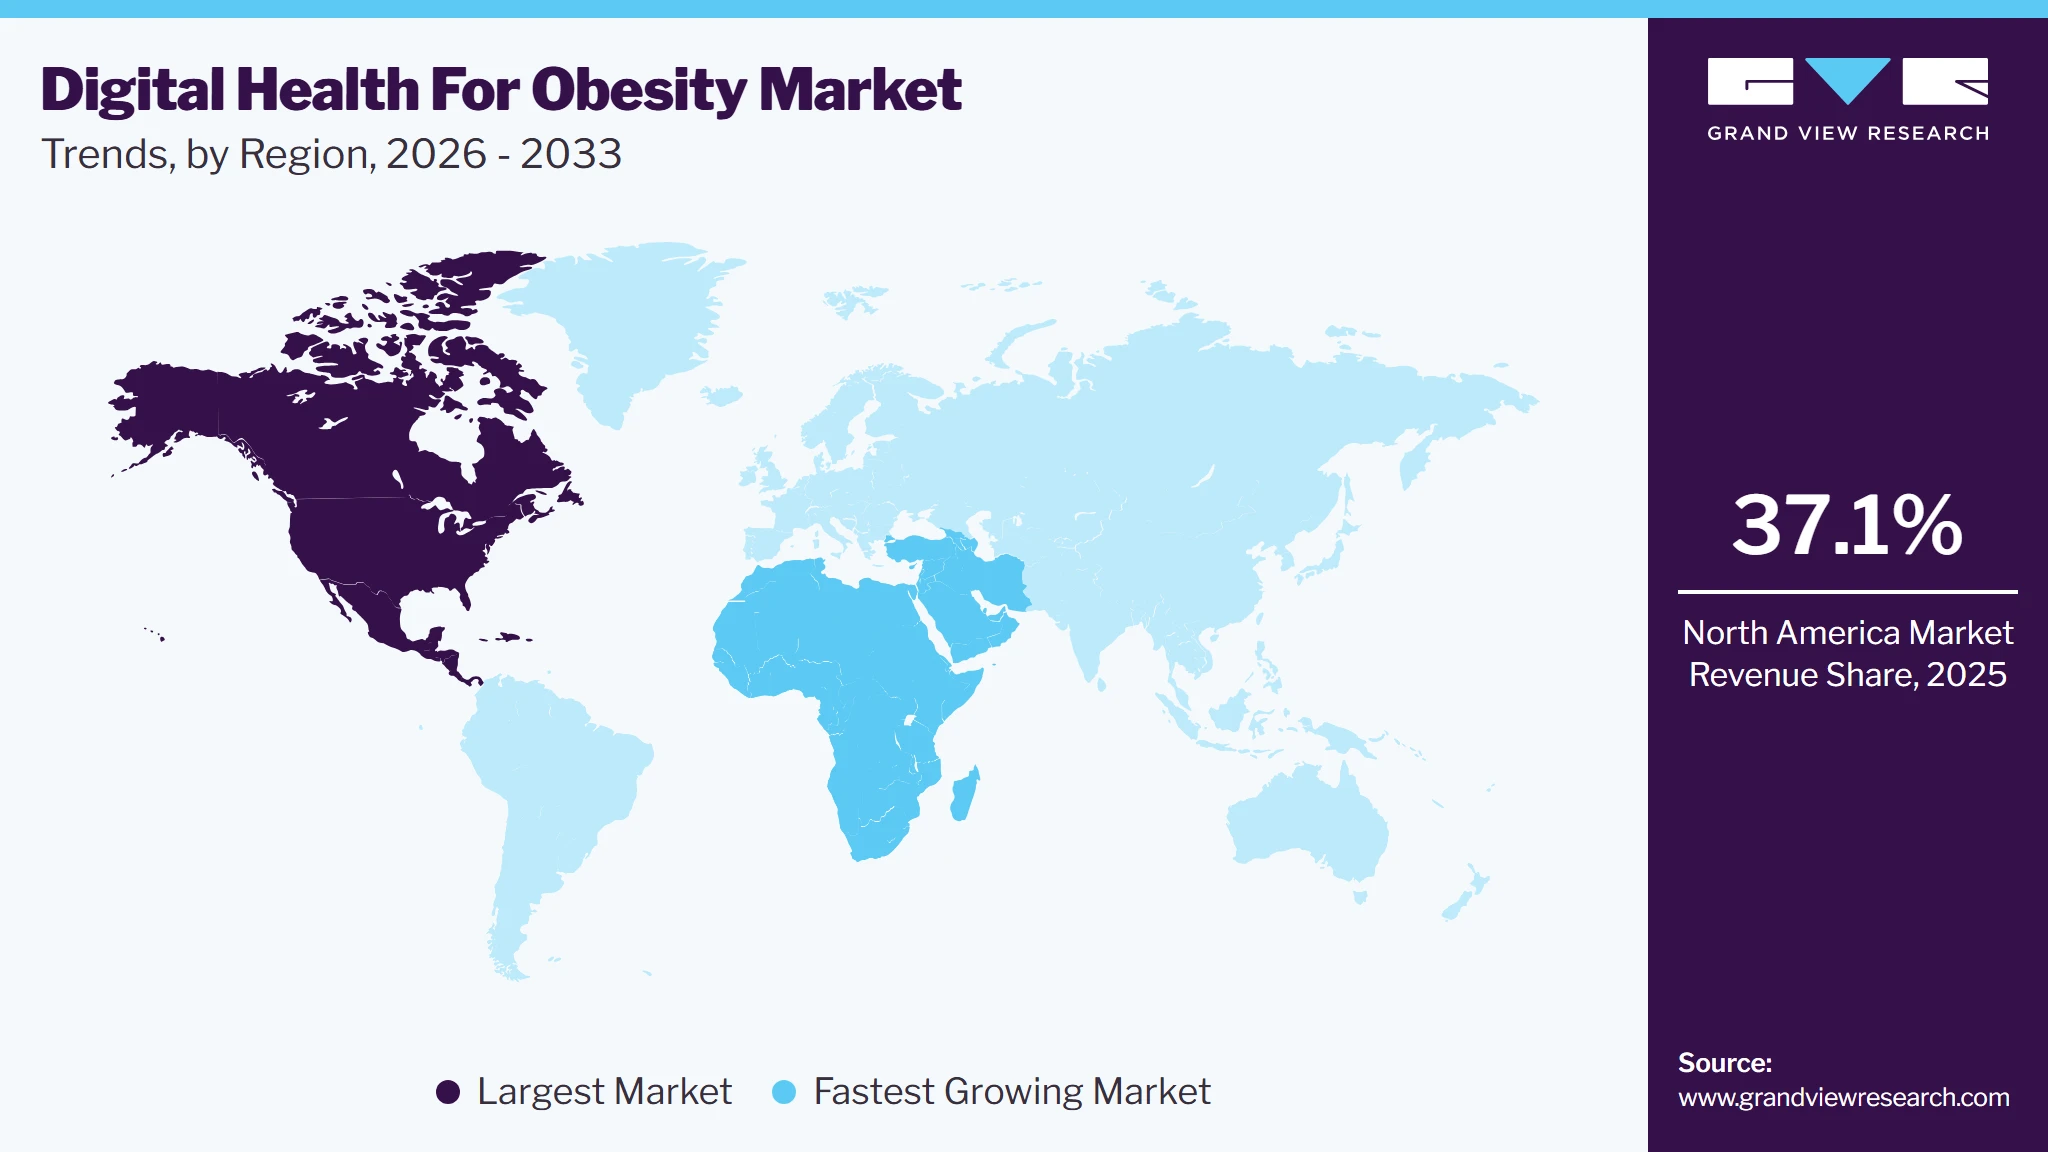
North America dominated the digital health for obesity market with the largest revenue share of 37.1% in 2025, owing to growing healthcare IT expenditure, availability of adequate digital infrastructure, technological advancements, the emergence of startups, favorable government initiatives, growing smartphone penetration, readiness in adopting advanced technological solutions, constant improvements in internet connectivity, and rise in funding & investments. In addition, factors such as advancements in coverage networks, growing penetration of smartphones, increasing lifestyle disorders, and a significant surge in the prevalence of chronic diseases are responsible for the industry’s growth.
 To learn more about this report, Download Free Sample Report
U.S. Digital Health for Obesity Market Trends
The digital health for obesity market in the U.S. held the largest share in the North America region in 2025. The U.S. digital health for obesity market is witnessing dynamic growth, driven by innovative technologies such as smart wearables, mobile applications, and telemedicine. Regulatory support, increasing awareness of health and wellness, and the demand for personalized interventions contribute to the market's expansion, making it a focal point for digital health companies aiming to address the pressing issue of obesity in the U.S.
For instance, in January 2024, Eli Lilly and Company introduced LillyDirect, a novel digital healthcare platform catering to U.S. patients with issues such as obesity, migraine, and diabetes. The platform provides comprehensive disease management resources, personalized assistance, and facilitates the convenient home delivery of specific Lilly medications through third-party pharmacy dispensing services, enhancing overall patient experience.
Europe Digital Health for Obesity Market Trends
The European digital health for obesity market is experiencing a transformative surge, propelled by cutting-edge technologies and innovative solutions. With a growing emphasis on personalized healthcare, mobile applications, wearables, and telemedicine platforms are gaining traction in aiding obesity management. Regulatory frameworks and increasing awareness of the importance of health and well-being contribute to the expansion of digital health initiatives across Europe. As the region embraces advancements in technology, the digital health sector for obesity is poised for sustained growth, providing personalized interventions and encouraging a shift in the approach to proactive health management.
The UK digital health for obesity market is expected to witness significant growth in the European market, owing to a rising adoption of innovative technologies to address the challenges of weight management. Mobile applications, wearable devices, and telehealth solutions are gaining prominence as tools for monitoring, personalized coaching, and remote consultations. The National Health Service's (NHS) digital initiatives and evolving regulatory support contribute to the expansion of digital health interventions tailored for obesity within the UK. The integration of technology into obesity management reflects a shift towards more proactive and patient-centric healthcare approaches in the country.
Asia Pacific Digital Health for Obesity Market Trends
Asia Pacific digital health for obesity market is estimated to witness the significant CAGR during the forecast period, fueled by factors like rising obesity rates, growing smartphone usage, and government-backed initiatives. An example of such an initiative is India's "Ayushman Bharat Digital Mission", which aims to leverage digital technologies to improve healthcare access and affordability. This mission promotes the development of telemedicine platforms and mobile apps for various health concerns, including weight management. These platforms offer personalized coaching, calorie tracking tools, and remote consultations with nutritionists, making weight management support more accessible and convenient for individuals across the vast and diverse regions.
China digital health for obesity market is rapidly expanding, driven by rising obesity rates, a tech-oriented population, and proactive government initiatives. The "Healthy China 2030" plan exemplifies this, prioritizing the development of digital health solutions for various health concerns, including obesity. This has spurred growth in mobile apps and online platforms specifically designed to offer personalized meal plans, workout routines, and professional consultations, empowering individuals to manage their weight and combat obesity-related health risks.
Latin America Digital Health for Obesity Market Trends
The Latin America digital health for obesity market is experiencing significant growth, driven by increasing awareness of health and wellness. Advancements in technology, such as augmented reality (AR) and voice assistants, are enhancing the user experience. For instance, in April 2024, Tech Roundup introduced Accessercise, a fitness app in Brazil, catering to the diverse needs of users.
Brazil digital health for obesity market is driven by rising strategic initiatives and investment in the country. For instance, in April 2025, Novo Nordisk announced the expansion of its production capacity in Montes Claros, Brazil. The expansion includes new aseptic production processes, a warehouse, and a new quality control laboratory. The facility will cater to multiple product formats, including GLP-1 products, and will feature advanced, future-proof technology.
Middle East and Africa Digital Health for Obesity Market Trends
The Middle East & Africa digital health for obesity market is expected to see significant growth in the coming years. The digital solutions are transforming healthcare in this region, driven by the growing internet connectivity and government initiatives. Telemedicine, digital health apps, wearable integration devices, and AI are the major trends revolutionizing healthcare accessibility, costs, & outcomes in the region. For instance, the UAE aims to leverage advanced technologies, such as AI and big data analytics, to improve healthcare outcomes & patient experiences.
The digital health for obesity market in Saudi Arabia is undergoing substantial growth. The adoption of digital technologies in Saudi Arabia is in its nascent stage. Increasing smartphone penetration and improving internet connectivity are some of the major drivers boosting the adoption rate. According to Ubuy estimates, approximately 92% of the Saudi population either has access to or owns a smartphone. The number of smartphone users has significantly increased from 14.31 million individuals in 2013 to 33.55 million individuals in 2024.
Key Digital Health for Obesity Company Insights
The digital health market for obesity management is competitive, with established players such as WW International and Noom battling for market share. Emerging companies such as Macrobiotics and Second Nature are entering the market, offering unique features like personalized coaching and macro-nutrient tracking. Companies target specific user segments, partnerships, and data-driven personalization while navigating market fragmentation, regulations, and user engagement challenges. Innovation, user engagement, and navigating the evolving landscape will be key to success in this market.
Key Digital Health for Obesity Companies
The following key companies have been profiled for this study on the digital health for obesity market.
-
WW International
-
MyFitnessPal
-
Teladoc Health, Inc.
-
Fitnesskeeper Inc.
-
Healthify (My Diet Coach)
-
Fitbit, Inc.
-
Noom
-
PlateJoy HEALTH
-
Tempus
-
WellDoc
-
Sidekick Health
-
BioAge Labs
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Fitbit, Inc., Noom, WellDoc)
- Expand integrated digital obesity management ecosystems through mobile applications, wearables and telehealth services.
- Strengthen partnerships with healthcare providers, employers, insurers, and pharmaceutical companies to increase user adoption and reimbursement opportunities.
- Strong brand recognition, large active user bases, and extensive health data repositories that support personalized weight management interventions.
- Well-established digital platforms with advanced analytics, behavioral coaching capabilities, and broad geographic market presence.
- High customer acquisition and retention costs due to intense competition from emerging digital health and wellness platforms.
- Dependence on long-term user engagement and subscription renewals, with effectiveness often impacted by declining user adherence over time.
Emerging Players (e.g., PlateJoy Health)
- Focus on AI-driven personalization, digital therapeutics, and precision health solutions to address obesity and related metabolic conditions.
- Invest heavily in technology innovation, clinical validation, and strategic partnerships with healthcare providers and research organizations to expand market presence.
- Strong capabilities in advanced analytics, machine learning, and personalized treatment approaches that differentiate their offerings from traditional weight management platforms.
- Agile business models that enable rapid product development and adoption of emerging technologies tailored to obesity care and chronic disease management.
- Limited brand recognition and smaller customer bases compared to established digital health and obesity management providers.
- Greater dependence on external funding, regulatory approvals, and partnership networks to scale operations and achieve broader market penetration.
Recent Developments
-
In December 2023, Hims & Hers, a digital health company, has recently introduced its weight loss program, featuring digital monitoring tools, informative content, and medication access. Notably, the current offering does not encompass prescriptions for the trendy weight loss medications referred to as GLP-1s.
-
In December 2023, Knownwell, a comprehensive healthcare provider seamlessly integrating virtual and in-person services, has introduced knownwell teens, an early intervention clinical program specifically crafted to assist the 14 million children and adolescents grappling with obesity in the U.S.
-
In July 2023, Alfie Health's launched ObesityRx platform, this platform employs artificial intelligence to generate metabolic profiles of individuals, seeking to comprehend the root causes of weight gain. Through this analysis, the system can propose customized treatment strategies and behavioral modifications. Preliminary findings indicate that a group of 300 patients utilizing this method experienced an average weight loss ranging from 10% to 15% over a nine-month duration.
-
In March 2023, WW International, Inc. finalized an agreement to purchase Weekend Health, Inc., operating under the name Sequence. Sequence is a subscription-based telehealth platform that grants users access to healthcare professionals specializing in chronic weight management. The platform effectively integrates the patient and clinician experience, facilitating continuous clinical care and medication management, with additional support in navigating the insurance approval process.
-
In February 2023, Allurion Technologies, Inc., focused on addressing obesity, and Compute Health Acquisition Corp, a special purpose acquisition company have officially agreed to merge, marking Allurion's transition into a publicly traded entity. Following the completion of the transaction, the unified company, named Allurion Technologies, Inc., is anticipated to list its common stock on the New York Stock Exchange.
-
In December 2023, Roche announced its conclusive merger agreements with Carmot Therapeutics. As per the official statement, Roche is set to acquire Carmot, including its portfolio of clinical-stage obesity drugs, for a sum of USD 2.7 billion, with the potential for an additional USD 400 million in milestone payments.
Digital Health For Obesity Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 70.1 billion
Market size value in 2026
USD 85.5 billion
Revenue forecast in 2033
USD 392.9 billion
Growth rate
CAGR of 24.3% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; China; India; Japan; Australia; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
WW International; MyFitnessPal; Teladoc Health, Inc.; Fitnesskeeper Inc.; Healthify (My Diet Coach); Fitbit, Inc.; Noom; PlateJoy HEALTH; Tempus; WellDoc; Sidekick Health; BioAge Labs
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchasse. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Digital Health For Obesity Market Report Segmentation
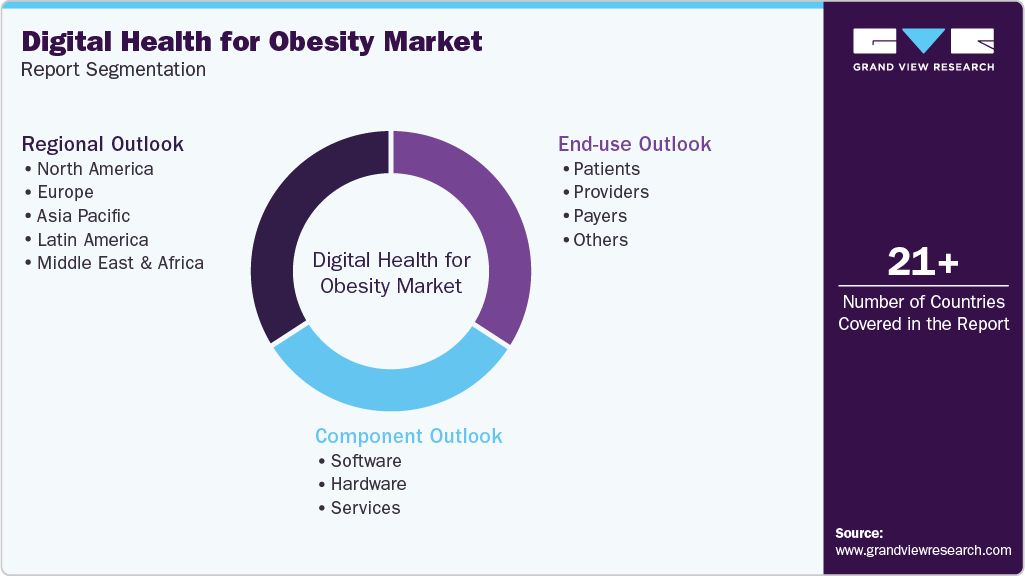
This report forecasts revenue growth at global, regional, and country levels and provides an analysis on industry trends in each of the segments from 2021 to 2033. For this study, Grand View Research, Inc. has segmented the global digital health for obesity market report based on components, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Component Outlook (Revenue in USD Million, 2021 - 2033)
-
Software
-
Hardware
-
Services
-
-
End-use Outlook (Revenue in USD Million, 2021 - 2033)
-
Patients
-
Providers
-
Payers
-
Others
-
-
Regional Outlook (Revenue in USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
Singapore
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The digital health for obesity market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each digital health for obesity segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Hardware
Hardware includes wearable devices, smart scales, fitness trackers, and remote monitoring equipment used to collect and track obesity-related health metrics. These devices enable real-time monitoring of physical activity, weight, body composition, and other health parameters.
Software
Software comprises mobile applications, digital therapeutics platforms, analytics tools, and cloud-based solutions designed for obesity management. These solutions support personalized coaching, nutrition tracking, behavior modification, and health data analysis.
Services
Services include virtual coaching, telehealth consultations, implementation support, training, and maintenance associated with digital obesity management solutions. They help users and healthcare providers maximize the effectiveness of digital health platforms.
Segment - End Use
Revenue capture definition
Patients
This segment includes individuals using digital health solutions to monitor weight, manage lifestyle changes, track nutrition, and achieve obesity-related health goals. Patients utilize these platforms for personalized and continuous obesity management.
Providers
Providers include hospitals, clinics, physicians, dietitians, and wellness professionals that use digital health tools to monitor patients, deliver remote care, and support obesity treatment programs. These solutions enhance patient engagement and clinical decision-making.
Payers
Payers comprise health insurance companies, employers, and government healthcare programs that utilize digital obesity management solutions to improve health outcomes and reduce long-term healthcare costs. They often support reimbursement and wellness initiatives through these platforms.
Other Buyers
Other buyers include research institutions, corporate wellness organizations, fitness centers, and public health agencies that adopt digital health solutions for obesity prevention, population health management, and wellness program delivery. These organizations leverage digital tools to support broader health improvement initiatives.
Estimation Model
Model 1: Parent Market-Based Penetration Analysis
The global digital health for obesity market was estimated using a parent-market penetration methodology, wherein the broader digital health market was analyzed across major regions and countries. The share attributable to obesity-focused digital health solutions was derived through penetration assumptions based on obesity prevalence, utilization of digital weight management platforms, telehealth services, wearable technologies, and digital therapeutics adoption.
Market estimates were further refined by assessing obesity-related healthcare spending, consumer engagement with weight management applications, reimbursement support, healthcare digitization initiatives, and adoption trends for AI-enabled obesity management solutions. Regional and country-level variations in obesity burden, healthcare infrastructure, smartphone penetration, and digital health maturity were incorporated to derive localized estimates. The resulting market figures were validated through primary discussions with digital health providers, obesity specialists, healthcare practitioners, and industry participants.
Model Factors Considered
-
Parent digital health market size
-
Obesity prevalence by country and region
-
Penetration of obesity-focused digital health solutions
-
Adoption of weight management mobile applications
-
Wearable device utilization rates
-
Telehealth adoption for obesity management
-
Digital therapeutics penetration
-
Obesity-related healthcare expenditure
-
Reimbursement coverage and payer support
-
Smartphone and internet penetration
-
AI and analytics adoption in obesity management
-
Primary expert interviews and industry validation
Model 2: Supply-Side Revenue Benchmarking
The market size was also estimated by analyzing revenues generated by leading providers of obesity-focused digital health solutions, including digital therapeutics platforms, weight management applications, telehealth providers, wearable technology companies, and AI-enabled obesity management solution providers. Company revenues were analyzed through annual reports, investor presentations, company disclosures, and industry databases.
Market estimates were developed by assessing product portfolios, regional presence, customer bases, subscription revenues, and obesity-specific solution offerings of key market participants. The aggregated revenue analysis was further validated through primary interviews and industry consultations to derive the overall market size and competitive landscape.
Model Factors Considered
-
Revenue of key market participants
-
Obesity-specific digital health revenues
-
Product portfolio analysis
-
Customer and subscriber base
-
Geographic revenue distribution
-
Pricing and subscription models
-
Strategic partnerships and acquisitions
-
New product launches
-
Funding and investment activities
-
Primary industry interviews
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Obesity Management Platform Adoption Analysis
Quantitative and qualitative assessment of adoption trends across mobile health apps, digital therapeutics, telehealth platforms, and wearable devices used for obesity management, with regional and country-level analysis.
Enables identification of high-growth technology segments, user adoption patterns, and investment opportunities across digital obesity management solutions.
Competitive Intelligence & Vendor Landscape Analysis
Comprehensive evaluation of leading digital health providers, including company-level market share assessment, product benchmarking, partnership analysis, innovation strategies, and competitive positioning.
Provides visibility into market leadership, competitive differentiation, partnership opportunities, and emerging threats from new entrants.
AI and Digital Therapeutics Impact Analysis
Evaluation of the role of artificial intelligence, machine learning, remote patient monitoring, and digital therapeutics in obesity management and patient engagement.
Helps stakeholders understand future technology trends, innovation opportunities, and product development priorities.
Frequently Asked Questions About This Report
The global digital health for obesity market size was estimated at USD 70.1 billion in 2025 and is expected to reach USD 85.5 billion in 2026.
Increasing smartphone penetration, growing lifestyle changes, including sedentary habits and unhealthy dietary choices, increasing prevalence of chronic diseases, rising healthcare expenditure, and increasing accessibility of virtual care are driving the adoption of digital health technologies in addressing obesity.
North America dominated with a 37.1% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The services segment led with a 38.0% revenue share in 2025, while software is the fastest-growing segment.
The global digital health for obesity market is expected to grow at a compound annual growth rate of 24.3% from 2026 to 2033 to reach USD 392.9 billion by 2033.
The patient segment dominated the end use segment with the largest market share of 34.8% in 2025. The growth is attributed to the rising shift towards patient-centered care and the growing demand of individuals in managing their personal health.
Some key players operating in the market include WW International; MyFitnessPal; Teladoc Health, Inc.; Fitnesskeeper Inc.; Healthify (My Diet Coach); Fitbit, Inc.; Noom; PlateJoy HEALTH; Tempus; WellDoc; Sidekick Health; BioAge Labs.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


