
- Home
- »
- Next Generation Technologies
- »
-
Enterprise Collaboration Market Size Report, 2026-2033GVR Report cover

Enterprise Collaboration Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Solution, Services), By Organization Size, By Deployment Mode (On-premises, Cloud-based), By End-use (BFSI, Healthcare, Education), By Region, And Segment Forecasts
Market Size, 2025
$60.6BMarket Estimate, 2026
$67.5BMarket Forecast, 2033
$159.9BCAGR, 2026–2033
13.1%Enterprise Collaboration Market Summary
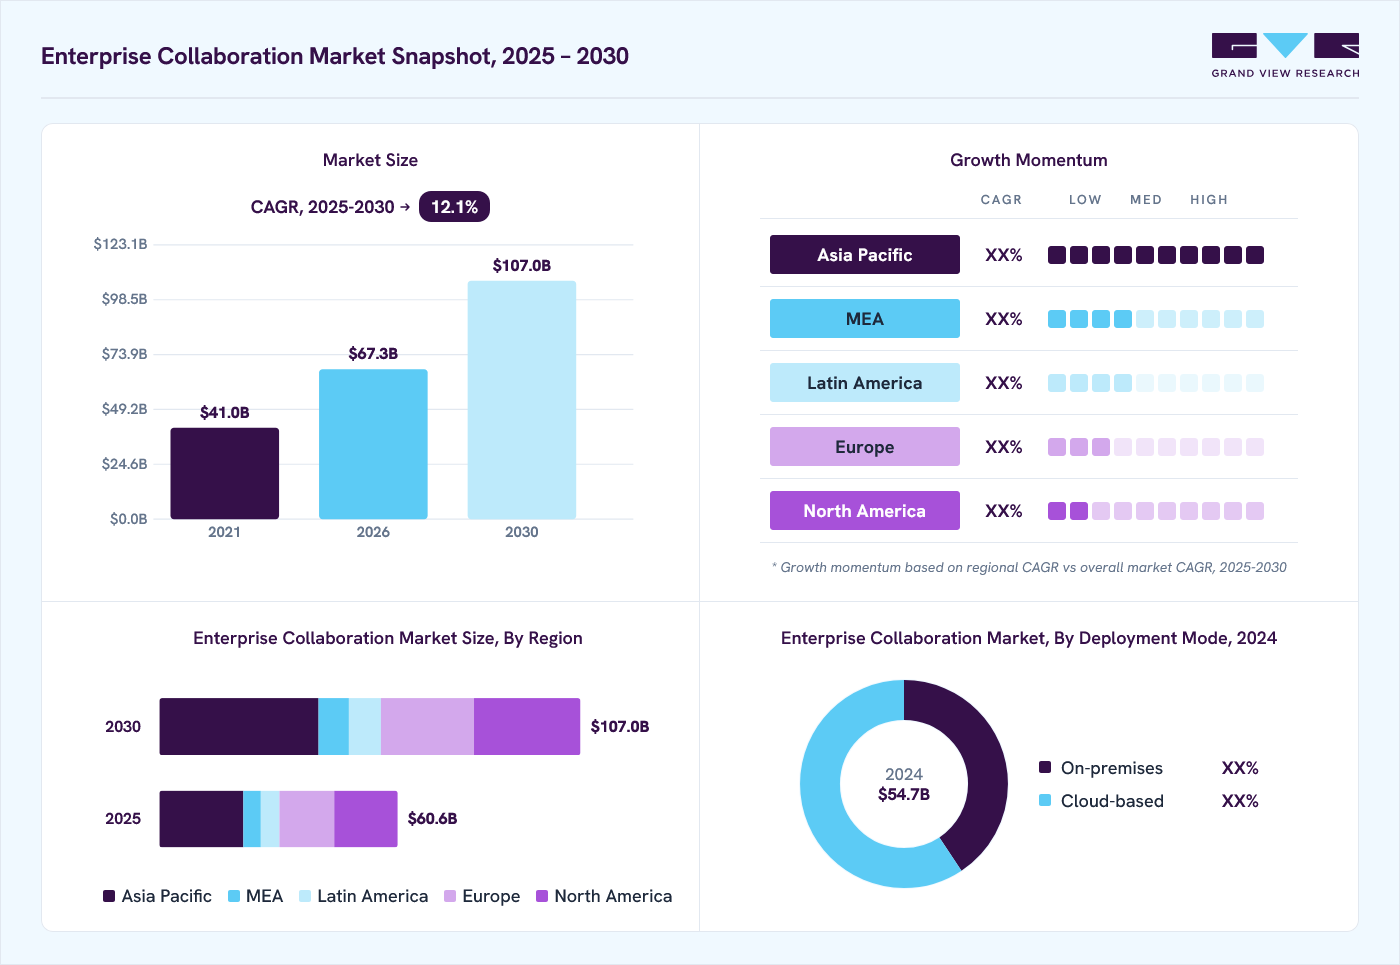
The global enterprise collaboration market size was estimated at USD 60.6 billion in 2025 and is projected to grow from USD 67.5 billion in 2026 to USD 159.9 billion by 2033, growing at a CAGR of 13.1% from 2026 to 2033. Asia Pacific dominated the global market, accounting for the largest revenue share of 33.7% in 2025. The growth of the enterprise collaboration market is primarily driven by the growing adoption of hybrid work models, increasing demand for cloud-based collaboration platforms, and the rising need for seamless communication across distributed teams.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: The solution segment accounted for the largest market share of 65.4% in 2025.
- By organization size: The large enterprises segment led the market with a share of 71.3% in 2025.
- By deployment mode: The cloud-based segment led the market with a share of 55.0% in 2025.
- By end use: The IT & telecom segment led the market with a share of 23.5% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (33.7% revenue share in 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR 14.7%, 2026-2033)
- By Country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 54.7 Billion
- Estimated market size in 2026: USD 60.6 Billion
- Projected market size by 2033: USD 159.9 Billion
- CAGR (2026-2033): 13.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Enterprise collaboration tools enable seamless connectivity across geographically dispersed teams. The shift toward digital transformation initiatives across industries and the emphasis on improving workforce engagement are significantly contributing to the expansion of the enterprise collaboration market. The increasing adoption of remote and hybrid work models is significantly driving the growth of the enterprise collaboration industry. Organizations that adapt to distributed workforces need seamless communication and real-time collaboration tools. Solutions such as video conferencing, instant messaging, shared workspaces, and project management platforms enable teams to remain productive regardless of location. This trend is prompting businesses to invest heavily in collaborative technologies that support flexibility and operational continuity.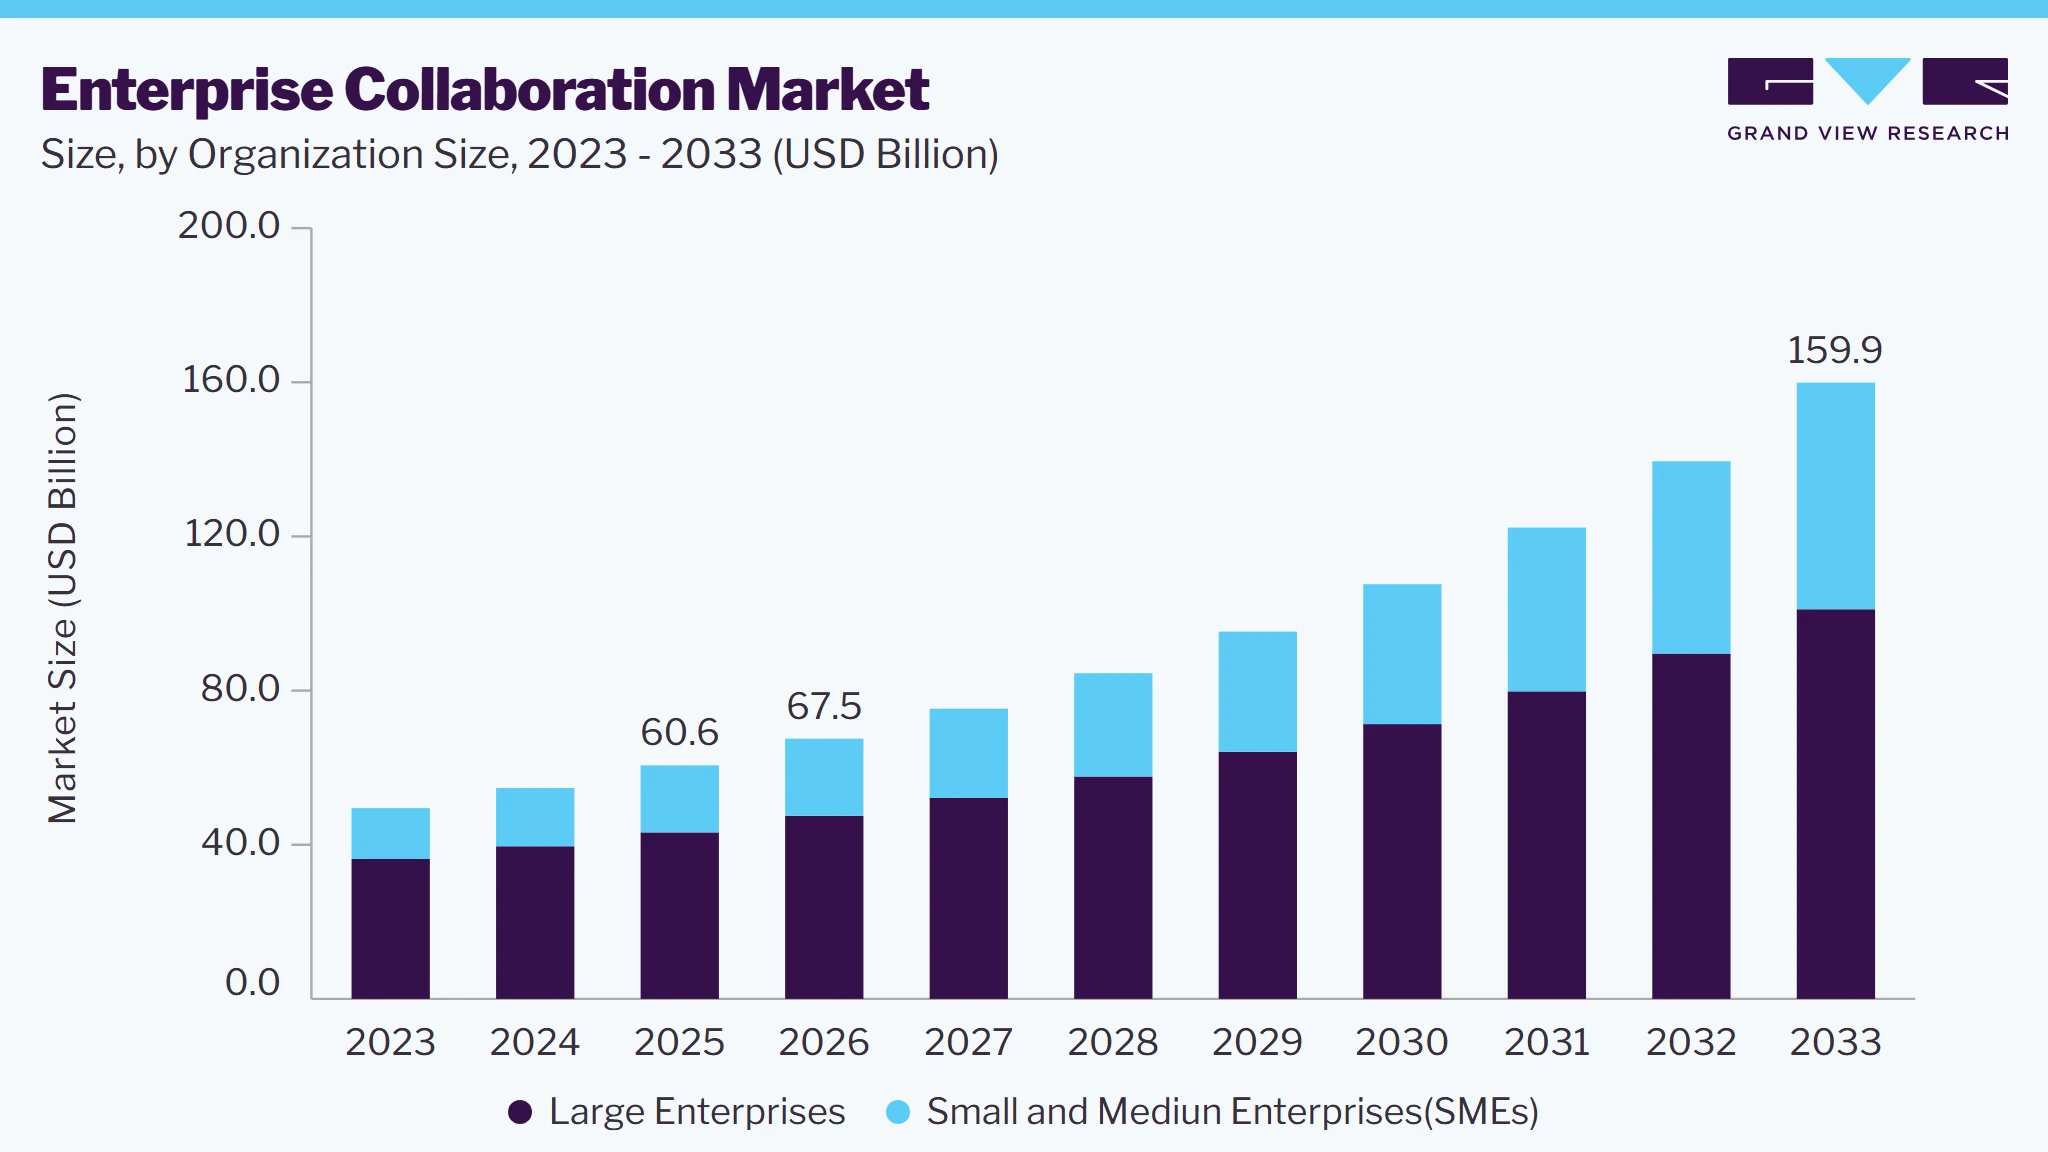 To learn more about this report, Download Free Sample Report
In addition, the growing focus on digital transformation initiatives across industries is fueling the demand for enterprise collaboration solutions. Companies are actively replacing legacy systems with modern, cloud-based platforms to streamline workflows, enhance productivity, and foster innovation. These tools facilitate cross-functional communication and integrate with other enterprise applications, creating unified digital ecosystems that improve efficiency and agility in dynamic business environments.
Furthermore, the rise of artificial intelligence and machine learning is enhancing the capabilities of enterprise collaboration tools. AI-powered features such as smart scheduling, automated meeting transcription, real-time language translation, and predictive analytics are transforming how teams interact and make decisions. These intelligent capabilities reduce manual workload, improve decision-making speed, and increase user engagement, making collaboration platforms more valuable to organizations.
Moreover, the integration of enterprise collaboration tools into mobile apps and browsers is revolutionizing how teams communicate and operate in real-time. Professionals increasingly rely on mobile devices for work-related tasks, and collaboration platforms that offer mobile accessibility are becoming essential. This growing dependence on mobile-enabled collaboration is expected to remain a critical driver of enterprise collaboration industry growth in the coming years.
Market Dynamics
The rising integration of AI-powered productivity tools, workflow automation, cybersecurity solutions, and digital workplace technologies is further accelerating market expansion as enterprises seek scalable, secure, and integrated collaboration ecosystems. Furthermore, increasing adoption of hybrid work environments, growing demand for real-time communication platforms, and the need for improved employee engagement and operational efficiency are driving investments in advanced enterprise collaboration solutions.
The increasing adoption of hybrid and remote work models is a major driver for the enterprise collaboration market, as organizations require seamless communication, virtual meetings, document sharing, and workflow management capabilities across distributed teams. Enterprises are increasingly investing in unified collaboration platforms that enable real-time interaction, improve workforce productivity, and support flexible working environments.
Additionally, the shift toward cloud-based collaboration solutions is accelerating market growth by offering scalability, accessibility, and cost efficiency compared with traditional on-premises systems. The integration of AI-powered assistants, automation, analytics, and enterprise application connectivity is further enhancing collaboration experiences and encouraging organizations across industries to modernize their digital workplace infrastructure.
Data security and privacy concerns remain key challenges limiting the adoption of enterprise collaboration platforms, particularly as organizations manage sensitive business information, customer data, and internal communications through cloud-based environments. Increasing cybersecurity threats, compliance requirements, and regulatory complexities require enterprises to implement robust security measures, which can increase deployment costs and operational complexity.
Furthermore, integration challenges with legacy systems, fragmented technology environments, and compatibility issues across collaboration tools can affect user adoption and overall platform efficiency. Organizations may face difficulties in achieving seamless interoperability between collaboration solutions and existing enterprise applications, creating barriers for widespread implementation.
The growing adoption of artificial intelligence and automation presents significant opportunities for enterprise collaboration vendors to develop intelligent workplace solutions. AI-powered features such as automated meeting summaries, virtual assistants, predictive analytics, workflow automation, and knowledge management capabilities are transforming collaboration platforms by improving productivity and decision-making.
Moreover, increasing demand for personalized, integrated, and industry-specific collaboration solutions creates opportunities for vendors to expand their offerings across sectors such as healthcare, BFSI, education, manufacturing, and professional services. The continued evolution of digital workplaces and investments in smart enterprise technologies are expected to create new growth avenues for collaboration platform providers.
Market Concentration & Characteristics
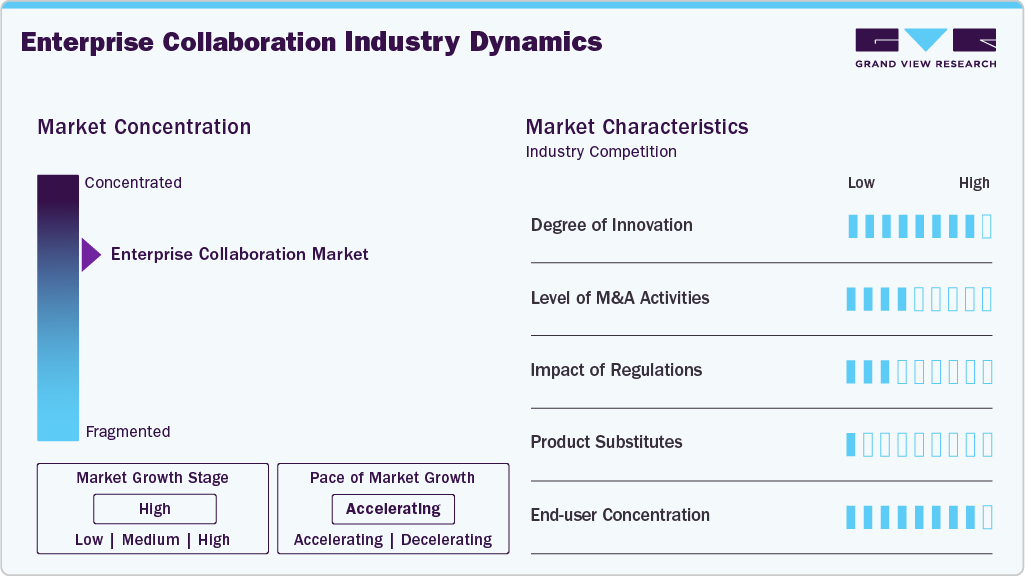
The enterprise collaboration market is moderately concentrated, comprising global technology providers, cloud service companies, unified communications and collaboration (UC&C) vendors, productivity software providers, customer experience platforms, and specialized digital workplace solution providers. The market is driven by continuous advancements in artificial intelligence (AI)-powered collaboration assistants, cloud computing, workflow automation, real-time communication technologies, enterprise application integrations, cybersecurity solutions, and digital workplace platforms. Mergers, acquisitions, and strategic partnerships remain at moderate to high levels, with companies expanding their capabilities through investments in AI technologies, cloud infrastructure, cybersecurity platforms, productivity tools, employee experience solutions, and industry-specific collaboration applications.
 To learn more about this report, Download Free Sample Report
Regulatory influence is moderate and shaped by data privacy regulations, cybersecurity standards, compliance requirements, cross-border data management policies, and enterprise communication governance frameworks. Product substitution is low to moderate, as integrated collaboration platforms provide comprehensive capabilities for communication, content sharing, project management, and workflow coordination that standalone tools cannot fully replicate. Market demand is diversified across IT & telecommunications, BFSI, healthcare, education, government, manufacturing, retail, media & entertainment, and professional services, supported by increasing adoption of hybrid work models, enterprise digital transformation initiatives, AI-driven productivity solutions, and growing investments in secure, scalable, and interconnected digital workplace ecosystems.
Analyst Perspective
The enterprise collaboration market is shifting toward AI-driven, cloud-enabled, and integrated digital workplace ecosystems that enhance productivity, connectivity, and employee engagement across hybrid and distributed work environments. Organizations are increasingly prioritizing collaboration platforms that combine real-time communication, workflow automation, knowledge management, cybersecurity, and business application integration into unified experiences. Overall, the enterprise collaboration market is expected to witness sustained growth as enterprises accelerate digital transformation initiatives and seek intelligent, flexible, and secure collaboration solutions to support evolving workplace models and improve organizational efficiency.
Type Insights
Based on type, the solution segment dominated the market with the largest revenue share of 65.4% in 2025, driven by the growing demand for integrated communication platforms that streamline workflows, enhance productivity, and support hybrid work environments. Enterprises are prioritizing platforms that support real-time collaboration and remote team coordination, leading to a surge in demand for comprehensive software solutions. This trend is further reinforced by the rising reliance on cloud infrastructure and AI-powered tools, solidifying the dominance of the solution segment in the market.
The services segment is expected to witness the highest CAGR of over 14% from 2025 to 2030. This growth is attributed to the increasing reliance of organizations on managed services, consulting, and support. Enterprises accelerate their digital transformation journeys, the demand for services that ensure seamless deployment, customization, and maintenance of collaboration platforms is growing. The integration of AI, automation, and cloud technologies into collaboration ecosystems is driving organizations to seek expert services to effectively implement and manage these innovations, thereby contributing to the robust growth of the services segment.
Organization Size Insights
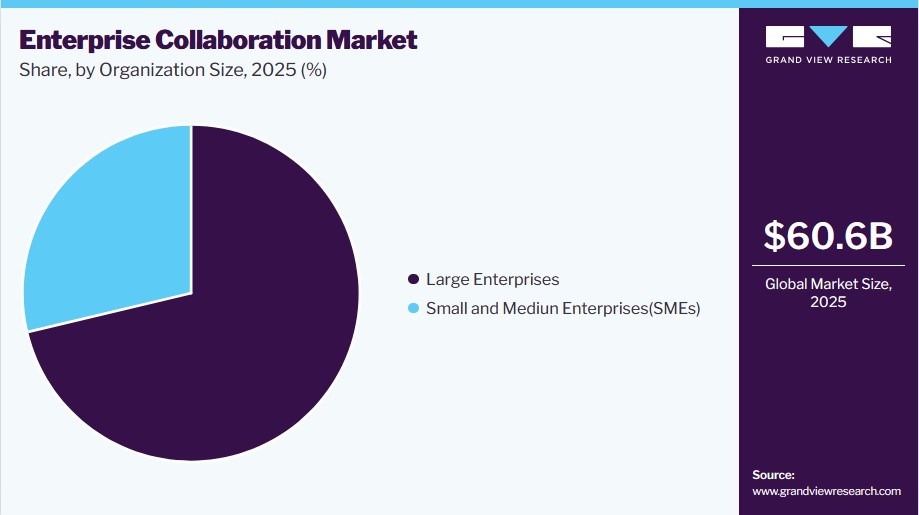
Based on organization size, the large enterprises segment led the market with the largest revenue share of 71.3% in 2025, owing to the substantial investments these organizations make in advanced collaboration tools, unified communication platforms, and digital transformation initiatives. Large enterprises often operate across multiple geographies and require robust, secure, and scalable collaboration solutions to manage distributed teams, complex workflows, and interdepartmental communication. These factors contribute to the dominance of the large enterprises segment in the enterprise collaboration industry.
 To learn more about this report, Download Free Sample Report
The small & medium enterprise segment is expected to witness the highest CAGR from 2025 to 2030, driven by the increasing need for cost-effective, scalable, and user-friendly collaboration tools. SMEs are rapidly adopting cloud-based enterprise collaboration platforms to enhance productivity, streamline communication, and support remote work environments. This growing reliance on digital tools to remain competitive and connect globally is a key factor propelling the rapid growth of the SME segment in the enterprise collaboration market.
Deployment Mode Insights
Based on deployment mode, the cloud-based segment led the market with the largest revenue share of 55.0% in 2025, as organizations increasingly prioritize flexibility, scalability, and remote accessibility in their collaboration tools. The integration of advanced technologies such as AI, machine learning, and analytics into cloud-based tools enhances decision-making and workflow automation. These drivers, coupled with the increasing demand for cross-functional collaboration and secure data access, propel the rapid adoption of cloud-based solutions in the enterprise collaboration industry.
The on-premises segment is expected to witness a significant CAGR from 2025 to 2030, owing to growing concerns over data security, regulatory compliance, and the need for greater control over collaboration environments. On-premises deployment allows organizations to maintain full ownership of their infrastructure, enabling tighter integration with internal IT systems and adherence to stringent data protection laws. These factors are collectively driving the growth of this deployment mode in the enterprise collaboration market.
End-use Insights
Based on end use, the IT & Telecom segment led the market with the largest revenue share of 23.5% in 2025, driven by the accelerating digital transformation initiatives and the increasing demand for seamless communication tools. Global telecom operators and IT service providers embrace hybrid and remote work models, there is a heightened need for integrated collaboration platforms that support real-time communication and file sharing. The growing reliance on cloud-based solutions reinforces the sector's leadership in adopting enterprise collaboration technologies across the global market.
The healthcare segment is expected to witness the highest CAGR from 2025 to 2030, driven by the industry's growing focus on digital transformation and patient-centric care. Healthcare providers are adopting enterprise collaboration industry to enhance communication. The increasing use of remote diagnostics, and virtual health consultations is further propelling the market. Technological advancements, combined with stringent regulatory compliance requirements, are pushing healthcare organizations to invest in robust collaboration solutions, thereby emerging as the fastest-growing segment in the enterprise collaboration industry.
Regional Insights
North America dominated the enterprise collaboration market, accounting for the largest revenue share of 27.4% in 2025, primarily driven by the region’s widespread adoption of hybrid work models and the increasing digital transformation initiatives across industries. In the U.S., enterprises are rapidly investing in cloud-based collaboration platforms to enhance remote team productivity and streamline communication workflows. The presence of major technology vendors and a robust IT infrastructure in North America continues to accelerate enterprise collaboration industry advancements across the region.
U.S. Enterprise Collaboration Market Trends
The enterprise collaboration market in the U.S. held the largest share in the North America region in 2025, driven by the state's position as a global hub for technology and innovation. The high concentration of tech companies in Silicon Valley, coupled with a strong startup ecosystem, fuels the demand for advanced collaboration tools that support remote and hybrid work environments. Digital infrastructure and investment in smart workplace solutions by both public and private sector organizations are accelerating the adoption of the enterprise collaboration industry.
Europe Enterprise Collaboration Market Trends
The Europe enterprise collaboration market is expected to grow at a CAGR of over 11% from 2025 to 2030, driven by the region’s robust industrial landscape and increasing digital maturity. A major driver across the region is the intensifying focus on sustainability and compliance with strict environmental regulations. These regulations, along with EU-wide climate policies, are compelling organizations to adopt collaborative tools that facilitate real-time communication and monitoring of environmental performance.
The UK enterprise collaboration market is expected to grow due to the country's progressive remote and hybrid work culture. The UK's emphasis on workplace flexibility has led to increased demand for cloud-based collaboration platforms, video conferencing tools, and integrated communication solutions. The push toward digital government services and public sector modernization also fuels enterprise collaboration adoption, as agencies seek efficient interdepartmental communication and workflow automation.
The Germany enterprise collaboration market is fueled by the country's growing trend toward remote and hybrid work models, particularly among its highly skilled workforce in sectors like IT, finance, and consulting. Germany’s strict data protection laws, such as the GDPR, compel enterprises to invest in compliant and secure collaboration platforms, further boosting demand for localized enterprise collaboration industry.
Asia Pacific Enterprise Collaboration Market Trends
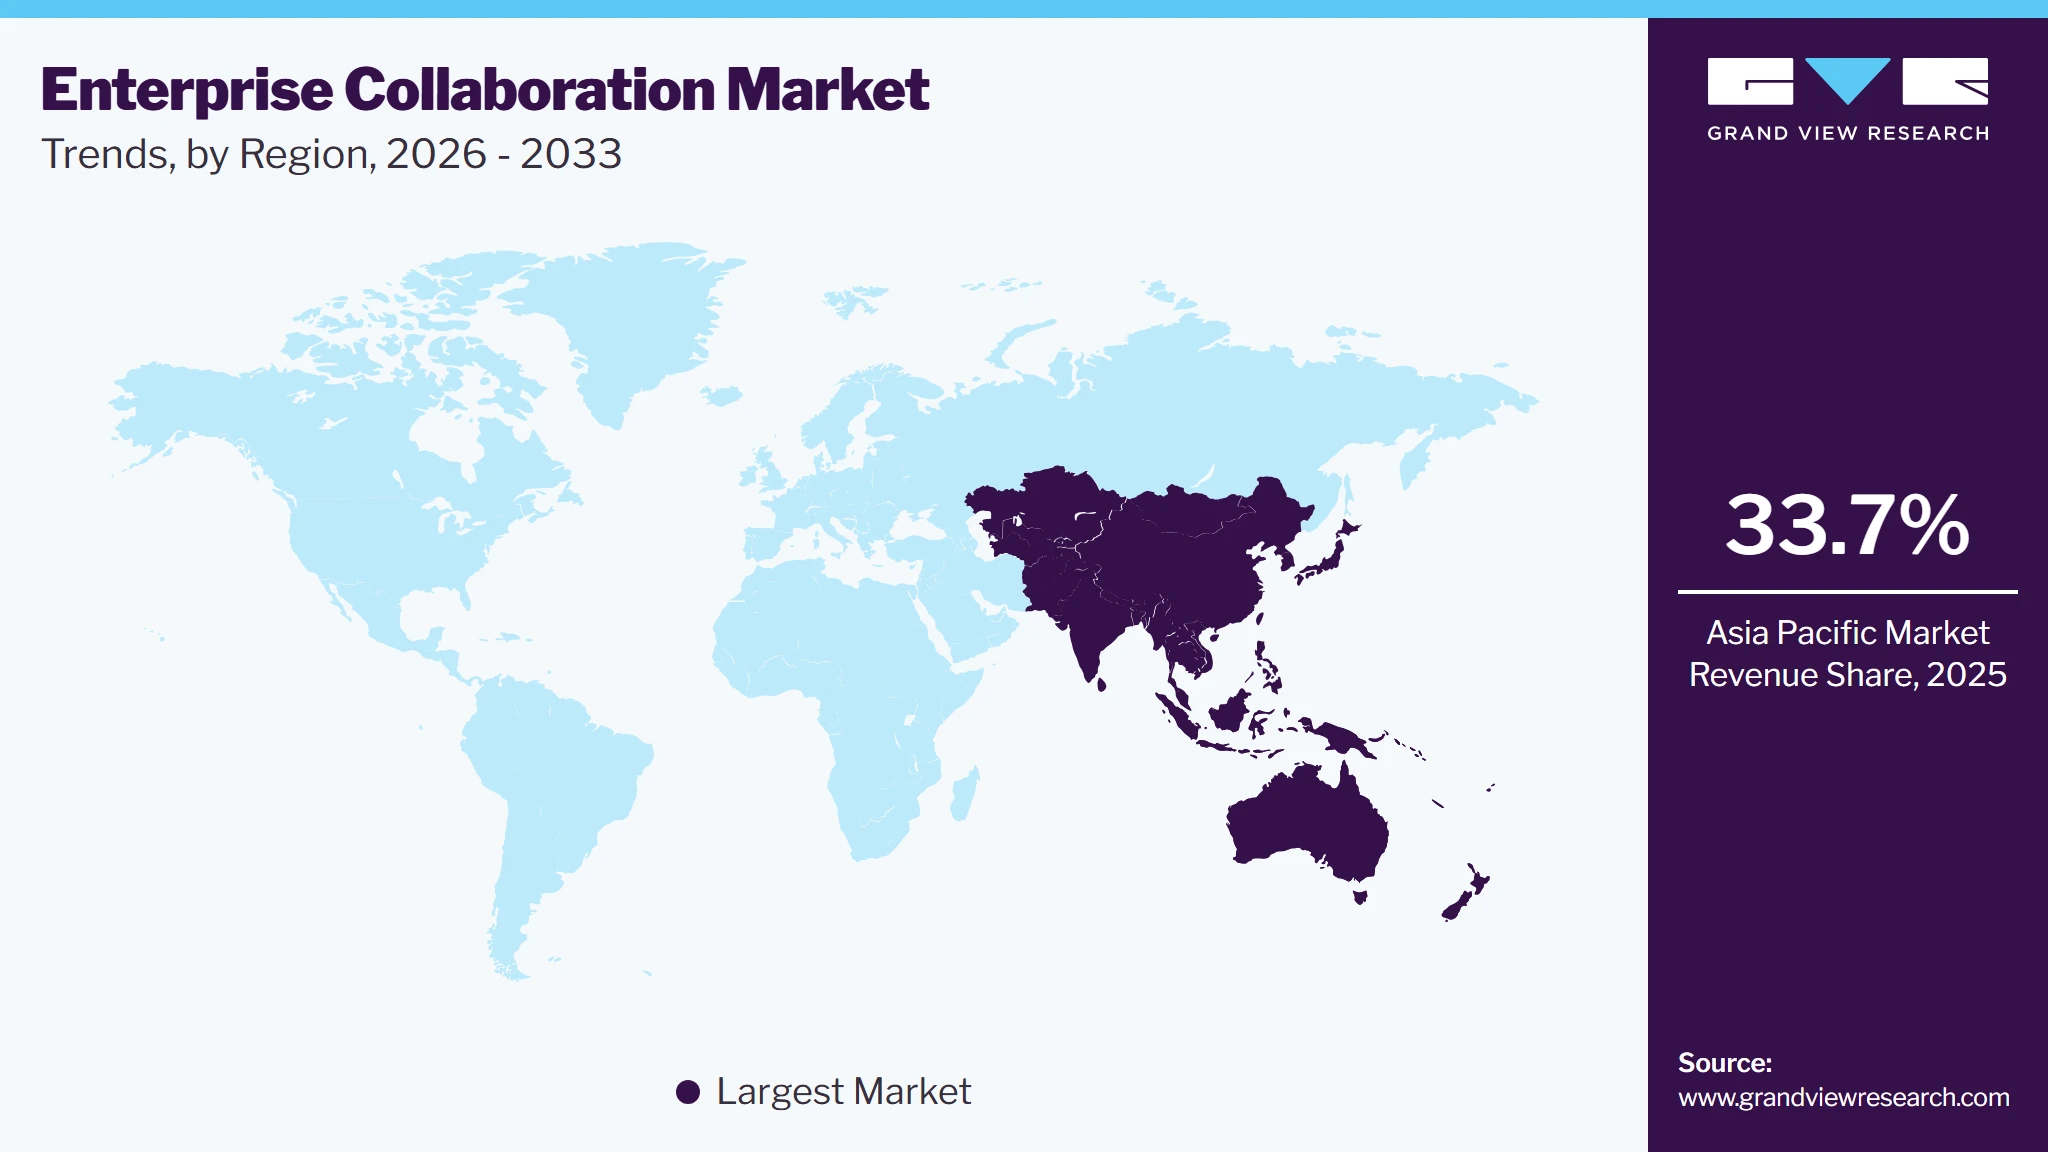
Asia pacific dominated the enterprise collaboration market, accounting for the largest revenue share of 33.7% in 2025, driven by increasing digitalization among small and medium enterprises, rising adoption of 5G networks, and the rapid expansion of cloud-based infrastructures. Accelerated deployment of AI-powered tools and automation within enterprise ecosystems is enhancing productivity and streamlining workflows, fueling the need for enterprise collaboration solutions.
 To learn more about this report, Download Free Sample Report
The Japan enterprise collaboration market is gaining traction, fueled by the country’s strong emphasis on digital transformation and seamless integration of advanced technologies. The government’s initiatives promoting Industry 4.0 and work-style reforms encourage organizations to adopt enterprise collaboration tools to improve productivity and address workforce challenges. The cultural focus on harmony within Japanese companies also supports the preference for enterprise collaboration technologies.
The China enterprise collaboration market is rapidly expanding. China's strong emphasis on building a smart and connected workforce to support its vast manufacturing and service sectors is a key driver of enterprise collaboration solutions adoption. The government's strategic policies, including the Digital China initiative and significant investments in 5G infrastructure, are enhancing connectivity and enabling seamless collaboration across geographically dispersed teams.
Key Enterprise Collaboration Company Insights
Some of the key players operating in the market include Microsoft and Salesforce, Inc., among others.
-
Microsoft is a global technology leader known for its comprehensive software products and cloud services. Microsoft Teams, its flagship enterprise collaboration platform, integrates chat, video conferencing, file sharing, and workflow automation within the Microsoft 365 ecosystem. The company’s continuous innovation in AI, cloud computing (Azure), and security drives digital transformation for organizations worldwide. Microsoft’s vast global presence and strong enterprise relationships make it a dominant force in the enterprise collaboration market.
-
Salesforce, Inc. offers a popular real-time messaging and collaboration platform designed to streamline communication across organizations. Salesforce integrates with hundreds of third-party applications, enabling seamless workflow management, file sharing, and team collaboration. With Salesforce’s backing, Slack is expanding its capabilities around CRM integration, AI-powered insights, and cross-platform collaboration, solidifying its position as a top player in the enterprise collaboration industry.
Igloo Software Limited and Zoho Corporation Pvt. Ltd. are some of the emerging market participants in the enterprise collaboration market.
-
Igloo Software specializes in modern digital workplace solutions that enable organizations to create engaging intranets, extranets, and collaboration hubs. The company focuses on improving knowledge sharing, communication, and team productivity by leveraging cloud-based platforms that integrate with popular enterprise tools. Igloo’s user-centric design and flexibility make it an attractive choice for mid-sized businesses and enterprises looking to enhance internal collaboration and culture. Its growing adoption in North America and Europe positions it as an emerging player in the enterprise collaboration market.
-
Zoho Corporation Pvt. Ltd. offers a comprehensive suite of cloud-based business applications, including collaboration tools such as Zoho Cliq (messaging), Zoho Projects (project management), and Zoho Connect (team collaboration). The company emphasizes affordability, integration, and ease of use, targeting SMEs and growing enterprises. Zoho’s continuous innovation in AI and automation, along with its global reach, is driving its emergence as a competitive player in the enterprise collaboration space.
Key Enterprise Collaboration Companies
The following key companies have been profiled for this study on the enterprise collaboration market.
-
Microsoft
-
Cisco Systems, Inc.
-
Zoom Communications, Inc.
-
Google LLC
-
Salesforce, Inc.
-
SAP SE
-
Cloud Software Group, Inc.
-
Atlassian
-
Igloo Software
-
Zoho Corporation Pvt. Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Microsoft, Cisco Systems, Inc., Zoom Communications, Inc., Google LLC, Salesforce, Inc., SAP SE, Cloud Software Group, Inc.)
- These companies focus on strengthening enterprise collaboration ecosystems through cloud-based platforms, unified communications and collaboration (UC&C) solutions, AI-powered productivity tools, and workflow automation.
- Their strategies emphasize platform consolidation, strategic partnerships, ecosystem expansion, enterprise-grade security, and integration of collaboration tools with business applications.
- Established players benefit from strong global brand presence, large enterprise customer bases, extensive cloud infrastructure, advanced AI capabilities, robust security frameworks, and broad software ecosystems.
- Their ability to provide integrated collaboration suites, communication platforms, productivity applications, and enterprise workflow solutions enables them to serve diverse industries and maintain strong market positions.
- Large-scale operations, complex product portfolios, and significant infrastructure investments can create challenges in agility and innovation speed.
- High subscription costs, feature complexity, integration challenges with legacy systems, and dependence on enterprise IT budgets may limit adoption among smaller organizations.
Emerging & Specialized Players (Magic Leap, Fusion VR, HCL Technologies)
- These companies focus on specialized digital workplace and employee experience solutions, including intranet platforms, knowledge management, employee engagement, internal communication, and enterprise community-building tools.
- Their strategies emphasize customization, industry-specific solutions, personalized employee experiences, integration capabilities, and customer-focused service delivery.
- Specialized players benefit from focused domain expertise, agility, customized solutions, and strong capabilities in addressing specific collaboration challenges such as employee engagement, knowledge sharing, and internal communications.
- Their ability to tailor platforms according to organizational needs provides differentiation against broader collaboration suites.
- Smaller market presence, limited global scale, and lower financial resources compared with major technology providers can restrict expansion.
- Dependence on integration partnerships, enterprise adoption cycles, and competition from bundled collaboration platforms may impact growth opportunities.
Recent Developments
-
In May 2025, at Zoholics USA, Zoho Corporation Pvt. Ltd. launched Vani, a new visual collaboration platform designed specifically to address the evolving needs of the enterprise collaboration market. Featuring an infinite canvas, smart templates, and built-in video conferencing, Vani aims to enhance collaborative workflows and foster creativity within teams. This launch reflects Zoho’s strategic focus on providing integrated, user-friendly solutions that support remote and hybrid work environments, helping enterprises improve productivity and streamline communication across diverse industries.
-
In April 2025, Atlassian made its enterprise AI solution, Rovo, available to all customers. This launch aims to address the growing demand in the enterprise collaboration market for AI-powered tools that enhance team productivity. Rovo offers advanced AI-driven search, chat, and agent capabilities designed to improve knowledge sharing and streamline communication across teams. Atlassian’s move reflects its commitment to integrating intelligent automation and collaboration features that support digital transformation in enterprises globally.
-
In April 2025, Microsoft introduced the nearby feature in Microsoft Teams to enhance real-time team interactions within physical workspaces. This innovation allows users to identify and connect with nearby colleagues from their 1:1 or group chats, facilitating spontaneous in-person meetings and brainstorming sessions. The launch underscores Microsoft’s commitment to strengthening hybrid work models and boosting productivity through seamless enterprise collaboration, positioning Teams as a critical tool in the evolving enterprise collaboration market.
Enterprise Collaboration Market Report Scope
Report Attribute
Details
Market size in 2025
USD 60.6 billion
Estimated market size in 2026
USD 67.5 billion
Projected market size by 2033
USD 159.9 billion
Growth rate
CAGR of 13.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, organization size, deployment mode, end-use, region
Regional scope
North America, Europe, Asia Pacific, Latin America, MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, China, Japan, India, South Korea, Australia, Brazil, South Africa, Saudi Arabia, UAE
Key companies profiled
Microsoft; Cisco Systems, Inc.; Zoom Communications, Inc.; Google LLC; Salesforce, Inc.; SAP SE; Cloud Software Group, Inc.; Atlassian; Igloo Software; Zoho Corporation Pvt. Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Enterprise Collaboration Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest technological trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the enterprise collaboration market report based on type, organization size, deployment mode, end-use, and region:
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Solution
-
Services
-
-
Organization Size Outlook (Revenue, USD Billion, 2021 - 2033)
-
Large Enterprises
-
Small and Medium Enterprises (SMEs)
-
-
Deployment Mode Outlook (Revenue, USD Billion, 2021 - 2033)
-
On-premises
-
Cloud-based
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
IT & Telecom
-
BFSI
-
Healthcare
-
Retail & Consumer Goods
-
Manufacturing
-
Education
-
Travel & Hospitality
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The enterprise collaboration market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each enterprise collaboration segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Solution
Revenue is generated through sales and subscriptions of enterprise collaboration software platforms, including communication, messaging, video conferencing, document collaboration, project management, knowledge sharing, workflow automation, and integrated productivity applications.
Services
Revenue is generated through professional and managed services, including consulting, implementation, customization, integration, migration, deployment, user training, technical support, maintenance, and managed administration of enterprise collaboration solutions.
Segment - Organization Size
Revenue capture definition
Large Enterprises
Revenue is generated through enterprise-wide licensing agreements, large-scale cloud subscriptions, customized collaboration platforms, premium support services, security enhancements, and long-term maintenance contracts for large organizations.
Small and Medium Enterprises
Revenue is generated through subscription-based collaboration software, scalable cloud solutions, implementation services, technical support, and affordable collaboration packages designed for small and medium-sized businesses.
Segment - Deployment
Revenue capture definition
On-premises
Revenue is generated through perpetual software licensing, infrastructure deployment, implementation services, hardware integration, software upgrades, maintenance contracts, and technical support for customer-hosted collaboration environments.
Cloud-based
Revenue is generated through recurring subscription fees for Software-as-a-Service (SaaS) collaboration platforms, cloud storage, premium features, user-based licensing, managed services, and platform upgrades delivered through cloud infrastructure.
Segment - End Use
Revenue capture definition
IT & Telecom
Revenue is generated through deployment of enterprise collaboration platforms for workforce communication, software development collaboration, project management, virtual meetings, knowledge sharing, and hybrid work enablement within IT and telecommunications organizations.
BFSI
Revenue is generated through secure collaboration platforms, document management solutions, compliance-enabled communication tools, workflow automation, virtual meetings, and collaboration services supporting banking, financial services, and insurance operations.
Healthcare
Revenue is generated through secure communication platforms, care coordination tools, telehealth collaboration, document sharing solutions, workflow management systems, and collaboration services that support healthcare providers and administrative teams.
Retail & Consumer Goods
Revenue is generated through team collaboration platforms, supply chain communication solutions, inventory coordination tools, workforce management applications, document collaboration, and omnichannel operational collaboration services.
Manufacturing
Revenue is generated through collaboration solutions supporting production planning, engineering collaboration, supply chain coordination, quality management, maintenance workflows, document sharing, and communication across manufacturing operations.
Education
Revenue is generated through virtual classrooms, communication platforms, collaborative learning tools, document sharing applications, campus workforce collaboration solutions, and cloud-based education productivity software subscriptions.
Travel & Hospitality
Revenue is generated through collaboration platforms that facilitate workforce communication, reservation management coordination, customer service collaboration, operational workflow management, remote meetings, and document sharing across travel and hospitality organizations.
Others
Revenue is generated through enterprise collaboration software, cloud subscriptions, implementation services, consulting, managed services, and communication solutions deployed across government, media, energy, logistics, construction, professional services, and other industry verticals.
Estimation Model
Layer Name
Key Question
Description
Collaboration Technology & Platform Enablement Layer
How are enterprise collaboration solutions developed, integrated, and enabled?
Represents the technologies, software platforms, and infrastructure that enable digital collaboration across organizations. Includes unified communications and collaboration (UC&C) platforms, video conferencing solutions, instant messaging and team collaboration tools, cloud collaboration infrastructure, AI-powered productivity assistants, workflow automation platforms, enterprise content management systems, APIs, integration frameworks, cybersecurity solutions, and identity management technologies that support secure and seamless workplace collaboration.
Industry Application & End-User Layer
Where are enterprise collaboration solutions deployed and which industries drive demand?
Represents the industries and business functions where collaboration platforms create value. Key end users include IT & telecommunications, BFSI, healthcare, education, government, manufacturing, retail & eCommerce, media & entertainment, professional services, and technology enterprises. Enterprise collaboration solutions support remote work, hybrid workforce management, virtual meetings, knowledge sharing, project management, customer engagement, employee communication, and cross-functional teamwork.
Collaboration Type, Deployment & Experience Delivery Layer
How are enterprise collaboration solutions structured and delivered?
Covers enterprise collaboration classifications based on communication methods, deployment models, and user experience. Includes synchronous collaboration (video conferencing, voice communication, instant messaging, virtual meetings), asynchronous collaboration (document sharing, enterprise social networks, knowledge management), project and workflow collaboration, and immersive collaboration experiences. Solutions are delivered through cloud-based platforms, on-premises infrastructure, hybrid environments, mobile applications, desktop applications, and web-based interfaces, with capabilities such as real-time collaboration, AI assistance, automation, and integrated digital workplace experiences.
Revenue Generation & Market Monetization Layer
How is revenue generated in the enterprise collaboration market?
Revenue is generated through software subscriptions, SaaS licensing, enterprise platform fees, communication service charges, hardware solutions, integration services, professional consulting, managed collaboration services, security and compliance solutions, training and support services, and customized enterprise collaboration deployments. Vendors monetize through per-user pricing models, enterprise contracts, usage-based plans, premium AI features, and bundled productivity suites offered to organizations across industries.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Sizing, Segmentation & Growth Opportunity Assessment
Assessed the global enterprise collaboration market size, historical trends, forecast growth outlook, and detailed segmentation by component (solutions and services), deployment model (cloud, on-premise, and hybrid), collaboration type (communication, conferencing, content sharing, project collaboration, workflow management, and employee engagement), organization size (SMEs and large enterprises), and end-use industries (IT & telecommunications, BFSI, healthcare, education, government, manufacturing, retail & eCommerce, media & entertainment, and others).
Supports strategic planning, identifies high-growth market segments, enables prioritization of product and technology investments, and helps stakeholders capitalize on increasing demand for AI-enabled, cloud-based, and integrated enterprise collaboration solutions.
Competitive Landscape & Strategic Positioning Analysis
Benchmarked key enterprise collaboration providers based on platform capabilities, unified communications and collaboration (UC&C) offerings, AI-powered productivity features, cloud infrastructure, workflow automation, security capabilities, enterprise integrations, partner ecosystems, acquisitions, geographic presence, and innovation strategies. The analysis assessed competitive positioning across collaboration suites, communication platforms, productivity tools, and digital workplace solutions.
Enables competitive benchmarking, identifies technology and capability gaps, supports partnership and acquisition strategies, strengthens market positioning, and helps companies align offerings with evolving enterprise requirements for secure, intelligent, and connected collaboration environments.
Regional Market Demand & Industry Adoption Analysis
Analyzed regional market dynamics across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa by evaluating cloud adoption, remote and hybrid workforce trends, enterprise digital transformation initiatives, IT infrastructure investments, cybersecurity requirements, regulatory considerations, and industry-specific collaboration needs. The analysis highlighted regional adoption patterns and growth opportunities across key enterprise sectors.
Supports regional expansion strategies, identifies high-potential markets, enables localized product positioning, guides investment decisions, and helps organizations optimize go-to-market strategies across diverse geographic and industry landscapes.
Frequently Asked Questions About This Report
The solution segment accounted for the largest market share of 65.4% in 2025.
The large enterprises segment led the market with a share of 71.3% in 2025.
The cloud-based segment led the market with a share of 55.0% in 2025.
The IT & telecom segment led the market with a share of 23.5% in 2025.
The global enterprise collaboration market size was valued at USD 60.6 billion in 2025 and is projected to grow from USD 67.5 billion in 2026.
The global enterprise collaboration market is expected to grow at a compound annual growth rate of 13.1% from 2026 to 2033 to reach USD 159.9 billion by 2033.
Asia Pacific enterprise collaboration market accounted for the largest market share of over 33% in 2025.
Some key players operating in the enterprise collaboration market include Microsoft, Cisco Systems, Inc., Zoom Communications, Inc., Google LLC, Salesforce, Inc., SAP SE, Cloud Software Group, Inc., Atlassian, Igloo Software, Zoho Corporation Pvt. Ltd.
The key factors driving the enterprise collaboration market include the rising adoption of remote and hybrid work models, increasing need for real-time communication and information sharing, growing use of cloud-based collaboration tools, demand for centralized project management solutions, and the integration of artificial intelligence (AI) and machine learning (ML) in collaborative platforms.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


