
- Home
- »
- Plastics, Polymers & Resins
- »
-
Frozen Food Packaging Market Size, Growth Report, 2026-2033GVR Report cover

Frozen Food Packaging Market 2026 - 2033
Size, Share & Trends Analysis Report By Material (Plastic, Paper and Paperboard, Metal), By Product, By Application (Meat, Poultry & Seafood, Fruit & Vegetables), By Region, And Segment Forecasts
Market Size, 2025
$50.8BMarket Estimate, 2026
$53.7BMarket Forecast, 2033
$79.7BCAGR, 2026–2033
5.8%Frozen Food Packaging Market Summary
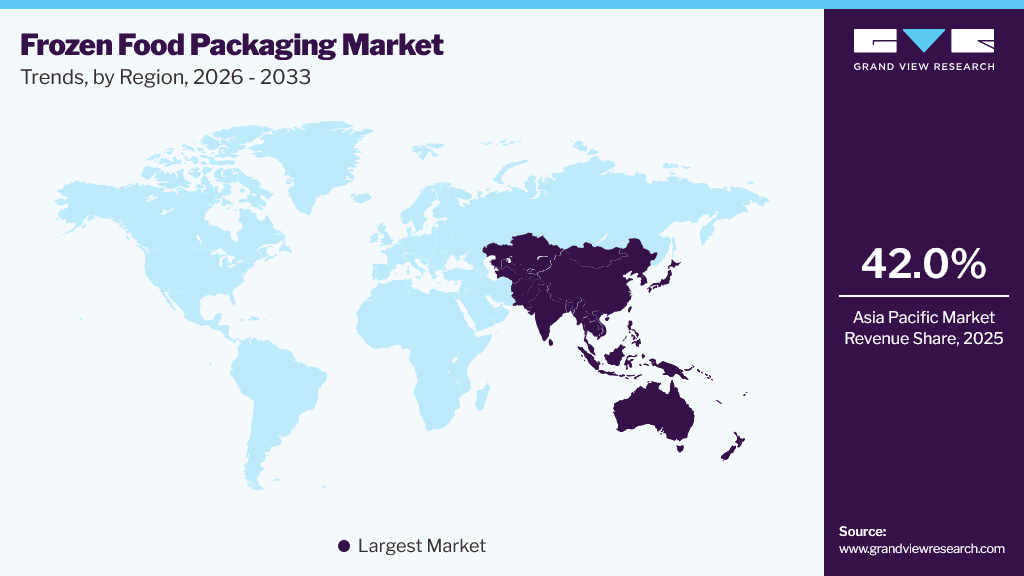
The global frozen food packaging market size was valued at USD 50.8 billion in 2025 and is projected to grow from USD 53.7 billion in 2026 to USD 79.7 billion in 2033, at a CAGR of 5.8% from 2026 to 2033. The Asia Pacific dominated the market, accounting for a revenue share of 42.0% in 2025. Growing demand for frozen food products, owing to advantages such as longer shelf life and easy availability, is expected to drive market growth.
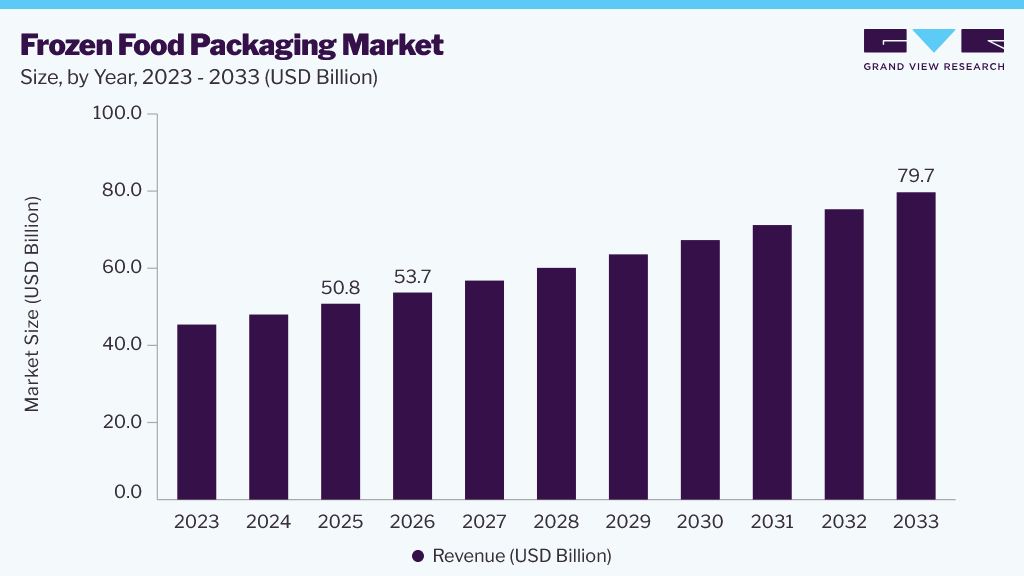 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The bags & pouches segment dominated the market and accounted for the largest revenue share of approximately 34.0% in 2025.
- By application: The meat, poultry & seafood application segment accounted for the largest revenue share of over 36.0% in 2025.
- By material: The plastic segment dominated the market with a share of approximately 59.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (42.0% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 50.8 Billion
- Estimated market size in 2026: USD 53.7 Billion
- Projected market size by 2033: USD 79.7 Billion
- CAGR (2026-2033): 5.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market is witnessing significant growth due to rising demand for convenient, ready-to-eat, and ready-to-cook food products across global markets. Changing consumer lifestyles, increasing urbanization, and busy work schedules have accelerated the adoption of frozen foods, including frozen dairy products, ready meals, fruits, vegetables, and snacks. This growing consumption is driving demand for reliable packaging solutions that ensure product quality, safety, and extended shelf life during transportation and storage.
The increasing consumption of frozen dairy products such as ice cream, frozen yogurt, and specialty desserts is further supporting demand for advanced packaging materials, including plastic pouches, cardboard cartons, and foil wraps. These packaging solutions help prevent spoilage, protect against moisture and temperature fluctuations, and maintain product freshness. In addition, the rising emphasis on sustainable and high-performance packaging solutions is encouraging manufacturers to develop innovative materials with improved barrier properties and recyclability.
In February 2026, the International Dairy Foods Association announced that U.S. dairy exports reached USD 9.5 billion in 2025, reflecting robust global demand and expanding international markets for dairy products. The rising production and trade of frozen dairy products are further contributing to demand for efficient frozen food packaging solutions.
Moreover, advancements in freezing technologies and cold chain infrastructure have significantly improved the storage, transportation, and shelf life of frozen food products. Improved freezing techniques help preserve nutrients, taste, and texture, increasing consumer confidence in frozen foods. Expanded cold chain networks also enable longer-distance transportation with reduced temperature fluctuations, supporting market growth.
Furthermore, rising health consciousness has increased demand for frozen fruits, vegetables, meals, and snacks marketed as healthier alternatives to shelf-stable products. Packaging plays a crucial role in communicating product freshness, nutritional value, and clean-label benefits to health-conscious consumers. Features such as transparent packaging, informative labeling, and secure sealing solutions are increasingly supporting consumer preference for high-quality frozen food products.
Analyst Perspective
The market is expected to sustain growth, driven by rising consumer demand for convenient, ready-to-eat frozen foods, expanding cold chain infrastructure, and increasing investment in high-performance packaging technologies. Growing consumption across key product categories, including frozen ready meals, meat, seafood, dairy products, bakery products, fruits, and vegetables, is further supporting market expansion. From an analyst’s perspective, manufacturers are shifting toward lightweight, high-barrier, and recyclable packaging solutions that enhance product protection, extend shelf life, and improve transportation efficiency while meeting evolving sustainability regulations. Flexible packaging formats, including bags, pouches, and films, are anticipated to gain significant traction due to their cost-effectiveness, space efficiency, and lower material usage.
Product Insights
The bags & pouches segment dominated the market, accounting for approximately 34.0% of revenue in 2025. Bags and pouches can be easily designed to fit the shape and size of frozen food products, helping to minimize excess headspace and improve storage efficiency. Their lightweight nature also enables more efficient packing, transportation, and stacking in freezers. The segment is further driven by increasing demand for flexible, lightweight, and cost-effective packaging solutions that offer strong barrier protection against moisture, oxygen, and temperature fluctuations. In addition, growing adoption of recyclable and sustainable flexible packaging materials is supporting segment growth. Rising demand for convenient portion-sized packaging, resealable formats, and easy-to-handle packaging solutions for frozen meals, seafood, vegetables, and snacks is further accelerating the adoption of bags and pouches in the market.
Films and wraps are widely used in frozen food packaging because they provide an effective barrier against oxygen, moisture, and odors while remaining lightweight and flexible. Plastic films such as polypropylene (PP) and polyethylene (PE), along with wraps including polyvinyl chloride (PVC) and polyvinylidene chloride (PVDC), help preserve product freshness and protect frozen foods from external contamination. The segment is driven by increasing demand for lightweight, cost-effective, and high-performance packaging solutions that enhance product shelf life and improve storage efficiency. Films and wraps are commonly used to package frozen meat, seafood, vegetables, ready meals, and bakery products due to their excellent sealing properties and strong resistance to low temperatures. In addition, advancements in recyclable and sustainable film materials are further supporting growth in this segment.
Application Insights
The meat, poultry & seafood application segment dominated the market, accounting for approximately 36.0% of revenue in 2025. The segment is expected to retain its leading position throughout the forecast period due to increasing global consumption of meat, poultry, and seafood products, driven by rising protein intake, shifting dietary preferences, and growing demand for convenient frozen foods. The need for reliable frozen food packaging is particularly high in this segment, as packaging plays a critical role in preventing contamination, preserving freshness, and extending shelf life during storage and transportation. In addition, increasing demand for processed and value-added frozen meat products is further supporting segment growth. Growing consumer preference for portion-controlled packaging, vacuum-sealed formats, and high-barrier packaging solutions is also accelerating demand in this segment. Furthermore, the expansion of cold chain logistics and advancements in packaging technologies are improving product safety, storage efficiency, and product quality, thereby supporting market growth.
The dairy products application segment is projected to grow at the fastest CAGR during the forecast period, driven by increasing demand for frozen dairy products such as ice cream, frozen yogurt, butter, and specialty desserts. Rising consumer preference for convenient, portion-controlled, and easy-to-store dairy products is further supporting segment growth. Packaging plays a critical role in preserving product freshness, preventing contamination, and protecting dairy products from moisture and temperature fluctuations during frozen storage and transportation. Advanced packaging formats such as pouches, cartons, tubs, and resealable packaging solutions are gaining traction due to their convenience, improved barrier properties, and enhanced consumer usability. In addition, features such as resealable closures and easy-to-pour designs have made dairy packaging more user-friendly, further supporting demand in this segment.
Material Insights
The plastic segment dominated the market, accounting for approximately 59.0% in 2025. Plastic is the most widely used material for frozen food packaging owing to several beneficial properties, including heat resistance, heat-sealing capability, and strong barrier performance against moisture and contaminants. In addition, plastic offers several options for color and transparency. Commonly used plastics for frozen food packaging include polyethylene (PE), polypropylene (PP), polyethylene terephthalate (PET), and high-impact polystyrene, among others. The segment continues to dominate due to the increasing demand for lightweight, durable, and cost-effective packaging solutions across frozen meat, seafood, ready meals, dairy products, and frozen fruits & vegetables. Plastic materials also offer excellent flexibility in packaging formats such as trays, containers, pouches, films, and wraps, further supporting their widespread adoption in the frozen food packaging industry.
Various grades of polyethylene, including low-density polyethylene (LDPE) and high-density polyethylene (HDPE), are commonly used in frozen food packaging due to their durability, flexibility, and moisture resistance. The paper & paperboard materials segment is expected to grow at a steady CAGR from 2026 to 2033. Paper and paperboard materials are widely used in frozen food packaging applications, including ice cream, frozen pizzas, frozen fruits and vegetables, and frozen dessert cones. The segment is gaining traction due to the increasing demand for sustainable and recyclable packaging solutions. Paper-based materials offer cost-effectiveness, broad availability, and greater environmental benefits than conventional plastic-based packaging. In addition, advancements in barrier coating technologies are enhancing the moisture, oxygen, and grease resistance of paper packaging, making it increasingly suitable for frozen food applications. For instance, in August 2025, Mondi ramped up production of its FunctionalBarrier Paper Ultimate following an investment in advanced manufacturing technology to meet the growing demand for sustainable high-barrier paper-based packaging. The recyclable solution offers excellent oxygen, moisture, and grease barrier properties, reinforcing the growing adoption of paper-based materials for food packaging, including frozen food.
Regional Insights
The North American regional market is characterized by extensive R&D to develop innovative technologies and processes for manufacturing food packaging solutions. Food packaging manufacturers are developing technologically advanced manufacturing processes to save time and effort in production, increase overall efficiency, and maximize profit. For instance, in July 2024, Lineage highlighted its use of automation, data analytics, and technology-driven warehouse operations across more than 480 temperature-controlled facilities, underscoring North America's continued investment in advanced frozen-food logistics and packaging infrastructure. Furthermore, increasing efforts undertaken by manufacturers in North America to develop edible packaging and micro-packaging solutions are expected to provide growth opportunities within the food packaging industry.
 To learn more about this report, Download Free Sample Report
U.S. Frozen Food Packaging Market Trends
The frozen food packaging market in the U.S. is one of the largest packaged food markets in the world, owing to a large population with high disposable income. Moreover, busy lifestyles in the country further lead to a surge in demand for packaged food products. The U.S. has one of the largest markets for fresh fruits & vegetables, including exotic fruits & mushrooms. Moreover, the extensive penetration of quick-service restaurants, which are the main consumers of frozen food products, is also contributing to the market growth.
Canada frozen food packaging market held a significant revenue share in 2025 due to its pursuit of a circular economy and a zero-plastic-waste agenda. The willingness of Canadians to pay premiums for sustainable food packaging reflects consumer awareness and shifting market dynamics.
Asia Pacific Frozen Food Packaging Market Trends
The frozen food packaging market in the Asia Pacific dominated the market, accounting for a revenue share of 42.0% of revenue in 2025, and is expected to maintain its leading position over the forecast period. The market is driven by rapid urbanization, rising disposable incomes, growing demand for convenience foods, and expanding cold chain logistics infrastructure across the region. Increasing consumption of frozen ready meals, frozen seafood, processed meat, and on-the-go snacks is further accelerating demand for advanced frozen food packaging solutions. Many food packaging companies are expanding their geographic presence across the Asia-Pacific, particularly in developing countries in Southeast Asia, such as Malaysia, Indonesia, Thailand, and Vietnam, to capitalize on the rising demand for packaged food products. For instance, in February 2025, SIG inaugurated its first aseptic carton production plant in India, with an annual production capacity of up to 4 billion aseptic carton packs. The investment strengthens the company’s manufacturing footprint in the Asia Pacific region and supports the rising demand for packaged food and beverages, reinforcing the region’s growing importance in the food packaging industry.
India frozen food packaging market is expected to grow significantly over the forecast period due to changing lifestyles, rising urbanization, increasing working hours, and growing consumer preference for convenient ready-to-cook and ready-to-eat food products. Rising disposable incomes, expansion of organized retail, and improving cold chain infrastructure are further supporting market growth. India is also witnessing a growing shift toward sustainable packaging solutions driven by evolving environmental regulations and increasing sustainability awareness among manufacturers and consumers. Historically, the use of recycled plastics in food-contact packaging applications was restricted due to limited recycling infrastructure and safety concerns. However, recent regulatory developments supporting recycled content in select food-grade packaging materials, subject to FSSAI compliance, are expected to encourage the adoption of sustainable packaging solutions. Such regulations are likely to accelerate the transition toward circular packaging systems and support long-term market growth.
Europe Frozen Food Packaging Market Trends
The frozen food packaging market in Europe accounted for a significant share of revenue in 2025, owing to ongoing innovations in sustainable and recyclable packaging solutions. The region’s strong regulatory focus on reducing packaging waste, along with increasing adoption of circular economy practices, is accelerating demand for eco-friendly packaging materials. Dutch Pack International provides mono-material packaging solutions with enhanced recyclability, supporting the region’s sustainability goals. Furthermore, in April 2025, Stora Enso launched Performa Nova, a next-generation folding boxboard designed for consumer packaging applications, including frozen and chilled foods. The lightweight, renewable, and recyclable material enhances packaging efficiency while reducing environmental impact, reinforcing Europe’s focus on sustainable fiber-based packaging solutions for frozen food applications.
Germany frozen food packaging market is primarily driven by increasing efforts by the Government of Germany and food packaging manufacturers to reduce plastic pollution, backed by partnerships among various players in food packaging to eliminate the use of multi-layered plastics. For instance, in October 2025, Delfort and Rieusset introduced a recyclable paper-based packaging solution for ice cream, which was first launched in German retail stores. The packaging is designed to protect frozen products from moisture, flavor loss, freezer burn, and dehydration while enhancing recyclability, supporting Germany's transition toward sustainable frozen food packaging.
Central & South America Frozen Food Packaging Market Trends
The frozen food packaging market in CSA is projected to expand at a significant CAGR during the forecast period, driven by growth in the middle-income population, high food quality expectations, rapid urbanization, and a gradual shift toward eco-friendly packaging solutions. The market is further supported by rising demand for convenience foods, increasing penetration of supermarkets and hypermarkets, expansion of cold-chain logistics, and growing investments in food-processing and packaging infrastructure across the region. Furthermore, rising consumer preference for packaged frozen meat, seafood, ready meals, and bakery products is driving demand for advanced frozen food packaging solutions. In South America, changing lifestyles have driven the adoption of ready-to-eat, convenient foods, thus supporting overall market growth.
Brazil frozen food packaging market is expected to register a considerable CAGR during the forecast period, primarily owing to rising consumer demand for dairy products. Growing awareness of the importance of consuming protein-rich foods is likely to raise demand for dairy products, in turn fostering market growth. Given the rising demand for innovative dairy packaging solutions in Brazil, SIG partnered with Brazilian dairy producer Cooperoeste to launch yogurt and dulce de leche in SIG CloverCap spouted pouches. The packaging solution offers a convenient, on-the-go format for dairy products while enhancing product protection and consumer convenience, underscoring the growing adoption of advanced flexible packaging in Brazil's dairy industry.
Middle East & Africa (MEA) Frozen Food Packaging Market Trends
The frozen food packaging market in MEA is influenced by evolving consumer preferences, government regulations on sustainable packaging, and a competitive landscape. The market is further driven by rapid urbanization, rising disposable incomes, growing demand for convenience and ready-to-cook frozen foods, and the expansion of modern retail and cold-chain infrastructure across the region. Growing tourism and the foodservice sector, particularly in GCC countries, are also contributing to higher consumption of frozen food products, thereby boosting demand for advanced packaging solutions. Al Kabeer Group and Sunbulah Group are among the top players operating in the region.
Saudi Arabia frozen food packaging market is expected to grow strongly, driven by the increasing population of working individuals with busy lifestyles and rising demand for convenient, ready-to-cook, and ready-to-eat food products. The country also benefits from high levels of disposable income, which support greater consumer spending on packaged and frozen food products. In addition, the expansion of modern retail channels, supermarkets, hypermarkets, and cold chain infrastructure is further supporting market growth. Saudi Arabia is also witnessing strong adoption of advanced packaging technologies and innovative design solutions, particularly in flexible frozen food packaging, to improve product shelf life, safety, and convenience. The growing focus on automation, digitalization, and sustainable packaging solutions among food packaging manufacturers is expected to further drive market growth. For instance, in March 2025, Tetra Pak International S.A. launched a three-year project with Al Rabie Saudi Foods to modernize and digitize its production facilities in Saudi Arabia using advanced packaging technologies and Industry 4.0 solutions. The project is expected to increase production capacity, improve resource efficiency, and strengthen sustainable food packaging capabilities, supporting the adoption of innovative packaging solutions across the Kingdom's food industry.
Key Frozen Food Packaging Company Insights
The market is highly fragmented, with a significant number of medium-sized companies. The frozen food packaging industry has been witnessing a significant number of new product launches and expansions over the past few years. This can be attributed to the growing urbanization, demand for easy-to-cook meals, and busy schedules of the working population across the globe.
Key Frozen Food Packaging Companies
The following are the leading companies in the frozen food packaging market. These companies collectively hold the largest market share and dictate industry trends.
-
Sonoco Products Company
-
Sealed Air
-
ProAmpac
-
Printpack
-
SÜDPACK
-
Amcor Plc
-
WestRock Company
-
Huhtamaki Oyj
-
Smurfit Westrock
-
Tetra Pak International S.A.
-
Transcontinental Inc.
-
Toyo Seikan Group Holdings, Ltd.
Recent Developments
-
In November 2025, Mondi launched an expanded portfolio of corrugated and solid board for the food packaging industry following its acquisition of Schumacher Packaging. The enhanced portfolio includes solid board solutions and digital printing capabilities, enabling food manufacturers to access sustainable, recyclable packaging that improves shelf visibility, handling efficiency, regulatory compliance, and product protection across a wide range of food applications.
-
In February 2025, the EU adopted the Packaging and Packaging Waste Regulation (PPWR), which generally applies from 12 August 2026 and restricts PFAS in food-contact packaging above specified thresholds. The regulation is expected to accelerate the shift toward PFAS-free, recyclable, and fiber-based food packaging and drive innovation in sustainable packaging materials.
-
In July 2023, Huhtamaki Oyj, a prominent global provider of sustainable packaging solutions, made a substantial investment in its facility located in Paris, Texas, U.S. This investment involves expanding manufacturing capacity and consolidating an external warehouse. The company planned to invest approximately USD 30.0 million in production assets while leasing a warehouse and manufacturing facility.
Frozen Food Packaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 50.8 billion
Estimated market size in 2026
USD 53.7 billion
Projected market size by 2033
USD 79.7 billion
Growth rate
CAGR of 5.8% from 2026 to 2033
Actual data
2021 – 2025
Forecast period
2026 – 2033
Quantitative units
Volume in kilotons, revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Volume forecast, revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Material, product, application, region
Regional Scope
North America; Europe; Asia Pacific; CSA; MEA
Country Scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; India; Japan; South Korea; Australia; Southeast Asia; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Sonoco Products Company; Sealed Air; ProAmpac; Printpack; SÜDPACK; Amcor Plc; WestRock Company; Huhtamaki Oyj; Smurfit Westrock; Tetra Pak International S.A.; Transcontinental Inc.; Toyo Seikan Group Holdings, Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Frozen Food Packaging Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global Frozen Food Packaging market report based on material, product, application, and region:
-
Material Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Plastic
-
Paper and Paperboard
-
Metal
-
Others
-
-
Product Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Containers
-
Trays
-
Bottles & Jars
-
Boxes & Cartons
-
Bags & Pouches
-
Films & Wraps
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Dairy Products
-
Meat, Poultry & Seafood
-
Baked Goods
-
Fruit & Vegetables
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
Southeast Asia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Frequently Asked Questions About This Report
The global frozen food packaging market size was valued at USD 50.8 billion in 2025 and is estimated at USD 53.7 billion in 2026
The global frozen food packaging market is expected to grow at a CAGR of 5.8% from 2026 to 2033, reaching USD 79.7 billion
The Asia Pacific market dominated with a revenue share of approximately 42.0% in 2025.
The plastic segment accounted for the largest revenue share of 59.0% in 2025
Key players in the market are Sonoco Products Company, Sealed Air, ProAmpac, Printpack, SÜDPACK, Amcor Plc, WestRock Company, Huhtamaki Oyj, Smurfit Westrock, Tetra Pak International S.A., Transcontinental Inc., Toyo Seikan Group Holdings, Ltd., and others.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


