
- Home
- »
- Clinical Diagnostics
- »
-
Genetic Testing Market Size, Share & Trends Report, 2033GVR Report cover

Genetic Testing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (NGS, PCR-based Testing, Array Technology), By Application, By Product, By Channel (Online, Offline), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$14.3BMarket Estimate, 2026
$17.4BMarket Forecast, 2033
$73.4BCAGR, 2026–2033
22.8%Genetic Testing Market Summary
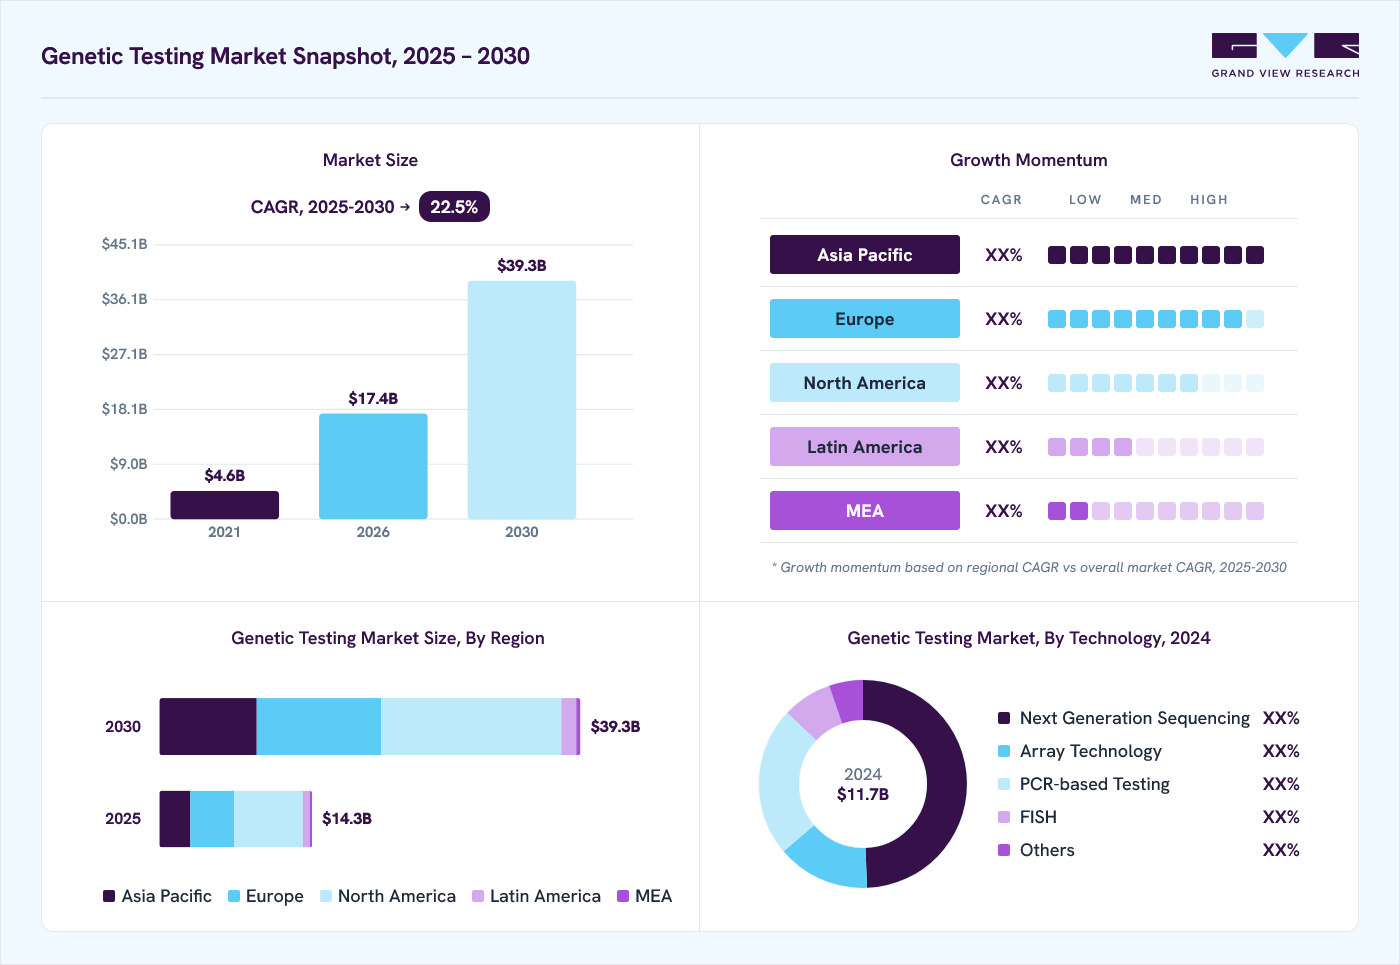
The global genetic testing market size was valued at USD 14.3 billion in 2025 and is projected to grow from USD 17.4 billion in 2026 to USD 73.4 billion by 2033, growing at a CAGR of 22.8% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 45.0% in 2025. The growing demand for newborn screening is likely to fuel the market for the genetic testing industry. In the United States, for example, newborn screening programs evaluate infants for over 60 different conditions, as highlighted by the American Association for Clinical Chemistry.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Next generation sequencing segment held the largest share of 50.1% in 2025.
- By application: Health and wellness-predisposition/risk/tendency segment held the largest share of 53.2% in 2025.
- By product: Consumables segment led the market with the largest revenue share of 60.4% in 2025.
- By channel: Offline segment led the market with the largest revenue share of 61.9% in 2025.
- By end-use: Hospitals and clinics segment led the market with the largest share of 43.5% in 2025.
Regional Highlights
- Largest regional market: North America (45.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 14.3 Billion
- Estimated market size in 2026: USD 17.4 Billion
- Projected market size by 2033: USD 73.4 Billion
- CAGR (2026-2033): 22.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The U.S. Department of Health and Human Services maintains a Recommended Uniform Screening Panel (RUSP), which lists specific genetic disorders that are recommended for mandatory screening. These recommendations are based on prior data on disease prevalence and incidence, supporting the push for early detection and intervention. Pharmacogenomics testing is increasingly vital in helping clinicians choose the most effective medications and appropriate dosages for patients. The Association for Molecular Pathology (AMP) has made strides toward standardizing these tests across laboratories. In August 2022, the AMP released recommendations for designing and validating clinical genotyping assays for genes like NUDT15 and TPMT. These guidelines provide a minimum set of alleles for labs to identify patients who may have a higher risk of thiopurine toxicity, thereby improving treatment safety and efficacy.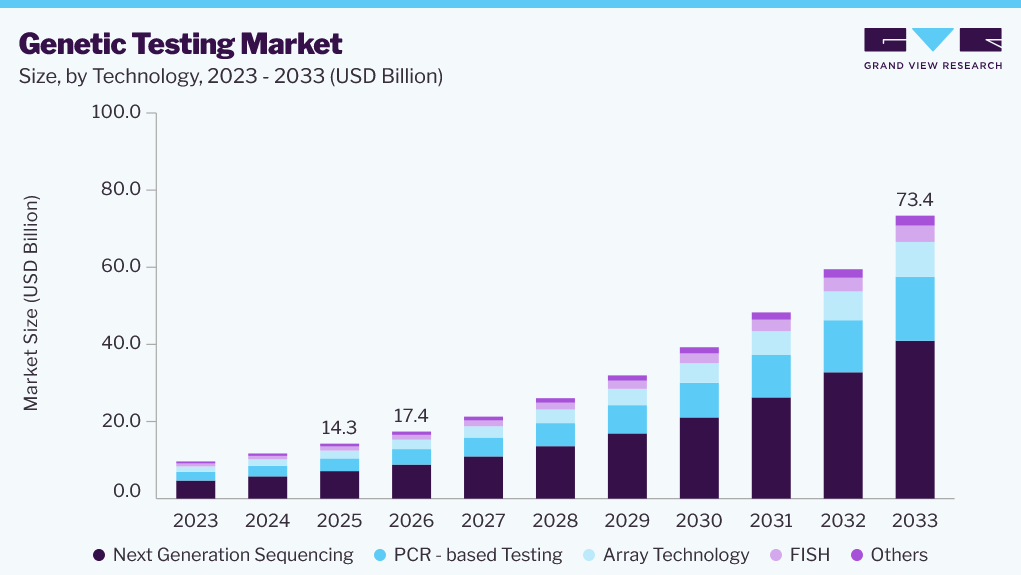 To learn more about this report, Download Free Sample Report
Pharmacogenomics testing is increasingly vital in helping clinicians choose the most effective medications and appropriate dosages for patients. The Association for Molecular Pathology (AMP) has made strides toward standardizing these tests across laboratories. In August 2022, the AMP released recommendations for designing and validating clinical genotyping assays for genes like NUDT15 and TPMT. These guidelines provide a minimum set of alleles for labs to identify patients who may have a higher risk of thiopurine toxicity, thereby improving treatment safety and efficacy.
The COVID-19 pandemic severely impacted public health systems and economies globally, yet it has spurred a moderate positive effect on the genetic testing industry. Researchers, for example, have used genotoxic testing to study the efficacy of drugs against COVID-19. In September 2020, a research team evaluated Chloroquine (CQ) and Hydroxychloroquine (HCQ) for potential use as prophylactic agents against the virus, highlighting the role of genetic toxicology tests in drug assessment, which is likely to contribute to stable market growth post-pandemic.
Despite these advancements, the high cost of genetic testing may impede market growth in developing countries. Depending on the test's complexity, costs can range from under $100 to over $2,000, and higher costs are associated with tests requiring multiple family samples. Results may also take weeks to arrive. In some instances, health insurance covers these tests when prescribed by a medical professional, but coverage varies widely across insurers and policies.
Market Dynamics
The genetic testing market is experiencing steady expansion as healthcare systems increasingly integrate genomic information into routine clinical decision making across oncology, rare diseases, reproductive health, and pharmacogenomics. Advances in sequencing technologies, broader clinical evidence supporting precision medicine, and growing adoption of companion diagnostics are improving the value of genetic testing in disease prevention, diagnosis, and treatment selection. At the same time, regulatory developments continue to shape commercialization strategies and laboratory operations across major markets. For instance, in March 2025, the U.S. District Court for the Eastern District of Texas vacated the FDA's laboratory developed test final rule, reaffirming that oversight of laboratory developed genetic tests remains under the Clinical Laboratory Improvement Amendments framework, providing greater regulatory clarity for laboratories offering genomic testing services. Industry participants are also strengthening testing capabilities through strategic collaborations and product innovation to expand access to clinically validated assays. These developments, together with increasing physician awareness and broader integration of genomic data into healthcare pathways, continue to support sustainable market growth while encouraging investment in advanced testing technologies and precision medicine applications.
The increasing integration of genetic testing into clinical decision making is a major driver of market growth as healthcare providers increasingly rely on genomic information to improve diagnosis, treatment selection, and disease management. The growing use of companion diagnostics in oncology, pharmacogenomics in medication optimization, and genomic screening for rare diseases is strengthening the clinical value of genetic testing across healthcare systems. Advances in sequencing technologies and expanding evidence supporting personalized medicine are encouraging hospitals, laboratories, and pharmaceutical companies to incorporate genetic testing into routine care pathways. For instance, in May 2026, Myriad Genetics received FDA approval for its MyChoice CDx as a companion diagnostic for Zejula in advanced ovarian cancer, further expanding the role of clinically validated genomic testing in targeted therapy selection while also strengthening the adoption of companion diagnostics in precision oncology. Such developments continue to reinforce confidence among clinicians and support sustained demand for genetic testing solutions.
Despite continued technological progress, the genetic testing market faces challenges due to inconsistent reimbursement policies and varying coverage criteria across healthcare systems. Many advanced genomic tests remain subject to payer specific evidence requirements, resulting in delayed adoption and restricted patient access, particularly for broad panel testing and preventive genetic screening. Smaller healthcare providers also face constraints related to test affordability, interpretation expertise, and integration of genomic data into clinical workflows. These factors can limit the routine use of genetic testing outside specialized centers despite growing clinical evidence. In addition, differences in national regulatory and reimbursement frameworks create variability in market penetration across regions, requiring diagnostic companies to generate additional clinical utility and health economic evidence before achieving broad commercialization. As a result, reimbursement uncertainty continues to influence purchasing decisions, laboratory investment, and the pace of adoption across several genetic testing applications.
Artificial intelligence is creating new opportunities for the genetic testing market by improving the speed, scalability, and accuracy of genomic data interpretation. As sequencing volumes continue to increase, laboratories and healthcare providers are seeking advanced analytical platforms capable of reducing interpretation time while supporting more consistent clinical reporting. AI enabled solutions also facilitate decentralized testing models by allowing genomic data generated at local laboratories to be interpreted using centralized knowledge platforms. For instance, in April 2025, GeneDx announced its acquisition of Fabric Genomics to combine genomic sequencing capabilities with artificial intelligence powered interpretation, enabling decentralized genomic testing and expanding access to genomic analysis across healthcare systems worldwide. This trend is expected to improve operational efficiency, strengthen diagnostic confidence, and accelerate the broader adoption of genomic testing in routine clinical practice.
Analyst Perspective
The genetic testing market is expected to witness sustained growth, driven by the increasing adoption of precision medicine, expanding clinical applications of genomics, and rising demand for early disease detection and personalized healthcare. Genetic testing serves as an essential tool for identifying inherited disorders, assessing disease risk, guiding targeted therapy selection, supporting reproductive health, and optimizing medication management through pharmacogenomics. The market is benefiting from continued advancements in next generation sequencing, polymerase chain reaction technologies, microarray platforms, and bioinformatics, which are improving testing accuracy, scalability, and clinical utility. Furthermore, growing integration of companion diagnostics into oncology care, increasing availability of direct to consumer genetic testing services, expanding physician awareness, and strengthening investments in genomic research are supporting market development. Ongoing improvements in genomic data interpretation, artificial intelligence enabled analytics, laboratory automation, and broader incorporation of genetic testing into routine clinical practice and preventive healthcare strategies are expected to strengthen the market's long term growth outlook.
Technology Insights
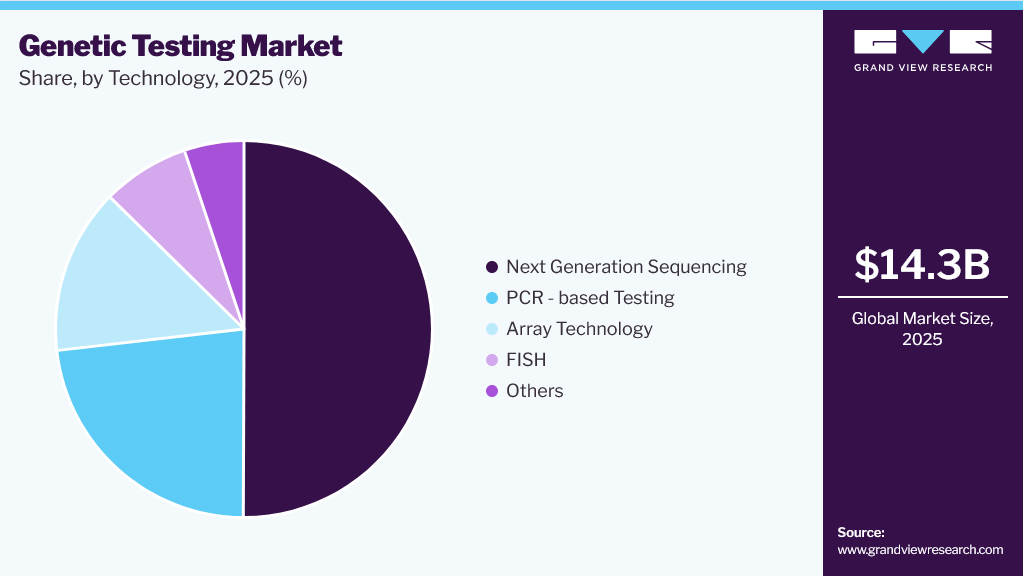
Based on technology, the next generation sequencing segment led the market with the largest revenue share of 50.1% in 2025. The expansion of genetic testing is being driven by an increase in genome mapping initiatives, higher healthcare spending, advancements in technology, and broader applications of next-generation sequencing (NGS). DNA sequencing is increasingly utilized to identify and analyze various cancers and genetic disorders, with tumor DNA sequencing playing a critical role in detecting unique DNA changes. This insight into genetic alterations supports the development of precisely targeted treatment plans, making genetic testing essential in both clinical and research settings as the incidence of cancer and genetic disorders rises.
 To learn more about this report, Download Free Sample Report
The array technology segment is expected to grow at a significant CAGR during the forecast period. This growth is fueled by the rising incidence of cancer, which has increased the adoption of DNA-based arrays in diagnosing genetic diseases and advancing personalized medicine. Arrays allow for the simultaneous analysis of thousands of gene sequences, making them highly valuable for early-stage cancer detection, gene expression studies, and drug discovery.
Application Insights
Based on application, the health and wellness-predisposition/risk/tendency segment led the market with the largest revenue share at 53.2% in 2025. This trend reflects the growing demand for predictive genetic testing and consumer wellness genomics, driven by a heightened focus on healthy lifestyles and increased healthcare awareness. Genetic testing is highly beneficial for assessing potential disease risks and understanding genetic information, including a child’s genetic makeup. It is especially valuable for individuals with a family history of genetic disorders. Nonetheless, the industry faces challenges such as the high cost of genomic research equipment and the complexity of predictive and wellness genomics, which may limit growth.
The genetic disease carrier status segment is also expected to grow at a significant CAGR over the forecast period. Carrier testing evaluates ancestral DNA to identify potential genetic conditions, making it increasingly popular as the field of genetics advances. As a result, demand for carrier testing is likely to increase, further supporting overall genetic testing industry growth.
Product Insights
The consumables segment led the market with the largest revenue share at 60.4% in 2025. The consumables market is poised for strong growth, driven by the consistent demand for reagents and accessories essential in testing processes. Many companies in this sector are pursuing both organic and inorganic strategies to expand their product lines and broaden their geographic reach.
The software & services segment is also expected to experience at a substantial CAGR during the forecast period, largely fueled by strategic investments from contract research organizations (CROs). For instance, in January 2022, Inotiv Inc. enhanced its toxicology research capabilities by acquiring an Integrated Laboratory System (ILS) for USD 56 million. This acquisition is anticipated to expand Inotiv’s capacity and foster growth in in-vivo and in-vitro toxicology services. In addition, the increasing array of services, including those in skin and genetic testing, further supports growth in this segment.
Channel Insights
Based on channel, the offline segment led the market with the largest revenue share of 61.9% in 2025. The rapid development of molecular genetic testing technologies has significantly expanded the genetic testing industry. This progress has also spurred the growth of private diagnostic laboratories offering diverse solutions. A notable trend in molecular-based testing services is the availability of buccal swab collection kits, and saliva-based tests sold over-the-counter in pharmacies, providing convenient options for consumers.
The online channel is expected to exhibit at the fastest CAGR of during the forecast period. This growth is driven by increased research funding in molecular biology, the rising popularity of direct-to-consumer testing, and greater awareness and acceptance of personalized medicine. Direct-to-consumer companies leverage both online and over-the-counter (OTC) channels to offer accessible genetic testing solutions. In 2020, online channels accounted for 77.8% of the global direct-to-consumer market, while OTC sales comprised 22.2%. By 2030, online channels are anticipated to dominate further, capturing 80% of the genetic testing industry share.
End-use Insights
Based on end-use, the hospitals and clinics segment led the market with the largest revenue share at 43.5% in 2025. The genetic testing industry is being propelled by mandatory newborn screening for genetic disorders and a growing prevalence of cancer across various regions. In the U.S., approximately 98% of births occur in hospitals, and an increase in hospital and clinic capacities is expected to further drive testing demand. Supporting this growth, the Australian government announced a healthcare budget of USD 70.12 billion for 2022-2023, marking a 5.7% increase from the previous year, with USD 26.27 million dedicated specifically to expanding newborn screening programs.
The adoption of telehealth and in-hospital services is also fueling market expansion. For instance, in December 2021, Intermountain, a U.S.-based healthcare company, reported an increase in telehealth visits from 7,000 in March 2020 to over 73,000 monthly. This shift was implemented across 225 clinics, 25 hospitals, and affiliated partner hospitals, reflecting a broader trend toward telehealth in healthcare.
The diagnostic laboratories segment is expected to grow at the significant CAGR over the forecast period, driven by increased partnerships and collaborations with genetic testing companies. For instance, Thermo Fisher Scientific supports laboratories in conducting genetic research by providing advanced technologies like next-generation sequencing (NGS) and quantitative PCR. These collaborations enable diagnostic labs to enhance their testing capabilities and expand their service offerings, contributing to the overall market growth.
Regional Insights
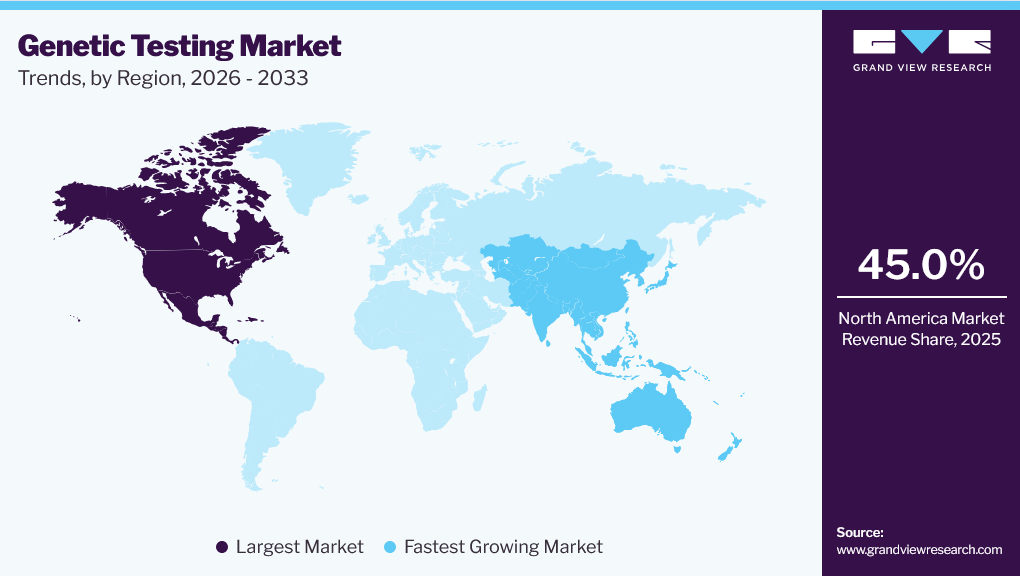
North America genetic testing market accounted for the largest revenue share of 45.0% in 2025 and is anticipated to grow at fastest growth over the forecast period. The rising demand for diagnostic services is largely driven by the growing prevalence of chronic illnesses and the advancement of diagnostic technologies. In addition, the increasing cases of infectious diseases, such as tuberculosis, HIV, and influenza, is expected to heighten the need for effective detection and treatment options. This demand is further supported by well-established healthcare infrastructure and government funding for research in the region, which together are anticipated to bolster market growth.
 To learn more about this report, Download Free Sample Report
U.S. Genetic Testing Market Trends
The genetic testing market in the U.S. held the largest share in the North America region in 2025, driven by combination of factors, including increasing awareness of the benefits of early disease detection, advancements in molecular biology, and a growing emphasis on personalized medicine.
Europe Genetic Testing Market Trends
The genetic testing market in Europe is likely to emerge as a lucrative region in the industry. Advances in genetic testing technologies, such as next-generation sequencing (NGS), have made testing more accurate, accessible, and cost-effective, fueling demand across both clinical and research settings. Furthermore, government initiatives and funding for genetic research and healthcare improvements, along with an increased focus on preventative care and early diagnosis, are accelerating market expansion.
The UK genetic testing market is projected to grow at the fastest CAGR during the forecast period. The UK government's commitment to healthcare innovation, including funding for genomic research and initiatives like the 100,000 Genomes Project, is accelerating the development and use of genetic testing. In addition, the increasing prevalence of genetic diseases and the growing adoption of direct-to-consumer genetic testing are further contributing to market expansion.
The genetic testing market in France is expected to grow at a steady CAGR over the forecast period, driven by advancements in medical research, an increasing focus on personalized healthcare, and rising awareness of genetic disorders. The French healthcare system is placing greater emphasis on precision medicine, which is driving the demand for genetic testing services, especially for oncology, hereditary diseases, and prenatal testing.
The Germany genetic testing market is projected to expand at a significant CAGR during the forecast period. The country's strong healthcare infrastructure and commitment to integrating genomic technologies into clinical practice are driving the adoption of genetic testing, particularly for oncology, rare diseases, and prenatal screening. Government funding for genomics research and the expansion of healthcare initiatives aimed at early disease detection further support market growth.
Asia Pacific Genetic Testing Market Trends
The genetic testing market in Asia Pacific is expected to experience at the fastest CAGR over the forecast period. The growing prevalence of chronic and genetic diseases, along with the rising demand for personalized medicine, is fueling the need for genetic testing services. Governments in several countries are also supporting the market by funding genomics research and integrating genetic testing into public health programs. Furthermore, the increasing adoption of direct-to-consumer genetic testing and the expansion of healthcare access in emerging economies are contributing to the overall market growth in the Asia Pacific region.
The China genetic testing market is projected to expand at a significant CAGR throughout the forecast period, driven by several key factors, including increasing healthcare investments, rising prevalence of genetic disorders, and advancements in medical research. The Chinese government is actively promoting the development of precision medicine and genomics research, which is driving the demand for genetic testing services.
The genetic testing market in Japan is anticipated to grow at the fastest CAGR during the forecast period, due to advancements in genomic research, increasing demand for personalized medicine, and a rising focus on preventive healthcare. The Japanese government has made significant investments in genomic healthcare, promoting initiatives to integrate genetic testing into public health programs and clinical practice.
Latin America Genetic Testing Market Trends
The genetic testing market in Latin Americais expected to experience at a significant CAGR throughout the forecast period. There is a growing demand for genetic testing services, particularly in countries with stronger healthcare infrastructure, like Brazil and Argentina. The expanding adoption of personalized medicine, coupled with government initiatives to enhance healthcare access and funding for genetic research, is further supporting the market. Moreover, the rising middle class, increasing healthcare investments, and greater access to direct-to-consumer genetic tests are fueling market expansion across the region.
The Brazil genetic testing market is anticipated to grow at the fastest CAGR during the forecast period, mainly due to increasing demand for personalized medicine, rising awareness of genetic disorders, and advancements in healthcare technology.
The genetic testing market in Saudi Arabia is anticipated to experience at a substantial CAGR during the forecast period. Saudi Arabia's government is actively supporting genetic research and the integration of genomic technologies into healthcare systems, aiming to improve early disease detection and personalized treatments. With a growing incidence of genetic disorders and chronic diseases, there is an increasing demand for genetic testing, particularly for prenatal screening, oncology, and rare diseases.
Key Genetic Testing Company Insights
The global genetic testing industry is highly competitive, with numerous players striving to maintain market leadership through innovation, product diversification, and strategic investments. These companies boast extensive product portfolios, a broad geographic presence, and robust distribution networks, allowing them to cater to a wide range of customer needs across both clinical and direct-to-consumer markets. To stay ahead of the competition, many industry leaders have made substantial investments in research and development, enabling them to introduce advanced and cutting-edge genetic testing solutions. These efforts not only enhance their market position but also drive the continuous evolution of the industry, meeting the growing demand for personalized medicine, early disease detection, and genomic research. For instance, in June 2023, Devyser announced the launch of LynchFAP and BRCA PALB2 which are used in Lynch syndrome diagnosis and cancers.
Key Genetic Testing Companies:
The following key companies have been profiled for this study on the genetic testing market.
-
24 genetics
-
Circle DNA
-
Tellmegen
-
23andme
-
AncestryDNA
-
MyDNA
-
Everly Well
-
Igenomix
-
VitaGen
-
Myriad Genetics, Inc.
-
Mapmygenome
-
Helix OpCo LLC
-
MyHeritage Ltd.
-
Illumina, Inc.
-
Color Genomics, Inc.
-
Amgen, Inc.
-
Beyond Nutrition Health and Wellness Services DMCC
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well Established Players (Illumina, Myriad Genetics, Quest Diagnostics, Labcorp, Eurofins Scientific, Fulgent Genetics, Natera)
- Focus on expanding comprehensive genetic testing portfolios across oncology, reproductive health, rare diseases, pharmacogenomics, and carrier screening using next generation sequencing, PCR, microarray, and bioinformatics platforms. Emphasize continuous product innovation, regulatory approvals, clinical evidence generation, reimbursement expansion, strategic collaborations with pharmaceutical companies, hospitals, and healthcare providers, and investment in laboratory automation to strengthen market presence.
- Strong global distribution networks, established laboratory infrastructure, extensive clinical validation, broad test portfolios, advanced sequencing capabilities, recognized brands, and long standing relationships with healthcare providers and pharmaceutical companies. Ability to scale testing volumes while supporting precision medicine and companion diagnostic applications.
- High capital investment requirements for advanced sequencing infrastructure, dependence on reimbursement policies and regulatory approvals, pricing pressure in mature markets, and increasing competition from specialized genomic testing companies. Maintaining continuous innovation and expanding clinical evidence require substantial long term investments.
Emerging & Regional Players (MapmyGenome, Helix, Color Health, CircleDNA, 24Genetics, tellmeGen, MyHeritage, Igenomix, Gene Solutions)
- Focus on expanding direct to consumer genetic testing, preventive health screening, reproductive genetics, ancestry testing, and AI enabled genomic interpretation. Emphasize digital health platforms, personalized wellness solutions, regional expansion, partnerships with healthcare providers, and affordable testing services to improve accessibility and consumer engagement.
- Flexibility in addressing regional healthcare needs, competitive pricing, digital first business models, personalized customer engagement, and rapid adoption of consumer focused genetic testing services. Strong ability to introduce specialized offerings and expand through strategic collaborations and technology driven service delivery.
- Limited international brand recognition, smaller laboratory capacity, restricted reimbursement coverage, and lower investment resources compared with global leaders. Dependence on regional regulatory approvals, consumer awareness, and external partnerships may slow broader market expansion and international commercialization.
Recent Developments
-
In October 2024, EpiMedTech announced launch of epiGeneComplete which is a complete profile test providing insight into aging, metabolism issues, inflammation, stress, and more. The test uses NGS platform along with DNA methylation & SNP markers for higher accuracy
-
In November 2024, ProPhase Labs, Inc announced that they have launched DNA Complete, Inc which will be a wholly owned subsidiary offering D2C DNA tests
-
In November 2024, Myriad Genetics, Inc. launched SneakPeek which is a at home gender test and available across 8800 retailers across the U.S.
Genetic Testing Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 14.3 billion
Market size value in 2026
USD 17.4 billion
Revenue forecast in 2033
USD 73.4 billion
Growth rate
CAGR of 22.8% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, application, product, channel, end-use, regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
24Genetics, CircleDNA, tellmeGen, 23andMe, AncestryDNA, MyDNA, Everlywell, Igenomix, VitaGen, Myriad Genetics, Inc., Mapmygenome, Helix OpCo LLC, MyHeritage Ltd., Illumina, Inc., Color Genomics, Inc., Amgen Inc., Beyond Nutrition Health and Wellness Services DMCC
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Genetic Testing Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global genetic testing market report on the basis of technology, application, product, channel, end-use and region:
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Next Generation Sequencing
-
Array Technology
-
PCR-based Testing
-
FISH
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Ancestry & Ethnicity
-
Traits Screening
-
Genetic Disease Carrier Status
-
New Baby Screening
-
Health and Wellness-Predisposition/Risk/Tendency
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Consumables
-
Equipment
-
Software & Services
-
-
Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Online
-
Offline
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals & Clinics
-
Diagnostic Laboratories
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
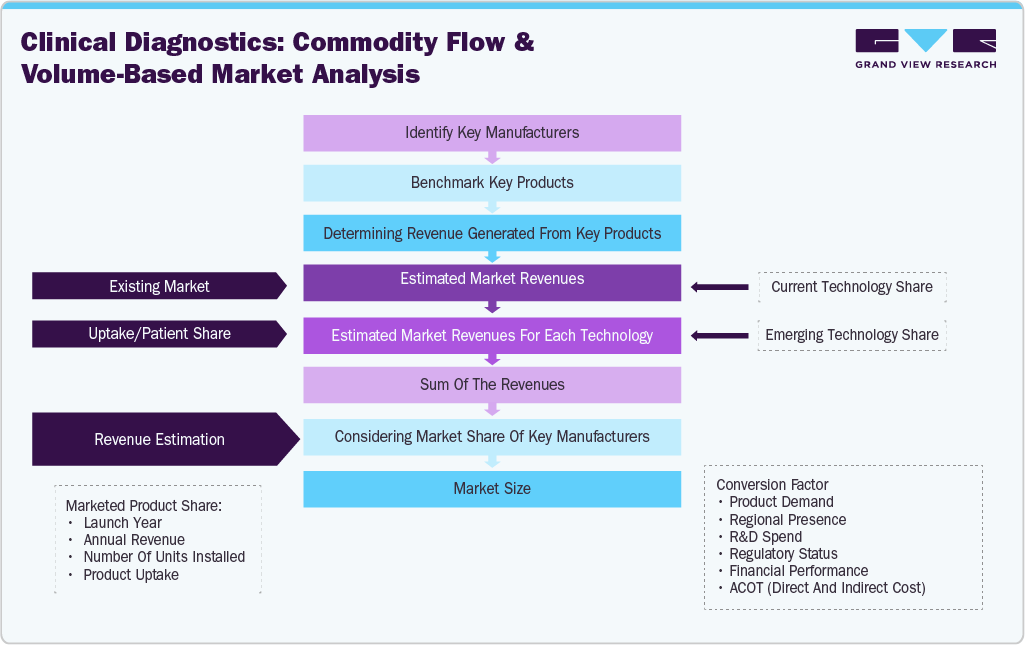
The genetic testing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each genetic testing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment
Revenue Capture Definition
Next Generation Sequencing (NGS)
Revenue is primarily derived from high throughput sequencing tests that simultaneously analyze multiple genes, exomes, or whole genomes for clinical diagnostics, reproductive testing, oncology, rare disease detection, and research applications.
Array Technology
Market value is captured through chromosomal microarray and SNP array tests used to detect copy number variations, chromosomal abnormalities, and genetic polymorphisms across prenatal, postnatal, oncology, and constitutional disorder testing.
PCR-Based Testing
Revenue flows from targeted genetic assays using polymerase chain reaction technologies for mutation detection, genotyping, inherited disorder testing, pharmacogenomics, and confirmation of known genetic variants in clinical settings.
FISH
Demand is driven by fluorescence based cytogenetic testing that identifies chromosomal rearrangements, gene amplifications, deletions, and translocations for cancer diagnostics, prenatal testing, and inherited chromosomal disorder assessment.
Others
Revenue encompasses specialized genetic testing technologies including Sanger sequencing, MLPA, digital PCR, Southern blotting, and emerging molecular techniques serving niche clinical and research applications.
Segment
Revenue Capture Definition
Ancestry & Ethnicity
Market value is captured through consumer genetic tests that determine ancestral origin, ethnic composition, geographic lineage, and family heritage using inherited DNA markers and population reference databases.
Traits Screening
Revenue originates from genetic tests evaluating inherited non disease related characteristics including nutrition response, fitness potential, metabolism, physical appearance, and lifestyle associated genetic traits.
Genetic Disease Carrier Status
Demand is generated through carrier screening tests that identify pathogenic variants linked to inherited recessive and X linked disorders, supporting reproductive planning and family risk assessment.
New Baby Screening
Revenue is captured from genetic screening conducted in newborns to detect inherited metabolic, endocrine, hematologic, and congenital disorders that require timely medical intervention after birth.
Health and Wellness – Predisposition, Risk, or Tendency
Revenue flows from predictive genetic tests that assess inherited susceptibility to multifactorial diseases and health conditions, supporting preventive healthcare strategies and personalized risk management.
Segment
Revenue Capture Definition
Consumables
Revenue is primarily derived from recurring sales of reagents, sequencing kits, extraction kits, assay cartridges, enzymes, primers, probes, and other disposable materials required throughout genetic testing workflows.
Equipment
Market demand is driven by capital purchases of sequencing instruments, PCR systems, microarray scanners, FISH imaging systems, automated extraction platforms, and laboratory hardware supporting genetic analysis.
Software & Services
Revenue is captured through bioinformatics software, genomic interpretation platforms, laboratory information systems, cloud analytics, maintenance, consulting, validation, and outsourced genetic testing services.
Segment
Revenue Capture Definition
Online
Revenue is generated through genetic tests ordered via company websites, digital health platforms, telehealth services, and direct to consumer channels with home sample collection and remote report delivery.
Offline
Market value is captured through genetic testing accessed via hospitals, clinics, diagnostic laboratories, pharmacies, physician offices, and other physical healthcare facilities requiring direct patient interaction.
Segment
Revenue Capture Definition
Hospitals & Clinics
Revenue is primarily derived from genetic testing prescribed or performed within hospitals and specialty clinics for disease diagnosis, treatment selection, prenatal care, oncology, and inherited disorder management.
Diagnostic Laboratories
Revenue flows from independent, reference, and specialized molecular laboratories providing high volume genetic testing services for hospitals, physicians, healthcare providers, and direct to consumer testing companies.
Others
Market value is captured through genetic testing conducted by academic and research institutions, public health laboratories, pharmaceutical and biotechnology companies, contract research organizations, and employer wellness programs.
Estimation Model
The genetic testing market is expected to witness sustained growth, driven by the increasing adoption of genomics in clinical decision making, expanding applications across oncology, reproductive health, rare diseases, pharmacogenomics, and preventive healthcare, and rising awareness of personalized medicine. Genetic tests play a critical role in disease diagnosis, carrier screening, risk assessment, treatment selection, and inherited disorder management, supporting more precise and timely healthcare interventions. The market is benefiting from continuous advancements in next generation sequencing, polymerase chain reaction technologies, microarrays, bioinformatics platforms, and artificial intelligence enabled genomic interpretation, which are improving testing accuracy, turnaround time, and accessibility. In addition, expanding clinical evidence, increasing availability of direct to consumer genetic testing services, growing integration of companion diagnostics into targeted therapy, and broader utilization of genomic testing within healthcare systems are supporting market expansion. Favorable investments in precision medicine initiatives, ongoing product innovation, and strengthening collaborations between diagnostic companies, healthcare providers, and pharmaceutical organizations are expected to further accelerate adoption, supporting the long term growth of the global genetic testing market.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Genetic Testing Market Competitive Landscape & Market Assessment
Assessed the global genetic testing market landscape, covering next generation sequencing, PCR based testing, microarray technology, FISH, direct to consumer genetic testing, clinical genetic testing, carrier screening, pharmacogenomics, ancestry testing, and companion diagnostics. Analyzed leading market participants, technology adoption trends, regulatory developments, reimbursement landscape, commercialization strategies, and competitive positioning across hospitals, diagnostic laboratories, and consumer health channels.
Helped the client identify growth opportunities across clinical and consumer genetic testing, evaluate competitive positioning, benchmark commercialization capabilities, and prioritize investments in precision medicine, genomic diagnostics, digital health integration, and expanding genetic testing applications across major healthcare markets.
Genetic Testing Technology & Product Benchmarking Study
Delivered a comprehensive benchmarking of genetic testing technologies including next generation sequencing, PCR based testing, microarray platforms, fluorescence in situ hybridization, bioinformatics software, laboratory automation, and direct to consumer testing solutions. Evaluated analytical performance, clinical utility, workflow efficiency, scalability, turnaround time, regulatory status, and product differentiation among leading market participants.
Enabled the client to assess technology competitiveness, identify innovation gaps, benchmark product development strategies, and prioritize investments in sequencing platforms, genomic data interpretation, artificial intelligence enabled analytics, laboratory automation, and next generation genetic testing solutions.
Genetic Testing Commercialization & Market Access Assessment
Assessed diagnostic laboratory infrastructure, hospital adoption, reimbursement frameworks, regulatory environments, physician acceptance, digital health integration, distribution channels, and commercialization pathways supporting genetic testing adoption. Evaluated patient access considerations, clinical implementation challenges, laboratory workflow requirements, and expansion opportunities across developed and emerging healthcare markets.
Supported commercialization planning by identifying market access opportunities, evaluating partnerships with healthcare providers, diagnostic laboratories, pharmaceutical companies, and payers, assessing reimbursement and regulatory considerations, mitigating operational risks, and strengthening long term scalability and adoption potential within the genetic testing market.
Frequently Asked Questions About This Report
The global genetic testing market size was valued at USD 14.3 billion in 2025 and is estimated at USD 17.4 billion in 2026.
The global genetic testing market is expected to grow at a compound annual growth rate of 22.8% from 2026 to 2033 to reach USD 73.4 billion by 2033.
North America dominated the genetic testing market with a share of 45.0% in 2025. This is attributable to increasing technological developments in sequencing, decreasing costs of sequencing, and growing awareness about the benefits of genetic testing.
Some key players operating in the genetic testing market include 24 genetics; Circle DNA; Illumina Inc.; tellmegene; 23andme; AncestryDNA; MyDNA; Everly Well; Igenomix; VitaGen; and Myriad Genetics, Inc.;
Key factors that are driving the market growth include factors such as increasing awareness of newborn screening and the rising prevalence rate of genetic disorders are directly impacting the market growth.
The genetic testing market in Asia Pacific is expected to experience at the fastest CAGR during the forecast period. The growing prevalence of chronic and genetic diseases, along with the rising demand for personalized medicine, is fueling the need for genetic testing services.
The consumables segment led the market with the largest revenue share at 60.4% in 2025. The consumables market is poised for strong growth, driven by the consistent demand for reagents and accessories essential in testing processes.
Based on technology, the next generation sequencing segment led the market with the largest revenue share of 50.1% in 2025. The array technology segment is expected to grow at a significant CAGR during the forecast period.
Artificial intelligence is creating new opportunities for the genetic testing market by improving the speed, scalability, and accuracy of genomic data interpretation. As sequencing volumes continue to increase, laboratories and healthcare providers are seeking advanced analytical platforms capable of reducing interpretation time while supporting more consistent clinical reporting.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


