
- Home
- »
- Electronic & Electrical
- »
-
Home Water Filtration Unit Market Size Report, 2026-2033GVR Report cover

Home Water Filtration Unit Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (RO-Based, UV-Based), By Region (North America Europe, Asia Pacific, Central & South America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$21.8BMarket Estimate, 2026
$23.6BMarket Forecast, 2033
$50.9BCAGR, 2026–2033
11.6%Home Water Filtration Unit Market Summary
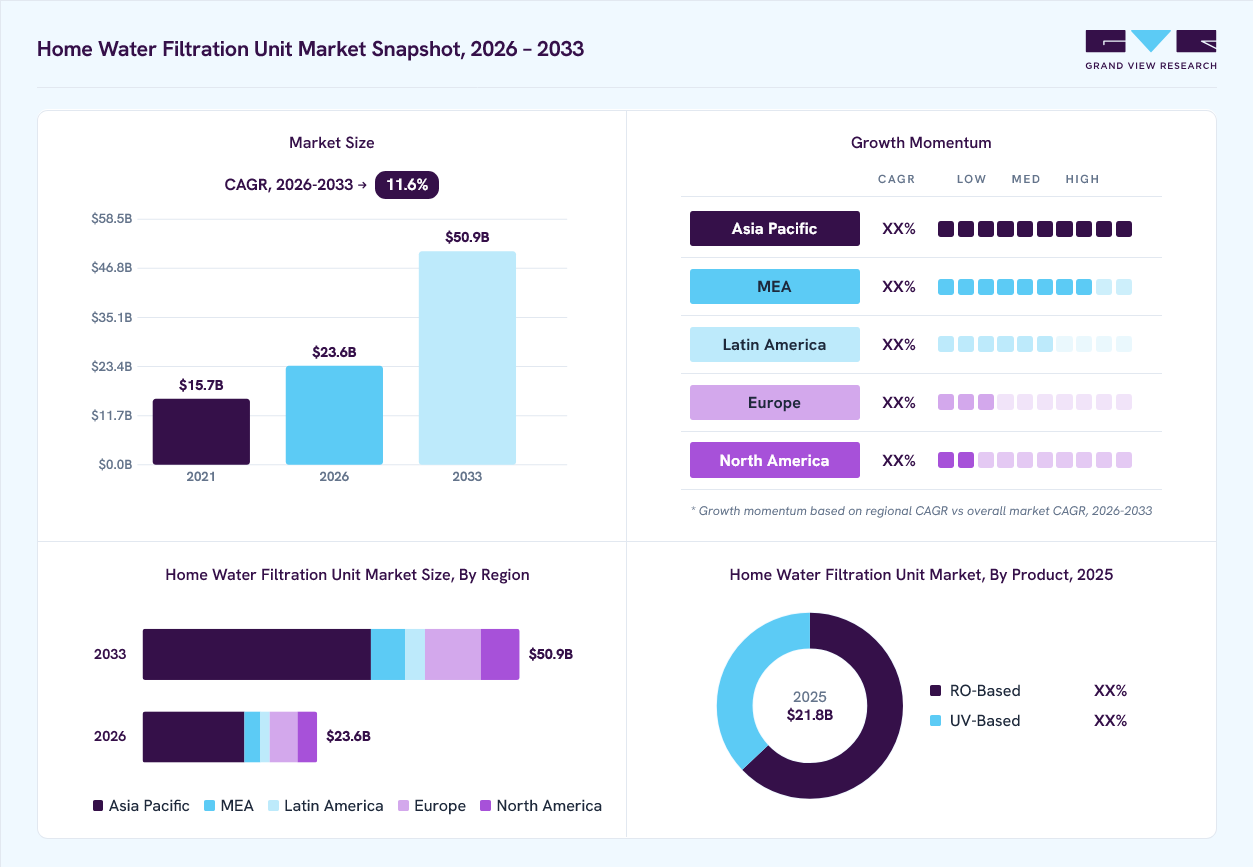
The global home water filtration unit market size was valued at USD 21.8 billion in 2025 and is projected to grow from USD 23.6 billion in 2026 to USD 50.9 billion by 2033, growing at a CAGR of 11.6% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 65.4% in 2025. This can be attributed to increasing concerns over water safety and the rising shift toward household purification systems.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: RO-based segment dominated the market, with a revenue share of 62.4% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (65.4% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 21.8 Billion
- Estimated market size in 2026: USD 23.6 Billion
- Projected market size by 2033: USD 50.9 Billion
- CAGR (2026-2033): 11.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Expanding urban adoption of RO, UV, and multi-stage units further strengthens demand. A key ongoing global trend is the rapid adoption of multi-stage, high-efficiency filtration systems, such as RO-UV-UF combinations, driven by rising awareness of contamination and stricter water quality norms across both developed and emerging regions. Consumers are increasingly replacing basic filters with advanced units that can handle heavy metals, microplastics, and chemical pollutants, reflecting a global shift toward more comprehensive and reliable household purification solutions.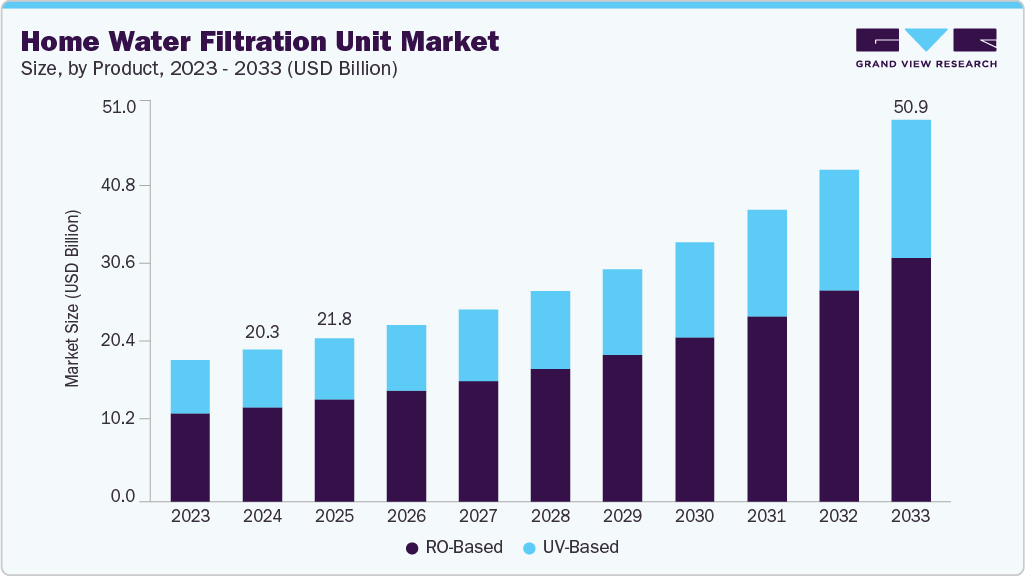 To learn more about this report, Download Free Sample Report
Global demand is primarily driven by rising concerns over water contamination, with an increasing number of households seeking reliable purification as incidents involving heavy metals, microplastics, and industrial pollutants become more widely reported. For example, growing awareness of lead-related cases in regions like the U.S. and chemical runoff issues in parts of Southeast Asia has prompted consumers to opt for certified multi-stage RO and UV systems, which ensure safer drinking water.
Another key driver is the expansion of urban middle-class populations, particularly in the Asia Pacific, where rapid urbanization puts a strain on municipal water infrastructure. Cities in India, China, and Indonesia are increasingly turning to home filtration units as everyday essentials, rather than discretionary purchases. This shift boosts sales of affordable under-sink RO units, compact countertop purifiers, and UV-based systems designed for densely populated residential environments.
The market is also propelled by technology upgrades and convenience-led innovation, with manufacturers introducing smart filters that track real-time TDS levels, send filter-replacement alerts, and optimize purification cycles. Brands offering IoT-enabled purifiers in markets such as Japan, South Korea, and the U.S. demonstrate how digital features enhance user trust and reduce maintenance friction, thereby accelerating adoption across both premium and mid-range segments. Examples include Xiaomi’s smart RO purifiers in China, Coway’s IoT-enabled models in South Korea, and Brita and A.O. Smith’s connected systems in the U.S., all of which offer filter-life tracking, real-time TDS monitoring, and automated alerts-making purification more reliable and maintenance-friendly.
Market Dynamics
The home water filtration unit market is being shaped by increasing consumer concerns over drinking water quality, aging municipal infrastructure, and the desire for convenient point-of-use purification solutions. Households are increasingly adopting filtration systems to address contaminants such as chlorine, sediment, heavy metals, pesticides, PFAS compounds, microorganisms, and unpleasant taste or odor. Demand is also being influenced by rising health awareness, urbanization, and growing distrust of untreated tap water in many regions. Technological advancements in reverse osmosis (RO), activated carbon, UV, and smart monitoring systems are further expanding product adoption across residential applications.
The primary driver for the home water filtration unit market is the growing public concern regarding the safety and quality of household drinking water. Consumers are becoming increasingly aware of contaminants that may be present in municipal and well water supplies, including lead, chlorine by-products, nitrates, microplastics, PFAS, and microbial pathogens. High-profile contamination incidents and greater access to water-quality information have heightened consumer demand for in-home treatment solutions that provide an additional layer of protection beyond municipal treatment.
Demand is particularly strong for point-of-use systems such as under-sink RO units, countertop filters, and whole-house filtration systems that can improve taste, odor, and perceived safety. The trend is further supported by increasing health-consciousness among urban households, families with children, and consumers seeking alternatives to bottled water for cost and sustainability reasons.
A major restraint in the home water filtration unit market is the total cost of ownership associated with advanced filtration systems. While entry-level pitcher filters are relatively inexpensive, higher-performance solutions such as multi-stage RO systems, UV-integrated units, and whole-house filtration systems can involve significant upfront installation costs. In addition, consumers must periodically replace filter cartridges, membranes, UV lamps, and other components to maintain performance.
Maintenance requirements can create adoption barriers, particularly in price-sensitive markets or among consumers unfamiliar with filtration technologies. Failure to replace filters on schedule may reduce filtration effectiveness, leading to concerns about reliability and product performance. These factors can slow replacement cycles and limit penetration of premium filtration systems in certain regions.
The integration of smart technologies and sustainability-focused solutions presents a significant opportunity for the home water filtration unit market. Manufacturers are increasingly introducing connected filtration systems with real-time water quality monitoring, filter-life tracking, leak detection, and mobile app integration. These features improve user convenience, optimize maintenance schedules, and enhance consumer confidence in system performance.
In parallel, growing environmental concerns are creating demand for filtration systems that reduce reliance on single-use plastic bottles and improve household water efficiency. Innovations such as low-waste RO systems, recyclable filter materials, and energy-efficient purification technologies are gaining attention. As consumers seek healthier and more sustainable water consumption habits, companies that combine advanced filtration performance with smart functionality and environmental benefits are expected to capture substantial growth opportunities.
Analyst Perspective
The home water filtration unit market is being shaped by growing consumer awareness of water quality variability rather than mere access to drinking water. Rising concerns over TDS levels, heavy metals, microbial contamination, and aging municipal infrastructure are driving demand for advanced multi-stage filtration systems. RO-based units continue to dominate in regions with poor source water quality, while UV and UF technologies are gaining traction where microbial safety is the primary concern. The market is also witnessing a shift toward smart filtration solutions with real-time filter monitoring and predictive maintenance features. Replacement cartridges and annual maintenance contracts are emerging as key revenue streams, strengthening long-term customer retention and recurring income for manufacturers.
Consumer Insights
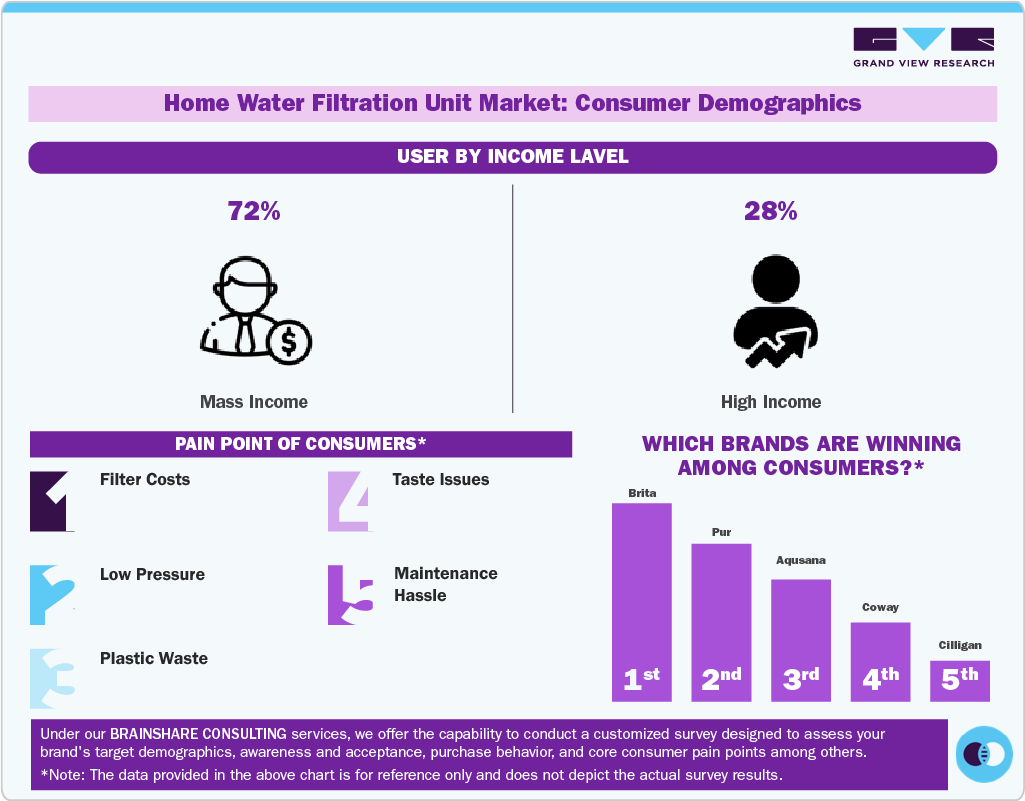
The income split shows that mass-income households (72%) make up the largest user base, as they prioritize affordable and practical solutions for safer water. These consumers generally opt for compact pitcher filters, faucet attachments, or basic under-sink units due to their lower upfront cost and wide retail availability.
The pain points reflect the most common frustrations across markets. Filter costs and maintenance hassle highlight the ongoing burden of replacement cycles. Issues such as low pressure and taste problems are tied to inconsistent municipal supplies, while plastic waste concerns are rising as consumers seek more sustainable cartridge systems.
 To learn more about this report, Download Free Sample Report
Global leaders such as Brita, Pur, Aquasana, Coway, and Culligan are winning because they address these pain points directly-offering subscription filter models, longer-life cartridges, eco-friendly materials, and higher-efficiency purification technologies. Their strong retail distribution, trust built over time, and consistent product reliability keep them ahead in consumer adoption.
Product Insights
Based on product, the RO-based segment led the market with the largest revenue share of 62.4% in 2025. The RO-based segment accounted for the largest share of the home water filtration units market due to its superior ability to remove dissolved salts, heavy metals, microorganisms, and other contaminants from drinking water. Growing concerns regarding water quality, increasing levels of groundwater contamination, and rising consumer awareness about waterborne diseases have significantly accelerated the adoption of reverse osmosis systems in residential applications.
 To learn more about this report, Download Free Sample Report
RO-based filtration units are particularly popular in regions facing issues related to high total dissolved solids (TDS), industrial pollution, and aging water infrastructure. Furthermore, continuous advancements in filtration technology, including multi-stage purification systems, smart monitoring features, and improved water recovery rates, have enhanced product efficiency and consumer acceptance. The combination of effective purification performance, increasing health consciousness, and expanding access to clean water solutions continues to support the segment’s dominant position in the global home water filtration unit’s market.
Regional Insights
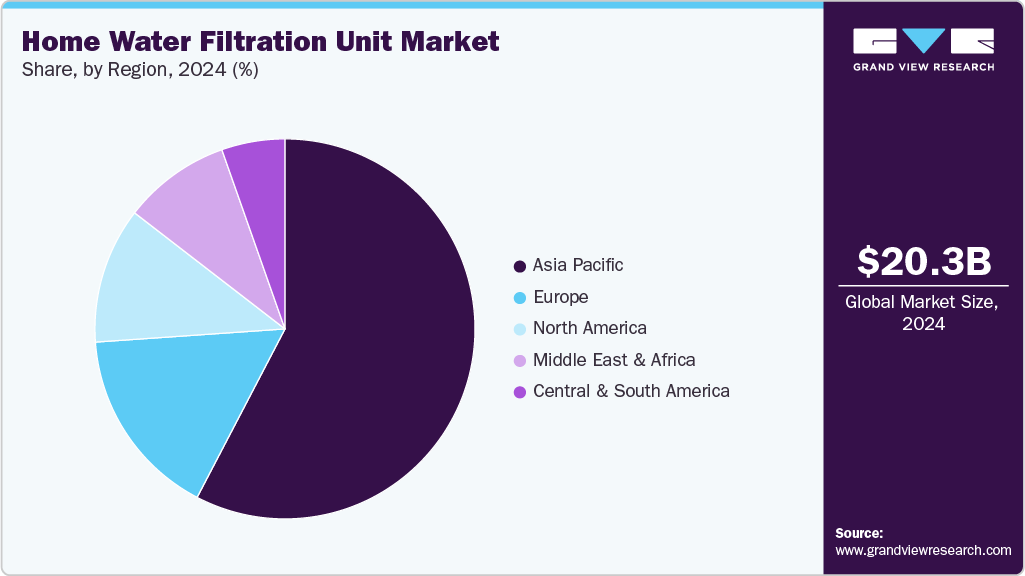
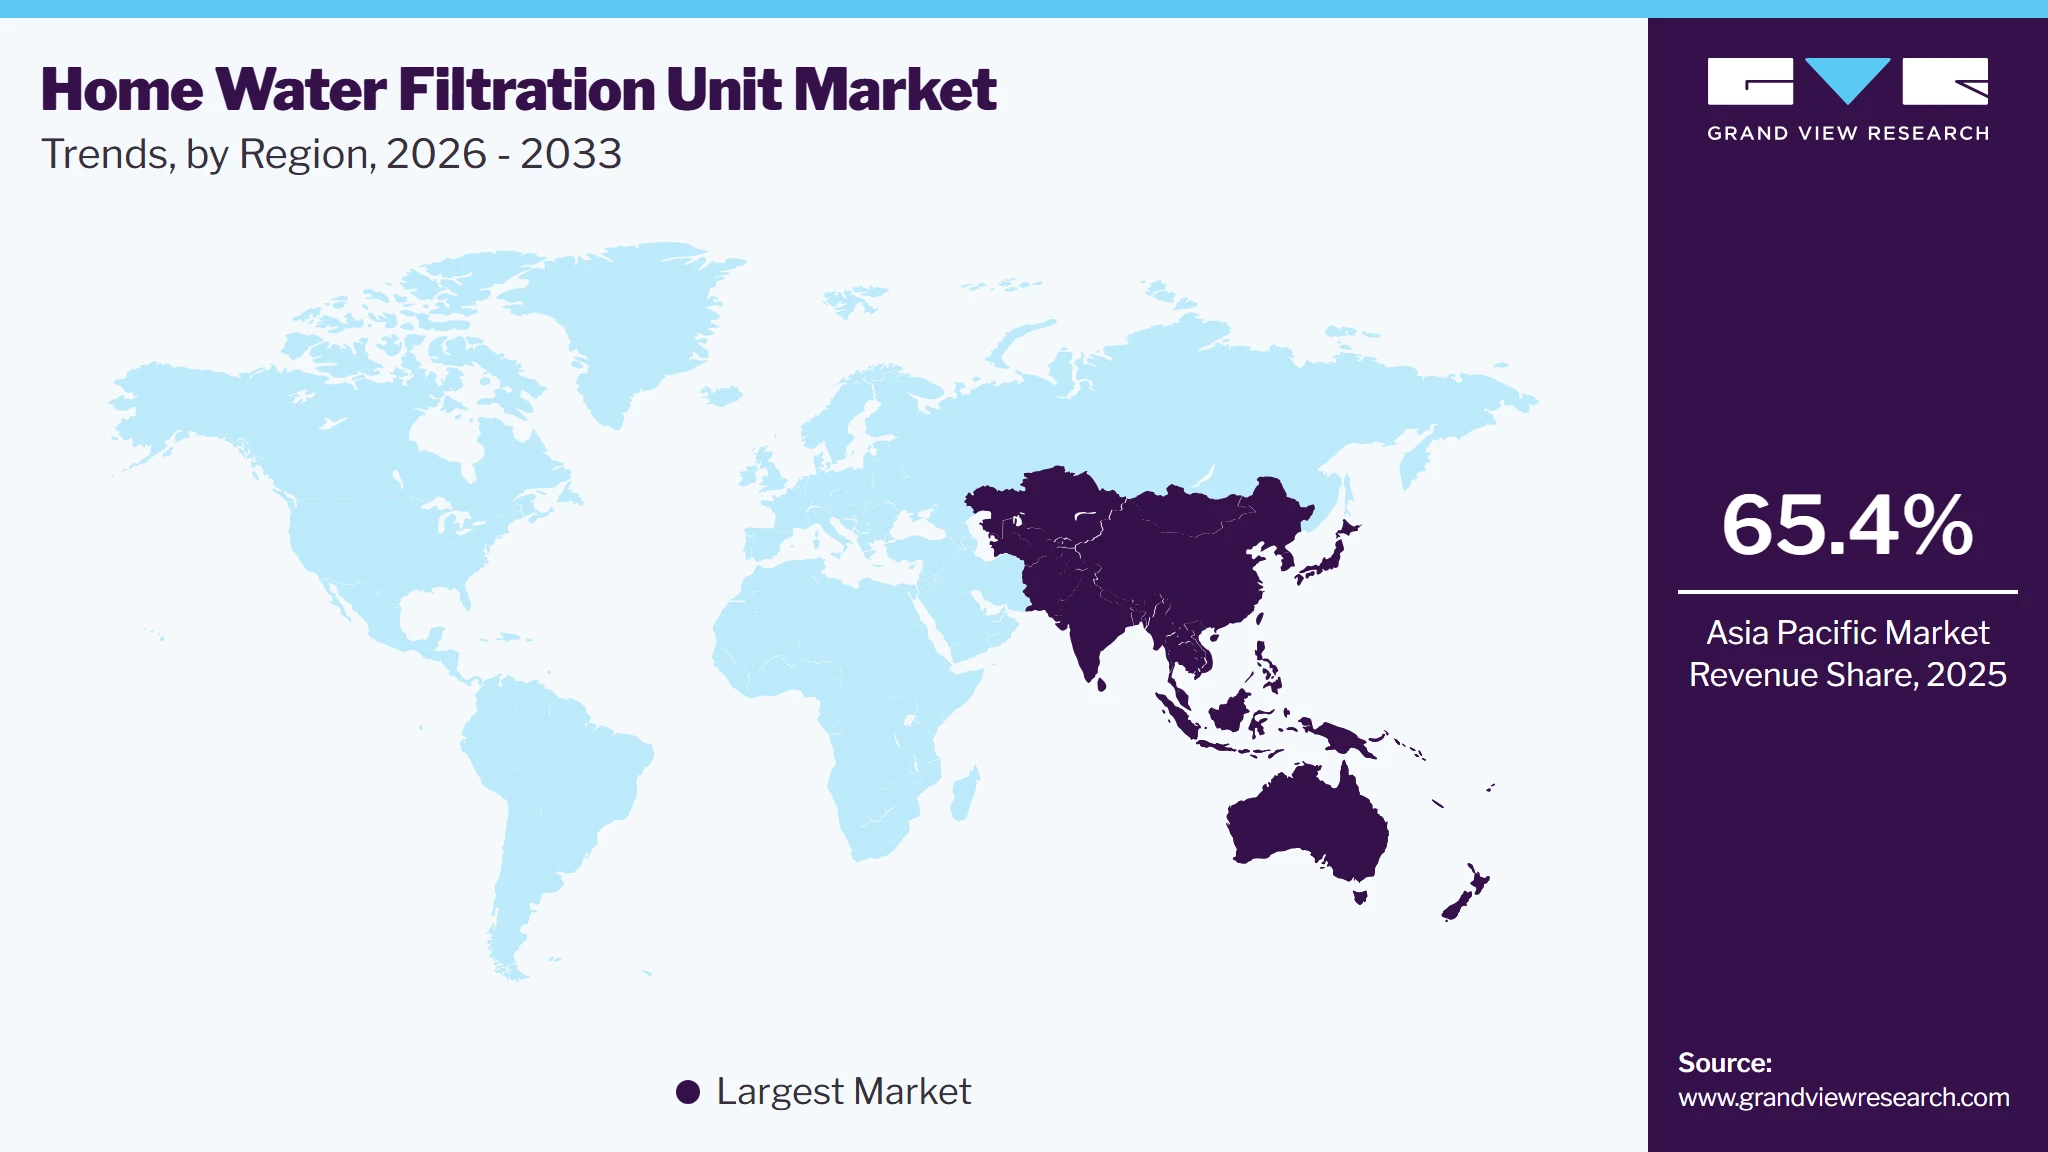
Asia Pacific dominated the home water filtration unit market with the largest revenue share of 65.4% in 2025. Asia Pacific accounted for the largest share of the home water filtration unit market, driven by rapid urbanization, rising concerns regarding drinking water quality, and increasing awareness of waterborne diseases. Growing populations in major economies such as China, India, and Southeast Asian countries have intensified demand for safe and reliable household water treatment solutions. In addition, expanding middle-class populations, rising disposable incomes, and greater adoption of health and wellness products have supported market growth. Government initiatives focused on improving water quality and access to clean drinking water have further encouraged the installation of home water filtration systems across the region.
 To learn more about this report, Download Free Sample Report
China Home Water Filtration Unit Market Trends
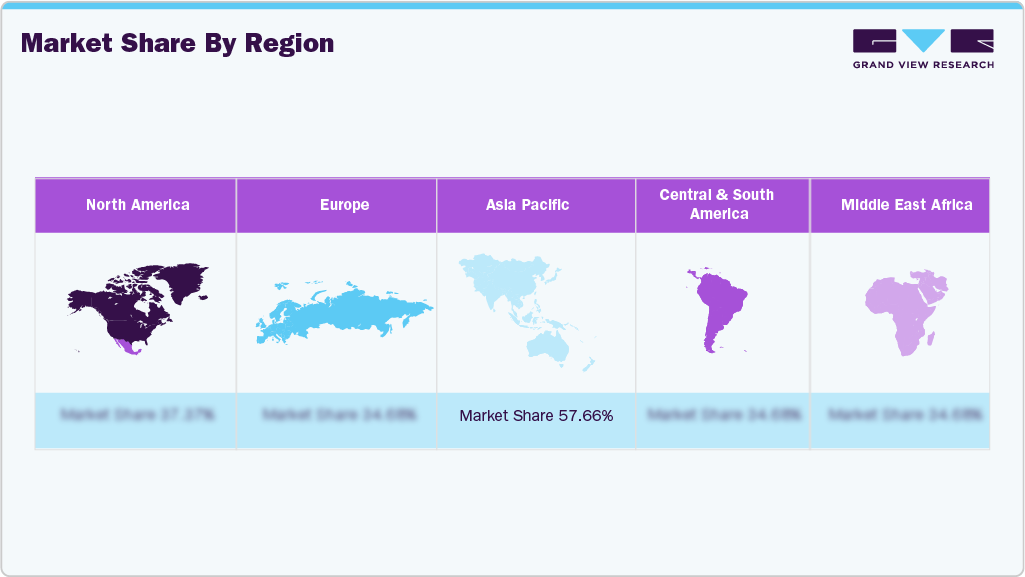
The home water filtration unit market in the China held the largest share of about 38.8% in the Asia Pacific region in 2025. China represented the largest market within Asia Pacific due to growing consumer concerns regarding tap water quality, increasing urban household penetration, and strong demand for advanced purification technologies. Rising industrialization and environmental pollution have heightened public awareness of water safety, encouraging households to invest in filtration systems that remove contaminants and improve taste. The country’s large population base, expanding middle-income consumer segment, and robust e-commerce ecosystem have further accelerated product adoption. Moreover, continuous product innovation and the availability of smart, multi-stage filtration systems have strengthened market growth across both metropolitan and emerging urban areas.
 To learn more about this report, Download Free Sample Report
North America Home Water Filtration Unit Market Trends
The Home Water Filtration Unit industry in North America is anticipated to witness a CAGR of 9.7% from 2025 to 2033. North America’s growth is driven by infrastructure-driven risks, not widespread contamination. Aging pipelines, especially in older U.S. and Canadian cities, lead to sporadic issues such as lead leaching, which prompts consumers to opt for under-sink and whole-house systems.
The rising demand for PFAS removal, unique to the U.S. regulatory climate, has triggered rapid product innovation from Aquasana and Culligan. The higher adoption of smart filtration units also shapes the market. This segment is more mature here than in APAC, with app-connected usage tracking and auto-delivery filter replacement services gaining traction.
U.S. Home Water Filtration Unit Market Trends
The U.S. Home Water Filtration Unit industry is expected to witness a CAGR of 9.4 % from 2025 to 2033. The U.S. is experiencing accelerated adoption due to regulatory tightening by the EPA on PFAS, chromium-6, and disinfection byproducts, prompting households to upgrade to NSF-certified multi-stage systems.
Growth is further pushed by the rising popularity of whole-home filtration in newly constructed suburban homes, where developers increasingly offer built-in systems as upgrades. High consumer willingness to pay for premium units from brands such as Brita Elite, Pelican, and GE Home Water differentiates the U.S. trajectory from Canada and Mexico, making its growth path distinct within North America.
Key Home Water Filtration Unit Company Insights
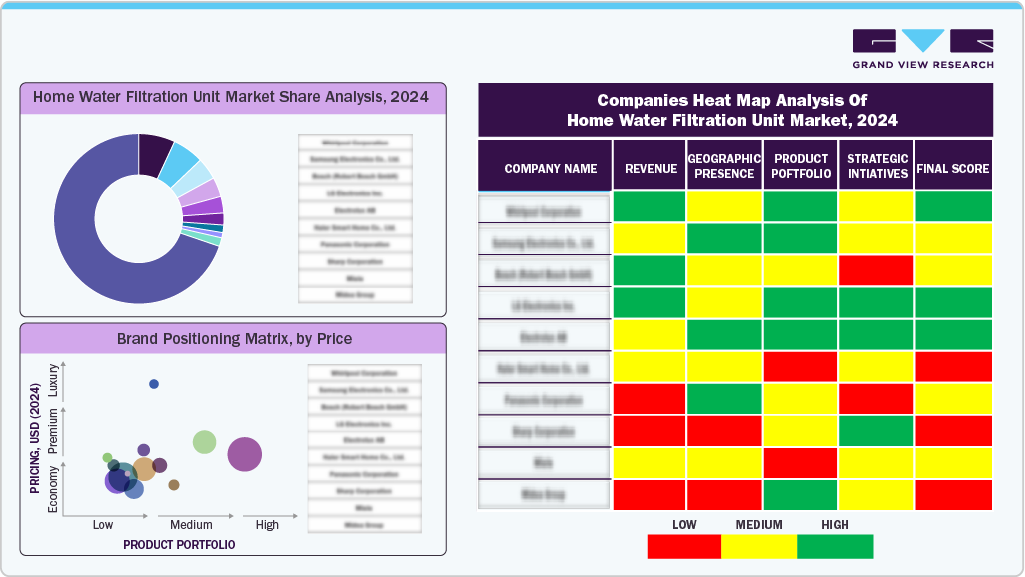
The global Home Water Filtration Unit Market is shaped by a mix of long-established purification specialists, premium innovation-driven brands, and fast-growing regional manufacturers serving different household needs.
Established players such as Brita, Pur, Culligan, and Aquasana lead the mainstream segment through strong certification standards, reliable multi-stage technologies, and widespread availability across retail and online channels. Premium brands, including Coway, Kent, and AO Smith, attract urban and health-focused consumers by offering smart connected systems, compact designs, and advanced RO and UV combinations.
Regional companies such as Midea, Xiaomi, Livpure, and Pureit are expanding rapidly in the Asia Pacific, the Middle East, and Latin America by providing affordable products tailored to local water issues, including high TDS levels and inconsistent municipal water supplies.
 To learn more about this report, Download Free Sample Report
Their strong presence on major e-commerce platforms and ability to customize features for local conditions have increased competitive intensity. This structure, which combines mass-market accessibility with technology-led premium offerings and region-specific value brands, continues to define the global competitive landscape.
Key Home Water Filtration Unit Companies:
The following key companies have been profiled for this study on the home water filtration unit market.
-
Brita
-
Pur
-
Culligan
-
Aquasana
-
Coway
-
Kent
-
AO Smith
-
Pureit (Hindustan Unilever)
-
3M Water Filtration
-
Pentair
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Brita; Culligan; Coway; AO Smith; Pentair; 3M Water Filtration)
- Expand comprehensive water treatment portfolios across point-of-use (POU) and point-of-entry (POE) systems, including RO, UV, activated carbon, and smart filtration technologies.
- Strengthen distribution through retail, direct sales, service networks, e-commerce platforms, and subscription-based filter replacement programs while investing in IoT-enabled and premium water purification solutions.
- Strong brand recognition, extensive service infrastructure, and proven expertise in water treatment technologies.
- Ability to offer end-to-end filtration solutions supported by robust R&D capabilities, certified product performance, and established customer trust in water quality and safety.
- High operating costs associated with manufacturing, certification, installation, and after-sales service networks.
- Slower adaptation to localized consumer preferences and pricing pressures in highly competitive and value-sensitive markets.
Emerging & Regional Specialists (PUR; Aquasana; Kent; Pureit (Hindustan Unilever))
- Focus on consumer-centric filtration solutions addressing specific concerns such as TDS reduction, microbial contamination, heavy metals, and affordability.
- Leverage digital marketing, direct-to-consumer channels, product innovation, and region-specific offerings to expand penetration across urban and semi-urban households.
- Greater agility in responding to changing consumer needs, regional water quality challenges, and emerging filtration trends.
- Strong positioning in targeted segments through specialized product offerings, competitive pricing, and localized brand strategies that enhance consumer engagement.
- Limited global footprint and lower diversification compared to multinational water treatment leaders.
- Dependence on specific geographic markets and consumer segments can increase vulnerability to competitive pressures, regulatory changes, and fluctuations in replacement filter demand.
Recent Developments
-
In October 2025, Xiaomi launched the Mijia Desktop Water Purifier Ice-Making Edition, a compact smart purifier that combines six-stage RO filtration with UV sterilisation, instant hot-water dispensing, and a variable-frequency ice maker. It offers app-based control, dual water tanks, and the ability to produce different ice sizes while delivering purified hot or cold water for everyday household use.
-
In October 2025, Elista entered the home water-purifier market with two new alkaline models-Amrit and Shuddh. The Amrit features a nine-stage purification process, with copper infusion, mineral restoration, instant hot-water dispensing, and a digital display; the Shuddh offers a seven-stage system in a compact design tailored for urban households.
-
In April 2025, Tappwater introduced three sustainable household filtration products in Sweden through Onlinefilter: the EcoPro Compact faucet filter with five-stage purification and significantly reduced plastic use, the ShowerPro shower filter that removes over 80 contaminants and minimizes limescale, and the PitcherPro glass jug filter that eliminates major pollutants while adding magnesium for better taste and alkalinity.
Home Water Filtration Unit Market Report Scope
Report Attribute
Details
Market size in 2025
USD 21.8 billion
Estimated market size in 2026
USD 23.6 billion
Projected market size by 2033
USD 50.9 billion
Growth rate
CAGR of 11.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, region
Regional scope
North America; Europe; Asia Pacific; MEA; and Central & South America
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Rest of Europe; China; Japan; India; South Korea; Australia & New Zealand; Rest of Asia Pacific; Brazil; Argentina; Rest of Latin America; South Africa; Israel; Rest of Middle East & Africa
Key companies profiled
Brita; Pur; Culligan; Aquasana; Coway; Kent; AO Smith; Pureit (Hindustan Unilever); 3M Water Filtration; Pentair
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Home Water Filtration Unit Market Report Segmentation
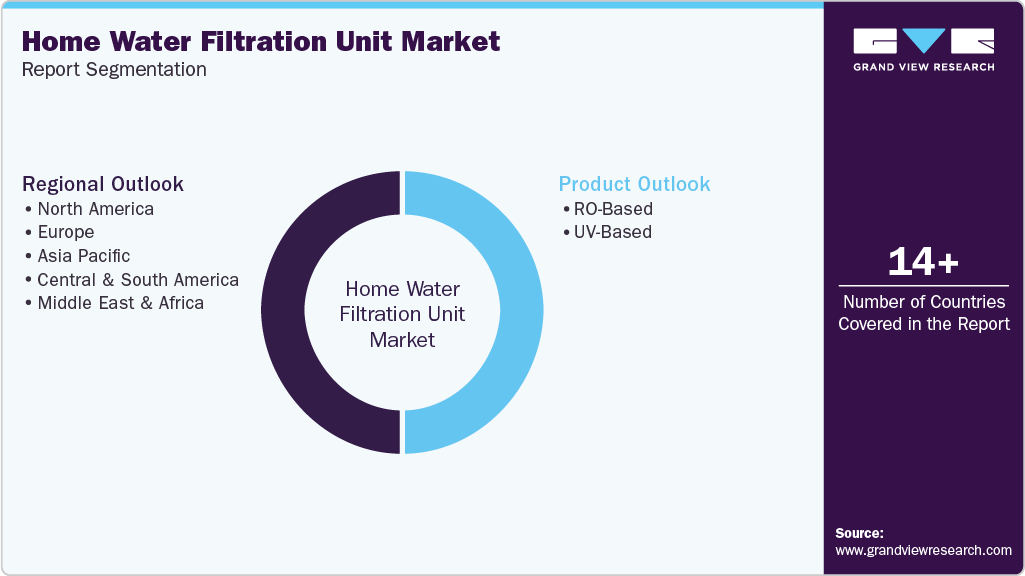
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global Home Water Filtration Unit Market report on the basis of product and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Thousand Units; Revenue, USD Million, 2021 - 2033)
-
RO-Based
-
UV-Based
-
-
Regional Outlook (Volume, Thousand Units; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia & New Zealand
-
South Korea
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
-
Research Methodology
The home water filtration market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each home water filtration segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
RO-Based
This segment covers residential water filtration units that utilize reverse osmosis membrane technology to remove dissolved solids, heavy metals, salts, nitrates, fluoride, and other contaminants from household water supplies. The scope includes under-sink, countertop, wall-mounted, and integrated RO purification systems used in apartments, independent homes, and residential complexes.
UV-Based
This segment includes home water filtration units that employ ultraviolet (UV) disinfection technology for microbial treatment of drinking water. The scope covers standalone UV purifiers as well as multi-stage systems where UV serves as the primary purification stage, encompassing household installations designed for the inactivation of bacteria, viruses, and other microorganisms in residential water sources.
Estimation Model
Layer Title
Guiding Question
Description
Household Water Risk Layer
Which households have a potential need for water purification?
Begin with the global household base and identify households relying on municipal water, groundwater, borewell water, tanker water, or other sources. Apply indicators such as water quality concerns, high TDS levels, and contamination exposure to estimate households requiring filtration solutions. Growing concerns over water safety and aging water infrastructure continue to drive demand for home filtration systems.
Accessibility & Affordability Layer
Which households can realistically purchase filtration units?
Filter the eligible household base using urbanization rates, middle-income household penetration, retail accessibility, e-commerce reach, electricity availability, and consumer purchasing power. This derives the addressable market that can access and afford home water filtration systems through organized sales channels. Urban middle-class households represent the primary addressable segment globally.
Adoption & Replacement Layer
Which households actively purchase filtration units?
Apply household adoption rates for RO-based and UV-based systems based on local water quality conditions. Incorporate first-time purchases, replacement demand, filter replacement cycles, technology upgrades, and new household formation. RO adoption is typically higher in regions with elevated TDS levels, while UV systems gain traction in areas with treated municipal water supplies.
Monetisation Layer
How much revenue is generated?
Multiply annual unit demand by blended ASPs across RO-based and UV-based filtration units. Add recurring revenue streams generated through filter replacement, annual maintenance contracts (AMCs), servicing, membrane replacement, UV lamp replacement, and extended warranties to estimate total market revenue. Recurring aftermarket revenue forms a significant portion of the value chain.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Water Quality Risk & Filtration Technology Adoption Mapping
Comprehensive assessment of household water quality challenges across major countries, including high TDS groundwater, heavy metal contamination, microbial contamination, aging municipal infrastructure, and chemical pollutants. The study maps these water conditions against adoption of RO-based and UV-based filtration systems and evaluates technology suitability by region.
Identifies where RO systems are essential due to high TDS and dissolved contaminants versus markets where UV systems are sufficient due to relatively treated municipal water supplies. Helps manufacturers prioritize product portfolios, technology investments, and country-specific go-to-market strategies.
Competitive Benchmarking of Global & Regional Water Purification Brands
Benchmarking of major filtration brands including Brita, Pur, Culligan, Aquasana, Coway, Kent, AO Smith, Pureit, Pentair, and 3M across purification technology, certification standards, filter lifespan, smart features, pricing, after-sales service, and geographic footprint.
Enables clients to understand how leading brands differentiate through purification performance, trust, service networks, smart monitoring capabilities, and subscription-based filter replacement programs. Also identifies consolidation opportunities and competitive gaps in premium and mass-market segments.
Country-Level Contamination Hotspot & Demand Forecast Analysis
Country-specific assessment of contamination hotspots, groundwater dependency, municipal water reliability, regulatory developments, and consumer awareness trends across key markets such as India, China, the U.S., Saudi Arabia, South Africa, and Brazil.
Supports market entry and expansion planning by identifying countries where water quality concerns are translating into accelerated filtration adoption and higher willingness to invest in advanced purification technologies.
Frequently Asked Questions About This Report
Asia Pacific dominated with a 34.7% revenue share in 2025.
The RO-based segment accounted for the largest volume share of 57.4% in 2025
The global home water filtration unit market is expected to grow at a CAGR of 11.6% from 2025 to 2033, reaching USD 50.9 billion by 2033.
The RO-Based segment led the market with a 62.9% revenue share in 2025. It is also expected to remain the fastest-growing product segment, registering a CAGR of 11.9% through 2033.
Key players include Brita, Pur, Culligan, Aquasana, Coway Co., Ltd., Kent RO Systems Ltd., A. O. Smith Corporation, Pureit, 3M, and Pentair plc.
Key factors include rising concerns regarding water contamination and waterborne diseases, increasing urbanization, growing consumer awareness of safe drinking water, deteriorating water infrastructure in several regions, rising adoption of point-of-use filtration systems, and increasing demand for advanced purification technologies such as RO and UV filtration.
The global home water filtration unit market size was valued at USD 21.8 billion in 2025 and is estimated at USD 23.6 billion in 2026.
About the Author(s)
Electronic & Electrical Research Team
Consumer Goods · Electronic & ElectricalThis report was authored by the electronic & electrical research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the electronic & electrical segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


