
- Home
- »
- Renewable Chemicals
- »
-
Hydroxyethyl Cellulose Market Size And Share Report, 2033GVR Report cover

Hydroxyethyl Cellulose Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Building Materials, Waterborne Paints & Coatings, Oil Fields, Food), By Region (North America, Europe, Asia Pacific, Central & South America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$950.8MMarket Estimate, 2026
$993.7MMarket Forecast, 2033
$1,332.8MCAGR, 2026–2033
4.3%Hydroxyethyl Cellulose Market Summary
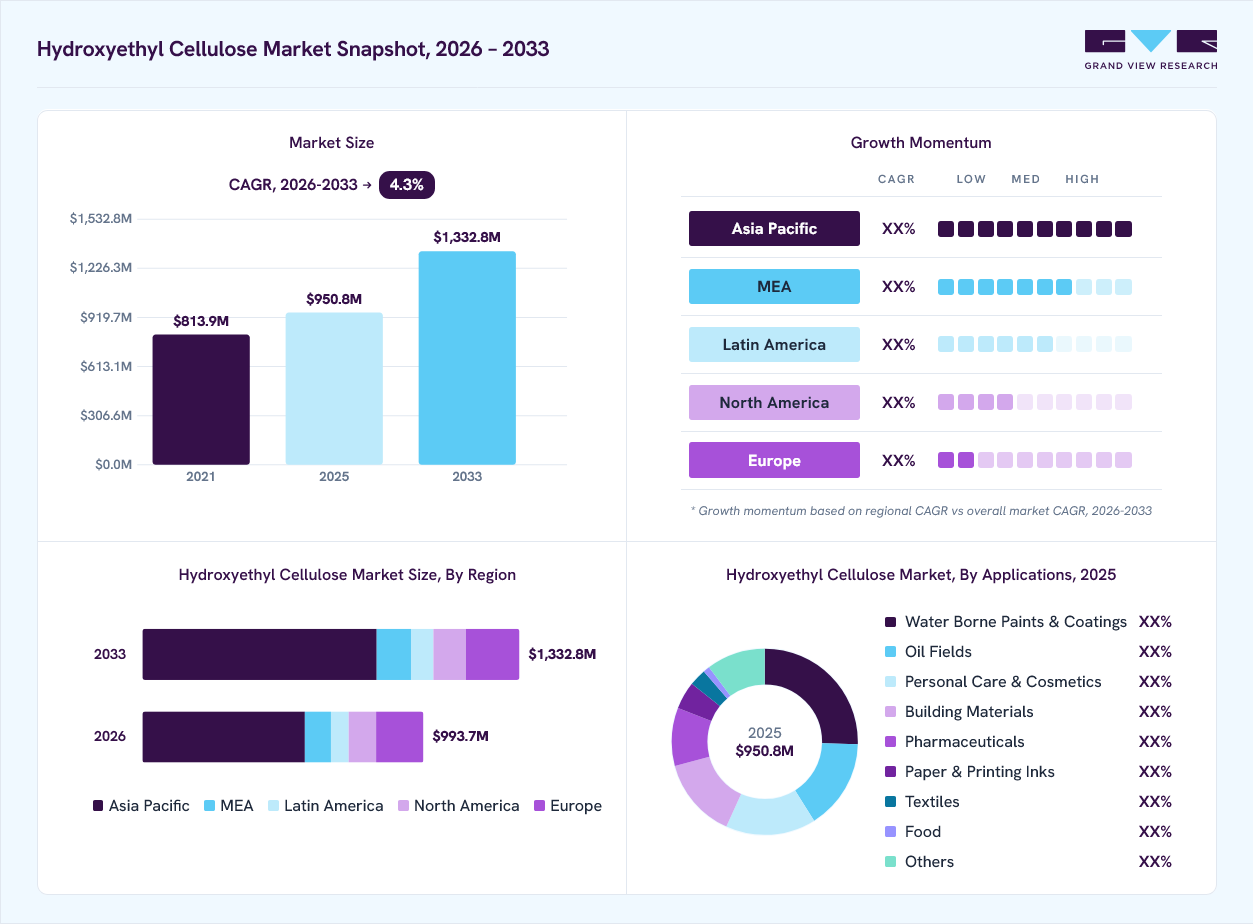
The global hydroxyethyl cellulose market size was valued at USD 950.8 million in 2025 and is projected to grow from USD 993.7 million in 2026 to USD 1,332.8 million by 2033, at a CAGR of 4.3% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 57.2% in 2025. Growing utilization of hydroxyethyl cellulose in several end-use industries such as construction, paints and coatings, textile, food, pharmaceuticals, paper and printing inks, personal care and cosmetics, and oilfields is estimated to drive the market in the near future.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Waterborne paints & coatings segment projected the largest share of 25.4% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (57.2% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 950.8 Million
- Estimated market size in 2026: USD 993.7 Million
- Projected market size by 2033: USD 1,332.8 Million
- CAGR (2026-2033): 4.3%
Prism AI by Grand View Research Free to tryAsk a question about the hydroxyethyl cellulose marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The market is highly competitive in nature, owing to the presence of a large number of players who try to gain a competitive edge over others with their product quality, superior distribution networks, and various other strategies. These companies contribute a high market share accounting for nearly 70-75%.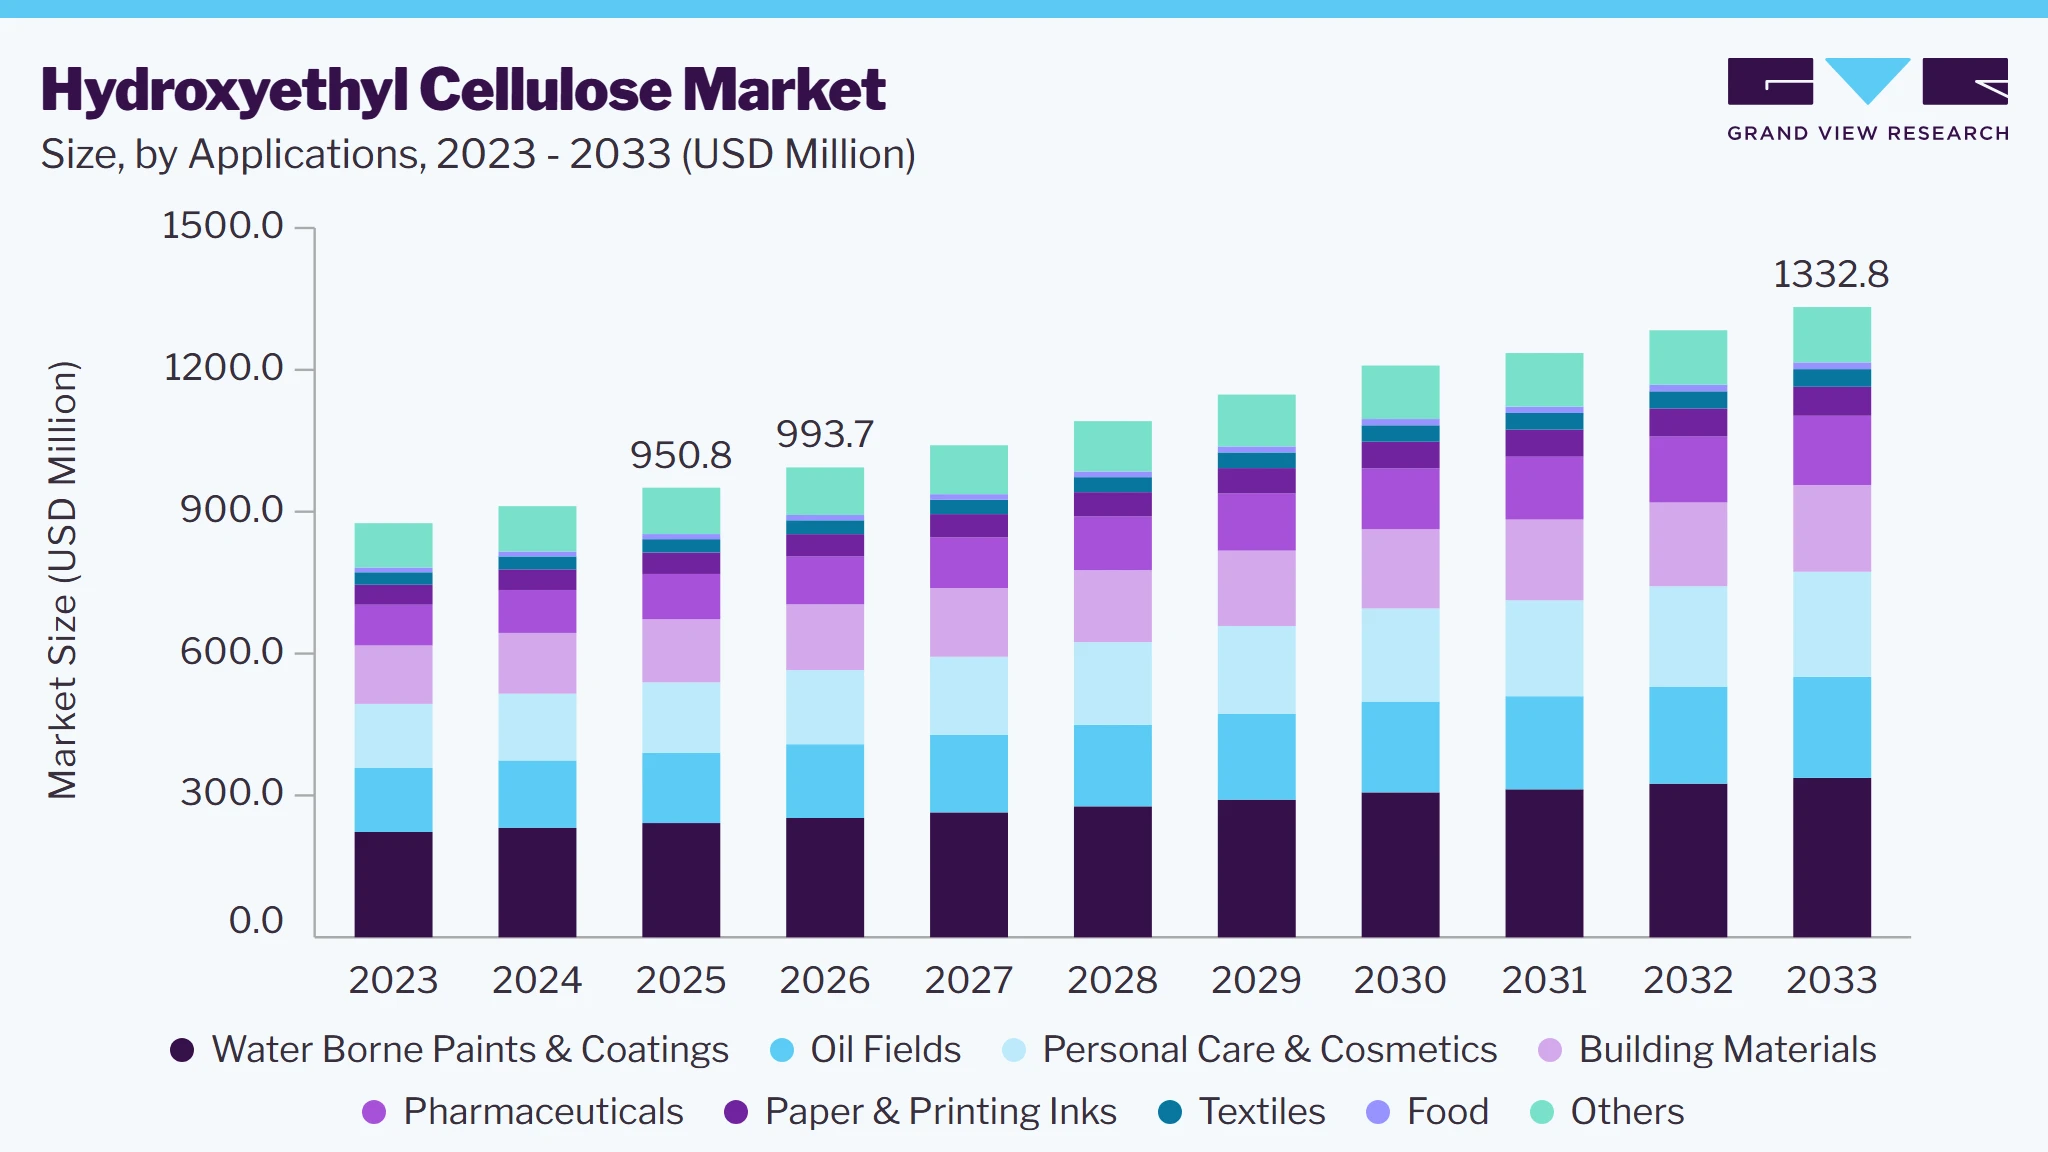 To learn more about this report, Download Free Sample Report
Top manufacturers have defined different grades of products such as pharmaceutical, application, and industrial-grade, which provide a competitive edge in the market for hydroxyethyl cellulose. Demand for hydroxyethyl cellulose is anticipated to be driven by the expanding construction and infrastructure industry and increasing oil and gas exploration activities. Similarly, the demand for building materials is expected to witness increasing consumption owing to the expanding construction industry. Similarly, consumption of water-borne paints and coatings is anticipated to increase owing to their growing consumption in architectural coatings over the forecasted period.
The regulatory framework for water borne coating is governed by the Technische Anleitung (TA), Luft environment protection act, US Environment Protection Agency, and REACH. These regulatory bodies specify the chemical and physical risks associated with the use of raw materials in the manufacturing of water borne coatings and paints and general requirements for labeling, storage, and the use of these raw materials. Rising health and environmental concerns arising from the use of hazardous textile chemicals have led to the increasing adoption of sustainable alternatives such as hydroxyethyl cellulose in the textile industry. Also, increasing awareness pertaining to the use of organic and sustainable alternatives in personal care and cosmetics products is likely to propel the product demand globally.
Market Dynamics
The hydroxyethyl cellulose market is growing due to the rising demand from construction, paints and coatings, personal care, and oilfield applications. Increasing infrastructure development and renovation activities are driving the consumption of hydroxyethyl cellulose as a thickener, water-retention agent, and rheology modifier in cement-based formulations and water-borne coatings. The expanding preference for low-VOC and environmentally compliant coatings further strengthens product adoption due to its compatibility with water-based systems. In the personal care and pharmaceutical sectors, growing demand for multifunctional, non-ionic polymers with excellent stability and formulation performance is contributing to sustained market expansion. However, fluctuations in cellulose feedstock prices, energy costs, and stringent environmental regulations governing chemical manufacturing can influence production economics and supply stability. At the same time, continuous product innovation, advancements in high-performance cellulose derivatives, and increasing industrialization across emerging economies are creating new opportunities for manufacturers.
The increasing adoption of water-borne paints and coatings is a key factor driving the growth of the hydroxyethyl cellulose market. As environmental regulations continue to encourage the use of low-VOC formulations, manufacturers are increasingly incorporating hydroxyethyl cellulose as a rheology modifier, thickener, and stabilizer to enhance product performance. Its ability to improve viscosity control, pigment suspension, and application properties makes it an essential additive in architectural and industrial coatings. Growing investments in residential, commercial, and infrastructure projects are further supporting the demand for water-based coating systems, thereby strengthening the consumption of hydroxyethyl cellulose.
In the construction industry, hydroxyethyl cellulose plays a critical role in cement-based mortars, tile adhesives, plasters, and wall putties by improving water retention, workability, and adhesion. Rapid urbanization, increasing government investments in infrastructure development, and the growing emphasis on high-performance building materials continue to accelerate product adoption. Additionally, the shift toward sustainable construction practices and energy-efficient buildings is encouraging manufacturers to develop advanced formulations, further reinforcing the market's long-term growth potential.
Fluctuations in the prices of cellulose feedstocks, energy, and chemical processing inputs remain a significant restraint for the hydroxyethyl cellulose market. Since hydroxyethyl cellulose production depends on purified cellulose and various chemical intermediates, variations in raw material availability, supply chain disruptions, transportation costs, and energy prices can substantially increase manufacturing expenses. These cost pressures often reduce profit margins for producers and create pricing uncertainties for downstream industries such as construction, paints and coatings, personal care, and pharmaceuticals. In highly competitive markets, manufacturers may find it difficult to fully transfer rising production costs to customers, resulting in margin compression and restrained investment in capacity expansion. The increasingly stringent environmental regulations governing chemical processing require continuous investment in compliance measures and cleaner production technologies, further elevating operational costs and creating challenges for small and mid-sized manufacturers.
The growing demand for premium personal care and pharmaceutical products presents a significant opportunity for the hydroxyethyl cellulose market. Hydroxyethyl cellulose is widely used in shampoos, lotions, creams, gels, toothpaste, ophthalmic solutions, and topical pharmaceutical formulations due to its excellent thickening, stabilizing, and film-forming characteristics. Rising consumer preference for high-quality personal care products with improved texture, stability, and performance is encouraging formulators to increase the use of multifunctional cellulose derivatives. Continuous innovation in cosmetic formulations and the expansion of the global beauty industry are expected to create sustained demand for hydroxyethyl cellulose.
The pharmaceutical sector is also generating new growth opportunities as manufacturers increasingly utilize hydroxyethyl cellulose in drug delivery systems, suspensions, and controlled-release formulations. Growing healthcare expenditure, expanding pharmaceutical production, and increasing investments in research and development are supporting the development of advanced formulations requiring reliable excipients.
Analyst Perspective
The hydroxyethyl cellulose market is supported by expanding demand from the construction, water-borne coatings, personal care, and pharmaceutical industries. Increasing adoption of environmentally friendly formulations and high-performance additives is strengthening the market outlook. Manufacturers are focusing on product innovation, capacity expansion, and sustainable production technologies to enhance competitiveness and meet evolving regulatory requirements. Asia Pacific remains the key growth hub, driven by rapid industrialization, infrastructure development, and expanding manufacturing activities. Companies that emphasize application-specific product development, supply chain resilience, and strategic customer partnerships are expected to strengthen their market position over the forecast period.
Application Insights
Based on application, waterborne paints & coatings segment projected the largest share of 25.4% in 2025. Its high share is attributable to the increasing usage of the product in architectural coatings intended for on-site application to interior and exterior surfaces of commercial, residential, and institutional buildings. The product provides thickness to paints and helps eliminate sagging, which is one of the most important characteristics required.
Stringent government regulations regarding VOC emissions, especially in Europe and North America, are projected to augment the growth of the water-borne coatings and paints segment. The rising trend in the automotive industry to use water borne coatings and paints in all repair work is further anticipated to propel the demand for hydroxyethyl cellulose over the coming years. The future growth of water borne paints and coatings, both in terms of volume and revenue, is highly dependent on the awareness among consumers regarding the safety of the products and the government regulations associated with them.
The oilfields segment accounted for the second-largest revenue share of 15.5% in the market for hydroxyethyl cellulose in 2021. This is attributed to the wide usage of HEC due to its properties such as thickening, lubrication suspension, and others. Hydroxyethyl cellulose is very effective in large hole drilling and spudding technologies. Using HEC with drilling fluid significantly reduces the hydrodynamic friction, which results in reduced pump pressure. It is also useful in reducing the chances of oil well leakage.
Regional Insights
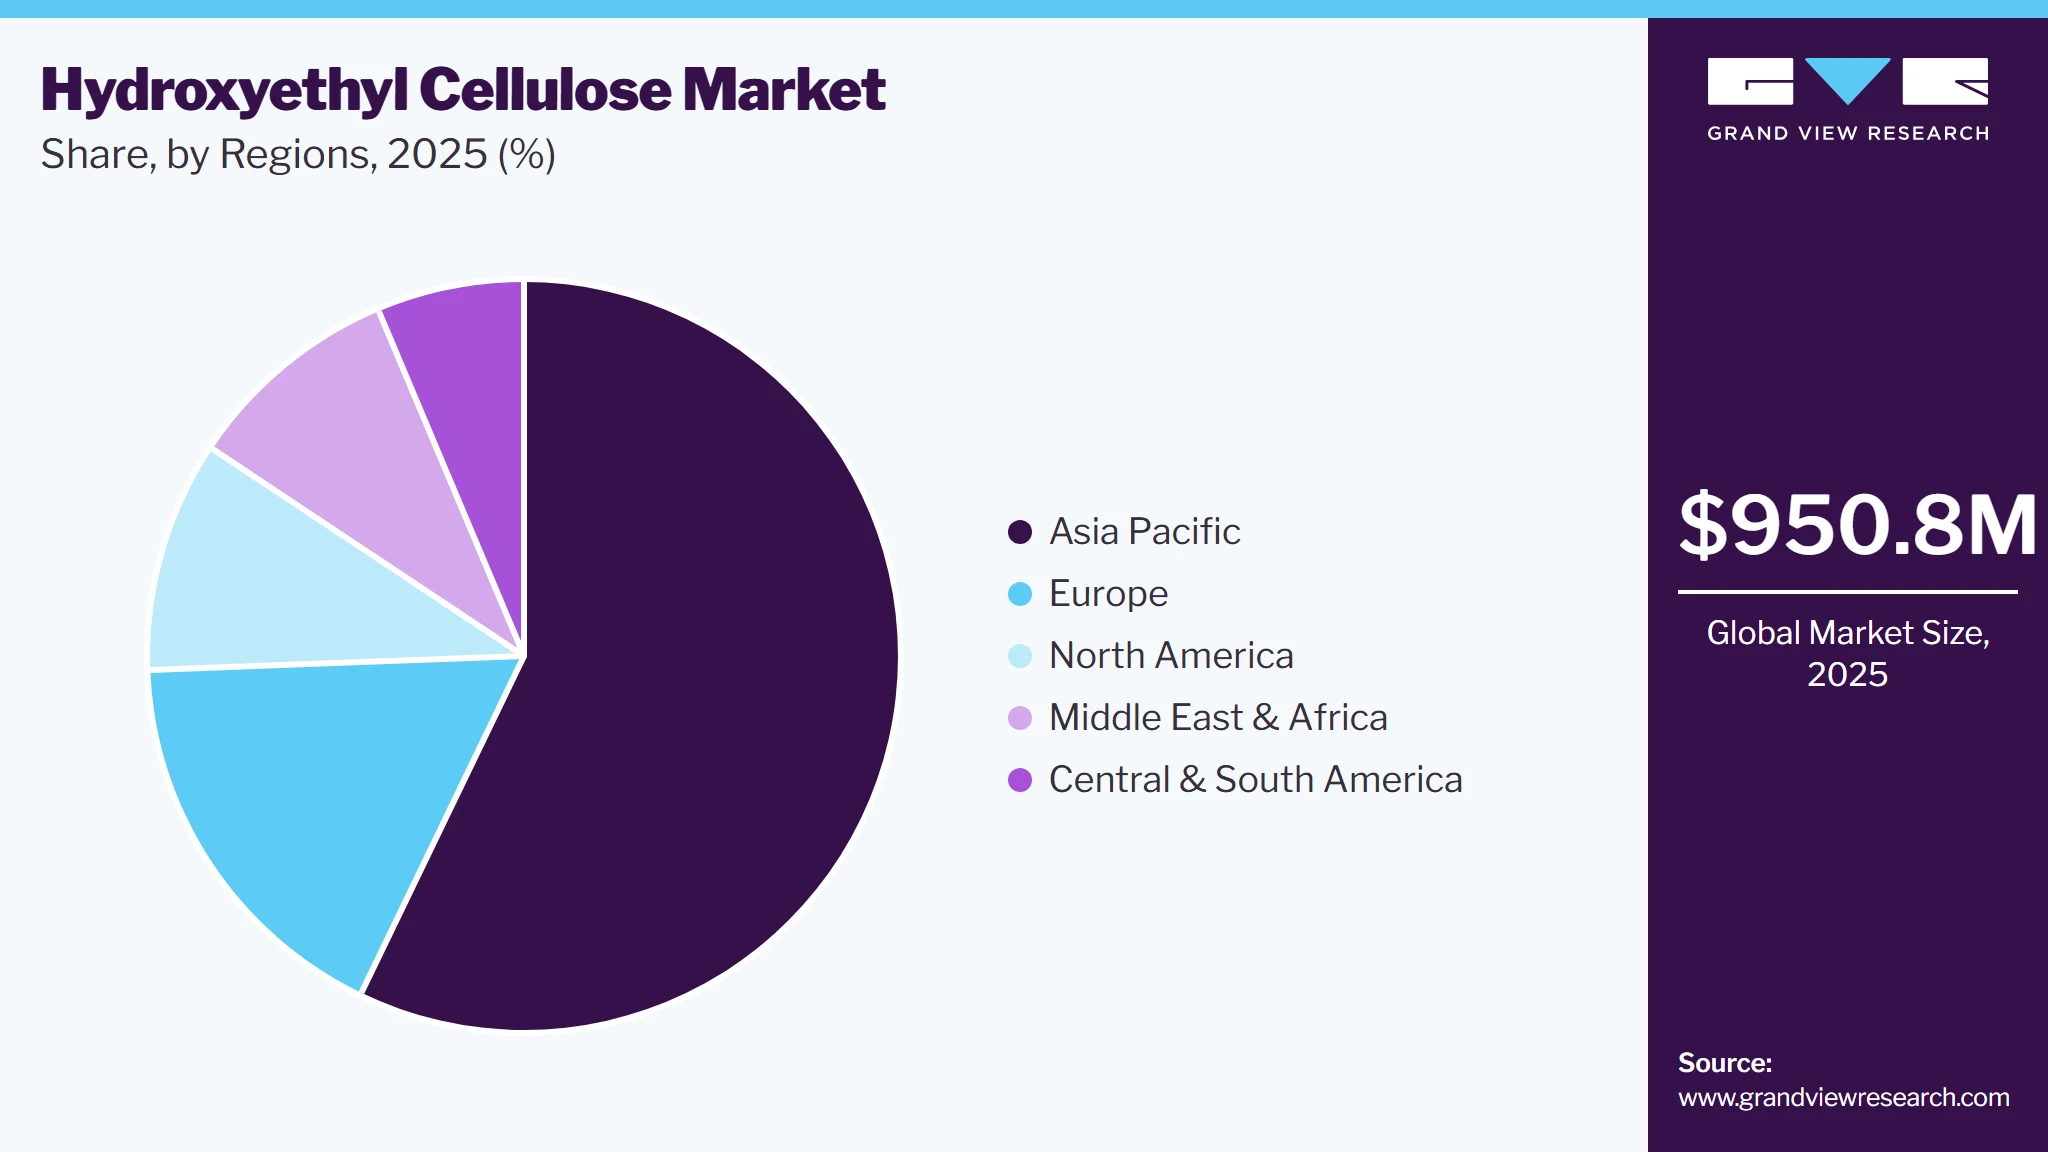
Asia Pacific accounted for 57.2% of the hydroxyethyl cellulose market revenue in 2025, making it the largest regional market. This is attributed to the growing consumption, owing to its increasing use in building material applications along with consumer preference for sustainable products. Asia Pacific is a highly import-dependent region. Although there are several market players with smaller capacities, the region is still not self-sufficient for the demand. Due to the rising demand-supply gap, market players are looking forward to expanding their production capacities across the region.
 To learn more about this report, Download Free Sample Report
China Hydroxyethyl Cellulose Market Trends
China held the highest market revenue share of the Asia Pacific in 2025. Increasing construction and infrastructure spending, particularly in countries like China, India, and Japan, is expected to drive the region’s market. Also, increasing population coupled with rising per-capita middle-class disposable income levels is expected to have a positive impact on the demand in the market for hydroxyethyl cellulose. The emergence of new industries due to low labor costs, availability of a large labor force, and government tax initiatives are expected to drive the market further. In the food industry, factors such as plastic packaging management, sugar reduction, reformulation, availability of locally sourced ingredients, use of plant-based proteins, and the rise of social commerce are anticipated to drive the market.
Europe Hydroxyethyl Cellulose Market Trends
Europe has accounted for the second-largest revenue share of the hydroxyethyl cellulose market. This is due to the presence of large food manufacturing units in the region that drive the market for hydroxyethyl cellulose. Europe is the home of major economies like Germany, France, and the U.K., with a continuously increasing number of manufacturers and suppliers of food products and beverages, cosmetics, construction, and chemical products. Awareness regarding wellness and health has swayed consumer preference towards organic products. Thus, increasing consumer demand for organic dietary supplements, pharmaceutical formulations, and growing awareness about harmful chemicals and ingredients is also anticipated to fuel the demand over the forecasted period.
Key Companies & Market Share Insights
The competition in the market for hydroxyethyl cellulose is highly dependent on the grade of products, the number of sellers/manufacturers, and geographical location. The products manufacturers are engaged in continuous R&D activities, capacity expansion, mergers and acquisitions, and other strategies to gain a competitive advantage over others. In March 2021, Ashland Global Holdings Inc. announced plans to expand its Natrosol Hydroxyethyl Cellulose (HEC) production capacity in Nanjing, China. This expansion is in line with the company’s growth strategy and commitment to investing in the region.
Manufacturers are focusing intensely on improving their product portfolios by forming strategic Joint Ventures (JV) with some prominent companies. In recent years, major players have made significant investments in innovation to assist corporations in developing new products, addressing the rising demand, and increasing their revenue. Many companies have diversified their supply sources to secure a steady supply of raw materials. Major firms have vertically integrated the manufacturing processes that enable them to procure raw materials at a comparatively lower cost.
Key Hydroxyethyl Cellulose Companies:
The following key companies have been profiled for this study on the hydroxyethyl cellulose market.
-
Ashland
-
Dow Chemicals
-
Shin-Etsu Chemicals Co., Ltd.
-
AkzoNobel N.V.
-
Daicel Corporation
-
Lotte fine Chemicals
-
Chemcolloids Ltd.
-
Zhejiang Haishen New Materials Limited
-
Yil-Long Chemical Group
-
Wuxi Sanyou New Material Technology Co., Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Ashland, Dow, Shin-Etsu Chemical Co., Ltd., AkzoNobel N.V., Daicel Corporation, LOTTE Fine Chemical, Chemcolloids Ltd.)
- Invest in continuous R&D to develop high-performance and application-specific hydroxyethyl cellulose grades.
- Expand global manufacturing capacity and distribution networks to ensure consistent product availability.
- Establish long-term supply agreements with construction, coatings, pharmaceutical, and personal care manufacturers.
- Focus on sustainable production practices, regulatory compliance, and process optimization.
- Strong global brand recognition supported by extensive technical expertise.
- Diverse product portfolios serve multiple end-use industries and premium applications.
- Advanced manufacturing capabilities that deliver consistent product quality and performance.
- Robust financial resources enabling innovation, acquisitions, and capacity expansion.
- Higher production and operational costs than regional competitors.
- Complex organizational structures can delay strategic decision-making.
- Significant compliance costs associated with stringent environmental regulations.
- Premium pricing limits competitiveness in cost-sensitive markets.
Emerging & Regional Players ( Zhejiang Haishen New Materials Co., Ltd., Yillong Chemical Group, Wuxi Sanyou New Material Technology Co., Ltd.)
- Increase production capacity to address growing regional and export demand.
- Emphasize cost-efficient manufacturing and streamlined supply chain management.
- Develop customized hydroxyethyl cellulose grades for specific customer applications.
- Expand international reach through strategic partnerships and distributor networks.
- Competitive pricing supported by lower manufacturing costs.
- Greater operational flexibility to respond quickly to changing customer needs.
- Strong presence in high-growth Asia-Pacific markets.
- Ongoing investments in production technology and quality improvement.
- Limited global brand recognition compared to multinational companies.
- Lower investment capacity for advanced research and product innovation.
- Higher dependence on regional market demand and export performance.
- Narrower product portfolios restrict participation in specialized applications.
Hydroxyethyl Cellulose Market Report Scope
Report Attribute
Details
Market size in 2025
USD 950.8 million
Estimated market size in 2026
USD 993.7 million
Projected market size by 2033
USD 1,332.8 million
Growth rate
CAGR of 4.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; Italy; France; Spain; China; India; Japan; South Korea; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
Ashland, Dow Chemicals; Shin-Etsu Chemicals Co., Ltd.; AkzoNobel N.V.; Daicel Corporation; Lotte fine Chemicals; Chemcolloids Ltd.; Zhejiang Hashem New Materials Limited; Yil-Long Chemical Group; Wuxi Sanyou New Material Technology Co., Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Hydroxyethyl Cellulose Market Report Segmentation
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global hydroxyethyl cellulose market report on the basis of application and region:
-
Application Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Building Materials
-
Waterborne Paints & Coatings
-
Oil Fields
-
Personal Care & Cosmetics
-
Pharmaceuticals
-
Textiles
-
Food
-
Paper & Printing Inks
-
Others
-
-
Regional Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The hydroxyethyl cellulose market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each hydroxyethyl cellulose segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Application
Revenue capture definition
Building Materials
Includes revenue generated from hydroxyethyl cellulose supplied for cement-based mortars, tile adhesives, wall putties, plasters, self-leveling compounds, and other construction formulations where it enhances water retention, workability, adhesion, and consistency.
Waterborne paints & coatings
Represents revenue earned from hydroxyethyl cellulose incorporated into water-based paints, architectural coatings, industrial finishes, and protective coatings to improve viscosity control, pigment suspension, application properties, and storage stability.
Oil fields
Covers revenue derived from hydroxyethyl cellulose utilized in drilling fluids, completion fluids, hydraulic fracturing, and well servicing operations to provide viscosity enhancement, fluid-loss control, and improved drilling performance under varying field conditions.
Personal care & cosmetics
Accounts for sales generated from hydroxyethyl cellulose used in skincare, haircare, oral care, and cosmetic formulations as a thickening, stabilizing, suspending, and texture-enhancing ingredient that improves product performance and consumer experience.
Pharmaceuticals
Captures revenue from hydroxyethyl cellulose supplied for pharmaceutical formulations, including ophthalmic solutions, topical gels, suspensions, and controlled-release drug delivery systems, where it functions as a binder, viscosity modifier, and stabilizing excipient.
Textiles
Represents income generated from hydroxyethyl cellulose incorporated into textile processing operations, including printing, dyeing, sizing, and finishing, to improve paste consistency, color uniformity, fiber protection, and process efficiency.
Food
Includes revenue from hydroxyethyl cellulose utilized in selected food processing applications as a thickener, stabilizer, and texture-modifying ingredient to enhance product consistency, moisture retention, and formulation stability where regulatory approvals permit.
Paper & Printing Inks
Encompasses revenue generated from hydroxyethyl cellulose used in paper coatings, paper processing, and printing ink formulations to improve viscosity, coating uniformity, print quality, pigment dispersion, and overall production efficiency.
Other Applications
Covers revenue from hydroxyethyl cellulose supplied for diverse industrial uses, including ceramics, adhesives, detergents, household products, and specialty chemical formulations requiring reliable rheology control, stabilization, and water-retention properties.
Estimation Model
Layer Name
Key Question
Description
Hydroxyethyl Cellulose Production Layer
What forms is the supply base?
Identify the global production capacity of hydroxyethyl cellulose by evaluating cellulose ether manufacturing facilities, raw material availability, ethoxylation capabilities, specialty chemical processing infrastructure, production technologies, quality control standards, and manufacturing capacities for industrial, pharmaceutical, food-grade, and cosmetic-grade hydroxyethyl cellulose across major production regions
Application Adoption Layer
Where are hydroxyethyl cellulose utilized?
Estimate the distribution of hydroxyethyl cellulose demand across building materials, water-borne paints and coatings, oilfield chemicals, personal care, pharmaceuticals, textiles, food processing, paper, printing inks, and other industrial applications by analyzing end-use production trends, formulation requirements, regulatory compliance, technological advancements, and sector-specific consumption patterns across key regional markets.
Consumption Intensity Layer
How much hydroxyethyl cellulose is consumed?
Assess hydroxyethyl cellulose consumption across major end-use industries by evaluating construction activity, coatings production volumes, oilfield operations, cosmetic manufacturing, pharmaceutical output, textile processing, food manufacturing, and paper production to estimate annual demand and application intensity across leading geographic markets.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the sale of hydroxyethyl cellulose across multiple purity grades and application-specific formulations supplied to construction material manufacturers, coatings producers, oilfield service providers, personal care and pharmaceutical companies, food processors, textile manufacturers, paper mills, and industrial distributors through direct sales, strategic partnerships, and global distribution networks.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional segmentation
The study delivers detailed country-level analysis across key hydroxyethyl cellulose production and consumption markets. It evaluates manufacturing capacity, cellulose feedstock availability, end-use industry demand, trade dynamics, regulatory framework, supply chain infrastructure, and regional growth potential.
Enables effective market expansion by identifying high-growth countries, manufacturing hubs, consumption patterns, supply chain advantages, and investment opportunities across major regions.
Competitive Benchmarking
Comparative assessment of leading hydroxyethyl cellulose manufacturers based on product portfolio, production capabilities, application expertise, manufacturing footprint, distribution network, innovation pipeline, sustainability initiatives, R&D investments, and recent strategic developments.
Supports strategic decision-making by highlighting competitive differentiation, technological capabilities, product innovation, market reach, and long-term growth strategies of key industry participants.
Opportunity Assessment
Comprehensive evaluation of emerging growth opportunities driven by expanding construction activities, rising adoption of water-borne coatings, increasing personal care and pharmaceutical demand, oilfield development, and advancements in specialty cellulose formulations.
Assists business planning by identifying high-potential application segments, evolving customer preferences, emerging industry trends, innovation prospects, and attractive investment avenues for sustainable market growth.
Frequently Asked Questions About This Report
Asia Pacific accounted for 57.2% of the hydroxyethyl cellulose market revenue in 2025, making it the largest regional market, supported by robust construction activity, expanding paints and coatings production, strong manufacturing capabilities, and increasing demand from personal care and pharmaceutical industries, particularly in China, India, and Southeast Asia.
The hydroxyethyl cellulose market is primarily driven by rising demand from the construction and water-borne paints & coatings industries, where it enhances viscosity, water retention, and application performance. Growth in the personal care, pharmaceutical, and oilfield sectors, along with increasing preference for environmentally friendly, water-based formulations, is further supporting market expansion.
The global hydroxyethyl cellulose market is anticipated to grow at a compound annual growth rate (CAGR) of 4.3% from 2026 to 2033 and reach USD 1,332.8 million by 2033.
The global hydroxyethyl cellulose market size was valued at USD 950.8 million in 2025 and is expected to reach USD 993.7 million in 2026.
Waterborne paints & coatings segment projected the largest share of 25.4% in 2025.
Some prominent players in the global HEC market include Ashland, Dow Chemicals; Shin-Etsu Chemicals Co., Ltd.; AkzoNobel N.V.; Daicel Corporation; Lotte fine Chemicals; Chemcolloids Ltd. and others.
About the Author(s)
Renewable Chemicals Research Team
Specialty & Chemicals · Renewable ChemicalsThis report was authored by the renewable chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable chemicals segment of the specialty & chemicals industry. All findings are based on proprietary specialty & chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


