
- Home
- »
- Biotechnology
- »
-
Immunotoxins Market Size, Share, Trends Report, 2026-2033GVR Report cover

Immunotoxins Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Diptheria Toxin (DT), Pseudomonas Exotoxin), By Application (Therapy Development), By End-use (Pharmaceutical & Biotechnology Companies), By Region, And Segment Forecasts
Market Size, 2025
$163.8MMarket Estimate, 2026
$176.3MMarket Forecast, 2033
$319.6MCAGR, 2026–2033
8.9%Immunotoxins Market Summary
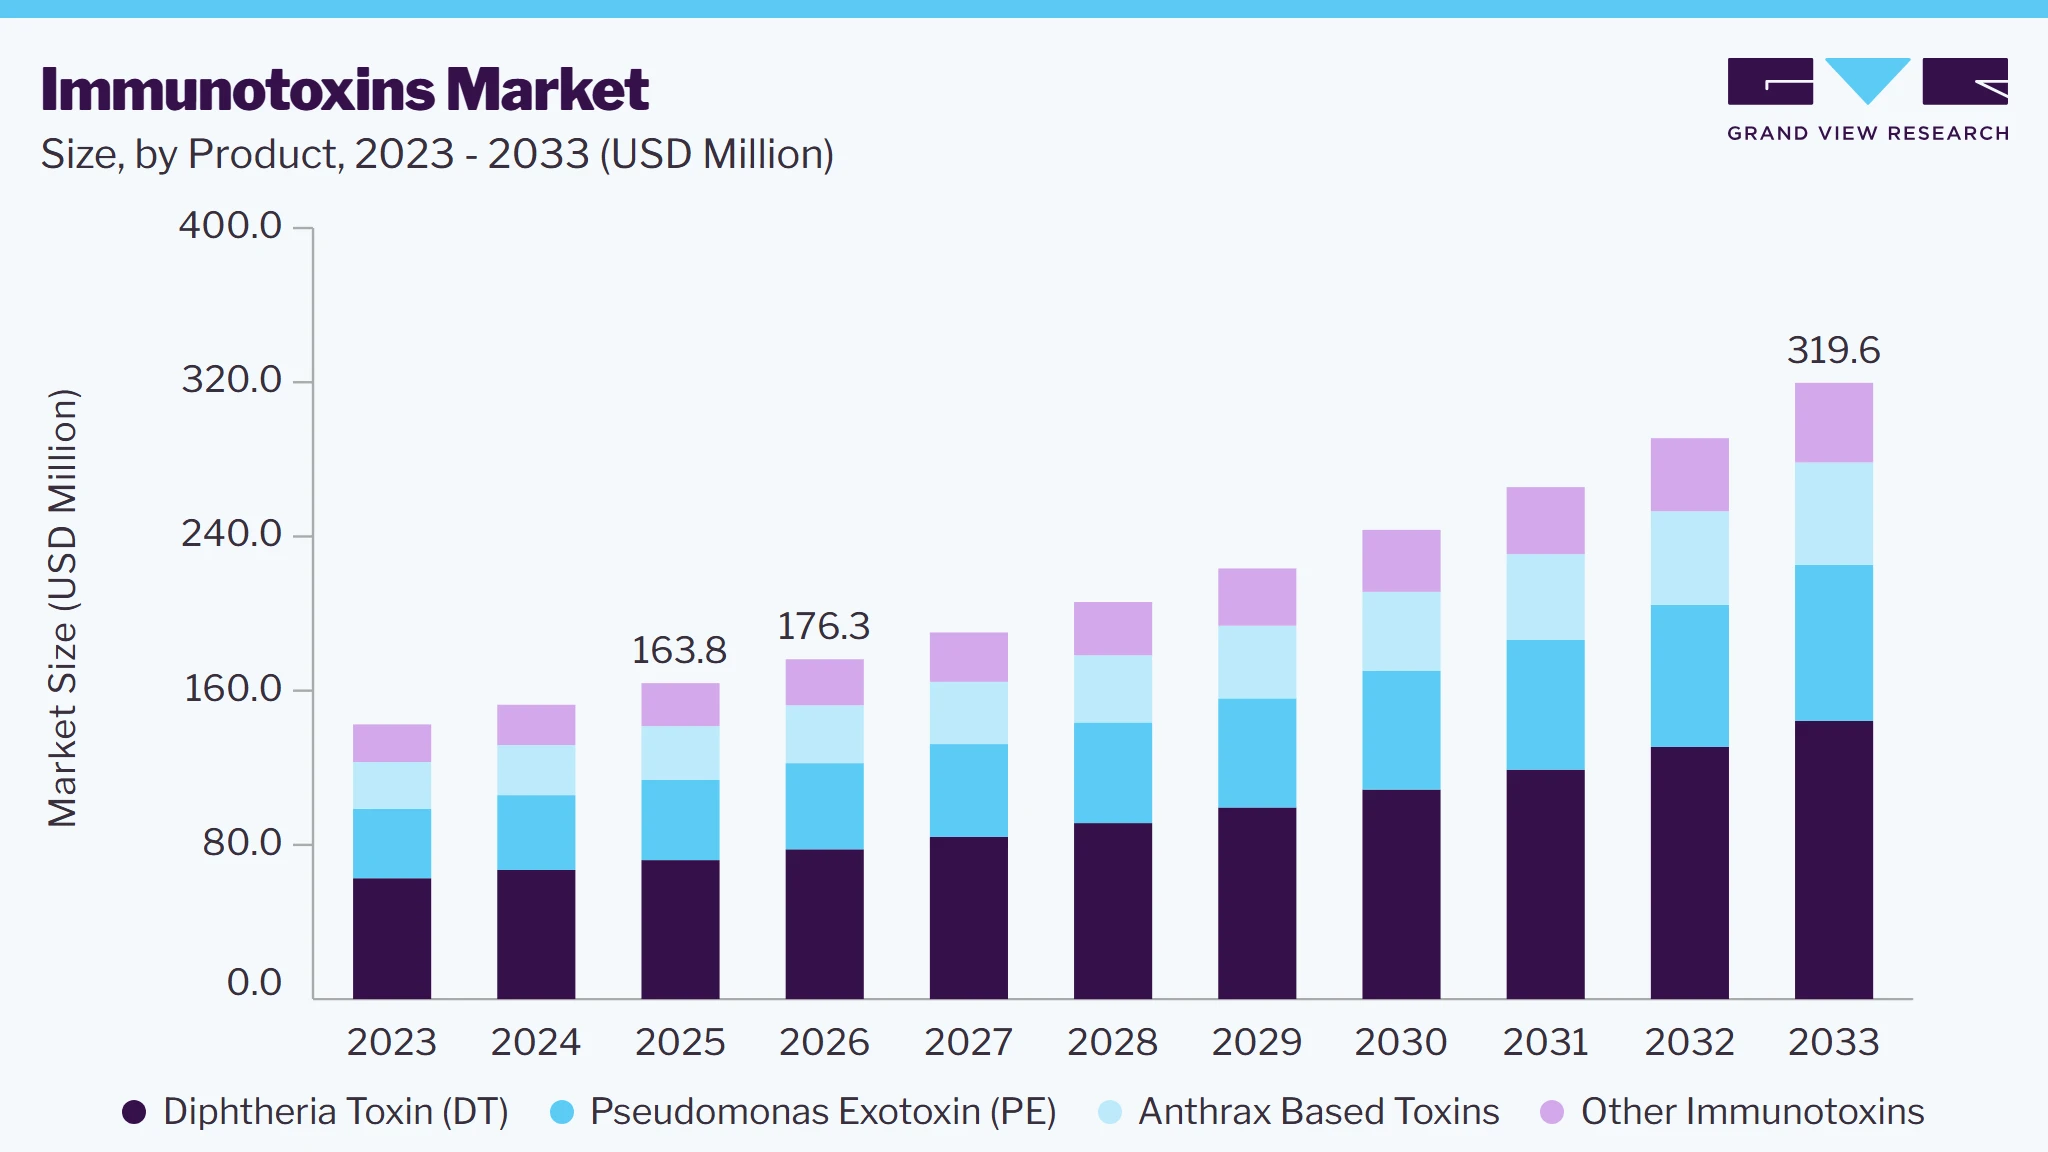
The global immunotoxins market size was valued at USD 163.8 million in 2025 and is projected to grow from USD 176.3 million in 2026 to USD 319.6 million by 2033, at a CAGR of 8.9% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 41.4% in 2025. The rising prevalence of chronic diseases such as cancer and technological advancements are the factors driving the market growth. Cancer remains one of the leading causes of death worldwide.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Diphtheria toxin (DT) segment dominated the market, with a revenue share of 44.0% in 2025.
- By application: Therapy development segment held the largest market share of 63.4% in 2025.
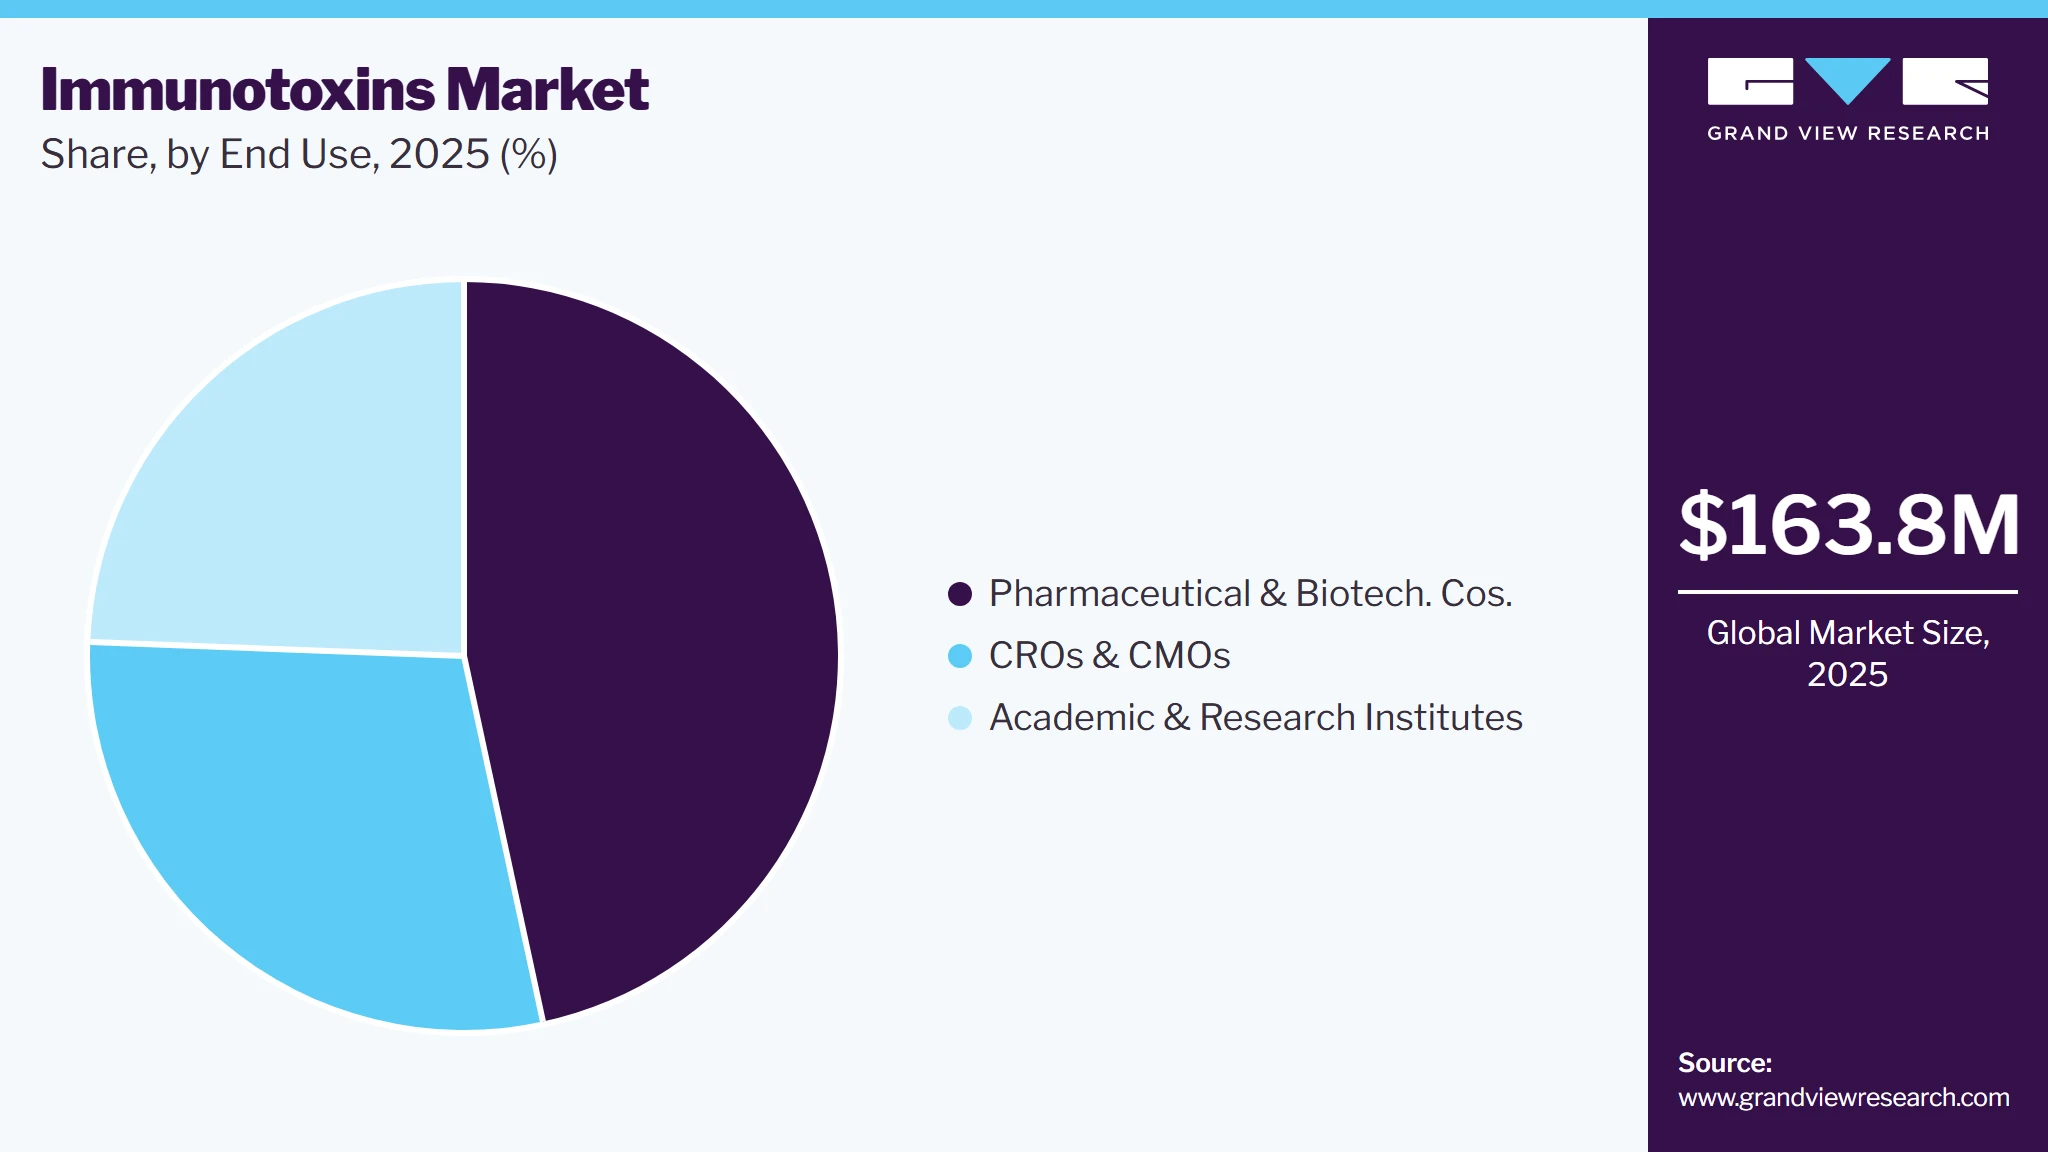
- By end use: Pharmaceutical & biotechnology companies segment held the largest revenue share of 46.6% in 2025.
Regional Highlights
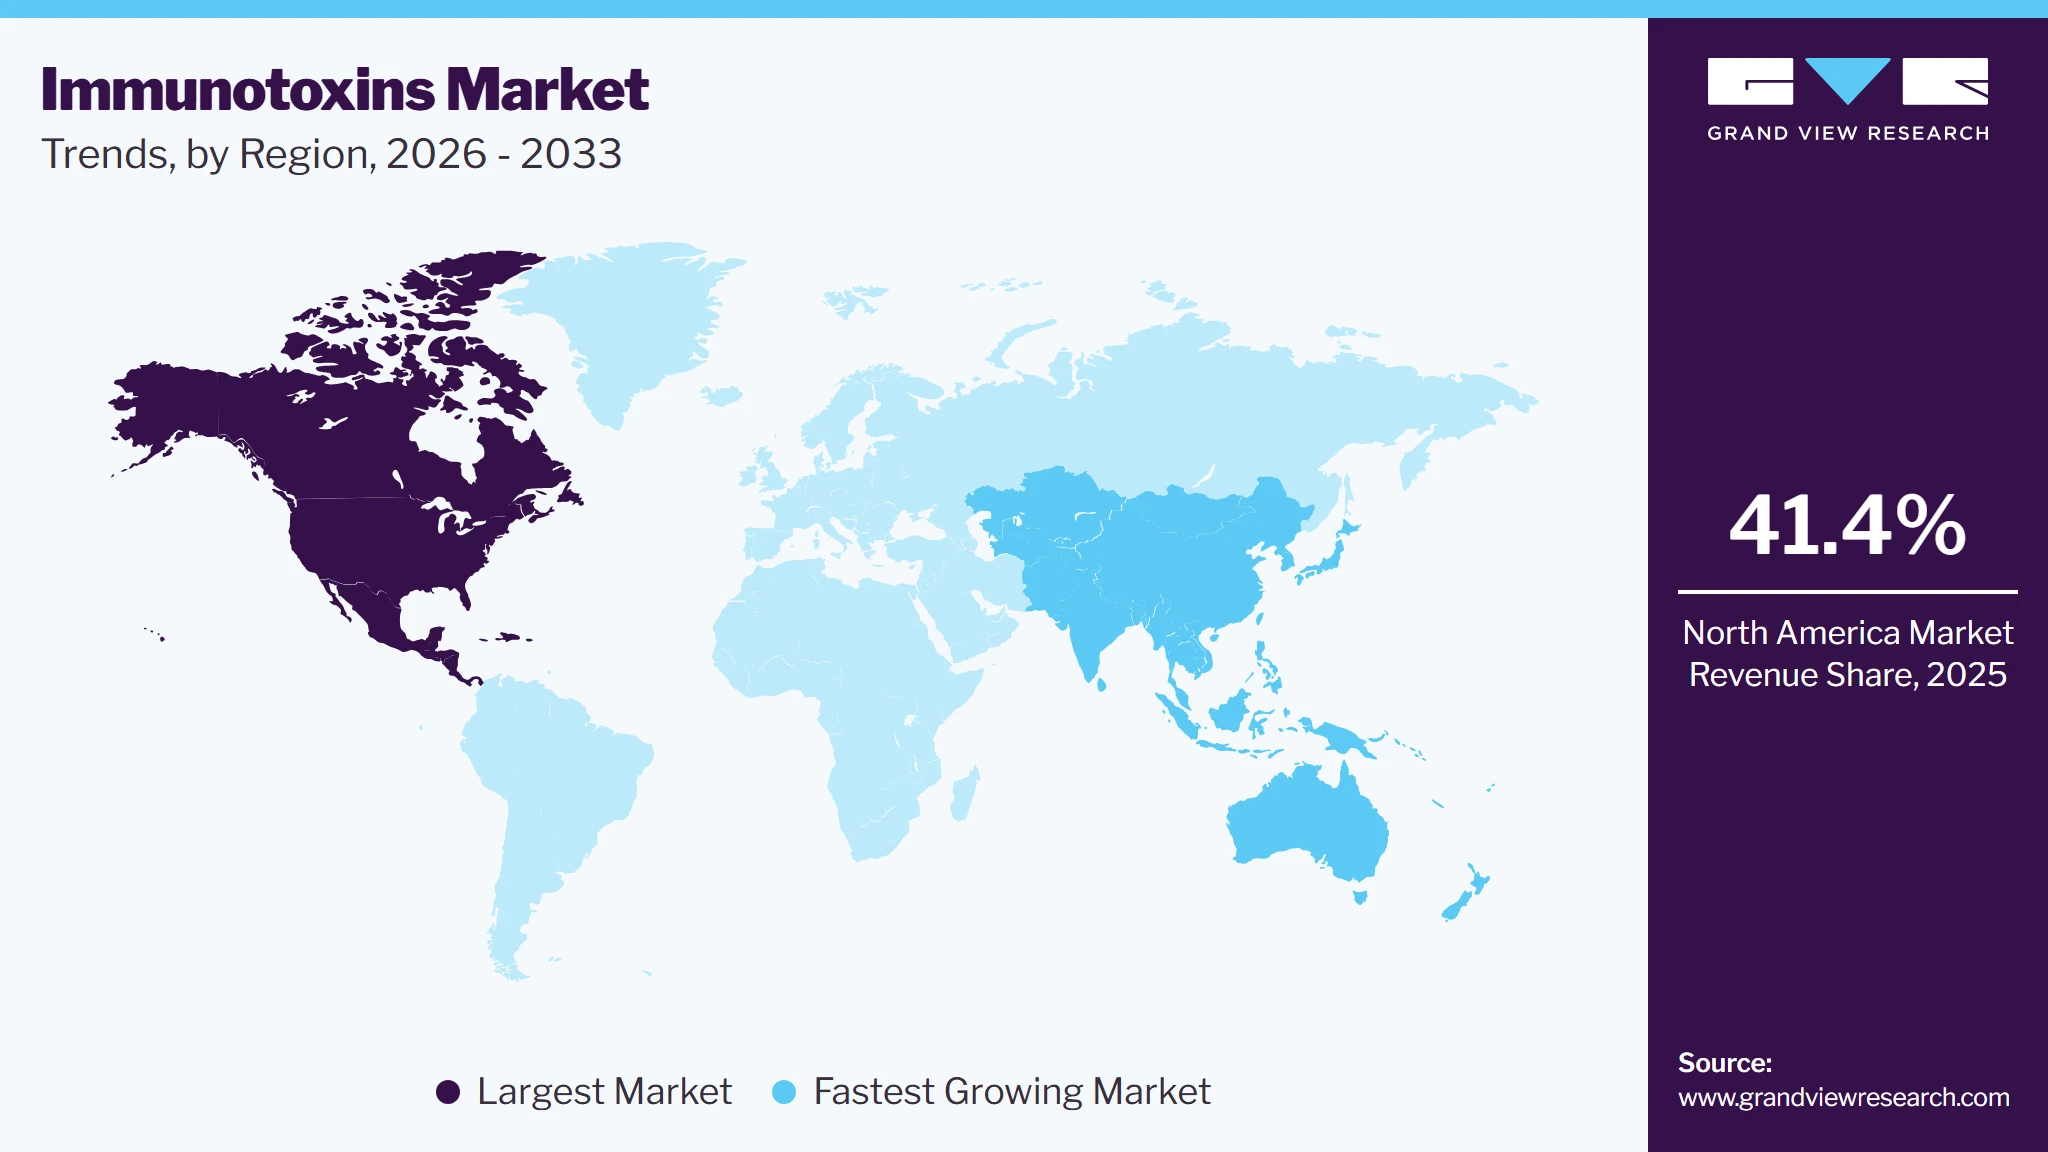
- Largest regional market: North America (41.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
- CAGR (2026-2033): 8.9%
Market Size & Forecast
- Market size in 2025: USD 163.8 Million
- Estimated market size in 2026: USD 176.3 Million
- Projected market size by 2033: USD 319.6 Million
- CAGR (2026-2033): 8.9%
Prism AI by Grand View Research Free to tryAsk a question about the immunotoxins marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Bacterial toxins have shown potential for cancer treatment due to their ability to specifically target cancer cells and their cytotoxic properties. Toxins such as Pseudomonas exotoxin, diphtheria toxin, and plant-derived ricin can be targeted to specific sites on the surface of cancer cells and can effectively kill them. By combining these toxins with cell-binding proteins like monoclonal antibodies or growth factors, they can selectively bind to and eliminate cancer cells.Bacteria-derived toxins possess potent anticancer properties by affecting cell cycle progression, apoptotic pathways, and tumorigenesis processes. For example, toxins like Exotoxin A from Pseudomonas aeruginosa can induce apoptosis in cancer cells by various mechanisms such as inactivating PARP, inducing caspase-dependent apoptosis, and disrupting cellular functions.
 To learn more about this report, Download Free Sample Report
Moreover, the development of PE-based immunotoxins has shown promise in treating various malignancies, including prostate and hematological cancers like hairy cell leukemia. Clinical trials have demonstrated significant efficacy, with some immunotoxins achieving complete remission in patients resistant to standard therapies. For instance, moxetumomab pasudotox (HA22), derived from PE38, has gained FDA approval for treating relapsed or refractory hairy cell leukemia due to its high response rates and manageable safety profile. Ongoing research continues to explore the potential of PE-derived immunotoxins in targeting other tumor types and improving therapeutic outcomes through enhanced delivery mechanisms.
The COVID-19 pandemic had a significant impact on the market, causing disruptions in several aspects of the market including clinical trial disruptions, supply chain challenges, and stringent regulations. The pandemic led to a shift in priorities and resources towards combating the virus, but it also underscored the importance of ongoing cancer research efforts. The pandemic impacted the development of immunotoxins, leading to clinical trial delays, reducing funding, and shifting resources to COVID-19 research.
Market Dynamics
The immunotoxins market is witnessing steady growth owing to the increasing burden of cancer and the growing demand for targeted therapeutics with improved treatment outcomes. Rising investments in oncology drug development, an expanding pipeline of novel immunotoxin candidates, and increasing collaborations between biotechnology and pharmaceutical companies are supporting market expansion. Moreover, favorable regulatory support for innovative biologics and the growing adoption of precision medicine are expected to create significant growth opportunities for the market over the forecast period.
Continuous advancements in antibody engineering and recombinant toxin technologies are significantly driving the immunotoxins market by improving the specificity, efficacy, and safety of targeted therapeutics. Innovations such as humanized and single-domain antibodies, optimized linker designs, and genetically engineered toxin payloads have enabled the development of immunotoxins with enhanced tumor selectivity, reduced immunogenicity, and improved intracellular toxin delivery. These advancements are expanding the therapeutic potential of immunotoxins across hematological malignancies and solid tumors while supporting the growing adoption of precision oncology approaches.
According to a research article published by science direct in January 2025, researchers developed a conditionally activated mesothelin-targeting immunotoxin (NbHSA-uPA-A1-PE24) designed with an albumin-binding nanobody and a tumor-specific cleavable linker to prolong circulation time while minimizing off-target toxicity. The engineered immunotoxin demonstrated enhanced tumor accumulation and robust antitumor efficacy across multiple preclinical cancer models, highlighting the role of next-generation recombinant toxin engineering in advancing safer and more effective immunotoxin-based therapies.
Dose-limiting toxicity and off-target adverse effects remain key challenges restraining the growth of the immunotoxins market. Although immunotoxins are designed to selectively target diseased cells, unintended binding to healthy tissues and the systemic activity of toxin payloads can lead to adverse events such as vascular leak syndrome, hepatotoxicity, and immune-related toxicities. These safety concerns often restrict the maximum tolerated dose, limit repeat administration, and complicate clinical development, thereby slowing broader adoption.
To address these limitations, companies and research institutions are developing next-generation immunotoxins with engineered toxin domains, improved target specificity, and optimized dosing strategies to reduce systemic toxicity while maintaining therapeutic efficacy. Despite these advances, demonstrating an acceptable safety profile continues to be a critical requirement during clinical evaluation, contributing to longer development timelines and higher overall development costs.
Market Concentration & Characteristics
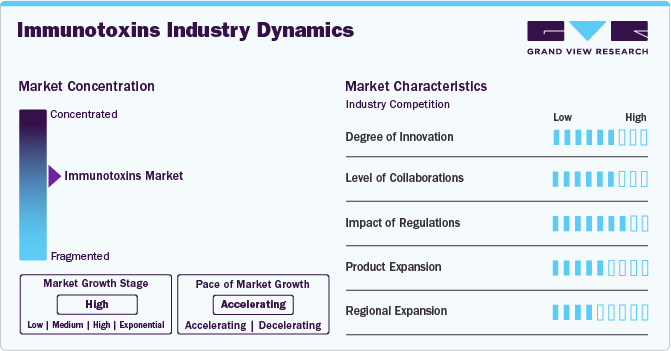
The degree of innovation in the immunotoxin industry is significant, with new technologies and processes constantly being developed to improve efficiency and effectiveness. Researchers are developing novel recombinant immunotoxins against different types of cancers that are more efficient than the existing drugs. Furthermore, the use of immunotoxins has gained traction for innovative approaches to drug discovery in medicine and therapeutics.
The market is also characterized by a moderate level of merger and acquisition activities undertaken by several industry players. This is due to several factors, including the desire to gain a competitive advantage in the industry and the need to consolidate in a rapidly growing market.
 To learn more about this report, Download Free Sample Report
Regulatory requirements governing the use and production of immunotoxins can pose challenges for market players. Compliance with regulations related to biosafety, immunotherapy, and other aspects can increase operational costs and create barriers to entry for new entrants in the market.
The immunotoxins industry is anticipated to experience growth due to expanding applications, advancements in biotechnology and production processes, and increased R&D investments. However, currently, the industry also observes fewer product launches and the commercial availability of immunotoxin products in the market, mainly due to possible toxicity prophylaxis and less demand for therapy.
The industry is experiencing moderate regional expansion, driven by an increasing customer base for immunotherapies. Companies are partnering with distributors to extend their regional presence.
Analyst Perspective
The immunotoxins market is expected to witness steady growth, driven by increasing research in targeted cancer therapies and the growing demand for precision oncology approaches. Rising investments in antibody-based therapeutics, expanding clinical development of immunotoxin candidates, and advancements in recombinant protein engineering are supporting market expansion. The ability of immunotoxins to selectively target diseased cells while minimizing damage to healthy tissues continues to drive interest across oncology and specialized therapeutic applications. Moreover, ongoing innovation in toxin conjugation technologies and growing collaborations between biotechnology companies and research institutions are expected to create long-term growth opportunities for market participants.
Product Insights
Based on product, the diphtheria toxin (DT) segment held the largest revenue share of 44.0% in 2025, and it is expected to grow with the fastest CAGR over the forecast period. Diphtheria toxin has been used in cancer treatment as part of targeted therapies designed to attack cancer cells. These treatments work by attaching the toxin to specific proteins or receptors that are found in high numbers on the surface of cancer cells, such as the transferrin or interleukin-13 receptors. Once the toxin enters the cancer cell, it triggers the cell to die. By combining an antibody or other targeting molecule with diphtheria toxin, researchers have created fusion proteins that have been effective in killing brain cancer cells, especially those that don’t respond well to standard treatments like radiation or chemotherapy. Thus, anticipated to propel the growth of the segment over the forecast period.
Pseudomonas Exotoxin is anticipated to grow at a significant CAGR of 8.21% over the forecast period. The growth is driven by its expanding use in targeted cancer therapies. This toxin is engineered to specifically attack cancer cells by binding to overexpressed receptors, delivering a highly potent cell-killing effect while sparing healthy tissues. Its effectiveness in treating cancers that are resistant to traditional therapies like chemotherapy has made it a valuable tool in the development of new, more precise treatments. Moreover, ongoing advancements in biotechnology are improving the stability, delivery, and targeting mechanisms of Pseudomonas Exotoxin, which is boosting its demand in the biopharmaceutical sector. These factors are positioning it as a key component in the future of cancer treatment innovation.
Application Insights
Based on application, the therapy development segment held the largest revenue share of 63.4% in 2025, and it is expected to grow with the fastest CAGR over the forecast period. This growth is driven by increasing investment in R&D, particularly in targeted cancer therapies, which offer more precise and effective treatment options. Advances in biotechnology and immunotherapy are also accelerating the innovation of new immunotoxin-based therapies. Additionally, the rising prevalence of cancer and the need for more specialized, less toxic treatment methods are fueling demand for these therapies in the global market.
In September 2018, the U.S. FDA approved AstraZeneca’s Lumoxiti to treat patients with relapsed or refractory hairy cell leukemia. However, due to the availability of other treatment options, complexity of administration, possible toxicity prophylaxis, and patient safety monitoring needs, in November 2022, the company announced the permanent withdrawal of Lumoxiti from the U.S. market.
Biomedical Research segment is expected to witness moderate growth over the forecast period. Scientists are engaged in studying pathways that initiate immune responses. According to an article published in October 2023 in Nature Scientific Reports, scientists from Howard University, Washington DC, U.S. investigated the innate immune modulation of hDT806 on the head and neck squamous cell carcinoma, initiated by the STING signaling pathway.
End-use Insights
Based on end use, the pharmaceutical & biotechnology companies segment held the largest revenue share of 46.6% in 2025, and it is expected to grow with the fastest CAGR over the forecast period. This is mainly due to their significant investment in research and development to create new immunotoxins tailored for specific medical conditions. These companies focus on targeting antigens that are highly expressed in certain types of tumors or disease conditions, which allows for more effective treatments. By using advanced technologies like recombinant DNA, they are able to produce immunotoxins with greater precision, resulting in fewer side effects and improved therapeutic outcomes. Their efforts are driving innovation in this space, making these companies key players in advancing the market.
 To learn more about this report, Download Free Sample Report
Academic and research institutes are expected to see significant growth of 7.98% over the forecast period. This growth is driven by ongoing research focused on developing engineered toxin fragments to reduce immunogenicity, minimize off-target toxic effects, and extend the half-life of immunotoxins. One major challenge in immunotoxin therapy is that once the immunotoxin is taken up by cells, much of it gets degraded in the lysosomes, and only a small amount manages to escape to the cytosol to trigger its toxic effect. To overcome this, researchers are working on creating new, more stable immunotoxins that can improve delivery, enhance stability, and increase their effectiveness in targeting tumors. These advancements are positioning academic and research institutions as key contributors to innovation in the field of immunotoxins.
Regional Insights
North America dominated the immunotoxins market with the largest revenue share of 41.4% in 2025, attributed to the region’s advanced healthcare infrastructure, strong presence of leading biotechnology firms, and significant funding for immunology and oncology research. Furthermore, growing healthcare expenditure, increasing awareness of gene and cell therapies, and supportive government initiatives are expected to boost the market.
 To learn more about this report, Download Free Sample Report
U.S. Immunotoxins Market Trends
The immunotoxins market in the U.S. held the largest share in the North America region in 2025. The immunotoxins market in the U.S. is anticipated to grow over the forecast period due to increasing government funding & growing focus on targeted treatments, and the rising prevalence of diseases. Moreover, increasing research in the fields of drug discovery and personalized medicine, is further anticipated to fuel market growth.
Europe Immunotoxins Market Trends
The Europe immunotoxins market is anticipated to grow over the forecast period. Europe has been actively involved in oncology studies and research, contributing to its growth in the region. Moreover, increasing research and development activities, collaborations between pharmaceutical companies and research institutions, and a growing demand for targeted cancer therapies, further propel market growth.
The UK immunotoxins market is expected to grow over the forecast period due to the rising prevalence of cancer and the growing demand for targeted therapies.
The immunotoxins market in Germany is expected to grow over the forecast period due to the growing incidence and prevalence of genetic disorders,favorable government policies supporting research activities and the introduction of new drugs and therapies by key players.
The immunotoxins market in France is expected to grow over the forecast period due to the growing investments in research and development, advancements in biotechnology, and a growing emphasis on precision medicine approaches for cancer treatment.
Asia Pacific Immunotoxins Market Trends
The Asia Pacific immunotoxins market is expected to experience highest growth, with a projected CAGR from 2026 to 2033. This is attributed to the rising prevalence of cancer, increasing government initiatives and funding for novel cancer therapy, and a strong presence of biotechnology and biopharmaceutical companies in the region.
The China immunotoxins market is anticipated to grow over the forecast period due to increasing investments in healthcare innovation and research. The country’s focus on advancing biotechnology and immunotherapy coupled with the rising awareness of personalized medicine, is driving the expansion of the immunotoxins market in China.
The Japan immunotoxins marketis expected to witness rapid growth over the forecast period. The increasing prevalence of diseases, coupled with the growing oncology research, anticipates market growth.
The immunotoxins market in India is anticipated to grow over the forecast period due to the rising prevalence of cancer in the country. In addition, increasing government funding for cancer research boosts market growth.
Middle East & Africa Immunotoxins Market Trends
The immunotoxins market in the Middle East and Africa is poised to grow in the near future, as increasing applications of biotechnology and immunomedicine contributing to its expansion.
The immunotoxins market in Saudi Arabia is expected to grow over the forecast period due to increasing investments in healthcare innovation and research.
The immunotoxins market in Kuwait is anticipated to witness growth over the forecast period owing to the escalating investment in scientific research and development by both governmental and private entities. This investment is propelling advancements in oncology research, consequently presenting opportunities for developing novel and enhanced cancer therapies.
Key Immunotoxins Company Insights
Key players operating in the market are undertaking various initiatives to strengthen their market presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are playing a key role in propelling the market growth.
Key Immunotoxins Companies:
The following are the leading companies in the immunotoxins market.
- Creative Biolabs.
- List Biological Labs, Inc.
- The Native Antigen Company
- Bio-Techne.
- Abcam Plc.
- CAYMAN CHEMICAL
- Merck KGaA
- Enzo Life Sciences, Inc.
- Santa Cruz Biotechnology, Inc.
- Quadratech Diagnostics Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Merck KGaA, Bio-Techne, Abcam Plc., CAYMAN CHEMICAL, etc.)
- Strengthen market presence through strategic collaborations with academic institutions, biotechnology companies, and pharmaceutical organizations to support oncology and targeted therapy research.
- Significant expertise in antibody engineering, protein sciences, and life science research tools, enabling reliable and reproducible immunotoxin development.
- Regulatory challenges and lengthy commercialization timelines for immunotoxin-based therapeutic applications.
Emerging Players (Creative Biolabs, List Biological Labs, The Native Antigen Company)
- Focus on specialized immunotoxin development services, custom antibody conjugation, and niche research reagents for targeted therapeutic and diagnostic applications.
- Greater flexibility and faster response to evolving customer requirements in research and early-stage drug discovery.
- Narrower product portfolios and greater dependence on academic, research, and contract-based revenue streams.
Recent Developments
-
In April 2024, Bio-Techne announced a distribution agreement with Thermo Fisher Scientific, Inc. Under this agreement, Thermo Fisher Scientific can distribute Bio-Techne’s products across Europe through its Fisher Scientific Channel.
-
In April 2024, Invera Inc. and Astellas Pharma collaborated to discover therapeutic bispecific antibodies. With this agreement, Astellas Pharma can use Invera’s B-Body bispecific antibody platform for bispecific therapeutic research.
-
In January 2023, List Biological Labs, Inc. expanded its bacterial therapeutic manufacturing capacity by adding a new 500L bioreactor and a tangential flow filtration system.
-
In July 2020, LGC acquired The Native Antigen Company, strengthening LGC’s IVD sector product portfolio.
-
In July 2019, The Native Antigen Company signed a distribution agreement with BIOZOl and Shanghai Bioloeaf, allowing researchers from Germany, Switzerland, Austria, and China to access the company's products.
Immunotoxins Market Report Scope
Report Attribute
Details
Market size in 2025
USD 163.8 million
Estimated market size in 2026
USD 176.3 million
Projected market size by 2033
USD 319.6 million
Growth rate
CAGR of 8.9% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, China, Japan, India, South Korea, Australia, Thailand, Brazil, Argentina, Saudi Arabia, South Africa, UAE, Kuwait
Key companies profiled
Creative Biolabs.; List Biological Labs, Inc.; The Native Antigen Company; Bio-Techne.; Abcam Plc.; CAYMAN CHEMICAL; Merck KGaA; Enzo Life Sciences, Inc; Santa Cruz Biotechnology, Inc.; Quadratech Diagnostics Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Immunotoxins Market Report Segmentation
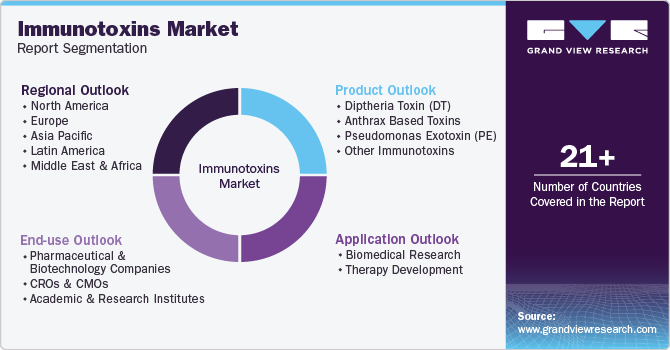
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global immunotoxins market report based on product, application, end-use, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Diptheria Toxin (DT)
-
Anthrax Based Toxins
-
Pseudomonas Exotoxin (PE)
-
Other Immunotoxins
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Biomedical Research
-
Therapy Development
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceutical & Biotechnology Companies
-
CROs & CMOs
-
Academic & Research Institutes
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The immunotoxins market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each immunotoxins segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue Capture Definition
Diphtheria Toxin (DT)
Revenue generated from immunotoxins that utilize genetically modified diphtheria toxin as the cytotoxic component to selectively eliminate target cells. These products are primarily employed in oncology research, targeted therapeutics development, and immunological studies due to their ability to inhibit protein synthesis and induce cell death following receptor-mediated internalization.
Anthrax Based Toxins
This segment captures income from immunotoxins incorporating modified anthrax toxin components engineered for targeted intracellular delivery of therapeutic payloads. These immunotoxins are widely investigated for precision cancer therapy, targeted drug delivery, and biomedical research aimed at improving treatment specificity while minimizing off-target toxicity.
Pseudomonas Exotoxin (PE)
Market value in this category stems from immunotoxins based on engineered Pseudomonas aeruginosa exotoxin A, which selectively inhibits protein synthesis in target cells. These products are extensively used in hematological malignancy research, solid tumor investigations, and the development of targeted biologic therapies.
Other Immunotoxins
Revenue originates from immunotoxin platforms employing alternative bacterial, plant-derived, or recombinant toxin molecules conjugated with antibodies, antibody fragments, ligands, or targeting proteins. These products support research and therapeutic development across oncology, autoimmune disorders, infectious diseases, and other emerging clinical applications.
Segment - Application
Revenue Capture Definition
Biomedical Research
Revenue generated from immunotoxins used in basic and translational research to selectively eliminate specific cell populations, investigate cellular signaling pathways, study immune mechanisms, validate therapeutic targets, and develop disease models across oncology, immunology, and molecular biology.
Therapy Development
This segment captures income from immunotoxins utilized during the discovery, preclinical evaluation, and clinical development of targeted therapeutics. These products support the development of precision medicines for cancer, autoimmune disorders, infectious diseases, and other conditions requiring selective destruction of pathogenic or diseased cells.
Segment - End Use
Revenue Capture Definition
Pharmaceutical & Biotechnology Companies
Revenue generated from immunotoxins utilized by pharmaceutical and biotechnology companies for biologics discovery, targeted therapy development, preclinical research, clinical development, and commercial biopharmaceutical programs focused on precision medicine.
CROs & CMOs
This segment captures income from contract research organizations (CROs) and contract manufacturing organizations (CMOs) providing immunotoxin-related research, process development, analytical testing, manufacturing, and regulatory support services for pharmaceutical and biotechnology clients.
Academic & Research Institutes
Market value in this category stems from immunotoxin products used by universities, government laboratories, cancer research centers, and academic institutions conducting fundamental, translational, and collaborative research in immunology, oncology, molecular biology, and targeted therapeutics.
Estimation Model
Section
Method
Description
Top-Down
Commodity Flow Analysis
Market size estimated by analyzing revenues generated by key immunotoxin developers and manufacturers, supported by company annual reports, investor presentations, product portfolios, regulatory filings, and premium industry databases. Revenue contributions from private biotechnology companies were assessed through secondary research and validated through primary interviews to derive the overall market value.
Parent Market
Parent Market & Penetration-Based Analysis
The immunotoxins market was evaluated within the broader biopharmaceutical market. Adoption trends across oncology therapeutics, targeted biologics, hematological malignancies, and precision medicine were analyzed along with clinical pipeline progression, commercialization rates, and treatment penetration to estimate the addressable market and segment-level opportunities.
Segmentation
Country-Level Segment Share Modeling
Market shares for product, application, and end-use segments were derived using country-specific cancer incidence, biopharmaceutical healthcare expenditure, reimbursement scenarios, regulatory approvals, and clinical trial activity. Weighted average calculations were applied to determine regional and global segment distributions.
Validation
Data Triangulation & Validation Model
Market estimates validated through triangulation of secondary research, primary interviews, company-level revenue assessments, clinical pipeline analysis, treatment adoption trends, and demand-side evaluation to ensure consistency and accuracy across all market segments and geographies.
Forecasting
Forecasting & CAGR Modeling
Market forecasts developed using historical commercialization trends, growth in targeted cancer therapies, expansion of biologics R&D pipelines, increasing investments in antibody-based therapies, regulatory approvals, and advancements in modern toxin engineering. Regression-based analysis and trend modeling were applied to project future market growth and CAGR.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Product & Application Opportunity Assessment for Immunotoxins
Detailed cross-segmentation analysis across immunotoxin products (Diphtheria Toxin, Pseudomonas Exotoxin, Anthrax-based Toxins, and Other Immunotoxins) by application including biomedical research and therapy development. Evaluation of technology adoption, clinical development pipeline, commercialization potential, and emerging therapeutic opportunities across oncology and targeted therapies.
Enables clients to identify high-growth product-application combinations, prioritize R&D investments, evaluate commercialization opportunities, and align product development strategies with evolving therapeutic demand.
Competitive Benchmarking & Pipeline Intelligence
Comprehensive benchmarking of key immunotoxin developers based on product portfolio, technology platform, clinical pipeline maturity, target indications, strategic collaborations, licensing agreements, manufacturing capabilities, geographic presence, and innovation focus. Includes competitive assessment of emerging pipeline candidates and next-generation immunotoxin platforms.
Supports competitive positioning, identification of licensing and partnership opportunities, benchmarking of innovation strategies, and informed decision-making for market entry, portfolio expansion, and investment planning.
Clinical Pipeline & Target Indication Assessment
Comprehensive analysis of the immunotoxin development pipeline across key therapeutic indications including hematological malignancies, solid tumors, autoimmune disorders, and other emerging applications. Assessment includes target antigen mapping, stage-wise clinical pipeline, technology platforms, regulatory progress, clinical trial landscape, and commercialization readiness.
Enables clients to identify high-potential therapeutic indications, evaluate pipeline maturity and competitive intensity, prioritize licensing and investment opportunities, and support strategic portfolio expansion based on future commercialization potential.
Frequently Asked Questions About This Report
The global immunotoxins market size was valued at USD 163.8 million in 2025 and is estimated at USD 176.3 million by 2026.
Therapy development segment held the largest revenue share of 63.4% in 2025, and it is expected to grow with the fastest CAGR over the forecast period.
North America dominated the immunotoxins market with the largest revenue share of 41.4% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The global immunotoxins market is expected to grow at a CAGR of 8.9% from 2026 to 2033, reaching USD 319.6 million by 2033.
Diphtheria Toxin (DT) segment dominated the product segment in the immunotoxins market with a market share of 44.0% in 2025. Diphtheria toxin has been widely used in cancer treatment as part of targeted therapies designed to attack cancer cells.
Key players operating in the market include Creative Biolabs.; List Biological Labs, Inc.; The Native Antigen Company; Bio-Techne.; Abcam Plc.; CAYMAN CHEMICAL; Merck KGaA; Enzo Life Sciences, Inc; Santa Cruz Biotechnology, Inc.; Quadratech Diagnostics Ltd.
The rising prevalence of cancer and technological advancements are some of the factors anticipated to drive market growth.
The pharmaceutical & biotechnology companies segment held the largest revenue share of over 46.6% in 2025, and it is expected to grow with the fastest CAGR over the forecast period.
About the Author(s)
Biotechnology Research Team
Healthcare · BiotechnologyThis report was authored by the biotechnology research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the biotechnology segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


