
- Home
- »
- Advanced Interior Materials
- »
-
Industrial Burner Market Size & Share Report, 2026-2033GVR Report cover

Industrial Burner Market (2026 - 2033)
Size, Share & Trends Analysis Report By Fuel Type (Gas, Oil, Solid Fuel, Multi-Fuel), By Configuration (New Machine/OEM Installation, Retrofit And Replacement), By End Use (Metals And Mining, Food & Beverage, Chemicals), By Region, And Segment Forecasts
Market Size, 2025
$7.0BMarket Estimate, 2026
$7.4BMarket Forecast, 2033
$11.0BCAGR, 2026–2033
5.8%Industrial Burner Market Summary
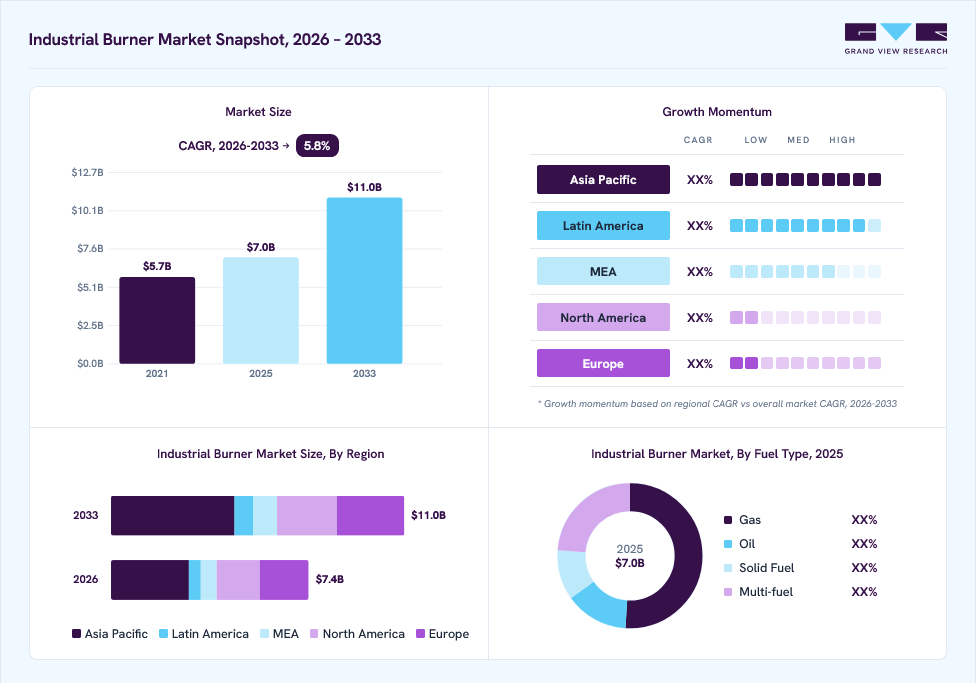
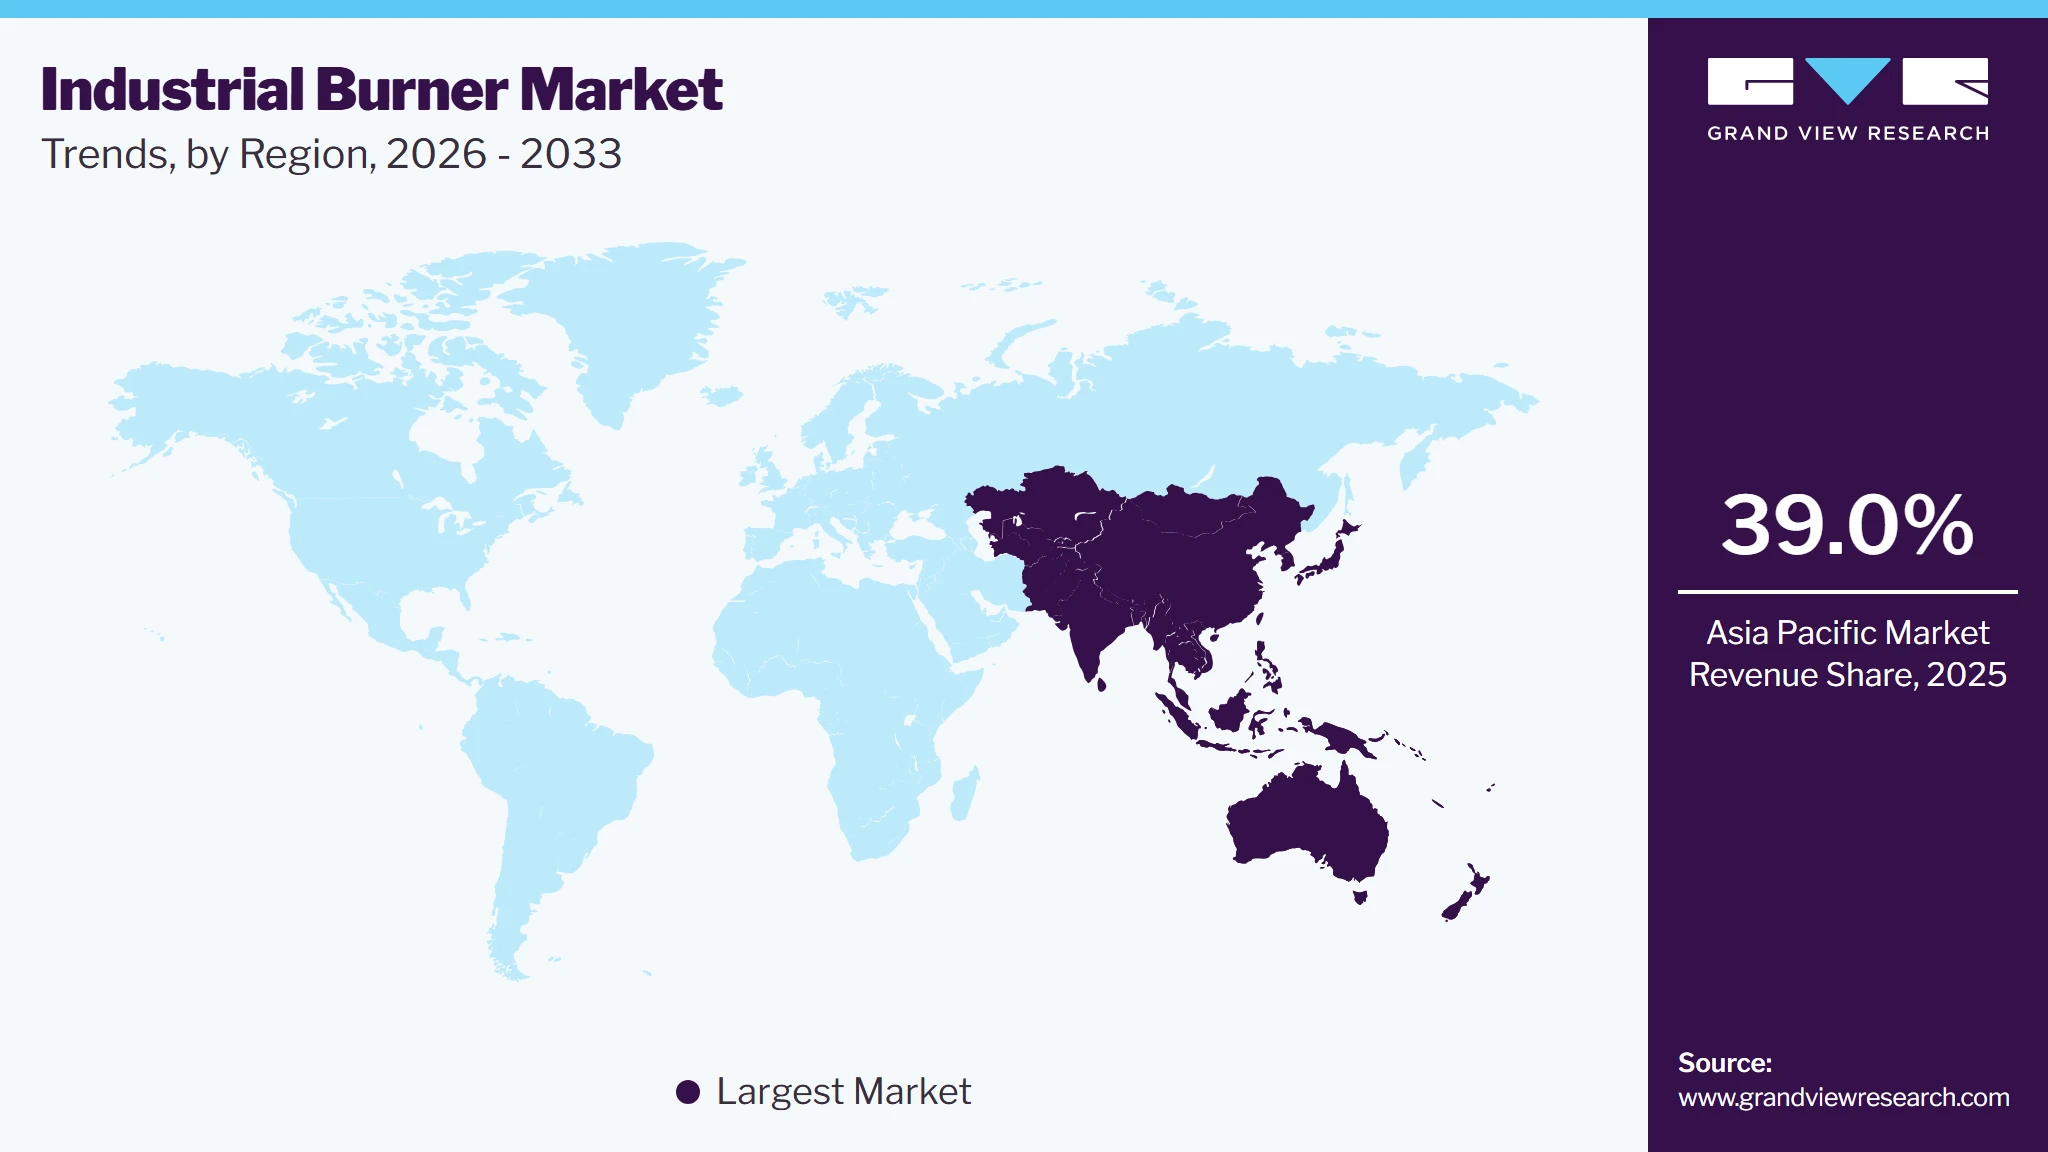
The global industrial burner market size was valued at USD 7.0 billion in 2025 and is projected to grow from USD 7.4 billion in 2026 to USD 11.0 billion by 2033, at a CAGR of 5.8% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 39.0% in 2025. The market is expected to grow primarily due to increasing industrial production and the need for efficient combustion systems across industries such as power generation, chemicals, food processing, metals, glass, and refining. Manufacturers are investing in burner technologies that improve fuel efficiency, reduce operating costs, and comply with stricter emission regulations.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By configuration: New machine/OEM installation segment held the largest market share of 58.2% in 2025.
- By fuel type: Gas segment held the largest market share of 50.9% in 2025.
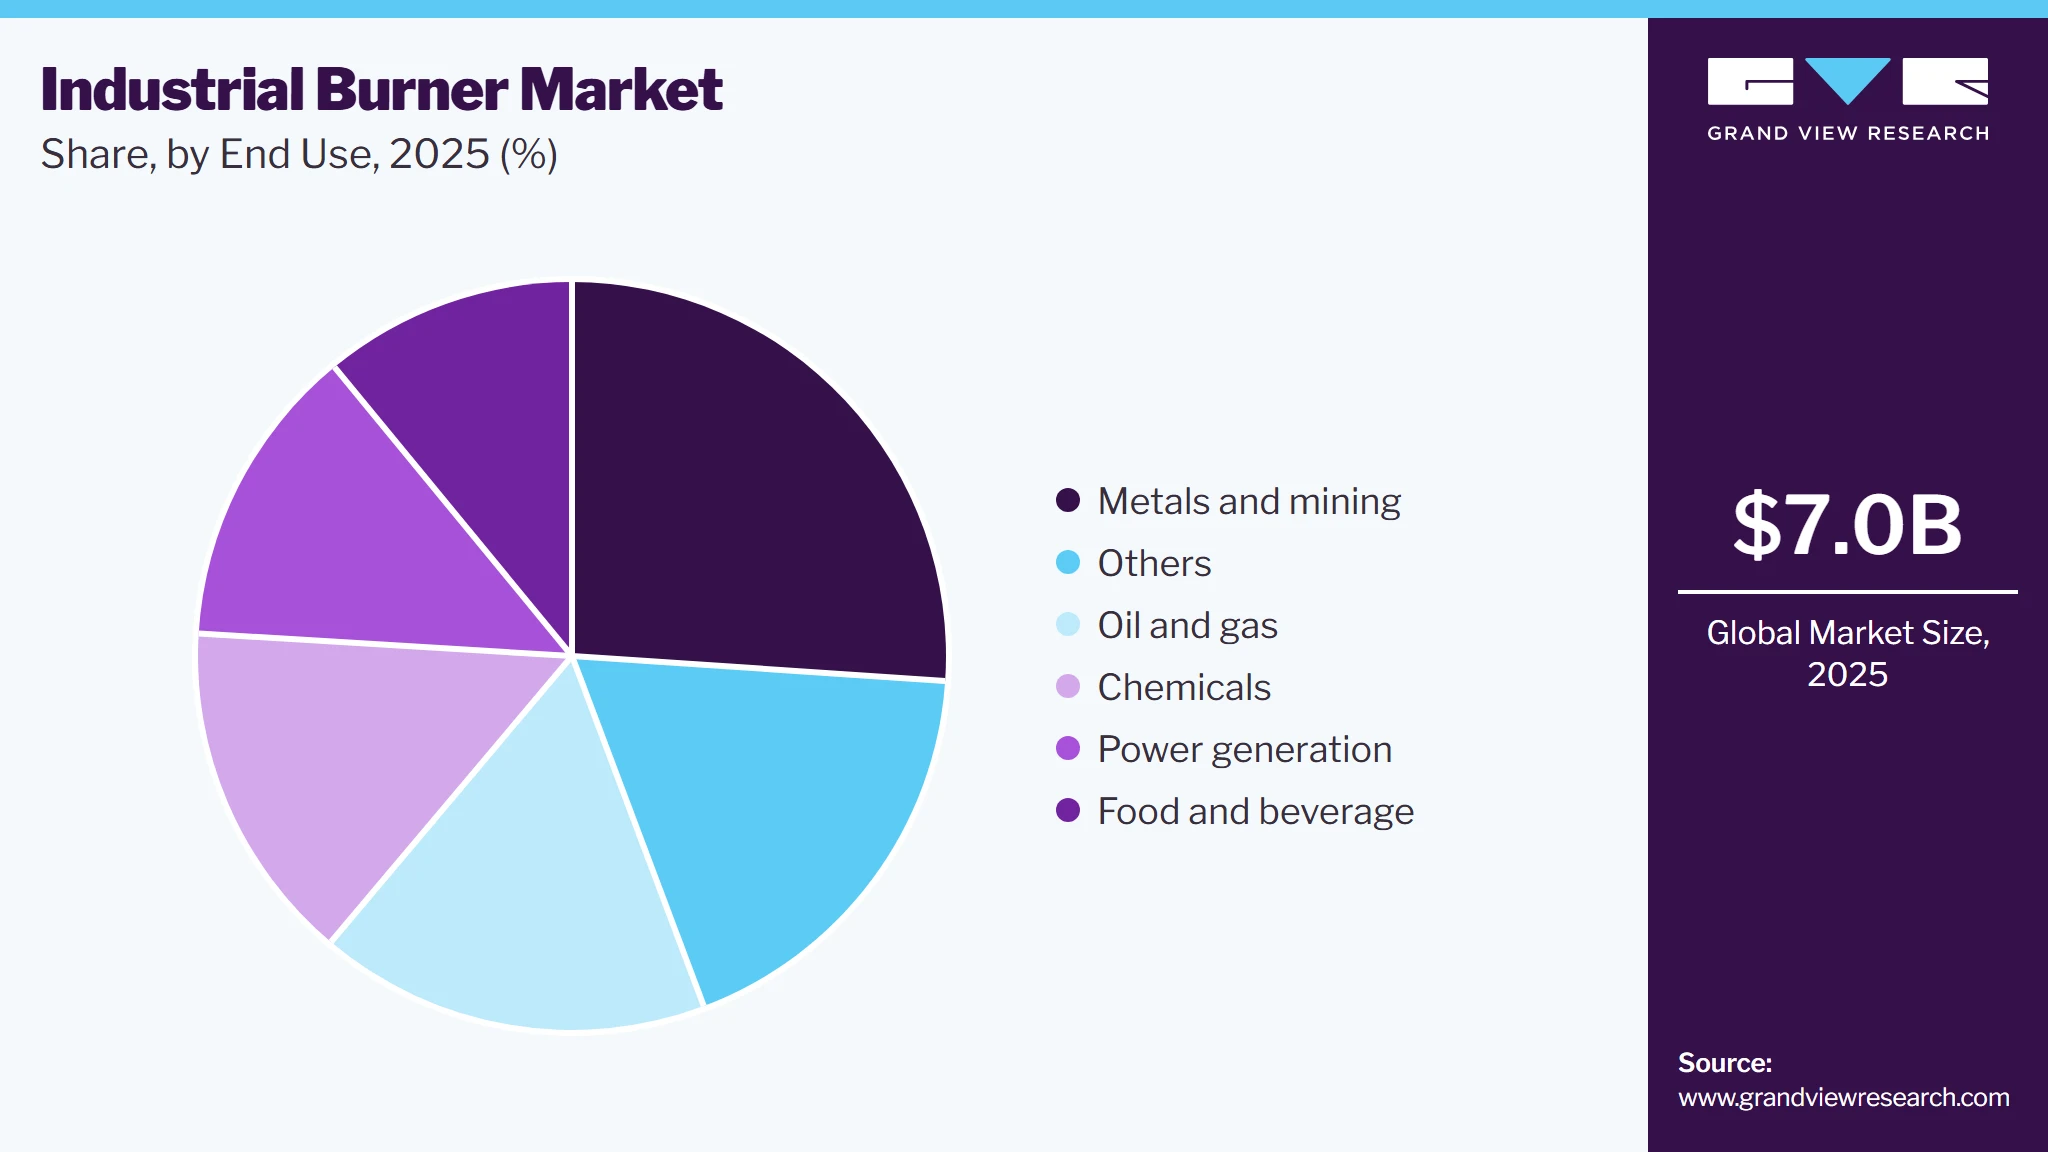
- By end use: Metals and mining segment held the largest market share of 26.1% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (39.0% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 7.0 Billion
- Estimated market size in 2026: USD 7.4 Billion
- Projected market size by 2033: USD 11.0 Billion
- CAGR (2026-2033): 5.8%
Prism AI by Grand View Research Free to tryAsk a question about the industrial burner market✓Every figure cited from GVR research Prefer the report? Download free sample →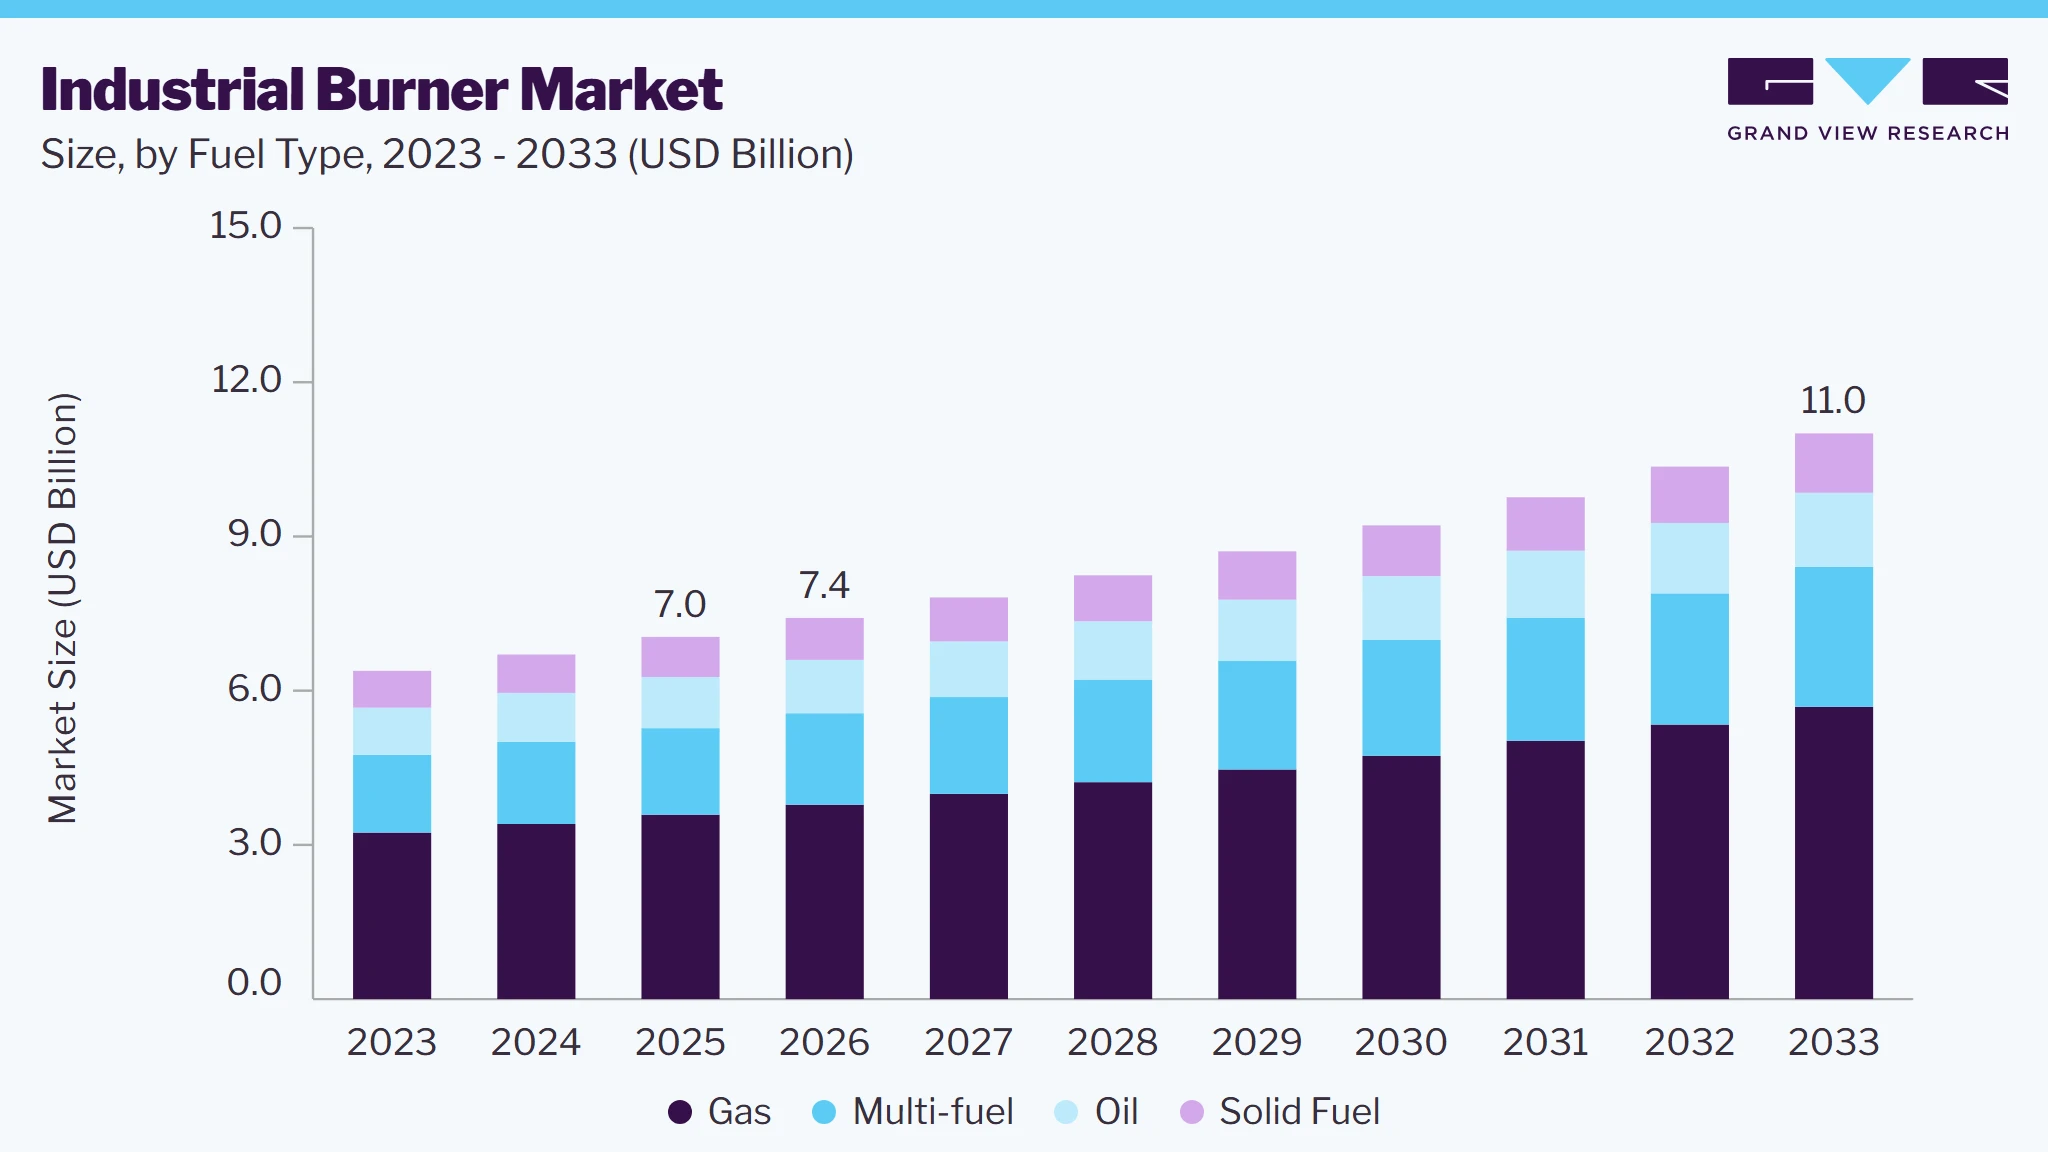 To learn more about this report, Download Free Sample Report
The adoption of low-NOx burner is increasing as industries seek to reduce nitrogen oxide emissions and comply with stricter environmental regulations. Digital combustion controls improve monitoring, automation, and fuel management, while fuel-flexible burner can operate with different fuels, including natural gas, hydrogen, and biofuels. These capabilities encourage industries to upgrade older combustion equipment for efficiency and compliance.Market Dynamics
The industrial burner market is influenced by industrial production, energy efficiency requirements, environmental regulations, and the modernization of combustion equipment. Demand varies across sectors such as chemicals, metals, food processing, power generation, glass, and refining. Manufacturers are developing low-NOx, ultra-low-NOx, fuel-flexible, and digitally controlled burner. At the same time, high installation costs, complex system integration, and fuel-price fluctuations affect purchasing decisions. Hydrogen and alternative-fuel adoption are creating additional market opportunities.
Rising energy costs and the need to improve industrial process efficiency are increasing demand for energy-efficient burner. Industrial facilities are replacing older combustion systems with burner that provide better fuel-air mixing, improved heat transfer, and precise combustion control. These systems can reduce fuel consumption while maintaining required process temperatures. Demand is particularly relevant in energy-intensive industries such as metals, ceramics, glass, chemicals, and food processing, supporting burner replacement and modernization projects.
High installation and replacement costs can restrain industrial burner adoption, particularly among small and medium-sized industrial facilities. Upgrading burner may require modifications to furnaces, boilers, combustion chambers, control systems, and associated infrastructure. Additional engineering, commissioning, and maintenance expenses increase the overall investment requirement. Customers may therefore continue operating existing equipment when performance remains acceptable, delaying replacement cycles and limiting short-term demand for advanced burner technologies.
The development of hydrogen-compatible industrial burner presents a significant opportunity as industries explore lower-carbon fuels for high-temperature processes. Manufacturers are developing burner capable of operating with hydrogen blends or 100% hydrogen while maintaining stable combustion and low emissions. Adoption can expand as hydrogen supply infrastructure develops and industrial users seek alternatives to conventional fossil fuels. This creates opportunities for burner suppliers offering fuel-flexible systems suitable for industrial heating applications.
Market Concentration & Characteristics
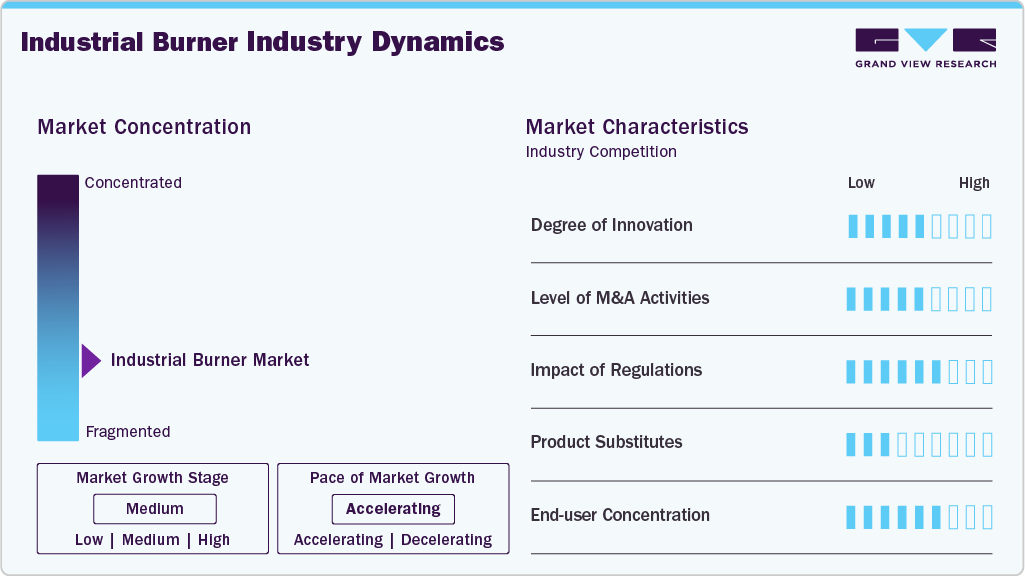
The industrial burner market is fragmented, with global manufacturers competing alongside regional and specialized suppliers. Companies differentiate through burner capacity, fuel compatibility, combustion technology, customization, and after-sales services. Established players generally serve large industrial projects, while smaller manufacturers focus on specific applications or geographic markets. The presence of numerous suppliers across Europe, North America, and Asia increases competition, particularly in standard burner systems and replacement equipment.
 To learn more about this report, Download Free Sample Report
Innovation in the industrial burner market is moderate to high, driven by requirements for higher combustion efficiency, lower emissions, and fuel flexibility. Manufacturers are developing low-NOx and ultra-low-NOx burners, digital combustion controls, intelligent monitoring systems, and hydrogen-compatible technologies. For instance, in January 2025 ClearSign Technologies and Zeeco expanded their partnership by introducing a co-branded process burner capable of operating on natural gas or 100% hydrogen while maintaining ultra-low emissions. The development supports industrial decarbonization efforts by enabling fuel flexibility and lower-emission combustion for applications requiring high-temperature process heating.
Environmental regulations are significantly shaping the industrial burner market by requiring industries to reduce nitrogen oxide, carbon monoxide, and other combustion-related emissions. Emission limits encourage replacement of conventional burner with low-NOx and ultra-low-NOx technologies. Efficiency standards and fuel-related regulations are also influencing equipment selection. In addition, policies supporting lower-carbon fuels are encouraging manufacturers to develop burner compatible with hydrogen, biogas, and other alternative fuels.
Analyst Perspective
The industrial burner market is influenced by increasing demand for energy-efficient combustion, industrial process heating, emissions reduction, and replacement of aging burner systems. Steel, metals, chemicals, refining, food processing, ceramics, glass, and other energy-intensive industries use industrial burner across furnaces, boilers, kilns, dryers, and process heaters. Adoption of low-emission burner, automated combustion controls, fuel-flexible systems, and hydrogen-compatible technologies is also supporting market development. Industrial capacity expansion and modernization of thermal processing equipment are further creating demand for new and replacement burner systems.
Fuel Type Insights
The gas segment led the market in 2025 as natural gas remains widely used for industrial heating due to its availability, controllable combustion, and relatively lower emissions than several liquid and solid fuels. Demand from the chemical, food & beverage, metals & mining, and other manufacturing industries, coupled with the replacement of aging combustion equipment, is expected to support the adoption of gas-fired industrial burners.
The multi-fuel segment is expected to grow at 6.3% CAGR during forecast period, as industries seek greater fuel flexibility and protection against fuel-price fluctuations or supply disruptions. Multi-fuel burner can operate with combinations of natural gas, hydrogen, biogas, oil, or other fuels, allowing facilities to adapt to changing energy availability and decarbonization requirements. Growing interest in alternative fuels is expected to further support their adoption.
Configuration Insights
The new machine/OEM installation segment dominated the market with the largest revenue share of 58.2% in 2025, as manufacturers invest in new industrial furnaces, boilers, ovens, dryers, and process-heating equipment. Industrial capacity expansion and modernization projects create demand for burners integrated during original equipment manufacturing. OEM installations also allow manufacturers to incorporate low-NOx combustion, digital controls, and fuel-flexible technologies directly into new systems.
The retrofit and replacement segment is expected to grow at 6.3% CAGR during forecast period as industries upgrade aging combustion equipment to improve efficiency, reduce emissions, and meet evolving environmental requirements. Replacement projects can involve upgrading burner while retaining existing furnaces or heating systems, reducing the need for complete equipment replacement. Demand likely to be supported by stricter emissions standards, aging industrial infrastructure, and energy-efficiency initiatives.
End Use Insights
The metals and mining segment led the market in 2025, holding 26.1% market share as industrial burners are increasingly used in furnaces, kilns, reheating systems, and metal-processing applications. Expansion of steel, aluminum, and non-ferrous metal production is increasing demand for high-temperature industrial heating. Investments in energy-efficient and low-emission combustion systems are also supporting the replacement and modernization of existing burner equipment across mining and metal-processing facilities.
 To learn more about this report, Download Free Sample Report
The chemicals segment is expected to grow with increasing demand for process heating in boilers, furnaces, dryers, heaters, and thermal treatment systems. Expansion of chemical manufacturing capacity and investments in specialty chemicals and petrochemical production are increasing requirements for reliable industrial heating. Adoption of energy-efficient and low-emission burner is also supporting equipment upgrades and replacement across chemical processing facilities.
Regional Insights
North America industrial burner market is expected to grow due to expansion of chemical and petrochemical processing capacity. The region has a large base of process industries that use burner in furnaces, process heaters, boilers, and thermal treatment equipment. New production capacity and investments in processing infrastructure are generating demand for industrial combustion systems. Increasing adoption of automated combustion controls is also supporting demand for burner that can provide precise temperature regulation in continuous industrial processes.
U.S. Industrial Burner Market Trends
The U.S. industrial burner market is expected to grow due to increasing domestic manufacturing activity. Expansion of industries such as metals, food processing, chemicals, and industrial manufacturing is creating additional requirements for process heating equipment. New and expanded production facilities require burners for furnaces, ovens, boilers, and dryers. The growth of domestic production capacity is therefore increasing demand for industrial combustion equipment across different manufacturing applications.
Asia Pacific Industrial Burner Market Trends
Asia Pacific industrial burner market dominated the global market and accounted for the largest revenue share of 39.0% in 2025, due to rapid expansion of industrial manufacturing capacity. Rising production of steel, chemicals, cement, ceramics, food products, and other manufactured goods is increasing requirements for high-temperature process heating. New factories and production lines require combustion equipment for furnaces, kilns, boilers, and dryers.
 To learn more about this report, Download Free Sample Report
Industrial burner market in China led the industrial burner market in Asia Pacific region due to large-scale steel and metal production. According to International Trade Administration, in 2025 China exported 131.0 million metric tons of steel a 14.5% increase from 2024. Growing steel production and processing activity is supporting demand for industrial burner used in reheating furnaces, heat treatment, forging, and other high-temperature applications.
India industrial burner market is growing in the due to increasing steel production capacity. For instance, in May 2026, JSW Steel commenced construction of a 13.2 MTPA greenfield integrated steel plant in Odisha, with an estimated investment of INR 65,000 crore (USD 6.8 billion) across 2,950 acres. The project is expected to expand India’s steel production capacity and increase demand for industrial heating equipment, including burner used in furnaces, reheating systems, and other high-temperature steelmaking processes.
Europe Industrial Burner Market Trends
Europe industrial burner market is expected to grow due to the transition toward lower-carbon industrial heating. Manufacturers are increasingly evaluating burner capable of operating with alternative fuels, including hydrogen and hydrogen blends. This is creating demand for combustion systems that can accommodate changing fuel requirements while maintaining process temperatures. Industries such as metals, chemicals, ceramics, and glass are important users of these technologies as they seek to reduce the carbon intensity of thermal processes.
Germany industrial burner market is expected to grow mainly due to hydrogen-compatible industrial heating development. The country’s energy-intensive manufacturing industries are evaluating hydrogen and other lower-carbon fuels for high-temperature processes. This is encouraging demand for burner technologies capable of handling alternative fuel mixtures while maintaining stable combustion. Steel, glass, ceramics, and chemical manufacturers represent important application areas due to their reliance on high-temperature industrial heating.
The UK industrial burner market is expected to grow due to decarbonization of industrial heat. Industrial companies are evaluating electrification and alternative-fuel combustion technologies, including hydrogen-based heating, for applications where conventional fossil-fuel systems remain important. Food processing, ceramics, glass, and chemical industries are among the sectors where industrial heating requirements can support adoption of advanced burner technologies.
Middle East & Africa Industrial Burner Market Trends
Expansion of downstream oil and gas processing is driving the Middle East and Africa industrial burner market. Investments in refineries, petrochemical plants, and associated processing facilities are increasing demand for burner used in process heaters, furnaces, boilers, and thermal systems. Growth in downstream capacity is shifting some regional activity beyond crude oil production toward value-added processing, creating additional requirements for industrial combustion equipment.
Industrial burner market in Saudi Arabia is expected to grow due to expansion of petrochemical manufacturing. Increasing downstream processing capacity is creating requirements for process heaters, furnaces, boilers, and other equipment that use industrial burner. Petrochemical production involves several high-temperature processes, making combustion systems an important component of new processing facilities. Expansion of downstream industrial capacity is therefore supporting demand for burner across petrochemical applications.
Latin America Industrial Burner Market Trends
Latin America is expected to grow at 6.1% CAGR during forecast period in industrial burner market. Countries across Latin America have significant agricultural and food-processing industries that use thermal equipment such as industrial ovens, dryers, boilers, and process heaters. Increasing processing of agricultural commodities and packaged food products is creating demand for combustion equipment. This application growth is supporting industrial burner demand beyond traditional heavy industries.
Industrial burner market in Brazil is expected to grow mainly due to expansion of steel production and metal processing. Increasing steelmaking capacity and downstream metal-processing activities are creating demand for high-temperature industrial heating equipment, including reheating furnaces, heat-treatment furnaces, and process heaters. These applications require reliable combustion systems to maintain controlled and consistent temperatures. Investments in steel-processing facilities and expansion of production capacity are therefore expected to support demand for industrial burner in Brazil.
Key Industrial Burner Company Insights
Some of the key players operating in the market include Honeywell International Inc., Fives Group, ANDRITZ AG, John Zink Hamworthy Combustion, Weishaupt Group, Riello S.p.A., among others.
-
Honeywell International Inc. is a diversified technology and manufacturing company with operations spanning industrial automation, aerospace, building technologies, and energy-related solutions. Its industrial combustion portfolio includes burner management systems, combustion controls, and related technologies used in industrial heating applications. Honeywell serves industries such as refining, petrochemicals, chemicals, metals, and manufacturing, where combustion control and process monitoring are required.
-
Fives Group is an industrial engineering company that provides equipment and process solutions for energy-intensive industries. Its combustion activities include industrial burner, combustion systems, and associated technologies for furnaces and thermal processing equipment. Fives serves sectors including steel, aluminum, cement, glass, and other industries requiring high-temperature industrial processes. Its solutions cover new installations as well as equipment upgrades.
Key Industrial Burner Companies
The following key companies have been profiled for this study on the industrial burner market.
-
Honeywell International Inc.
-
Fives Group
-
ANDRITZ AG
-
John Zink Hamworthy Combustion
-
ALZETA Corporation
-
Weishaupt Group
-
Riello S.p.A.
-
Oilon Group Oy
-
ELCO GmbH
-
SAACKE GmbH
-
Babcock Wanson
-
Selas Heat Technology LLC
-
Zeeco, Inc.
-
Baltur S.p.A.
- Nu-Way Burner Company
Company Categorization
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Honeywell International Inc., Fives Group, ANDRITZ AG, John Zink Hamworthy Combustion, Weishaupt Group, Riello S.p.A.
- These manufacturers focus on expanding product portfolios, developing low-emission and fuel-flexible combustion technologies, maintaining global distribution networks, and providing installation and aftermarket services.
- They also invest in research and development to address efficiency, automation, emissions, and industry-specific process-heating requirements.
- Mature players benefit from extensive industry experience, established customer relationships, broad geographic presence, recognized technical capabilities, and large installed equipment bases.
- Their ability to provide integrated burner, combustion-control, and burner-management solutions enables them to serve large industrial projects and long-term replacement requirements.
- These manufacturers face higher operating costs owing to large organizational structures, extensive facilities, and complex supply networks.
- Their broader product portfolios can also reduce flexibility compared with specialized manufacturers, while legacy product platforms may require significant investment to incorporate emerging combustion technologies.
Emerging Players: ALZETA Corporation, Selas Heat Technology LLC, Nu-Way Burner Company.
- Emerging players generally focus on specialized applications, customized burner designs, regional markets, and niche combustion requirements.
- They emphasize technological development, flexible production, direct customer engagement, and partnerships with engineering companies to enter industrial heating applications without requiring extensive global infrastructure.
- Emerging players can compete through customized solutions, shorter response times, specialized technical expertise, and competitive pricing. Their smaller organizational structures can enable faster product development and customer-specific modifications.
- Focus on alternative fuels, digital combustion controls, and low-emission technologies can provide opportunities in specialized applications.
- Emerging players generally have smaller installed bases, limited geographic coverage, and lower brand recognition than established manufacturers. Restricted financial resources can constrain research, manufacturing expansion, and aftermarket networks.
- Limited experience with large industrial projects may also make it difficult to compete for major international contracts.
Recent Developments
-
In June 2026, DUNGS acquired IBS Industrie-Brenner-Systeme GmbH, a German manufacturer of industrial burner systems. The acquisition expands DUNGS’ product scope beyond combustion controls, gas trains, and safety components to include complete industrial burner systems. IBS’s high- and low-temperature process burner capabilities strengthen DUNGS’ position across industrial heating applications and broaden its offerings for process industries requiring integrated combustion solutions.
-
In May 2026, R.W. Beckett Corporation acquired Wayne Combustion Systems, expanding its industrial burner portfolio. The acquisition combines two established combustion engineering companies with complementary applications across commercial, food service, and industrial markets.
Industrial Burner Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.0 billion
Estimated market size in 2026
USD 7.4 billion
Projected market size by 2033
USD 11.0 billion
Growth rate
CAGR of 5.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market position analysis, competitive landscape, growth factors, and trends
Segments covered
Fuel type, configuration, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; and Middle East & Africa
Country Scope
U.S.; Canada; Mexico; Germany; UK; Italy; Spain; France; China; Japan; India; Australia; South Korea; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
Honeywell International Inc.; Fives Group; ANDRITZ AG; John Zink Hamworthy Combustion; ALZETA Corporation; Weishaupt Group; Riello S.p.A.; Oilon Group Oy; ELCO GmbH; SAACKE GmbH; Babcock Wanson; Selas Heat Technology LLC; Zeeco Inc.; Baltur S.p.A.; Nu-Way Burner Company
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Industrial Burner Market Report Segmentation
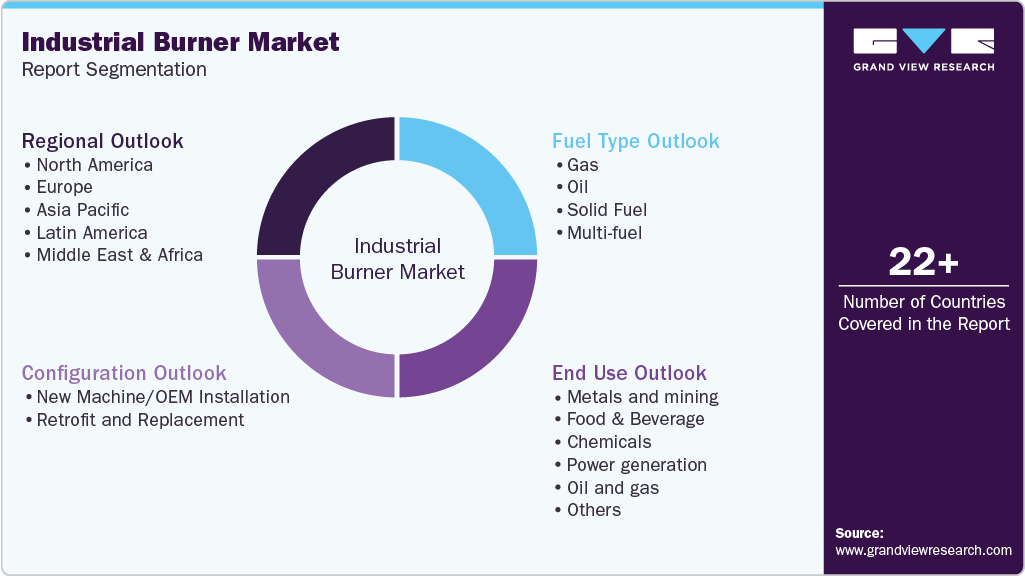
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the industrial burner market based on fuel type, configuration, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Fuel Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Gas
-
Oil
-
Solid Fuel
-
Multi-fuel
-
-
Configuration Outlook (Revenue, USD Billion, 2021 - 2033)
-
New Machine/OEM Installation
-
Retrofit and Replacement
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Metals and mining
-
Food & Beverage
-
Chemicals
-
Power generation
-
Oil and gas
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The industrial burner market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each industrial burner segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product Type
Revenue Capture Definition
Gas
Revenue is derived from the sale of industrial burner designed to operate primarily on gaseous fuels such as natural gas, LPG, biogas, and other combustible gases.
Oil
Revenue is generated from industrial burner designed to operate using liquid fuels such as diesel, fuel oil, light oil, and heavy oil for industrial heating applications.
Solid Fuel
Revenue is captured from industrial burner designed to combust solid fuels such as coal, biomass, wood pellets, and other solid combustible materials.
Multi-fuel
Revenue is obtained from industrial burner capable of operating with two or more fuel types, including combinations such as gas and oil or gas and biomass.
Configuration
Revenue Capture Definition
New Machine/OEM Installation
Revenue is derived from industrial burner installed in newly manufactured machinery, furnaces, boilers, kilns, process heaters, or newly constructed industrial facilities.
Retrofit and Replacement
Revenue is generated from industrial burner supplied to replace existing equipment or retrofit industrial heating systems to improve combustion performance, fuel efficiency, emissions performance, or operating capability.
End Use
Revenue Capture Definition
Metals and mining
Revenue comprises sales of industrial burner supplied for metal production, metal processing, mining-related thermal processes, furnaces, reheating, and heat-treatment applications.
Food & Beverage
Revenue is obtained from industrial burner used in food and beverage processing, including boilers, ovens, dryers, fryers, and other industrial heating equipment.
Chemicals
Revenue is generated from industrial burner supplied for chemical manufacturing and processing, including process heating, furnaces, boilers, dryers, and thermal treatment systems.
Power generation
Revenue is captured from industrial burner used in power-generation facilities, including boilers, auxiliary heating systems, and other combustion-based thermal applications.
Oil and gas
Revenue is derived from industrial burner used in oil and gas extraction, refining, processing, petrochemical operations, process heaters, furnaces, and boilers.
Others
Revenue includes sales of industrial burner supplied to glass, ceramics, textiles, and pulp and paper industries.
Estimation Model
Layer Name
Key Question
Description
Industrial Production & Process Heating Demand Layer
Which industries generate demand for industrial burner?
The estimation begins by evaluating industrial production and process-heating requirements across metals and mining, oil and gas, chemicals, power generation, food and beverage, and other end-use industries. Production capacity, furnace and boiler requirements, process temperatures, fuel consumption, and industrial facility additions establish the base demand for industrial burner.
Fuel Type & Burner Technology Layer
Which fuel types and burner technologies drive market demand?
This layer refines demand by assessing gas, oil, solid-fuel, and multi-fuel industrial burner. Demand is evaluated based on fuel availability, combustion requirements, operating temperature, energy efficiency, emissions requirements, and compatibility with industrial heating equipment.
End-Use & Deployment Layer
What determines industrial burner utilization and installation?
Market demand is estimated through burner deployment across metals and mining, oil and gas, chemicals, power generation, food and beverage, and other industries. Industrial production capacity, process-heating requirements, facility expansion, equipment replacement cycles, fuel requirements, and environmental regulations influence new installations and replacement demand.
Revenue Layer
How is total market revenue calculated?
Revenue is estimated by aggregating spending on industrial burner across fuel types, end-use industries, configurations, and regional markets. New machine/OEM installations and retrofit and replacement demand are assessed using burner shipments, average selling prices, system specifications, installation requirements, and replacement activity to validate the total market size.
Delivered Customizations
We have successfully delivered the following deep-dive customizations:
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed regional analysis was conducted across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, including country-level assessment for key markets such as the U.S., Germany, China, India, Brazil, and Saudi Arabia. The study evaluated industrial production, steel and metals manufacturing, chemical and petrochemical activity, refining capacity, energy-intensive industries, environmental regulations, and investments in industrial heating infrastructure influencing industrial burner demand.
Helped identify regional differences in industrial burner adoption, country-specific demand patterns, and markets with increasing requirements for process heating equipment. The analysis also supported assessment of industrial capacity expansion, emissions regulations, fuel-transition initiatives, and modernization of combustion systems across major markets.
Competitive benchmarking
Comprehensive benchmarking was carried out for major industrial burner market participants based on product portfolios, burner types, fuel compatibility, firing capacity, combustion efficiency, emissions performance, automation capabilities, industry coverage, manufacturing capabilities, geographic presence, distribution networks, and aftermarket services.
Assisted clients in understanding competitor positioning, combustion technology capabilities, product differentiation, geographic coverage, and service offerings within the industrial burner market.
Opportunity assessment
In-depth opportunity assessment was conducted by analyzing industrial production, steel and metals manufacturing, chemicals, refining, food processing, ceramics, glass, and other process industries. The study evaluated opportunities related to low-emission burner, high-efficiency combustion systems, automated burner controls, fuel-flexible systems, hydrogen-compatible burner, and replacement of aging combustion equipment.
Enabled clients to identify markets with increasing industrial burner demand and evaluate opportunities across end-use industries and technology segments.
Frequently Asked Questions About This Report
The gas segment led the market and accounted for 50.9% market revenue share in 2025.
The new machine/OEM installation segment led the market and accounted for 58.2% market revenue share in 2025.
The metals and mining segment led the market and accounted for 26.1% market revenue share in 2025.
Some of the key players operating in the industrial burner include Honeywell International Inc., Fives Group, ANDRITZ AG, John Zink Hamworthy Combustion, ALZETA Corporation, Weishaupt Group, Riello S.p.A., Oilon Group Oy, ELCO GmbH, SAACKE GmbH, Babcock Wanson, Selas Heat Technology LLC, Zeeco, Inc., Baltur S.p.A., Nu-Way Burner Company
Key factors driving the industrial burner market include expansion of energy-intensive industries, increasing demand for process heating, replacement of aging combustion equipment, adoption of energy-efficient and low-emission burner, industrial capacity additions, and growing use of automated combustion-control systems across metals, chemicals, oil and gas, food processing, and power generation industries.
The Asia Pacific region led the market and accounted for 39.0% of the global market revenue share in 2025.
The global industrial burner market is expected to grow at a CAGR of 5.8% from 2026 to 2033, reaching USD 11.0 billion by 2033.
The Asia Pacific region is expected to grow at 6.8% CAGR during the forecast period.
The global industrial burner market size was valued at USD 7.0 billion in 2025 and is estimated at USD 7.4 billion for 2026.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


