
- Home
- »
- Advanced Interior Materials
- »
-
Inverter Welding Equipment Market Size, Share Report, 2033GVR Report cover

Inverter Welding Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type, (Manual Arc Welding, Mechanized Arc Welding), By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$5.2BMarket Estimate, 2026
$5.5BMarket Forecast, 2033
$8.1BCAGR, 2026–2033
5.7%Inverter Welding Equipment Market Summary
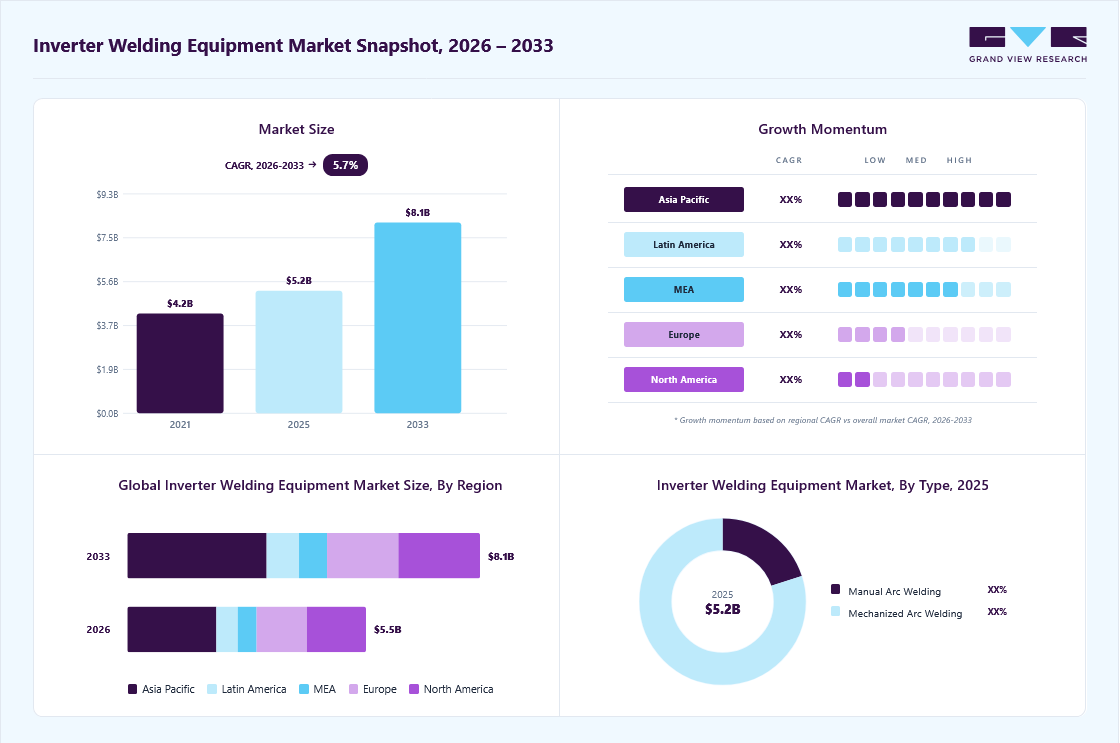
The global inverter welding equipment market size was valued at USD 5.2 billion in 2025 and is projected to grow from USD 5.5 billion in 2026 to USD 8.1 billion by 2033, at a CAGR of 5.7% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 37.0% in 2025. The global market is witnessing steady growth, driven by the widespread adoption of inverter welding equipment across the automotive, construction, shipbuilding, and aerospace industries. Additionally, the rising focus on sustainable manufacturing processes and reducing operational costs has contributed to the growth of this market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Mechanized arc welding segment held the largest market share of 80.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (37.0% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.2 Billion
- Estimated market size in 2026: USD 5.5 Billion
- Projected market size by 2033: USD 8.1 Billion
- CAGR (2026-2033): 5.7%
Prism AI by Grand View Research Free to tryAsk a question about the inverter welding equipment marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The growing adoption of inverter welding equipment in the automotive industry is driving market growth. Inverter technology ensures precise control of spot-welding parameters with rapid response times, enhancing weld quality and efficiency. It also offers an improved power factor, reduced energy consumption, and superior weld appearance & strength owing to significantly shorter operation times.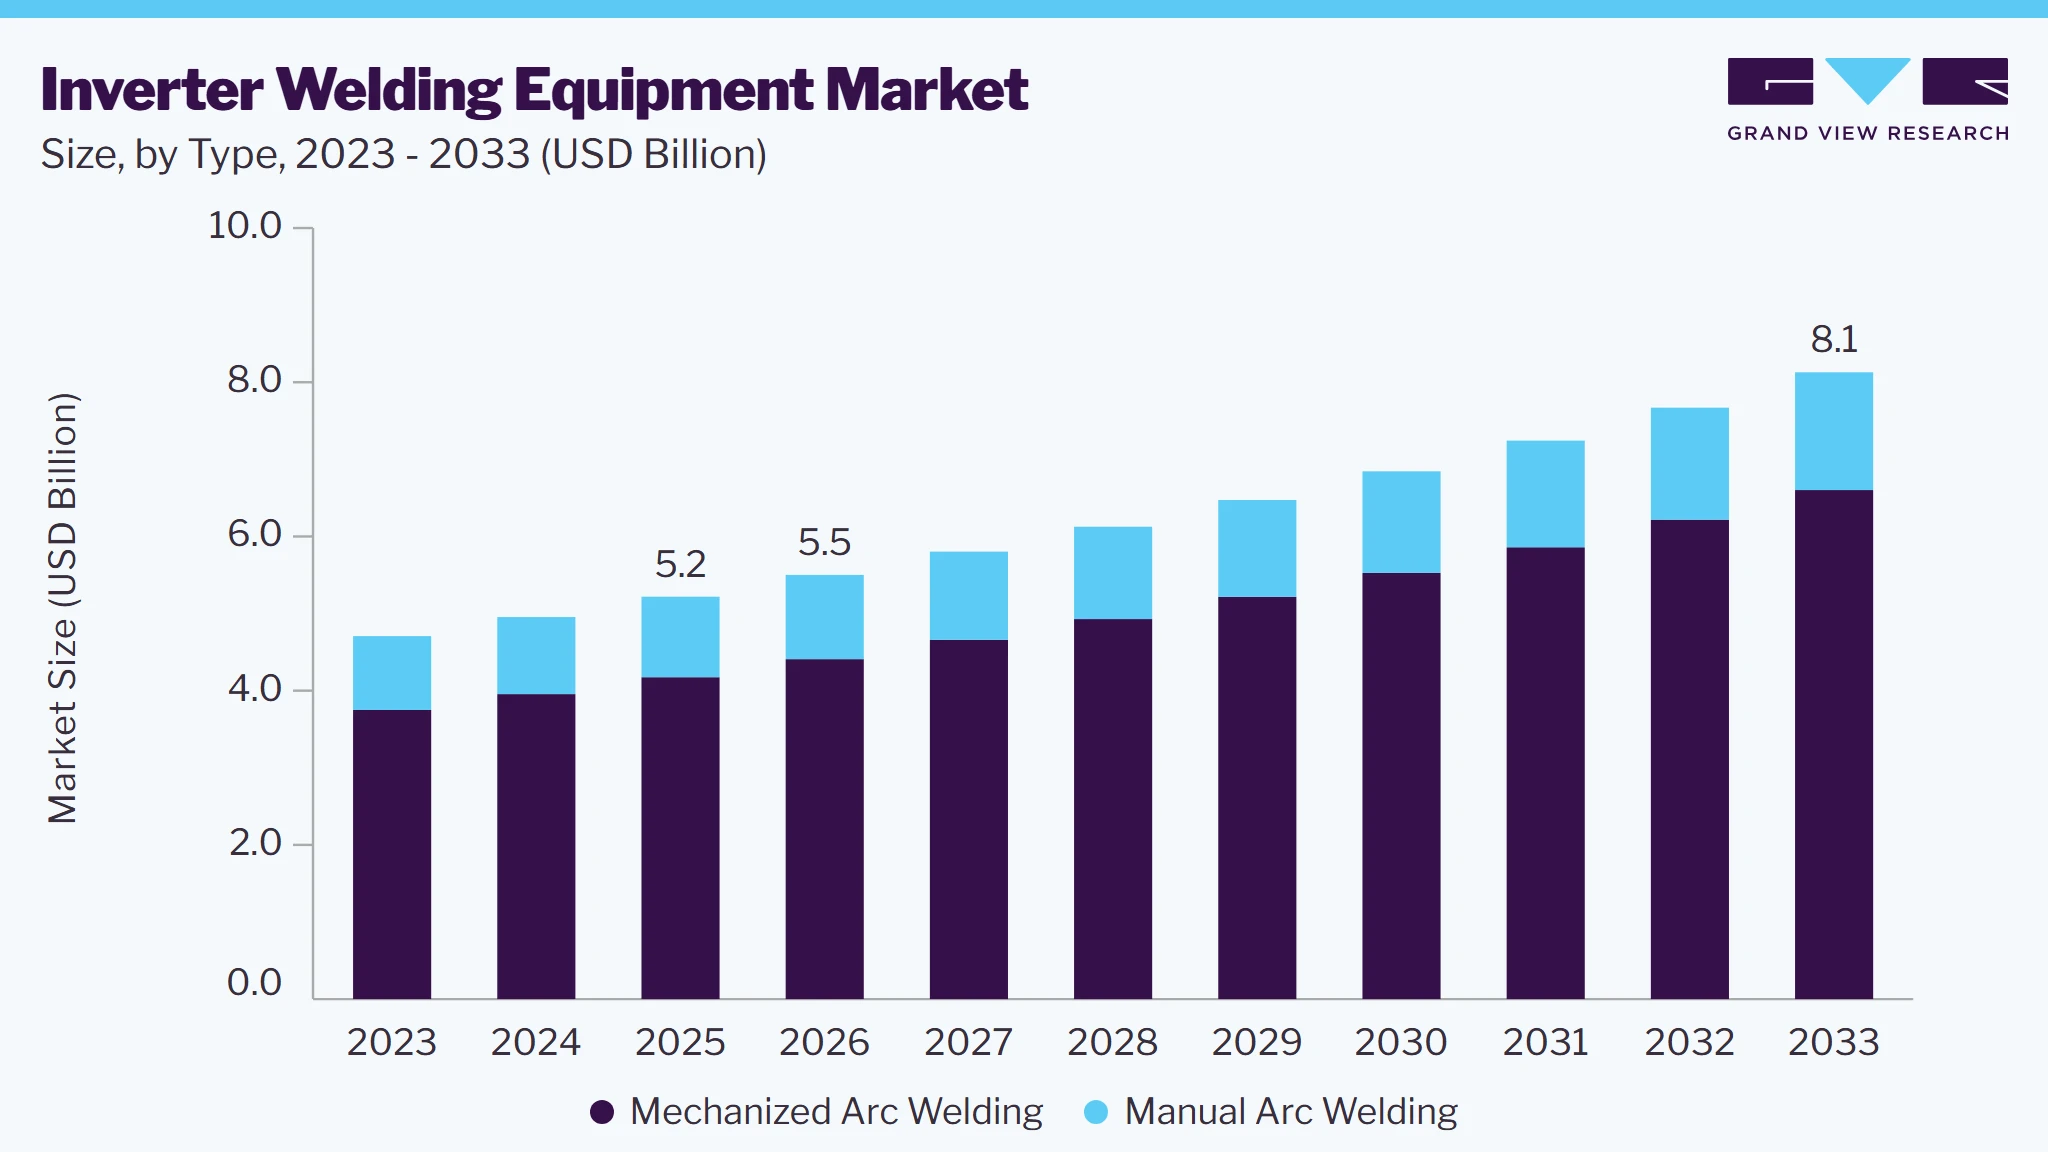 To learn more about this report, Download Free Sample Report
Market Dynamics
The inverter welding equipment market is driven by strong demand from automotive, construction, shipbuilding, aerospace, and general manufacturing industries, where high precision, reliability, and operational efficiency are critical. The ongoing shift from conventional welding systems to inverter-based technologies is supported by their compact design, reduced power consumption, and improved arc stability. Advancements in digital control systems, inverter circuitry, and multi-process welding capabilities are enhancing welding accuracy, productivity, and overall process consistency. The increasing integration of automation and robotics in manufacturing facilities is also supporting the adoption of inverter welding systems that can be easily integrated into smart production environments. However, the relatively high initial investment and maintenance requirements of advanced systems continue to restrict wider adoption among small and medium-scale enterprises.
The inverter welding equipment market is primarily driven by increasing adoption of automation across manufacturing industries, including automotive, construction, shipbuilding, aerospace, and heavy engineering. Manufacturers are progressively shifting from conventional welding systems to inverter-based solutions due to their superior energy efficiency, compact design, and enhanced arc stability, which support higher productivity and improved weld quality.
In addition, the growing integration of robotic welding systems and digitally controlled fabrication processes is strengthening demand for inverter welding technologies that are compatible with smart manufacturing environments. Expansion of industrial infrastructure, coupled with rising focus on operational efficiency and cost optimization, is further supporting adoption across large-scale and mid-sized production facilities.
The inverter welding equipment market is constrained by the high initial investment required for advanced systems, which limits adoption among small and medium-sized enterprises. Costs associated with procurement, system integration, and workforce training further increase the overall financial burden, extending payback periods and discouraging replacement of conventional welding equipment.
In addition, the technical complexity of inverter-based systems requires skilled operators and regular maintenance, which can be challenging in price-sensitive and less industrialized markets. Fluctuations in electronic component costs and supply chain dependencies also impact pricing stability, further restricting wider market penetration.
The increasing adoption of Industry 4.0 technologies, automation, and robotic welding systems is creating significant opportunities for inverter welding equipment manufacturers. Integration of IoT-enabled monitoring, predictive maintenance, and digitally controlled welding processes is enhancing productivity, precision, and operational reliability across manufacturing facilities.
Furthermore, growing investments in electric vehicle production, renewable energy infrastructure, and advanced construction projects are expanding the application scope for high-performance welding solutions. Rising industrialization in emerging economies and increasing demand for lightweight and high-strength materials in automotive and aerospace sectors are further strengthening the need for advanced inverter-based welding technologies.
Market Concentration & Characteristics
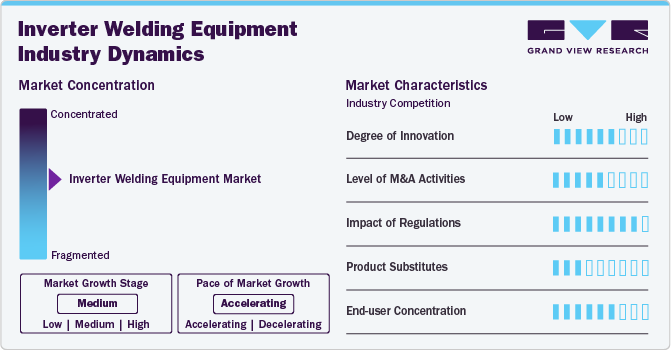
The inverter welding equipment market exhibits a moderate level of concentration, characterized by a blend of established domestic manufacturers and prominent global players. Leading brands dominate the landscape by leveraging their strong brand reputation, extensive distribution networks, and comprehensive service offerings. The participation of international manufacturers has notably influenced market dynamics, introducing technological innovations and competitive pricing strategies that enhance the overall landscape.
This competitive environment compels companies to invest continuously in research and development, striving to deliver reliable, energy-efficient, and advanced inverter welding solutions that cater to the diverse needs of industrial and commercial clients. Notably, the demand for inverter welding equipment is on the rise, driven by economic growth, increased construction and manufacturing activities, and a heightened need for versatile and efficient welding solutions across various applications.
 To learn more about this report, Download Free Sample Report
Market characteristics reveal a growing trend toward energy-efficient and environmentally friendly welding equipment, supported by regulatory frameworks aimed at promoting sustainability and minimizing operational costs. This shift not only improves operational efficiency but also aligns with broader goals of environmental responsibility within the industry. Overall, the North American inverter welding equipment market is evolving, emphasizing innovation, efficiency, and sustainability.
Analyst Perspective
The inverter welding equipment market is gaining momentum as manufacturers increasingly shift toward energy-efficient, lightweight, and digitally controlled welding solutions. Compared to conventional transformer-based systems, inverter welders offer greater portability, improved arc stability, lower power consumption, and better welding precision, making them well suited for modern fabrication environments. Demand is being supported by expanding infrastructure projects, automotive production, renewable energy installations, and industrial automation, where productivity and weld quality are critical. At the same time, the growing adoption of mechanized and semi-automated welding processes is encouraging investment in advanced inverter-based equipment.
Type Insights
Based on the type, the mechanized arc welding segment led the market with the largest revenue share of 80.0% in 2025. The demand for the mechanized arc welding type segment is expected to grow at a notable CAGR of 5.8% from 2025 to 2030 in terms of revenue. Mechanized arc welding brings automation to the welding process, improving efficiency, accuracy, and safety across various industries. By mechanizing aspects of welding such as angles, speed, and stick-out length, the process gains partial automation while still under the vigilant supervision of an operator. These adjustments can be made on the fly to ensure optimal performance.
Manual arc welding, also known as manual metal arc welding (MMAW) or shielded metal arc welding (SMAW), is a widely used fabrication process that creates an electric arc between a coated electrode and the workpiece to melt and fuse metals. Manual arc welding is favored in various industries owing to its flexibility, thereby allowing high-quality welds on thick materials. Moreover, it can used in various challenging environments, such as at heights or in confined spaces in shipyards or construction sites. The simplicity and minimal equipment requirements of this welding method also appeal to small- and medium-sized enterprises and hobbyists, as well as users in remote locations.
Regional Insights
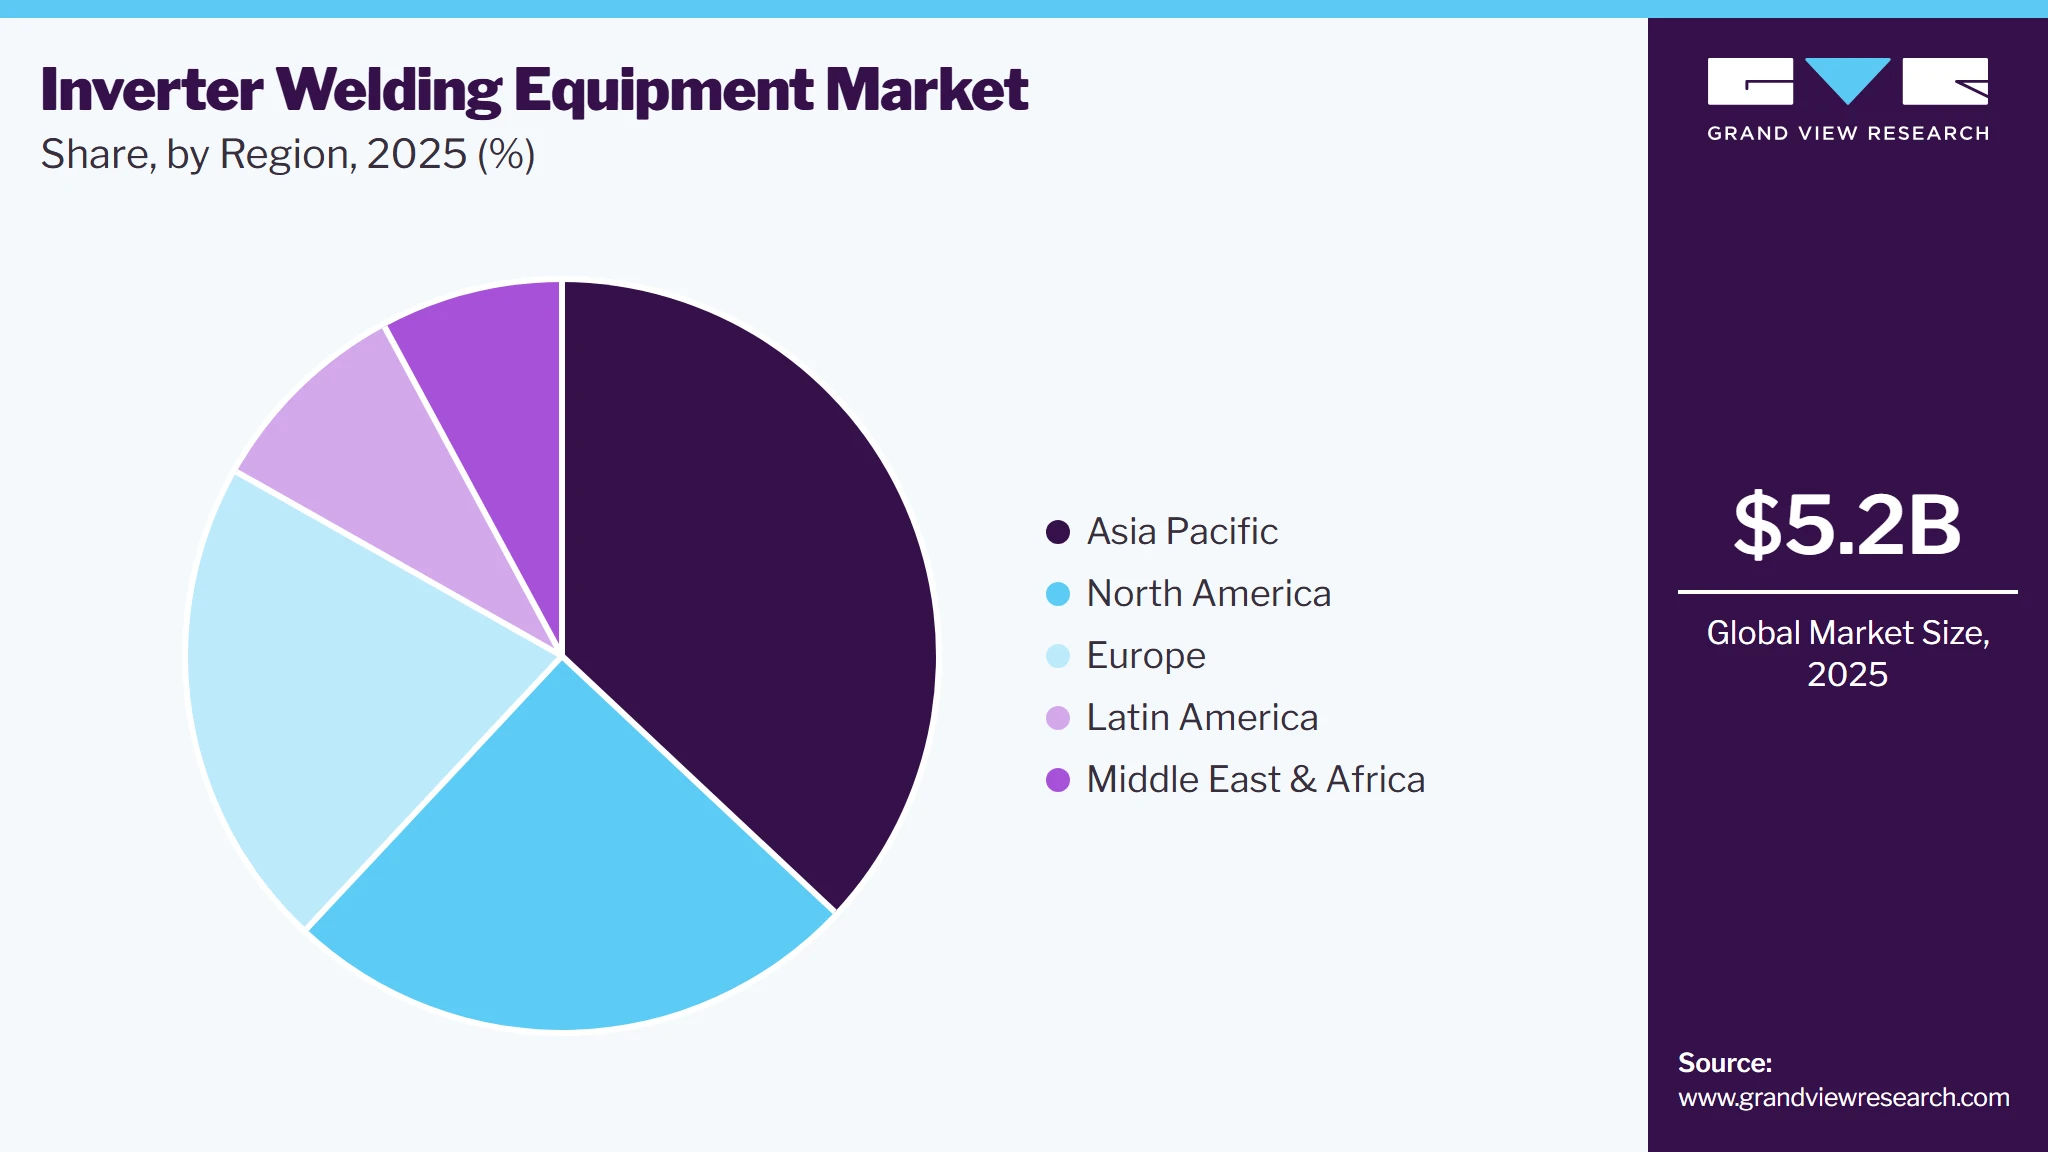
North America inverter welding equipment market accounted for 25.0% of the global revenue share in 2025. The demand is projected to be driven by the growing usage of inverter welding equipment in key application industries, such as aerospace, automotive, oil & gas, and power generation. North America is witnessing rapid expansion owing to the industrial dynamism and easy availability of raw materials in its countries. In addition, the increasing number of oil & gas plants in the U.S. and Canada is anticipated to surge the demand and the requirement for inverter welding equipment in North America.
 To learn more about this report, Download Free Sample Report
U.S. Inverter Welding Equipment Market Trends
The inverter welding equipment market in the U.S. is expected to grow at a CAGR of 4.7% from 2026 to 2033. As the U.S. is one of the prime automotive markets in North America, it witnesses high consumption of welding equipment by established players such as Ford, Toyota, GM, Nissan, and Chevrolet. Continuous improvements, development of innovative manufacturing methods, technological advancements, and application of standard and specific welding techniques are expected to help overcome the challenges and aid in the robust growth of the welding equipment market in the U.S.
Canada inverter welding equipment market is expected to grow at a CAGR of 5.0% from 2026 to 2033. Inverter welding equipment market in Canada is expected to grow at a significant rate during the forecast period owing to the rising demand for welding equipment from various end-use industries such as construction, automotive, and shipbuilding.
Europe Inverter Welding Equipment Market Trends
The inverter welding equipment market in Europe held a significant share in 2025. Europe is one of the largest producers of automobiles across the globe and attracts maximum foreign direct investment (FDI) in the automotive sector. Process innovation, improving R&D, and expansion of automobile production in countries such as Germany, the UK, and France are expected to fuel the growth of the automotive sector over the forecast period.
Germany's inverter welding equipment market held a 25.8% revenue share in the European market in 2025. Germany is witnessing a rapidly expanding infrastructure as the government is increasingly investing in the development of transport and broadband infrastructure. In the 2030 Federal Transport Infrastructure Plan, the government has planned to invest USD 147.6 billion for the construction of roads till 2030 and allocate USD 74 billion for maintenance and replacement infrastructure. Welding is a key joining technology used for infrastructure development including rail tracks, bridges, and other steel structures.
The inverter welding equipment market in the UK held a substantial share of the Europe market. In the UK, an increase in the number of new industrial & commercial buildings and the output of the refurbishment market are boosting the growth of the inverter welding equipment market in the economy. Thus, the increasing utilization of metal panels in the roofing industry is propelling the demand for welding, which is majorly used for installation.
Asia Pacific Inverter Welding Equipment Market Trends
Asia Pacific dominated the inverter welding equipment market with the largest revenue share of 37.0% in 2025. According to the World Bank, Asia Pacific is the fastest-growing region in terms of both population and economic growth. Rapid urbanization, increased investments by governments, and rising consumer spending have boosted the Asian economy, thereby propelling infrastructure development in the construction industry. Economies such as China, India, and Japan are the key countries driving the development of the oil & gas, automotive, aviation, and building & construction industries in this region.
The inverter welding equipment market in China held the largest share in the Asia Pacific region in 2025. Increased government spending on the One Belt, One Road (OBOR) project in China, wherein the Belt indicates a network of roadways and road implies sea routes, is projected to have a positive impact on infrastructural development in the country. This project involves the construction of a large network of maritime ports, roadways, railways, oil & gas pipelines, power grids, and associated infrastructure. Thus, increased government spending on such infrastructure development projects is expected to drive the demand for inverter welding equipment.
India inverter welding equipment market is expected to grow at a CAGR of 7.0% from 2026 to 2033. Expanding population and urbanization are likely to drive infrastructural development projects in India. Continuing economic development in the country is expected to trigger the growth of the construction market. The Indian construction industry is expected to exhibit significant growth owing to the high level of investments in energy projects under programs such as the National Skill Development Mission (NMSD), Atal Mission for Rejuvenation and Urban Transformation (AMRUT), 100 Smart Cities Mission, Make in India, and Power for all (PFA), which, in turn, are anticipated to have a positive impact on the product demand.
Middle East & Africa Inverter Welding Equipment Market Trends
The Middle East & Africa is projected to be emerging markets for inverter welding equipment over the forecast period on account of the rising number of civil engineering and commercial construction activities in the region, including the construction of stadiums and hotels. In December 2021, the UAE government launched a railways program worth USD 13.6 billion. The UAE railways initiative is expected to witness the construction of a 1200km rail network connecting the Saudi border to Fujairah. This investment in railroads is expected to open new market opportunities for inverter welding equipment manufacturers.
Saudi Arabia inverter welding equipment market does not have a substantial vehicle production base. The country's primary objective is to become the next automotive center in the Middle East. Despite being a significant importer of vehicles and auto parts, the government is currently striving to entice original equipment manufacturers (OEMs) to construct production units in the country to develop the domestic auto sector, which is anticipated to increase the demand for inverter welding equipment.
Latin America Inverter Welding Equipment Market Trends
The inverter welding equipment market in Latin America has been witnessing an inflow of new companies, particularly from North America in the region. Most of the manufacturing and construction companies based in North America are strategically orienting their investments in this region, specifically in Mexico and Brazil owing to the presence of excellent engineering, manufacturing, and servicing facilities in Latin America.
According to the National Agency for Petroleum, Natural Gas, and Biofuel, Brazil is expected to increase its oil production to over 5 million barrels of oil per day by 2027. In addition, the country requires multiple terminals and an extensive pipeline network to transport and store hydrocarbon-based products owing to their large size. These factors are expected to drive the demand for inverter welding equipment in Brazil as they are mainly used for joining oil-transporting pipelines.
Key Inverter Welding Equipment Company Insights
Some key players operating in the market include The Lincoln Electric Company, Miller Electric Mfg. LLC, and voestalpine Böhler Welding Group GmbH.
-
Lincoln Electric Holdings, Inc. offers development, design, and manufacturing of arc welding products, plasma, assembly & cutting systems, automated joining, and oxyfuel cutting equipment, and is one of the major players in the brazing and soldering alloys industry. It operates through three operating segments such as International Welding, Americas Welding, and The Harris Products GroupThe welding products manufactured by the company include stick electrodes, TIG wires, submerged arc consumables, ceramic backing materials, MIG wires, flux-cored wires, and autogenous wires.
-
Miller Electric Mfg. LLC provides innovative, solution-focused products and meets critical welding safety and health requirements. The company manufactures arc welding and cutting equipment. It offers a wide range of equipment such as welders, gas equipment, wire feeders, fume extraction, plasma cutters, automation, induction heating, integrated truck solutions, training equipment, and welding intelligence. The company supports a wide range of industries such as aerospace, construction & fabrication, heavy equipment, manufacturing, railcar, shipbuilding, transportation, and work trucks.
ESAB, Ador Welding Limited are some emerging players in the market.
-
ESAB offers welding & cutting equipment and consumables. It also offers personal protective equipment (PPE), specialty gas, digital solutions, arc accessories, gouging, & exothermic, manual plasma, welding automation, cutting automation arc equipment, gas control equipment, and filler metals. It caters to a wide range of end-use sectors such as aerospace, process industry, automotive, shipbuilding, pipelines, repair & maintenance, power generation, transport & mobile machinery.
-
Ador Welding Limited is engaged in the manufacturing and distribution of welding equipment, consumables, and automation solutions. It offers a wide range of welding consumables, including electrodes, wires, and fluxes, along with brazing products. In addition, the company also provides welding equipment based on different welding principles. The company operates through three business segments, namely Consumables, Equipment & Automation, and Flares & Process Equipment Division (FPED).
Key Inverter Welding Equipment Companies
The following key companies have been profiled for this study on the inverter welding equipment market.
-
The Lincoln Electric Company
-
Ador Welding Limited
-
ESAB
-
Fronius International GmbH
-
voestalpine Böhler Welding Group GmbH
-
Panasonic Industry Co., Ltd.
-
Miller Electric Mfg. LLC
-
Kemppi Oy
-
GYS
-
Migatronic A/S
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Lincoln Electric Holdings, Inc.; ITW; ESAB; Fronius International GmbH; Panasonic Industry Co., Ltd.; voestalpine Böhler Welding Group GmbH)
- Focus on development of advanced inverter welding machinery with automation, digital control systems, and Industry 4.0 integration.
- Strong emphasis on continuous R&D, product innovation, and expansion of global manufacturing, sales, and service networks.
- Strategic collaborations and acquisitions to strengthen technology capabilities and expand application reach.
- Strong global brand equity with broad product range across inverter welding machines.
- High technological expertise enabling efficient, precise, and energy-saving welding machinery solutions.
- Strong integration with industrial automation and robotics ecosystems.
- High equipment cost limits adoption in price-sensitive markets.
- Requires skilled operators and technical training for optimal machine utilization.
- Longer product upgrade cycles due to complex industrial systems.
Emerging & Regional Players (e.g., Ador Welding Limited; Kemppi Oy; GYS; Migatronic A/S, regional players)
- Focus on cost-effective inverter welding machinery tailored to regional industrial needs.
- Expansion through distributor-led sales, localized production, and SME-focused offerings.
- Increasing focus on product customization and rapid delivery to strengthen regional competitiveness.
- Strong regional presence with competitive pricing in inverter welding machines.
- Flexible product customization and responsiveness to local industrial requirements.
- Faster product adaptation and shorter time-to-market for regional demand shifts.
- Limited global footprint compared to multinational machinery manufacturers.
- Lower scale of R&D and weaker penetration in high-end automated welding systems.
- Limited after-sales and service infrastructure in emerging export markets.
Recent Developments
-
In April 2024, Miller Electric Mfg. LLC unveiled its latest innovation in the realm of collaborative robotic welding systems - the Copilot. This system boasts the newly introduced Auto Deltaweld as its core welding power source. Initially available with the air-cooled Copilot, plans are in place to incorporate the Auto Deltaweld into the water cooled variant later in the same year.
-
In April 2024, ESAB launched the Warrior Edge 500 DX, a versatile multi-process power source that integrates four sophisticated MIG/MAG WeldModes: ROOT, THIN, ROOT Pipe, and SPEED, along with an Advanced Pulse WeldMode. These WeldModes are designed to significantly enhance arc stability, offer superior control at increased travel speeds, and minimize spatter, thereby reducing the need for post-weld clean-up. The Warrior Edge DX aims to elevate the skill levels of welders, boost productivity, and enhance the quality and consistency of welding operations, while also streamlining the training process.
Inverter Welding Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.2 billion
Estimated market size in 2026
USD 5.5 billion
Projected market size by 2033
USD 8.1 billion
Growth rate
CAGR of 5.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, units, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Germany; UK; France; Italy; Spain; Japan; China; India; Australia; South Korea; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Lincoln Electric Holdings, Inc.; Miller Electric Mfg. LLC; Ador Welding Limited; ESAB; Fronius International GmbH; voestalpine Böhler Welding Group GmbH; Panasonic Industry Co., Ltd;, Kemppi Oy; GYS; Migatronic A/S
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Inverter Welding Equipment Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global inverter welding equipment market report based on the type and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Volume, Units; Revenue, USD Million; 2021 - 2033)
-
Manual Arc Welding
-
MIG
-
By End Use
-
Aerospace
-
Automotive
-
Building & Construction
-
Energy
-
Oil & Gas
-
Marine
-
Others
-
-
By Power Supply
-
1 Phase
-
3 Phase
-
-
-
TIG
-
By End Use
-
Aerospace
-
Automotive
-
Building & Construction
-
Energy
-
Oil & Gas
-
Marine
-
Others
-
-
By Power Supply
-
1 Phase
-
3 Phase
-
-
-
Plasma
-
-
Mechanized Arc Welding
-
MIG
-
By End Use
-
Aerospace
-
Automotive
-
Building & Construction
-
Energy
-
Oil & Gas
-
Marine
-
Others
-
-
By Power Supply
-
1 Phase
-
3 Phase
-
-
By Degree of Mechanism
-
Fully Mechanized Welding
-
Partially Mechanized Welding
-
-
-
TIG
-
By End Use
-
Aerospace
-
Automotive
-
Building & Construction
-
Energy
-
Oil & Gas
-
Marine
-
Others
-
-
By Power Supply
-
1 Phase
-
3 Phase
-
-
By Degree of Mechanism
-
Fully Mechanized Welding
-
Partially Mechanized Welding
-
-
-
Plasma
-
-
-
Regional Outlook (Volume, Units; Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
Mexico
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The inverter welding equipment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each inverter welding equipment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue Capture Definition
Manual Arc Welding
Revenue generated from the sale of inverter-based manual arc welding (MMA/SMAW) machines used for manual welding operations across industrial, construction, repair, and maintenance applications.
Mechanized Arc Welding
Revenue generated from the sale of inverter-based mechanized arc welding equipment used in semi-automated and fully mechanized welding applications across industrial manufacturing, construction, shipbuilding, energy, oil & gas, and heavy engineering.
Estimation Model
Layer Name
Key Question
Description
Welding Equipment Demand Layer
Where is inverter welding equipment required?
Analyze demand across key end-use industries including automotive, aerospace, building & construction, energy, oil & gas, marine, and general manufacturing.
Manufacturing & Industrial Investment Layer
Where is new equipment demand being created?
Evaluate investments in manufacturing facilities, fabrication shops, automotive production, shipbuilding, pipeline construction, renewable energy projects, and industrial infrastructure. Assess equipment modernization initiatives and capacity expansions that drive procurement of inverter welding equipment across manual and mechanized welding applications.
Technology Adoption Layer
Which inverter welding technologies are being deployed?
Segment demand by welding type (Manual Arc Welding and Mechanized Arc Welding), welding process (MIG, TIG, Plasma), power supply, degree of mechanization, and end-use industry. Apply adoption rates based on welding productivity, energy efficiency, portability, duty cycle, weld quality, and automation requirements.
Revenue Conversion Layer
How is market revenue generated ?
Estimate annual shipments of inverter welding equipment by welding type, welding process, power supply, and end-use industry. Quantify revenues generated exclusively from the sale of new inverter welding machines supplied to OEMs, fabrication shops, industrial manufacturers, and distributors.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
Benchmarked key inverter welding equipment manufacturers based on product portfolio, technology capabilities, financial strength, industry focus, and geographic presence.
Enabled clear understanding of competitive positioning and identification of key market players and differentiation opportunities.
Regional Segmentation
Analyzed shift from conventional to inverter-based welding systems, highlighting gains in energy efficiency, arc stability, portability, and automation integration including digital and IoT-enabled systems.
Enabled understanding of technology transition trends and next-generation welding adoption across industries.
Opportunity assessment
Identified growth opportunities driven by automation, energy-efficient welding demand, EV manufacturing, renewable energy projects, and smart manufacturing adoption.
Supported identification of high-growth end-use sectors and technology-driven investment opportunities.
Frequently Asked Questions About This Report
Asia Pacific dominated the inverter welding equipment market with the largest revenue share of 37.0% in 2025.
Asia Pacific is anticipated to be one of the fastest-growing regional markets over the forecast period, driven by rapid industrialization, expanding manufacturing activities, and increasing investments in infrastructure and fabrication industries.
The global market is witnessing steady growth, driven by the widespread adoption of inverter welding equipment across the automotive, construction, shipbuilding, and aerospace industries.
Key trends include increasing adoption of inverter-based welding technologies, rising use of mechanized and automated welding systems, growing demand for energy-efficient equipment, and integration of digital controls for improved welding precision and productivity.
The global inverter welding equipment market size was valued at USD 5.2 billion in 2025 and is estimated at USD 5.5 billion for 2026.
The global inverter welding equipment market is expected to grow at a CAGR of 5.7% from 2026 to 2033, reaching USD 8.1 billion by 2033.
The mechanized arc welding segment led the market with the largest revenue share of 80.0% in 2025.
Some of the key players operating in the inverter welding equipment market include Lincoln Electric Holdings, Inc., ITW, Ador Welding Limited, ESAB, Fronius International GmbH, voestalpine Böhler Welding Group GmbH, Panasonic Industry Co., Ltd., Kemppi Oy, GYS, Migatronic A/S.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


