
- Home
- »
- Advanced Interior Materials
- »
-
Liquid Analytical Instrument Market Size Report, 2026-2033GVR Report cover

Liquid Analytical Instrument Market (2026 - 2033)
Size, Share & Trends Analysis Report By Instrument, By Application (Drug Discovery, Water Purification), By End-use (Chemical, Energy, Food & Beverage, Healthcare & Biotechnology), By Region, And Segment Forecasts
Market Size, 2025
$505.0MMarket Estimate, 2026
$540.9MMarket Forecast, 2033
$845.0MCAGR, 2026–2033
6.6%Liquid Analytical Instrument Market Summary
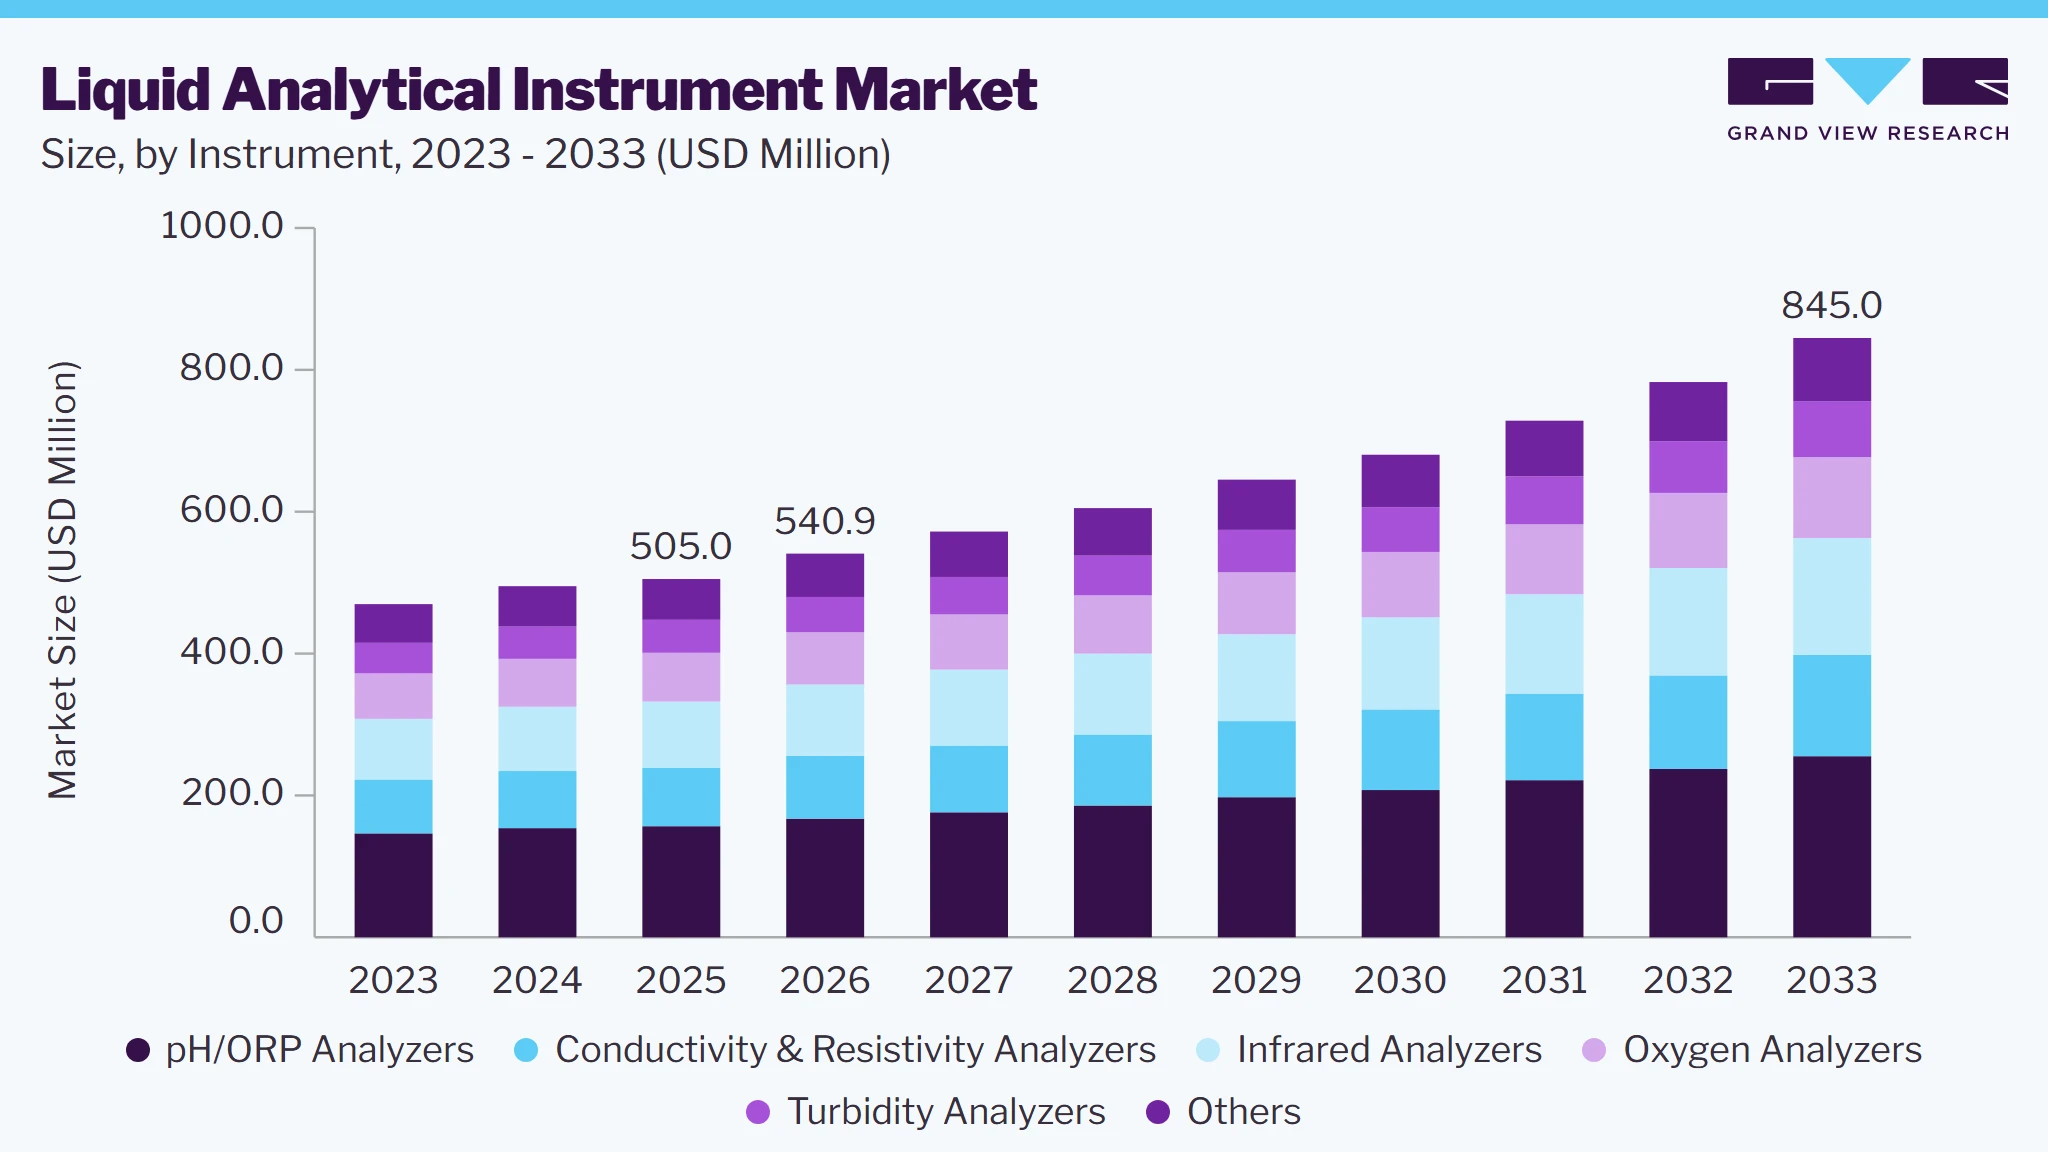
The global liquid analytical instrument market size was valued at USD 505.0 million in 2025 and is projected to grow from USD 540.9 million in 2026 to USD 845.0 million by 2033, at a CAGR of 6.6% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 30.2% in 2025. The market is experiencing a notable evolution driven by increased demand for real-time, precise monitoring in industries such as water treatment, pharmaceuticals, food & beverage, and chemicals.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By instrument: pH/ORP analyzers segment dominated the market, with a revenue share of 31.0% in 2025.
- By application: Wastewater management segment held the largest market share of 31.3% in 2025.
- By end use: Pharmaceutical segment accounted for the largest revenue share of 24.5% in 2025.
Regional Highlights
- Largest regional market: Europe (30.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: Germany held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 505.0 Million
- Estimated market size in 2026: USD 540.9 Million
- Projected market size by 2033: USD 845.0 million
- CAGR (2026-2033): 6.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
There is a growing emphasis on process optimization, regulatory compliance, and sustainability, which is pushing industries to invest in advanced analytical tools such as pH meters, conductivity sensors, dissolved oxygen analyzers, and multi-parameter systems.
 To learn more about this report, Download Free Sample Report
Another significant trend is the shift toward digitalization and automation. Modern liquid analytical instruments are increasingly being embedded with smart features such as wireless connectivity, cloud-based data storage, and predictive maintenance capabilities. These innovations not only improve accuracy and ease of use but also support data-driven decision-making across operations. Moreover, the rise in environmental monitoring initiatives and stricter quality control standards worldwide is further boosting the adoption of these technologies across a diverse range of applications.
Market Dynamics
The liquid analytical instrument market is shaped by rising demand for accurate, real-time monitoring of liquid process parameters across industries such as pharmaceuticals, chemicals, water and wastewater treatment, food and beverage, and power generation. Increasing regulatory emphasis on product quality, process safety, and environmental compliance is driving the adoption of advanced analytical solutions for continuous measurement of parameters, including pH, conductivity, dissolved oxygen, turbidity, and total organic carbon. Ongoing technological advancements, such as digital sensing technologies, IoT-enabled monitoring systems, and automated calibration and diagnostics, are enhancing operational efficiency, measurement precision, and remote accessibility, thereby supporting wider deployment. However, the market is constrained by high capital investment requirements, complex maintenance needs, and frequent calibration demands, which can limit adoption among cost-sensitive end users.
The liquid analytical instrument market is primarily driven by the increasing demand for accurate and continuous monitoring of liquid process parameters across industries such as pharmaceuticals, chemicals, oil & gas, water and wastewater treatment, food and beverage, power generation, and pulp and paper. Growing emphasis on product quality, process optimization, and operational safety is encouraging industries to deploy advanced analytical instruments for precise measurement and control of critical parameters.
In addition, stringent environmental regulations governing wastewater discharge, emissions, and industrial process compliance are accelerating the adoption of reliable liquid analysis solutions. The ongoing shift toward industrial automation, digitalization, and Industry 4.0 is further driving demand for intelligent analytical instruments with remote monitoring, predictive diagnostics, and enhanced data integration capabilities.
The market is restrained by the substantial capital investment required for the procurement and installation of advanced liquid analytical instruments, particularly for small and medium-sized enterprises with limited budgets. Operational challenges, including routine calibration, sensor replacement, periodic maintenance, and the requirement for skilled personnel to ensure accurate measurements, further increase the total cost of ownership.
Additionally, variations in raw material prices, supply chain disruptions, and extended equipment replacement cycles can affect manufacturing costs and purchasing decisions. These factors collectively may slow the adoption of advanced analytical systems, particularly in price-sensitive and developing markets.
Opportunity: Expansion of Smart Analytical Technologies and Sustainable Water Management Initiatives
The market presents significant growth opportunities through the increasing adoption of smart analytical technologies integrated with IoT, artificial intelligence, cloud computing, and advanced data analytics. These innovations enable real-time monitoring, predictive maintenance, improved process efficiency, and centralized asset management across industrial facilities.
Furthermore, rising investments in water and wastewater treatment infrastructure, water reuse and recycling projects, and sustainable industrial operations are creating strong demand for advanced liquid analytical instruments. Rapid industrialization, expansion of manufacturing facilities, and tightening environmental regulations across emerging economies are expected to further broaden the market's application scope and create long-term growth opportunities for industry participants.
Analyst Perspective
The liquid analytical instrument market is expected to grow steadily, driven by rising demand for process optimization, regulatory compliance, and operational efficiency across industries such as water & wastewater, pharmaceuticals, chemicals, food & beverage, and energy. The market is shifting toward intelligent solutions with digital connectivity, remote monitoring, and cloud-based data management. Advancements in sensor durability, measurement accuracy, and automation integration, along with industrial growth and stricter environmental standards in emerging economies, are expected to create new growth opportunities.
Drivers, Opportunities & Restraints
The liquid analytical instrumentation industry is experiencing robust growth, propelled by several key factors. Stringent environmental regulations across industries such as water treatment, pharmaceuticals, and food and beverage are compelling companies to adopt advanced analytical tools for precise monitoring and compliance. Technological advancements in sensor technologies, including AI and IoT integration, are enhancing the capabilities of liquid analyzers, enabling real-time data collection and predictive maintenance. In addition, the increasing emphasis on process optimization and sustainability is driving demand for instruments that ensure product quality and minimize environmental impact.
Despite the market's expansion, several challenges hinder its growth. The high initial investment required for advanced liquid analytical instruments poses a significant barrier, particularly for small to mid-sized laboratories with limited budgets. Moreover, the complexity of these instruments necessitates specialized training and a skilled workforce, which is currently in short supply. Issues such as sensor calibration failures, drift in readings, and contamination further complicate maintenance and reliability, potentially leading to operational inefficiencies.
The market presents numerous opportunities for growth and innovation. The integration of artificial intelligence and machine learning into liquid analytical instruments is revolutionizing data analysis, offering faster and more accurate results. In addition, the increasing demand for compact, portable, and automated systems is opening avenues in healthcare diagnostics and field applications. Emerging markets in regions like Asia-Pacific, Latin America, and Africa are witnessing industrialization and stricter regulatory frameworks, creating a fertile ground for market expansion.
Instrument Insights
Based on instrument, the pH/ORP analyzers segment led the market with the largest revenue share of 31.0% in 2025. pH/ORP analyzers are essential tools for monitoring and controlling the acidity, alkalinity, and redox potential in various industrial processes. These instruments are widely used in applications such as water treatment, chemical manufacturing, and food processing to ensure product quality and compliance with environmental regulations.
Infrared analyzers utilize the absorption of infrared light to identify and quantify specific gases or chemical compounds in a sample. This technology is particularly valuable in applications such as environmental monitoring, industrial emissions control, and process optimization, where precise gas composition analysis is critical. IR analyzers are known for their high sensitivity, selectivity, and non-destructive testing capabilities, making them suitable for continuous monitoring in challenging environments.
Application Insights
Based on application, the wastewater management segment led the market with the largest revenue share of 31.5% in 2025. In wastewater management, liquid analytical instrumentation is essential for monitoring and controlling water quality. Instruments such as pH/ORP analyzers and infrared (IR) analyzers are employed to measure critical parameters like acidity, alkalinity, and the presence of specific contaminants. These tools enable real-time detection of pollutants, ensuring compliance with environmental regulations and protecting public health.
The liquid chemistry monitoring is a pivotal factor propelling the market growth. Industries such as water and wastewater treatment, pharmaceuticals, food and beverage, and biotechnology rely on precise and continuous analysis of liquid parameters like pH, conductivity, dissolved oxygen, and turbidity to ensure product quality, safety, and regulatory compliance. The increasing emphasis on environmental sustainability and stringent regulatory standards has heightened the need for real-time monitoring solutions.
End-use Insights
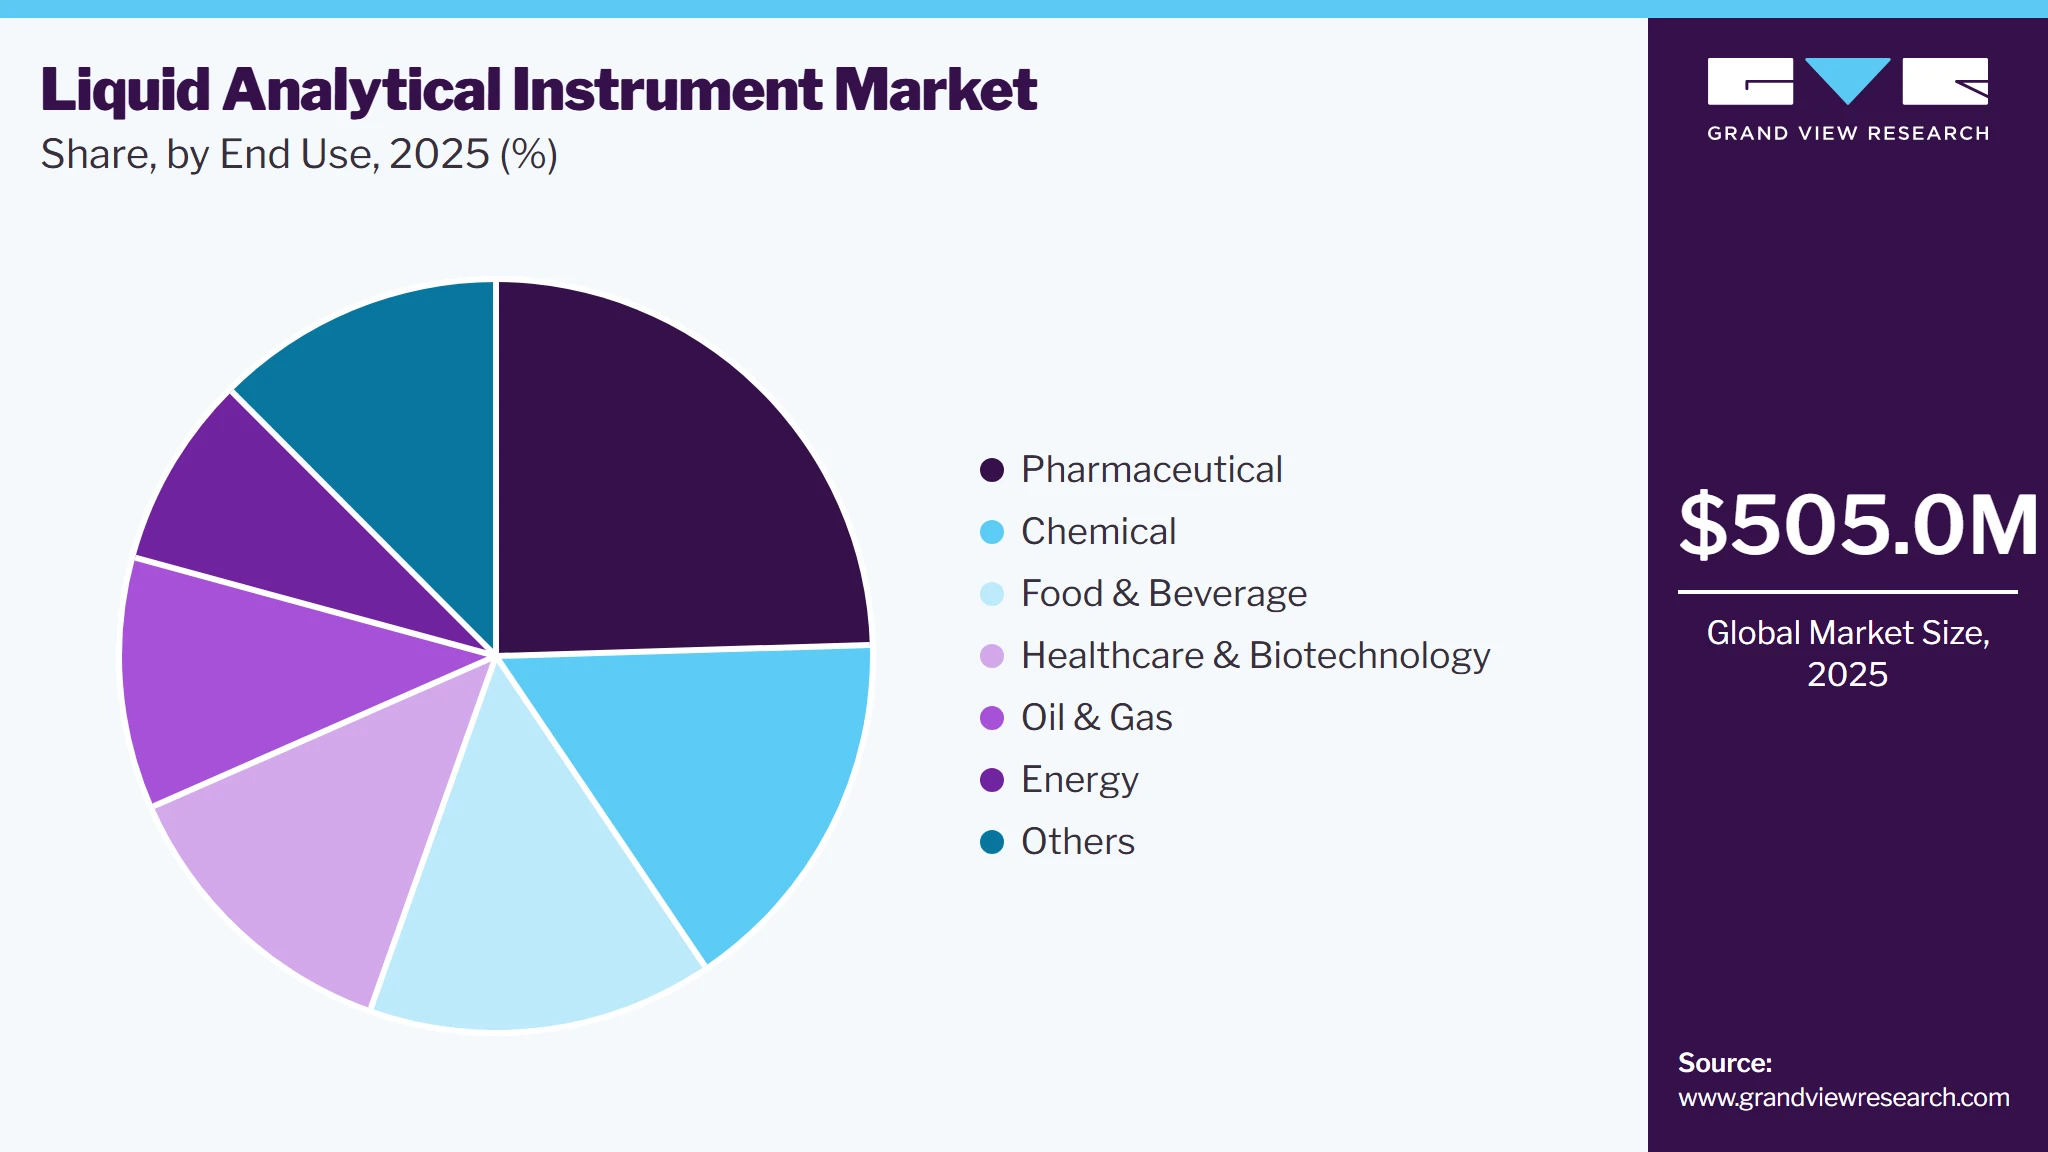
Based on end use, the pharmaceutical segment led the market with the largest revenue share of 24.5% in 2025. The pharmaceutical sector is a significant driver of the market growth, primarily due to its stringent requirements for quality control, regulatory compliance, and process optimization. Analytical instruments such as high-performance liquid chromatography (HPLC), mass spectrometry, and pH/ORP analyzers are integral to various stages of pharmaceutical development, including drug discovery, formulation, and manufacturing.
 To learn more about this report, Download Free Sample Report
In healthcare & biotechnology, liquid analytical instruments are crucial for research, development, and quality control processes. They are extensively used in drug discovery to analyze complex biological samples, identify biomarkers, and assess the purity and potency of pharmaceutical compounds. These instruments also support the optimization of fermentation processes in biotechnology by monitoring parameters such as pH, oxygen levels, and nutrient concentrations, ensuring consistent yields of bioproducts.
Regional Insights
The liquid analytical instrument market in North America is characterized by advanced technological adoption and a strong regulatory framework. Industries such as pharmaceuticals, food & beverage, and water treatment drive demand for high-precision instruments like pH/ORP analyzers, conductivity sensors, and infrared analyzers. The region's emphasis on quality control, environmental compliance, and process optimization fuels the market growth.
U.S. Liquid Analytical Instrument Market Trends
The liquid analytical instrument market in the U.S. is expected to grow at a significant CAGR of 6.5% from 2025 to 2030. The United States stands as a dominant force in the U.S. market, owing to its robust industrial base and significant investments in research and development. Key sectors including pharmaceuticals, biotechnology, and environmental monitoring contribute to the widespread adoption of liquid analytical instruments.
The Canada liquid analytical instrument market is expected to grow at the fastest CAGR of 7.9% from 2025 to 2030. Canada's market is influenced by its strong emphasis on environmental sustainability and natural resource management. Industries such as mining, agriculture, and water treatment require precise analytical tools to monitor and manage liquid processes effectively.
Europe Liquid Analytical Instrument Market Trends
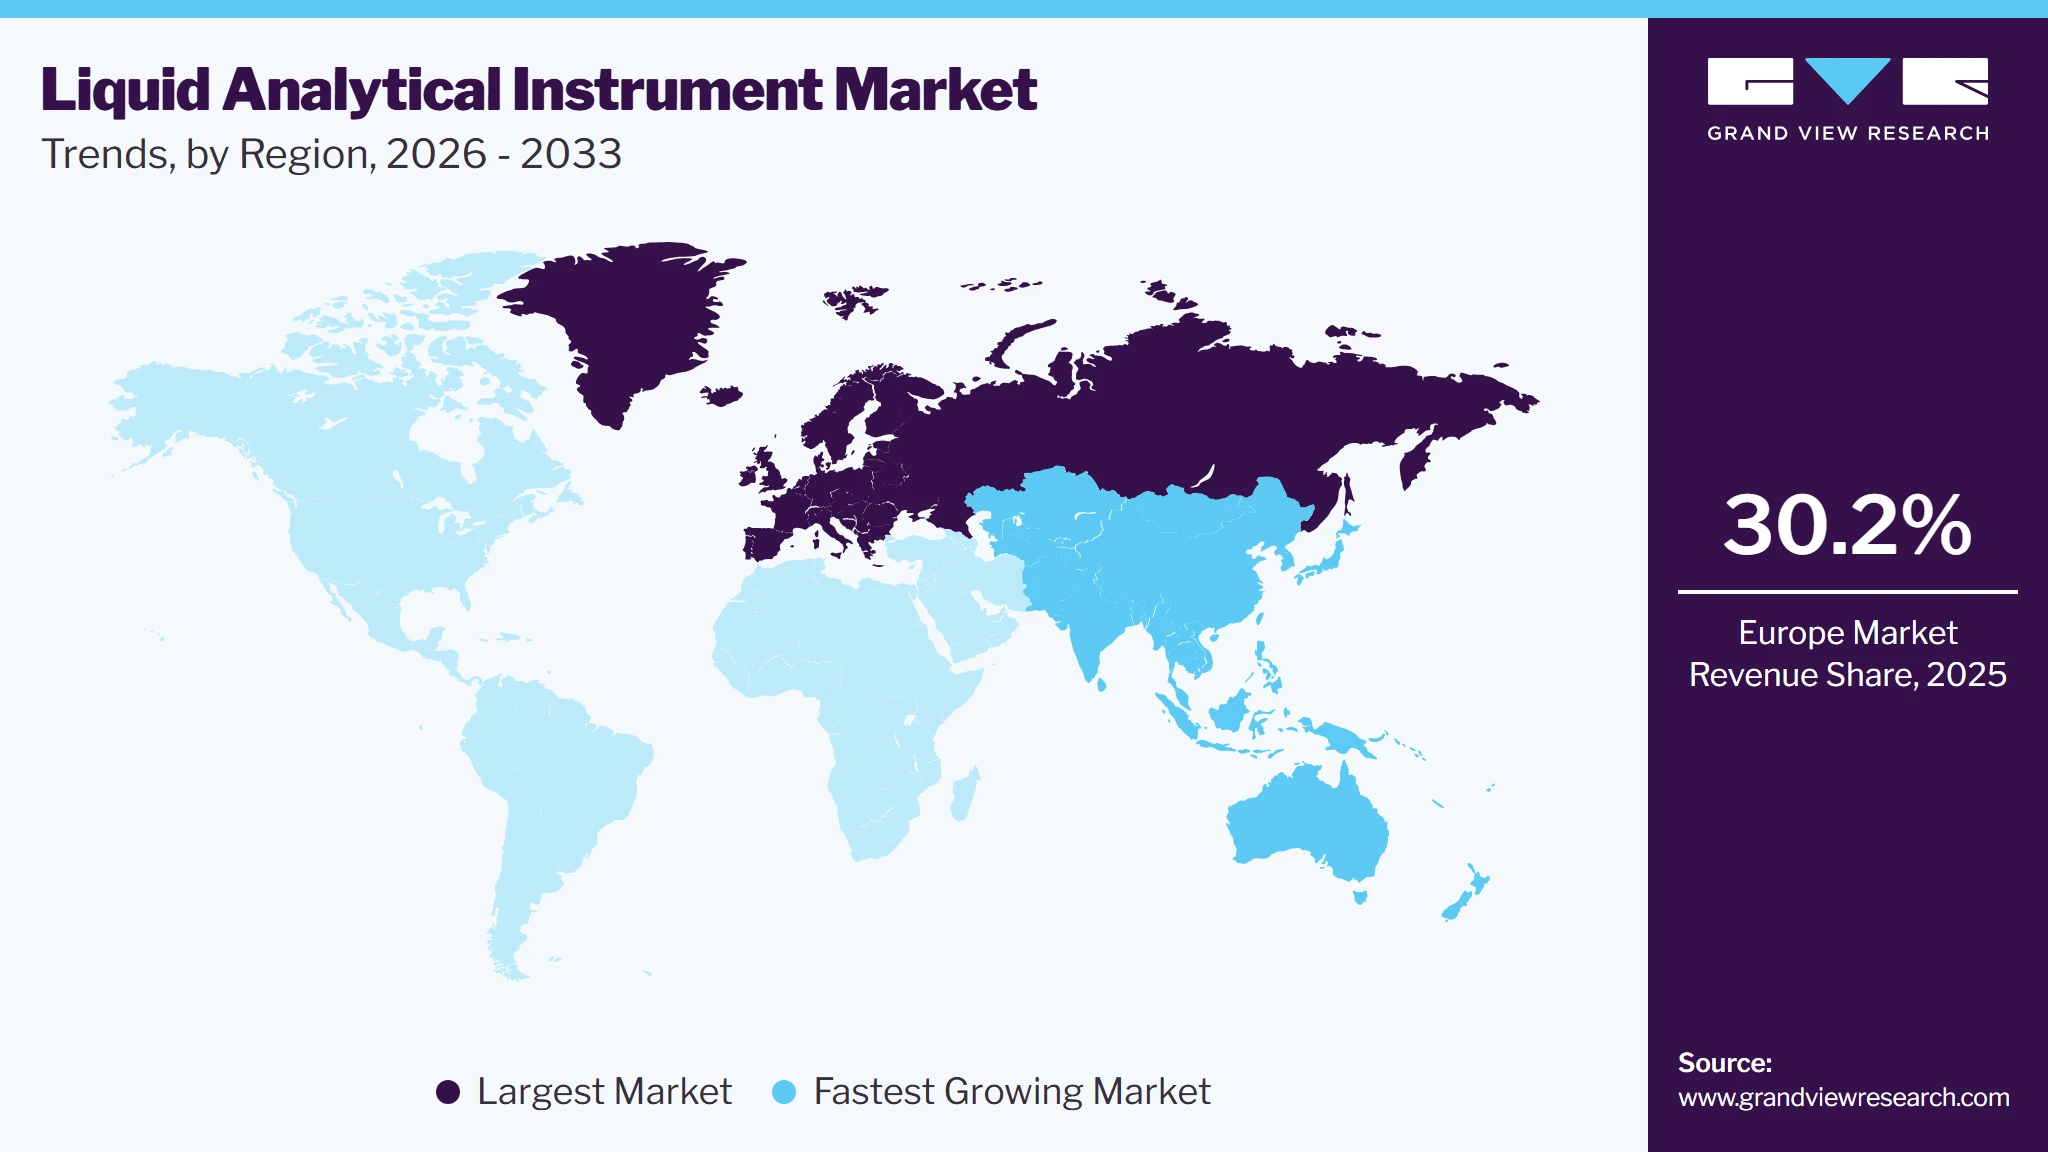
Europe dominated the liquid analytical instrument market with the largest revenue share of 30.2% in 2025. Europe exhibits a diverse and mature in Europe market, with significant contributions from countries such as Germany, the UK, and France. The region's stringent environmental regulations and quality standards in sectors such as pharmaceuticals, food and beverage, and water treatment necessitate the use of advanced analytical instruments. Ongoing investments in research and development further enhance the market's growth prospects.
 To learn more about this report, Download Free Sample Report
The liquid analytical instrument market in Germany held the largest share in the Europe region in 2025. The liquid analytical instrument market in the Germany is driven by its strong industrial sector, particularly in chemicals, pharmaceuticals, and environmental monitoring. The country's commitment to precision engineering and innovation fosters the development and adoption of advanced analytical instruments. Germany's regulatory framework also ensures high standards in quality control and environmental compliance, supporting market growth.
The UK liquid analytical instrument market is driven by its robust healthcare and pharmaceutical industries, which require precise analytical tools for research and quality control. The country's focus on innovation and regulatory adherence promotes the adoption of advanced liquid analytical instruments.
Asia Pacific Liquid Analytical Instrument Market Trends
The liquid analytical instrument industry in the Asia Pacific is anticipated to grow at the fastest CAGR from 2026 to 2033. The liquid analytical instrument market in the Asia Pacific is experiencing rapid growth, driven by industrialization and urbanization in countries like China and India. Sectors such as pharmaceuticals, food and beverage, and environmental monitoring are major contributors to this growth. The region's increasing focus on quality control and environmental sustainability further propels the demand for advanced analytical instruments.
The China liquid analytical instrument market held a significant share in the Asia Pacific market owing to its large-scale industrial activities and stringent regulatory requirements in sectors like pharmaceuticals, chemicals, and environmental monitoring. The government's initiatives to enhance environmental protection and industrial efficiency drive the adoption of advanced analytical instruments.
The liquid analytical instrument market in the India is expected to grow at the fastest CAGR of 8.1% from 2025 to 2030. India's market is witnessing growth, fueled by its expanding pharmaceutical, chemical, and water treatment industries. The country's focus on improving infrastructure and regulatory standards enhances the demand for precise analytical tools. Government initiatives aimed at environmental protection and industrial development further support the market's expansion.
Middle East & Africa Liquid Analytical Instrument Market Trends
The liquid analytical instrument market in the Middle East & Africa is emerging, with countries focusing on industrial development and environmental sustainability. Sectors such as oil and gas, water treatment, and agriculture require advanced analytical instruments to monitor and manage liquid processes effectively. Government initiatives and investments in infrastructure contribute to the market's growth potential.
The Saudi Arabia liquid analytical instrument market is expanding, driven by its oil and gas industry and initiatives in water treatment and environmental monitoring. The country's focus on technological advancement and regulatory compliance fosters the adoption of advanced analytical instruments. Saudi Arabia's investments in infrastructure and industrial development further support market growth.
Latin America Liquid Analytical Instrument Market Trends
The liquid analytical instrument market in Latin America is developing, with countries like Brazil investing in industrial growth and environmental monitoring. The region's agricultural, mining, and water treatment sectors require advanced analytical instruments to ensure quality control and regulatory compliance. Ongoing investments in infrastructure and technology adoption contribute to the market's growth prospects.
The Brazil liquid analytical instrument market is influenced by its large agricultural and mining industries, which necessitate precise analytical tools for process optimization and environmental monitoring. The country's regulatory framework and focus on sustainable development drive the demand for advanced analytical instruments. Brazil's commitment to technological advancement further supports market growth.
Key Liquid Analytical Instrument Company Insights
Some of the key players operating in the liquid analytical instrument industry include ABB, Schneider Electric, and Honeywell International Inc.
-
ABB Ltd. is a Swedish-Swiss multinational corporation specializing in robotics, power, and automation technologies. Headquartered in Zurich, Switzerland, ABB operates in over 100 countries and employs approximately 110,000 people worldwide. The company was formed in 1988 through the merger of Sweden's ASEA and Switzerland's Brown, Boveri & Cie. ABB provides a wide range of electrification and automation solutions, including robotics, industrial automation, and digitalization services, aiming to enhance industrial productivity and sustainability.
-
Schneider Electric SE is a French multinational corporation that specializes in digital automation and energy management. Founded in 1836, Schneider Electric is headquartered in Rueil-Malmaison, France, and operates in over 100 countries with a workforce of approximately 153,000 employees. The company provides integrated solutions across various sectors, including smart industries, resilient infrastructure, and intelligent buildings, focusing on sustainability and efficiency.
-
Honeywell International Inc. is an American multinational conglomerate headquartered in Charlotte, North Carolina. Established in 1906, Honeywell operates in four main business segments: aerospace, building technologies, performance materials and technologies, and safety and productivity solutions. The company serves various industries, including defense, aerospace, and industrial automation, providing products and services that enhance safety, efficiency, and sustainability.
Analytical Systems Keco and Electro-Chemical Devices, Inc. are some of the emerging market participants in the liquid analytical instrument industry.
-
Established in 1984 and headquartered in Houston, Texas, Analytical Systems KECO specializes in the design and manufacture of process and laboratory analyzers for industries such as gas processing, refining, chemical processing, and water treatment. Their product portfolio includes analyzers for detecting contaminants like hydrogen sulfide (H₂S), carbon dioxide (CO₂), sulfur, and hydrocarbons in liquids and gases. KECO emphasizes precision and reliability, ensuring that each analyzer undergoes rigorous quality control measures throughout the manufacturing process.
-
Founded in 1977 and based in Anaheim, California, Electro-Chemical Devices, Inc. is a leading manufacturer of liquid analytical process instrumentation. ECD offers a wide range of products, including pH, conductivity, resistivity, oxidation-reduction potential (ORP), dissolved oxygen (DO), turbidity, and ion-selective electrodes. Their instruments are utilized across various industries, such as chemical, food and beverage, oil and gas, mining, power generation, pulp and paper, semiconductor, steel, and water and wastewater treatment. ECD is recognized for its technical innovations, including the development of the industry's first 2-wire conductivity transmitters and the Sentinel product line with sensor diagnostics and predictive sensor replacement.
Key Liquid Analytical Instrument Companies:
The following are the leading companies in the liquid analytical instrument market.
- ABB
- Analytical Systems Keco
- Electro-Chemical Devices, Inc.
- Schneider Electric
- Emerson Electric Co.
- Endress-Hauser Management AG
- Honeywell International Inc.
- METTLER TOLEDO
- Teledyne Technologies Incorporated
- Yokogawa Electric Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Endress+Hauser, Emerson Electric Co., METTLER TOLEDO,)
- Prioritize continuous investment in R&D to strengthen product innovation, digital analytics, and smart sensing capabilities.
- Expand market presence through strategic partnerships, acquisitions, and comprehensive global sales and service networks.
- Deliver integrated analytical solutions with lifecycle services, calibration, and predictive maintenance to enhance customer retention and long-term contracts.
- Extensive product portfolios addressing a broad range of liquid analytical applications across multiple end-use industries.
- Strong global brand equity, established customer relationships, and widespread distribution and service infrastructure.
- Significant financial resources and technological expertise support continuous product development and regulatory compliance.
- Premium pricing strategies may limit penetration in cost-sensitive markets.
- Complex organizational structures can extend product development and commercialization timelines.
- Greater dependence on mature industrial markets may moderate growth relative to regional competitors in emerging economies.
Emerging & Regional Players (e.g., Teledyne Technologies Incorporated, Electro-Chemical Devices, Inc., regional players)
- Focus on application-specific solutions and niche market segments to strengthen competitive positioning.
- Expand regional market presence through localized distribution networks, technical support, and customer-centric service models.
- Emphasize product customization, operational flexibility, and competitive pricing to address specific end-user requirements.
- Strong technical expertise in specialized liquid analytical technologies and targeted industrial applications.
- Agile organizational structures enable faster product customization and responsiveness to evolving customer needs.
- Cost-competitive offerings facilitate market penetration in price-sensitive and developing regions.
- Comparatively limited global presence and lower brand recognition than leading multinational manufacturers.
- Smaller product portfolios and lower R&D investments may restrict technology diversification.
- Limited operational scale and financial capacity may constrain participation in large-scale international projects and rapid geographic expansion.
Recent Developments
-
In October 2024, Agilent Technologies Inc. unveiled its advanced InfinityLab LC Series portfolio, introducing the 1290 Infinity III LC and 1260 Infinity III LC systems, all available in biocompatible versions. These cutting-edge HPLC systems are the first to feature Agilent’s new InfinityLab Assist Technology, a smart support platform designed to streamline operations with intuitive, built-in guidance. By automating routine tasks and simplifying maintenance, this innovation empowers laboratories to focus more on high-quality analytical results and less on system management.
-
In March 2023, Waters Corporation introduced the Alliance iS, its next-generation intelligent high-performance liquid chromatography (HPLC) system, specially designed to enhance compliance by incorporating advanced proactive error detection, troubleshooting capabilities, and user-friendly features. The platform streamlines the process of obtaining accurate and precise measurements while significantly reducing common errors by up to 40% by combining the Alliance iS HPLC system with Waters' eConnect HPLC Columns and Empower Chromatography Software. This breakthrough technology empowers QC laboratories to consistently achieve their quality, safety, compliance, and timely product delivery objectives.
Liquid Analytical Instrument Market Report Scope
Report Attribute
Details
Market size in 2025
USD 505.0 million
Estimated market size in 2026
USD 540.9 million
Projected market size by 2033
USD 845.0 million
Growth rate
CAGR of 6.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Instrument, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Russia; China; Japan; India; South Korea; Australia; Thailand; Indonesia; Malaysia; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
Endress+Hauser, Emerson Electric Co., ABB, Yokogawa Electric Corporation, METTLER TOLEDO, Honeywell International Inc., Hach, Thermo Fisher Scientific Inc., Teledyne Technologies Incorporated, Electro-Chemical Devices, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Liquid Analytical Instrument Market Report Segmentation
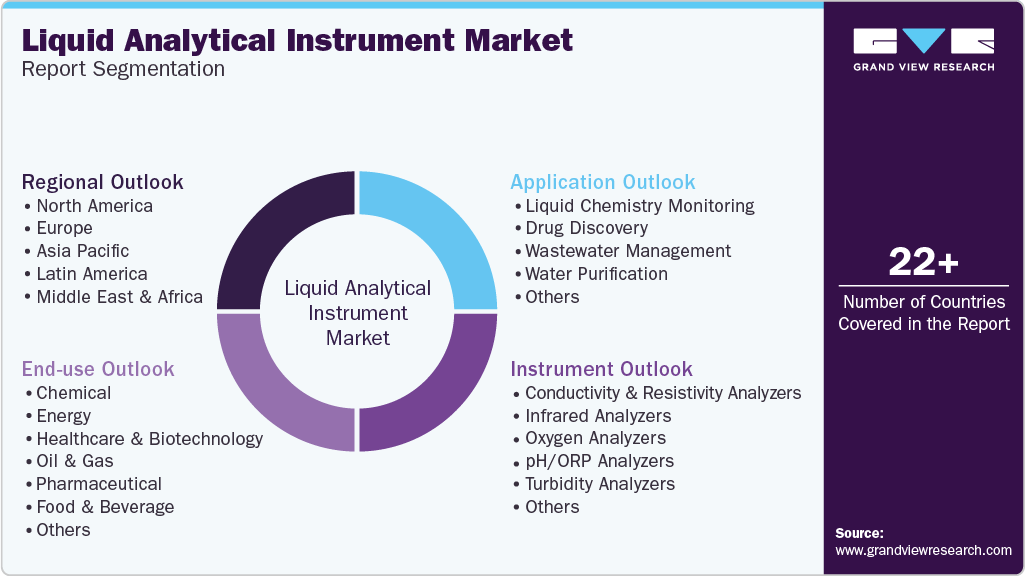
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global liquid analytical instrument market report based on the instrument, end-use, application, and region:
 To learn more about this report, Download Free Sample Report
-
Instrument Outlook (Revenue, USD Million, 2021 - 2033)
-
Conductivity & Resistivity Analyzers
-
Infrared Analyzers
-
Oxygen Analyzers
-
pH/ORP Analyzers
-
Turbidity Analyzers
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Chemical
-
Energy
-
Healthcare & Biotechnology
-
Oil & Gas
-
Pharmaceutical
-
Food & Beverage
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Liquid Chemistry Monitoring
-
Drug Discovery
-
Wastewater Management
-
Water Purification
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Russia
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
Thailand
-
Indonesia
-
Malaysia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The liquid analytical instrument market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each liquid analytical instrument segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Instrument
Revenue Capture Definition
Conductivity & Resistivity Analyzers
Revenue generated from the sale of instruments used to measure the electrical conductivity and resistivity of liquids for process control, water quality assessment, and industrial monitoring applications.
Infrared Analyzers
Revenue generated from the sale of infrared-based analyzers designed to identify and quantify chemical constituents in liquid samples for industrial, environmental, and laboratory applications.
Oxygen Analyzers
Revenue generated from the sale of analyzers used to measure dissolved oxygen levels in water and process liquids for environmental monitoring, wastewater treatment, and industrial process optimization.
pH/ORP Analyzers
Revenue generated from the sale of analyzers used to measure pH and oxidation-reduction potential (ORP) for quality control, chemical processing, water treatment, and process optimization.
Turbidity Analyzers
Revenue generated from the sale of analyzers designed to measure the concentration of suspended particles in liquids for water quality monitoring and industrial process control.
Others
Revenue generated from the sale of other analytical systems, including total organic carbon (TOC), chlorine, fluoride, sodium, silica, ammonia, nitrate, and multiparameter analyzers.
Segment - Application
Revenue Capture Definition
Liquid Chemistry Monitoring
Revenue generated from sales for monitoring and analysis of chemical parameters in industrial processes, water systems, and laboratory environments.
Drug Discovery
Revenue generated from sales of instruments for pharmaceutical and biotechnology research activities, including formulation development, sample analysis, and laboratory testing.
Wastewater Management
Revenue generated from sales of instrument used for monitoring wastewater quality, treatment efficiency, and compliance with environmental regulations.
Water Purification
Revenue generated from sales of instrument for the monitoring and optimization of purification processes in municipal, industrial, and commercial water treatment facilities.
Others
Revenue generated from sales of other instrument for applications including environmental monitoring, academic research, specialty industrial processes, and food quality testing not covered under the above categories.
Segment - End Use
Revenue Capture Definition
Chemical
Revenue generated from sales of instruments to chemical manufacturers for process monitoring, product quality assurance, and regulatory compliance.
Energy
Revenue generated from sales of instrument to power generation and utility facilities for boiler water analysis, cooling water monitoring, and process efficiency improvement.
Healthcare & Biotechnology
Revenue generated from sales of instrument to healthcare institutions and biotechnology companies for laboratory testing, bioprocess monitoring, and research applications.
Oil & Gas
Revenue generated from sales of instruments to upstream, midstream, and downstream operations for produced water analysis, corrosion monitoring, and process control.
Pharmaceutical
Revenue generated from sales of instruments to pharmaceutical manufacturers for water quality monitoring, formulation control, process validation, and regulatory compliance.
Food & Beverage
Revenue generated from sales of instruments to food and beverage manufacturers for process monitoring, sanitation verification, ingredient analysis, and product quality assurance.
Others
Revenue generated from sales of instrument to industries such as pulp & paper, mining & metals, semiconductor, municipal water utilities, environmental laboratories, and research institutions.
Estimation Model
Layer Name
Key Question
Description
End-use Industry Base Layer
Which industries represent the addressable market?
Quantify facilities across chemical, energy, healthcare & biotechnology, oil & gas, pharmaceutical, food & beverage, water & wastewater treatment, and other process industries requiring liquid analytical instruments for process monitoring, quality assurance, and regulatory compliance.
Application Demand Layer
Which applications drive the demand for liquid analytical instruments?
Assess market demand across liquid chemistry monitoring, water purification, wastewater management, drug discovery, and other industrial and laboratory applications requiring continuous measurement of liquid parameters.
Instrument Deployment Layer
Which instrument categories are adopted across end-use applications?
Estimate the adoption of conductivity & resistivity analyzers, infrared analyzers, oxygen analyzers, pH/ORP analyzers, turbidity analyzers, and other liquid analytical instruments by application, industry, and region, considering replacement demand and technology adoption.
Supply-side Validation Layer
How is the market size validated?
Validate market estimates through manufacturer revenues, product portfolio analysis, production capacities, shipment volumes, regional sales distribution, channel partnerships, import-export trends, company financial disclosures, and interviews with industry participants to reconcile demand- and supply-side estimates.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
Benchmarked key liquid analytical instrument manufacturers based on product portfolio, technology capabilities, innovation pipeline, financial performance, end-use industry coverage, geographic presence, and strategic developments.
Enabled a comprehensive view of the competitive landscape, enabling the client to assess competitive positioning, identify technology leaders, benchmark market participants, and support strategic decision-making.
Regional Segmentation
Refined regional market analysis by evaluating industrialization trends, water and wastewater treatment infrastructure, process industry concentration, regulatory environment, manufacturing investments, and automation adoption across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
Enabled identification of high-growth regional markets, demand concentration, investment priorities, and expansion opportunities by highlighting regional growth drivers and adoption patterns.
Opportunity assessment
Assessed growth opportunities across process industries, water quality monitoring, industrial automation, digital analytical technologies, replacement demand, and expanding applications in pharmaceuticals, food & beverage, chemicals, energy, and environmental monitoring.
Identified high-growth application areas and emerging technology opportunities, enabling the client to prioritize strategic investments, strengthen market positioning, and align product development with evolving industry requirements.
Frequently Asked Questions About This Report
The global liquid analytical instrument market size was estimated at USD 505.0 million in 2025 and is expected to reach USD 540.9 million in 2026.
The global liquid analytical instrument market, in terms of revenue, is expected to grow at a CAGR of 6.6% from 2026 to 2033, reaching USD 845.0 million by 2033.
Some key players operating in the liquid analytical instrument market include ABB Ltd.; Analytical Systems Keco; Electro-Chemical Devices, Inc.; Schneider Electric SE; Emerson Electric Co.; Endress-Hauser Management AG; Honeywell International Inc.; Mettler-Toledo International Inc.; Teledyne Technologies Incorporated; and Yokogawa Electric Corporation.
The liquid analytical instrument market is experiencing a notable evolution driven by increased demand for real-time, precise monitoring in industries such as water treatment, pharmaceuticals, food & beverage, and chemicals.
Europe dominated the liquid analytical instrument market with a largest revenue share of 30.2% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The wastewater management segment led the market with the largest revenue share of 31.5% in 2025.
The pH/ORP analyzers segment dominated the market, with a revenue share of 31.0% in 2025.pH/ORP analyzers are essential tools for monitoring and controlling the acidity, alkalinity, and redox potential in various industrial processes.
The pharmaceutical end use segment held a 24.5% market share in 2025. The pharmaceutical sector is a significant driver of the liquid analytical instrument market, primarily due to its stringent requirements for quality control, regulatory compliance, and process optimization.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


