
- Home
- »
- Pharmaceuticals
- »
-
Metabolic Disorder Therapeutics Market Report, 2026-2033GVR Report cover

Metabolic Disorder Therapeutics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Disease (Lysosomal Storage Diseases, Diabetes, Obesity), By Therapy, By Route Of Administration (Oral, Parenteral), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$83.1BMarket Estimate, 2026
$89.4BMarket Forecast, 2033
$149.2BCAGR, 2026–2033
7.6%Metabolic Disorder Therapeutics Market Summary
The global metabolic disorder therapeutics market size was valued at USD 83.1 billion in 2025 and is projected to grow from USD 89.4 billion in 2026 to USD 149.2 billion by 2033, at a CAGR of 7.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 39.9% in 2025. Mexico faces a serious challenge as well, with around 30% of its adult population affected, particularly among the aging demographics. These statistics underscore the urgent need for modern treatments to combat the rising tide of metabolic disorders, propelling market demand.
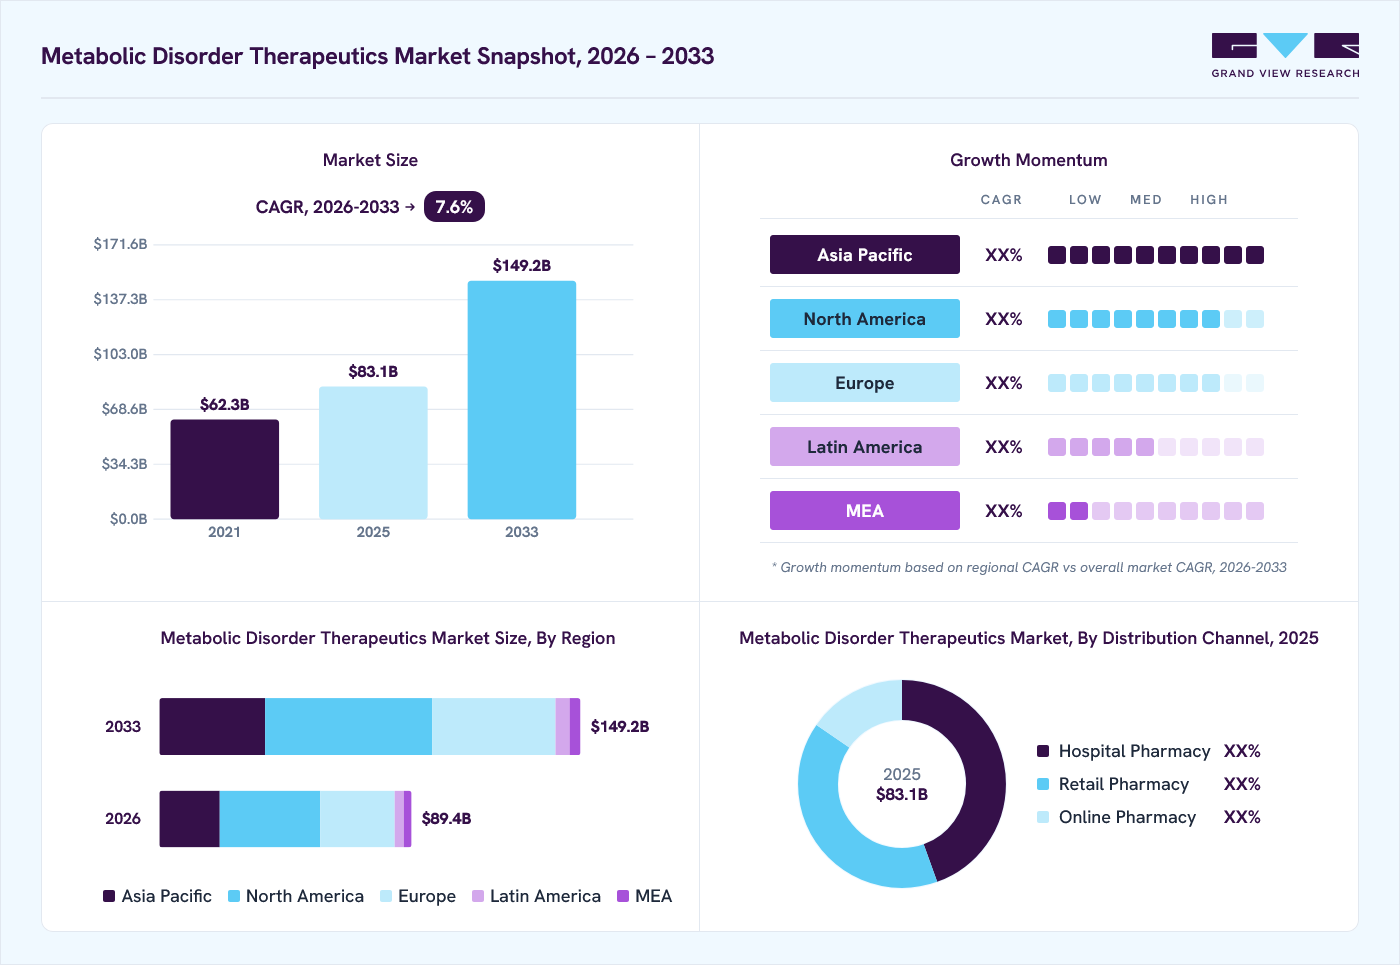 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
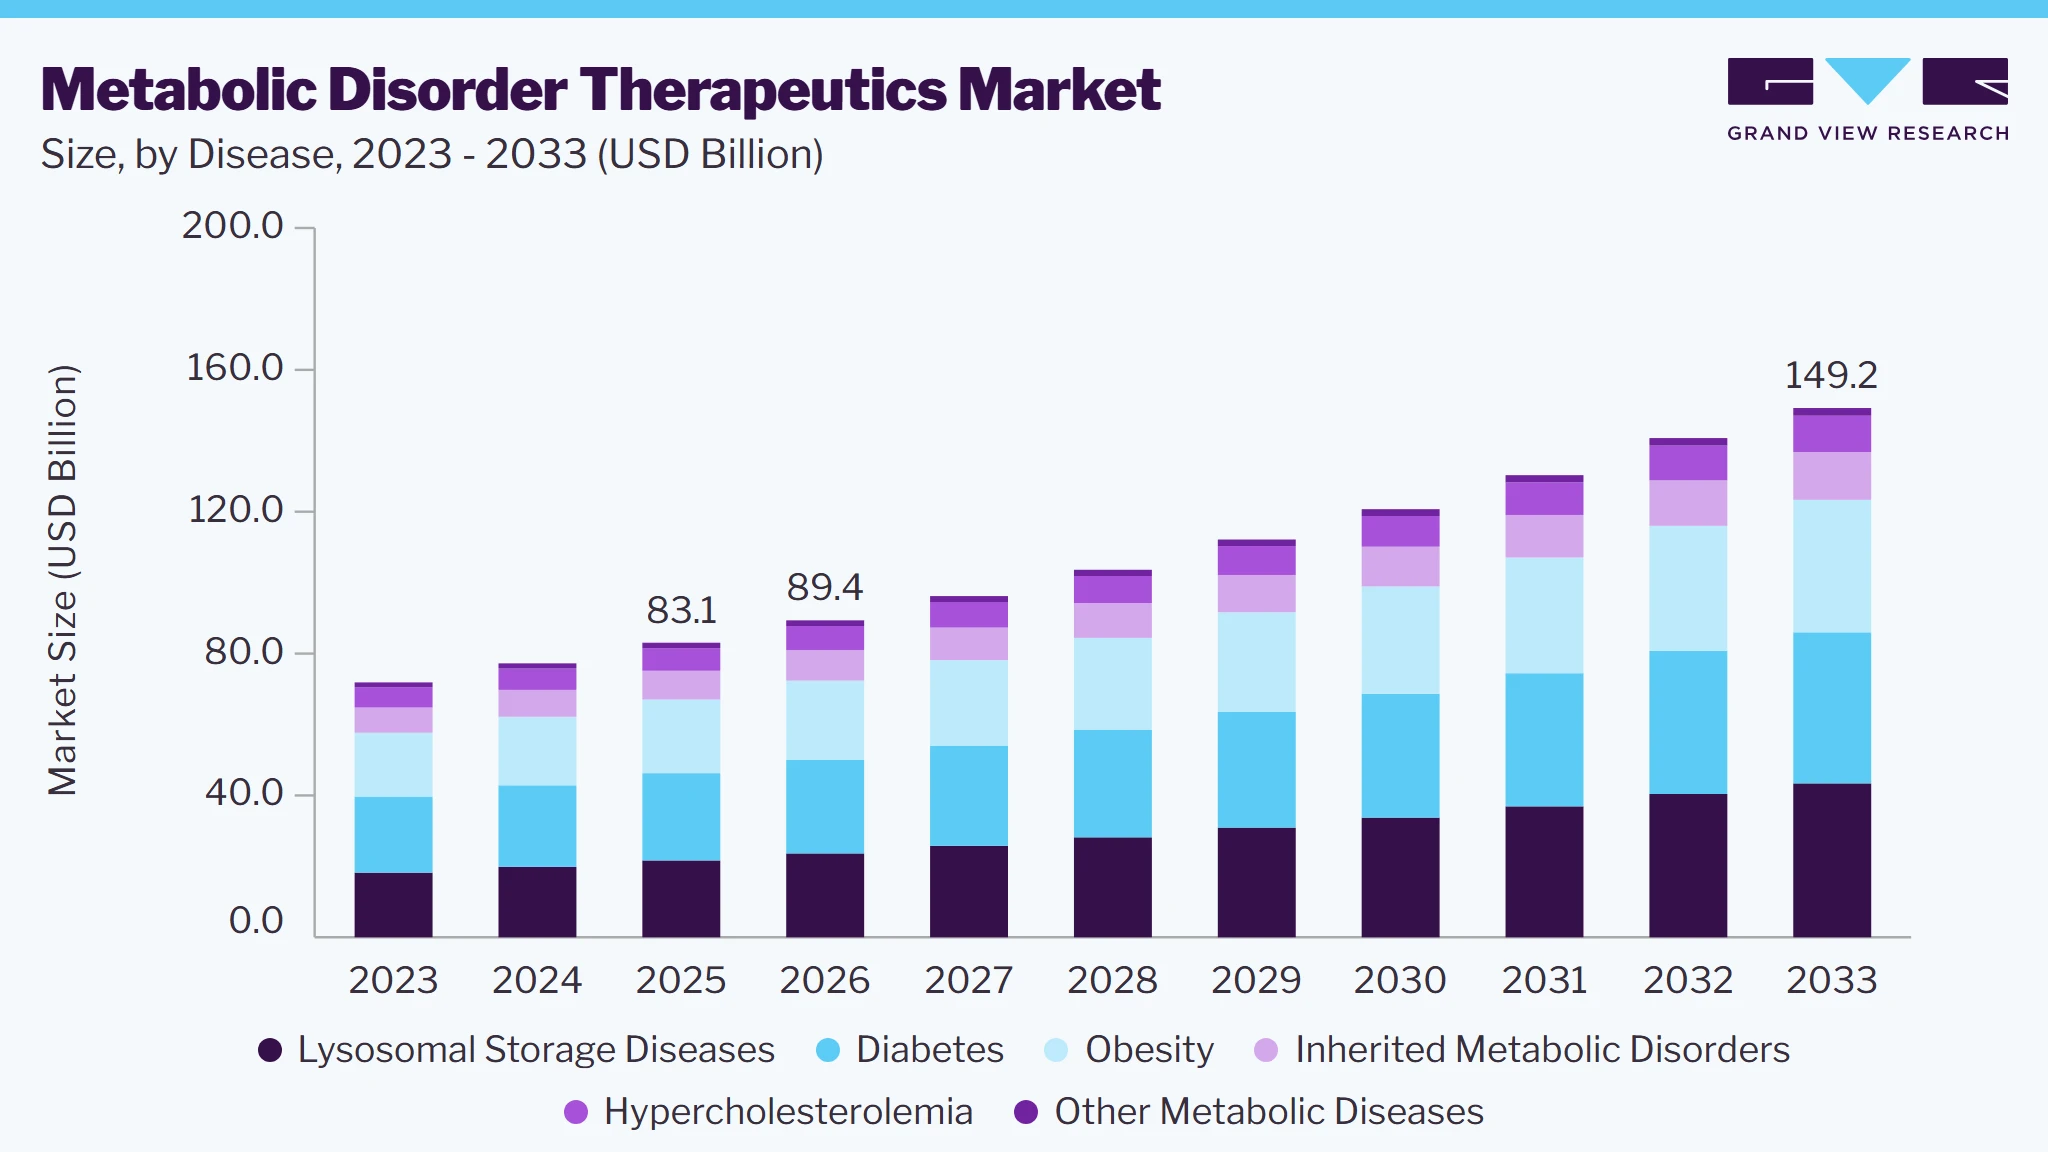
- By disease: Diabetes segment led the market with the largest revenue share of 29.6% in 2025.
- By therapy: Enzyme replacement therapy segment led the market with the largest revenue share of 30.8% in 2025.
- By route of administration: Parenteral segment led the market with the largest revenue share of 49.9% in 2025.
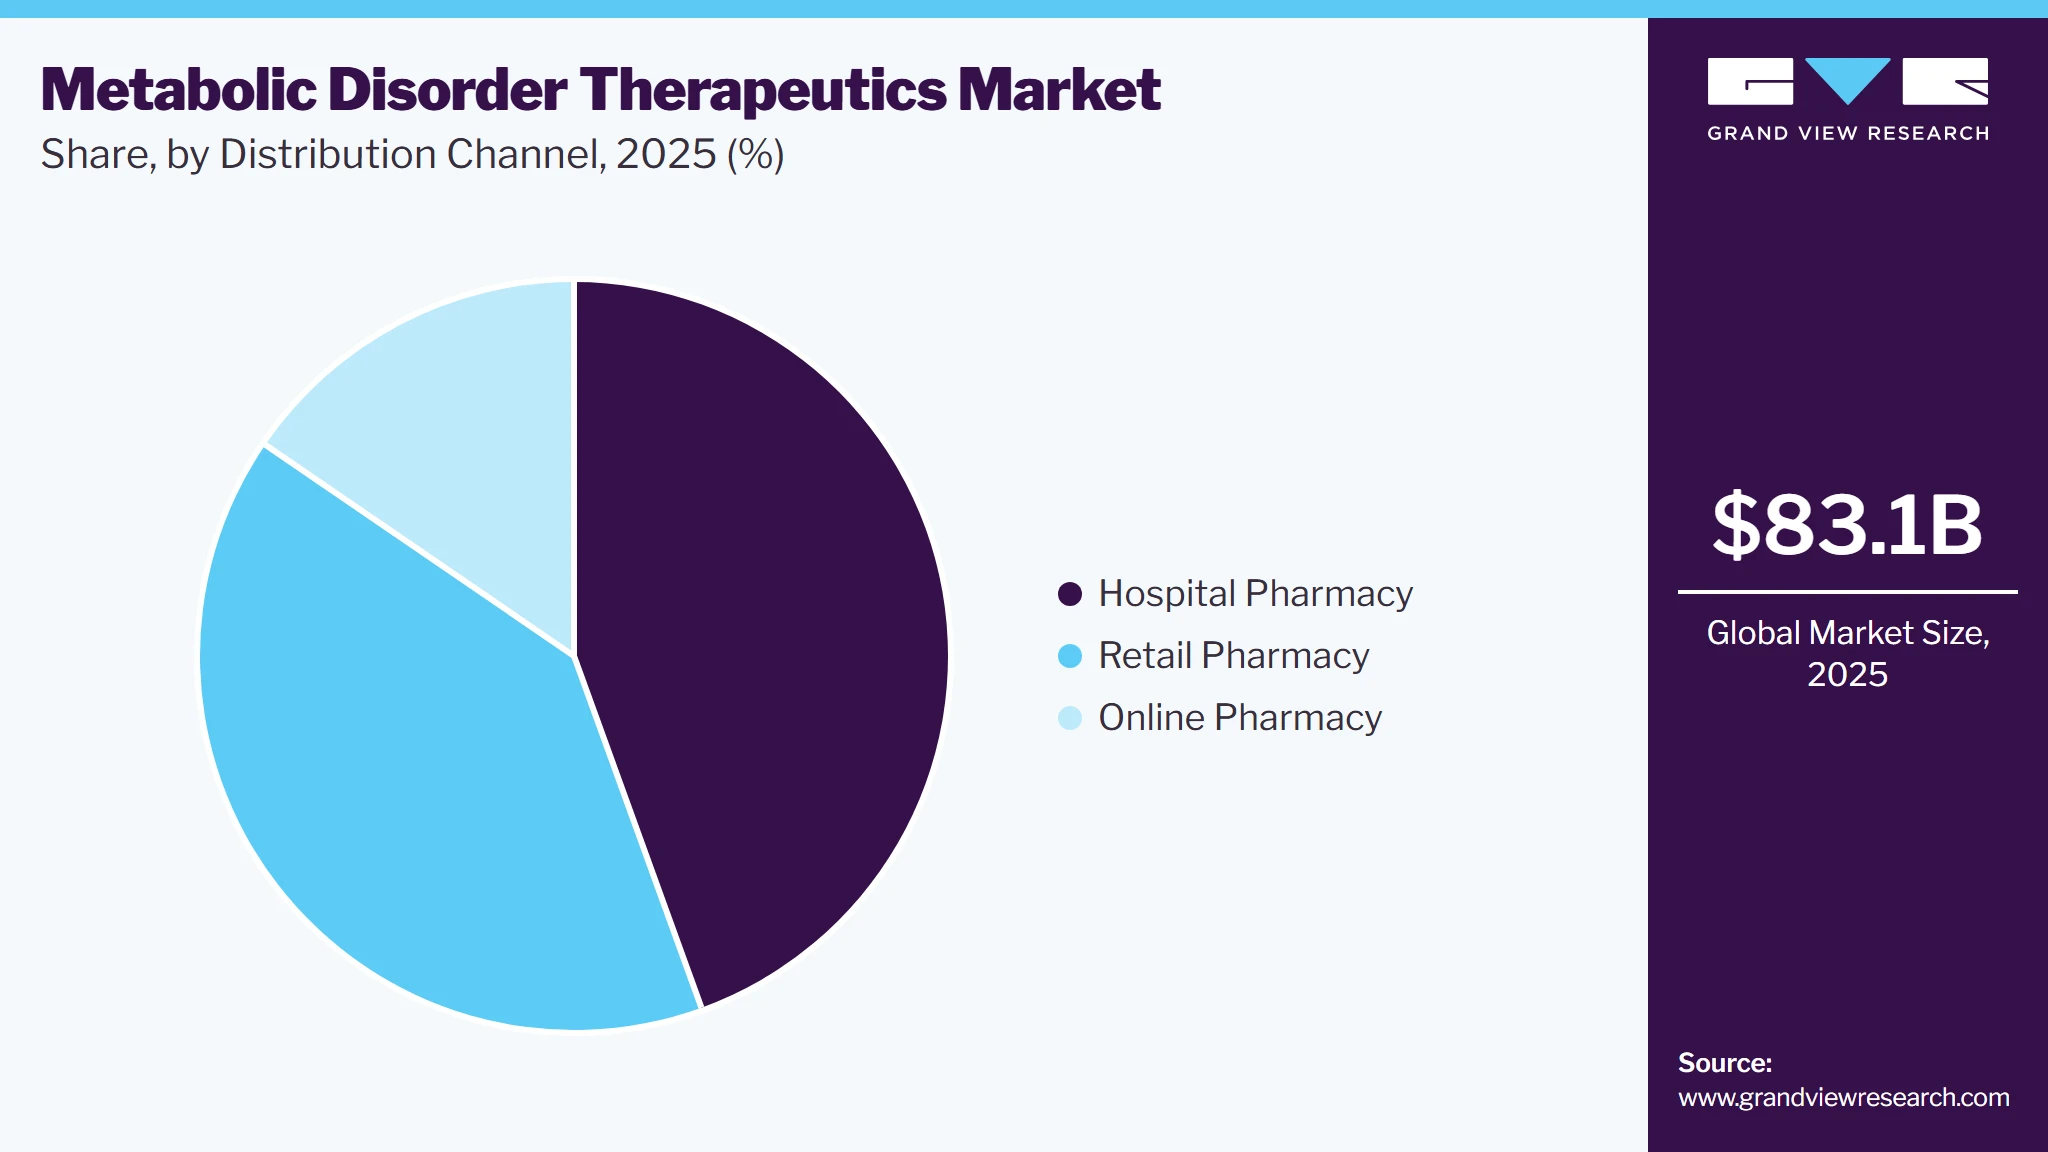
- By distribution channel: Hospital pharmacy segment led the market with the largest revenue share of 44.5% in 2025.
Regional Highlights
- Largest regional market: North America (39.9% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 83.1 Billion
- Estimated market size in 2026: USD 89.4 Billion
- Projected market size by 2033: USD 149.2 Billion
- CAGR (2026-2033): 7.6%
Prism AI by Grand View Research Free to tryAsk a question about the metabolic disorder therapeutics marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Innovative biotechnology and pharmaceuticals have paved the way for the launch of novel drug formulations and targeted therapies that cater to the unique needs of individual patients. Tailored metabolic disorder therapies offering enhanced efficacy and safety profiles to improve patient outcomes are being developed. Moreover, partnerships and collaborations in the industry reflect a shift towards precision medicine approaches. For instance, in November 2024, Ascendis Pharma and Novo Nordisk A/S formed a collaboration to develop and commercialize TransCon technology products for metabolic and cardiovascular diseases.
 To learn more about this report, Download Free Sample Report
Increased financial investment in research and development has led to a wider array of therapeutic options and improved access to care for patients suffering from metabolic disorders. This trend is further supported by regulatory bodies that provide essential backing for clinical trials targeting new therapies. For instance, in September 2024, Travere Therapeutics announced that the FDA granted full approval for FILSPARI (sparsentan), establishing it as the only non-immunosuppressive treatment to significantly slow kidney function decline in IgA nephropathy.
Furthermore, growing awareness and education about metabolic disorders are driving market demand. As healthcare professionals and the public become more informed about the importance of early diagnosis and effective management strategies, more individuals are seeking treatment. With educational initiatives emphasizing the need for timely interventions, broader recognition of these disorders and their consequences is fostering a more proactive approach to healthcare. Collectively, these factors underscore a burgeoning Metabolic Disorder Therapeutics Market, ripe with opportunities for innovative solutions and impactful regulatory support.
Market Dynamics
The metabolic disorder therapeutics market is expanding as the global burden of diabetes, obesity, dyslipidemia, and rare inherited metabolic disorders continues to increase. Rising diagnosis rates, aging populations, sedentary lifestyles, and changing dietary patterns are supporting sustained demand for long term pharmacological management. The market is benefiting from continued innovation in incretin-based therapies, enzyme replacement therapies, gene therapies, and targeted treatments for rare metabolic diseases. Strong clinical outcomes and broader reimbursement for selected high value therapies are encouraging adoption across major healthcare markets. Pharmaceutical companies are increasing investments in research, lifecycle management, and label expansion to strengthen their metabolic disease portfolios. However, high treatment costs for advanced therapies, limited access in low- and middle-income countries, and pricing pressure from healthcare systems remain important challenges. Growing availability of biosimilars and generic medicines is increasing treatment accessibility in several markets. Regulatory support for orphan drugs, advances in precision medicine, and expanding newborn screening programs are expected to create additional opportunities, particularly for rare metabolic disorders requiring early diagnosis and specialized therapeutic intervention.
The metabolic disorder therapeutics market is expanding due to increasing investments in innovative therapies targeting obesity, diabetes, and other metabolic diseases. Pharmaceutical companies are strengthening their pipelines through collaborations focused on oral therapies, precision medicine, and novel drug targets that improve patient outcomes and treatment adherence. The growing prevalence of metabolic disorders, increasing diagnosis rates, and supportive regulatory pathways are encouraging manufacturers to accelerate research and development activities. Advances in small molecule therapeutics and targeted medicines are also broadening treatment options for patients with chronic metabolic conditions. For instance, in May 2025, Reuters reported that Novo Nordisk entered a collaboration with Septerna to develop oral small molecule therapies for obesity, type 2 diabetes, and other cardiometabolic diseases. The collaboration covered four development programs targeting G protein coupled receptors, highlighting continued industry investment in expanding next generation metabolic therapeutics.
The adoption of advanced metabolic disorder therapeutics continues to face challenges due to reimbursement restrictions, pricing pressure, and increasing scrutiny from healthcare payers. Many innovative therapies require comprehensive clinical evidence before achieving broad reimbursement, while healthcare systems continue to implement cost containment measures for chronic disease treatments. These factors can delay patient access and influence prescribing decisions despite strong clinical efficacy. In addition, manufacturers are facing increasing pressure from government pricing initiatives and reimbursement negotiations in major pharmaceutical markets. For instance, in January 2025, Reuters reported that the U.S. government selected Novo Nordisk's Ozempic and Wegovy among 15 medicines for Medicare price negotiations under the Inflation Reduction Act. The announcement included 15 prescription medicines that would undergo negotiated pricing for implementation in 2027, reflecting increasing government efforts to manage pharmaceutical expenditure for metabolic therapies.
The development of oral therapies represents a significant opportunity for the metabolic disorder therapeutics market by improving patient convenience, increasing treatment adherence, and expanding access across broader patient populations. Pharmaceutical companies are increasingly prioritizing oral formulations that can provide efficacy comparable to injectable therapies while reducing treatment burden. Continued advances in targeted drug discovery and precision medicine are expected to support the introduction of differentiated therapies for obesity and diabetes. For instance, in January 2025, Reuters reported that Medicare began covering Eli Lilly's Zepbound for adults with obesity and obstructive sleep apnea following its regulatory approval for this indication. The decision expanded access to the first approved medicine for obstructive sleep apnea and increased treatment availability across the Medicare population of approximately 65 million beneficiaries.
Disease Insights
Based on disease, the diabetes segment led the market with the largest revenue share of 29.6% in 2025, driven by the increasing prevalence of diabetes, particularly type 2 diabetes, affecting more than 5% of the global population. Lifestyle factors, including sedentary behavior and poor dietary habits, exacerbate this issue. The ongoing requirement for consistent medication to regulate blood sugar levels ensures sustained demand for antidiabetic therapies, bolstered by advancements in drug development and heightened awareness of effective diabetes management practices.
Lysosomal storage diseases (LSDs) are expected to grow at the fastest CAGR of 9.3% over the forecast period. LSDs are progressive neurological conditions resulting from enzyme deficiencies, causing severe symptoms and early mortality. Current therapies, including enzyme replacement and substrate reduction, are limited for neurological issues. Recent advancements in gene therapy and targeted treatments provide promising prospects for improved patient outcomes and management options.
Therapy Insights
Based on therapy, the enzyme replacement therapy segment led the market with the largest revenue share of 30.8% in 2025. ERT targets the fundamental enzyme deficiencies associated with lysosomal storage disorders, significantly improving patient health and quality of life. Growing awareness and enhanced diagnostic capabilities are leading to increased patient identification and treatment, while advancements in ERT formulations and delivery methods are improving adherence and driving demand.
Gene therapy is anticipated to witness the fastest rate of 9.7% over the forecast period. Gene therapy holds significant potential to offer curative solutions for inherited metabolic diseases with limited treatment options. By directly targeting defective genes through gene editing and viral vector delivery, this transformative approach is showing promising results in recent clinical trials. For instance, in September 2023, UC Davis Health initiated the first gene therapy for Wilson Disease. As regulatory approvals increase, improved patient outcomes are anticipated.
Route Of Administration Insights
Based on route of administration, the parenteral segment led the market with the largest revenue share of 49.9% in 2025, aided by rapid onset of action and high bioavailability. Parenteral administration effectively bypasses the gastrointestinal tract, avoiding first-pass metabolism, crucial for immediate therapeutic effects. This method ensures precise dosing and is vital for medications with poor oral absorption, improving treatment adherence and patient outcomes.
Oral therapeutics are expected to register the fastest CAGR of 8.2% over the forecast period. Oral administration is non-invasive, easy for patients to self-administer, and typically preferred over injections, resulting in higher treatment adherence. This route accommodates diverse formulations, offering enhanced therapeutic options for metabolic disorders, while advancements in drug delivery technologies are improving the bioavailability of oral medications for conditions such as diabetes and obesity.
Distribution Channel Insights
Based on distribution channel, the hospital pharmacy segment led the market with the largest revenue share of 44.5% in 2025. Hospital pharmacies play a vital role in dispensing complex medications, particularly for metabolic disorders that necessitate specialized handling. The rising hospitalization rates for these conditions, combined with enhanced healthcare infrastructure and trained professionals, underscore the importance of hospital pharmacies in providing immediate access and effective management of therapeutic interventions.
 To learn more about this report, Download Free Sample Report
The online pharmacies sector is projected to grow at the fastest CAGR of 8.8% over the forecast period. Online pharmacies provide convenience and accessibility, enabling patients, particularly those with chronic conditions or mobility challenges, to order medications from home. Competitive pricing, automated refill reminders, and comprehensive medication information promote adherence, while the privacy offered appeals to patients hesitant to discuss sensitive health issues in person.
Regional Insights
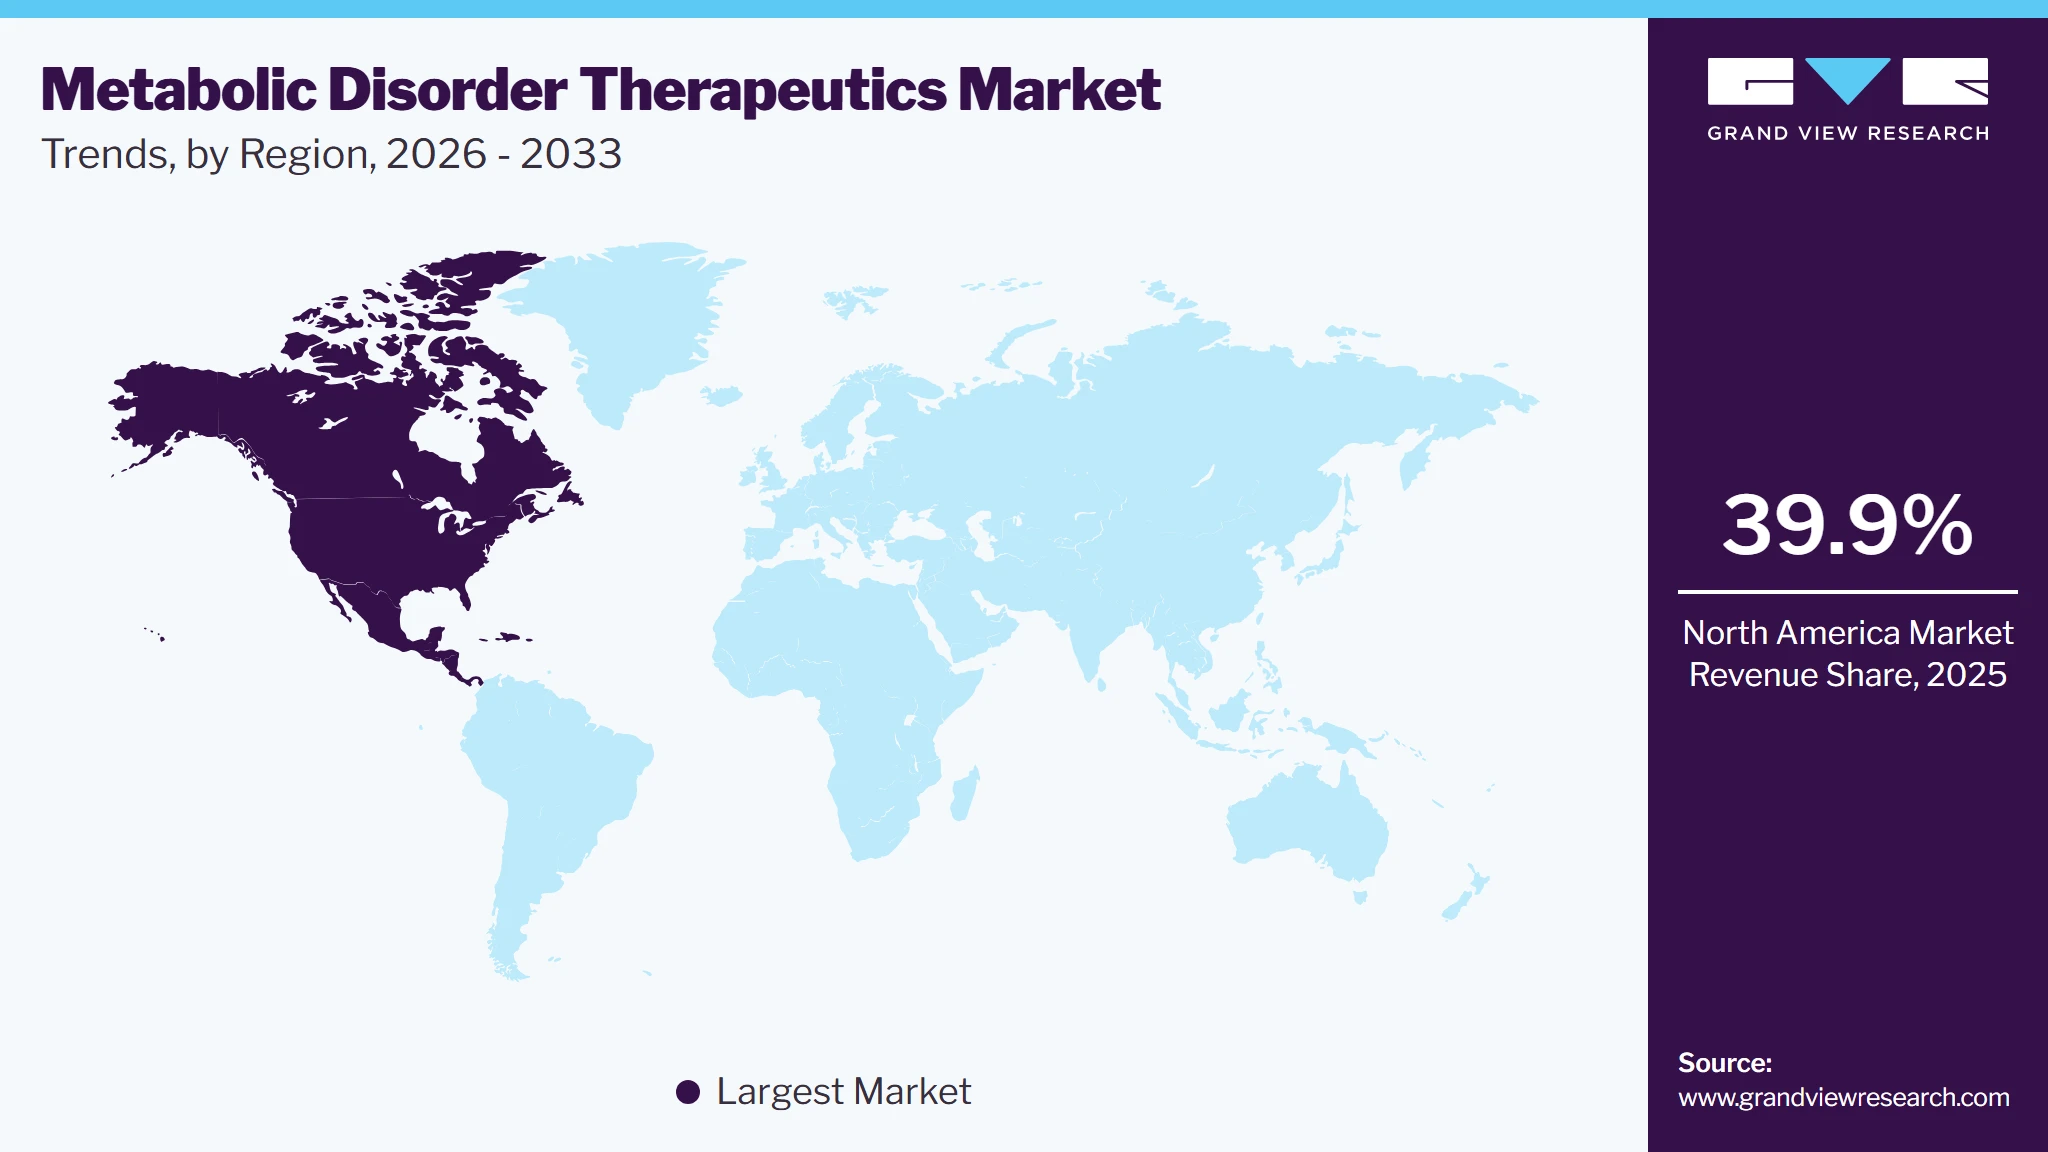
North America dominated the metabolic disorder therapeutics market with the largest revenue share of 39.9% in 2025. North America boasts a strong healthcare infrastructure, substantial investments in research and development, and a notable prevalence of metabolic disorders such as diabetes and obesity. The region’s advanced medical technologies, vibrant pharmaceutical industry, and supportive government policies bolster innovative therapies, while growing public awareness enhances the demand for effective treatments.
 To learn more about this report, Download Free Sample Report
U.S. Metabolic Disorder Therapeutics Market Trends
The metabolic disorder therapeutics market in the U.S. held the largest share in the North America region in 2025. The healthcare system in the U.S. ensures access to advanced therapies and clinical trials. According to the CDC, over 30% of U.S. adults are estimated to have metabolic syndrome, with notable disparities related to race and socioeconomic status. Significant investments in biotechnology and pharmaceutical research, combined with the presence of major companies and a focus on personalized medicine, are aiding the metabolic disorder therapeutics industry in the country.
Europe Metabolic Disorder Therapeutics Market Trends
Europe metabolic disorder therapeutics market held substantial market share in 2024. The region has launched multiple health initiatives to enhance diagnosis and treatment of diabetes and obesity. Supportive regulatory frameworks promote the introduction of innovative therapies, while substantial healthcare expenditures ensure access. Collaborative efforts among European nations to boost research funding and biotechnology advancements further solidify the region’s prominence in metabolic disorder therapeutics.
The metabolic disorder therapeutics market in Germany led the Europe market in 2024. The country hosts numerous biotech firms and research institutions dedicated to metabolic disorders, driving innovation in treatment options. Germany’s strong healthcare system offers comprehensive patient coverage, ensuring access to advanced therapies. Rising public awareness of metabolic health issues and governmental support for healthcare initiatives further enhance this landscape.
Asia Pacific Metabolic Disorder Therapeutics Market Trends
Asia Pacific metabolic disorder therapeutics market is expected to register the fastest CAGR of 8.5% in the forecast period. The region’s growing middle class is fueling demand for effective healthcare solutions, supported by improvements in healthcare infrastructure that enhance treatment access. Government initiatives targeting metabolic diseases through public health campaigns are further stimulating market growth. The ICMR-INDIAB study indicates that diabetes prevalence in India is 11.4%, with obesity at 28.6% and hypertension at 35.5%, highlighting the necessity for innovative therapeutic approaches to address these concerns.
The metabolic disorder therapeutics market in China is expected to grow at the fastest rate of 9.8% over the forecast period in the Asia Pacific market. In Asia, particularly in China, the prevalence of metabolic syndrome is approximately 28.8%, driven by rapid urbanization and lifestyle changes. The Chinese government has prioritized healthcare reforms, enhancing access to medications and treatment options. Economic growth has boosted disposable incomes, enabling greater healthcare service utilization, while ongoing investments in biotechnology and pharmaceutical research are fostering innovation in treatment development.
Key Metabolic Disorder Therapeutics Company Insights
Some key companies operating in the market include Novo Nordisk A/S; Eli Lilly and Company; Takeda Pharmaceutical Company Limited; Sanofi; among others. Companies are actively pursuing strategic initiatives, including collaborations, product innovations, and increased investment in R&D, to effectively tackle the growing prevalence of metabolic disorders.
-
Novo Nordisk A/S operates in diabetes care, specializing in innovative insulin products, GLP-1 receptor agonists, and therapies for obesity and metabolic disorders, with a focus on enhancing glycemic control and managing diabetes-related complications.
-
Sanofi provides a diverse portfolio of insulin products and GLP-1 receptor agonists to improve patient outcomes. The company also invests in innovative solutions, including RNA-based therapies, to comprehensively address metabolic diseases.
Key Metabolic Disorder Therapeutics Companies:
The following key companies have been profiled for this study on the metabolic disorder therapeutics market.
- Novo Nordisk A/S
- Eli Lilly and Company
- Takeda Pharmaceutical Company Limited
- Sanofi
- Merck KGaA
- AstraZeneca
- AbbVie Inc.
- Johnson & Johnson Innovative Medicine
- Amgen Inc.
- Biocon
- BioMarin
- Boehringer Ingelheim International GmbH
- Bristol-Myers Squibb Company
- Cipla Inc.
Recent Developments
-
In October 2024, Boehringer Ingelheim received U.S. FDA Breakthrough Therapy designation for survodutide and initiated two Phase III trials for specific metabolic conditions.
-
In September 2024, Novo Nordisk A/S announced successful results from a Phase 2a trial of monlunabant, demonstrating significant weight loss in participants compared to placebo, following the acquisition of Inversago Pharmaceuticals.
-
In August 2024, Eli Lilly and Company announced the release of single-dose vials of Zepbound (tirzepatide), priced at over 50% less than other obesity incretin medicines, enhancing access for adults with obesity.
-
In July 2024, Merck signed a non-binding Memorandum of Understanding with Gene Therapy Research Institution, collaborating on GMP production of viral vectors to accelerate gene therapy advancements for Parkinson’s Disease.
Metabolic Disorder Therapeutics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 83.1 billion
Estimated market size in 2026
USD 89.4 billion
Projected market size by 2033
USD 149.2 billion
Growth rate
CAGR of 7.6% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Disease, therapy, route of administration, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Novo Nordisk A/S; Eli Lilly and Company; Takeda Pharmaceutical Company Limited; Sanofi; Merck KGaA; AstraZeneca; AbbVie Inc.; Johnson & Johnson Innovative Medicine; Amgen Inc.; Biocon; BioMarin; Boehringer Ingelheim International GmbH; Bristol-Myers Squibb Company; Cipla Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Metabolic Disorder Therapeutics Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global metabolic disorder therapeutics market report based on disease, therapy, route of administration, distribution channel, and region:
-
Disease Outlook (Revenue, USD Million, 2021 - 2033)
-
Lysosomal Storage Diseases
-
Diabetes
-
Obesity
-
Inherited Metabolic Disorders
-
Hypercholesterolemia
-
Other Metabolic Diseases
-
-
Therapy Outlook (Revenue, USD Million, 2021 - 2033)
-
Enzyme Replacement Therapy
-
Cellular Transplantation
-
Small Molecule Based Therapy
-
Substrate Reduction Therapy
-
Gene Therapy
-
Drug Therapy
-
-
Route Of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Oral
-
Parenteral
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Online Pharmacies
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The metabolic disorder therapeutics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each metabolic disorder therapeutics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Disease
Revenue capture definition
Lysosomal Storage Diseases
Revenue generated from therapeutics prescribed for the treatment of lysosomal storage diseases, including Gaucher disease, Fabry disease, Pompe disease, Mucopolysaccharidoses (MPS), Niemann Pick disease, and other lysosomal storage disorders. All sales associated with these indications are included exclusively within this segment, irrespective of therapy type or route of administration.
Diabetes
Revenue generated from therapeutics indicated for the treatment of type 1 diabetes, type 2 diabetes, gestational diabetes, and other diabetes related conditions. This includes insulin products, GLP 1 receptor agonists, SGLT2 inhibitors, DPP 4 inhibitors, sulfonylureas, biguanides, and other approved antidiabetic therapies. Revenue from all diabetes specific indications is classified exclusively within this segment.
Obesity
Revenue generated from therapeutics approved for chronic weight management and obesity treatment, including GLP 1 receptor agonists, dual incretin therapies, combination anti obesity medicines, and other pharmacological interventions. All revenue associated with obesity indications is included solely within this segment regardless of treatment setting or administration route.
Inherited Metabolic Disorders
Revenue generated from therapeutics used to treat inherited metabolic disorders, including phenylketonuria, maple syrup urine disease, homocystinuria, urea cycle disorders, glycogen storage diseases, and other inherited metabolic conditions. Revenue is captured exclusively for approved inherited metabolic disorder indications.
Hypercholesterolemia
Revenue generated from therapeutics prescribed for hypercholesterolemia and related lipid disorders, including statins, PCSK9 inhibitors, siRNA therapies, ATP citrate lyase inhibitors, bile acid sequestrants, and other lipid lowering medicines. All sales related to hypercholesterolemia treatment are classified exclusively within this segment.
Others
Revenue generated from therapeutics used for metabolic disorders not included in the above categories, including hypertriglyceridemia, metabolic associated steatotic liver disease, lipodystrophy, rare endocrine metabolic disorders, and other approved metabolic disease indications.
Segment - Therapy
Revenue capture definition
Enzyme Replacement Therapy
Revenue generated from enzyme replacement therapies administered to replace deficient or absent enzymes in metabolic disorders, including approved recombinant enzyme products. Revenue is captured exclusively from enzyme replacement therapy products across all eligible indications.
Cellular Transplantation
Revenue generated from cellular transplantation procedures and associated therapeutic products used in the treatment of metabolic disorders, including hematopoietic stem cell transplantation and other approved cellular therapies intended to restore metabolic function.
Small Molecule Based Therapy
Revenue generated from small molecule therapeutics that modulate metabolic pathways or disease mechanisms through targeted pharmacological action. This segment includes approved oral and injectable small molecule therapies indicated for metabolic disorders.
Substrate Reduction Therapy
Revenue generated from substrate reduction therapies designed to decrease the production or accumulation of toxic metabolites in metabolic disorders. All approved substrate reduction therapies are included exclusively within this segment.
Gene Therapy
Revenue generated from gene therapies intended to correct or replace defective genes responsible for inherited metabolic disorders. Revenue includes approved in vivo and ex vivo gene therapy products indicated for metabolic diseases.
Drug Therapy
Revenue generated from conventional pharmacological therapies used in the treatment and long term management of metabolic disorders, excluding enzyme replacement therapy, substrate reduction therapy, gene therapy, and cellular transplantation. This includes biologics and small molecule medicines prescribed across metabolic disease indications.
Segment - Route of Administration
Revenue capture definition
Oral
Revenue generated from metabolic disorder therapeutics administered orally, including tablets, capsules, powders, granules, oral liquids, and other approved oral formulations.
Parenteral
Revenue generated from therapeutics administered through injectable routes, including intravenous, subcutaneous, intramuscular, and other approved parenteral formulations.
Others
Revenue generated from therapeutics administered through alternative routes, including inhalational, topical, transdermal, buccal, nasal, and other approved administration routes not classified as oral or parenteral.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacies
Revenue generated from metabolic disorder therapeutics dispensed through hospital pharmacies, including inpatient, outpatient, specialty hospital, and institutional healthcare settings.
Retail Pharmacies
Revenue generated from therapeutics distributed through chain pharmacies, independent pharmacies, drug stores, and community pharmacy networks for outpatient use.
Online Pharmacies
Revenue generated from therapeutics dispensed through licensed online pharmacies and digital pharmacy platforms that deliver prescription metabolic disorder medicines directly to patients.
Estimation Model
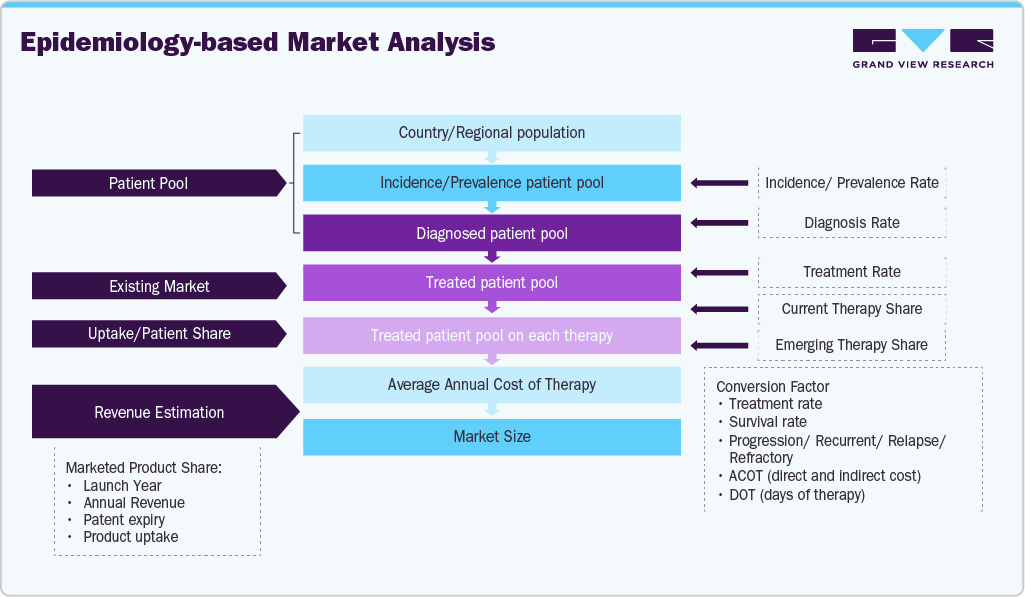
The metabolic disorder therapeutics market was estimated using a patient-based epidemiology and revenue modeling approach. The study began by assessing the country and regional population using government statistics and international demographic databases. Disease specific prevalence and incidence were analyzed for diabetes, obesity, lysosomal storage diseases, inherited metabolic disorders, hypercholesterolemia, and other metabolic diseases using peer reviewed literature, disease registries, and public health agencies. The diagnosed and treated patient pools were estimated by evaluating healthcare access, diagnosis rates, treatment guidelines, reimbursement policies, and prescribing practices. Treated patients were allocated across enzyme replacement therapy, drug therapy, small molecule therapy, substrate reduction therapy, gene therapy, and cellular transplantation based on approved indications and market adoption. Average annual therapy costs were determined using manufacturer information, public pricing databases, reimbursement schedules, and published literature. Country level revenues were aggregated to regional and global markets and validated through primary interviews, secondary research, and data triangulation.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Metabolic Disorder Therapeutics Competitive Landscape & Pipeline Assessment
Conducted a comprehensive assessment of the global metabolic disorder therapeutics landscape by evaluating approved therapies, late-stage pipeline assets, mechanisms of action, clinical development progress, and competitive positioning across diabetes, obesity, lysosomal storage diseases, inherited metabolic disorders, and hypercholesterolemia. The study profiled leading companies including Novo Nordisk, Eli Lilly, Sanofi, Takeda, BioMarin, AstraZeneca, and emerging innovators, while analyzing innovation trends, licensing activities, and future therapeutic opportunities.
Enabled the client to identify high growth therapeutic segments, evaluate competitive threats, benchmark pipeline maturity, and prioritize licensing, acquisition, and partnership opportunities across both common and rare metabolic disorders.
Metabolic Therapeutics Technology & Treatment Benchmarking Study
Delivered a detailed benchmarking assessment of therapeutic technologies, comparing enzyme replacement therapies, gene therapies, substrate reduction therapies, small molecule therapies, conventional drug therapies, and cellular transplantation approaches. The study evaluated clinical efficacy, safety profiles, regulatory status, manufacturing complexity, commercialization readiness, and differentiation across leading metabolic disease treatment platforms.
Enabled the client to assess technology competitiveness, identify innovation gaps, benchmark emerging therapeutic platforms, and prioritize research and development investments aligned with evolving standards of care and future market demand.
Metabolic Therapeutics Manufacturing & Commercialization Feasibility Assessment
Conducted a strategic assessment of the manufacturing and commercialization ecosystem for metabolic disorder therapeutics, evaluating biologics manufacturing capabilities, enzyme production, gene therapy infrastructure, supply chain resilience, regulatory compliance requirements, contract development and manufacturing organizations, and regional commercialization readiness. The study also assessed manufacturing scalability and distribution capabilities supporting global product launches.
Supported strategic manufacturing and commercialization planning by identifying qualified manufacturing partners, optimizing supply chain strategies, evaluating outsourcing opportunities, mitigating operational risks, and strengthening long term commercial scalability across global metabolic therapeutics markets.
Frequently Asked Questions About This Report
The global metabolic disorder therapeutics market size was valued at USD 83.1 billion in 2025 and is estimated at USD 89.4 billion for 2026.
The global metabolic disorder therapeutics market is expected to grow at a CAGR of 7.6% from 2026 to 2033, reaching USD 149.2 billion by 2033.
The diabetes segment accounted for the largest market share, representing 29.6% of the global metabolic disorder therapeutics market in 2025.
North America dominated the metabolic disorder therapeutics market with a 39.9% revenue share in 2025.
Asia Pacific is expected to be the fastest-growing regional market during the forecast period, supported by increasing healthcare expenditure, improving access to advanced therapies, and the rising burden of metabolic diseases.
The enzyme replacement therapy segment led the metabolic disorder therapeutics market, accounting for the largest revenue share of 30.8% in 2025.
The parenteral route of administration led the metabolic disorder therapeutics market with a 49.9% revenue share in 2025.
Key players include Novo Nordisk A/S, Eli Lilly and Company, Takeda Pharmaceutical Company Limited, Sanofi, Merck KGaA, AstraZeneca, AbbVie Inc., Johnson & Johnson Innovative Medicine, Amgen Inc., Biocon, BioMarin, Boehringer Ingelheim International GmbH, Bristol Myers Squibb Company, and Cipla Inc.
The market is driven by the rising prevalence of diabetes, obesity, dyslipidemia, and rare inherited metabolic disorders, increasing diagnosis rates, growing investments in next generation therapies, advances in enzyme replacement therapy and gene therapy, supportive orphan drug regulations, and expanding precision medicine approaches.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


