
- Home
- »
- Consumer F&B
- »
-
Natural Dog Treats Market Size & Share Report, 2026-2033GVR Report cover

Natural Dog Treats Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Eatables, Chewable), By Distribution Channel (Supermarkets & Hypermarkets, Specialty Pet Stores, Online), By Region, And Segment Forecasts
Market Size, 2025
$7.8BMarket Estimate, 2026
$8.8BMarket Forecast, 2033
$18.6BCAGR, 2026–2033
12.3%Natural Dog Treats Market Summary
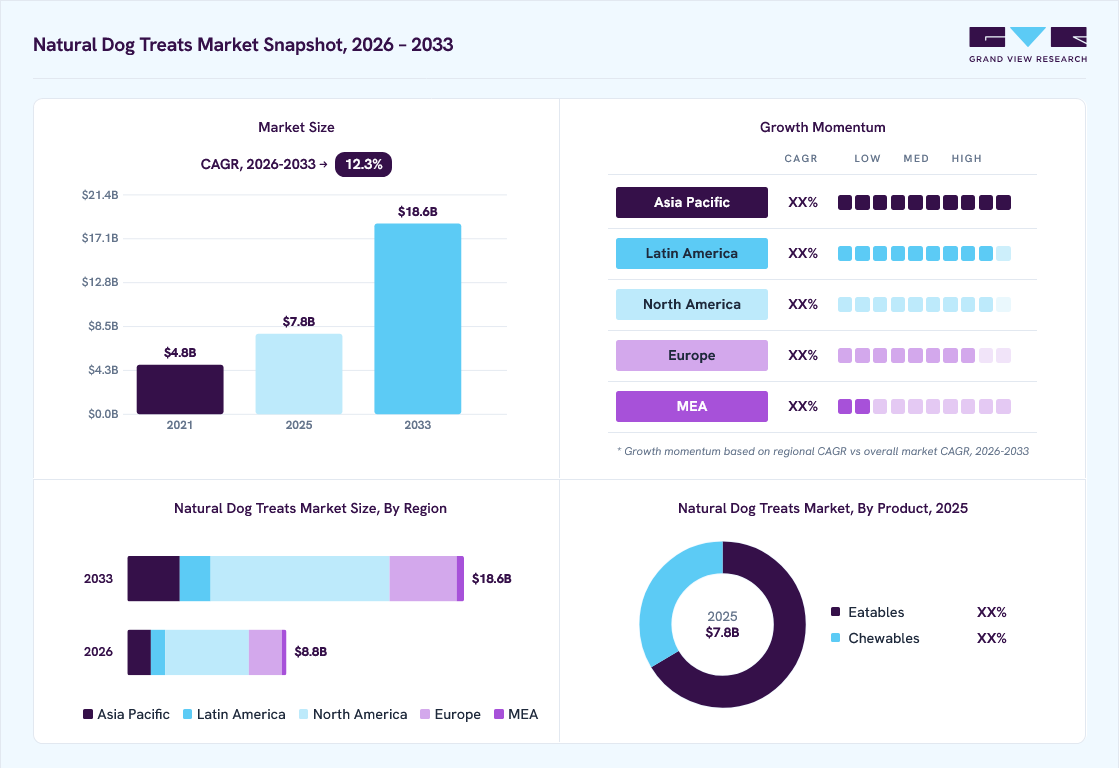
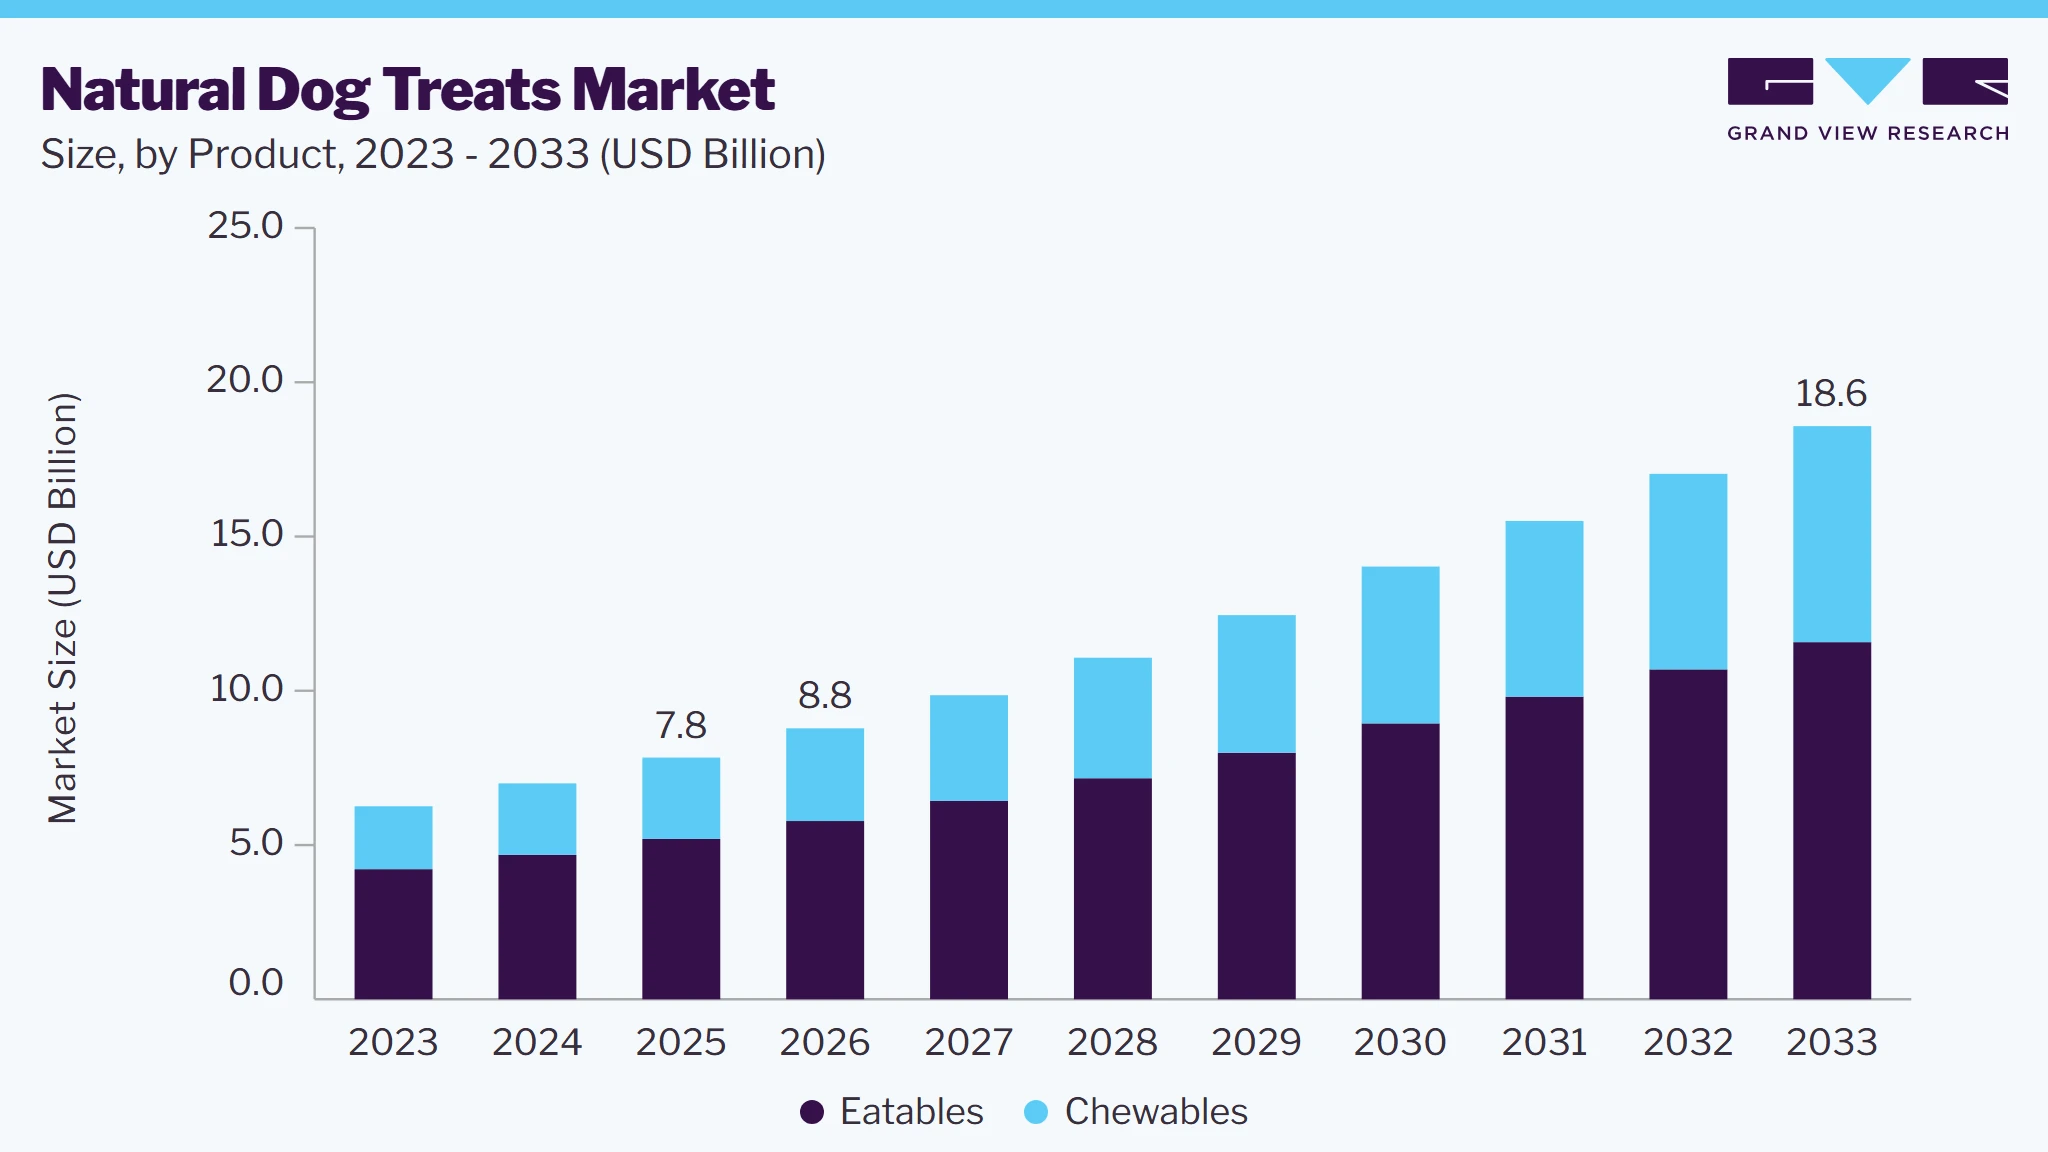
The global natural dog treats market size was valued at USD 7.8 billion in 2025 and is projected to grow from USD 8.8 billion in 2026 to USD 18.6 billion by 2033, at a CAGR of 12.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 52.6% in 2025. The rise in pet ownership globally, particularly among millennials and Gen Z, has led to a greater focus on pet health and wellness.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Eatables segment dominated the market, with a revenue share of 66.3% in 2025.
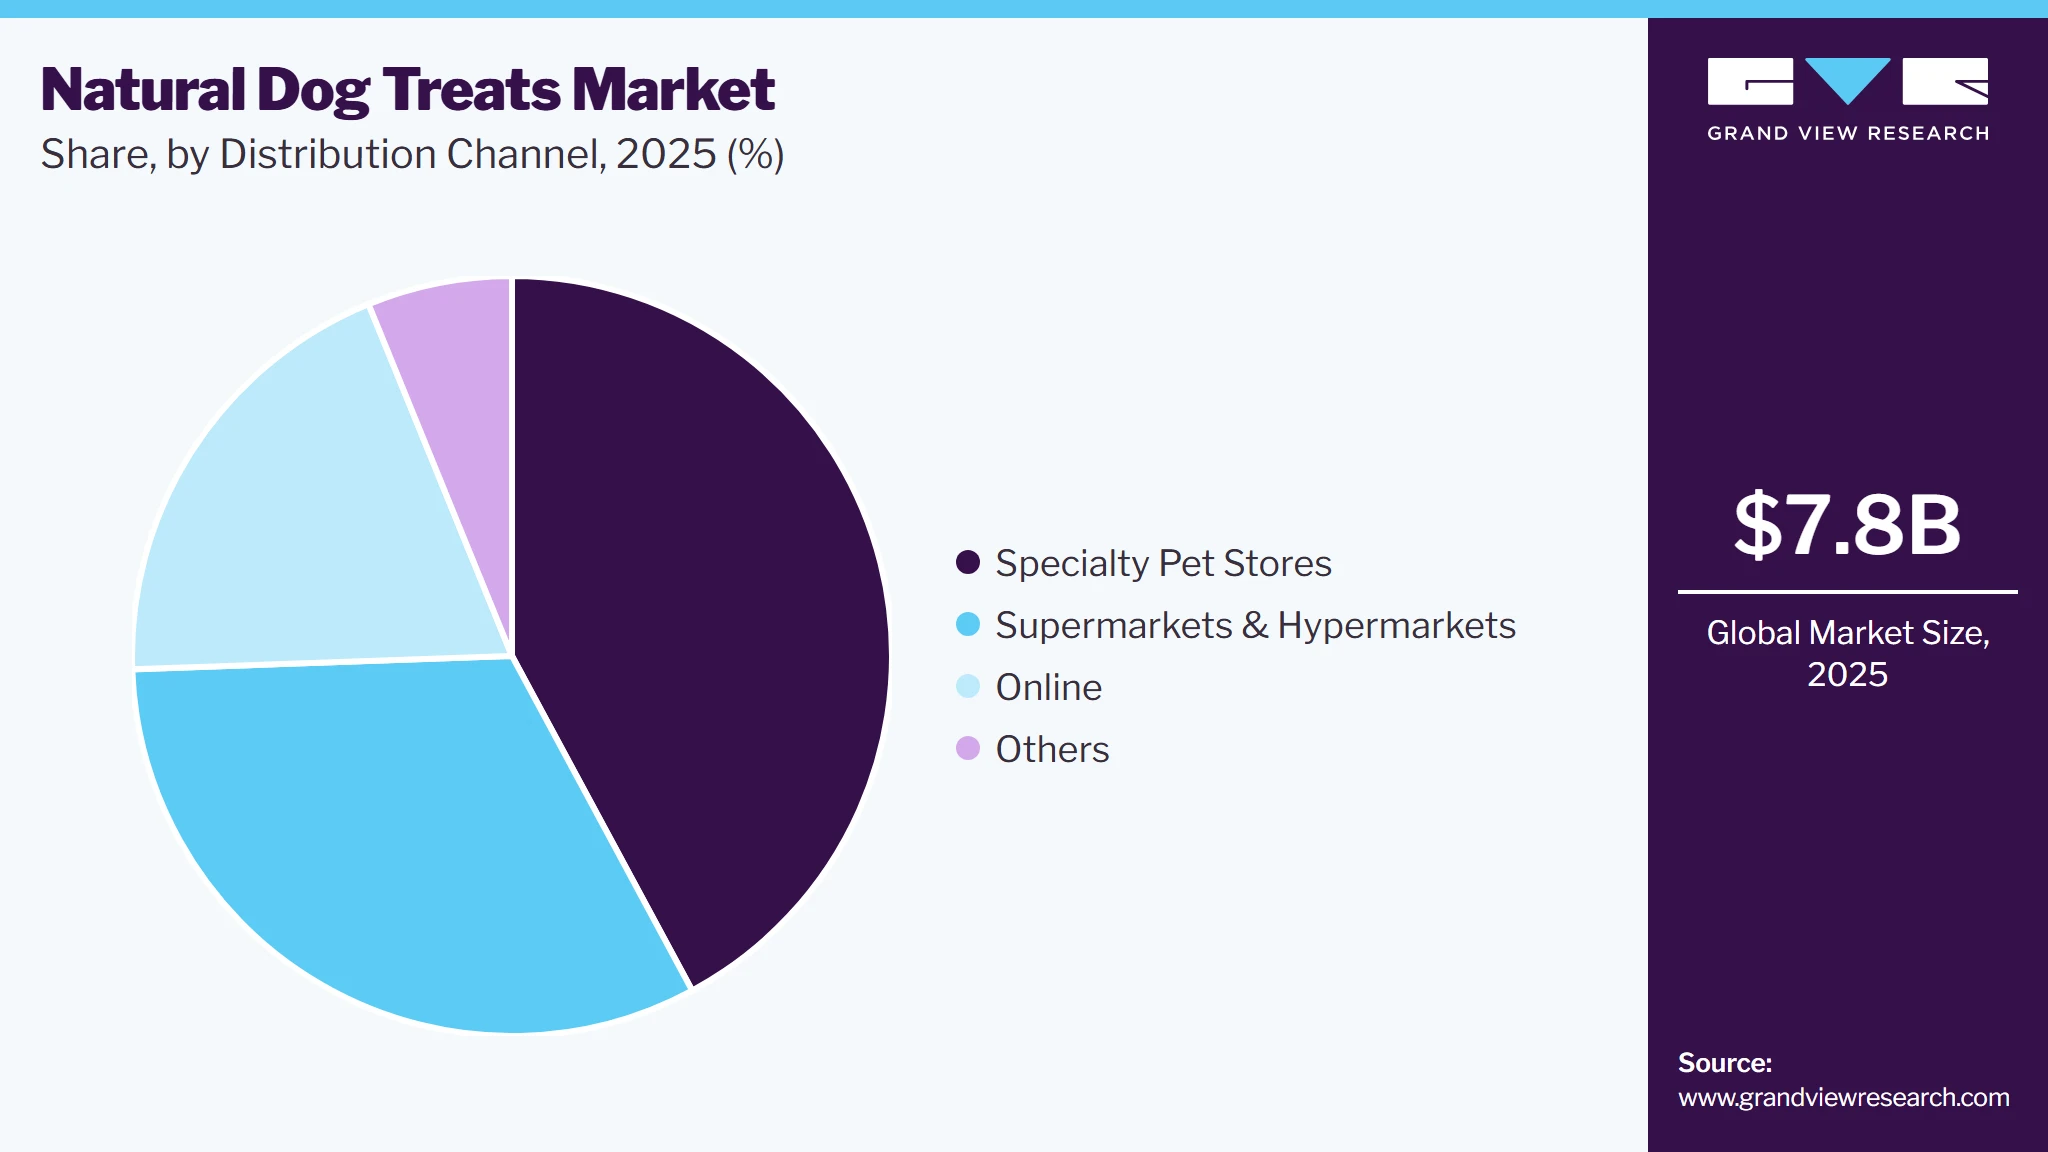
- By distribution channel: Specialty pet stores segment held the largest market share of 42.1% in 2025.
Regional Highlights
- Largest regional market: North America (52.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 7.8 Billion
- Estimated market size in 2026: USD 8.8 Billion
- Projected market size by 2033: USD 18.6 Billion
- CAGR (2026-2033): 12.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
This demographic is more inclined towards natural and organic products, extending this preference to their pets' diets. The trend of treating pets as family members has led to higher spending on premium pet products, including natural dog treats. Pet owners are more concerned about the ingredients in pet food, seeking high-quality, natural options that mirror the health-conscious choices they make for themselves.There is a growing awareness among pet owners about the importance of proper nutrition for their pets. Natural dog treats, free from artificial additives, preservatives, and fillers, are perceived as healthier options. This awareness is driving demand for treats that contribute to the overall well-being of pets.
 To learn more about this report, Download Free Sample Report
The increasing adoption of pet companions, such as dogs, is anticipated to present favorable opportunities for key players in the market over the forecast period. As per the findings of the 2023-2024 APPA National Pet Owners Survey, approximately 66% of households in the U.S., totaling 86.9 million households, are pet owners. Among these households, approximately 65.1 million own at least one dog.
Moreover, major market players are introducing new products to meet the growing demand for snacks and treats among dog owners. In March 2024, BARK broadened its range of consumable products with an inaugural collection comprising seven distinct flavors of dog treats. Branded as the Snack Pack, these treats draw inspiration from popular breakfast cereals, complete with corresponding mascots and delightful surprises in each box. The treat assortment consists of four flagship 10-ounce boxes and three resealable 10-ounce bags and is currently accessible at Target outlets, on target.com, and via bark. Co.
The market is set for sustained growth, driven by innovations in product formulations, strategic marketing efforts, and expanding distribution networks. Manufacturers and stakeholders in this sector have significant opportunities to capitalize on changing consumer trends and strengthen their positions in the global market. Companies are adopting strategies that resonate with human food marketing, emphasizing transparency in ingredient sourcing, nutritional benefits, and eco-friendly packaging. For instance, in May 2023, U.K.-based nut butter brand Pip & Nut entered the pet-food category by partnering with Butternut Box, a local dog-food supplier. The duo launched peanut butter bites, a range of dog treats made with peanut butter.
Companies are launching extensive awareness campaigns to educate pet owners about the benefits of natural dog treats. These campaigns highlight the nutritional advantages, health benefits, and ethical sourcing of natural ingredients, thereby encouraging pet owners to choose healthier options for their pets. In April 2024, Pawlistic Treats, a trusted provider of delicious and healthy pet treats, is excited to introduce the "Treats for Treats" campaign, dedicated to supporting pets in need. Committed to offering the best for pets, Pawlistic Treats has developed a line of cat and dog treats made from natural ingredients that promote good health.
Market Dynamics
The natural dog treats market is witnessing steady growth as pet owners increasingly prioritize premium nutrition, clean-label ingredients, and functional health benefits for their pets. Consumers are becoming more conscious of ingredient quality and are actively seeking treats made from natural, minimally processed, and preservative-free ingredients. Rising pet humanization trends, growing expenditure on companion animal care, and increased awareness regarding pet health and wellness are encouraging the adoption of natural dog treats. In addition, product innovations featuring grain-free formulations, organic ingredients, single-protein recipes, and functional additives are further supporting market expansion.
The increasing tendency of pet owners to treat dogs as family members is a major factor driving demand for natural dog treats. Consumers are becoming more attentive to their pets’ dietary needs and are willing to spend on products that promote overall health, digestion, immunity, skin health, and weight management. Concerns regarding artificial preservatives, synthetic flavors, fillers, and low-quality ingredients found in conventional treats have accelerated the shift toward natural alternatives.
Furthermore, rising dog ownership rates, particularly among urban households and younger consumers, are supporting market growth. Pet owners are increasingly purchasing treats not only as rewards and training aids but also as nutritional supplements that contribute to long-term health. The growing availability of premium pet products through supermarkets, specialty pet stores, veterinary clinics, and e-commerce platforms continues to strengthen demand for natural dog treats across both developed and emerging markets.
The relatively higher price of natural dog treats compared to conventional alternatives remains a significant challenge for market growth. Natural formulations often utilize premium ingredients, sustainable sourcing practices, and stricter manufacturing standards, resulting in higher production and retail costs. Price-sensitive consumers may be reluctant to transition from traditional treats, particularly in developing markets where pet care spending remains limited.
In addition, confusion surrounding product labeling and ingredient claims can affect purchasing decisions. While demand for natural products is increasing, varying definitions of terms such as natural, organic, and clean-label across regions may create uncertainty among consumers. Limited awareness regarding the nutritional benefits of natural treats and concerns over product shelf life due to reduced use of artificial preservatives may further restrict market penetration in certain regions.
The growing demand for functional pet nutrition presents significant opportunities for manufacturers operating in the natural dog treats market. Pet owners are increasingly seeking treats that deliver targeted health benefits beyond basic nutrition, including support for joint mobility, digestive health, dental hygiene, skin and coat condition, anxiety management, and immune function. This trend is encouraging the development of value-added products formulated with natural ingredients such as probiotics, omega fatty acids, collagen, turmeric, pumpkin, and other plant-based extracts.
Advancements in pet nutrition research, coupled with increasing personalization of pet diets, are creating opportunities for breed-specific, age-specific, and condition-specific natural treats. The rapid growth of online pet retail channels is further enabling manufacturers to reach broader consumer audiences and introduce innovative product offerings. Additionally, rising interest in sustainable and ethically sourced pet food ingredients is expected to create new avenues for premium natural dog treat brands seeking differentiation and long-term market growth.
Analyst Perspective
The natural dog treats market is evolving into a premium, health-focused category as pet owners increasingly prioritize ingredient quality, nutritional value, and overall canine wellbeing. While demand is being fueled by pet humanization and the shift toward natural and functional nutrition, the most sustainable competitive advantage will belong to brands that successfully combine clean-label formulations, functional health benefits, and transparent sourcing practices. As consumers increasingly view treats as an extension of their dogs’ daily nutrition rather than occasional rewards, companies capable of building trust, supporting pet health outcomes, and maintaining premium positioning will be best placed to capture long-term market growth and customer loyalty.
Product Insights
Based on product, the eatables segment led the market with the largest revenue share of 66.3% in 2025. Rising awareness about pet food and treats that provide functional benefits, such as supporting joint, coat and skin health, is fueling the demand for edible pet snacks and treats. Major industry players are actively launching a diverse range of products to meet this growing consumer demand. Many pet edibles now include natural ingredients like hemp and CBD, which have demonstrated promising benefits in managing various health conditions in animals, including cancer, anxiety, sleep disorders, and epilepsy. The increasing prevalence of anxiety disorders among pets, particularly dogs, is a significant driver for the expansion of this market segment.
Chewable segment is expected to grow at a CAGR of 14.0% from 2026 to 2033. Chewable treats often come with added health benefits such as dental hygiene, joint support, and digestion aid. These functional benefits are highly appealing to pet owners who are increasingly concerned about their pets' overall well-being. Chewable treats are designed to be highly palatable, making them an easy and enjoyable way for dogs to consume beneficial ingredients. The taste and texture of these treats make them a favorite among dogs, ensuring consistent demand.
Manufacturers are capitalizing on this opportunity by introducing CBD-infused chewable treats for dogs. These innovative products cater to the growing demand for natural remedies to address various health issues in pets. In March 2024, CV Sciences, Inc., a wellness company that focuses on consumer products derived from hemp extracts and other scientifically validated ingredients, launched its new CBD chew line for pets. The +PlusCBD Pet collection includes specially formulated chew treats aimed at promoting the health and well-being of dogs, harnessing the benefits of cannabidiol (CBD) to help address prevalent health concerns within the canine community.
Distribution Channel Insights
Based on distribution channel, the specialty pet stores segment led the market with the largest revenue share of 42.1% in 2025. Growing initiatives by specialty pet stores, such as partnerships with prominent manufacturers of pet snacks and treats, are likely to boost segment growth and give players a competitive advantage. In September 2023, Pet Supermarket, a prominent specialty retailer of pet supplies with over 225 stores in the Southeast U.S., announced its new partnership with Fromm Family Foods. This collaboration highlighted Pet Supermarket's dedication to improving pet health and well-being by introducing Fromm Family Foods' dry and wet treats and complete-and-balanced foods to its stores and online platform.
 To learn more about this report, Download Free Sample Report
The sales of natural dog treats through online channels is expected to grow at a CAGR of 13.5% from 2026 to 2033. Online platforms offer round-the-clock accessibility, allowing consumers to purchase natural dog treats at any time from the comfort of their homes or on the go. E-commerce has significantly altered consumer shopping behavior, offering several advantages, such as doorstep delivery, attractive discounts, and the convenience of finding various items on a single platform. Moreover, the availability of a diverse array of pet snacks and treats and growing customer loyalty facilitated by 'Subscribe & Save' programs are anticipated to strengthen the online channel.
Regional Insights
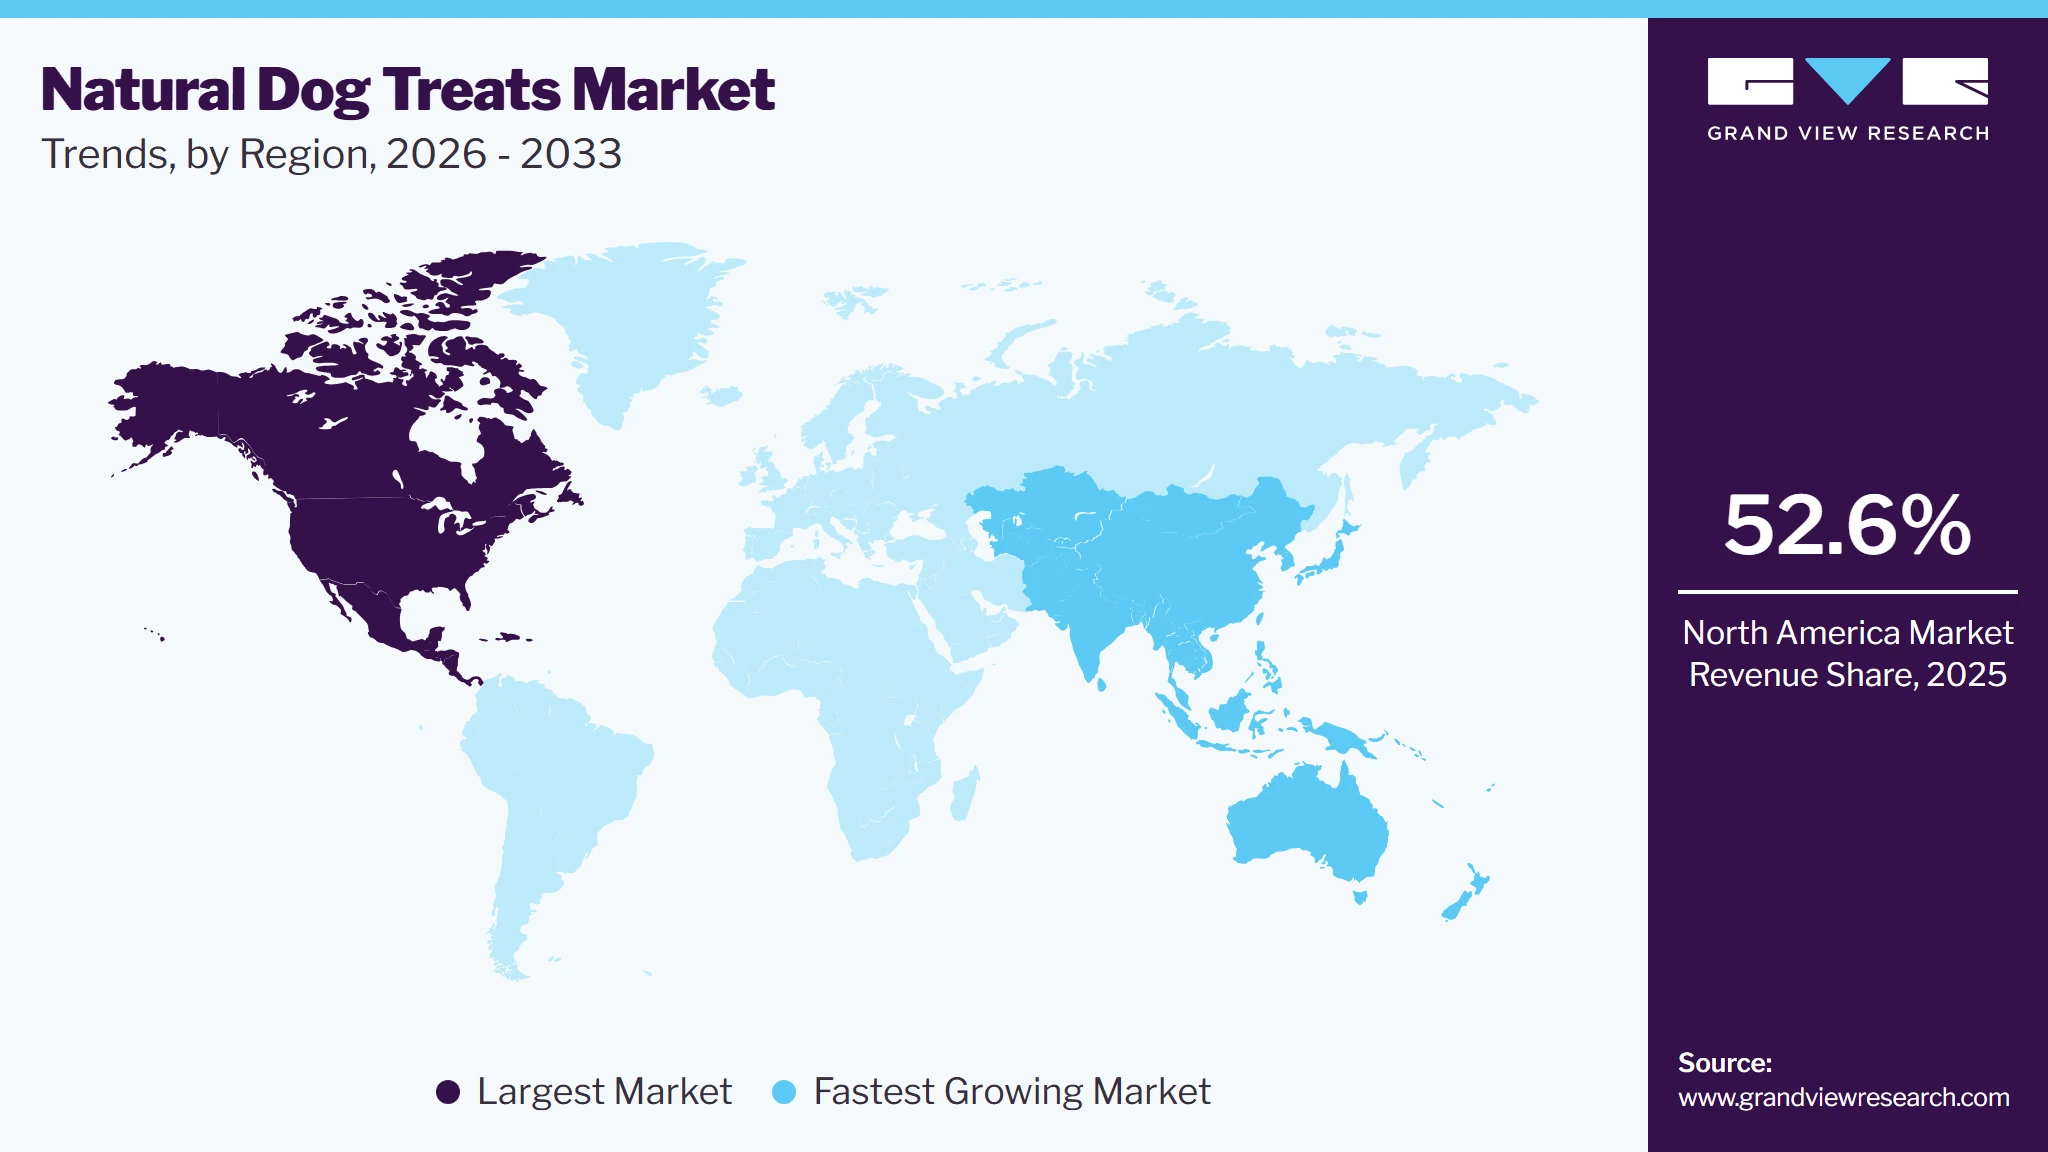
North America dominated the natural dog treats market with the largest revenue share of 52.6% in 2025. North America, particularly the U.S. and Canada, has one of the highest pet ownership rates in the world. This large pet population creates a substantial market for pet-related products, including natural dog treats. Consumers in North America prioritize products made with natural ingredients and seek out organic certifications. Banana ketchup brands that offer clean label formulations can attract health-conscious consumers. Major supermarkets, specialty food stores, and online retailers in North America increasingly stock international and ethnic food products, including natural dog treats. This accessibility makes it easier for consumers to discover and purchase the product.
 To learn more about this report, Download Free Sample Report
U.S. Natural Dog Treats Market Trends
The natural dog treats market in the U.S. held the largest share in the North America region in 2025. As U.S. households increasingly choose pets like dogs and cats over children, pet owners' commitment to their furry companions' well-being and nutrition is steadily rising. The preference for clean-label, natural, and non-GMO products has become a mainstream expectation across all segments, especially for products featuring human-grade and fresh/frozen ingredients.
Europe Natural Dog Treats Market Trends
The natural dog treat market in Europe is expected to grow at a CAGR of 11.8% from 2026 to 2033. Europe has seen a notable rise in pet ownership, with more households adopting pets such as dogs and cats. This growing pet population naturally leads to increased demand for pet-related products, including snacks and treats. Urbanization and changing lifestyles in Europe have led to more people living in apartments and smaller homes. Pets, particularly dogs and cats, are becoming more popular as companions in these settings, contributing to higher spending on pet products.
Asia Pacific Natural Dog Treats Market Trends
Asia Pacific natural dog treat market is expected to witness a fastest CAGR from 2026 to 2033. The rise in pet ownership has led to significant growth in the market in the Asia Pacific region. This growth is driven by evolving consumer lifestyles and an increasing focus on pet health and wellness. As dog ownership becomes more widespread across Asia Pacific countries, pet owners are increasingly seeking specialized and premium snacks and treats for their beloved companions.
Key Natural Dog Treats Company Insights
The market is characterized by dynamic competitive dynamics shaped by a combination of factors including product innovation, regional production capabilities, and evolving consumer preferences. Leading manufacturers invest in R&D and technological advancements to provide cost-effective and quality products.
Market players are entering into joint ventures, partnerships, mergers, agreements, and acquisitions to strengthen their market position and expand their geographical reach. Key manufacturers in the market utilize their expansive distribution networks and robust brand recognition to sustain a substantial market presence. They prioritize quality, innovation, and regional preferences, thereby reinforcing their leadership in international markets that embrace dog treats.
Key Natural Dog Treats Companies:
The following key companies have been profiled for this study on the natural dog treats market.
-
Mars, Incorporated
-
Nestlé S.A.
-
The J.M. Smucker Company
-
General Mills Inc.
-
Colgate Palmolive Company
-
Off-Leash Pet Treats
-
Wellness Pet, LLC
-
Merrick Pet Care
-
Spectrum Brands, Inc.
-
The Dog Chew Company
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Nestlé Purina PetCare, Mars Petcare, Hill's Pet Nutrition, Blue Buffalo)
- Expand premium and natural treat portfolios through product innovation and acquisitions. Strengthen distribution through supermarkets, pet specialty stores, veterinary channels, and e-commerce platforms.
- Invest in clean-label formulations, functional ingredients, and sustainable sourcing initiatives.
- Strong brand recognition, extensive distribution networks, and large-scale manufacturing capabilities.
- Significant R&D resources and established consumer trust in pet nutrition and safety.
- Higher operating costs and slower product development cycles. Less flexibility in addressing emerging niche trends and rapidly changing consumer preferences.
Emerging Players (e.g., Bocce's Bakery, The Honest Kitchen, Open Farm, Shameless Pets)
- Focus on niche segments such as organic, grain-free, single-ingredient, freeze-dried, and functional treats. Leverage direct-to-consumer channels, social media marketing, and sustainability-focused branding.
- Faster innovation cycles and ability to capitalize on emerging pet wellness trends.
- Strong differentiation through transparency, premium ingredients, and targeted product positioning.
- Limited financial resources and distribution reach. Challenges in scaling production, building brand awareness, and competing with established players on pricing and shelf space.
Recent Developments
-
In May 2024, Dr. Clauder’s partnered with protein innovator Calysta to introduce the world’s first dog treats made with FeedKind Pet protein, a groundbreaking pet food ingredient. Unveiled at the premier global pet trade fair, Interzoo, this pioneering air-dried treat from Dr. Clauder’s utilizes Calysta’s nutritionally dense protein, which is produced through natural fermentation. This non-GMO ingredient addresses market demands for high nutritional quality, excellent palatability, and health benefits for pets.
-
In March 2024, W.F. Young, the esteemed parent company behind beloved pet care brands such as Absorbine and The Missing Link, unveiled an exciting new addition to its product lineup: Honest to Goodness Plant Snacks. Designed for the health-minded canine community, these innovative plant-based treats promise to deliver the natural benefits of wholesome ingredients while catering to specific health needs.
Natural Dog Treats Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.8 billion
Estimated market size in 2026
USD 8.8 billion
Projected market size by 2033
USD 18.6 billion
Growth rate
CAGR of 12.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Central & South America;
America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Australia & New Zealand; Brazil; South Africa
Key companies profiled
Mars, Incorporated; Nestlé S.A.; The J.M. Smucker Company; General Mills Inc.; Wellness Pet, LLC; Merrick Pet Care; Redbarn Pet Products; Cloud Star; Charlee Bear Products; The Honest Kitchen.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Natural Dog Treats Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global natural dog treats market report based on product, distribution channel, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Eatables
-
Chewable
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Supermarkets & Hypermarkets
-
Specialty Pet Stores
-
Online
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
France
-
Germany
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia & New Zealand
-
South Korea
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
-
Research Methodology
The natural dog treats market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each natural dog treats segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Eatables
This segment includes the sales of ready-to-consume natural dog treats such as biscuits, jerky treats, meat snacks, training treats, and soft chews made from natural ingredients. These products are primarily used for rewards, training, and supplemental nutrition.
Chewables
This segment includes the sales of natural dog chews designed for prolonged chewing activity, including rawhide alternatives, bully sticks, dental chews, and other long-lasting treats. These products support dental health, chewing instincts, and behavioral enrichment.
Segment - Distribution Channel
Revenue capture definition
Supermarkets & Hypermarkets
This segment includes the sales of natural dog treats through large retail chains that offer a wide range of pet care products. These outlets provide consumers with convenient access to both mainstream and premium natural treat brands.
Specialty Pet Stores
This segment includes the sales of natural dog treats through dedicated pet retail stores that focus on pet nutrition, wellness, and specialty products. These stores typically offer a broader selection of premium, organic, and functional treats.
Online
This segment includes the sales of natural dog treats through e-commerce platforms, brand-owned websites, and online pet supply retailers. The channel offers product variety, subscription options, home delivery, and access to niche brands.
Others
This segment includes the sales of natural dog treats through veterinary clinics, farm and feed stores, convenience stores, independent retailers, and other alternative distribution channels. These outlets cater to specific consumer needs and regional purchasing preferences.
Estimation Model
Layer Name
Key Question
Description
Pet Population Layer
Who owns dogs that consume treat products?
Identify the global and regional dog population, household pet ownership rates, and demographic distribution of dog-owning households to establish the total addressable consumer base.
Health-Conscious Consumer Layer
Who prefers natural treats?
Apply penetration rates for premium pet food and natural pet products, considering income levels, pet humanisation trends, and consumer willingness to spend on healthier pet nutrition.
Consumption Layer
Who purchases regularly?
Estimate the share of dog owners actively purchasing treats and apply purchase frequency, product usage rates, and category-specific adoption levels for natural and functional treats.
Monetisation Layer
How much revenue is generated?
Multiply active purchasers by annual spending on natural dog treats, incorporating premium pricing, repeat purchases, subscriptions, and retail/e-commerce channels to estimate market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Natural & Organic Dog Treat Consumption Trends
Conducted a focused analysis of natural dog treat categories including organic treats, grain-free formulations, single-ingredient products, freeze-dried snacks, functional treats, and clean-label ingredient trends across major pet markets.
Helps stakeholders identify high-growth product segments, evolving pet owner preferences, and premiumization opportunities within the natural pet nutrition industry.
Pet Humanization & Premium Pet Food Adoption Trends
Evaluated consumer purchasing behavior, pet humanization trends, demand for healthier pet snacks, premium treat spending patterns, and the influence of e-commerce and specialty pet retail channels.
Provides insights into emerging consumption trends, purchasing drivers, and commercially attractive product categories to support product development and market expansion strategies.
Functional Nutrition & Sustainable Ingredient Opportunity Assessment
Assessed demand for functional dog treats supporting dental health, digestion, immunity, joint health, and weight management, alongside sustainable sourcing, natural ingredient innovation, and regulatory considerations.
Supports investment and expansion strategies by identifying underserved niches, evaluating innovation opportunities, and strengthening long-term growth potential in the natural pet treats market.
Frequently Asked Questions About This Report
North America dominated with a 52.6% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Specialty pet stores segment held the largest market share of 42.1% in 2025.
The global natural dog treats market size was valued at USD 7.8 billion in 2025 and is expected to reach USD 8.8 billion in 2026.
The global natural dog treats market is expected to grow at a compounded growth rate of 12.3% from 2026 to 2033 to reach USD 18.6 billion by 2033.
Eatables segment dominated the market, with a revenue share of 66.3% in 2025.
Key players include Mars, Incorporated; Nestlé S.A.; The J.M. Smucker Company; General Mills Inc.; Wellness Pet, LLC; Merrick Pet Care; Redbarn Pet Products; Cloud Star; Charlee Bear Products and The Honest Kitchen.
Key drivers include rising pet humanization, increasing demand for clean-label and natural ingredients, and growing awareness of pet health and nutrition. Higher disposable incomes are driving spending on premium pet products and functional treats. The expansion of e-commerce and subscription-based pet treat services is further supporting market growth.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


