
- Home
- »
- Electronic Devices
- »
-
Non-destructive Testing Market Size & Share Report, 2033GVR Report cover

Non-destructive Testing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Offering (Services, Equipment), By Test Methods, By Vertical (Manufacturing, Construction, Automotive, Power Generation), By Region, And Segment Forecasts
Market Size, 2025
$22.7BMarket Estimate, 2026
$24.4BMarket Forecast, 2033
$46.0BCAGR, 2026–2033
9.5%Non-destructive Testing Market Summary
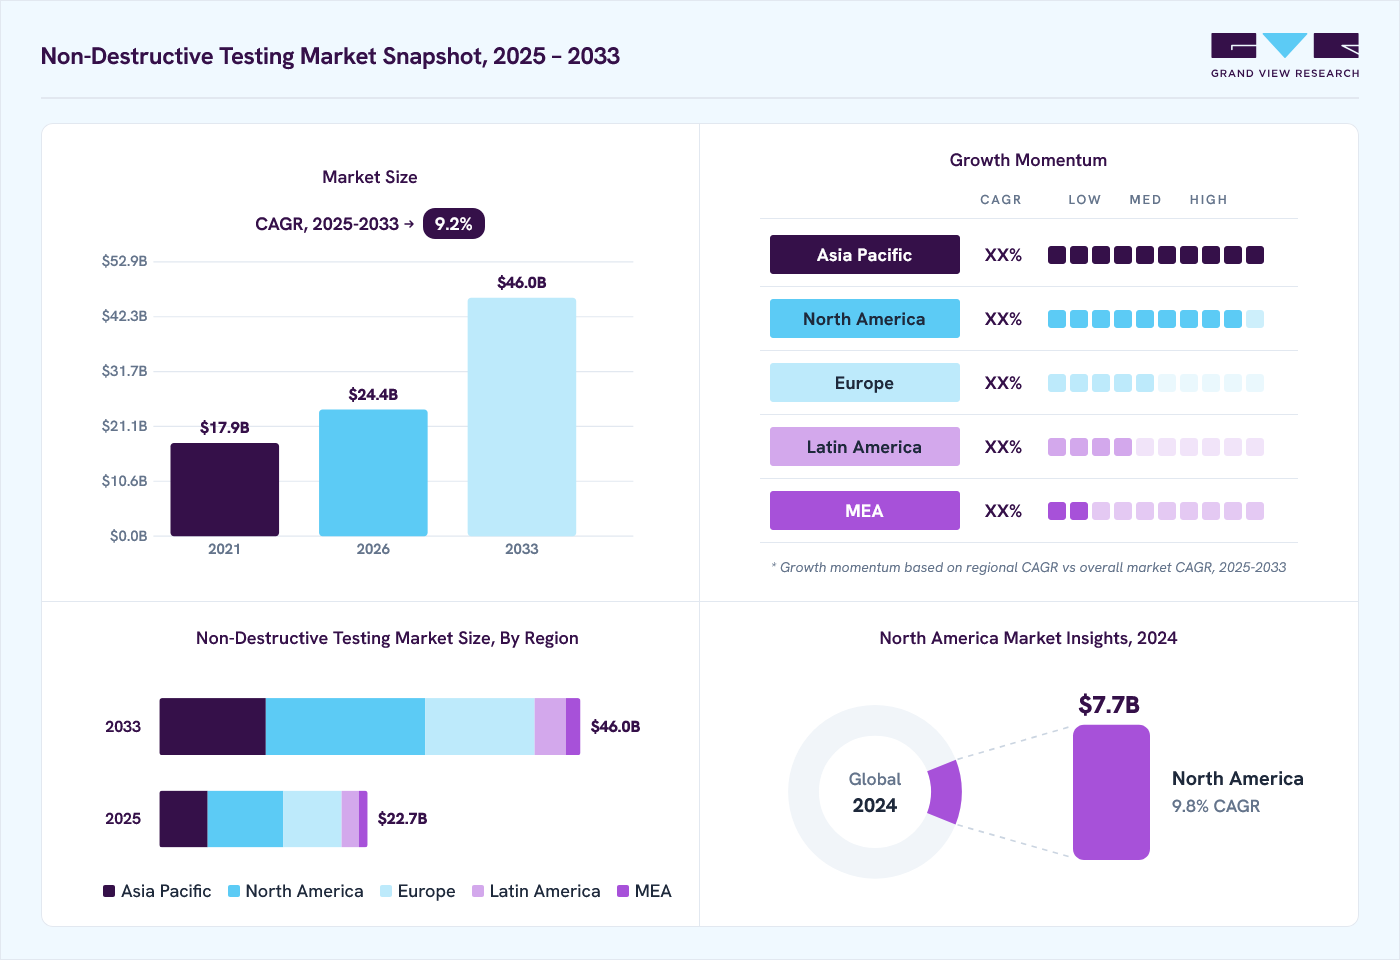
The global non-destructive testing market size was valued at USD 22.7 billion in 2025 and is projected to grow from USD 24.4 billion in 2026 to USD 46.0 billion by 2033, at a CAGR of 9.5% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 38.5% in 2025. The growing manufacturing activities across the developing and the developed nations are estimated to drive the market over the forecast period.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By offering: Services segment dominated the market, with a revenue share of 77.0% in 2025
- By test methods: Traditional NDT Method segment held the largest market share of 79.7% in 2025
- By vertical: Manufacturing accounted for the largest revenue share in 2025
Regional Highlights
- Largest regional market: North America (38.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 22.7 Billion
- Estimated market size in 2026: USD 24.4 Billion
- Projected market size by 2033: USD 46.0 Billion
- CAGR (2026-2033): 9.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The increasing technological innovations have enabled the development of advanced non-destructive testing processes with improved & precise safety & fault detection. Furthermore, increasing awareness amongst the manufacturers regarding the use of Non-destructive Testing (NDT) is expected to improve the penetration of NDT techniques in the coming years.The utilization of NDT techniques in projects allows for quicker completion due to the detection of faults in complex areas and irregular surfaces. This reduction in the possibility of failures is expected to drive the demand for non-destructive testing in the coming years. Additionally, the ease of operating and efficiency in fault detection provided by ultrasonic equipment, compared to other NDT equipment, is a significant factor contributing to the increasing adoption of the ultrasonic test method. Moreover, advancements in ultrasonic technology anticipated within the next eight years are likely to further boost the adoption of this testing procedure due to its simplicity.
 To learn more about this report, Download Free Sample Report
The market is projected to experience significant growth during the forecast period. This growth can be attributed to the increasing urbanization in developing countries like India and China, which involves extensive construction and manufacturing projects. The fast pace of such projects necessitates the implementation of testing processes to ensure the quality of work. This trend is expected to have a positive impact on the growth of non-destructive testing (NDT) in these countries, consequently enhancing its global market penetration.
Increasing oil and gas projects in the Middle East and North America are expected to deploy NDT techniques in order to complete the projects in prescribed timelines and with finesse, thus fueling the demand for NDT equipment in the regions. Besides, the advancements in non-destructive testing technology have led to the development of radiographic testing equipment such as industrial CT scanners, which precisely detect faults in machinery and components. However, the cost of the NDT equipment and the expertise required to perform the tests increases the complexity and difficulty of deploying the radiographic testing method.
The global COVID-19 pandemic has had detrimental and unexpected consequences for various industries worldwide, such as automotive, construction, airlines, and manufacturing, among others. To mitigate the spread of the novel coronavirus and its negative impacts, governments around the world implemented lockdowns as a precautionary measure. This led to disruptions in the global supply chain and a decline in industrial productivity, placing a strain on the global economy. Furthermore, the sudden outbreak of the virus also caused disruptions in companies' production and manufacturing capabilities.
Moreover, the influence of the pandemic on the non-destructive testing (NDT) market arises from the combined response of interconnected industries that utilize NDT for their operations. One such example is the defense industry, which has experienced a relatively mild impact compared to other sectors. This can be attributed to government budget allocations that safeguard the supply and demand ecosystem. While certain defense companies have been significantly affected by the financial shock, the impact is comparatively less than that observed in the aerospace sector.
Market Dynamics
The non-destructive testing (NDT) market is experiencing steady growth, driven by increasing industrial safety regulations, aging infrastructure inspection requirements, digital transformation across asset-intensive industries, and the growing adoption of Industry 4.0 technologies. The integration of artificial intelligence (AI), robotics, digital imaging, cloud-based inspection management, and advanced ultrasonic technologies is improving inspection accuracy, reducing downtime, and enabling predictive maintenance. Demand continues to expand across oil & gas, aerospace, automotive, manufacturing, construction, and power generation as organizations increasingly prioritize asset integrity, operational reliability, and regulatory compliance.
Industrial facilities such as refineries, power plants, aircraft, pipelines, bridges, and manufacturing equipment are operating under increasingly stringent safety and regulatory requirements. Aging infrastructure, higher operational risks, and the need to prevent catastrophic failures have significantly increased the importance of periodic inspection without interrupting operations. Regulatory agencies and industry standards require organizations to verify structural integrity while minimizing production losses, making reliable inspection technologies an operational necessity.
Non-destructive Testing solutions enable operators to detect corrosion, fatigue cracks, weld defects, material degradation, and structural discontinuities before failures occur. Modern ultrasonic, radiographic, eddy current, and digital inspection technologies support preventive maintenance strategies, extend equipment lifespan, improve worker safety, and reduce unplanned downtime. As industries continue investing in asset reliability programs and predictive maintenance initiatives, NDT adoption continues to accelerate across both mature and developing industrial markets.
Advanced NDT systems such as phased array ultrasonic testing, digital radiography, automated ultrasonic inspection, and robotic inspection platforms require significant upfront investment in equipment, software, calibration tools, and operator certification. In addition, international inspection standards require highly trained personnel capable of accurately interpreting inspection results, thereby increasing operational costs for service providers and end users.
These challenges particularly affect small and medium-sized manufacturers, regional inspection firms, and developing economies, where capital budgets and the availability of skilled labor remain limited. Organizations often postpone technology upgrades or continue using conventional inspection techniques due to financial constraints. Consequently, the adoption of advanced digital NDT solutions progresses more slowly in cost-sensitive industries, delaying the modernization of inspection workflows and limiting overall market expansion.
The rapid digitalization of industrial maintenance is creating substantial opportunities for advanced non-destructive testing solutions. Industry 4.0 initiatives, the Industrial Internet of Things (IIoT), artificial intelligence, machine learning, cloud computing, digital twins, and robotic inspection systems are enabling organizations to automate inspections, improve the accuracy of defect detection, and support real-time asset health monitoring. Increasing investments in smart manufacturing and predictive maintenance further strengthen demand for intelligent inspection technologies.
Equipment manufacturers and software vendors offering digital radiography, automated ultrasonic testing, AI-assisted defect recognition, cloud-based inspection reporting, and remote monitoring platforms are well positioned to capitalize on this opportunity. The aerospace, energy, automotive, and large-scale manufacturing sectors are expected to remain primary adopters due to their high inspection frequency, strict quality standards, and continuous investment in digital asset management, thereby supporting long-term market growth.
Analyst Perspective
The non-destructive testing market continues to benefit from growing industrial safety requirements, aging infrastructure modernization, and increasing investment in predictive maintenance strategies. Digital radiography, AI-assisted defect recognition, robotics, cloud-connected inspection platforms, and advanced ultrasonic technologies are transforming inspection efficiency and data quality across industrial sectors. Vendors are increasingly expanding integrated hardware, software, and service portfolios to support intelligent asset management solutions. Moreover, continued investments in digital industrial infrastructure, smart manufacturing, and automated inspection technologies are expected to strengthen market competitiveness and create sustained long-term growth opportunities.
Offering Insights
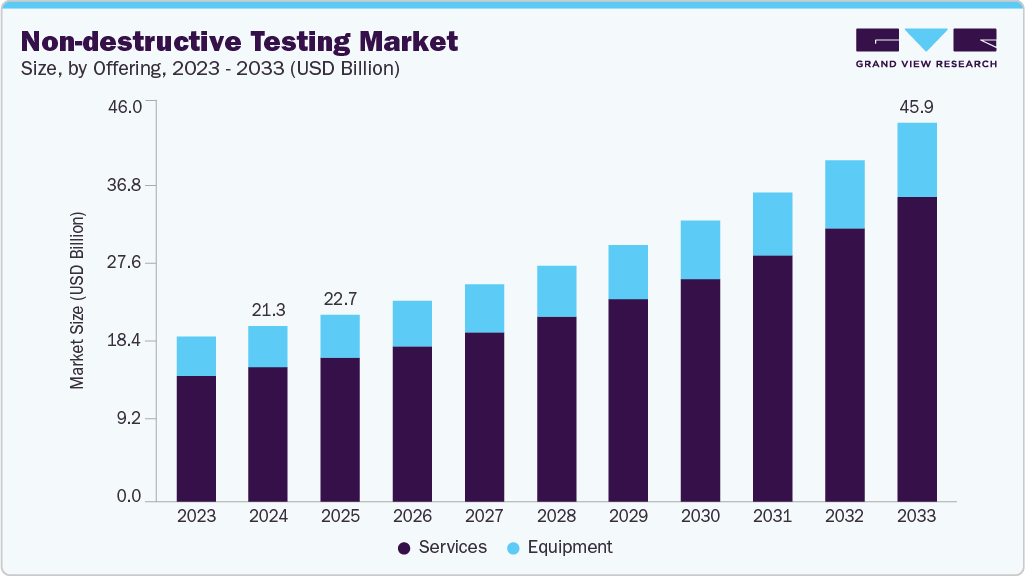
Based on offering, the services segment led the market with the largest revenue share of 77.0% in 2025 and is expected to remain dominant over the forecast period. The primary factor that drives end-users to outsource their NDT operations is the significant upfront cost associated with non-destructive equipment, combined with the technical complexities involved in their deployment and installation. Additionally, the shortage of a skilled workforce proficient in non-destructive testing acts as another constraint, limiting the widespread adoption of NDT equipment worldwide. Furthermore, stringent government regulations pertaining to workplace safety further encourage end-users to outsource their NDT operations to third-party service providers.
The equipment segment is expected to experience steady growth throughout the forecast period. This growth can be attributed to technological advancements, which have resulted in the availability of state-of-the-art equipment variants. The availability of these advanced variants has broadened the range of applications for non-destructive testing (NDT) equipment, thereby generating additional demand. Moreover, the resurgence of the industrial sector, particularly in emerging economies such as India and China, is expected to stimulate the installation of new NDT equipment in the coming years.
Test Methods Insights
The non-destructive testing methods include traditional NDT methods and digital/advanced NDT methods. The traditional NDT method segment led the market with the largest revenue share of 79.7% in 2025. The notable market growth is attributed to the increasing utilization of traditional non-destructive testing methods, including visual testing, magnetic particle testing, liquid penetrant testing, eddy current testing, ultrasonic testing, and radiographic testing. Among these methods, ultrasonic testing stands out as it dominates the market due to its portability, ease of use, and ability to provide precise results compared to other traditional NDT techniques. Consequently, the adoption of ultrasonic testing is experiencing significant growth and is expected to continue improving in the forthcoming years.
The digital/advanced NDT method segment is projected to grow at the fastest CAGR over the forecast period. Within the digital/advanced NDT method segment, the phased array ultrasonic testing (PAUT) segment accounted for a significant share of 20.5% in 2024. This growth can be attributed to the increasing preference for PAUT over other digital NDT methods. The detailed visualization feature offered by the PAUT method enables the identification of defect size, depth, shape, and orientation. PAUT is considered an advanced version of ultrasonic testing as it employs multiple transducers and sets of ultrasonic testing (UT) probes comprised of numerous smaller elements.
Vertical Insights
Based on vertical, the manufacturing segment led the market with the largest revenue share of 23.2% in 2025 and is projected to grow at the fastest CAGR over the forecast period. The growth is attributed to the ever-increasing volume of manufacturing across the globe. The manufacturing vertical is expected to deploy numerous NDT processes, thereby leading to an increase in demand for non-destructive testing services globally. Moreover, non-destructive testing has been traditionally used extensively in oil and gas applications. Test methods such as ultrasonic and eddy current have been used to detect cracks in the pipes, both underground and elevated. However, with increasing awareness, non-destructive testing techniques are being deployed in several other applications such as aerospace, defense, and automotive.
 To learn more about this report, Download Free Sample Report
The oil & gas vertical is further sub-segmented into Upstream, Midstream, & Downstream. The downstream activities in the oil & gas industry include refining petroleum products to produce end products, such as gasoline and kerosene. Refineries and petrochemical plants work with large volumes of oil flowing through tubing, pressure vessels, storage tanks, and pipes. Hence, downstream oil & gas companies particularly need to ensure the safety of the environment, workers, and the facility by ensuring the integrity of equipment and spot welding.
The power generation segment comprises numerous industries such as power grids and hydroelectric power plants. The segment is expected to witness healthy growth over the forecast period with a CAGR of 9.8%. Continuous increase in the power demand in developing nations is the major reason for the considerable adoption rate of NDT techniques in power generation, as the use of NDT techniques guarantees faster production rates.
Regional Insights
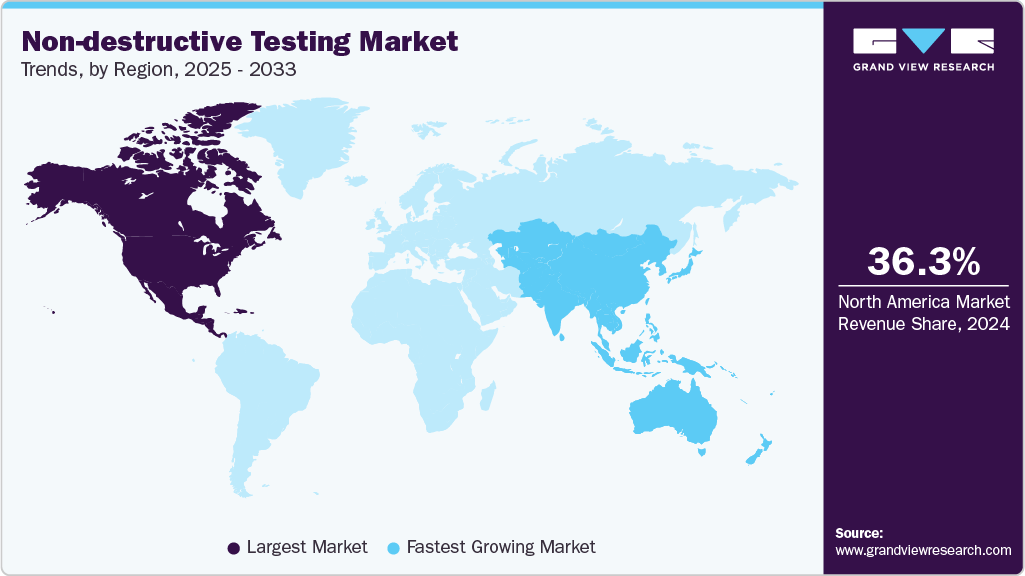
North America dominated the global non-destructive testing market with the largest revenue share of 38.5% in 2025. North America is quietly shifting from traditional, event-based inspections to a “digital forensics” model where every inspection is treated like a data asset. Large aerospace and energy operators are building centralized inspection intelligence hubs that combine phased-array UT scans, drone visuals, and decades of archived inspection files. This is creating a new kind of demand: companies don’t just want instruments; they want systems that help them interpret the flood of inspection data. As a result, software, AI-assisted crack characterization, and digital traceability are growing faster than hardware sales.
 To learn more about this report, Download Free Sample Report
U.S. Non-destructive Testing Market Trends
The non-destructive testing market in the U.S. held the largest share in the North America region in 2025. In the U.S., the single strongest trend is the merging of infrastructure renewal programs and strict regulatory oversight. With so many pipelines, bridges, and transmission assets past mid-life, operators are upgrading from manual checks to long-range ultrasonic, guided-wave, and permanent monitoring systems. Real-world contracts increasingly specify not just "inspect the asset" but “provide digital evidence that can stand up in an audit.” This is turning NDT service providers into compliance partners, and companies that can supply certified technicians plus digital documentation workflows are expanding rapidly.
Europe Non-destructive Testing Market Trends
Europe holds a substantial share of the non-destructive testing market. Europe is pushing NDT further into the realm of structural health monitoring (SHM) than any other region. Governments and private operators are embedding sensors directly into infrastructure, from bridges to aging industrial plants, and treating inspection as a continuous process rather than a scheduled event. Several European pilot projects involving rail lines and elevated structures are demonstrating that permanent sensors can reduce emergency maintenance dramatically. This shift is pulling NDT vendors toward longer-term contracts and more integrated engineering roles rather than just equipment supply.
The Germany non-destructive testing market is industrializing advanced NDT at the production-line level. Automotive and mechanical engineering plants are turning phased-array ultrasonic and automated eddy-current testing into routine, in-line stations, much like torque testing or dimensional checks. The motivation isn’t just defect detection; it’s production consistency. German manufacturers increasingly view advanced NDT as a productivity tool, not a cost. Vendors who can supply turnkey robotic cells, plug-and-play scanners, or Industry 4.0-ready systems are finding strong traction.
The UK non-destructive testing market is evolving into a leader in automated rail inspection. With rail availability targets tightening, rail operators are adopting train-mounted ultrasonic, vision, and thermal systems that inspect tracks at normal operating speeds. Instead of dispatching teams to walk tracks, software now flags anomalies from miles of continuous data. This has created a surprising trend: inspection is no longer about the sensor alone, but about algorithms that minimize false alarms. Vendors who excel in defect-triage analytics are emerging as preferred partners for rail and infrastructure clients.
Asia Pacific Non-destructive Testing Market Trends
The Asia Pacific region is growing at the fastest CAGR during the forecast period. APAC is the region where leapfrogging is most visible. Many large infrastructure and energy projects across Southeast Asia, Australia, and East Asia bypass older manual-only methods and adopt drone-based inspection, cloud reporting, and advanced UT systems from day one. Because many assets here are new, operators integrate digital inspection workflows early, without legacy resistance. The combination of new infrastructure and willingness to adopt automation makes APAC the fastest-growing region for advanced NDT platforms and long-term managed inspection services.
China's non-destructive testing market is experiencing the fastest commercial adoption curve in the global NDT market. Local manufacturers have become highly capable in developing digital ultrasonic systems, portable PAUT units, and magnetic particle equipment, putting competitive pressure on foreign brands. Large shipyards, rail manufacturers, and petrochemical plants are rapidly standardizing automated UT and radiography. With strong government emphasis on industrial quality and export standards, the demand for high-throughput, automated inspection lines is expanding at a pace unmatched elsewhere.
Japan's non-destructive testing market continues to lead in compact, robotics-driven inspection technologies. Japanese industries, especially shipbuilding, nuclear, and precision manufacturing, are pushing for robots that can navigate extremely confined or hazardous environments. This has driven the development of miniature ultrasonic crawlers, micro-robots for boiler tube inspection, and AI-assisted defect recognition tools. The cultural emphasis on precision and repeatability means that Japan is shifting from “find the defect” to “quantify the defect with extreme accuracy,” which is influencing global expectations for high-resolution imaging.
India's non-destructive testing market is being reshaped by rapid infrastructure growth and massive outsourcing. Pipeline networks, refineries, metro rail projects, and power plants are generating steady inspection work, but the supply of certified technicians hasn’t kept pace. As a result, operators rely heavily on third-party inspection companies, many of which are introducing LRUT, PAUT, and drone inspections to meet demand. One emerging trend is the strong preference for rugged, affordable instruments paired with remote mentoring or digital training modules, a model that fits India’s scale and diverse project conditions.
Key Non-destructive Testing Company Insights
Some of the major players in the Non-destructive Testing (NDT) market include Previan Technologies, Inc., Bureau Veritas, Fischer Technology Inc. (Helmut Fischer), MISTRAS Group, Comet Group (YXLON International), MME Group, TWI Ltd., Nikon Corporation, Olympus Corporation, Sonatest, Acuren, Intertek Group plc, Creaform, Vidisco Ltd., SGS S.A., and General Electric, among others, owing to their extensive inspection capabilities, advanced technology portfolios, and strong presence across safety-critical industries such as aerospace, energy, automotive, heavy manufacturing, and infrastructure. These companies consistently invest in next-generation NDT technologies, including phased-array ultrasonics, digital radiography, industrial CT, eddy current arrays, 3D metrology, AI-driven defect analytics, and robotics-assisted inspection, which enable high-precision evaluation of complex materials and components. Their ability to support a wide range of applications, such as weld integrity assessment, composite inspection, pipeline monitoring, structural health evaluation, and electronics testing, makes them central to the global NDT value chain. Furthermore, leading service providers like Bureau Veritas, Intertek, SGS, MISTRAS Group, and Acuren continue to strengthen their relevance through certified global technician networks, asset integrity management expertise, and compliance-focused inspection programs, while technology innovators like Creaform, Vidisco, Nikon, Olympus, and Helmut Fischer drive advancements in portable imaging, digital workflows, and high-resolution measurement systems. Combined with their strategic global footprints, continuous R&D investments, and deep partnerships with industrial OEMs and regulatory bodies, these firms remain highly competitive and indispensable in a market increasingly shaped by automation, predictive maintenance, and digital reporting standards.
-
General Electric has a diverse set of business units, including GE Power, GE Healthcare, GE Aviation, GE Digital, GE Transportation, GE Renewable Energy, GE Addictive, GE Lighting, GE Capital, GE Global Research, and Baker Hughes, a GE Company (BHGE). BHGE was formed by merging GE Oil & Gas with Baker Hughes Company in July 2017. In 2020, Baker Hughes rebranded its Inspection Technologies business as Waygate Technologies, following the integration of GE’s inspection technologies business into Baker Hughes.
-
MISTRAS Group is a provider of asset protection solutions for evaluating the structural reliability and integrity of critical industrial, public, and energy infrastructure. The company specializes in integrating products and technologies to deliver customized solutions ranging from complex to routine inspections. It offers destructive testing, non-destructive testing, predictive maintenance, and mechanical integrity services.
Key Non-destructive Testing Companies:
The following key companies have been profiled for this study on the non-destructive testing market.
-
Previan Technologies, Inc.
-
Bureau Veritas
-
Fischer Technology Inc. (Helmut Fischer)
-
MISTRAS Group
-
Comet Group (YXLON International)
-
MME Group
-
TWI Ltd.
-
Nikon Corporation
-
Olympus Corporation
-
Sonatest
-
Acuren
-
Intertek Group plc
-
CREAFORM
-
Vidisco Ltd.
-
SGS S.A.
-
General Electric
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Established Players (Bureau Veritas, MISTRAS Group, Nikon Corporation, Olympus Corporation, Comet Group (YXLON International), Acuren)
- These players are focused on global service networks, continuous product innovation, acquisitions, digital inspection technologies, integrated equipment and inspection services, and long-term industrial contracts.
- These players have extensive global presence, diversified inspection portfolios, advanced digital technologies, certified inspection workforce, strong brand recognition, and established customer relationships across multiple industries.
- High operating costs and complex organizational structures can slow decision-making and increase overall expenses. Their reliance on industrial capital expenditure also exposes revenue to fluctuations, as reduced investment in sectors such as oil & gas and manufacturing delays equipment purchases and large inspection projects.
Emerging Players (Fischer Technology Inc. (Helmut Fischer), MME Group, TWI Ltd., Sonatest)
- These players are focused on specialized NDT technologies, customized inspection solutions, research collaborations, product innovation, regional expansion, and niche application expertise.
- Strong technical specialization, flexible product development, expertise in specific inspection techniques, faster innovation cycles, and customized customer support.
- Limited global distribution and smaller service networks restrict expansion into international markets and reduce access to large customers. Lower brand recognition and financial resources also make it more difficult to invest in R&D, expand product portfolios, and compete for large, long-term industrial contracts with established multinational companies.
Recent Developments
-
In June 2025, Previan Technologies, Inc. announced a strategic realignment that will spin its two industrial technology businesses, Eddyfi Technologies and NDT Global, into independent, autonomous entities to sharpen focus on advanced NDT instrumentation and integrity-management services, the move is aimed at unlocking tailored growth for both the high-end inspection hardware (Eddyfi) and large-scale pipeline inspection and analytics (NDT Global)
-
In November 2024, Comet Yxlon (Comet Group) launched the CA20 3D X-ray/CT system tailored for high-throughput semiconductor and advanced-packaging inspection, a move that strengthens its industrial CT portfolio for precision NDT in electronics and aerospace component inspection.
Non-destructive Testing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 22.7 billion
Estimated market size in 2026
USD 24.4 billion
Projected market size by 2033
USD 46.0 billion
Growth rate
CAGR of 9.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Offering, test methods, vertical, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
Bureau Veritas; Fischer Technology Inc. (Helmut Fischer); MISTRAS Group; Comet Group (YXLON International); MME Group; TWI Ltd.; Nikon Corporation; Olympus Corporation; Sonatest; Acuren
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Non-destructive Testing Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global non-destructive testing market report based on offering, test methods, vertical, and region:
-
Offering Outlook (Revenue, USD Million, 2021 - 2033)
-
Services
-
Equipment
-
-
Test Methods Outlook (Revenue, USD Million, 2021 - 2033)
-
Traditional NDT Method
-
Visual Testing
-
Magnetic Particle Testing
-
Liquid Penetrant Testing
-
Eddy Current Testing
-
Ultrasonic Testing
-
Radiographic Testing
-
-
Digital/Advanced NDT Method
-
Digital Radiography (DR)
-
Phased Array Ultrasonic Testing (PAUT)
-
Pulsed Eddy Current (PEC)
-
Time-Of-Flight Diffraction (TOFD)
-
Alternating Current Field Measurement (ACFM)
-
Automated Ultrasonic Testing (AUT)
-
-
-
Vertical Outlook (Revenue, USD Million, 2021 - 2033)
-
Oil & Gas
-
Upstream
-
Midstream
-
Downstream
-
-
Manufacturing
-
Aerospace & Defense
-
Construction
-
Automotive
-
Power Generation
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The non-destructive testing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each non-destructive testing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment Offering
Revenue capture definition
Services
Revenue generated from contract inspection services, field testing, laboratory testing, equipment calibration, inspection consulting, integrity assessment, certification, technician training, maintenance services, recurring inspection contracts, and outsourced NDT operations.
Equipment
Revenue generated from sales of NDT instruments, digital imaging systems, ultrasonic equipment, radiographic systems, eddy current instruments, magnetic particle equipment, liquid penetrant systems, inspection robots, software-integrated inspection hardware, accessories, probes, detectors, and replacement components.
Segment Test Methods
Revenue capture definition
Traditional NDT Method
Revenue generated from inspection services, testing contracts, equipment sales, consumables, calibration services, maintenance, technician certification, and rental of conventional NDT instruments. The segment includes traditional NDT methodssuch as Visual Testing, Magnetic Particle Testing, Liquid Penetrant Testing, Eddy Current Testing, Ultrasonic Testing, and Radiographic Testing.
- Visual Testing (VT): Revenue generated from visual inspection services, borescopes, videoscopes, inspection cameras, drones, remote visual inspection (RVI) systems, lighting equipment, image documentation software, and technician services.
- Magnetic Particle Testing (MPT): Revenue generated from magnetic yokes, electromagnetic benches, magnetic particles, contrast paints, UV lamps, demagnetization equipment, inspection services, and consumable sales.
- Liquid Penetrant Testing (LPT): Revenue generated from penetrant chemicals, developers, cleaners, automated penetrant inspection systems, consumables, inspection services, and equipment maintenance.
- Eddy Current Testing (ECT): Revenue generated from eddy current flaw detectors, probes, conductivity meters, inspection software, calibration blocks, inspection services, and equipment servicing.
- Ultrasonic Testing (UT): Revenue generated from ultrasonic flaw detectors, thickness gauges, transducers, couplants, scanners, inspection software, calibration services, field inspection contracts, and technician training.
- Radiographic Testing (RT): Revenue generated from X-ray generators, gamma-ray systems, film-based radiography equipment, imaging plates, radiation safety accessories, inspection services, film processing, and maintenance contracts.
Digital/Advanced NDT Method
Revenue generated from advanced digital inspection systems, AI-enabled inspection software, automation platforms, cloud-based reporting solutions, robotic inspection systems, equipment integration, software licensing, and premium inspection services. The segment includes Digital/Advanced NDT Methodssuch as Digital Radiography (DR), Phased Array Ultrasonic Testing (PAUT), Pulsed Eddy Current (PEC), Time-of-Flight Diffraction (TOFD), Alternating Current Field Measurement (ACFM), and Automated Ultrasonic Testing (AUT).
- Digital Radiography (DR): Revenue generated from digital X-ray detectors, flat-panel detectors, digital imaging software, image analysis platforms, portable DR systems, system integration, and digital inspection services.
- Phased Array Ultrasonic Testing (PAUT): Revenue generated from phased array instruments, multi-element probes, encoded scanners, imaging software, automated inspection systems, advanced inspection services, and operator certification.
- Pulsed Eddy Current (PEC): Revenue generated from PEC instruments, corrosion monitoring systems, inspection software, pipeline integrity assessment services, equipment calibration, and long-term asset monitoring contracts.
- Time-of-Flight Diffraction (TOFD): Revenue generated from TOFD inspection systems, ultrasonic scanners, software licenses, weld inspection services, calibration equipment, and integrity assessment projects.
- Alternating Current Field Measurement (ACFM): Revenue generated from ACFM instruments, crack sizing software, offshore inspection services, subsea inspection equipment, equipment maintenance, and specialized inspection contracts.
- Automated Ultrasonic Testing (AUT): Revenue generated from automated scanning systems, robotic inspection platforms, pipeline inspection systems, software analytics, system integration, maintenance services, and large-scale automated inspection projects.
Segment Vertical
Revenue capture definition
Oil & Gas
Revenue generated from NDT inspection equipment, asset integrity management services, pipeline inspection, corrosion monitoring, weld inspection, pressure vessel testing, storage tank inspection, refinery maintenance, shutdown inspection projects, and long-term inspection contracts across the oil & gas value chain. The segment includes Oil & Gas, such as upstream, midstream, and downstream
- Upstream: Revenue generated from inspection of drilling rigs, offshore platforms, wellheads, subsea equipment, pipelines, production facilities, pressure vessels, drilling tools, and exploration assets through periodic inspection and maintenance services.
- Midstream: Revenue generated from inspection of transmission pipelines, compressor stations, LNG terminals, storage tanks, pumping stations, valves, and pipeline integrity assessment programs using advanced NDT technologies.
- Downstream: Revenue generated from inspection of refineries, petrochemical plants, process piping, boilers, heat exchangers, reactors, pressure vessels, storage tanks, and turnaround maintenance services.
Manufacturing
Revenue generated from quality control inspection of castings, forgings, welds, fabricated components, machinery, industrial equipment, production lines, and factory maintenance programs.
Aerospace and Defense
Revenue generated from inspection of aircraft structures, engines, turbine blades, landing gear, composite materials, military vehicles, missiles, naval platforms, defense equipment, and MRO (Maintenance, Repair & Overhaul) activities.
Construction
Revenue generated from the inspection of bridges, tunnels, buildings, steel structures, concrete infrastructure, weld joints, reinforcing bars, dams, and civil engineering projects during construction and maintenance phases.
Automotive
Revenue generated from the inspection of engines, transmissions, battery systems, EV components, chassis, castings, welds, lightweight materials, suspension systems, and automotive manufacturing quality assurance programs.
Power Generation
Revenue generated from the inspection of power plants, turbines, generators, boilers, nuclear reactors, wind turbines, hydroelectric equipment, transmission infrastructure, renewable energy assets, and scheduled maintenance services.
Others
Revenue generated from inspection services and equipment supplied to marine & shipbuilding, railways, mining, chemical processing, healthcare, telecommunications, public infrastructure, and other industrial sectors requiring asset integrity and safety inspections.
Estimation Model
Layer Name
Key Question
Description
Industry Opportunity Assessment
Which industries generate demand for NDT solutions?
This layer identifies the major end-use industries adopting NDT technologies, including oil & gas, aerospace, manufacturing, automotive, construction, and power generation. It evaluates inspection frequency, regulatory requirements, infrastructure investments, and asset replacement cycles. Industry expansion and maintenance spending establish the total addressable market for NDT solutions.
Technology Adoption Assessment
Which NDT technologies are being implemented?
This layer evaluates adoption across traditional and advanced inspection methods including ultrasonic testing, radiography, digital radiography, PAUT, TOFD, PEC, and automated inspection systems. It assesses technology migration, digital transformation initiatives, inspection accuracy improvements, and equipment modernization trends. Technology maturity influences market penetration across industries.
Revenue Mapping
Where is commercial revenue generated?
This layer allocates revenue across equipment sales, inspection services, software, calibration, maintenance, recurring service contracts, and industry-specific deployments. Revenue is analyzed by inspection frequency, equipment replacement, service outsourcing, and customer investment patterns. It reflects the commercial structure of the NDT ecosystem.
Regional & Competitive Validation
Which regions and vendors drive market expansion?
This layer validates market estimates by evaluating regional industrial output, infrastructure investments, regulatory environments, manufacturing activity, and competitive positioning of major vendors. Company product portfolios, strategic partnerships, acquisitions, and technology innovation are incorporated to refine market sizing and forecast assumptions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Non-destructive Testing Market Opportunity Assessment
Country/region-wise market sizing and forecasts
Analysis of demand, adoption trends, and regulatory landscape
Identification of high-growth regions and investment hotspots
Identified region-specific growth opportunities
Supported expansion and go-to-market strategy
Enabled informed regional investment decisions
Cross-Segmentation Analysis for the Non-destructive Testing Market
Criss-cross market analysis by offering, test methods, vertical
Demand and adoption assessment across key segments
Segment attractiveness and growth potential benchmarking
Identified high-potential market segments
Supported targeted Test Methods positioning and marketing strategy
Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the Non-destructive Testing Market
Benchmarking of key competitors across test methods, pricing, partnerships, and innovation
Comparative assessment of market share, capabilities, and strategies
Analysis of competitive strengths, gaps, and differentiation areas
Identified competitive white spaces and growth gaps
Supported strategic positioning and differentiation
Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
The global non-destructive testing market size was valued at USD 22.7 billion in 2025 and is estimated at USD 24.4 billion for 2026.
The global non-destructive testing market is expected to grow at a CAGR of 9.5% from 2026 to 2033, reaching USD 46.0 billion by 2033.
Services segment dominated the market, with a revenue share of 77.0% in 2025. The primary factor that drives end-users to outsource their NDT operations is the significant upfront cost associated with non-destructive equipment, combined with the technical complexities involved in their deployment and installation.
The traditional test method segment dominated the market, accounting for the largest revenue share of 79.9% in 2024.
North America dominated the global market with the largest revenue share of 38.5% in 2025. North America is quietly shifting from traditional, event-based inspections to a “digital forensics” model where every inspection is treated like a data asset.
Asia Pacific is the fastest-growing over the forecast period.
Some key players operating in the non-destructive testing market include Bureau Veritas; Fischer Technology Inc. (Helmut Fischer); MISTRAS Group; Comet Group (YXLON International); MME Group; TWI Ltd.; Nikon Corporation; Olympus Corporation; Sonatest; Acuren
The growing manufacturing activities across the developing and the developed nations are estimated to drive the market over the forecast period.
Manufacturing accounted for the largest revenue share of 23.2% in 2025 and is the fastest growing over the forecast period.
About the Author(s)
Electronic Devices Research Team
Semiconductors & Electronics · Electronic DevicesThis report was authored by the electronic devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the electronic devices segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


