
- Home
- »
- Medical Devices
- »
-
Eye Examination Equipment Market Size, Share 2033GVR Report cover

Eye Examination Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Ophthalmic Ultrasound Imaging Systems, OCT, Corneal Topography Systems), By End Use (Hospitals, Clinics), By Region, And Segment Forecasts
Market Size, 2025
$4.6BMarket Estimate, 2026
$4.9BMarket Forecast, 2033
$8.1BCAGR, 2026–2033
7.4%Eye Examination Equipment Market Summary
The eye examination equipment market size was valued at USD 4.6 billion in 2025 and is projected to grow from USD 4.9 billion in 2026 to USD 8.1 billion by 2033, at a CAGR of 7.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 29.3% in 2025. This growth is driven by the rising prevalence of eye diseases such as cataracts, glaucoma, and age-related macular degeneration, increasing the demand for diagnostic and treatment equipment.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Optical coherence tomography scanners segment led the market with the largest revenue share of 21.0% in 2025.
- By end use: Hospital segment led the market with the largest revenue share of 77.3% in 2025.
Regional Highlights
- Largest regional market: North America (29.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.6 Billion
- Estimated market size in 2026: USD 4.9 Billion
- Projected market size by 2033: USD 8.1 Billion
- CAGR (2026-2033): 7.4%
GVR research-powered AIAsk Prism AI about the eye examination equipment marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗
Technological advancements in ophthalmic devices, including optical coherence tomography (OCT) and advanced retinal imaging systems, make eye examinations more accurate and efficient. The aging population is also more susceptible to eye conditions, further driving the need for eye examination equipment. The growing awareness about eye health and regular eye check-ups is encouraging more people to seek professional eye care, boosting the demand for eye examination equipment.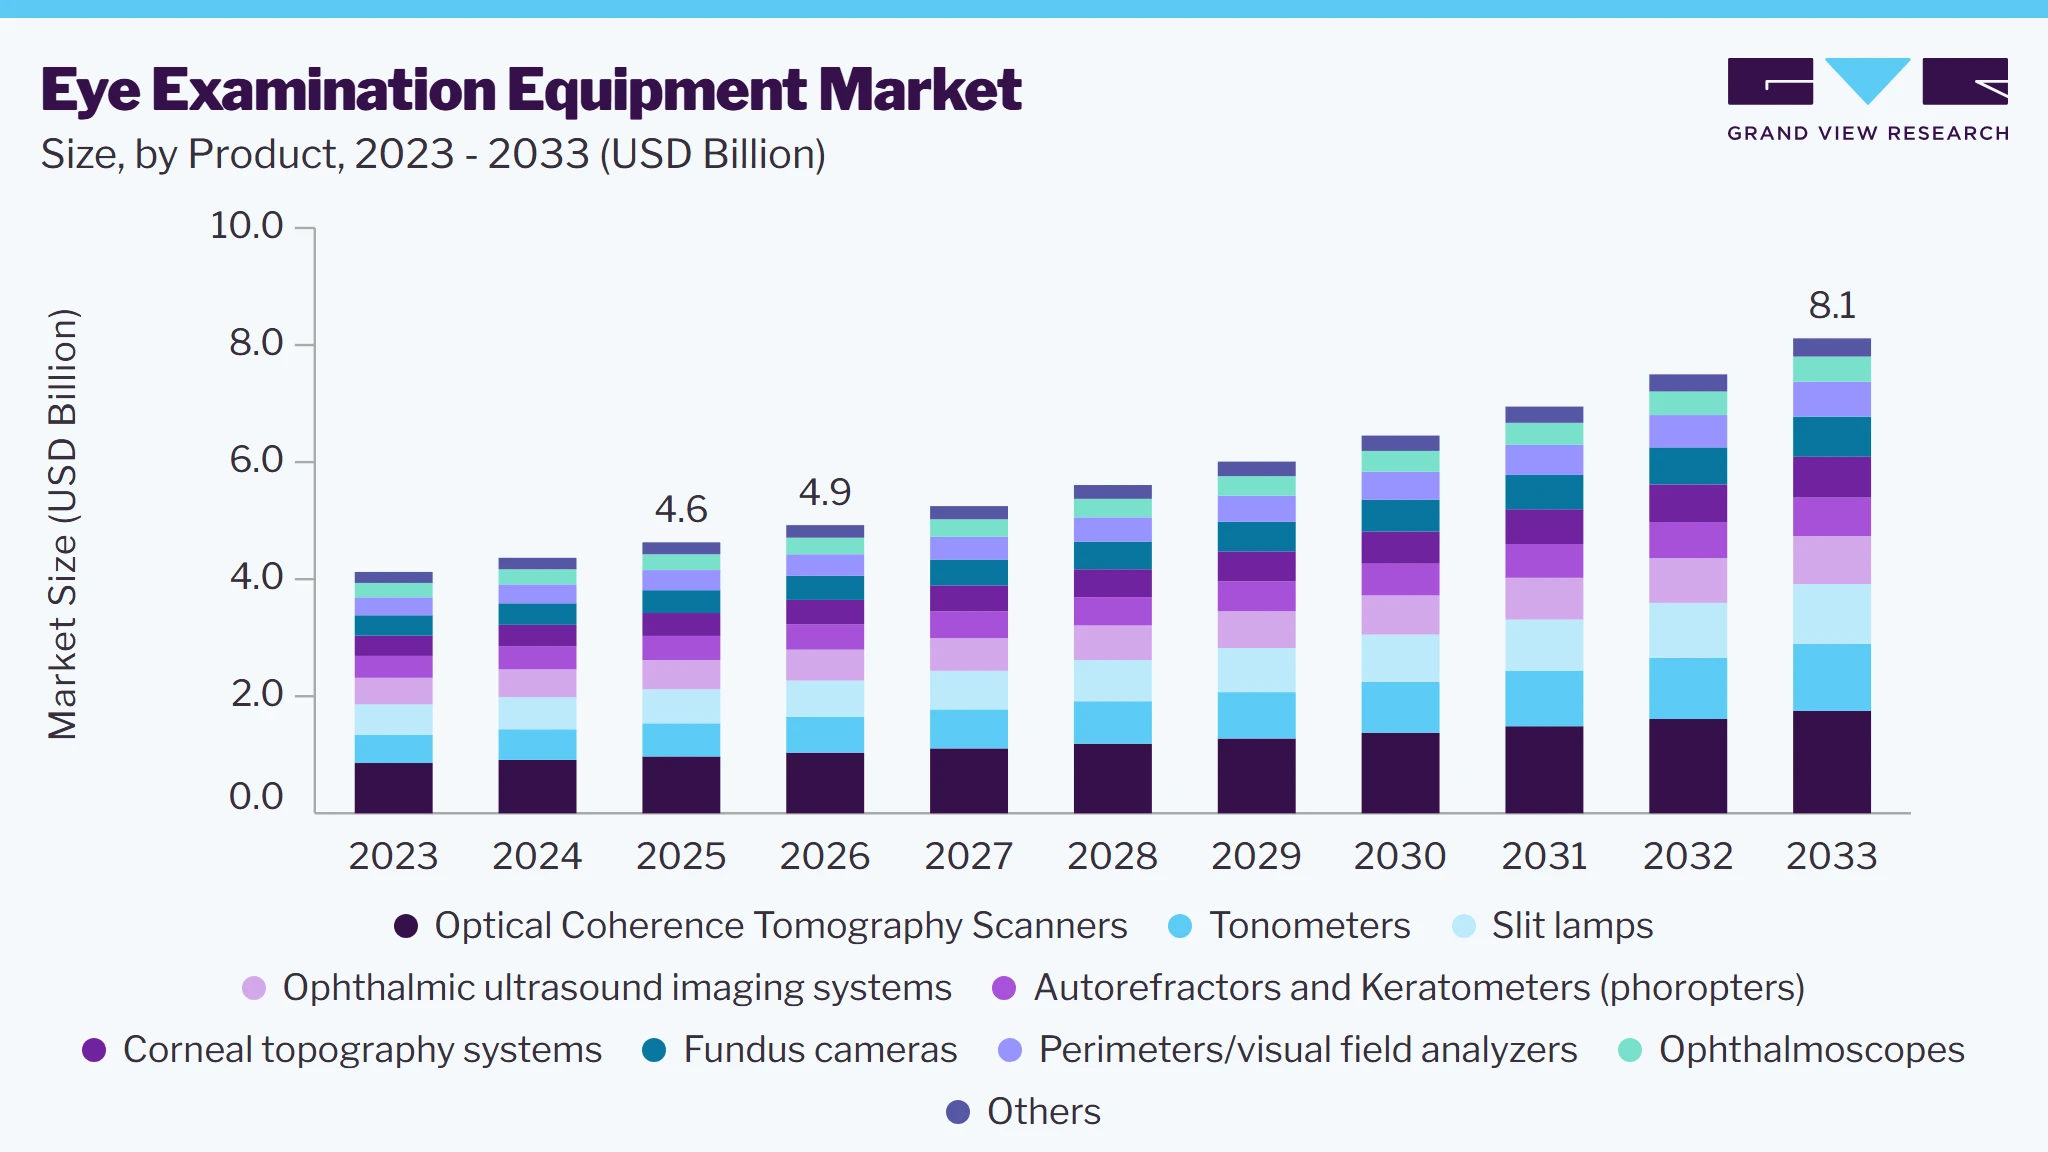 To learn more about this report, Download Free Sample Report
The rise in digital device usage has led to increased digital eye strain, prompting more frequent eye examinations and the need for specialized equipment. For example, the widespread use of smartphones and computers has resulted in a surge of patients seeking eye care to address symptoms like dry eyes and headaches. This trend is driving demand for advanced diagnostic tools and treatments.
Additionally, government initiatives and funding to improve access to eye care services are crucial in market growth. For instance, the World Health Organization (WHO) launched a guide to integrate eye care into health systems, supporting member states in planning and implementing eye care services. In India, the National Programme for Control of Blindness and Visual Impairment (NPCBVI) has been instrumental in reducing blindness through comprehensive care, including prevention, early detection, and treatment. These efforts are making eye care more accessible, especially in underserved areas, and addressing unmet healthcare needs.
Market Dynamics
The eye examination equipment market is experiencing steady growth, driven by the rising prevalence of ophthalmic disorders, increasing demand for early and accurate vision assessment, growing awareness regarding preventive eye care, and continuous technological advancements in ophthalmic diagnostic equipment. The market is further supported by the expanding geriatric population, increasing incidence of chronic diseases such as diabetes and hypertension that contribute to vision impairment, growing burden of refractive errors, cataracts, glaucoma, and age-related macular degeneration (AMD), as well as improved access to specialized eye care services across developed and emerging healthcare markets. Eye examination equipment enables hospitals, ophthalmology clinics, optometry practices, ambulatory surgical centers, vision care centers, and specialty eye hospitals to perform comprehensive ocular assessments, facilitate early disease detection, monitor disease progression, and support treatment planning through advanced diagnostic technologies. These devices play a critical role in improving diagnostic accuracy, enhancing clinical workflow efficiency, and enabling timely intervention to prevent avoidable vision loss.
The increasing prevalence of ophthalmic disorders and vision impairment is one of the primary drivers fueling the growth of the eye examination equipment market. The global burden of eye diseases, including cataracts, glaucoma, diabetic retinopathy, age-related macular degeneration (AMD), refractive errors, and dry eye disease, continues to rise due to population aging, increasing diabetes prevalence, lifestyle changes, and prolonged exposure to digital screens. For instance, in February 2026, the World Health Organization (WHO) reported that 2.2 billion people worldwide are living with near or distance vision impairment, with at least 1 billion cases being preventable or still unaddressed. The WHO emphasized that the growing burden of eye diseases highlights the importance of early diagnosis, routine eye examinations, and improved access to ophthalmic diagnostic services, which is expected to accelerate the adoption of advanced eye examination equipment globally. Healthcare providers are increasingly adopting sophisticated diagnostic technologies such as optical coherence tomography (OCT), fundus cameras, slit lamps, autorefractors, tonometers, and visual field analyzers to improve diagnostic precision and clinical decision-making. In addition, government-led vision screening programs, growing public awareness regarding routine eye examinations, and expanding access to ophthalmic care services are increasing the volume of diagnostic procedures performed globally.
The high cost of advanced eye examination equipment remains a significant restraint to the growth of the eye examination equipment market. Modern ophthalmic diagnostic systems, including optical coherence tomography (OCT) scanners, fundus imaging systems, corneal topographers, optical biometers, automated perimeters, and multimodal retinal imaging platforms, require substantial capital investment for procurement, installation, and integration into clinical workflows. In addition to the initial acquisition cost, healthcare providers incur recurring expenses related to software upgrades, annual maintenance contracts, calibration, consumables, cybersecurity, and staff training, further increasing the total cost of ownership. These financial barriers are particularly challenging for small ophthalmology practices, independent optometry clinics, rural healthcare facilities, and hospitals in low- and middle-income countries, where budget constraints often delay the adoption of advanced diagnostic technologies. As a result, many providers continue to rely on conventional or refurbished equipment, limiting access to high-precision diagnostic capabilities and slowing the replacement cycle for newer systems.
Analyst Perspective
The global eye examination equipment market is positioned at the intersection of several long-term healthcare and technological trends, including the rising prevalence of ophthalmic disorders, increasing demand for early vision screening and preventive eye care, growing awareness of eye health, and continuous advancements in ophthalmic diagnostic technologies. The increasing incidence of vision-related conditions such as cataracts, glaucoma, diabetic retinopathy, age-related macular degeneration (AMD), refractive errors, dry eye disease, retinal disorders, and other chronic ocular diseases is creating significant growth opportunities for manufacturers of ophthalmic diagnostic equipment, hospitals, ophthalmology clinics, ambulatory surgical centers, and optical care providers. The market is further supported by the rapidly growing geriatric population, increasing prevalence of diabetes, rising screen time associated with digital device usage, and expanding government initiatives focused on preventing avoidable blindness through routine eye screening programs.
Product Insights
Based on product, the optical coherence tomography scanners segment led the market with the largest revenue share of 21.0% in 2025. This dominance can be attributed to the widespread adoption of OCT scanners in ophthalmology for their non-invasive, high-resolution imaging capabilities. The increasing prevalence of these eye disorders, coupled with advancements in OCT technology such as the development of spatially encoded frequency domain OCT is also driving the demand. This advanced imaging technique offers improved scanning capabilities and reduced motion artifacts, making it a preferred choice in clinical settings.
On the other hand, the ophthalmic ultrasound imaging systems segment is projected to grow at a CAGR of 6.8% during the forecast period. This growth can be attributed to the versatility and essential role of ultrasound imaging in various ophthalmic applications, including A-scan and B-scan ultrasound techniques. The ability of ultrasound imaging to provide real-time data and its non-invasive nature makes it a crucial tool in both emergency and routine eye examinations. The portability of these devices makes them particularly valuable in remote and underserved areas where access to advanced eye care is limited.
End Use Insights
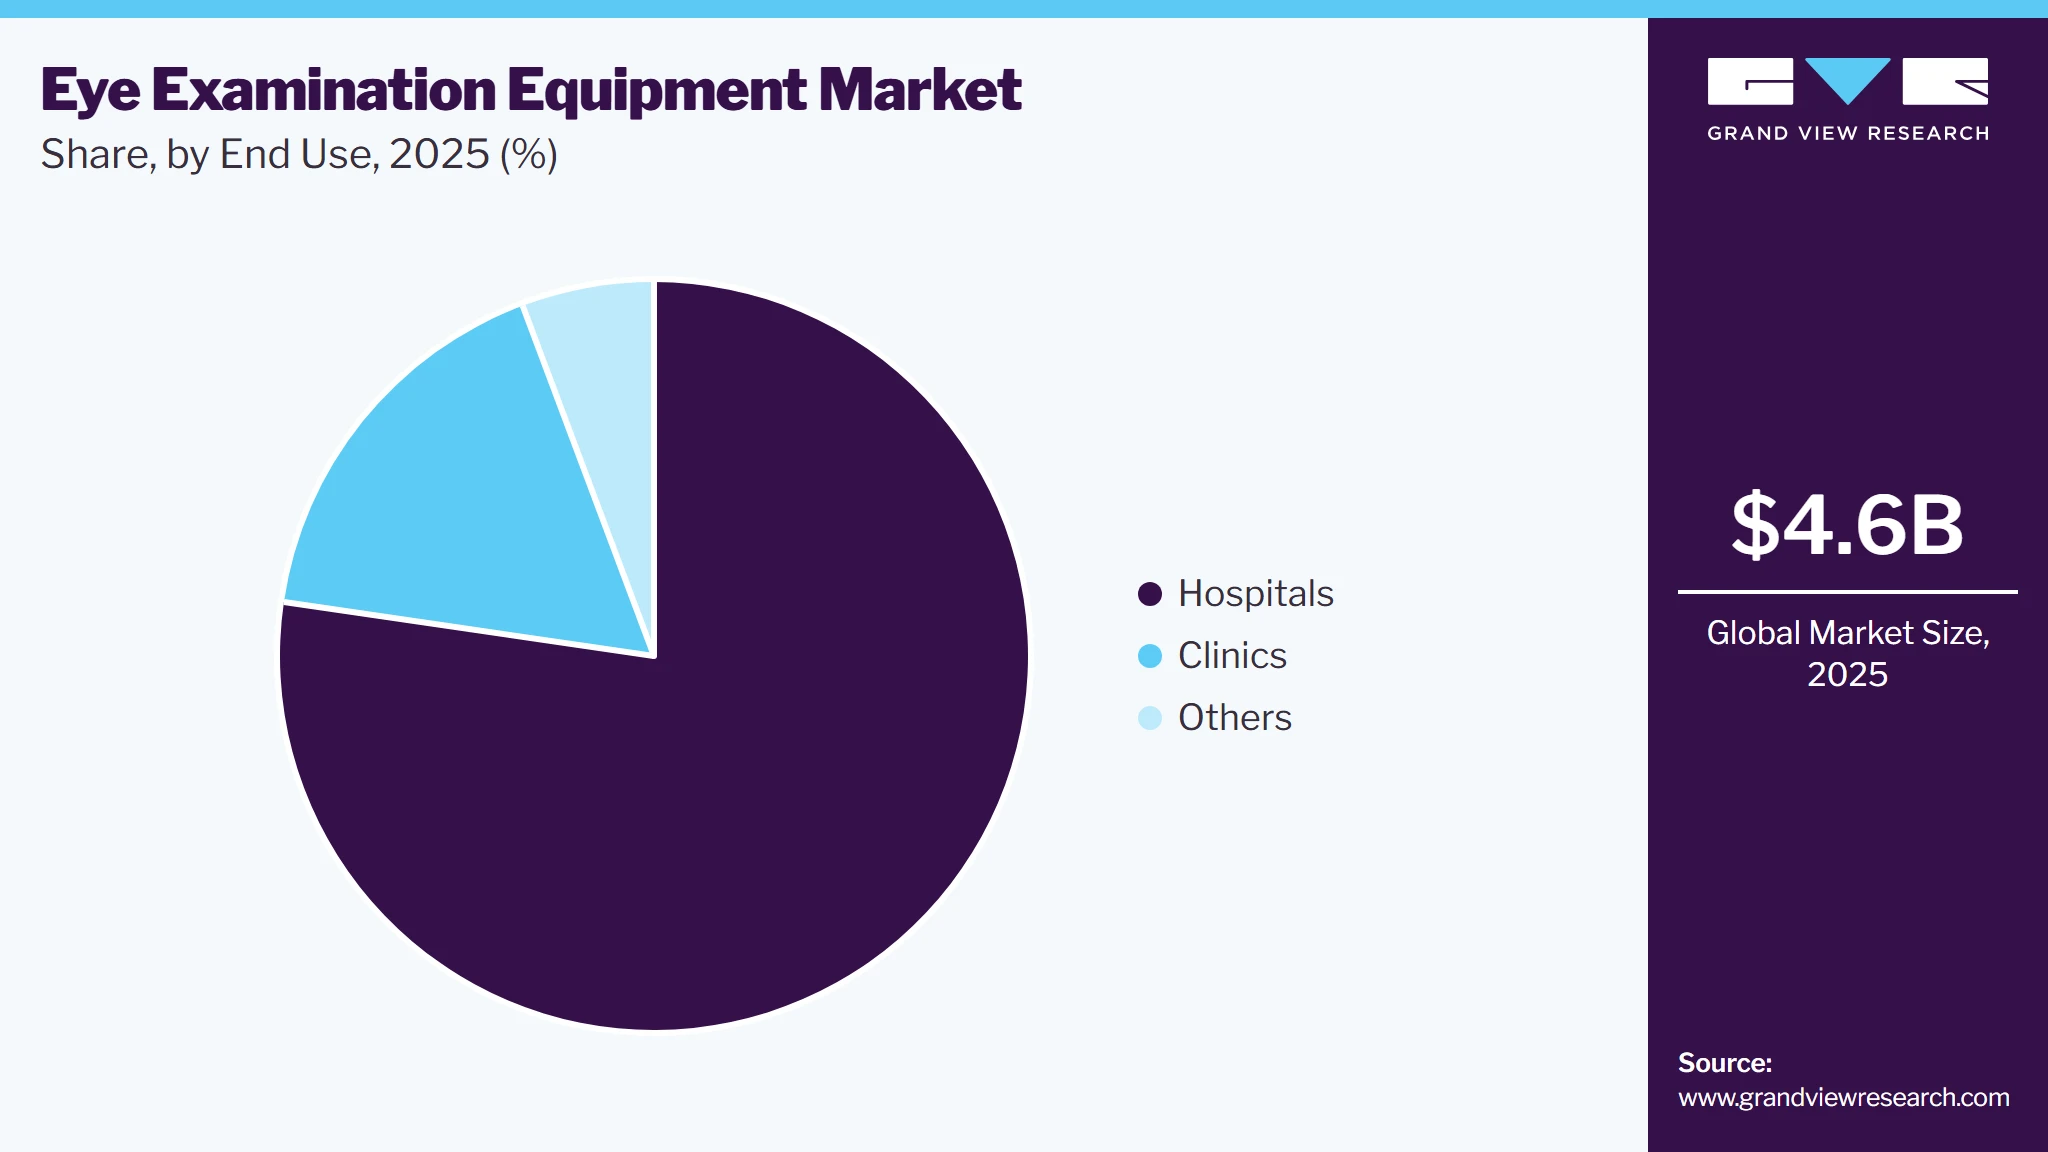
Based on end use, the hospital segment led the market with the largest revenue share of 77.3% in 2025, owing to the many ophthalmic surgeries performed in these facilities. Hospitals are equipped with advanced surgical and diagnostic equipment, such as optical coherence tomography (OCT) scanners and fundus cameras, which are essential for comprehensive eye examinations and treatments. The increasing prevalence of eye disorders, particularly among the aging population, drives demand for hospital-based services. For instance, the number of corneal transplants and cataract surgeries has steadily risen, necessitating sophisticated equipment to ensure successful outcomes. Hospitals also benefit from established reimbursement frameworks that support acquiring high-cost equipment, further solidifying their market dominance.
 To learn more about this report, Download Free Sample Report
The clinics segment is projected to grow at the fastest CAGR of 6.7% over the forecast period. This growth can be attributed to several factors, including the rising number of private clinical practices and the increasing accessibility of specialized optometry services. Clinics often provide more affordable treatment options than hospitals, making them attractive to patients seeking routine eye examinations and minor procedures. The growing awareness of eye health and the need for regular check-ups drive patient traffic to these facilities. Furthermore, advancements in portable diagnostic equipment allow clinics to offer a range of services without the need for extensive infrastructure. For instance, devices like portable tonometers and autorefractors enable quick eye health assessments, making clinics an appealing choice for patients.
Regional Insights
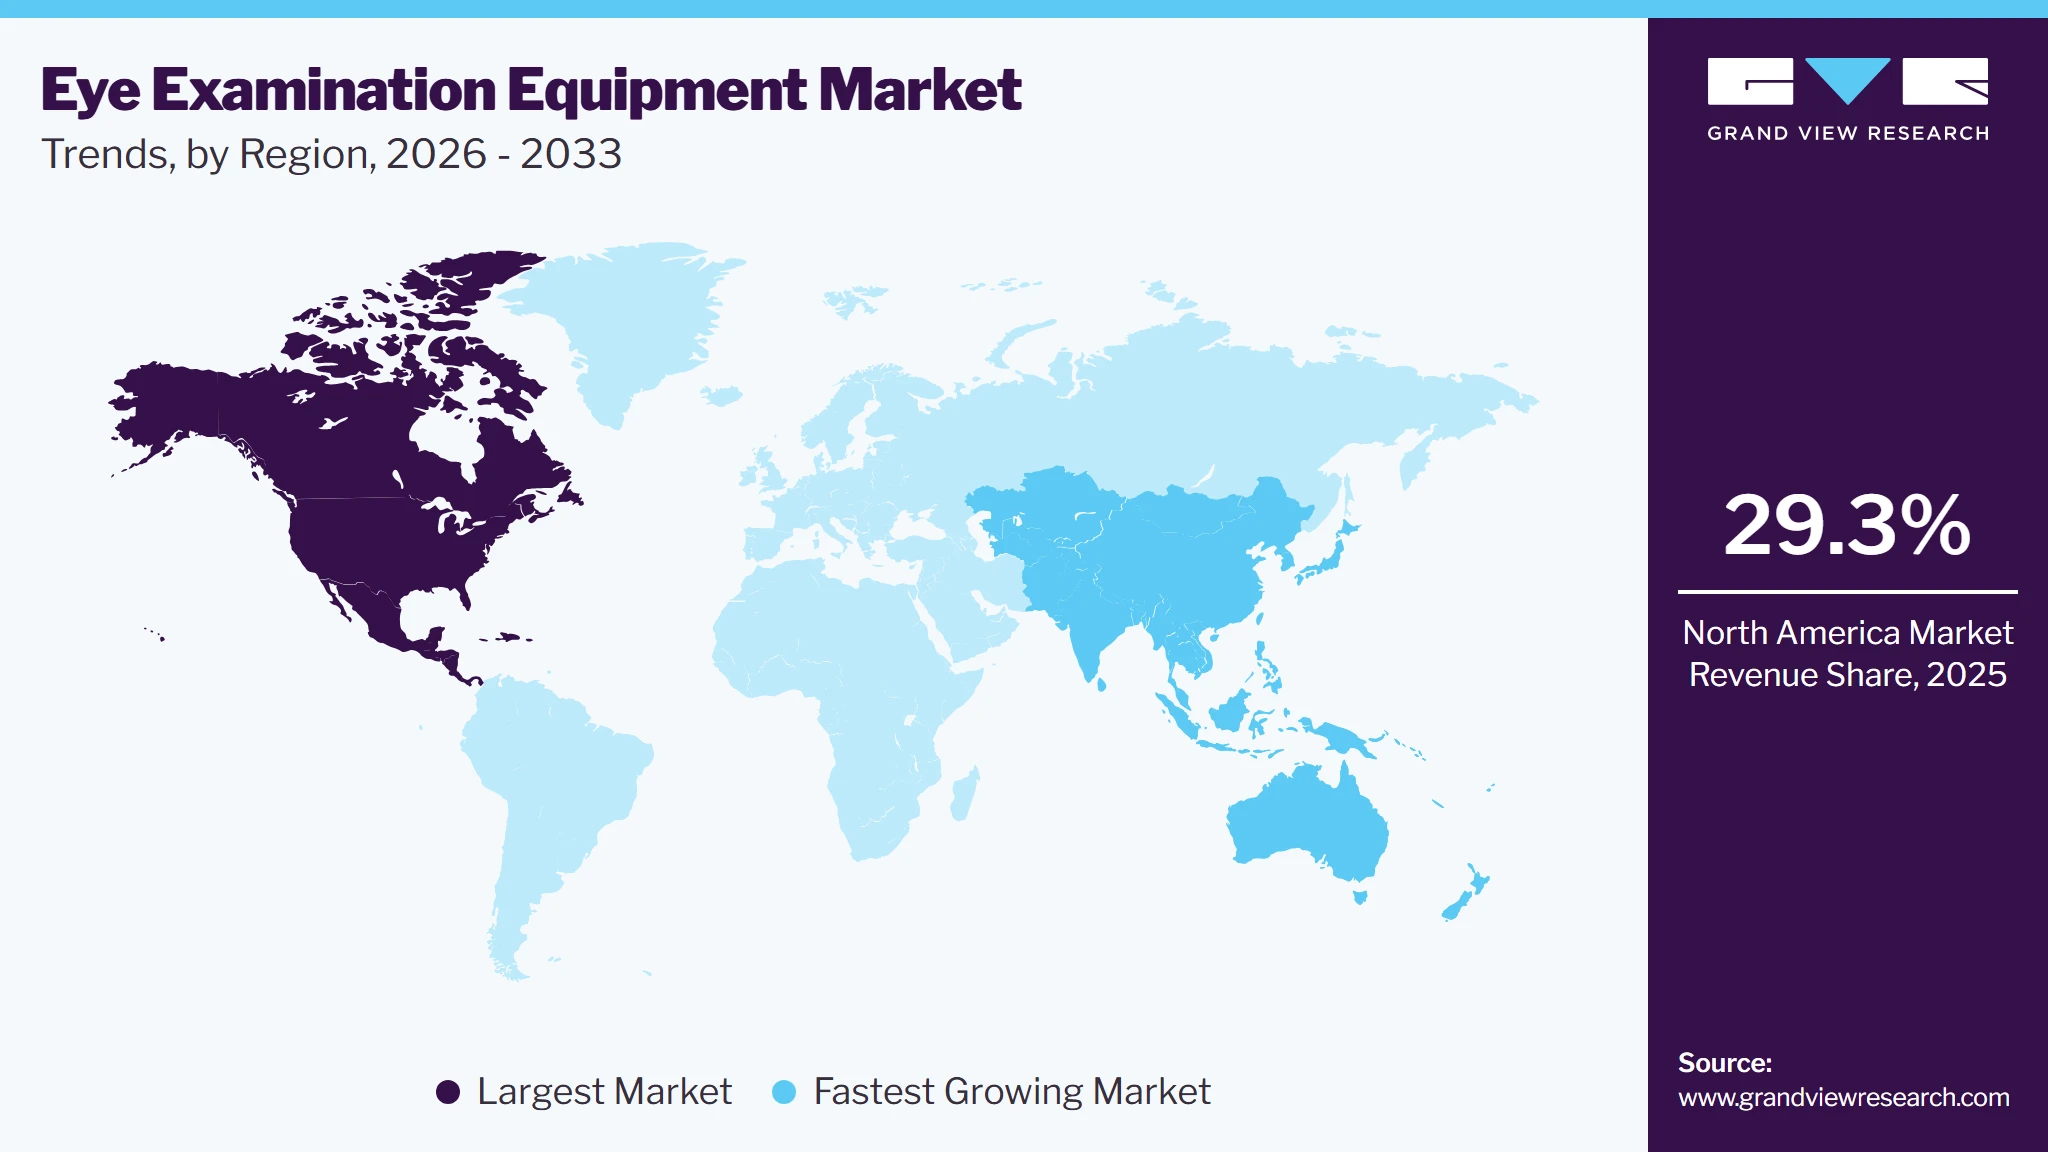
North America dominated the eye examination equipment market with the largest revenue share of 29.3% in 2025. due to the region's advanced healthcare infrastructure and high prevalence of eye diseases. The strong presence of leading market players and continuous technological advancements have also contributed significantly. Investment in research and development by both the government and private sectors has further propelled market growth.
 To learn more about this report, Download Free Sample Report
U.S. Eye Examination Equipment Market Trends
The eye examination equipment market in the U.S. held the largest share in the North America region in 2025. The country's focus on preventive healthcare and the increasing adoption of teleophthalmology have played crucial roles in this growth. Technological advancements, such as AI-driven diagnostic tools and remote monitoring systems, have further enhanced the efficiency and accuracy of eye examinations. Additionally, favorable reimbursement policies and government initiatives supporting eye care, like the Vision Health Initiative by the Centers for Disease Control and Prevention (CDC), have contributed to the market's expansion.
Europe Eye Examination Equipment Market Trends
The European eye examination equipment market was identified as a lucrative region in 2024. This growth is fueled by the rising prevalence of eye diseases and the region's commitment to improving healthcare services. Government initiatives to control visual impairment and promote regular eye check-ups have significantly boosted the demand for advanced eye examination equipment. For instance, the UK's National Health Service (NHS) has implemented several programs to increase access to eye care services.
Asia Pacific Eye Examination Equipment Market Trends
The Asia Pacific eye examination equipment market is anticipated to grow at a CAGR of 7.0% during the forecast period. This rapid growth can be attributed to the region's increasing healthcare expenditure and the rising awareness of eye health. Countries like India and China are leading the charge, with significant investments in healthcare infrastructure and the adoption of advanced medical technologies. The expanding middle class and the growing demand for quality healthcare services are also driving this region's growth.
Key Eye Examination Equipment Company Insights
Some of the key companies in the eye examination equipment market include Johnson & Johnson Services, Inc., Carl Zeiss Meditec AG, Alcon, Bausch & Lomb Incorporated, Quantel Medical, TOPCON CORPORATION, Essilor, and others.
-
Johnson & Johnson Services, Inc. offers a comprehensive range of eye examination equipment and solutions through its Vision Care division. Its product portfolio includes advanced diagnostic tools like OCT scanners, slit lamps, and phoropters, which are widely used by ophthalmologists and optometrists.
-
Carl Zeiss Meditec AG’s product offerings include VISUSCOUT 100 portable digital fundus cameras, VISUCORE 500 digital needs analysis systems, and VISUFIT 1000 platform for comprehensive eye examinations. It also offers i.Profilerplus is a 4-in-1 device that combines wavefront aberrometry, autorefractokeratometry, and corneal topography for providing eye measurement.
Key Eye Examination Equipment Companies
The following key companies have been profiled for this study on the eye examination equipment market.
-
Johnson & Johnson Services, Inc.
-
Carl Zeiss Meditec AG
-
Alcon
-
Bausch & Lomb Incorporated
-
Quantel Medical
-
TOPCON CORPORATION
-
Essilor
-
NIDEK CO., LTD.
-
HAAG-STREIT
-
VISIONCARE INC.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Johnson & Johnson Services, Inc., Carl Zeiss Meditec AG, Alcon, Bausch & Lomb Incorporated,)
- Focus on expanding comprehensive ophthalmic diagnostic portfolios including slit lamps, fundus cameras, OCT systems, autorefractors, tonometers, and AI-enabled diagnostic platforms.
- Invest in continuous product innovation, regulatory approvals, strategic acquisitions, and global distribution network expansion to strengthen presence across hospitals, eye clinics, and optical retail chains.
- Strong global brand recognition, extensive service networks, and diversified ophthalmic product portfolios provide significant competitive advantage.
- Advanced imaging technologies, AI-assisted diagnostic capabilities, cloud-based data management, and integrated ophthalmic workflow solutions improve diagnostic accuracy and clinical efficiency.
- High R&D expenditure, stringent regulatory compliance requirements, and frequent software validation increase operational costs.
- Premium pricing limits adoption in price-sensitive healthcare settings.
Emerging Players (NIDEK CO., LTD., HAAG-STREIT, VISIONCARE INC.)
- Focus on portable, handheld, and AI-enabled eye examination devices targeting primary care, teleophthalmology, community screening, and emerging markets.
- Prioritize innovation in smartphone-based retinal imaging, cloud connectivity, and affordable diagnostic solutions through research collaborations and strategic partnerships.
- Faster innovation cycles enable rapid commercialization of AI-powered screening technologies and portable diagnostic devices.
- Cost-effective and compact solutions improve accessibility for rural healthcare facilities, ambulatory care centers, and vision screening programs.
- Limited financial resources, smaller sales and service networks, and lower brand recognition restrict global market penetration.
- Challenges in obtaining regulatory approvals and generating large-scale clinical validation data may delay commercialization.
Recent Developments
-
In July 2024, EssilorLuxottica completed the acquisition of an 80% stake in Heidelberg Engineering, a German-based company specializing in OCT scanners. This acquisition represents a major step forward in EssilorLuxottica's strategic expansion into the medical technology sector.
-
In January 2023, Visibly and EyecareLive officially announced their merger. This collaboration will facilitate the launch of real-time video visits between optometrists and patients, enhancing the scope of vision consultations.
Eye Examination Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.6 billion
Estimated market size in 2026
USD 4.9 billion
Projected market size by 2033
USD 8.1 billion
Growth rate
CAGR of 7.4% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; Italy; Spain; Sweden; Norway; Denmark; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Johnson & Johnson Services, Inc., Carl Zeiss Meditec AG, Alcon, Bausch & Lomb Incorporated, Quantel Medical, TOPCON CORPORATION, Essilor, NIDEK CO., LTD., HAAG-STREIT, VISIONCARE INC.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Eye Examination Equipment Market Report Segmentation
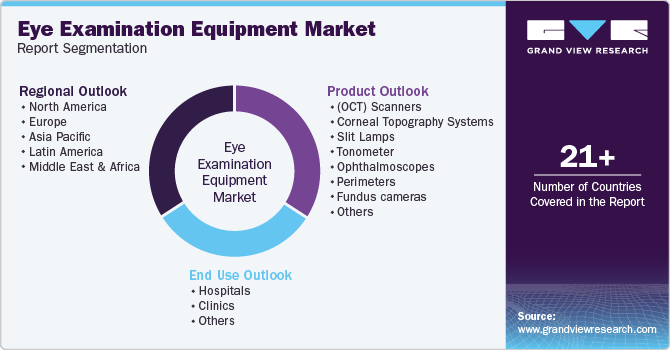
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global eye examination equipment market report based on product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Optical coherent tomography scanners (OCT)
-
Ophthalmic ultrasound imaging systems
-
Corneal topography systems
-
Slit lamps
-
Tonometer
-
Ophthalmoscopes
-
Perimeters/visual field analyzers
-
Fundus cameras
-
Autorefractors and Keratometers (phoropters)
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospitals
-
Clinics
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
Kuwait
-
-
Research Methodology
The lacrimal cannula market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each lacrimal cannula segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Product
Revenue capture definition
Optical Coherence Tomography Scanners
Revenue is generated through the capital sale of premium, high-resolution optical tomography systems used to capture cross-sectional micrometer-resolution images of the retina and anterior segment. Manufacturers secure upfront capital revenue from equipment hardware installations, which is continuously supplemented over time by multi-year service warranties, software licensing fees for advanced retinal layer tracking algorithms, and modular anterior/posterior imaging adapter sales.
Ophthalmic ultrasound imaging systems
Revenue flows from the commercialization of specialized diagnostic A-scan, B-scan, and ultrasound biomicroscopy (UBM) hardware consoles designed to evaluate the internal structures of the eye when optical media are opaque. Market participants derive income from primary console sales, multi-frequency transducer probes, specialized ultrasound gel consumables, and institutional maintenance agreements.
Corneal topography systems
Revenue is captured through the capital procurement of non-invasive medical mapping systems designed to analyze the surface curvature and outer shape profile of the cornea. Device providers monetize this segment via upfront workstation sales, integration software patches for refractive or cataract surgery planning software suites, and recurring revenue from specialized calibration fixtures and technical maintenance contracts.
Slit lamps
Revenue is derived from the steady procurement of baseline optical examination stations equipped with intense, adjustable slit illumination beams to evaluate the anterior and posterior ocular segments. Income is anchored on capital tool sales spanning traditional mechanical and high-definition digital slit lamps supplemented by aftermarket sales of integrated digital camera modules, teaching tubes, applanation tonometer mounts, and replacement bulb assemblies.
Tonometers
Revenue is generated through the distribution of intraocular pressure (IOP) measuring instruments essential for glaucoma screening and management. Manufacturers monetize this category through two distinct commercial pathways: upfront capital equipment sales of non-contact air-puff or handheld rebound tonometers, and a high-volume, highly predictable recurring stream from single-use disposable tonometer probes, sensor tips, or sterile prism covers.
Ophthalmoscopes
Revenue flows through the high-frequency supply of portable direct and indirect optical viewing systems designed to illuminate and examine the inner fundus of the eye. Income is characterized by transaction-based wholesale or clinic accounts purchasing handheld diagnostic sets, specialized binocular indirect headsets, rechargeable power handles, wall-mounted charging bays, and long-life LED bulb upgrades.
Perimeters/visual field analyzers
Revenue is captured by distributing automated projection perimetry hardware setups configured to map and measure a patient's visual field sensitivity. Companies derive significant upfront revenue from advanced capital diagnostic towers, layered alongside ongoing software subscription fees for progression analysis data suites, patient response button replacements, and continuous IT system integration service packages.
Fundus cameras
Revenue is generated via the capital commercialization of specialized medical microscopes attached to high-performance digital cameras used to photograph the interior surface of the eye. Manufacturers maximize revenue from premium desktop and mobile fundus systems, capturing value through hardware configurations, integrated artificial intelligence (AI) diagnostic software licenses for automated diabetic retinopathy screening, and secondary cloud-storage database packages.
Autorefractors and Keratometers (phoropters)
Revenue flows through the sale of dual-function automated refraction and keratometry workstations used to rapidly measure objective refractive errors and corneal curvature parameters. Income is driven by major optical retail and clinical group procurement setups purchasing automated diagnostic stations, digital phoropter refractors, manual lensmeter accessories, and recurring print-paper or device calibration tools.
Others
Revenue encompasses alternative, niche, or emerging diagnostic ophthalmic tools, including color vision testing plates, retro-illuminated visual acuity charts, digital eye-tracking diagnostic modules, exophthalmometers, and continuous firmware upgrades or maintenance contracts for multi-instrument integrated testing suites.
Segment – End Use
Revenue capture definition
Hospitals
Revenue is generated through structured, large-scale capital budget allocations, public or private medical tenders, and institutional group purchasing organization (GPO) supply alignments. Device manufacturers earn robust wholesale revenue via bulk deployment of premium multi-instrument diagnostic lanes, institution-wide software network licenses (DICOM/PACS integrations), and comprehensive multi-year service contracts covering the entire facility's diagnostic hardware fleet.
Clinics
Revenue flows via direct-to-practice purchasing accounts, equipment leasing programs, and specialized distributor networks supplying private optometry practices and independent ophthalmology clinics. This segment captures highly profitable revenue margins through modular, space-saving multi-functional diagnostic units, software add-ons, and immediate aftermarket service packages tailored to high-throughput, private patient-care operations.
Others
Revenue is derived from alternative and expanding healthcare delivery channels, including retail optical chains, commercial lens-fitting centers, mobile tele-ophthalmology outreach programs, military medical clinics, and academic research institutes purchasing specialized, high-tier configurations for clinical trials and vision science training programs.
Estimation Model
Step Number
Step
Guiding Question
Process Steps
Data Sources
01
Scope Definition
What components of the eye examination equipment market are being measured?
- Define product categories including slit lamps, OCT systems, fundus cameras, autorefractometers, tonometers, phoropters, lensmeters, and visual field analyzers. - Segment the market by product type, application, technology, and portability. - Define end users including hospitals, clinics, ASCs, and optical retail chains. - Establish geographic scope, base year, forecast criteria, and market breakdown.
Company annual reports, SEC filings, regulatory agencies, industry associations, hospital databases
02
Build the Product Base
What is the potential demand for eye examination equipment?
- Estimate the installed base of ophthalmic diagnostic equipment across healthcare facilities. - Assess the patient population requiring routine eye examinations and disease screening. - Evaluate healthcare infrastructure, eye care facilities, and ophthalmologist availability by region. - Forecast equipment demand based on disease incidence, replacement cycles, and clinical practice patterns.
WHO, Ministry of Health reports, company annual reports, distributor sales data
03
Estimate Penetration
How widely are advanced eye examination technologies adopted?
- Measure adoption of OCT, digital fundus cameras, AI, retinal imaging, and automated refraction systems. - Evaluate technology penetration across hospitals, eye clinics, optometry centers, and retail chains. - Assess replacement demand driven by technology upgrades and new installations. - Analyze regional adoption based on reimbursement, healthcare spending, and clinical awareness.
Industry databases, ophthalmology associations, manufacturer data, healthcare databases
04
Revenue Conversion
How is equipment demand converted into market revenue?
- Determine average selling prices (ASPs) for each eye examination equipment category. - Estimate revenues by product, end user, and region. - Include revenues from software, service contracts, and accessories. - Validate market estimates using company financials, distributor feedback, and sales data.
Company annual reports, SEC filings, pricing databases, distributor data
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Porters Analysis
Conducted a comprehensive Porter's Five Forces analysis of the global eye examination equipment market with a dedicated assessment of European and Asia Pacific markets. The study evaluated the bargaining power of equipment manufacturers, ophthalmology clinics, hospitals, ambulatory surgical centers, optical retail chains, and distributors. It assessed supplier concentration for critical components such as optical lenses, imaging sensors, AI-enabled diagnostic software, OCT modules, slit lamps, autorefractors, fundus cameras, and visual field analyzers. The analysis examined the threat of new entrants considering regulatory requirements, technological barriers, manufacturing capabilities, and capital investment. Competitive rivalry among established ophthalmic equipment manufacturers, pricing dynamics, product differentiation, digital ophthalmology innovations, AI-based diagnostics, teleophthalmology integration, and after-sales service capabilities were evaluated. Furthermore, substitute technologies, procurement trends, reimbursement environments, and purchasing behavior across Europe and Asia Pacific were analyzed to understand their influence on market competitiveness.
Enables stakeholders to understand the competitive intensity of the eye examination equipment market across Europe and Asia Pacific. The study supports strategic decisions related to pricing, product differentiation, supplier partnerships, distribution expansion, technology investments, and market entry strategies. It further assists manufacturers in identifying competitive threats, optimizing procurement and supply chain strategies, strengthening regional positioning, and capitalizing on evolving demand for advanced ophthalmic diagnostic technologies.
Competitive Landscape Analysis
Conducted a detailed competitive landscape assessment of the global eye examination equipment market with a special focus on key manufacturers operating across Europe and Asia Pacific. The study analyzed company market positioning, product portfolios covering OCT systems, fundus cameras, slit lamps, autorefractors, keratometers, tonometers, perimeters, retinal imaging systems, and AI-enabled diagnostic platforms. It evaluated product innovation strategies, pricing models, regulatory approvals, distribution partnerships, manufacturing footprints, mergers & acquisitions, collaborations with hospitals and ophthalmology clinics, regional expansion initiatives, R&D investments, digital ophthalmology capabilities, and commercialization strategies. The assessment also benchmarked technological advancements in cloud-based imaging, artificial intelligence-assisted diagnosis, portable ophthalmic devices, and integrated eye examination solutions adopted across developed and emerging healthcare markets.
Enables stakeholders to gain a comprehensive understanding of the competitive landscape and innovation ecosystem within the eye examination equipment market. The study supports strategic planning through competitor benchmarking, portfolio optimization, identification of technology gaps, partnership opportunities, commercialization strategies, and regional expansion planning. It also helps manufacturers strengthen competitive positioning by aligning product development with evolving clinical requirements and digital ophthalmology trends across Europe and Asia Pacific.
Geographic Analysis
Conducted an in-depth geographic assessment of the eye examination equipment market across Europe and Asia Pacific, evaluating country-level demand, healthcare infrastructure, ophthalmology care delivery models, demographic trends, disease burden, healthcare expenditure, regulatory frameworks, reimbursement policies, and technology adoption patterns. The study assessed market maturity across major European countries including Germany, France, the United Kingdom, Italy, Spain, and the Nordic region, as well as high-growth Asia Pacific countries including China, Japan, India, South Korea, Australia, and Southeast Asia. The analysis examined the prevalence of cataracts, glaucoma, diabetic retinopathy, age-related macular degeneration, refractive errors, increasing aging populations, vision screening programs, AI adoption in ophthalmology, digital healthcare initiatives, public and private investments, and expansion of ophthalmic clinics influencing demand for advanced eye examination equipment across both regions.
Enables stakeholders to identify high-growth countries and prioritize investments across Europe and Asia Pacific based on healthcare infrastructure, disease prevalence, technology adoption, reimbursement environments, and regulatory landscapes. The study supports regional expansion planning, distributor selection, market prioritization, product localization, pricing strategies, and investment decisions while identifying emerging opportunities in rapidly expanding ophthalmology diagnostics markets.
Frequently Asked Questions About This Report
Key factors that are driving the market growth include rising prevalence of eye diseases, technological advancements in ophthalmic surgical and diagnostic instruments, and government initiatives for increasing awareness related to visual impairment.
The global eye examination equipment market size was valued at USD 4.6 billion in 2025 and is projected to grow from USD 4.9 billion in 2026
The global eye examination equipment market is expected to grow at a compound annual growth rate of 7.4% from 2026 to 2033 to reach USD 8.1 billion by 2033.
Some key players operating in the optometry/eye examination market include Bausch & Lomb Inc, Carl Zeiss Meditec AG, Alcon Inc, Johnson & Johnson Vision Care Inc., Bausch & Lomb Incorporated, ESSILOR INTERNATIONAL S.A., Ziemer Ophthalmic Systems AG, NIDEK CO. LTD., TOPCON MEDICAL SYSTEMS, INC., HAAG-STREIT, and VISIONCARE INC.
North America dominated the optometry/eye examination market with a share of 29.3% in 2025. This is attributable to significant advances in ophthalmic surgical procedures and devices, which helped improve diagnosis and treatment of various ophthalmic diseases, including retinal disorders, glaucoma, or refractory disorders.
Hospital segment led the market with the largest revenue share of 77.3% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Based on product, the optical coherence tomography (OCT) scanners segment accounted for a share of 21.0% in 2025, primarily due to the increasing prevalence of retinal and macular disorders, growing demand for non-invasive and high-resolution eye imaging, rising adoption of advanced diagnostic technologies, and the ability of OCT scanners to provide detailed cross-sectional images of ocular structures.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


