
- Home
- »
- Healthcare IT
- »
-
Patient Data Hub Solutions Market Size Report, 2026-2033GVR Report cover

Patient Data Hub Solutions Market (2026 - 2033)
Size, Share & Trends Analysis Report By Solution Type (Health Data Apps & AI Solutions, Data Integration Solutions, Patient 360 View Platforms), By Deployment Mode (Cloud-based,), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$1.7BMarket Estimate, 2026
$1.8BMarket Forecast, 2033
$3.0BCAGR, 2026–2033
7.5%Patient Data Hub Solutions Market Summary
The global patient data hub solutions market size was valued at USD 1.7 billion in 2025 and is projected to grow from USD 1.8 billion in 2026 to USD 3.0 billion by 2033, at a CAGR of 7.5% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.7% in 2025. The market demand is attributed to a rising need for centralized patient data to improve patient care, a need for interoperability, and advancements in health IT infrastructure.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By solution type: Health data apps & AI solutions segment dominated the market, with a revenue share of 42.0% in 2025.
- By deployment mode: Cloud-based segment held the largest market share of 55.0% in 2025.
- By end use: Healthcare companies accounted for the largest revenue share of 39.3%in 2025.
Regional Highlights
- Largest regional market: North America (40.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.7 Billion
- Estimated market size in 2026: USD 1.8 Billion
- Projected market size by 2033: USD 3.0 Billion
- CAGR (2026-2033): 7.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In October 2023, Microsoft launched advanced data and AI solutions aimed at empowering healthcare organizations to derive deeper insights and enhance both patient care and clinician experiences. According to the World Economic Forum, hospitals generate around 50 petabytes of siloed data annually-the equivalent of nearly 10 billion music files. Yet, an astonishing 97% of this data remains untapped, meaning countless insights with the potential to improve patient care and streamline operations are left unexplored. Effectively harnessing this data is essential to achieving meaningful clinical and operational advancements.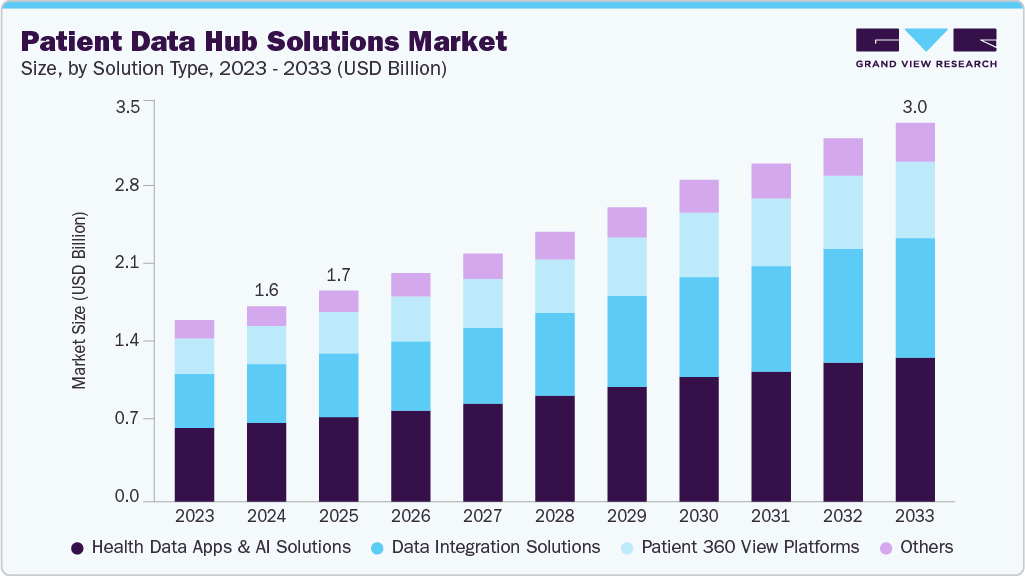 To learn more about this report, Download Free Sample Report
The growing demand for centralized patient data drives the patient data hub solutions market. As healthcare providers face challenges in delivering better, more personalized care, having a unified view of a patient's medical history has become essential. Centralized data helps reduce redundancies, supports accurate diagnosis, and improves treatment plans. The article published by the National Library of Medicine in January 2024 discusses the implementation of a Centralized Healthcare Database (CHD) to enhance patient care, streamline healthcare systems, and support research. It emphasizes the importance of addressing challenges related to data management, security, and standardization to maximize the benefits of CHD.
Hospitals and clinics often use diverse systems that don’t communicate well with each other. Patient data hub solutions address this by integrating various platforms into a single, connected ecosystem. This improves communication among healthcare providers and reduces the risk of errors. Because of this, many companies are coming up with various services and solutions. For instance, in February 2025, Cotiviti agreed to acquire Edifecs to enhance healthcare interoperability. The combined platform aims to improve connectivity between payers and providers, streamline operations, and accelerate the deployment of value-based care solutions in healthcare systems.
Technological advancements in healthcare IT infrastructure significantly contribute to the growth of the patient data hub solutions market. Tools like cloud computing and AI enable smarter, faster, and more secure handling of patient information.
Market Dynamics
The patient data hub solutions market is driven by the increasing adoption of digital healthcare, rising demand for interoperable health information systems, and the growing need to consolidate patient data from multiple sources into a unified longitudinal record. The expansion of value-based care models, increasing implementation of cloud-based healthcare IT platforms, and regulatory initiatives promoting data interoperability are further accelerating market growth.
The growing demand for centralized patient data management is driving the patient data hub solutions market. As healthcare providers strive to deliver more coordinated and personalized care, access to a unified view of a patient's medical history has become increasingly important. Centralized patient data enables clinicians to consolidate information from multiple healthcare systems, reducing duplicate records, improving diagnostic accuracy, supporting informed clinical decision-making, and enhancing treatment planning. The increasing adoption of value-based care and data-driven healthcare models is further encouraging healthcare organizations to invest in patient data hub solutions.
According to an article published by the National Library of Medicine in January 2024, implementing a Centralized Healthcare Database (CHD) can improve patient care, streamline healthcare operations, and support clinical research by providing integrated access to patient information. The publication also highlights the importance of effective data management, security, privacy, and standardization to maximize the benefits of centralized healthcare databases, reinforcing the growing need for advanced patient data hub solutions.
Patient data hub solutions store and exchange large volumes of sensitive patient information, making them vulnerable to cyberattacks, data breaches, and unauthorized access. As healthcare organizations increasingly rely on digital platforms, protecting patient data has become a critical challenge. Organizations must also comply with stringent healthcare data privacy and security regulations while ensuring secure data sharing across systems. The added costs and complexity associated with cybersecurity measures and regulatory compliance can slow the adoption of patient data hub solutions.
The integration of artificial intelligence (AI) into patient data hub solutions is creating significant opportunities for healthcare organizations to transform large volumes of fragmented patient data into actionable clinical insights. AI-powered patient data hubs can aggregate information from electronic health records (EHRs), laboratory systems, imaging platforms, wearable devices, and remote patient monitoring solutions to generate real-time patient summaries, identify care gaps, predict disease risks, and support personalized treatment decisions. As healthcare providers increasingly adopt value-based care models, AI-enabled data hubs are becoming essential for improving care coordination, reducing clinician workload, and enhancing population health management through predictive analytics and automated clinical workflows.
The growing industry focus on AI-enabled patient data platforms is also a significant opportunity. For instance, in September 2025, Oracle Health announced new AI capabilities for its Patient Portal that enable patients to receive simplified explanations of medical records and interact with their health information using conversational AI, strengthening patient engagement through unified health data. This advancement is accelerating the adoption of AI-powered patient data hubs across healthcare systems.
Market Concentration & Characteristics
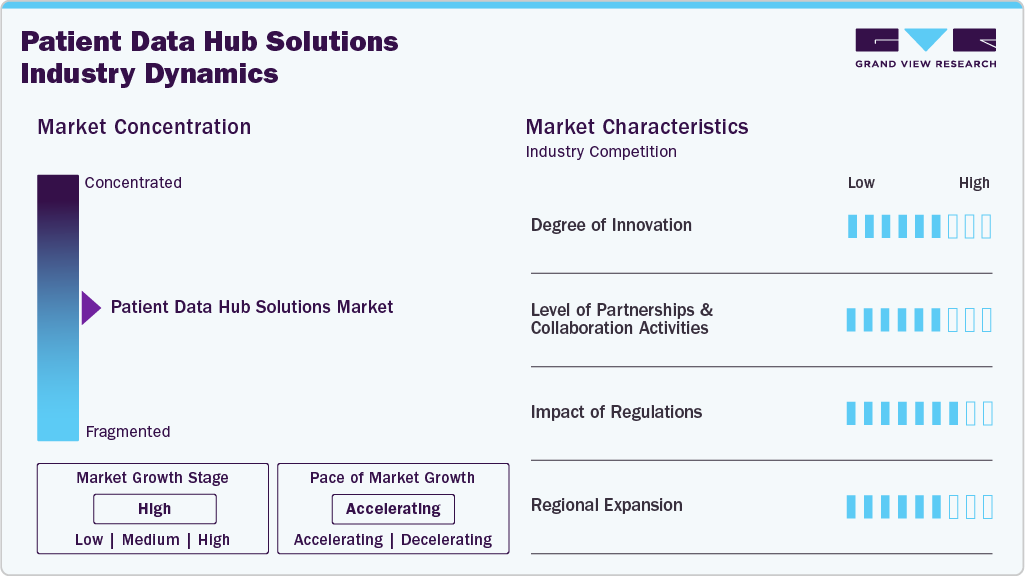
The degree of innovation in the patient data hub solutions industry is high, driven by rapid advancements in digital health technologies, growing investments in healthcare IT, and the increasing adoption of AI and machine learning. These innovations enable real-time analytics, predictive insights, and more personalized care delivery.
The level of mergers and acquisitions in industry is significantly growing as companies seek to expand their technological capabilities, strengthen their market presence, and address the rising demand for integrated healthcare solutions. Larger health IT firms are acquiring innovative startups to gain access to advanced data integration, analytics, and interoperability tools. These strategic partnerships allow firms to offer more comprehensive solutions that cater to complex healthcare data management needs.
 To learn more about this report, Download Free Sample Report
The impact of regulations in the industry is high, as healthcare providers must comply with strict data privacy, security, and interoperability standards. Laws such as HIPAA in the United States, GDPR in Europe, and other regional regulations mandate secure storage, access, and sharing of patient information. In addition, governing bodies promoting electronic health records (EHRs) and value-based care models further intensify the need for regulated, interoperable data infrastructure.
For instance, in July 2023, the World Health Organization (WHO) and Health Level Seven International (HL7) signed a Project Collaboration Agreement to promote the global adoption of open interoperability standards in digital health. This partnership aims to support the implementation of the WHO Global Strategy on Digital Health 2020-2025 by enhancing countries' capacities to adopt and effectively use interoperability standards. A key focus is integrating HL7's Fast Healthcare Interoperability Resources (FHIR) standard, facilitating seamless data exchange across diverse health systems.
The industry is experiencing moderate to high regional expansion as healthcare systems worldwide increasingly recognize the importance of centralized, interoperable data platforms. While North America and Europe lead due to advanced healthcare infrastructure and supportive regulatory frameworks, emerging markets in Asia-Pacific, Latin America, and the Middle East are rapidly adopting digital health technologies.
Analyst Perspective
The increasing adoption of digital healthcare, rising demand for interoperable health information systems, and the growing need for centralized patient data management are driving the patient data hub solutions market. The expansion of value-based care, the increasing implementation of cloud-based healthcare platforms, and the growing adoption of AI-enabled analytics are further supporting demand for patient data hub solutions among healthcare providers, payers, life sciences companies, and research organizations. Market participants are focusing on developing AI-powered patient data platforms, enhancing interoperability through FHIR-based solutions, expanding cloud-native offerings, and pursuing strategic partnerships, acquisitions, and product innovations to strengthen their market presence and address the evolving needs of data-driven healthcare.
Emerging Pricing Models Analysis
The pricing structures in the Patient Data Hub Solutions market are designed to align with healthcare providers’ evolving needs for data integration, scalability, and compliance. Vendors typically offer flexible and tiered pricing strategies to accommodate various organizational sizes, data volumes, and integration complexities.
- Subscription-Based Pricing (Annual or Monthly)
This is the most common pricing model adopted by patient data hub providers. Clients are charged a fixed monthly or annual fee based on selected modules, user access levels, and data storage capacity. This model offers predictable budgeting for providers and supports long-term service contracts. Example: A health system subscribing to a patient data aggregation and analytics suite for multi-hospital deployment.
- Usage-Based or Pay-Per-Interaction
This model charges clients based on the actual volume of data processed, patient interactions managed, or API calls made. It is especially favored by smaller practices or those with fluctuating data loads. It aligns costs with utilization, offering a cost-effective entry point for early adopters. This is often used in value-based care programs or for payer-provider integration platforms.
Case Study: Transforming Healthcare with Apexon's Patient 360 and HDAP Platform
Background
Healthcare organizations are under growing pressure to deliver personalized, seamless, and outcomes-driven care experiences. In response to updated Centers for Medicare & Medicaid Services (CMS) guidelines, which by 2023 allocated 57% of Medicare Advantage (MA) star ratings to patient experience, providers are actively seeking technology solutions that unify patient data and drive care transformation.
To address this need, Apexon, an AWS Advanced Tier Services Partner, developed the Patient 360 solution powered by its proprietary Health Data Analytics Platform (HDAP) and hosted on AWS.
The Challenge
Healthcare data is inherently complex, fragmented, and sensitive. Providers struggle to integrate data from clinical visits, diagnostics, medications, wearables, and social determinants of health to create a unified view of each patient. This disjointed information landscape hinders proactive engagement, care coordination, and patient outcomes.
Solution Overview: Apexon's Patient 360 and HDAP
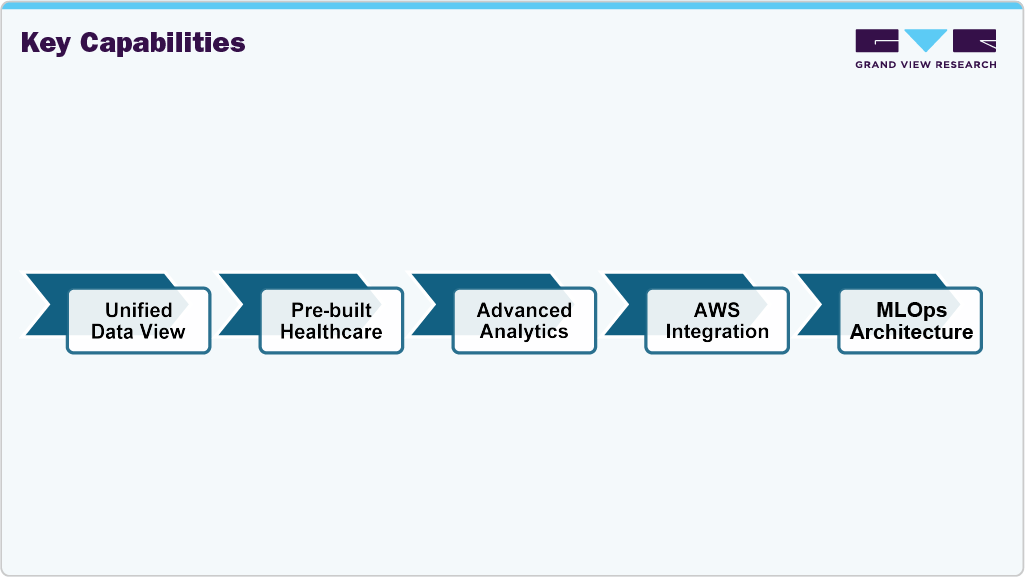
Patient 360 is a healthcare analytics framework that provides a real-time, 360-degree view of patient health, supported by Apexon's HDAP-a scalable, secure platform built on AWS.
 To learn more about this report, Download Free Sample Report
 To learn more about this report, Download Free Sample Report
Conclusion
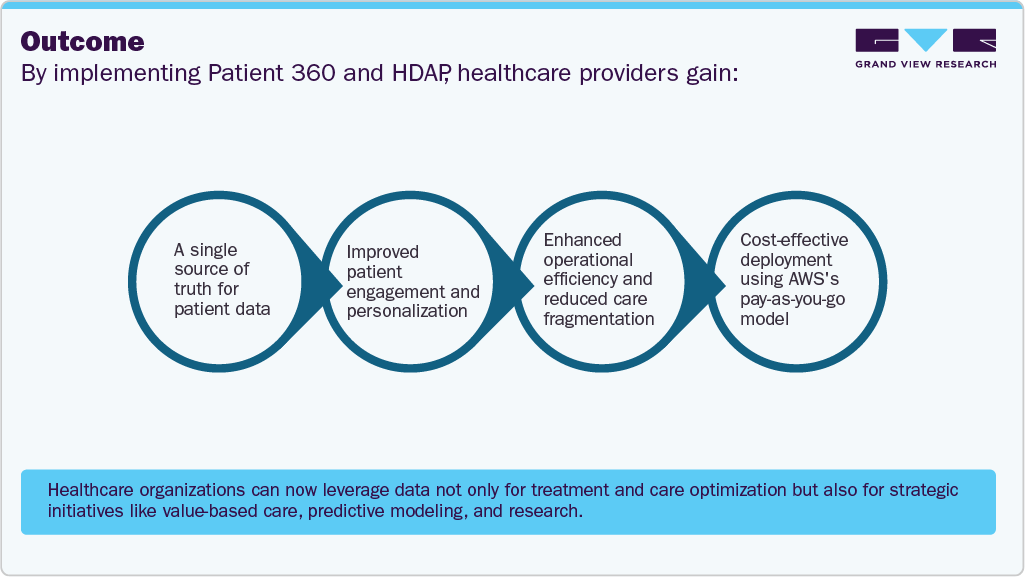
Apexon's Patient 360, powered by HDAP and AWS, is a next-generation healthcare solution that bridges data silos, enhances patient engagement, and improves clinical and operational outcomes. It positions providers to meet the rising expectations of value-based care and consumer-centric delivery.
Solution Type Insights
Based on solution type, the health data apps & AI solutions segment held the largest market share of 42.0% in 2025. The demand is rising as healthcare organizations rely on intelligent technologies to improve diagnosis and treatment and manage, analyze, and interpret large volumes of patient data. Integrating these solutions with remote monitoring tools and apps enhances their utility in chronic disease management and telehealth. Furthermore, the need for faster decision-making, reduced administrative burden, and improved workflow efficiency is pushing healthcare organizations to adopt AI-driven data hub technologies at a growing rate.
Data Integration Solutions is expected to grow at the fastest CAGR over the forecast period. This is due to the increasing need for seamless connectivity among disparate healthcare systems and the consolidation of clinical, financial, and operational data into unified platforms. As healthcare organizations continue to adopt various electronic health record (EHR) systems, laboratory information systems, and third-party applications, data silos have become a major challenge. Data integration solutions address this by enabling interoperability, real-time data sharing, and streamlined data workflows.
Deployment Mode Insights
Based on deployment mode, the cloud-based segment accounted for the largest revenue share of 55.0% in 2025. This is due to the increasing preference for scalable, cost-effective, and easily accessible data management solutions across healthcare organizations. Cloud-based platforms enable real-time access to patient information from multiple locations, essential for remote care, telemedicine, and multi-site healthcare systems. They also reduce the need for heavy on-premise infrastructure, cutting IT maintenance costs and facilitating faster deployment. Moreover, cloud solutions offer huge data backup, disaster recovery, and enhanced security features that help healthcare providers comply with strict regulatory standards. As interoperability and data sharing across healthcare networks become more critical, cloud-based deployment models are gaining traction for flexibility, easy integration with other systems, and support for advanced analytics and AI capabilities.
The on-premise segment is expected to grow significantly over the forecast period. This can be attributed to the increasing concerns around data privacy, security, and regulatory compliance. Healthcare organizations, especially large hospitals and government institutions, prefer on-premise deployments to maintain direct control over sensitive patient information and to meet strict regional data protection regulations such as HIPAA and GDPR. The segment also benefits from growing investments in internal IT capabilities, particularly in markets with limited cloud adoption due to connectivity or policy constraints.
End-use Insights
Based on end use, the healthcare companies segment held the largest market share of 39.3%in 2025. This is attributed to their extensive investment in digital transformation, growing emphasis on drug development efficiency, and the need for real-time data analytics. Pharmaceutical and biotechnology companies increasingly rely on patient data hub solutions to streamline clinical trials, accelerate R&D, and support pharmacovigilance.
These hubs enable comprehensive data integration from multiple sources, enhancing decision-making and compliance with regulatory standards. As these companies handle vast volumes of sensitive health data, strong and secure platforms are essential, driving their dominance in the market. For instance, in January 2024, XO Health partnered with Innovaccer to enhance member experiences for self-insured employers. The collaboration uses Innovaccer's data platform, CRM, and population health tools to unify data-driven healthcare journeys, benefits, care delivery, and advocacy, enabling personalized and improved outcomes.
 To learn more about this report, Download Free Sample Report
Healthcare providers are expected to grow at the fastest CAGR during the forecast period. This is due to the rising demand for efficient patient care, improved clinical decision-making, and enhanced interoperability. Hospitals, clinics, and diagnostic centers are adopting patient data hubs to unify fragmented data from EHRs, imaging systems, and lab results. This integration supports better diagnosis, treatment planning, and patient engagement while ensuring compliance with healthcare regulations. The push toward value-based care and remote monitoring further fuels the need for centralized, accessible patient data.
Regional Insights
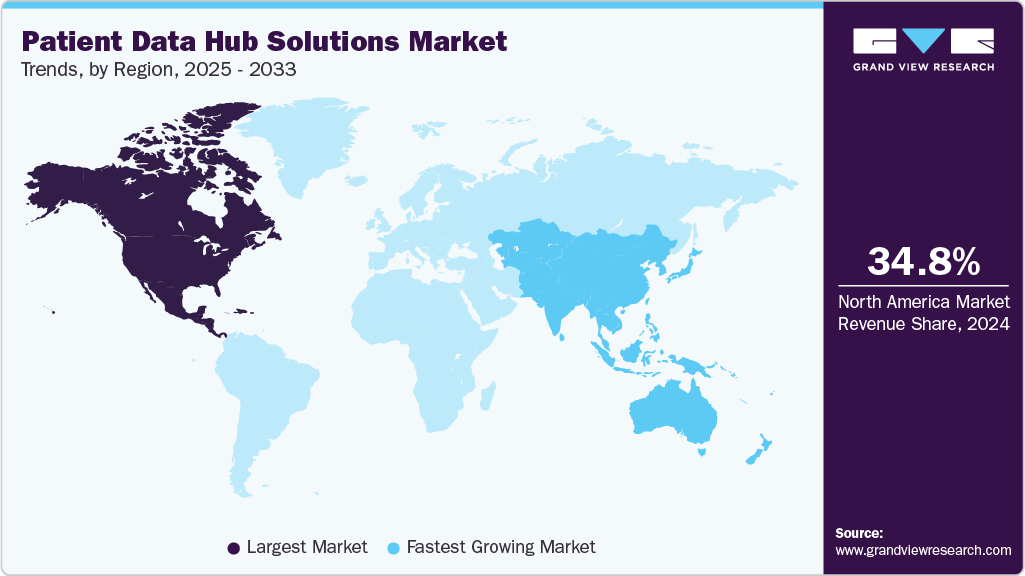
North America dominated the patient data hub solutions market with the largest revenue share of 40.7% in 2025. due to its advanced healthcare infrastructure, early adoption of digital technologies, and strong regulatory frameworks like HIPAA. The demand is driven by the need for real-time patient data access, value-based care models, and integration of AI and analytics in patient care. Investments in health IT and support from government initiatives like the HITECH Act further boost market growth in this region. The strong presence of market players further propels the market. For instance, in September 2021, ZS, a U.S.-based company, launched ZAIDYN, an intelligent, cloud-based platform designed to transform life sciences operations digitally. It integrates AI-driven analytics, modular applications, and business-ready connectors to enhance customer engagement, field performance, and clinical development.
 To learn more about this report, Download Free Sample Report
U.S. Patient Data Hub Solutions Market Trends
The patient data hub solutions market in the U.S. held the largest share in the North America region in 2025. The shift toward value-based care models emphasizes the importance of integrated data solutions that can provide comprehensive patient insights, thereby improving treatment efficacy and reducing healthcare costs. Advancements in healthcare technology, including the integration of artificial intelligence and machine learning, have further propelled the adoption of patient data hubs by enabling predictive analytics and personalized care strategies.
Europe Patient Data Hub Solutions Market Trends
The patient data hub solutions market in Europe is growing as the region has a strong demand due to the increasing digitization of healthcare and emphasis on cross-border health data sharing under initiatives like the European Health Data Space. The region is also witnessing a rise in chronic illness, elderly population, and AI integration, which fuels demand for centralized patient data hub solutions for better patient management and research efficiency.
The UK patient data hub solutions market is anticipated to grow as the country is actively investing in NHS digital transformation programs, including unified health records and interoperability standards. Demand is high due to national-level strategies focusing on integrated care systems (ICS), improved patient outcomes, and reduced healthcare costs through better data management. The shift toward personalized medicine and population health management also accelerates market growth.
The patient data hub solutions industry in Germany is projected to grow due to reforms like the Hospital Future Act (Krankenhauszukunftsgesetz), which promotes hospital digitalization. The country’s move towards electronic patient records (ePA), better healthcare data management, and GDPR-compliant cloud and hybrid solutions further fuel the demand. Investments from both the public and private sectors are further encouraging adoption.
Asia Pacific Patient Data Hub Solutions Market
The patient data hub solutions market in Asia-Pacific is growing at the fastest CAGR, driven by rapid adoption of cloud based technologies, increasing healthcare expenditure, and government focus on health tech modernization. The demand arises from the growing patient population, urbanization, and the need for remote health services. There’s also a shift toward centralized health data platforms for population health and outbreak tracking.
China patient data hub solutions market is seeing significant demand due to government-led initiatives like "Healthy China 2030" and investments in digital health infrastructure. The push for smart hospitals and AI-driven health systems requires integrated data platforms, making patient data hubs essential for hospital management, chronic disease tracking, and AI training models. For instance, IQVIA's China Regional Electronic Health Records (rEHR) dataset integrates patient-level data from 333 hospitals and 256 health centers across Chongqing, Tianjin, and Yinzhou. It encompasses inpatient and outpatient records, including demographics, diagnoses, procedures, lab results, and treatment costs. This standardized, longitudinal dataset supports real-world research, AI/ML applications, and healthcare optimization.
The patient data hub solutions market in India is significantly growing due to initiatives such as the government’s National Digital Health Mission (NDHM), which aims to provide digital health IDs and unified health records for citizens. The rise in chronic illnesses, telemedicine, and private hospital chains further drives demand for interoperable and scalable health data hubs.
Latin America Patient Data Hub Solutions Market
The patient data hub solutions market in Latin America is driven by increasing investment in health IT infrastructure and efforts to improve healthcare quality and access. Countries like Brazil and Mexico focus on digital health strategies, and the rising demand for integrated EHR systems pushes the market forward.
Middle East & Africa Patient Data Hub Solutions Market
The patient data hub solution market in the Middle East and Africa region is projected to grow, led by Gulf countries like the UAE and Saudi Arabia, which invest in smart healthcare as part of Vision 2030 strategies. The need to modernize outdated systems, manage population health data, and improve care coordination in urban hospitals is driving adoption. In Africa, digital transformation projects supported by NGOs and international agencies create a foundation for future growth.
Key Patient Data Hub Solutions Companies Insights
Key players operating in the patient data hub solutions market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth.
Key Patient Data Hub Solutions Companies
The following are the leading companies in the These companies collectively hold the largest market share and dictate industry trends.
The following key companies have been profiled for this study on the patient data hub solutions market.
-
IQVIA, Inc.
-
WellSky
-
Veeva Systems
-
Capgemini (LiquidHub)
-
Optum (UnitedHealth Group)
-
ZS
-
Equipo Health Inc.
-
NXGN Management, LLC. (NextGen Healthcare, Inc.)
-
Beghou Consulting
-
IntegriChain Incorporated
-
Informatica
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (IQVIA, Optum, Oracle Health, InterSystems, Informatica, Veeva Systems, WellSky)
- Invest in AI-powered patient data hubs, cloud-native interoperability platforms, strategic acquisitions, FHIR-enabled data integration, and partnerships with healthcare providers, payers, and life sciences organizations to expand digital health capabilities.
- Strong brand recognition, comprehensive healthcare data platforms, advanced AI and analytics capabilities, large customer base, extensive partner ecosystems, and global presence.
- High implementation and integration costs, complex deployment processes, lengthy sales cycles, dependence on large enterprise customers, and evolving regulatory compliance requirements.
Emerging Players (Innovaccer, Veradigm, Equipo Health Inc., NextGen Healthcare, ZS Associates, Capgemini)
- Focus on cloud-based patient data platforms, AI-driven analytics, value-based care solutions, interoperability services, regional expansion, and strategic collaborations with healthcare organizations.
- Agile product innovation, cloud-native architecture, flexible deployment models, specialized healthcare expertise, faster implementation, and competitive pricing.
- Limited global presence, smaller customer base, lower brand recognition than established vendors, dependence on partnerships, and constrained financial and R&D resources.
Recent Development
-
In March 2026, IQVIA launched IQVIA.ai, a unified agentic AI platform powered by NVIDIA to help life sciences organizations leverage healthcare data, automate workflows, and improve decision-making across clinical, commercial, and real-world operations.
“IQVIA.ai reflects our longstanding commitment to translating innovation into practical, high impact solutions for life sciences, “By bringing together our data, expertise and Healthcare-grade AI within a unified, agentic platform, IQVIA.ai enables organizations to move faster and smarter while meeting the rigorous standards of trust and reliability that are required in the industry.”
- Bernd Haas, senior vice president, AI and Technology Solutions at IQVIA.
Patient Data Hub Solutions Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.7 billion
Estimated market size in 2026
USD 1.8 billion
Projected market size by 2033
USD 3.0 billion
Growth rate
CAGR of 7.5% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Solution type, deployment mode, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, China, Japan, India, South Korea, Australia, Thailand, Singapore, Brazil, Argentina, Saudi Arabia, South Africa, UAE, Kuwait
Key companies profiled
IQVIA, Inc., WellSky, Veeva Systems, Capgemini, Optum (UnitedHealth Group), ZS Associates, Equipo Health Inc., NextGen Healthcare, Informatica, Oracle Health, InterSystems, Innovaccer, Veradigm.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Patient Data Hub Solutions Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global patient data hub solutions market report based on solution type, deployment mode, end use, and regions.
 To learn more about this report, Download Free Sample Report
-
Solution Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Health Data Apps & AI Solutions
-
Data Integration Solutions
-
Patient 360 View Platforms
-
Others
-
-
Deployment Mode Outlook (Revenue, USD Million, 2021 - 2033)
-
Cloud-based
-
On-premise
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Healthcare Companies
-
Healthcare Providers
-
Healthcare Payers
-
Others (Include CRO, CDMO, etc.)
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The patient data hub solutions market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each patient data hub solutions segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Solution Type
Revenue Capture Definition
Health Data Apps & AI Solutions
Revenue generated from AI-enabled healthcare applications that aggregate, analyze, and interpret patient data to support clinical decision-making, predictive analytics, patient engagement, and workflow automation.
Data Integration Solutions
Revenue generated from platforms that integrate patient data from multiple sources, including EHRs, laboratory systems, imaging systems, pharmacy systems, wearable devices, and claims databases into a unified repository.
Patient 360 View Platforms
Revenue generated from solutions that create a comprehensive, longitudinal view of patient information by consolidating clinical, administrative, financial, and behavioral health data into a single profile.
Others
Revenue generated from other patient data hub solutions, including patient identity management, master patient index (MPI), interoperability platforms, health information exchange (HIE), consent management, and healthcare data governance solutions.
Deployment Mode
Revenue Capture Definition
Cloud-based
Revenue generated from subscription- or SaaS-based patient data hub solutions hosted on public, private, or hybrid cloud environments, enabling scalable data integration, interoperability, analytics, and remote access.
On-premise
Revenue generated from patient data hub solutions deployed within an organization's own IT infrastructure, providing greater control over data security, compliance, and system customization.
End Use
Revenue Capture Definition
Healthcare Companies
Revenue generated from pharmaceutical, biotechnology, medical device, and digital health companies using patient data hub solutions for clinical research, real-world evidence generation, pharmacovigilance, and commercial analytics.
Healthcare Providers
Revenue generated from hospitals, health systems, physician practices, clinics, diagnostic laboratories, and ambulatory care centers using patient data hub solutions to improve care coordination, clinical decision-making, and patient outcomes.
Healthcare Payers
Revenue generated from health insurance companies and managed care organizations using patient data hub solutions for claims integration, member data management, population health management, and value-based care initiatives.
Others (Include CRO, CDMO, etc.)
Revenue generated from contract research organizations (CROs), contract development and manufacturing organizations (CDMOs), academic institutions, government agencies, and public health organizations using patient data hub solutions for research, clinical trials, and healthcare data management.
Estimation Model
Number
Category
Heading
Content
1
Top-Down
Commodity Flow Analysis
Market size was estimated by analyzing revenues generated by key geneticology testing service providers and laboratory solution providers, supported by company annual reports, investor presentations, service portfolios, regulatory databases, and premium industry sources. Revenue contributions from private contract research organizations (CROs) and regional laboratories were assessed through secondary research and validated through primary interviews to derive the overall market.
2
Segmentation
Country-Level Segment Share Modeling
Market shares for type, product, application, and technology segments were derived using country-specific pharmaceutical R&D expenditure, regulatory compliance requirements, preclinical testing volumes, CRO outsourcing trends, and biotechnology research activity. Weighted average calculations were applied to determine regional and global segment distributions.
3
Validation
Data Triangulation & Validation Model
Market estimates were validated through triangulation of secondary research, primary interviews, company-level revenue assessments, testing volume analysis, regulatory requirements, and end-user demand evaluation to ensure consistency and accuracy across all market segments and geographies.
4
Forecasting
Forecasting & CAGR Modeling
Market forecasts were developed using historical trends in pharmaceutical and biotechnology R&D, increasing outsourcing of preclinical studies, evolving regulatory guidelines for safety assessment, growth in biologics and advanced therapeutics development, and expansion of CRO services. Regression-based analysis and trend modeling were applied to project future market growth and CAGR.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Pricing Models Analysis
Comprehensive analysis of pricing models for patient data hub solutions, including subscription-based (SaaS), usage-based, or Pay-Per-Interaction, implementation, maintenance, and support service pricing across deployment models and regions.
Supports pricing strategy, revenue forecasting, competitive benchmarking, and evaluation of recurring revenue opportunities.
Company Market Share Analysis
Detailed market share analysis of leading patient data hub solutions providers at the global and regional levels, including revenue contribution, competitive positioning, product portfolio, and strategic initiatives.
Helps identify market leaders, benchmark competitors, assess competitive intensity, and support strategic decision-making.
Regional Opportunity and Trends Analysis
In-depth assessment of regional growth opportunities, digital health adoption, interoperability initiatives, AI implementation trends, healthcare IT investments, and regulatory developments across major regions.
Enables identification of high-growth markets, emerging technology trends, investment opportunities, and region-specific expansion strategies.
Frequently Asked Questions About This Report
The global patient data hub solutions market is expected to grow at a CAGR of 7.5% from 2026 to 2033, reaching USD 3.0 billion by 2033.
North America dominated the patient data hub solutions market with a share of 40.7% in 2025.
Some key players operating in the Patient Data Hub Solutions market include IQVIA, Inc., WellSky, Veeva Systems, Capgemini, Optum (UnitedHealth Group), ZS Associates, Equipo Health Inc., NextGen Healthcare, Informatica, Oracle Health, InterSystems, Innovaccer, Veradigm.
Key factors that are driving the market growth driven by increasing adoption of interoperable healthcare data platforms and digital health infrastructure, growing demand for unified longitudinal patient records to support value-based care, growing demand for centralized patient data management, and rising adoption of cloud, AI, and FHIR-enabled patient data integration solutions.
The health data apps & AI solutions segment held the largest market share of 42.0% in 2025 and data integration solutions segment is second fastest growing market
The cloud-based segment accounted for the largest revenue share of 55.0% in 2025.This is due to the increasing preference for scalable, cost-effective, and easily accessible data management solutions across healthcare organizations.
The hospitals and clinics segment held the largest market share of 65.5% in 2025.
Asia Pacific is the fastest growing region in patient data hub solutions market.
The global patient data hub solutions market size was valued at USD 1.7 billion in 2025 and is estimated at USD 1.8 billion for 2026.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


