
- Home
- »
- Pharmaceuticals
- »
-
Phenylketonuria Treatment Market Size Report, 2026-2033GVR Report cover

Phenylketonuria Treatment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Drug (Kuvan, Palynziq), By Mode of Administration (Oral Administration, Parenteral Administration), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$543.8MMarket Estimate, 2026
$602.9MMarket Forecast, 2033
$1,028.3MCAGR, 2026–2033
7.9%Phenylketonuria Treatment Market Summary
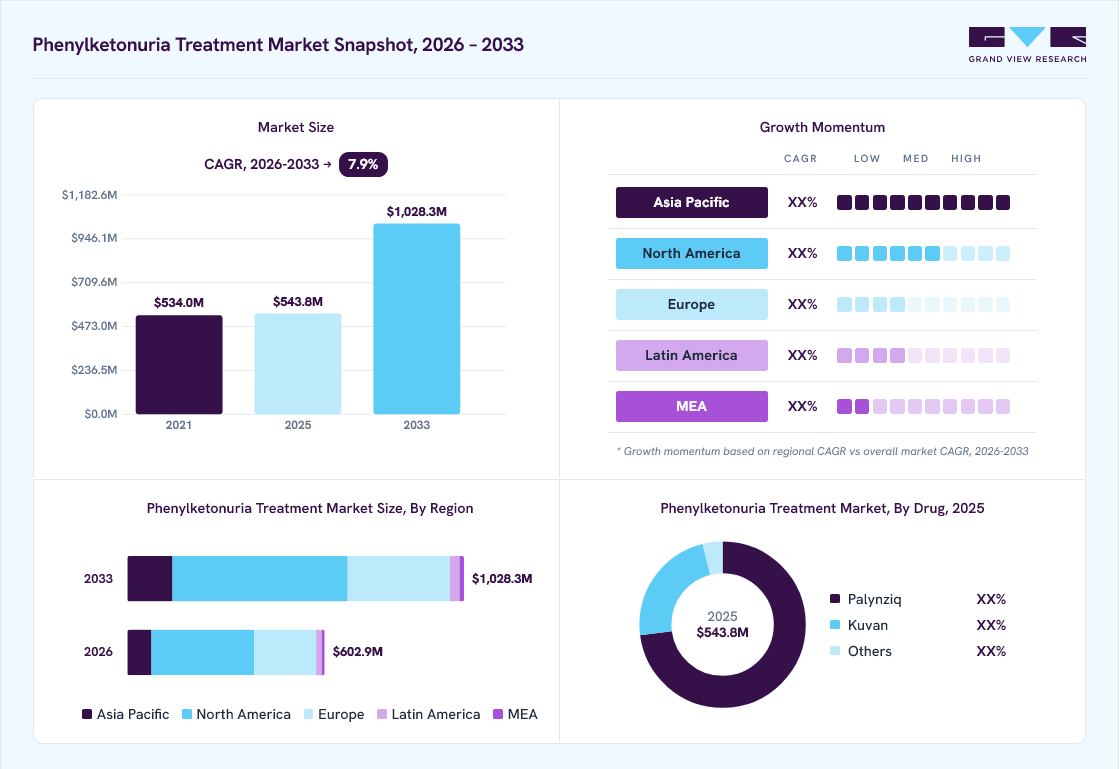
The global phenylketonuria treatment market size was valued at USD 543.8 million in 2025 and is projected to grow from USD 602.9 million in 2026 to USD 1,028.3 million by 2033, at a CAGR of 7.9% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 52.1% in 2025. The market is driven by the increasing prevalence of phenylketonuria and rising healthcare expenditures that boost treatment accessibility.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By drug: Palynziq segment dominated the market, with a revenue share of 72.8% in 2025.
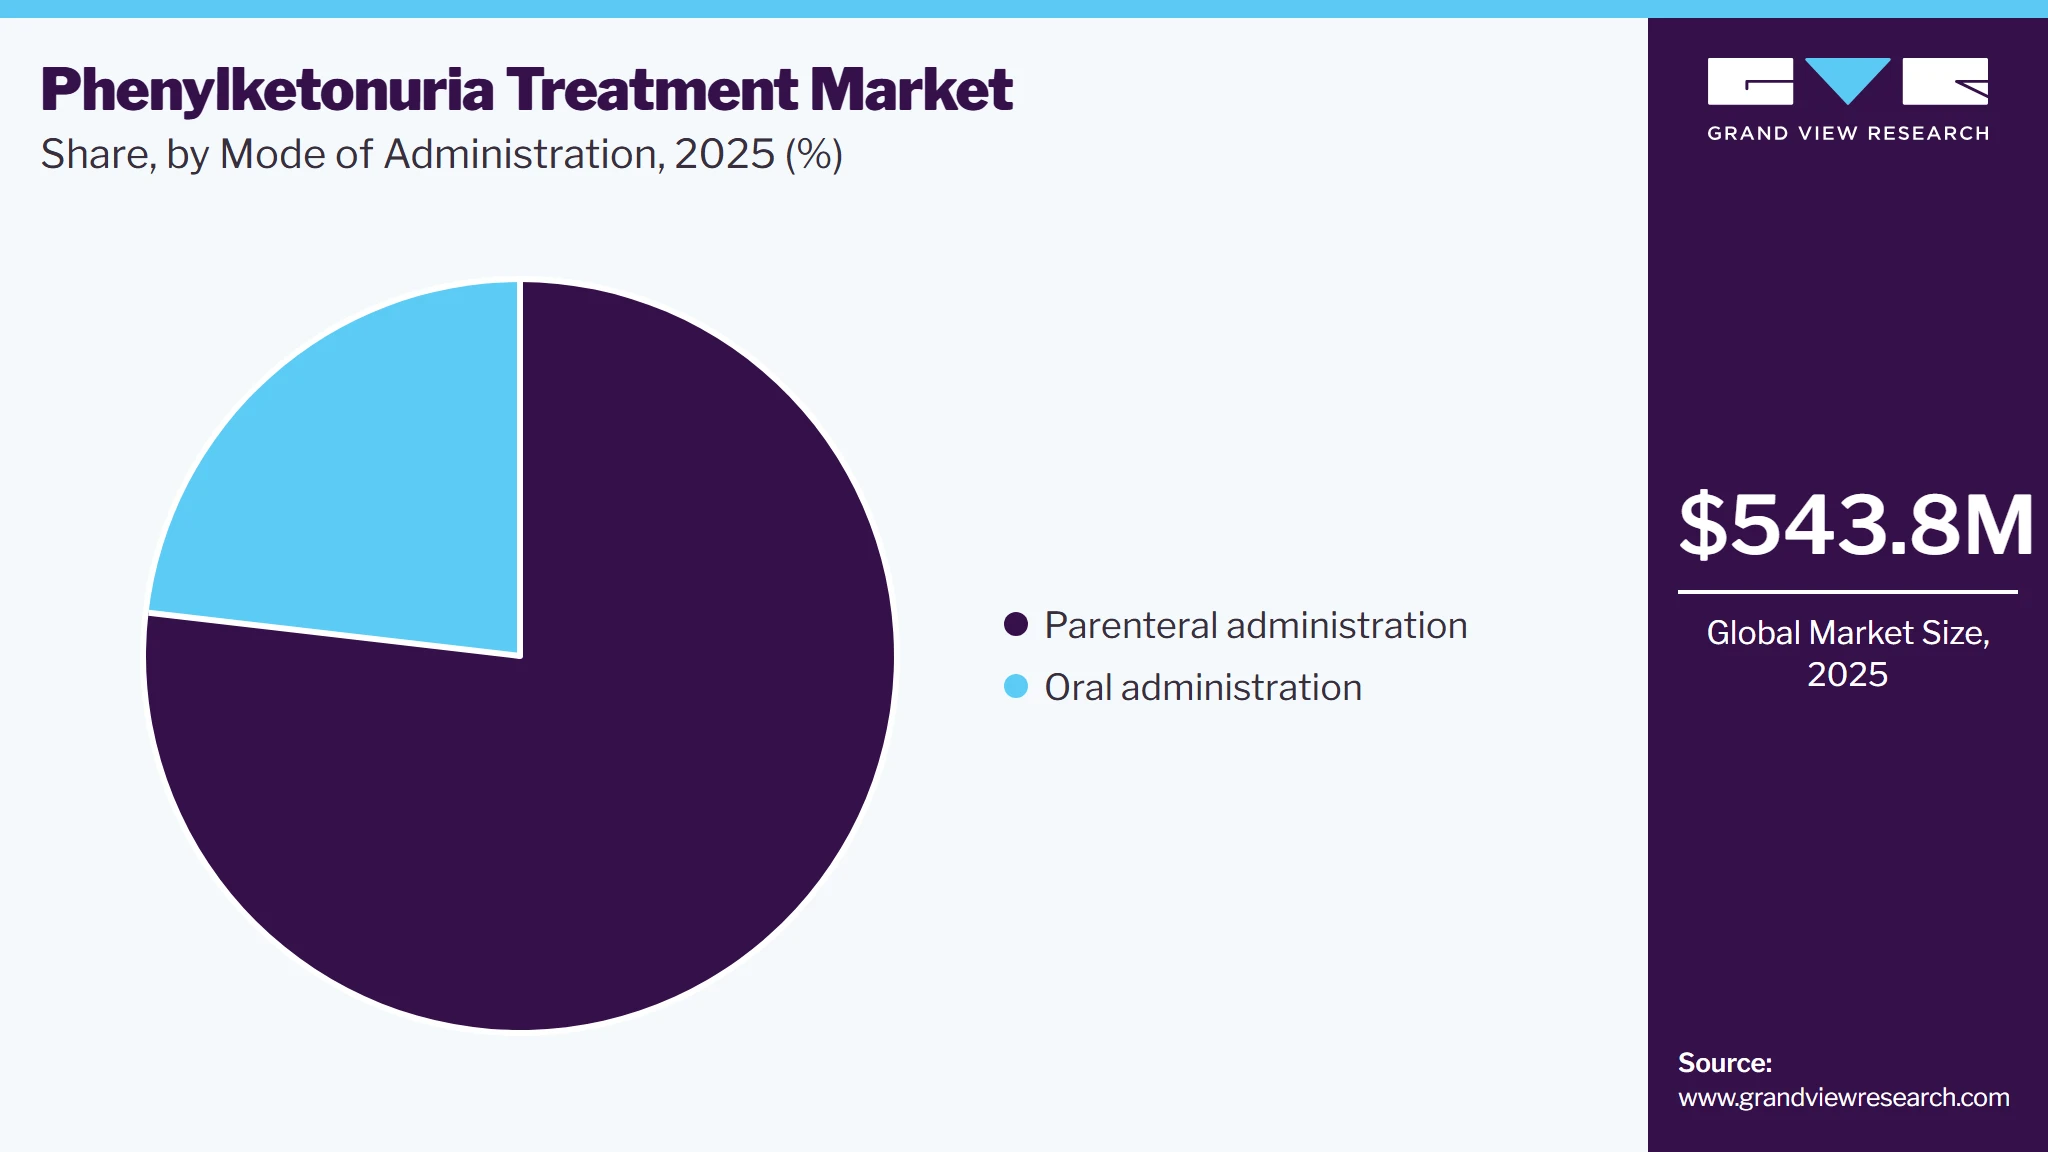
- By mode of administration: Parenteral segment held the largest market share of 76.8% in 2025.
Regional Highlights
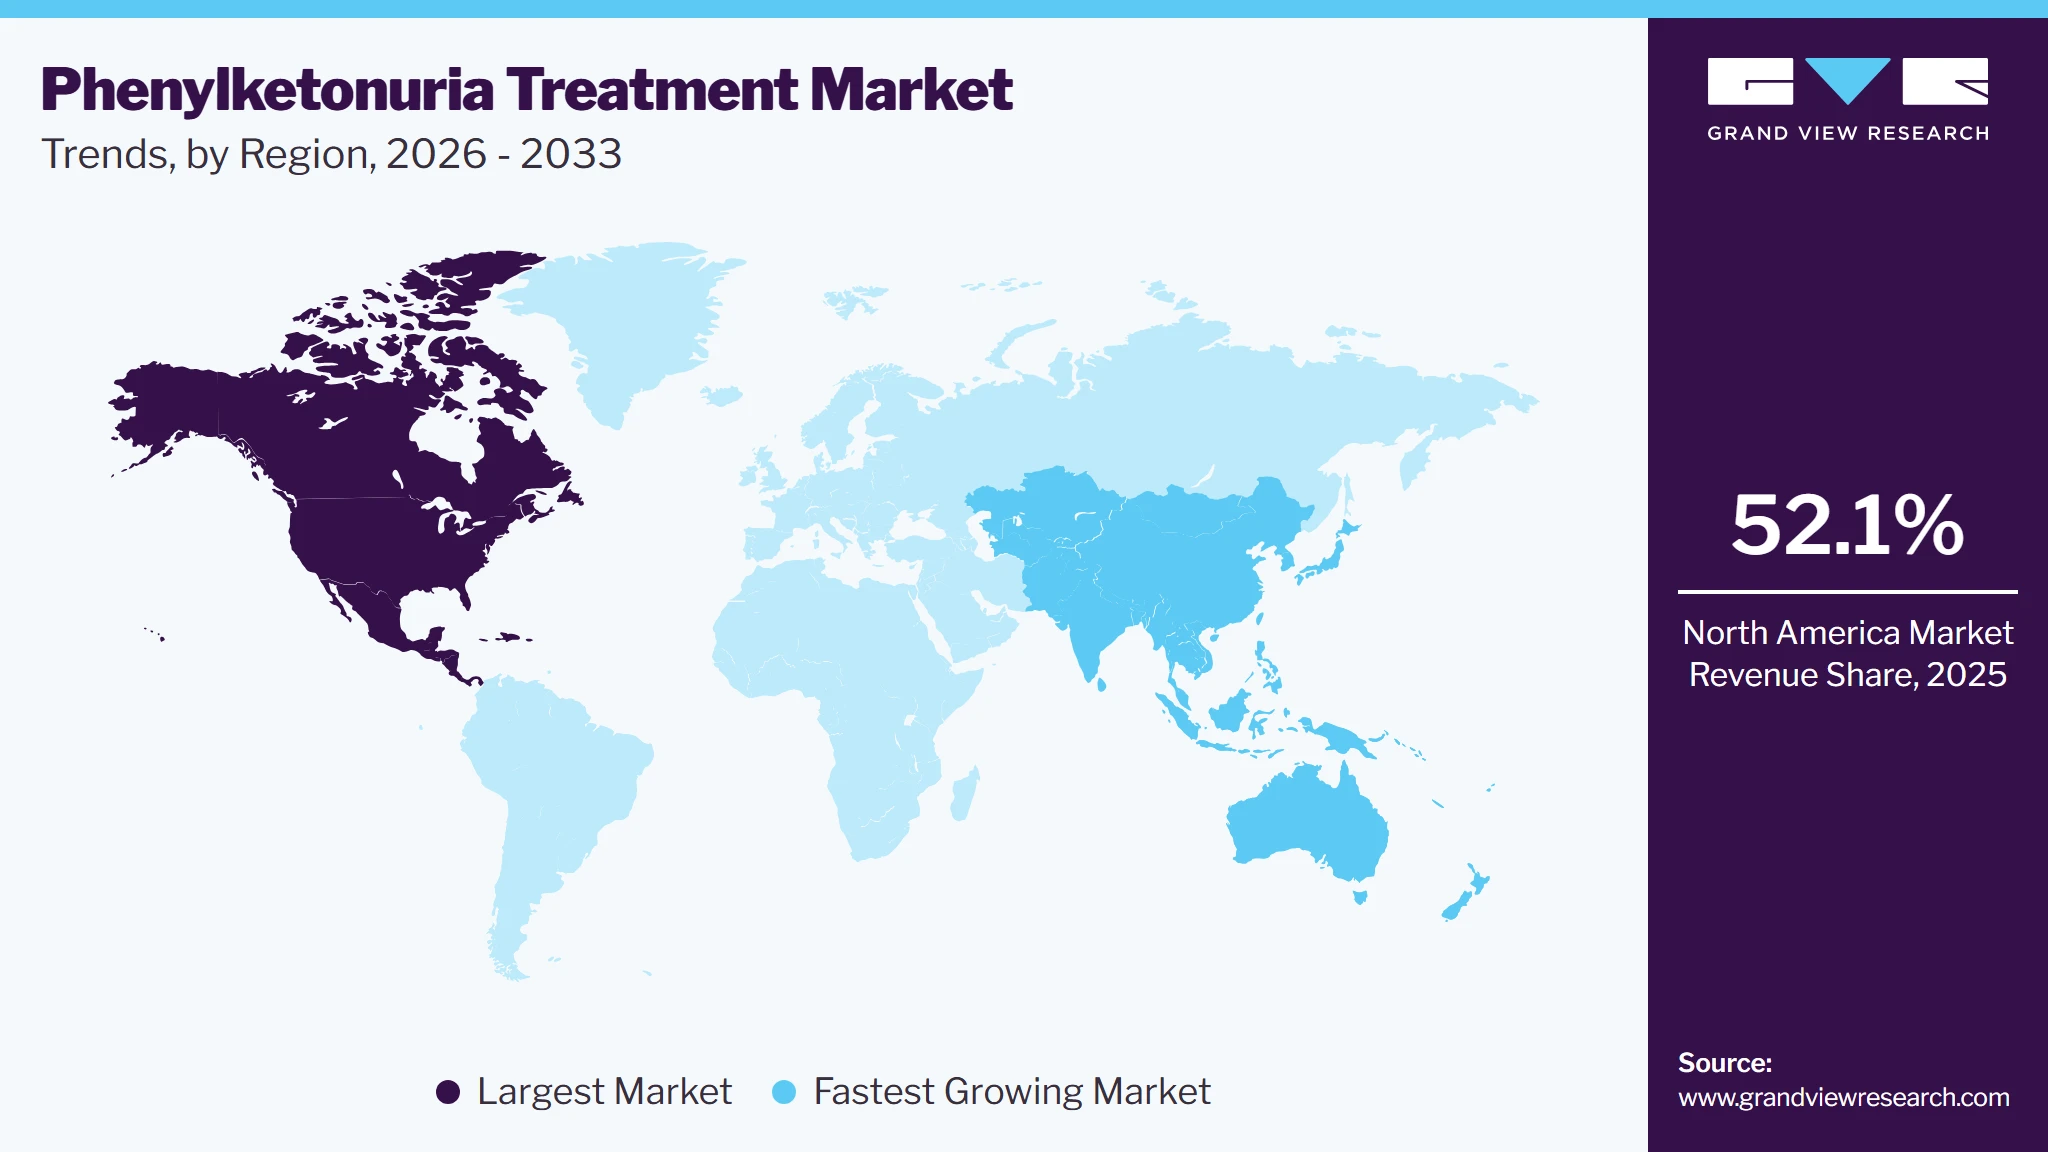
- Largest regional market: North America (52.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 543.8 Million
- Estimated market size in 2026: USD 602.9 Million
- Projected market size by 2033: USD 1,028.3 Million
- CAGR (2026-2033): 7.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
It is further supported by pipeline drugs and growing collaborations among key players to enhance research and development efforts. Rising healthcare expenditures propel the phenylketonuria treatment market by enabling increased access to advanced therapies and improved patient care. Higher investments in healthcare facilitate research, development, and the availability of specialized treatments. For instance, in 2022, U.S. health spending grew by 4.1% to USD 4.5 trillion, matching pre-pandemic growth rates. Pandemic-related government spending fell in 2021, but medical goods and services usage rebounded. Health expenditure was 17.3% of GDP, aligning closely with pre-pandemic levels after spikes in 2020 and 2021.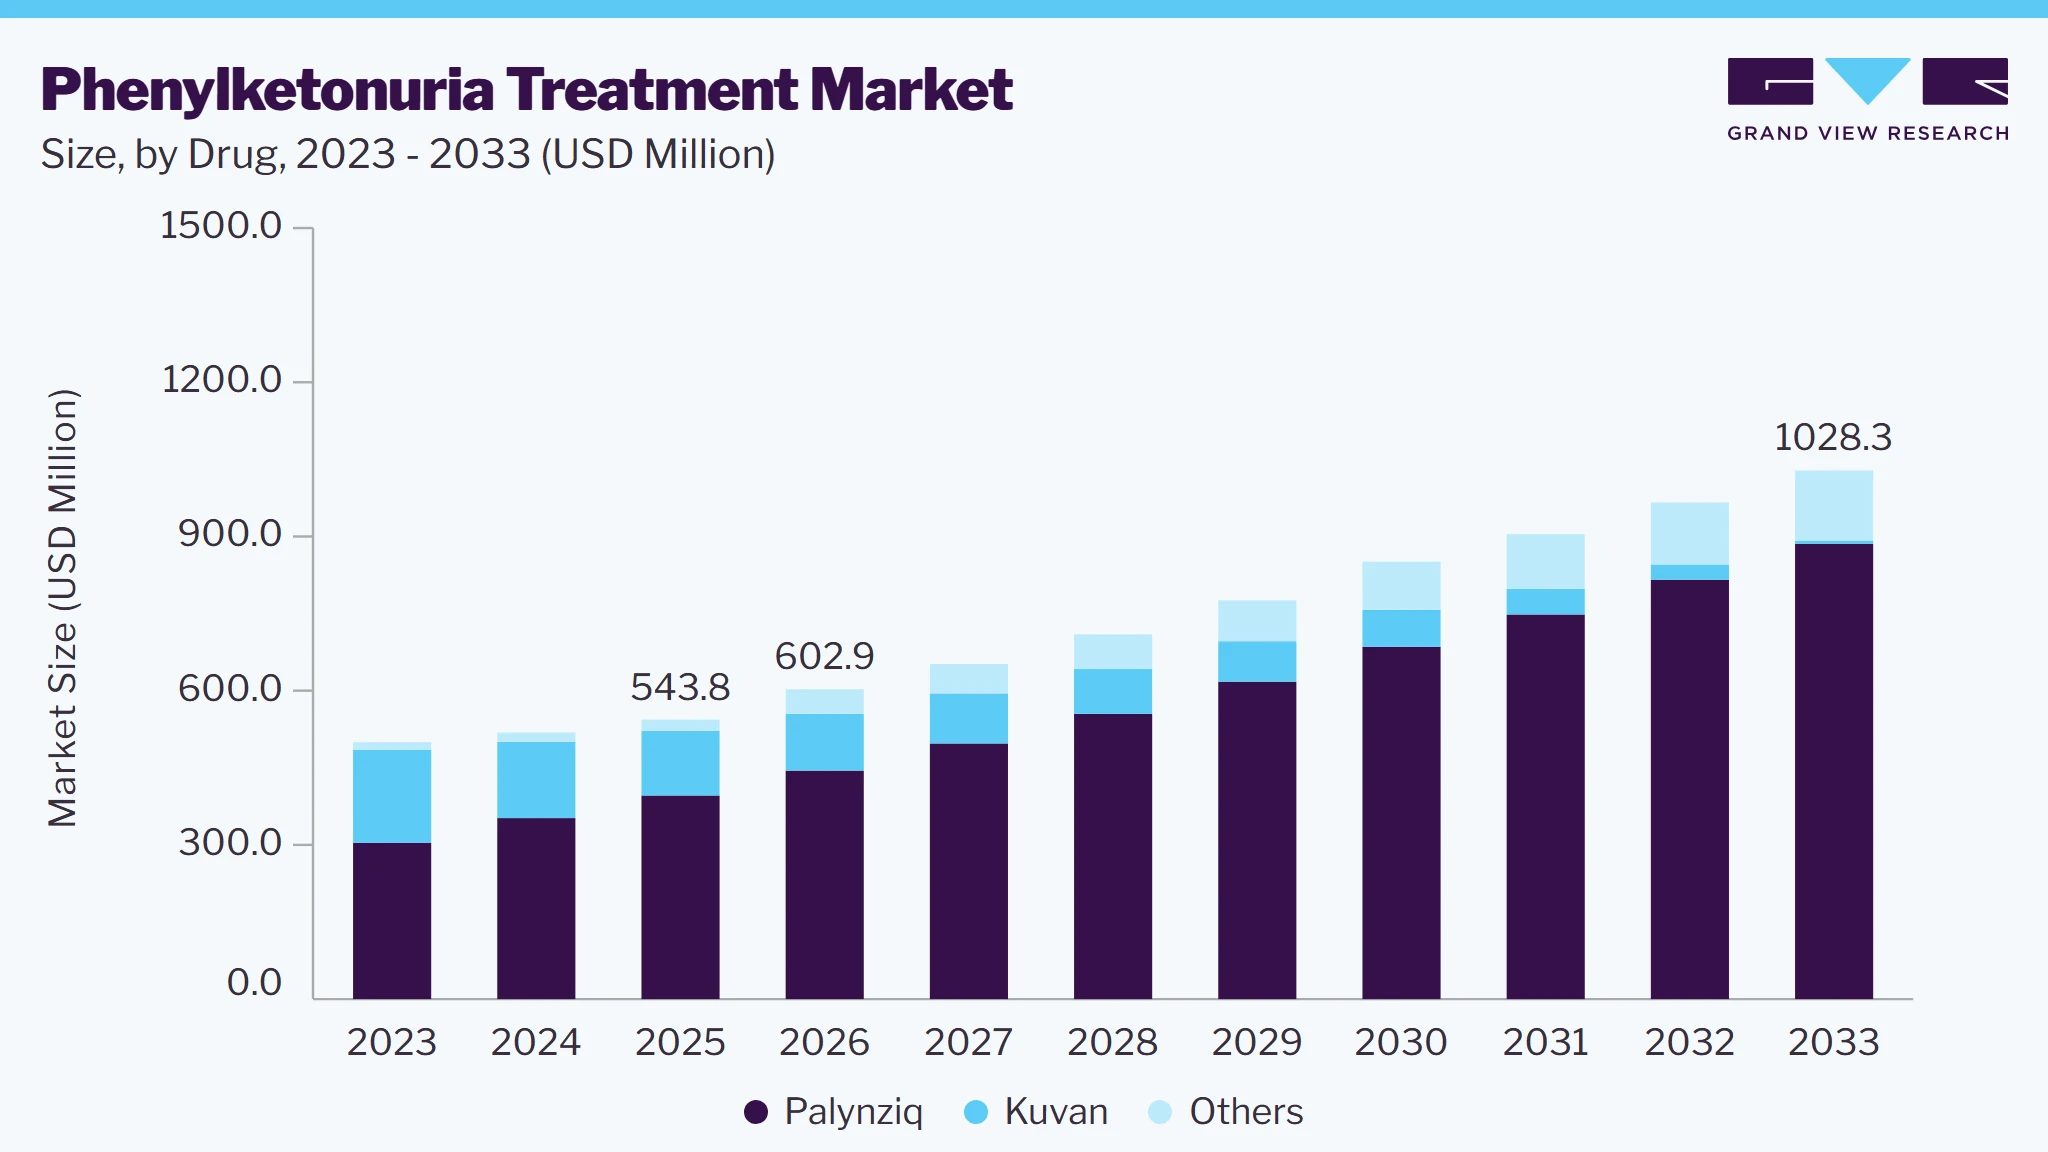 To learn more about this report, Download Free Sample Report
Pipeline drugs and growing collaborations among key players drive the phenylketonuria treatment market by accelerating research and development efforts. These partnerships foster innovation and expedite the introduction of new and effective treatment options. For instance, in March 2024, Eton Pharmaceuticals acquired the U.S. rights to PKU GOLIKE from Relief Therapeutics to treat phenylketonuria (PKU), enhancing its metabolic product line. The acquisition includes taste-masked, extended-release formulas, and rights to future formulations for related conditions. Eton expects this move to boost earnings, with peak annual sales projected to exceed USD 10 million.
Market Dynamics
The phenylketonuria treatment market is witnessing steady development as healthcare systems place greater emphasis on early diagnosis, lifelong disease management, and access to specialized therapies. Phenylketonuria is a rare inherited metabolic disorder that requires continuous control of blood phenylalanine levels to prevent neurological complications. New treatment options are expanding beyond dietary management through enzyme replacement therapy and other targeted approaches, while medical foods and amino acid formulations continue to play an important role in patient care. Regulatory approvals and broader newborn screening programs are supporting earlier treatment initiation and improved clinical outcomes. Pharmaceutical companies are also investing in research to develop therapies that reduce dietary restrictions and improve quality of life for patients. In addition, patient advocacy organizations and rare disease initiatives are increasing awareness of phenylketonuria and encouraging timely diagnosis and treatment. The market continues to benefit from collaboration among healthcare providers, researchers, regulatory agencies, and manufacturers to improve long term disease management and expand treatment availability across different regions.
Driver: Expansion of targeted therapies and continued focus on improving lifelong disease management
The phenylketonuria treatment market is driven by the growing availability of targeted therapies that complement dietary management and improve metabolic control for patients across different age groups. Although a phenylalanine restricted diet remains the foundation of treatment, pharmacological therapies are expanding treatment options for patients who require additional disease control. Continued advances in rare disease research have improved the understanding of the metabolic pathways involved in phenylketonuria, encouraging pharmaceutical companies to invest in therapies that address the underlying enzyme deficiency. Healthcare providers are also adopting more individualized treatment strategies based on patient response, age, and disease severity, supporting better long term outcomes. Newborn screening programs and updated clinical guidelines continue to promote earlier diagnosis and treatment initiation, reducing the risk of irreversible neurological complications. In addition, regulatory incentives for orphan drugs continue to support innovation and accelerate clinical development in rare metabolic disorders. For instance, in April 2025, BioMarin Pharmaceutical Inc. announced positive Phase 3 PEGASUS trial results for PALYNZIQ (pegvaliase pqpz) in adolescents with phenylketonuria. The study demonstrated a statistically significant reduction in blood phenylalanine levels compared with dietary management alone, supporting the expansion of enzyme substitution therapy to younger patients. This development strengthened confidence in targeted therapies and supported continued growth of the treatment market.
The phenylketonuria treatment market continues to face challenges associated with lifelong disease management and unequal access to specialized metabolic care. Patients require continuous monitoring of blood phenylalanine levels, regular consultations with metabolic specialists, and strict adherence to dietary restrictions throughout life. Maintaining these treatment requirements can become difficult during adolescence and adulthood, affecting long term treatment adherence and clinical outcomes. Access to specialized metabolic clinics and experienced dietitians remains limited in several countries, resulting in differences in the quality of patient management. In addition, advanced therapies are not suitable for every patient because treatment eligibility depends on disease characteristics and therapeutic responsiveness. The availability and affordability of medical foods and amino acid formulations also remain a challenge in healthcare systems with limited reimbursement support. Delayed diagnosis in regions where comprehensive newborn screening programs are not fully established further increases the risk of neurological complications before treatment begins. These factors continue to limit broader treatment access despite ongoing progress in therapeutic development. Continued investment in healthcare infrastructure, patient education, and specialized metabolic services will be necessary to improve access and support effective lifelong management of phenylketonuria.The phenylketonuria treatment market presents significant opportunities as regulatory agencies continue to approve new therapies that expand treatment choices for patients with rare metabolic disorders. Pharmaceutical companies are strengthening their development programs to introduce therapies that improve metabolic control while reducing dependence on strict dietary management. Continued advances in precision medicine and enzyme targeted therapies are expected to improve treatment outcomes across broader patient populations. In addition, orphan drug incentives and streamlined regulatory pathways continue to encourage investment in rare disease research, supporting the development of innovative therapies. Increasing awareness of inherited metabolic disorders and expanding newborn screening programs are also expected to improve diagnosis rates and enable earlier treatment initiation. These factors are creating opportunities for broader patient access and continued innovation across major healthcare markets. For instance, in July 2025, PTC Therapeutics, Inc. received United States Food and Drug Administration approval for Sephience (sepiapterin) for the treatment of hyperphenylalaninemia in adults and pediatric patients aged one month and older with sepiapterin responsive phenylketonuria, to be used with a phenylalanine restricted diet. The approval expanded the availability of targeted oral therapy and created opportunities for wider clinical adoption and future geographic expansion.
Analyst Perspective
The phenylketonuria treatment market is evolving from reliance on dietary management toward a broader treatment approach supported by targeted therapies and continued rare disease research. The market remains centered on a limited number of companies with approved therapies and experience in rare metabolic disorders. BioMarin Pharmaceutical Inc. continues to maintain a leading position through its marketed phenylketonuria therapies, while PTC Therapeutics has expanded the treatment landscape with the approval of Sephience. Other pharmaceutical companies are advancing pipeline programs and evaluating new treatment approaches to improve long term disease management. Continued regulatory support for orphan drugs and wider newborn screening programs are supporting steady market development.
Drug Insights
Based on drug, the palynziq segment led the market with the largest revenue share of 72.8% in 2025. Advancements in targeted therapies such as Palynziq that effectively control blood phenylalanine levels are driving the segment's growth. For instance, in May 2023, PTC Therapeutics, Inc. announced a significant development in rare disease treatments, specifically for Phenylketonuria (PKU), a genetic disorder affecting phenylalanine metabolism. The company presented clinical trial results for its investigational drug, PTC923, showing positive outcomes for patients with PKU. These results were promising advancements in PKU treatment, offering a potential oral therapy that could reduce the need for restrictive dietary management, which was the standard of care for PKU patients.
Palynziq can effectively reduce blood phenylalanine levels and maintain long-term control in patients with PKU who have not responded adequately to other treatments. According to the European Medicines Agency (EMA), Palynziq is a phenylketonuria (PKU) treatment that helps break down phenylalanine, a harmful amino acid, using a PEGylated bacterial enzyme called pegvaliase. It has more effect than a placebo in controlling blood phenylalanine levels in patients whose condition was not well-managed with other treatments. Long-term use of Palynziq effectively keeps phenylalanine levels under control for most patients over 18 months.
Mode of Administration Insights
Based on mode of administration, the parenteral segment led the market with the largest revenue share of 76.8% in 2025 and is also expected to grow at the fastest CAGR over the forecast period, attributed to the need for rapid and complete drug absorption to achieve precise therapeutic levels, bypassing gastrointestinal variability and enhancing treatment efficacy. According to the National Center for Biotechnology Information (NCBI), parenteral drugs, especially when given intravenously, have 100% bioavailability, meaning the full dose reaches systemic circulation. This route allows faster absorption and onset of action compared to oral medications, as the drug bypasses the gastrointestinal tract. As a result, parenteral drugs often have a stronger effect due to different metabolic processes.
 To learn more about this report, Download Free Sample Report
The need for rapid, reliable therapeutic effects and limited effective oral treatments drives the segment’s growth. Emerging gene therapies that require parenteral delivery offer long-term solutions. Positive regulatory approvals and reimbursement support enhance market growth. These factors collectively fuel the demand for parenteral routes in managing PKU.
Regional Insights
North America dominated the phenylketonuria treatment market with the largest revenue share of 52.1% in 2025 owing to the rising diagnoses through enhanced newborn screening programs, advances in treatment options such as enzyme replacement and gene therapies, and government initiatives supporting research and early detection. In addition, growing awareness, improvements in genetic testing, and a shift toward personalized medicine contribute to market growth.
 To learn more about this report, Download Free Sample Report
The well-established healthcare infrastructure and funding options facilitate patient treatment access, boosting market expansion. For instance, in June 2023, Synlogic launched a Phase III trial, Synpheny-3, to assess the safety and efficacy of SYNB1934 for treating phenylketonuria (PKU). The study was expected to be conducted at 30 sites across several countries, including the U.S., Germany, and Israel. It involves a multi-part design to evaluate the drug's effects on plasma phenylalanine levels in PKU patients.
U.S. Phenylketonuria Treatment Market Trends
The phenylketonuria treatment market in the U.S. held the largest share in the North America region in 2025 due to the development of innovative therapies that enable better management of phenylalanine levels and support diet liberalization for PKU patients. For instance, in October 2024, PTC Therapeutics, Inc. announced that the FDA accepted the New Drug Application (NDA) for sepiapterin to treat phenylketonuria (PKU) in adult and pediatric patients. The NDA is supported by positive Phase 3 trial results, showing significant reductions in phenylalanine (Phe) levels. The sapropterin may allow diet liberalization for PKU patients by enabling higher protein intake while maintaining Phe control.
Europe Phenylketonuria Treatment Market Trends
The Europe phenylketonuria treatment market was identified as a lucrative region in 2024. European governments provide funding and implement policies to support rare disease treatments such as PKU, enhancing access to therapies and driving innovation. Technological advancements, such as enzyme replacement and gene therapies, improving treatment options and patient outcomes. The growing interest in rare disease treatments, particularly in the orphan drug market, encourages pharmaceutical companies to develop more effective therapies for PKU. For instance, in October 2023, POA Pharma announced its expansion into Austria with the launch of its PKU Easy Microtabs Plus, a treatment for Phenylketonuria (PKU). Following its previous product launches in Germany, the company broadens its European presence in the inborn metabolic disease (IMD) sector. The expansion aims further to enhance the availability of treatments for PKU in Europe.
The UK phenylketonuria treatment market is expected to grow rapidly in the coming years due to the authorities' initiatives to increase patients' access to advanced treatments and ensure equitable care across regions. For instance, in January 2024, the Alliance Party in Northern Ireland welcomed the Department of Health's decision to provide access to Kuvan (sapropterin) for the treatment of PKU patients over 21.
The phenylketonuria treatment market in Germany held a substantial market share in 2024 due to the increasing availability of innovative and convenient treatment options that address unmet patient needs and enhance disease management. For instance, in September 2021, Relief Therapeutics launched a treatment for Phenylketonuria (PKU), the PKU GoLike Krunch, in Germany and Italy. This product was designed to help manage the PKU metabolic disorder by offering a convenient nutritional supplement to address unmet needs in the PKU patient community.
Asia Pacific Phenylketonuria Treatment Market Trends
The Asia Pacific phenylketonuria treatment market is anticipated to grow at a CAGR of 10.8% during the forecast period, attributed to the advancements in diagnostic technologies, enabling early detection and treatment, and proactive government initiatives with healthcare policies that enhance newborn screening and accessibility.
In addition, growing healthcare investments in key countries such as Japan, China, India, and South Korea support better diagnostics and patient care options, boosting market growth. For instance, the decline in Out-of-Pocket expenditure from 64.2% to 39.4% of total health expenditure (2013-2022) indicated a reduced financial burden on individuals. Government health expenditure's share in GDP rose from 1.13% to 1.84%, showing increased public health investment. The rise in government health expenditure's share from 29.0% to 48.0% of total health expenditure highlights enhanced public funding in healthcare.
The Japan phenylketonuria treatment market is expected to grow rapidly in the coming years due to driven by advancements in medical research, including innovative therapies such as enzyme replacement and gene therapy. Government support and funding for rare disease research enhances treatment accessibility. Expanded neonatal screening and awareness programs lead to early diagnosis and better PKU management—collaborations between pharmaceutical companies and research institutions further boost treatment development and commercialization.
The phenylketonuria treatment market in Australia held a substantial market share in 2024 owing to the nationwide newborn screening program and the emphasis on lifelong adherence to a strict, low-protein diet to ensure normal development in diagnosed individuals. For instance, people in Australia are tested for phenylketonuria (PKU) through newborn screening to detect the disorder early, which allows for immediate intervention, such as adopting a strict low-protein diet, which prevents brain damage and developmental issues associated with untreated PKU. This early diagnosis and lifelong dietary management help individuals develop normally, supporting overall health and avoiding severe outcomes such as intellectual disability. This approach benefits Australia by reducing the burden of medical complications and enhancing the quality of life for those diagnosed.
Key Phenylketonuria Treatment Company Insights
Some of the key companies in the phenylketonuria treatment market include BioMarin, Synlogic, Travere Therapeutics, Inc., and others. Organizations are focusing on increasing the customer base to gain a competitive edge in the industry. Therefore, key players are taking several strategic initiatives, such as mergers and acquisitions and partnerships with other major companies.
-
BioMarin is a biotechnology company specializing in developing and commercializing innovative treatments for rare genetic diseases such as Duchenne muscular dystrophy (DMD), achondroplasia, phenylketonuria (PKU), and hemophilia A. The company is focused on breakthrough therapies for serious conditions and has a portfolio that includes clinical and preclinical products.
-
Synlogic is a clinical-stage company developing living medicines for rare and genetic metabolic diseases, including SYNB1618 for phenylketonuria, using its synthetic biology and microbiome platform. It collaborates with pharmaceutical partners to create innovative treatments for various conditions, including liver diseases and cancer.
Key Phenylketonuria Treatment Companies:
The following key companies have been profiled for this study on the phenylketonuria treatment market.
- BioMarin
- Synlogic
- Travere Therapeutics, Inc.
- DAIICHI SANKYO COMPANY, LIMITED.
- Codexis, Inc.
- SOM BIOTECH
- Homology Medicines, Inc. (Q32 Bio Inc.)
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BioMarin Pharmaceutical Inc., Sanofi S.A., Recordati Rare Diseases, Shire Plc, Alexion Pharmaceuticals Inc.)
- Focus on expanding rare disease portfolios through continued product development, regulatory approvals, and entry into additional geographic markets. Work with metabolic treatment centers, healthcare providers, and patient organizations to improve disease awareness, diagnosis, and long term patient management.
- Recognized presence in the rare disease market supported by marketed products, regulatory experience, and relationships with metabolic specialists and healthcare institutions. Well-developed commercial and distribution networks support product availability across major healthcare markets.
- High research and development costs associated with rare disease therapies and long regulatory timelines. Dependence on a relatively small patient population may limit commercial growth and increase development risk.
Recent Developments
-
In August 2024, Otsuka Holdings Co., Ltd. agreed to acquire Jnana Therapeutics Inc., a biotechnology company known for its investigational phenylketonuria (PKU) drug, in a deal valued at up to USD 800 million. This strategic move aims to enhance Otsuka's portfolio of rare metabolic diseases. The acquisition is expected to accelerate the development of Jnana's innovative small-molecule therapeutics targeting solute carrier (SLC) metabolite transporters.
-
In March 2024, Q32 Bio Inc. completed its merger with Homology Medicines, forming a combined company focused on immune system-targeted biologic therapeutics. The merger includes USD 42 million in private placement and around USD 130 million in cash to fund operations through mid-2026. The company's clinical focus involves Phase 2 trials for treatments targeting atopic dermatitis, alopecia areata, and complement system regulation.
Phenylketonuria Treatment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 543.8 million
Estimated market size in 2026
USD 602.9 million
Projected market size by 2033
USD 1,028.3 million
Growth rate
CAGR of 7.9% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Drug, mode of administration, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
BioMarin; Synlogic; Travere Therapeutics, Inc.; DAIICHI SANKYO COMPANY, LIMITED.; Codexis, Inc.; SOM BIOTECH; Homology Medicines, Inc. (Q32 Bio Inc.)
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Phenylketonuria Treatment Market Report Segmentation
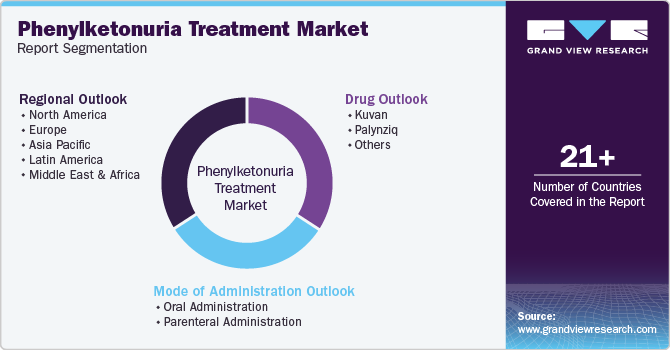
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global phenylketonuria treatment market report based on drug, mode of administration, and region.
 To learn more about this report, Download Free Sample Report
-
Drug Outlook (Revenue, USD Million, 2021 - 2033)
-
Kuvan
-
Palynziq
-
Others
-
-
Mode of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Oral Administration
-
Parenteral Administration
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The phenylketonuria treatment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each phenylketonuria treatment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Drug
Revenue capture definition
Kuvan
Revenue generated from Kuvan (sapropterin dihydrochloride) across all approved phenylketonuria indications and geographic markets. This segment includes all commercial sales of Kuvan irrespective of patient age, treatment duration, or distribution channel. Revenue attributable to Kuvan is reported exclusively within this segment.
Palynziq
Revenue generated from Palynziq (pegvaliase pqpz) across all approved phenylketonuria indications and geographic markets. This segment includes all commercial sales of Palynziq irrespective of patient population, treatment setting, or distribution channel. Revenue is assigned exclusively to this segment.
Others
Revenue generated from all commercially marketed phenylketonuria therapies not separately identified under Kuvan or Palynziq. This includes newly approved branded therapies, marketed formulations introduced during the forecast period, and future commercial product launches. Revenue is allocated to this segment only when it does not belong to the predefined product categories above.
Segment - Mode of Administration
Revenue capture definition
Oral Administration
Revenue generated from phenylketonuria treatments formulated for oral administration. This segment includes tablets, capsules, powders, granules, oral solutions, oral suspensions, and other commercially marketed oral formulations. Revenue is attributed exclusively to products administered through the oral route irrespective of product brand or manufacturer.
Parenteral Administration
Revenue generated from phenylketonuria treatments formulated for parenteral administration. This segment includes commercially marketed injectable formulations administered through approved parenteral routes. Revenue from all injectable phenylketonuria therapies is assigned exclusively to this segment irrespective of product brand, manufacturer, or healthcare setting.
Estimation Model
 To learn more about this report, Download Free Sample Report
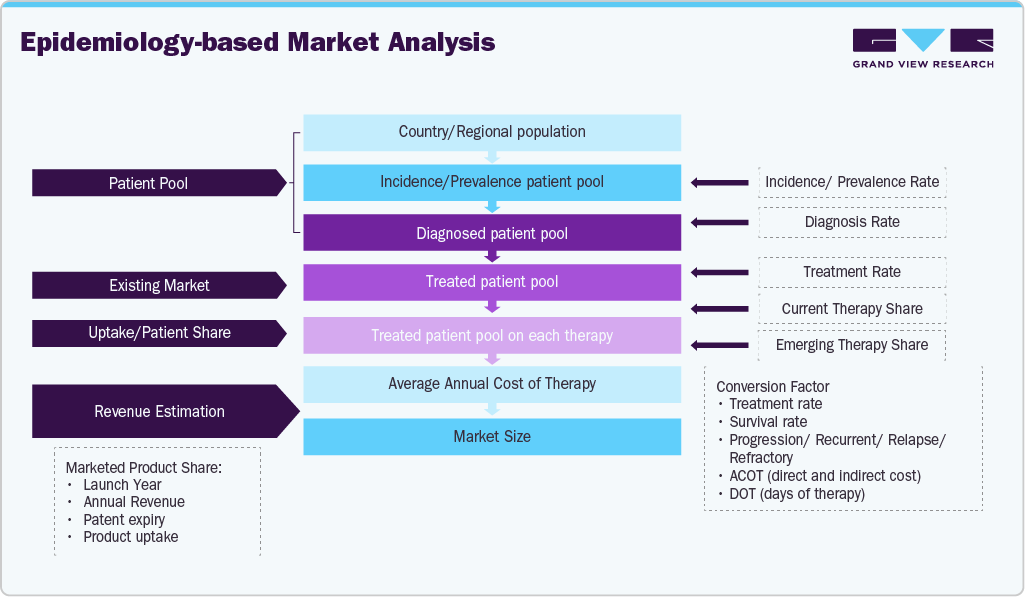
The study adopted an epidemiology based market analysis approach to estimate the size of the global phenylketonuria treatment market. Country level population data were evaluated to estimate the prevalence of phenylketonuria, followed by assessment of diagnosed and treated patient populations using newborn screening statistics, rare disease registries, published literature, and government health databases. Treatment rates were analyzed across available therapies, including Kuvan, Palynziq, and other marketed products, considering patient eligibility, prescribing patterns, and clinical practice guidelines. Average annual treatment costs were estimated using publicly available pricing information, reimbursement data, company disclosures, and healthcare publications. Market estimates were validated through primary interviews with metabolic specialists, pediatric endocrinologists, hospital pharmacists, and industry participants. Final market size calculations incorporated therapy uptake, regional treatment access, regulatory approvals, and country specific reimbursement scenarios to ensure accurate and consistent market estimation.
Customization Table
Client Request
Customization Delivered
Value Added
Phenylketonuria Treatment Competitive Landscape & Pipeline Assessment
Conducted a comprehensive analysis of the PKU treatment pipeline, including competitive benchmarking of leading companies, drug development strategies, clinical trial progress, and regulatory approvals. The study evaluated innovative therapies such as enzyme substitution, gene therapy, and small molecule drugs.
Helps stakeholders understand the competitive landscape, track pipeline developments, identify emerging therapies, and assess potential market entrants for strategic decision-making.
Phenylketonuria Treatment Benchmarking Study
Delivered a benchmarking study comparing PKU treatment approaches across geographies, patient demographics, and healthcare systems. The analysis included dietary management, medical food adoption, pharmacological therapies, and reimbursement frameworks.
Provides insights into best practices, treatment adoption trends, and regional differences. Supports healthcare providers and policymakers in improving patient outcomes and optimizing treatment strategies.
Phenylketonuria Treatment Market Access & Commercial Assessment
Developed a market access evaluation covering pricing strategies, reimbursement policies, payer perspectives, and commercial adoption challenges. The study assessed barriers to entry, patient affordability, and long-term sustainability of PKU therapies.
Supports pharmaceutical companies in designing effective market entry strategies, improving patient access, and maximizing commercial success in the PKU treatment market.
Frequently Asked Questions About This Report
The global phenylketonuria treatment market size was valued at USD 543.8 million in 2025 and is estimated at USD 602.9 million for 2026.
The global phenylketonuria treatment market is expected to grow at a CAGR of 7.9% from 2026 to 2033, reaching USD 1,028.3 million by 2033.
The Palynziq segment accounted for the largest market share, representing 72.8% of the global revenue in 2025.Advancements in targeted therapies such as Palynziq that effectively control blood phenylalanine levels are driving the segment's growth.
Key players include BioMarin Pharmaceutical Inc., Synlogic, Travere Therapeutics, Inc., DAIICHI SANKYO COMPANY, LIMITED., Codexis, Inc., SOM BIOTECH, Homology Medicines, Inc. (Q32 Bio Inc.), PTC Therapeutics, Sanofi S.A., Recordati Rare Diseases, Shire Plc, and Alexion Pharmaceuticals Inc.
Key factors include expanding availability of targeted therapies, increasing newborn screening programs, growing regulatory support for orphan drugs, continued investment in rare disease research, and rising focus on improving lifelong disease management.
North America dominated the phenylketonuria treatment market with a 52.1% revenue share in 2025.
Asia Pacific is expected to be the fastest-growing regional market during the forecast period.
The parenteral segment dominated the market, accounting for 76.8% of the revenue share in 2025, driven by the widespread use of injectable therapies.
Major opportunities include increasing regulatory approvals for innovative therapies, expanding precision medicine, development of enzyme-targeted treatments, broader newborn screening programs, and improving access to rare disease therapies across emerging markets.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


