
- Home
- »
- Plastics, Polymers & Resins
- »
-
Polyurea Market Size, Share And Growth Report, 2026-2033GVR Report cover

Polyurea Market (2026 - 2033)
Size, Share & Trends Analysis Report By Raw Material (Aromatic, Aliphatic), By Product (Coating, Lining, Adhesives & Sealants), By Application (Construction, Industrial, Transportation), By Region, And Segment Forecasts
Market Size, 2025
$996.8MMarket Estimate, 2026
$1,054.2MMarket Forecast, 2033
$1,731.8MCAGR, 2026–2033
7.3%Polyurea Market Summary
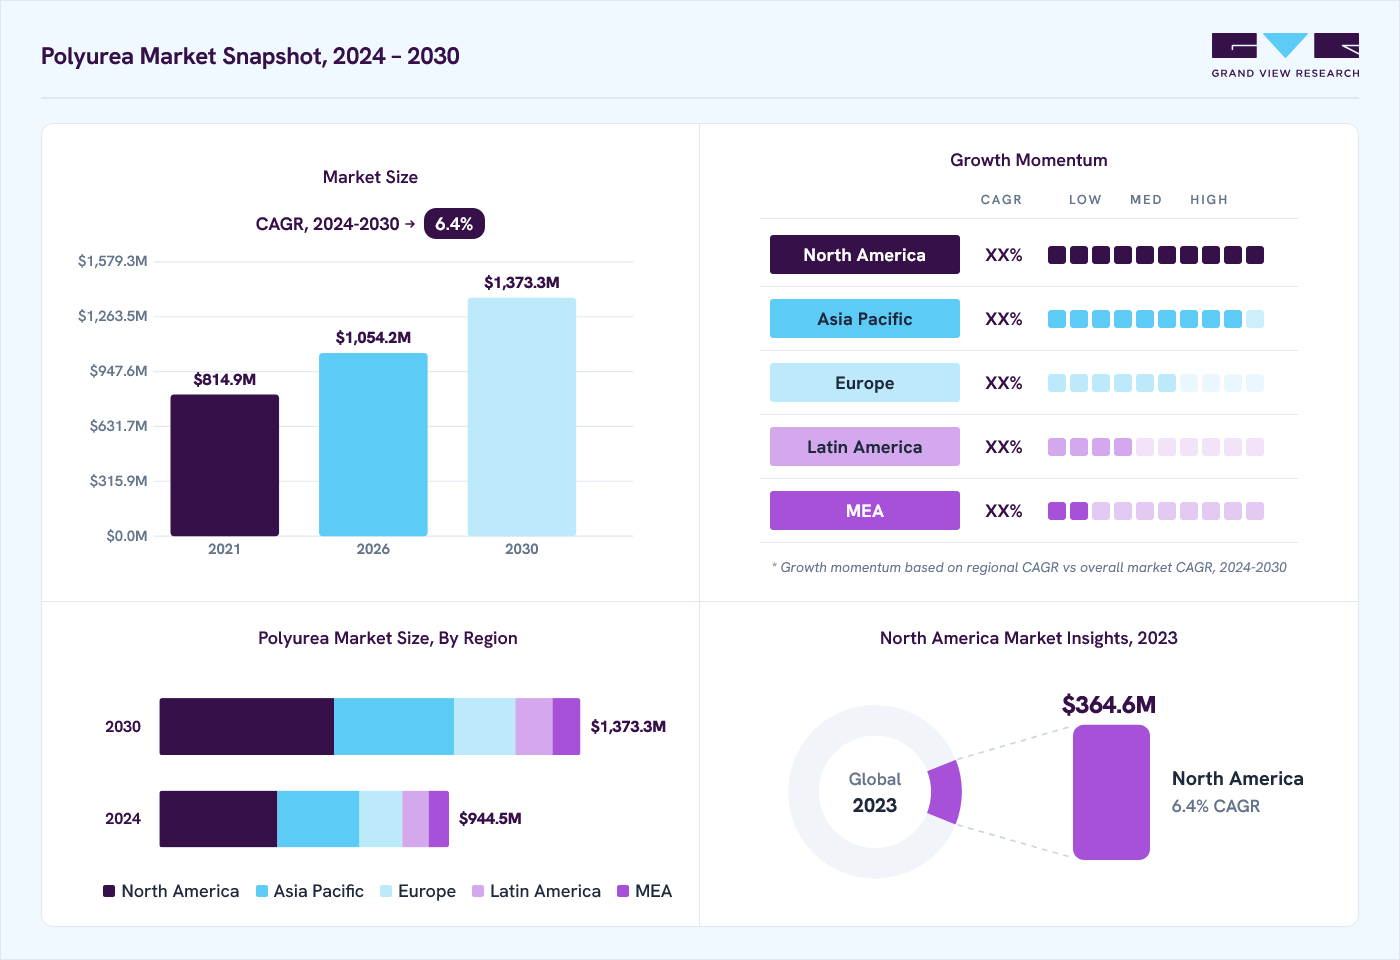
The global polyurea market size was valued at USD 996.8 million in 2025 and is projected to grow from USD 1,054.2 million in 2026 to USD 1,731.8 million by 2033, at a CAGR of 7.3% from 2026 to 2033. The market in North America dominated with a revenue share of 40.9% in 2025. The market growth is being fueled by the use of polyurea in many construction applications, including containment liners, waterproofing membranes, and flooring systems.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By raw material: Aromatic segment held the largest market share of 67.2% in 2025.
- By product: Coating segment held the largest market share of 66.5% in 2025.
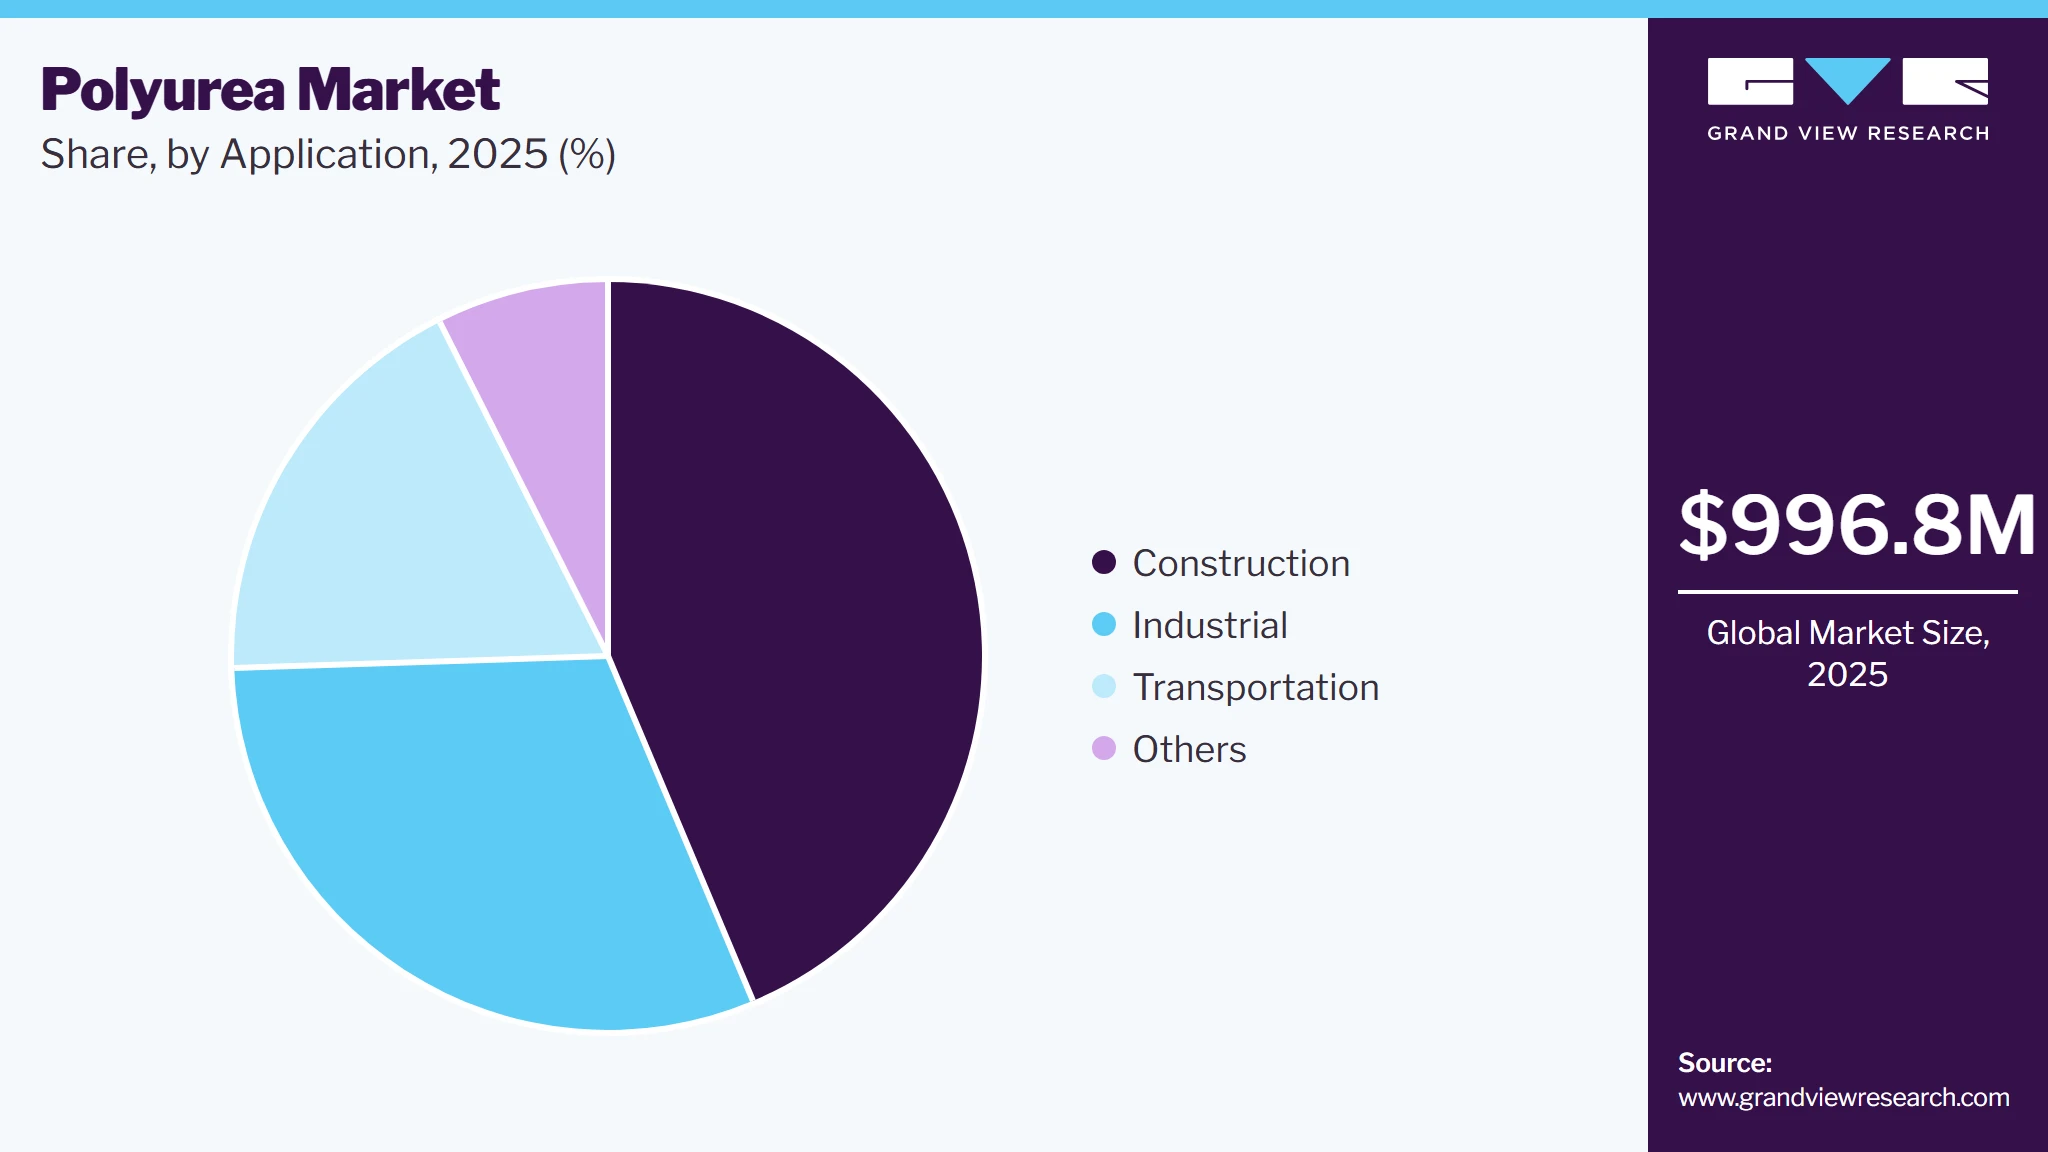
- By application: Construction segment held the largest market share of 43.7% in 2025.
Regional Highlights
- Largest regional market: North America (40.9% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 996.8 Million
- Estimated market size in 2026: USD 1,054.2 Million
- Projected market size by 2033: USD 1,731.8 Million
- CAGR (2026-2033): 7.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Polyurea coatings offer high corrosion protection standards, abrasion resistance, waterproofing, chemical and atmospheric resistance, and structural enhancement. Moreover, these products exhibit superior characteristics in spray applications, such as high thermal, mechanical, & chemical resistance, short setting & curing time, absence of solvents, hydrolysis stability, water insensitivity, and a high degree of adherence as compared to their substitutes. The expansion of these end-use industries is expected to propel the growth of the coatings market over the forecast period.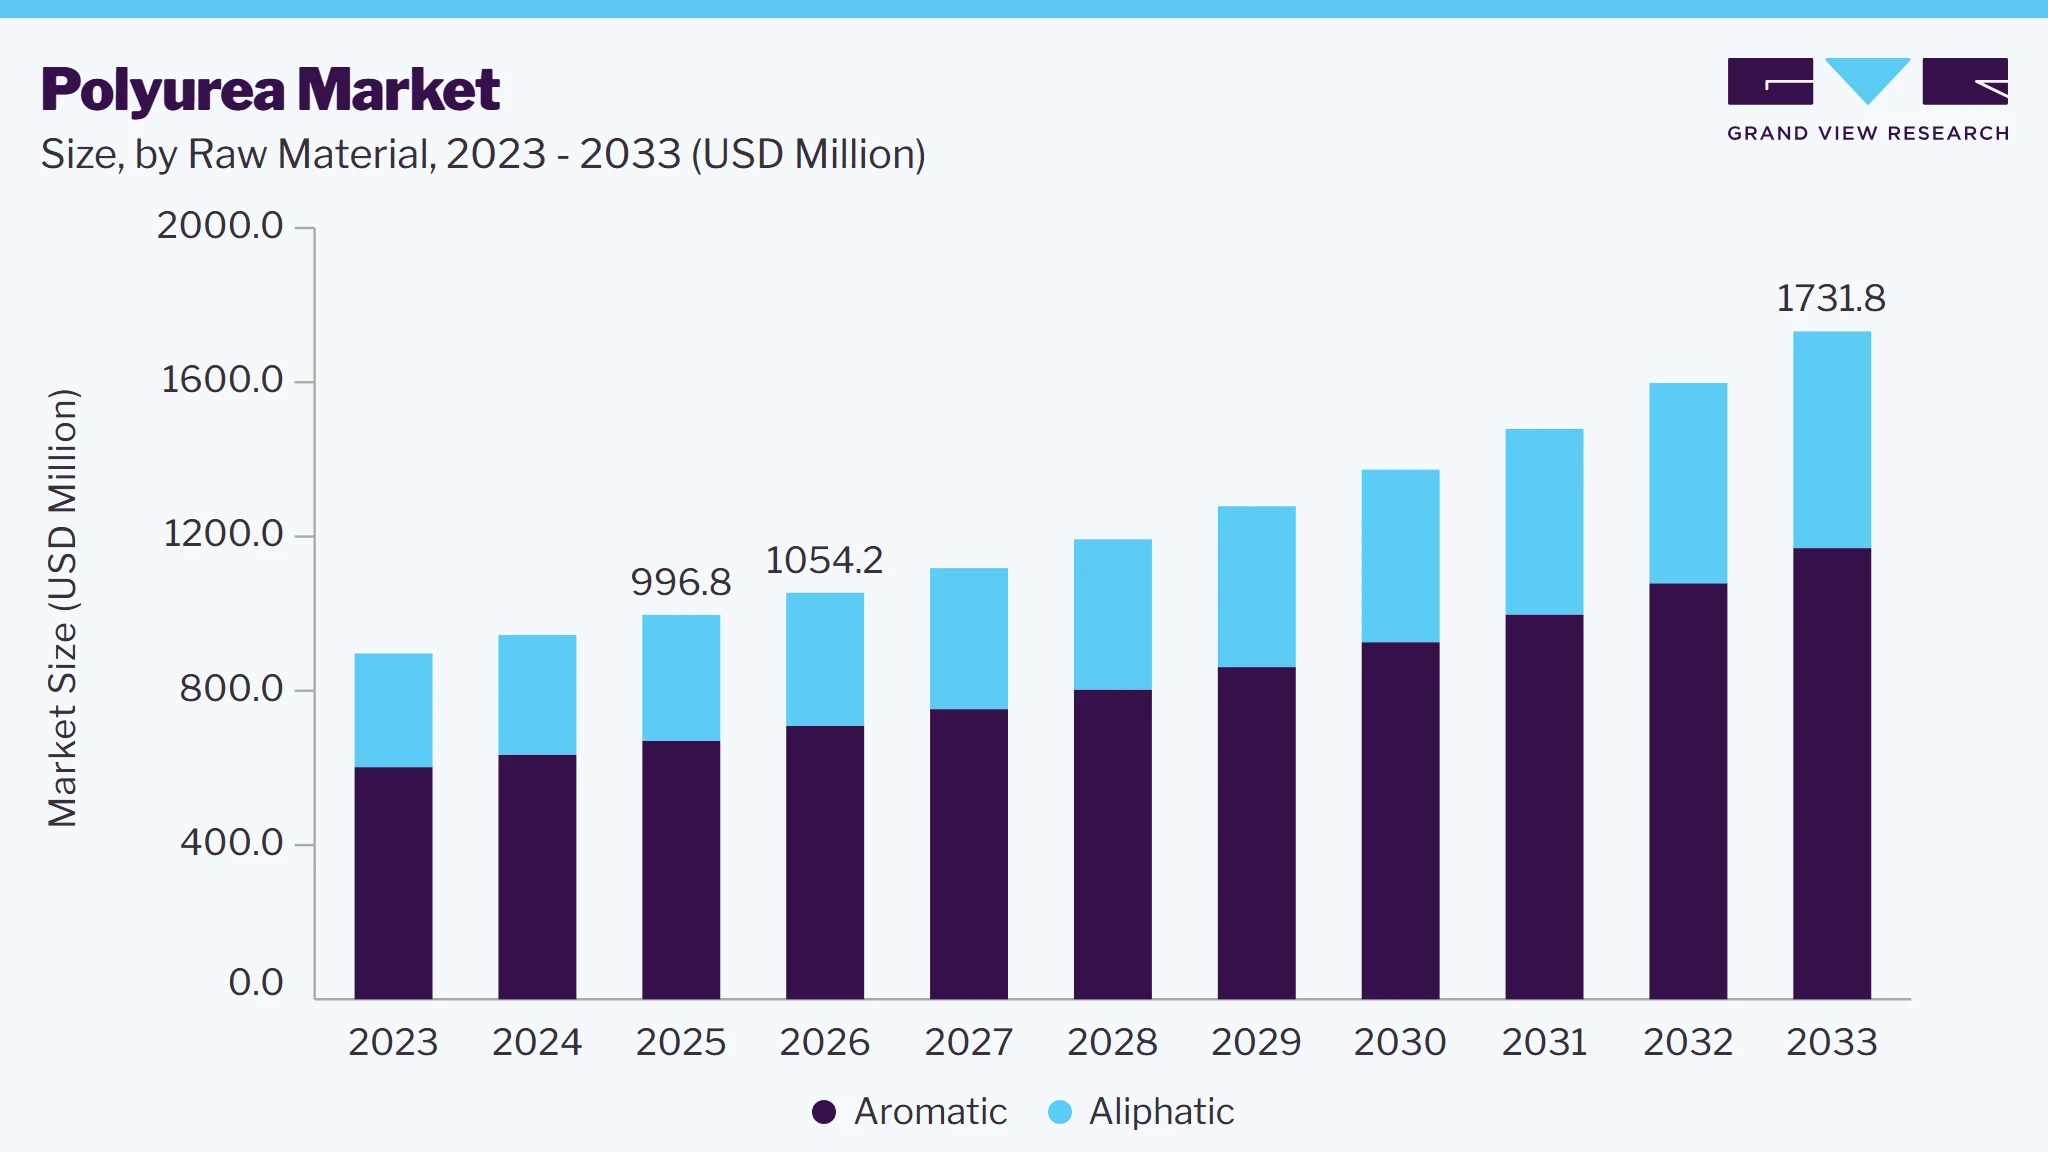 To learn more about this report, Download Free Sample Report
To cater to the increasing growth in the automotive industry, polyurea plastics are being utilized for providing rust prevention and UV resistance. Polyurea is increasingly being used to substitute metal fasteners in automobiles to reduce overall car weight by around 15%, leading to a reduction in carbon emissions. The aforementioned trends are expected to promote the application of polyurea in the automotive and construction industries.
Increasing requirements for coating solutions with specifications, such as enhanced service life, improved corrosion resistance, and good thermal stability on account of the rising importance of condition-based monitoring over breakdown maintenance in manufacturing industries is expected to fuel market growth.
Market Dynamics
Polyurea coatings are increasingly moving beyond heavy-duty industrial protection systems into thinner, rapid-deployment solutions as asset owners prioritize faster maintenance and reduced downtime. Demand from infrastructure rehabilitation, parking decks, wastewater facilities, and waterproofing applications is driving preference for polyurea due to its ultra-fast curing, crack-bridging performance, and long-term resistance to abrasion and chemicals. Spray-applied low-build formulations, polyurea hybrid technologies, and user-friendly cartridge systems are gaining traction because they simplify installation while preserving durability and flexibility. This transition is positioning polyurea from a specialized protective coating into a mainstream asset preservation material for lifecycle extension and infrastructure resilience projects.
The polyurea market is being driven by increasing demand for durable, fast-curing, and high-performance protective coating systems across construction and infrastructure. Polyurea coatings are widely preferred due to their excellent abrasion resistance, waterproofing performance, chemical resistance, and long service life. Their ability to cure rapidly under varying environmental conditions makes them suitable for large-scale infrastructure projects and critical asset protection applications. Growing investments in infrastructure refurbishment across developed economies and expanding commercial construction activity are further supporting market growth.
Construction and infrastructure applications remain key demand drivers for the market. Polyurea is extensively used in bridge deck waterproofing, tunnel linings, roofing systems, containment structures, and heavy-duty industrial flooring due to its seamless protection and superior durability. Rising residential development, increasing construction of offices and data centers, and growing adoption of green and smart buildings are accelerating product demand. In addition, stringent hygiene and safety regulations in pharmaceutical and food and beverage facilities are driving the use of seamless, chemical-resistant, and easy-to-maintain flooring and containment solutions.
One of the key restraints on the polyurea market is the high cost of specialty raw materials and precision manufacturing processes. Polyimide film production requires advanced polymer synthesis technologies, controlled processing environments, and high-temperature treatment systems to achieve required performance specifications. These factors significantly increase production costs compared with conventional polymer films, limiting adoption in cost-sensitive applications.
The expanding need for durable waterproofing and containment systems is creating significant growth opportunities for polyurea coatings. Rising investments in commercial buildings, industrial facilities, water storage infrastructure, and wastewater treatment projects are increasing demand for high-performance protective materials. Polyurea provides seamless application, rapid curing, strong chemical resistance, and long-term impermeability, making it highly suitable for roofs, foundations, tanks, and containment structures.
Market Concentration & Characteristics
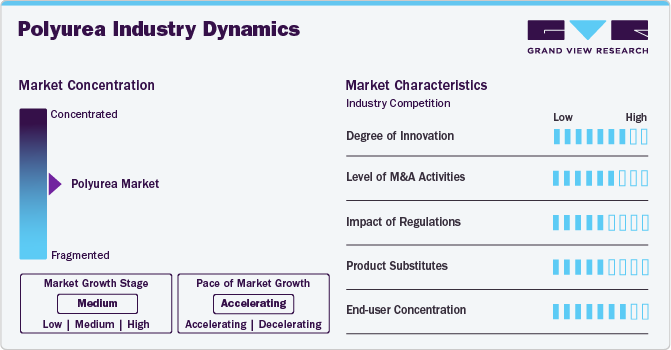
The polyurea market is moderately consolidated in nature BASF; W.R. Grace; SWD Polyurethane; Specialty Products Inc.; LINE-X Protective Coatings; Nukote Coating Systems International; VersaFlex Inc. Nukote Coating Systems, and PPG Industries, which dominate a significant market share. These companies often engage in aggressive marketing strategies, R&D initiatives, and M&As to strengthen their market position and expand their product offerings.
In the polyurea market, there are several product substitutes that cater to similar applications. Polyurethane coatings and epoxy coatings are prominent alternatives offering comparable protective qualities and versatility in applications, such as waterproofing, corrosion protection, and industrial coatings. Polyurethanes are valued for their flexibility and chemical resistance, while epoxies are known for their high adhesion and durability. In addition, acrylic coatings are another substitute known for their weather resistance and aesthetic appeal in architectural and automotive applications.
 To learn more about this report, Download Free Sample Report
The polyurea market is characterized by a significant end-use concentration showcasing a substantial presence in construction, automotive, and industrial applications. In construction, polyurea coatings are extensively used for waterproofing and protecting concrete structures due to their rapid curing time and durability. The automotive sector utilizes polyurea for protective coatings on vehicles and components to enhance resistance against wear, chemicals, and UV exposure. In industrial settings, polyurea is favored for its versatility in corrosion protection, containment linings, and flooring applications.
Analyst Perspective
The polyurea market is evolving from volume-driven to value-driven growth, fueled by demand for high-performance, durable, and cost-effective solutions across construction, transportation, manufacturing, oil and gas, water treatment, and renewable energy. Advances in spray technology, hybrid formulations, bio-based materials, and low-emission products are creating new opportunities while meeting environmental standards. Future growth will depend on innovation, technical expertise, strong distribution, and collaboration with contractors and end users. Despite challenges such as raw material price volatility, supply chain risks, and pricing pressure, companies offering sustainable, customized, and high-performance solutions are expected to achieve long-term growth and profitability.
Raw Material Insights
Based on raw material, the aromatic segment led the market with the largest revenue share of 67.2% in 2025. These raw materials provide good physical properties and easy processability. Hence, aromatic systems are coated with aliphatic topcoats for desired color stability on exposure to UV light. Because they exhibit excellent flexibility characteristics, aromatics-based polyurea compounds are expected to find applications in the construction and manufacturing sectors in developed countries, including Germany, the UK, and Spain.
Factors, such as suitable demographics for production and a rise in population, are expected to drive the product demand in the construction industry. Polyurea is used for vacuum construction, pipes, and fittings due to its excellent mechanical strength and low weight. Products made using polyurea are corrosion-resistant and more durable than polyvinyl chloride (PVC), and they are used to manufacture waste collector products. These advantageous properties are anticipated to augment demand for aromatic compounds in the polyurea market.
Product Insights
Based on product, the coating segment led the market with the largest revenue share of 66.5% in 2025. The rising importance of coatings as a surface protection medium in the automotive, aerospace, civil construction, oil & gas sectors is anticipated to positively impact the polyurea industry. However, the high market visibility of other coating formulations, including acrylic, epoxy, and polyurethane, is expected to restrict polyurea application.
In addition, increasing construction spending in China and India owing to regulatory support aimed at infrastructure improvement at a domestic level is expected to fuel polyurea demand. Furthermore, the strong presence of automotive manufacturing units in the U.S. and Mexico is expected to fuel the demand for polyurea coatings.
The lining segment is expected to witness significant growth over the forecast period. This growth is driven primarily by its exceptional properties, which make it ideal for various industrial applications. Polyurea linings are valued for their rapid curing time, which minimizes downtime during installation, which is crucial for industries where operational continuity is paramount. These linings offer superior chemical resistance, durability, and flexibility, making them suitable for containment applications such as tanks, pipelines, and secondary containment systems.
Application Insights
Based on application, the construction segment led the market with the largest revenue share of 43.7% in 2025. This can be attributed to the increasing investments in infrastructural activities in developing economies such as the Asia Pacific and Middle East & Africa regions. Polyurea coatings are highly valued in construction for their fast curing times, which allow for quick project turnaround and reduced downtime. They offer exceptional durability and flexibility, making them ideal for waterproofing applications on roofs, parking decks, and building exteriors. Their ability to adhere to various substrates, including concrete, metal, and wood, makes them versatile for new construction and renovation projects.
 To learn more about this report, Download Free Sample Report
The industrial segment is poised to witness significant growth over the forecast period, owing to the rapid industrialization in emerging economies and growing exports by well-developed countries. Polyurea coatings are highly sought after in industries such as oil and gas, mining, and manufacturing due to their superior chemical resistance, durability, and ability to withstand extreme conditions. These coatings offer adequate protection against corrosion, abrasion, and impact damage, prolonging the lifespan of equipment, storage tanks, and infrastructure.
Regional Insights
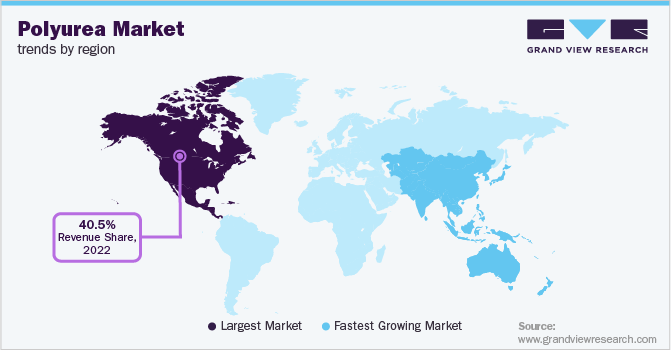
North America dominated the polyurea market with the largest revenue share of 40.9% in 2025. Expansions in the shale gas industry of the U.S. and Canada, on account of increasing expenditure on hydraulic fracturing, are expected to fuel polyurea demand as coatings and lining systems over the forecast period. Sluggish growth in the manufacturing sectors of developed countries including Canada and Mexico, on account of increasing utility expenditure, is expected to reduce product consumption in the form of sealants and coatings.
 To learn more about this report, Download Free Sample Report
U.S. Polyurea Market Trends
The polyurea market in the U.S. accounted for the largest market revenue share in North America in 2025. Increasing construction activities for residential purposes in the U.S. is expected to have a positive impact on the coatings market over the forecast period. Recovery after the great recession in 2008-09 has played an important role in driving the growth of the U.S. construction industry.
The Polyurea Market in Canada is expected to witness significant growth. The harsh climate, characterized by freezing winters and hot summers, underscores the necessity for durable and reliable coatings like polyurea. These coatings are essential for infrastructure projects, such as bridges, roads, and buildings, where they provide robust protection against temperature fluctuations and environmental wear.
Europe Polyurea Market Trends
The Europe polyurea market is anticipated to grow at a significant pace during the forecast period. In Europe, the market benefits significantly from stringent environmental standards that prioritize sustainability and safety. These regulations propel the adoption of polyurea coatings due to their low volatile organic compound (VOC) emissions and eco-friendly properties, aligning with Europe's commitment to reducing environmental impact.
Polyurea Market in Germany held the largest share of the Europe regional market. The country is renowned for its precision engineering and high-quality standards. Polyurea coatings play a crucial role in Germany's automotive industry, where they are essential for vehicle assembly, component protection, and aftermarket applications. These coatings are valued for their exceptional durability, providing reliable protection against wear and corrosion, which is crucial for extending the lifespan of automotive components and ensuring long-term vehicle performance.
The UK Polyurea Market is significantly growing owing to the growing emphasis on sustainability and energy efficiency in construction practices. This focus drives the adoption of polyurea coatings for their eco-friendly attributes, such as low volatile organic compound (VOC) emissions and energy-saving capabilities. These coatings are highly valued in the construction sector for their ability to enhance building envelopes and roofing systems, providing effective waterproofing, insulation, and durability.
Asia Pacific Polyurea Market Trends
The polyurea market in Asia Pacific accounted for a substantial market share in 2025 owing to the robust presence of automobile manufacturing facilities in China, India, Japan, and South Korea in light of easy access to consumables. In addition, high market visibility for conventional coatings including epoxy in China in light of an increased number of local manufacturing units is expected to reduce the application of polyurea coatings over the forecast period.
The China Polyurea Market dominated the Asia Pacific regional market in 2025 due to rapid urbanization and extensive infrastructure development. As cities expand and modernize, there is a heightened demand for polyurea coatings in construction projects aimed at waterproofing, corrosion protection, and enhancing structural durability across buildings and transportation infrastructure. The booming construction sector in China, driven by government investments and urban development initiatives, continues to propel the adoption of polyurea coatings as a critical solution for ensuring the long-term sustainability and resilience of infrastructure projects.
The Polyurea Market in Japan is anticipated to grow at a substantial CAGR from 2026 to 2033, benefiting significantly from its advanced manufacturing sector, which necessitates high-performance coatings for critical applications in electronics, automotive components, and precision machinery. As Japan continues to innovate in technology and manufacturing, the demand for polyurea coatings is expected to grow, driven by their ability to meet stringent quality standards and enhance the performance and longevity of sophisticated industrial equipment and products.
Central & South America Polyurea Market Trends
The Central and South America polyurea market is experiencing significant growth driven by expanding industrial sectors including mining, oil & gas, and manufacturing. These industries require robust protective coatings such as polyurea for equipment and infrastructure to withstand harsh environmental conditions and operational challenges. In addition, increasing investments in infrastructure projects across the region, including transportation networks and energy facilities, further stimulate the demand for polyurea coatings.
Middle East & Africa Polyurea Market Trends
The polyurea market in the Middle East and Africa is witnessing steady growth driven by infrastructure development, and increasing disposable income. Large-scale infrastructure projects, such as Saudi Arabia’s NEOM city and the UAE’s Expo 2020 developments, increase the demand for high-performance coatings and materials that use saturated polyester resins for long-lasting protection.
Another key factor driving growth is the region's prominent oil and gas industry, which relies heavily on polyurea coatings for critical applications such as pipeline protection, corrosion resistance, and containment solutions. Furthermore, substantial investments in regional infrastructure projects, including urban development and transportation networks, propel the demand for polyurea coatings.
Key Polyurea Company Insights
Key companies are adopting several organic and inorganic expansion strategies, such as mergers & acquisitions, new product launches, capacity expansions, and joint ventures, to maintain and expand their market share.
-
In October 2023, Everest Systems Co. launched EverMax Polyurea, a flexible roof coating. Evermax Polurea offers resistance to mechanical damage, flexibility, and low shrinkage.
-
In October 2020, PPG, a global coatings company, launched PPG SaniShield 3000/5000, a polyurea coating system. This system is designed to provide long-lasting protection against viruses, bacteria, and other microorganisms on various surfaces. The PPG SaniShield 3000/5000 is a two-component, fast-curing polyurea coating that can be applied to floors, walls, and other surfaces in commercial and industrial settings. It offers excellent chemical resistance, abrasion resistance, and flexibility, making it suitable for high-traffic areas.
Key Polyurea Companies:
The following key companies have been profiled for this study on the polyurea market.
-
BASF
-
W.R. Grace
-
SWD Polyurethane
-
Specialty Products Inc.
-
LINE-X Protective Coatings
-
Nukote Coating Systems International
-
VersaFlex Inc. Nukote Coating Systems
-
PPG Industries
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF, W. R. Grace, PPG Industries, LINE-X Protective Coatings, Nukote Coating Systems International)
- Broad portfolio of polyurea coatings and linings serving construction, infrastructure, industrial maintenance, transportation, and protective containment applications.
- Continuous investment in high-performance spray polyurea technologies, corrosion protection systems, and fast-curing coating solutions.
- Strong distribution networks, technical service capabilities, and partnerships with contractors and infrastructure developers to support large-scale projects.
- Extensive expertise in protective coatings, material science, and application engineering.
- Established global presence with strong brand recognition and access to diverse end-use industries.
- Advanced formulation capabilities enable customized solutions for abrasion resistance, waterproofing, chemical protection, and asset life extension.
- Exposure to fluctuations in construction, infrastructure, and industrial capital spending cycles.
- High raw material and formulation costs can pressure margins during periods of feedstock volatility.
- Competitive market environment requires continuous investment in product innovation, contractor training, and regulatory compliance to maintain market position.
Emerging Players (Arakawa Chemical Industries Ltd.; Anabond; Goodfellow)
- Focus on high-performance polyurea coatings, protective linings, waterproofing systems, and specialized infrastructure protection applications.
- Emphasis on customized formulations for construction, industrial, wastewater, secondary containment, and asset protection projects.
- Expansion into niche end-use sectors requiring rapid curing, chemical resistance, and long-term durability.
- Strong technical expertise in polyurea formulation and application-specific product development.
- Greater flexibility in addressing customer-specific performance requirements and project needs.
- Ability to respond quickly to emerging opportunities in infrastructure rehabilitation, industrial maintenance, and protective coatings.
- Smaller production scale and global market presence compared with diversified multinational coating manufacturers.
- Limited geographic reach and distribution networks in certain high-growth regions. Dependence on construction, infrastructure investment, and industrial maintenance spending cycles.
Polyurea Market Report Scope
Report Attribute
Details
Market size in 2025
USD 996.8 million
Estimated market size in 2026
USD 1,054.2 million
Projected market size by 2033
USD 1,731.8 million
Growth rate
CAGR of 7.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Raw material, product, application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; China; Japan; India; Brazil; Argentina; GCC countries; South Africa
Key companies profiled
BASF; W.R. Grace; SWD Polyurethane; Specialty Products Inc.; LINE-X Protective Coatings; Nukote Coating Systems International; VersaFlex Inc. Nukote Coating Systems, PPG Industries
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Polyurea Market Report Segmentation
This report forecasts revenue and volume growth at the global, regional, and country levels and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global polyurea market report based on raw material, product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Raw Material Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Aromatic
-
Aliphatic
-
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Coating
-
Lining
-
Adhesives & Sealants
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Construction
-
Industrial
-
Transportation
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
GCC Countries
-
South Africa
-
-
Research Methodology
The polyurea market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each polyurea segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Raw Material
Revenue Capture Definition
Aromatic
Revenue is captured through the sale of aromatic polyurea systems used in large-scale industrial, commercial, and infrastructure protection applications, including secondary containment, wastewater facilities, pipelines, tank linings, parking decks, and general waterproofing. Demand is driven by cost-effectiveness, rapid curing, high mechanical strength, abrasion resistance, and excellent performance in environments where long-term color stability and UV resistance are not primary requirements.
Aliphatic
Revenue is captured through the sale of premium aliphatic polyurea systems designed for applications requiring superior UV stability, color retention, weather resistance, and aesthetic durability. These materials are widely used in architectural coatings, decorative surfaces, roofing systems, stadiums, bridges, marine structures, and exposed infrastructure. Sales are supported by growing demand for long-lasting protective coatings that maintain appearance and performance under prolonged sunlight exposure and harsh environmental conditions.
Segment - Product
Revenue capture definition
Coating
Revenue is captured through the sale of polyurea coating systems used for corrosion protection, waterproofing, abrasion resistance, and asset preservation across construction, industrial, transportation, marine, and energy sectors. Demand is driven by rapid curing properties, seamless application, chemical resistance, durability, and the need to extend the service life of critical infrastructure and equipment.
Lining
Revenue is captured through the supply of polyurea lining materials for containment structures, storage tanks, pipelines, wastewater facilities, secondary containment systems, and process equipment. Sales are supported by the material’s impermeability, chemical resistance, flexibility, and ability to provide long-term protection against leaks, corrosion, and environmental exposure in demanding operating environments.
Adhesives & Sealants
Revenue is captured through sales of polyurea-based adhesives and sealants used in construction, transportation, industrial assembly, and infrastructure applications. Growth is supported by strong bonding performance, crack-bridging capability, flexibility, moisture resistance, and the increasing need for durable sealing and joining solutions in high-performance applications.
Others
Revenue is captured through specialized and emerging polyurea product formats, including elastomeric membranes, spray-applied protective systems, hybrid formulations, and customized solutions serving defense, mining, renewable energy, and specialty industrial applications. These sales are driven by evolving performance requirements, technological innovation, and the growing adoption of advanced protective materials in niche end-use sectors.
Segment - Application
Revenue capture definition
Construction
Revenue is captured through polyurea coatings, linings, and waterproofing systems supplied for roofs, foundations, parking structures, bridges, tunnels, water tanks, and wastewater facilities. Value is driven by rapid curing, seamless application, crack-bridging capability, chemical resistance, and long-term protection against moisture ingress, corrosion, and environmental degradation in critical infrastructure projects.
Industrial
Revenue is generated through polyurea solutions used for secondary containment, processing equipment, storage tanks, pipelines, flooring systems, and corrosion protection across manufacturing, chemical, oil and gas, mining, and utility sectors. Pricing is influenced by chemical resistance, abrasion protection, operational durability, reduced maintenance requirements, and the ability to extend asset service life in harsh industrial environments.
Transportation
Revenue is captured through polyurea coatings and protective systems used in railcars, trucks, trailers, marine vessels, ports, airports, and transportation infrastructure. Demand is supported by impact resistance, waterproofing performance, corrosion protection, weight optimization, and the need for durable coatings that withstand heavy mechanical stress and continuous exposure to challenging weather conditions.
Others
Revenue comes from specialized applications including defense equipment, renewable energy assets, agricultural facilities, recreational infrastructure, and custom-engineered protective systems. Value is supported by application-specific performance requirements, specialized formulations, environmental resistance, and technical service capabilities that enable premium pricing and higher-margin project opportunities.
Estimation Model
Layer Name
Key Question
Description
Top-Down Polyurea Demand Assessment Layer
What defines market boundaries?
This layer begins with global polyurea consumption across construction, transportation, industrial, water management, energy, and protective coating applications. Demand is filtered through infrastructure spending, industrial maintenance activity, transportation asset investments, wastewater treatment expansion, and energy sector development to establish the total addressable market.
End-Use Application Validation Layer
Where is demand generated?
This layer evaluates demand distribution across waterproofing, corrosion protection, secondary containment, flooring systems, roofing, pipeline protection, and marine coatings. Market sizing is aligned with performance requirements such as chemical resistance, abrasion protection, rapid curing, environmental exposure tolerance, and asset lifecycle extension needs.
Consumption-to-Revenue Conversion Layer
Who captures market revenue?
This layer converts coated surface area and project activity into market revenue by applying polyurea consumption rates, coating thickness requirements, substrate characteristics, application methods, project specifications, and pricing variations across pure and hybrid polyurea systems used in different industries.
Regional Demand Verification Layer
How are assumptions validated?
This layer validates demand concentration by comparing infrastructure development in Asia Pacific, industrial maintenance and energy investments in North America, and environmental protection and rehabilitation projects in Europe. Regional construction activity, regulatory compliance requirements, and industrial asset protection spending are assessed to verify market assumptions and growth projections.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed market sizing, growth forecasts, demand analysis, and competitive landscape assessment across North America, Europe, Asia Pacific, Central & South America, and the Middle East & Africa. Country-level evaluation for key markets, including the U.S., Germany, China, India, and GCC countries.
Identifies high-growth regional markets, supports geographic expansion strategies, and enables resource allocation based on regional demand patterns and infrastructure investments.
Cross-Segmentation Analysis
Comprehensive analysis by raw material type, technology, application, and end-use industry. Cross-segmentation provided for coating type versus end-use sector, and application versus regional demand trends.
Reveals high-value growth pockets, uncovers niche revenue opportunities, and supports targeted product development and market entry decisions.
Opportunity Assessment
Identification of high-growth opportunities across infrastructure waterproofing, industrial flooring, wastewater containment, secondary containment systems, transportation, energy, and asset protection applications. Future demand hotspots and emerging investment areas are evaluated.
Supports strategic planning, investment prioritization, new product development, and long-term revenue growth initiatives in attractive market segments.
Frequently Asked Questions About This Report
The coating segment led the market with the largest revenue share of 66.5% in 2025.
The construction segment led with a 43.7% revenue share in 2025.
Polyurea coatings are increasingly moving beyond heavy-duty industrial protection systems into thinner, rapid-deployment solutions as asset owners prioritize faster maintenance and reduced downtime. Demand from infrastructure rehabilitation, parking decks, wastewater facilities, and waterproofing applications is driving preference for polyurea due to its ultra-fast curing, crack-bridging performance, and long-term resistance to abrasion and chemicals.
The global polyurea market is expected to grow at a CAGR of 7.3% from 2026 to 2033, reaching USD 1,731.8 million by 2033.
The aromatic segment led the market with the largest revenue share of 67.2% in 2025.
Key factors that are driving the market growth include growing use of protective coatings in automotive and construction applications on account of their rust prevention and high durability properties and increasing application in adhesives and sealants as bonding agents.
North America dominated with a 40.9% revenue share in 2025.
The global polyurea market size was valued at USD 996.8 million in 2025 and is estimated at USD 1,054.2 million for 2026.
Some key players operating in the polyurea market include BASF; W.R. Grace; SWD Polyurethane; Nukote Coating Systems International; LINE-X Protective Coatings; PPG Industries; Specialty Products Inc.; and VersaFlex Inc. Nukote Coating Systems.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


