
- Home
- »
- Advanced Interior Materials
- »
-
Pre-consumer Textile Waste Recycling Market Report, 2033GVR Report cover

Pre-consumer Textile Waste Recycling Market (2026 - 2033)
Size, Share & Trends Analysis Report By Waste Generation Stage (Garment manufacturing; Dyeing, printing & finishing), By Recycling Process, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$2.4BMarket Estimate, 2026
$2.6BMarket Forecast, 2033
$4.6BCAGR, 2026–2033
8.6%Pre-consumer Textile Waste Recycling Market Summary
The global pre-consumer textile waste recycling market size was valued at USD 2.4 billion in 2025 and is projected to grow from USD 2.6 billion in 2026 to USD 4.6 billion by 2033, at a CAGR of 8.6% from 2026 to 2033. Asia Pacific dominated the market with the largest revenue share of 41.0% in 2025. The market is gaining importance as textile manufacturers increasingly seek to reduce production waste, improve raw material efficiency, and transition toward circular manufacturing models.
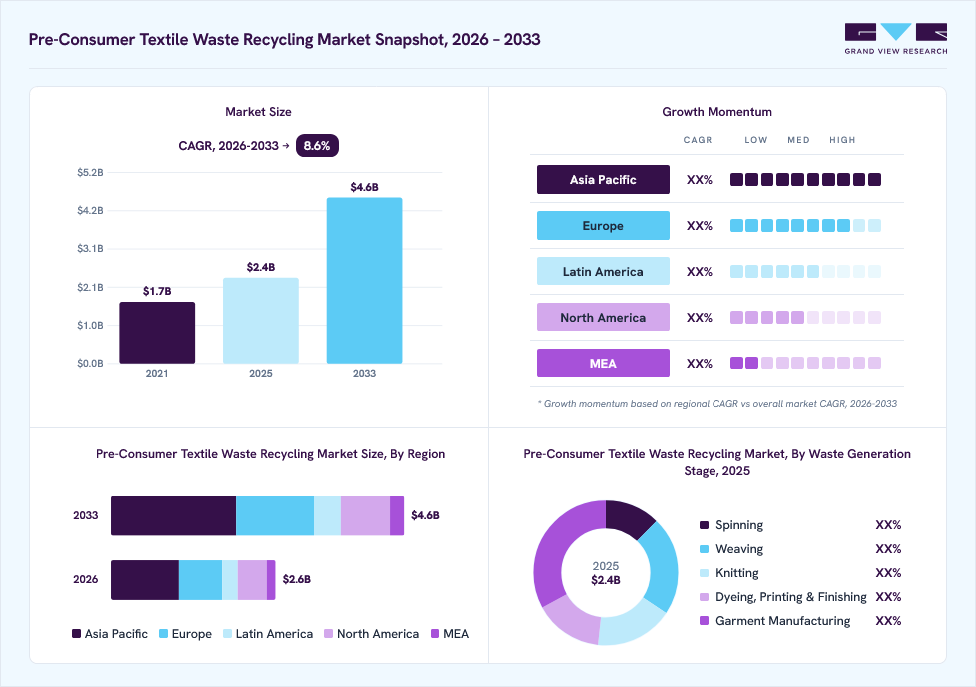 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By waste generation stage: The garment manufacturing segment is expected to grow at a CAGR of 8.9% over the forecast period.
- By end use: The apparel & fashion segment dominated the market with a revenue share of 44.8% in 2025.
- By recycling process: The chemical recycling segment is projected to register a CAGR of 9.3% during the forecast period from 2026 to 2033.
Regional Highlights
- Largest regional market: Asia Pacific (41.0% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 2.4 Billion
- Estimated market size in 2026: USD 2.6 Billion
- Projected market size by 2033: USD 4.6 Billion
- CAGR (2026-2033): 8.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Pre-consumer waste is generated before textiles reach consumers and includes fabric-cutting waste, production scraps, yarn waste, selvages, and quality-rejected textile materials. These materials are comparatively cleaner and more homogeneous than post-consumer waste, making them attractive feedstocks for recycling. A major market driver is the growing adoption of closed-loop and fiber-to-fiber recycling. Mechanical recycling remains widely used for cotton and other relatively homogeneous textile waste, converting production scraps into recycled fibers for use in yarn, nonwovens, insulation, and other textile applications.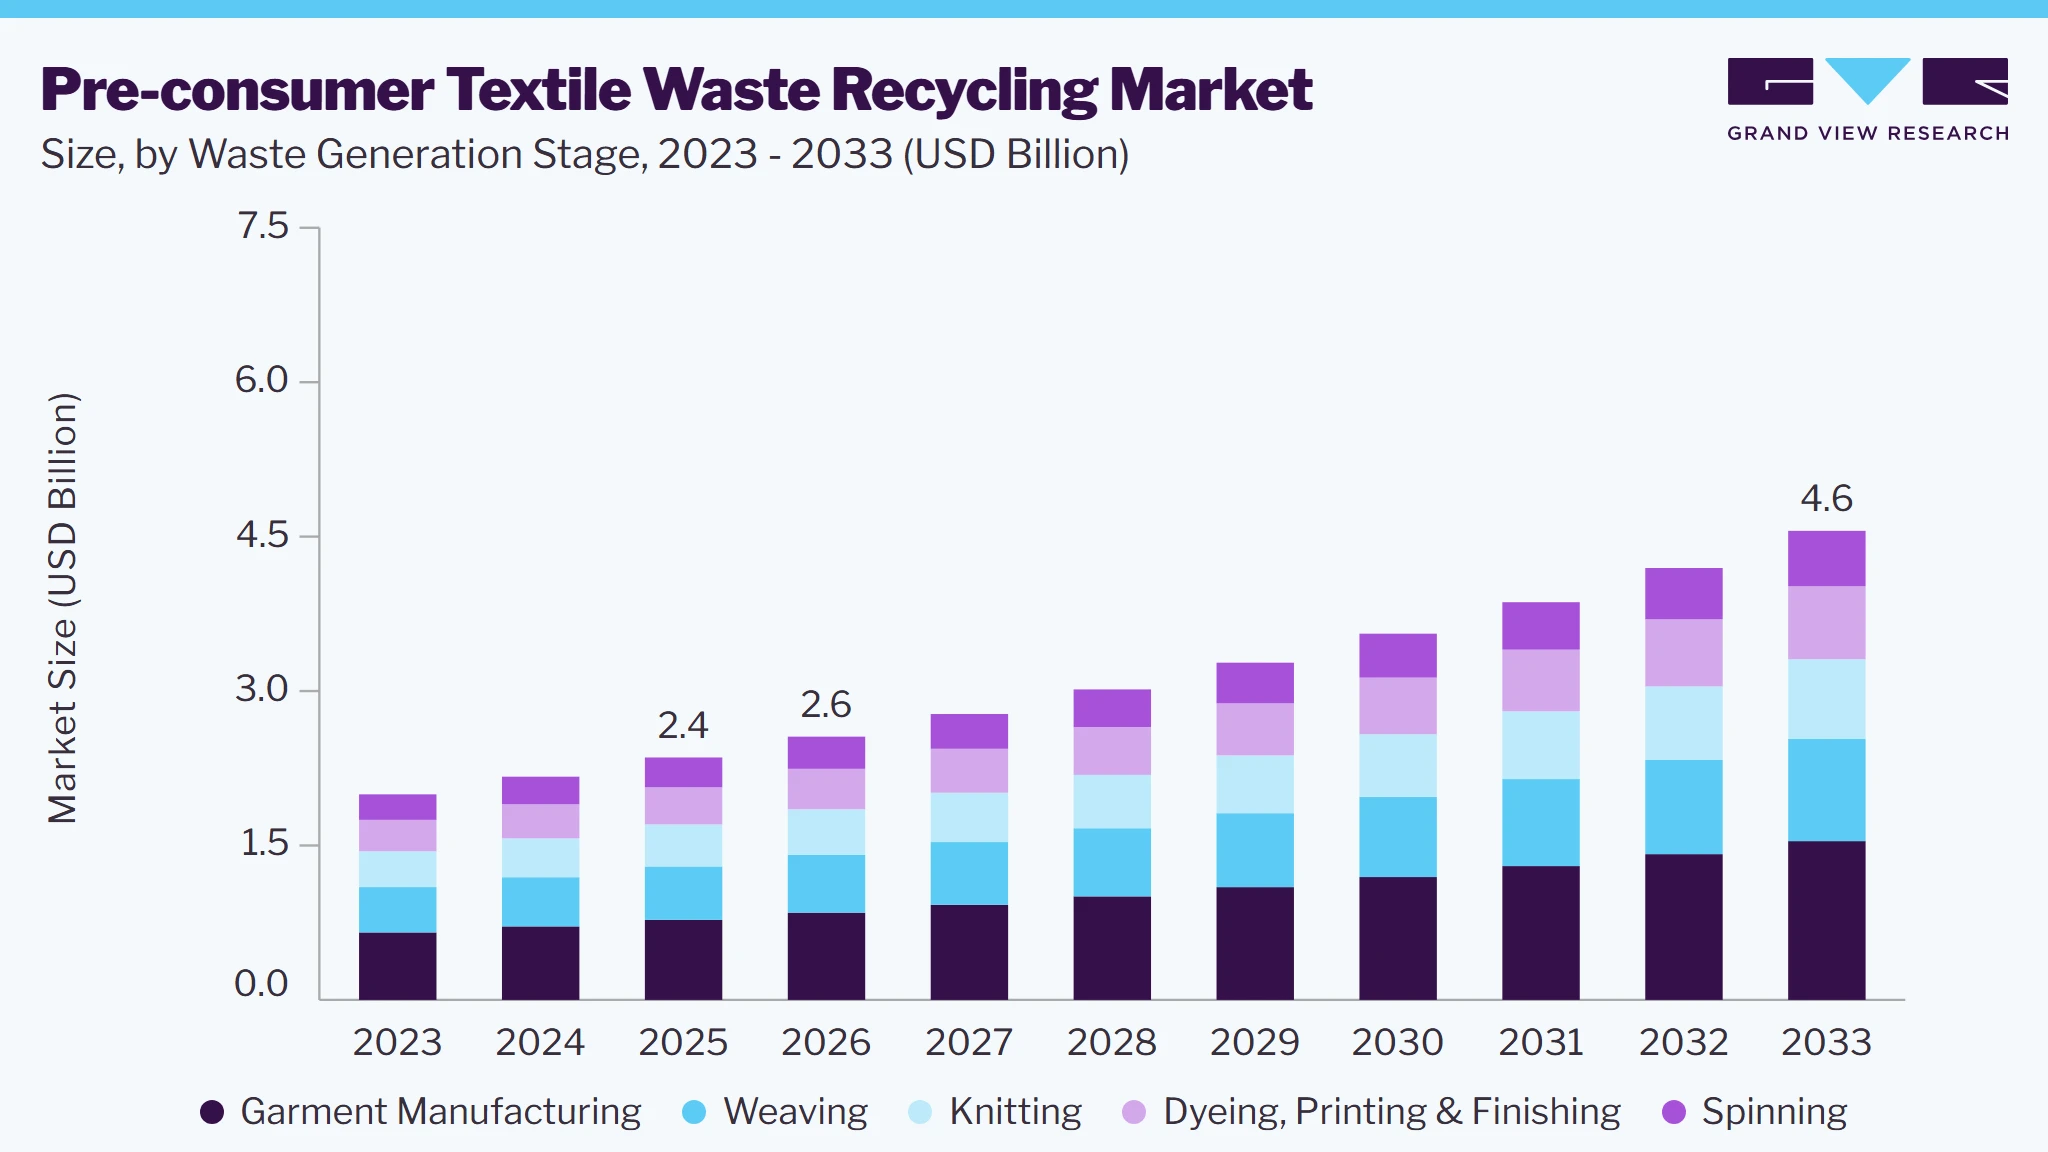 To learn more about this report, Download Free Sample Report
Chemical recycling is gaining attention for polyester, polyamide, cellulosic fibers, and selected blended materials because it can potentially recover materials with properties closer to virgin feedstocks. Pre-consumer textile waste is particularly suitable for these technologies because its composition and origin can often be traced more easily. Technology development is shifting the market from conventional waste downcycling toward higher-value textile-to-textile recycling. Automated sorting, optical identification, improved shredding and fiber-opening systems, advanced spinning, solvent-based recycling, depolymerization, and enzymatic processing are improving the ability to recover useful fibers from manufacturing waste. Digital traceability and material certification are also becoming increasingly important as brands seek verified recycled content and transparent supply chains. Chemical recycling is particularly relevant for synthetic and blended textile waste, while mechanical recycling remains important for cotton and other fiber streams.
Market Dynamics
The market is influenced by the increasing need to reduce manufacturing waste, rising demand for recycled fibers, sustainability commitments from textile and apparel companies, and government initiatives promoting circular textile systems. The relatively consistent composition of manufacturing waste provides recyclers with an advantage over mixed post-consumer waste, while technological improvements are expanding the range of materials that can be recycled. However, challenges related to fiber degradation, blended materials, collection logistics, recycling economics, and the availability of suitable processing infrastructure continue to influence market development.
Textile manufacturers are increasingly integrating waste recovery directly into production processes to minimize material losses and improve raw material utilization. Cutting waste, yarn waste, selvages, and quality-rejected fabrics can often be collected at the manufacturing site and routed directly to recyclers or reintegrated into production. This creates a comparatively efficient feedstock stream because the material is available before contamination, extensive wear, or complex consumer-use histories occur. India's textile-waste mapping initiative also highlights the strong recovery and reintegration potential of pre-consumer textile waste, reinforcing the importance of production-stage circularity.
The growing demand for recycled fibers is further encouraging manufacturers to establish closed-loop relationships with recyclers and fiber producers. Apparel and textile brands are increasingly incorporating recycled content into sustainability strategies, while manufacturers are seeking ways to convert their own production residues into secondary raw materials. Mechanical recycling can provide relatively straightforward recovery routes for homogeneous cotton and synthetic waste, whereas chemical recycling offers opportunities to recover higher-quality raw materials from selected synthetic and cellulosic streams. This combination of recycling pathways is expanding the potential applications for pre-consumer textile waste.
A key restraint is the deterioration of fiber properties during repeated mechanical processing. Shredding and opening textile waste can shorten fibers, reducing their strength and limiting their suitability for high-quality yarn production. Blended fabrics, elastane-containing materials, dyes, finishes, coatings, and complex textile constructions can further complicate recycling. Chemical recycling can overcome some of these limitations but generally requires more sophisticated processing systems, feedstock preparation, chemical management, and capital investment. Consequently, recyclers must balance feedstock quality, processing costs, recovered-material quality, and end-use requirements.
The transition toward fiber-to-fiber recycling represents a major opportunity for the market. Rather than converting production waste into lower-value insulation, wiping materials, or industrial products, advanced recycling systems can potentially return recovered material to textile manufacturing. The European Commission identifies innovative fiber-to-fiber recycling capacity as an important component of a circular textile ecosystem, while research programs increasingly target improved recycling of complex textile streams. This creates opportunities for technology providers, textile mills, recyclers, fiber producers, and brands to develop integrated closed-loop supply chains.
Market Concentration & Characteristics
The pre-consumer textile waste recycling industry is moderately fragmented, with participation from textile mills, specialized recycling companies, fiber manufacturers, nonwoven producers, technology developers, and vertically integrated apparel companies. Market structure varies by material, with established mechanical recyclers serving cotton and relatively homogeneous waste streams while emerging technology companies focus on chemical recycling and high-value fiber recovery. Larger fiber and textile manufacturers increasingly collaborate with recycling technology providers to secure feedstock and develop recycled fiber capacity. At the same time, regional recyclers continue to play an important role because textile manufacturing waste is geographically concentrated around major production clusters.
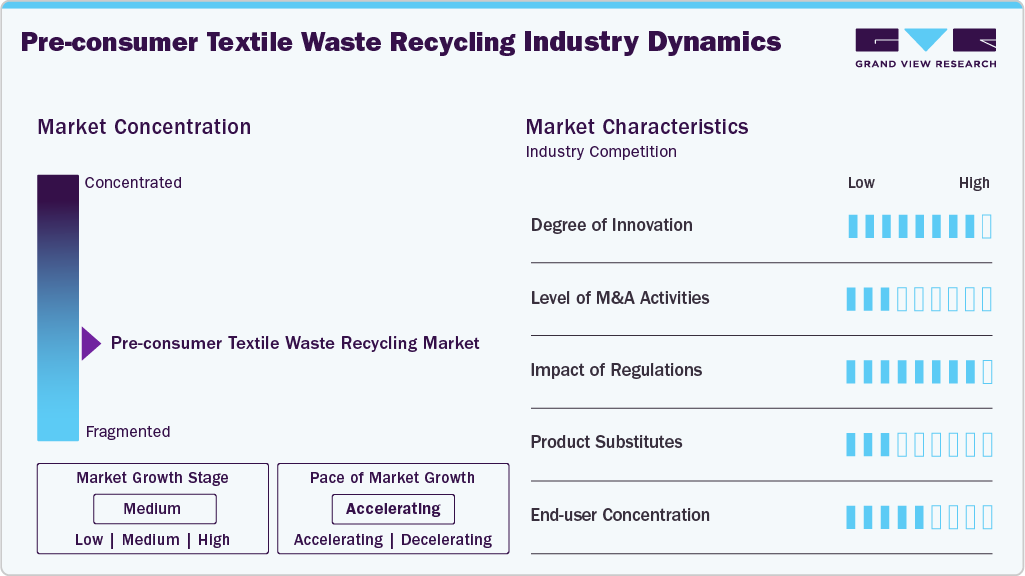 To learn more about this report, Download Free Sample Report
The threat of substitutes is moderate because recycled pre-consumer textile fibers compete primarily with virgin fibers and other recycled feedstocks. Virgin cotton, polyester, nylon, viscose, and other fibers remain established alternatives because of their consistent quality, availability, and well-developed supply chains. Recycled PET from non-textile sources is also an important substitute for recycled polyester textile waste. However, increasing demand for textile-to-textile circularity is gradually reducing the attractiveness of non-textile recycled inputs, particularly as brands seek closed-loop sourcing. Textile Exchange has highlighted the need to increase textile-to-textile recycling rather than relying predominantly on recycled materials originating from other industries.
Analyst Perspective
The market is positioned as an attractive segment within the broader transition toward circular textile manufacturing, primarily because production-stage waste is generally more accessible, traceable, and consistent in composition than post-consumer textile waste. From an analyst perspective, the market opportunity is shifting from conventional downcycling toward fiber-to-fiber recycling and closed-loop material recovery, supported by increasing recycled-fiber demand, brand sustainability commitments, and tightening textile-waste regulations. The strongest commercial opportunities are expected in textile-manufacturing hubs where recyclers can secure large volumes of segregated production waste and establish direct relationships with mills and apparel manufacturers.
Waste Generation Stage Insights
The garment manufacturing segment held the highest revenue share of 33.0% in 2025, supported by the substantial generation of fabric cutting waste, trimmings, rejected garments, and production scraps during apparel manufacturing. These waste streams are generally available in relatively consistent volumes and can be efficiently collected, sorted, and mechanically recycled. The proximity of garment manufacturers to recycling facilities and established waste-recovery networks further supports revenue generation from this segment.
The dyeing, printing & finishing segment is expected to grow at a CAGR of 8.8% over the forecast period, driven by increasing efforts to recover rejected fabrics, process scraps, and other textile waste generated during finishing operations. Growing demand for higher-value recycling is encouraging the development of processes capable of handling dyed, printed, and chemically treated materials. Advances in chemical and biochemical recycling are expected to improve the recovery potential of such complex textile waste streams.
Recycling Process Insights
The mechanical recycling segment held the highest revenue share of 71.8% in 2025, owing to its established commercial use, relatively straightforward processing requirements, and suitability for homogeneous pre-consumer textile waste. Processes such as shredding, opening, carding, blending, and respinning enable manufacturers to convert production scraps into recycled fibers and yarns. Its established infrastructure and scalability continue to support its leading market position.
The chemical recycling segment is expected to grow at a CAGR of 9.3% over the forecast period, supported by increasing demand for high-quality recycled fibers and technologies capable of processing textile waste that is difficult to recycle mechanically. Chemical processes can break down or dissolve textile materials into reusable molecular building blocks, creating opportunities for fiber-to-fiber recycling and improved material quality. Continued development of technologies for blended and chemically treated textiles is expected to strengthen adoption.
End-use Insights
The apparel & fashion segment held the highest revenue market share of 44.8% in 2025, primarily due to the large availability of pre-consumer waste from garment production and the industry's increasing adoption of recycled fibers and circular manufacturing practices. Fabric cutting waste, trimmings, rejected garments, and production scraps can be recovered and converted into fibers and yarns for new apparel applications, supporting a closed-loop textile supply chain.
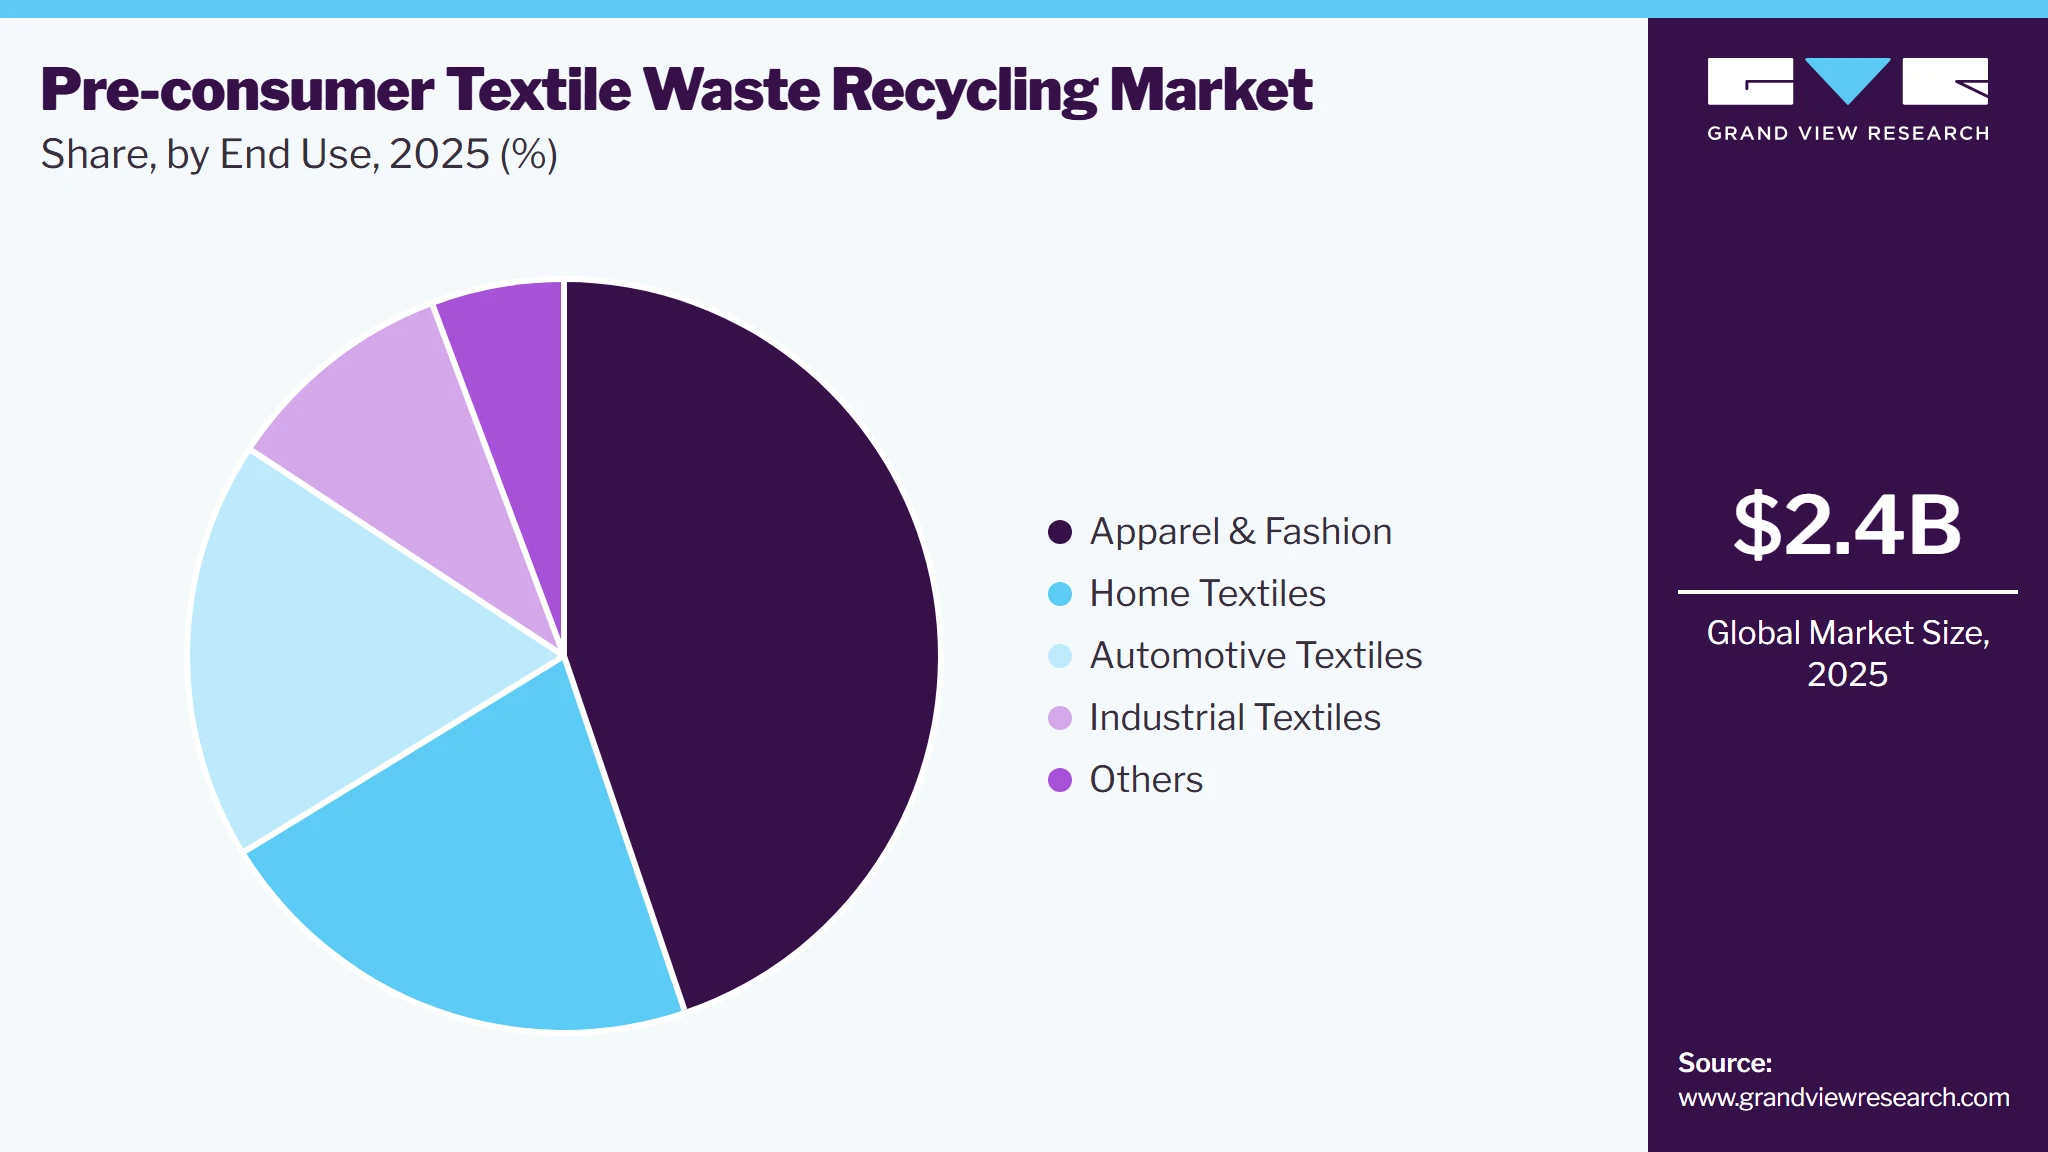 To learn more about this report, Download Free Sample Report
The automotive textiles segment is expected to grow at a CAGR of 9.1% over the forecast period, driven by increasing utilization of recycled textile materials in vehicle interiors, insulation, carpeting, acoustic materials, and other technical applications. Pre-consumer textile waste can provide relatively consistent and traceable feedstock for producing nonwoven and composite materials used in automotive applications. Growing emphasis on lightweight materials, recycled content, and sustainable vehicle manufacturing is expected to create additional opportunities for recycled textile inputs.
Regional Insights
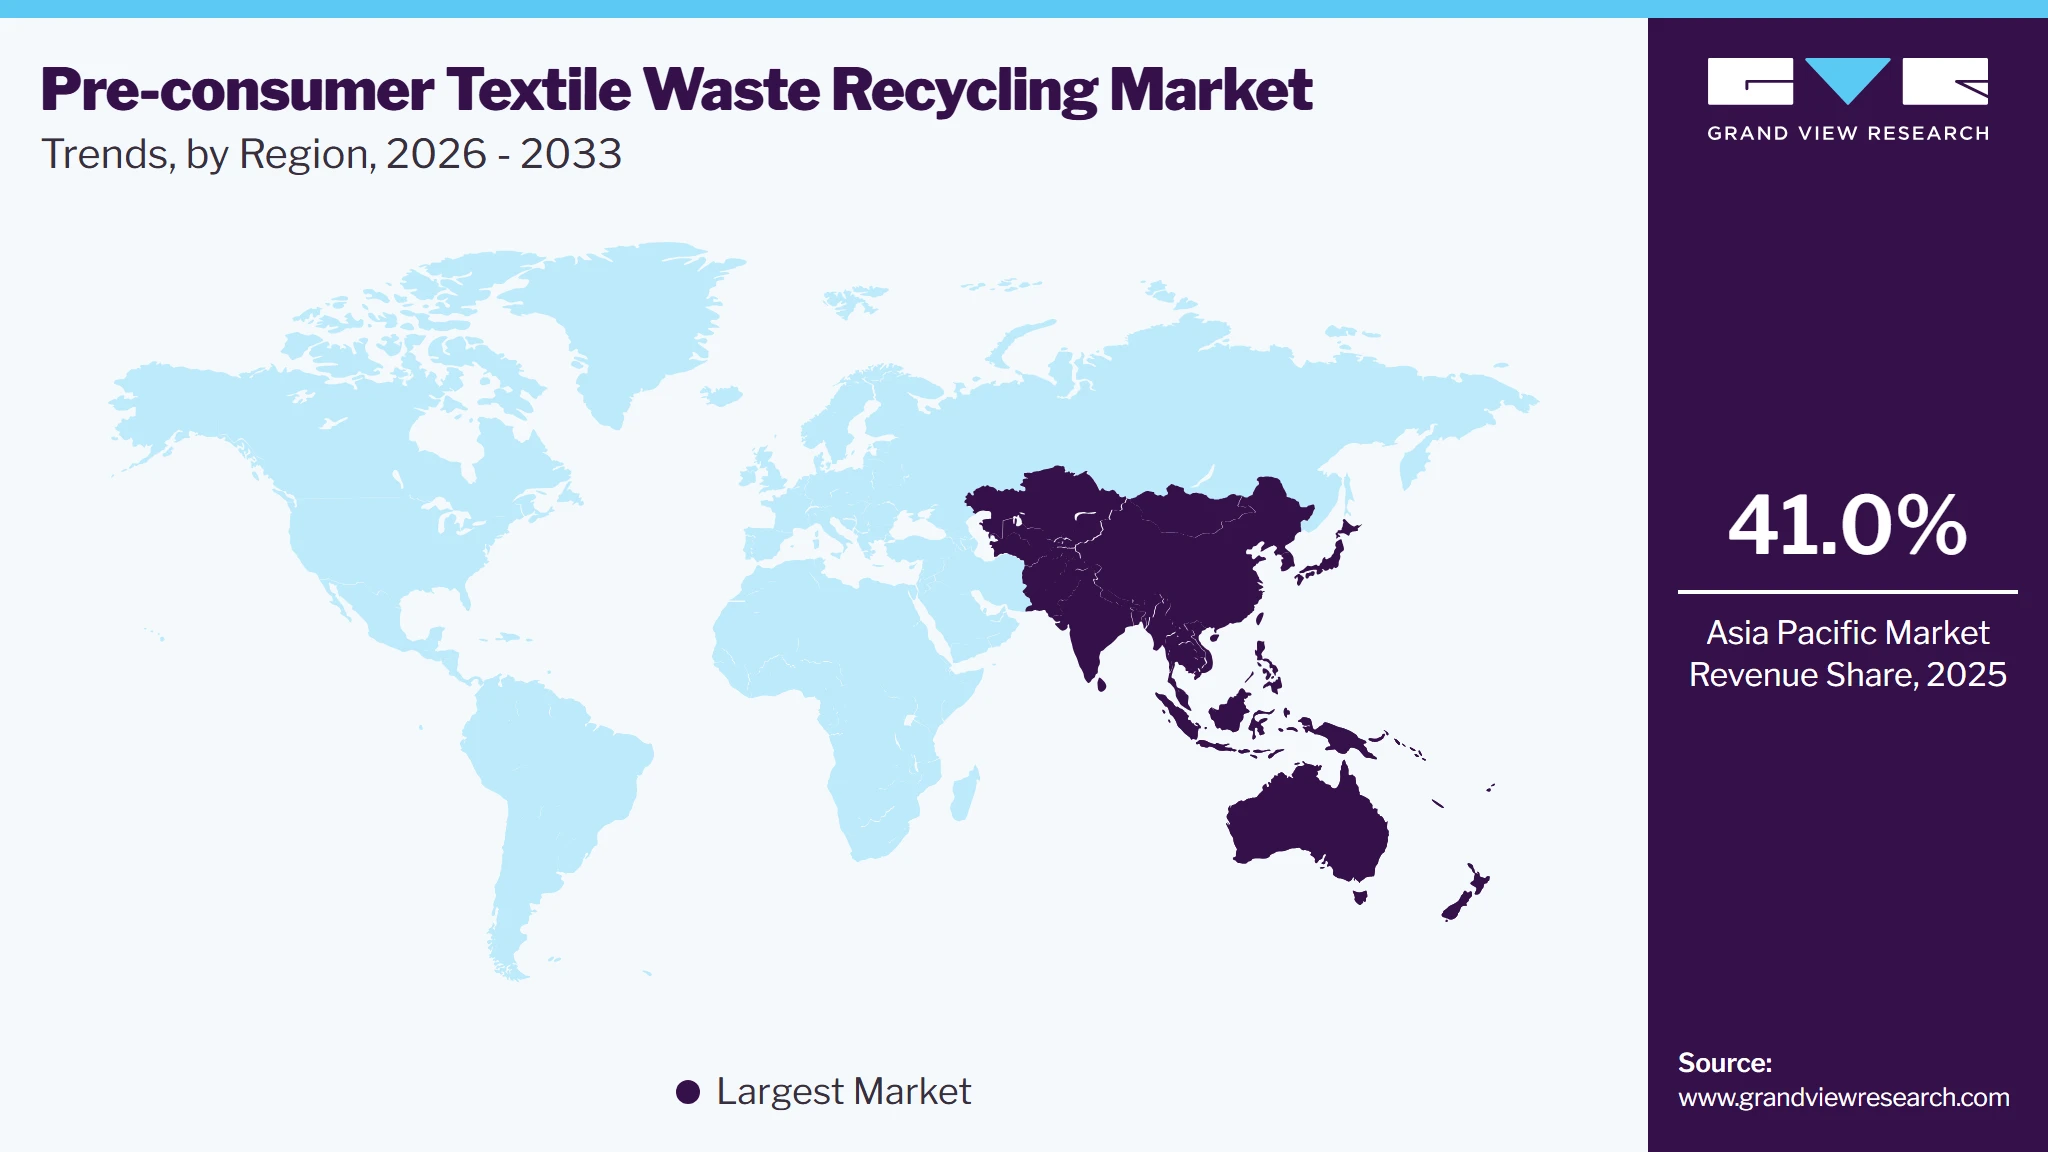
Asia Pacific dominated the global pre-consumer textile waste recycling market, accounting for the largest revenue share of 41.0% in 2025 due to its extensive textile and apparel manufacturing base. Large concentrations of spinning, weaving, knitting, dyeing, finishing, and garment manufacturing generate substantial volumes of production-stage textile residues. China, India, Bangladesh, Vietnam, Indonesia, and other manufacturing centers offer access to relatively concentrated waste streams, supporting the economics of collection and recycling. Textile manufacturers are increasingly adopting waste segregation and recovery systems to reduce material losses and comply with customer sustainability requirements.
 To learn more about this report, Download Free Sample Report
China Pre-consumer Textile Waste Recycling Market Trends
The pre-consumer textile waste recycling market in China represents one of the largest opportunities for pre-consumer textile waste recycling because of its extensive textile manufacturing ecosystem and vertically integrated supply chain. The country's concentration of spinning, weaving, knitting, dyeing, and apparel production provides recyclers with access to large volumes of relatively homogeneous manufacturing waste. Mechanical recycling is well established for suitable textile residues, while investment in advanced recycling is expanding as manufacturers seek higher-value applications for recovered fibers. China's large synthetic-fiber industry also creates opportunities for polyester and polyamide recycling.
North America Pre-consumer Textile Waste Recycling Market Trends
The pre-consumer textile waste recycling market in North America is characterized by increasing demand for recycled textile inputs, driven by sustainability commitments from apparel brands, retailers, and textile manufacturers. The region has a comparatively developed recycling and waste-management infrastructure, although textile recycling capacity remains more limited than conventional recycling streams. Pre-consumer waste offers an attractive feedstock because it can be collected directly from manufacturing facilities and often requires less sorting than post-consumer material. Growing interest in domestic textile-to-textile recycling is encouraging investments in mechanical and chemical recycling technologies.
The U.S. pre-consumer textile waste recycling marketis supported by increasing corporate sustainability commitments, demand for recycled fibers, and technological investment in textile recycling. Pre-consumer textile waste generated by domestic textile production, apparel manufacturing, and industrial textile operations provides relatively consistent feedstock for recyclers. Mechanical recycling remains relevant for cotton and other suitable waste, while chemical recycling is gaining attention for synthetic and blended materials. Research institutions, startups, textile companies, and technology developers are increasingly exploring fiber-to-fiber solutions.
Europe Pre-consumer Textile Waste Recycling Market Trends
The pre-consumer textile waste recycling market in Europe is among the most advanced in the world and is expected to remain a key market for pre-consumer textile waste recycling. Regulatory measures are encouraging textile durability, recyclability, recycled-material use, producer responsibility, and improved waste management. The EU's revised Waste Framework Directive establishes common principles for textile EPR systems, while broader circular-economy initiatives are encouraging investment in recycling infrastructure. European recyclers are increasingly focusing on closed-loop fiber recovery rather than lower-value applications, while textile producers and brands are developing partnerships to secure recycled feedstocks.
Germany pre-consumer textile waste recycling marketrepresents an important European market due to its advanced manufacturing infrastructure, engineering capabilities, environmental regulations, and strong industrial recycling ecosystem. Textile manufacturers and technology companies are increasingly exploring automated sorting, efficient fiber separation, mechanical recycling, and advanced chemical processes. The country's emphasis on resource efficiency and industrial circularity supports investment in technologies that can convert production residues into reusable materials. Germany also benefits from its position within the broader European textile and chemical industries, creating opportunities for collaboration between recyclers, machinery suppliers, fiber manufacturers, and research institutions.
Central and South America Pre-consumer Textile Waste Recycling Market Trends
The pre-consumer textile waste recycling market in CSA offers emerging opportunities for pre-consumer textile waste recycling as textile and apparel manufacturing expands its focus on resource efficiency and sustainability. Brazil, Mexico, and other manufacturing centers provide concentrated textile production and, therefore, potential sources of pre-consumer waste. Mechanical recycling is likely to remain important because of its relatively established technology and applicability to homogeneous textile residues. Increasing exports to sustainability-conscious markets is encouraging manufacturers to improve waste management and recycled-material utilization.
Middle East & Africa Pre-consumer Textile Waste Recycling Market Trends
The pre-consumer textile waste recycling market in MEA remains comparatively developing but offers long-term opportunities through expanding textile manufacturing, industrial diversification, and sustainability initiatives. Countries with growing apparel and textile manufacturing capabilities can benefit from recycling production residues locally instead of sending valuable materials to disposal or lower-value applications. Investment in textile-processing infrastructure, industrial recycling, and circular manufacturing is expected to gradually improve market conditions. The region also provides opportunities for partnerships with international recyclers and technology providers to establish modern fiber-recovery facilities.
Key Pre-consumer Textile Waste Recycling Company Insights
Some of the key players operating in the market include Birla Cellulose and Kishco Group.
- Birla Cellulose, the cellulosic fiber business of Grasim Industries, is a major global producer of man-made cellulosic fibers, including viscose and modal fibers. The company is developing circular fiber solutions that incorporate pre-consumer and post-consumer textile waste, supporting the transition toward recycled and more sustainable textile production.
- Kishco Group is an India-based textile waste recycling company specializing in the collection, sorting, processing, and recycling of pre-consumer textile waste. Its operations cover waste streams such as fabric cutting waste, yarn waste, fiber waste, sliver waste, and other manufacturing residues, which are processed into recovered fibers and other reusable textile materials.
SaXcell and Circ are some of the emerging market participants.
- SaXcell is a Netherlands-based textile recycling technology company focused on converting cotton-rich textile waste into regenerated cellulose fibers. Its technology aims to transform discarded textile materials into new, high-quality fibers suitable for textile manufacturing, supporting closed-loop and fiber-to-fiber recycling.
- Circ is a U.S.-based textile recycling technology company developing a chemical recycling process for blended textile waste, particularly polyester-cotton fabrics. Its technology is designed to separate and recover cellulose and polyester components so they can be converted into new textile-grade materials, addressing one of the key challenges in textile-to-textile recycling.
Key Pre-consumer Textile Waste Recycling Companies
The following key companies have been profiled for this study on the pre-consumer textile waste recycling market.
-
Birla Cellulose
-
FabScrap
-
Infinited Fibre Company
-
Martex Fiber
-
Lenzing AG
-
SaXcell
-
Hyosung TNC
-
UNIFI, Inc.
-
Kishco Group
-
Circ
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players - Birla Cellulose, Lenzing AG, Hyosung TNC, UNIFI, Inc., Martex Fiber, Kishco Group
- Invest in advanced textile waste collection, sorting, fiber recovery, mechanical recycling, and textile-to-textile recycling technologies to process pre-consumer cotton, polyester, and blended textile waste.
- Expand recycling capacity and partnerships with textile manufacturers, apparel brands, spinners, and fiber producers to secure consistent pre-consumer feedstock.
- Focus on producing higher-value recycled fibers and regenerated materials with consistent quality, traceability, and sustainability credentials.
- Established market presence, strong relationships across the textile and apparel value chain, and established recycling or fiber-production capabilities.
- Advanced technological capabilities enable processing of different textile waste streams and development of recycled fibers for apparel, home textiles, and industrial applications.
- Strong sustainability credentials and certifications support adoption by global brands and textile manufacturers.
- Advanced recycling processes can require significant capital investment, specialized infrastructure, and reliable feedstock supply.
- Higher processing costs and technical limitations associated with blended, dyed, coated, or elastane-containing textiles can restrict recycling economics.
- Large established operations may also be less flexible than smaller specialists in serving highly customized or localized pre-consumer waste-recycling requirements.
Emerging Players - FabScrap, Infinited Fibre Company, SaXcell, Circ
- Develop and scale pre-consumer textile waste collection, recycling, and fiber-to-fiber solutions, with emphasis on converting production scraps and manufacturing residues into recycled yarns or fibers.
- Expand through partnerships with textile mills, apparel manufacturers, brands, and recycling technology providers to secure feedstock and increase downstream demand.
- Prioritize material traceability, recycled-content solutions, processing efficiency, and application-specific recycled fibers to differentiate from conventional waste processors.
- Flexible business models and greater ability to focus on specific waste streams, recycling technologies, or textile applications.
- Strong technical expertise in recycled polyester, regenerated fibers, or textile-waste processing provides opportunities to address specific feedstock challenges.
- Partnerships with textile manufacturers and brands can provide direct access to pre-consumer waste and support closed-loop recycling models.
- Smaller scale or narrower geographic presence compared with the largest global fiber and textile companies.
- Dependence on partnerships, availability of suitable pre-consumer feedstock, and the successful scaling of newer recycling technologies can create operational challenges.
- Emerging players also compete against established companies with stronger manufacturing infrastructure, established customer relationships, and greater financial resources.
Recent Developments
-
In February 2026, Birla Cellulose launched Liva Reviva M, a next-generation circular fiber made from recycled clothing. The product represents an expansion of Birla Cellulose's recycled-fiber portfolio and supports textile-to-textile circularity.
-
In September 2025, Hyosung TNC presented its textile-to-textile recycling solution Loop, which converts low-value textile waste into high-purity recycled polyester and subsequently into performance yarns under the regen portfolio.
Pre-consumer Textile Waste Recycling Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.4 billion
Estimated market size in 2026
USD 2.6 billion
Projected market size by 2033
USD 4.6 billion
Growth rate
CAGR of 8.6% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Waste generation stage, recycling process, end-use, region
Regional scope
North America; Asia Pacific; Europe; CSA; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Brazil; Saudi Arabia
Key companies profiled
Birla Cellulose; FabScrap; Infinited Fibre Company; Martex Fiber; Lenzing AG; SaXcell; Hyosung TNC; UNIFI, Inc.; Kishco Group; Circ
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pre-consumer Textile Waste Recycling Market Report
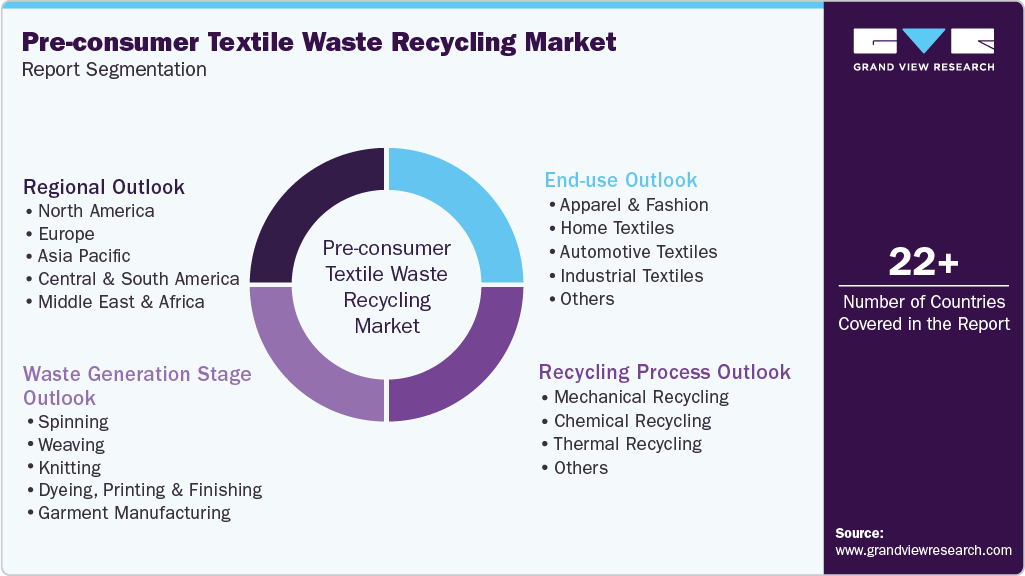
This report forecasts revenue growth at regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pre-consumer textile waste recycling market report based on waste generation stage, recycling process, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Waste Generation Stage Outlook (Revenue, USD Billion, 2021 - 2033)
-
Spinning
-
Weaving
-
Knitting
-
Dyeing, Printing & Finishing
-
Garment Manufacturing
-
-
Recycling Process Outlook (Revenue, USD Billion, 2021 - 2033)
-
Mechanical Recycling
-
Chemical Recycling
-
Thermal Recycling
-
Others
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Apparel & Fashion
-
Home Textiles
-
Automotive Textiles
-
Industrial Textiles
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Central and South America
-
Brazil
-
-
Middle East and Africa
-
Saudi Arabia
-
-
Research Methodology
The pre-consumer textile waste recycling market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pre-consumer textile waste recycling segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Waste Generation Stage
Revenue capture definition
Spinning
Revenue generated from the collection, processing, and recycling of textile waste generated during fiber and yarn spinning, including hard waste, yarn waste, noils, sliver waste, and other spinning residues.
Weaving
Revenue generated from the collection, processing, and recycling of textile waste generated during weaving operations, including selvedges, yarn remnants, fabric edges, and weaving defects.
Knitting
Revenue generated from the collection, processing, and recycling of textile waste generated during knitting operations, including knitted fabric scraps, yarn waste, cutting remnants, and production rejects.
Dyeing, Printing & Finishing
Revenue generated from the processing and recycling of textile materials and fabric waste generated during dyeing, printing, and finishing operations, including rejected fabrics, process scraps, and finishing-stage production waste.
Garment Manufacturing
Revenue generated from the collection, sorting, processing, and recycling of textile waste generated during garment manufacturing, including fabric cutting waste, trimmings, defective garments, and production scraps.
Segment - Recycling Process
Revenue capture definition
Mechanical Recycling
Revenue generated from the mechanical processing of pre-consumer textile waste through sorting, cutting, shredding, opening, carding, and fiber recovery to produce recycled fibers, yarns, or other textile materials.
Chemical Recycling
Revenue generated from the chemical processing of pre-consumer textile waste to separate, dissolve, or depolymerize textile materials and produce regenerated fibers, cellulose, polymers, or other recycled feedstocks.
Thermal Recycling
Revenue generated from the thermal treatment of pre-consumer textile waste to recover materials, fuels, chemicals, or energy through processes such as pyrolysis, gasification, or other thermochemical conversion methods.
Others
Revenue generated from alternative recycling and recovery processes for pre-consumer textile waste that do not fall under mechanical, chemical, or thermal recycling, including specialized biological, enzymatic, or hybrid recycling processes.
Segment - End Use
Revenue capture definition
Apparel & Fashion
Revenue generated from recycled fibers, yarns, fabrics, and other textile materials produced from pre-consumer waste and supplied for use in apparel and fashion products.
Home Textiles
Revenue generated from recycled textile materials derived from pre-consumer waste and used in products such as bedding, towels, curtains, upholstery, carpets, and other household textile applications.
Automotive Textiles
Revenue generated from recycled textile fibers and materials derived from pre-consumer waste and supplied for automotive applications such as seat fabrics, interior components, insulation, carpets, and other textile-based components.
Industrial Textiles
Revenue generated from recycled textile materials produced from pre-consumer waste and used in industrial applications, including filtration, insulation, protective materials, geotextiles, and other technical textile products.
Others
Revenue generated from recycled textile materials derived from pre-consumer waste and used in applications outside apparel, home textiles, automotive textiles, and industrial textiles, including nonwovens, construction materials, furniture, and other specialty applications.
Estimation Model
Layer Name
Key Question
Description
Parent Market Analysis
What is the overall size and growth outlook of the global textile waste management and textile recycling markets?
The estimation begins with the broader global textile recycling and textile waste management market, covering collection, sorting, reuse, recycling, and recovery of textile materials. Textile and apparel production volumes, manufacturing waste generation, circular-economy initiatives, and demand for recycled fibers are assessed to establish the addressable market for pre-consumer textile waste recycling.
Pre-consumer Textile Waste Penetration Analysis
What proportion of the overall textile recycling market is represented by pre-consumer textile waste recycling?
This layer estimates the share of textile recycling attributable to pre-consumer waste, including fabric cutting waste, yarn waste, selvedges, production scraps, defective fabrics, and other manufacturing residues. Penetration is assessed based on textile manufacturing volumes, waste generation rates, material composition, recycling suitability, and the extent to which production waste is recovered and converted into recycled fibers or other products.
Regional & End-use Demand Assessment
Which regions and end-use industries contribute the highest demand for pre-consumer textile waste recycling?
Demand is assessed across major regions based on textile and apparel manufacturing activity, fiber and yarn production, garment production, home textiles, technical textiles, automotive textiles, and nonwoven applications. Regional textile production concentration, availability of recyclable manufacturing waste, recycled-fiber adoption, sustainability requirements, and demand from apparel brands and textile manufacturers are evaluated to determine regional market contribution.
Company Revenue Validation & Market Forecasting
How is the final market size validated and forecast?
Estimates are validated using company revenues, recycling capacity, processing volumes, product portfolios, manufacturing facilities, recycled-fiber output, partnerships, investments, and capacity expansions. Revenues attributable specifically to pre-consumer textile waste recycling are isolated where possible. Bottom-up and top-down approaches are triangulated with data on textile production, waste generation, recycling rates, and company-level data to develop market estimates and forecasts.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Pre-consumer Textile Waste Type & Recycling Route Assessment
Evaluate pre-consumer textile waste including fabric cutting waste, yarn waste, spinning waste, selvedges, rejected fabrics, and production scraps based on fiber composition, recyclability, processing requirements, and suitability for mechanical, chemical, and other recycling routes.
Helps textile manufacturers and recyclers identify high-potential waste streams and recycling technologies, supporting feedstock selection, technology positioning, and higher-value recovery opportunities.
Recycled Fiber & End-use Application Assessment
Assess demand for recycled materials across apparel, home textiles, technical textiles, automotive textiles, nonwovens, insulation, and industrial applications, based on recycled-fiber quality, performance requirements, and compatibility with end-use products.
Helps identify high-growth end-use applications and opportunities to move from conventional downcycling toward higher-value and fiber-to-fiber recycling applications.
Regional & Regulatory Opportunity Assessment
Evaluate regional demand based on textile and apparel manufacturing concentration, pre-consumer waste generation, recycling infrastructure, circular-economy initiatives, recycled-content requirements, EPR regulations, and sustainability standards.
Helps identify attractive geographic markets, regulatory-driven opportunities, and regions with strong feedstock availability, supporting market-entry and capacity-expansion decisions.
Frequently Asked Questions About This Report
Asia Pacific held the highest revenue market share of 41.0% in 2025, driven by its large textile manufacturing base, substantial pre-consumer waste generation, expanding recycling infrastructure, and growing adoption of circular textile production practices.
Key factors driving the pre-consumer textile waste recycling market include increasing textile manufacturing waste generation, rising demand for recycled fibers, growing adoption of circular production practices, and stricter sustainability and waste-management regulations.
Some key players in the pre-consumer textile waste recycling market include Birla Cellulose, FabScrap, Infinited Fibre Company, Martex Fiber, Lenzing AG, SaXcell, Hyosung TNC, UNIFI, Inc., Circ, and Kishco Group
The chemical recycling segment is the fastest-growing recycling process in the pre-consumer textile waste recycling market.
The global pre-consumer textile waste recycling market size was valued at USD 2.4 billion in 2025 and is estimated at USD 2.6 billion in 2026
The global pre-consumer textile waste recycling market is expected to grow at a compound annual growth rate of 8.6% from 2026 to 2033 to reach USD 4.6 billion by 2033.
The mechanical recycling segment accounted for the highest revenue share of 71.8% in 2025, driven by its established infrastructure, cost-efficient processing, and suitability for a wide range of pre-consumer textile waste streams.
The automotive textiles segment is the fastest-growing end use in the pre-consumer textile waste recycling market.
The apparel & fashion segment accounted for the largest revenue share of 44.8% in 2025, driven by strong demand for recycled fibers and yarns in sustainable clothing production and the growing adoption of circular fashion practices.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


