
- Home
- »
- Plastics, Polymers & Resins
- »
-
Pressure Sensitive Adhesives Market Size Report, 2033GVR Report cover

Pressure Sensitive Adhesives Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Tapes, Labels, Graphic Films), By Technology (Water-borne, Solvent-borne), By End Use (Packaging, Consumer Goods), By Adhesive Chemistry, By Region, And Segment Forecasts
Market Size, 2023
$13.7BMarket Estimate, 2026
$14.3BMarket Forecast, 2033
$18.8BCAGR, 2024–2033
4.0%Pressure Sensitive Adhesives Market Summary
The global pressure sensitive adhesives market size was valued at USD 13.7 billion in 2025 and is projected to grow from USD 14.3 billion in 2026 to USD 18.8 billion in 2033, at a CAGR of 4.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 40.0% in 2025. Market growth is anticipated to be driven by strong demand for pressure-sensitive tapes and labels in the packaging industry.
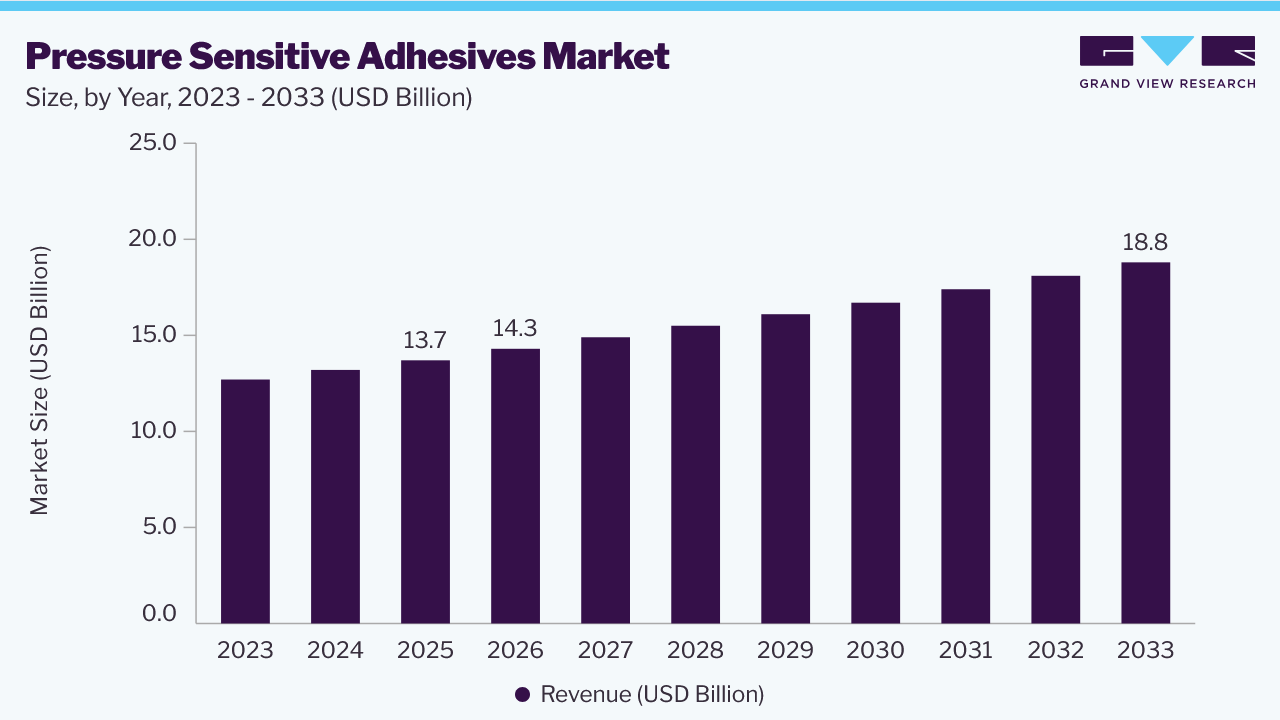 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The tapes segment held the largest market share of around 35.0% in 2025.
- By technology: The water-borne segment held the largest market share of around 38.5% in 2025.
- By adhesive chemistry: The acrylic segment held the largest market share of around 42.0% in 2025.
- By end use: The packaging segment held the largest market share of around 28.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (40.0% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 13.7 Billion
- Estimated market size in 2026: USD 14.3 Billion
- Projected market size by 2033: USD 18.8 Billion
- CAGR (2026-2033): 4.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2024–2033 annual, 2023 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
PSAs are easy to use and can tackle adhesion challenges across a variety of technologies and coatings in the packaging industry. Packaging requirements are becoming increasingly complex, especially in the food & beverages industry, due to product proliferation and rising competition. This is anticipated to open new avenues for the market as PSAs offer the flexibility to meet these complex requirements. PSAs are also used in other industries, such as automotive, where they serve end uses in safety and warning labels and component identification labels in the supply chain.
Pressure-sensitive adhesives are increasingly used across the packaging industry for labels, tapes, and flexible packaging applications owing to their strong adhesion, durability, and compatibility with high-speed production processes. The growing demand for sustainable packaging solutions is further encouraging the adoption of recyclable pressure-sensitive adhesives. For instance, in August 2024, Henkel Adhesive Technologies showcased its portfolio of pressure-sensitive adhesives for labels and packaging at Labelexpo Americas, including recyclable PSA solutions for tapes and labels as well as products approved for food packaging applications.
Analyst Perspective
The market is supported by expanding demand from packaging, automotive, healthcare, electronics, and construction industries, where efficient bonding, labeling, and surface protection solutions remain essential. The transition toward sustainable packaging materials and low-VOC adhesive technologies is encouraging manufacturers to develop high-performance formulations that comply with evolving environmental regulations. The growing adoption of lightweight materials, automation in manufacturing, and the increasing demand for durable specialty tapes and labels continue to broaden application areas. While fluctuations in raw material prices remain a key challenge, ongoing investments in sustainable adhesive technologies, capacity expansion, and product innovation are expected to support long-term market development.
Product Insights
The tapes segment held the largest market share of around 35.0% in 2025. Water-borne pressure-sensitive adhesives accounted for the largest market share owing to their low VOC emissions, regulatory compliance, and widespread adoption across labeling and packaging applications. Their compatibility with paper substrates and food-contact labeling continues to support demand across the packaging and consumer goods industries. The increasing use of self-adhesive labels across food & beverages, pharmaceuticals, logistics, consumer goods, and industrial packaging continues to support segment growth. Acrylic emulsion-based pressure-sensitive labels remain widely adopted owing to their excellent adhesion performance, process efficiency, and compatibility with high-speed labeling operations.
Graphic films are expected to register the fastest CAGR during the forecast period. Pressure-sensitive adhesives are used in graphic films across numerous applications, including branding graphics, road traffic signage, advertising graphics, large format weather-resistant graphics, home décor, outdoor advertising, point-of-purchase promotions, and vehicle graphics. Branding and advertising graphics are gaining greater emphasis in the corporate strategies of multinational companies, as brand logos and advertising play a crucial role in influencing consumer demand. For instance, in September 2024, Avery Dennison introduced its Supreme Wrapping Film, a color collection called Bright Escapes. The three-color collection expands the Supreme Wrapping Film portfolio and is designed for color-change vehicle wraps, offering outstanding durability, performance, and easy application.
Technology Insights
The water-borne segment held the largest market share of around 38.5% in 2025. This is attributed to its environmentally friendly nature and its significant adoption in the manufacturing of tapes and labels. Water-based PSAs are extensively used on paper and are preferred over other technologies for food & beverage labels. Moreover, they are used to produce general-purpose permanent, removable, and pharmaceutical labels. For instance, in August 2024, Avery Dennison introduced its innovations in labeling technology at Labelexpo Americas. The company will demonstrate labeling materials with a lower carbon footprint, solutions that advance sustainability and circularity, next-generation label technology, and connected packaging solutions.
Radiation-cured (UV-cured) materials are expected to register the fastest CAGR during the forecast period. The technology is designed to meet a variety of end-use requirements, including the tapes and labels in different end-use industries, such as food packaging, automotive, and Electronics. They have similar advantages to those of solvent-based acrylic, including resistance to cleaners and solvents. Moreover, they do not require special ovens to dry and have no appreciable VOC emissions.
Adhesive Chemistry Insights
The acrylic segment held the largest market share of around 42.0% in 2025. They are generally used on paper and on polar surfaces such as glass, steel, aluminum, polycarbonate, zinc, tin, and Polyvinyl Chloride (PVC). Rubber-based products are typically based on hot-melt and solvent-based systems. The adoption of rubber-based products in tapes is driven by their ability to provide quick adhesion to both rough and smooth surfaces.
Silicone is expected to register the fastest CAGR during the forecast period. Silicone-based pressure-sensitive adhesives are expected to witness the fastest growth owing to their superior resistance to extreme temperatures, UV exposure, chemicals, and weathering, making them well-suited for demanding industrial, automotive, aerospace, and electronics applications.
End Use Insights
The packaging segment held the largest market share of around 28.0% in 2025. Tapes find various applications in the packaging industry, ranging from containers, boxes, and envelopes to bank bags and pouches. Self-adhesive labels are widely used for packaged food & beverages, beauty products, warehouse boxes, jars, pharmaceuticals, and other packaging. The user-friendly nature and rapid bonding speed of tapes and self-adhesive labels are major factors driving demand for these products in the packaging industry.
PSAs are also used in the building & construction industry for applications such as automotive, roofing linings, vapor barriers, masking, and interior design. Growing investments in energy-efficient buildings and advanced construction materials continue to expand the use of pressure-sensitive adhesives across roofing membranes, insulation systems, vapor barriers, interior finishing, and specialty construction tapes.
The automotive industry is expected to register the fastest growth owing to the increasing adoption of lightweight bonding solutions that improve manufacturing efficiency while reducing vehicle weight. Pressure-sensitive adhesives are increasingly replacing conventional fastening methods across interior components, trim assemblies, wiring systems, and electric vehicle applications, supporting lightweight vehicle design and production automation.
Regional Insights
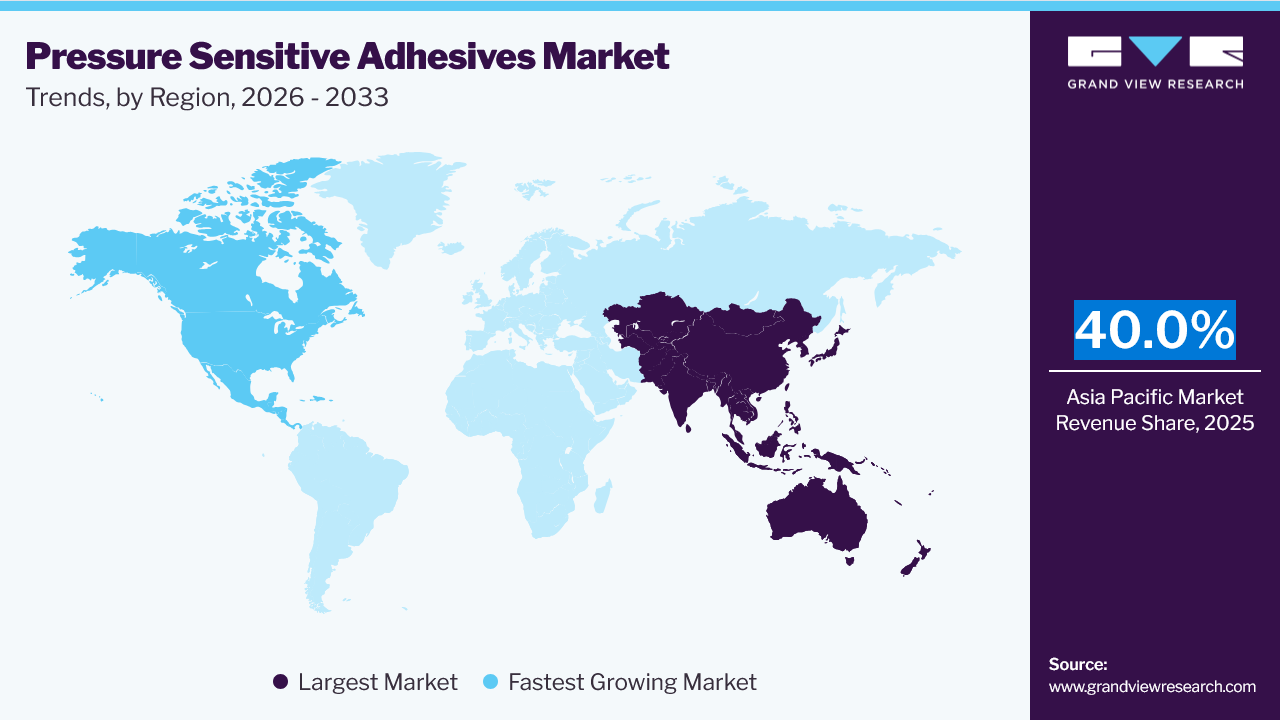
Asia Pacific dominated the pressure sensitive adhesives market, accounting for approximately 40.0% of revenue in 2025. The growing economies in the region, especially in China and India, are driving higher demand for consumer products, increasing the need for packaging and labeling options. The strong growth of the automotive industry and the increasing emphasis on electric vehicles and lightweight parts are driving the use of PSAs in assembly and bonding processes. Moreover, rapid urbanization and infrastructure growth in the construction sector are creating opportunities for PSA-based insulation, roofing, and flooring products.
 To learn more about this report, Download Free Sample Report
India Pressure Sensitive Adhesives Market Trends
The pressure sensitive adhesives market in India held a substantial share in 2025, driven by growth in the automotive industry and government initiatives supporting electric vehicle and automotive component manufacturing, which are increasing the adoption of PSAs in assembly and bonding applications. Rapid urbanization and infrastructure development are also driving demand for PSA-based products used in roofing, insulation, and flooring applications. In addition, the expanding electronics manufacturing sector is driving market growth by increasing demand for reliable adhesive solutions for electronic components. For instance, in February 2025, Henkel opened a state-of-the-art Application Engineering Center in Chennai, India, to support electronics customers with advanced adhesive solutions. The company also announced plans to establish an adhesive materials manufacturing facility at its multi-technology manufacturing site in Pune to strengthen its electronics business in India.
North America Pressure Sensitive Adhesives Market Trends
The pressure sensitive adhesives market in North America is expected to grow at the fastest CAGR during the forecast period. Growth is supported by rising demand from the construction industry, where pressure-sensitive adhesives are widely used in insulation systems, roofing membranes, and flooring applications. The expanding healthcare sector is also contributing to market growth through increasing demand for medical tapes, wound care products, and drug delivery systems. In addition, the continued expansion of e-commerce is driving demand for PSA-based packaging and labeling materials, while rising vehicle electrification is supporting the adoption of lightweight adhesive solutions in automotive manufacturing.
The U.S. pressure sensitive adhesives market dominated North America in 2025. Several main factors drive the U.S. pressure-sensitive adhesives (PSA) market. The growing e-commerce sector plays a key role, as PSAs are vital for packaging and mailing items. Furthermore, the increasing emphasis on vehicle electrification is driving the adoption of PSA in the automotive industry, driven by demand for lightweight, efficient components.
Europe Pressure Sensitive Adhesives Market Trends
The pressure sensitive adhesives market in Europe accounted for a significant market share in 2025, supported by ongoing advancements in adhesive technologies and rising demand for high-performance products across packaging, automotive, healthcare, and industrial applications. The region's strong focus on sustainability is accelerating the adoption of pressure-sensitive adhesives formulated with renewable and recyclable materials. In addition, stringent environmental regulations and increasing demand for sustainable packaging solutions continue to encourage the development of eco-friendly adhesive technologies across the region.
Key Pressure Sensitive Adhesives Company Insights
Key players in the market are focusing on expanding their customer base to gain a competitive advantage. Hence, major stakeholders are implementing various strategic actions, including mergers, acquisitions, and collaborations with other leading firms.
Key Pressure Sensitive Adhesives Companies
The following key companies have been profiled for this study on the pressure sensitive adhesives market:
-
Henkel Corporation
-
Bostik
-
Momentive Performance Materials
-
3M
-
Avery Dennison Corp.
-
tesa Tapes
-
Nitto Denko Corporation
-
Ashland
-
H.B. Fuller Company
-
Arkema
-
Dow
-
Eastman Chemical Company
Recent Developments
- In January 2026, Henkel acquired Switzerland-based ATP Adhesive Systems from Arsenal Capital Partners. The acquisition expands Henkel's portfolio of water-based high-performance pressure-sensitive tape technologies used across building and construction, automotive, electronics, and graphics applications, further strengthening its adhesive solutions portfolio.
- In April 2024, Bostik, an Arkema company specializing in adhesive solutions, announced an investment to expand its UV acrylic hot melt pressure-sensitive adhesive (HMPSA) production capabilities at its North American facilities. The investment supports the company's portfolio of high-performance adhesive solutions for industrial and specialty applications.
- In May 2024, Arkema acquired Dow's flexible packaging laminating adhesives business. The acquisition expands Arkema's portfolio of packaging adhesive solutions and strengthens its position in the flexible packaging adhesives market.
Pressure Sensitive Adhesives Market Report Scope
Report Attribute
Details
Market size in 2025
USD 13.7 billion
Estimated market size in 2026
USD 14.3 billion
Projected market size by 2033
USD 18.8 billion
Growth rate
CAGR of 4.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, technology, adhesive chemistry, end use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; Mexico; Germany; UK; France; Spain; Italy; China; Japan; India; Brazil; Argentina; Colombia; Saudi Arabia; South Africa
Key companies profiled
Henkel Corporation; Bostik; Momentive Performance Materials; 3M; Avery Dennison Corp.; tesa Tapes; Nitto Denko Corporation; Ashland; B. Fuller Company; Arkema; Dow; Eastman Chemical Company
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Pressure Sensitive Adhesives Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pressure sensitive adhesives market report based on product, technology, adhesive chemistry, end use, and region:
-
Product Outlook (Revenue, USD Billion, Kilo Tons, 2021 - 2033)
-
Tapes
-
Labels
-
Graphic Films
-
Others
-
-
Technology Outlook (Revenue, USD Billion, Kilo Tons, 2021 - 2033)
-
Water-borne
-
Solvent-borne
-
Hotmelt
-
Radiation Cured (UV Cured)
-
-
Adhesive Chemistry Outlook (Revenue, USD Billion, Kilo Tons, 2021 - 2033)
-
Acrylic
-
Rubber
-
Silicone
-
Others
-
-
End Use Outlook (Revenue, USD Billion, Kilo Tons, 2021 - 2033)
-
Automotive
-
Electrical & Electronics
-
Consumer Goods
-
Packaging
-
Construction
-
Others
-
-
Regional Outlook (Revenue, USD Billion, Kilo Tons, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Latin America
-
Brazil
-
Argentina
-
Colombia
-
-
Middle East and Africa (MEA)
-
South Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
The global pressure sensitive adhesives market size was valued at USD 13.7 billion in 2025 and is estimated at USD 14.3 billion in 2026.
The global pressure sensitive adhesives market is expected to grow at a CAGR of 4.0% from 2026 to 2033, reaching USD 18.8 billion.
Asia Pacific dominated with an approximately 40.0% revenue share in 2025.
The tapes segment accounted for the largest revenue share of around 35.0% in 2025.
Key players in the market include Henkel Corporation, Bostik, Momentive Performance Materials, 3M, Avery Dennison Corp., tesa Tapes, Nitto Denko Corporation, Ashland, B. Fuller Company, Arkema, Dow, Eastman Chemical Company, and others.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


