
- Home
- »
- Next Generation Technologies
- »
-
Satellite Manufacturing Market Size & Share Report, 2033GVR Report cover

Satellite Manufacturing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Category (LEO, MEO, GEO), By Mass (Large Satellites, Medium-sized Satellites, Nano Satellites), By Type of Business (Government, Commercial), By Application, By Region, And Segment Forecasts
Market Size, 2025
$27.1BMarket Estimate, 2026
$32.6BMarket Forecast, 2033
$75.8BCAGR, 2026–2033
12.8%Satellite Manufacturing Market Summary
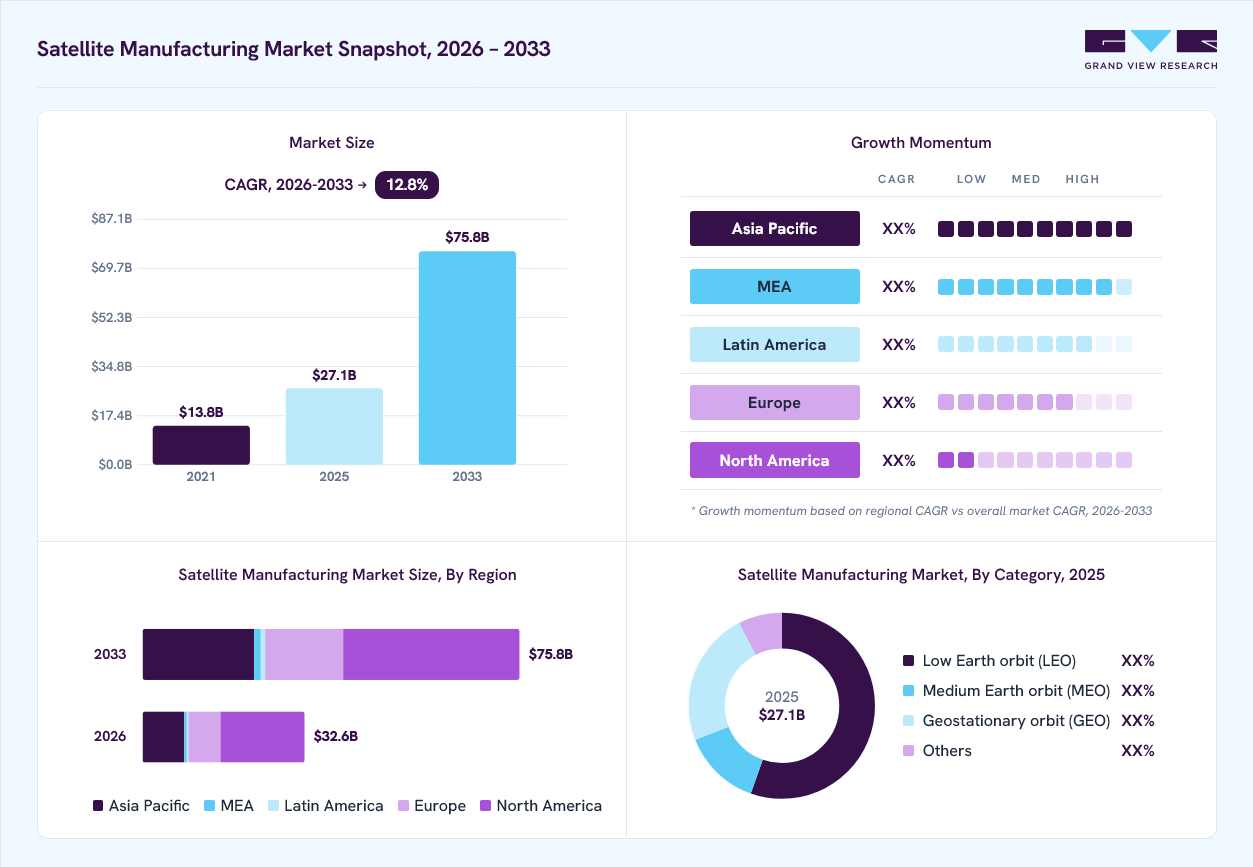
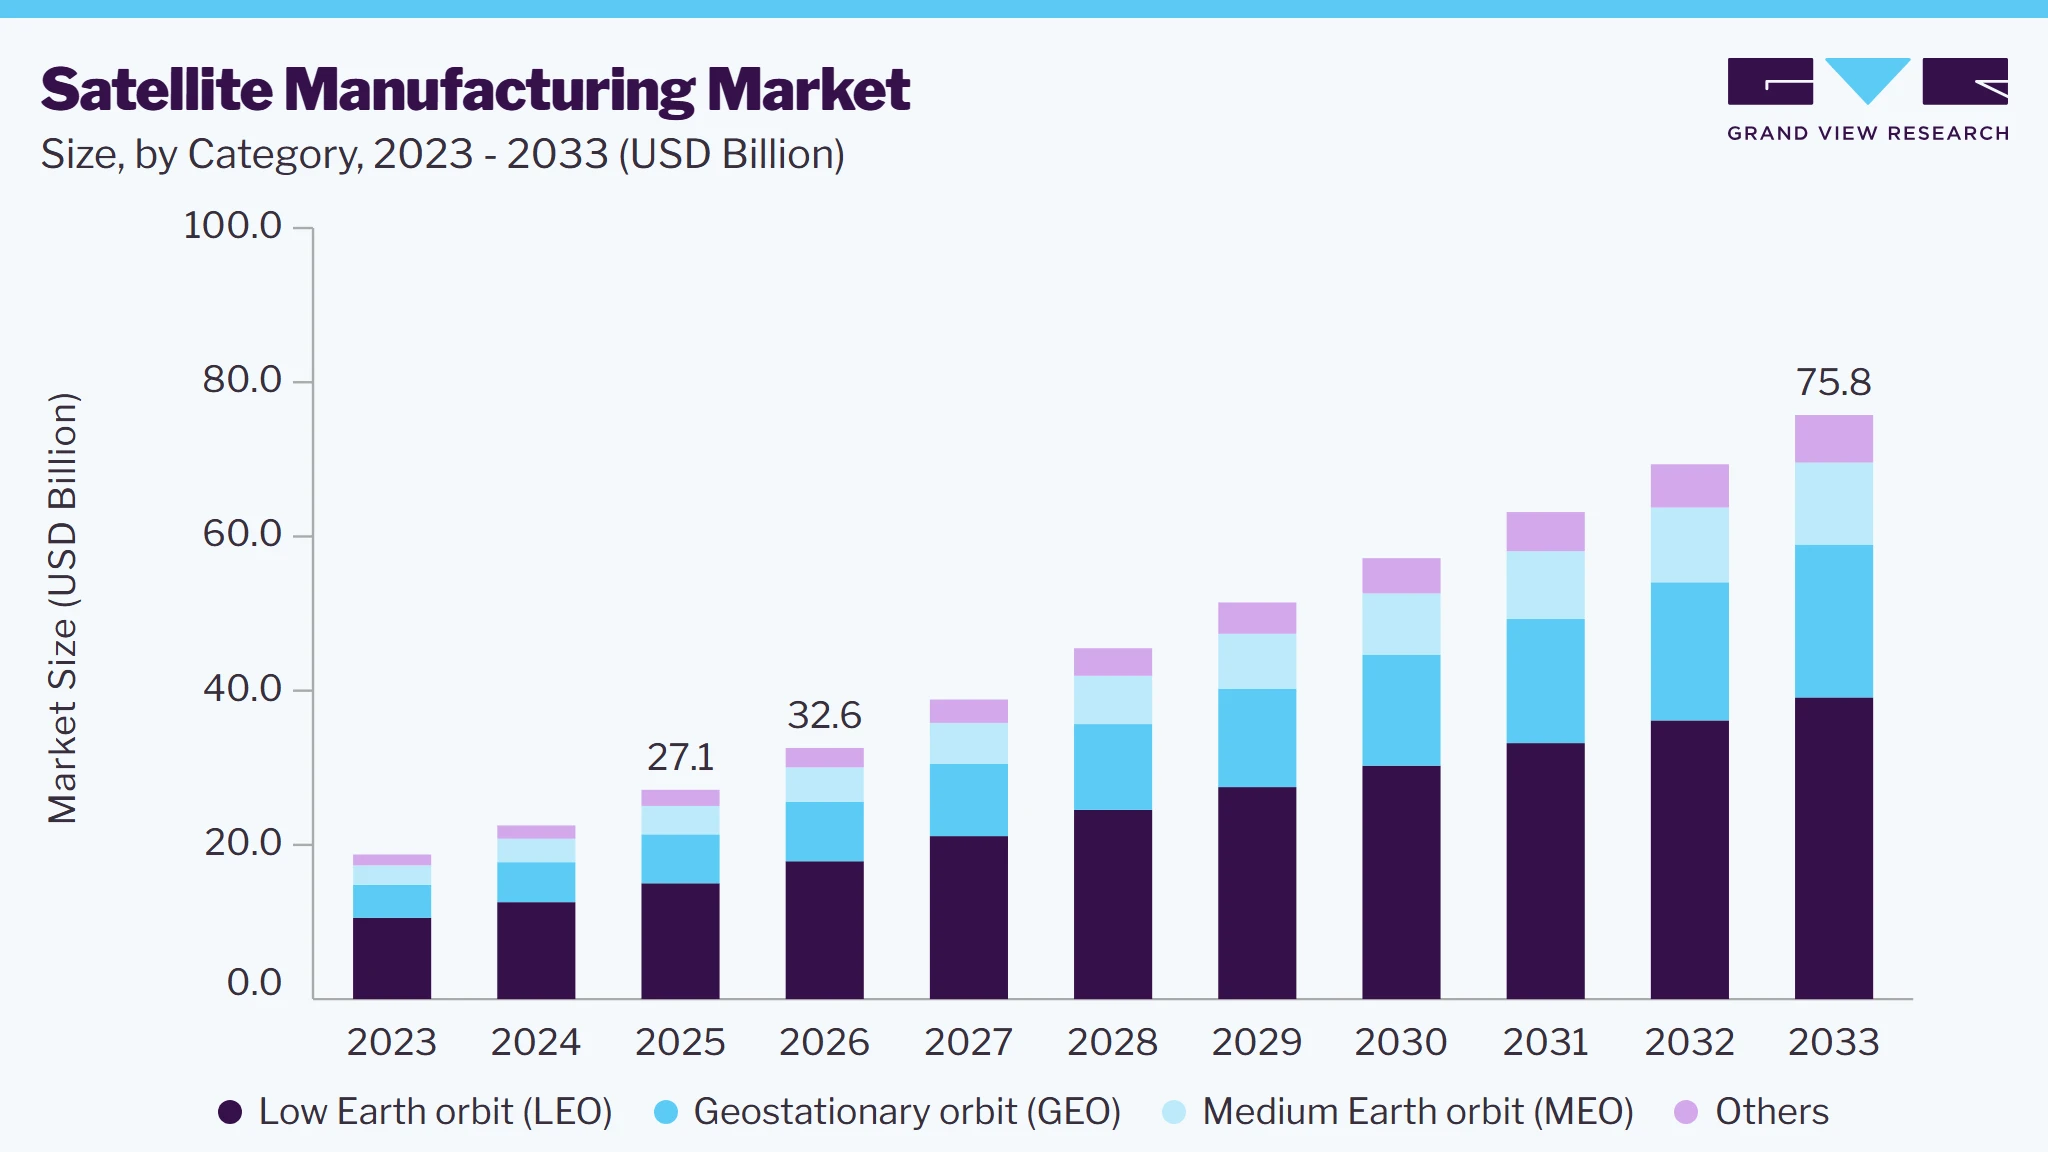
The global satellite manufacturing market size was valued at USD 27.1 billion in 2025 and is projected to grow from USD 32.6 billion in 2026 to USD 75.8 billion by 2033, at a CAGR of 12.8% from 2026 to 2033. North America dominated the global market, accounting for the largest revenue share of 52.7% in 2025. The satellite manufacturing market growth is primarily driven by the increasing demand for satellite-based communication, Earth observation, navigation, and defense applications, rising investments in commercial space programs, and the expansion of low Earth orbit (LEO) satellite constellations.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By category: The low-earth orbit (LEO) segment accounted for the largest market share of 55.3% in 2025.
- By mass: The medium-sized satellites segment led the market with a share of 68.5% in 2025.
- By type of business: The commercial segment dominated the market with a share of 75.4% in 2025.
- By application: The communication segment led the market with a share of 47.3% in 2025.
Regional Highlights
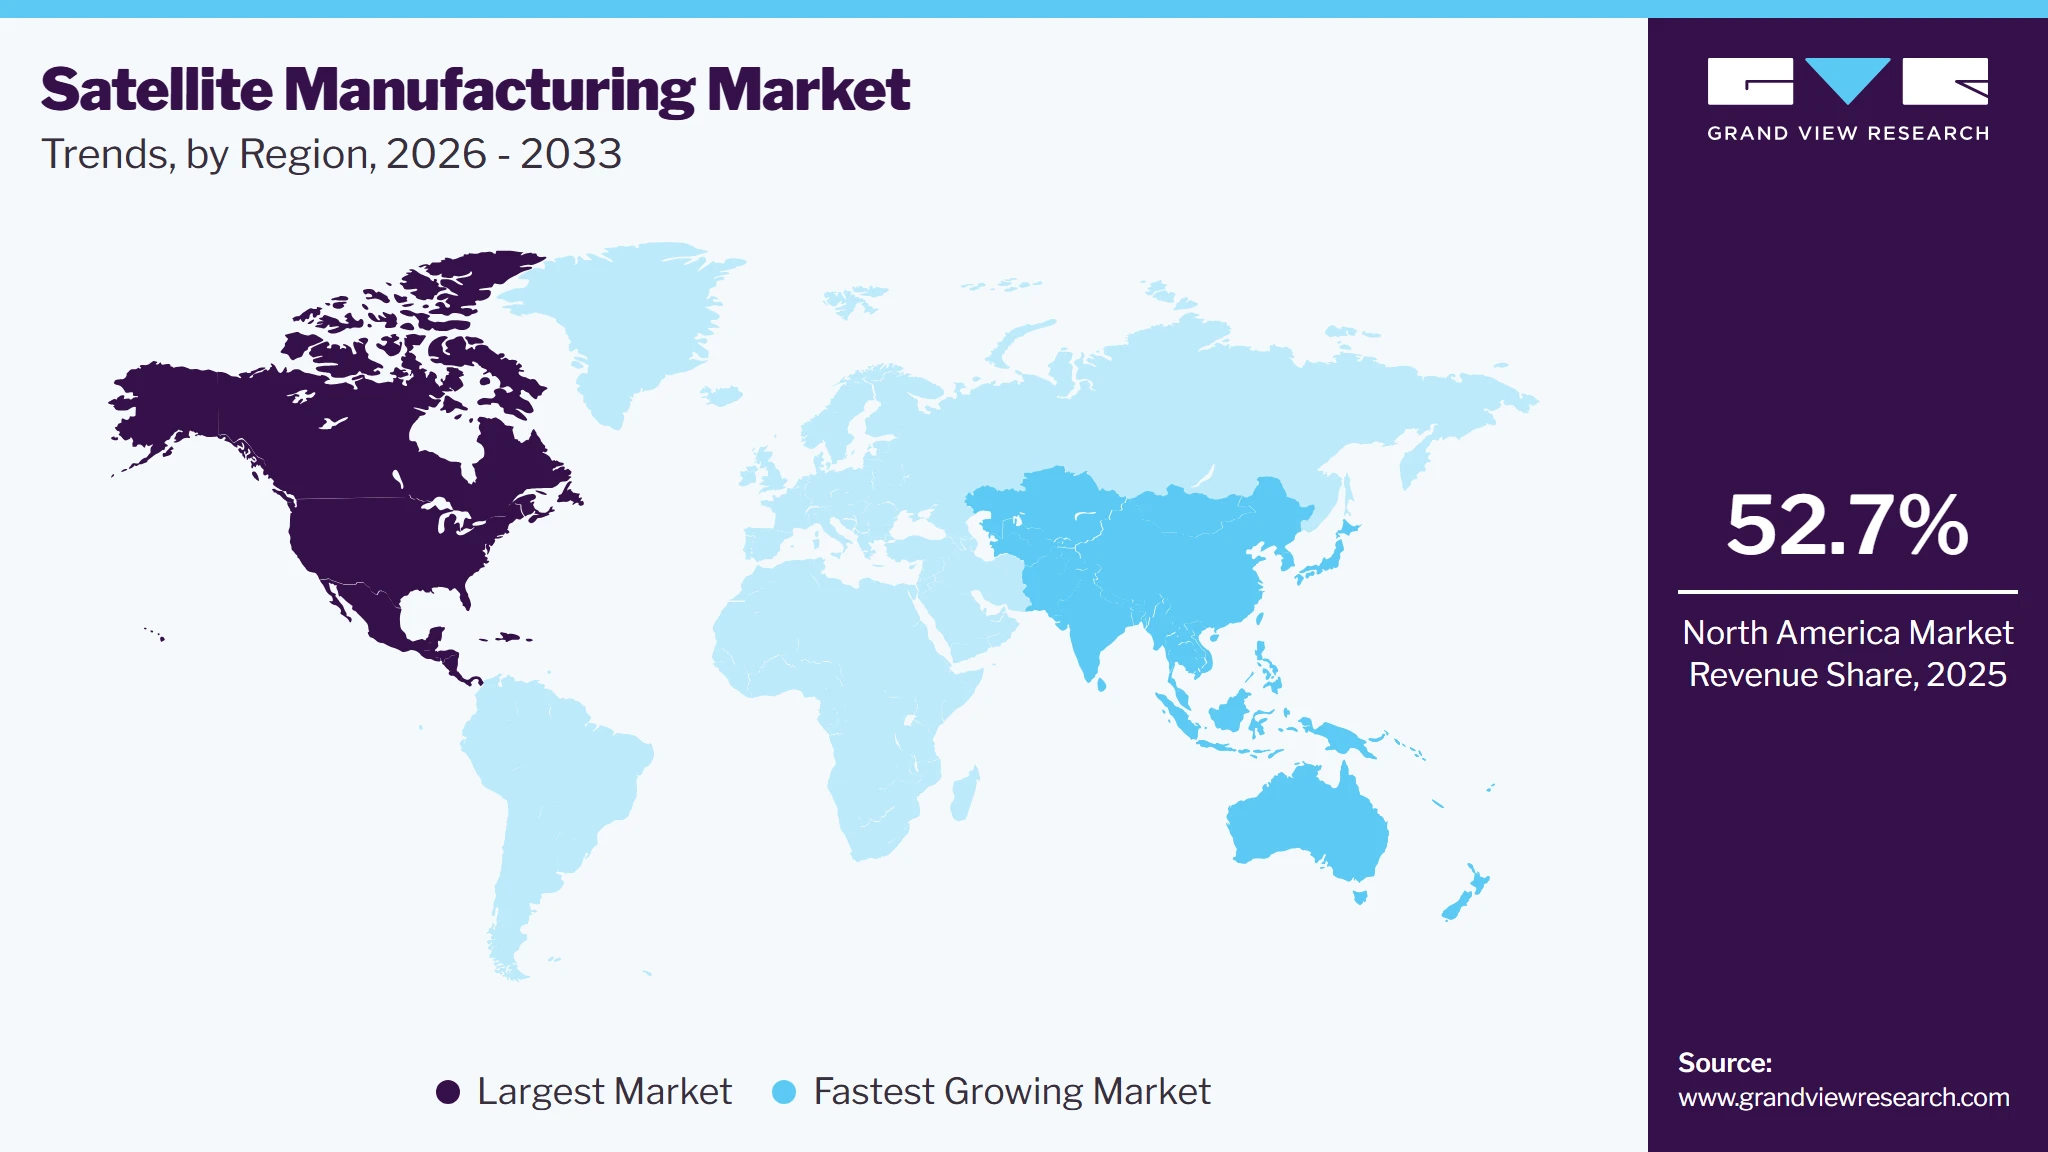
- Largest regional market: North America (52.7% revenue share in 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR 15.1%, 2026-2033)
- By Country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 27.1 Billion
- Estimated market size in 2026: USD 32.6 Billion
- Projected market size by 2033: USD 75.8 Billion
- CAGR (2026-2033): 12.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These satellites provide high-resolution imagery and data that support better decision-making and policy formulation across industries and government agencies, fueling their adoption for a wider range of commercial and governmental applications. The satellite manufacturing industry is seeing a substantial increase in the deployment of small satellites and CubeSats due to their cost-effectiveness, faster development cycles, and adaptability for low-Earth orbit (LEO) missions. Small satellites, including CubeSats, are increasingly used for telecommunications, research, and IoT applications, as they are cheaper to manufacture, launch, and maintain compared to traditional large satellites. This trend is particularly popular among new market entrants, private companies, and startups, which seek affordable solutions to access space.Technological advancements in satellite miniaturization are making it possible to design satellites with enhanced capabilities while reducing their size and weight. This trend not only supports the deployment of more satellites in constellations but also enables the integration of advanced technologies, such as AI, quantum communication, and laser-based data transmission. Miniaturization is helping reduce the overall cost and energy consumption of satellite operations, further accelerating the growth of satellite manufacturing industry by making satellite-based solutions more accessible.
 To learn more about this report, Download Free Sample Report
Satellites play a key role in facilitating secure and reliable communication between military units, command centers, and allied forces, even in remote or hostile environments. Satellite communication systems provide the backbone for voice, data, and video transmissions, allowing for seamless operational coordination. As militaries seek to maintain connectivity across dispersed forces, the demand for robust satellite communication systems continues to grow, driving investment in satellite manufacturing.
The satellite manufacturing industry is witnessing rapid growth, driven by increasing demand for small satellites, advancements in AI and automation, and expanding commercial applications. Governments, defense agencies, and private companies are investing heavily in satellite technology for communications, Earth observation, navigation, and scientific research. The shift toward miniaturization is a key trend, with small satellite constellations in low Earth orbit (LEO) gaining traction for broadband internet. Additionally, AI-powered satellite operations, edge computing, and quantum communication are enhancing satellite efficiency and security. The push for sustainability has also led to innovations in reusable satellite components and debris mitigation strategies, shaping the future of satellite manufacturing industry.
Another major trend in the satellite manufacturing industry is the push for sustainability and reusability in satellite manufacturing. Companies are developing modular and reusable satellite components to reduce space debris and mission costs. The use of advanced propulsion technologies, such as electric and ion propulsion, is improving fuel efficiency and extending satellite lifespans. Quantum communication is also emerging as a game-changer, enhancing data security for military and commercial applications. Meanwhile, mega-constellations, such as SpaceX’s Starlink and Amazon’s Project Kuiper, are driving advancements in mass production and satellite networking. With increasing collaborations between private companies and government agencies, innovations in AI, IoT, and energy-efficient materials are expected to further shape the future of satellite manufacturing, improving performance, reliability, and cost-effectiveness.
Market Dynamics
The satellite manufacturing market is experiencing robust growth, driven by the increasing demand for earth observation and remote sensing satellites, supported by their expanding applications in environmental monitoring, precision agriculture, disaster management, and urban planning is significantly driving the market growth. Additionally, technological advancements in satellite design, manufacturing processes, and component integration are further accelerating the market innovation.
The rise of the Internet of Things (IoT) and the expansion of 5G networks present new applications for satellite technology. Satellites can bridge connectivity gaps in regions lacking traditional network infrastructure, supporting IoT applications in areas like agriculture, mining, logistics, and maritime operations. This expanding use of satellites in IoT and 5G networks creates opportunities for manufacturers to produce specialized satellites tailored for connectivity in these sectors.
Furthermore, the integration of advanced communication technologies, high-throughput satellites, and low Earth orbit (LEO) constellations is enhancing satellite connectivity capabilities, enabling faster data transmission, lower latency, and scalable network solutions. This growth is encouraging satellite manufacturers to develop next-generation communication satellites that support emerging applications such as smart cities, autonomous systems, connected devices, and industrial IoT networks.
The satellite manufacturing industry operates within a complex and evolving regulatory landscape, which can pose challenges for manufacturers. Different countries have varying regulations regarding satellite launches, spectrum allocation, and environmental compliance. Navigating these regulatory frameworks can be time-consuming and resource-intensive, leading to delays in satellite deployment. Moreover, stringent regulations concerning space debris management and the licensing of satellite frequencies add layers of complexity, potentially hindering the growth of the market.
The demand for high-speed internet and connectivity in remote or underserved regions is driving investment in LEO satellite constellations. Companies like SpaceX and Amazon are actively developing satellite networks to deliver global broadband coverage, creating significant opportunities for satellite manufacturers.
The lower altitude of LEO satellites offers reduced latency, appealing to various industries requiring real-time data, such as telecommunication, defense, and finance. This trend is expected to provide manufacturers with ongoing contract opportunities as LEO satellite constellations expand.
Market Concentration & Characteristics
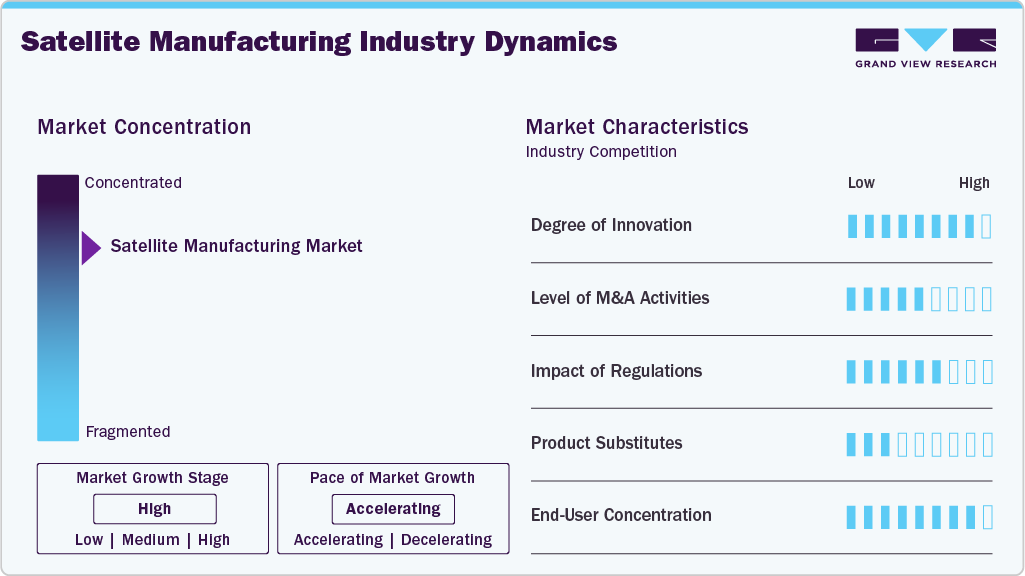
The satellite manufacturing market is moderately concentrated, comprising established aerospace and defense companies, commercial satellite manufacturers, and emerging space technology firms. The market is driven by innovation in small satellite platforms, modular designs, advanced payloads, AI-enabled systems, electric propulsion, automated manufacturing, and sustainable space technologies. Mergers and acquisitions remain moderate, with companies investing in satellite technology providers, component manufacturers, and space startups to expand capabilities, strengthen supply chains, and accelerate innovation.
 To learn more about this report, Download Free Sample Report
Regulatory influence is high, shaped by satellite licensing, spectrum allocation, export controls, orbital management, and space sustainability requirements. Product substitution is low to moderate, as alternatives such as terrestrial networks and high-altitude platforms have limited applicability for many satellite functions. Market demand is diversified across commercial, government, and defense sectors, supported by growing LEO constellation deployments, communication needs, Earth observation applications, military surveillance programs, and increasing investments in space infrastructure.
Analyst Perspective
The satellite manufacturing market is experiencing strong structural growth, driven by the increasing demand for satellite-based communication, Earth observation, navigation, defense, and scientific applications, rapid expansion of low Earth orbit (LEO) satellite constellations, rising government investments in space infrastructure and national space programs, growing participation of private space companies, advancements in small satellite platforms, modular manufacturing, and automation technologies, and the increasing need for real-time data, connectivity, and space-based intelligence solutions across commercial and government sectors.
Category Insights
Based on category, the low earth orbit (LEO) segment dominated the market with the largest revenue share of 55.3% in 2025, driven by factors such as the increasing demand for earth observation and satellite-based services. This demand stems from various sectors, including agriculture, environmental monitoring, and telecommunications, where real-time data is essential for decision-making.
The geostationary orbit (GEO) segment is expected to register the fastest CAGR of over 14.4% from 2026 to 2033. The growth of this segment is driven by the need for high-capacity communication systems. GEO satellites provide continuous coverage over specific areas, making them ideal for broadcasting and telecommunications services. The rising demand for direct-to-home (DTH) services and high-definition content has spurred investments in GEO satellite technology.
Mass Insights
Based on mass, the medium-sized satellites dominated the market with the largest revenue share of 68.5% in 2025, owing to the growing demand for versatile communication and monitoring services. These satellites are increasingly utilized for applications such as Earth observation, telecommunications, and scientific research. The rise in global internet connectivity and the need for real-time data transmission have spurred investments in medium-sized satellite technology.
The nano satellites segment is expected to witness a notable CAGR from 2026 to 2033, driven by the growing demand for nano satellites due to their cost-effectiveness and versatility in various applications. These small satellites are particularly favored for Earth observation, technology demonstration, and educational purposes. The increasing interest from startups and academic institutions in deploying nano satellites for research and commercial purposes is driving the expansion of satellite manufacturing industry.
Type of Business Insights
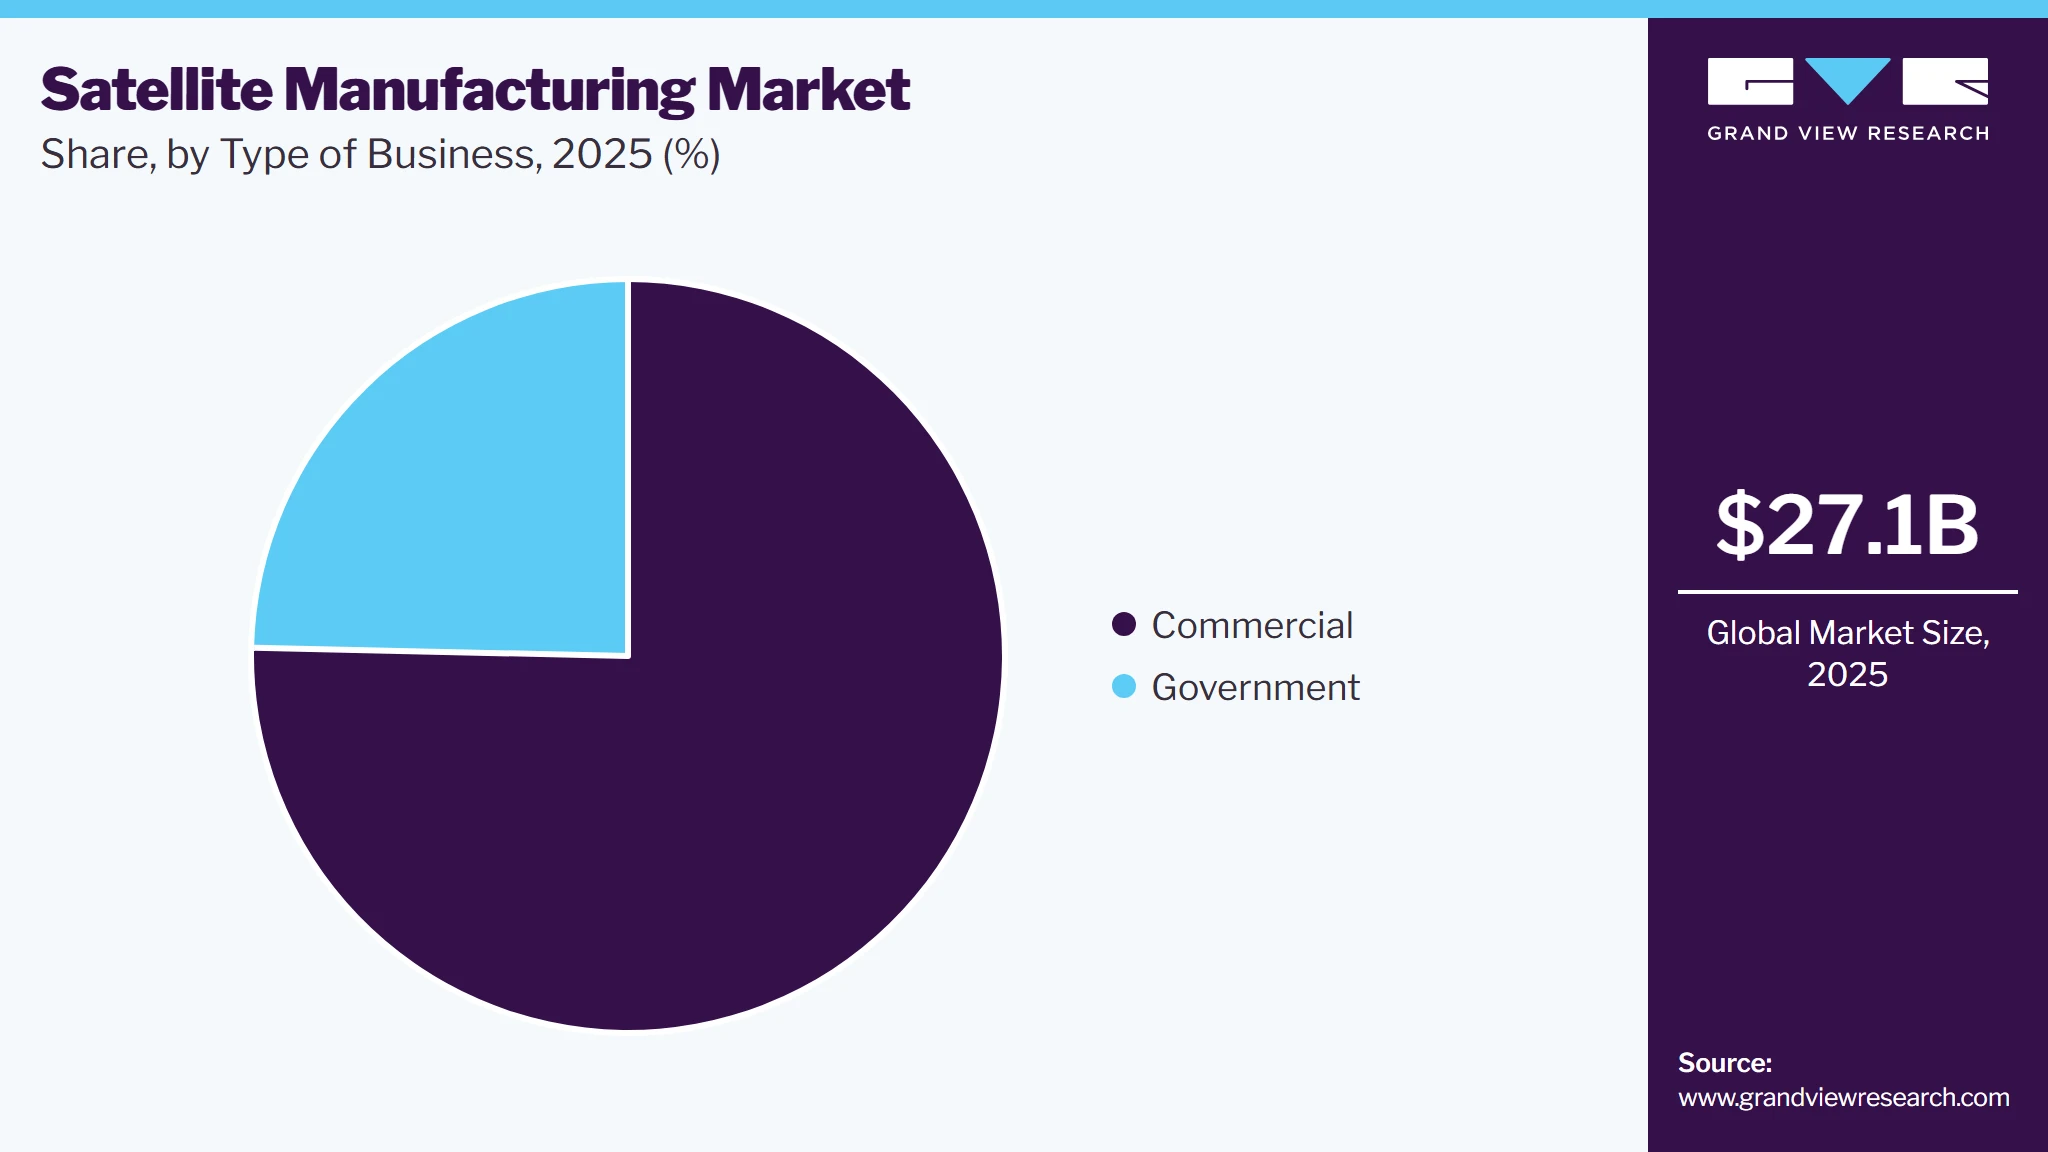
Based on type of business, the commercial segment led the market with the largest revenue share of 75.4% in 2025, owing to the increasing demand for satellite-based services across various sectors, including telecommunications, Earth observation, and internet connectivity. The rise of digital technologies and the need for high-speed internet access, especially in remote and underserved regions, are significant factors propelling the demand for commercial satellites.
 To learn more about this report, Download Free Sample Report
The government segment is expected to register the notable CAGR from 2026 to 2033, driven by the increasing reliance on satellite technologies for national security, surveillance, and communication. Governments worldwide are investing heavily in satellite systems to enhance their capabilities in areas such as reconnaissance, disaster management, and environmental monitoring. The need for secure and reliable communication channels, particularly in defense applications, has led to a surge in demand for government-operated satellites.
Regional Insights
North America dominated the satellite manufacturing market, accounting for the largest revenue share of 52.7% in 2025, driven by increasing demand for speed communications, national security needs, and advancements in earth observation technologies. Additionally, government support through NASA, the Department of Defense, and private-public partnerships drives innovation in satellite technology. The growing use of satellites for environmental monitoring, weather forecasting, and emergency response is also contributing to the satellite manufacturing industry growth, as satellite data becomes critical for various sectors.
 To learn more about this report, Download Free Sample Report
U.S. Satellite Manufacturing Market Trends
The satellite manufacturing market in the U.S. held the largest share in the North America region in 2025. The market growth is fueled by strong government funding, private sector innovation, and a rapidly growing demand for commercial satellites. NASA, the U.S. Department of Defense, and agencies like the National Reconnaissance Office (NRO) play a critical role in advancing satellite capabilities for defense, Earth observation, and deep space exploration. Additionally, government initiatives such as the U.S. Space Force and increased commercial-military partnerships are shaping the future of satellite manufacturing, solidifying the U.S. as a dominant force in the global space industry.
Asia Pacific Satellite Manufacturing Market Trends
The Asia Pacific satellite manufacturing market is anticipated to grow at a CAGR of around 15.1% from 2026 to 2033. This growth is attributed to the increasing government investments, rising commercial space ventures, and advancements in satellite technology. Countries such as China, Japan, India, and South Korea are leading the region, with strong support from space agencies such as CNSA, JAXA, ISRO, and KARI. Private space startups are also emerging, particularly in China and India, fostering innovation and cost-effective satellite production. Additionally, advancements in AI, quantum communication, and reusable satellite technologies are shaping market trends.
Japan Satellite Manufacturing Market Trends
The Japan satellite manufacturing market is expected to grow rapidly in the coming years due to a focus on high-tech, high-performance satellites for a range of applications, including Earth observation, communication, and scientific research, advancements in miniaturization, precision, and innovative payload technologies, and growing focus on enhancing satellite communication infrastructure, with developments in both low Earth orbit (LEO) and geostationary orbit (GEO) satellite constellations.
China Satellite Manufacturing Market Trends
The China satellite manufacturing market held a substantial market share in 2025. The growth is attributed to strong government support, military-space advancements, and a growing commercial space sector, and growing adoption of small satellite constellations for broadband internet and leveraging AI and quantum communication technologies to enhance satellite capabilities.
Europe Satellite Manufacturing Market Trends
Europe satellite manufacturing market is expected to grow at a considerable CAGR of over 13.6% from 2026 to 2033, driven by the rising demand for small satellites, government investments, and technological advancements. The European Space Agency (ESA) plays a key role in fostering innovation, and supporting projects in Earth observation, telecommunications, and defense. The shift toward miniaturization, AI-powered satellite operations, and reusable technologies is shaping market trends. Additionally, growing commercial investments and international collaborations are enhancing Europe's competitiveness in the global satellite industry.
UK Satellite Manufacturing Market Trends
The UK satellite manufacturing market is expected to grow rapidly in the coming years. In the UK satellite manufacturing demand is rising due to the government support, private investments, and a strong focus on small satellite technology, and increasing collaborations with international space agencies and private players.
Germany Satellite Manufacturing Market Trends
The Germany satellite manufacturing market held a substantial market share in 2025, driven by increasing demand for small satellites, advancements in space technology, and government initiatives supporting space exploration and defense. The market is seeing strong adoption of satellite miniaturization, AI-powered satellite operations, and reusable satellite components to enhance cost efficiency and sustainability.
Key Satellite Manufacturing Company Insights
Some of the key players operating in the market include Thales Group, Lockheed Martin Corporation among others.
-
Thales Group is a global technology company, specializing in defense, security, aerospace, and digital identity, among other fields. The company focuses on advancing digital and "deep tech" innovations, including AI, cybersecurity, and quantum technology, to create reliable solutions that support the vital missions of governments and organizations. The company designs and manufactures advanced satellite systems for communication and Earth observation, leveraging its expertise to enhance connectivity and data transmission capabilities essential for modern applications.
-
Lockheed Martin Corporation is an aerospace & defense company that focuses on delivering innovative solutions to complex global challenges. The company specializes in advanced technology systems across various fields, including aeronautics, space, missile defense, and cybersecurity. The company is recognized for its commitment to enhancing national security and advancing technological capabilities by leveraging AI and connected protection systems.
Dhruva Space Private Limited and Maxar Technologies Inc. are some of the emerging participants in the virtual tour market.
-
Dhruva Space Private Limited is an aerospace manufacturing company specializing in developing small satellites. The company provides full-stack space engineering solutions that encompass the design, launch, and operation of satellites. The company has been involved in various space missions, including the Thybolt Mission, which marked the deployment of India's first private satellites. The company provides integrated launch services, ensuring rapid deployment of satellites across various platform sizes and launch vehicle providers. Dhruva Space develops scalable and modular satellite platforms ranging from less than 1 kg to 300 kg, catering to commercial, defense, and scientific missions in Low Earth Orbit (LEO) and beyond.
-
Maxar Technologies Inc. is a space technology company that specializes in advanced satellite imaging and geospatial services. The company provides a diverse range of products, including Synthetic Aperture Radar (SAR) and various data suites, alongside services that cater to sectors such as telecommunications, climate research, and defense. The company designs and builds high-powered satellites for various applications, including communications, Earth observation, exploration, and on-orbit servicing. Their spacecraft platforms, such as the Maxar 1300 series, are renowned for reliability and versatility, serving a broad range of telecommunications, civil, defense, and intelligence missions.
Key Satellite Manufacturing Companies:
The following key companies have been profiled for this study on the satellite manufacturing market.
- Airbus SE
- ArianeGroup
- Azista BST Aerospace
- The Boeing Company
- Dhruva Space Private Limited
- Gilmour Space Technologies
- INVAP
- Lockheed Martin Corporation
- Maxar Technologies Inc
- Mitsubishi Electric Corporation
- Northrop Grumman
- RTX Corporation
- Sierra Nevada Corporation
- SpaceX
- Thales Group
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Thales Group, Lockheed Martin Corporation, RTX Corporation, Airbus, Northrop Grumman,The Boeing Company )
- These players are focusing on scalability and efficiency to meet the increasing demand. They are adopting innovative manufacturing techniques, including additive manufacturing and digitalization.
- These companies are also enhancing their supply chains by collaborating closely with suppliers to ensure high-quality components for mass production.
- The competitive edge of mature players lies in their extensive experience, technological prowess, and robust government support.
- Their established infrastructure and advanced engineering capabilities enable these firms to innovate continuously, which is crucial in a rapidly evolving market characterized by the increasing demand for satellite-based applications.
- Mature players face challenges, such as high operational costs and lengthy production timelines, due to conventional manufacturing processes.
- Their reliance on custom-built satellites can lead to inefficiencies and increased expenses, making it difficult to compete with emerging companies that offer quicker and more cost-effective solutions.
Emerging & Specialized Players (Dhruva Space Private Limited, Glimour Space Technologies, Maxar Technologies, Inc.)
- These players are adopting innovative operating strategies that emphasize agility and cost-effectiveness. These companies are focusing on producing small, affordable satellites that can compete with conventional large satellites.
- They are prioritizing rapid development cycles and flexible designs, enabling them to respond quickly to changing market demands and customer needs.
- Emerging players gain a competitive advantage by leveraging lower production costs and innovative technologies to produce small satellites quickly and affordably.
- Their focus on mass-producing standardized satellites positions them favorably against established players who may struggle with legacy manufacturing processes.
- Emerging players lack the extensive resources and established networks of their larger counterparts, which can limit their ability to scale operations and secure large contracts.
- They may also struggle with brand recognition and gaining trust among potential clients who prefer established manufacturers with proven track records.
Recent Developments
-
In October 2024, SpaceX launched 20 satellites for Eutelsat Group as part of their first mission following the merger with OneWeb. This launch marks a significant step for Eutelsat in expanding its Low Earth Orbit (LEO) satellite communications network, which serves various telecommunications and broadcasting clients.
-
In September 2024, Airbus SE announced that the EUTELSAT 36D telecommunications satellite built by the company was launched via a Falcon 9 rocket from the Kennedy Space Center in Florida, U.S. The satellite, part of the Eurostar Neo family, aimed to provide TV broadcasting and government services across Africa, Europe, and Eastern countries, with a planned operational lifetime exceeding 15 years.
-
In August 2024, Northrop Grumman launched the Arctic Satellite Broadband Mission (ASBM) constellation, developed for Space Norway, aboard a SpaceX Falcon 9 rocket from Vandenberg Space Force Base in California. This mission marks a historic collaboration between Space Norway and the U.S. Space Force, as it is the first operational U.S. military payload hosted on an international commercial space mission.
Satellite Manufacturing Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 27.1 billion
Market size value in 2026
USD 32.6 billion
Revenue forecast in 2033
USD 75.8 billion
Growth rate
CAGR of 12.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Category, mass, type of business, application, region
Regional scope
North America, Europe, Asia Pacific, Latin America, MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, China, Japan, India, South Korea, Australia, Brazil, South Africa, Saudi Arabia, UAE
Key companies profiled
Airbus SE, ArianeGroup, Azista BST Aerospace, The Boeing Company, Dhruva Space Private Limited, Gilmour Space Technologies, INVAP, Lockheed Martin Corporation, Maxar Technologies Inc., Mitsubishi Electric Corporation, Northrop Grumman, RTX Corporation, Sierra Nevada Corporation, SpaceX, and Thales Group.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Satellite Manufacturing Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest technology trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global satellite manufacturing market report based on category, mass, type of business, application and region:
-
Category Outlook (Revenue, USD Million; 2021 - 2033)
-
Low Earth Orbit (LEO)
-
Medium Earth Orbit (MEO)
-
Geostationary orbit (GEO)
-
Others
-
-
Mass Outlook (Revenue, USD Million; 2021 - 2033)
-
Large Satellites
-
Medium-Sized Satellites
-
Nano Satellites
-
Others
-
-
Type of Business Outlook (Revenue, USD Million; 2021 - 2033)
-
Government
-
Commercial
-
-
Application Outlook (Revenue, USD Million; 2021 - 2033)
-
Communication
-
Earth Observation and Remote Sensing
-
Navigation
-
Research and Development
-
Military Surveillance
-
Others
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The satellite manufacturing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each satellite manufacturing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Category
Revenue capture definition
Low Earth Orbit (LEO)
Revenue is generated through the manufacturing and supply of satellites deployed in low Earth orbit for communication, Earth observation, remote sensing, and commercial constellation applications.
Geostationary Orbit (GEO)
Revenue is generated through the production of high-capacity satellites used for telecommunications, broadcasting, weather monitoring, and strategic applications in geostationary orbit.
Medium Earth Orbit (MEO)
Revenue is generated through the development and manufacturing of satellites used for navigation, communication networks, and specialized space services in medium Earth orbit.
Others
Revenue is generated through satellites operating in alternative orbits, including highly elliptical and specialized mission-specific orbital deployments.
Segment - Mass
Revenue capture definition
Medium-sized Satellites
Revenue is generated through the manufacturing of medium-class satellites designed for commercial, government, scientific, and Earth observation missions.
Large Satellites
Revenue is generated through the production of large satellites for high-capacity communication, defense, exploration, and complex space missions.
Nano Satellites
Revenue is generated through the development and manufacturing of small, low-cost satellites used for research, IoT connectivity, Earth observation, and constellation-based services.
Others (Satellite Size)
Revenue is generated through the production of other satellite classes, including microsatellites, small satellites, and customized spacecraft platforms.
Segment - Type of Business
Revenue capture definition
Commercial
Revenue is generated through satellite manufacturing contracts for private companies providing communication, imaging, navigation, and other commercial space services.
Government
Revenue is generated through satellite development programs, procurement contracts, and defense or civil space missions funded by government agencies.
Segment - Application
Revenue capture definition
Communication
Revenue is generated through the manufacturing of satellites that provide broadband connectivity, broadcasting, mobile communication, and data transmission services.
Earth Observation and Remote Sensing
Revenue is generated through satellites designed for imaging, environmental monitoring, agriculture, mapping, and geospatial data collection.
Navigation
Revenue is generated through the production of satellites supporting global positioning, navigation, timing, and location-based services.
Research and Development
Revenue is generated through satellites developed for scientific research, technology demonstrations, and experimental space missions.
Military Surveillance
Revenue is generated through the manufacturing of defense satellites used for intelligence, surveillance, reconnaissance (ISR), and security applications.
Others
Revenue is generated through specialized satellites used for space exploration, technology testing, meteorology, and other mission-specific applications.
Estimation Model
Layer Name
Key Question
Description
Satellite Technology & Manufacturing Enablement Layer
How are satellites designed, manufactured, and integrated?
Represents the technologies, production capabilities, and infrastructure that enable satellite development and manufacturing. Includes satellite design engineering, advanced materials, electronics manufacturing, propulsion systems, payload integration, avionics, thermal management systems, testing facilities, automated manufacturing, digital engineering, simulation tools, and quality assurance processes supporting efficient and reliable satellite production.
Satellite Application & End-User Layer
Where are satellites deployed and what purposes do they serve?
Represents the industries, applications, and mission areas where satellites generate value. Key applications include communication services, Earth observation and remote sensing, navigation and positioning, scientific research, defense and military surveillance, climate monitoring, disaster management, agriculture monitoring, space exploration, and commercial space services across government, defense, telecommunications, research institutions, and private enterprises.
Orbit, Platform & Mission Configuration Layer
How are satellite systems structured and deployed?
Covers satellite classifications based on orbital position, size, and mission requirements. Includes Low Earth Orbit (LEO), Medium Earth Orbit (MEO), Geostationary Orbit (GEO), and other specialized orbits, satellite categories such as nano satellites, medium-sized satellites, large satellites, and customized spacecraft platforms, and mission-specific configurations designed for commercial, government, and defense applications.
Revenue Generation & Market Monetization Layer
How is revenue generated in the satellite manufacturing market?
Revenue is generated through satellite design and manufacturing contracts, government and defense procurement programs, commercial satellite orders, constellation development agreements, spacecraft integration services, payload manufacturing, satellite component supply, testing and validation services, launch partnership agreements, maintenance and upgrade services, and long-term strategic contracts between satellite manufacturers, operators, governments, and commercial organizations.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Sizing, Segmentation & Growth Opportunity Assessment
Assessed the global satellite manufacturing market size, historical performance, forecast growth trends, and detailed segmentation by category (Low Earth Orbit (LEO), Medium Earth Orbit (MEO), Geostationary Orbit (GEO), and others), mass (nano satellites, medium-sized satellites, large satellites, and others), type of business (commercial and government), and application (communication, Earth observation and remote sensing, navigation, research and development, military surveillance, and others).
Supports strategic market entry decisions, identifies high-growth satellite segments and application opportunities, enables investment prioritization across satellite technologies and manufacturing capabilities, and assists stakeholders in developing targeted growth strategies.
Competitive Landscape & Strategic Positioning Analysis
Benchmarked leading satellite manufacturers based on product portfolios, satellite platforms, manufacturing capabilities, technological expertise, orbital solutions, payload integration capabilities, production scalability, partnerships, contracts, geographic presence, innovation initiatives, and investments in advanced technologies including small satellites, AI-enabled systems, propulsion technologies, and automated manufacturing.
Enables competitive differentiation, identifies technology and capability gaps, supports partnership and acquisition strategies, strengthens market positioning, and helps companies align manufacturing strategies with evolving commercial and government space requirements.
Regional Market Demand & Space Industry Adoption Analysis
Analyzed regional market dynamics across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa by evaluating government space programs, defense investments, commercial satellite deployments, LEO constellation initiatives, private sector participation, regulatory frameworks, and regional satellite manufacturing capabilities.
Supports geographic expansion planning, identifies high-potential regional markets, enables localization strategies, guides investments in manufacturing facilities and partnerships, and improves long-term market penetration strategies.
Frequently Asked Questions About This Report
The key players in the satellite manufacturing market include ArianeGroup, Beijing Spacecraft Manufacturing Co., Ltd. (BSC), Boeing, Dhruva Space Private Limited, Gilmour Space Technologies, INVAP, Lockheed Martin Corporation, Maxar Technologies Inc., Mitsubishi Electric Corporation, Northrop Grumman, RTX Corporation, Sierra Nevada Corporation, and SpaceX.
Key factors that are driving the market growth include the owing to increasing demand for satellites for research & development activities and various applications across industries. Several industries, including mining, construction, oil & gas, energy & utilities, agriculture, transportation, etc., are adopting satellite communication solutions to monitor on-site operations and conduct research activities remotely.
The low-earth orbit (LEO) segment accounted for the largest market share of 55.3% in 2025.
The medium-sized satellites segment led the market with a share of 68.5% in 2025.
The commercial segment dominated the market with a share of 75.4% in 2025.
The communication segment led the market with a share of 47.3% in 2025.
The North America region dominated the global market in 2025. This can be attributed to the rising growing space industry, the presence of prominent industry players, and the ongoing expansion of various private aerospace companies.
The global satellite manufacturing market size was valued at USD 27.1 billion in 2025 and is estimated at USD 32.6 billion for 2026.
The global satellite manufacturing market is expected to grow at a CAGR of 12.8% from 2026 to 2033, reaching USD 75.8 billion by 2033.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


