
- Home
- »
- Advanced Interior Materials
- »
-
Shell And Tube Heat Exchanger Market Report, 2026-2033GVR Report cover

Shell And Tube Heat Exchanger Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Haste Alloy, Titanium, Nickel & Nickel Alloys, Tantalum, Steel), By End Use (Power Generation, Petrochemicals, Chemical), By Region, And Segment Forecasts
Market Size, 2025
$6.9BMarket Estimate, 2026
$7.2BMarket Forecast, 2033
$11.3BCAGR, 2026–2033
6.6%Shell And Tube Heat Exchanger Market Summary
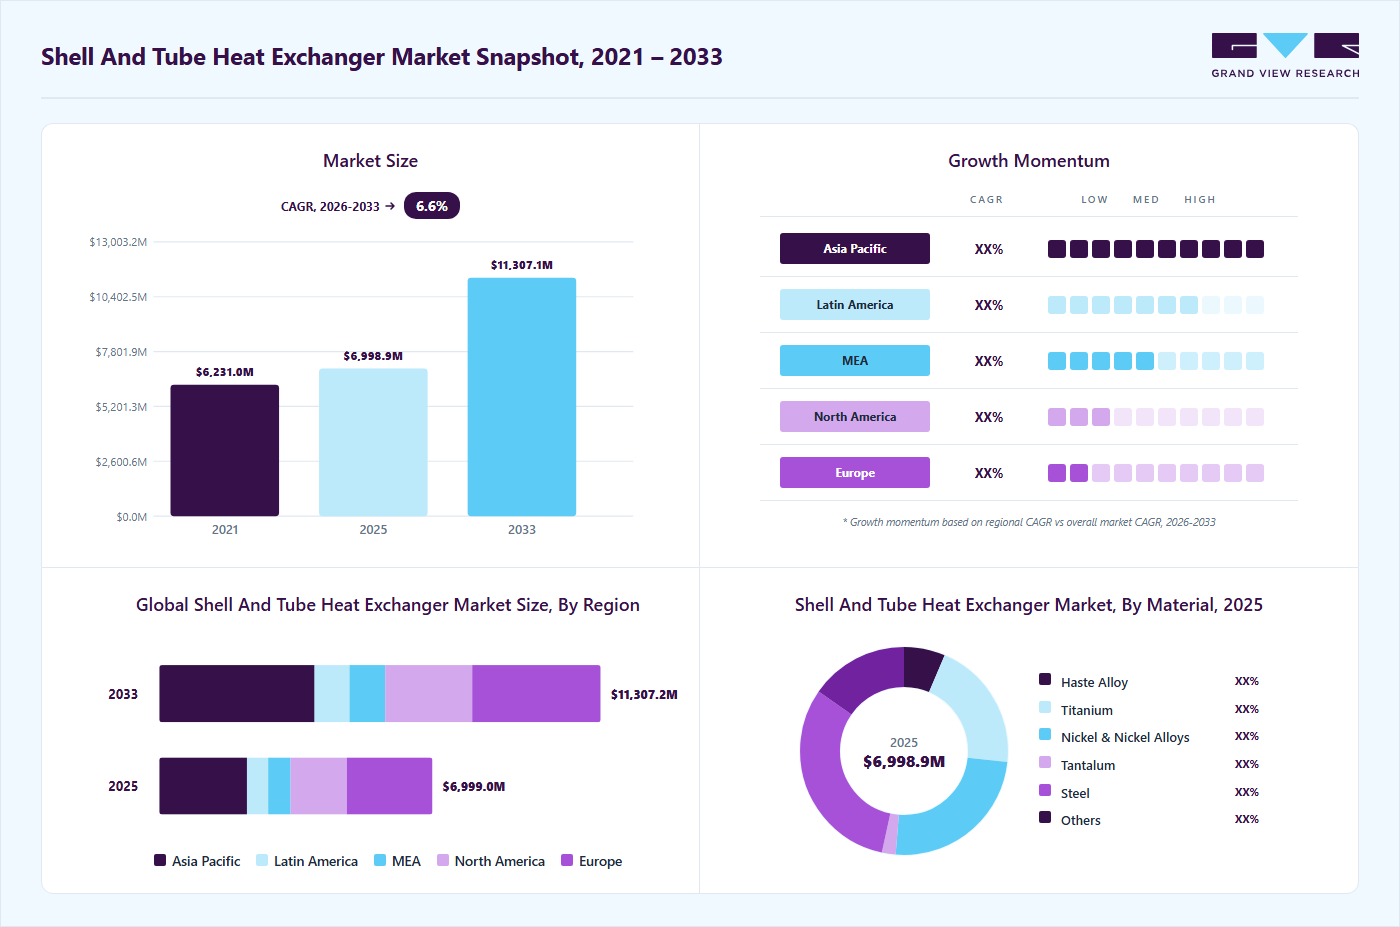
The global shell and tube heat exchanger market size was valued at USD 6.9 billion in 2025 and is projected to grow from USD 7.2 billion in 2026 to USD 11.3 billion by 2033, at a CAGR of 6.6% from 2026 to 2033. Asia Pacific emerged as the leading region in the global market, accounting for a 32.1% share in 2025. The growth is mainly driven by rising demand from core industrial sectors such as power generation, oil & gas, and chemicals.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: The steel material segment dominated the market, holding a 31.2% share in 2025.
- By material: The nickel and nickel alloys segment is expected to grow at the fastest CAGR of 7.1% from 2026 to 2033.
- By end use: The chemical segment held the largest share of 22.3% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (32.1% revenue share, 2025)
- By country: The China shell & tube heat exchanger industry led APAC with the largest share in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.9 Billion
- Estimated market size in 2026: USD 7.2 Billion
- Projected market size by 2033: USD 11.3 Billion
- CAGR (2026-2033): 6.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These industries rely heavily on efficient heat transfer systems to maintain process stability, improve energy efficiency, and reduce operational costs. With increasing global energy consumption and the expansion of refining and petrochemical capacities, the need for reliable, high-performance heat exchangers continues to grow.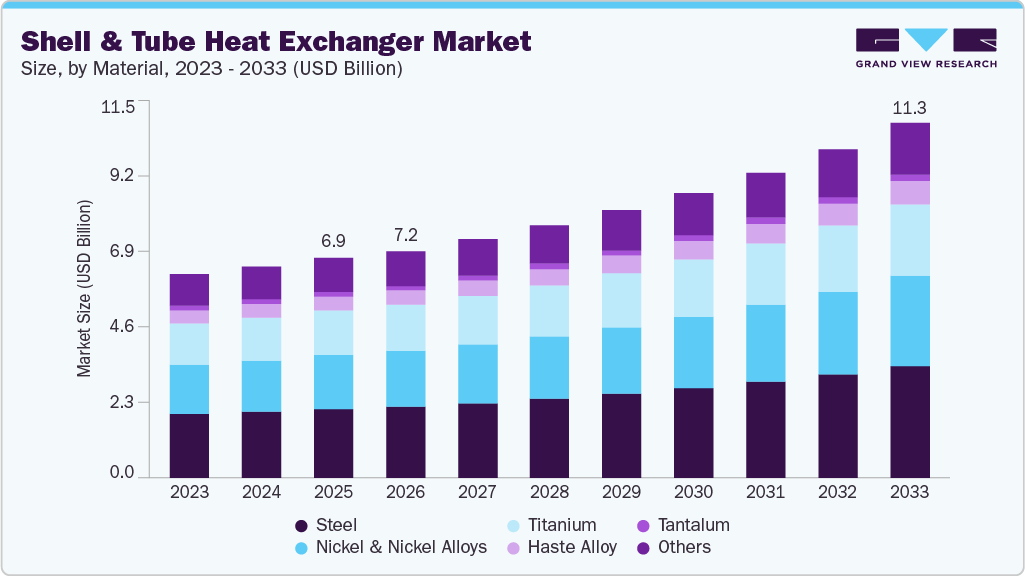 To learn more about this report, Download Free Sample Report
Another key driver is the rapid industrialization and infrastructure development across emerging economies, particularly in Asia Pacific. Growth in sectors like HVAC, food & beverages, and pulp & paper is increasing the use of heat exchangers for temperature control and process optimization. Technological advancements, including the use of corrosion-resistant materials and enhanced design efficiency, are also contributing to market expansion by extending equipment lifespan and reducing maintenance requirements. Together, these factors are creating sustained demand for shell and tube heat exchangers across a wide range of applications.
Market Concentration & Characteristics
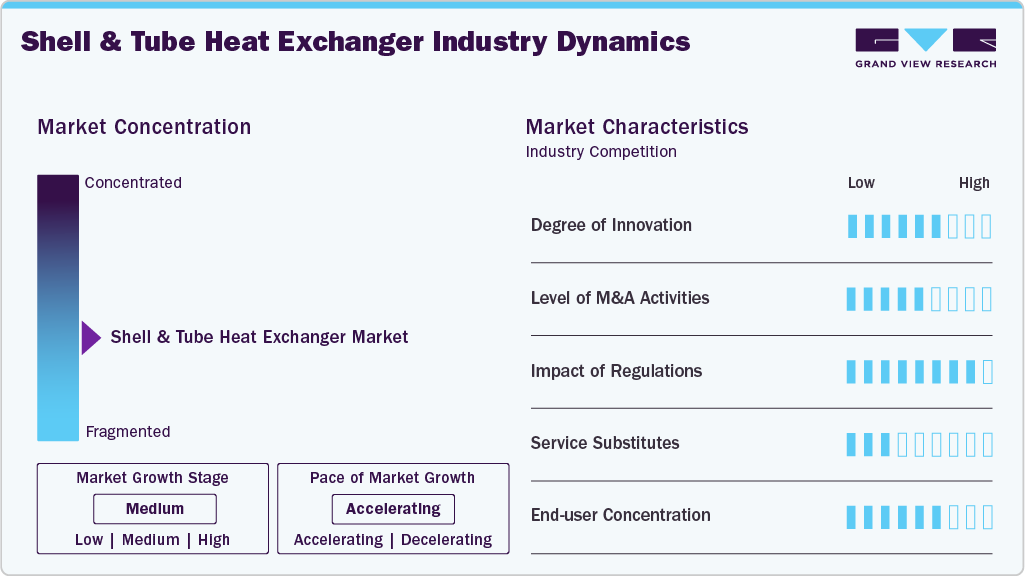
The shell and tube heat exchanger market is fragmented, with the presence of numerous global and regional manufacturers competing across different end-use industries. While a few large multinational players hold a significant share due to their strong engineering capabilities, broad product portfolios, and long-term contracts in sectors like oil & gas and power generation, the market still includes a wide base of small and mid-sized companies catering to niche and local demand. Customization requirements, project-based procurement, and varying material specifications further limit market consolidation, allowing regional players to remain competitive. As a result, the industry reflects a balanced mix of established leaders and specialized manufacturers rather than being highly concentrated.
The shell and tube heat exchanger industry showcases moderate to high levels of innovation, largely driven by the need for improved efficiency, durability, and operational reliability. Manufacturers are focusing on advanced designs such as enhanced tube geometries, compact configurations, and better thermal performance optimization. Material innovation is also a key area, with the increasing use of corrosion-resistant alloys such as duplex steel, titanium, and nickel-based alloys to extend equipment lifespan.
 To learn more about this report, Download Free Sample Report
Regulatory frameworks play a significant role in shaping the market, particularly in industries such as power generation, chemicals, and oil & gas. Strict environmental and energy-efficiency standards are pushing companies to adopt heat exchangers that enable waste heat recovery and reduce emissions. Compliance with safety standards related to pressure vessels and heat transfer equipment is also critical, influencing design, material selection, and manufacturing processes.
The market is characterized by a relatively high concentration of demand from a few key end-use industries, including petrochemicals, power generation, and chemical processing. These sectors account for a substantial share of overall demand due to their continuous need for heat transfer equipment in large-scale operations. However, there is also a growing contribution from diversified sectors, such as HVAC, food & beverages, and pulp & paper, broadening the application base. While large industrial players dominate procurement volumes, smaller industries and regional facilities contribute to steady, distributed demand across the market.
Drivers, Opportunities & Restraints
The growth of the shell & tube heat exchanger market is primarily driven by the growing demand for energy-efficient solutions across various industries, including oil and gas, chemical processing, and HVAC. As industries focus on reducing energy consumption and operational costs, the efficiency and reliability of shell and tube heat exchangers make them an attractive option. Additionally, stringent regulations regarding emissions and energy use are pushing companies to adopt advanced heat exchanger technologies that comply with environmental standards.
Despite their advantages, the shell and tube heat exchanger market faces several restraints, including high initial installation and maintenance costs. These systems often require significant investment in materials and fabrication, which can deter smaller companies from adopting them. Furthermore, the complexity of design and potential for fouling can lead to increased downtime and operational challenges, making some businesses hesitant to invest in these systems.
The market presents substantial opportunities driven by advancements in materials and manufacturing technologies that can enhance the performance and lifespan of shell and tube heat exchangers. Innovations such as the use of corrosion-resistant materials and the integration of smart monitoring systems can improve efficiency and reliability. Additionally, the growing emphasis on renewable energy and sustainable practices opens new avenues for shell and tube heat exchangers in industries such as solar thermal and waste heat recovery, providing a platform for growth and innovation.
Material Insights
The steel material segment led the shell and tube heat exchanger industry in 2025. Due to the growing demand for highly efficient plant operations and the elimination of expensive plant shutdowns, stainless steel shell & tube heat exchanger sales are expected to increase significantly. The material's low cost helps increase its uptake across a variety of end-use sectors. It is anticipated that the characteristics of stainless steel, such as its resistance to corrosion in chemical environments and cooling waters, high-temperature resistance to scaling and oxidation, good strength in low- and high-temperature applications, and resistance to fouling caused by corrosion, will increase material penetration in heat exchangers.
The nickel and nickel alloys segment in the shell and tube heat exchanger market is expected to grow at the fastest CAGR of 7.1% from 2026 to 2033, driven by the increasing demand for materials that offer superior corrosion resistance and durability in harsh operating environments. These materials are particularly favored in industries such as petrochemical, pharmaceutical, and marine, where exposure to aggressive chemicals and extreme temperatures is common. Nickel alloys provide enhanced performance and longevity, reducing maintenance costs and downtime associated with corrosion-related failures. As industries prioritize reliability and efficiency, the shift towards nickel and nickel alloy heat exchangers is becoming a key factor in their adoption.
End Use Insights
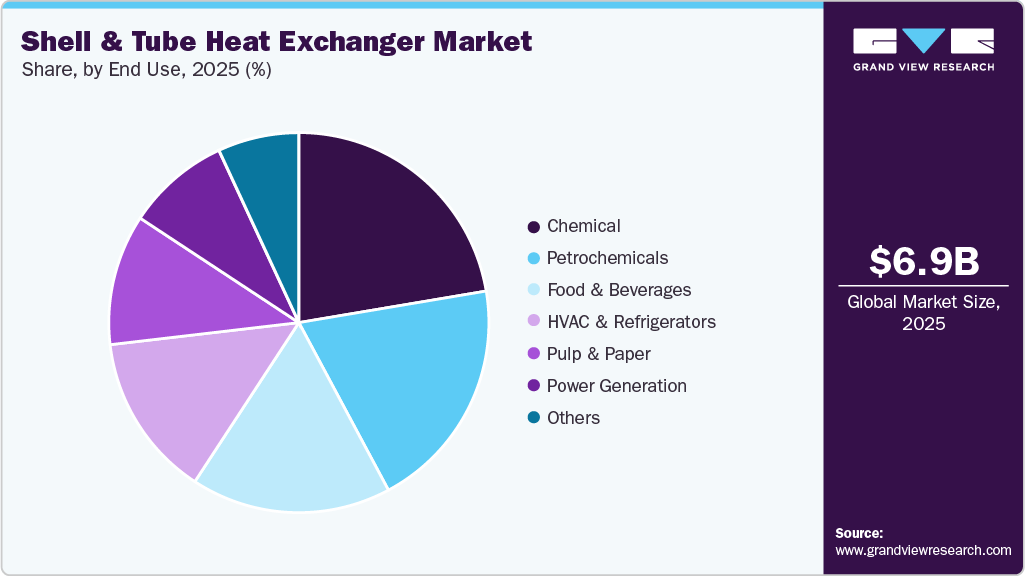
The chemical end-use segment led the shell & tube heat exchanger market, accounting for 22.3% global revenue share in 2025. Shell & tube heat exchangers play a crucial role in the chemical industry, facilitating efficient heat transfer across processes such as reactions, distillation, and cooling. Their design allows high-pressure, high-temperature operations, making them ideal for handling corrosive fluids and the harsh operating conditions typical in chemical manufacturing. These heat exchangers are used for heating or cooling process streams, recovering heat from exothermic reactions, and condensing vapors in distillation columns. Their versatility, robustness, and ability to accommodate large surface areas make them essential for optimizing energy efficiency and enhancing overall process performance in the chemical industry.
 To learn more about this report, Download Free Sample Report
The petrochemicals end-use segment’s growth is primarily driven by the increasing global demand for petrochemical products, such as plastics, fertilizers, and synthetic fibers. As the petrochemical industry expands to meet the needs of various sectors, including automotive, construction, and consumer goods, the efficiency and effectiveness of heat exchangers become critical for optimizing production processes. Shell & tube heat exchangers are preferred for their ability to handle high-pressure, high-temperature applications, making them essential for processes such as refining and chemical reactions. Additionally, the industry's focus on energy efficiency and sustainability further propels the need for advanced heat exchanger solutions that minimize energy consumption and improve overall process performance.
Regional Insights
North America Shell and Tube Heat Exchanger Market Trends
The North America shell & tube heat exchanger industry is witnessing steady growth, driven by the modernization of aging industrial infrastructure and a strong focus on energy optimization. The presence of established oil & gas and chemical industries supported continuous demand for high-performance heat exchangers. Furthermore, increasing adoption of advanced technologies and emphasis on reducing carbon emissions encouraged industries to upgrade existing systems with more efficient solutions.
U.S. Shell and Tube Heat Exchanger Market Trends
The U.S. shell and tube heat exchanger industry’s growth is supported by strong demand from the oil & gas and petrochemical sectors. According to the American Fuel & Petrochemical Manufacturers, the U.S. has 130 refineries producing key fuels such as gasoline, diesel, and jet fuel, as well as 311 petrochemical facilities. This extensive refining and processing infrastructure drives consistent demand for shell and tube heat exchangers, which are widely used for temperature control, heat recovery, and process optimization.
Europe Shell and Tube Heat Exchanger Market Trends
Europe experienced stable growth, largely influenced by strict environmental regulations and a strong push toward sustainable industrial practices. Industries across the region emphasized energy efficiency and waste heat recovery, leading to increased deployment of advanced heat exchanger systems. Additionally, the region’s focus on clean energy transition and industrial decarbonization supported consistent demand from sectors such as chemicals and district heating.
The Germany shell and tube heat exchanger market leads Europe, supported by its strong industrial and manufacturing base, particularly in chemicals and process industries. According to Germany Trade & Invest (GTAI), the country was the world’s third-largest exporter of chemical products in 2023, with exports valued at USD 153.7 billion, accounting for around 9% of the global market. This robust chemical export landscape continues to drive demand for advanced heat transfer equipment for processing, temperature control, and energy-efficiency applications.
The shell and tube heat exchanger market in France is witnessing steady growth, driven by rising investments in the energy, chemical, and food processing industries. The country’s ongoing transition toward cleaner energy systems and emphasis on improving industrial efficiency are encouraging the adoption of modern heat exchanger solutions. Additionally, demand from sectors such as nuclear power generation and HVAC is driving market expansion, supported by government initiatives to reduce carbon emissions and enhance energy optimization across industrial operations.
Asia Pacific Shell and Tube Heat Exchanger Market Trends
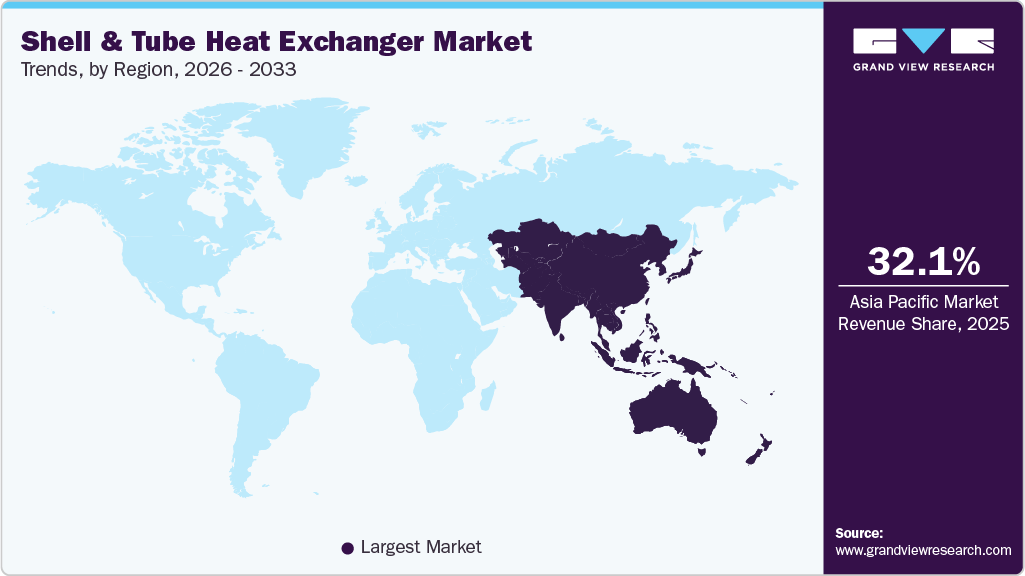
Asia Pacific led the shell and tube heat exchanger industry, accounting for 32.1% share in 2025, supported by strong industrial growth and expanding energy demand across countries such as China, India, and Southeast Asia. Rapid development in refining, chemical manufacturing, and power generation created consistent demand for heat transfer equipment. In addition, ongoing infrastructure expansion and increased investments in industrial facilities have strengthened the region's dominance, with manufacturers focusing on cost-effective, large-scale production.
 To learn more about this report, Download Free Sample Report
The shell and tube heat exchanger market in China dominated Asia Pacific in 2025, supported by its extensive industrial base and strong demand from sectors such as chemicals, power generation, and oil refining. According to the World Steel Association, China produced 1,005.1 million tonnes of crude steel in 2024, underscoring its position as the world's leading steel producer. This abundant steel production plays a crucial role in supporting the manufacturing of shell and tube heat exchangers, where steel is a primary construction material. The easy availability of raw materials, along with large-scale industrial operations, continues to strengthen China’s dominance in the regional market.
The India shell and tube heat exchanger market is emerging as a fast-growing segment, driven by rapid industrialization and rising demand across theenergy, petrochemical, and manufacturing sectors. Increasing domestic steel production also supports the heat exchanger supply chain, ensuring cost-effective access to key materials. Additionally, government initiatives promoting infrastructure development and local manufacturing are encouraging the adoption of advanced heat exchanger systems. Growing emphasis on energy efficiency and process optimization further supports market expansion across industries in the country.
Middle East and Africa Shell & Tube Heat Exchanger Market Trends
The Middle East & Africa shell & tube heat exchanger industry is poised for notable growth, driven by strong investments in oil & gas, petrochemicals, and power generation. In the Middle East, large-scale refining and processing projects created steady demand for robust heat exchanger systems. Meanwhile, in Africa, ongoing industrialization and energy development initiatives have supported gradual market expansion, with an increasing focus on improving operational efficiency across key industries.
The Saudi Arabia shell & tube heat exchanger market led the Middle East & Africa in 2-25, driven by its strong oil & gas and petrochemical industry base. According to the International Trade Administration (ITA), the country holds around 17% of the world’s proven petroleum reserves and is one of the largest net exporters of petroleum. This extensive hydrocarbon infrastructure creates significant demand for shell and tube heat exchangers, which are essential for refining, processing, and thermal management applications.
Latin America Shell and Tube Heat Exchanger Market Trends
Latin America emerged as a growing market, supported by gradual expansion in oil refining, mining, and industrial processing activities. Countries such as Brazil and Argentina contributed to demand through investments in energy and industrial infrastructure. The need for reliable and cost-efficient thermal management solutions in these sectors played a key role in driving adoption across the region.
The Brazil shell and tube heat exchanger market led Latin America in 2025, supported by its strong presence in oil refining, petrochemicals, and industrial processing sectors. The country’s well-established energy industry, along with ongoing investments in offshore oil exploration and refining capacity, continues to drive demand for efficient heat transfer equipment.
Key Shell and Tube Heat Exchanger Company Insights
Some of the key players operating in the shell & tube heat exchanger market include Alfa Laval, API Heat Transfer, and Xylem.
-
Alfa Laval is a provider of heat transfer, separation, and fluid handling solutions, serving industries such as energy, chemicals, food processing, and marine. The company’s shell and tube heat exchangers are designed for efficient heating and cooling of liquids and gases, in which one medium flows through the tubes and the other through the surrounding shell, facilitating efficient heat transfer. These systems are known for their high thermal efficiency, compact design, and ability to handle a wide range of temperatures, pressures, and fluid types, including aggressive and viscous media. With advanced design features such as enhanced tube surfaces and optimized flow patterns, Alfa Laval’s heat exchangers ensure reliable performance, reduced fouling, and suitability for demanding applications like petrochemical plants, refineries, and power generation facilities.
-
The API Heat Transfer company focused on manufacturing and supplying heat transfer equipment. It markets its products under five brands, namely AirTech, Basco, Covrad, Schmidt, and TTP. Furthermore, the company operates through four heat transfer groups, namely Air Cooled, Shell & Tube, Plate & Thermal Systems, and Fluid Power & Distributed Products, which provide optimal heat transfer solutions for required applications. Major products offered by the company include gasketed plate, brazed plate, welded plate, plate & shell, shell & tube heat exchangers, air coolers, radiators, evaporation systems, dealcoholization systems, and pasteurization systems.
Key Shell and Tube Heat Exchanger Companies:
The following key companies have been profiled for this study on the shell & tube heat exchanger market.
- Alfa Laval
- HRS Heat Exchangers
- Kelvion Holding GmbH
- API Heat Transfer
- Brask, Inc.
- Metalforms, LLC
- Xylem
- WCR, Inc.
- SHECO Industries, Inc.
- Rubiconhx
- Delpro Equipments Pvt.Ltd
- Mersen
- Thermex Limited
- Tinita Engineering Pvt. Ltd
- Barriquand Heat Exchangers
Recent Developments
-
In October 2025, WCR opened a new plate heat exchanger manufacturing facility in Xenia, Ohio, marking a major expansion in its U.S. operations. The 212,000 sq. ft. plant increases production capacity for heat exchangers, gaskets, and related components. This development enables faster delivery and improved service support across key industries, including HVAC, chemicals, and food processing. It also strengthens the company’s presence in North America while supporting local job creation.
-
In April 2025, TransTech Group, through Metalforms, acquired the international operations and intellectual property of Koch Heat Transfer, strengthening its position in the global heat transfer market. The acquisition includes advanced technologies such as BROWN FINTUBE and TWISTED TUBE, along with key engineering capabilities. This move enhances Metalforms’ ability to serve industries like energy and petrochemicals with more advanced solutions.
-
In September 2024, Alfa Laval launched three new heat exchangers at Chillventa 2024, specifically designed for propane (R290), CO2 (R744), and ammonia (R717) systems. Renowned for its engineering solutions in heat transfer, separation, and fluid handling across sectors such as HVAC&R, power generation, and wastewater treatment, Alfa Laval is introducing these products for residential, commercial, and industrial applications. The new offerings include the SE series, AC900, and a semi-welded plate heat exchanger.
Shell & Tube Heat Exchanger Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.9 billion
Estimated Market size in 2026
USD 7.2 billion
Projected Market size in 2033
USD 11.3 billion
Growth rate
CAGR of 6.6% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, end use, region
Country scope
U.S.; Canada; Mexico; Germany; France; Italy; Spain; UK; China; India; Japan; South Korea; Australia; Brazil; Argentina; UAE; Saudi Arabia; South Africa
Key companies profiled
Alfa Laval; HRS Heat Exchangers; Kelvion Holding GmbH; API Heat Transfer; Brask, Inc.; Metalforms, LLC; Xylem; WCR, Inc.; SHECO Industries, Inc.; Rubiconhx; Delpro Equipments Pvt. Ltd; Mersen; Thermex Limited; Tinita Engineering Pvt. Ltd; Barriquand Heat Exchangers
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Shell And Tube Heat Exchanger Market Report Segmentation
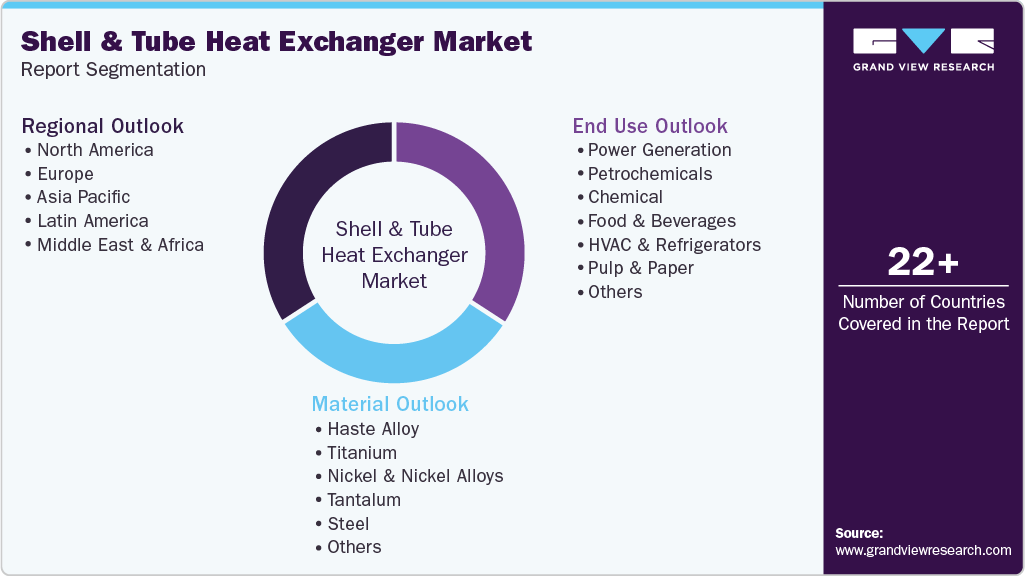
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the shell & tube heat exchanger market report based on material, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Material Outlook (Revenue, USD Million, 2021 - 2033)
-
Haste Alloy
-
Titanium
-
Nickel & Nickel Alloys
-
Tantalum
-
Steel
-
Stainless Steel
-
Duplex Steel
-
Carbon Steel
-
Super Duplex Steel
-
Others
-
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Power Generation
-
Petrochemicals
-
Chemical
-
Food & Beverages
-
HVAC & Refrigerators
-
Pulp & Paper
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
Spain
-
UK
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Frequently Asked Questions About This Report
The global shell and tube heat exchanger market size was estimated at USD 6.9 billion in 2025 and is expected to reach USD 7.2 billion in 2026.
Asia Pacific dominated with a 32.1% revenue share in 2025.
The steel material segment dominated the market, holding a 31.2% share in 2025.
The petrochemicals end-use segment is expected to register strong growth, with a projected CAGR of 7.7% from 2026 to 2033 in terms of revenue.
Key players include Alfa Laval, HRS Heat Exchangers, Kelvion Holding GmbH, API Heat Transfer, Brask, Inc., Metalforms, LLC, Xylem, WCR, Inc., SHECO Industries, Inc., Rubiconhx, Delpro Equipments Pvt. Ltd, Mersen, Thermex Limited, Tinita Engineering Pvt. Ltd, Barriquand Heat Exchangers.
The global shell and tube heat exchanger market, in terms of revenue, is expected to grow at a compound annual growth rate of 6.6% from 2026 to 2033 to reach USD 11.3 billion by 2033.
Key factors include rapid industrialization in the emerging countries of Asia and the Pacific and expanding investments in commercial, manufacturing, and industrial projects.
Asia Pacific led the shell and tube heat exchanger market and accounted for 32.1% share in 2025, supported by strong industrial growth and expanding energy demand across countries such as China, India, and Japan. Rapid development in refining, chemical manufacturing, and power generation created consistent demand for heat transfer equipment.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


