
- Home
- »
- Distribution & Utilities
- »
-
Silicon Anode Battery Market Size Report, 2026-2033GVR Report cover

Silicon Anode Battery Market (2026 - 2033)
Size, Share & Trends Analysis Report By Capacity (< 1,500 mAh, 1,500 to 2,500 mAh, > 2,500 mAh), By Application (Automotive, Consumer Electronics, and Energy & Power, Medical Devices), By Region, And Segment Forecasts
Market Size, 2025
$475.1MMarket Estimate, 2026
$682.5MMarket Forecast, 2033
$7,654.4MCAGR, 2026–2033
41.2%Silicon Anode Battery Market Summary
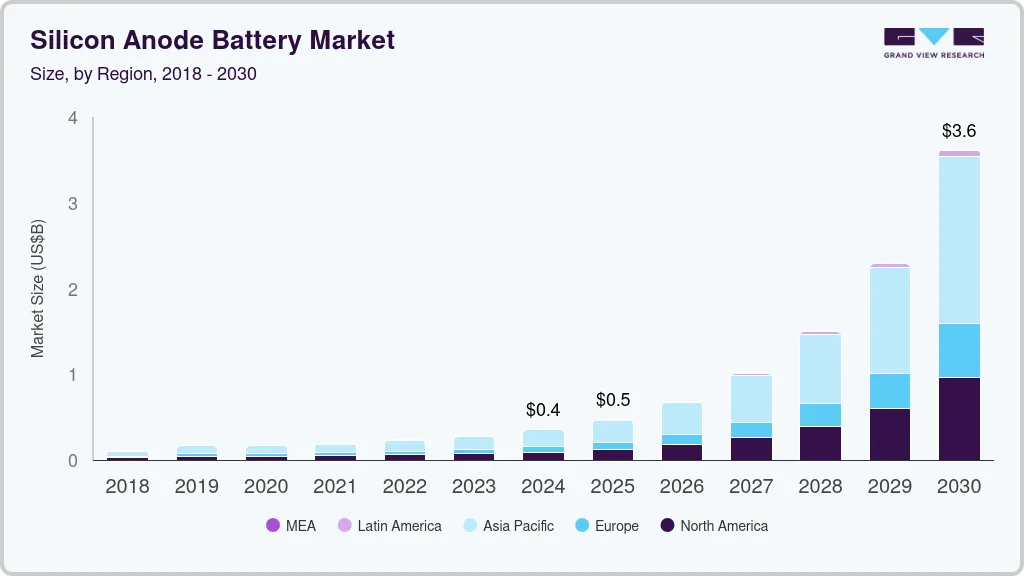
The global silicon anode battery market size was valued at USD 475.1 million in 2025 and is projected to grow from USD 682.5 million in 2026 to USD 7654.4 million by 2033, at a CAGR of 41.2% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 54.3% in 2025. Driven by several key factors such as the increasing demand for high-energy density batteries across industries, including consumer electronics, automotive, and renewable energy, silicon anode batteries provide superior energy storage capabilities compared to traditional lithium-ion batteries.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By capacity: The < 1,500 mAh segment led the market with the largest revenue share of 45.7% in 2025.
- By application: Automotive segment led the market with the largest revenue share of 41.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (54.3% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 475.1 Million
- Estimated market size in 2026: USD 682.5 Million
- Projected market size by 2033: USD 7654.4 Million
- CAGR (2026-2033): 41.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market is experiencing significant growth, driven by several key factors such as the increasing demand for high-energy density batteries across industries, including consumer electronics, automotive, and renewable energy. Silicon anode batteries provide superior energy storage capabilities compared to traditional lithium-ion batteries.In addition, government initiatives promoting clean energy and electric vehicle adoption are enhancing market prospects, as they create a favorable regulatory environment.
 To learn more about this report, Download Free Sample Report
The rise in miniaturized consumer devices further fuels demand, as these applications require compact and efficient power sources. Technological advancements in battery design and materials also contribute to market expansion, making silicon anode batteries an attractive option for various applications, including electric vehicles and portable electronics.
Market Dynamics
The silicon anode battery market is witnessing rapid growth due to the increasing demand for high-performance and fast-charging batteries. The rapid adoption of electric vehicles and advanced consumer electronics is driving the need for batteries with higher energy density. Companies are investing heavily in research and development to improve silicon anode performance and extend battery life. Advances in silicon composite materials and manufacturing technologies are making these batteries more reliable and commercially viable. Strategic partnerships between battery manufacturers and automotive companies are further accelerating market development. However, challenges such as high production costs, silicon expansion during charging, and limited large-scale commercialization continue to restrain market growth.
The growing adoption of electric vehicles is a major driver of the silicon anode battery market. Automakers are seeking batteries with higher energy density, faster charging, and longer driving range to improve vehicle performance. Silicon anodes can store significantly more lithium than conventional graphite anodes, enabling lighter battery packs and shorter charging times. As EV production continues to increase worldwide, battery manufacturers are expanding silicon anode production to meet the evolving performance requirements of next-generation electric vehicles.
In September 2025, Sila began operations at its Washington automotive-scale silicon anode manufacturing plant. The facility started producing initial batches of Titan Silicon, a silicon-carbon anode material designed for electric mobility applications. The plant has an initial production capacity of 2-5 GWh, with plans to expand to 250 GWh within five years. According to the company, Titan Silicon delivers up to 20% higher energy density than conventional graphite anodes and enables up to two times faster charging, supporting the growing demand for high-performance EV batteries. This expansion reflects the increasing commercialization of silicon anode technology to meet the needs of the electric vehicle industry.
The high cost of manufacturing silicon anode batteries is a major restraint on market growth. Producing silicon anodes requires advanced material processing, nano-engineering, and specialized coatings to improve battery stability and cycle life. These complex manufacturing processes increase production costs compared to conventional graphite anodes. In addition, scaling up production while maintaining consistent quality remains a significant challenge for manufacturers. The need for specialized equipment and continuous research and development further increases overall production expenses. Silicon anode batteries are currently used mainly in premium consumer electronics and high-performance electric vehicles, limiting their adoption in mass-market applications.
The rising demand for compact and high-performance consumer electronics is creating significant opportunities for the silicon anode battery market. Smartphones, smartwatches, wireless earbuds, AR/VR devices, and other wearables require batteries with higher energy density and longer operating life without increasing device size. Silicon anodes can deliver 20% to 50% higher energy density than conventional graphite anodes, enabling thinner, lighter, and longer-lasting devices. The rapid expansion of IoT devices and AI-enabled electronics is further increasing the need for advanced battery technologies. Asia Pacific, the global hub for electronics manufacturing, is expected to drive the adoption of silicon anode batteries as device makers focus on improving product performance and battery efficiency.
Analyst Perspective
The silicon anode battery market is growing as battery manufacturers increasingly adopt high-capacity anode materials to improve energy density, enable faster charging, and extend battery life for electric vehicles and consumer electronics. Companies are investing in advanced silicon anode technologies and expanding production capacity to meet the rising demand for next-generation lithium-ion batteries. The market is also witnessing stronger collaborations between material suppliers, battery manufacturers, and automotive OEMs to accelerate commercialization. A key trend is the growing adoption of silicon-carbon composite anodes, which offer higher battery capacity while remaining compatible with existing lithium-ion battery manufacturing processes. However, manufacturing costs, cycle-life challenges, and large-scale production scalability continue to influence the pace of market growth.
Capacity Insights
Based on capacity, the < 1,500 mAh segment led the market with the largest revenue share of 45.7% in 2025. The demand for silicon anode batteries with a capacity of less than 1,500 mAh is growing, primarily driven by the increasing need for compact and efficient energy solutions in consumer electronics. This segment is particularly favored for applications in portable devices such as smartphones and wearables, where space and weight are critical. As manufacturers seek to enhance battery performance while minimizing size, the adoption of silicon anode technology is expected to rise, contributing to the overall growth of the market.
Moreover, the silicon anode battery market for capacities between 1,500 to 2,500 mAh is gaining traction, primarily driven by the increasing demand for enhanced energy storage solutions in consumer electronics and automotive applications. This segment is particularly favored for devices requiring a balance of size and performance, as silicon anodes offer higher energy density and longevity compared to traditional graphite anodes.
Application Insights
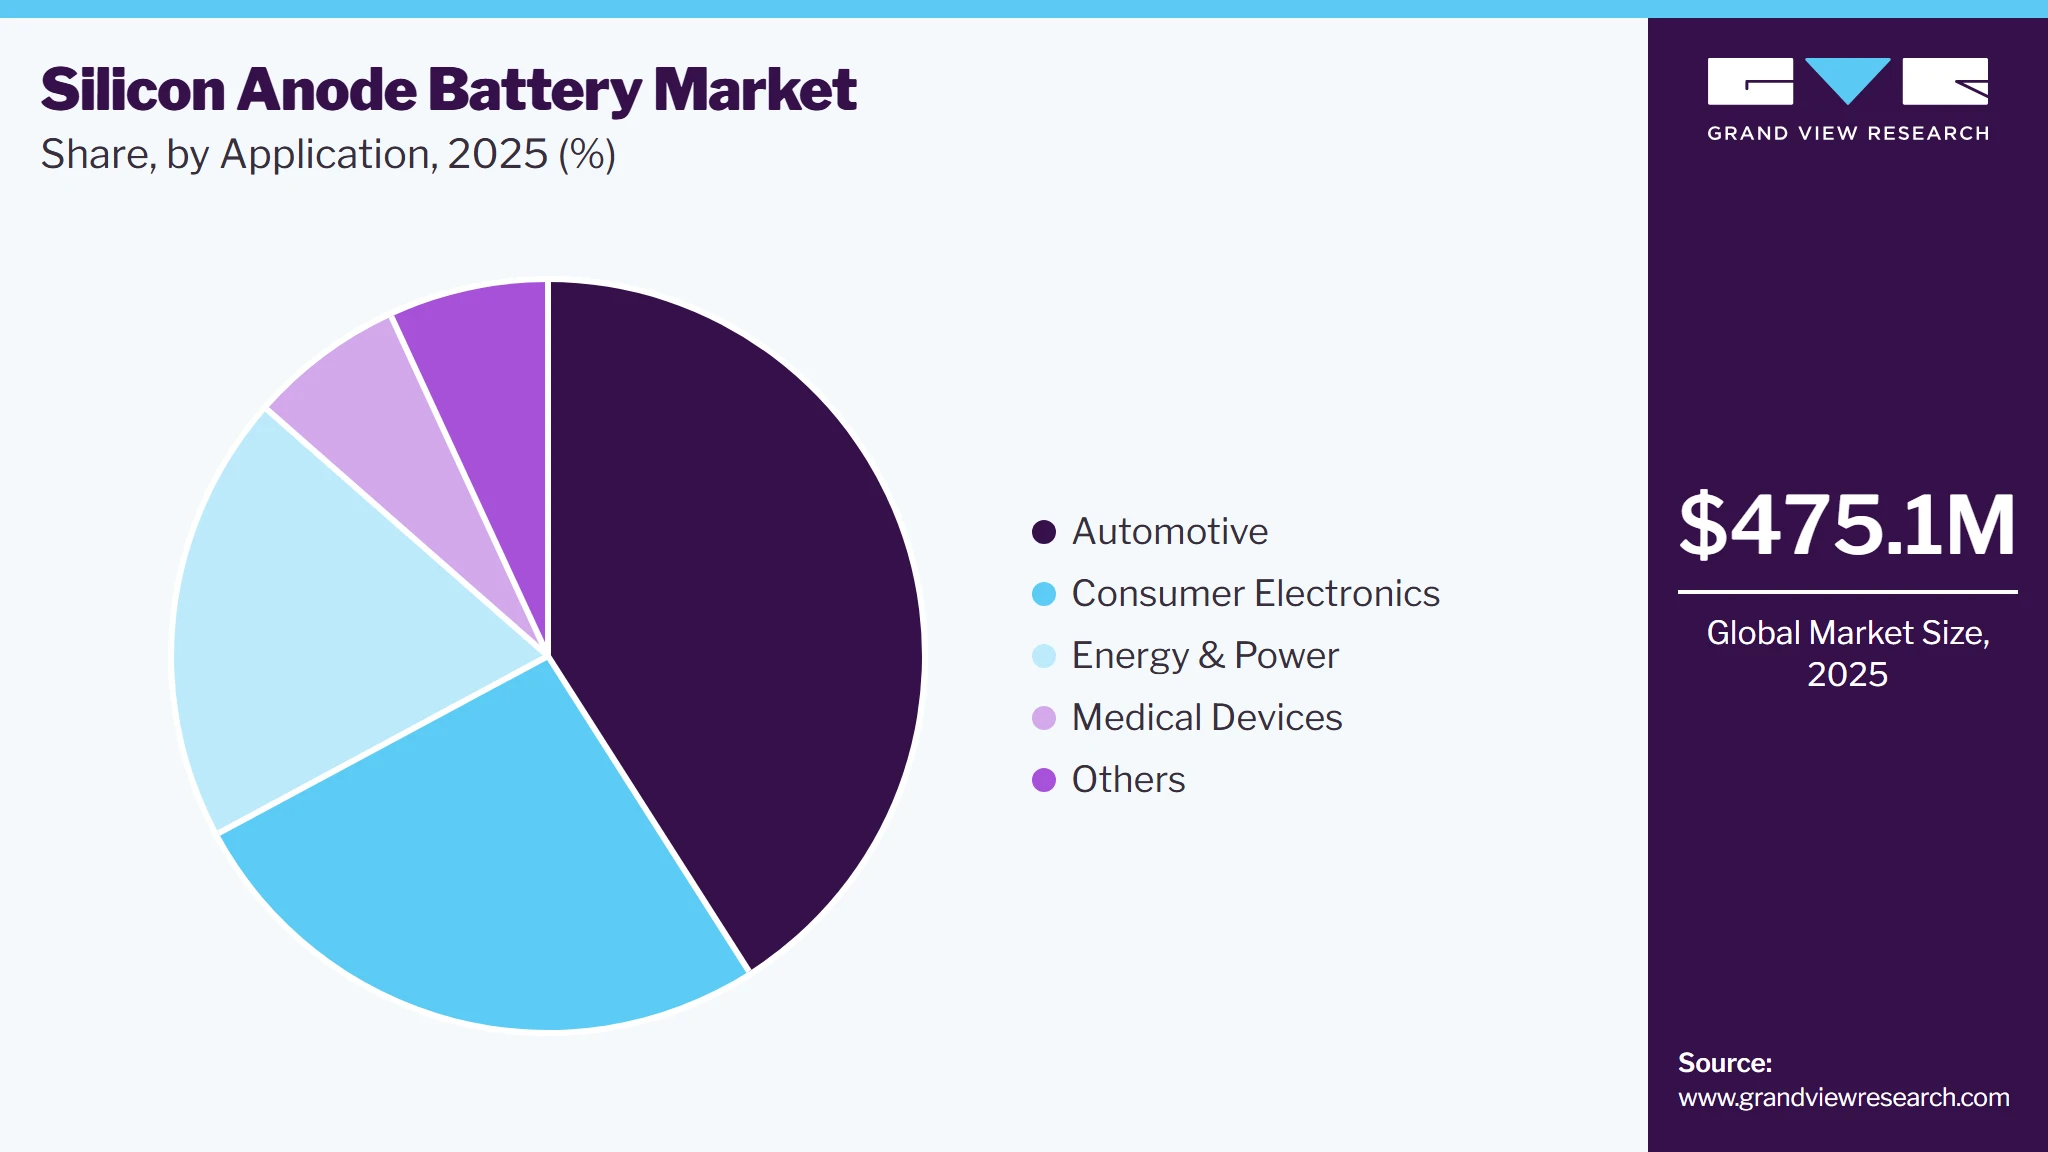
Based on application, the automotive segment led the market with the largest revenue share of 41.0% in 2025. The automotive silicon anode battery market is characterized by its rapid growth, driven by the demand for high-energy density and safer battery solutions in electric vehicles. These batteries offer superior performance, longer life cycles, and enhanced safety compared to traditional lithium-ion batteries. The market is also marked by significant technological advancements and collaborations among manufacturers, aiming to improve battery efficiency and reduce costs.
 To learn more about this report, Download Free Sample Report
The demand for silicon anode batteries in medical devices is increasing due to the growing need for compact, high-performance energy solutions in healthcare applications. These batteries offer enhanced energy density, longer life cycles, and improved safety, making them ideal for portable medical equipment and wearable health monitoring devices.
Regional Insights
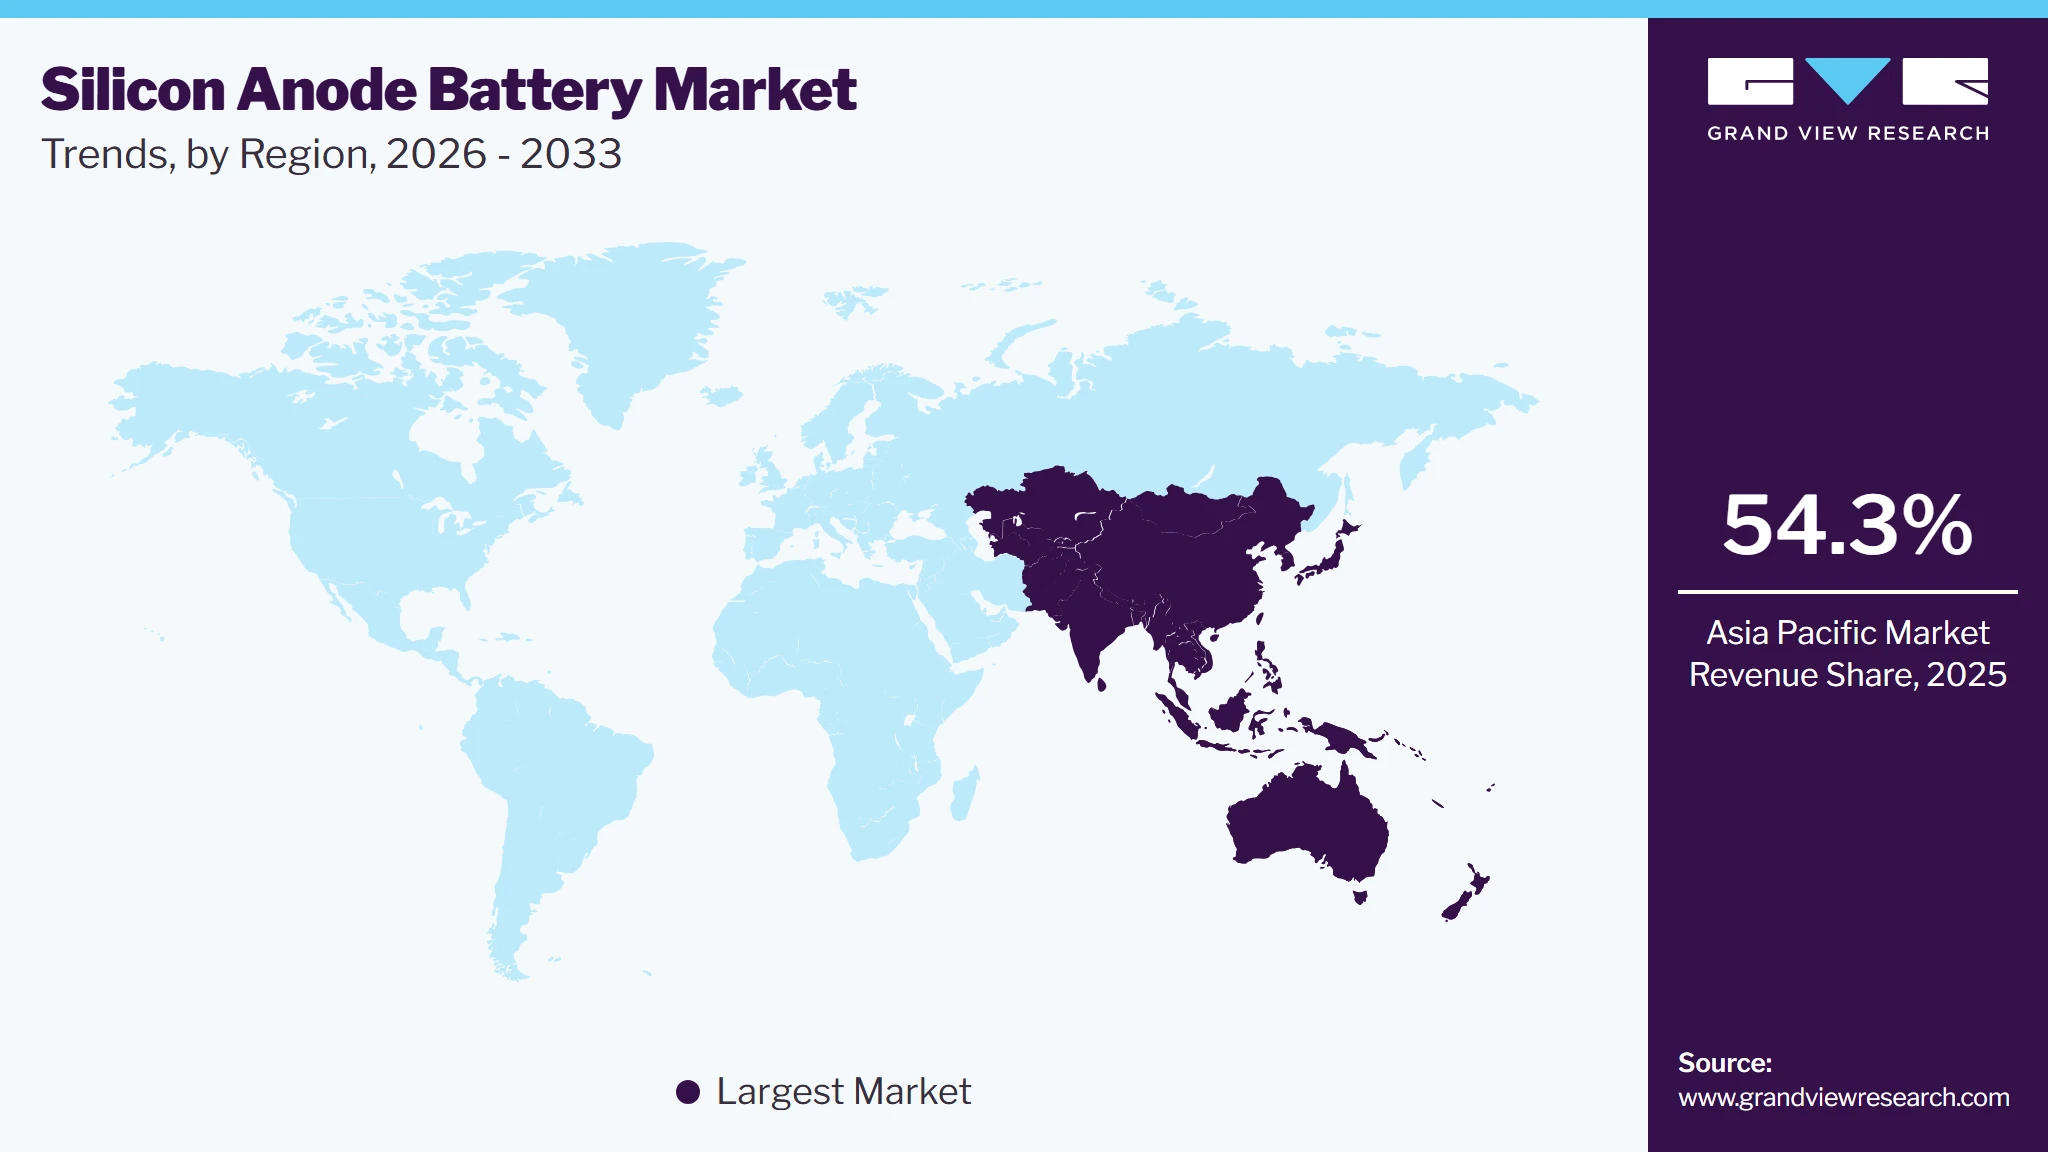
Asia Pacific dominated the silicon anode battery market with the largest revenue share of 54.3% in 2025. The demand for silicon anode batteries in the Asia Pacific region is rapidly increasing, driven by the growing adoption of electric vehicles and advancements in consumer electronics. This surge is supported by a robust manufacturing base in countries like China, Japan, and South Korea, which are leading the way in battery innovation and production. Additionally, government initiatives promoting sustainable energy solutions further enhance market growth, positioning silicon anode batteries as a key component in the transition to cleaner energy technologies across various sectors. The market is characterized by the need for high-energy density solutions, contributing significantly to the increasing demand for these batteries in both automotive and consumer electronics applications.
 To learn more about this report, Download Free Sample Report
China Silicon Anode Battery Market Trends
The silicon anode battery market in China held the largest share in the Asia Pacific region in 2025. China silicon anode battery marketis experiencing demandfor silicon anode batteries due to the country's dominance in electric vehicle production and advancements in consumer electronics. The growing focus on sustainable energy solutions and the need for high-performance batteries further enhance market opportunities, positioning China as a key player in the global silicon anode battery landscape.
Silicon anode battery market in India is growing due tothe country focuses on sustainable energy solutions, manufacturers are investing in research and development to enhance battery performance. This trend is supported by government initiatives promoting clean energy and electric mobility, positioning India as a significant player in the silicon anode battery market. The combination of rising environmental awareness and the need for high-performance energy storage solutions is expected to further accelerate market growth in the coming years.
North America Silicon Anode Battery Market Trends
North America is a significant market for Silicon Anode Battery and is characterized by the growing adoption of electric vehicles, increasing demand for high-energy density batteries in consumer electronics, and the presence of major manufacturers investing in R&D to enhance battery performance and reduce costs.
The U.S. silicon anode battery market is poised for significant growth, driven by the presence of leading manufacturers, government initiatives promoting clean energy, and the increasing demand for high-energy density batteries across industries. Key factors fueling this expansion include the rapid growth of the automotive sector, particularly electric vehicles, and the rising adoption of advanced consumer electronics. The U.S. Department of Energy's Small Business Innovation Research (SBIR) program is also supporting the development of silicon anode battery technology, further propelling market growth.
Europe Silicon Anode Battery Market Trends
The demand for silicon anode batteries in Europe is rapidly increasing, fueled by the growing emphasis on electric vehicles and renewable energy solutions. Countries like Germany, France, and the UK are leading this growth due to their strong automotive industries and government initiatives promoting sustainable energy. Additionally, the rising demand for compact, efficient batteries in consumer electronics further supports market expansion across the region.
The UK silicon anode battery marketis growing due to the government initiatives aimed at reducing carbon emissions and promoting sustainable energy technologies. Additionally, the UK’s robust automotive sector is embracing silicon anode technology for its superior energy density and longevity, making it a preferred choice for manufacturers seeking to enhance vehicle performance and efficiency. As a result, the UK market is becoming a key player in the broader European silicon anode battery landscape.
The silicon anode battery in Germany is projected to grow significantly, driven by the robust automotive sector and increasing adoption of electric vehicles.This growth is further supported by advancements in battery technology, partnerships between manufacturers and chemical companies, and government initiatives promoting clean energy solutions. As Germany aims to lead in electric mobility, the demand for high-performance silicon anode batteries is set to rise, positioning the country as a key player in the European market.
Latin America Silicon Anode Battery Market Trends
The demand for silicon anode batteries in Central and South Africa is expected to grow, driven by the increasing adoption of electric vehicles and advancements in consumer electronics. However, the market is still in its early stages compared to other regions, and factors such as limited manufacturing capabilities and infrastructure challenges may hinder rapid growth.
Middle East & Africa Silicon Anode Battery Market Trends
The Middle East & Africa silicon anode battery market is characterized by its early stage of development compared to other regions. While the demand for silicon anode batteries is expected to grow, driven by the increasing adoption of electric vehicles and advancements in consumer electronics, factors such as limited manufacturing capabilities and infrastructure challenges may hinder rapid market expansion. However, as countries in the region focus on sustainable energy solutions and promote electric mobility, the silicon anode battery market presents opportunities for manufacturers and investors to establish a presence and contribute to the development of the industry. The GCC and South Africa are expected to lead the growth in the Middle East & Africa region.
Key Silicon Anode Battery Company Insights
The Silicon Anode Battery Market is a highly competitive industry with several key players operating globally.
Key Silicon Anode Battery Companies:
The following key companies have been profiled for this study on the silicon anode battery market.
-
XG Sciences
-
Enevate Corporation
-
ENOVIX Corporation
-
Amprius technologies
-
Huawei
-
OneD Material, Inc.
-
Nexeon Ltd
-
California Lithium Battery
-
EoCell Inc.
-
Group14 Technologies
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BTR New Material Group Co., Ltd., Shanshan co., Nexeon Ltd., Enovix Corporation, Amprius Technologies)
- Focus on expanding commercial-scale manufacturing capacity and improving production yields to meet growing demand from EV and consumer electronics manufacturers.
- Invest in advanced silicon anode technologies to enhance energy density, cycle life, and fast-charging performance while reducing material degradation.
- Strengthen long-term supply agreements and strategic partnerships with battery manufacturers, automotive OEMs, and consumer electronics companies.
- Established manufacturing capabilities and proven commercial production enable reliable large-volume supply.
- Strong intellectual property portfolios and proprietary silicon anode technologies create high barriers to entry.
- Long-standing relationships with leading battery manufacturers and OEMs facilitate faster commercialization and repeat business.
- High capital expenditure requirements for scaling advanced silicon anode manufacturing facilities.
- Commercial-scale production remains challenged by silicon expansion and cycle-life limitations compared to conventional graphite.
- Dependence on a limited number of large customers increases revenue concentration risk.
Emerging Players (OneD Battery Sciences, Group14 Technologies, Inc., Sila Nanotechnologies Inc., NanoGraf Corporation, E-magy)
- Focus on developing differentiated silicon anode materials through intensive research, pilot-scale validation, and technology innovation.
- Collaborate with battery manufacturers, research institutions, and OEMs to accelerate product qualification and commercialization.
- Expand pilot production facilities while demonstrating manufacturing scalability before investing in large-scale plants.
- Highly innovative material designs enable superior energy density, faster charging, and improved battery performance.
- Agile organizational structures allow rapid technology development and quicker adaptation to evolving market requirements.
- Strong patent portfolios centered on next-generation silicon anode architectures provide technological differentiation.
- Limited commercial production capacity compared with established material suppliers.
- Heavy reliance on external funding and strategic partnerships to support technology development and manufacturing expansion.
- Longer qualification cycles with automotive and battery manufacturers delay revenue generation.
Recent Developments
-
In 2025, Sicona Battery Technologies began developing its first U.S. commercial facility in the southeastern region. The plant will initially produce 6,700 tpa of silicon-carbon anode material, with plans to scale up to 26,500 tpa. This capacity will support battery needs for over 3.25 million electric vehicles annually.
-
In May 2025, Sila Nanotechnologies began commissioning its Moses Lake, Washington facility to produce Titan Silicon, a next-gen silicon anode material. Developed in partnership with Panasonic, this material aims to boost EV battery energy density by up to 25% and cut charging times.
Silicon Anode Battery Market Report Scope
Report Attribute
Details
Market size in 2025
USD 475.1 million
Estimated market size in 2026
USD 682.5 million
Projected market size by 2033
USD 7,654.4 million
Growth rate
CAGR of 41.2% from 2026 to 2033
Market size in 2025
CAGR of 41.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Capacity, Application, Region
Regional scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, France, UK, Italy, Spain, Russia, China, India, Japan, Australia, Brazil, Argentina, Saudi Arabia, South Africa, UAE
Key companies profiled
Enovix Corporation, Amprius Technologies, OneD Battery Sciences, Nexeon Ltd., Group14 Technologies, Inc., Sila Nanotechnologies Inc., NanoGraf Corporation, E-magy, BTR New Material Group Co., Ltd., Shanshan co.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Silicon Anode Battery Market Report Segmentation
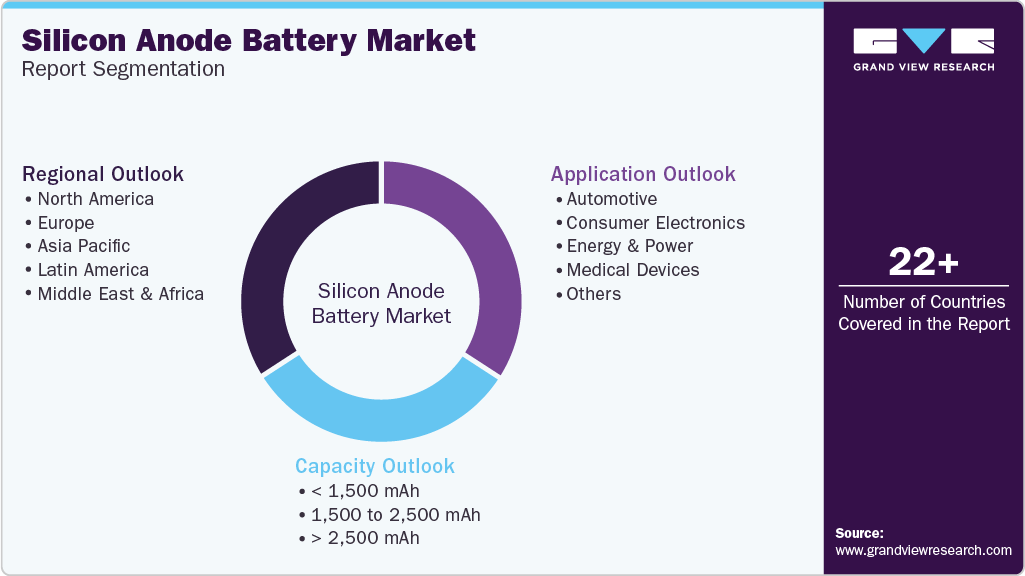
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global silicon anode battery market report based on capacity, application, and region:
 To learn more about this report, Download Free Sample Report
-
Capacity Outlook (Revenue, USD Million, 2021 - 2033)
-
< 1,500 mAh
-
1,500 to 2,500 mAh
-
> 2,500 mAh
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Consumer Electronics
-
Energy & Power
-
Medical Devices
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Italy
-
Spain
-
France
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The silicon anode battery market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each silicon anode battery segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Capacity
Revenue capture definition
< 1,500 mAh
Revenue represents sales of silicon anode batteries with a rated capacity below 1,500 mAh, supplied across various end-use applications.
1,500 to 2,500 mAh
Captures revenue generated from the sales of silicon anode batteries with a rated capacity ranging from 1,500 mAh to 2,500 mAh, supplied across various end-use applications.
> 2,500 mAh
Covers revenue generated from the sales of silicon anode batteries with a rated capacity above 2,500 mAh, supplied across various end-use applications.
Segment - Application
Revenue capture definition
Automotive
Revenue represents sales of silicon anode batteries used in electric vehicles, hybrid electric vehicles, and other automotive applications requiring high-energy-density battery systems.
Consumer Electronics
Captures revenue generated from silicon anode batteries supplied for consumer electronic devices, including smartphones, laptops, tablets, wearables, cameras, drones, and other portable electronic products.
Energy & Power
Covers revenue generated from silicon anode batteries used in energy storage systems, backup power solutions, renewable energy integration, and other stationary power applications.
Medical Devices
Represents revenue from silicon anode batteries supplied for medical equipment, including portable diagnostic devices, patient monitoring systems, implantable devices, and other battery-powered healthcare applications.
Others
Encompasses revenue generated from silicon anode batteries supplied for aerospace, defense, industrial equipment, robotics, telecommunications, and other niche end-use applications.
Estimation Model
Layer Name
Key Question
Description
Silicon Anode Battery Demand Layer
What drives the demand for silicon anode batteries?
Identify the key factors driving demand for silicon anode batteries, including the need for higher energy density, longer battery runtime, faster charging, growing electric vehicle adoption, increasing demand for advanced consumer electronics, and investments in next-generation battery technologies. Assess the impact of battery performance improvements, lightweight designs, and expansion of renewable energy storage applications on market growth.
Silicon Anode Battery Capacity Layer
Which battery capacity segments are witnessing higher demand?
Analyze demand based on battery capacity, including <1,500 mAh, 1,500-2,500 mAh, and >2,500 mAh. Assess adoption based on device power requirements, battery life expectations, charging performance, portability, and end-use application needs.
Silicon Anode Battery Application Layer
Where are silicon anode batteries primarily used?
Evaluate the adoption of silicon anode batteries across automotive, consumer electronics, energy & power, medical devices, and other applications. Assess demand based on battery performance requirements, energy density, charging speed, product innovation, electrification trends, and the increasing use of high-performance rechargeable batteries.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sales of silicon anode batteries across different battery capacity ranges and application segments. The overall market value is determined by revenue generated from the sale of silicon anode batteries supplied for automotive, consumer electronics, energy & power, medical device, and other end-use applications.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Battery Anode Materials Market Analysis
Conducted a detailed analysis of the battery anode materials market by material (lithium, silicon, graphite, and other materials) and application. The assessment included material adoption trends, performance comparison, application-wise demand, manufacturing capacity, supply chain dynamics, pricing trends, and future commercialization potential.
Enabled clients to compare the growth prospects of silicon anode materials against conventional graphite and other alternatives, identify high-growth application areas, evaluate technology transition trends, and make informed investment and product development decisions.
Competitive Benchmarking
Prominent battery anode material manufacturers were benchmarked based on material portfolio (graphite, silicon, lithium, and other anode materials), technology capabilities, R&D investments, manufacturing footprint, strategic partnerships, application focus, patent portfolio, and recent product launches and expansion initiatives.
Provided insights into competitive positioning, technology leadership, commercialization progress, manufacturing scale, strategic partnerships, and opportunities for product differentiation and market expansion.
Application Opportunity Assessment
Conducted a detailed demand analysis across automotive, consumer electronics, energy & power, medical devices, and other applications. The assessment evaluated silicon anode battery adoption trends, performance requirements, regulatory landscape, end-user demand, commercialization status, and future growth potential across each application segment.
Identified the highest-growth application areas, assessed application-specific demand drivers and adoption barriers, and enabled clients to prioritize product development, target high-value end-use markets, and optimize go-to-market strategies.
Frequently Asked Questions About This Report
Some key players operating in the silicon anode battery market include XG Sciences, Enevate Corporation, ENOVIX Corporation, Amprius technologies, Huawei, OneD Material, Inc. and others
The global silicon anode battery market size was valued at USD 357.3 million in 2024 and is estimated at USD 682.46 million for 2026.
The global silicon anode battery market is expected to grow at a CAGR of 50.1% from 2025 to 2030, reaching USD 3,618.5 million by 2030.
Key factors driving the growth of the silicon anode battery market include the increasing demand for high-energy density batteries across industries such as consumer electronics, automotive, and renewable energy is a primary driver, as silicon anode batteries provide superior energy storage capabilities compared to traditional lithium-ion batteries
< 1,500 mAh was the largest segment accounting for a share of over 42.0% of the global Silicon Anode Battery market revenue in 2024. The demand for silicon anode batteries with a capacity of less than 1,500 mAh is growing, primarily driven by the increasing need for compact and efficient energy solutions in consumer electronics.
About the Author(s)
Distribution & Utilities Research Team
Energy & Power · Distribution & UtilitiesThis report was authored by the distribution & utilities research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the distribution & utilities segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


