
- Home
- »
- Consumer F&B
- »
-
Sugar Market Size, Growth Report, 2026-2033GVR Report cover

Sugar Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (White Sugar, Brown Sugar), By Form (Granulated Sugar, Powdered Sugar), By End-use, By Source, By Region, And Segment Forecasts
Market Size, 2025
$75.3BMarket Estimate, 2026
$80.2BMarket Forecast, 2033
$124.3BCAGR, 2026–2033
6.5%Sugar Market Summary
The global sugar market size was valued at USD 75.3 billion in 2025 and is projected to grow from USD 80.2 billion in 2026 to USD 124.3 billion by 2033, at a CAGR of 6.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 42.0% in 2025. The increasing global population leads to a higher demand for sugar as it is a key ingredient in many food and beverage products. Changes in consumer preferences towards sweetened goods and beverages also play a significant role in driving the market growth.
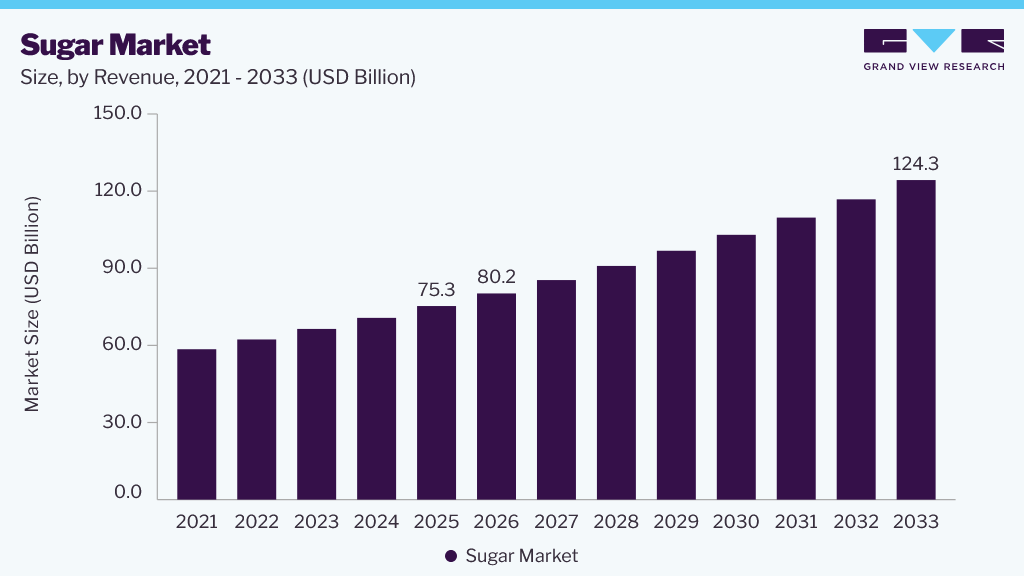 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The white sugar segment dominated the market, with a revenue share of around 67.0% in 2025.
- By form: The granulated sugar segment held the largest revenue share of around 79.0% in 2025.
- By end use: The food & beverages segment held the largest revenue share of around 45.0% in 2025.
- By source: The sugarcane segment held the largest revenue share of around 77.0% in 2025.
Regional Highlights
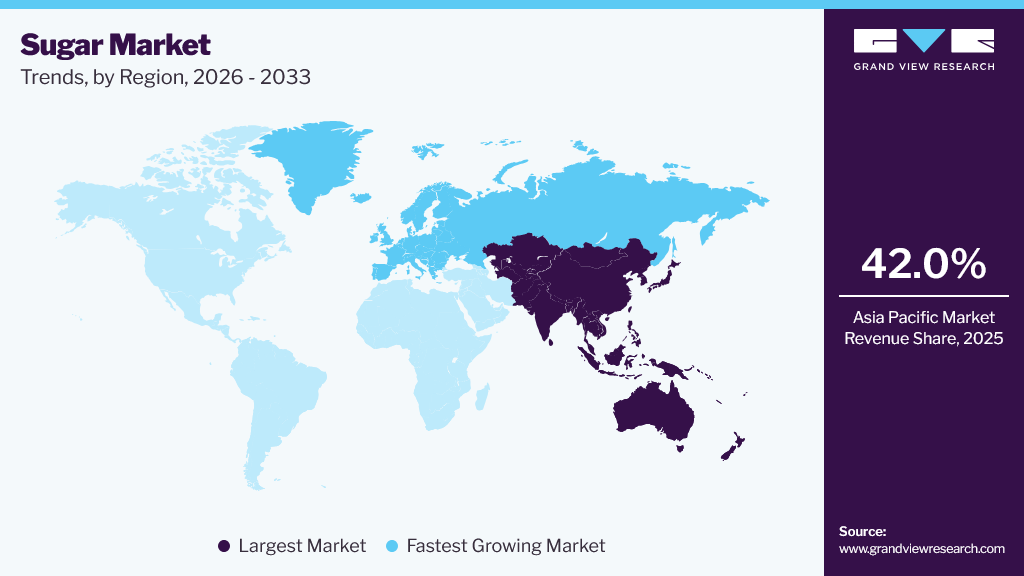
- Largest regional market: Asia Pacific (42.0% revenue share, 2025)
- Fastest-growing regional market: Europe (Highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 75.3 Billion
- Estimated market size in 2026: USD 80.2 Billion
- Projected market size by 2033: USD 124.3 Billion
- CAGR (2026-2033): 6.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The food industry remains the largest consumer of sugar, using it extensively in confectionery, bakery products, beverages, dairy products, sauces, and processed foods. Beyond providing sweetness, sugar enhances texture, improves mouthfeel, supports fermentation, and acts as a natural preservative, making it an indispensable ingredient in food manufacturing. The continued expansion of the global food processing industry and increasing consumption of packaged and convenience foods are key factors driving sugar demand.
Rapid urbanization, rising disposable incomes, and changing dietary habits, particularly in emerging economies, are further supporting market growth. As consumers adopt busier lifestyles, demand for ready-to-eat meals, snacks, confectionery, and sugar-sweetened beverages continues to increase, contributing to higher sugar consumption across both retail and foodservice channels.
In addition, the growing use of sugarcane and sugar beet as feedstocks for ethanol and other bio-based products is creating new growth opportunities for the market. Government mandates promoting biofuel blending, together with investments in renewable energy and sustainable agriculture, are encouraging greater cultivation of sugar crops and strengthening demand beyond traditional food applications. Furthermore, the widespread availability of sugar-containing products through supermarkets, convenience stores, e-commerce platforms, and foodservice outlets continues to support market expansion. Product innovation, premium confectionery offerings, and expanding retail distribution networks are increasing consumer access to sugar-based products and reinforcing demand across global markets.
Analyst Perspective
Growing investments in sustainable sugarcane and sugar beet cultivation, modernization of sugar processing facilities, precision agriculture, and energy-efficient production technologies are improving operational efficiency and supporting market expansion. In addition, the increasing utilization of sugar as a feedstock for ethanol, bio-based chemicals, and other renewable products is creating new growth opportunities for industry participants. However, climate variability, fluctuations in sugarcane and sugar beet yields, volatile raw material prices, evolving trade policies, and increasing regulatory initiatives to reduce sugar consumption may pose challenges to market growth. Nevertheless, continued technological advancements, product innovation, and the expansion of sustainable production practices are expected to support long-term growth.
Product Insights
By product, the white sugar segment led the market, accounting for 67.0% of revenue in 2025. White sugar's versatility makes it a preferred choice across various industries, including baking, confectionery, beverages, dairy products, and food processing. Its neutral flavor, consistent quality, and high solubility make it suitable for a wide range of culinary applications, appealing to both consumers and manufacturers. Moreover, its refined appearance and uniform composition make it the preferred choice for standardized food production and packaged consumer goods. In addition, its long shelf life, ease of storage, and compatibility with automated food manufacturing processes further strengthen its market leadership. White sugar's extensive use as a key ingredient in industrial food and beverage manufacturing continues to support segment growth.
The brown sugar segment is expected to grow at the fastest CAGR from 2026 to 2033. Growing consumer interest in natural, minimally processed, and specialty sweeteners is driving demand for brown sugar across retail and foodservice channels. Its molasses content imparts a distinctive caramel-like flavor, moist texture, and darker color, making it a preferred ingredient in bakery products, confectionery, sauces, marinades, and specialty beverages. Although its nutritional advantages over white sugar are limited, many consumers perceive brown sugar as a more natural alternative, supporting its adoption among health- and wellness-conscious buyers. In addition, the growing popularity of artisanal baking, premium desserts, and gourmet food products is expected to further drive demand for brown sugar.
Source Insights
By source, the sugarcane segment accounted for the largest revenue share of 77.0% in 2025. Sugarcane boasts a higher sugar content than sugar beet, making it a more efficient and economical source for sugar production. This inherent advantage translates into higher yields and lower production costs, ultimately contributing to sugarcane's dominance in the market. In addition, sugarcane cultivation is more widespread globally, with tropical regions providing ideal conditions for its growth. Its cultivation in these regions benefits from abundant sunlight, ample rainfall, and fertile soils, further enhancing its productivity and availability. Moreover, sugarcane's versatility extends beyond sugar production, with its by-products finding forms in biofuel production, animal feed, and various industries.
The sugar beet segment is projected to register a significant CAGR from 2026 to 2033. Sugar beet cultivation offers significant advantages in temperate regions with suitable soil and climate conditions, expanding its geographic reach and production potential. Its adaptability to cooler climates makes it a viable alternative to sugarcane in regions where sugarcane cultivation is less feasible. In addition, increasing investments in sustainable farming practices, precision agriculture, and advanced beet processing technologies are improving crop yields, resource efficiency, and sugar extraction rates. The adoption of high-yield sugar beet varieties, coupled with modern harvesting techniques and energy-efficient processing facilities, is supporting the expansion of sugar beet cultivation across Europe, North America, and other temperate regions.
End Use Insights
By end use, the food & beverages segment led the market with the largest revenue share of 45.0% in 2025. Sugar is a fundamental ingredient in a wide range of food and beverage products, contributing sweetness, texture, and flavor. From sweetening beverages to enhancing the taste of baked goods, confectionery, and dairy products, sugar plays a central role in the formulation and production of various consumer favorites. Its versatility enables seamless integration into a wide range of culinary creations, making it indispensable for manufacturers across the food and beverage industry. Moreover, consumer preferences for sweetened products drive the demand for sugar in the food and beverage sector. Sugary treats, snacks, and beverages remain perennially popular among consumers worldwide, reflecting a universal craving for sweetness and indulgence. As a result, food and beverage manufacturers rely heavily on sugar to meet consumer expectations for taste, texture, and sensory experiences.
Furthermore, the sheer scale of consumption in the food and beverage industry contributes to sugar's dominance as an end-use category. With billions of consumers worldwide consuming a wide array of food and beverage products daily, the demand for sugar remains consistently high, driving production volumes and market growth.
The pharmaceutical & personal care segment is expected to grow at a significant CAGR from 2026 to 2033. There has been a growing awareness and recognition of the multifaceted benefits of sugar in pharmaceutical and personal care forms. Sugar is a versatile ingredient in pharmaceutical formulations, used as an excipient, binder, or coating agent in the production of tablets, capsules, and syrups. Its hygroscopic properties also contribute to the stability and shelf life of certain medications. In the personal care industry, sugar is increasingly incorporated into skincare, haircare, and cosmetic products for its exfoliating, moisturizing, and humectant properties. The growing emphasis on sustainable and bio-based ingredients is encouraging manufacturers to develop next-generation cosmetic ingredients derived from renewable feedstocks. For instance, in March 2023, L'Oréal S.A., through its corporate venture fund BOLD, invested in a biotechnology venture led by Geno to develop sustainable bio-based ingredients produced from plant-based sugars. The investment supports the replacement of conventional cosmetic ingredients with renewable alternatives across L'Oréal's beauty portfolio, advancing more sustainable skincare and personal care formulations.
Form Insights
By form, the granulated sugar segment led the market with the largest revenue share of around 79.0% in 2025. The granulated form offers versatility, dissolving uniformly and blending easily into a wide range of food and beverage applications, making it an essential ingredient in both household and industrial food production. In addition, its long shelf life, resistance to moisture-induced clumping, and ease of storage and transportation make it highly preferred by consumers and manufacturers. Its cost-effectiveness, widespread availability, and compatibility with numerous food processing applications further strengthen its market dominance across diverse end-use industries.
The sugar syrups segment is projected to register a significant CAGR from 2026 to 2033. Sugar syrup is widely used as a sweetener, flavor enhancer, humectant, and texturizing agent in beverages, bakery products, confectionery, dairy products, and processed foods. The growing demand for ready-to-drink beverages, convenience foods, and customized food formulations is accelerating the adoption of sugar syrups due to their ease of handling, consistent sweetness, and efficient incorporation into large-scale manufacturing processes. In addition, their ability to improve product texture, extend shelf life, and deliver uniform flavor distribution is expected to support segment growth.
Regional Insights
The North America sugar market is expected to grow at a significant CAGR from 2026 to 2033. The trend toward convenience foods and snacking continues to drive demand for sugar-based products, including packaged snacks, sweetened beverages, confectionery, bakery products, and other processed foods. Consumers' busy lifestyles and on-the-go eating habits further support the consumption of these products. In addition, increased investment in modernizing domestic sugar-refining infrastructure is enhancing production efficiency, strengthening regional supply chains, and supporting the long-term availability of refined sugar. For instance, in May 2026, American Sugar Refining, Inc. broke ground on the first phase of a USD 785 million modernization project at the Domino Sugar Chalmette Refinery in Louisiana, representing the company's largest capital investment to date. The initial phase, valued at more than USD 200 million, includes the construction of a new state-of-the-art process building equipped with modern refining systems designed to improve operational reliability, reduce energy and water consumption, and meet future demand for refined sugar. The refinery, the largest sugar refinery in the Western Hemisphere, is expected to further strengthen North America's sugar refining capacity.
U.S. Sugar Market Trends
The sugar market in the U.S. is expected to grow at a significant CAGR from 2026 to 2033, owing to its widespread use as a sweetening agent in various food and beverage products. Sugar is a staple ingredient in the food industry, used in the production of baked goods, confectionery, beverages, sauces, and other processed foods, which contributes to its sustained demand. In addition, the expansion of the country's food processing and beverage manufacturing industries, coupled with strong demand for convenience and packaged foods, is expected to further drive sugar consumption. The pharmaceutical industry also supports market growth by using sugar in syrups, chewable tablets, and other medicinal formulations.
Asia Pacific Sugar Market Trends
The sugar market in Asia Pacific dominated with a revenue share of around 42.0% in 2025. The region is home to some of the world's largest sugar-producing countries, including India, China, Thailand, and Indonesia, supported by favorable agro-climatic conditions, extensive arable land, and well-established sugarcane cultivation. Rapid population growth, rising disposable incomes, urbanization, and changing dietary preferences continue to drive strong demand for sugar across food and beverage, confectionery, bakery, dairy, and processed food applications. In addition, expanding investments in sustainable sugarcane cultivation, modernizing milling operations, and improving crop quality are enhancing production efficiency and strengthening the regional sugar industry. For instance, in March 2026, Mitr Phol Group announced that its Let's Green the Sugarcane campaign increased the share of fresh sugarcane supplied to its mills to more than 96% during the 2025/26 crushing season. The initiative promotes fresh cane harvesting, modern farming practices, and the utilization of sugarcane leaves for biomass power generation, improving raw material quality, enhancing mill efficiency, and supporting more sustainable sugar production in Thailand.
 To learn more about this report, Download Free Sample Report
In addition, rapid urbanization, industrialization, and economic development in countries such as China and India have led to increased urban consumption and demand for convenience foods, where sugar plays a crucial role as a primary sweetener and preservative. Furthermore, Asia Pacific's expanding pharmaceutical and personal care industries contribute to the demand for sugar-based ingredients in medications, cosmetics, and personal care products.
The China sugar market is expected to grow at a significant CAGR from 2026 to 2033. Rising disposable incomes, continued urbanization, and changing consumer lifestyles are driving demand for confectionery, bakery products, beverages, dairy products, and other processed foods that utilize sugar as a key ingredient. In addition, the expansion of the country's food processing industry, supported by increasing retail and e-commerce penetration, is expected to sustain sugar consumption over the forecast period.
Europe Sugar Market Trends
The sugar market in Europe is expected to grow at a significant CAGR from 2026 to 2033, supported by the strong presence of the food and beverage industry, where sugar remains an essential ingredient in confectionery, bakery, dairy products, beverages, and processed foods. In addition, increased investment in sustainable sugar production, advances in beet processing technologies, and the adoption of energy-efficient manufacturing practices are enhancing production efficiency. Although growing health awareness has encouraged demand for reduced-sugar alternatives, the continued use of sugar in food processing, coupled with favorable agricultural policies and stable sugar beet cultivation across major producing countries, is expected to support market growth.
The Germany sugar market is anticipated to grow at a significant CAGR from 2026 to 2033. Germany is one of Europe's leading sugar producers, supported by extensive sugar beet cultivation and well-established processing infrastructure. The country's robust food and beverage industry continues to drive demand for sugar across confectionery, bakery, dairy, beverage, and processed food applications. In addition, ongoing investments in production modernization, energy efficiency, and sustainable manufacturing by major sugar producers are expected to strengthen domestic production and support long-term market growth.
Key Sugar Companies Insights
The market includes both international and domestic participants. Brand market share analysis indicates that key market players are focusing on strategies such as new product launches, partnerships, mergers and acquisitions, global expansion, and others.
Key Sugar Company Insights
The following key companies have been profiled for this study on the sugar market:
-
Südzucker AG
-
Tereos
-
Cosan
-
Mitr Phol Group
-
Associated British Foods plc
-
Nordzucker
-
Cargill, Incorporated
-
Raízen S.A.
-
Wilmar International Ltd
-
Thai Roong Ruang Group
Recent Developments
-
In January 2026, Nordzucker AG announced the successful completion of its 2025/2026 beet campaign while highlighting significant progress under its GoGreen program. The company reported investments in factory modernization, energy efficiency improvements, and CO₂ reduction initiatives to strengthen sustainable sugar production and improve operational performance across its manufacturing network.
-
In June 2025, Wilmar Sugar and Renewables completed a USD 12 million modernization project at its Kalamia Mill in Queensland, Australia, with the installation of a new 72-meter steel boiler stack replacing aging infrastructure. The project improves operational reliability, manufacturing efficiency, and long-term processing capacity while supporting sustainable sugar production through modern engineering solutions.
Sugar Market Report Scope
Report Attribute
Details
Market size in 2025
USD 75.3 billion
Estimated market size in 2026
USD 80.2 billion
Projected market size by 2033
USD 124.3 billion
Growth rate
CAGR of 6.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Product, form, source, end-use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; Indonesia; Thailand; Brazil; South Africa
Key companies profiled
Südzucker AG; Tereos; Cosan; Mitr Phol Group; Associated British Foods plc; Nordzucker; Cargill, Incorporated; Raízen S.A.; Wilmar International Ltd; Thai Roong Ruang Group
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Sugar Market Report Segmentation
This report forecasts revenue growth at the global, regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global sugar market report based on product, form, source, end-use, and region.
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
White Sugar
-
Brown Sugar
-
Liquid Sugar
-
-
Form Outlook (Revenue, USD Billion, 2021 - 2033)
-
Granulated Sugar
-
Powdered Sugar
-
Syrup Sugar
-
-
Source Outlook (Revenue, USD Billion, 2021 - 2033)
-
Sugarcane
-
Sugar Beet
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Food & Beverages
-
Confectionary
-
Bakery Products
-
Dairy Products
-
Beverages
-
Others
-
-
Pharmaceuticals
-
Personal Care
-
Household
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Indonesia
-
Thailand
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
-
Frequently Asked Questions About This Report
The global sugar market size was valued at USD 75.3 billion in 2025 and is estimated at USD 80.2 billion for 2026.
The global sugar market is expected to grow at a CAGR of 6.5% from 2026 to 2033, reaching USD 124.3 billion.
Asia Pacific sugar market held the largest revenue share of around 42.0% in 2025 and is expected to retain its dominance during 2024-2030. Asia Pacific is home to some of the world's largest sugar-producing countries, including India, China, Thailand, and Indonesia. The region's favorable agro-climatic conditions and extensive arable land make it conducive to sugarcane cultivation, which forms the backbone of the sugar industry. Moreover, the region's large and growing population, coupled with rising disposable incomes and changing dietary patterns, drives robust demand for sugar as a staple ingredient in various food and beverage products
Key players in the market include Südzucker AG; Tereos; Cosan; Mitr Phol Group; Associated British Foods plc; Nordzucker; Cargill, Incorporated; Raízen S.A.; Wilmar International Ltd; Thai Roong Ruang Group, and others.
The white sugar segment accounted for the largest revenue share of approximately 67.0% in 2025.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


