
- Home
- »
- Medical Devices
- »
-
Surgical Drills Market Size, Share, Trends Report, 2026-2033GVR Report cover

Surgical Drills Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Instrument, Accessories), By Application (Orthopedic, Dental, ENT, Others), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$1.4BMarket Estimate, 2026
$1.4BMarket Forecast, 2033
$2.1BCAGR, 2026–2033
5.5%Surgical Drills Market Summary
The global surgical drills market size was estimated at USD 1.4 billion in 2025 and is projected to grow from USD 1.4 billion in 2026 to USD 2.1 billion by 2033, growing at a CAGR of 5.5% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 36.5% in 2025. Technological advancements, such as battery-powered and computer-assisted drills, enhance precision and efficiency, thereby fueling demand. The rising number of orthopedic, dental, and neurosurgical procedures, due to aging populations and increased trauma cases, also boosts the market.
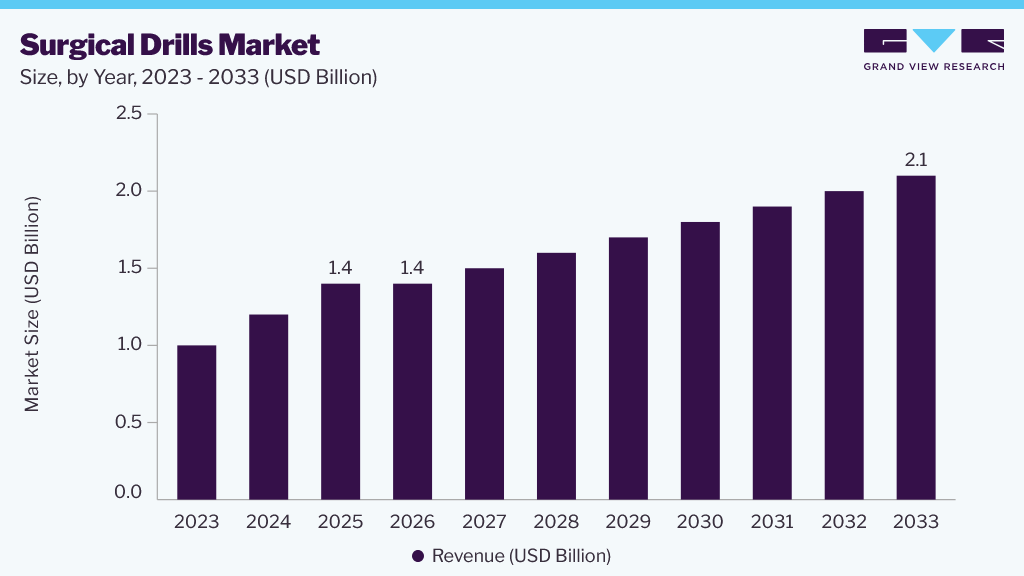 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The instruments segment dominated the market, with a revenue share of about 62.0% in 2025.
- By application: The orthopedic surgeries segment dominated the market, with a revenue share of about 43.0% in 2025.
- By end use: The hospitals & clinics segment dominated the market, with a revenue share of about 49.0% in 2025.
Regional Highlights
- Largest regional market: North America (36.5% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 1.4 Billion
- Estimated market size in 2026: USD 1.4 Billion
- Projected market size by 2033: USD 2.1 Billion
- CAGR (2026-2033): 5.5%
Prism AI by Grand View Research Free to tryAsk a question about the surgical drills marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The global market is experiencing steady growth, driven by the increasing number of orthopedic, neurosurgical, dental, and trauma procedures worldwide. Rising healthcare expenditure, particularly in developing economies, is enabling healthcare providers to invest in advanced surgical equipment, while the growing adoption of minimally invasive and robotic-assisted procedures is increasing the demand for high-performance surgical drills that offer greater precision, efficiency, and procedural safety.
The rising burden of musculoskeletal disorders and the expanding geriatric population are among the primary factors supporting market growth. According to the WHO, approximately 1.71 billion people worldwide live with musculoskeletal conditions, while 250,000–500,000 people sustain spinal cord injuries each year. Furthermore, Our World in Data estimates that around 10% of the global population is aged 65 years and above, increasing the prevalence of osteoporosis, osteoarthritis, and other age-related orthopedic conditions that frequently require surgical intervention. This growing patient population continues to drive demand for advanced orthopedic surgical drills.
The increasing incidence of sports injuries and road traffic accidents is further accelerating market expansion. Rising participation in sports and recreational activities has led to a greater number of ligament tears, fractures, and other orthopedic injuries requiring surgical treatment. In addition, the WHO estimates that road traffic crashes result in approximately 1.19 million deaths annually, while tens of millions of people sustain non-fatal injuries, many involving complex fractures that require orthopedic fixation procedures. These trends are contributing to sustained demand for surgical drills in trauma and reconstructive surgeries.
Technological advancements are also reshaping the market. Manufacturers are introducing battery-powered, high-speed, lightweight, and ergonomically designed surgical drills with improved precision, reduced vibration, and enhanced safety features to improve surgical outcomes. The integration of robotic-assisted surgery, navigation systems, and smart surgical technologies is further expanding the applications of advanced drilling systems across multiple surgical specialties. For instance, in March 2024, Northwestern Medicine became the first healthcare system to use a novel bedside neurosurgical drill designed to provide faster, safer, and more precise access during brain surgery. The innovative system enhances procedural efficiency, minimizes surgical risks, and supports improved patient outcomes, highlighting the growing emphasis on technological innovation in surgical drilling systems. Overall, the combination of rising surgical volumes, expanding healthcare infrastructure, increasing trauma and orthopedic cases, and continuous technological innovation is expected to create significant growth opportunities for manufacturers operating in the market.
Analyst Perspective
The market is expected to grow steadily over the forecast period, driven by the increasing number of orthopedic, neurosurgical, dental, spinal, and trauma procedures worldwide. The rising prevalence of musculoskeletal disorders, osteoporosis, arthritis, sports-related injuries, and road traffic accidents, coupled with the expanding geriatric population, is creating sustained demand for advanced surgical drilling systems. In addition, the growing adoption of minimally invasive and robotic-assisted surgeries is driving demand for high-performance surgical drills that deliver greater precision, efficiency, and improved patient safety. Manufacturers are increasingly focusing on product innovation by developing lightweight, battery-powered, high-speed, and ergonomically designed surgical drills integrated with smart technologies, navigation systems, and robotic platforms to improve surgical accuracy and workflow efficiency. Furthermore, rising healthcare expenditure, continuous investments in hospital infrastructure, expanding access to advanced surgical care in emerging economies, and favorable technological advancements are expected to create significant growth opportunities for market participants throughout the forecast period.
Product Insights
The instruments segment, comprising electric, battery-powered, and pneumatic drills, accounted for the largest revenue share of 62.0% in 2025 and is expected to register the fastest CAGR during the forecast period. The segment's dominance is attributed to the widespread use of powered surgical instruments across orthopedic, neurosurgical, spinal, and trauma procedures. Electric drills are preferred for their high precision, consistent performance, and ability to support complex surgical procedures, while battery-powered drills offer greater portability, cordless operation, and improved maneuverability within the operating room. In addition, the growing adoption of lightweight, high-speed, and ergonomically designed powered instruments, coupled with increasing demand for minimally invasive and robotic-assisted surgeries, is further driving segment growth. For instance, in June 2025, Arthrex, Inc. released the Synergy PowerSystem, an electrosurgical power-tool platform that includes rechargeable surgical devices intended for orthopedic surgeries such as sports medicine, arthroplasty, trauma surgery, and distal extremity procedures. It comes with a variety of powered attachments and blades for cutting and drilling operations.
Pneumatic drills, known for their robustness and reliability, are preferred in high-demand surgical environments where consistent performance is essential. Their widespread adoption is driven by their ability to support a broad range of surgical procedures, continuous technological advancements, and their contribution to improved surgical precision and patient outcomes. In addition, pneumatic drills are widely used in high-volume orthopedic and trauma surgeries because they provide high torque, consistent drilling performance, and uninterrupted operation without battery limitations, making them well-suited for lengthy and demanding procedures. As surgical procedures become more complex and minimally invasive, the demand for these advanced drilling instruments is expected to grow, reinforcing their significant market share.
Application Insights
The orthopedic surgeries segment accounted for the largest revenue share of 43.0% in 2025, driven by the increasing prevalence of musculoskeletal disorders and the growing demand for joint replacement, fracture fixation, and sports medicine procedures. The expanding geriatric population, rising incidence of osteoporosis, osteoarthritis, and traumatic bone fractures, and increasing participation in sports activities continue to support segment growth. Orthopedic procedures require high-precision surgical drills for bone preparation, implant placement, and fixation, making advanced powered drilling systems essential for improving surgical accuracy and clinical outcomes. Furthermore, the increasing adoption of robotic-assisted orthopedic surgeries is accelerating demand for technologically advanced surgical drills that offer greater precision and control. For instance, in June 2024, Johnson & Johnson MedTech announced that DePuy Synthes received U.S. FDA clearance to expand the use of its VELYS Robotic-Assisted Solution for unicompartmental knee arthroplasty (UKA), reflecting the growing adoption of advanced orthopedic surgical technologies that complement precision-powered surgical instruments, including surgical drills.
The dental surgeries segment is expected to register the fastest CAGR from 2026 to 2033, driven by the increasing number of dental procedures, continuous advancements in dental drill technology, and the rising demand for cosmetic, restorative, and implant dentistry. The growing geriatric population requiring tooth replacement procedures, increasing awareness of oral health, and the rising prevalence of dental disorders such as tooth decay, periodontal disease, and edentulism are further contributing to market growth. In addition, the expanding adoption of dental implants and digital dentistry technologies, including computer-guided implant placement, is significantly increasing the demand for high-speed, precision dental surgical drills. Furthermore, technological innovations, such as lightweight, ergonomically designed, low-noise, and high-speed dental drills with improved cooling systems, are enhancing procedural accuracy, patient comfort, and clinical efficiency, thereby accelerating market expansion in the dental surgery segment.
End Use Insights
The hospitals & clinics segment accounted for the largest revenue share of 49.0% in 2025 and is expected to register the fastest CAGR during the forecast period. This dominance is primarily attributed to the high volume of orthopedic, neurosurgical, dental, and trauma procedures performed in these settings, which drives substantial demand for surgical drills. Hospitals and clinics continuously invest in advanced surgical technologies and modern powered instruments to improve procedural precision, efficiency, and patient outcomes. In addition, the growing availability of skilled surgeons and the increasing number of multispecialty hospitals are further supporting the adoption of advanced surgical drill systems.
The increasing prevalence of chronic conditions, such as osteoarthritis and osteoporosis, coupled with the rising number of orthopedic surgeries, further supports demand for surgical drills. Additionally, the growing adoption of minimally invasive and robotic-assisted surgeries, which require specialized high-precision drilling systems, is accelerating growth in this segment. Furthermore, the expansion and modernization of hospital infrastructure, including the development of hybrid operating rooms and digital surgical suites, are increasing the adoption of technologically advanced surgical drill systems. Continuous investments in healthcare infrastructure and medical technology reinforce the segment's leading position in the market.
Regional Insights
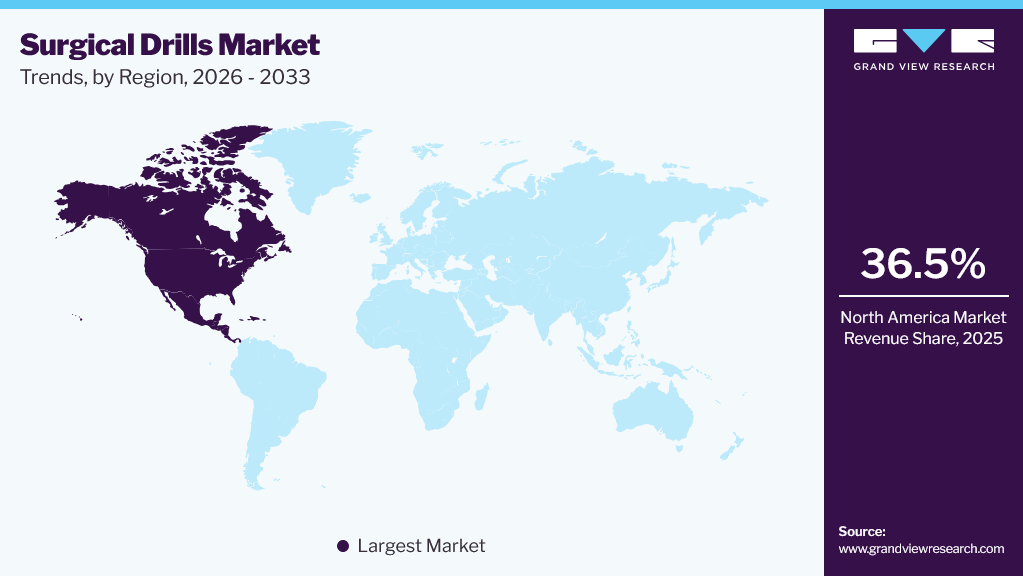
The North America surgical drills market dominated the global market, accounting for 36.5% of revenue in 2025. The regional market is driven by the high volume of orthopedic, neurosurgical, dental, and trauma procedures, supported by a well-established healthcare infrastructure and the widespread adoption of advanced surgical technologies. The increasing prevalence of musculoskeletal disorders, sports-related injuries, and traumatic fractures, coupled with the growing geriatric population, continues to drive demand for precision-powered surgical drills. In addition, the rapid adoption of robotic-assisted and minimally invasive surgical procedures, along with favorable reimbursement policies and continuous investments in hospital modernization, is accelerating the adoption of technologically advanced surgical drill systems across the region. Furthermore, the strong presence of leading medical device manufacturers and continuous product innovations are expected to sustain North America's leading position in the global market.
 To learn more about this report, Download Free Sample Report
U.S. Surgical Drills Market Trends
The surgical drills market in the U.S. held a significant share of North America's surgical drill market in 2025. The U.S. market for surgical drills is driven by factors such as rising global healthcare expenditure and expanding applications of 3D printing in the healthcare sector. Increasing investment in the technological advancement of surgical drills and rising R&D spending are factors contributing to market growth in this region. Companies offering various types of devices are increasingly adopting expansion strategies, such as product launches, mergers, acquisitions, partnerships, and collaborations.
Europe Surgical Drills Market Trends
The surgical drills market in Europe is experiencing significant growth, driven by expanding healthcare infrastructure, increasing healthcare expenditure, and a thriving medical tourism sector. The market is further supported by the growing geriatric population, which is associated with a higher prevalence of osteoarthritis, osteoporosis, bone fractures, and obesity, leading to increased demand for orthopedic and trauma surgeries. In addition, the rising adoption of robotic-assisted and minimally invasive surgical procedures, coupled with ongoing investments in technologically advanced operating rooms across European healthcare facilities, is driving demand for precision-powered surgical drills.
The UK surgical drills market is expected to grow over the forecast period, driven by the rising prevalence of osteoporosis, osteoarthritis, and other musculoskeletal disorders, as well as the increasing incidence of sports-related injuries and road traffic accidents. The growing number of orthopedic and trauma procedures is increasing demand for precision-powered surgical drills. In addition, ongoing investments in healthcare infrastructure, expanding adoption of minimally invasive and robotic-assisted surgeries, and continuous technological advancements in surgical devices are expected to create significant growth opportunities for market participants.
The surgical drills market in France is expected to grow steadily, supported by government investments in healthcare innovation, increasing adoption of advanced medical technologies, and the continued expansion of the domestic MedTech industry. Government initiatives promoting medical device innovation and manufacturing are creating a favorable environment for market growth. Furthermore, the rising prevalence of orthopedic disorders, trauma injuries, and age-related musculoskeletal conditions, coupled with the increasing number of orthopedic procedures, is driving demand for advanced surgical drills across healthcare facilities.
Germany surgical drills market is driven by the increasing prevalence of musculoskeletal disorders, a rapidly aging population, and the growing number of orthopedic and trauma surgeries. Osteoarthritis remains one of the leading causes of joint replacement procedures, while the rising incidence of fractures and sports-related injuries continues to support demand for advanced orthopedic surgical devices. In addition, Germany's well-established healthcare infrastructure, widespread adoption of minimally invasive and robotic-assisted surgical techniques, and strong focus on precision medical technologies are accelerating the adoption of technologically advanced surgical drill systems.
Asia Pacific Surgical Drills Market Trends
The surgical drills market in the Asia Pacific is expected to grow substantially over the forecast period, driven by rapid healthcare infrastructure development, rising healthcare expenditure, and the increasing volume of orthopedic, neurosurgical, and dental procedures in countries such as China, India, and Japan. The rising prevalence of musculoskeletal disorders, increasing incidence of trauma and sports-related injuries, and expanding geriatric population are fueling demand for advanced surgical drills. In addition, the growing adoption of minimally invasive and robotic-assisted surgeries, coupled with continuous technological advancements in powered surgical instruments, is accelerating market growth. Furthermore, the expansion of medical tourism, particularly in India and Thailand, is increasing the demand for high-quality surgical equipment. According to the Ministry of Tourism of India, the number of foreign tourists visiting India for medical reasons has been increasing consistently, making the country a strong destination for health care services in the Asia-Pacific region. The development of advanced surgical centers and the increasing volume of orthopedic procedures are expected to drive the adoption of technologically advanced surgical drills across the region.
Japan surgical drills market is expected to witness steady growth over the forecast period, driven by the country's rapidly aging population, increasing prevalence of musculoskeletal disorders, and growing demand for joint replacement and spinal surgeries. Japan's well-established medical device industry, advanced manufacturing capabilities, and early adoption of innovative surgical technologies continue to support market expansion. In addition, the growing adoption of robotic-assisted orthopedic procedures and minimally invasive surgical techniques is driving demand for high-precision surgical drills across healthcare facilities.
The surgical drills market in China is expected to grow significantly, driven by the country's rapidly aging population, expanding healthcare infrastructure, and increasing adoption of minimally invasive surgical procedures. Rising cases of orthopedic disorders, trauma injuries, and sports-related injuries are increasing the demand for advanced surgical drills. Furthermore, government investments in hospital modernization, the expansion of domestic medical device manufacturing, and supportive policies that promote healthcare innovation are accelerating the adoption of technologically advanced, cost-effective surgical drill systems across the country.
India surgical drills market is expected to witness robust growth, supported by the increasing adoption of minimally invasive orthopedic procedures, expanding geriatric population, and rising prevalence of musculoskeletal disorders such as osteoporosis and osteoarthritis. The growing burden of obesity and lifestyle-related disorders is contributing to higher rates of joint deterioration and orthopedic surgeries. In addition, increasing investments in healthcare infrastructure, expansion of multispecialty hospitals, and rising medical tourism are driving the demand for advanced surgical drills across the country.
Latin America Surgical Drills Market Trends
The surgical drills market in Latin America is expected to grow steadily, driven by the expanding elderly population and increasing prevalence of chronic musculoskeletal disorders requiring surgical intervention. Rising healthcare expenditure, improving access to orthopedic and trauma care, and ongoing investments in healthcare infrastructure are further supporting market growth. In addition, the increasing incidence of road traffic accidents and sports-related injuries across the region is contributing to the growing demand for advanced surgical drills used in trauma and reconstructive procedures.
Saudi Arabia surgical drills market is anticipated to expand during the forecast period, driven by the growing geriatric population and increasing prevalence of chronic musculoskeletal disorders that require surgical intervention. According to the Saudi Central Bank (formerly SAMA), the proportion of the population aged 60 years and above is projected to reach approximately 25% by 2050, increasing the demand for orthopedic and spinal procedures. Furthermore, ongoing healthcare infrastructure development under Vision 2030, rising investments in advanced medical technologies, and expansion of specialized hospitals are expected to accelerate the adoption of technologically advanced surgical drill systems across the country.
Key Surgical Drills Company Insights
The market is highly competitive, with key players including Arthrex, Inc., B. Braun SE, Medtronic, Johnson & Johnson, Stryker, Apothecaries Sundries Mfg. Pvt. Ltd., CONMED Corporation, 3M, MicroAire, and Zimmer Biomet. These companies are strengthening their market presence through continuous product innovation and portfolio expansion.
Key Surgical Drills Companies
The following key companies have been profiled for this study on the surgical drills market:
-
Arthrex, Inc.
-
B. Braun SE
-
Medtronic
-
Johnson & Johnson
-
Stryker
-
Apothecaries Sundries Mfg. Pvt. Ltd.
-
CONMED Corporation
-
3M
-
MicroAire
-
Zimmer Biomet
Recent Developments
-
In January 2024, Myron Meditech launched a new website dedicated to orthopedic bone drills. This platform provides detailed information on their advanced bone-drilling technology, enhancing accessibility for healthcare professionals and facilitating informed purchasing decisions. The launch signifies the company's commitment to innovation and customer engagement in the medical device industry.
-
In February 2023, McGinley Orthopedics received an Innovative Technology contract from Vizient for its Intellisense Orthopedic Drill. This recognition highlights the drill's advanced capabilities in enhancing surgical precision and efficiency, potentially leading to improved patient outcomes and streamlined orthopedic procedures within Vizient's extensive healthcare network.
Surgical Drills Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.4 billion
Estimated market size in 2026
USD 1.4 billion
Projected market size by 2033
USD 2.1 billion
Growth rate
CAGR of 5.5% from 2026 to 2033
Base year estimation
2024
Actual data
2021 – 2025
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Arthrex, Inc.; B. Braun SE; Medtronic; Johnson & Johnson Services, Inc.; Stryker; Apothecaries Sundries Mfg. Pvt. Ltd.; ConMed Corporation; 3M; MicroAire; Zimmer Biomet
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Surgical Drills Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global surgical drills market report based on product, application, end use, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Instrument
-
Pneumatic Drill
-
Electric Drill
-
Battery-Powered Drill
-
-
Accessories
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Orthopedic Surgeries
-
Dental Surgeries
-
ENT Surgeries
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
-
Hospitals & Clinics
-
Ambulatory Surgical Centers
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
-
Frequently Asked Questions About This Report
The global surgical drills market size was valued at USD 1.5 billion in 2025 and is estimated at USD 1.4 billion for 2026.
The instruments segment accounted for the largest revenue share of approximately 62.0% in 2025.
Key players include Arthrex, Inc., B. Braun SE, Medtronic, Johnson & Johnson Services, Inc., Stryker, Apothecaries Sundries Mfg. Pvt. Ltd., ConMed Corporation, 3M, MicroAire, Zimmer Biomet, and others.
The global surgical drills market is expected to grow at a CAGR of 5.5% from 2026 to 2033, reaching USD 2.1 billion by 2033.
North America dominated with a 36.5% revenue share in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


