
- Home
- »
- Renewable Energy
- »
-
Syngas Market Size, Share & Growth Report, 2026-2033GVR Report cover

Syngas Market (2026 - 2033)
Size, Share & Trends Analysis Report By Production Technology (Steam Reforming, Partial Oxidation, Autothermal Reforming, Biomass Gasification), By Feedstock, By Gasifier Type, By Application, By Region, And Segment Forecasts
Market Size, 2025
$272.9MMarket Estimate, 2026
$303.7MMarket Forecast, 2033
$642.0MCAGR, 2026–2033
11.3%Syngas Market Summary
The global syngas market size was valued at 272.9 million in 2025 and is projected to grow from 303.7 million in 2026 to 642.0 million by 2033, at a CAGR of 11.3% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of around 53.5% in 2025. Rising demand for cleaner alternative fuels is expected to drive market growth. Growing government support for clean energy initiatives, including tax credits and renewable portfolio standards, incentivizes investments in syngas technologies, fostering market expansion.
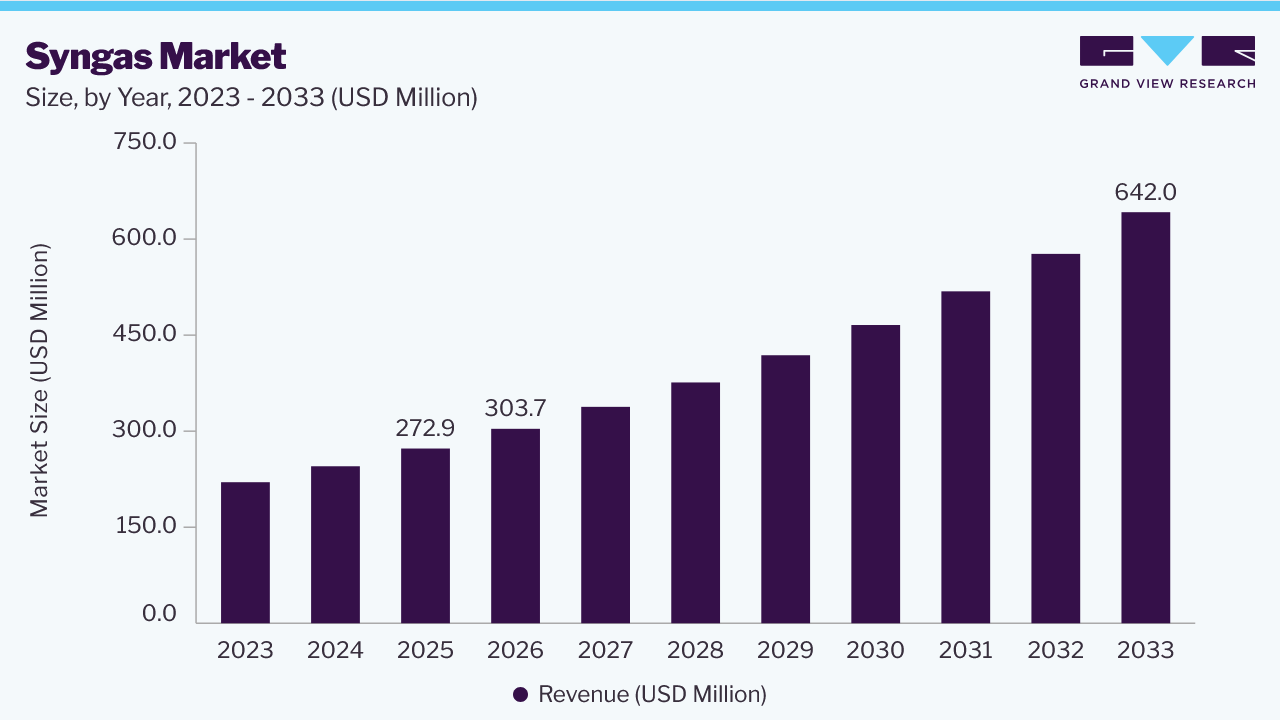 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By production technology: The steam reforming segment held the largest market share of approximately 48.0% in 2025.
- By feedstock: The natural gas segment held the largest market share of over 46.5% in 2025.
- By gasifier: The fluidized bed segment held the largest volume share of over 59.0% in 2025.
- By application: The chemical segment held the largest volume share of over 42.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (53.5% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 272.9 Million
- Estimated market size in 2026: USD 303.7 Million
- Projected market size by 2033: USD 642.0 Million
- CAGR (2026-2033): 11.3%
Prism AI by Grand View Research Free to tryAsk a question about the syngas marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Stringent environmental regulations, such as the Clean Air Act and carbon emission reduction targets, are driving demand for cleaner alternatives in various industries. Syngas can help industries comply with these regulations by offering a lower-emission fuel alternative.
Continuous advancements in gasification technologies are leading to more efficient syngas production processes, reducing costs and improving the economic viability of syngas projects. Potential for utilizing waste-to-energy conversion technologies for syngas production offers a cost-effective solution for waste management while generating valuable energy.
Fluctuations in natural gas prices, which are a primary feedstock for syngas production, can impact the economic competitiveness of syngas compared to other energy sources. However, technological advancements and the exploration of alternative feedstock can help mitigate this dependence.
Analyst Perspective
The industry is supported by heavy investment in capacity expansion, low-carbon production technologies, and the integration of industrial complexes. In addition, manufacturers are strengthening their market positions through large-scale projects, while major players are introducing innovative production pathways based on renewable feedstocks and biomass. However, the rising emphasis on hydrogen, sustainable fuels, and carbon will influence competition and make investments more profitable in the long run. Furthermore, rapid industrialization and chemical production in the Asia-Pacific region have driven growth in development projects, whereas Europe has begun investing in renewable syngas projects to reduce carbon emissions from fossil fuels.
Production Technology Insights
The steam reforming segment held the largest market share of around 48.0% in 2025 and is expected to witness robust growth over the forecast period. Steam reforming is a widely used technology for producing syngas from various feedstocks, including natural gas, biogas, and even coal. The process involves heating feedstock in a controlled environment with steam, typically at high temperatures ranging from 700°C to 1000°C. This reaction breaks down complex molecules in feedstock into simpler components like hydrogen, carbon monoxide, and carbon dioxide, forming a syngas mixture. For instance, in January 2024, Topsoe A/S published the first industrial-scale operational results of its eREACT electrified steam methane reforming (eSMR) technology, demonstrating the production of sustainable synthesis gas (syngas) from biogas while significantly reducing carbon emissions compared with conventional steam reforming. The milestone highlights continued innovation in steam reforming technology, reinforcing its importance as a commercially viable process for efficient syngas and hydrogen production while supporting industrial decarbonization.
The biomass gasification segment is anticipated to grow at the fastest rate over the forecast period. This process involves thermochemical conversion of organic matter like wood chips, agricultural residues, and even municipal waste into a gaseous mixture primarily composed of hydrogen, carbon monoxide, and methane.
Feedstock Insights
The natural gas segment dominated the market and accounted for the largest market share of over 46.5% in 2025. Natural gas serves as a crucial and widely utilized feedstock in the syngas market, playing a pivotal role in the production of synthesis gas. Methane, the primary component of natural gas, undergoes a process known as steam methane reforming (SMR) to generate syngas. Given the abundance and relatively low cost of natural gas, it has become a preferred feedstock for syngas production, offering a cost-effective and efficient means to meet growing demand for industrial gases and chemicals. For instance, in November 2024, Air Liquide announced a long-term agreement with Total Energies to build, own, and operate a new hydrogen production unit at the La Mède bio refinery in France. The project strengthens Air Liquide's hydrogen production network and demonstrates the continued investment in large-scale syngas and hydrogen infrastructure, where natural gas-based steam methane reforming remains the industry's established and most widely deployed production route. The development reinforces the strategic importance of natural gas as a reliable feedstock for industrial syngas and hydrogen production.
The biomass segment is projected to progress at the fastest CAGR over the forecast period. Biomass, including agricultural residues, forestry waste, and dedicated energy crops, presents a promising alternative to traditional fossil fuels for syngas production.
Gasifier Type Insights
The fluidized bed segment dominated the market in 2025 and is likely to consolidate its position over the forecast period. Fluidized bed gasification is used for converting various feedstocks, including biomass, coal, and waste materials, into syngas. Fluidized beds enable efficient conversion of feedstock into syngas with good control over product gas composition. They can handle a wide range of feedstock qualities and sizes, making them adaptable to different project requirements. It operates at lower temperatures, resulting in reduced emissions of pollutants like nitrogen oxides and sulfur oxides. This characteristic aligns well with the growing demand for cleaner energy solutions in the syngas market. For instance, in February 2024, Coal India Limited and Bharat Heavy Electricals Limited signed a joint venture agreement to establish an ammonium nitrate plant in Odisha using BHEL's indigenously developed pressurized fluidized bed gasification (PFBG) technology. The project will convert coal into synthesis gas (syngas) for downstream chemical production, demonstrating the growing commercial adoption of fluidized bed gasification owing to its feedstock flexibility, efficient syngas production, and support for cleaner industrial processes.
The fixed-bed gasifier type segment is anticipated to grow at the fastest rate over the forecast period. Fixed-bed gasifiers operate by passing feedstock, like biomass or coal, through a fixed bed of inert material while introducing an oxidizing agent (air, oxygen, or steam). The process generates a combustible gas mixture called syngas, containing hydrogen, carbon monoxide, and other gases.
Application Insights
The chemicals segment dominated the global market in 2025. Syngas serves as a valuable feedstock for producing various essential chemicals, including methanol, which is a versatile chemical used in the production of plastics, formaldehyde, and various other chemicals. Ammonia is a crucial ingredient in fertilizers, explosives, and various industrial processes, and acetic acid is used in the production of solvents, paints, and pharmaceuticals.
Leading chemical producers like BASF, Dow, and DuPont are actively exploring syngas as a feedstock for manufacturing various chemicals. Their extensive experience in chemical production, established market presence, and research & development capabilities position them well to capitalize on growth opportunities in this segment.
Several innovative startups are developing and deploying novel syngas-to-chemicals technologies. These companies, such as LanzaTech, Syngaschem, and Carbon Engineering, are focusing on developing efficient and cost-effective processes for converting syngas into valuable chemicals like methanol, ethanol, and olefins. Their agility and focus on technological advancements can potentially disrupt the traditional landscape in this segment. These factors are expected to spur syngas market potential in the future.
Regional Insights
The North America syngas market is experiencing steady growth, driven by several key factors such as a clean energy push wherein environmental concerns and stricter regulations on energy sources are propelling demand for cleaner alternatives. Syngas, with its ability to be derived from biomass and generate fewer emissions compared to traditional fossil fuels, is finding favor in various industries. Also, North America's rising electricity needs are creating a market for syngas in power generation. Syngas-fueled power plants offer an efficient and cleaner alternative to traditional options, contributing to the overall growth of the market.
U.S. Syngas Market Trends
The syngas market in the U.S. is expected to grow at a significant CAGR from 2026 to 2033. Key factors contributing to the growth of the market are increasing adoption of syngas in combined heat and power (CHP) plants for efficient energy generation and continuous advancements in gasification technologies, leading to more efficient syngas production processes.
Europe Syngas Market Trends
The syngas market in Europe is expected to witness moderate growth over the forecast period as the region is actively exploring alternative feedstock like biomass and waste for syngas production, reducing dependence on traditional fossil fuels like coal and natural gas.
The Germany syngas market held the largest share in the European market due to various factors such as a robust chemical industry, supportive clean energy initiatives through various funding programs and incentive schemes.
The syngas market in France is anticipated to grow at a significant CAGR over the forecast period. This growth can be attributed to stringent environmental regulations in France, like the Energy Transition for Green Growth Law, which incentivize industries to adopt cleaner technologies. Syngas, with its lower carbon footprint compared to traditional fossil fuels, can help industries comply with these regulations and contribute to France's ambitious climate goals.
The Italy syngas market is growing at a significant rate due to increasing focus on circular economy principles in Italy, which may boost the adoption of syngas in waste valorization and recycling processes. Syngas production from organic waste and biomass aligns with circular economy goals by converting waste materials into valuable energy resources.
Asia Pacific Syngas Market Trends
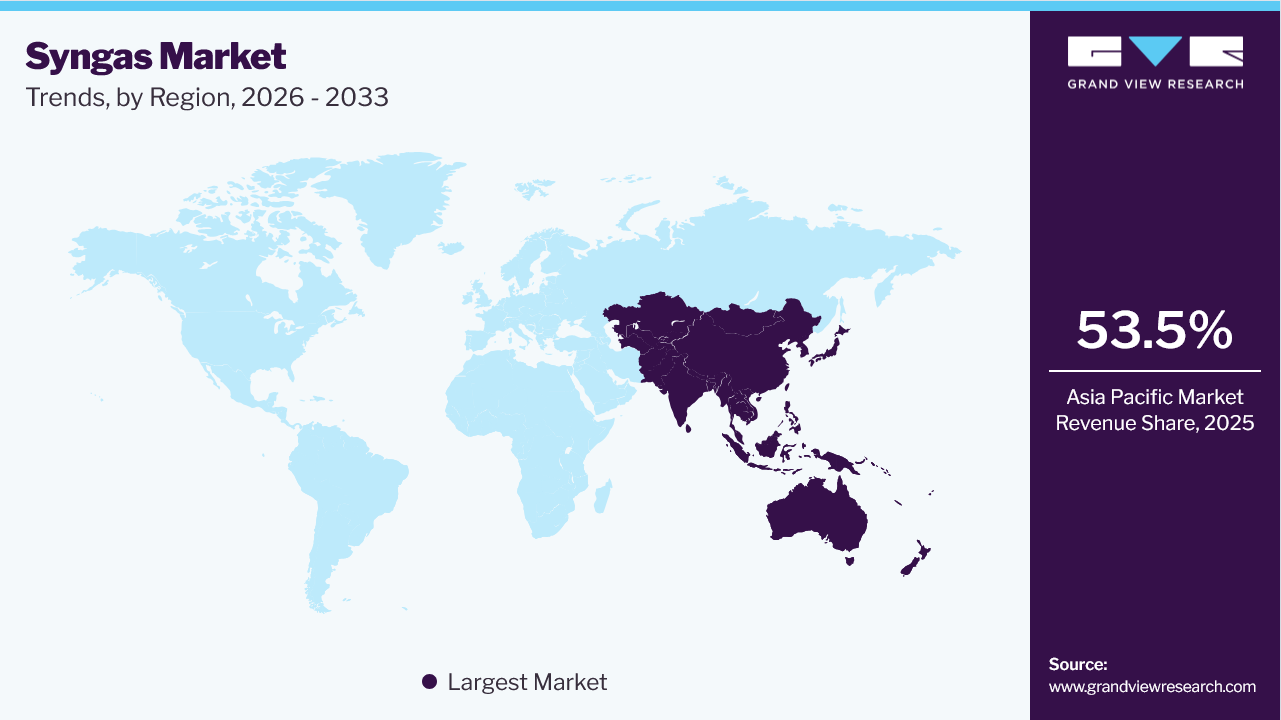
The syngas market in Asia Pacific dominated and accounted for the largest share of over 53.5% in 2025. The region is likely to dominate the industry over the forecast period as well. Governments in the region, such as China, India, Japan, and South Korea, are at the forefront of this growth, driven by supportive policies, increasing disposable incomes, and growing environmental concerns. These countries are actively promoting clean energy solutions and waste-to-energy initiatives. Syngas, with its potential for cleaner burning and waste utilization, aligns well with these goals, attracting government support and investments. This boom is driven by factors like rising demand for chemicals and fuels, stringent emission regulations pushing for cleaner alternatives, and growing investments in gasification technologies.
 To learn more about this report, Download Free Sample Report
The China syngas market held a significant share in the Asia Pacific region in 2025. This surge is driven by a potent mix: rising power generation needs, booming chemical and fertilizer industries, and increasing demand for liquid and gaseous fuels. Major players are expanding their production capacity, while companies like Air Products are securing long-term contracts to fuel major projects.
The syngas market in India is anticipated to register a significant CAGR over the forecast period. This surge is driven by factors like rising demand for chemicals like olefins and fertilizers, growing awareness of cleaner fuel alternatives, and government initiatives promoting gasification technologies.
Middle East & Africa Syngas Market Trends
The syngas market in the Middle East & Africa is expected to grow at a lucrative CAGR over the forecast period. This growth is fueled by two key trends: rising demand for electricity and a booming chemical industry. Governments across the region are investing heavily in power generation infrastructure, often utilizing syngas-fired plants due to their flexibility and ability to integrate renewable energy sources. Simultaneously, the chemical industry sees syngas as a valuable feedstock for producing methanol, ammonia, and other essential chemicals, further driving market expansion.
The Saudi Arabia syngas market holds a dominant share in the Middle East & Africa region in 2025. Growing demand for cleaner power generation via Integrated Gasification Combined Cycle (IGCC) plants and synthetic natural gas (SNG) production fuels this market. Government initiatives towards economic diversification and attracting investments in petrochemicals create further opportunities.
The syngas market in the UAE is expected to grow at a significant CAGR over the forecast period. This growth is further bolstered by rising demand for chemicals, alternative fuels, and clean electricity, creating a strong market for syngas & its derivatives across sectors like agriculture, transportation, and industrial manufacturing.
Key Syngas Company Insights
Some major companies in the syngas market include A.H.T Syngas Technology NV; Air Liquide; Air Products and Chemicals Inc.; Airpower Technologies Limited; John Wood Group PLC; KBR Inc.; Linde Plc; Sasol; Shell Plc; Topsoe AS; Maire Tecnimont Spa; Synthesis Energy Systems, Inc.; Chiyoda Corporation; Dow Inc.; and Methanex Corporation.
Key Syngas Companies
The following are the leading companies in the syngas market. These companies collectively hold the largest market share and dictate industry trends.
-
A.H.T Syngas Technology NV
-
Air Liquide
-
Air Products and Chemicals Inc.
-
Airpower Technologies Limited
-
John Wood Group PLC
-
KBR Inc.
-
Linde Plc
-
Sasol
-
Shell Plc
-
Topsoe AS
-
Maire Tecnimont Spa
-
Synthesis Energy Systems Inc.
-
Chiyoda Corporation
-
Dow Inc.
-
Methanex Corporation
Recent Developments
- In February 2025, MAIRE S.p.A., together with Eni and Iren, initiated the permitting process for an innovative circular methanol and hydrogen plant in Italy based on NEXTCHEM's proprietary NX Circular technology. The facility will convert approximately 200,000 tonnes of non-recyclable waste annually into synthesis gas (syngas), which will subsequently be used to produce low-carbon methanol and hydrogen, strengthening MAIRE's position in sustainable syngas technologies.
- In January 2024, the Government of India approved an approximately USD 893 million incentive scheme to promote coal and lignite gasification projects across the public and private sectors. The initiative supports the establishment of new facilities for syngas production and downstream chemicals, accelerating domestic syngas capacity expansion while strengthening energy security and reducing dependence on imported methanol, ammonia, and natural gas.
Syngas Market Report Scope
Report Attribute
Details
Market size in 2025
USD 272.9 million
Estimated market size in 2026
USD 303.7 million
Projected market size by 2033
USD 642.0 million
Growth rate
CAGR of 11.3% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Volume in Nm3/hr; revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Volume & revenue forecast, competitive landscape, growth factors and trends
Segments covered
Production technology, feedstock, gasifier type, application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
A.H.T Syngas Technology NV; Air Liquide; Air Products and Chemicals Inc.; Airpower Technologies Limited; John Wood Group PLC; KBR Inc.; Linde Plc; Sasol; Shell Plc; Topsoe AS; Maire Tecnimont Spa; Synthesis Energy Systems, Inc.; Chiyoda Corporation; Dow Inc.; Methanex Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Syngas Market Report Segmentation
This report forecasts volume & revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global syngas market report based on production technology, feedstock, gasifier type, application, and region:
-
Production Technology Outlook (Volume, Nm3/hr.; Revenue, USD Million, 2021 - 2033)
-
Steam Reforming
-
Partial Oxidation
-
Autothermal Reforming
-
Biomass Gasification
-
Others (Plasma Gasification, heat exchange reforming, and underground coal gasification)
-
-
Feedstock Outlook (Volume, Nm3/hr.; Revenue, USD Million, 2021 - 2033)
-
Petroleum Byproducts
-
Coal
-
Natural Gas
-
Biomass/ Waste
-
Others (Petcoke, Plastic Wase, and Medical Waste)
-
-
Gasifier Type Outlook (Volume, Nm3/hr.; Revenue, USD Million, 2021 - 2033)
-
Fixed Bed
-
Entrained Flow
-
Fluidized Bed
-
Others (Plasma Arc and Black Liquor) Others (Petcoke, Plastic Waste, and Medical Waste)
-
-
Application Outlook (Volume, Nm3/hr.; Revenue, USD Million, 2021 - 2033)
-
Chemicals
-
Methanol
-
Ammonia
-
FT Synthesis Products
-
-
Fuels
-
Liquid
-
Gaseous
-
-
Power Generation
-
-
Regional Outlook (Volume, Nm3/hr.; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Frequently Asked Questions About This Report
The global syngas market size was valued at USD 272.9 million in 2025 and is estimated at USD 303.7 million for 2026.
The global syngas market is expected to grow at a CAGR of 11.3% from 2026 to 2033, reaching USD 642.0 million.
Asia Pacific dominated with over 53.5% revenue share in 2025.
Key players in the market include A.H.T Syngas Technology NV; Air Liquide; Air Products and Chemicals Inc.; Airpower Technologies Limited; John Wood Group PLC; KBR Inc.; Linde Plc; Sasol; Shell Plc; Topsoe AS; Maire Tecnimont Spa; Synthesis Energy Systems, Inc.; Chiyoda Corporation; Dow Inc.; Methanex Corporation, and others.
The steam reforming segment accounted for the largest revenue share of approximately 48.0% in 2025.
About the Author(s)
Renewable Energy Research Team
Energy & Power · Renewable EnergyThis report was authored by the renewable energy research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable energy segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


