
- Home
- »
- Clothing, Footwear & Accessories
- »
-
Toys And Games Market Size & Share, Industry Report, 2033GVR Report cover

Toys And Games Market (2026 - 2033) Size, Share & Trends Analysis By Product (Electronic Games, Dolls, Preschool Toys), By End User (Up To 8 Years, 9-15 Years), By Distribution Channel (Offline, Online), By Region, Segment Forecasts
Market Size, 2025
$357.6BMarket Estimate, 2026
$374.0BMarket Forecast, 2033
$489.3BCAGR, 2026–2033
3.9%Toys And Games Market Summary
The global toys and games market size was valued at USD 357.6 billion in 2025 and is projected to grow from USD 374.0 billion in 2026 to USD 489.3 billion by 2033, at a CAGR of 3.9% from 2026 to 2033. Asia Pacific held the largest share, at 40.0%, of the global market in 2025. The industry continues to expand, supported by growth in household spending on discretionary products, increasing emphasis on early childhood development, and rising demand for structured indoor entertainment.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The electronic games market accounted for a share of 52.5% of the global revenue in 2025.
- By end use: Consumers aged 15 years & above accounted for a share of 48.6% of the global revenue in 2025
- By distribution channel: Sales of toys and games through offline channels accounted for a share of around 54.1% of the global revenue in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (40.0% revenue share, 2025)
- China held the largest revenue share of the global toys and games industry in 2025.
Market Size & Forecast
- Market size in 2025: USD 357.6 Billion
- Estimated market size in 2026: USD 374.0 Billion
- Projected market size by 2033: USD 489.3 Billion
- CAGR (2026-2033): 3.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Urbanization, smaller family sizes, and changing lifestyles are encouraging parents to invest in toys that can be used within home environments and across multiple age groups. At the same time, broader access to products through organized retail and e-commerce platforms has improved availability and visibility, supporting sustained demand across both developed and emerging markets. These dynamics are creating growth opportunities across multiple segments, including interactive early-learning formats such as the crawling crab toy market and environmentally responsible product categories within the sustainable toys market.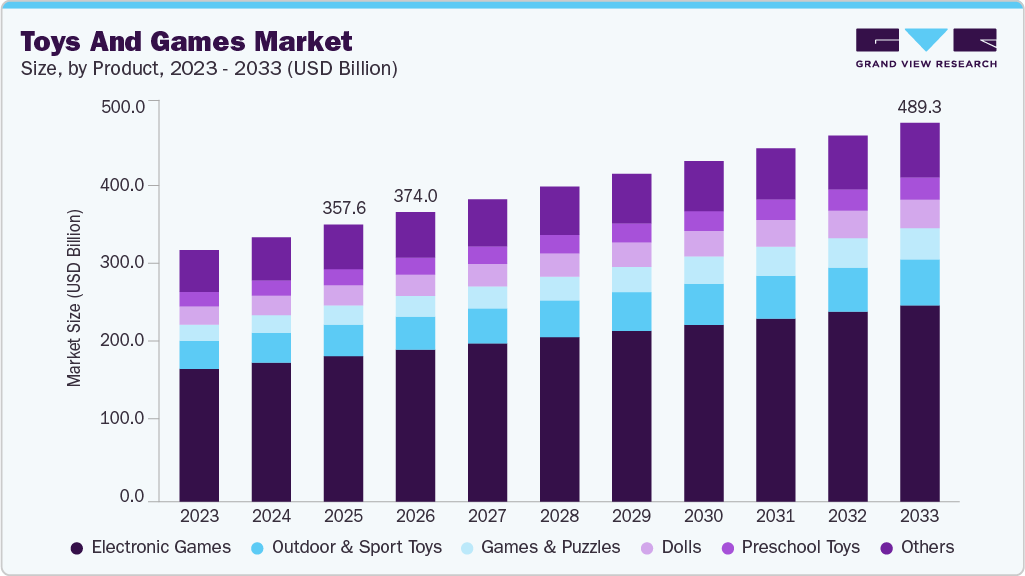 To learn more about this report, Download Free Sample Report
According to a trend-spotting article published in the Toy Association's March 2025 outlook, the industry continues to monitor evolving play preferences using both consumer behavior and sales performance data. The report shows that 58% of U.S. parents favor toys that help children build specific skill sets, 60% seek toys that develop STEAM-related skills, and 56% look for products that encourage outdoor or active play. In addition, 63% of Millennial parents consider how toys contribute to mental, emotional, and social health when making purchase decisions. Close to three-quarters of parents (73%) reported purchasing toys for themselves, and 61% did so to connect with their children, underscoring a resurgence of interest in play formats that bridge generations and promote shared experiences. The report highlights how these demand shifts are influencing product priorities, from skill-building toys to collectible and entertainment-linked categories.
Further insight is provided by a survey-based performance update released by Circana in partnership with the Toy Association in August 2025, covering the first half of the year. According to the survey, U.S. toy dollar sales increased by 6% year over year, while unit volumes rose by 3%, with average selling price (ASP) increasing by 3%. Seven of the eleven toy supercategories recorded positive dollar growth, led by games and puzzles (+39%), explorative and discovery toys (+19%), youth electronics (+9%), action figures (+8%), building sets (+7%), and arts and crafts (+4%). Licensed toys accounted for approximately 37% of total U.S. toy sales, with licensed categories outperforming non-licensed segments during the period, underscoring the continued strength of established brands and familiar play patterns.
In response to these market dynamics, manufacturers are adjusting their portfolios to strengthen participation in high-engagement toy categories. In a 2024 press release, Mattel announced the launch of Mattel Brick Shop, marking its expansion into the construction and building-sets segment. The announcement outlines Mattel’s intent to develop modular play systems that emphasize creativity, customization, and structured building, while extending the company’s presence beyond traditional toy formats. This strategic direction aligns with rising demand for repeat-play products, environmentally responsible materials, and developmental play patterns, reinforcing long-term growth potential across segments such as the sustainable toys market and sensory-motor categories, including the crawling crab toys market.
Brand Market Share Insights
The global market is shaped by the presence of established multinational manufacturers alongside an expanding pool of regional players and digitally native brands, all competing to meet evolving expectations around engagement, learning, and play quality. Companies are increasingly designing products that blend physical interaction with creativity, problem-solving, and cognitive development, reinforcing toys and games as part of everyday routines rather than purely seasonal purchases. This evolution is evident across emerging segments such as the crawling crab toy market, which supports early motor skill development through interactive movement, and the sustainable toys market, where demand is rising for products made from recycled, biodegradable, or responsibly sourced materials. Collectively, these trends are broadening the role of toys and games beyond entertainment, positioning them as continuous engagement tools aligned with developmental and environmental priorities.
 To learn more about this report, Download Free Sample Report
Consumer Insights
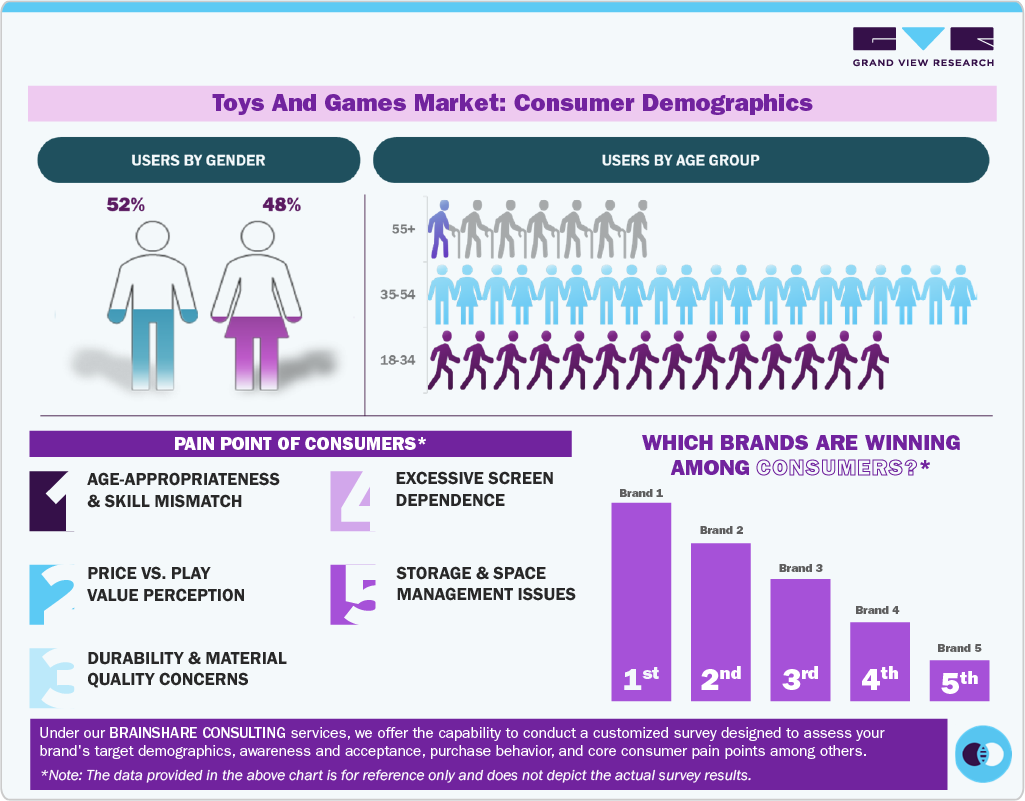
The toys and games industry is increasingly influenced by adult participation, expanding demand beyond traditional child-focused consumption. A growing share of adults now purchase toys and collectibles for personal use, reflecting their role as lifestyle, hobby, and fandom-driven products. Recent findings from the CivicScience consumer survey, published in August 2025, show that 35% of U.S. adults reported buying a toy or collectible for themselves or another adult at least once in the past year, up from 28% in 2022, indicating a clear increase in adult-driven purchases over time. This behavior is most pronounced among Generation Z and Millennials, who report significantly higher purchasing frequency than consumers aged 45 and above, reflecting the growing role of toys and collectibles as lifestyle and hobby products.
 To learn more about this report, Download Free Sample Report
Brand attachment remains a defining characteristic of adult toy buyers. The survey highlights that 90% of adults who recently purchased toys or collectibles describe themselves as at least somewhat loyal to the brands they buy, demonstrating strong repeat-purchase behavior. In addition, 80% of adult buyers continue to purchase from toy brands they were familiar with during childhood, underscoring how early brand exposure translates into long-term consumer affinity and sustained demand across life stages.
Spending patterns further underline the role of toys and collectibles within broader discretionary consumption. Adults who purchase toys are more likely to report higher overall consumer spending than non-buyers, particularly in leisure-oriented categories such as dining out, streaming subscriptions, and entertainment. Collectively, these behaviors suggest that toys and games are increasingly embedded within lifestyle spending rather than confined to seasonal gifting or child-centric occasions. As adult demand continues to rise, it is reshaping how toys and games are positioned, marketed, and distributed, strengthening the category’s relevance across wider age demographics.
Product Insights
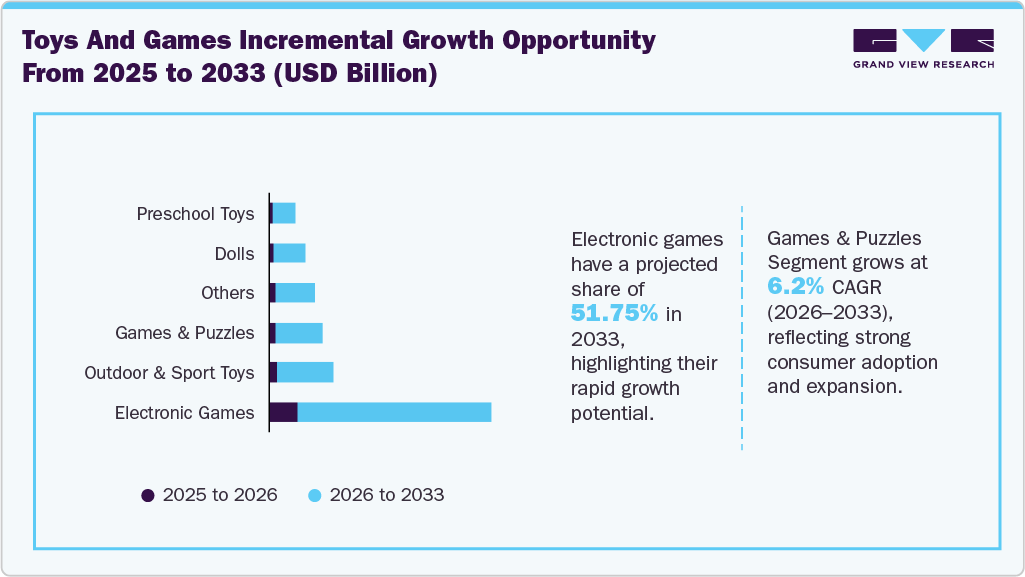
The electronic games market accounted for a share of 52.5% of the global revenue in 2025. This segment remains widely adopted among children, teenagers, and adult consumers due to its strong engagement, recurring content updates, and ability to deliver immersive, interactive entertainment. Console, PC, and mobile-based games continue to benefit from advances in graphics, online multiplayer ecosystems, and live-service models that encourage long-term usage and in-game spending. Leading electronic gaming companies are expanding their portfolios through new franchise releases, subscription-based access models, and cross-platform compatibility, while also integrating features such as cloud gaming, social connectivity, and customizable gameplay experiences.
 To learn more about this report, Download Free Sample Report
The games & puzzles market is projected to grow at a CAGR of 6.2% from 2026 to 2033, driven by increasing demand for interactive, skill-based entertainment that can be used in home, educational, and social settings. The segment benefits from its broad age appeal, with products designed for early learning, cognitive training, and adult leisure. Growing adoption of board games, strategy games, and advanced jigsaw puzzles is being supported by their role in enhancing concentration, memory, and analytical thinking.
End User Insights
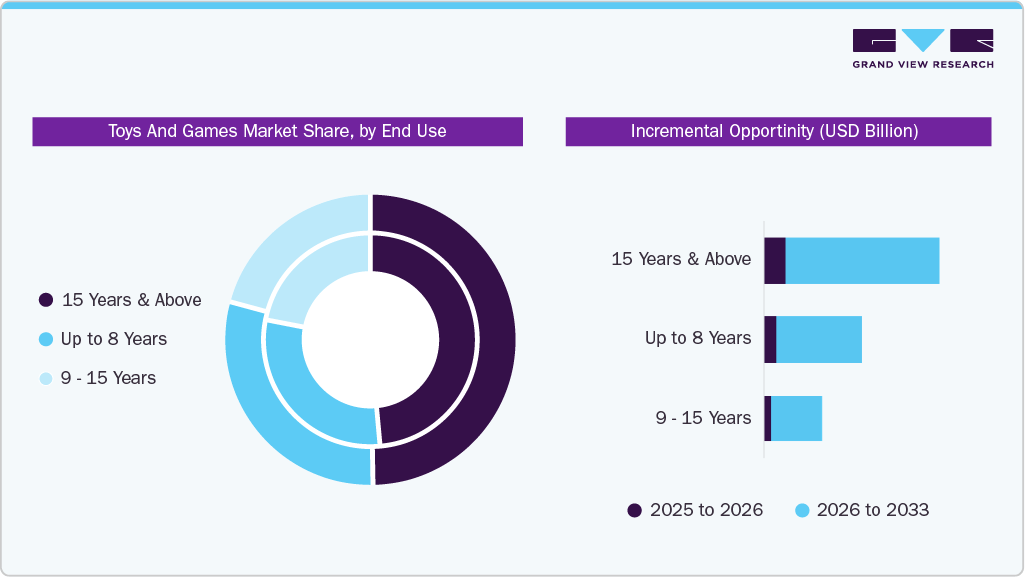
Consumers aged 15 years & above accounted for a share of 48.6% of the global revenue in 2025, underscoring the expanding role of teenagers and adults in category consumption. Purchases in this age group increasingly reflect personal entertainment preferences, social interaction, and hobby-driven interests rather than child-only use. Board games, puzzles, electronic games, and collectibles are commonly selected for group activities, casual gatherings, and at-home leisure. Broad availability across mass-market, mid-range, and premium offerings enables this segment to access products suited to varying budgets and usage occasions, supporting sustained engagement and repeat purchasing in the market.
 To learn more about this report, Download Free Sample Report
Consumers aged up to 8 years are projected to grow at a CAGR of 3.9% from 2026 to 2033, reflecting stable demand for toys and games aligned with early developmental stages. Purchases in this age group are largely parent-driven and focused on products that support foundational learning milestones such as counting, language development, spatial awareness, and fine motor coordination. Toys that encourage tactile interaction, such as stacking sets, beginner puzzles, educational games, and role-play kits, remain central to consumption, as they support guided play in home and early-education environments. Safety compliance, age labeling, and ease of supervision strongly influence buying decisions, while frequent gifting occasions and regular product replacement as children progress through developmental phases sustain consistent demand within this segment.
Distribution Channel Insights
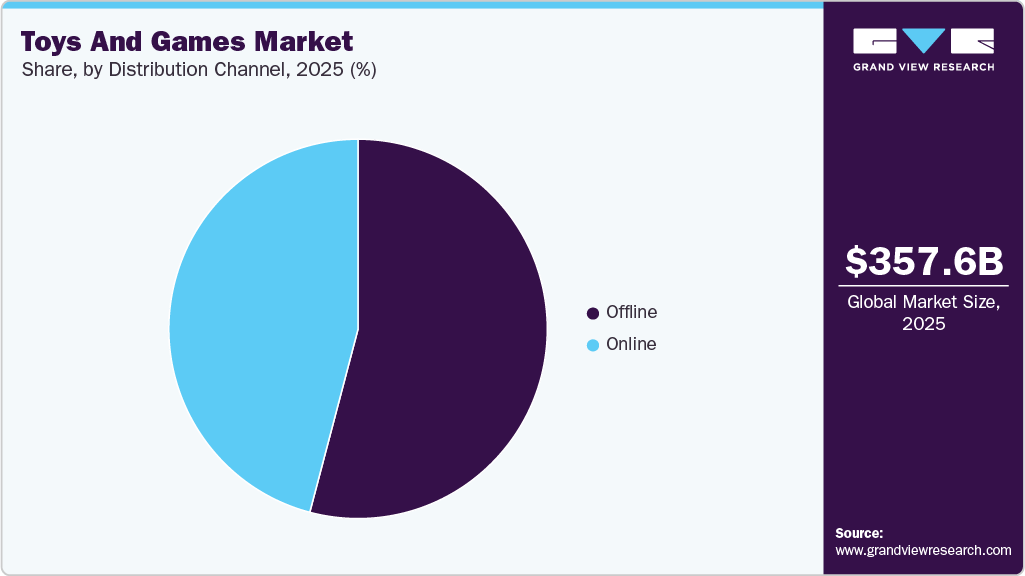
Sales of toys and games through offline channels accounted for a share of around 54.1% of the global revenue in 2025. Brick-and-mortar stores remain a preferred purchase point for parents and gift buyers who value in-person product evaluation, age-appropriate guidance, and immediate product availability. Specialty toy stores, department stores, and mass retailers support sales by curating category-specific assortments, hosting in-store promotions, and offering exclusive products or bundled sets that are not always available online. Physical retail also plays a critical role during peak gifting periods, as in-store visibility, impulse buying, and trusted retail environments help reinforce consumer confidence and sustain the relevance of offline channels.
 To learn more about this report, Download Free Sample Report
Sales of toys and games through online channels are projected to grow at a CAGR of 4.5% from 2026 to 2033. Online platforms are increasingly used to access a wider selection of products across educational toys, games, puzzles, and electronic play formats, often supported by competitive pricing and promotional offers. Digital channels also enable consumers to evaluate product features, age suitability, safety information, and user feedback before purchase, reducing uncertainty in buying decisions. The growth of brand-owned websites and large marketplaces, combined with improved logistics, doorstep delivery, and flexible return policies, is strengthening consumer confidence and accelerating the shift toward online purchasing.
Regional Insights
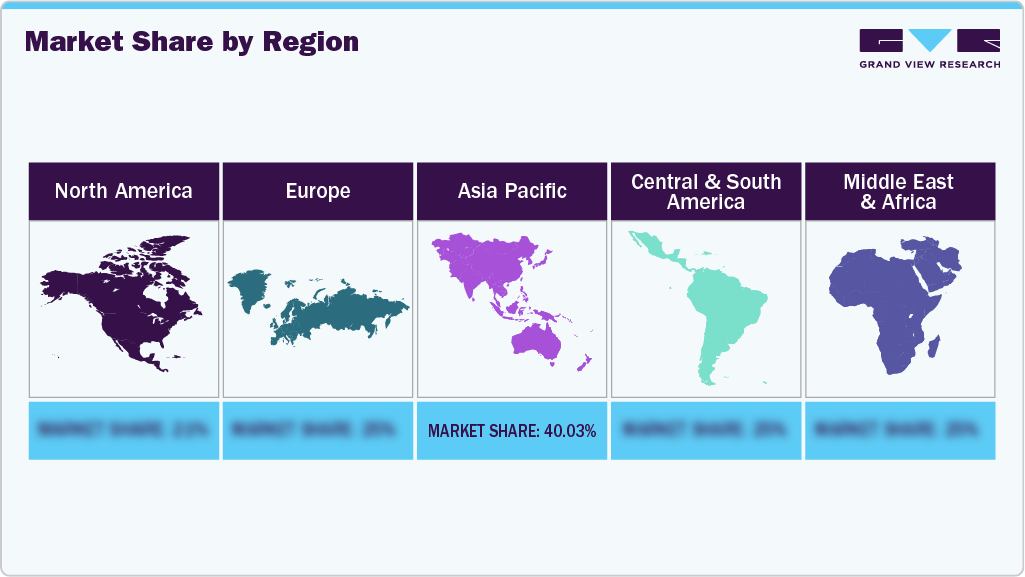
The toys and games market in North America accounted for 29.8% of the global revenue in 2025, supported by high household spending power, a strong gifting culture, and widespread acceptance of toys and games as year-round entertainment products. Consumers across the U.S. and Canada actively purchase toys and games not only for children but also for teenagers and adults, reflecting the region’s strong engagement with board games, puzzles, collectibles, and electronic games. Demand is reinforced by well-developed retail infrastructure, high penetration of organized toy stores and mass retailers, and advanced e-commerce ecosystems that support frequent product launches and rapid adoption of new play formats.
 To learn more about this report, Download Free Sample Report
U.S. Toys and Games Market Trends
The toys and games market in the U.S. accounted for 74.2% of North America's market in 2025. The U.S. benefits from a highly developed toy retail ecosystem, encompassing mass merchandisers, specialty toy stores, department stores, brand-owned outlets, and a strong direct-to-consumer and marketplace-led online presence. High household spending, a strong gifting culture, and frequent product refresh cycles linked to entertainment franchises, holidays, and seasonal demand continue to support sales momentum. In addition, the widespread adoption of licensed toys, collectibles, board games, and electronic games among children, teenagers, and adults drives repeat purchases and sustained consumer engagement.
Canada's toys and games market is projected to grow at a CAGR of 4.1% from 2026 to 2033. Canadian households demonstrate strong engagement with toys and games that support indoor entertainment, cognitive development, and social interaction, particularly during extended indoor seasons. Board games, puzzles, and educational toys remain widely purchased for family use, while electronic games continue to attract teenagers and young adults.
Europe Toys and Games Market Trends
The toys and games market in Europe is projected to grow at a CAGR of 4.8% from 2026 to 2033, supported by strong consumer interest in licensed entertainment products, STEM-focused learning toys, and family-oriented board and strategy games. Europe’s long-standing culture of tabletop gaming and puzzle-solving continues to sustain demand across households, hobby communities, and educational settings. The region hosts several major toy manufacturers, including LEGO, Ravensburger, Mattel, and Hasbro, all of which actively introduce localized products and licensed offerings tailored to European markets. In addition, heightened focus on sustainability, product safety, and educational value is influencing purchasing decisions and encouraging manufacturers to develop eco-friendly materials and learning-led play formats.
The UK toys and games market accounted for 16.7% of the European market in 2025. Demand in the UK is supported by a well-established culture of board games, puzzles, collectibles, and licensed entertainment products, alongside steady purchasing for educational and family-oriented play. Households increasingly favor toys and games that offer long-term usability, replay value, and quality construction, driving sustained demand across multiple age groups.
The toys and games market in France is projected to grow at a CAGR of 5.7% from 2026 to 2033. French consumers show consistent demand for board games, puzzles, construction toys, and learning-based products that encourage cognitive development and shared play across age groups. Demand is further reinforced by seasonal gifting traditions, widespread availability through specialty toy stores and large retail chains, and growing penetration of online platforms that expand access to domestic and international toy brands.
Asia Pacific Toys and Games Market Trends
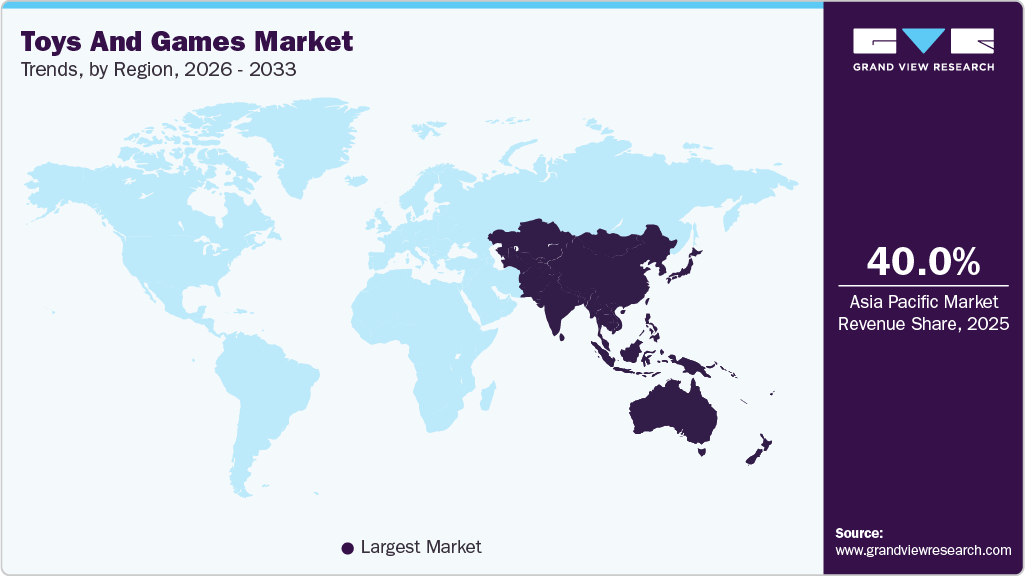
The toys and games market in the Asia Pacific accounted for a share of 40.0% of the global revenue in 2025, driven primarily by the region’s large child population, rapid urbanization, and rising disposable incomes across key markets such as China, India, Japan, and Southeast Asia. Demand in the region is strongly supported by high spending on educational toys, construction sets, puzzles, and electronic games, reflecting parental focus on early learning and academic skill development. Local manufacturing depth in China and Southeast Asia enables frequent product launches at varied price points, while Japan and South Korea continue to influence demand for character-based toys, collectibles, and gaming formats linked to anime, manga, and digital entertainment ecosystems.
 To learn more about this report, Download Free Sample Report
China toys and games market accounted for a share of 26.60% of the regional revenue in 2025. Demand is strongly supported by China’s large child population, a rising number of middle-income households, and sustained spending on educational and skill-based play. Parents place high emphasis on toys that support early learning, STEM development, and cognitive skills, driving strong uptake of construction toys, puzzles, learning kits, and interactive games. At the same time, teenagers and young adults contribute meaningfully to demand through electronic games, collectibles, and licensed merchandise linked to gaming, animation, and popular IP.
The toys and games market in India is projected to grow at a CAGR of 4.4% from 2026 to 2033. Demand is particularly strong for educational toys, puzzles, construction sets, and STEM-based games, as parents actively invest in products that support early cognitive development and academic readiness. The market also benefits from India’s strong gifting culture linked to birthdays, festivals, and school milestones, which sustains year-round purchases beyond seasonal peaks. Rapid expansion of e-commerce platforms and quick-commerce delivery in Tier I and Tier II cities has significantly improved access to branded toys, while domestic manufacturers and startups are introducing affordable, locally adapted products aligned with Indian curricula and cultural themes.
Central and South America Toys and Games Market Trends
The toys and games market in Central and South America is projected to grow at a CAGR of 5.3% from 2026 to 2033. supported by expanding urban populations, rising middle-income households, and improving retail penetration across key markets such as Brazil, Mexico, Chile, and Colombia. Demand is being reinforced by growing access to organized retail formats, including shopping malls, specialty toy stores, and multi-brand outlets, which are improving visibility of both international and regional toy brands. At the same time, increasing smartphone usage and the expansion of e-commerce platforms are enabling consumers in semi-urban and secondary cities to access a wider range of toys, games, puzzles, and electronic play products.
Middle East & Africa Toys and Games Market Trends
The toys and games market in the Middle East & Africa is projected to grow at a CAGR of 3.1% from 2026 to 2033, supported by gradual improvements in retail infrastructure, rising urban populations, and increasing household spending on leisure and educational products. Demand across the region is driven by strong family-oriented consumption patterns, with toys and games widely purchased for home-based entertainment, gifting occasions, and early learning. Educational toys, board games, puzzles, and basic electronic games continue to see steady uptake, particularly in urban centers where access to organized retail and e-commerce platforms is expanding.
Key Toys and Games Companies:
The following key companies have been profiled for this study on the toys and games market.
- Spin Master
- The LEGO Group
- SANRIO CO., LTD.
- Playmates Toys Limited
- JAKKS Pacific, Inc.
- Mattel
- Hasbro
- Schylling
- Bandai Namco Holdings Inc.
- Dream International Limited
Recent Developments
-
In February 2026, Spin Master partnered with Universal Products & Experiences to introduce Hellbreak, a new horror-themed trading card game planned for release in 2026. The game brings together well-known horror characters from Universal’s film portfolio in a collectible, competitive card format centered on strategic battles. Developed in collaboration with game design studio Ghost Galaxy, Hellbreak is positioned to blend the popularity of trading card games with established horror franchises, with scope for future expansion beyond the initial launch.
-
In November 2025, Skidos partnered with Rovio to introduce a new range of Angry Birds-themed learning games designed for young children. The games use well-known characters to deliver interactive activities that support early learning, emotional awareness, and basic problem-solving skills. Integrated within the Skidos platform, the launch aims to make educational screen time more engaging by combining structured learning content with familiar entertainment-driven gameplay.
Toys and Games Market Report Scope
Report Attribute
Details
Market size in 2025
USD 357.6 billion
Estimated market size in 2026
USD 374.05 billion
Projected market size by 2033
USD 489.30 billion
Growth rate
CAGR of 3.9% from 2026 to 2033
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end user, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Spain; Italy; China; India; Japan; Australia & New Zealand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia
Key companies profiled
Spin Master; The LEGO Group; SANRIO CO., LTD.; Playmates Toys Limited; JAKKS Pacific, Inc.; Mattel; Hasbro; Schylling; Bandai Namco Holdings Inc.; Dream International Limited
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Toys and Games Market Report Segmentation
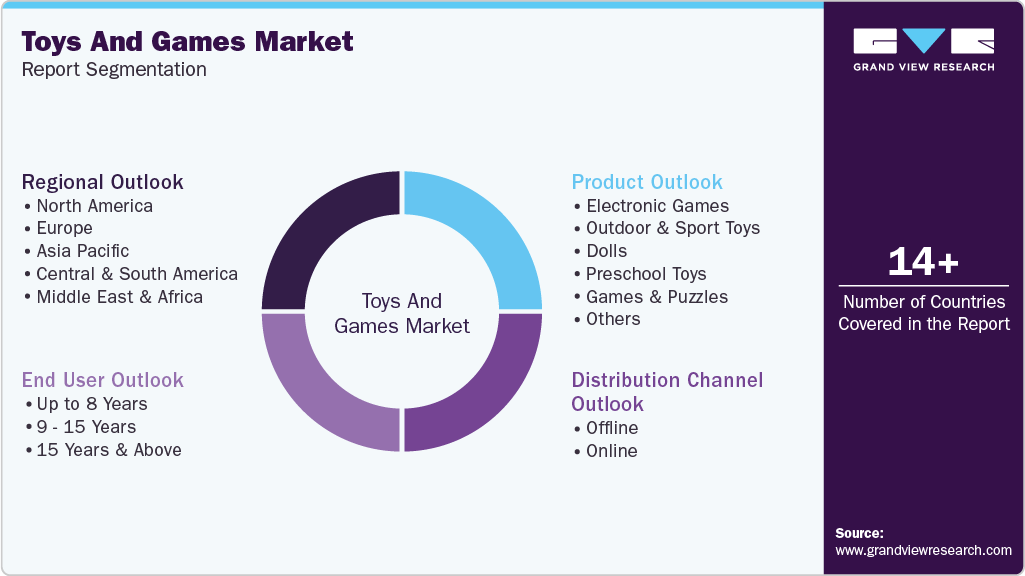
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest trends and opportunities in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global toys and games market based on product, end user, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Electronic Games
-
Outdoor & Sport Toys
-
Dolls
-
Preschool Toys
-
Games & Puzzles
-
Others
-
-
End User Outlook (Revenue, USD Billion, 2021 - 2033)
-
Up to 8 years
-
9 - 15 years
-
15 years & above
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Offline
-
Online
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia & New Zealand
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
-
Frequently Asked Questions About This Report
Some key players in the global toys and games market include Spin Master, The LEGO Group, SANRIO CO., LTD., Playmates Toys Limited, JAKKS Pacific, Inc., Mattel, Hasbro, Schylling, Bandai Namco Holdings Inc., and Dream International Limited.
Key factors that are driving the toys and games market growth include increasing launch of educational games, commercialization of favorite movies and cartoon characters, and an increasing number of video game tournaments and spending on video games.
Asia Pacific dominated with a 40.0% revenue share in 2025.
Electronic games held the largest revenue share in 2025.
Consumers aged 15 years & above accounted for 48.6% of revenue in 2025.
The global toys and games market size was estimated at USD 357.6 billion in 2025 and is expected to reach USD 374.0 billion in 2026.
The global toys and games market is expected to grow at a compound annual growth rate of 3.9% from 2026 to 2033 to reach USD 489.3 billion by 2033.
The offline distribution channel dominated the global toys and games market with a share of 54.1% in 2025. This is attributable to the increase in product visibility at physical stores and flexible working hours, where supermarkets or hypermarkets ensure maximum access.
About the Author(s)
Clothing, Footwear & Accessories Research Team
Consumer Goods · Clothing, Footwear & AccessoriesThis report was authored by the clothing, footwear & accessories research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clothing, footwear & accessories segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


