
- Home
- »
- Animal Health
- »
-
Veterinary Oxygen Therapy Market Size Report, 2026-2033GVR Report cover

Veterinary Oxygen Therapy Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Veterinary Oxygen Concentrator, Accessories), By Animal Type (Small Animal, Large Animal), By Application, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$1.4BMarket Estimate, 2026
$1.5BMarket Forecast, 2033
$2.5BCAGR, 2026–2033
7.7%Veterinary Oxygen Therapy Market Summary
The global veterinary oxygen therapy market size was valued at USD 1.4 billion in 2025 and is projected to grow from USD 1.5 billion in 2026 to USD 2.5 billion by 2033, at a CAGR of 7.7% from 2026 to 2033. North America dominated the veterinary oxygen therapy market with the largest revenue share of 38.1% in 2025. The market is experiencing growth driven by the rising prevalence of respiratory and critical conditions in animals, the expansion of veterinary infrastructure and specialized clinics, and advancements in veterinary essential care technologies.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By animal type: Small animals segment held the largest market share of 50.9% in 2025.
- By product: Veterinary oxygen concentrator segment held the largest market share of 84.9% in 2025.
- By end use: Veterinary hospitals segment held the largest market share of 47.8% in 2025.
- By application: ICU segment held the largest market share of 67.0% in 2025.
Regional Highlights
- Largest regional market: North America (38.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 1.4 Billion
- Estimated market size in 2026: USD 1.5 Billion
- Projected market size by 2033: USD 2.5 Billion
- CAGR (2026-2033): 7.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Increasing cases of pneumonia, asthma, cardiac failure, and trauma-induced hypoxemia in companion animals, along with better diagnostic tools, highlight the need for respiratory support. The rising prevalence of respiratory diseases in companion animals and increasing efforts to combat disease outbreaks are expected to rapidly fuel market growth. Veterinarians across the U.S. reported outbreaks of a canine respiratory illness in August 2023 that did not respond to standard treatments and appeared more severe and prolonged than typical canine infectious respiratory disease (CIRD). The exact cause remains unknown. In response, Cornell University’s College of Veterinary Medicine, through its Animal Health Diagnostic Center and Riney Canine Health Center, launched a rapid-response research project to investigate this disease and develop effective therapeutics to cure it.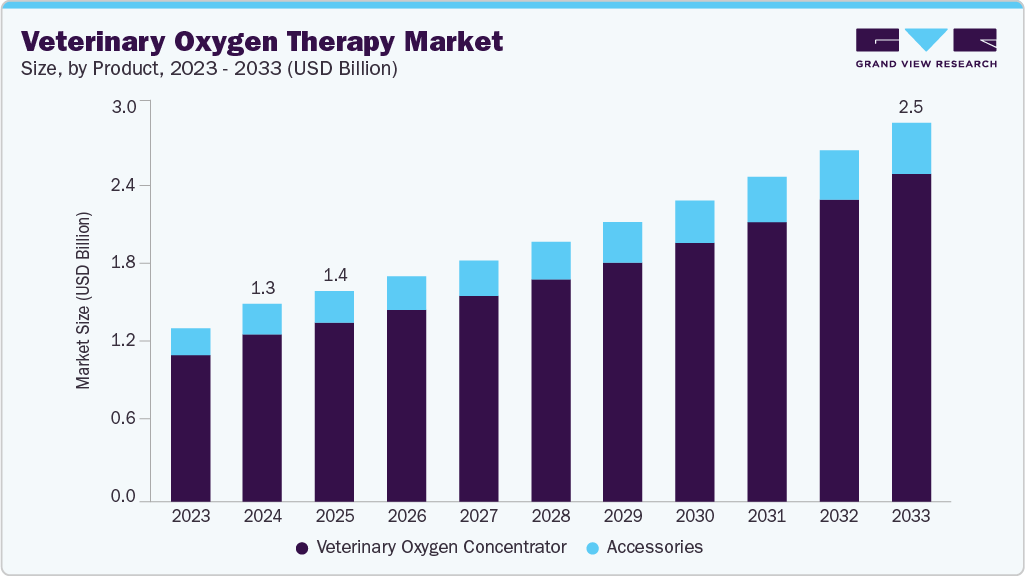 To learn more about this report, Download Free Sample Report
In addition, oxygen therapy plays a vital role in stabilizing patients during emergencies and in post-surgical care. Clinics and hospitals must invest in oxygen cages, masks, and concentrators. This demand increases sales of veterinary oxygen equipment, boosts adoption rates, and propels businesses to develop innovative, portable solutions. The market is growing due to the rapid advancements in oxygen delivery and monitoring technologies in contemporary veterinary care, such as integrated anesthetic equipment, portable oxygen concentrators, and flow regulators.
Manufacturers are constantly developing small, cost-effective, and easy-to-use products that allow even mobile units and small clinics to offer top-notch care. For instance, in January 2025, Super Air Smart ICU was introduced by Bionet America, Inc., with effective oxygenation, CO2 removal without soda-lime, air purification, and sophisticated climate control that improves the dependability of critical care. These innovations reduce operational complexity and enhance treatment reliability, encouraging veterinarians to adopt oxygen therapy widely. Improved outcomes boost pet owner confidence, leading to greater acceptance of oxygen-based interventions. The availability of diverse, advanced solutions broadens usage across companion, equine, and livestock practices, fueling market expansion.
Furthermore, with the help of government programs and private investments, there is an increasing number of veterinary hospitals, referral centers, and specialist clinics. The services in rural regions are growing with portable oxygen equipment, and the urban cities have emergency rooms and veterinary intensive care units. The expansion of this infrastructure increases the accessibility of oxygen therapy for both livestock farmers and pet owners. Adoption of modern oxygen equipment is fueled by competition among clinics to provide advanced services. In addition, the proliferation of specialist institutions normalizes oxygen therapy as a component of routine veterinary care.
 To learn more about this report, Download Free Sample Report
Market Dynamics
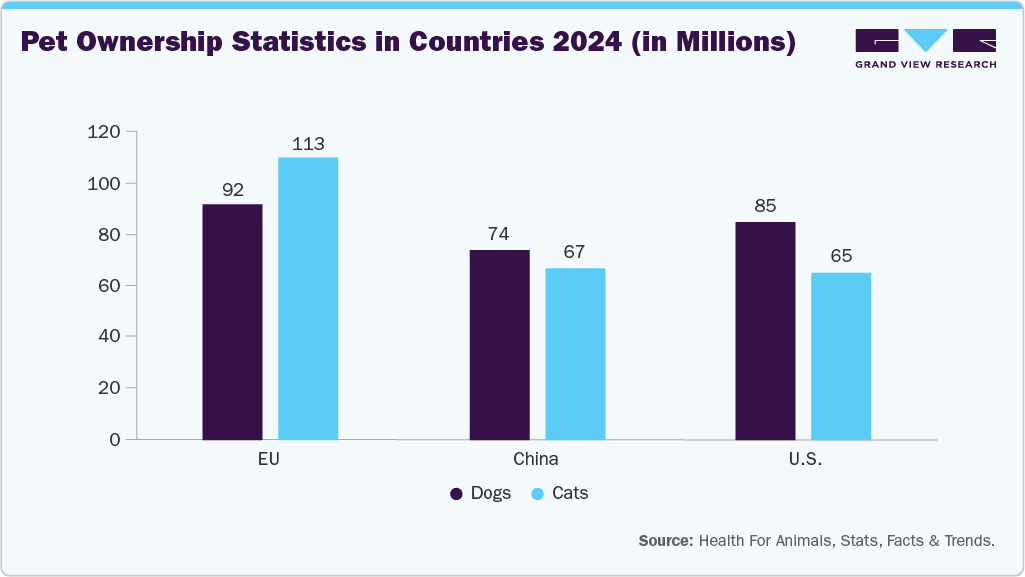
The veterinary oxygen therapy market is being driven by the increasing incidence of respiratory diseases, trauma cases, and postoperative complications in companion and livestock animals, coupled with the growing adoption of advanced critical care practices in veterinary medicine. Rising pet ownership, increasing pet humanization, and higher spending on animal healthcare are encouraging veterinary hospitals and clinics to invest in reliable oxygen delivery systems. In addition, advancements in portable, energy-efficient, and user-friendly oxygen concentrators, along with the emergence of home-based oxygen therapy solutions, are expanding the application of these devices beyond traditional clinical settings. The market is also advancing from the expansion of veterinary hospitals, specialty referral centers, and emergency care facilities, particularly in emerging economies, where improving veterinary infrastructure is increasing access to advanced respiratory support technologies.
Furthermore, regulatory authorities continue to implement stringent quality, safety, and performance standards for oxygen delivery devices, ensuring product reliability while extending approval timelines in some regions. Despite these positive developments, the market faces challenges related to the high acquisition and maintenance costs of oxygen concentrators, limited affordability among smaller veterinary practices, and the need for trained personnel to operate advanced respiratory equipment. These factors are encouraging manufacturers to focus on developing cost-effective, portable, and low-maintenance solutions to support broader adoption across both developed and emerging markets.
The growing adoption of home-based oxygen therapy for companion animals is a key driver of the veterinary oxygen therapy market, supported by increasing pet humanization, rising expenditure on advanced veterinary care, and the growing prevalence of respiratory disorders requiring long-term oxygen support. Pet owners are increasingly seeking portable and easy-to-use oxygen concentrators that enable continuous, non-invasive respiratory care in a home environment, reducing hospitalization time and improving recovery outcomes for pets with chronic respiratory diseases, post-surgical complications, or emergency conditions such as heatstroke. Manufacturers are responding to this demand by introducing innovative home-care solutions; for instance, in April 2026, VARON launched veterinary-inspired oxygen therapy bundles that combine continuous-flow oxygen concentrators with dedicated oxygen chambers, allowing pet owners to safely provide controlled oxygen therapy for pets at home. Such product innovations are expanding access to advanced respiratory care beyond veterinary clinics and accelerating the adoption of veterinary oxygen concentrators worldwide.
The high cost of veterinary oxygen concentrators and related respiratory care equipment significantly hampers the market growth. Veterinary-grade oxygen concentrators, oxygen cages, monitoring systems, and maintenance requirements involve substantial upfront and operational expenses, making them less affordable for small veterinary clinics, animal shelters, and individual pet owners. In addition, the need for regular servicing, replacement of filters and accessories, and reliable power supply further increases the total cost of ownership. In developing and price-sensitive markets, limited reimbursement for veterinary treatments and lower pet healthcare spending further restrict the adoption of advanced oxygen therapy systems. Consequently, cost concerns continue to limit the widespread deployment of veterinary oxygen concentrators, particularly in smaller practices and emerging economies.
The increasing incidence of canine respiratory disease outbreaks, including cases of canine respiratory disease of unknown origin, presents a significant opportunity for the veterinary oxygen therapy market. As veterinarians report more severe and prolonged respiratory illnesses that often do not respond to conventional treatment protocols, there is a growing need for supportive respiratory care to stabilize affected animals. For instance, according to an article published by Cornell University, oxygen therapy has become a critical component in managing dogs experiencing labored breathing, pneumonia, and other respiratory complications, both in veterinary hospitals and during recovery. The heightened focus on rapid diagnosis, intensive care, and preparedness for respiratory disease outbreaks is expected to encourage veterinary clinics to invest in advanced oxygen delivery systems. Furthermore, increasing awareness among pet owners about respiratory health and the expansion of specialized veterinary critical care services are likely to drive demand for veterinary oxygen concentrators, creating substantial growth opportunities for manufacturers to develop innovative, portable, and high-efficiency respiratory support solutions.
Market Concentration & Characteristics
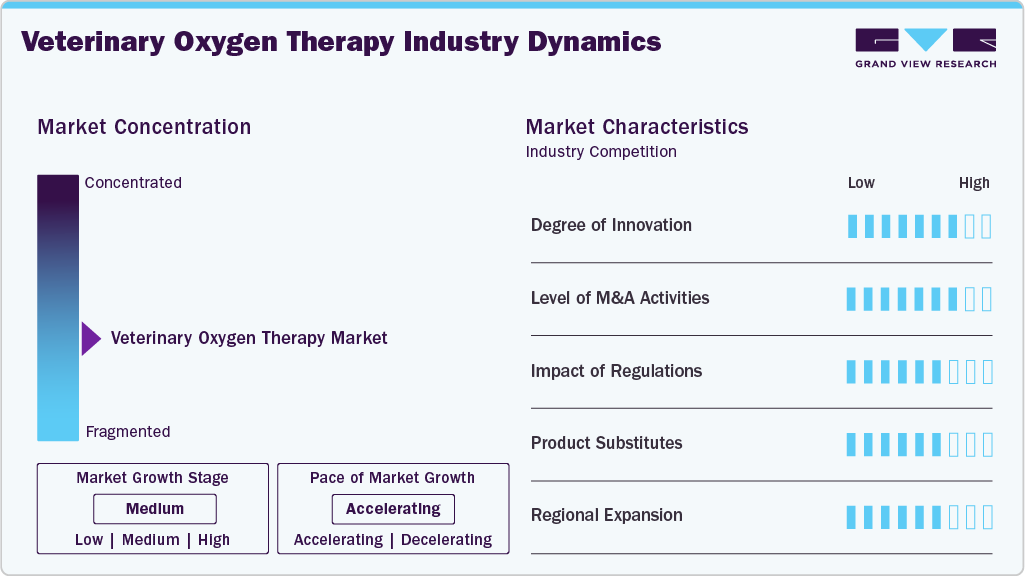
The veterinary oxygen therapy industry is moderately concentrated, and the pace is accelerating. It includes a mix of global medical device leaders and specialized veterinary equipment manufacturers. Competition centers on innovation, quality, and service support. Key players continually introduce advanced oxygen delivery systems, ICU units, and portable concentrators, driving differentiation while fostering strategic collaborations and regional expansions.
Manufacturers are launching smart intensive care units, integrated monitoring systems, and portable concentrators; the market is witnessing consistent innovation. The innovations' emphasis on easy-to-use design, effective oxygenation, and low maintenance allows for wider application in hospitals and clinics. For instance, in April 2025, Virginia Tech's Veterinary Teaching Hospital ICU improved critical care safety and efficiency by upgrading to VetFlex ICU oxygen equipment, the first soda lime-free units in the world. Veterinarians can now prioritize patient outcomes because of this breakthrough.
 To learn more about this report, Download Free Sample Report
Mergers and acquisitions remain moderate, with strategic partnerships focused on expanding product portfolios and geographic reach. Larger animal health companies are exploring acquisitions of niche device makers to strengthen ICU and respiratory care offerings. For instance, in January 2025, Infinium Medical’s veterinary division partnered exclusively with Vapotherm to distribute the Vapotherm VET 2.0 system, delivering advanced high-flow oxygen therapy technology to enhance respiratory support and critical care in veterinary medicine.
The market is directly impacted by laws pertaining to veterinary supplies and animal welfare. Adherence to safety, quality, and performance standards ensures trust between veterinarians and pet owners. Stricter welfare standards drive the need for oxygen support in emergency and surgical situations. On the other hand, protracted approval procedures and disparate local regulations delay product introductions, which affects expansion plans and market entry tactics.
In veterinary medicine, substitutes for oxygen therapy include manual ventilation, traditional ICU units, and basic airway management devices. However, these alternatives are less efficient, labor-intensive, and limited in sustaining oxygen levels for critical cases. Their shortcomings reinforce the importance of advanced oxygen therapy systems, positioning them as the preferred standard for respiratory support in veterinary critical and emergency care.
The market is propelled by regional expansion as the demand for veterinary oxygen therapy becomes more popular outside of developed nations. Opportunities abound throughout Asia Pacific and Latin America due to growing pet ownership, the need for livestock health care, and advancements in veterinary infrastructure. Global producers are expanding access to advanced care and hastening the global adoption of veterinary respiratory support systems by introducing portable, reasonably priced oxygen therapy options for emerging countries.
Analyst Perspective
The veterinary oxygen therapy market is witnessing sustained growth as respiratory support becomes an integral part of modern veterinary critical care. Increasing adoption of advanced treatment protocols and expanding specialty hospitals, emergency care facilities, and intensive care units are driving demand for reliable oxygen delivery systems. Veterinary oxygen concentrators are increasingly preferred due to their continuous oxygen supply, lower operating costs, and convenience. Technological advancements in portable concentrators, integrated monitoring, and home-based oxygen therapy are further expanding applications across animal care. Despite challenges such as high equipment costs, maintenance requirements, trained personnel, and regulatory barriers, cost-effective product development and greater awareness of clinical and economic benefits are expected to support long-term market growth.
Product Insights
Based on product, the veterinary oxygen concentrator segment led the market with the largest revenue share of 84.9% in 2025 and is the fastest-growing segment over the forecast period. The market's expansion is attributed to their effectiveness, affordability, and simplicity of use. Veterinary oxygen concentrators, which eliminate the need for refills and save operating costs for veterinary clinics, are more widely used than traditional oxygen cylinders because they deliver a consistent oxygen supply from ambient air. These veterinary oxygen concentrators are suitable for small animal practices, emergency care, and mobile veterinary units due to their portability and versatility. Rising rates of respiratory diseases in companion animals and more knowledge of advanced critical care solutions have contributed to their growing appeal.
Accessories accounted for the second fastest-growing segment in the market, driven by the need for complementary tools that enhance treatment efficiency and patient safety. For precise oxygen administration, this segment comprises oxygen masks, nasal cannulas, flow meters, tubing, regulators, and monitoring equipment. The demand for these goods rises with the adoption of core equipment as clinics offer more critical care services. Growth is further supported by the trend toward specialized, animal-specific accessories made for various breeds and sizes.
Animal Insights
Based on animal type, the small animals segment led the market with the largest revenue share of 50.9% in 2025, owing to the high prevalence of respiratory and critical care conditions in these animals. Rising pet ownership, increased spending on advanced veterinary treatments, and the humanization of pets drive demand for oxygen therapy solutions. Small animal clinics and hospitals prioritize emergency interventions, making oxygen therapy indispensable for emergencies, surgeries, and chronic respiratory care. Portable concentrators, masks, and ICU systems designed for smaller animals enhance adoption.
Large animal segments, including horses, cattle, and livestock, are the second fastest growing segment in the market due to increasing awareness of animal welfare and the economic importance of livestock health. Respiratory disorders, post-surgical recovery, and emergency care in large animals require specialized oxygen delivery systems. Equine hospitals, dairy farms, and veterinary practices increasingly adopt portable concentrators and high-flow oxygen devices designed for larger patients. Rising investments in veterinary infrastructure, combined with the need for advanced critical care in valuable livestock and performance animals, are driving rapid adoption, making large animals a key growth segment in the market.
Application Insights
Based on application, the ICU segment led the market with the largest revenue share of 67.0% in 2025, boosted by the increasing need for critical care facilities in veterinary hospitals and specialty clinics. Intensive care units are equipped with sophisticated oxygen delivery systems. Animals suffering from severe respiratory illnesses, trauma, or post-operative complications can get emergency care, precise oxygenation, and continuous monitoring. Growing pet ownership, more knowledge of advanced veterinary treatment, and the prevalence of acute and chronic illnesses in companion animals have all increased demand for ICU-based oxygen therapy. The ICU's standing as the market's favored category is strengthened by the combination of temperature control, high-flow oxygen systems, and monitoring apparatus.
The homecare setting/postoperative care segment is expanding fastest due to rising demand for ongoing, easy-to-access care for recuperating pets. Pet owners can safely provide oxygen therapy at home due to advancements in portable oxygen concentrators and small delivery systems, which lessen hospital stays and animal stress. Adoption is further accelerated by growing knowledge of chronic respiratory care and post-operative rehabilitation procedures. Furthermore, the humanization of dogs motivates owners to spend money on superior home care products.
End Use Insights
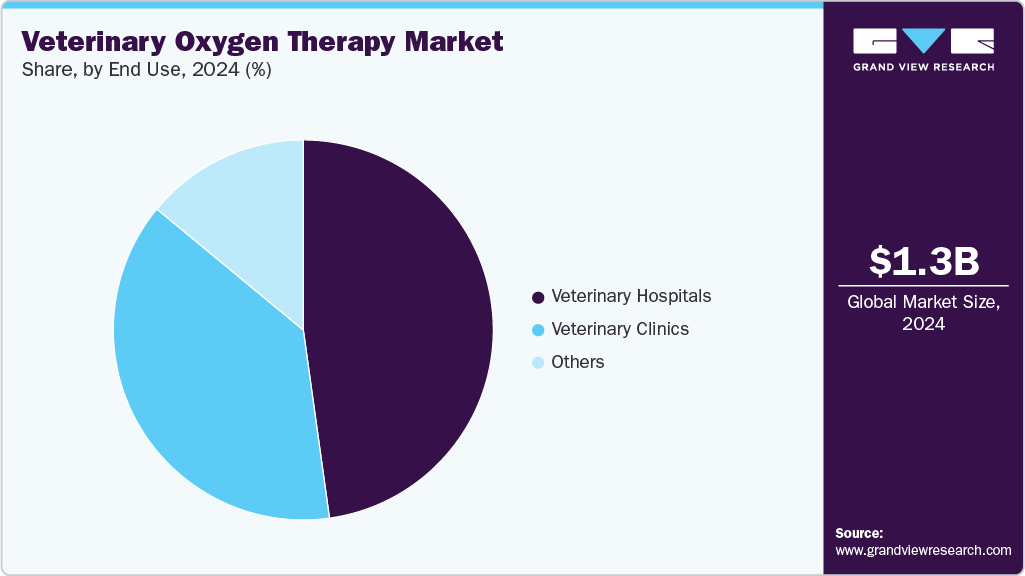
Based on end use, the veterinary hospitals segment led the market with the largest revenue share of 47.8% in 2025, driven by the concentration of specialist services, critical care units, and leading medical facilities. Numerous companion animals, livestock, and equine patients who need oxygen therapy for respiratory distress, surgical recuperation, or emergency care are served by hospitals. Hospitals offer accurate oxygen supply and continuous monitoring due to their ICU units, portable concentrators, and high-flow oxygen systems. Equipped with ICU units, portable concentrators, and high-flow oxygen systems, hospitals provide continuous monitoring and precise oxygen delivery.
 To learn more about this report, Download Free Sample Report
Veterinary clinics held the highest CAGR as they are the fastest-growing market, driven by the increasing number of small and mid-sized clinics expanding critical care services. Awareness of advanced respiratory care has encouraged clinics to adopt portable oxygen concentrators, masks, and high-flow therapy systems. Clinics benefit from cost-effective, convenient solutions that enable timely intervention for emergencies, surgeries, and chronic respiratory conditions. The demand is further fueled by the humanization of pets and owners’ preference for local, accessible care.
Regional Insights
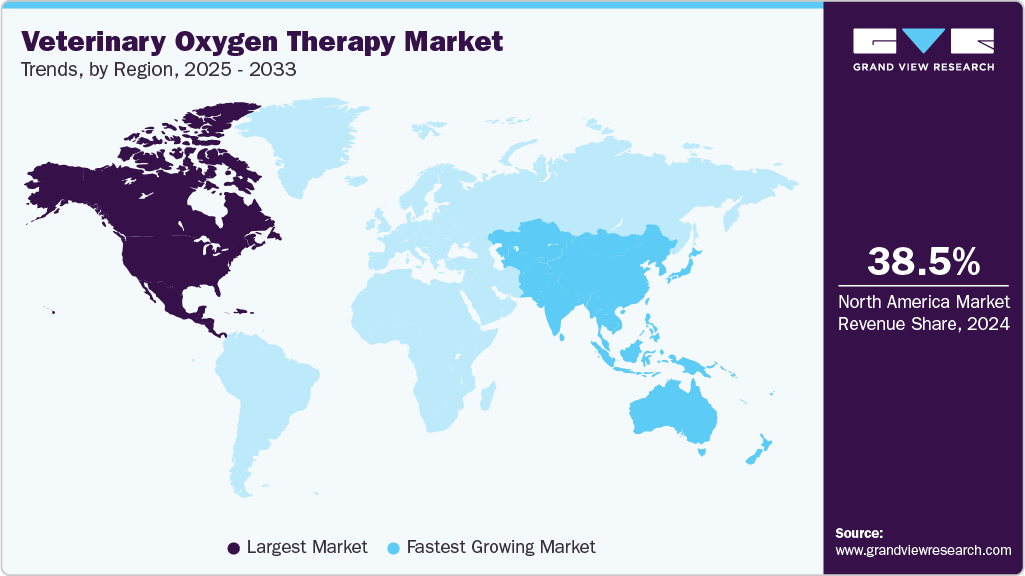
North America dominated the veterinary oxygen therapy market with the largest revenue share of 38.1% in 2025. The market growth is attributed to increasing awareness of advanced veterinary care and the growing adoption of pet insurance, which enables access to critical respiratory treatments. Some players, such as CAIRE Inc., Drive DeVilbiss Healthcare, Longfian Scitech, and Imex Medical Group, focus on innovations such as portable oxygen concentrators, high-flow therapy systems, and integrated ICU solutions. Technological advancements in mobile concentrators, air purification, and precise oxygen delivery enhance treatment outcomes, expanding adoption across clinics, hospitals, and home care settings.
 To learn more about this report, Download Free Sample Report
U.S. Veterinary Oxygen Therapy Market Trends
The veterinary oxygen therapy market in the U.S. held the largest share in the North America region in 2025, owing to rising pet ownership and demand for convenient, portable solutions. Technological advancements are boosting market growth with their new inventions. For instance, in 2024, Dynarex Corporation launched its expanded Resp-O2 line, offering portable oxygen delivery, suction care, and nebulization products that enable flexible, high-performance therapy in clinics, home care, and transport settings, supporting patient mobility and improving clinical outcomes.
Canada veterinary oxygen therapy market is expected to grow significantly during the forecast period. The market is driven by the expansion of veterinary clinics and hospitals and the shift towards home-care preferences. Additionally, advancements in portable oxygen concentrators and high-flow therapy systems enhance treatment options for animals across various settings. The regulatory landscape for veterinary oxygen therapy products is regulated to ensure safety, efficacy, and quality. Health Canada oversees medical devices used in veterinary care, requiring compliance with manufacturing, labeling, and performance standards. These regulations ensure reliable oxygen delivery, protect animal welfare, and guide veterinary practices adopting approved respiratory therapy equipment.
Europe Veterinary Oxygen Therapy Market Trends
The veterinary oxygen therapy market in Europe is driven by the expansion of veterinary facilities and regulatory support. Innovations such as hyperbaric oxygen therapy (HBOT) chambers provide high-pressure environments that accelerate healing and reduce inflammation in pets, as well as portable oxygen concentrators. Key players in the European market include AEOLUS International Pet Products, Airnetic, BMV Animal Technology, CAIRE, Drive DeVilbiss International, Imex Medical Limited, Koninklijke Philips, and Longfian Scitech. These companies are investing in research and development to introduce advanced oxygen therapy solutions, catering to the growing demand for effective and efficient animal respiratory care.
Germany veterinary oxygen therapy market held the highest share in 2024. Animals with respiratory problems and technological developments like high-flow therapy devices and portable oxygen concentrators drive this expansion. In addition, the market is growing due to the increased demand for sophisticated veterinary treatment and the increasing prevalence of respiratory disorders in animals. Throughout Germany, these developments improve the standard of care and availability of respiratory therapies for animals.
The veterinary oxygen therapy market in the UK is expected to grow significantly over the forecast period. The country’s growth is influenced by the consolidation of veterinary practices as larger groups acquire smaller surgery centers. To ensure uniform care across all locations, this tendency increases demand for standardized equipment, such as oxygen concentrators. Reliable oxygen therapy systems are even more important because merger practices frequently expand their offerings to encompass sophisticated critical care and difficult surgeries. For instance, the acquisition of Ark Animal Services by CVS Group in February 2024 demonstrates the increasing demand for veterinary equipment, such as oxygen concentrators, to support expanding operations and improved treatment capacities.
Asia Pacific Veterinary Oxygen Therapy Market Trends
The veterinary oxygen therapy market in the Asia Pacific is expected to grow at the fastest CAGR over the forecast period. The growing emphasis on providing high-quality veterinary care and the growth of AAHA accreditation in the area are the main factors propelling the market. Advanced equipment will become more necessary as more veterinary clinics strive for accreditation and higher standards, which will assist the expansion of the industry. One notable instance of a rising dedication to strict veterinary care standards is the AAHA's accreditation of Daktari Animal Hospital Tokyo Medical Center, the first outside of the United States and Canada. The need for equipment will increase as more Asia-Pacific practices work toward AAHA accreditation, supporting industry expansion.
China veterinary oxygen therapy market is witnessing new growth opportunities due to urbanization, the aging pet population, and the expansion of veterinary networks. In April 2025, China’s customs authorities ceased supervising goods under drugs, veterinary drugs, and medical devices, potentially easing the import and distribution of veterinary oxygen therapy devices. Despite this, all devices must still comply with NMPA registration and quality standards, ensuring safety, efficacy, and regulatory adherence in the Chinese market.
The veterinary oxygen therapy market in Japan is driven by the increasing number of animal clinics and the rising lifespan of pets, which is expected to drive demand for veterinary oxygen therapy. According to data from the Agriculture, Forestry, and Fisheries Ministry published in April 2022, there were 12,435 animal facilities in Japan in 2021, an 18% growth over the previous ten years. Increased rates of age-related illnesses, including cancer and renal failure, are a result of pets living longer. The rising market for veterinary services is reflected in Tokyo University of Agriculture and Technology's new hospital, which has expanded its animal clinics and implemented 24-hour care. To promote high-quality care for elderly dogs and emergencies, this trend is anticipated to increase demand for veterinary oxygen concentrators.
India veterinary oxygen therapy marketis expanding significantly, which may be ascribed to increased livestock production, government initiatives, and animal welfare programs. Technological developments have created affordable portable oxygen concentrators, improving therapy effectiveness and accessibility. Major players in the market, such as Philips India Limited, BPL Medical Technologies, Nidek Medical India, and Imex Medical, are vital in transforming market growth. These companies are focusing on innovation and expanding their product offerings to meet the growing needs of the veterinary healthcare sector.
Latin America Veterinary Oxygen Therapy Market Trends
The veterinary oxygen therapy market in Latin America is expected to witness significant growth over the estimated time period. In Latin America, the market is developing steadily, supported by the integration of telemedicine in veterinary care and the expansion of veterinary education and training. In addition, growing pet humanization trends and an increasing emphasis on improving animal health outcomes drive higher demand for oxygen concentrators in veterinary facilities throughout Latin America.
Brazil veterinary oxygen therapy market is witnessing notable growth due to the expansion of veterinary service networks across the country. For example, in September 2022, VetFamily launched in Brazil with 25 clinics onboard, tapping into a vibrant pet population exceeding 149.6 million. Their innovative business model offers veterinarians solutions and tools to support their professional growth. As veterinary clinic networks like VetFamily expand, the demand for advanced medical equipment, including oxygen concentrators, rises, essential for animal respiratory care, surgical procedures, and post-operative recovery.
Middle East & Africa Veterinary Oxygen Therapy Market Trends
The veterinary oxygen therapy market in the MEA is expanding significantly due to improvements in veterinary procedures like those at Modern Vet in Dubai. Successfully correcting congenital heart abnormalities and intricate small animal surgeries are two innovative procedures driving demand for innovative veterinary equipment. The UAE's Ministry of Climate Change and Environment (MOCCAE) supports efforts to advance veterinary care, emphasizing the growing demand for high-quality oxygen concentrators in this growing industry.
South Africa veterinary oxygen therapy market is the fastest-growing over the forecast period, propelled by the rising number of veterinary clinics and hospitals. Increasing animal healthcare awareness and the expanding pet population drive demand for advanced veterinary services. In addition, technological innovations in veterinary medical devices and an emphasis on delivering high-quality care support the widespread adoption of oxygen concentrators in veterinary practices throughout the country.
The veterinary oxygen therapy market in the UAE is experiencing growth driven by increased pet ownership and improvements in veterinary care. Technological advancements, including stationary and portable oxygen concentrators, are providing more options for treating animal respiratory disorders. Among the major participants in the area are Drive Through product development and strategic alliances. DeVilbiss Healthcare, Imex Medical Limited, Longfian Scitech, and RWD Life Science are bolstering the market's expansion.
Key Veterinary Oxygen Therapy Company Insights
Major global market players include Drive DeVilbiss Healthcare, Imex Medical Limited, Longfian Scitech, Philips, CAIRE, and BMV Animal Technology. These companies lead through innovation, strategic collaborations, and expanding product portfolios, strengthening their market presence and shaping competitive dynamics across regions in the rapidly growing veterinary oxygen therapy sector. For instance, in July 2025, Penlon launched a new Veterinary Product Range featuring anesthesia systems, MRI-compatible devices, and patient monitoring solutions, with integrated oxygen therapy to enhance veterinary surgical safety and critical care outcomes.
Key Veterinary Oxygen Therapy Companies:
The following key companies have been profiled for this study on the veterinary oxygen therapy market.
-
VETLAND MEDICAL SALES & SERVICES. LLC
-
Airnetic, LLC
-
CAIRE Inc.
-
Longfian Scitech Co., Ltd.
-
IMEX MEDICAL LIMITED,
-
RWD Life Science Co., Ltd.
-
AEOLUS International Pet Products, LLC.
-
Koninklijke Philips N.V.
-
Drive DeVilbiss International
-
Shinova Systems
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Koninklijke Philips N.V.; Drive DeVilbiss International; CAIRE Inc.; Longfian Scitech Co., Ltd.; IMEX MEDICAL LIMITED; RWD Life Science Co., Ltd.)
- Established companies focus on expanding their respiratory care portfolios by offering stationary and portable oxygen concentrators, oxygen cages, ICU systems, flowmeters, and oxygen delivery accessories for veterinary applications. They emphasize continuous product innovation, product quality, regulatory compliance, global distribution expansion, strategic partnerships with veterinary hospitals and distributors, and investments in R&D to improve oxygen delivery efficiency, portability, and patient safety.
- These companies benefit from strong global distribution networks, recognized brands, diversified respiratory care portfolios, advanced engineering capabilities, regulatory expertise, and long-standing relationships with veterinary hospitals and specialty clinics. Their ability to invest in technological innovation, after-sales service, and international expansion enables them to maintain a competitive position.
- Established manufacturers face challenges associated with high manufacturing and regulatory compliance costs, pricing pressure from regional manufacturers, lengthy product approval processes, and increasing competition from low-cost oxygen concentrator suppliers. Dependence on hospital capital expenditure and reimbursement limitations in some regions may also restrict market expansion.
Emerging Players (VETLAND MEDICAL SALES & SERVICES, LLC; Airnetic, LLC; AEOLUS International Pet Products, LLC.; Shinova Systems)
- Emerging companies primarily focus on niche veterinary respiratory care solutions, portable oxygen systems, homecare applications, and customized oxygen therapy equipment for companion animals. They compete through flexible pricing strategies, rapid product customization, online sales channels, distributor partnerships, and expansion into underserved regional markets.
- Emerging players compete through product flexibility, quicker product development cycles, niche specialization, and the ability to address specific veterinary requirements. Many differentiate themselves through portable designs, customer support, and customized respiratory care solutions for veterinary practices.
- Emerging companies often have limited financial resources, smaller distribution networks, lower brand recognition, and limited manufacturing capacity. They may also face challenges in obtaining regulatory approvals, expanding internationally, competing with multinational manufacturers, and investing in large-scale product development.
Recent Developments
-
In February 2025, Bionet America unveiled its Super Air Smart ICU, a next-generation veterinary critical care unit featuring efficient oxygenation, CO₂ management without soda-lime, ionization-based air purification, and advanced climate control. Designed to reduce workload and costs while improving patient comfort and safety, the launch sets a new standard for veterinary ICUs, enhancing overall treatment efficiency.
-
In January 2025, Infinium Medical announced an exclusive partnership to distribute Vapotherm VET 2.0, an advanced high-flow oxygen therapy system for veterinary use. The system transforms respiratory care with enhanced mobility, user-friendly design, improved animal comfort, and advanced medication delivery. The launch strengthens Infinium’s portfolio while empowering veterinary clinics with innovative technology for better patient outcomes.
-
In February 2024, Tata Trusts opened India's first Small Animal Hospital in Mahalaxmi, Mumbai. It will provide round-the-clock services through pet-sensitized veterinarians, nurses, and technicians, focusing on emergency and critical care, surgery, and oxygen therapy. The hospital will feature advanced radiology, imaging, and laboratory equipment catering to a wide range of veterinary needs.
Veterinary Oxygen Therapy Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.4 billion
Estimated market size in 2026
USD 1.5 billion
Projected market size by 2033
USD 2.5 billion
Growth rate
CAGR of 7.7% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, animal type, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
VETLAND MEDICAL SALES & SERVICES. LLC; Airnetic, LLC; CAIRE Inc.; Longfian Scitech Co., Ltd.; IMEX MEDICAL LIMITED; RWD Life Science Co., Ltd.; AEOLUS International Pet Products, LLC.; Koninklijke Philips N.V.; Drive DeVilbiss International; Shinova Systems
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary Oxygen Therapy Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global veterinary oxygen therapy market report based on product, animal, application, end use, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Veterinary Oxygen Concentrator
-
Portable Oxygen Concentrator
-
Stationary Oxygen Concentrator
-
-
Accessories
-
-
Animal Outlook (Revenue, USD Million, 2021 - 2033)
-
Small Animal
-
Large Animal
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
ICU
-
Homecare setting/postoperative care
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Veterinary Hospitals
-
Veterinary Clinics
-
Others
-
-
Region Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
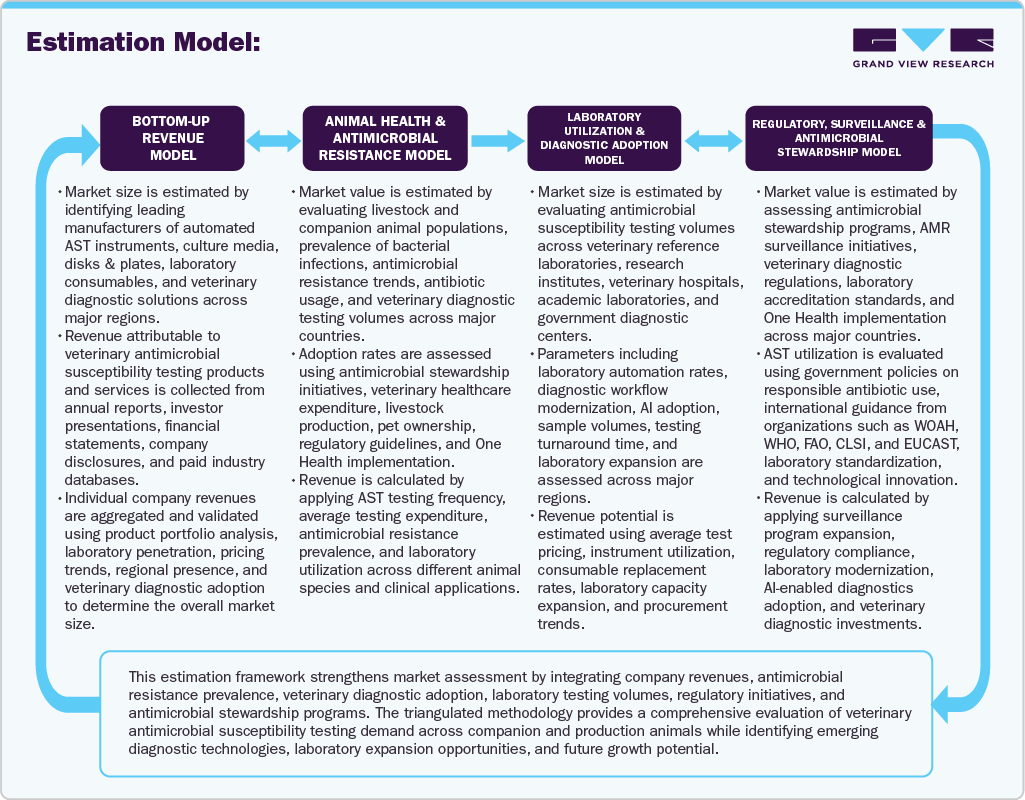
The veterinary oxygen therapy market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each veterinary oxygen therapy segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue Capture Definition
Veterinary Oxygen Concentrator
Revenue generated from the sale of veterinary oxygen concentrators designed to deliver a continuous supply of medical-grade oxygen for respiratory support in animals.
Portable Oxygen Concentrator
Revenue generated from the sale of portable veterinary oxygen concentrators designed to provide a continuous supply of medical-grade oxygen for animals in mobile veterinary units, emergency care, transport, homecare, and other settings requiring lightweight and portable respiratory support.
Stationary Oxygen Concentrator
Revenue generated from the sale of stationary veterinary oxygen concentrators installed in veterinary hospitals, clinics, and intensive care units to deliver a continuous and reliable oxygen supply for surgical procedures, critical care, hospitalization, and long-term respiratory therapy.
Accessories
Revenue generated from the sale of accessories used with veterinary oxygen concentrators, including oxygen masks, nasal cannulas, tubing, humidifier bottles, oxygen cages, flowmeters, connectors, and related consumables.
Segment - Animal Type
Revenue Capture Definition
Small Animals
Revenue generated from oxygen therapy equipment and accessories utilized for companion animals such as dogs, cats, rabbits, and other small mammals requiring respiratory support.
Large Animals
Revenue generated from veterinary oxygen concentrators and associated products used for livestock and equine animals, including cattle, horses, sheep, goats, and pigs.
Others
Revenue generated from oxygen therapy solutions provided for other animal species, including birds, reptiles, zoo animals, and exotic wildlife requiring respiratory care.
Segment - Application
Revenue Capture Definition
ICU
Revenue generated from the use of veterinary oxygen concentrators in intensive care units for managing critically ill animals requiring continuous oxygen therapy and respiratory support.
Homecare Setting/Postoperative Care
Revenue generated from oxygen concentrators deployed in homecare and postoperative recovery settings to support animals recovering from surgery, anesthesia, or chronic respiratory conditions outside intensive care environments.
Others
Revenue generated from veterinary oxygen concentrators used in other clinical applications, including emergency stabilization, diagnostic procedures, transport, and routine inpatient care.
Segment - End Use
Revenue Capture Definition
Veterinary Hospitals
Revenue generated from the procurement and utilization of veterinary oxygen concentrators by veterinary hospitals for emergency, surgical, intensive care, and inpatient treatment of animals.
Veterinary Clinics
Revenue generated from the adoption of veterinary oxygen concentrators by veterinary clinics to provide respiratory support during routine consultations, procedures, and outpatient treatments.
Others
Revenue generated from oxygen concentrators supplied to other end users, including animal shelters, veterinary teaching institutions, research laboratories, rehabilitation centers, and homecare providers.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Respiratory Device Competitive Benchmarking
Performed detailed benchmarking of leading veterinary oxygen therapy manufacturers based on oxygen concentrator technologies, portability, ICU compatibility, product innovation, manufacturing capabilities, geographic presence, pricing strategies, distribution partnerships, and after-sales support. Included comparative assessment of established and emerging manufacturers.
Provides actionable insights into oxygen therapy adoption trends, critical care infrastructure, technology penetration, and purchasing behavior, enabling stakeholders to optimize product positioning, investment planning, and commercialization strategies.
Critical Care Equipment Adoption Assessment
Conducted a comprehensive assessment of the adoption of veterinary oxygen therapy equipment across veterinary hospitals, specialty clinics, emergency care centers, and homecare settings. Evaluated oxygen concentrator utilization, ICU infrastructure, respiratory disease burden, product portfolios, technology advancements, procurement trends, and end-user purchasing behavior across major regions.
Enables identification of competitive gaps, product differentiation opportunities, acquisition and partnership targets, pricing optimization strategies, and innovation leadership while supporting long-term competitive positioning and strategic decision-making.
Regional Demand & Commercial Expansion Analysis
Assessed regional demand by evaluating veterinary infrastructure, respiratory disease incidence, pet ownership, livestock healthcare expenditure, regulatory requirements, and expansion of specialty veterinary services. Identified priority markets and recommended commercialization and distribution strategies based on market maturity and future growth potential.
Enables companies to prioritize high-growth countries, strengthen distribution networks, optimize market-entry strategies, and allocate investments efficiently while minimizing commercial and regulatory risks.
Frequently Asked Questions About This Report
The global veterinary oxygen therapy market size was estimated at USD 1.4 billion in 2025 and is expected to reach USD 1.5 billion in 2026.
The global veterinary oxygen therapy market is expected to grow at a compound annual growth rate of 7.7% from 2025 to 2033 to reach USD 2.5 billion by 2033.
North America dominated the veterinary oxygen therapy market with a share of 38.1% in 2025.
Some key players operating in the veterinary oxygen therapy market include VETLAND MEDICAL SALES & SERVICES. LLC, Airnetic, LLC, CAIRE Inc., Longfian Scitech Co., Ltd, IMEX MEDICAL LIMITED, RWD Life Science Co., LTD, AEOLUS International Pet Products, LLC., Koninklijke Philips N.V., Drive DeVilbiss International, Shinova Systems
Key factors that are driving the market growth include rising prevalence of respiratory diseases in animals, a growing number of pet owners, increasing adoption of pet insurance, and rapid technological advancements in veterinary oxygen therapy.
Asia Pacific is also the fastest-growing region over the forecast period.
The veterinary oxygen concentrators segment led with a 84.9% revenue share in 2025, and is the fastest-growing segment.
The small animals segment led with a 50.9% revenue share in 2025, and is the fastest-growing segment.
The ICU segment led with a 67.0% revenue share in 2025, while the Homecare setting/postoperative care is the fastest-growing segment.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


