
- Home
- »
- Biotechnology
- »
-
Antibody Production Market Size, Share Report, 2026-2033GVR Report cover

Antibody Production Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Instruments, Consumables, Software), By Type (Polyclonal Antibody, Monoclonal Antibody), By Process (Upstream Processing, Downstream Processing), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$17.0BMarket Estimate, 2026
$18.8BMarket Forecast, 2033
$39.8BCAGR, 2026–2033
11.3%Antibody Production Market Summary
The global antibody production market size was valued at USD 17.0 billion in 2025 and is projected to grow from USD 18.8 billion in 2026 to USD 39.8 billion by 2033, at a CAGR of 11.3% from 2026 to 2033. North America dominated the global market with the largest revenue share of 37.5% in 2025. Increasing prevalence of chronic diseases such as cancer, diabetes, and cardiovascular diseases, coupled with the growing demand for therapeutic antibodies, has led to the rapid growth of the antibody production market.
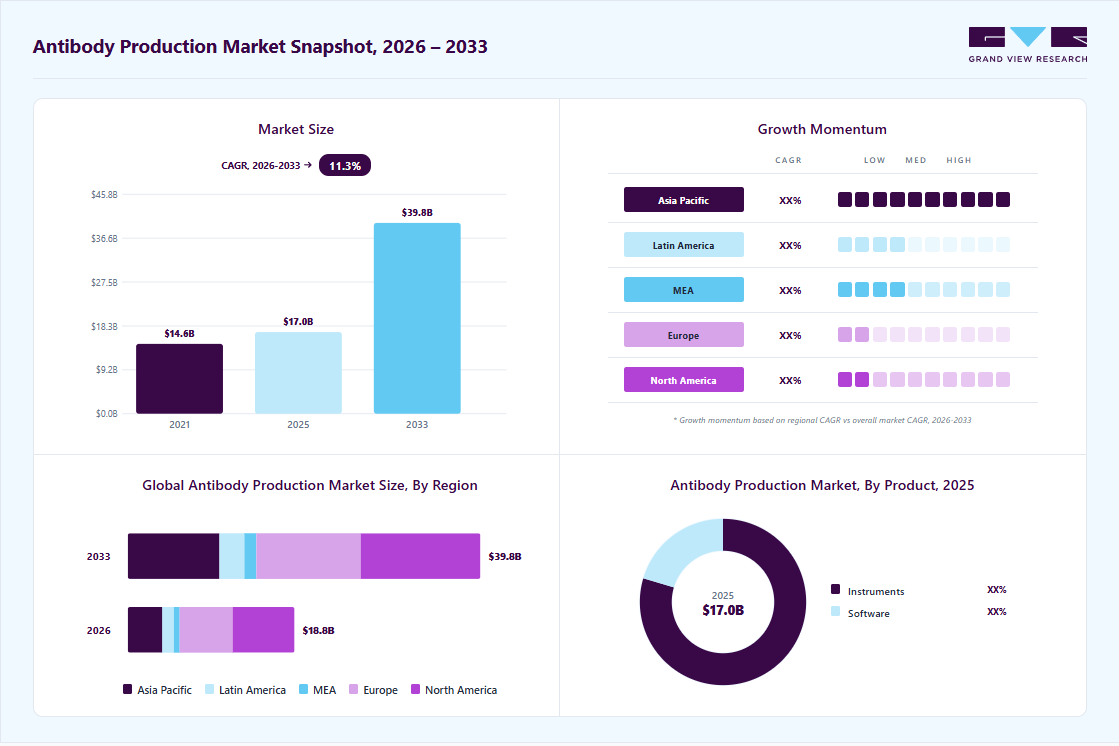 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Consumables segment led the market with the largest revenue share of 55.9% in 2025.
- By process: Downstream processing segment led the market with the largest revenue share of 67.5% in 2025.
- By type: Monoclonal antibody segment led the market with the largest revenue share of 63.8% in 2025.
- By end use: Pharmaceutical & biotechnology companies segment led the market with the largest revenue share of 55.3% in 2025.
Regional Highlights
- Largest regional market: North America (37.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 17.0 Billion
- Estimated market size in 2026: USD 18.8 Billion
- Projected market size by 2033: USD 39.8 Billion
- CAGR (2026-2033): 11.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
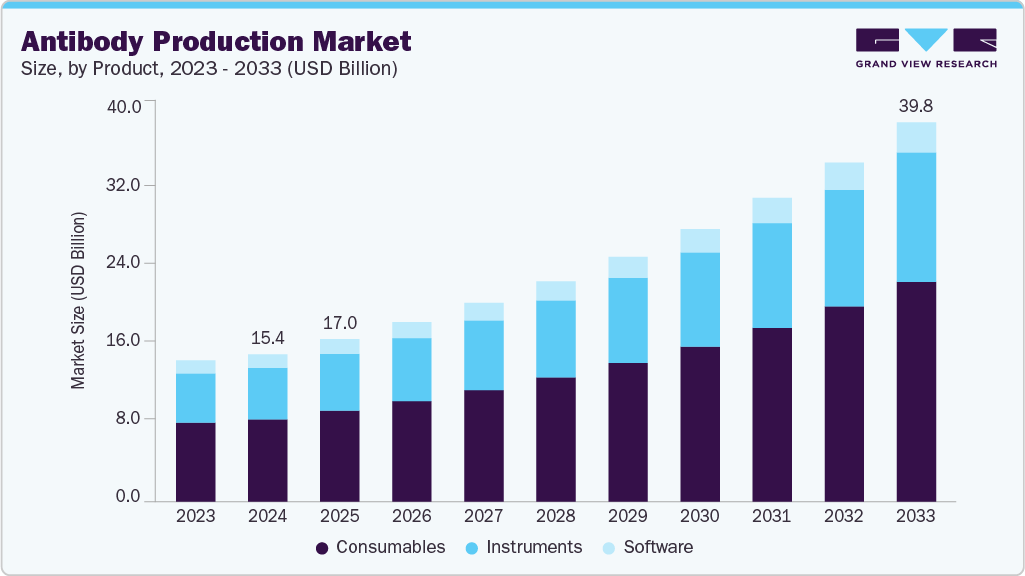 To learn more about this report, Download Free Sample Report
Market Dynamics
The antibody production market was driven by the rising demand for monoclonal antibodies in therapeutics, diagnostics, and research applications, supported by the increasing prevalence of chronic diseases, cancer, autoimmune disorders, and infectious diseases. Growing investments in biopharmaceutical research and development, coupled with advancements in cell culture technologies, expression systems, and bioprocessing methods, continued to enhance production efficiency and scalability. Furthermore, expanding biologics pipelines, increasing adoption of personalized medicine, and growing demand for high-quality antibodies in drug discovery and clinical diagnostics created substantial opportunities for market growth across both developed and emerging healthcare markets.
The primary driver of the antibody production market is the growing demand for monoclonal antibody-based therapies used in the treatment of cancer, autoimmune disorders, infectious diseases, and other chronic conditions. Monoclonal antibodies have become a cornerstone of modern biopharmaceutical development due to their high specificity, effectiveness, and ability to target disease pathways with greater precision than traditional therapies.
In addition, the expanding pipeline of antibody-based drugs and biosimilars has increased the need for large-scale production capabilities. Pharmaceutical and biotechnology companies continue to invest in advanced manufacturing technologies to meet rising global demand and improve production efficiency.
A major restraint in the antibody production market is the high cost associated with antibody manufacturing. Production requires sophisticated bioprocessing infrastructure, specialized equipment, expensive cell culture media, and stringent quality control measures, all of which contribute to significant operational expenses.
Furthermore, antibody production involves complex upstream and downstream processing steps that must consistently meet regulatory and quality standards. Maintaining product purity, yield, and batch-to-batch consistency remains challenging, particularly as production volumes increase, adding to the overall cost and complexity of manufacturing.
The increasing adoption of personalized medicine presents a significant opportunity for the antibody production market. As healthcare providers move toward targeted treatment approaches, demand for customized and highly specific antibody therapies is expected to rise, creating new avenues for innovation and commercial expansion.
Additionally, the development of next-generation antibody formats, including bispecific antibodies, antibody-drug conjugates (ADCs), and engineered antibodies, is expanding the scope of therapeutic applications. Continued advancements in production technologies and bioprocess optimization are expected to support the scalable manufacture of these complex biologics and drive future market growth.
Market Concentration & Characteristics
The antibody production industry demonstrates a high degree of innovation, driven by advances in bioprocessing technologies, adoption of single-use systems, and development of next-generation formats such as bispecifics and antibody-drug conjugates. Continuous investments in R&D, capacity expansion, and digitalized manufacturing solutions are enhancing scalability, efficiency, and product quality. These innovations are not only meeting rising therapeutic demand but also shaping a competitive market landscape with accelerated time-to-market for novel biologics.
The antibody production industry demonstrates a high degree of innovation, driven by advances in bioprocessing technologies, adoption of single-use systems, and development of next-generation formats such as bispecifics and antibody-drug conjugates. Continuous investments in R&D, capacity expansion, and digitalized manufacturing solutions are enhancing scalability, efficiency, and product quality. These innovations are not only meeting rising therapeutic demand but also shaping a competitive market landscape with accelerated time-to-market for novel biologics.
 To learn more about this report, Download Free Sample Report
Regulations significantly impact the antibody production industry, shaping manufacturing standards, product quality, and market access. Strict guidelines from agencies such as the FDA and EMA mandate compliance with Good Manufacturing Practices (GMP), driving investments in advanced production technologies and robust quality control systems. While regulatory oversight ensures the safety and efficacy of therapeutic antibodies, it also increases operational complexity and costs, compelling companies to adopt innovative, compliant, and scalable processes to remain competitive.
Product expansion is emerging as a key growth strategy in the antibody production industry, with leading players actively broadening their portfolios to meet diverse therapeutic needs and capture wider market share. Companies are introducing next-generation antibodies, biosimilars, and innovative production platforms to strengthen competitiveness. This strategy not only addresses rising demand across oncology, autoimmune, and infectious diseases but also supports differentiation in an increasingly crowded market, positioning firms for sustainable long-term growth.
Regional expansion has become a central strategy for companies operating in the antibody production market, as demand for biologics accelerates across emerging and developed economies. Firms are investing in new manufacturing facilities, partnerships, and localized supply chains to strengthen presence in high-growth regions such as Asia-Pacific and the Middle East. This approach enhances market access, reduces distribution challenges, and enables closer collaboration with regional biopharma players, ultimately driving competitiveness and long-term growth opportunities.
Analyst Perspective
The antibody production market remains a foundational and steadily expanding segment within the broader biopharmaceutical industry, supported by the sustained clinical success and commercial adoption of monoclonal antibodies across multiple therapeutic areas. Growth is being reinforced by continuous pipeline expansion, increasing biosimilar penetration, and rising demand for scalable, cost-efficient manufacturing solutions as companies aim to balance high production complexity with pricing pressures. At the same time, the market is evolving toward intensified bioprocessing, single-use technologies, and continuous manufacturing to improve yield and reduce operational bottlenecks. While high capital investment and stringent regulatory requirements continue to shape entry barriers, long-term visibility remains strong due to growing biologics consumption, expansion of contract manufacturing organizations, and increasing focus on next-generation antibody formats such as bispecific and antibody-drug conjugates.
Personalized and Next-Generation Antibodies
The global antibody production market is experiencing a significant shift as the industry moves beyond conventional monoclonal antibodies toward more complex, next-generation formats. Personalized therapies are increasingly becoming the standard of care, with bispecific antibodies, antibody-drug conjugates (ADCs), and engineered monoclonal antibodies emerging as critical tools in targeting diseases with greater precision and efficacy. These novel modalities not only enhance therapeutic outcomes but also open new opportunities for biopharmaceutical companies to differentiate their portfolios in an increasingly competitive landscape.
The rise of next-generation antibodies is fueling demand for advanced and highly specialized production technologies. Unlike traditional mAbs, which rely on relatively standardized production processes, bispecifics and ADCs require more sophisticated cell line development, purification techniques, and conjugation platforms. Manufacturers are rapidly adopting innovative solutions such as high-density perfusion bioreactors, modular single-use systems, and integrated continuous bioprocessing to meet these evolving requirements. This technological advancement is essential to achieve cost-effective scalability while maintaining the high quality and safety standards expected for complex biologics.
Market growth is further reinforced by strong investment flows from both established pharmaceutical players and emerging biotech firms aiming to capitalize on next-generation antibody pipelines. Partnerships, acquisitions, and capacity expansion initiatives are accelerating globally, with a particular focus on regions that are investing heavily in biopharma infrastructure. As regulatory frameworks evolve to accommodate these innovative therapies, companies that can align their production capabilities with the unique demands of personalized and next-generation antibodies are well positioned to capture a larger share of this expanding market. Ultimately, the convergence of scientific innovation, manufacturing excellence, and strategic investment is reshaping the antibody production landscape and sustaining robust long-term growth.
Rising Disease Burden Fueling Monoclonal Antibody Demand
The growing prevalence of chronic and infectious diseases is a critical driver of the antibody production market, as monoclonal antibodies (mAbs) increasingly serve as frontline therapies across multiple therapeutic areas. With the global incidence of cancers, autoimmune disorders, and infectious diseases continuing to rise, demand for highly targeted and effective treatment options has intensified. Monoclonal antibodies provide unique advantages through their ability to specifically bind to disease-related antigens, offering improved safety profiles, reduced side effects, and greater treatment efficacy compared to traditional small-molecule drugs. This clinical superiority has firmly established mAbs as a cornerstone of modern therapeutics, driving consistent growth in development pipelines and regulatory approvals worldwide.
This expanding demand directly impacts antibody production, as healthcare systems and pharmaceutical companies face the dual challenge of scaling manufacturing capacity while maintaining cost efficiency and product quality. Advances in bioprocessing, such as high-yield cell culture platforms, single-use bioreactor technologies, and continuous processing methods, are being rapidly adopted to meet the growing need for large-scale, reliable supply. Moreover, the rise of biosimilars, spurred by the expiry of patents on blockbuster mAbs, is further stimulating production activity by broadening patient access and intensifying competition among manufacturers. Collectively, the convergence of rising disease prevalence, expanding therapeutic pipelines, and advancing production technologies is positioning monoclonal antibodies as a key growth engine within the global biopharmaceutical sector.
Product Insights
IBased on product, the consumables segment led the market with the largest revenue share of 55.9% in 2025 and is estimated to have the fastest CAGR during the forecast period. Consumables include a wide range of products such as reagents, kits, media, buffers, and other materials that are used in the production of antibodies. Rising demand for antibodies across research, diagnostic, and therapeutic applications is driving significant growth in consumables. Moreover, the growing adoption of automated production systems is further boosting consumables usage, as advanced platforms require consistent supplies to ensure efficiency, scalability, and high-quality outcomes in antibody manufacturing.
The instruments segment is poised for significant growth in the global antibody production market. These instruments are essential to the production process, encompass bioreactors, centrifuges, chromatography systems, and other critical equipment. Advancements in automation, high-throughput technologies, and process optimization are driving demand for more efficient and scalable production solutions. As the global need for therapeutic and research antibodies rises, manufacturers are increasingly investing in state-of-the-art instruments to enhance yield, reduce production timelines, and ensure consistent product quality. This positions the instruments segment as a key growth driver within the antibody production market in the coming years.
Process Insights
Based on process, the downstream processing segment led the market with the largest revenue share of 67.5% in 2025. Downstream processes are critical for ensuring antibody quality, safety, efficacy, purity, and identity. Technological innovations are enhancing efficiency and driving bio-manufacturing advancements. Key developments include single-use sensors, membrane chromatography, remote monitoring, and advanced data analytics, all of which streamline processing and improve consistency. As manufacturers focus on scaling production and meeting rising global demand, the downstream segment remains a central growth driver, underpinned by continuous innovation and process optimization in antibody manufacturing.
The upstream process segment is expected to witness strong growth in the antibody production market over the forecast period. This growth is driven by significant investments in advanced production infrastructure by key manufacturers. Companies are increasingly adopting state-of-the-art bioreactors and process optimization technologies in the upstream stage to enhance yield, efficiency, and product quality. These innovations not only improve the consistency and scalability of antibody production but also support the rising global demand for therapeutic and research antibodies. As a result, the upstream process segment is positioned as a critical driver of growth and technological advancement within the antibody production market.
Type Insights
Based on type, the monoclonal antibody segment led the market with the largest revenue share of 63.8% in 2025. The segment’s growth is driven by rising investments in monoclonal antibody research and the launch of various innovative antibody-based products. For instance, in March 2023, Eli Lilly, a US-based pharmaceutical company, invested nearly USD 1 billion in a monoclonal antibody (mAbs) manufacturing plant in Ireland that would start the production of novel clinical products by the 2026.
The polyclonal antibody segment is expected to experience a significant growth over the forecast period, driven by advantages such as a straightforward production process, low cost, and rising demand for diagnostic tests for prevalent diseases. Advances in technologies such as recombinant DNA methods and transgenic animal models are further supporting this growth. In addition, polyclonal antibodies can be produced faster and more cost-effectively than monoclonal antibodies, as they do not require the complex cell culture and screening processes involved in monoclonal antibody production.
End Use Insights
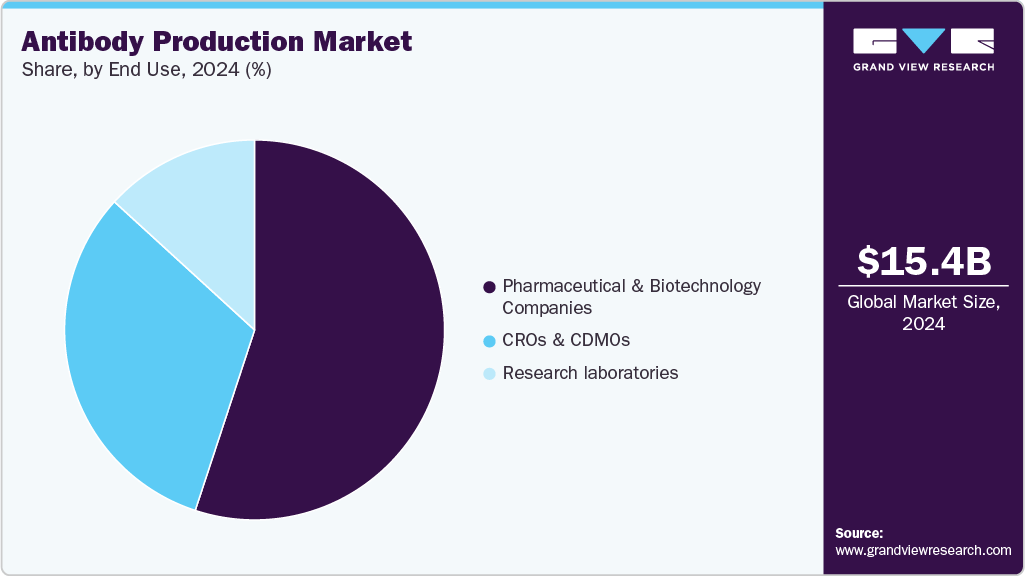
Based on end use, the pharmaceutical & biotechnology companies segment led the market with the largest revenue share of 55.3% in 2025. A major driver of segment growth is the expanding role of biopharmaceutical companies in antibody production. Leading pharmaceutical and biotechnology firms are investing heavily in R&D, leveraging substantial financial resources and advanced technologies. This enables the development of innovative antibody products that address the evolving needs of healthcare providers and patients, reinforcing their pivotal position in the antibody production market.
 To learn more about this report, Download Free Sample Report
CROs and CDMOs held the highest CAGR of 12.5% during 2025-2033. The growth is largely driven by rising demand for outsourcing services, as pharmaceutical and biotechnology companies aim to lower operational costs and concentrate on core competencies. Additionally, the COVID-19 pandemic has amplified demand for CMOs and CROs, with companies seeking to accelerate the development and production of antibody-based therapies and vaccines.
Regional Insights
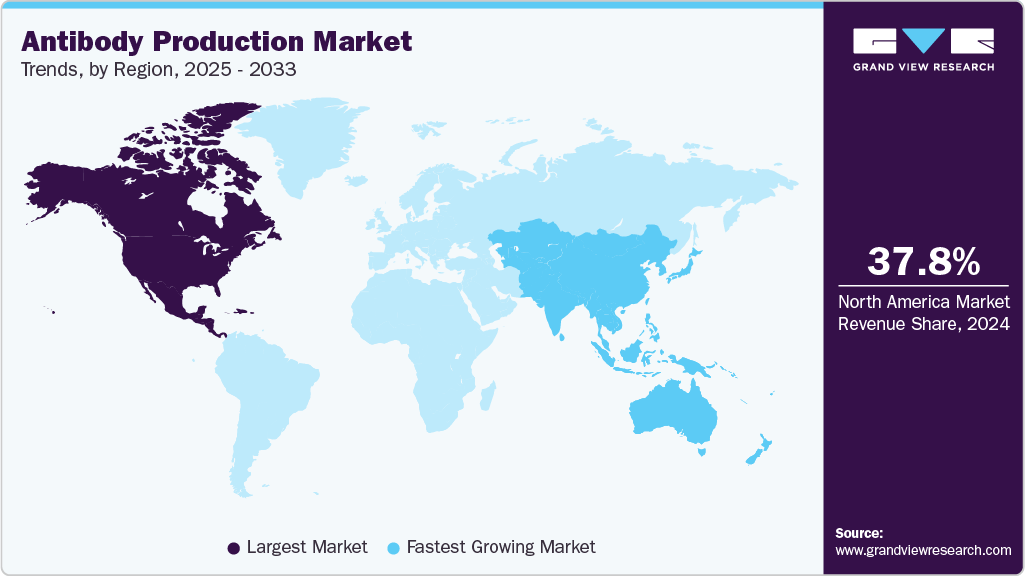
North America dominated the antibody production market with the largest revenue share of 37.5% in 2025. This leadership is driven by the presence of major biopharmaceutical companies, advanced research infrastructure, and significant investments in antibody development and manufacturing. Strong regulatory support, high adoption of innovative technologies, and growing demand for therapeutic and diagnostic antibodies further reinforce the region’s dominant position, making North America a key contributor to global market growth.
 To learn more about this report, Download Free Sample Report
U.S Antibody Production Market Trends
The antibody production market in the U.S. held the largest share in the North America region in 2025. The U.S. antibody production market is growing rapidly, supported by advanced biopharmaceutical infrastructure, substantial R&D investments, high adoption of cutting-edge production technologies, and strong demand for therapeutic and diagnostic antibodies. Additionally, favorable regulatory frameworks and the presence of leading global players further drive market expansion, positioning the U.S. as a key hub in the global antibody production landscape.
Europe Antibody Production Market Trends
The European antibody production industry is driven by strong R&D capabilities, government support for biopharmaceutical innovation, and the presence of leading pharmaceutical and biotechnology companies. High adoption of advanced production technologies, growing investments in antibody-based therapeutics, and increasing demand for diagnostics further fuel market growth. In addition, collaborations between industry players and research institutions are accelerating innovation, enabling Europe to maintain a competitive position in the global antibody production market.
The UK antibody production market is supported by a strong biopharmaceutical ecosystem, robust R&D infrastructure, and significant investments in antibody therapeutics and diagnostics. High adoption of advanced manufacturing technologies, favorable government policies, and active collaborations between academia and industry further drive market growth, positioning the UK as a key contributor to Europe’s antibody production landscape.
Antibody production market in Germany is expanding steadily, fueled by the country’s strong pharmaceutical and biotechnology infrastructure, advanced R&D capabilities, and significant investments in antibody-based therapeutics. High adoption of innovative production technologies, government support for biopharma innovation, and strategic collaborations with research institutions further drive market growth, reinforcing Germany’s leadership in the European antibody production landscape.
Asia Pacific Antibody Production Market Trends
The Asia Pacific antibody production market is projected to grow at a robust CAGR of 13.5% over the forecast period, driven by expanding biopharmaceutical manufacturing capabilities, rising investments in R&D, and increasing demand for therapeutic and diagnostic antibodies. Rapidly growing healthcare infrastructure, adoption of advanced production technologies, and supportive government initiatives further contribute to market growth. Additionally, collaborations between local and global players are accelerating innovation and production efficiency, positioning the region as a key emerging hub in the global antibody production landscape.
The China antibody production market is experiencing rapid growth, supported by expanding biopharmaceutical infrastructure, substantial R&D investments, and increasing demand for therapeutic and diagnostic antibodies. Government incentives, adoption of advanced manufacturing technologies, and collaborations between domestic and international companies further drive market expansion, positioning China as a major player in the Asia Pacific antibody production landscape.
Antibody production market in Japan is driven by advanced biopharmaceutical infrastructure, strong R&D capabilities, and significant investments in antibody-based therapeutics and diagnostics. High adoption of innovative production technologies, government support for healthcare innovation, and collaborations between industry and research institutions further propel market growth, positioning Japan as a key player in the Asia Pacific antibody production landscape.
MEA Antibody Production Market Trends
The Middle East & Africa antibody production industry is developing steadily, driven by increasing healthcare investments, rising demand for therapeutic and diagnostic antibodies, and growing biopharmaceutical infrastructure. Governments in the region are supporting innovation through favorable policies and funding initiatives. Additionally, collaborations with global pharmaceutical and biotechnology companies are enhancing local production capabilities, enabling the region to expand its presence in the global antibody production market. Rising awareness of advanced healthcare solutions and adoption of modern manufacturing technologies further contribute to the sector’s growth in the coming years.
The Kuwait antibody production market is at an early stage, supported by growing healthcare infrastructure, increasing investments in biopharmaceutical R&D, and rising demand for therapeutic and diagnostic antibodies. Government initiatives to promote advanced healthcare solutions, coupled with collaborations with international biopharma companies, are further fostering the development of local antibody production capabilities.
Key Antibody Production Company Insights
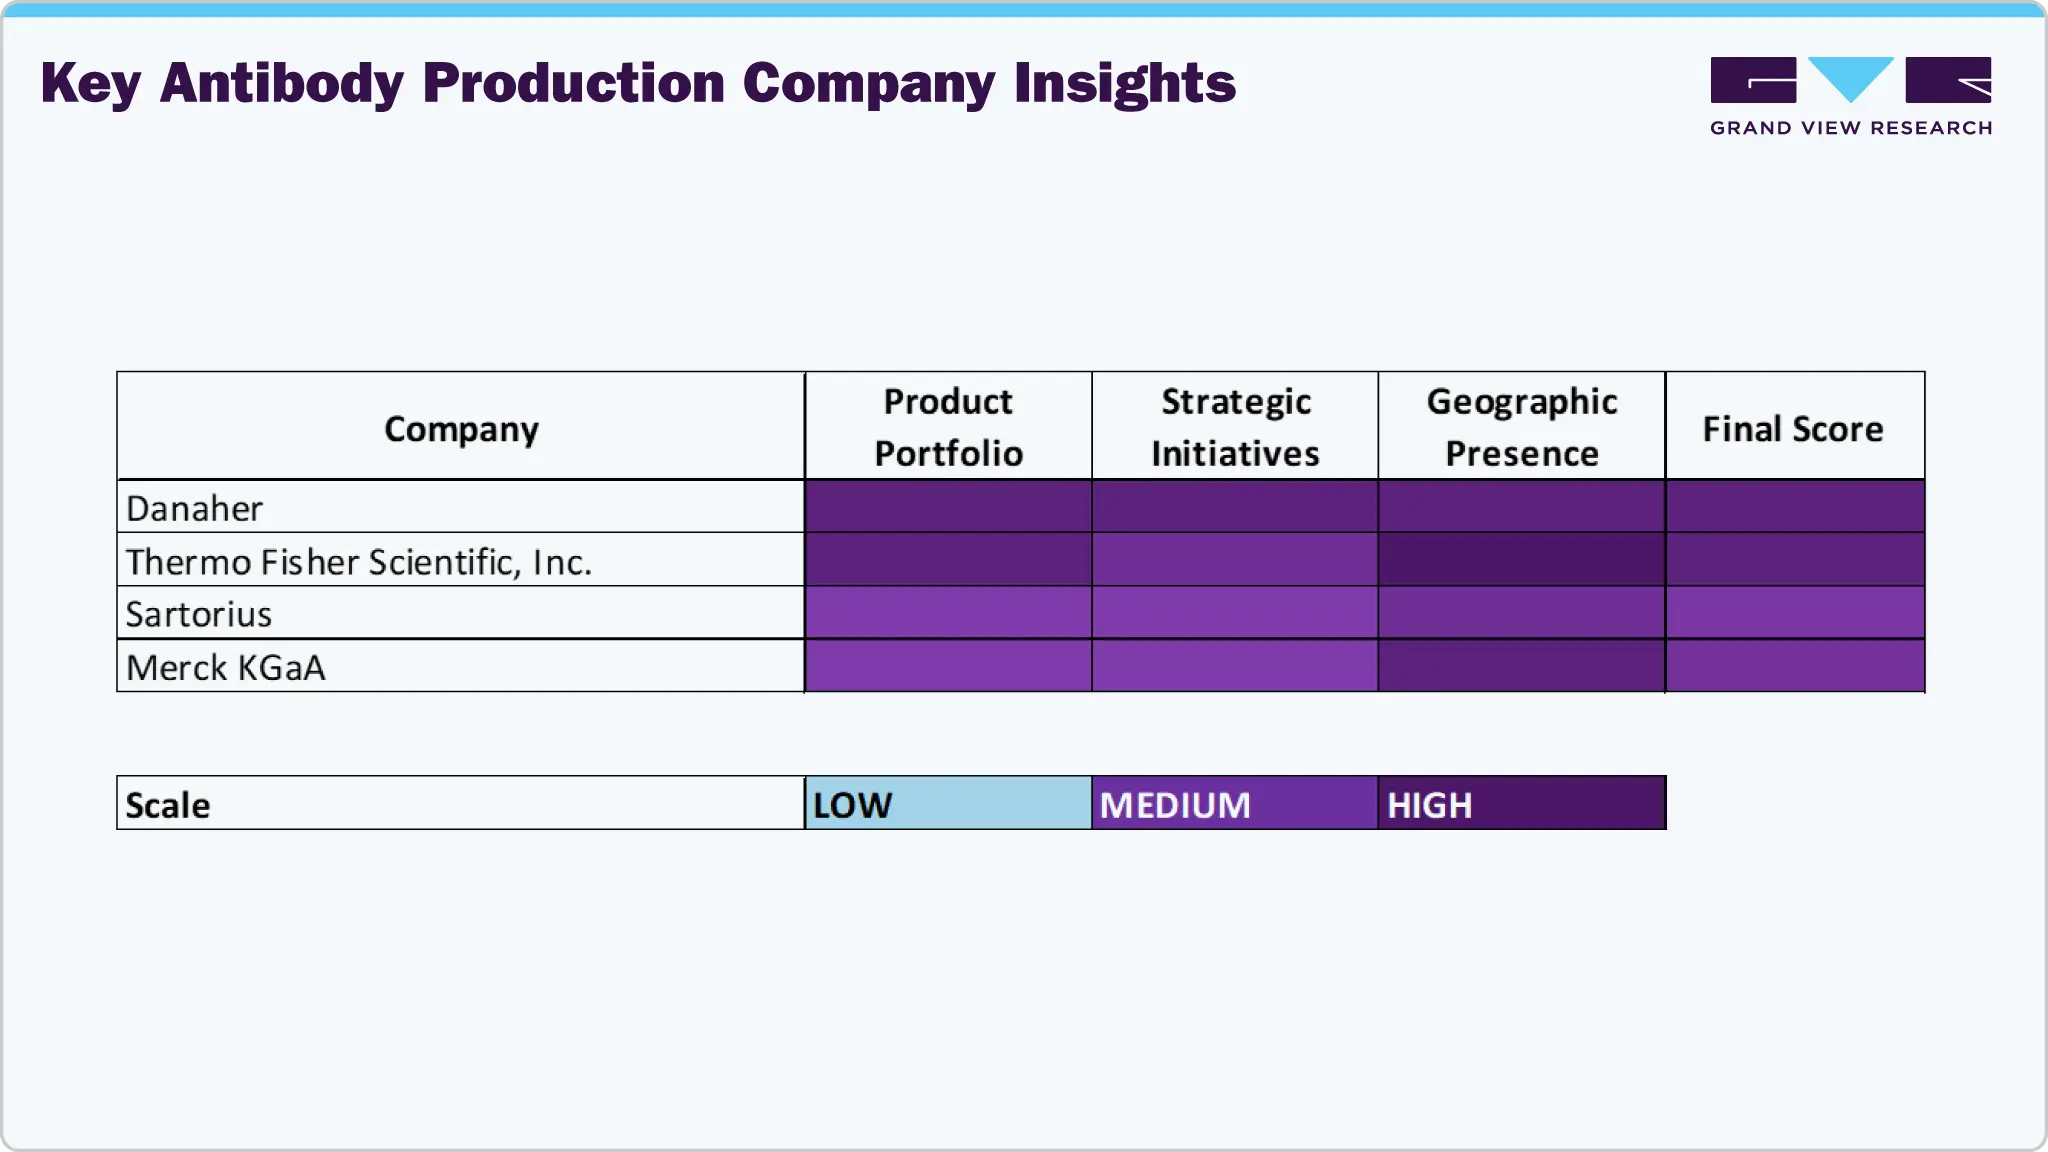
The global antibody production market is highly competitive, with several leading biopharmaceutical companies driving innovation and capturing significant market share. Key players include Danaher, Merck KGaA, Thermo Fisher Scientific, Eppendorf, and Sartorius, among others. These companies leverage advanced technologies, strong R&D capabilities, and extensive global manufacturing networks to maintain leadership. Danaher and Thermo Fisher Scientific, for example, are recognized for their high-throughput antibody production platforms and consumables, while Merck KGaA and Sartorius focus on providing integrated solutions for both upstream and downstream processes. Eppendorf contributes specialized instruments that optimize production efficiency and scalability.
In addition to the established players, several other companies are expanding their footprint through strategic partnerships, acquisitions, and innovative product launches. Lonza Group, AGC Biologics, Wuxi Biologics, Charles River Laboratories, and Abcam are notable players providing contract development and manufacturing services, high-quality antibodies, and cutting-edge discovery platforms. These companies are increasingly leveraging automation, AI-driven technologies, and single-use systems to streamline antibody development and production, enabling faster timelines and reduced costs. Emerging players like Biointron and Creative Biolabs are also contributing to market dynamism by introducing high-throughput and fully human antibody discovery platforms.
 To learn more about this report, Download Free Sample Report
Regional market presence further influences market share distribution. North America dominates globally, supported by robust R&D infrastructure, strong regulatory frameworks, and the presence of major biopharmaceutical companies. Europe, led by Germany, the UK, and France, benefits from advanced research capabilities, collaborations between industry and academia, and adoption of innovative production technologies. Asia Pacific, particularly China and Japan, is witnessing rapid growth due to expanding biopharma infrastructure, government support, and increasing demand for therapeutic and diagnostic antibodies. The Middle East & Africa markets are at nascent stages but developing steadily, driven by healthcare investments and international collaborations. Overall, market leadership is shaped by technological innovation, strategic expansion, and regional penetration, defining the competitive landscape of the antibody production industry.
Key Antibody Production Companies:
The following key companies have been profiled for this study on the antibody production market.
-
Danaher Corporation
-
Sartorius
-
Thermo Fisher Scientific
-
Eppendorf
-
Merck KGaA
-
Lonza Group
-
AGC Biologics
-
Wuxi Biologics
-
Charles River Laboratories
-
Biointron
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Danaher Corporation, Sartorius, Thermo Fisher Scientific, Eppendorf, Merck KGaA, Lonza Group)
- Focus on providing integrated antibody production solutions spanning cell line development, upstream and downstream bioprocessing, analytical testing, automation, and manufacturing support. Expand market presence through strategic acquisitions, bioprocessing technology innovation, and partnerships with pharmaceutical and biotechnology companies. Invest heavily in scalable manufacturing platforms, single-use technologies, and digital bioprocessing solutions.
- Strong global distribution networks, comprehensive product portfolios, extensive regulatory expertise, and long-standing relationships with major biopharmaceutical companies. Ability to offer end-to-end solutions across antibody discovery, development, and commercial manufacturing creates significant customer retention and recurring revenue opportunities.
- High operational and infrastructure costs, complex organizational structures, and slower responsiveness to highly specialized or niche customer requirements. Exposure to pricing pressures in mature bioprocessing segments and lengthy product validation cycles.
Specialized CDMOs & Emerging Players (e.g., AGC Biologics, WuXi Biologics, Charles River Laboratories, Biointron)
- Focus on contract antibody discovery, development, cell line generation, process optimization, and commercial manufacturing services. Emphasize rapid project execution, flexible capacity expansion, customized solutions, and support for emerging biopharma companies. Invest in advanced expression platforms, high-throughput screening technologies, and global manufacturing footprints.
- High flexibility, specialized expertise in antibody development and manufacturing, faster turnaround times, and strong capabilities in supporting clinical-stage and emerging biologics programs. Ability to provide cost-efficient outsourced services enables clients to reduce capital expenditures and accelerate time-to-market.
- Dependence on project-based revenues and client pipelines, exposure to capacity utilization fluctuations, and increasing competition among global CDMOs. Limited diversification compared to large life science conglomerates and potential regulatory risks associated with multi-client manufacturing operations.
Recent Developments
-
In June 2026, Bio’Techne Corporation and Refeyn had announced a workflow that combined imaged capillary isoelectric focusing fractionation with mass photometry technology for analyzing charge and size variants in bispecific antibodies and biosimilars.
-
In August 2025, Zifo launched an AI-powered Antibody Engineering app on the Snowflake Marketplace, enabling faster design, optimization, and analysis of therapeutic antibodies, directly supporting efficiency and innovation in the global antibody production market.
-
In March 2025, Biointron launched AbDrop, a high-throughput platform for rapid discovery of fully human antibodies, enhancing efficiency and innovation in the global antibody production market.
Antibody Production Market Report Scope
Report Attribute
Details
Market size in 2025
USD 17.0 billion
Estimated market size in 2026
USD 18.8 billion
Projected market size by 2033
USD 39.8 billion
Growth rate
CAGR of 11.3% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, process, type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Danaher Corporation; Sartorius; Thermo Fisher Scientific; Eppendorf; Merck KGaA; Lonza Group; AGC Biologics; Wuxi Biologics; Charles River Laboratories; Biointron
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Antibody Production Market Report Segmentation
This report forecasts revenue growth and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global antibody production market based on product, process, type, end use, and region.
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Instruments
-
Bioreactors
-
Multi-use Bioreactors
-
Single-use bioreactors
-
-
Chromatography systems
-
Filtration systems
-
-
Consumables
-
Media
-
Buffers and reagents
-
Chromatography resins and columns
-
Filtration consumables and accessories
-
Others
-
Software
-
-
-
Process Outlook (Revenue, USD Million, 2021 - 2033)
-
Upstream Processing
-
Downstream Processing
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Monoclonal Antibody
-
Polyclonal Antibody
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceutical and biotechnology companies
-
Research laboratories
-
CROs and CDMOs
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
Segment Definition
Segment - Product
Revenue capture definition
Instruments
Revenue is generated through the sale of bioreactors, fermenters, cell culture systems, chromatography systems, filtration equipment, automated liquid handling platforms, and analytical instruments used throughout antibody development, production, purification, and quality control processes.
Consumables
Revenue is captured from recurring purchases of cell culture media, reagents, purification resins, filters, assay kits, buffers, disposable bioprocessing components, and other consumables required for antibody production workflows. This segment benefits from continuous demand throughout research, development, and commercial manufacturing cycles.
Software
Revenue is derived from bioprocess management software, laboratory information management systems (LIMS), process analytics platforms, automation software, and data management solutions that support antibody production optimization, quality assurance, and regulatory compliance.
Segment - Process
Revenue capture definition
Upstream Processing
Revenue is generated from technologies, equipment, consumables, and services associated with cell line development, media preparation, cell culture expansion, transfection, and bioreactor-based antibody expression. Demand is driven by efforts to improve antibody yield, productivity, and process scalability.
Downstream Processing
Revenue is captured through purification, filtration, chromatography, viral clearance, formulation, and quality testing solutions used to isolate and refine antibodies for research and therapeutic applications. This segment represents a critical component of manufacturing costs and regulatory compliance.
Segment - Type
Revenue capture definition
Polyclonal Antibody
Revenue is derived from the production and commercialization of polyclonal antibodies used in research, diagnostics, and selected therapeutic applications. Demand is supported by their ability to recognize multiple epitopes, making them valuable in immunoassays and laboratory research.
Monoclonal Antibody
Revenue is generated through the development and manufacturing of monoclonal antibodies for therapeutic, diagnostic, and research applications. This segment represents the largest revenue contributor due to extensive use in oncology, autoimmune diseases, infectious diseases, and targeted biologic therapies.
Segment - End-use
Revenue capture definition
Pharmaceutical and
Biotechnology Companies
Revenue is captured through procurement of antibody production systems, consumables, software, and outsourced manufacturing services by pharmaceutical and biotechnology companies engaged in biologics discovery, development, clinical trials, and commercial-scale production.
Research Laboratories
Revenue is generated from academic institutions, government laboratories, and private research organizations utilizing antibody production technologies for basic research, translational medicine, biomarker discovery, and preclinical studies.
CROs and CDMOs
Revenue is derived from contract research organizations (CROs) and contract development and manufacturing organizations (CDMOs) investing in antibody production capabilities to provide outsourced discovery, development, process optimization, scale-up, and manufacturing services to biopharmaceutical clients.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Antibody Production Market Landscape & Technology Adoption Analysis
Developed a tailored assessment of the global antibody production market across product (instruments, consumables, software), process (upstream and downstream), type (monoclonal and polyclonal antibodies), and end-user segments. The analysis also evaluates adoption trends in biopharmaceutical manufacturing, clinical development, and research applications, with emphasis on single-use technologies, high-yield expression systems, and automation-driven bioprocessing platforms.
Enables stakeholders to understand evolving antibody production workflows, identify high-growth monoclonal antibody manufacturing demand, evaluate shift toward single-use and automated bioprocessing systems, and assess expansion opportunities across biologics development and commercial manufacturing ecosystems.
Competitive Landscape & CDMO Capability Benchmarking Assessment
Delivered a customized benchmarking of leading antibody production solution providers and CDMOs, including analysis of upstream and downstream capabilities, cell line development platforms, bioreactor technologies, purification systems, and scalability of manufacturing operations. The study also evaluates integration of digital bioprocessing tools and regulatory compliance readiness.
Provides actionable insights into competitive positioning, manufacturing capabilities, technology differentiation, and outsourcing trends, helping clients identify partnership opportunities, optimize sourcing strategies, and strengthen positioning in biologics development and production value chains.
Capacity Expansion & Outsourcing Opportunity Assessment in Biologics Manufacturing
Conducted a focused evaluation of global antibody production capacity expansion trends, including rising outsourcing to CDMOs, increasing demand for monoclonal antibodies, and investments in large-scale biomanufacturing infrastructure. The analysis also assessed regional manufacturing hubs, supply chain resilience, and scalability constraints in upstream and downstream processing.
Supports strategic decision-making by identifying high-growth outsourcing opportunities, optimizing manufacturing capacity planning, reducing production bottlenecks, and strengthening long-term investment strategies in biologics and antibody-based therapeutics.
Frequently Asked Questions About This Report
The global antibody production market size was valued at USD 17.0 billion in 2025 and and is expected to reach USD 18.8 billion in 2026.
The global antibody production market is expected to grow at a compound annual growth rate of 11.3% from 2026 to 2033 to reach USD 39.8 billion by 2033.
Downstream processing dominated the antibody production market, with a share of 67.5% in 2025. This is attributable to various technological advancements supporting the downstream process to maintain efficiency. This fuels innovations in bio-manufacturing and hence increases the demand for the process in the antibody production market.
Some of the key players operating in the antibody production market include Danaher Corporation; Sartorius; Thermo Fisher Scientific; Eppendorf; Merck KGaA; Lonza Group; AGC Biologics; Wuxi Biologics; Charles River Laboratories; Biointron.
Major factors driving market growth include the rising incidence of chronic illnesses such as cancer, diabetes, and cardiovascular diseases, as well as the increased need for therapeutic antibodies the antibody production market is anticipated a significant growth.
North America dominated the antibody production market with the largest revenue share of 37.5% in 2025
pharmaceutical & biotechnology companies segment led the market with the largest revenue share of 55.3% in 2025
consumables segment led the market with the largest revenue share of 55.9% in 2025.
monoclonal antibody segment led the market with the largest revenue share of 63.8% in 2025
About the Author(s)
Biotechnology Research Team
Healthcare · BiotechnologyThis report was authored by the biotechnology research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the biotechnology segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


