
- Home
- »
- Digital Media
- »
-
Asia Pacific Creator Economy Market Size Report 2026-2033GVR Report cover
![Asia Pacific Creator Economy Market (2026 - 2033)Report]()
Asia Pacific Creator Economy Market (2026 - 2033)
Size, Share & Trends Analysis Report By Platform (Video, Blogging, Podcasting), By Creative Service, By Revenue Channel, By End Use, By Country, And Segment Forecasts
Market Size, 2025
$65.7BMarket Estimate, 2026
$84.3BMarket Forecast, 2033
$498.0BCAGR, 2026–2033
28.9%Asia Pacific Creator Economy Market Summary
The Asia Pacific creator economy market size was valued at USD 65.7 billion in 2025 and is projected to grow from USD 84.3 billion in 2026 to USD 498.0 billion by 2033, at a CAGR of 28.9% from 2026 to 2033. The rapid growth is driven by increasing internet and social media penetration, which is increasing digital content consumption and encouraging more content creation. Growing opportunities to create, distribute, and monetize digital content are further supporting the market.
Key Market Trends & Insights
- By platform: Video streaming segment led the market and held the largest revenue share of 52.0% in 2025.
- By creative service: Photography & videography segment held the dominant position in the market and accounted for a revenue share of 43.8% in 2025.
- By revenue channel: Subscriptions segment is expected to grow at the fastest CAGR of 38.5% from 2026 to 2033.
- By end use: Individual content creators segment dominated the market and accounted for a revenue share of 57.5% in 2025.
Market Size & Forecast
- Market size in 2025: USD 65.7 Billion
- Estimated market size in 2026: USD 84.3 Billion
- Projected market size by 2033: USD 498.0 billion
- CAGR (2026-2033): 28.9%
Three ways to get this report
Buy it, customize it, or ask a question.Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
The Asia Pacific region is adopting AI-powered content creation tools to improve the speed and efficiency of digital content production. These tools allow creators to generate content from simple inputs, reducing the time and effort required for traditional content creation. The growing availability of customizable AI tools is enabling creators to produce content tailored to different audiences and platforms. This is encouraging more creators and businesses to integrate AI into their content-production workflows. For instance, in February 2025, Amazon Web Services, Inc. launched Amazon Nova Creative Models in Asia Pacific, enabling AI-powered image and video generation from text and image inputs. The models support content creators, marketers, and developers with customizable visual content and built-in responsible AI controls.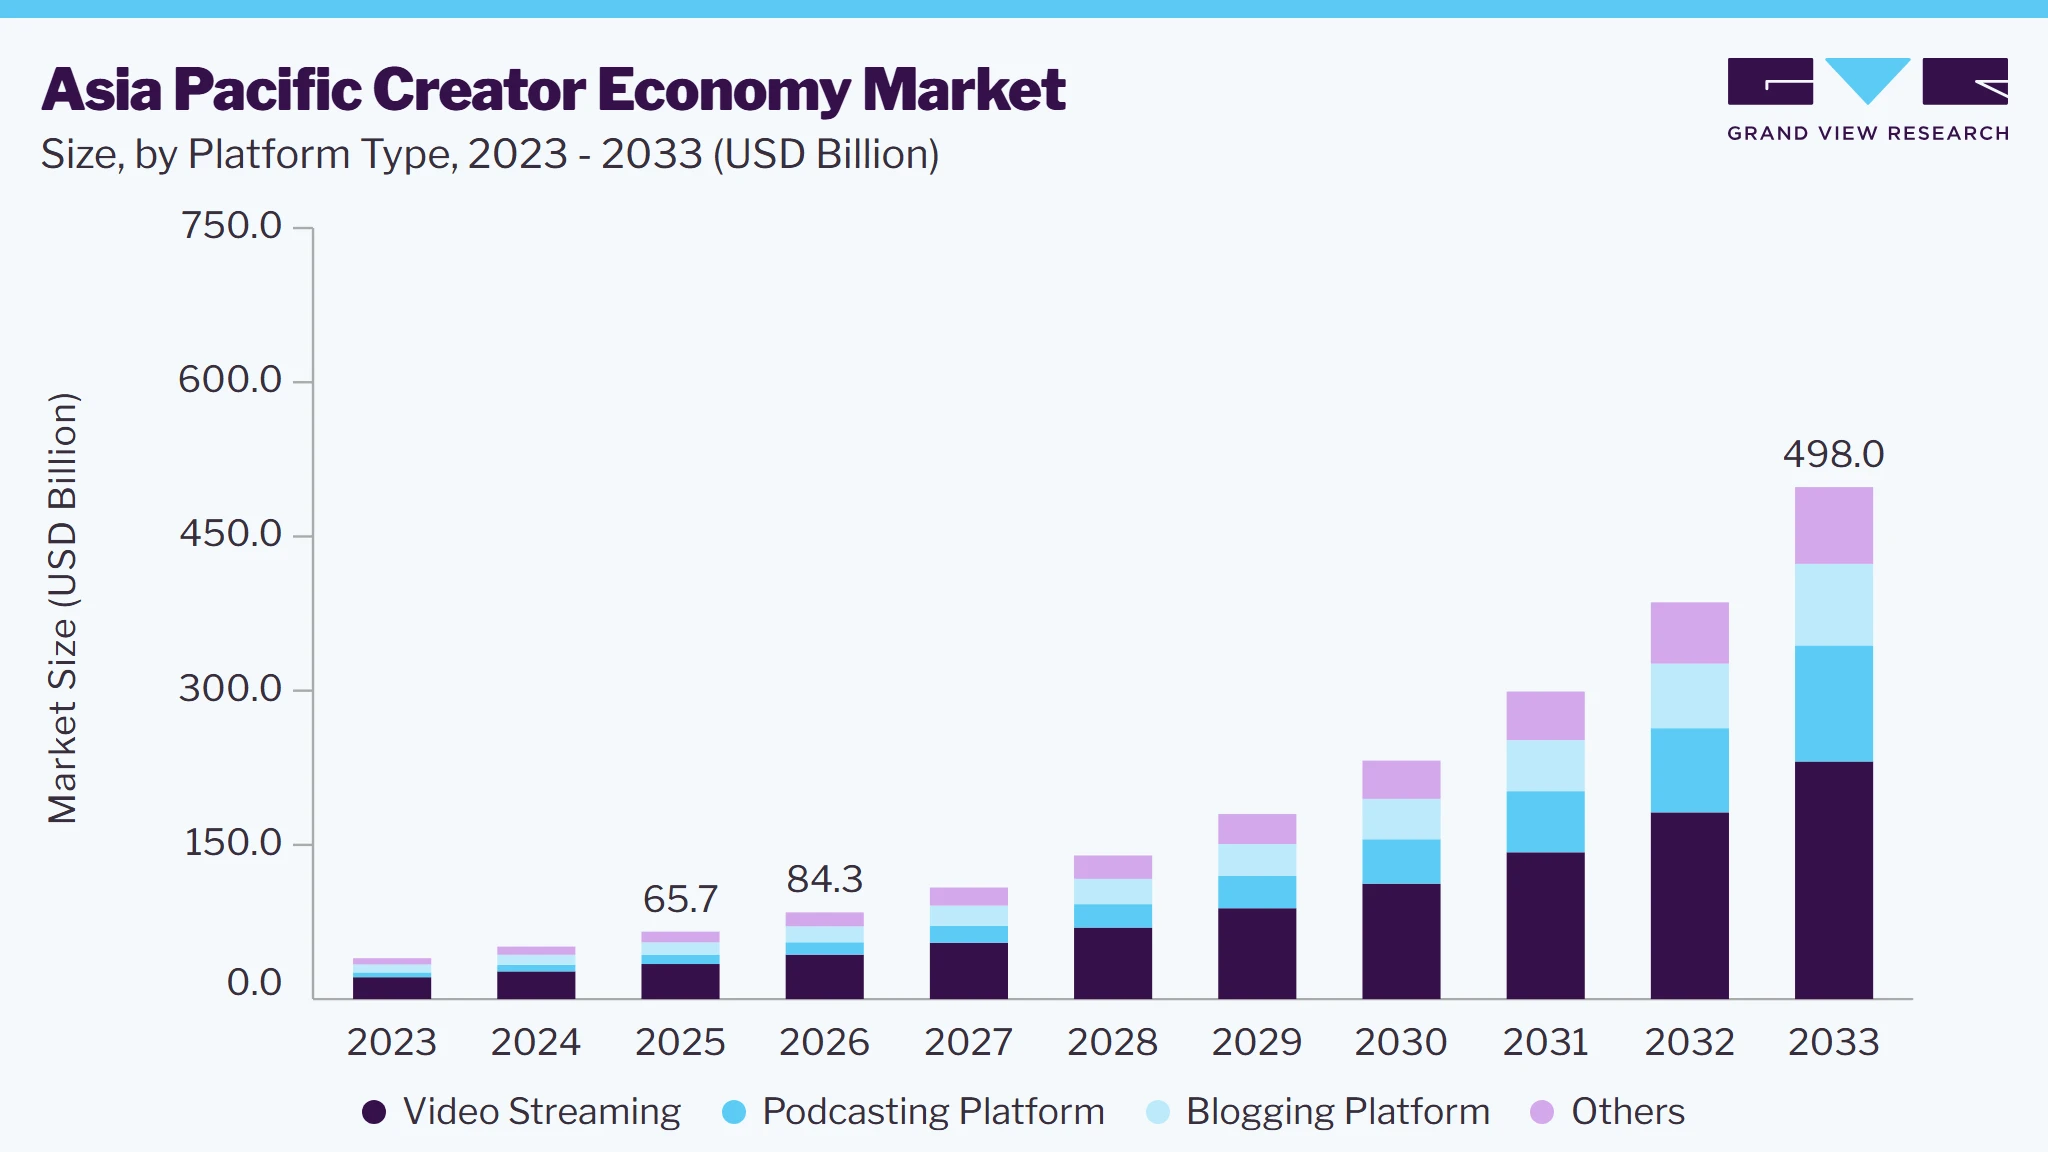
The growing use of AI is also enabling platforms to offer new and interactive content formats, creating more opportunities for creators to engage audiences. As platforms combine content creation, distribution, engagement, and monetization, AI is becoming an important part of the creator ecosystem. For instance, in June 2026, ByteDance, a technology company and the parent company of TikTok, introduced native Mini Dramas and Mini Games on TikTok in Southeast Asia, while also integrating AI-powered creative tools to support content creation and monetization. This development highlights the growing integration of AI within creator platforms and is expected to further support the expansion of the Asia Pacific creator economy.
The industry is also witnessing the growing adoption of virtual influencers and digital avatars across social media and digital entertainment platforms. These digital personalities are being used by brands and creators to develop distinctive and engaging online identities. Virtual influencers allow brands to maintain consistent digital personas while interacting with audiences across multiple platforms. The growing popularity of immersive digital experiences further supports the use of avatars in creator-led content. Virtual creators are also gaining traction in gaming, fashion, entertainment, and digital marketing applications. Brands are collaborating with virtual influencers to reach younger and digitally engaged audiences. The expansion of social media platforms and creator-focused digital ecosystems is creating more opportunities for virtual personalities to attract followers and generate engagement. This trend is expected to support the diversification of content formats and contribute to the continued growth of the Asia Pacific creator economy.
Market Dynamics
The industry is evolving rapidly as digital platforms continue to expand their creator-focused ecosystems. Creators are using multiple platforms and content formats to reach and engage diverse audiences. The market is becoming more commercially oriented as creators, brands, and platforms develop stronger connections. Growing audience participation and changing digital consumption patterns are influencing the overall structure of the creator ecosystem. The market is moving toward a more diverse, professional, and integrated digital creator landscape.
The region is experiencing rapid growth in social media users, expanding the potential audience available to digital creators. Increasing access to social networking platforms is encouraging more people to consume and interact with creator-generated content. Social media has become an important channel for entertainment, communication, information, and product discovery across the region. The growing user base is providing creators with larger and more diverse audiences to target. Higher levels of audience engagement are also creating greater opportunities for creators to build communities around their content.
The expansion of social media usage is also increasing the number of potential participants in the creator ecosystem. Individuals can use established platforms to publish content and reach audiences without requiring traditional media infrastructure. This accessibility is encouraging more users to experiment with content creation across different formats. The growing number of active users is also increasing competition for audience attention among creators. Platforms are continuously introducing features that encourage users to create, share, and engage with content. Consequently, continued social media user growth is contributing to a broader and more active creator ecosystem across Asia Pacific.
The industry is facing increasing content saturation as more individuals and businesses enter digital content platforms. The growing number of creators is making it more difficult for individual creators to attract and retain audience attention. Creators are competing across multiple platforms for visibility, engagement, and follower growth. This competition can increase the effort required to consistently produce content that stands out in crowded digital environments. Smaller creators may find it challenging to build a stable audience without sufficient resources, experience, or platform visibility. As competition continues to increase, content saturation may limit the growth potential of individual creators across the region.
The availability of large volumes of creator-generated content is also influencing audience consumption patterns. Users have access to a wide variety of content, making audience attention fragmented across platforms and creators. Creators may therefore need to maintain consistent engagement to remain visible within rapidly changing digital environments. Frequent changes in audience preferences can further increase the pressure on creators to adapt their content strategies. This environment can make audience retention and long-term creator sustainability more challenging.
The growing integration of content and online shopping presents significant opportunities for creators across the Asia Pacific region. Social platforms are enabling creators to connect audiences with products and services through digital content. Creators can influence purchasing decisions by providing product demonstrations, reviews, recommendations, and interactive content. This creates opportunities for creators to generate income through affiliate sales, commissions, sponsorships, and direct product promotions. Businesses can also use creator communities to reach specific consumer segments in a more targeted manner. The expansion of creator-led commerce is therefore creating new pathways for revenue generation within the creator economy.
The growing adoption of digital payments and e-commerce platforms is further supporting the development of creator-led commerce. Creators can connect content discovery with purchasing activities within digital environments. This integration can shorten the path between audience engagement and consumer transactions. Local creators can also promote products that are tailored to regional preferences, languages, and cultural interests. As social platforms continue to develop commerce-related features, opportunities for creators to participate in digital retail ecosystems are expected to increase. This trend can further strengthen the commercial potential.
Market Concentration & Characteristics
The market is moderately concentrated, with a mix of large digital platforms and independent creators. Major platforms maintain substantial audience reach and influence over content distribution. These platforms also play an important role in creator engagement and monetization. At the same time, numerous regional platforms serve specific markets and audience groups. Agencies and individual creators further contribute to the diversity of the competitive landscape. This combination creates a market structure that includes both established platforms and emerging participants.
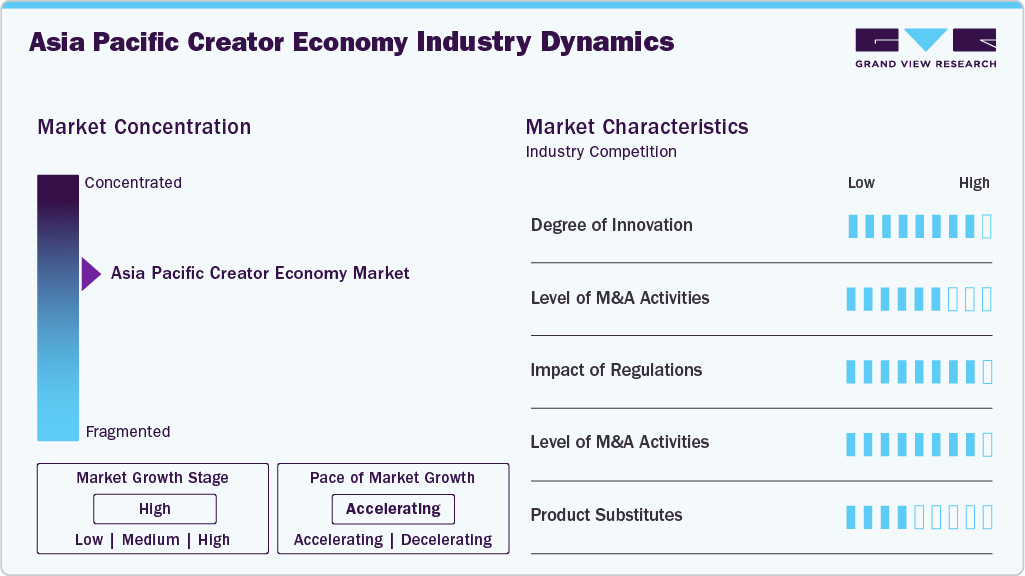
The large number of independent creators reduces concentration at the individual creator level. Creators operate across diverse content categories, including entertainment, gaming, lifestyle, education, and short-form video. Regional platforms also compete by offering localized content and monetization opportunities. However, leading platforms retain strong positions due to their extensive user bases and established digital ecosystems. Their scale provides advantages in audience acquisition, content distribution, and creator monetization. Overall, the market remains moderately concentrated, with competition distributed across major platforms and a broad creator base.
Analyst Perspective
The market is evolving rapidly as digital platforms are being integrated into everyday content consumption and communication. Platforms are also broadening their creator ecosystems by introducing new content formats, engagement features, and monetization opportunities. Changing audience preferences are encouraging creators to experiment with diverse formats and build more specialized communities. Businesses are increasingly engaging with creators as part of their digital marketing and customer engagement strategies.
Platform Insights
The video streaming segment led the market and accounted for 52.0% of the revenue in 2025, supported by the growing consumption of digital video content. Increasing smartphone and internet penetration is expanding access to video streaming platforms. The availability of diverse content across entertainment, education, gaming, and lifestyle categories is attracting a broader audience. Rising demand for convenient and on-demand content is further supporting segment growth. Continued expansion of streaming platforms and digital content consumption is expected to strengthen the position of the segment.
The podcasting platform segment is growing steadily as consumers seek convenient and on-demand audio content. The availability of podcasts across diverse topics is attracting a wider range of listeners. Increasing smartphone usage is making podcast content more accessible to audiences across the region. Creators are also using podcasting platforms to build dedicated communities and strengthen audience engagement. Continued expansion of digital audio consumption is expected to support the growth of the segment.
Creative Service Insights
The photography & videography segment dominated the market in 2025, supported by the growing popularity of visual content across digital platforms. Increasing smartphone adoption is enabling more individuals to create and share high-quality photos and videos. The expansion of social media and short-form video platforms is further increasing demand for visual content. Growing creator participation in lifestyle, travel, fashion, and product-related content is supporting segment growth. Continued audience preference for engaging and visually rich content is expected to strengthen the photography & videography segment.
The music production segment is growing as digital platforms provide creators with greater opportunities to produce, distribute, and monetize original music. Increasing consumption of digital music is expanding the audience base for independent and emerging artists. Social media platforms are also enabling creators to promote music and reach audiences directly. The availability of accessible music production and distribution platforms is encouraging more individuals to enter the segment. Growing demand for original and creator-led music content is expected to support the continued growth of the music production segment.
Revenue Channel Insights
The advertising segment dominated the market in 2025, supported by increasing investment in digital advertising. Growing brand participation across social media platforms is creating greater demand for creator-led advertising campaigns. Creators provide brands with access to targeted and engaged audiences across diverse content categories. The expansion of influencer marketing is further supporting advertising activity within the creator ecosystem. Continued digitalization of marketing activities is expected to maintain the strong position of the advertising segment.
The subscriptions segment is growing as creators adopt recurring revenue models to monetize their audiences. Subscription-based offerings allow creators to provide exclusive content, communities, and personalized experiences to paying followers. Growing audience willingness to support creators directly is creating opportunities for more sustainable revenue generation. Digital platforms are also expanding subscription features, making these models more accessible to creators. Increasing adoption of recurring monetization models is expected to support the continued growth of this segment.
End Use Insights
The individual content creators segment dominated the market in 2025, supported by the growing participation of individuals in digital content creation. Social media platforms are providing creators with accessible channels to produce, publish, and distribute content. The increasing popularity of creator-led content is helping individuals build large and engaged audiences. Growing opportunities for monetization are also encouraging more individuals to pursue content creation as a source of income. Continued expansion of digital platforms is expected to maintain the strong position of individual content creators.
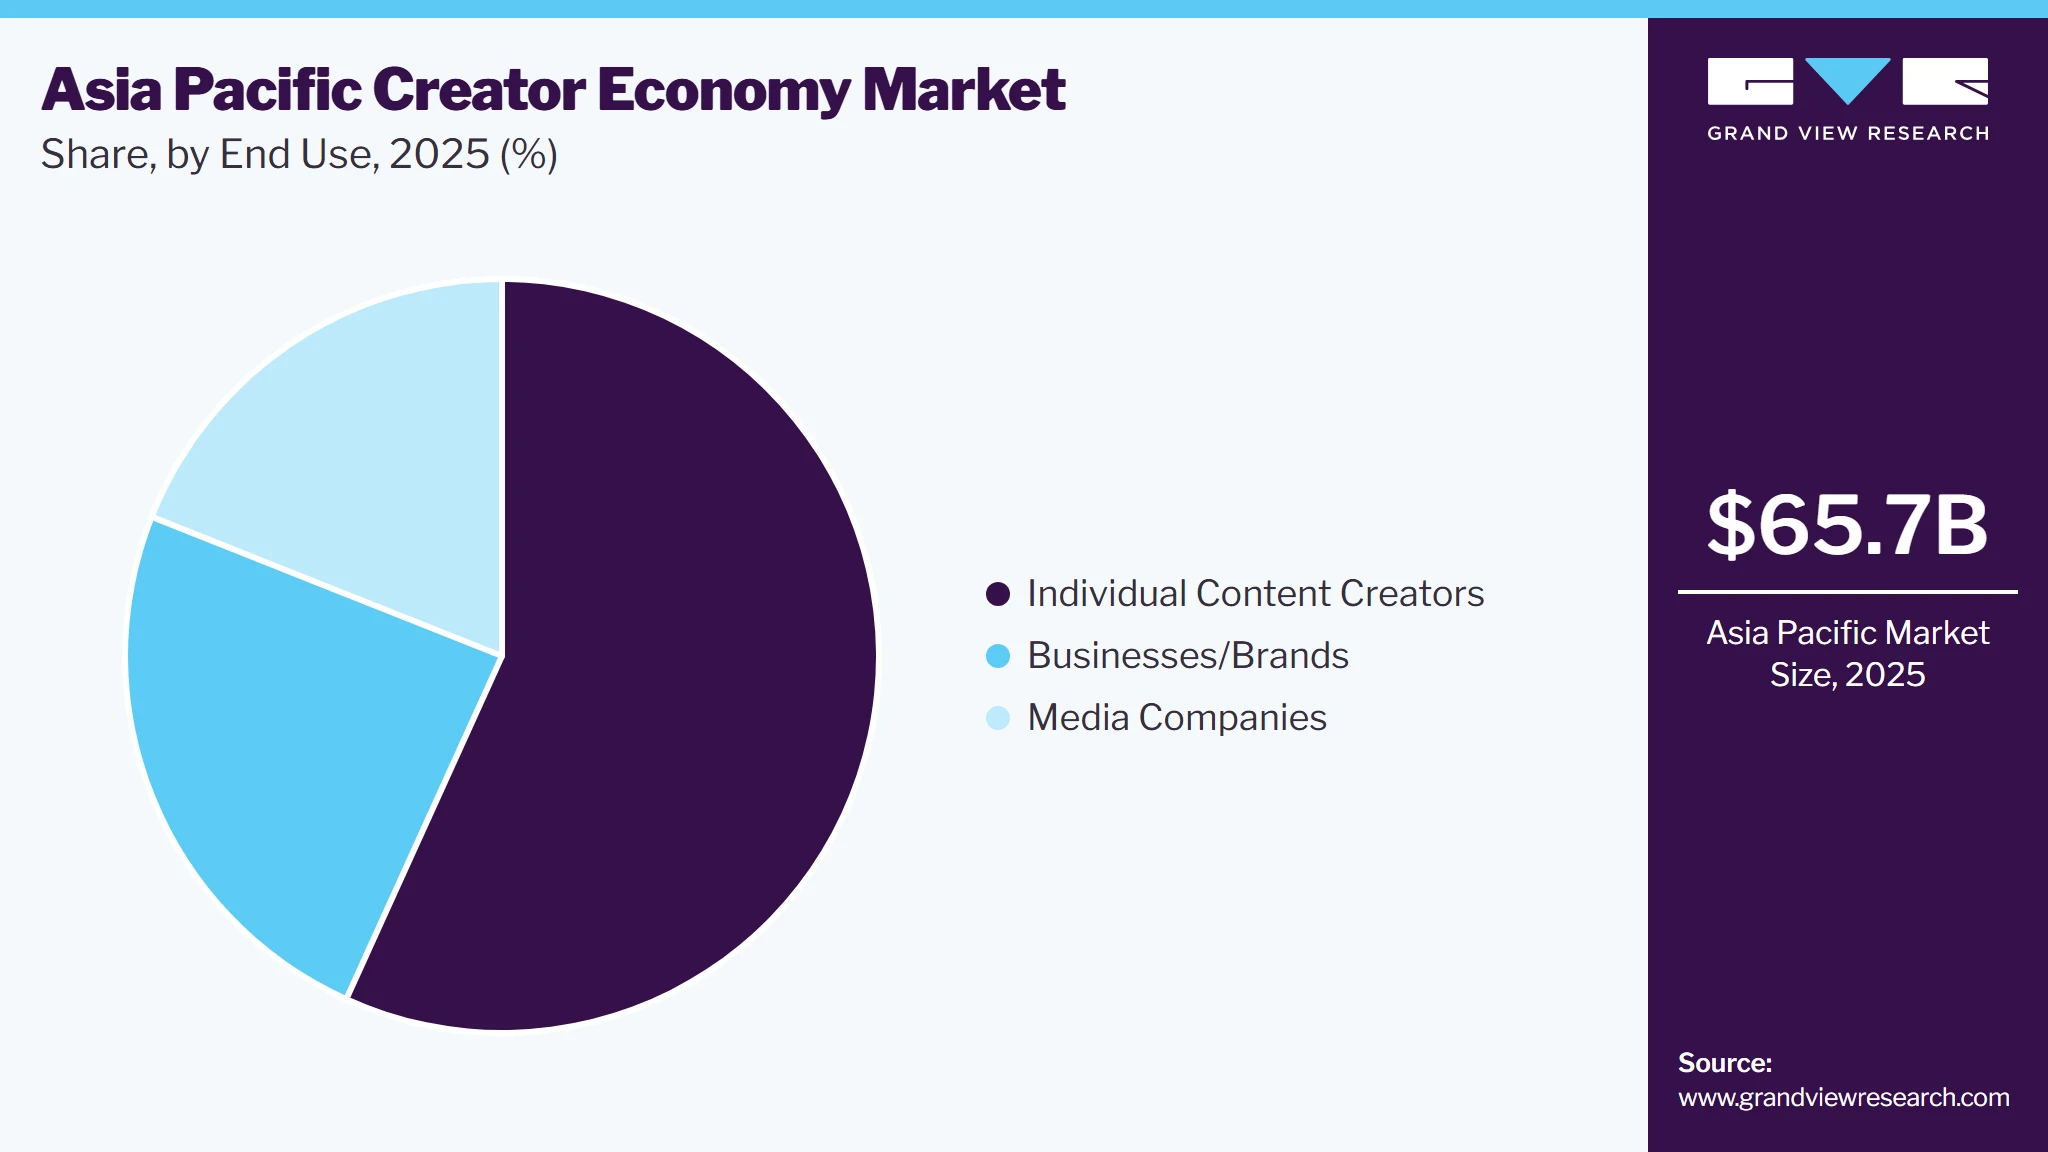
The businesses/brands segment is growing as companies use creator ecosystems to strengthen their digital presence and audience engagement. Brands are collaborating with creators to promote products and services across various digital platforms. Creator-led campaigns can help businesses reach targeted audiences through relevant and engaging content. The increasing importance of digital marketing is encouraging more businesses to participate in the creator economy. Growing adoption of creator-based marketing strategies is expected to support the expansion of the segment.
Country Insights
The China creator economy market dominated Asia Pacific in 2025, accounting for 29.9% revenue share. The country has a large and active digital audience, supporting strong demand for creator-generated content. The widespread use of social media and digital entertainment platforms is providing creators with broad opportunities to reach audiences. The growing participation of brands and businesses in digital content is further supporting the creator ecosystem. China is expected to remain an important market within the Asia Pacific over the forecast period.
India Creator Economy Market Trends
The creator economy market in India is expected to be the fastest-growing market in Asia Pacific during the forecast period. This growth is supported by increasing digital adoption and the expanding use of social media platforms. Rising smartphone and internet penetration are enabling more consumers to access creator-generated content. The growing participation of individual creators and businesses is further expanding the creator ecosystem in India. Increasing opportunities for content monetization are also encouraging more creators to enter the market.
Key Asia Pacific Creator Economy Company Insights
Some key companies in the Asia Pacific creator economy industry are ByteDance, Kuaishou Technology, Bilibili Inc., Tencent, Kakao Corp.
-
Kuaishou Technology is strengthening its presence through its short-video and live-streaming ecosystem. The company provides creators with tools to produce, distribute, and monetize digital content. Its platform enables creators to engage audiences through short-form videos, live streams, and interactive content formats. Kuaishou also supports creator monetization through advertising, virtual gifting, and other commercial activities. Its strong focus on creator engagement helps expand opportunities for individual content creators and businesses.
-
Meta Platforms, Inc. participates in the industry through platforms such as Instagram and Facebook. The company provides creators with tools for content creation, audience engagement, and digital monetization. Instagram, in particular, has become an important platform for creators across lifestyle, entertainment, fashion, and other content categories. Meta supports creator monetization through advertising, subscriptions, branded content, and other platform-based features. Its large user base provides creators with opportunities to reach diverse audiences across the region.
Key Asia Pacific Creator Economy Companies
-
ByteDance
-
Kuaishou Technology
-
Bilibili Inc.
-
Tencent
-
Kakao Corp.
-
NAVER Corporation
-
Canva
-
Meta Platforms, Inc.
-
Amazon.com, Inc.
-
Spotify AB
-
Snap Inc.
-
Roblox Corporation
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: ByteDance, Tencent, NAVER Corporation, Amazon.com, Inc.
- Focus on expanding creator tools, improving AI-powered content creation, increasing creator monetization opportunities, strengthening platform engagement, and expanding partnerships with creators, brands, and advertisers.
- Large and active user bases, strong brand recognition, extensive creator ecosystems, advanced technology capabilities, diverse content formats, and strong financial resources.
- High competition, regulatory challenges, dependence on user engagement, high technology and content costs, and the need for continuous innovation to retain creators and users.
Emerging Players: Kuaishou Technology, Bilibili Inc., Kakao Corp., Canva
- Focus on developing specialized creator tools, improving AI-powered content capabilities, expanding monetization features, and targeting specific creator segments and markets.
- Faster innovation, flexible product offerings, specialized creator solutions, and the ability to respond quickly to changing creator needs.
- Smaller user bases, limited financial resources, lower brand recognition, and greater dependence on partnerships and continued product development.
Recent Developments:
-
In August 2026, Meta Platforms, Inc. and Roblox agreed with Philippine officials to strengthen child-safety measures, including age verification, parental controls, faster removal of harmful content, and cooperation with law enforcement. The initiative aims to improve online safety for minors and support stronger platform accountability in the Philippines.
-
In May 2026, Tencent announced a multi-year investment in India’s AVGC sector to support skill development, training, and mentorship. The initiative aims to strengthen India’s gaming and creative technology ecosystem through industry training, developer engagement, and global collaboration.
-
In June 2025, Canva announced its intention to acquire MagicBrief, an Australian AI-powered creative intelligence startup based in Sydney, in June 2025. The acquisition strengthens Canva’s AI-driven marketing and advertising capabilities by integrating creative performance analysis and optimization into its platform.
Asia Pacific Creator Economy Market Report Scope
Report Attribute
Details
Market size in 2025
USD 65.7 billion
Estimated market size in 2026
USD 84.3 billion
Projected market size by 2033
USD 498.0 billion
Growth rate
CAGR of 28.9% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Platform, creative service, revenue channel, end use, region
Regional scope
Asia Pacific
Country scope
China; Japan; India; Australia; South Korea; Malaysia; Thailand; Vietnam; Indonesia; Philippines; Singapore
Key companies profiled
ByteDance; Kuaishou Technology; Bilibili Inc.; Tencent; Kakao Corp.; NAVER Corporation; Canva; Meta Platforms, Inc.; Amazon.com, Inc.; Spotify AB; Snap Inc.; Roblox Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Asia Pacific Creator Economy Market Report Segmentation
This report forecasts revenue growth at the regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the Asia Pacific creator economy market report based on platform, creative service, revenue channel, end use, and region.
-
Platform Outlook (Revenue, USD Billion, 2021-2033)
-
Video Streaming
-
Blogging Platform
-
Podcasting Platform
-
Others
-
-
Creative Service Outlook (Revenue, USD Billion, 2021-2033)
-
Written Content
-
Photography & Videography
-
Music Production
-
Others
-
-
Revenue Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Advertising
-
Subscriptions
-
Tips/Donations
-
Affiliate Marketing
-
Brand Partnerships
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Individual Content Creators
-
Businesses/Brands
-
Media Companies
-
-
Country Outlook (Revenue, USD Billion, 2021-2033)
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
Malaysia
-
Thailand
-
Vietnam
-
Indonesia
-
Philippines
-
Singapore
-
Research Methodology
The Asia Pacific creator economy market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Asia Pacific creator economy segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Platform
Revenue Capture Definition
Video Streaming
Revenue generated through creator-focused video streaming platforms from paid subscriptions, advertising, virtual gifts, memberships, and other monetization features that enable creators to earn from video content.
Blogging Platform
Revenue generated through blogging platforms from creator subscriptions, advertising, sponsored content, premium articles, paid memberships, and other monetization options associated with written content.
Podcasting Platform
Revenue generated through podcasting platforms from advertising, paid subscriptions, listener memberships, sponsorships, premium episodes, and other monetization services that enable creators to generate income from audio content.
Others
Revenue generated through other creator platforms, including social media platforms, livestreaming platforms, creator marketplaces, newsletter platforms, and other digital services that provide monetization opportunities to content creators.
Segment - Creative Service
Revenue Capture Definition
Written Content
Revenue generated from creator activities involving blogs, articles, newsletters, social media posts, scripts, ebooks, and other written content produced for audiences, businesses, or brands.
Photography & Videography
Revenue generated from creator services involving photography, video production, short-form videos, livestreams, visual content, and other multimedia content created for audiences, businesses, or brands.
Music Production
Revenue generated from creator activities involving music composition, recording, production, sound design, songwriting, and other music-related content created for personal, commercial, or entertainment purposes.
Others
Revenue generated from other creative services, including graphic design, illustration, animation, digital art, gaming content, educational content, and other creative activities performed by individual creators.
Segment - Revenue Channel
Revenue Capture Definition
Advertising
Revenue generated by creators through advertisements displayed, embedded, or integrated within their digital content, including video ads, display ads, sponsored placements, and other advertising formats.
Subscriptions
Revenue generated through recurring payments made by audiences for access to exclusive content, premium communities, memberships, subscriptions, or other creator-provided offerings.
Tips/Donations
Revenue generated through voluntary monetary contributions from audiences to support creators, including tips, donations, virtual gifts, and other direct fan-support mechanisms.
Affiliate Marketing
Revenue generated when creators promote third-party products or services and receive commissions based on qualifying purchases, referrals, clicks, or other completed transactions.
Brand Partnerships
Revenue generated through paid collaborations between creators and businesses or brands, including sponsored content, product placements, endorsements, campaigns, and branded creative projects.
Others
Revenue generated through other monetization channels, including merchandise sales, digital products, courses, licensing, creator services, crowdfunding, and other direct or indirect income sources.
Segment - End Use
Revenue Capture Definition
Individual Content Creators
Revenue generated from creator-economy activities performed by independent individuals who monetize their own content, audience, creative skills, personal brand, or digital products.
Businesses/Brands
Revenue generated from creator-economy activities used by businesses and brands to develop, distribute, promote, or monetize branded content, marketing campaigns, products, and customer engagement initiatives.
Media Companies
Revenue generated from creator-economy activities adopted by media companies to produce, distribute, manage, and monetize creator-led content across digital media, entertainment, publishing, and streaming channels.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
End-user Industry Layer
Who creates demand for the Asia Pacific Creator Economy?
Identifies the total base of individual creators, businesses, brands, media companies, and other organizations generating demand for creator-economy platforms and services across video, blogging, podcasting, social media, livestreaming, digital content, and other creator-led activities.
02
Adoption / Usage Layer
Who actively adopts the Asia Pacific Creator Economy?
Filters the addressable market based on the adoption of digital content creation, social media, video and audio content, blogging, livestreaming, influencer marketing, digital communities, and other creator-economy activities across Asia Pacific.
03
Technology & Platform Layer
What technologies and platforms support the Asia Pacific Creator Economy?
Estimates adoption across video streaming, blogging, podcasting, social media, livestreaming, content management, creator monetization, analytics, collaboration, and other technology platforms delivered through web, mobile, desktop, and API-based environments.
04
Revenue Capture Layer
How is revenue generated in the Asia Pacific Creator Economy ecosystem?
Calculates revenue generated through advertising, subscriptions, tips and donations, affiliate marketing, brand partnerships, sponsorships, merchandise and digital product sales, licensing, and other monetization models used by creators and creator-focused businesses across Asia Pacific.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Objective
Custom Research Modules Delivered
Strategic Value / Business Impact
Creator Economy Technology & Platform Assessment
- Emerging creator-economy technology and platform trends
- Video streaming, blogging, and podcasting platform assessment
- Creator tools, monetization features, analytics, and content-management capabilities analysis
- Technology ecosystem and platform partner mapping
- Identified emerging technology and platform opportunities
- Supported technology investment planning
- Evaluated platform adoption and monetization readiness
- Strengthened technology and ecosystem partnership decisions
Platform Positioning & Competitive Intelligence
- Creator platform benchmarking
- Platform feature, capability, and monetization comparison
- Pricing and subscription model analysis
- Competitive strategy, creator acquisition, and product portfolio evaluation
- Improved platform differentiation strategy
- Supported pricing and monetization optimization
- Identified creator requirements and platform gaps
- Enhanced competitive positioning
Market Entry & Growth Assessment
- Regional market sizing and forecasting
- Creative Service and End Use segmentation analysis
- Revenue Channel analysis across advertising, subscriptions, tips/donations, affiliate marketing, and brand partnerships
- Platform, competitive landscape, and regulatory assessment
- Identified high-growth market and Creative Service opportunities
- Supported go-to-market strategy development
- Highlighted investment priorities and market risks
- Enabled data-driven market expansion planning
About the Author(s)
Digital Media Research Team
Technology · Digital MediaThis report was authored by the digital media research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the digital media segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


