
- Home
- »
- Medical Devices
- »
-
Atherectomy Devices Market Size & Share Report, 2033GVR Report cover

Atherectomy Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Directional, Rotational, Orbital, Laser), By Region (North America, Asia Pacific, Europe, Latin America), And Segment Forecasts
Market Size, 2025
$1.1BMarket Estimate, 2026
$1.2BMarket Forecast, 2033
$1.9BCAGR, 2026–2033
7.9%Atherectomy Devices Market Summary
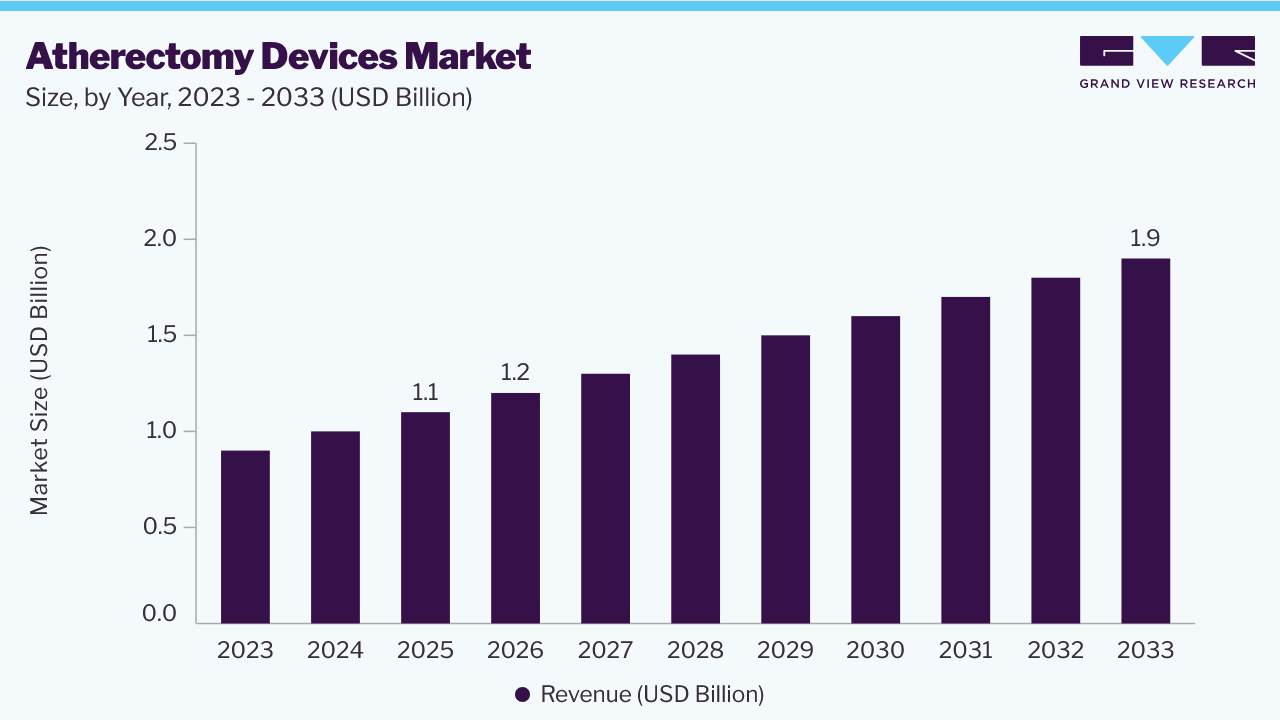
The global atherectomy devices market size was valued at USD 1.1 billion in 2025 and is projected to grow from USD 1.2 billion in 2026 to USD 1.9 billion by 2033, at a CAGR of 7.9% from 2026 to 2033. North America dominated the market, accounting for a revenue share of around 40.0% in 2025. The increasing prevalence of target vascular diseases, including coronary artery disease (CAD) and peripheral artery disease (PAD), coupled with the growing emphasis on developing advanced minimally invasive treatment options, is expected to drive growth in the atherectomy devices market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Directional atherectomy segment held the largest revenue share of over 36.0% in 2025.
- By type: The laser atherectomy segment is expected to register the fastest CAGR from 2026 to 2033
Regional Highlights
- Largest regional market: North America (40.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 1.1 Billion
- Estimated market size in 2026: USD 1.2 Billion
- Projected market size by 2033: USD 1.9 Billion
- CAGR (2026-2033): 7.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The rising global burden of target vascular diseases is primarily associated with population aging, sedentary lifestyles, obesity, and other cardiovascular risk factors. According to the National Center for Biotechnology Information (NCBI), PAD affects more than 230 million people worldwide, with prevalence particularly high among older adults. This growing disease burden is expected to increase demand for effective vascular treatment and atherectomy devices.
The demand for minimally invasive surgeries/procedures (MIS) is on the rise as these surgeries have a success rate of around 90%. These procedures result in less trauma for the patient and quicker recovery than invasive procedures. Another reason for this change is the risk of infection associated with invasive surgeries. Atherectomy is a minimally invasive procedure; therefore, the rising demand for minimally invasive surgeries is expected to render a high-impact driver for the market during the forecast period.
Traditionally, open surgery has been used to address plaque buildup, which is invasive, hazardous, and takes a long time to recover from. However, atherectomy devices have enabled doctors to perform fewer invasive treatments that lead to shorter recovery times and a lower risk of complications. In addition, atherectomy devices have the potential to increase drug efficacy by evaluating the use of orbital atherectomy to treat CAD in patients who are not eligible for Coronary Artery Bypass (CAB) grafting and evaluating the use of rotational atherectomy to treat PAD in patients who are not eligible for Endovascular Therapy (EVT). The results of these clinical trials are expected to further demonstrate the potential of atherectomy devices and could lead to their wider adoption in the treatment of cardiovascular diseases.
Analyst Perspective
The atherectomy devices market is expected to witness steady growth in the coming years, driven by the rising prevalence of peripheral artery disease, the increasing incidence of calcified vascular lesions, and the growing adoption of minimally invasive endovascular procedures. Technological advancements in rotational, orbital, directional, and laser atherectomy systems are improving procedural efficiency and expanding clinical applications. North America is expected to remain a key market, while the Asia Pacific is likely to experience faster growth due to improving healthcare infrastructure and procedure volumes. However, competition from intravascular lithotripsy and pricing pressures may moderate market expansion over the forecast period.
Market Dynamics
The rising prevalence of peripheral artery disease (PAD) is a major factor driving the growth of the atherectomy devices market. PAD is a common vascular condition in which narrowed or blocked arteries restrict blood flow to the limbs, with diabetes, obesity, smoking, and aging being key risk factors. According to the post-market JET Registry of the Jetstream Atherectomy System, 41% of the 241 treated patients had diabetes, highlighting the substantial presence of diabetes among patients undergoing peripheral atherectomy procedures.
Atherectomy devices are minimally invasive, catheter-based tools designed to remove or modify plaque within diseased arteries through mechanisms such as cutting, shaving, sanding, or laser ablation. The procedure can facilitate plaque removal and vessel preparation while potentially reducing the need for more invasive surgical interventions in appropriately selected patients. The increasing adoption of minimally invasive endovascular procedures, combined with the growing burden of PAD and complex arterial lesions, is expected to support market growth.
High procedural costs and inconsistent reimbursement remain important challenges for the atherectomy devices market. Although atherectomy can provide effective plaque modification in selected lesions, its incremental clinical and economic benefits relative to other endovascular approaches remain under ongoing evaluation. Studies have reported substantial variation in atherectomy utilization and physician payments, suggesting that financial incentives can influence procedure volumes.
Furthermore, evidence comparing atherectomy with balloon angioplasty and stenting has not consistently demonstrated superior long-term outcomes across all patient populations. These considerations, together with the cost of specialized devices and procedural infrastructure, may limit adoption among cost-sensitive healthcare providers and payers.
The increasing use of atherectomy for heavily calcified PAD lesions represents a significant growth opportunity. Severe calcification can make balloon angioplasty and stent delivery or expansion challenging, thereby increasing the need for effective plaque modification and vessel preparation strategies. Atherectomy can be used to modify plaque before adjunctive therapies such as balloon angioplasty, drug-coated balloons, or stent placement.
Clinical evidence from the OASIS registry demonstrated the potential of orbital atherectomy in complex infrapopliteal disease, reporting procedural success in 90.1% of treated lesions and a 3.2% 30-day major adverse event rate. The growing prevalence of diabetes, chronic kidney disease, and other conditions associated with vascular calcification is expected to increase the number of patients presenting with complex lesions. Continued improvements in device precision, lesion-crossing capabilities, aspiration, and procedural safety are expected to further support adoption.
Type Insights
The directional atherectomy segment accounted for the largest revenue share in 2025, exceeding 36%. Directional systems enable targeted plaque excision and are particularly well-suited to lesions where controlled, localized tissue removal is desired. Advances in image-guided atherectomy have further enhanced procedural precision. For instance, Avinger's Pantheris system incorporates real-time optical coherence tomography (OCT) to visualize the vessel and guide targeted plaque removal while helping physicians avoid disruption of healthy vessel layers.
The laser atherectomy segment is expected to register the fastest CAGR from 2026 to 2033, supported by continued technological advancements and increasing use of laser-based plaque modification in complex peripheral lesions. Laser atherectomy provides a minimally invasive approach to modifying or removing plaque and improving the vessel lumen in appropriately selected patients with PAD. Increasing demand for less invasive treatment options and continued innovation in laser catheter technology are expected to support segment growth.
The rotational atherectomy segment accounted for a significant share of revenue in 2025, supported by its established use in plaque modification and the treatment of complex, calcified lesions. Rotational systems can facilitate lesion preparation when conventional balloon angioplasty alone may be insufficient. Growing demand for vessel-preparation technologies and advances in catheter design are expected to support continued adoption of rotational atherectomy devices.
Regional Insights
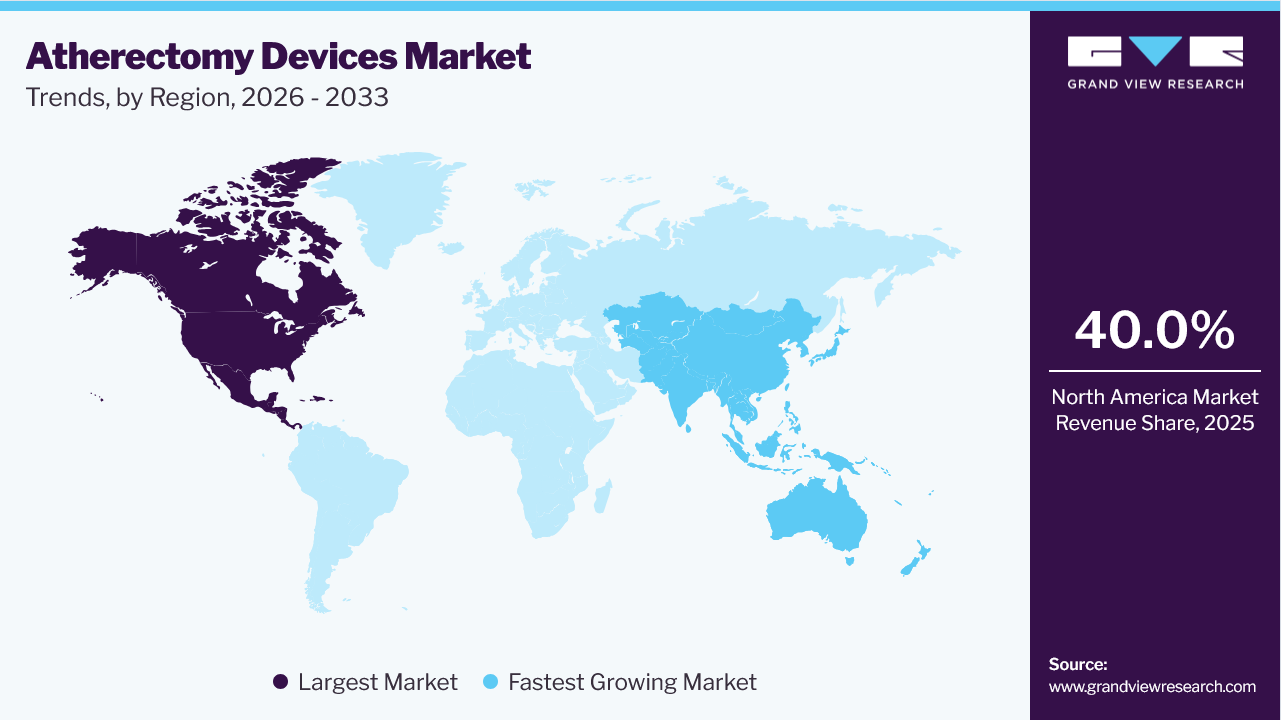
North America atherectomy devices market dominated the global market in 2025, accounting for around 40.0% of the global revenue in 2025. The region’s dominance is attributed to the presence of advanced healthcare infrastructure, favorable reimbursement conditions, a high prevalence of PAD and cardiovascular diseases, and broad availability of FDA-cleared atherectomy technologies. The region also benefits from high procedural volumes, a well-established network of vascular intervention centers, and strong adoption of minimally invasive endovascular procedures. Continued investments in innovative plaque-modification technologies and increasing use of atherectomy for complex and calcified lesions are expected to sustain regional market growth.
 To learn more about this report, Download Free Sample Report
Asia Pacific Atherectomy Devices Market Trends
Asia Pacific is expected to register the fastest CAGR during the forecast period from 2026 to 2033. The growth is driven by the rising burden of PAD and other cardiovascular diseases, population aging, improving healthcare infrastructure, and increasing adoption of minimally invasive vascular interventions. Expanding access to advanced medical devices, growing healthcare expenditure, and increasing investments by global medical device manufacturers are further supporting market expansion. For instance, in February 2025, China's National Medical Products Administration (NMPA) approved Boston Scientific's JETSTREAM PVCN100 Console and JETSTREAM Over-the-Wire Atherectomy Catheter for marketing, expanding access to advanced plaque-excision technology for femoropopliteal disease in China.
Europe Atherectomy Devices Market Trends
Europe is expected to maintain a significant share of the atherectomy devices market during the forecast period, supported by the region's aging population, high burden of cardiovascular and peripheral vascular diseases, and well-developed healthcare infrastructure. Increasing adoption of minimally invasive endovascular procedures, rising awareness of advanced PAD treatment options, and the availability of sophisticated vascular intervention technologies are contributing to regional growth. In addition, favorable healthcare policies, established reimbursement systems in major European markets, and continued investments in medical device innovation are expected to support the adoption of atherectomy technologies, particularly for the treatment of complex and heavily calcified lesions.
Key Atherectomy Devices Company Insights
Market participants are focusing on product development, clinical evidence generation, regulatory approvals, strategic collaborations, and geographic expansion to strengthen their positions in the global atherectomy devices market. The competitive landscape includes established medical device companies with broad vascular intervention portfolios as well as specialized manufacturers focused on atherectomy technologies.
Key Atherectomy Devices Companies
The following key companies have been profiled for this study on the atherectomy devices market.
-
Abbott
-
Avinger
-
BD
-
Boston Scientific Corporation
-
Cardiovascular Systems, Inc.
-
Cordis
-
Koninklijke Philips N.V.
-
Medtronic
-
Terumo Medical Corporation
Recent Development
- In October 2025, BD announced the enrollment of the first patient in the XTRACT Registry for its Rotarex Catheter System. The post-market study is designed to collect real-world evidence on the performance of Rotarex in treating peripheral artery disease lesions and support clinical decision-making and treatment optimization.
- In May 2025, BD announced plans to initiate the XTRACT prospective, multicenter post-market registry to evaluate real-world outcomes associated with its Rotarex Atherectomy System in patients with peripheral artery disease. The registry is expected to enroll up to 600 patients across approximately 100 U.S. clinical sites, generating additional evidence on the safety and effectiveness of the system in peripheral vascular interventions
- In January 2025, AngioDynamics initiated the AMBITION BTK randomized controlled trial and registry to evaluate the Auryon Atherectomy System in combination with standard balloon angioplasty for below-the-knee peripheral artery disease lesions in patients with critical limb ischemia. The study is expected to generate additional clinical evidence supporting the use of laser atherectomy in complex and calcified lesions, strengthening the company's position in the peripheral atherectomy market
Atherectomy Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.1 billion
Estimated market size in 2026
USD 1.2 billion
Projected market size by 2033
USD 1.9 billion
Growth rate
CAGR of 7.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Boston Scientific Corporation; Cardiovascular Systems, Inc.; Medtronic; Avinger; Koninklijke Philips N.V.; BD; Abbott; Cordis; Terumo Medical Corporation.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Atherectomy Devices Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global atherectomy devices market based on type and region:
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Directional Atherectomy
-
Rotational Atherectomy
-
Orbital Atherectomy
-
Laser Atherectomy
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The directional atherectomy segment accounted for the largest market share of over 36.0% in 2025.
The global atherectomy devices market size was valued at USD 1.1 billion in 2025 and is estimated at USD 1.2 billion for 2026.
The global atherectomy devices market is expected to grow at a CAGR of 7.9% from 2026 to 2033, reaching USD 1.9 billion by 2033.
North America dominated with approximately 40.0% revenue share in 2025.
Key players in the market include Boston Scientific Corporation, Cardiovascular Systems, Inc., Medtronic, Avinger, Koninklijke Philips N.V., BD, Abbott, Cordis, Terumo Medical Corporation, and others.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


