
- Home
- »
- Plastics, Polymers & Resins
- »
-
Automotive Parts Packaging Market Size Report, 2025-2030GVR Report cover

Automotive Parts Packaging Market (2025 - 2030)
Size, Share & Trends Analysis Report By Packaging Type (Reusable, Disposable), By Component Type (Battery, Underbody Components), By Product Type (Corrugated Products, Pallets), By Region, And Segment Forecasts
Market Size, 2024
$9.4BMarket Estimate, 2026
$10.2BMarket Forecast, 2030
$12.2BCAGR, 2025–2030
4.5%Automotive Parts Packaging Market Summary
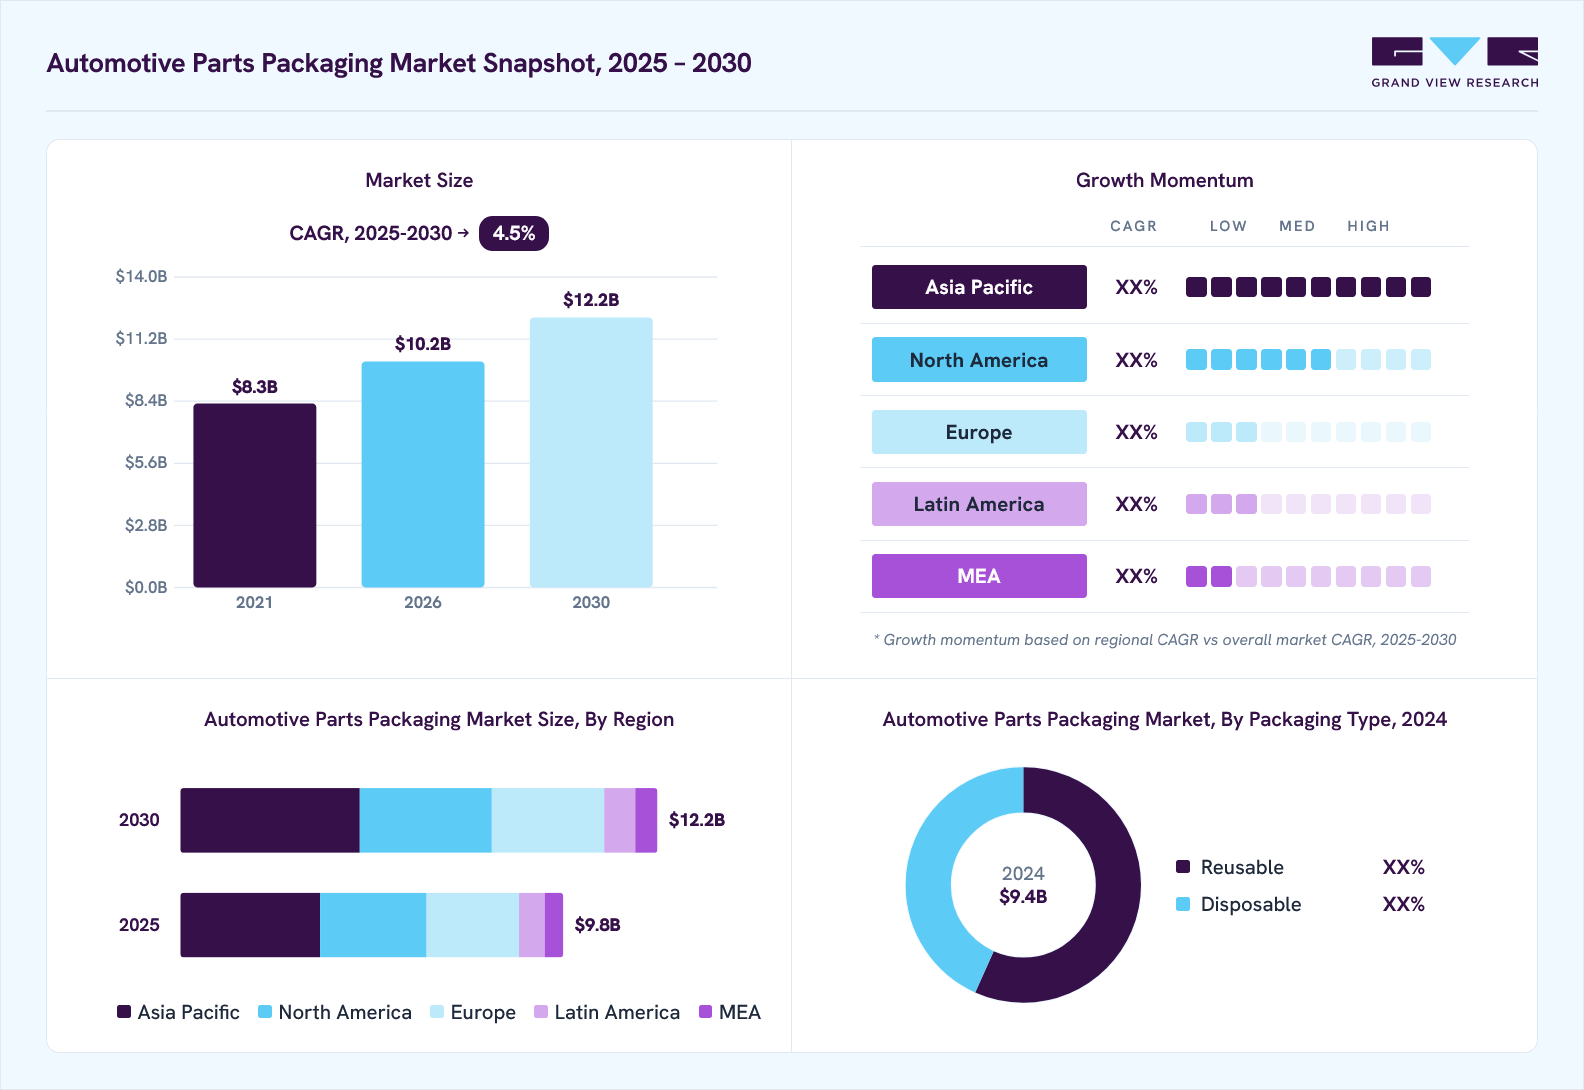
The global automotive parts packaging market size was valued at USD 9.4 billion in 2024 and is projected to grow from USD 10.2 billion in 2026 to USD 12.2 billion by 2030, at a CAGR of 4.5% from 2025 to 2030. Asia Pacific dominated the market, accounting for a revenue share of 36.0% in 2024. The market is primarily driven by the expanding global automotive industry, especially the growth in automotive production and aftermarket sales.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By packing type, the reusable segment recorded the largest revenue share of over 56.0% in 2024.
- By component type, the battery segment recorded the largest revenue share of over 18.0% in 2024.
- By product type, the corrugated products segment recorded the largest revenue share of over 18.0% in 2024.
Market Size & Forecast
- 2024 Market Size: USD 9.4 Billion
- 2030 Projected Market Size: USD 12.2 Billion
- CAGR (2025-2030): 4.5%
- Asia Pacific: Largest market in 2024
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2025–2030 annual, 2024 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
As vehicle ownership increases across developing and developed economies, so does the demand for parts replacement, maintenance, and repair. This directly correlates with the need for protective, efficient, and sustainable packaging solutions to transport and store a wide range of components, from small fasteners to large engine parts. Moreover, the rise of e-commerce platforms specializing in auto parts has further fueled the need for durable and tamper-proof packaging to ensure product integrity during last-mile delivery.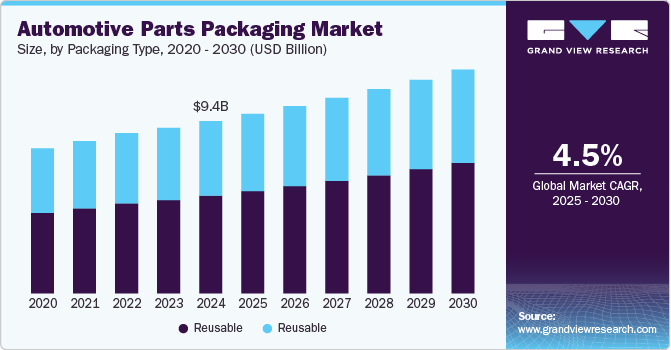 To learn more about this report, Download Free Sample Report
As vehicle ownership increases across developing and developed economies, so does the demand for parts replacement, maintenance, and repair. This directly correlates with the need for protective, efficient, and sustainable packaging solutions to transport and store a wide range of components, from small fasteners to large engine parts. Moreover, the rise of e-commerce platforms specializing in auto parts has further fueled the need for durable and tamper-proof packaging to ensure product integrity during last-mile delivery.
The increasing focus on part protection and supply chain efficiency is also propelling market growth. Automotive components are often sensitive to corrosion, moisture, static, and physical damage. As such, manufacturers are investing in packaging solutions that offer advanced protective features, including anti-corrosion films, VCI (volatile corrosion inhibitors) packaging, and ESD (electrostatic discharge) protection. Alongside protection, packaging must support optimized stacking, space efficiency, and tracking through barcoding or RFID tagging, all of which streamline warehouse operations and logistics.
Sustainability trends are also influencing the automotive parts packaging market. As OEMs and Tier 1 suppliers move toward reducing their environmental footprint, the demand for recyclable, reusable, and returnable packaging solutions is on the rise. Returnable packaging systems, especially plastic crates and pallets, are gaining traction in intra-industry logistics due to their durability and cost-effectiveness over multiple use cycles. Additionally, regulations and corporate sustainability goals are pushing suppliers to innovate in biodegradable or compostable material alternatives.
Lastly, technological advancements and smart packaging are further reshaping the market. Integration of IoT, sensors, and blockchain in packaging allows real-time tracking, temperature monitoring, and authenticity verification of high-value components, reducing the risks of counterfeiting and improving inventory visibility. As supply chains become more global and complex, such innovations are becoming indispensable, further strengthening the growth outlook for the automotive parts packaging market.
Market Dynamics
Increasing global vehicle production and expanding automotive component trade are major factors supporting the growth of the automotive parts packaging market. Automotive manufacturers and suppliers require highly durable, protective packaging solutions to safely transport engines, transmissions, electronic components, batteries, interior parts, and precision mechanical systems across complex supply chains. As automotive production becomes increasingly globalized, the need for packaging that minimizes product damage, improves handling efficiency, and supports long-distance transportation continues to rise. Packaging solutions such as returnable containers, corrugated boxes, plastic crates, pallets, dunnage trays, and foam protective systems are widely used to maintain component integrity during shipping and storage operations.
The rapid evolution of electric vehicles (EVs), autonomous technologies, and advanced automotive electronics is also driving demand for specialized packaging solutions. EV batteries, lightweight components, sensors, and electronic systems require enhanced shock protection, temperature resistance, and anti-static packaging materials to prevent product damage and contamination. In addition, automotive manufacturers are increasingly adopting reusable and sustainable packaging systems to reduce logistics costs, improve operational efficiency, and support environmental goals. Automation in warehouses, smart logistics systems, and just-in-time manufacturing practices are further driving the adoption of standardized, high-performance automotive packaging solutions across global supply chains.
Despite growing demand, the automotive parts packaging market faces challenges associated with high packaging development and operational costs. Automotive components often vary significantly in size, weight, shape, and fragility, requiring customized packaging designs and specialized protective materials. Developing durable packaging solutions that meet strict automotive industry standards can increase production complexity and overall packaging costs. Returnable packaging systems, while cost-efficient in the long term, require substantial upfront investment in containers, tracking systems, and reverse logistics infrastructure.
Meeting sustainability targets while maintaining high packaging durability and logistics performance remains a major challenge for the automotive parts packaging industry. Automotive packaging solutions must provide strong protection against vibration, impact, moisture, dust, and electrostatic discharge while supporting efficient stacking, storage, and transportation. At the same time, manufacturers are under increasing pressure to reduce packaging waste, minimize material usage, and transition toward recyclable or reusable packaging systems.
Packaging Type Insights
The reusable packaging type segment recorded the largest revenue share of over 56.0% in 2024 and is expected to grow at the fastest CAGR of 5.0% during the forecast period. Reusable packaging for automotive parts typically includes containers, racks, pallets, and bins that are designed to be used multiple times over an extended period. The growth of reusable packaging is driven by rising environmental concerns, the need to reduce packaging waste, and increasing pressure on manufacturers to adopt sustainable practices.
Disposable packaging is intended for single use and includes materials such as cardboard boxes, plastic wraps, and molded pulp. This type of packaging is commonly used for aftermarket parts, spare parts distribution, and international shipping, where packaging retrieval is impractical or too costly. Disposable packaging is lightweight, cost-effective for short-term use, and easier to customize for various part sizes and shapes. The demand for disposable packaging is fueled by the growing e-commerce channel for automotive parts, especially in the aftermarket segment.
Component Type Insights
The battery segment recorded the largest revenue share of over 18.0% in 2024. Automotive batteries, especially in electric vehicles (EVs), are large, heavy, and sensitive to temperature and impact. They require packaging that provides structural strength, insulation, and protection against short circuits, leakage, and mechanical stress during transportation. The global shift toward EVs, increased electrification of vehicles, and demand for safer logistics in battery distribution are key drivers. Regulatory compliance for hazardous materials and sustainability considerations also encourage the use of advanced and eco-friendly packaging materials.
The underbody components segment is expected to grow at the fastest CAGR of 5.4% during the forecast period. Underbody components include parts such as suspension systems, control arms, chassis frames, and subframes. These parts are typically large and irregularly shaped and require packaging that can withstand heavy loads while preventing corrosion, scratches, and deformation. Globalization of the auto supply chain and the need for damage-free delivery further push the demand for reliable and customized packaging in this segment.
Product Type Insights
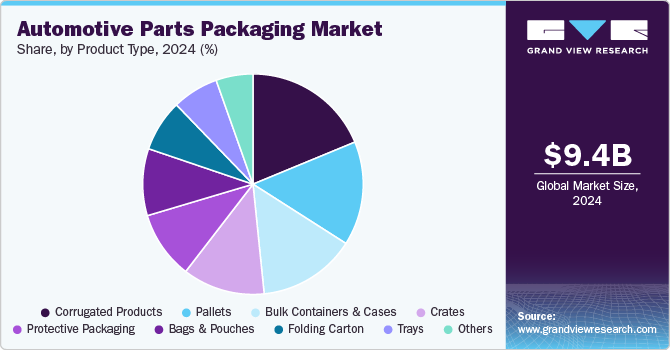
The corrugated products segment recorded the largest revenue share of over 18.0% in 2024 and is projected to grow at the fastest CAGR of 5.2% during the forecast period. Corrugated products, such as corrugated boxes and sheets, are lightweight yet strong packaging solutions made from corrugated fiberboard. They are commonly used for both primary and secondary packaging of automotive parts. The shift toward sustainable, recyclable packaging and the need for cost-effective, lightweight materials in logistics are driving growth in this segment.
 To learn more about this report, Download Free Sample Report
Pallets are flat transport structures used to support automotive parts during storage or transportation, typically made from wood, plastic, or metal. They facilitate easier handling, stacking, and storage efficiency with forklifts and automated systems. The adoption of automated warehousing systems and lean manufacturing in the automotive sector is fueling the demand for pallets. Additionally, their compatibility with global shipping standards and efforts to reduce product damage during transit are driving pallet usage.
Region Insights
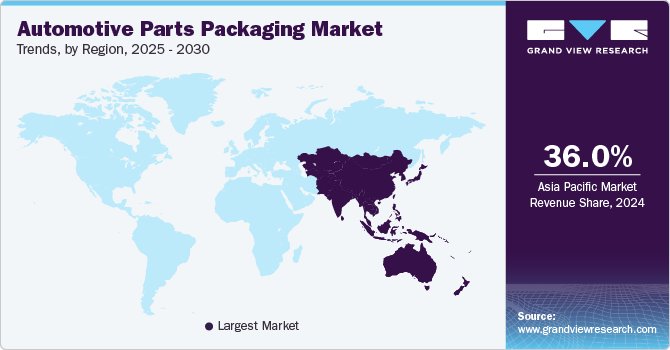
Asia Pacific automotive parts packaging market dominated the global market and accounted for the largest revenue share of over 36.0% in 2024 and is projected to grow at the fastest CAGR of 5.1% during the forecast period. The region hosts major automotive manufacturing hubs in countries such as China, Japan, India, Thailand, and South Korea, which collectively produce millions of vehicles annually. This extensive manufacturing base creates a substantial demand for specialized packaging solutions to protect components throughout complex supply chains. Additionally, the rapid expansion of aftermarket parts sales across developing economies has significantly boosted packaging requirements.
 To learn more about this report, Download Free Sample Report
China Automotive Parts Packaging Market Trends
The automotive parts packaging market in China is primarily driven by its significant manufacturing capacity and rapidly expanding automotive industry. As the world's largest automobile producer and consumer market, China's automotive parts sector requires extensive packaging solutions to support both domestic consumption and its massive export operations. In addition, the Chinese government's strategic policies have further accelerated this growth, with initiatives such as "Made in China 2025" specifically targeting automotive manufacturing advancement. These policies have is driving the market growth in the country.
North America Automotive Parts Packaging Market Trends
The North America automotive parts packaging market hosts a mature automotive manufacturing ecosystem with established OEMs like General Motors, Ford, and Tesla operating alongside a dense network of tier-1, tier-2, and tier-3 suppliers. This integrated supply chain necessitates sophisticated packaging solutions to ensure parts arrive undamaged and assembly-ready. For example, Ford's just-in-time manufacturing systems require custom-designed returnable packaging for transmissions and engine components that can withstand multiple logistics cycles while maintaining precise tolerances.
The automotive parts packaging market in the U.S. is primarily driven by its massive automotive aftermarket sector. The US automotive parts packaging market is further bolstered by the growing e-commerce trend, with companies such as RockAuto and Amazon significantly expanding their automotive parts offerings. Moreover, manufacturing reshoring initiatives have also strengthened the US position in automotive packaging.
Europe Automotive Parts Packaging Market Trends
The growth of Europe automotive parts packaging market is due to its robust automotive manufacturing infrastructure and stringent quality standards. Countries such as Germany, France, Italy, and the UK host major automotive OEMs and tier suppliers, which propels the demand for reliable and protective automotive packaging. Moreover, the region’s advanced logistics networks further strengthen its position in this market. The region’s interconnected transportation systems allow for seamless movement of automotive components across borders, necessitating standardized yet customizable automotive parts packaging solutions.
The automotive parts packaging market in Germany is primarily driven by its robust automotive manufacturing ecosystem. It is home to global automotive giants such as Volkswagen, BMW, Mercedes-Benz, and Audi, thus positively influencing the market in the country. Moreover, the German Packaging Act (VerpackG) has driven the industry toward circular economy principles, resulting in packaging solutions that use fewer raw materials while maintaining protection standards. This environmental leadership has positioned German suppliers advantageously as global automotive manufacturers increasingly prioritize sustainability in their supply chains.
Key Automotive Parts Packaging Company Insights
The competitive environment of the automotive parts packaging industry is characterized by intense rivalry among established global players and regional manufacturers. Companies compete on factors such as material innovation, customization capabilities, supply chain efficiency, and compliance with automotive industry standards. Key players are increasingly investing in eco-friendly materials, such as recyclable plastics and biodegradable composites, to align with sustainability goals and OEM preferences. Strategic collaborations, mergers, and expansions are also shaping the competitive landscape.
Key Automotive Parts Packaging Companies:
The following are the leading companies in the automotive parts packaging market. These companies collectively hold the largest market share and dictate industry trends.
- Sealed Air
- DS Smith
- Smurfit Kappa
- Knauf Industries
- Nefab Group
- Thermopack
- Holostik
- ITB Packaging
- Storopack Hans Reichenecker GmbH
- Alpha Packaging, Inc.
- Ficus Pax Pvt. Ltd.
- Corplex
- Schoeller Allibert
- Coleman Containers
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weakness
Mature Players: DS Smith; Smurfit Westrock; NEFAB GROUP; ORBIS Corporation; CHEP
- Mature companies are investing heavily in reusable transport packaging, sustainable materials, and customized protective packaging systems for automotive supply chains.
- These players focus on automation-friendly packaging designs, lightweight solutions, and smart logistics integration to improve transportation efficiency.
- Large-scale production capabilities and integrated logistics services support efficient global supply chain management.
- Strong sustainability initiatives and reusable packaging systems strengthen long-term competitive positioning.
- High operational costs related to reusable packaging management, reverse logistics, and customized product development can affect profitability.
- Dependence on automotive production cycles and economic conditions may create demand volatility.
Emerging Players: Schoeller Allibert; Sonoco Products Company; Sealed Air; Knauf Industries; GWP Group
- Emerging companies focus on specialized protective packaging, EV battery packaging systems, anti-static solutions, and custom transit packaging for sensitive automotive components.
- Many players are investing in recyclable materials, modular packaging systems, and lightweight protective structures to improve sustainability and operational efficiency.
- Emerging players are generally more agile in addressing evolving EV packaging requirements and niche automotive logistics applications.
- Specialized expertise in customized protective solutions and reusable packaging innovation supports market differentiation.
- Smaller global presence and limited economies of scale may reduce competitiveness against multinational industrial packaging suppliers.
- Rising raw material costs, sustainability compliance expenses, and logistics complexities can impact long-term scalability and margins.
Recent Developments
-
In November 2024, Nefab opened a new 19,000-square-foot mold-making facility in Grand Blanc, Michigan, through its PolyFlex subsidiary, enhancing its ability to design, prototype, and manufacture tooling for injection-molded packaging solutions. This state-of-the-art site integrates processes like injection molding, thermoforming, and tool production under one roof, enabling faster lead times, cost efficiency, and streamlined operations.
-
In August 2022, ORBIS Corporation presented its range of reusable packaging solutions tailored for batteries and electric vehicles (EVs) at The Battery Show. The event took place at the Suburban Collection Showplace, Michigan, wherein ORBIS team members were available at Booth 345 to engage with attendees and showcase to them the way packaging solutions of the company can enhance production efficiency, sustainability, and product protection throughout the supply chain.
Automotive Parts Packaging Market Report Scope
Report Attribute
Details
Market size in 2024
USD 9.4 billion
Estimated market size in 2026
USD 10.2 billion
Projected market size by 2030
USD 12.2 billion
Growth rate
CAGR of 4.5% from 2025 to 2030
Actual data
2018 - 2024
Forecast period
2025 - 2030
Quantitative units
Revenue in USD million/billion and CAGR from 2025 to 2030
Report coverage
Revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Packaging type, component type, product type, region
States scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Key companies profiled
Sealed Air; DS Smith; Smurfit Kappa; Knauf Industries; Nefab Group; Thermopack; Holostik; ITB Packaging; Storopack Hans Reichenecker GmbH; Alpha Packaging, Inc.; Ficus Pax Pvt. Ltd.; Corplex; Schoeller Allibert; Coleman Containers
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional, and segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Parts Packaging Market Report Segmentation
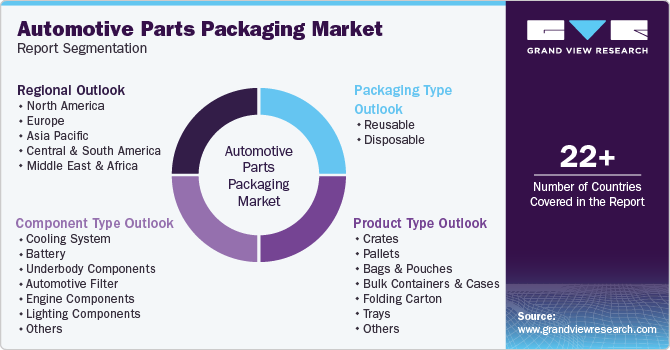
This report forecasts revenue growth at global level, regional, and country levels, and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global automotive parts packaging market report based on packaging type, component type, product type, and region:
 To learn more about this report, Download Free Sample Report
-
Packaging Type Outlook (Revenue, USD Million, 2018 - 2030)
-
Reusable
-
Disposable
-
-
Component Type Outlook (Revenue, USD Million, 2018 - 2030)
-
Cooling System
-
Battery
-
Underbody Components
-
Automotive Filter
-
Engine Components
-
Lighting Components
-
Electrical Components
-
Others
-
-
Product Type Outlook (Revenue, USD Million, 2018 - 2030)
-
Crates
-
Pallets
-
Bags and Pouches
-
Bulk Containers and Cases
-
Folding Carton
-
Trays
-
Corrugated Products
-
Protective Packaging
-
Others
-
-
Region Outlook (Revenue, USD Million 2018 - 2030)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Comprehensive assessment of the global automotive parts packaging market across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, including country-level vehicle production trends, automotive supply chain activity, EV manufacturing growth, logistics infrastructure, and industrial packaging demand analysis.
Help identify high-growth automotive manufacturing regions, emerging EV production hubs, and regional packaging opportunities. Support strategic planning through analysis of logistics capabilities, automotive investments, and sustainability trends.
Cross-Segmentation
Detailed segmentation analysis by packaging type, material type, product category, application, vehicle type, and end-use industry, including both value and volume evaluation across major global markets. The study further examines reusable packaging demand, EV battery packaging trends, protective transit solutions, and industrial packaging innovations.
Enable identification of fast-growing automotive packaging categories and emerging logistics applications. Support packaging optimization strategies, product development planning, and investment prioritization by understanding evolving automotive supply chain requirements.
Trade Assessment
In-depth analysis of global trade flows, raw material sourcing trends, automotive component transportation networks, packaging regulations, import-export activity, and regional supply chain dependencies affecting the automotive parts packaging market. The assessment also includes logistics challenges, reusable packaging fleet management trends, and procurement risks across international automotive supply chains.
Support supply chain optimization and sourcing strategy development by identifying trade risks, supplier opportunities, and logistics bottlenecks. Help improve operational resilience, reusable packaging efficiency, and long-term international expansion planning.
Frequently Asked Questions About This Report
The global automotive parts packaging market size was valued at USD 9.4 billion in 2024 and is estimated at USD 10.2 billion for 2026.
The global automotive parts packaging market is expected to grow at a CAGR of 4.5% from 2025 to 2030, reaching USD 12.2 billion by 2030.
Corrugated products dominated the automotive parts packaging market in 2024 with an 18.0% value share due to their superior strength-to-weight ratio and cost-efficiency. Their recyclability and ability to protect heavy or fragile components further boosted their adoption.
The key players in the automotive parts packaging market include Sealed Air; DS Smith; Smurfit Kappa; Knauf Industries; Nefab Group; Thermopack; Holostik; ITB Packaging; Storopack Hans Reichenecker GmbH; Alpha Packaging, Inc.; Ficus Pax Pvt. Ltd.; Corplex; Schoeller Allibert; Coleman Containers.
The automotive parts packaging market is driven by the increasing global vehicle production and aftermarket demand, necessitating durable and protective packaging solutions. Additionally, the rise of e-commerce and a shift towards eco-friendly, reusable packaging materials are further propelling market growth.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


