
- Home
- »
- Specialty Glass, Ceramic & Fiber
- »
-
Ballistic Composites Market Size & Share Report, 2026-2033GVR Report cover

Ballistic Composites Market (2026 - 2033)
Size, Share & Trends Analysis Report By Raw Material (Polymer Matrix Composite, Polymer-ceramic Matrix Composite, Metal Matrix Composite), By End-use (Vehicle Armor, Body Armor), By Region, And Segment Forecasts
Market Size, 2025
$2.1BMarket Estimate, 2026
$2.3BMarket Forecast, 2033
$3.7BCAGR, 2026–2033
7.1%Ballistic Composites Market Summary
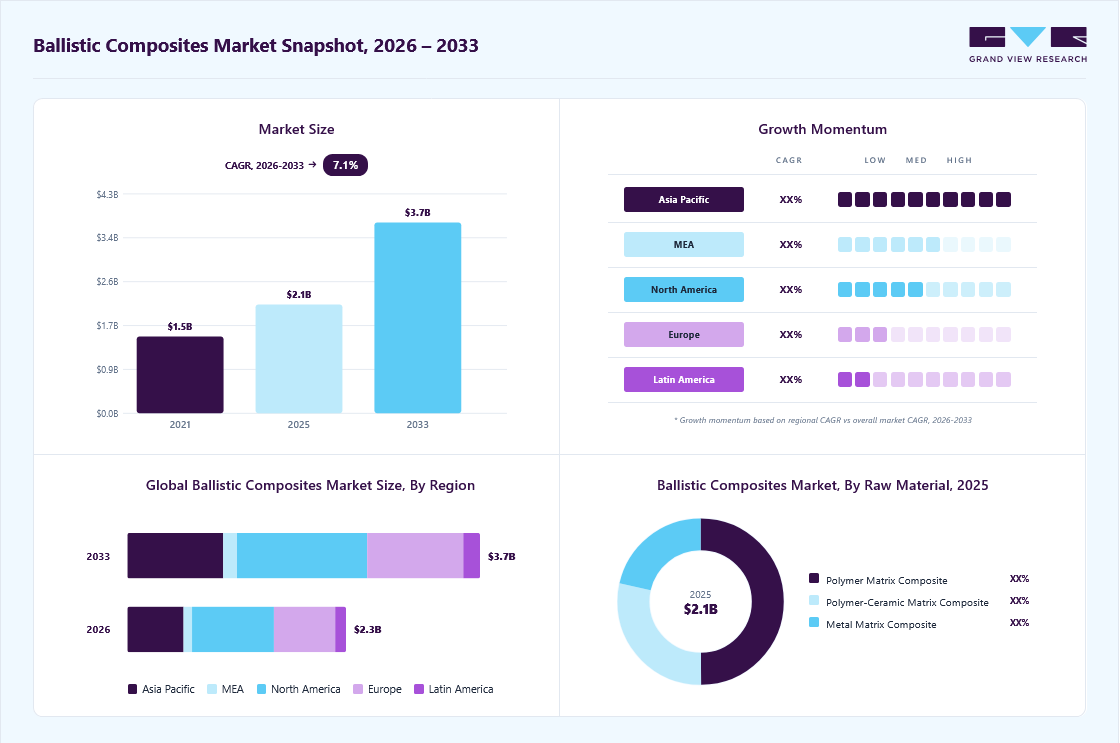
The global ballistic composites market size was valued at USD 2.1 billion in 2025 and is projected to grow from USD 2.3 billion in 2026 to USD 3.7 billion by 2033, at a CAGR of 7.1% from 2026 to 2033. North America dominated the ballistic composites market with the largest revenue share of 37.5% in 2025. Rising armed conflicts, terrorism, and security risks have pushed law enforcement to use advanced ballistic materials, such as ballistic composites.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By raw material: Polymer matrix composite segment held the largest market share of 49.8% in 2025.
- By end use: Vehicle armor segment held the largest market share of 40.7% in 2025.
Regional Highlights
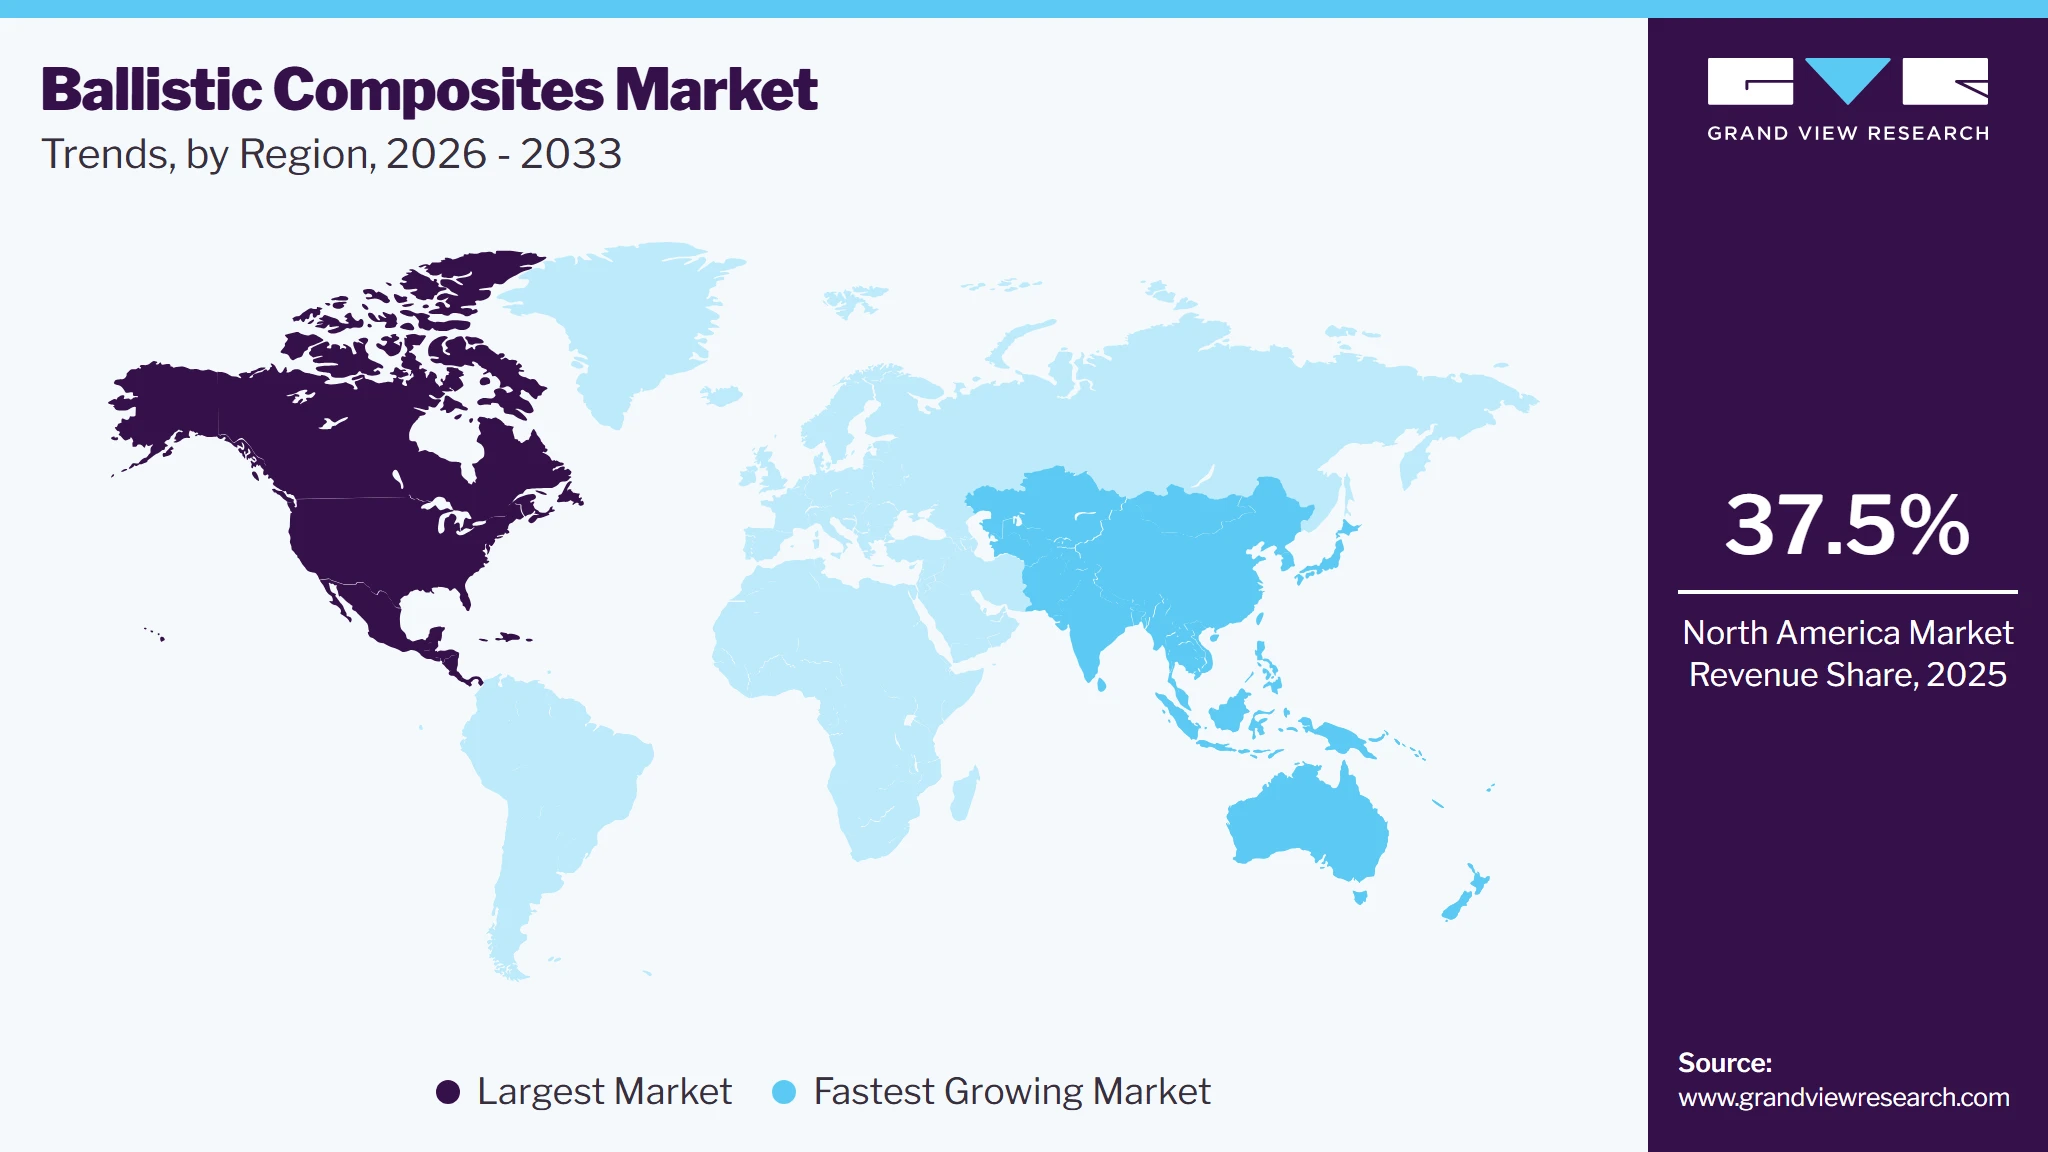
- Largest regional market: North America (37.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 2.1 Billion
- Estimated market size in 2026: USD 2.3 Billion
- Projected market size by 2033: USD 3.7 Billion
- CAGR (2026-2033): 7.1%
Prism AI by Grand View Research Free to tryAsk a question about the ballistic composites marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
There is an increased demand for ballistic equipment such as helmets, body armor, and vehicle protection. This equipment aids in the protection of military and law enforcement officers in times of armed conflict. Hence, these factors are responsible for the growth of the ballistic components market. This surge in investment directly impacts the demand for advanced materials, especially ballistic composites, which provide superior protection in military vehicles, personal armor, and defense systems. The need for lightweight, durable, and high-performance materials is propelling innovation, making ballistic composites a critical component in modern defense infrastructure and fueling market expansion.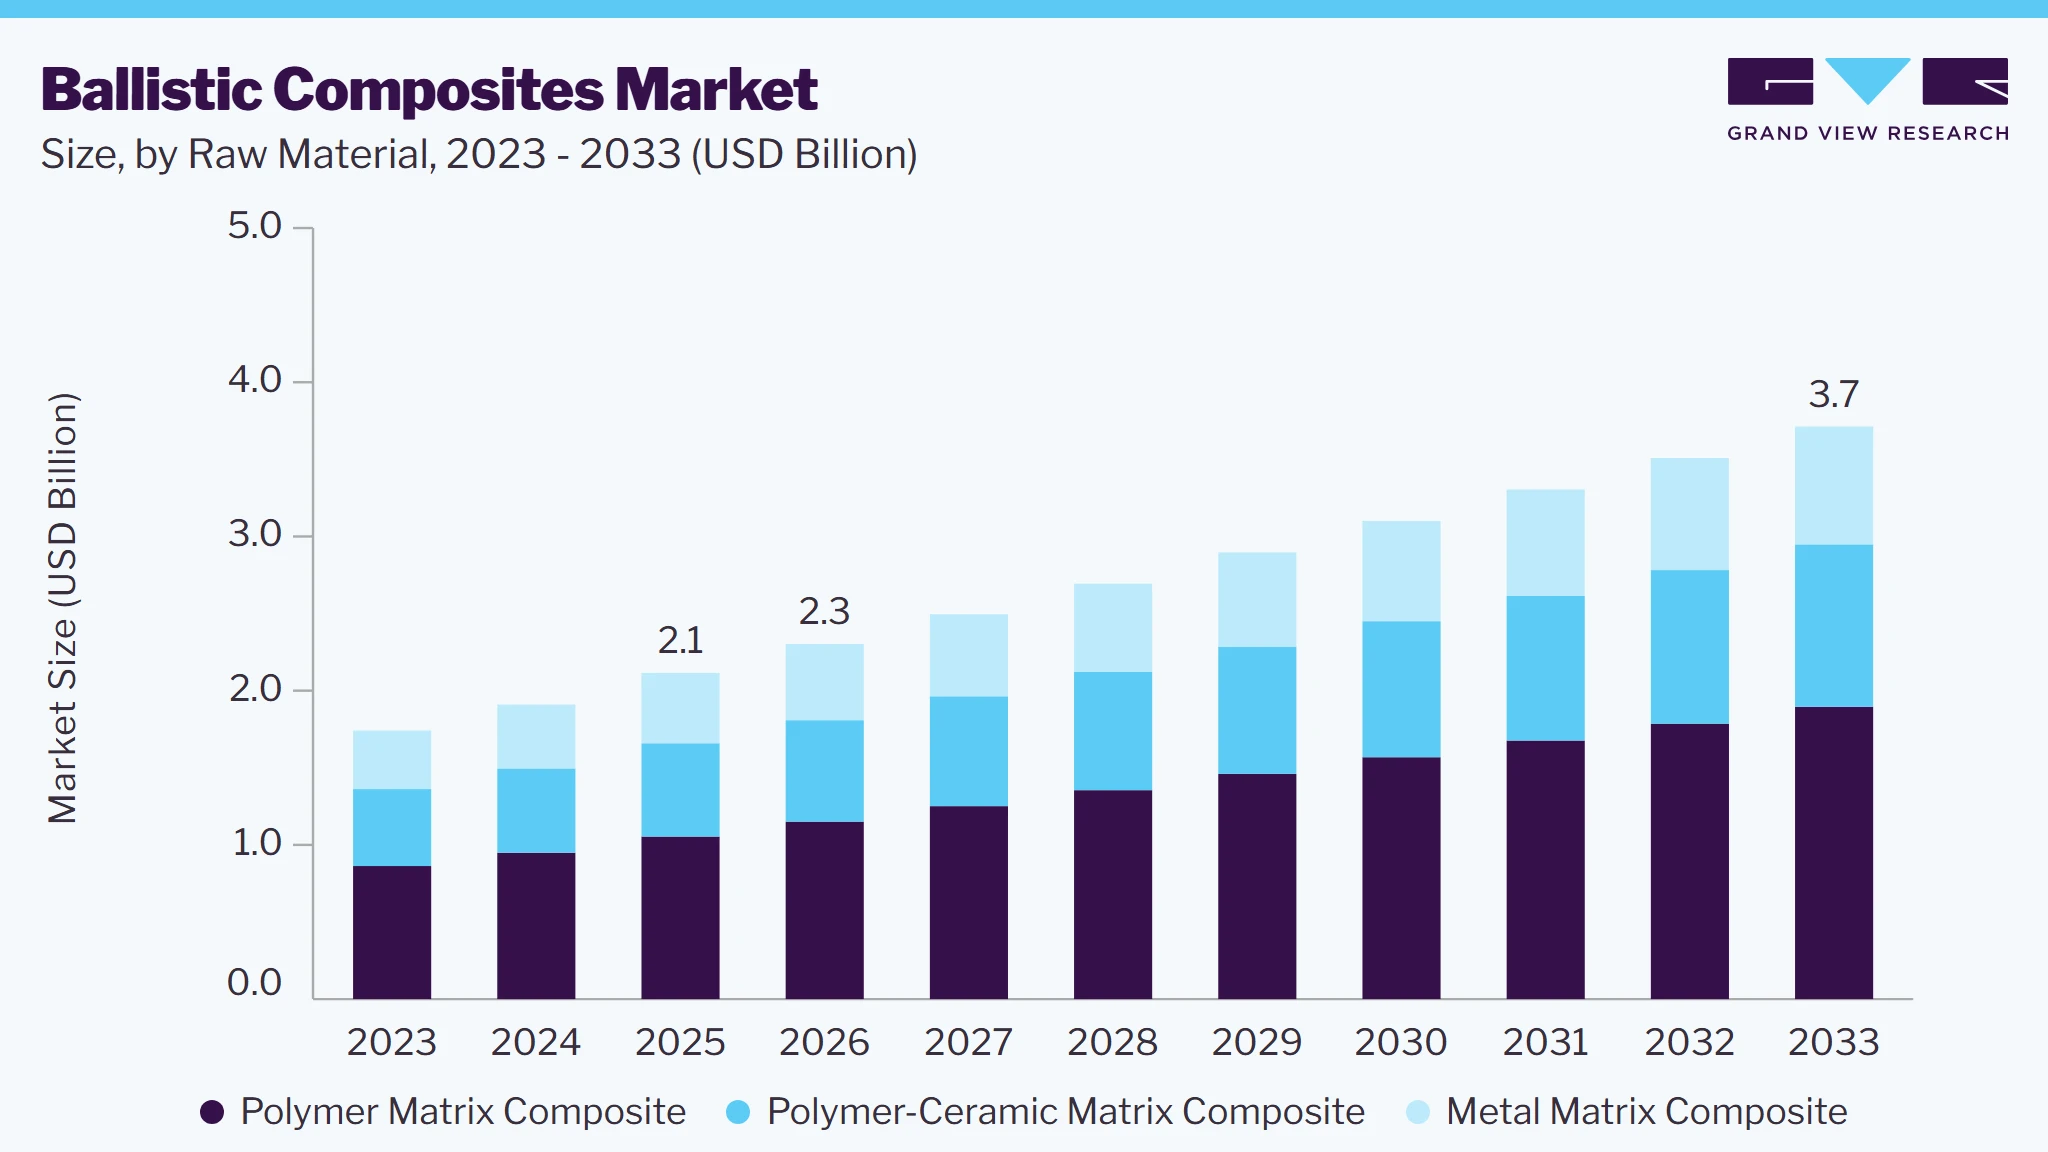 To learn more about this report, Download Free Sample Report
Technological advancements in materials science and the increasing demand for lightweight, high-performance solutions are expected to drive the growth of the ballistic composites industry. Innovations in composite materials, particularly improved fibers and matrix systems, enable the creation of lighter, stronger, and more durable products for military, law enforcement, and defense applications. In addition, the rising need for vehicle armor, body armor, and protective gear further fuels this demand. As safety standards evolve and industries prioritize mobility and efficiency, ballistic composites are poised for widespread adoption, expanding their market presence globally.
Market Dynamics
The ballistic composites market is witnessing strong growth due to increasing defense modernization programs, rising geopolitical tensions, and growing demand for lightweight yet high-performance protective materials. Ballistic composites offer superior strength-to-weight ratios compared to conventional steel armor, making them highly suitable for body armor, helmets, armored vehicles, aircraft protection systems, and naval applications. Continuous innovations in aramid fibers, ultra-high molecular weight polyethylene (UHMWPE), ceramic matrix composites, and hybrid composite technologies are improving ballistic resistance while reducing overall system weight. Rising investments in soldier modernization programs and homeland security initiatives are further supporting market expansion across developed and emerging economies.
Defense agencies worldwide are increasingly replacing traditional metallic armor systems with advanced ballistic composites to improve mobility, survivability, and operational efficiency. Modern military operations require lightweight protective equipment that enhances soldier endurance and vehicle maneuverability without compromising protection levels. As a result, armed forces are investing heavily in advanced composite-based body armor, helmets, armored vehicles, and aircraft protection systems. Rising defense budgets and long-term military modernization programs continue to create substantial demand for ballistic composites globally.
Additionally, growing geopolitical tensions and evolving battlefield threats are accelerating the adoption of next-generation armor solutions. Advanced materials such as aramid fibers, UHMWPE, and ceramic-reinforced composites provide superior ballistic protection while significantly reducing weight compared to conventional steel armor. These advantages are driving widespread implementation across military, law enforcement, aerospace, and homeland security sectors, creating long-term growth opportunities for ballistic composite manufacturers.
Despite their performance advantages, ballistic composites face challenges related to high production costs and complex manufacturing processes. Advanced fibers, specialized resins, and ceramic materials require sophisticated fabrication techniques and extensive quality control procedures, increasing overall product costs. This cost burden can limit adoption among budget-constrained defense organizations and commercial end users, particularly in developing economies.
Technological advancements in smart armor systems, nanocomposites, hybrid composite structures, and advanced manufacturing technologies are creating significant opportunities within the ballistic composites market. Manufacturers are increasingly focusing on integrating lightweight materials with enhanced energy absorption capabilities, multi-threat protection, and embedded sensor technologies. These innovations are improving protection performance while reducing weight and operational burden for defense personnel.
Market Concentration & Characteristics
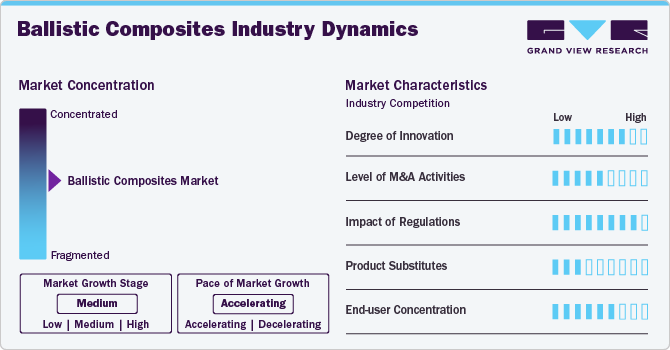
The market growth stage is medium, and the pace of growth is accelerating. Ongoing efforts by governments and key industry participants have resulted in concentrated market scenarios. In June 2024, Graphene Composites (GC) partnered with Black Swan Graphene Inc. to supply Black Swan’s advanced graphene for integration into GC Shield, an innovative, patented ballistic protection technology designed to enhance safety and performance. These combined efforts are propelling the growth and evolution of the ballistic composites market.
 To learn more about this report, Download Free Sample Report
The global ballistic composites industry is characterized by the growing integration of smart technologies, driving high innovation. Advanced materials, including smart fabrics and composites with embedded sensors, are being developed to enhance the performance and functionality of ballistic protection systems. These innovations enable real-time monitoring of armor integrity, improving safety and durability. Incorporating smart technologies enhances ballistic materials' effectiveness and creates new applications across defense, law enforcement, and personal protection sectors, fueling market growth and transformation. For instance, in January 2025, Dyneema launched its most advanced hard ballistic materials-Dyneema HB330 and HB332-featuring third-generation fiber technology. These unidirectional materials deliver a 45% weight reduction while significantly improving ballistic protection in armor systems, including body inserts, helmets, and vehicle armor.
Analyst Perspective
The ballistic composites market is evolving beyond its traditional role as an armor materials segment and is increasingly being shaped by advancements in lightweight protection technologies, high-performance material engineering, and next-generation survivability requirements. The demand is being driven by the growing need for solutions that offer superior ballistic resistance while reducing weight, thereby enhancing soldier mobility, vehicle efficiency, and overall mission effectiveness. The strongest opportunities are emerging across body armor, military helmets, armored vehicles, aerospace protection systems, and homeland security applications, where end users are actively replacing conventional metallic armor with advanced composite materials. Continued military modernization programs, rising defense expenditures, geopolitical uncertainties, and the increasing focus on multi-threat protection capabilities are expected to sustain long-term market growth and accelerate the adoption of advanced ballistic composites across global defense and security sectors.
Raw Material Insights
Based on raw material, the polymer matrix composite segment led the market with the largest revenue share of 49.8% in 2025 and is expected to grow at a CAGR of 7.4% over the forecast period, driven by properties offered by polymer matrix, such as low-weight features and robust performance. Polymer composites offer lower weight than traditional materials, especially ceramic or steel. This helps reduce physical strain and enhances the mobility of the personnel wearing protective gear. The polymer matrix also protects against bullets. Hence, there is an increase in the use of polymer matrix for manufacturing components such as helmets, body armor, and more.
The polymer-ceramic matrix composites segment is anticipated to grow at a significant CAGR of 7.8% over the forecast period. The combination of polymer and ceramic offers enhanced protection against penetration and impacts. Many companies are investing in research and development to explore new ways to improve the performance for polymer-ceramic matrix components. Furthermore, increasing demand for ballistic components in industries, particularly military and defense, helps in the segment's growth.
End-use Insights
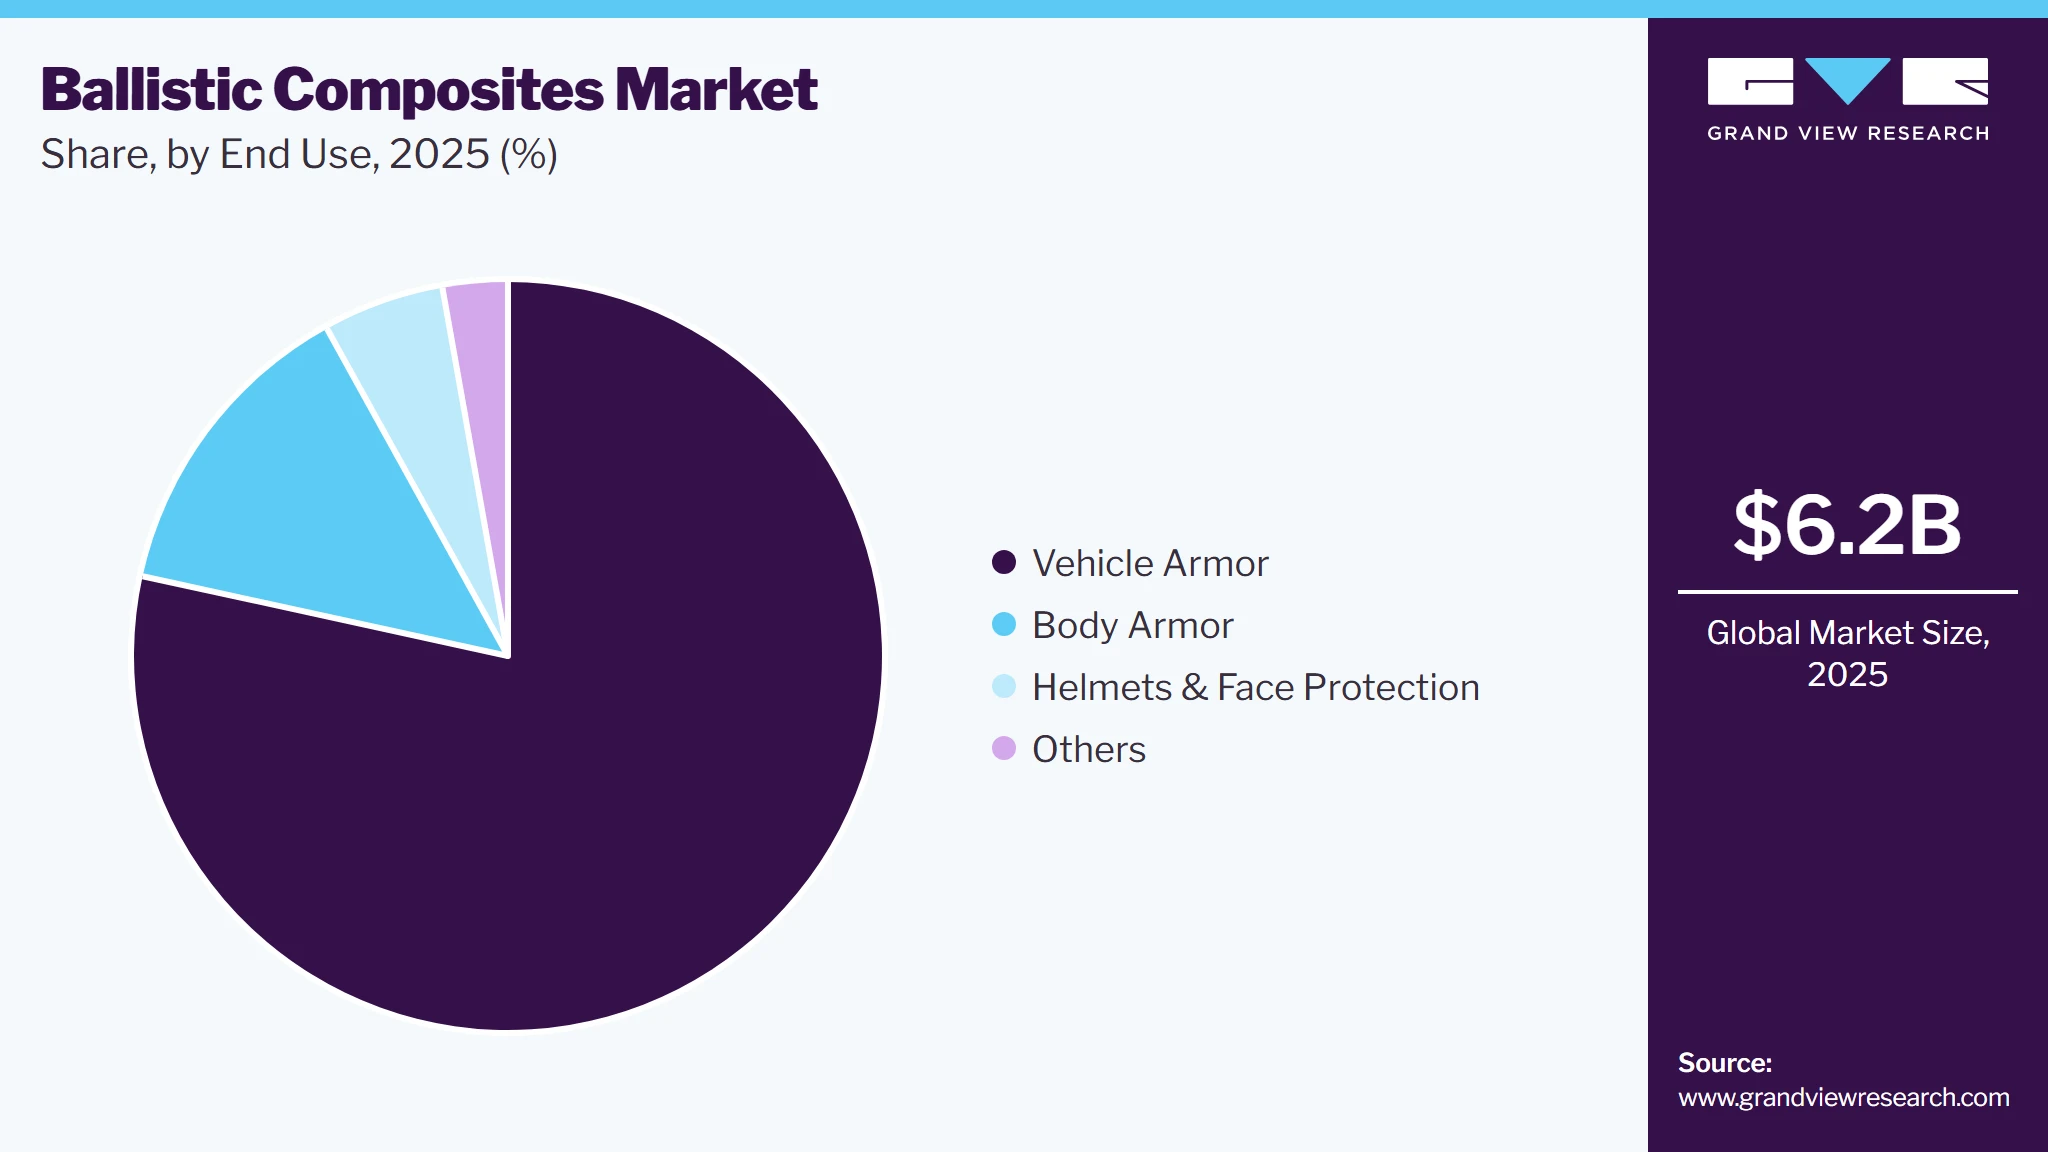
Based on end use, the vehicle armor segment led the market with the largest revenue share of 40.7% in 2025 and is expected to grow at a CAGR of 6.7% over the forecast period. The rising use of ballistic composites for vehicle protection and the increased prevalence of terrorism, armed conflicts, and security threats have driven growth in the industry. The growing adoption of vehicle armor by high-profile individuals and government personnel has increased its significance. In addition, the lightweight nature and enhanced protective properties of ballistic composites have led to a rise in armored vehicle manufacturing within the market.
 To learn more about this report, Download Free Sample Report
The body armor segment is projected to witness the fastest CAGR from 2025 to 2030. The market growth is due to increased demand for body armor for military and police personnel due to rising civil unrest and terrorism. Governments emphasize improving the protection of frontline personnel during conflicts. Therefore, many companies are developing weapons and equipment solutions that offer maximum protection. The rise in defense budgets by governments of major countries has led to increased demand for body armor.
Regional Insights
North America dominated the ballistic composites market with the largest revenue share of 37.5% in 2025. Increased defense spending in North America drives significant demand for ballistic composites, especially in advanced military applications such as armored vehicles, body armor, and helmets. The U.S. Department of Defense's substantial budget allocation for defense technologies enhances the adoption of these materials. Moreover, the expansion of ballistic composites into commercial sectors, including law enforcement, private security, and armored vehicle manufacturing, is further fueling market growth. The combination of defense investments and broader commercial usage increases the overall market size and accelerates innovation in composite material technologies.
 To learn more about this report, Download Free Sample Report
U.S. Ballistic Composites Market Trends
The ballistic composites market in U.S. held the largest share in the North America region in 2025. Advancements in fiber technology, particularly the development of materials such as aramid and UHMWPE, enhance the performance of ballistic composites by offering superior strength-to-weight ratios. These innovations allow lighter, more effective armor systems, improving mobility and protection. Furthermore, the integration of smart technologies is boosting market growth. Embedding sensors and monitoring systems into ballistic composites enables real-time data collection, threat detection, and enhanced performance during critical operations. These developments are driving demand for advanced composite solutions, propelling the U.S. ballistic composites industry expansion.
Europe Ballistic Composites Market Trends
Europe ballistic composites market is set to experience significant expansion over the forecast period. This is owing to the rise in civil unrest, organized crime, and terrorist attacks in the region. This has led to governments adopting increased usage of ballistic equipment to improve the protection of their military and law enforcement personnel. Furthermore, the presence of technologically advanced manufacturing companies aids in producing high-quality military and ballistic equipment. Hence, these factors help the region's market growth of ballistic composites. Enhanced protective gear, including body armor and armored vehicles, is a priority for improving officer safety, increasing the demand for advanced composite materials. Advancements in materials science, such as developing lightweight yet highly durable fibers - UHMWPE and aramid, further contribute to this trend. These innovations enable the creation of more efficient and effective ballistic solutions, driving the expansion of the market in response to evolving security needs.
Germany's ballistic composites market is expected to grow rapidly due to the rising defense budget, which improves the country's security against increasing terrorist attacks and crimes. Major companies focus on domestic production of ballistic composites to reduce their dependency on imported equipment. Furthermore, the rise in military personnel has led to increased demand for ballistic equipment in the country.
Asia Pacific Ballistic Composites Market Trends
Asia Pacific ballistic composites market is expected to grow at the fastest CAGR of 7.9% from 2026 to 2033, owing to indigenous defense manufacturing and strategic defense investments by ASEAN nations. Countries such as India are promoting local production through initiatives such as "Make in India" to decrease reliance on imports. Additionally, significant defense spending in nations including Indonesia, Japan, and others highlights an increasing demand for advanced protective materials. These factors are creating new opportunities for ballistic composites, driving market expansion across various defense sectors, from armored vehicles to personal protective gear.
India ballistic composites market accounted for the largest share in the regional market in 2024, attributed to the growing preference for lightweight and high-performance materials in India. Aramid and UHMWPE fibers are gaining popularity due to their superior strength-to-weight ratios, offering enhanced protection and mobility. These advanced composites are increasingly being integrated into defense applications, including body armor and armored vehicles. Moreover, the expansion of ballistic composites into commercial sectors such as private security, armored vehicle manufacturing, and law enforcement is further contributing to market growth, broadening their adoption beyond traditional military uses.
Key Ballistic Composites Company Insights
Some of the key companies in the ballistic composites industry include Honeywell International Inc.; BAE Systems; DuPont; Avient Corporation; and Morgan Advanced Materials.
-
Honeywell International Inc. delivers innovative solutions across diverse industries, including aerospace, building technologies, safety, performance materials, and industrial automation. Its products and services enhance efficiency, sustainability, and safety, aiming to create smarter, more connected environments.
-
BAE Systems provides cutting-edge defense, aerospace, and security solutions, including advanced military technologies, cybersecurity, naval ships, and intelligence systems. Its products support governments and commercial clients worldwide, enhancing national defense, security, and critical infrastructure capabilities.
Key Ballistic Composites Companies:
The following key companies have been profiled for this study on the ballistic composites market.
-
Honeywell International Inc.
-
TEIJIN LIMITED
-
BAE Systems
-
DuPont
-
Avient Corporation
-
Morgan Advanced Materials
-
3M
-
Saint-Gobain Performance Plastics Corporation
-
TenCate Protective Fabrics
-
Gurit Services AG
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Honeywell International Inc., TEIJIN LIMITED, BAE Systems, DuPont)
- Focus on long-term defense procurement contracts and military modernization programs.
- Invest heavily in R&D for advanced aramid, UHMWPE, and hybrid armor technologies.
- Expand global manufacturing and vertically integrate raw material supply chains.
- Strong brand recognition and established relationships with defense agencies worldwide.
- Extensive product portfolios covering fibers, composites, armor systems, and protective equipment.
- Large-scale production capabilities supported by global distribution networks.
- Higher operational costs due to large manufacturing footprints and regulatory compliance requirements.
- Longer product development and approval cycles for new armor technologies.
- Dependence on government defense budgets and procurement timelines.
Emerging Players (Avient Corporation, Morgan Advanced Materials, TenCate Protective Fabrics, Gurit Services AG)
- Target niche ballistic protection applications and specialty armor solutions.
- Develop customized composite materials for specific defense and law-enforcement requirements.
- Form strategic partnerships with OEMs, armor integrators, and defense contractors.
- Greater flexibility in product development and customization.
- Faster adoption of emerging composite and ceramic technologies.
- Ability to address specialized customer requirements with innovative solutions.
- Limited production scale compared to industry leaders.
- Lower bargaining power in large military procurement programs.
- Restricted global market presence and comparatively smaller R&D budgets.
Recent Developments
-
In March 2024, Avient Corporation announced the launch of Polystrand thermoplastic composite materials. These materials offer properties such as enhanced strength, low weight, and corrosion resistance. The polystrand portfolio included Thermoballistic panels, Polystrand tapes, Hammerhead marine composite panels, and more.
-
In November 2023,Integris Composites introduced customizable ballistic shields and soft body armor vests, featuring its "make your own shield" concept and Rapid Don/Doff system. The gear combines HDPE, aramids, and ceramics to provide high protection and tailored solutions.
-
In April 2023, DuPont announced the launch of its new product, Kevlar EXO. It is an aramid fiber offering flexibility and low-weight properties. The material is used by law enforcement officers and military personnel to manufacture soft body armor. It offers ballistic protection without reducing mobility.
Ballistic Composites Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.1 billion
Estimated market size in 2026
USD 2.3 billion
Projected market size by 2033
USD 3.7 billion
Growth rate
CAGR of 7.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Raw material, end-use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; Italy; Spain; China; Japan; India; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
Honeywell International Inc.; TEIJIN LIMITED; BAE Systems; DuPont; Avient Corporation; Morgan Advanced Materials; 3M; Saint-Gobain Performance Plastics Corporation; TenCate Protective Fabrics; Gurit Services AG.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Ballistic Composites Market Report Segmentation
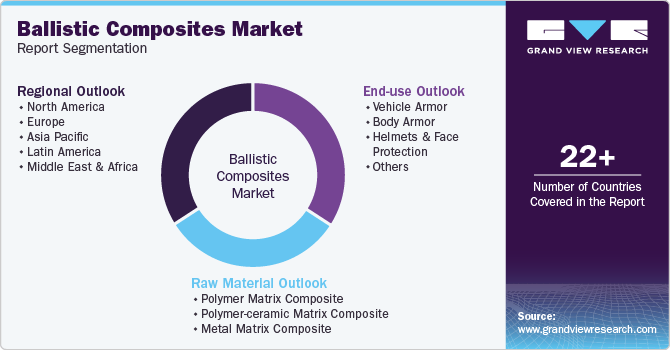
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global ballistic composites market report based on raw material, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Raw Material Outlook (Revenue, USD Million, 2021 - 2033)
-
Polymer Matrix Composite
-
Polymer-ceramic Matrix Composite
-
Metal Matrix Composite
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Vehicle Armor
-
Body Armor
-
Helmets & Face Protection
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The ballistic composites market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each ballistic composites segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Raw Material
Revenue capture definition
Polymer Matrix Composite
Revenue generated from ballistic composites manufactured using polymer-based matrix systems reinforced with high-performance fibers such as aramid, ultra-high molecular weight polyethylene (UHMWPE), carbon fiber, and glass fiber. This segment includes revenues from the production and sale of lightweight ballistic panels, armor systems, helmets, shields, and protective structures utilized across defense, law enforcement, aerospace, and security applications.
Polymer-Ceramic Matrix Composite
Revenue generated from ballistic composites incorporating polymer matrices combined with ceramic materials such as alumina, silicon carbide, boron carbide, and other advanced ceramics. This segment includes revenues from the manufacture and sale of high-performance armor solutions designed to provide enhanced penetration resistance, multi-hit protection, and lightweight ballistic performance for military vehicles, body armor, aircraft, and naval defense systems.
Metal Matrix Composite
Revenue generated from ballistic composites produced using metal matrices reinforced with ceramic particles, fibers, or other strengthening materials. This segment includes revenues from the production and sale of advanced armor structures, vehicle protection systems, aerospace components, and specialized defense equipment requiring high impact resistance, structural integrity, and durability under extreme operating conditions.
Segment - End Use
Revenue capture definition
Vehicle Armor
Revenue generated from ballistic composite materials used in armored military vehicles, tactical vehicles, personnel carriers, combat vehicles, naval vessels, and aerospace platforms. This segment includes revenues from armor panels, spall liners, structural protection systems, and lightweight composite armor solutions designed to enhance vehicle survivability while minimizing weight.
Body Armor
Revenue generated from ballistic composite materials utilized in personal protective equipment such as bullet-resistant vests, tactical armor carriers, protective inserts, and soft armor systems. This segment includes revenues from composite-based body protection solutions supplied to military personnel, law enforcement agencies, security forces, and civilian protection markets.
Helmets & Face Protection
Revenue generated from ballistic composite materials used in military helmets, combat helmets, tactical headgear, ballistic visors, face shields, and facial protection systems. This segment includes revenues from lightweight protective equipment designed to provide resistance against ballistic threats, fragmentation, and impact hazards.
Others
Revenue generated from ballistic composite applications not included under vehicle armor, body armor, or helmets and face protection. This segment includes revenues from ballistic shields, protective barriers, aircraft armor, naval protection systems, bomb disposal equipment, security infrastructure, and other specialized defense and homeland security applications.
Estimation Model
Layer Name
Key Question
Description
Global Defense & Security Spending Analysis
What is the total addressable spending base supporting ballistic protection systems globally?
Estimation begins with evaluating global defense budgets, homeland security expenditures, law enforcement spending, and military modernization investments. Macroeconomic indicators, geopolitical tensions, military procurement programs, and defense infrastructure investments are analyzed to determine the overall demand potential for ballistic protection solutions.
Ballistic Protection Systems Adoption Analysis
What proportion of defense and security spending is allocated to ballistic protection equipment?
This layer assesses spending on body armor, combat helmets, armored vehicles, aircraft protection systems, naval armor, ballistic shields, and protective infrastructure. Adoption trends across military, law enforcement, border security, and special operations units are evaluated to estimate the market size for ballistic protection systems.
Ballistic Composite Material Penetration Analysis
What percentage of ballistic protection systems utilize composite-based armor materials?
This layer examines the penetration of polymer matrix composites, polymer-ceramic matrix composites, metal matrix composites, aramid fiber composites, UHMWPE composites, and hybrid armor materials within ballistic protection applications. The shift from conventional steel armor to lightweight advanced composites is incorporated into the analysis.
Ballistic Composites Revenue Estimation
What revenue is generated from the production and sale of ballistic composite materials and solutions?
The final layer quantifies revenues generated from ballistic composite manufacturers supplying raw materials, armor panels, body armor inserts, helmets, vehicle armor systems, and other protective composite solutions. Revenue estimates are segmented by raw material type, end-use application, region, and major industry participants to derive the total ballistic composites market size.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Regulatory and Standards Framework Assessment
Analysis of ballistic testing standards, military specifications, defense procurement requirements, certification protocols, and export control regulations governing ballistic protection products
Assisted companies in navigating compliance requirements, accelerating product qualification processes, and mitigating regulatory risks associated with defense applications
Regional Growth Opportunity Analysis
Assessment of defense spending patterns, military procurement programs, indigenous manufacturing initiatives, and security investments across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa
Enabled strategic market entry planning, regional expansion prioritization, and identification of high-growth countries for future business development
Technology and Innovation Mapping
Comprehensive review of advancements in aramid fibers, UHMWPE composites, ceramic armor systems, hybrid composite structures, nanomaterials, and smart armor technologies
Provided insights into emerging technologies, future product development directions, and innovation-driven growth opportunities across defense applications
Frequently Asked Questions About This Report
The global ballistic composites market size was valued at USD 2.1 billion in 2025 and is estimated at USD 2.3 billion for 2026.
The global ballistic composites market is expected to grow at a CAGR of 7.1% from 2026 to 2033, reaching USD 3.7 billion by 2033.
North America dominated with a revenue share of 37.5% in 2025.
Some key players operating in the ballistic composites market include Honeywell International, DuPont, DSM, MKU, Teijin, BAE Systems, Gurit, and Gaffco ballistics.
Key factors that are driving the market growth include heavy investment in military and other armed forces, innovative gadgets, and increasing research & development for improving the efficiency of the armors.
The polymer matrix composite segment is the fastest growing in the ballistic composites market.
The body armor is the fastest growing segment in the ballistic composites market.
The polymer matrix composite segment led the market with the largest revenue share of 49.8% in 2025.
The vehicle armor segment accounted for the largest market revenue share of 40.7% in 2025
About the Author(s)
Specialty Glass, Ceramic & Fiber Research Team
Advanced Materials · Specialty Glass, Ceramic & FiberThis report was authored by the specialty glass, ceramic & fiber research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the specialty glass, ceramic & fiber segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


