
- Home
- »
- Plastics, Polymers & Resins
- »
-
High Barrier Packaging Films Market Size Report, 2026-2033GVR Report cover

High Barrier Packaging Films Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Polyethylene, BOPET, Polypropylene), By Product (Bags & Pouches, Wrapping Films, Blister Packs), By Application, By Region, And Segment Forecasts
Market Size, 2025
$37.8BMarket Estimate, 2026
$40.1BMarket Forecast, 2033
$56.8BCAGR, 2026–2033
5.1%High Barrier Packaging Films Market Trends
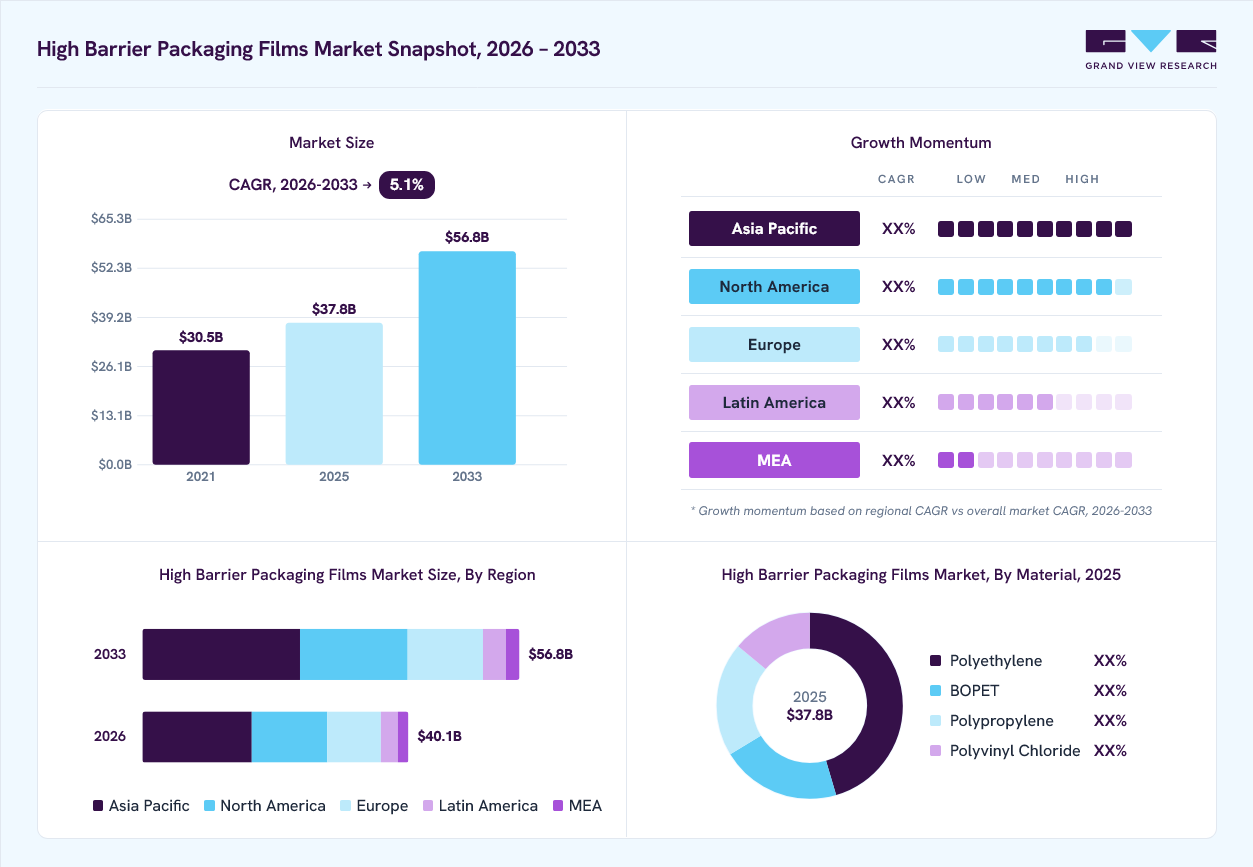
The global high barrier packaging films market size was valued at USD 37.8 billion in 2025 and is projected to grow from USD 40.1 billion in 2026 to USD 56.8 billion by 2033, at a CAGR of 5.1% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 41.0% in 2025. The increasing demand for extended shelf life, safe food preservation, and high-performance packaging solutions is driving the growth of the high barrier packaging films market. The superior oxygen, moisture, and contamination resistance offered by these films is accelerating their adoption across food and beverage and pharmaceutical applications, while rising consumption of convenient packaged products and evolving consumer lifestyles continue to support market expansion during the forecast period.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: Polyethylene (PE) segment held the largest market share of 45.4% in 2025.
- By product: Bags & pouches segment held the largest market share of 43.6% in 2025.
- By application: Food & beverages segment held the largest market share of 51.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (41.0% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 37.8 Billion
- Estimated market size in 2026: USD 40.1 Billion
- Projected market size by 2033: USD 56.8 Billion
- CAGR (2026-2033): 5.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Technological advancements have also played a crucial role in expanding the high barrier packaging films market. Innovations in materials, such as the development of multilayer films and the incorporation of nanotechnology, have significantly improved the barrier properties and mechanical strength of these films. As a result, they are now used in a wide range of applications, from food packaging to industrial uses. Moreover, growing environmental concerns have led to the development of biodegradable and recyclable barrier films, which are gaining popularity among environmentally conscious consumers and businesses.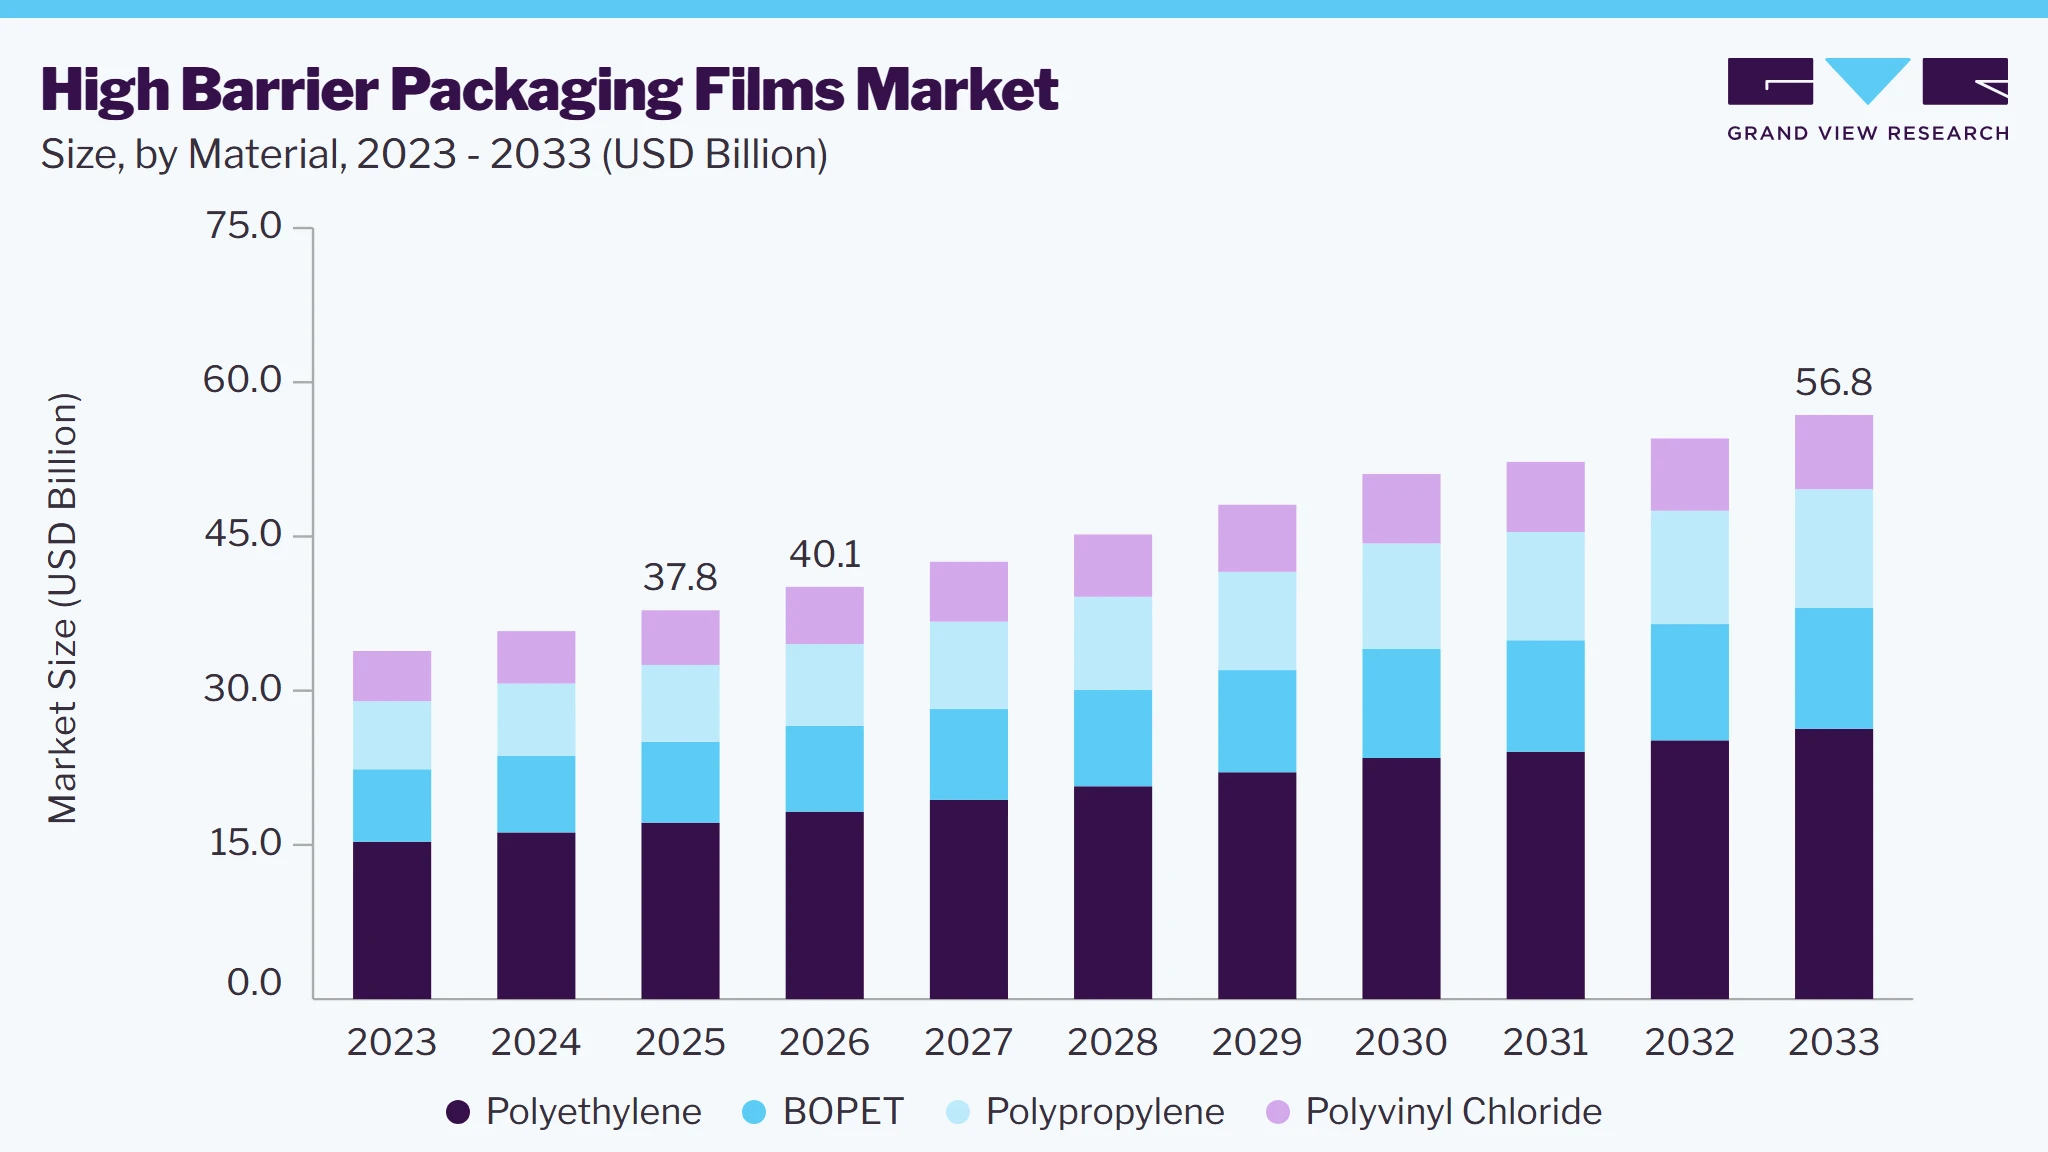 To learn more about this report, Download Free Sample Report
Market Dynamics
The high barrier packaging films market is witnessing robust growth, driven by continuous advancements in packaging technologies and the increasing demand for high-performance protective materials across food, pharmaceutical, and industrial applications. High barrier packaging films offer an excellent combination of oxygen and moisture resistance, mechanical strength, product protection, and extended shelf life, accelerating their adoption across diverse end-use industries. Furthermore, ongoing innovations in multilayer film structures, nanotechnology integration, and the development of recyclable and sustainable barrier films continue to enhance product performance and strengthen the long-term growth prospects of the global high barrier packaging films market.
The high barrier packaging films market is experiencing steady growth, driven by expanding demand across the food, beverage, and pharmaceutical industries, where the need for high-performance packaging solutions continues to increase. High barrier packaging films are extensively used for flexible packaging, pouches, blister packs, sachets, and vacuum packaging owing to their superior oxygen, moisture, aroma, and contamination barrier properties. These performance advantages help extend product shelf life, preserve freshness, reduce food waste, and maintain product integrity, accelerating the adoption of high barrier packaging films across diverse consumer and healthcare applications.
Market growth is further supported by the rapid expansion of e-commerce, increasing consumption of packaged and convenience foods, and rising regulatory requirements for food and pharmaceutical safety across global markets. The growing preference for lightweight, durable, and sustainable packaging solutions has significantly increased demand for advanced high barrier films that offer enhanced product protection and transportation efficiency. As manufacturers continue to prioritize packaging performance, regulatory compliance, and sustainability, high barrier packaging films are expected to witness sustained demand across global packaging applications during the forecast period.
High production costs remains a significant restraint for the high barrier packaging films market. Manufacturing high barrier films requires advanced multilayer processing technologies, specialized coating techniques, and premium raw materials to achieve superior oxygen, moisture, and aroma barrier performance. These requirements increase production costs and limit adoption, particularly among small and medium-sized manufacturers. Additionally, the complex structure of multilayer films creates recycling and disposal challenges, requiring substantial investments in recyclable material innovations and waste management infrastructure, which continue to hinder broader market penetration despite their superior packaging performance.
The increasing focus on sustainable packaging and circular economy initiatives is creating significant growth opportunities for the high barrier packaging films market. Rising demand for recyclable, biodegradable, and high-performance barrier films with superior product protection and extended shelf life is accelerating innovation across the packaging industry. Market growth is further supported by stringent environmental regulations, expanding investments in sustainable packaging technologies, and increasing corporate sustainability commitments. Additionally, rapid urbanization, rising disposable incomes, and growing consumption of packaged goods across emerging economies are expected to drive strong demand for advanced high barrier packaging films during the forecast period.
Analyst Perspective
The high barrier packaging films market is expected to shift from a volume-driven to a value-driven and sustainability-focused industry, driven by demand for advanced solutions that improve product protection, extend shelf life, and reduce food waste. Growth will be led by the food & beverage and pharmaceutical sectors, with additional opportunities in personal care, pet food, and specialty industrial packaging. Advances in multilayer films, high-performance coatings, recyclable mono-materials, and bio-based barriers, along with evolving regulations and circular economy initiatives, will shape product development. Companies with integrated capabilities, material expertise, broad geographic presence, and strong partnerships will be better positioned to capitalize on opportunities. However, resin price volatility, stringent environmental regulations, limited recycling infrastructure, pricing pressure, and continued innovation investments will challenge profitability. Innovation, operational efficiency, and sustainability leadership will increasingly differentiate market leaders.
Drivers, Opportunities & Restraints
The primary drivers of the high barrier packaging films market include the rising demand for packaged food and beverages, increasing consumer awareness regarding food safety, and the need for longer shelf life of products. The growth of the e-commerce sector has also contributed to the increased demand for protective packaging solutions to ensure products reach consumers in optimal condition. Furthermore, the pharmaceutical industry’s stringent regulations for product safety and quality have necessitated the use of high barrier films to protect medications and medical devices from contamination.
 To learn more about this report, Download Free Sample Report
With growing environmental concerns and stringent regulations on plastic usage, there is a substantial demand for eco-friendly alternatives. Companies investing in research and development to create biodegradable and recyclable high barrier films are likely to gain a competitive edge. Additionally, emerging markets in Asia-Pacific and Latin America present lucrative opportunities due to the rapid urbanization, increasing disposable incomes, and changing consumer preferences towards packaged goods in these regions.
The high cost of raw materials and production can limit the adoption of these films, particularly among small and medium-sized enterprises. Additionally, the complex manufacturing process and the need for advanced technology can act as barriers for new entrants. Environmental concerns related to the disposal and recycling of plastic barrier films also pose challenges, necessitating significant investments in developing sustainable solutions and effective recycling infrastructure.
Material Insights
Based on material, the polyethylene (PE) segment led the market with the largest revenue share of 45.4% in 2025. Polyethylene is widely used due to its excellent moisture barrier properties, flexibility, and cost-effectiveness. It's commonly employed in applications requiring moisture resistance, such as food packaging. Biaxially Oriented Polyethylene Terephthalate (BOPET) is another critical material known for its superior strength, clarity, and barrier properties against gases and aromas. This makes it ideal for preserving the freshness of perishable goods and ensuring product integrity.
Polypropylene (PP) is appreciated for its versatility and resistance to chemical and physical stress, making it suitable for a range of packaging needs. Its ability to withstand high temperatures also makes it a preferred choice for microwaveable food packaging. Polyvinyl Chloride (PVC), though less favored due to environmental concerns, remains in use for its excellent clarity and barrier properties, particularly in applications requiring high visibility and contamination prevention, such as in pharmaceutical and medical packaging.
Product Insights
Based on product, the bags & pouches segment led the market with the largest revenue share of 43.6% in 2025. Bags and pouches are popular due to their versatility and convenience. They are used for packaging a wide range of products, from snacks and pet foods to pharmaceuticals and personal care items. These packaging types offer excellent barrier properties, ensuring product freshness and extending shelf life.
Trays and lidding films are essential in applications requiring rigid packaging solutions, such as ready-to-eat meals and fresh produce. These films provide a high barrier against external contaminants while maintaining product visibility and integrity. Wrapping films are commonly used for bulk packaging and pallet wrapping, providing protection against moisture and physical damage during transportation and storage.
Blister packs are particularly prevalent in the pharmaceutical industry, offering a high level of protection for individual doses of medication. This type of packaging ensures that each dose remains uncontaminated and secure until it is used. Other types of high barrier packaging films, such as laminates and shrink films, serve specialized applications where tailored barrier properties and structural characteristics are essential.
Application Insights
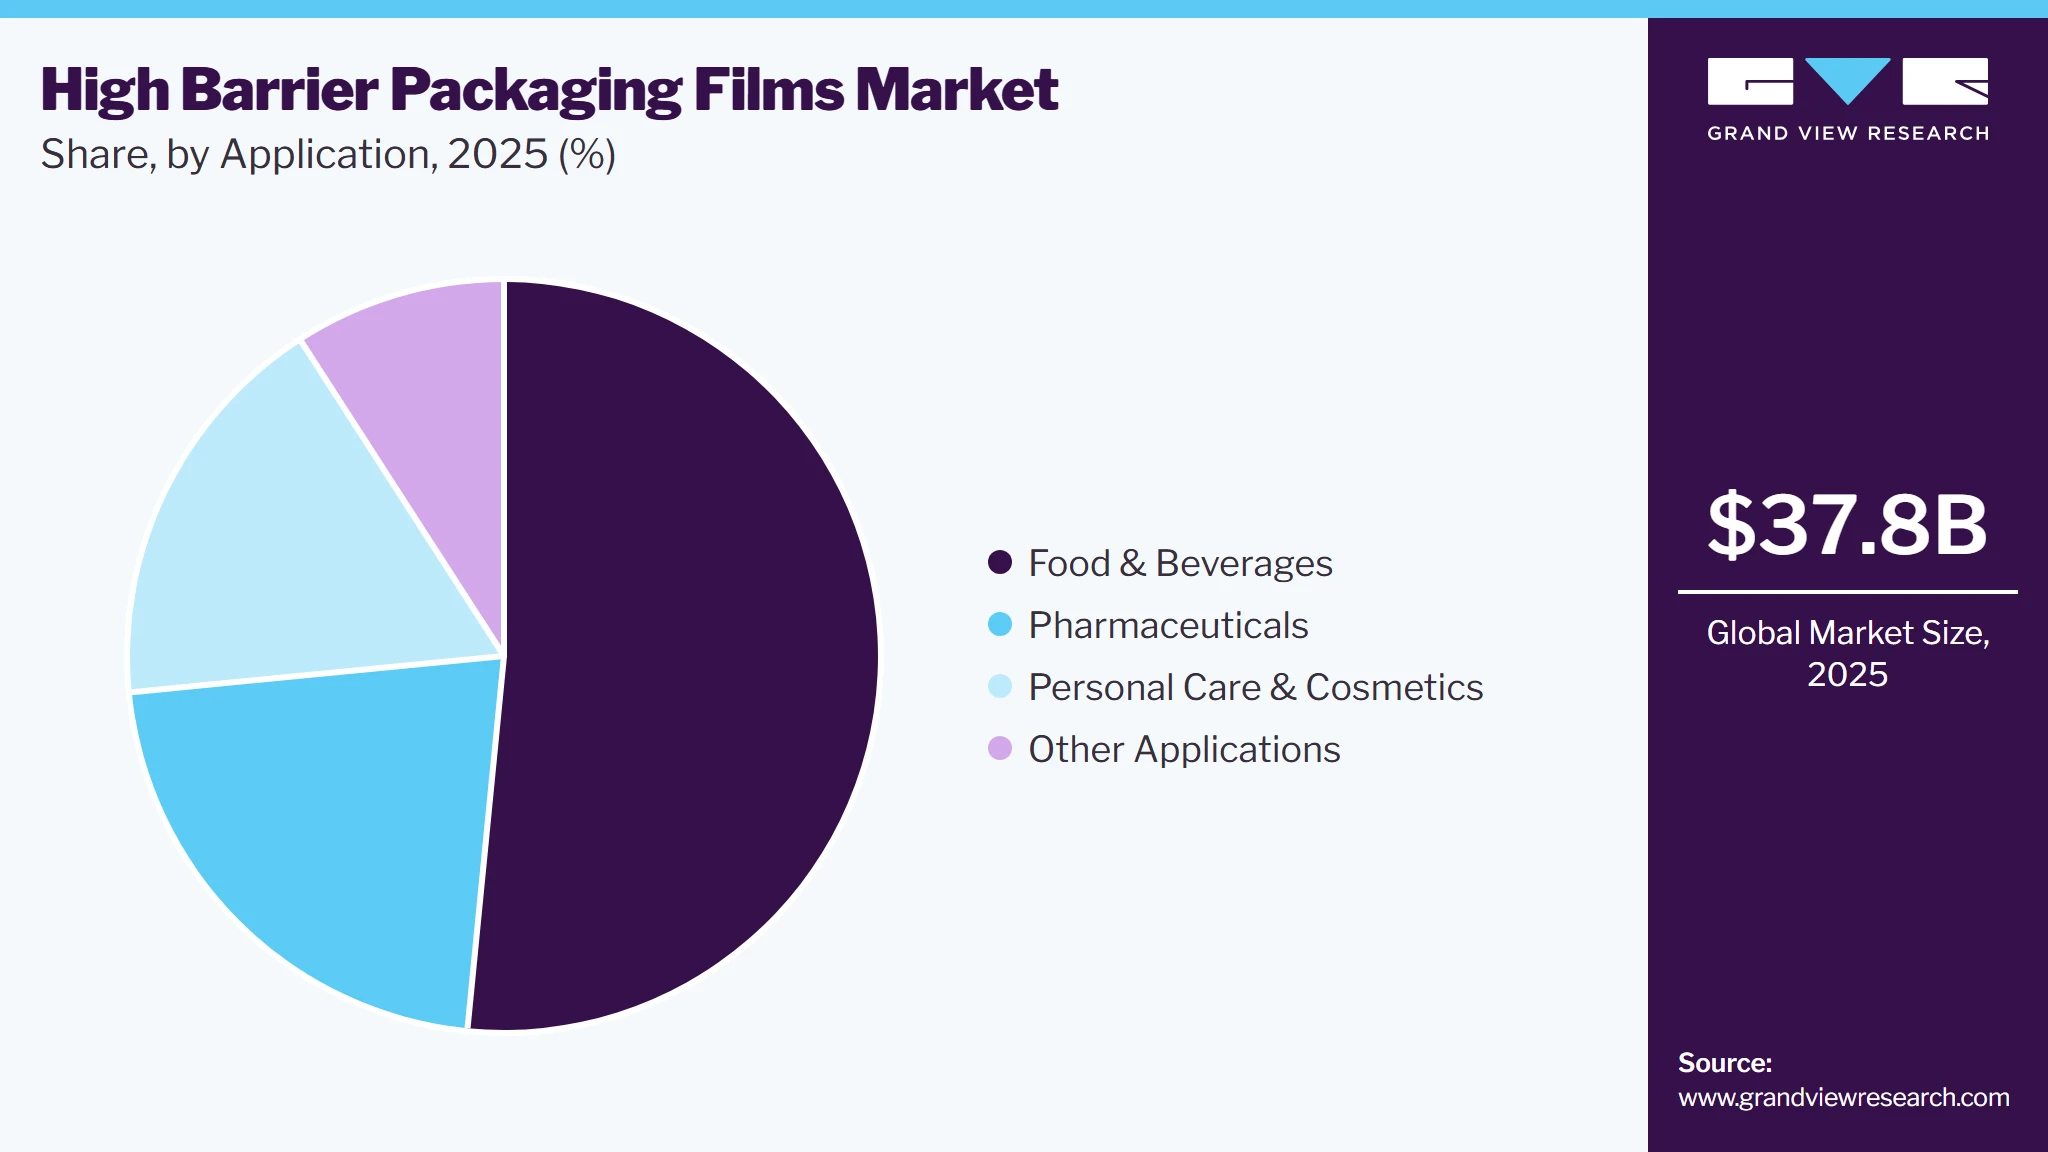
Based on application, the food & beverages segment led the market with the largest revenue share of 51.6% in 2025. In the food and beverages sector, these films are critical for maintaining the freshness and quality of products. They are used to package everything from snacks and dairy products to beverages and frozen foods, providing a robust barrier against moisture, oxygen, and other contaminants.
 To learn more about this report, Download Free Sample Report
The pharmaceutical industry relies heavily on high barrier packaging films to ensure the safety and efficacy of medications. These films protect sensitive pharmaceuticals from environmental factors such as light, moisture, and oxygen, which can degrade the active ingredients. This is crucial for maintaining the potency and shelf life of drugs, as well as ensuring patient safety.
In the personal care and cosmetics industry, high barrier packaging films are used to protect products from contamination and degradation. These films help maintain the integrity and efficacy of various cosmetic products, from lotions and creams to shampoos and conditioners. Other applications include industrial and household products, where high barrier films provide essential protection against environmental factors and physical damage, ensuring product quality, and longevity.
Regional Insights
North America is a significant market for high barrier packaging films, driven by the high consumption of packaged food and beverages, pharmaceuticals, and personal care products. The region's advanced manufacturing capabilities and technological innovations contribute to the development and adoption of high-performance packaging solutions. Additionally, stringent regulations concerning food safety and pharmaceutical packaging standards enhance the demand for high barrier films. Environmental concerns and the push for sustainable packaging solutions also influence market dynamics, leading to increased investment in recyclable and biodegradable films.
U.S. High Barrier Packaging Films Market Trends
The United States, being the largest market in North America, plays a crucial role in the high barrier packaging films industry. The United States market are witnessing robust growth due to their developed industries and consumer markets. The country's robust food and beverage sector, coupled with its significant pharmaceutical industry, drives substantial demand for these films. Innovation and consumer preference for convenience and sustainability are key factors propelling market growth.
Europe High Barrier Packaging Films Market Trends
Europe is a mature market for high barrier packaging films, characterized by its strong emphasis on sustainability and stringent regulatory standards. The region's well-established food and beverage industry and the growing pharmaceutical sector are primary drivers of market growth. Countries like Germany, France, and the United Kingdom lead in the adoption of advanced packaging technologies.
Asia Pacific High Barrier Packaging Films Market Trends
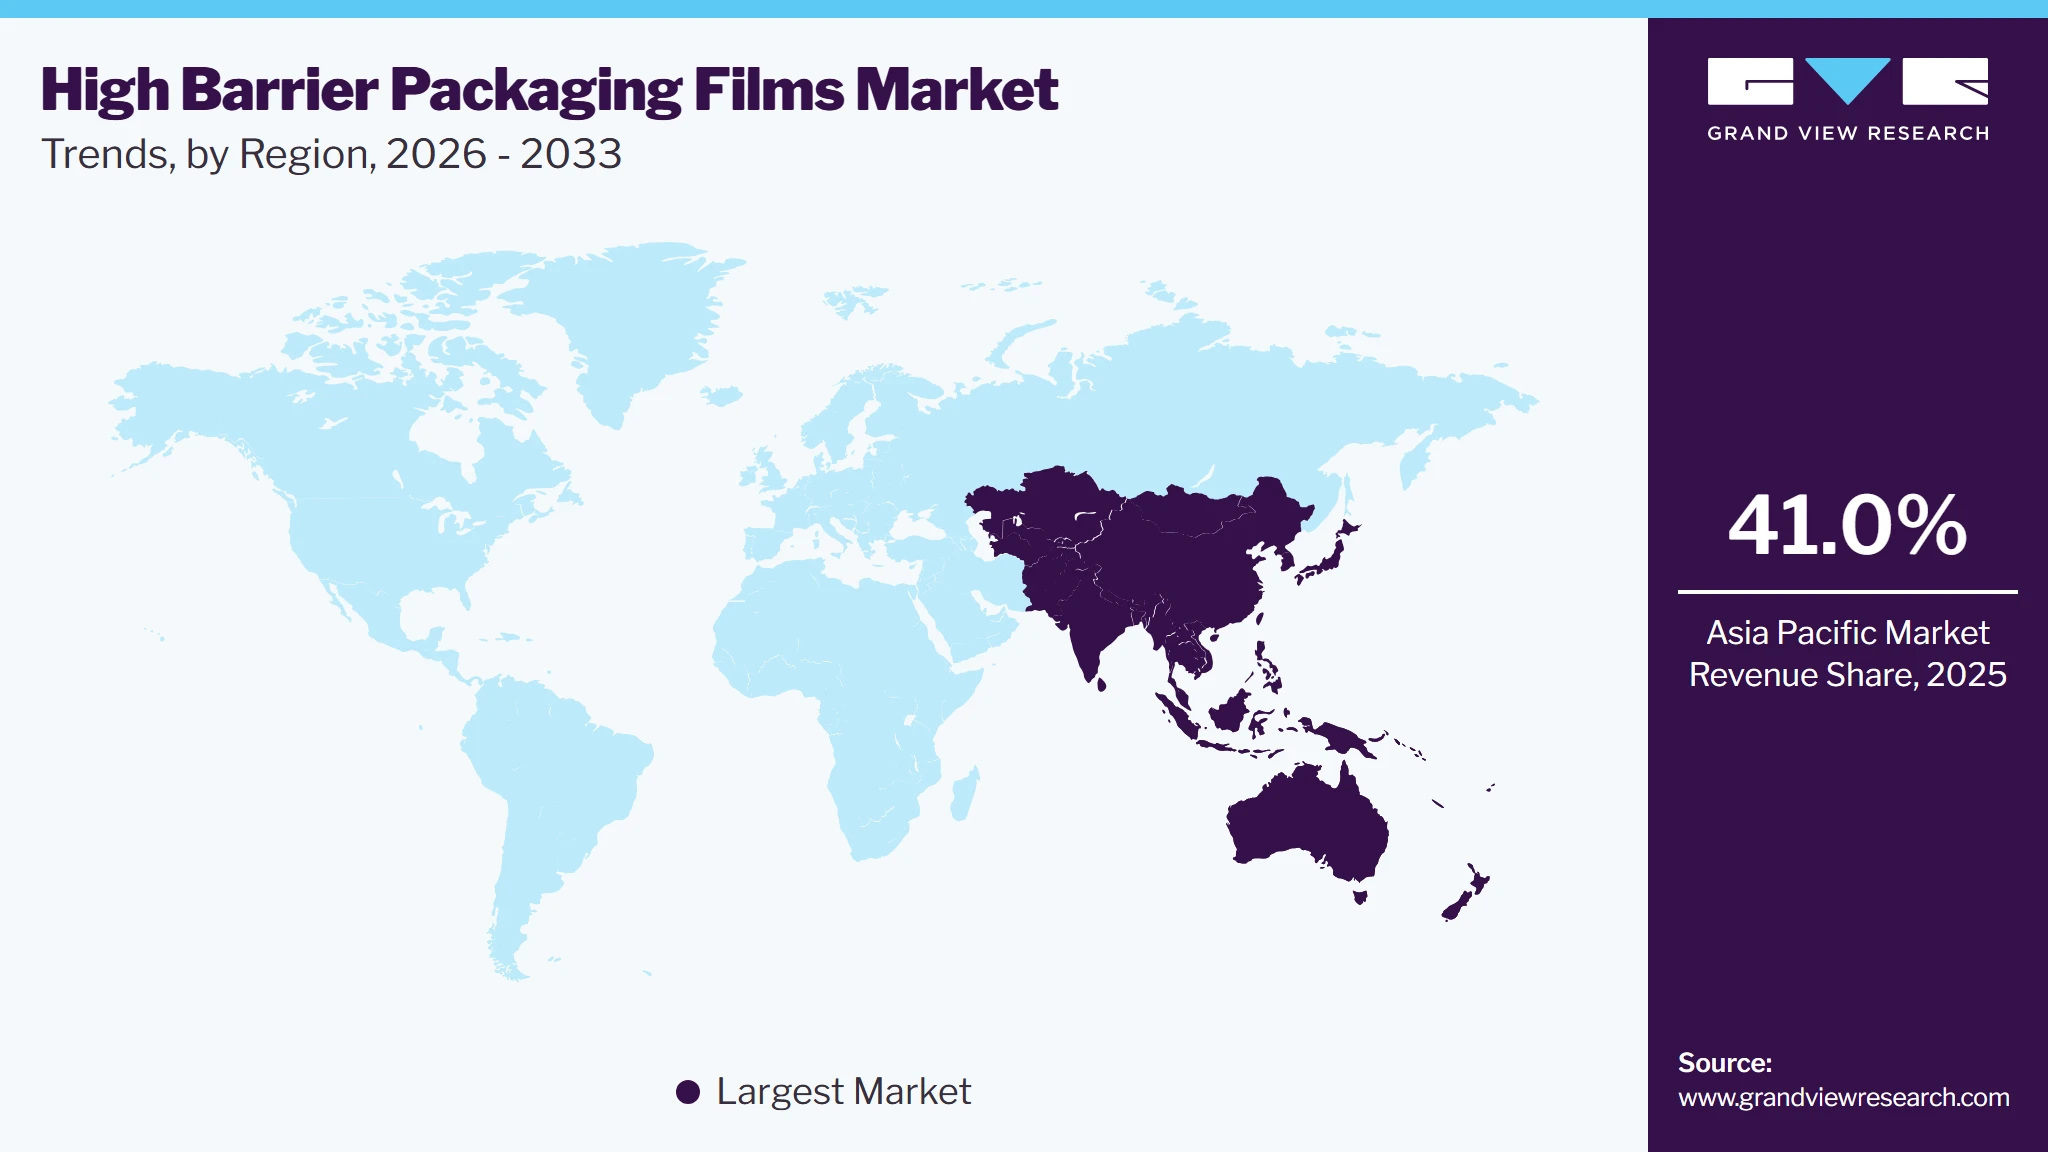
Asia Pacific dominated the high barrier packaging films market with the largest revenue share of 41.0% in 2025. The increasing demand for sustainable packaging solutions and advancements in packaging technologies are driving the market forward. The Asia-Pacific region is experiencing rapid growth due to the expanding food and beverage industry, rising urbanization, and increasing disposable incomes. Countries like China, India, and Japan are major contributors to this growth, with a significant demand for packaged food, pharmaceuticals, and personal care products. The region's large population base and evolving consumer lifestyles are key factors boosting market demand.
 To learn more about this report, Download Free Sample Report
High Barrier Packaging Films Market Company Insights
Major companies such as Amcor plc, Berry Global Inc., Sealed Air Corporation, and Mondi Group hold significant market shares due to their extensive product portfolios, advanced technological capabilities, and strong distribution networks. These companies focus on continuous innovation and the development of sustainable and high-performance packaging solutions to meet evolving consumer demands and regulatory requirements. Strategic collaborations, mergers, and acquisitions are common strategies employed by these market leaders to enhance their market presence and expand their geographical reach.
Key High Barrier Packaging Films Companies
The following key companies have been profiled for this study on the high barrier packaging films market.
-
Amcor plc
-
Sealed air
-
Huhtamaki
-
Klockner pentaplast
-
Mondi
-
Constantia flexibles
-
Berry global inc
-
Coveris
-
Sonoco product company
-
Wipak
-
Uflex limited
-
Printpack
-
Jindal poly films
-
Cosmo films ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Amcor Plc., Sealed Air, Huhtamaki, Klöckner Pentaplast, Mondi, Constantia Flexibles, Berry Global Inc., Coveris, Sonoco Products Company, Wipak, Printpack)
- Focus on strengthening their position in the high barrier packaging films market through the development and commercialization of high-performance multilayer barrier films, flexible packaging solutions, thermoformed packaging, lidding films, pouches, and pharmaceutical packaging for food & beverages, healthcare, personal care, and industrial applications.
- Strong emphasis is placed on expanding sustainable packaging portfolios featuring recyclable, mono-material, bio-based, and high-performance barrier films.
- Continuous investments in packaging innovation, advanced converting technologies, production capacity expansion, and strategic collaborations with food manufacturers, pharmaceutical companies, retailers, and consumer goods companies support global market penetration and long-term commercial growth.
- Extensive expertise in flexible packaging technologies, multilayer film engineering, material science, and global packaging operations enables the commercialization of high barrier packaging films offering superior oxygen and moisture barrier performance, product protection, sealability, and extended shelf life.
- Strong research and development capabilities, integrated manufacturing and converting facilities, established customer relationships, diversified product portfolios, and global distribution networks provide sustainable competitive differentiation and recurring revenue opportunities across multiple end-use industries.
- High capital investment requirements for advanced film extrusion, coating, lamination, and converting technologies increase operational complexity and production costs.
- Market growth is influenced by fluctuations in raw material prices, food and consumer goods demand, and evolving packaging regulations.
- Additionally, increasing sustainability requirements, regulatory pressure on plastic packaging, volatile resin costs, and continuous investments in recyclable packaging technologies and manufacturing modernization may affect profitability and long-term market share.
Emerging Players (Uflex Limited, Jindal Poly Films, Cosmo Films Ltd.)
- Focus on expanding their presence in the high barrier packaging films market through the development of cost-effective, application-specific barrier films, flexible packaging materials, metalized films, and sustainable packaging solutions for food, pharmaceutical, personal care, and industrial applications.
- Emphasis is placed on enhancing barrier performance, improving manufacturing efficiency, expanding product portfolios, and increasing the adoption of recyclable and high-value packaging materials.
- Strategic partnerships with packaging converters, brand owners, regional distributors, and consumer goods manufacturers support product innovation, commercial expansion, and entry into high-growth domestic and international markets.
- Strong flexibility in customized product development, competitive manufacturing costs, integrated film production capabilities, and rapid commercialization enable these companies to effectively address evolving customer requirements.
- Their ability to deliver application-specific packaging solutions, competitive pricing, shorter product development cycles, and expanding manufacturing capacities strengthens adoption across regional and export markets.
- Agile business models, growing sustainability initiatives, and expanding distribution networks further enhance their competitive positioning in the global high barrier packaging films market.
- Limited global brand recognition compared with multinational packaging companies, relatively smaller international converting networks, and comparatively lower research and development resources may restrict competition in premium packaging segments.
- Dependence on regional demand, exposure to raw material price volatility, and increasing compliance requirements for sustainable packaging can constrain market expansion.
- Additionally, significant investments in advanced barrier technologies, global manufacturing expansion, circular packaging solutions, and international customer acquisition are required to compete effectively in the global high barrier packaging films market.
Recent Developments
-
In April 2024, UFlex launched a series of new high barrier packaging films, designed to provide superior product protection and extended shelf life while enhancing sustainability. These advanced packaging solutions cater to the growing demand for high-performance, eco-friendly materials in the flexible packaging industry.
-
In March 2024, Toppan announced the launch of a new high barrier packaging film that combines recyclability with superior barrier performance, enhancing sustainability in the packaging industry.
-
In December 2023, Amcor introduced a new recyclable high barrier packaging film, designed to deliver exceptional product protection while supporting sustainability efforts.
High Barrier Packaging Films Market Report Scope
Report Attribute
Details
Market size in 2025
USD 37.8 billion
Estimated market size in 2026
USD 40.1 billion
Projected market size by 2033
USD 56.8 billion
Growth rate
CAGR of 5.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, product, application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
Amcor Plc.; Sealed Air; Huhtamaki; Klockner Pentaplast; Mondi; Constantia Flexibles; Berry Global Inc; Coveris; Sonoco Product Company; Wipak; Uflex limited; Printpack; Jindal Poly Films; Cosmo Films Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global High Barrier Packaging Films Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented high barrier packaging films market report based on material, product, application, and region:
-
Material Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Polyethylene
-
BOPET
-
Polypropylene
-
Polyvinyl Chloride
-
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Bags & Pouches
-
Trays Lidding Films
-
Wrapping Films
-
Blister Packs
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Food & Beverages
-
Pharmaceuticals
-
Personal Care & Cosmetics
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Italy
-
Spain
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The high barrier packaging films market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each high barrier packaging films segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Material
Revenue capture definition
Polyethylene (PE)
Revenue is captured through the production and sale of polyethylene-based high barrier packaging films used in flexible packaging, pouches, bags, liners, and protective packaging solutions. Demand is driven by excellent moisture barrier properties, flexibility, cost-effectiveness, sealability, and increasing adoption across food, beverage, pharmaceutical, and consumer goods packaging applications.
Biaxially Oriented Polyethylene Terephthalate (BOPET)
Revenue is captured through the commercialization of BOPET-based high barrier packaging films used in laminates, lidding films, retort packaging, and specialty flexible packaging. Growth is supported by high tensile strength, superior oxygen and aroma barrier properties, excellent dimensional stability, transparency, and increasing demand for premium food, pharmaceutical, and industrial packaging applications.
Polypropylene (PP)
Revenue is captured through the production and sale of polypropylene-based high barrier packaging films utilized in snack packaging, confectionery, bakery products, labels, and multilayer flexible packaging. Demand is driven by excellent moisture resistance, lightweight properties, high clarity, heat sealability, and growing consumption of convenience foods and consumer packaged goods worldwide.
Polyvinyl Chloride (PVC)
Revenue is captured through the commercialization of PVC-based high barrier packaging films used in pharmaceutical blister packs, shrink films, medical packaging, and consumer product packaging. Growth is supported by excellent formability, chemical resistance, product visibility, durability, and increasing demand for protective packaging solutions across healthcare, retail, and industrial applications.
Product
Revenue capture definition
Bags & Pouches
Revenue is captured through the production and sale of high barrier bags and pouches used for food, beverage, pharmaceutical, and consumer goods packaging. Demand is driven by superior oxygen and moisture barrier performance, lightweight construction, extended shelf life, convenience, and increasing adoption of flexible packaging solutions.
Trays & Lidding Films
Revenue is captured through the commercialization of high barrier trays and lidding films used for fresh produce, meat, seafood, dairy, and ready-to-eat meal packaging. Growth is supported by enhanced product protection, modified atmosphere packaging compatibility, leak resistance, extended freshness, and increasing demand for packaged convenience foods.
Wrapping Films
Revenue is captured through the production and sale of high barrier wrapping films utilized in food preservation, industrial packaging, and consumer goods applications. Demand is driven by excellent sealing performance, high puncture resistance, product protection, transparency, and increasing use across retail, logistics, and food processing industries.
Blister Packs
Revenue is captured through the commercialization of high barrier blister packaging films used primarily for pharmaceutical products, medical devices, and healthcare applications. Growth is supported by superior moisture and oxygen protection, product integrity, tamper evidence, regulatory compliance, and increasing global demand for secure pharmaceutical packaging solutions.
Other Products
Revenue is captured through the production and sale of specialized high barrier packaging products, including sachets, stick packs, vacuum packaging, thermoformed packaging, and customized flexible packaging formats. Demand is driven by product innovation, application-specific packaging requirements, sustainability initiatives, and expanding end-use industries requiring advanced barrier protection.
Application
Revenue capture definition
Food & Beverages
Revenue is captured through the production and sale of high barrier packaging films used for fresh foods, processed foods, dairy products, beverages, frozen foods, snacks, and ready-to-eat meals. Demand is driven by increasing requirements for extended shelf life, food safety, moisture and oxygen protection, reduced food waste, and growing consumption of packaged food products globally.
Pharmaceuticals
Revenue is captured through the commercialization of high barrier packaging films used in blister packs, medical pouches, sachets, and protective pharmaceutical packaging. Growth is supported by stringent regulatory requirements, superior contamination protection, excellent moisture and oxygen barrier performance, product stability, and increasing global pharmaceutical manufacturing activities.
Personal Care & Cosmetics
Revenue is captured through the production and sale of high barrier packaging films used for skincare, cosmetics, personal hygiene products, and beauty care packaging. Demand is driven by increasing consumer preference for premium packaging, enhanced product preservation, extended product stability, attractive shelf presentation, and growing demand for sustainable flexible packaging solutions.
Other Applications
Revenue is captured through the commercialization of high barrier packaging films used in industrial products, chemicals, electronics, agricultural products, pet food, and specialty consumer goods. Growth is supported by increasing demand for protective packaging, improved storage stability, superior barrier performance, and expanding adoption across diverse industrial and commercial applications.
Estimation Model
Layer No.
Layer Name
Key Question
Description
1
Top-Down High Barrier Packaging Films Demand Assessment Layer
What defines market boundaries?
This layer begins with global demand for high barrier packaging films across food & beverages, pharmaceuticals, personal care & cosmetics, and other industrial packaging applications. Demand is filtered based on packaged food consumption, pharmaceutical production, increasing preference for flexible packaging, rising shelf-life requirements, growing e-commerce activities, and stringent food safety and product protection regulations across major end-use industries.
2
Application Validation Layer
Where is demand generated?
This layer evaluates demand distribution across bags & pouches, trays and lidding films, wrapping films, blister packs, and other specialty packaging formats. Market revenue is aligned with critical packaging performance requirements including oxygen and moisture barrier properties, aroma retention, puncture resistance, heat sealability, product integrity, transparency, and extended shelf life required across diverse packaging applications.
3
Product and Material Conversion Layer
Who captures market revenue?
This layer converts application-level demand into high barrier packaging films market revenue by applying material mix ratios across polyethylene (PE), biaxially oriented polyethylene terephthalate (BOPET), polypropylene (PP), polyvinyl chloride (PVC), and other specialty barrier materials. Revenue allocation considers barrier performance, multilayer film structures, processing technologies, product pricing, sustainability attributes, manufacturing efficiency, and supplier positioning across the global packaging value chain.
4
Regional Commercial Cross-Check Layer
How are assumptions validated?
This layer validates demand concentration by comparing North America's mature food processing and pharmaceutical industries; Europe's demand supported by stringent packaging sustainability regulations and circular economy initiatives; and Asia Pacific's rapid growth driven by expanding packaged food consumption, pharmaceutical manufacturing, urbanization, and e-commerce penetration. It also evaluates emerging opportunities across Central & South America and the Middle East & Africa, supported by increasing retail modernization, rising disposable incomes, growing healthcare investments, and expanding demand for packaged consumer goods.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Delivered detailed market sizing, forecasts, and demand analysis across North America, Europe, Asia Pacific, Middle East & Africa, and Central & South America, with country-level assessment for key markets. Included evaluation of regional consumption patterns, production capacities, regulatory frameworks, packaging trends, and end-use industry demand.
Enables clients to identify high-growth regional markets, optimize geographic expansion strategies, prioritize investments, and align sales and distribution networks with regional demand dynamics.
Cross-Segmentation
Delivered comprehensive cross-analysis by Product (Polyethylene, BOPET, Polypropylene, PVC), Packaging Format (Bags & Pouches, Trays & Lidding Films, Wrapping Films, Blister Packs, Other Products), and Application (Food & Beverages, Pharmaceuticals, Personal Care & Cosmetics, Other Applications) across all major regions.
Provides granular demand insights, identifies high-value market niches, supports product portfolio optimization, and enables targeted go-to-market strategies for specific customer segments.
Opportunity Assessment
Delivered strategic opportunity analysis across high-growth applications, emerging sustainable packaging technologies, recyclable and mono-material barrier films, expanding pharmaceutical and food packaging demand, regional investment hotspots, and untapped customer segments. Included assessment of future innovation opportunities and evolving regulatory landscape.
Assists clients in prioritizing high-return investments, identifying emerging revenue streams, accelerating product innovation, strengthening long-term growth strategies, and improving strategic decision-making in evolving packaging markets.
Frequently Asked Questions About This Report
The global high barrier packaging films market is expected to grow at a CAGR of 5.1% from 2026 to 2033, reaching USD 56.8 billion by 2033.
The key players in the high barrier packaging films market are Amcor Plc.; Sealed Air; Huhtamaki; Klockner Pentaplast; Mondi; Constantia Flexibles; Berry Global Inc; Coveris; Sonoco Product Company; Wipak; Uflex limited; Printpack; Jindal Poly Films; Cosmo Films Ltd.
The global high barrier packaging films market size was valued at USD 37.8 billion in 2025 and is estimated at USD 40.1 billion for 2026.
The Asia Pacific high barrier packaging films market accounted for the largest share of 41.0% market size in 2025.
The bags & pouches segment led with a 43.6% revenue share in 2025.
Based on application, the food & beverages segment accounted for the largest share of 51.6% market size in 2025. The increasing demand for extended shelf life, safe food preservation, and high-performance packaging solutions, rising consumption of packaged and convenience foods, and growing emphasis on reducing food waste are accelerating the use of high barrier packaging films in the food and beverage industry owing to their superior oxygen and moisture barrier properties, aroma retention, product protection, sealability, and ability to maintain freshness and quality throughout the product lifecycle.
The wrapping films segment, based on product, is expected to grow at a CAGR of 6.0% for the forecast period.
The polyethylene led the high barrier packaging films market in 2025 with a 45.4% share. Growing demand for cost-effective, high-performance flexible packaging solutions is driving the adoption of polyethylene (PE) in the high barrier packaging films market due to its excellent moisture barrier properties, flexibility, sealability, lightweight nature, and compatibility with multilayer film structures across food & beverages, pharmaceuticals, personal care, and industrial packaging applications.
The increasing demand for extended shelf life, safe food preservation, and high-performance packaging solutions is driving the growth of the high barrier packaging films market. The superior oxygen, moisture, and contamination resistance offered by these films is accelerating their adoption across food and beverage and pharmaceutical applications, while rising consumption of convenient packaged products and evolving consumer lifestyles continue to support market expansion during the forecast period.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


