
- Home
- »
- Plastics, Polymers & Resins
- »
-
Hydrogel Market Size, Share And Growth Report, 2026-2033GVR Report cover

Hydrogel Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (Synthetic Hydrogel, Natural Hydrogel, Hybrid Hydrogel), By Form (Amorphous, Semi-Crystalline, Crystalline), By Application, By Region, And Segment Forecasts
Market Size, 2025
$36.2BMarket Estimate, 2026
$38.5BMarket Forecast, 2033
$68.7BCAGR, 2026–2033
8.6%Hydrogel Market Summary
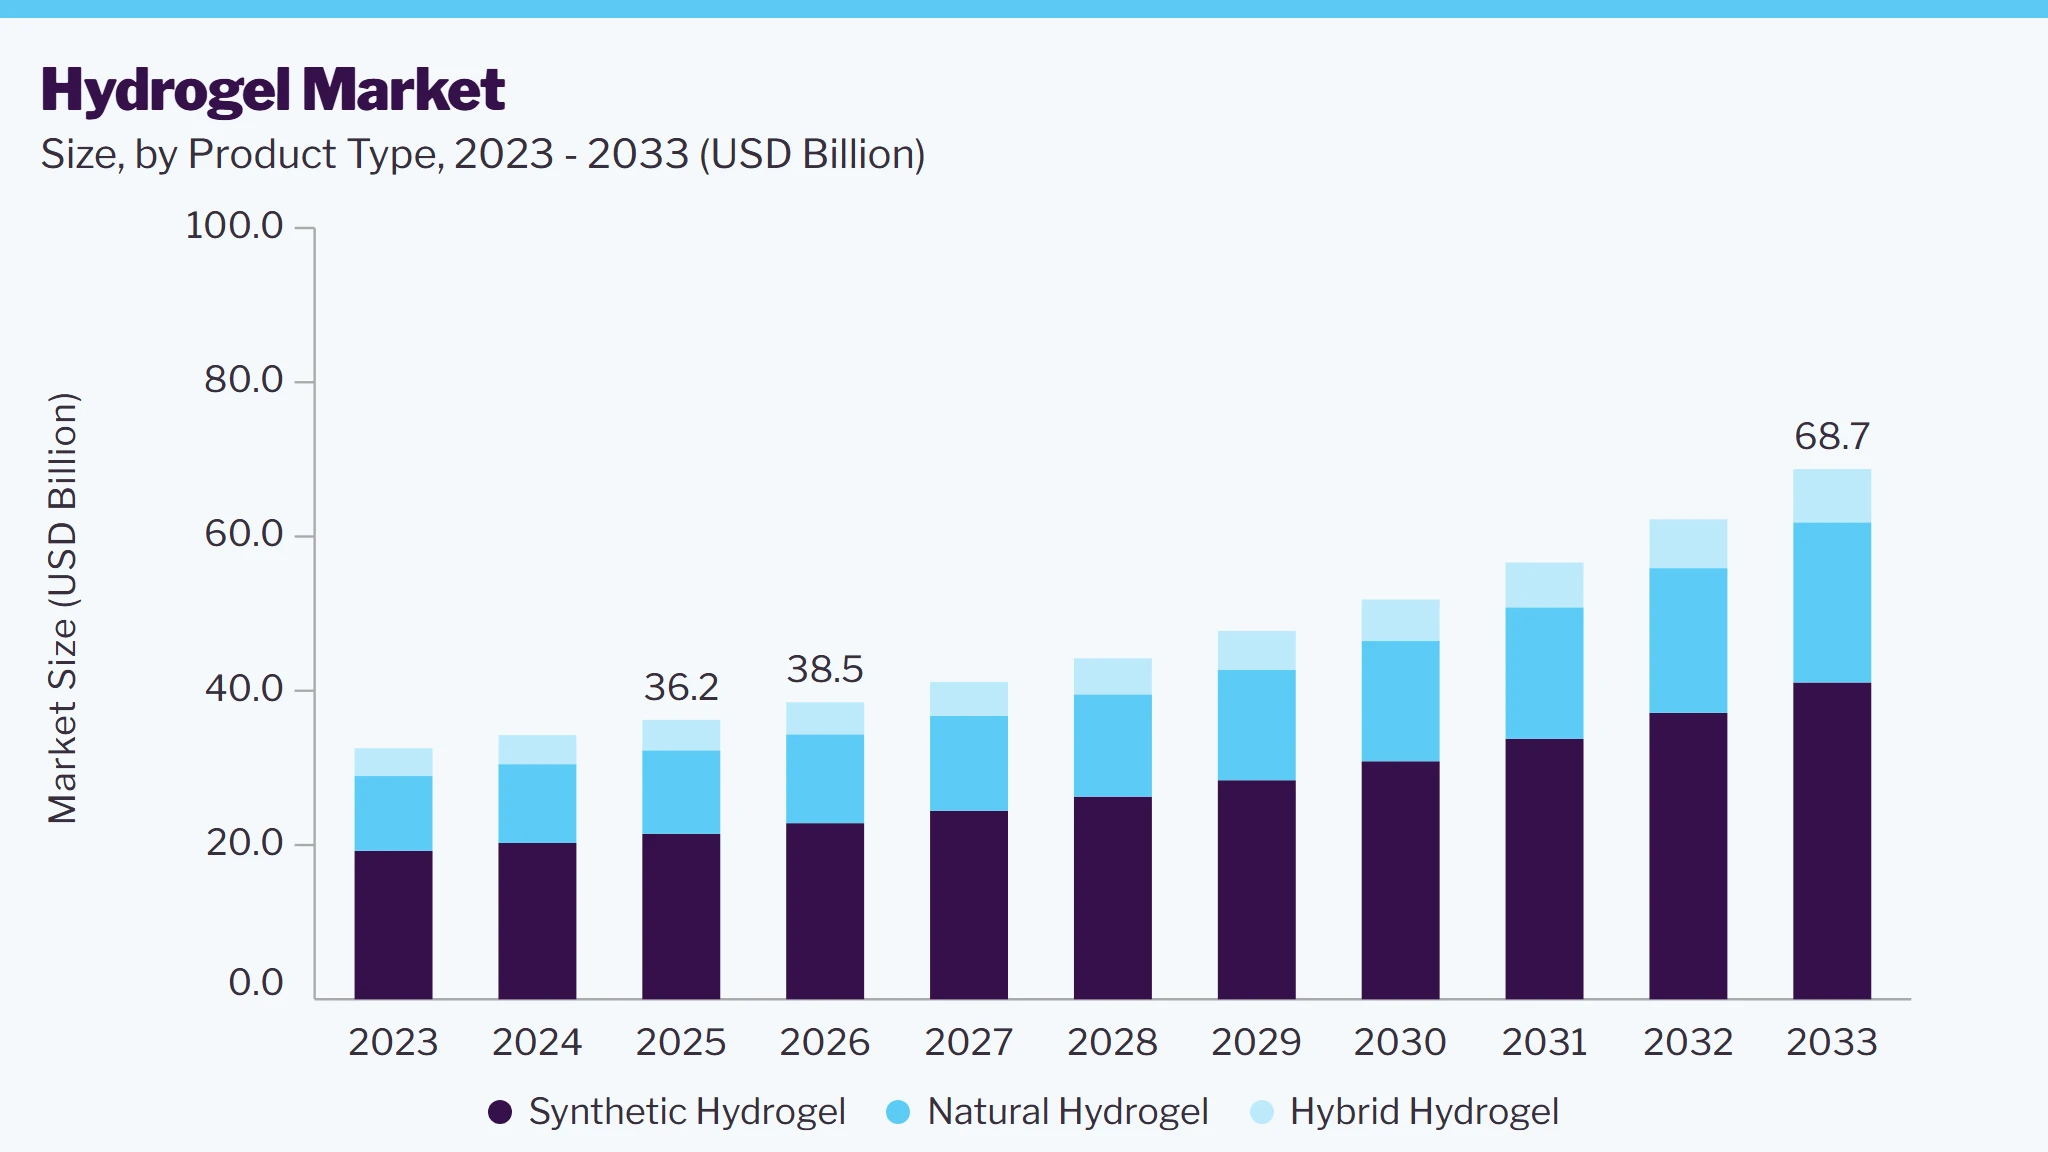
The global hydrogel market size was valued at USD 36.2 billion in 2025 and is projected to grow from USD 38.5 billion in 2026 to USD 68.7 billion by 2033, at a CAGR of 8.6% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 40.5% in 2025. Increasing demand for advanced wound care products and expanding adoption of hydrogel-based materials across wound dressings, burn care, surgical applications, personal care, pharmaceutical, and biomedical sectors are driving the hydrogel market growth.
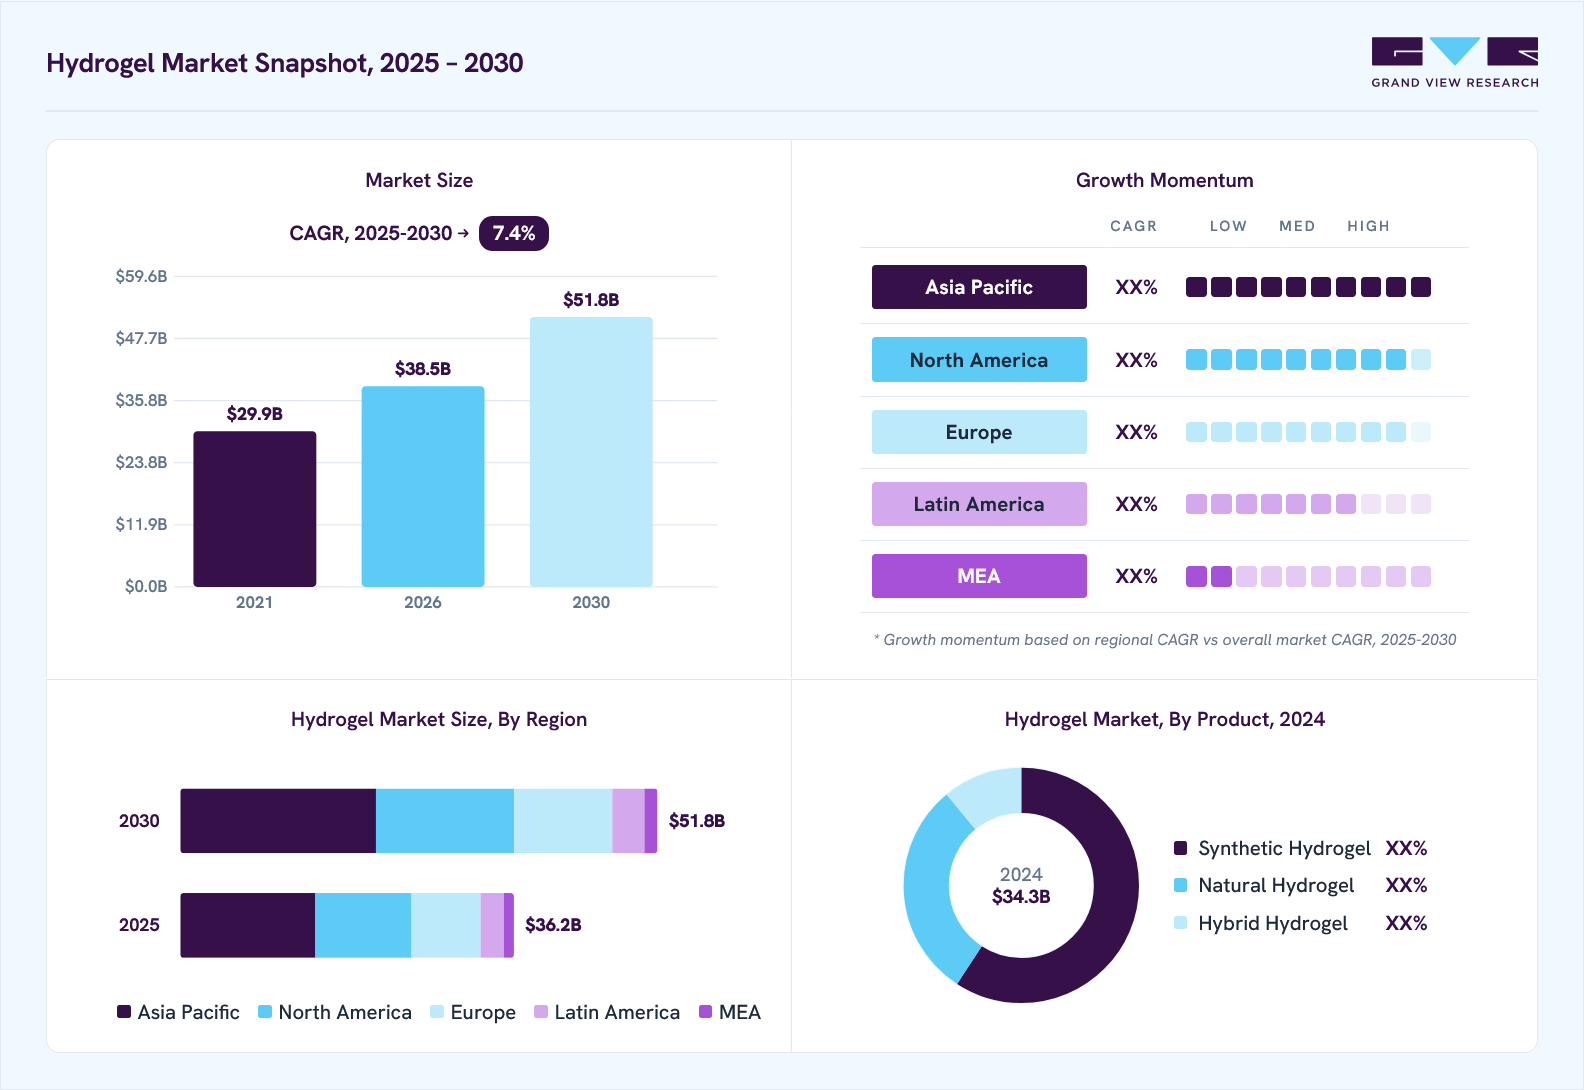 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Synthetic hydrogel segment led the market with the largest revenue share of 59.2% in 2025.
- By form: Amorphous segment led the market with the largest revenue share of 57.5% in 2025.
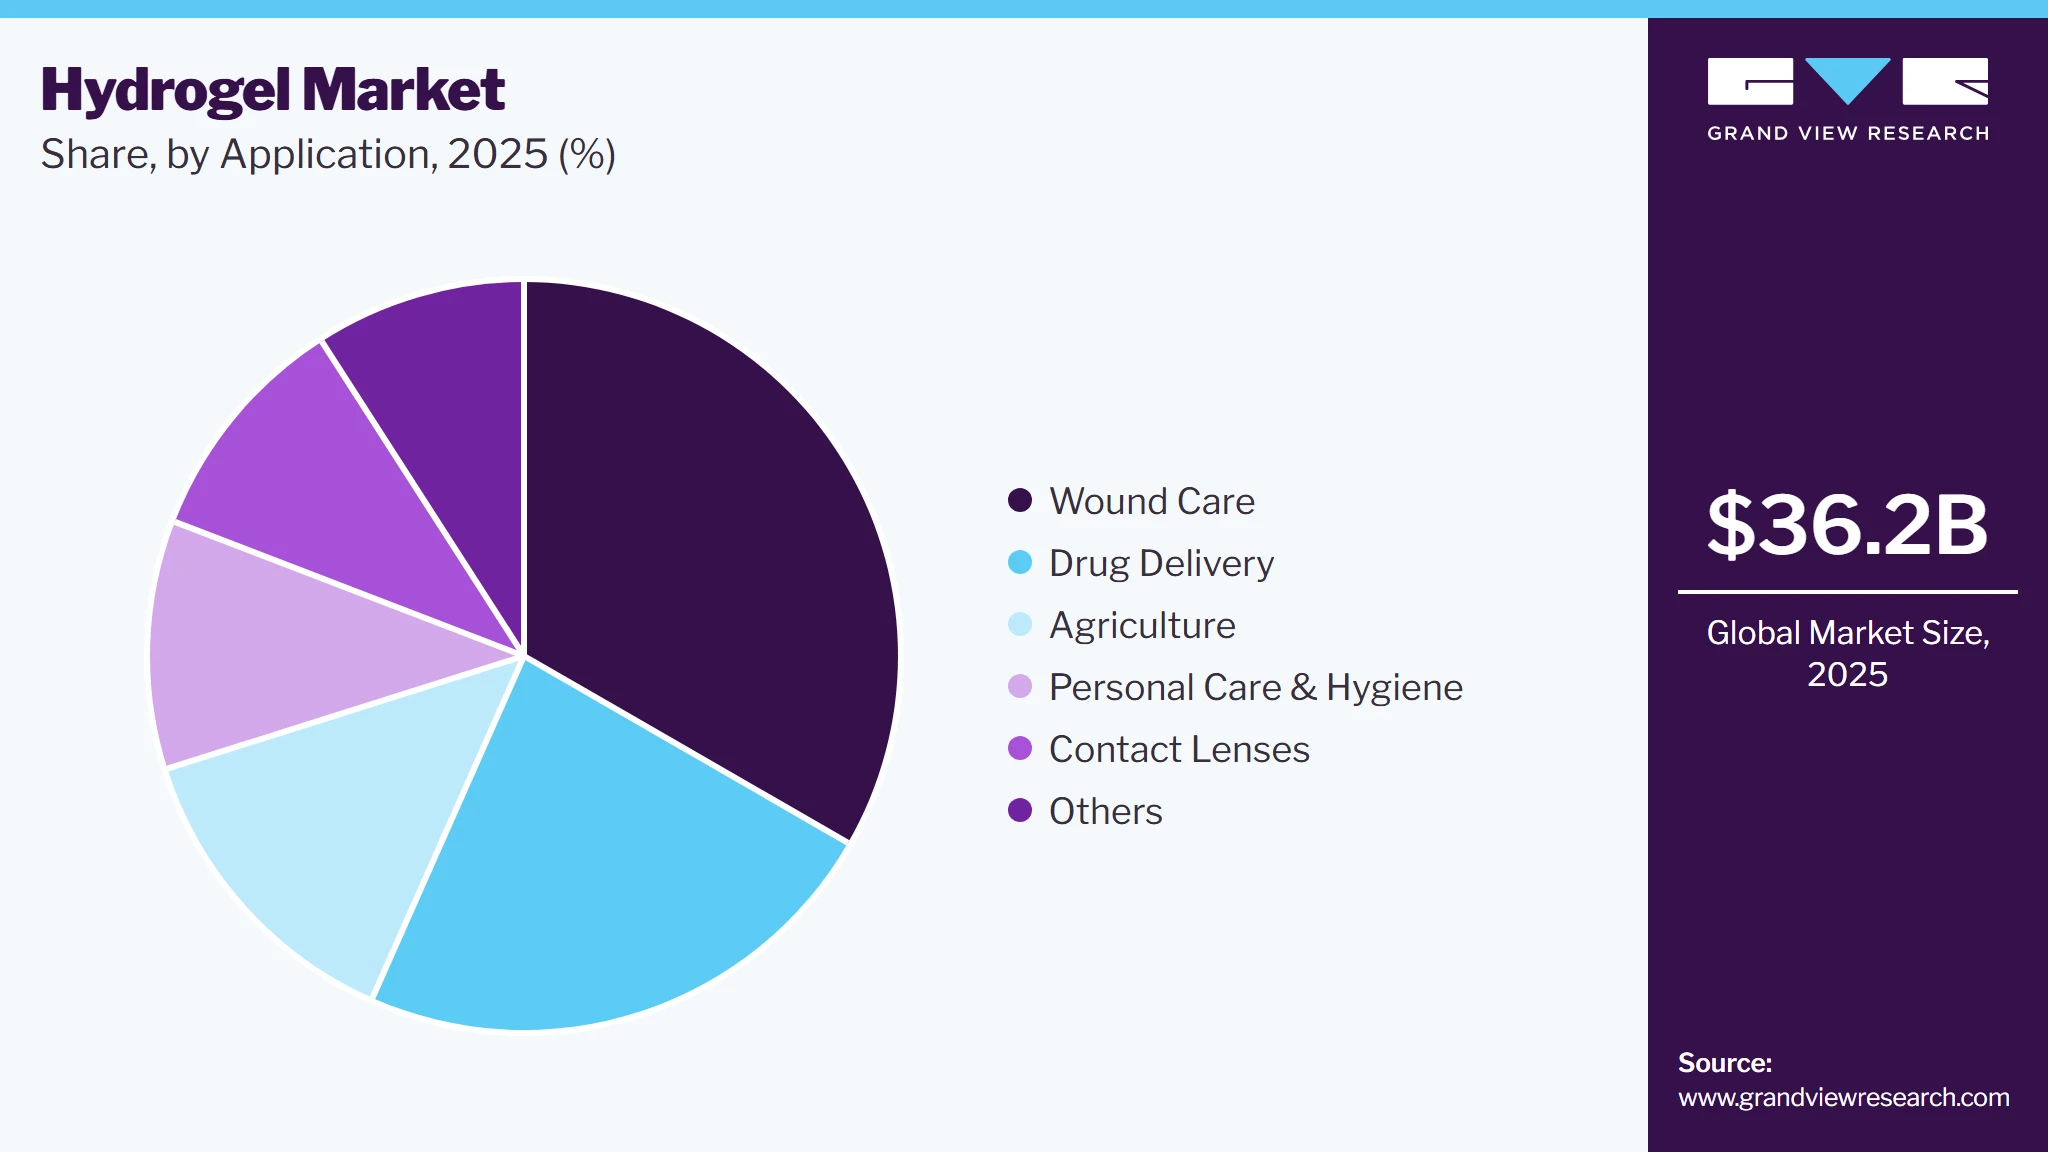
- By application: Wound care segment led the market with the largest revenue share of 33.3% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (40.5% revenue share, 2025)
- By country: China held the largest share of the Asia Pacific market in 2025.
Market Size & Forecast
- Market size in 2025: USD 36.2 Billion
- Estimated market size in 2026: USD 38.5 Billion
- Projected market size by 2033: USD 68.7 Billion
- CAGR (2026-2033): 8.6%
Prism AI by Grand View Research Free to tryAsk a question about the hydrogel market✓Every figure cited from GVR research Prefer the report? Download free sample →
Rising use of hydrogels in controlled drug delivery systems and emerging applications such as wearable healthcare devices and soft robotics further support market expansion due to their excellent biocompatibility, high water content, flexibility, and responsive properties. Hydrogels, due to their high water content and biocompatibility, are widely used in medical applications such as wound dressings, burn care, and surgical applications. Another significant factor driving the market is the growing use of hydrogels in personal care and hygiene products. Hydrogels are integral to the production of diapers, sanitary pads, and adult incontinence products due to their high absorbent properties. The increasing global birth rate in developing regions, coupled with the aging population and rising awareness about hygiene, has led to a surge in the demand for superabsorbent polymers (SAPs), a type of hydrogel. Companies like Procter & Gamble and Kimberly-Clark have been leveraging hydrogel technology to create innovative hygiene products that offer superior absorption and comfort.The increasing adoption of hydrogels in drug delivery systems is also a crucial growth factor. Hydrogels are gaining traction in the pharmaceutical industry as carriers for targeted and sustained drug release. Their ability to encapsulate drugs and release them in a controlled manner makes them suitable for applications in oncology, ophthalmology, and chronic disease management. For instance, researchers are developing hydrogel-based systems for delivering cancer drugs directly to tumor sites, reducing side effects and improving treatment efficacy. The rising focus on precision medicine and advancements in hydrogel formulations are expected to further boost their application in this field.
 To learn more about this report, Download Free Sample Report
Moreover, the expanding applications of hydrogels in emerging industries such as wearable technology and soft robotics are contributing to market growth. Hydrogels' unique properties, including flexibility, self-healing, and responsiveness to external stimuli, make them ideal for use in electronic skin, biosensors, and actuators. For example, researchers are exploring hydrogel-based materials for use in smart contact lenses that monitor glucose levels in real time. The rapid advancements in these cutting-edge applications are creating new growth opportunities for hydrogel manufacturers, particularly in developed markets like North America and Europe.
Market Dynamics
Hydrogel demand is anchored by wound care, personal care and hygiene, and drug delivery, where high water content, biocompatibility, and conformability support repeat use across medical and consumer channels. Synthetic hydrogel leads revenue, while amorphous grades dominate because they conform to irregular surfaces and fit dressings and moisturizing applications. Asia Pacific remains the main demand center, supported by healthcare infrastructure, pharmaceutical manufacturing, and medical device investment. Commercially, the market is shaped by formulation depth, clinical validation, and regional supply proximity rather than by commodity scale alone.
Hydrogel use in wound care is the strongest commercial driver because the material maintains a moist healing environment, supports burn care and surgical dressings, and can be engineered with antimicrobial and bioactive functions. Rising chronic wound incidence, aging populations, and higher diabetes burden are pushing hospitals, clinics, and home care providers toward hydrogel-based dressings that improve patient comfort and reduce dressing frequency. The largest application share in the report is wound care, which confirms its central role in revenue generation.
The fit between hydrogel performance and procurement priorities in medical care reinforces the driver. Buyers are paying for absorbency, conformability, and clinical consistency, not only for raw polymer cost. This favors suppliers that can deliver sterile, high-specification, and application-specific products for advanced wound management, where synthetic hydrogel already holds the largest share and continues to anchor premium revenue.
Hydrogel commercialization is constrained by formulation complexity and the cost of clinical validation. Manufacturers must balance swelling, strength, biocompatibility, degradation behavior, and shelf stability across very different uses, from contact lenses to wound dressings and drug delivery systems. That raises R&D, testing, and quality-control costs, while regulatory expectations are stricter for medical grades than for consumer grades. Smaller suppliers also face scale disadvantages in sterile production, packaging, and evidence generation, which limits their ability to compete on price or win institutional contracts.
Hybrid hydrogels and smart-device-linked formats create a clear value opportunity as buyers look for sustained release, stronger mechanical performance, and more responsive therapy. Growth in wearable technology, soft robotics, and smart contact lenses expands the addressable market beyond conventional dressings. Suppliers that combine biomaterial chemistry with device integration and application-specific performance can move into higher-margin niches, especially in developed markets where precision medicine and connected care are advancing quickly..
Analyst Perspective
Over the next 5 to 10 years, the hydrogel market is likely to move from broad volume-led consumption toward value-led, application-specific solutions. Wound care will remain the core demand base, but growth will increasingly come from drug delivery, advanced hygiene, and specialty uses such as smart contact lenses and wearable interfaces. Product differentiation will depend on formulation control, biocompatibility, antimicrobial performance, and the ability to combine synthetic and natural polymers into hybrid systems. Sustainability will matter more as buyers favor biodegradable and lower-toxicity materials, especially in personal care and agriculture. Leaders will be defined by IP, sterile manufacturing, clinical evidence, regional supply access, and partnerships with device makers and healthcare providers. Profitability will still face pressure from raw material volatility, regulatory scrutiny, long validation cycles, and competition from alternative absorbent and delivery materials.
Product Type Insights
Based on product type, the synthetic hydrogel segment led the market with the largest revenue share of 59.2% in 2025. The demand for synthetic hydrogels is primarily driven by their use in advanced medical applications, such as contact lenses, injectable gels, and drug delivery systems, due to their controlled swelling behavior and biocompatibility. Additionally, growth in the healthcare industry and advancements in polymer chemistry are boosting their adoption.
Natural hydrogels are derived from biological polymers, such as alginate, chitosan, gelatin, and hyaluronic acid. They are biodegradable, biocompatible, and mimic the extracellular matrix, making them ideal for tissue engineering, wound healing, and cosmetics applications. Natural hydrogels are also widely used in agriculture and food packaging due to their eco-friendly nature. The rising preference for environmentally sustainable materials and the increasing demand for natural and organic personal care products are key drivers for natural hydrogels.
Hybrid hydrogels combine synthetic and natural polymers to leverage the benefits of both. These hydrogels offer improved mechanical strength, tunable degradation rates, and enhanced biocompatibility. Due to their superior properties, they are widely used in areas such as drug delivery, tissue scaffolding, and 3D bioprinting.
Form Insights
Based on form, the amorphous segment led the market with the largest revenue share of 57.5% in 2025. Amorphous hydrogels are non-structured, highly flexible, and exhibit no distinct crystalline pattern. They are often transparent and soft, enabling them to conform to irregular surfaces, which makes them ideal for wound care, drug delivery, and moisturizing applications. The demand for amorphous hydrogels is driven by their versatility in biomedical applications, such as wound care and tissue engineering.
Semi-crystalline hydrogels feature a combination of crystalline and amorphous regions, offering a balance of strength and flexibility. These hydrogels are known for their controlled swelling behavior, making them suitable for applications requiring precise water absorption, such as agriculture, drug delivery systems, and controlled-release fertilizers.
Crystalline hydrogels have a highly organized structure, providing rigidity and stability. These hydrogels are often employed in applications that require defined shape retention and mechanical strength, such as packaging, scaffolding in tissue engineering, and industrial uses. Their reduced swelling capacity compared to amorphous and semi-crystalline hydrogels allows them to maintain structural integrity under stress.
Application Insights
Based on application, the wound care segment led the market with the largest revenue share of 33.3% in 2025. Hydrogels are extensively used in wound care due to their ability to maintain a moist environment, which is critical for wound healing. The growing prevalence of chronic wounds, such as diabetic foot ulcers and pressure ulcers, and the rising aging population drive the demand for hydrogel-based wound care products. Additionally, advancements in hydrogel formulations, such as antimicrobial and bioactive hydrogels, further bolster market growth.
 To learn more about this report, Download Free Sample Report
Hydrogels are employed as drug delivery systems due to their biocompatibility, high water content, and controlled release properties. They can encapsulate a variety of drugs, including small molecules and macromolecules, ensuring targeted and sustained delivery to specific tissues. The demand for non-invasive drug delivery methods, increased focus on personalized medicine, and advancements in hydrogel nanotechnology for smart drug delivery systems are key factors driving the adoption of hydrogels in this segment.
Hydrogels are used in agriculture to enhance water retention in soils, improve crop yield, and optimize fertilizer usage. These superabsorbent polymers reduce water wastage, particularly in arid and semi-arid regions, and improve soil structure. The rising need for sustainable farming practices, increasing awareness about water conservation, and government initiatives promoting hydrogel usage in agriculture drive market growth. Climate change and water scarcity concerns also boost the adoption of hydrogels.
Region Insights
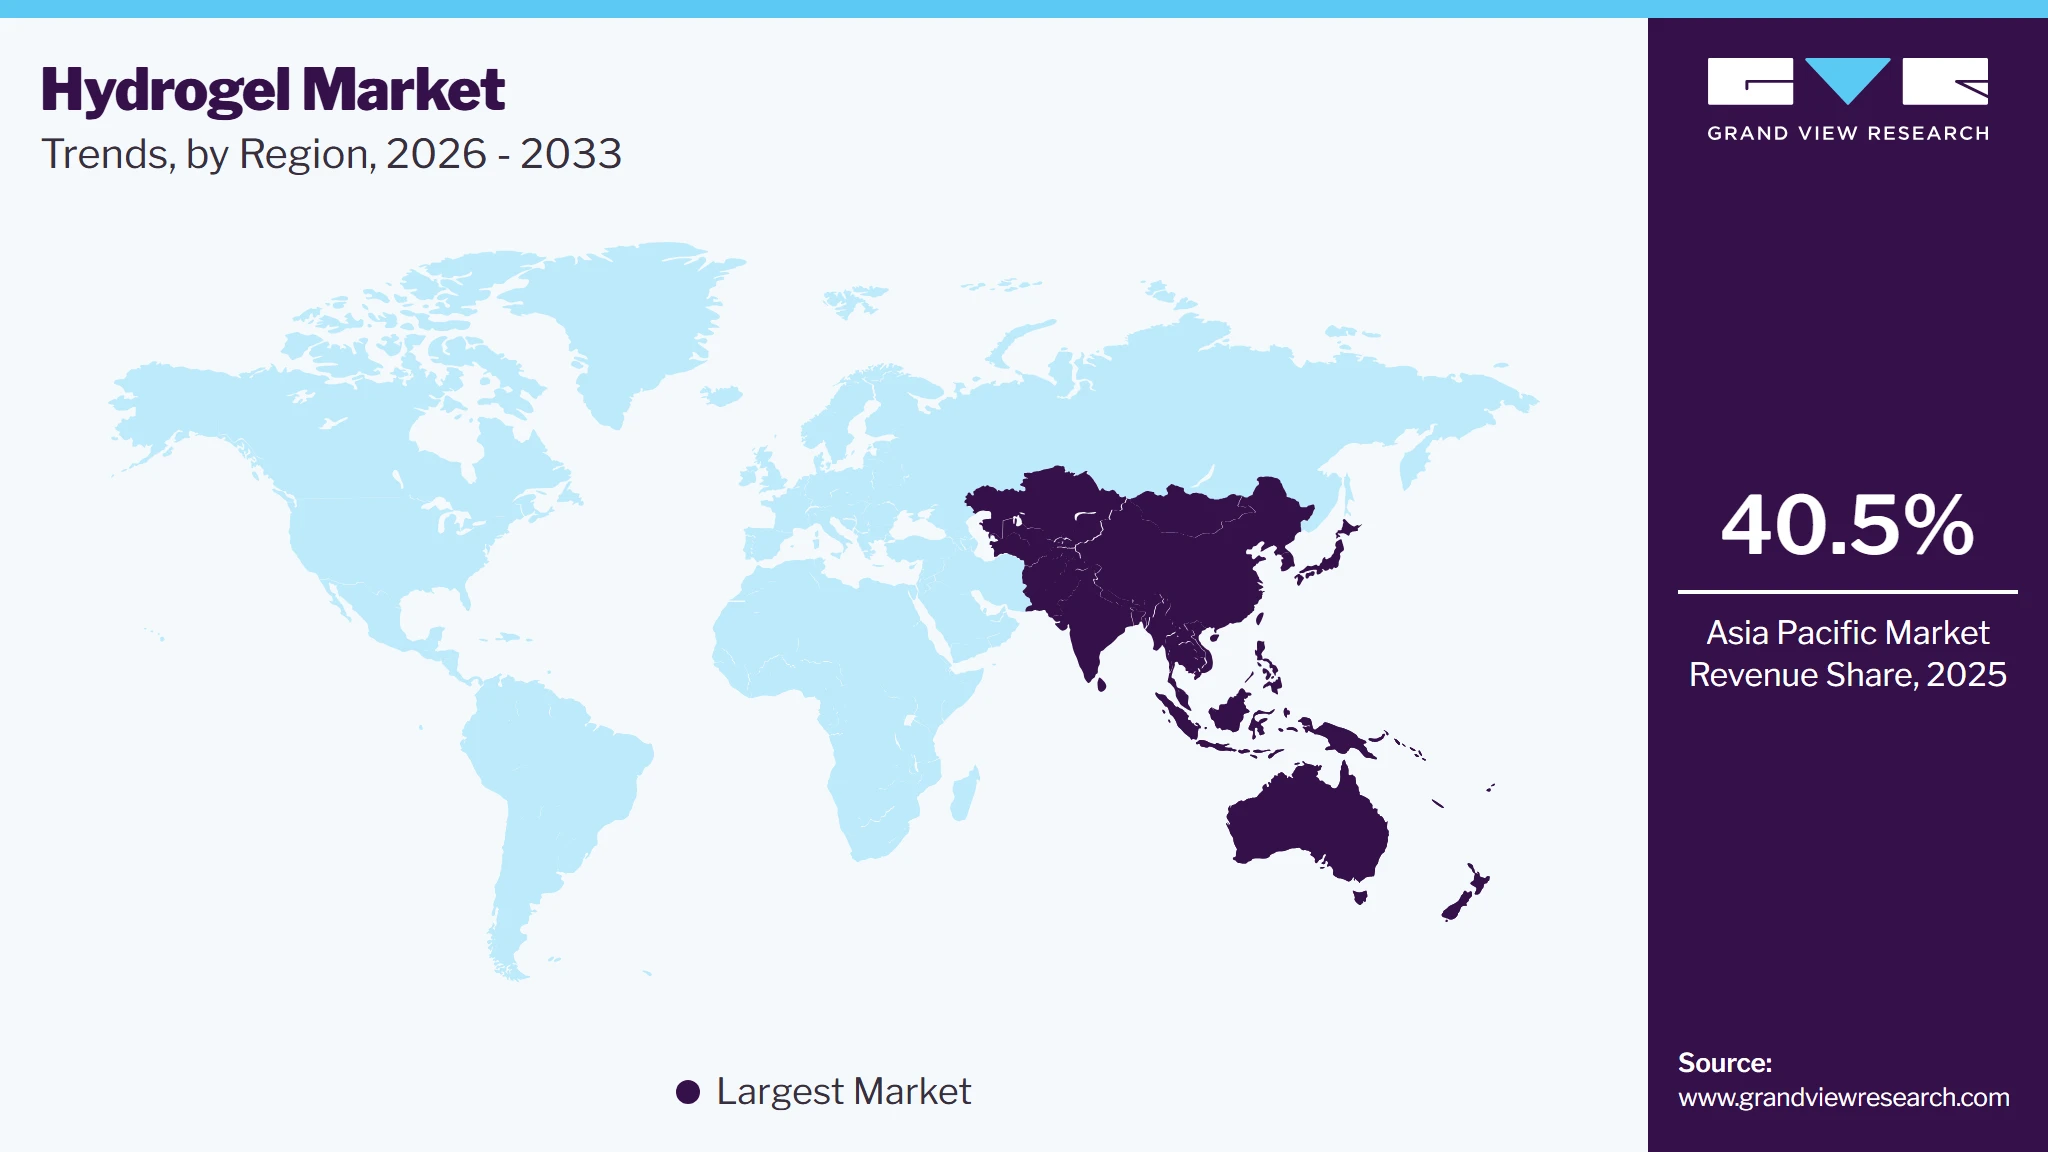
Asia Pacific dominated the hydrogel market with the largest revenue share of 40.5% in 2025. Rapidly expanding healthcare infrastructure, increasing research investments, and a growing pharmaceutical and medical device industry are key catalysts behind the region's market dominance. Countries such as China, Japan, South Korea, and India are leading this transformation, with substantial government support for advanced medical technologies and biomedical innovations.
 To learn more about this report, Download Free Sample Report
China Hydrogel Market Trends
The hydrogel market in China accounted for the largest market revenue share in the Asia Pacific in 2025. China Hydrogel market is primarily driven by its country's robust pharmaceutical and medical device manufacturing infrastructure, coupled with substantial government investments in biotechnology and healthcare innovation. The Chinese government's strategic policy initiatives, such as the "Made in China 2025" plan, have explicitly prioritized biomaterials and medical technology as key development areas. This national-level support has enabled domestic hydrogel manufacturers to receive significant funding, tax incentives, and research grants, accelerating technological innovation and manufacturing capabilities.
North America Hydrogel Market Trends
The region's growing healthcare expenditure, aging population, and increasing prevalence of chronic wounds and diseases are additional catalysts driving hydrogel market demand. Sophisticated healthcare systems, high patient awareness, and willingness to adopt cutting-edge medical technologies make North America an attractive market for hydrogel manufacturers. The combination of technological innovation, research excellence, and significant healthcare infrastructure ensures that North America remains a dominant force in the global hydrogel market.
The Hydrogel market in the U.S. is primarily driven by robust research infrastructure, significant investments in biomedical innovation, and advanced manufacturing capabilities. In the healthcare sector, U.S. medical institutions and research universities are pioneering hydrogel applications in wound healing, tissue engineering, and drug delivery systems. The U.S. Food and Drug Administration's supportive regulatory framework for innovative medical technologies further accelerates commercialization of these advanced hydrogel solutions.
Europe Hydrogel Market Trends
The European market's leadership is particularly evident in biomedical applications, where countries like Germany, France, and the United Kingdom are pioneering hydrogel technologies for wound healing, tissue engineering, and drug delivery systems. For instance, research institutions and companies in these countries are developing sophisticated hydrogel-based wound dressings that can actively monitor healing progress and release medications precisely, representing significant advancements in medical treatment strategies.
Hydrogel market in the Germany is primarily driven by its robust technological innovation, strong manufacturing capabilities, and strategic focus on advanced materials research. The country's pharmaceutical, medical device, and biotechnology industries have been particularly instrumental in pushing hydrogel applications forward, especially in medical and healthcare sectors. The German market's position is exemplified by companies such as BASF and Evonik, which have heavily invested in developing cutting-edge hydrogel technologies. These firms are pioneering innovations in areas such as wound dressings, drug delivery systems, and tissue engineering.
Key Hydrogel Company Insights
The global hydrogel market is characterized by intense competition, with numerous established players and emerging companies vying for market share. Key players, such as 3M, Smith & Nephew, Cardinal Health, and Johnson & Johnson, dominate the market with strong product portfolios and significant investments in research and development. Emerging players, particularly in Asia-Pacific, are gaining traction by offering cost-effective and specialized hydrogel solutions, further intensifying competition. Strategic partnerships, mergers and acquisitions, and a focus on sustainability are prevalent trends shaping the competitive landscape as companies strive to meet evolving consumer demands and regulatory standards.
Key Hydrogel Companies:
The following key companies have been profiled for this study on the hydrogel market.
-
Johnson & Johnson
-
Cardinal Health
-
3M Company
-
Coloplast
-
B. Braun Melsungen
-
Smith & Nephew
-
Derma Sciences
-
Royal DSM
-
Dow Corning Corporation
-
Paul Hartmann
-
Ashland
-
Evonik Industries
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Johnson & Johnson, Cardinal Health, 3M Company, Coloplast, B. Braun Melsungen, Smith & Nephew, Royal DSM, Dow Corning Corporation, Paul Hartmann, Ashland, Evonik Industries)
- Expand wound care, hygiene, and drug delivery portfolios through incremental product upgrades and cross-selling into hospital and retail channels.
- Use clinical evidence, regulatory approvals, and distributor networks to protect share and support premium pricing.
- Prioritize formulation scale-up, sterile production, and material science partnerships.
- Strong brand equity and long-standing hospital relationships.
- Broader geographic reach and deeper regulatory capability.
- Better integration across materials, devices, and channels.
- Slower product refresh cycles.
- Higher compliance and overhead costs.
- Less agility in niche applications.
Emerging Players (Derma Sciences)
- Focus on niche wound care and specialty hydrogel formats.
- Use targeted partnerships and selective market entry.
- Compete with application-specific innovation rather than breadth.
- Faster product iteration.
- Better focus on underserved use cases.
- Leaner commercial structure.
- Limited scale and manufacturing leverage.
- Narrower portfolio and weaker bargaining power.
- Lower global reach and less clinical trust.
Recent Developments
-
In November 2024, UPM Biomedicals launched FibGel, the world's first injectable nanocellulose hydrogel specifically designed for permanent implantable medical devices. This innovative product is made entirely from birch wood cellulose and water, making it a safe, sustainable, and biocompatible alternative to traditional hydrogels derived from synthetic or animal sources.
-
In July 2024, Cosmos Health successfully completed the pilot production and scale-up phases for its weight management hydrogel, CCX0722. This achievement marks the conclusion of the development phase for this biocompatible hydrogel, which is designed to assist in weight management and is made from natural ingredients. The hydrogel has demonstrated a swelling ratio exceeding 100 g/g, indicating significant improvements in its properties during the scale-up process.
Global Hydrogel Market Report Scope
Report Attribute
Details
Market size in 2025
USD 36.2 billion
Estimated Market size in 2026
USD 38.5 billion
Projected Market size by 2033
USD 68.7 billion
Growth rate
CAGR of 8.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, form, application, region
RegioFinal scope
North America, Europe, Asia Pacific, Central & South America, and the Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, UK, France, Italy, Spain, China, India, Japan, South Korea, Australia, Brazil, Argentina, Saudi Arabia, UAE, South Africa
Key companies profiled
Johnson & Johnson; Cardinal Health; 3M Company; Coloplast; B. Braun Melsungen; Smith & Nephew; Derma Sciences; Royal DSM; Dow Corning Corporation; Paul Hartmann; Ashland; Evonik Industries
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase-addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Hydrogel Market Report Segmentation
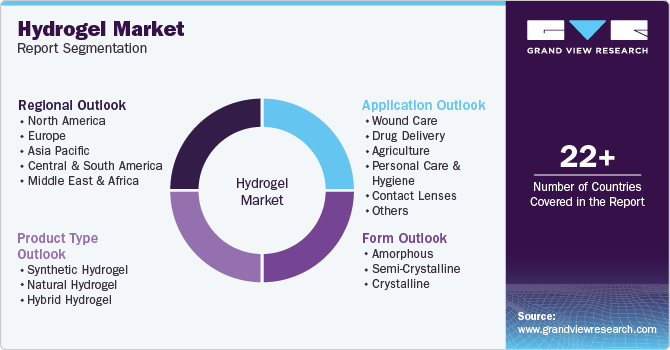
This report forecasts revenue growth at a global level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global Hydrogel market report based on product type, form, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Type Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Synthetic Hydrogel
-
Natural Hydrogel
-
Hybrid Hydrogel
-
-
Form Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Amorphous
-
Semi-Crystalline
-
Crystalline
-
-
Application Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Wound Care
-
Drug Delivery
-
Agriculture
-
Personal Care & Hygiene
-
Contact Lenses
-
Others
-
-
Region Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The hydrogel market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each hydrogel segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue capture definition
Synthetic Hydrogel
Revenue is captured through high-specification medical and technical grades used in contact lenses, injectable gels, wound dressings, and controlled drug delivery, where performance consistency and regulatory acceptance support premium pricing.
Natural Hydrogel
Revenue is generated from biodegradable and biocompatible formulations derived from biological polymers, with commercial traction in wound healing, cosmetics, agriculture, and tissue engineering, where sustainability and natural positioning matter.
Hybrid Hydrogel
Revenue is earned from blended systems that combine synthetic and natural polymers to improve mechanical strength, tunable degradation, and therapeutic performance in drug delivery, scaffolding, and advanced biomedical uses.
Segment - Form
Revenue capture definition
Amorphous
Revenue is captured from conformable, soft, and highly adaptable hydrogel grades used in wound care, moisturizing products, and drug delivery, where surface coverage and user comfort drive purchasing decisions.
Semi-Crystalline
Revenue comes from products that balance strength and flexibility, supporting controlled swelling, precision absorption, and repeatable performance in agriculture, drug release, and specialized medical systems.
Crystalline
Revenue is derived from rigid, shape-stable hydrogel formats used where structure retention, mechanical integrity, and defined geometry are required, including tissue scaffolding and select industrial applications.
Segment - Application
Revenue capture definition
Wound Care
Revenue is generated through dressings, pads, and advanced wound-contact products for chronic wounds, burns, and post-surgical care, with repeat demand supported by clinical use and hospital procurement.
Drug Delivery
Revenue is captured through sustained-release and targeted-delivery systems for pharmaceuticals, where hydrogel performance enables controlled dosing, specialty formulations, and research-to-commercial conversion.
Agriculture
Revenue is earned from soil-conditioning and water-retention products, as well as controlled-release fertilizer systems that improve moisture management and crop efficiency in water-stressed regions.
Personal Care & Hygiene
Revenue flows from absorbent consumer and hygiene products such as diapers, sanitary pads, and adult incontinence solutions, where swelling capacity, comfort, and absorbency determine conversion.
Contact Lenses
Revenue is generated from lens materials and ophthalmic formulations that rely on oxygen permeability, comfort, and biocompatibility, with higher-value capture in premium vision-care products.
Others
Revenue includes wearable interfaces, soft robotics, biosensors, tissue engineering, and other niche uses that monetize hydrogel responsiveness, flexibility, and specialty performance beyond core medical and consumer categories.
Estimation Model
Layer Name
Key Question
Description
Demand Layer
Why does demand lead?
This layer maps end-use pull, showing how wound care, hygiene, and drug delivery convert clinical need into commercial hydrogel demand.
Product Chemistry Layer
Why separate product types?
This layer separates synthetic, natural, and hybrid formats because formulation choice shapes performance, regulatory acceptance, and margin potential.
Application Monetization Layer
Why map application revenue?
This layer captures where revenue concentrates, since medical, consumer, and agricultural uses monetize hydrogel performance through different buying structures.
Regional Execution Layer
Why assess regional demand?
This layer reflects supply concentration and adoption speed, with Asia Pacific driving scale and developed regions favoring higher-value applications.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
U.S. and Western Europe focus
Expanded the regional view to emphasize the U.S., Germany, France, and the U.K., with hydrogel demand mapped to advanced wound care, contact lenses, and regulated drug delivery use cases.
Improves visibility into the most mature, premium, and regulation-led demand centers.
Application Split
Added tighter segmentation across wound care, drug delivery, agriculture, personal care and hygiene, and contact lenses, with revenue logic tied to clinical use, absorbency, and formulation performance.
Clarifies where pricing power and volume concentration are most likely to sit.
Company Benchmarking
Built a relative player map across mature and emerging suppliers, highlighting scale, channel access, formulation depth, and application-specific positioning within hydrogel commercialization.
Supports competitive screening, partner selection, and strategic due diligence.
Frequently Asked Questions About This Report
The Asia Pacific Hydrogel market accounted for the largest share of 40.5% market size in 2025.
China was the leading Hydrogel market and is expected to grow at a compound annual growth rate of 9.4%.
Based on application, the wound care segment accounted for the largest share of 33.3% market size in 2025.
The personal care & hygiene segment, based on application, is expected to grow at a CAGR of 9.6% for the forecast period.
The synthetic hydrogel industry led the hydrogel market in 2025 with a 59.2% share. Rising demand for advanced wound care products, drug delivery systems, contact lenses, and implantable medical devices is accelerating the adoption of synthetic hydrogel due to its excellent biocompatibility, high water content, controlled swelling behavior, mechanical strength, chemical stability, and tunable physical properties across healthcare and biomedical applications.
Increasing demand for advanced wound care products and expanding adoption of hydrogel-based materials across wound dressings, burn care, surgical applications, personal care, pharmaceutical, and biomedical sectors are driving the hydrogel market growth. Rising use of hydrogels in controlled drug delivery systems and emerging applications such as wearable healthcare devices and soft robotics further support market expansion due to their excellent biocompatibility, high water content, flexibility, and responsive properties.
The key players in the hydrogel market are Johnson & Johnson; Cardinal Health; 3M Company; Coloplast; B. Braun Melsungen; Smith & Nephew; Derma Sciences; Royal DSM; Dow Corning Corporation; Paul Hartmann; Ashland; Evonik Industries
The global hydrogel market was estimated at around USD 36.2 billion in the year 2025 and is expected to reach around USD 38.5 billion in 2026.
The global hydrogel market is expected to grow at a compound annual growth rate of 8.6% from 2026 to 2033 to reach around USD 68.7 billion by 2033.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


