
- Home
- »
- HVAC & Construction
- »
-
Insulated Wire And Cable Market Size & Share Report, 2033GVR Report cover

Insulated Wire And Cable Market (2026 - 2033)
Size, Share, & Trends Analysis Report By Cable Type, By Conductor Material (Copper, Aluminum), By Voltage Rating (Low Voltage, Medium Voltage), By Installation (Overhead, Underground), By End-use, By Region, and Segment Forecasts
Market Size, 2025
$225.9BMarket Estimate, 2026
$237.5BMarket Forecast, 2033
$368.2BCAGR, 2026–2033
6.5%Insulated Wire and Cable Market Summary
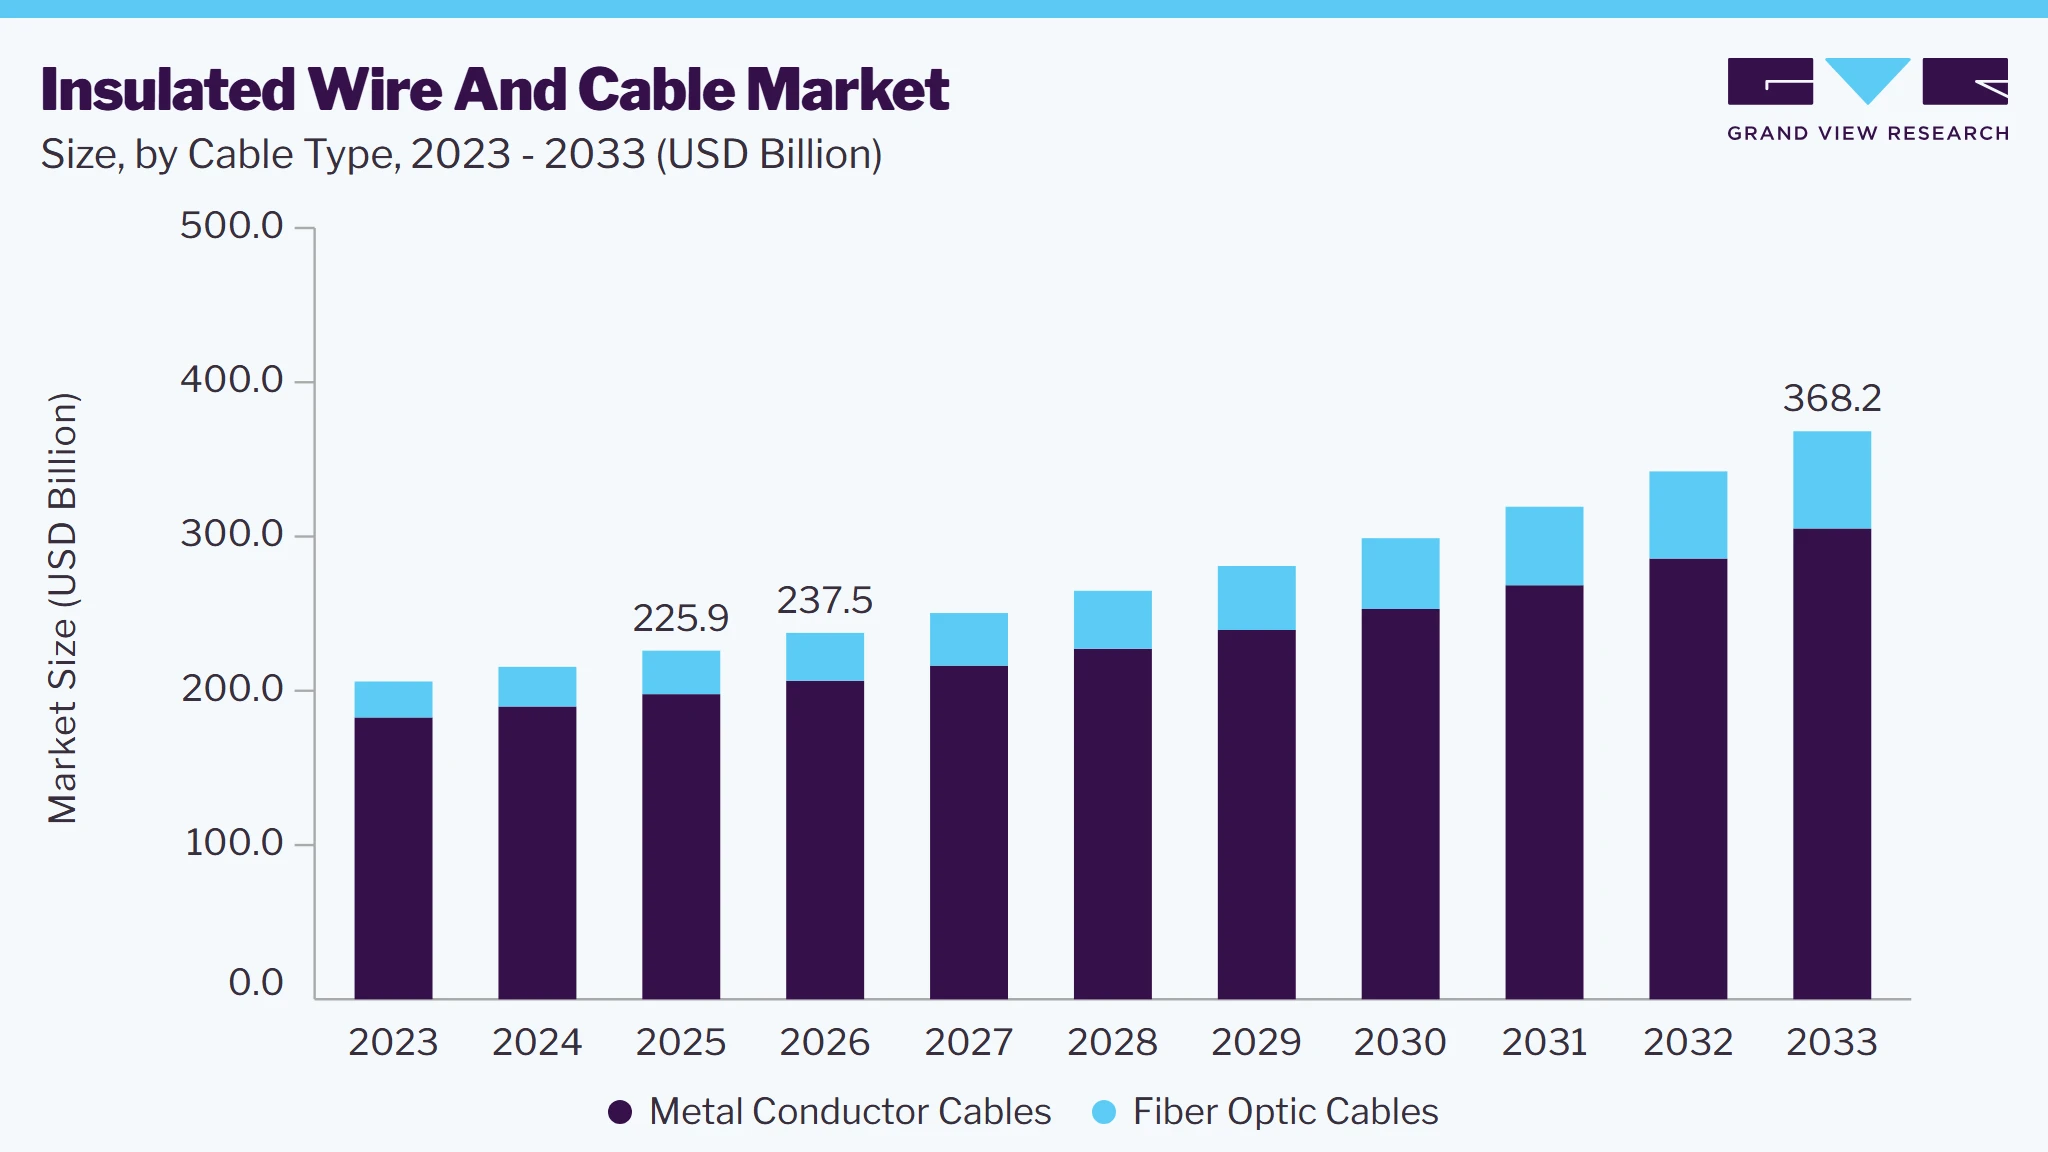
The global insulated wire and cable market size was valued at USD 225.9 billion in 2025 and is projected to grow from USD 237.5 billion in 2026 to USD 368.2 billion by 2033, at a CAGR of 6.5% from 2026 to 2033. Asia Pacific dominated, with a revenue share of 35% in 2025. The market is driven by rising investments in power transmission and distribution networks, renewable energy infrastructure, and urban construction activities.
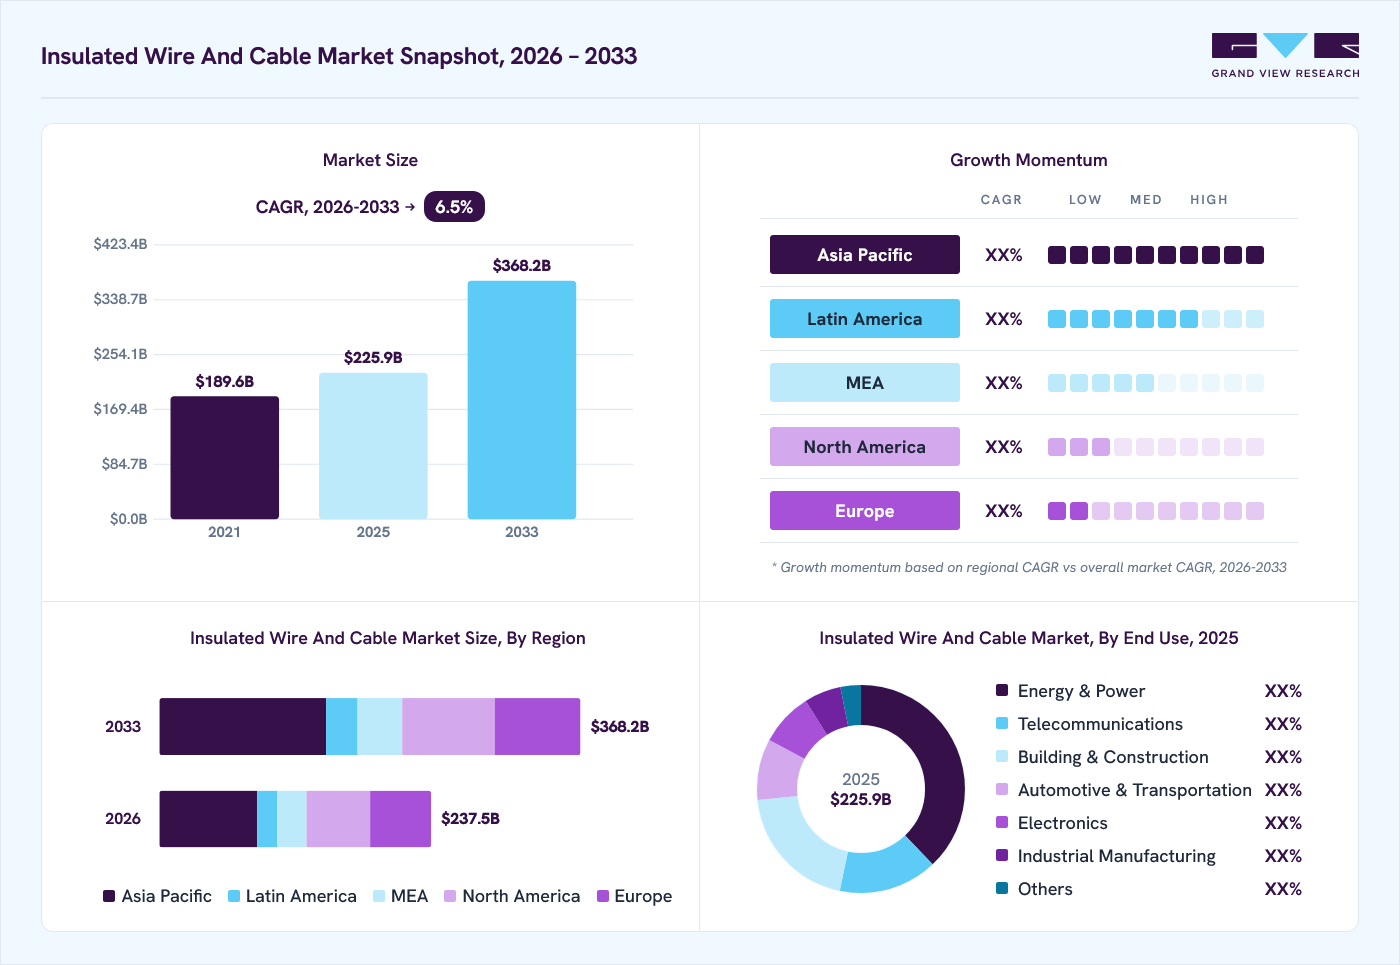 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By cable type: Metal conductor cables segment held the largest market share of 87.0% in 2025.
- By conductor material: Copper segment held the largest market revenue share of 55.0% in 2025.
- By voltage rating: Low voltage segment led the market with the largest revenue share of 54.0% in 2025.
- By installation: Underground segment held the largest market revenue share of 57.0% in 2025.
- By end use: Energy & power segment led the market with the largest revenue share of 37.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (35.0% revenue share, 2025)
- By country: China held the largest share in 2025.
Market Size & Forecasts
- Market size in 2025: USD 225.9 Billion
- Estimated market size in 2026: USD 237.5 Billion
- Projected market size by 2033: USD 368.2 Billion
- CAGR (2026-2033): 6.5%
Prism AI by Grand View Research Free to tryAsk a question about the insulated wire and cable marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Growing telecommunications infrastructure, electric vehicle production, and industrial automation further accelerate demand for high-performance, durable, and application-specific insulated cables. Increasing investments in power transmission infrastructure are accelerating the adoption of high-voltage and extra-high-voltage cables. Expansion of high-voltage direct current (HVDC) networks is driving demand for advanced cables capable of transmitting electricity efficiently over long distances. Renewable energy installations are further increasing the requirement for high-capacity cables to connect offshore wind farms and remote power generation facilities with national grids. Manufacturers are focusing on advanced insulation materials, improved thermal performance, and enhanced cable durability to meet higher transmission requirements. These developments are strengthening demand for specialized high-voltage cables across utility and energy infrastructure projects.
 To learn more about this report, Download Free Sample Report
Growing offshore energy investments are creating significant demand for submarine power cables across international electricity networks. Expansion of offshore wind farms and cross-border electricity interconnectors is driving investments in high-capacity submarine cable systems. Telecommunications operators are also increasing investments in undersea fiber-optic cables to accommodate rising international data traffic and cloud connectivity requirements. Manufacturers are focusing on improved insulation, mechanical protection, corrosion resistance, and long-distance transmission capabilities to enhance submarine cable performance. These investments are expanding opportunities for specialized cable manufacturers across renewable energy, utilities, and telecommunications infrastructure.
Rapid expansion of hyperscale data centers and cloud computing infrastructure is increasing demand for high-performance power and communication cables. Growing artificial intelligence workloads and data traffic are driving requirements for high-bandwidth fiber-optic cables and specialized electrical cables used in data center power distribution. Expansion of 5G networks and fiber-to-the-home infrastructure is further increasing demand for reliable, high-capacity communication cable systems. Manufacturers are developing higher-density fiber-optic cables, advanced connectivity solutions, and cables designed to meet the power requirements of modern data centers. This shift is strengthening demand for communication and power cables across digital infrastructure applications.
Market Dynamics
The insulated wire and cable market is driven by increasing investments in electricity transmission and distribution infrastructure, renewable energy projects, and grid modernization initiatives. Rapid urbanization and expanding residential, commercial, and industrial construction activities are increasing demand for insulated cables used in electrical installations and power distribution networks. Growing deployment of electric vehicles, charging infrastructure, and industrial automation is further accelerating the adoption of specialized cables with improved insulation, flexibility, and thermal resistance. Additionally, expanding telecommunications networks, 5G deployment, and data center investments are strengthening demand for high-performance communication and fiber-optic cables. Continuous advancements in insulation materials, high-voltage cable technologies, and sustainable manufacturing processes are supporting product innovation and expanding market opportunities across major end-use industries.
Increasing investments in electricity transmission and distribution networks are driving demand for insulated wires and cables across residential, commercial, and industrial applications. Governments and utility providers are expanding grid infrastructure to address rising electricity consumption, improve power reliability, and reduce transmission losses. The integration of renewable energy sources, including solar and wind power, is further increasing requirements for specialized cables to connect generation facilities with existing power networks. Grid modernization initiatives and cross-border electricity transmission projects are also supporting the deployment of medium- and high-voltage cables. These infrastructure developments are strengthening procurement opportunities for cable manufacturers across established and emerging economies.
Establishing and expanding wire and cable manufacturing facilities requires substantial capital investment in production machinery, extrusion systems, testing equipment, and quality-control infrastructure. Manufacturing high-voltage, submarine, and specialized industrial cables involves additional technical requirements, advanced insulation processes, and stringent testing procedures. Smaller manufacturers often face difficulties in securing the capital and technical capabilities required to compete in these specialized product categories. Rising energy, labor, maintenance, and compliance costs further increase overall manufacturing expenses. These investment requirements can restrict capacity expansion and limit market entry for smaller industry participants.
Rapid expansion of hyperscale data centers, cloud computing facilities, and telecommunications networks is creating new opportunities for cable manufacturers. Increasing artificial intelligence workloads and data processing requirements are driving demand for high-capacity power distribution cables and advanced connectivity solutions. Expansion of 5G networks, fiber-to-the-home infrastructure, and international communication networks is further supporting demand for communication and fiber-optic cables. Data center operators are also investing in reliable electrical infrastructure to support higher power densities and uninterrupted operations. These developments are creating opportunities for manufacturers offering specialized power, control, and communication cable solutions.
Market Concentration & Characteristics
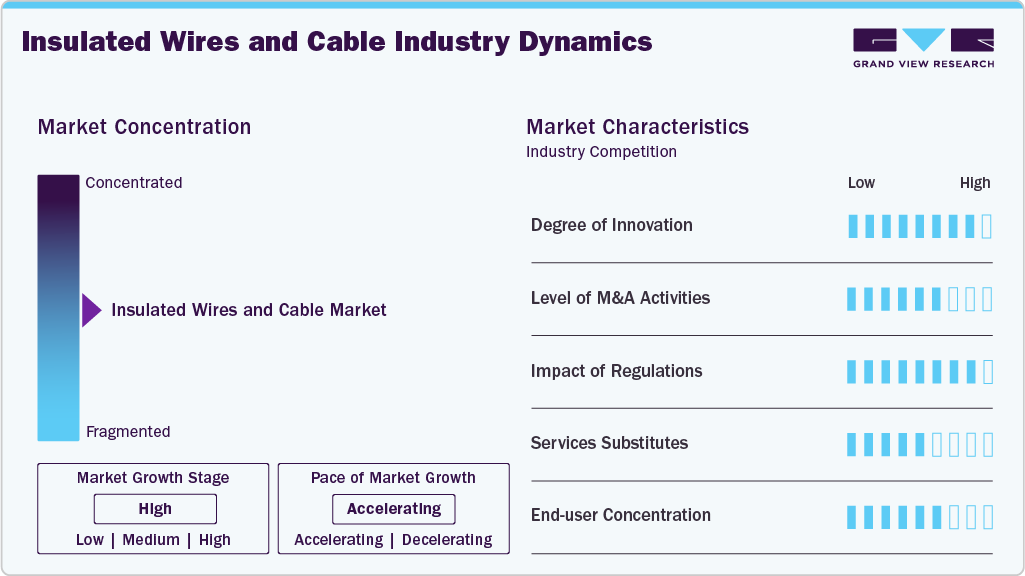
The Insulated Wire and Cable Market is moderately fragmented, with the presence of established global manufacturers and regional players competing across power transmission, telecommunications, construction, automotive, and industrial applications. Leading companies such as Prysmian, Nexans, Sumitomo Electric, Southwire, and LS Cable & System strengthen their competitive positions through broad product portfolios, manufacturing capabilities, geographic expansion, and investments in advanced cable technologies. The market exhibits high innovation intensity as manufacturers focus on advanced insulation materials, high-voltage transmission systems, sustainable cable solutions, and specialized products for renewable energy and electric mobility applications. Regulatory requirements related to electrical safety, fire resistance, product quality, and environmental compliance significantly influence product development, manufacturing processes, and market entry.
 To learn more about this report, Download Free Sample Report
Market growth is supported by expanding electricity infrastructure, renewable energy deployment, urban construction, and increasing demand for reliable telecommunications connectivity. Merger and acquisition activities and strategic partnerships enable manufacturers to expand production capacity, strengthen regional presence, access specialized technologies, and diversify product offerings. Substitution threats remain relatively low because insulated wires and cables are essential components of electrical power distribution and communication infrastructure, although alternative materials and transmission technologies influence product selection. End-user concentration remains moderate, as demand is distributed across utilities, construction companies, telecommunications operators, automotive manufacturers, electronics producers, and industrial facilities. Overall, the market demonstrates an established growth structure with accelerating opportunities driven by infrastructure modernization, electrification, and technological advancements.
Analyst Perspective
Rising investments in power transmission and distribution infrastructure, renewable energy projects, urban construction, and telecommunications networks are creating significant growth opportunities for cable manufacturers across India. Increasing electricity consumption, government-led infrastructure development, and expanding domestic manufacturing activities are strengthening demand across the India insulated wire and cable market. Manufacturers are focusing on expanding production capacities, improving insulation technologies, and developing specialized cable products to meet evolving requirements for electrical safety, durability, and operational efficiency. Additionally, growing electric vehicle adoption, industrial automation, and data center investments are creating new demand opportunities across automotive, industrial, and communication applications. The market is positioned for sustained growth, supported by infrastructure modernization, electrification initiatives, and increasing demand for reliable power transmission and connectivity solutions.
Cable Type Insights
Based on type, the metal conductor cables segment dominated the insulated wires and cables market, accounting for over 87% of global revenue in 2025, driven by increasing investments in power transmission and distribution infrastructure, expanding construction activities, and rising demand for reliable electrical connectivity. Growing adoption across energy and power, automotive, electronics, and industrial manufacturing applications is further supporting segment growth. Additionally, high electrical conductivity, mechanical strength, and compatibility with diverse voltage requirements are reinforcing the preference for copper and aluminum conductor cables. Ongoing grid modernization, renewable energy installations, and electric vehicle infrastructure development are further driving demand for metal conductor cables.
The fiber optic cables segment is anticipated to witness significant growth during the forecast period, owing to increasing investments in telecommunications infrastructure, 5G network expansion, and rising demand for high-speed data transmission. Growing deployment of fiber-to-the-home (FTTH) networks, hyperscale data centers, and cloud computing infrastructure is driving the adoption of high-bandwidth optical connectivity solutions. Increasing internet penetration and data consumption are further accelerating investments in long-distance communication networks and submarine fiber-optic cable systems. Additionally, expanding digital infrastructure and demand for low-latency connectivity are creating new opportunities for fiber-optic cable manufacturers.
Conductor Material Insights
Based on conductor material, the copper segment dominated the insulated wire and cable market, accounting for share of 55.0% of global revenue in 2025, primarily driven by its high electrical conductivity, excellent thermal performance, and widespread use in power transmission, building wiring, and industrial applications. Growing demand for reliable electrical connections across automotive, electronics, and telecommunications infrastructure is further supporting copper cable adoption. Its superior flexibility, durability, and lower electrical resistance compared with alternative conductive materials make it suitable for diverse cable applications. Additionally, expanding electrification, renewable energy installations, and electric vehicle production are strengthening demand for copper-based insulated wires and cables.
The steel segment is expected to witness steady growth during the forecast period, supported by increasing demand for reinforced cables across power transmission, infrastructure, and industrial applications. Growing investments in overhead transmission networks and utility infrastructure are driving the use of steel-reinforced cables that offer enhanced mechanical strength and resistance to tensile stress. Expansion of renewable energy projects and long-distance electricity transmission networks is further supporting demand for specialized steel-based cable solutions. Additionally, the durability and load-bearing capabilities of steel reinforcement are encouraging its adoption in applications requiring improved structural stability and operational reliability.
Voltage Rating Insights
Based on voltage rating, the low voltage segment dominated the insulated wire and cable market, accounting for over 54.0% of global revenue in 2025, owing to its extensive use in residential, commercial, and industrial electrical installations. Rising construction activities, urbanization, and increasing electricity consumption are driving demand for low-voltage cables used in power distribution, lighting, and electrical equipment connections. Growing deployment of electrical systems across buildings, manufacturing facilities, and infrastructure projects is further supporting segment adoption. Additionally, increasing investments in smart buildings, commercial infrastructure, and electric vehicle charging networks are strengthening demand for low-voltage insulated cables.
The high voltage segment is anticipated to witness significant growth during the forecast period, driven by increasing investments in power transmission and distribution infrastructure, grid modernization, and long-distance electricity transmission projects. Growing renewable energy capacity, particularly offshore wind and large-scale solar installations, is increasing demand for high-voltage cables to connect remote generation facilities with national grids. Expansion of cross-border electricity interconnectors and high-voltage direct current (HVDC) networks is further supporting segment demand. Additionally, rising electricity consumption and the need to strengthen grid reliability are encouraging utilities to adopt advanced high-voltage cable systems with improved insulation and transmission capabilities.
Installation Insights
Based on installation, the underground segment dominated the insulated wire and cable market, accounting for over 57.0% of global revenue in 2025, driven by increasing investments in urban power distribution networks, infrastructure modernization, and underground utility installations. Growing urbanization and limited space for overhead transmission infrastructure are encouraging utilities to deploy underground cable systems. Rising emphasis on grid reliability, protection against weather-related disruptions, and improved electrical safety is further supporting segment adoption. Additionally, expanding renewable energy connections, smart city projects, and commercial infrastructure development are strengthening demand for underground insulated cables.
The submarine segment is anticipated to witness significant growth during the forecast period, supported by increasing investments in offshore renewable energy projects, cross-border electricity interconnections, and international telecommunications networks. Expansion of offshore wind farms is driving demand for high-capacity submarine power cables to connect offshore generation facilities with onshore electricity grids. Growing international data traffic, cloud computing, and digital connectivity requirements are further accelerating the deployment of submarine fiber-optic cable networks. Additionally, rising investments in undersea power transmission infrastructure and intercontinental connectivity projects are encouraging manufacturers to develop advanced cables with improved insulation, mechanical strength, and corrosion resistance.
End-use Insights
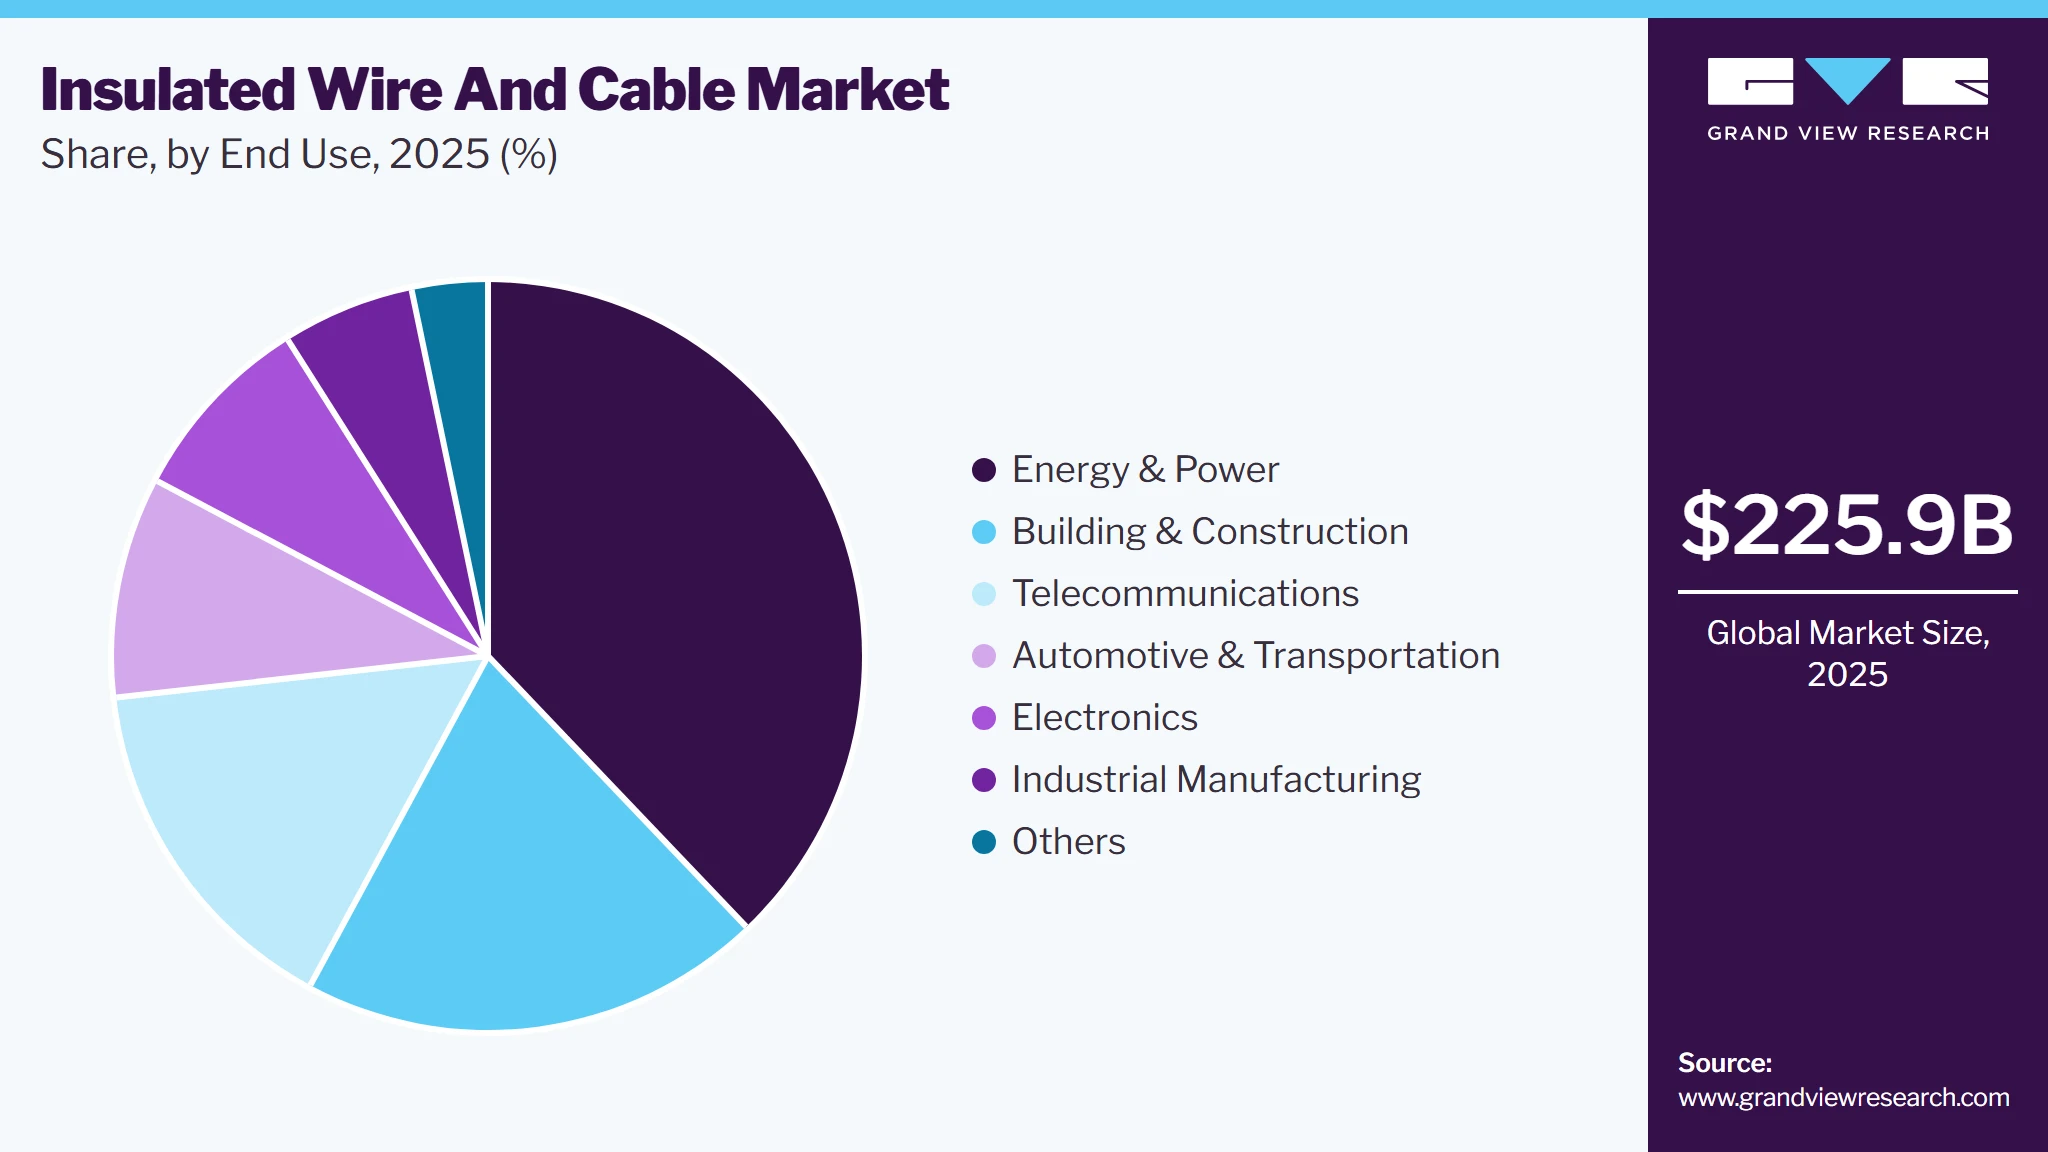
Based on end-use, the energy & power segment dominated the insulated wire and cable market, accounting for over 37.0% of global revenue in 2025. The rising demand for electricity, increasing investments in power transmission and distribution infrastructure, and expansion of renewable energy installations are driving segment growth. Growing deployment of solar and wind power projects is increasing requirements for insulated cables used in power generation, grid connectivity, and electricity distribution. Additionally, grid modernization initiatives, expanding electrification, and cross-border power transmission projects are strengthening demand for reliable and high-capacity cable systems.
 To learn more about this report, Download Free Sample Report
The automotive & transportation segment is expected to witness significant growth during the forecast period, owing to increasing electric vehicle production, expanding charging infrastructure, and rising adoption of advanced electrical systems in vehicles. Growing integration of electronic components, battery management systems, and high-voltage power architectures is driving demand for specialized insulated cables with enhanced thermal resistance, flexibility, and electrical performance. Increasing investments in vehicle electrification, railway modernization, and public transportation infrastructure are further supporting cable requirements across transportation applications. Additionally, rising demand for lightweight wiring solutions and improved vehicle connectivity is encouraging manufacturers to develop advanced cables for electric and conventional vehicles.
Regional Insights
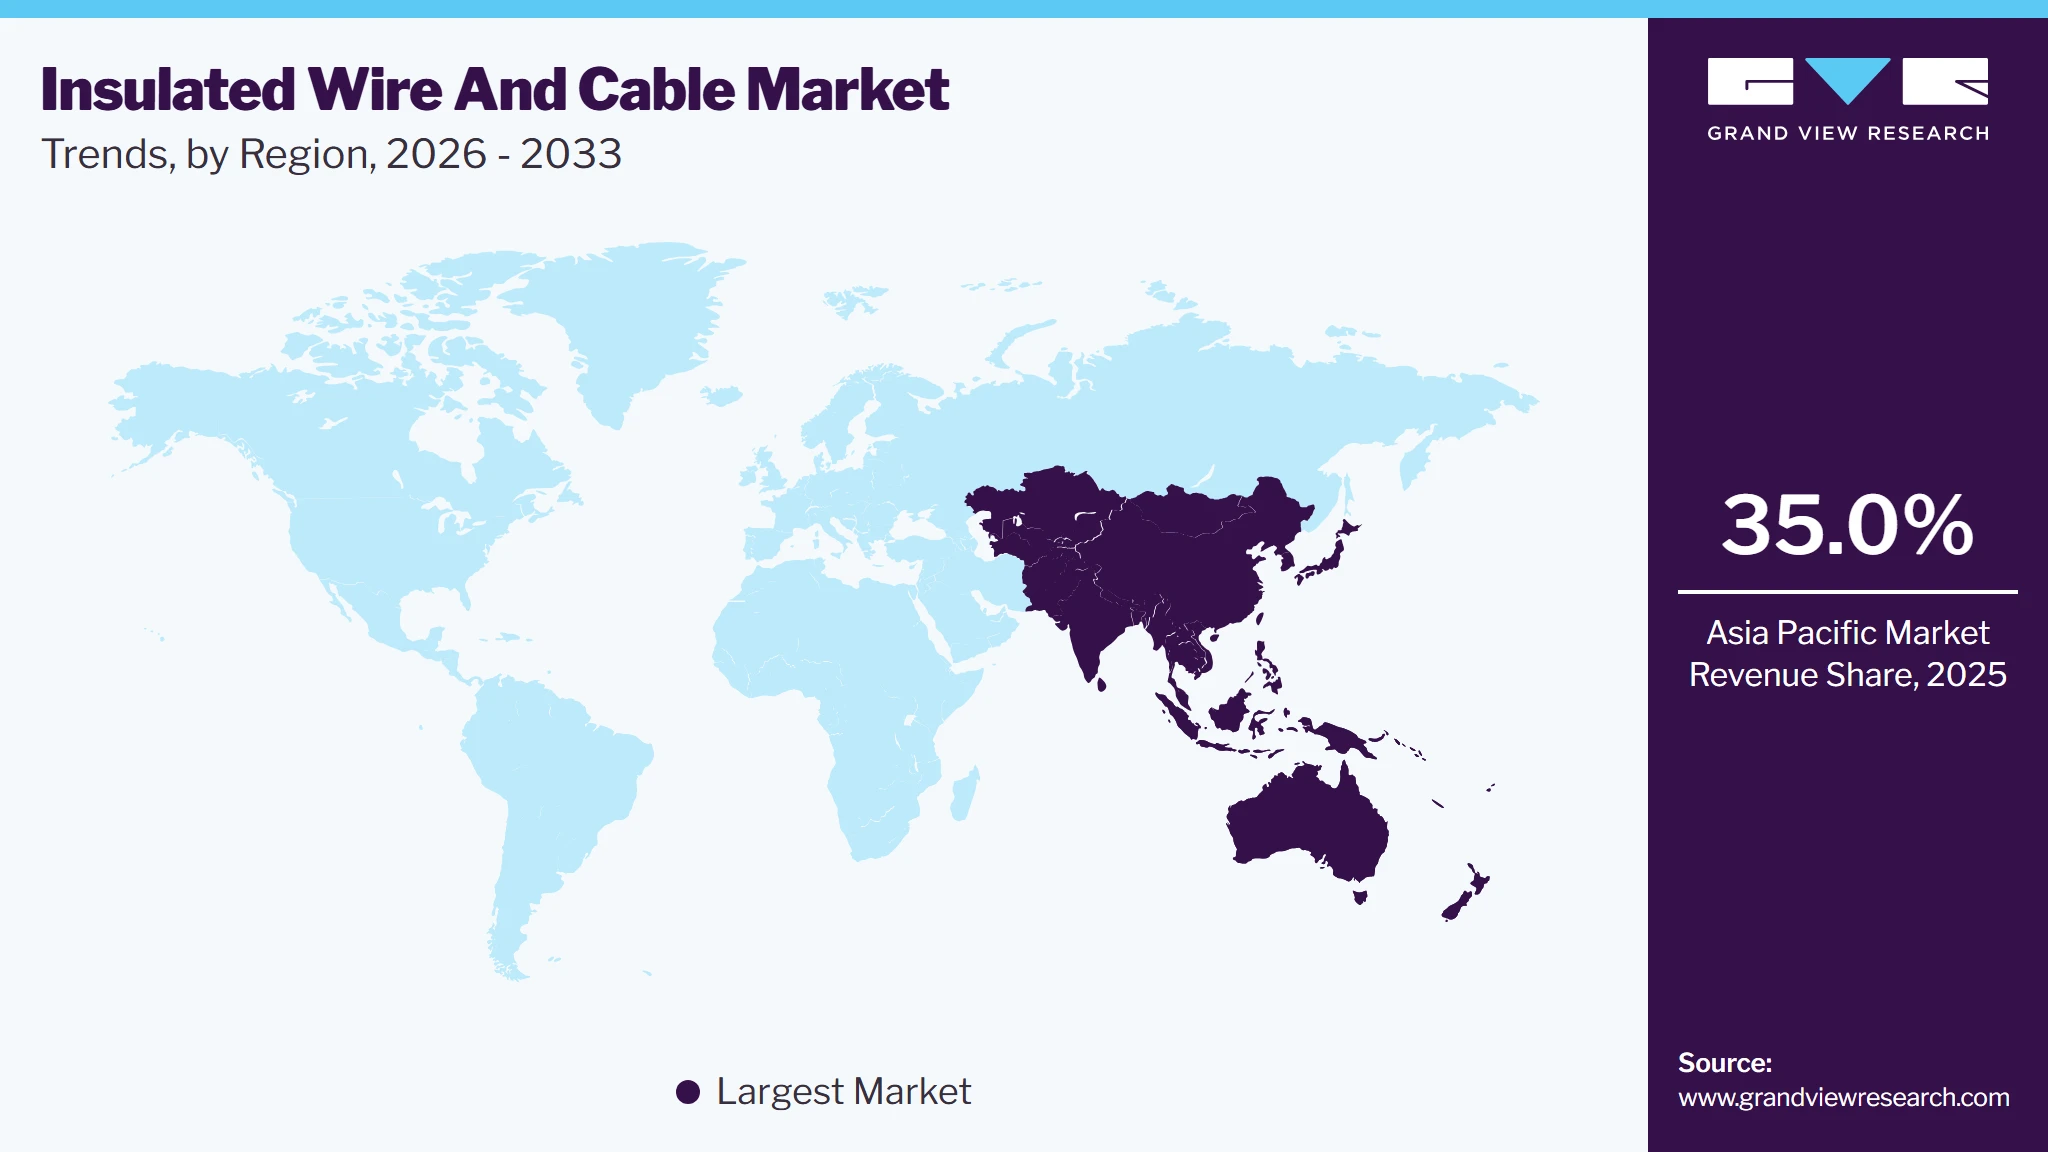
The Asia Pacific insulated wire and cable market accounted for the largest revenue share of 35.0% in 2025, driven by rapid adoption of renewable energy, expanding power transmission infrastructure, and increasing urbanization across major economies. Rising investments in residential and commercial construction, electric vehicle manufacturing, and telecommunications networks are further accelerating regional demand. Additionally, strong manufacturing capabilities, growing electricity consumption, and government-led infrastructure development in China, India, Japan, and South Korea are supporting market expansion.
 To learn more about this report, Download Free Sample Report
China Insulated Wire And Cable Market Trends
The China insulated wire and cable market is gaining momentum, driven by substantial investments in power transmission and distribution infrastructure, renewable energy projects, and urban development. Expanding electric vehicle production, telecommunications networks, and industrial manufacturing activities are further increasing demand for insulated cables across key applications. Additionally, government initiatives focused on grid modernization, electrification, and advanced manufacturing are supporting market growth and encouraging domestic manufacturers to expand production capabilities.
Europe Insulated Wire And Cable Market Trends
The Europe insulated wire and cable market is witnessing robust growth, driven by increasing investments in renewable energy infrastructure, power grid modernization, and cross-border electricity transmission projects. Rising adoption of electric vehicles, expansion of charging networks, and growing demand for high-speed telecommunications connectivity are further supporting cable consumption across the region. Additionally, stringent energy efficiency and safety regulations, along with the development of offshore wind projects, are encouraging manufacturers to expand production and develop advanced, high-performance cable solutions.
Asia Pacific Insulated Wire And Cable Market Trends
The Asia Pacific insulated wire and cable market is growing rapidly, driven by rising investments in power generation, transmission and distribution infrastructure, and renewable energy projects across major economies. Rapid urbanization, expanding construction activities, electric vehicle manufacturing, and growing telecommunications networks are further strengthening regional demand. Additionally, government-led electrification initiatives, industrial expansion, and increasing electricity consumption are encouraging cable manufacturers to expand production capacities and develop advanced insulation solutions.
Key Insulated Wire And Cable Company Insights
Key players operating in the Insulated Wire and Cable market include Prysmian S.p.A., Nexans, Sumitomo Electric Industries, Ltd., LS Cable & System Ltd., Furukawa Electric Co., Ltd., and among others
-
Prysmian S.p.A. is a global manufacturer of cable systems serving the energy and telecommunications industries. The company offers a broad portfolio of power transmission, distribution, and communication cables for utility, infrastructure, and industrial applications. In the insulated wire and cable market, it specializes in high-voltage and extra-high-voltage cables, underground and submarine cable systems, fiber-optic cables, and specialized solutions for renewable energy projects.
-
Nexans is a global cable manufacturer providing electrification solutions for energy, infrastructure, building, and industrial applications. Its product portfolio includes power cables, building wires, telecommunications cables, and specialized cable systems. In the insulated wire and cable market, the company specializes in medium- and high-voltage cables, submarine power cables, underground transmission systems, and cable solutions for renewable energy and electric vehicle charging infrastructure.
Key Insulated Wire And Cable Companies
The following key companies have been profiled for this study on the insulated wire and cable market.
-
Belden Inc.
-
Encore Wire Corporation
-
Finolex Cables Limited
-
Fujikura Ltd.
-
Furukawa Electric Co., Ltd.
-
LEONI AG
-
LS Cable & System Ltd.
-
Nexans
-
NKT A/S
-
Prysmian S.p.A.
-
Southwire Company, LLC
-
Sumitomo Electric Industries, Ltd.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Prysmian S.p.A., Nexans, Sumitomo Electric Industries, Ltd., LS Cable & System Ltd., Furukawa Electric Co., Ltd., Southwire Company, LLC, NKT A/S, Belden Inc.
Mature players focus on expanding global manufacturing capacity, strengthening high-voltage and submarine cable portfolios, developing advanced insulation materials, and securing large-scale infrastructure contracts. Their strategies also include investments in renewable energy connections, grid modernization, telecommunications infrastructure, and specialized cable solutions for automotive and industrial applications.
Their competitive advantage lies in established global operations, extensive product portfolios, advanced manufacturing capabilities, strong customer relationships, technical expertise, and experience in executing large-scale power and communication infrastructure projects. Their established presence across multiple end-use industries also supports customer retention and diversified revenue streams.
These companies face challenges related to raw material price volatility, high capital expenditure, complex manufacturing requirements, regulatory compliance, and competition from regional manufacturers. Maintaining production efficiency, securing long-term infrastructure contracts, and adapting to changing insulation technologies may also influence their operating performance.
Emerging Players: Encore Wire Corporation, Finolex Cables Limited, Fujikura Ltd., LEONI AG
These companies focus on strengthening their positions across specific product categories and regional markets through capacity expansion, product development, distribution partnerships, and customer-focused cable solutions. Their activities address demand from building and construction, automotive, telecommunications, energy, and industrial applications.
Their competitive strengths include specialized product expertise, established regional customer networks, manufacturing experience, application-specific solutions, and the ability to serve targeted end-use industries. Their focused product portfolios and market presence support competition across selected cable categories.
Their growth may be constrained by comparatively narrower product or geographic coverage, exposure to fluctuations in raw material prices, and competition from larger integrated manufacturers. Capacity expansion, technology investments, customer diversification, and access to large infrastructure contracts may also influence their ability to strengthen market positions.
Recent Developments
-
In September 2025, Nexans launched its ULTIMO installation cable range, comprising Nexans XGB ULTIMO and Nexans XVB ULTIMO. The new cables feature improved stripping efficiency, UV resistance, enhanced installation safety, and sustainable manufacturing practices. This launch strengthens Nexans' building wire portfolio by addressing installer productivity, electrical installation safety, and demand for durable cable solutions.
-
In August 2026, Belden Inc. introduced a range of new connectivity and infrastructure products, including expanded Safe-T-Line life-safety cabling, high-density MPO fiber infrastructure, and connectivity solutions for industrial and data center applications. The Safe-T-Line expansion includes shielded and unshielded cables certified to EN 50200 PH120 and CPR Cca standards, designed for fire alarm, evacuation, and emergency communication systems. This launch strengthens Belden's insulated wire and cable portfolio, particularly in safety-critical building infrastructure and high-density fiber connectivity applications.
-
In May 2026, NKT A/S launched JCSI-35, an IEEE-qualified, all-in-one medium-voltage cold-shrink cable splice designed for power cable applications in the North American market. The product is engineered to provide high reliability, electrical integrity, and long-term service life under demanding operating conditions across the United States and Canada. This launch strengthens NKT’s medium-voltage cable accessories portfolio and supports its regional expansion in the insulated wire and cable industry.
Insulated Wire and Cable Market Report Scope
Report Attribute
Details
Market size in 2025
USD 225.9 billion
Estimated market size in 2026
USD 237.5 billion
Projected market size by 2033
USD 368.2 billion
Growth rate
CAGR of 6.5% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company share, competitive landscape, growth factors, and trends
Segments covered
Cable type, conductor material, voltage rating, installation, end-use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East and Africa
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; China; Japan; India; South Korea; Australia; Brazil; UAE; KSA; South Africa
Key companies profiled
Belden Inc.; Encore Wire Corporation; Finolex Cables Limited; Fujikura Ltd.; Furukawa Electric Co., Ltd.; LEONI AG; LS Cable & System Ltd.; Nexans; NKT A/S; Prysmian S.p.A.; Southwire Company, LLC; Sumitomo Electric Industries, Ltd.
Customization scope
Free report customization (equivalent to up to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Insulated Wire And Cable Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global insulated wire and cable market report based on cable type, conductor material, voltage rating, installation, end-use, and region.
-
Cable Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Metal Conductor Cables
-
Fiber Optic Cables
-
-
Conductor Material Outlook (Revenue, USD Billion, 2021 - 2033)
-
Copper
-
Aluminum
-
Steel
-
-
Voltage Rating Outlook (Revenue, USD Billion, 2021 - 2033)
-
Low Voltage
-
Medium Voltage
-
High Voltage
-
-
Installation Outlook (Revenue, USD Billion, 2021 - 2033)
-
Overhead
-
Underground
-
Submarine
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Energy & Power
-
Telecommunications
-
Building & Construction
-
Automotive & Transportation
-
Electronics
-
Industrial Manufacturing
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa
-
UAE
-
KSA
-
South Africa
-
-
Research Methodology
The insulated wire and cable market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Insulated wire and cable segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Cable Type
Revenue Capture Definition
Metal Conductor Cables
This segment includes insulated electrical cables manufactured using metallic conductors such as copper, aluminum, or steel. It covers cables designed to transmit and distribute electrical power across residential, commercial, industrial, and infrastructure applications.
Fiber Optic Cables
This segment includes cables containing optical fibers that transmit data and communication signals through light. It covers fiber-optic cables used in telecommunications networks, broadband connectivity, data centers, and submarine communication infrastructure.
Conductor Material
Revenue Capture Definition
Copper
This segment includes insulated wires and cables manufactured using copper as the primary electrical conductor. It covers products used in power transmission, building wiring, automotive systems, electronics, and industrial applications.
Aluminum
This segment includes insulated electrical wires and cables that use aluminum as the primary conductor. It covers lightweight and cost-efficient cable solutions used in power distribution, transmission networks, renewable energy projects, and infrastructure installations.
Steel
This segment includes cables incorporating steel as a conductive or load-bearing component within the cable structure. It covers specialized electrical and reinforced cable applications requiring high mechanical strength, tensile capacity, and structural support.
Voltage Rating
Revenue Capture Definition
Low Voltage
This segment includes insulated electrical cables rated up to 1,000 volts. It covers wiring solutions used in residential, commercial, and industrial buildings, lighting systems, electrical equipment, and low-voltage distribution networks.
Medium Voltage
This segment includes insulated electrical cables rated above 1,000 volts and up to 35,000 volts. It covers cables used in electricity distribution networks, industrial facilities, renewable energy installations, and utility infrastructure.
High Voltage
This segment includes insulated electrical cables rated above 35,000 volts. It covers cables designed for bulk power transmission, grid interconnections, underground transmission networks, and offshore renewable energy projects.
Installation
Revenue Capture Definition
Overhead
This segment includes insulated wires and cables installed above ground using poles, towers, or supporting structures. It covers electrical distribution and transmission applications where cables are suspended across designated routes.
Underground
This segment includes insulated cables installed below ground through direct burial, ducts, conduits, or underground cable tunnels. It covers power distribution, transmission, and communication applications requiring protected cable installations.
Submarine
This segment includes insulated cables designed for installation beneath seas, oceans, rivers, and other water bodies. It covers subsea power transmission, offshore wind connections, cross-border electricity interconnectors, and submarine communication networks.
End Use
Revenue Capture Definition
Energy & Power
This segment includes insulated wires and cables used in power generation, transmission, distribution, and renewable energy installations. It covers utility networks, substations, grid connections, and power infrastructure projects.
Telecommunications
This segment includes insulated electrical and fiber-optic cables used to transmit communication signals and support network connectivity. It covers broadband, fiber-to-the-home, mobile networks, data centers, and submarine communication infrastructure.
Building & Construction
This segment includes insulated wires and cables used in residential, commercial, and institutional building installations. It covers electrical wiring for lighting, power outlets, HVAC systems, fire safety, and building automation.
Automotive & Transportation
This segment includes insulated wires and cables used in vehicles and transportation infrastructure. It covers automotive wiring harnesses, electric vehicle power cables, charging systems, railway signaling, and electrical connections in transport systems.
Electronics
This segment includes insulated wires and cables used in electronic devices, components, and equipment. It covers internal wiring, signal transmission, connectivity, and power supply cables for consumer electronics and electronic systems.
Industrial Manufacturing
This segment includes insulated wires and cables used in manufacturing facilities, machinery, automation systems, and industrial equipment. It covers control cables, instrumentation cables, motor connections, and specialized cables designed for demanding operating environments.
Others
This segment includes insulated wires and cables used in applications not classified under the previously listed end-use categories. It covers specialized requirements across sectors such as healthcare, aerospace, defense, and marine applications.
Estimation Model
Layer
Key Questions
Description
Insulated Wire and Cable Demand Layer
Who drives demand for insulated wires and cables?
Identify demand across utility companies, construction firms, telecommunications operators, automotive manufacturers, and industrial users for insulated electrical wires, power cables, and fiber-optic cables.
Insulated Wire and Cable Spending Layer
How much do end users and organizations spend on insulated wires and cables?
Assess expenditure on low-, medium-, and high-voltage cables, building wires, fiber-optic cables, specialized cables, and related cable systems across key end-use industries.
Insulated Wire and Cable Adoption & Segmentation Layer
Which cable types, materials, voltage ratings, and installation formats are adopted?
Evaluate market adoption across cable type, conductor material, voltage rating, installation, and end-use segments to determine market distribution and demand patterns.
Insulated Wire and Cable Revenue Realization Layer
How much revenue is generated by the insulated wire and cable market?
Estimate revenue from the sale of insulated metal conductor cables and fiber-optic cables across product categories, end-use industries, and regions to establish the total market size.
Delivered Customizations
This report has been delivered with the following in-depth customizations
Client Request
Customization Delivered
Value Adds
Component-Wise Assessment
Evaluated Software and Services segments and their market contribution.
Identifies component-level demand and growth opportunities.
Analytics Type & Application Analysis
Assessed Descriptive, Diagnostic, Predictive, and Prescriptive Analytics across key business applications.
Highlights high-demand analytics capabilities and application opportunities.
Deployment Mode Assessment
Analyzed Cloud, On-premises, and Hybrid deployment adoption.
Provides insights into deployment preferences and technology requirements.
End-Use Industry Assessment
Evaluated adoption across BFSI, IT & Telecom, Retail, Healthcare, Manufacturing, and other industries.
Identifies high-growth industries and sector-specific demand.
Competitive Landscape Assessment
Reviewed leading providers, product portfolios, market positioning, and competitive strategies.
Highlights competitive strengths, market opportunities, and potential expansion areas.
Frequently Asked Questions About This Report
The metal conductor cables segment led with 87.0% revenue share in 2025, while the fiber optic cables is the fastest-growing segment.
Asia Pacific dominated, with a revenue share of 35.0% in 2025.
Key players include Belden Inc.; Encore Wire Corporation; Finolex Cables Limited; Fujikura Ltd.; Furukawa Electric Co., Ltd.; LEONI AG; LS Cable & System Ltd.; Nexans; NKT A/S; Prysmian S.p.A.; Southwire Company, LLC; Sumitomo Electric Industries, Ltd.
The copper segment led with over 55.0% revenue share in 2025, while the steel segment is the fastest-growing.
The low-voltage segment led with over 54.0% revenue share in 2025, while the high-voltage segment is the fastest-growing.
The underground segment led with over 57.0% revenue share in 2025 and is the fastest-growing segment.
The global insulated wire and cable market size was valued at USD 225.9 billion in 2025 and is estimated at USD 237.5 billion for 2026.
The global insulated wire and cable market is expected to grow at a CAGR of 6.5% from 2026 to 2033, reaching USD 368.2 billion.
Key factors that are driving the market growth include rising investments in power transmission and distribution networks, renewable energy infrastructure, and urban construction activities.
About the Author(s)
HVAC & Construction Research Team
Technology · HVAC & ConstructionThis report was authored by the hvac & construction research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the hvac & construction segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


