
- Home
- »
- Medical Devices
- »
-
Laparoscopic Devices Market Size And Share Report, 2033GVR Report cover

Laparoscopic Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Laparoscopes, Energy Systems, Trocars), By Application (Bariatric Surgery, Urological Surgery), By End-use (Hospital, Clinic), By Region, And Segment Forecasts
Market Size, 2025
$8.8BMarket Estimate, 2026
$9.4BMarket Forecast, 2033
$15.9BCAGR, 2026–2033
7.8%Laparoscopic Devices Market Summary
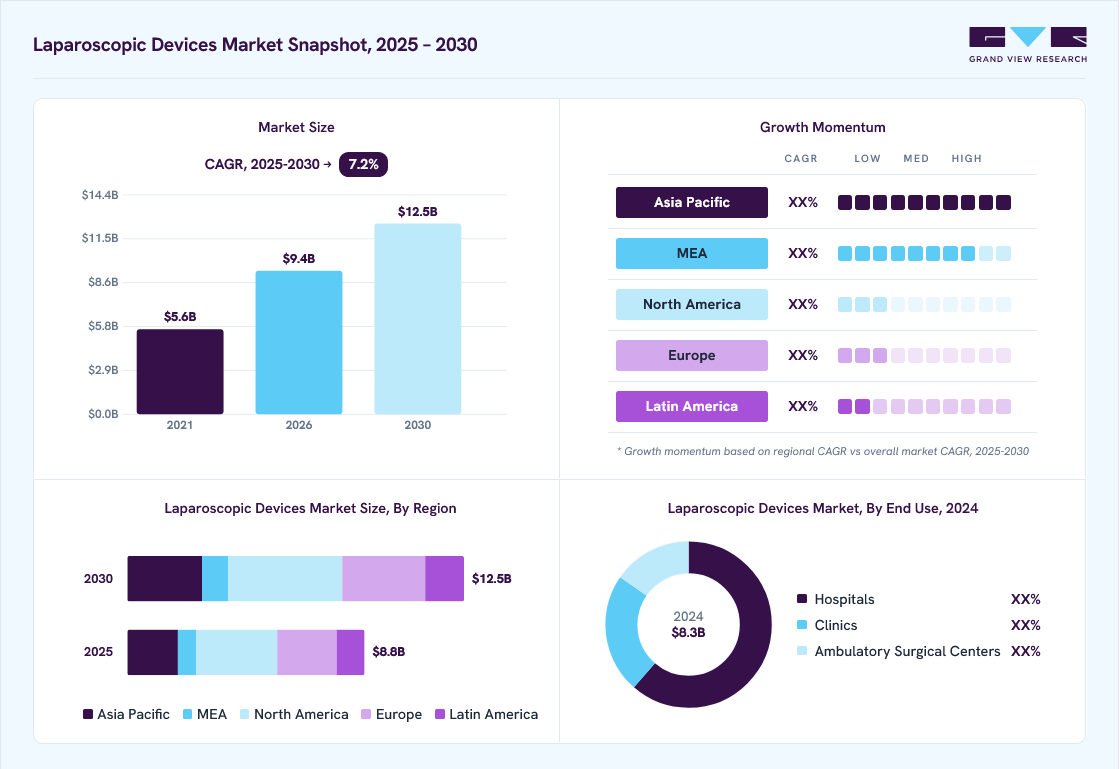
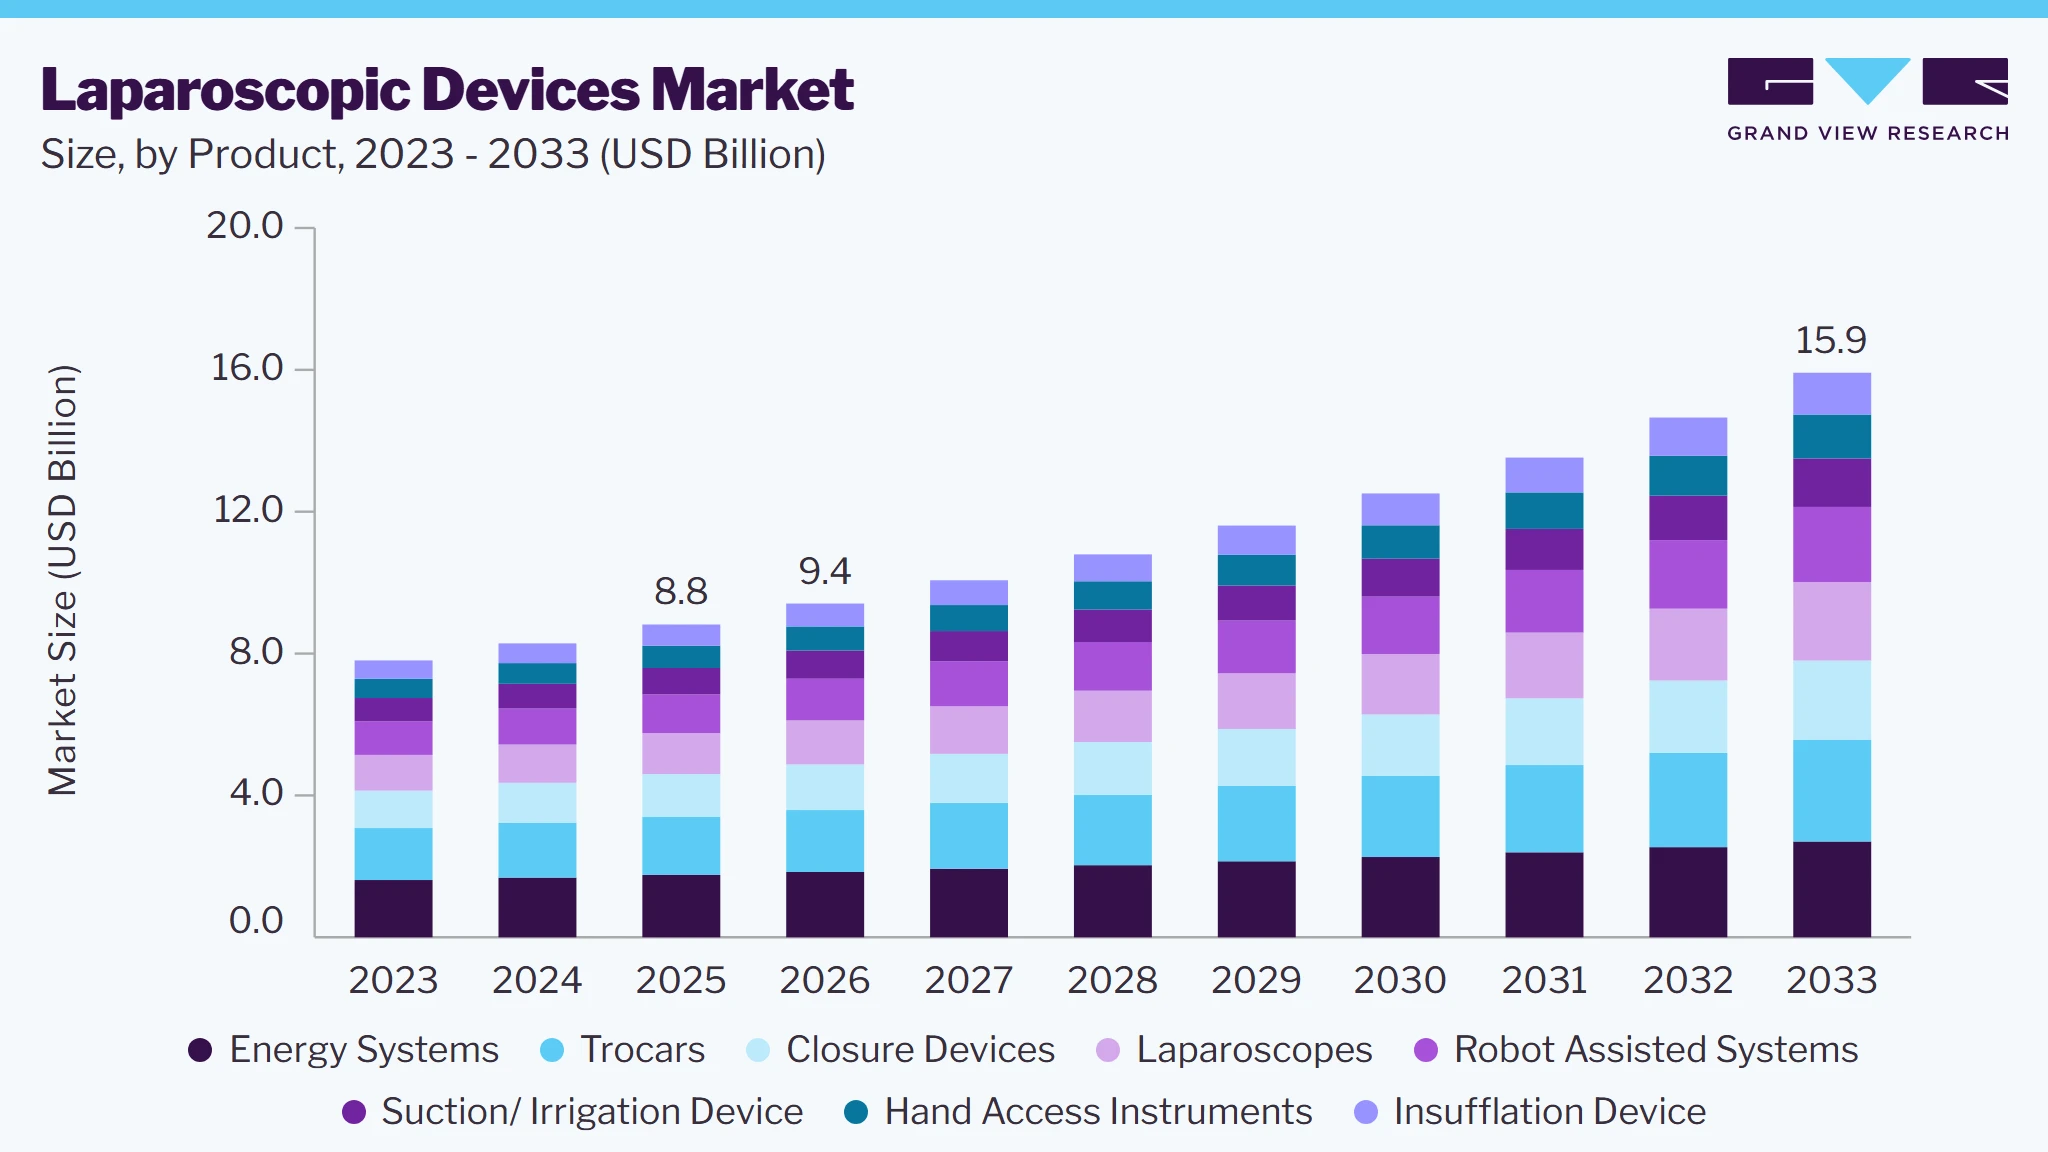
The global laparoscopic devices market size was valued at USD 8.8 billion in 2025 and is projected to grow from USD 9.4 billion in 2026 to USD 15.9 billion by 2033, at a CAGR of 7.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 34.2% in 2025. The laparoscopic devices market is experiencing significant growth, driven by several key factors.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Energy systems segment led the market with the largest revenue share of 19.9% in 2025.
- By application: Bariatric surgery segment led the market with the largest revenue share of 27.0% in 2025.
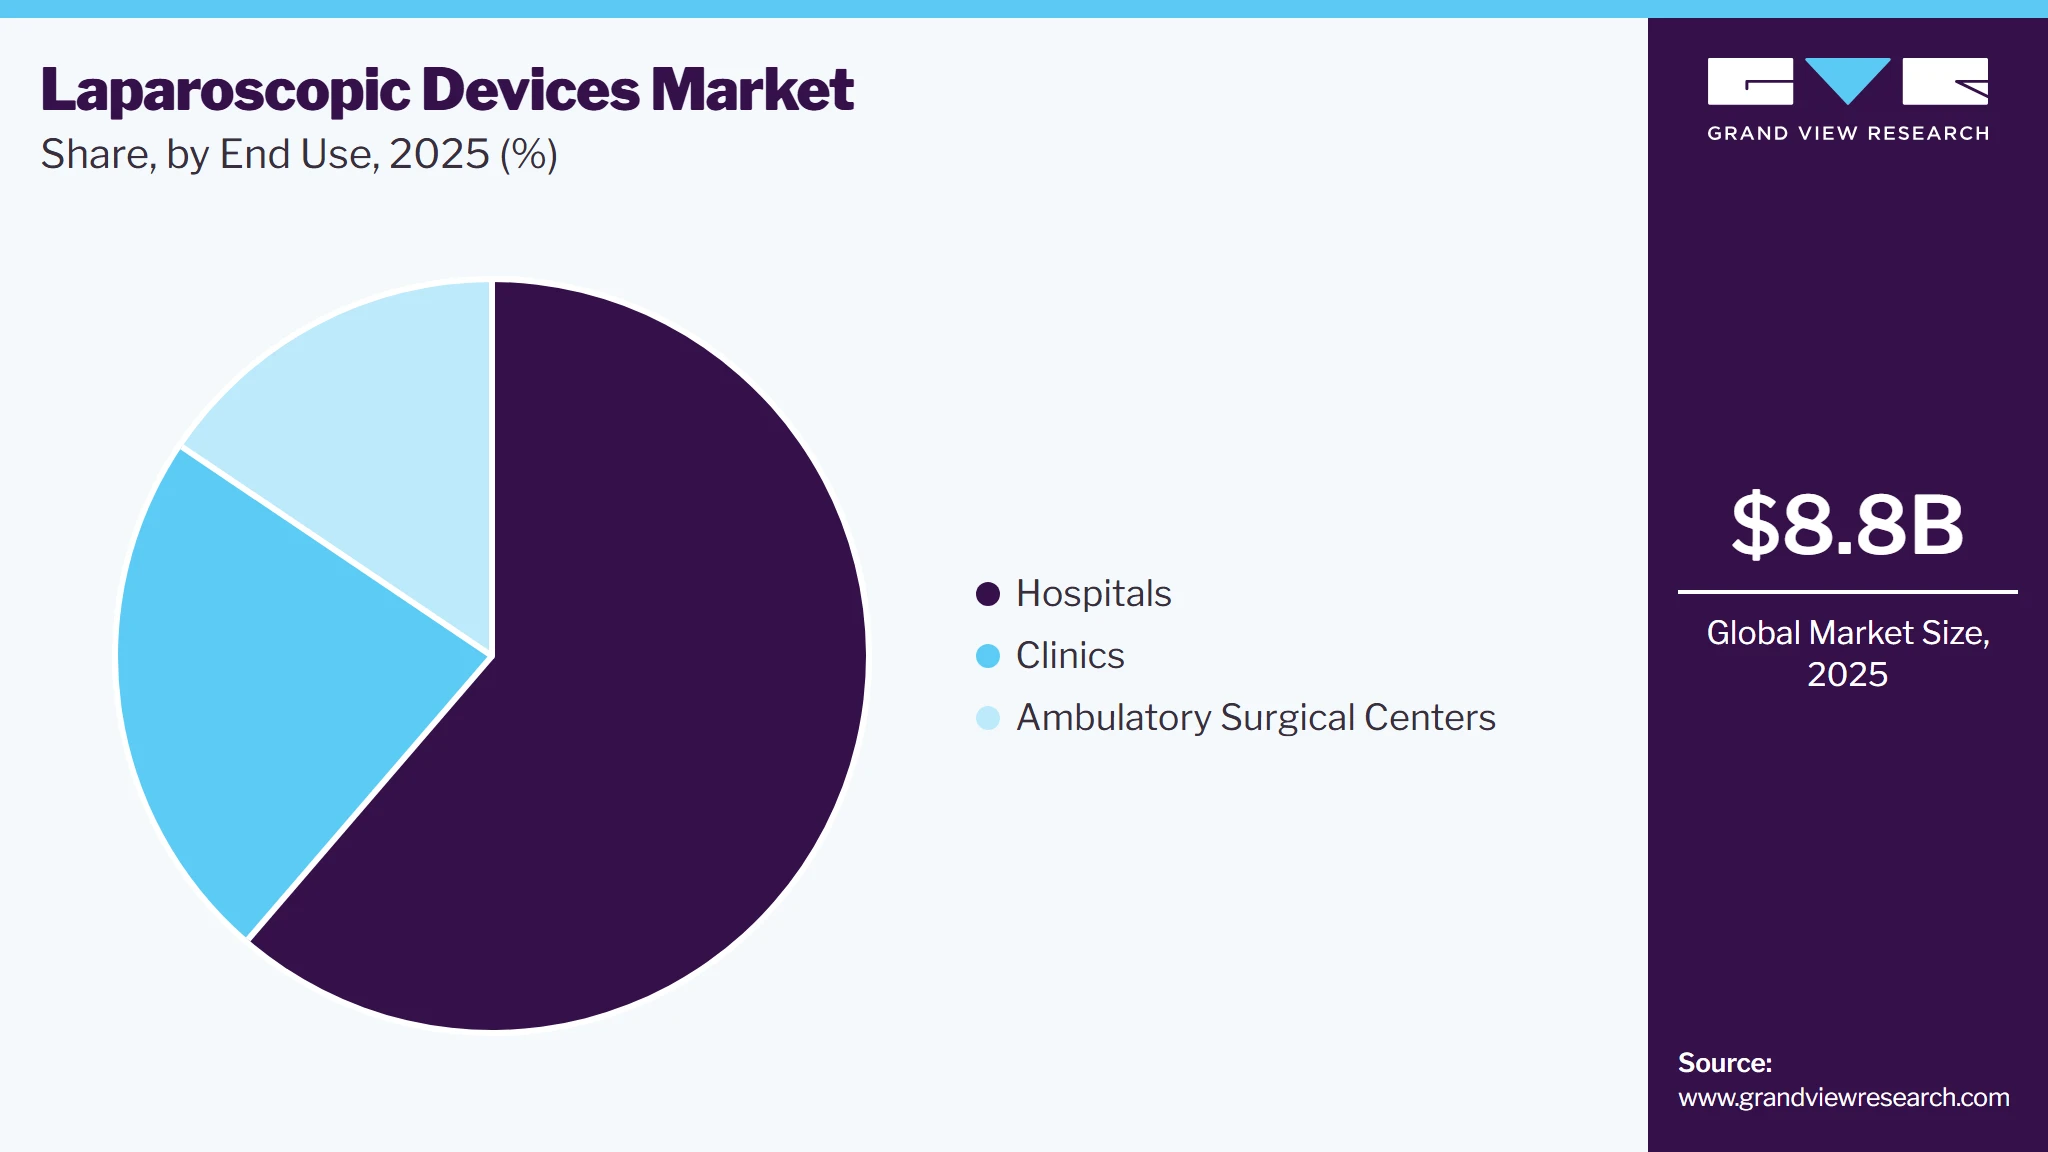
- By end use: Hospitals segment led the market with the largest revenue share of 61.3% in 2025.
Regional Highlights
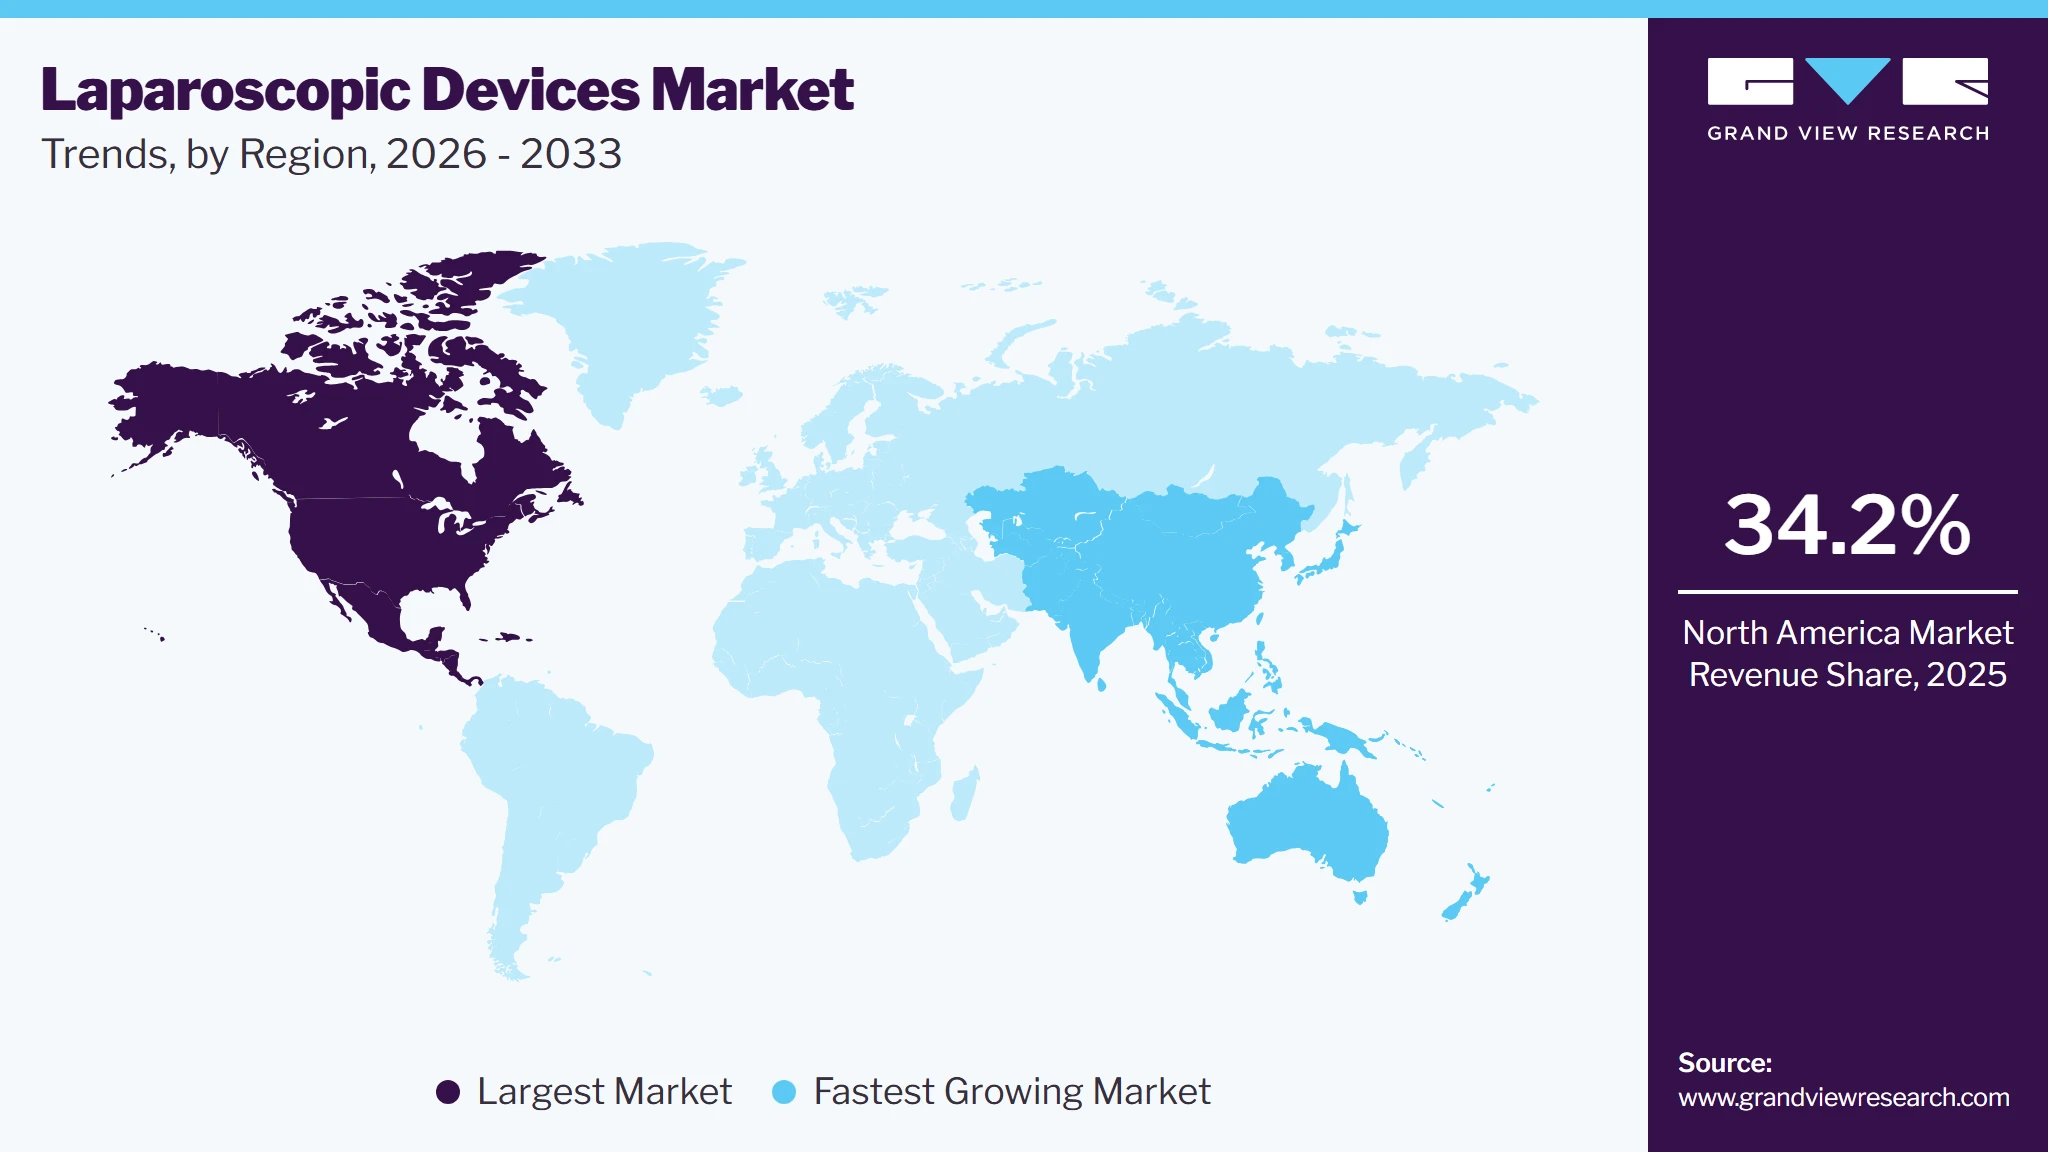
- Largest regional market: North America (34.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 8.8 Billion
- Estimated market size in 2026: USD 9.4 Billion
- Projected market size by 2033: USD 15.9 Billion
- CAGR (2026-2033): 7.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Advancements in technology, such as improved imaging systems and enhanced surgical instruments, are further propelling market expansion. The growing prevalence of conditions requiring laparoscopic interventions, such as obesity and gastrointestinal disorders, contributes to rising procedure volumes.In recent times, laparoscopic surgery is preferred more than conventional ones owing to its numerous benefits, such as shorter hospital stay, decreased blood loss, and lower patient morbidity of laparoscopy, as well as offering quick recovery time, rapid and successful outcomes, low risk of infection, small or no incision and less pain. Since the demand for laparoscopic surgery is significantly increasing, the demand for laparoscopic devices is likely to also grow during the forecast period. The factors driving the growth of the market are the increasing number of patients suffering from health issues such as uterine fibroids, and endometriosis, the rising number of hysterectomy and myomectomy procedures, and growing awareness about the improving healthcare infrastructure in emerging economies.
 To learn more about this report, Download Free Sample Report
Key players are looking to expand their operations regionally by establishing new warehouses in various locations and utilizing multiple channels in the hardest-hit areas. Companies are implementing different strategies to address supply chain disruptions, such as rerouting logistics, sourcing from additional partners, and utilizing air freight. In July 2024, Amber Therapeutics, a start-up associated with the University of Oxford, raised USD100 million in Series A funding to develop Amber-UI, an innovative implantable therapy for mixed urinary incontinence (MUI). This device targets the pudendal nerve through a minimally invasive procedure, representing a significant advancement in treatment. The funding will aid its development and clinical trials as it seeks U.S. regulatory approval.
The rising prevalence of obesity as a chronic disease is critical for the laparoscopic device market. With obesity linked to serious health issues like type 2 diabetes, heart disease, and certain cancers, there's an increasing demand for surgical interventions, particularly laparoscopic bariatric surgery. For instance, in May 2024, Advanced Laparoscopic Surgeons of Morris partnered with the New York Bariatric Group (NYBG), a top provider of bariatric services. This collaboration aims to enhance access to advanced surgical techniques and patient care, with new offices in Edison and Florham Park, NJ, increasing NYBG's presence to 30 locations in the tri-state area. As healthcare providers seek effective solutions to manage obesity and its associated risks, laparoscopic procedures are favored due to their minimally invasive nature, shorter recovery times, and improved patient outcomes. The need for effective weight management solutions is driving innovations and investments in laparoscopic technologies, contributing to market growth. Enhanced diagnostic measures like BMI and waist circumference assessments further facilitate early interventions, emphasizing the importance of laparoscopic devices in obesity treatment.
Market Dynamics
The laparoscopic devices market is witnessing robust growth due to the increasing adoption of minimally invasive surgical procedures and continuous advancements in laparoscopic technologies that improve surgical precision, patient safety, and postoperative recovery. Laparoscopic devices comprise a broad range of specialized instruments, including laparoscopes, trocars, insufflators, energy devices, hand instruments, suction and irrigation systems, access devices, and visualization systems used across general surgery, gynecology, urology, bariatric surgery, colorectal surgery, hepatobiliary surgery, and other minimally invasive procedures.
These devices enable surgeons to perform complex operations through small incisions, resulting in reduced blood loss, shorter hospital stays, faster recovery, lower infection risk, and improved cosmetic outcomes. The rising prevalence of obesity, gastrointestinal disorders, colorectal cancer, gynecological diseases, and urological conditions, coupled with increasing surgical volumes and a growing geriatric population, is driving market demand globally. In addition, advancements in high-definition imaging, 3D and 4K visualization, robotic-assisted laparoscopy, energy-based surgical devices, and ergonomic instrument design are enhancing procedural efficiency, surgical accuracy, and clinical outcomes, thereby supporting continued market growth.
The growing preference for minimally invasive surgery (MIS) is one of the primary factors driving the global laparoscopic devices market. Healthcare providers and patients increasingly favor laparoscopic procedures over conventional open surgeries due to benefits such as smaller incisions, reduced postoperative pain, shorter hospitalization, faster recovery, lower complication rates, and quicker return to normal activities. The increasing incidence of gastrointestinal disorders, obesity, colorectal cancer, gallbladder diseases, hernias, gynecological disorders, and urological conditions is contributing to the growing number of laparoscopic procedures performed worldwide. Furthermore, expanding healthcare infrastructure, rising surgeon expertise, increasing awareness regarding minimally invasive techniques, and favorable clinical outcomes are accelerating adoption across hospitals and ambulatory surgical centers. Continuous technological innovations, including high-definition imaging systems, advanced energy platforms, articulating instruments, fluorescence-guided surgery, and robotic-assisted laparoscopy, are further improving surgical precision, workflow efficiency, and patient outcomes, creating sustained growth opportunities for the laparoscopic devices market.
Despite significant technological advancements, the laparoscopic devices market continues to face challenges associated with the high capital cost of advanced laparoscopic equipment and the need for specialized surgical expertise. Modern laparoscopic systems require substantial investment in visualization platforms, insufflation systems, energy devices, imaging equipment, and reusable surgical instruments, making adoption difficult for smaller hospitals and healthcare facilities with limited budgets. In addition, successful laparoscopic procedures require extensive surgeon training, advanced hand-eye coordination, and specialized technical skills, creating barriers in regions facing shortages of experienced minimally invasive surgeons. Ongoing maintenance costs, equipment sterilization requirements, and periodic technology upgrades further increase operational expenses. Limited reimbursement in certain healthcare systems and financial constraints in developing countries may also slow the adoption of advanced laparoscopic technologies, particularly in resource-limited healthcare settings.
Market Concentration & Characteristics
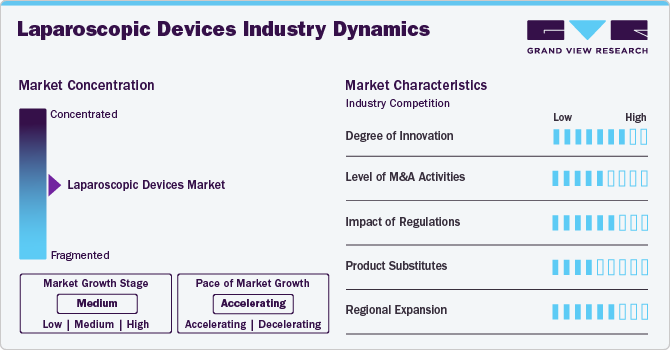
The laparoscopic devices industry is characterized by moderate to high concentration, with several key players such as Karl Storz SE & CO. Kg, Medtronic, Olympus Corporation, and others dominating the market. Established manufacturers often lead in innovation, quality, and market share, while new entrants focus on niche products and technological advancements. The industry encompasses various devices, including cameras, instruments, and access systems, catering to minimally invasive procedures. Regulatory compliance is crucial, impacting product development and market entry. Additionally, increasing demand for minimally invasive surgeries and advancements in surgical technologies drive competitive dynamics, prompting continuous innovation and collaboration among industry stakeholders to enhance patient outcomes and operational efficiency.
The laparoscopic devices industry witnessed a notable innovation when UC Davis Health adopted ConMed's AirSeal System in November 2022, establishing low-pressure insufflation as the standard for all laparoscopic surgeries. This initiative makes UC Davis the first multi-site health system in the U.S. to implement this method, which enhances patient comfort and improves surgical outcomes. Such advancements highlight the industry's commitment to adopting cutting-edge technologies that prioritize patient well-being while optimizing surgical procedures.
 To learn more about this report, Download Free Sample Report
Regulations play a crucial role in the laparoscopic devices industry, ensuring the safety, efficacy, and quality of surgical instruments. Regulatory bodies, such as the FDA and EMA, impose stringent requirements for device approval, necessitating comprehensive clinical trials and thorough documentation. Compliance with these regulations can increase development costs and timelines but ultimately fosters consumer trust and drives innovation. Additionally, evolving regulatory standards encourage manufacturers to invest in advanced technologies and improve product designs. This regulatory landscape shapes market dynamics, influencing competition and market entry, while ensuring that laparoscopic devices meet the highest safety and performance standards.
Mergers and acquisitions in the laparoscopic devices industry are rising due to the need for research and development, reflecting the industry's dynamic nature. Companies are leveraging M&A activities to innovate and offer advanced solutions that meet the evolving needs of healthcare professionals. For instance, in June 2024, Karl Storz SE & CO. entered into a merger agreement with Asensus Surgical to expand its surgical robotics division. Asensus will become a subsidiary of KARL STORZ Endoscopy-America after the deal is finalized in the third quarter of 2024. This move strengthens KARL STORZ's presence in the robotics space, enhancing its innovation capabilities.
In the laparoscopic devices industry, product substitutes can significantly influence market dynamics. Alternatives such as traditional open surgery may be considered for certain procedures, particularly when laparoscopic techniques are not feasible or when surgeons prefer conventional methods. Additionally, advancements in non-invasive technologies, such as endoscopic and robotic-assisted surgeries, present viable substitutes that can enhance surgical precision and reduce recovery times. Furthermore, emerging innovations in imaging and diagnostic tools may also compete with traditional laparoscopic devices. As these alternatives gain traction, they prompt manufacturers to continually innovate and improve their laparoscopic offerings to maintain a competitive edge in the market.
The laparoscopic devices industry is witnessing significant regional expansion, driven by increasing healthcare demands and advancements in surgical techniques. Emerging markets in Asia-Pacific and Latin America are experiencing rapid growth due to rising investments in healthcare infrastructure and a growing number of surgical procedures. For instance, in May 2024, B. Braun Melsungen AG has opened a new factory in Switzerland, expanding its production capabilities for advanced medical devices. The facility is designed to enhance efficiency and quality in manufacturing, aligning with the company’s commitment to innovation in the healthcare sector. This expansion reflects B. Braun’s growth strategy in the MedTech industry.
Analyst Perspective
The laparoscopic devices market is shaped by transformative healthcare trends. Growing adoption of minimally invasive surgery is a major driver. Surgical volumes are rising due to obesity, gastrointestinal disorders, colorectal cancer, gynecological, and urological conditions. Continuous advancements in surgical visualization technologies are reshaping the competitive landscape. Integration of robotic-assisted surgery enhances precision, ergonomics, and patient outcomes. Healthcare providers invest in devices that reduce tissue trauma and shorten recovery times. Innovations include high-definition imaging, 3D systems, fluorescence-guided imaging, and articulating instruments. Expansion of outpatient surgical care and modern operating room infrastructure boosts demand. Overall, hospitals, ambulatory centers, and specialty clinics worldwide are steadily increasing adoption of advanced laparoscopic devices.
Product Insights
Based on product, the energy systems segment led the market with the largest revenue share of 19.9% in 2025. Increasing incidence of obesity and urological diseases is expected to contribute to market growth. These systems have wide applications in bariatric surgeries, such as gastric bypass, sleeve gastrectomy, adjustable gastric band, and biliopancreatic diversion with duodenal switch. According to the IFSO Global Registry Report 2019, 833,687 bariatric surgeries were performed in 61 countries globally in 2019. Thus, the abovementioned factors are expected to fuel market growth during the forecast period.
The insufflation device segment held significant market is projected to experience the fastest compound annual growth rate (CAGR) over the forecast period. This growth is driven by the increasing adoption of minimally invasive surgical procedures, where insufflation devices play a critical role in creating a working space within the abdomen. Advances in technology, such as low-pressure insufflation systems, enhance patient safety and comfort, further fueling demand. As more healthcare providers recognize the benefits of these devices in improving surgical outcomes, the insufflation segment is positioned for robust growth, reflecting broader trends in the minimally invasive surgery landscape.
Application Insights
Based on application, the bariatric surgery segment led the market with the largest revenue share of 27.0% in 2025. With obesity rates rising globally, the demand for bariatric procedures has surged, increasing the need for specialized instruments and consumables. According to the World Obesity Federation, in 2024, the NCD Risk Factor Collaboration (NCD-RisC) reported that over one billion people worldwide now live with obesity, including nearly 880 million adults and 159 million children and adolescents aged 5-19. Their analysis showed that almost 3 billion people are affected by overweight or obesity, making these conditions a greater health risk globally than underweight. This trend drives demand for laparoscopic tools and energy-based devices tailored for bariatric procedures.
The general surgery segment in the laparoscopic devices market is projected to experience the fastest compound annual growth rate (CAGR) over the forecast period. General surgery, which encompasses a wide range of procedures, including abdominal surgeries, hernia repairs, and appendectomies, is a key segment within the laparoscopic devices market. This field requires a diverse array of specialized instruments and consumables, such as scalpels, forceps, cannulas, retractors, and dilators, tailored to various surgical needs. Technological advancements in devices such as energy systems, closure devices, and hand access instruments have significantly improved surgical precision and outcomes.
End-use Insights
Based on end use, the hospitals segment led the market with the largest revenue share of 61.3% in 2025. driven by an increase in cases requiring surgical intervention and preventive procedures. In the U.S., the CDC reported approximately 125.7 million outpatient department visits, reflecting a growing need for surgical equipment. Surgical procedures such as angioplasties, kidney and liver transplants, and trauma care have contributed to this demand. Moreover, the aging population and rising unhealthy lifestyle choices, including smoking and alcohol consumption, have led to a surge in noncommunicable diseases, such as cancer, diabetes, and cardiovascular disorders.
 To learn more about this report, Download Free Sample Report
The ambulatory surgical centers segment is projected to witness the fastest CAGR over the forecast period due to increasing preference for same-day surgeries, cost savings, and reduced waiting times. These centers facilitate minimally invasive procedures, and better reimbursement policies compared to hospitals are driving segment expansion. The rising number of ASCs is also boosting market growth, with approximately 9,600 active centers in the U.S. as of 2024, according to Definitive Healthcare. The ability to perform large volumes of surgeries efficiently is expected to sustain this trend during the forecast period.
Regional Insights
North America dominated the laparoscopic devices market with the largest revenue share of 34.2% in 2025. The growing preference for laparoscopic surgeries over open surgeries is significantly driving the market. Surgeons increasingly recommend laparoscopy for its faster recovery and better outcomes. Moreover, competition among key players in terms of product innovation will impact market dynamics. The rising incidence of cardiovascular diseases also fuels demand for laparoscopic devices. The CDC reports that heart disease accounted for 702,880 deaths in the U.S. in 2022. As minimally invasive procedures gain popularity for their advantages, the laparoscopic devices market is expected to see substantial growth in the coming years.
 To learn more about this report, Download Free Sample Report
U.S. Laparoscopic Devices Market Trends
The laparoscopic devices market in the U.S. held the largest share in the North America region in 2025. Technological innovations like robotic-assisted surgeries and miniaturized devices are crucial in the laparoscopic field. In February 2024, the FDA authorized Virtual Incision Corporation’s MIRA Surgical System, a groundbreaking miniaturized robotic-assisted device for colectomy procedures. This approval, under the FDA's De Novo Classification process for novel devices, was partly based on U.S. clinical trials conducted under the Investigational Device Exemption (IDE). The MIRA system marks a significant advancement in surgical technology, improving precision in minimally invasive procedures.
Europe Laparoscopic Devices Market Trends
The European laparoscopic devices market is witnessing growth. The UK, France, Germany, Italy, and Spain are some of the major markets in this region. Growth in the region can be attributed to the increasing prevalence of chronic diseases such as diabetes, which often necessitates surgeries due to complications associated with the condition. According to the International Diabetes Federation report published in May 2023, around 61 million Europeans were living with type 2 diabetes, which is further expected to reach 67 million by 2030.
In the UK, the laparoscopic devices market is experiencing significant growth due to several key factors. High per capita income, an established healthcare system, a substantial number of healthcare professionals, good access to healthcare services, the availability of advanced devices, and favorable reimbursement policies are all expected to drive market expansion in the UK.
The laparoscopic devices market in France is witnessing growth, benefits from a comprehensive healthcare system and advanced medical technology adoption. France has high healthcare spending that ensures access to high-quality, people-centered treatment and health services in the country. According to World Bank data, France’s healthcare expenditure was around 12.31% of its GDP in 2021. France has a strong healthcare infrastructure, which meets the healthcare needs of its citizens. This favors the usage of minimally invasive surgical instruments & devices.
The laparoscopic devices market in Germany is undergoing significant growth, driven by the growing prevalence of chronic diseases in the country. As per data from International Diabetes Federation for 2021, in Germany, out of the total adult population of 62,027,700, the prevalence of diabetes in adults was 10%, resulting in a total of 6,199,900 diabetes cases in adults.
Asia Pacific Laparoscopic Devices Market Trends
The Asia Pacific laparoscopic devices market is witnessing significant growth driven by rising healthcare investments, expanding elderly population, and increasing prevalence of chronic respiratory diseases. Countries like China, India, and Japan are key contributors, with growing adoption of advanced medical technologies and improving healthcare infrastructure. The APAC laparoscopic devices market is expected to expand due to the region's numerous FDA, TGA, and EMA-approved facilities.
The Japan laparoscopic devices market is set for significant growth, primarily driven by the country's aging population. As of 2023, approximately 30% of the population is aged 65 and older, making them more susceptible to diseases like cancer, blood disorders, and autoimmune conditions. This demographic shift is anticipated to boost demand for laparoscopic devices in the coming years.
The laparoscopic devices market in China is expected to grow in the Asia Pacific in 2023. China's swiftly changing healthcare landscape and patient needs significantly contribute to the growth of the laparoscopic devices market. The country faces a rising prevalence of chronic diseases like diabetes, cardiovascular conditions, and autoimmune disorders. For instance, the International Diabetes Federation (IDF) reported that in 2021, 537 million people globally had diabetes, with 206 million in the Western Pacific Region; this number is projected to increase to 260 million by 2045.
The India laparoscopic devices market is rapidly growing, driven by the integration of VR and telesurgery technologies, highlighting the country’s commitment to advanced medical practices. This innovation is expected to boost confidence in minimally invasive techniques, leading to increased adoption of laparoscopic devices and attracting investments in equipment and education. As hospitals adopt these technologies, demand for cutting-edge laparoscopic tools will rise, further fueling market expansion.
Latin America Laparoscopic Devices Trends
The Latin American laparoscopic devices market is experiencing growth driven by increasing surgical procedures and rising healthcare investments. The market is propelled by the rise in the prevalence of chronic diseases and a rapidly aging population, which is increasing the number of surgical procedures. Surgical equipment such as forceps, dilators, scissors, and retractors are widely used in several surgeries related to orthopedic, cardiac, and gynecological conditions in the region.
The laparoscopic devices market in Saudi Arabia is anticipated to expand in the forecast period. The growing geriatric population, which is highly susceptible to chronic diseases, is one of the major factors positively influencing the market growth in this country. For instance, as per Saudi Arabian Monetary Agency (SAMA), the proportion of the Saudi Arabian population aged 60 and above is estimated to reach 25% by the end of 2050.
Key Laparoscopic Devices Company Insights
The competitive scenario in the laparoscopic devices market is highly competitive, with key players such as B. Braun Melsungen AG, BD; and Medtronic holding significant positions. The major companies are undertaking various organic as well as inorganic strategies such as new product development, collaborations, acquisitions, mergers, and regional expansion for serving the unmet needs of their customers.
Key Laparoscopic Devices Companies:
The following key companies have been profiled for this study on the laparoscopic devices market.
- Karl Storz SE & CO. Kg
- Medtronic
- Johnson and Johnson
- Olympus Corporation
- CONMED Corporation
- B. Braun Melsungen AG
- The Cooper Companies Inc.
- Richard Wolf GmbH
- Microline Surgical
- BD
- Welfare Medical Ltd
- DEAM
- Intuitive Surgical
- Shenzen Mindray Bio Medical Electronics Co., Ltd
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Karl Storz SE & CO. Kg; Medtronic; Johnson and Johnson; Olympus Corporation; CONMED Corporation; B. Braun Melsungen AG)
- Established companies focus on expanding comprehensive laparoscopic device portfolios comprising laparoscopes, energy systems, trocars, insufflation systems, hand instruments, robotic-assisted surgical platforms, visualization systems, and access devices. They emphasize continuous innovation in high-definition and 3D imaging, advanced energy technologies, AI-assisted surgical visualization, ergonomic instrument design, surgeon training programs, strategic partnerships with hospitals, and global distribution expansion to strengthen market leadership.
- Strong global distribution networks, extensive relationships with hospitals, ambulatory surgical centers, and surgeons support sustained market leadership. Broad product portfolios, proven clinical performance, advanced manufacturing capabilities, significant R&D investments, and strong regulatory expertise enable continuous innovation and widespread adoption across general surgery, gynecology, urology, bariatric surgery, and colorectal procedures.
- Dependence on premium-priced laparoscopic systems may create affordability challenges in cost-sensitive healthcare markets. High capital investment requirements, stringent regulatory approvals, and lengthy product development cycles can increase commercialization timelines. Large organizational structures may also reduce agility in responding rapidly to emerging surgical technologies and evolving clinical requirements.
Emerging Players (The Cooper Companies Inc.; Richard Wolf GmbH; Microline Surgical; BD; Welfare Medical Ltd; DEAM; Intuitive Surgical; Shenzen Mindray Bio Medical Electronics Co., Ltd)
- Emerging companies prioritize the development of cost-effective laparoscopic devices, advanced visualization technologies, innovative energy systems, robotic-assisted surgical solutions, and ergonomically designed minimally invasive instruments. They focus on expanding regional distribution, strengthening collaborations with hospitals and surgical centers, improving product performance, and addressing unmet clinical needs through technology-driven product innovation.
- Agile product development, competitive pricing strategies, and the ability to rapidly introduce technologically advanced minimally invasive surgical solutions enable emerging companies to strengthen market presence. Their focus on innovation, flexible manufacturing, robotic technologies, and underserved regional markets provides opportunities to gain market share while adapting quickly to changing surgeon preferences.
- Limited global brand recognition and comparatively smaller distribution infrastructures may restrict international expansion. Lower financial resources can constrain large-scale clinical studies, regulatory approvals, manufacturing scale-up, and commercialization activities. Dependence on third-party distributors and strong competition from established multinational surgical device manufacturers may challenge long-term market penetration and sustainable revenue growth.
Recent Developments
-
In April 2024,Medtronic introduced AI capabilities with its new Touch Surgery Live Stream, featuring 14 AI algorithms. These enhance post-operative analysis and provide AI-driven surgical insights across both laparoscopic and robotic-assisted surgeries.
-
In August 2024, Olympus Corporation introduced the new 5mm POWERSEAL Sealer/Divider devices, enhancing its advanced bipolar surgical energy lineup. These POWERSEAL devices offer surgeons dependable sealing, dissection, and grasping functions in both laparoscopic and open surgeries, while minimizing the force needed to close the jaws.
-
In June 2024, Intuitive Surgical announced that the U.S. Food and Drug Administration (FDA) has cleared a labeling update for the da Vinci X and Xi systems, specifically related to radical prostatectomy procedures.
Laparoscopic Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.8 billion
Estimated market size in 2026
USD 9.4 billion
Projected market size by 2033
USD 15.9 billion
Growth rate
CAGR of 7.8% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Thailand; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Karl Storz SE & CO. Kg; Medtronic; Johnson and Johnson; Olympus Corporation; CONMED Corporation; B. Braun Melsungen AG; The Cooper Companies Inc.; Richard Wolf GmbH; Microline Surgical; BD; Welfare Medical Ltd; DEAM; Intuitive Surgical; Shenzen Mindray Bio Medical Electronics Co., Ltd
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Laparoscopic Devices Market Report Segmentation
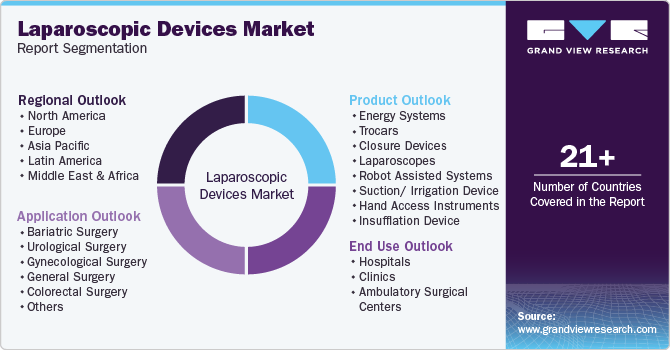
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global laparoscopic devices market report on the basis of product, application, end-use and region:
 To learn more about this report, Download Free Sample Report
-
Laparoscopic Devices Market by Product Outlook (Revenue, USD Million; 2021 - 2033)
-
Energy Systems
-
Trocars
-
Closure Devices
-
Laparoscopes
-
Robot Assisted Systems
-
Suction/ Irrigation Device
-
Hand Access Instruments
-
Insufflation Device
-
-
Laparoscopic Devices Market by Application Outlook (Revenue, USD Million; 2021 - 2033)
-
Bariatric Surgery
-
Urological Surgery
-
Gynecological Surgery
-
General Surgery
-
Colorectal Surgery
-
Others
-
-
Laparoscopic Devices Market by End Use Outlook (Revenue, USD Million; 2021 - 2033)
-
Hospitals
-
Clinics
-
Ambulatory Surgical Centers
-
-
Laparoscopic Devices Market by Region Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The Laparoscopic devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Laparoscopic devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Laparoscopes
Revenue is generated from rigid laparoscopic visualization systems used to provide high-definition internal imaging during minimally invasive surgeries. This segment includes standard, HD, 3D, and 4K laparoscopes utilized across general surgery, gynecology, urology, and colorectal procedures to improve surgical precision and visualization.
Energy Systems
Revenue is captured from advanced surgical energy devices, including electrosurgical, ultrasonic, bipolar, and vessel-sealing systems used for tissue dissection, coagulation, cutting, and hemostasis during laparoscopic procedures. Growing demand for efficient blood loss management supports this segment.
Trocars
Revenue is generated from disposable and reusable trocar systems that provide safe access ports for laparoscopic instruments. These devices facilitate instrument insertion while maintaining pneumoperitoneum and are widely used across virtually all laparoscopic surgical procedures.
Closure Devices
Revenue is captured from laparoscopic fascial closure systems, clip appliers, staplers, suturing devices, and wound closure products used to securely close trocar sites and internal tissues. Demand is driven by increasing minimally invasive surgical volumes and improved postoperative outcomes.
Suction/Irrigation Device
Revenue is generated from suction and irrigation systems used to remove blood, fluids, and debris while maintaining a clear surgical field during laparoscopic procedures. These devices enhance visualization and improve procedural efficiency across multiple surgical specialties.
Insufflation Device
Revenue is captured from carbon dioxide (CO₂) insufflation systems that establish and maintain pneumoperitoneum during laparoscopic surgery. These devices regulate intra-abdominal pressure and gas flow, ensuring optimal working space and enhanced surgical safety.
Robot-Assisted Systems
Revenue is generated from robotic-assisted laparoscopic surgical platforms and associated instruments that improve dexterity, precision, visualization, and ergonomics during complex minimally invasive procedures. Increasing adoption of robotic surgery continues to support segment growth.
Hand Access Instruments
Revenue is captured from hand-assist devices, access ports, retractors, and specialized instruments that allow surgeons to introduce a hand into the abdominal cavity while preserving pneumoperitoneum. These products are primarily utilized in complex laparoscopic and hybrid surgical procedures.
Segment - Application
Revenue capture definition
Bariatric Surgery
Revenue is generated from laparoscopic devices used in weight-loss procedures such as gastric bypass, sleeve gastrectomy, and adjustable gastric banding. Increasing obesity prevalence and demand for minimally invasive bariatric interventions are driving this segment.
Urological Surgery
Revenue is captured from laparoscopic devices utilized in nephrectomy, prostatectomy, adrenalectomy, pyeloplasty, and other minimally invasive urological procedures. Advanced visualization and precision instruments contribute to improved surgical outcomes and faster patient recovery.
Gynecological Surgery
Revenue is generated from laparoscopic devices used in hysterectomy, myomectomy, ovarian cyst removal, endometriosis treatment, and other gynecological procedures. Rising adoption of minimally invasive women's health surgeries significantly supports market demand.
General Surgery
Revenue is captured from laparoscopic devices used in cholecystectomy, appendectomy, hernia repair, gastrointestinal surgery, and other common abdominal procedures. This represents one of the largest application segments due to high global procedural volumes.
Colorectal Surgery
Revenue is generated from laparoscopic instruments used for colorectal cancer surgery, bowel resection, inflammatory bowel disease treatment, diverticular disease management, and rectal surgery. Growing preference for minimally invasive colorectal procedures supports segment expansion.
Others
Revenue is captured from laparoscopic devices used in hepatobiliary surgery, thoracic surgery, pediatric surgery, endocrine surgery, trauma surgery, and other specialized minimally invasive procedures requiring advanced laparoscopic technologies.
Segment - End Use
Revenue capture definition
Hospitals
Revenue is generated from laparoscopic devices procured by public and private hospitals performing a wide range of minimally invasive surgical procedures. Hospitals account for the largest market share due to high surgical volumes, advanced operating rooms, and multidisciplinary surgical teams.
Clinics
Revenue is captured from specialty surgical clinics and physician-owned centers utilizing laparoscopic devices for elective and outpatient minimally invasive procedures. Growth is supported by increasing demand for convenient, cost-effective surgical care.
Ambulatory Surgical Centers
Revenue is generated from laparoscopic devices used in ambulatory surgical centers performing same-day minimally invasive procedures. The increasing shift toward outpatient surgery, lower healthcare costs, shorter recovery times, and improved patient convenience continues to drive demand in this segment.
Estimation Model
Step
Guiding Question
Process Steps
Data Sources
Scope Definition
What is being sized?
1. Define the market scope covering laparoscopic energy systems. 2. Identify end users. 3. Establish Geographic Coverage (Global/Regional). 4. Align base year & forecast horizon (2020–2030).
EUA, EMA, MFDA, Hospital Imaging Database
Build the Install Base
How large is the addressable laparoscopic surgery population?
1. Estimate annual laparoscopic surgical procedures by specialty. 2. Analyze disease prevalence, obesity trends, gastrointestinal disorders, colorectal cancer incidence. 3. Incorporate healthcare infrastructure, hospital availability, operating rooms. 4. Forecast procedure growth based on demographic trends.
Company Annual Reports, Hospital Procurement Database, Distributor Sales Data
Estimate Utilization & Procedure
What proportion utilizes laparoscopic devices?
1. Assess utilization of laparoscopic devices by market category, surgical specialty, healthcare facility type, and geographic region. 2. Evaluate adoption rates of advanced laparoscopic devices via robotic‑assisted surgery, visualization, 3D imaging, and energy systems technology. 3. Validate penetration assumptions through triangulation with procedure data. 4. Cross‑verify adoption estimates using historical/procedure data.
Company Interviews, OECD Database, clinical trainers, industry experts
Revenue Conversion
How are procedure volumes converted into market revenue?
1. Determine average selling prices (ASPs) of laparoscopic devices. 2. Calculate market revenues by product type, application, end use, and region. 3. Validate revenue estimates using company financial reports. 4. Cross‑check final market estimates through triangulation using company revenues.
Company Annual Reports, Distributor pricing sheets, procurement data, expert interviews
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client request
Customization delivered
Value adds
Product Technology and Innovation Assessment
Conducted a comprehensive evaluation of laparoscopic device technologies, including laparoscopes, energy systems, trocars, insufflation devices, closure devices, robotic-assisted systems, and hand access instruments. The study assessed visualization quality, energy delivery technologies, ergonomic design, AI integration, robotic compatibility, reusable versus disposable instruments, and technological advancements across minimally invasive surgical procedures.
Enables stakeholders to identify emerging technologies, evaluate innovation trends, benchmark product performance, and prioritize investments in next-generation laparoscopic solutions. Supports R&D planning, product differentiation, and long-term portfolio expansion strategies.
Competitive Landscape and Strategic Benchmarking
Performed a detailed competitive analysis of leading laparoscopic device manufacturers based on product portfolios, technological innovation, regulatory approvals, manufacturing capabilities, pricing strategies, geographic footprint, strategic collaborations, mergers & acquisitions, distribution networks, and recent product launches across global markets.
Provides actionable competitive intelligence by benchmarking leading manufacturers, identifying market gaps, evaluating strategic positioning, and highlighting growth opportunities. Supports informed business decisions, partnership evaluation, and competitive strategy development.
Regional Market and Procedure Analysis
Conducted an extensive regional assessment across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, analyzing laparoscopic procedure volumes, healthcare infrastructure, surgeon adoption, reimbursement frameworks, regulatory environments, minimally invasive surgery penetration, and hospital investments in advanced surgical technologies.
Supports regional expansion strategies by identifying high-growth markets, emerging adoption trends, investment opportunities, and unmet clinical needs. Enables optimized market entry, distribution planning, and resource allocation across developed and emerging healthcare systems.
Frequently Asked Questions About This Report
Key factors that are driving the laparoscopic devices market growth include the increasing number of patients suffering from gallstones, obesity, rectal prolapse, and severe gastroesophageal reflux disease syndrome.
Asia Pacific is the fastest-growing region over the forecast period.
The global laparoscopic devices market size was valued at USD 8.8 billion in 2025 and is estimated at USD 9.4 billion for 2026.
The global laparoscopic devices market is expected to grow at a CAGR of 7.8% from 2026 to 2033, reaching USD 15.9 billion by 2033.
Hospitals segment led the market with the largest revenue share of 61.3% in 2025.
Key companies operating in the laparoscopic devices market are Karl Storz SE & CO. Kg; Medtronic; Johnson and Johnson; Olympus Corporation; CONMED Corporation; B. Braun Melsungen AG; The Cooper Companies Inc.; Richard Wolf GmbH; Microline Surgical; BD; Welfare Medical Ltd; DEAM; Intuitive Surgical; Shenzen Mindray Bio Medical Electronics Co., Ltd
North America dominated the laparoscopic devices market with the largest revenue share of 34.2% in 2025.
The bariatric surgery segment led the market with the largest revenue share of 27.0% in 2025.
Energy systems segment led the market with the largest revenue share of 19.9% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


