
- Home
- »
- Plastics, Polymers & Resins
- »
-
Medical 3D Printing Plastics Market Size Report, 2026-2033GVR Report cover

Medical 3D Printing Plastics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (ABS, PEEK, Photopolymer, Polyamide), By Form (Filament, Powder, Ink), By Region (North America, Asia Pacific, Europe, Latin America, Middle East and Africa), And Segment Forecasts
Market Size, 2025
$858.8MMarket Estimate, 2026
$1,086.8MMarket Forecast, 2033
$4,983.8MCAGR, 2026–2033
24.3%Medical 3D Printing Plastics Market Summary
The global medical 3d printing plastics market size was valued at USD 858.8 million in 2025 and is projected to grow from USD 1,086.8 million in 2026 to USD 4,983.8 million by 2033, at a CAGR of 24.3% from 2026 to 2033. The market in North America dominated with a revenue share of 45.2% in 2025. The medical 3D printing plastics market is experiencing steady growth, driven by the expansion of the advertising industry and increasing investments in promotional and point-of-sale display materials.
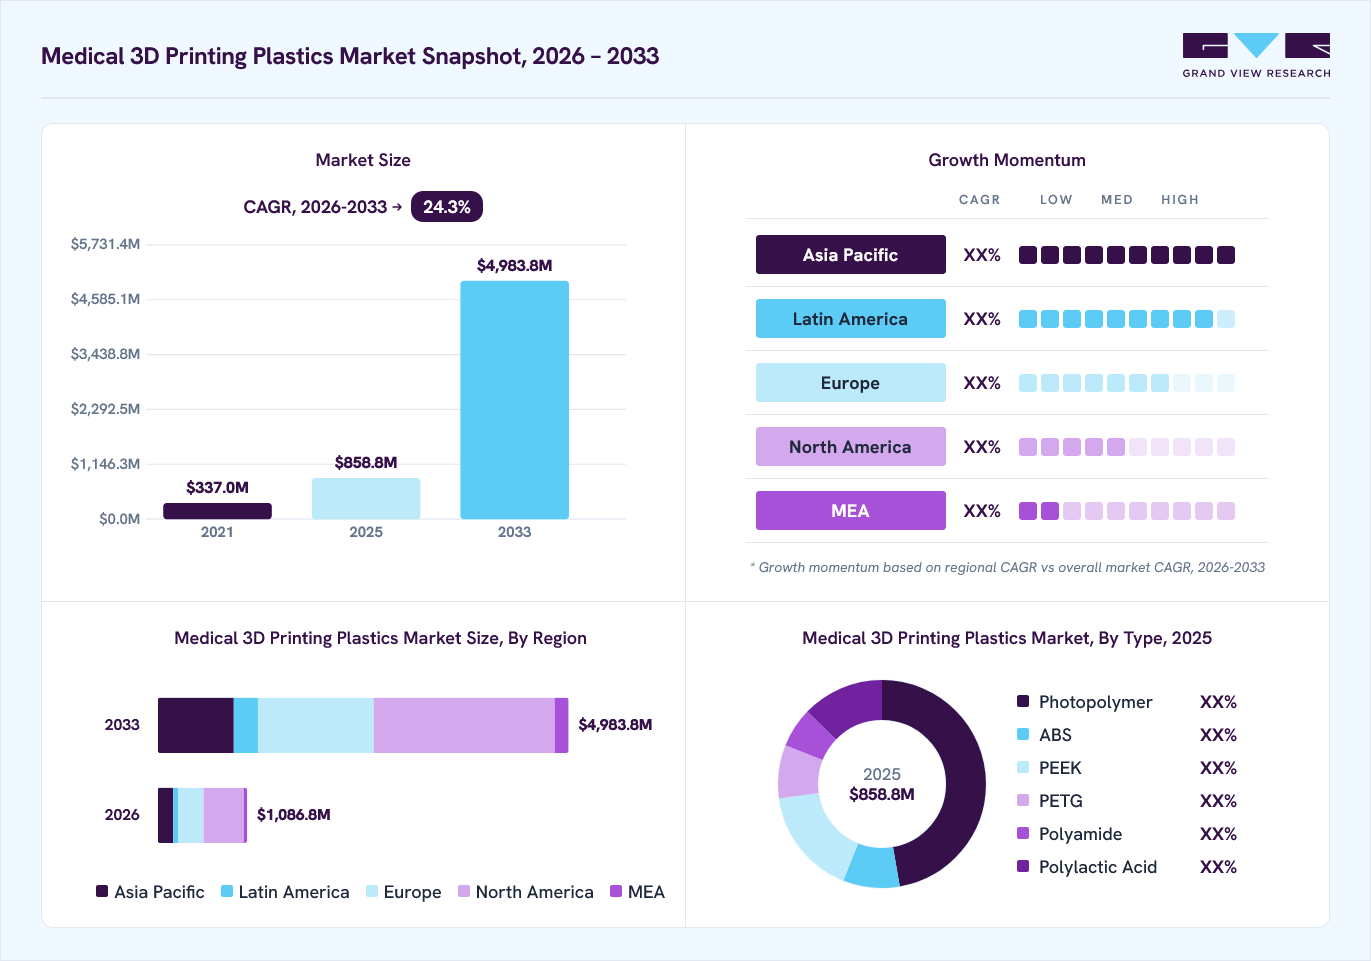 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By form: Filament segment held the largest market share of 75.6% in 2025.
- By type: Photopolymer segment held the largest market share of 47.2% in 2025.
Regional Highlights
- Largest regional market: North America (45.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 858.8 Million
- Estimated market size in 2026: USD 1,086.8 Million
- Projected market size by 2033: USD 4,983.8 Million
- CAGR (2026-2033): 24.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Additionally, rising demand for visually appealing gaming panels and graphics is supporting product adoption. Growing consumer preference for online retail channels, coupled with continuous advancements in printing technologies that enhance design quality, efficiency, and customization capabilities, is further creating significant growth opportunities for the market globally.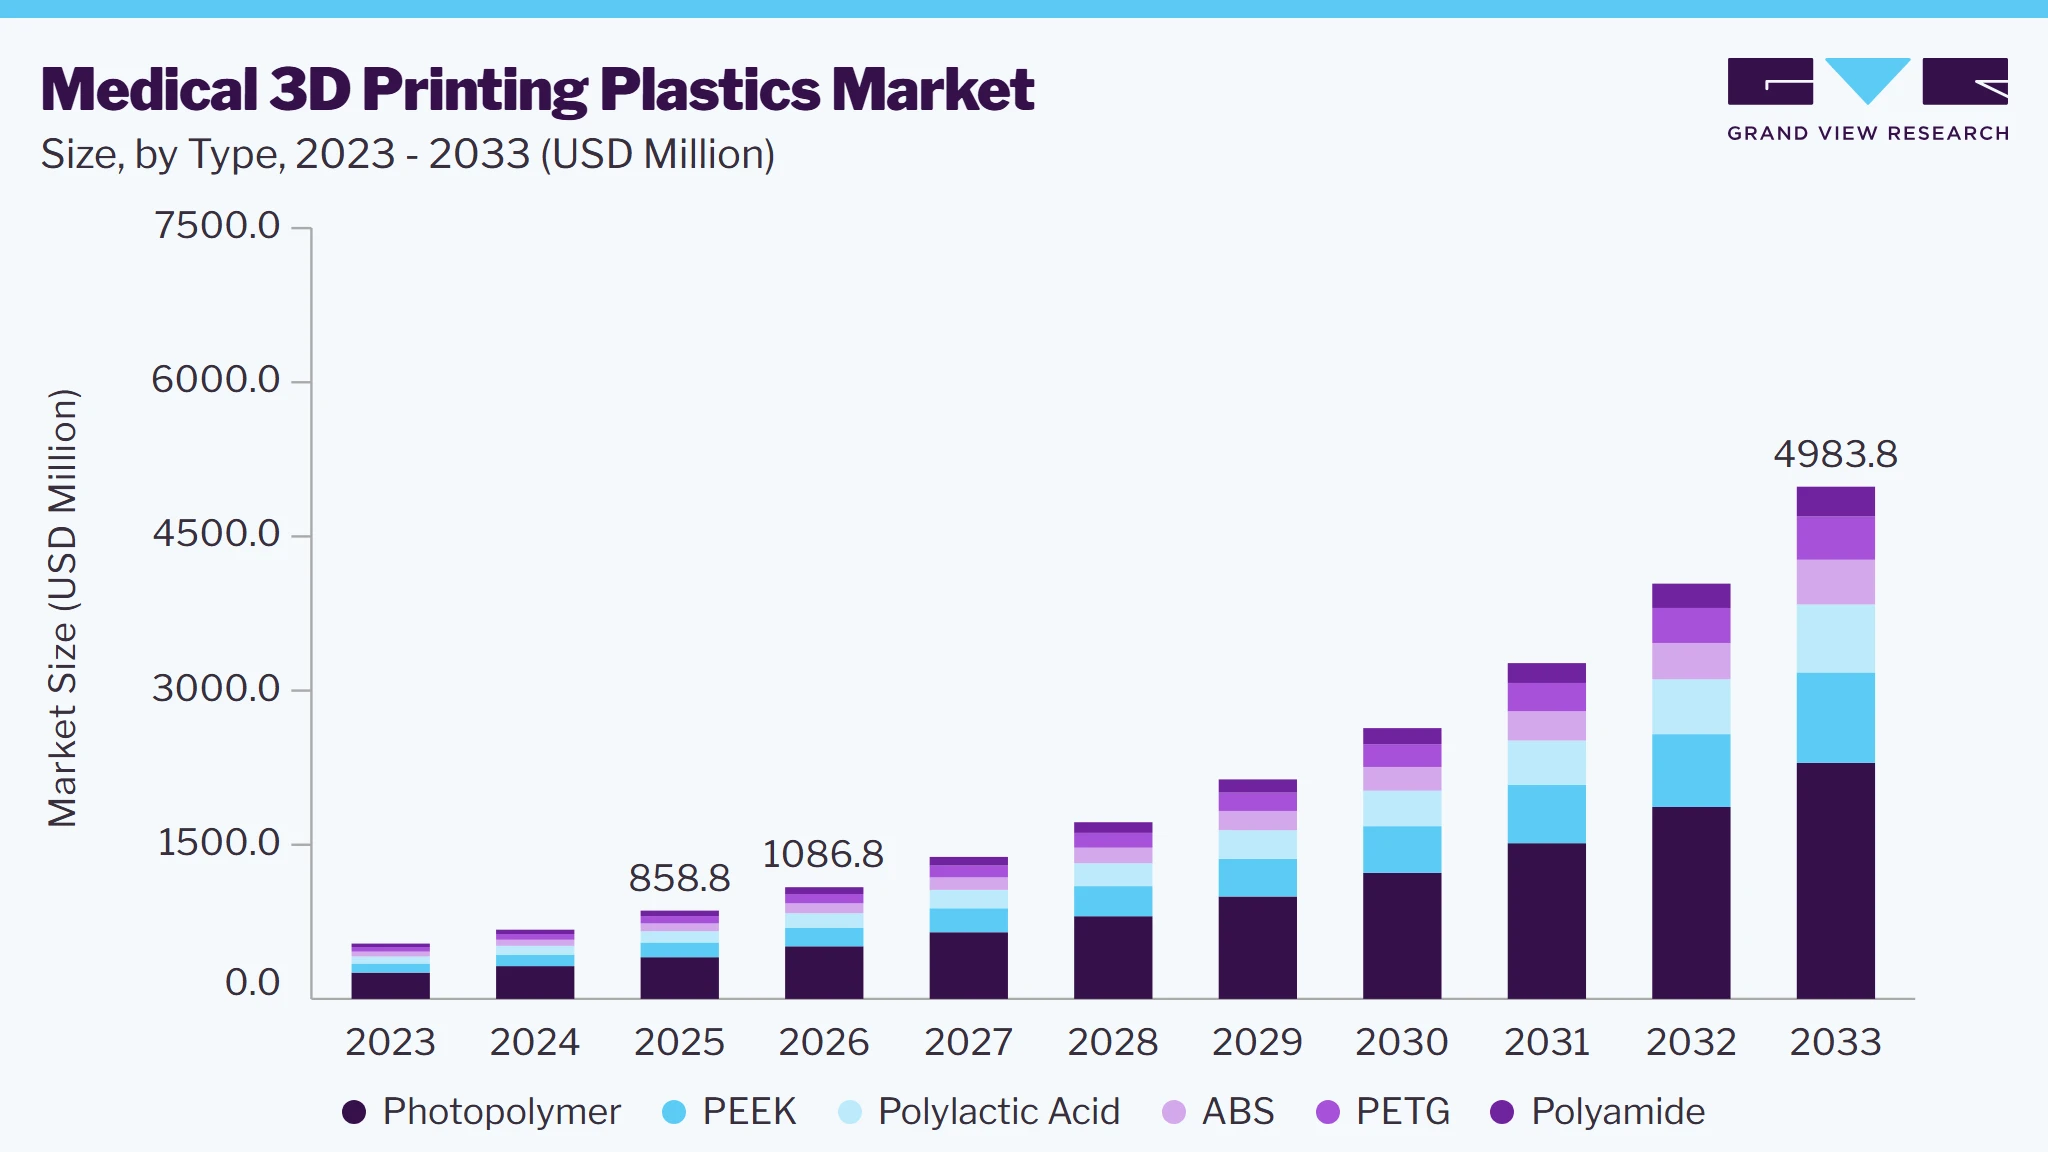 To learn more about this report, Download Free Sample Report
The global medical 3d printing plastics market size was valued at USD 673.4 million in 2024 and is projected to grow from USD 1,086.8 million in 2026 to USD 2,634.8 million by 2030, at a CAGR of 25.1% from 2025 to 2030. North America dominated the market, accounting for a revenue share of 45.3% in 2024. This growth is attributed to the increasing aging population and rising healthcare awareness significantly contribute to the demand for customized medical solutions. In addition, advancements in 3D printing technologies enable the production of complex, patient-specific devices and implants. Furthermore, the COVID-19 pandemic has also accelerated the adoption of 3D printing in healthcare, highlighting its potential for rapid prototyping and production of essential medical supplies, thus fostering market expansion.
Medical 3D printing plastics refer to specialized materials used in additive manufacturing to create customized medical devices and implants tailored to individual patient needs. The rising incidence of osteoarthritis and similar musculoskeletal disorders significantly contributes to the growth of the 3D printed medical devices market. Osteoarthritis leads to joint cartilage deterioration, causing pain and functional limitations. 3D printing allows for the precise replication of a patient's joint structure, offering surgeons vital insights that traditional imaging may not reveal. As the population ages, the prevalence of osteoarthritis is expected to rise, driving demand for these innovative medical solutions.
In addition, the increasing occurrence of cardiovascular diseases is another factor propelling the market forward. These conditions encompass a range of heart and vascular issues that necessitate personalized treatment approaches. Furthermore, 3D printed medical devices facilitate the creation of patient-specific cardiac models derived from advanced imaging techniques, enhancing treatment planning and outcomes.
Moreover, the growing burden of cardiovascular diseases underscores the need for tailored medical interventions, fueling the adoption of 3D printing technologies in healthcare. As both osteoarthritis and cardiovascular diseases become more prevalent, the market for medical 3D printing plastics is poised for significant expansion, driven by advancements in technology and a focus on personalized medicine.
Market Dynamics
The medical 3D printing plastics market is emerging as a critical segment of the advanced healthcare materials industry, driven by the growing demand for customized medical devices, implants, and patient-specific treatment solutions. The rising prevalence of osteoarthritis and cardiovascular diseases is accelerating the adoption of 3D printing technologies, enabling the development of precise anatomical models and personalized medical components that improve treatment planning and clinical outcomes. Additionally, continuous advancements in additive manufacturing, imaging integration, and material innovation are enhancing production accuracy and efficiency. The increasing focus on personalized medicine and improved patient care is further creating significant growth opportunities for the market globally.
The medical 3D printing plastics market is experiencing strong growth, driven by increasing adoption in dental laboratories and clinics. Dental professionals are prioritizing advanced biocompatible materials that enable faster production of customized dental devices with high dimensional accuracy. Medical 3D printing plastics are widely used to manufacture temporary crowns, clear aligners, orthodontic models, surgical guides, and casting patterns. These materials support precise treatment planning while reducing production time and laboratory costs. As demand for aesthetic dentistry and personalized dental care rises, adoption of 3D-printable dental plastics continues to accelerate across clinical and laboratory settings.
Demand is further supported by the growing shift toward digital dentistry workflows and chairside manufacturing solutions. Medical 3D printing plastics are increasingly used alongside intraoral scanning and computer-aided design technologies to improve patient outcomes and operational efficiency. Advancements in resin formulations are enhancing biocompatibility, mechanical strength, and printing accuracy, broadening their suitability for a wider range of dental applications. As dental providers seek scalable, cost-effective, and patient-specific treatment solutions, medical 3D printing plastics are emerging as a critical material platform, strengthening their role in next-generation dental manufacturing and market growth.
High material costs continue to constrain growth in the medical 3D printing plastics market. Medical-grade polymers and biocompatible materials require rigorous testing, validation, and regulatory compliance, which increases production costs. In addition, advanced 3D printers, controlled manufacturing environments, post-processing, sterilization, and quality assurance systems require significant investment. These costs can limit adoption among smaller healthcare providers and research organizations, making cost reduction, process efficiency, and material innovation essential for broader market adoption.
The growing adoption of patient-specific orthopedic and dental devices is creating significant opportunities for the medical 3D printing plastics market. Healthcare providers increasingly use advanced medical-grade polymers to manufacture custom braces, casts, joint implants, clear aligners, crowns, and orthotic insoles tailored to individual patient anatomy. Integrating CT and MRI imaging with 3D printing technologies enables precise production of personalized implants and surgical components, improving clinical outcomes and patient comfort. In addition, the expansion of point-of-care manufacturing within hospitals is reducing lead times and treatment costs. Rising demand for customized healthcare solutions, combined with advancements in medical imaging, material performance, and additive manufacturing workflows, is further supporting long-term market growth.
Analyst Perspective
The market for medical 3D printing plastics is experiencing significant growth, fueled by the increasing shift towards personalized healthcare solutions, precision implants, and quick prototyping of medical devices. This growth is strongly backed by advancements in additive manufacturing technologies such as stereolithography and selective laser sintering, which allow for the utilization of high-performance biocompatible polymers like photopolymers, PEEK, polyamide, and PLA for intricate anatomical designs. The rising prevalence of chronic diseases, heightened demand for customized surgical instruments, and broadening applications in orthopedics, dentistry, and prosthetics are further bolstering adoption. Moreover, the incorporation of 3D printing into surgical planning and regenerative medicine is improving clinical results, while continuous material innovations are enhancing the mechanical strength, sterilization resistance, and biocompatibility of printed parts, collectively positioning the market for ongoing high-growth potential.
Type Insights
Based on type, the photopolymer segment led the market with the largest revenue share of 47.2% in 2025. This growth is attributed to the advancements in technology that enhance the precision and quality of printed medical devices. In addition, photopolymers are increasingly favored for their ability to produce intricate designs and patient-specific solutions, particularly in applications such as dental and orthopedic devices. Furthermore, the rising demand for customized implants and surgical tools further propels the adoption of photopolymers within the healthcare sector.
The polyether ether ketone (PEEK) is expected to grow at a CAGR of 25.2% over the forecast period, owing to its exceptional mechanical properties and biocompatibility, making it ideal for high-performance medical applications. In addition, PEEK is increasingly utilized in creating durable implants and surgical instruments due to its resistance to heat and chemicals. Furthermore, the growing emphasis on personalized medicine also drives demand for PEEK, as healthcare providers seek advanced materials that can be tailored to individual patient needs, thereby enhancing treatment outcomes and overall patient safety.
Form Insights
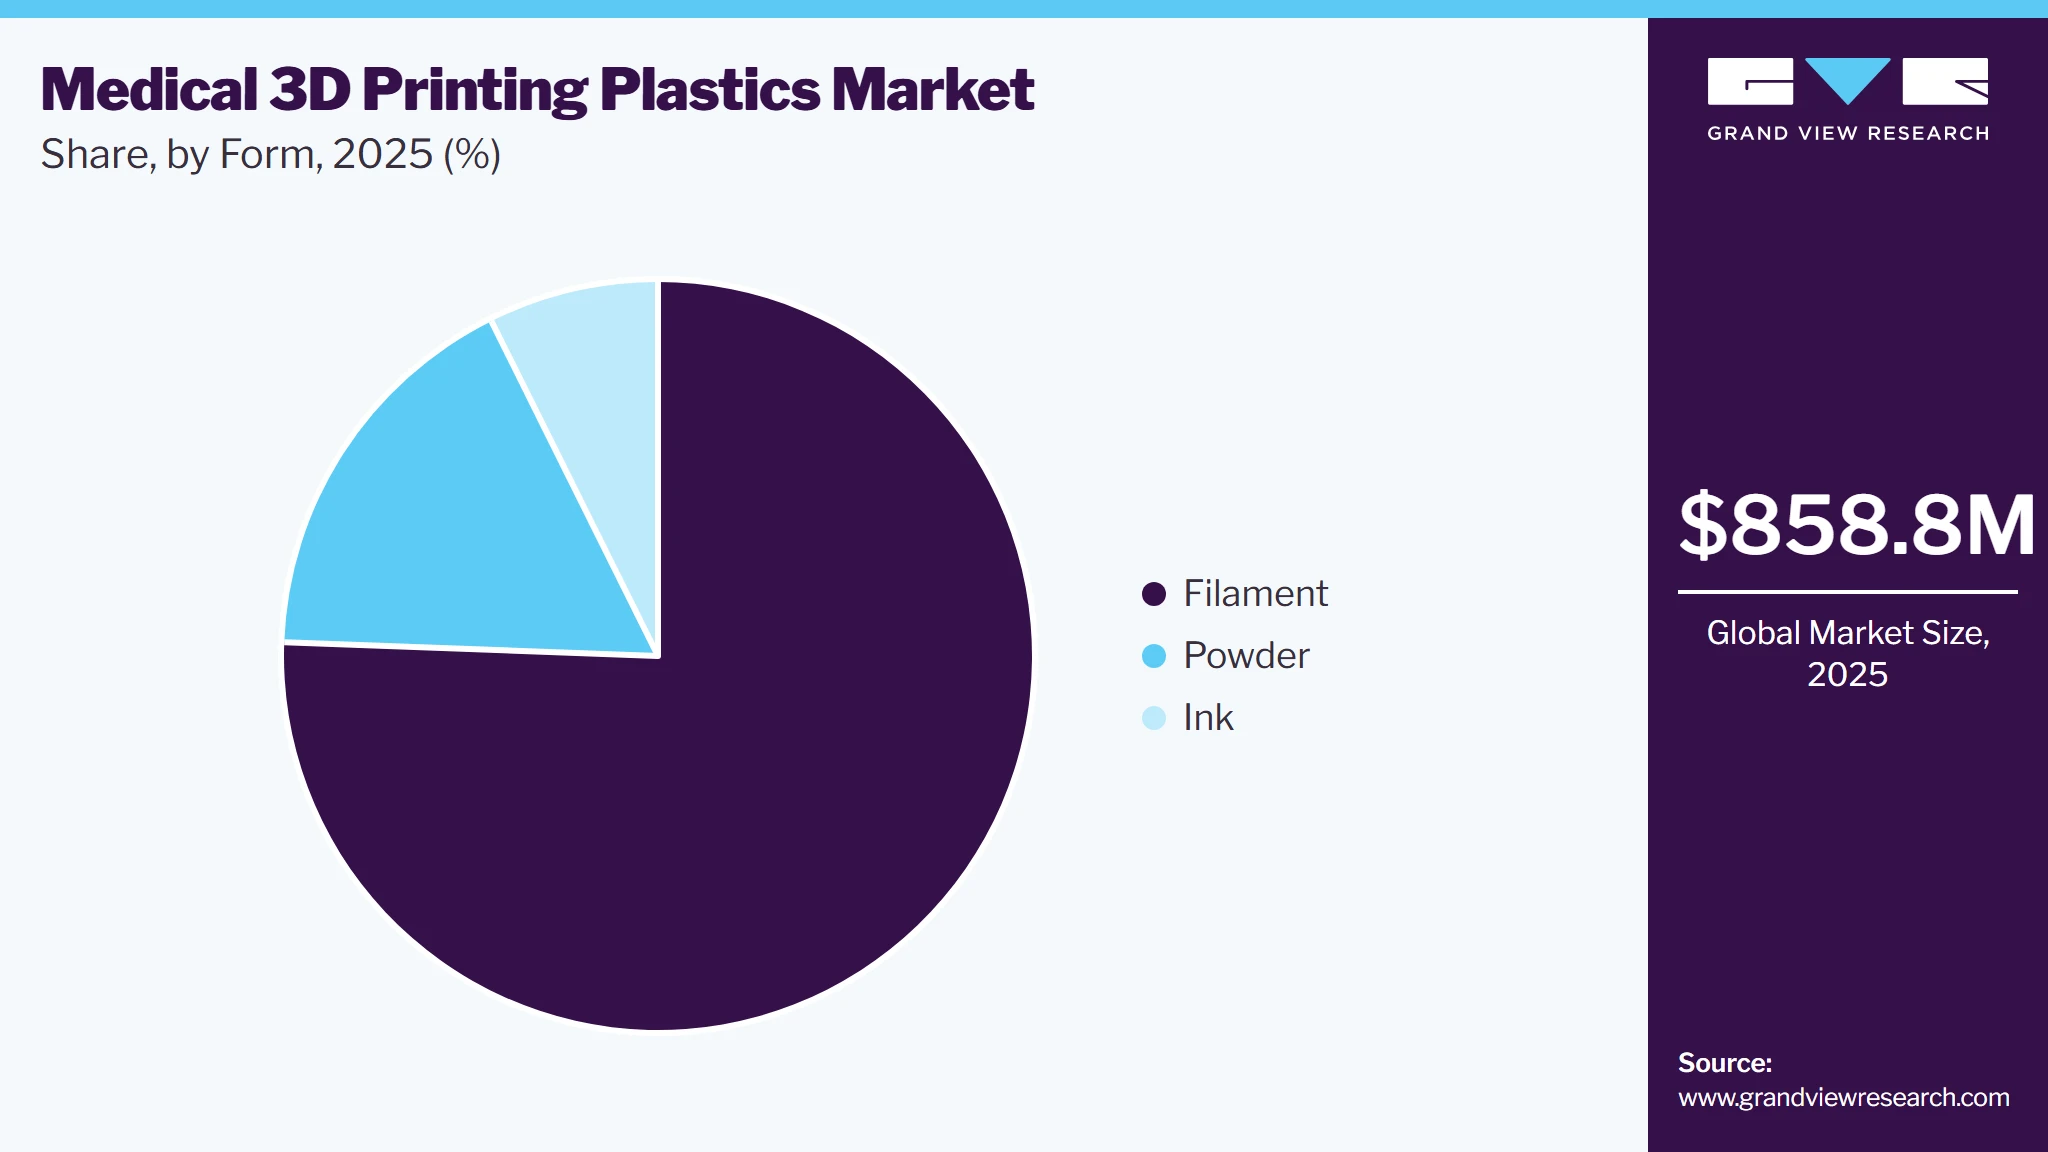
Based on form, the filament segment led the market with the largest revenue share of 75.6% in 2025, primarily driven by the increasing demand for customized medical devices and implants. In addition, filaments offer versatility and ease of use, enabling healthcare providers to produce patient-specific solutions efficiently. Furthermore, the advancements in material formulations also enhance the mechanical properties and biocompatibility of filaments, making them suitable for various applications, including surgical guides and prosthetics, thus significantly contributing to their rising adoption in the medical field.
 To learn more about this report, Download Free Sample Report
The powder segment is expected to grow at a CAGR of 23.9% from 2026 to 2033, owing to its ability to facilitate the production of complex geometries and high-resolution parts. Powder-based 3D printing technologies, such as selective laser sintering, allow for precise control over material properties and density, which are crucial for medical applications. Furthermore, the increasing focus on personalized medicine and the need for advanced manufacturing techniques further propel the demand for powders in creating tailored medical devices and implants, enhancing patient outcomes and operational efficiency in healthcare settings.
Regional Insights
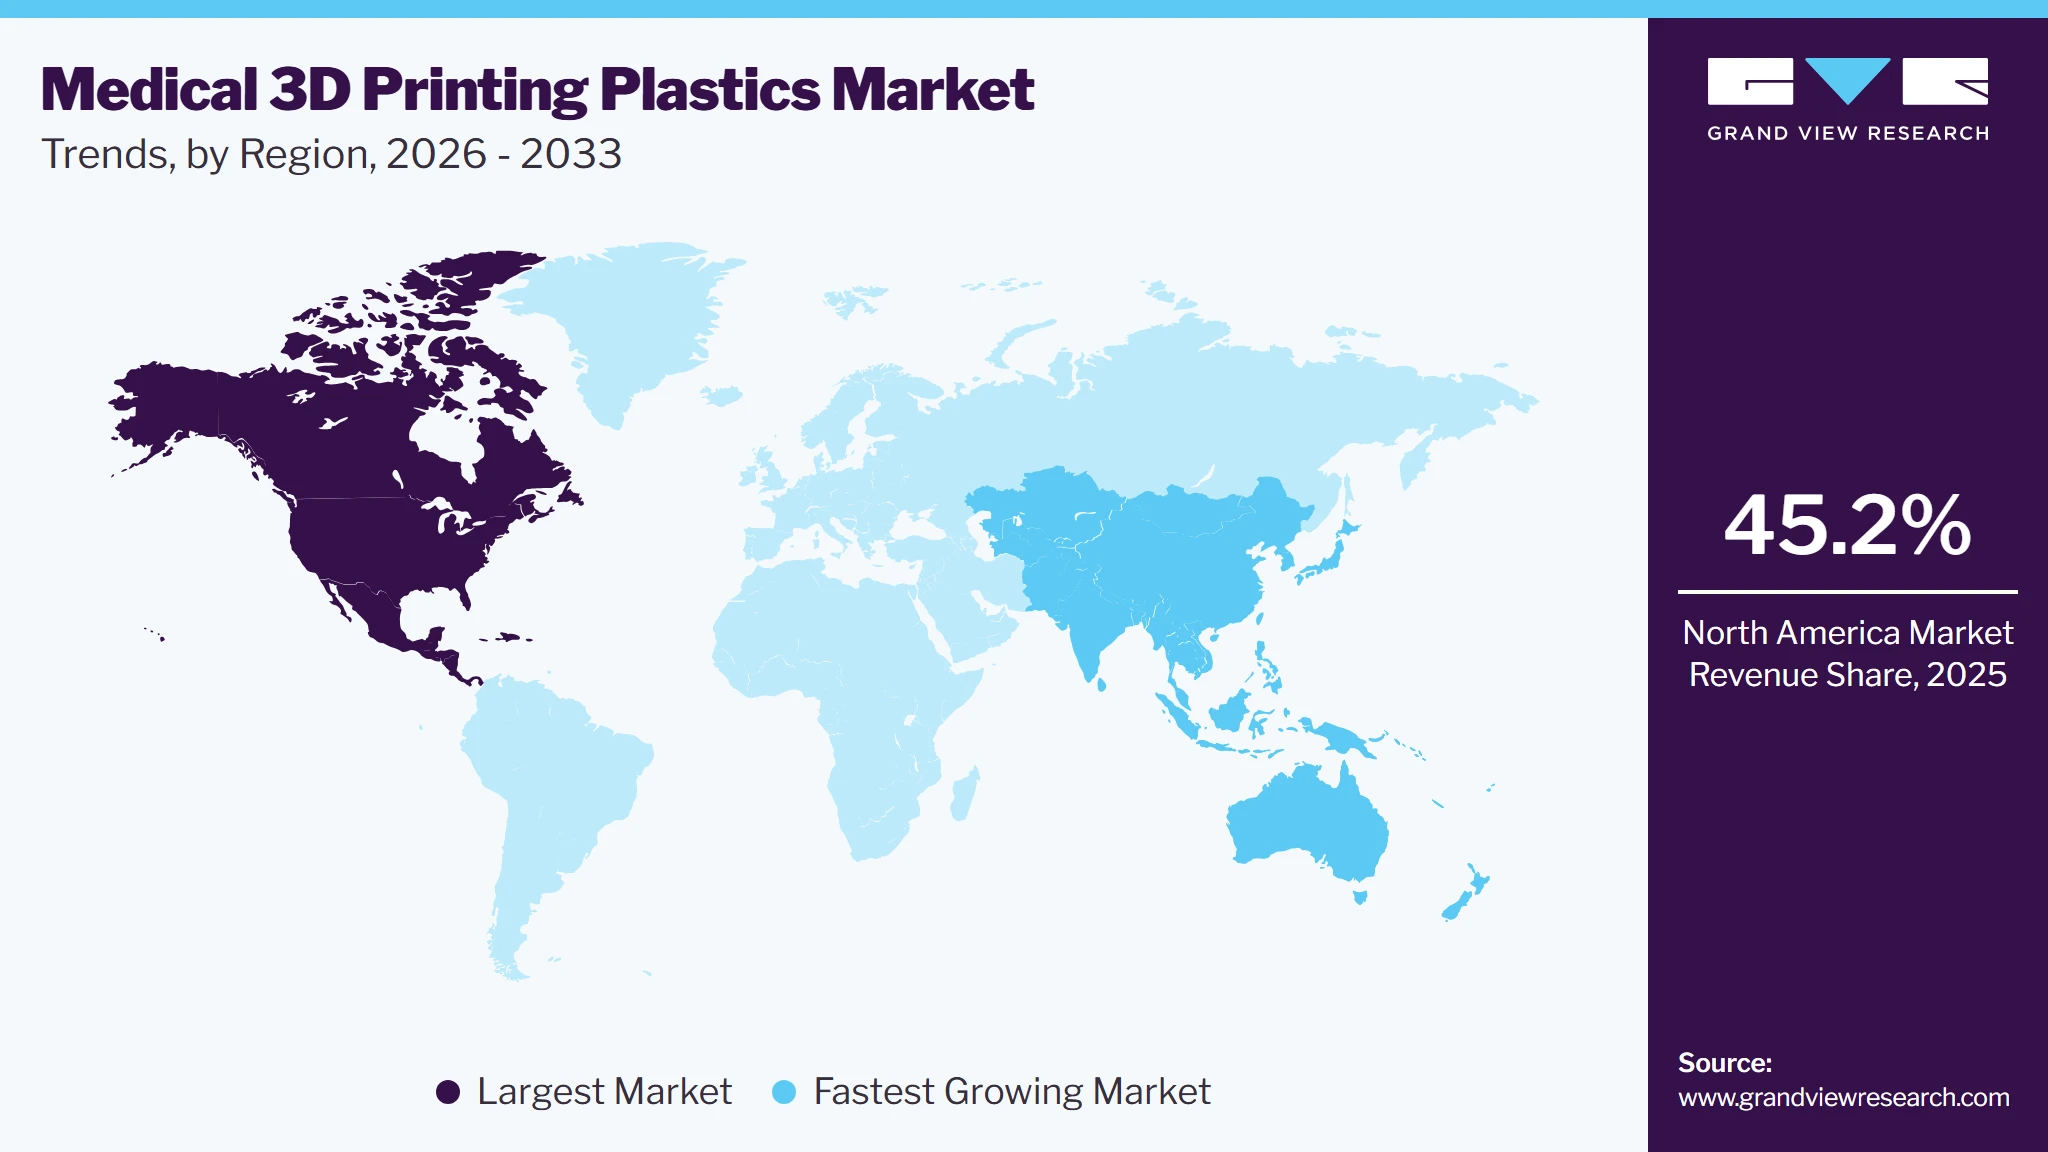
North America dominated the medical 3D printing plastics market with the largest revenue share of 45.2% in 2025. This growth is attributed to increasing healthcare spending and a rising demand for personalized medical solutions. In addition, the region's advanced healthcare infrastructure supports the adoption of innovative technologies, particularly in response to the COVID-19 pandemic, which heightened the need for rapid production of medical devices. Furthermore, a strong focus on research and development, coupled with the presence of key industry players, further propels market expansion in North America.
 To learn more about this report, Download Free Sample Report
U.S. Medical 3D Printing Plastics Market Trends
The medical 3D printing plastics market in U.S. accounted for the largest market revenue share in North America region in 2025, primarily driven by the aging population and the prevalence of chronic diseases. The demand for customized implants and surgical tools is rising, as healthcare providers seek solutions that improve patient outcomes. The U.S. also benefits from robust technological advancements and a well-established manufacturing base, enabling rapid prototyping and efficient production processes. These factors collectively enhance the growth prospects of the medical 3D printing plastics market in the country.
Asia Pacific Medical 3D Printing Plastics Market Trends
The Asia Pacific medical 3D printing plastics market is expected to grow at the highest CAGR of 25.3% over the forecast period, owing to rapid urbanization and increasing healthcare expenditures are key drivers of growth in the. In addition, countries such as India and China are witnessing a surge in demand for advanced medical devices due to rising awareness about personalized healthcare solutions. Furthermore, government initiatives promoting 3D printing technology in healthcare are fostering innovation and adoption across the region, contributing to market expansion.
The medical 3D printing plastics market in China held the significant revenue share and dominated the Asia Pacific market in 2025, driven by its large population and increasing prevalence of chronic diseases. In addition, the country's investments in healthcare infrastructure and advancements in 3D printing technologies are facilitating the production of patient-specific medical devices. Furthermore, collaborations between research institutions and industry players are driving innovation, enhancing China's position in the global medical 3D printing landscape.
Europe Medical 3D Printing Plastics Market Trends
Europe medical 3D printing plastics market is expected to grow substantially over the forecast period, due to factors such as stringent regulations on medical devices and a growing emphasis on personalized medicine are driving market growth. Furthermore, the region's commitment to innovation in healthcare technology is evident through substantial investments in research and development. Moreover, increasing collaboration among academic institutions and industry stakeholders is fostering advancements in medical 3D printing plastics, enhancing their applications across various healthcare sectors.
Germany medical 3D printing plastics market growth is expected to be driven by a strong manufacturing sector and a focus on high-quality healthcare solutions. The country's robust regulatory framework ensures safety and efficacy in medical devices, driving demand for advanced materials. Additionally, Germany's emphasis on sustainability and environmentally friendly practices encourages the development of innovative 3D printing materials, further contributing to market growth within the region.
Key Medical 3D Printing Plastics Company Insights
Key companies in the medical 3D printing plastics industry include 3D Systems, Inc., Arkema, DSM, and others. These players are adopting various strategies to enhance their competitive edge. Strategic partnerships are being formed to leverage complementary strengths, enabling collaborative innovation and resource sharing. In addition, new product development is prioritized to meet evolving market demands, focusing on advanced materials and technologies. Furthermore, mergers and acquisitions are pursued to expand market presence and diversify product offerings.
-
ENVISIONTEC, INC develops and manufactures advanced 3D printing technologies and materials, particularly in the medical sector. The company focuses on producing high-resolution 3D printers and biocompatible materials tailored for medical applications, including dental, orthopedic, and surgical devices. Operating primarily in the healthcare segment, the company emphasizes innovation in additive manufacturing to enhance patient care through customized solutions that improve clinical outcomes and streamline production processes in medical device manufacturing.
-
Stratasys Ltd. offers a wide range of medical-grade 3D printers and materials designed for various healthcare applications. The company operates in the medical segment, focusing on creating patient-specific models, surgical aids, and prototypes that facilitate improved surgical planning and education. Stratasys delivers comprehensive solutions that enhance the efficiency and effectiveness of medical manufacturing processes while supporting personalized healthcare initiatives.
Key Medical 3D printing plastics Companies:
The following key companies have been profiled for this study on the medical 3D printing plastics market.
-
3D Systems, Inc.
-
Apium Additive Technologies GmbH
-
Arkema
-
DSM
-
ENVISIONTEC, INC.
-
Evonik Industries AG
-
Proclaim Health
-
SABIC
-
Solvay
-
Stratasys Ltd.
-
Victrex plc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (3D Systems, Inc.; Arkema; DSM; EnvisionTEC, Inc.; Evonik Industries AG; SABIC; Solvay; Stratasys Ltd.; Victrex plc.)
- Broad portfolios of medical 3D printing materials and additive manufacturing solutions serving orthopedic implants, dental devices, surgical guides, anatomical models, prosthetics, orthotics, cranio-maxillofacial implants, and patient-specific medical applications. Strong focus on the development of biocompatible photopolymers, PEEK, polyamide, and advanced medical-grade thermoplastics compatible with multiple 3D printing technologies. Continuous investments in material innovation, regulatory certifications, application development, healthcare collaborations, and point-of-care manufacturing solutions support expansion across hospitals, dental laboratories, research institutions, and medical device manufacturers. Strategic partnerships with healthcare providers, academic centers, and medical technology companies further strengthen commercialization opportunities and market penetration.
- Extensive expertise in additive manufacturing technologies, biomaterial science, regulatory compliance, and medical device applications enables the development of high-performance medical printing materials with superior biocompatibility, mechanical properties, and processing reliability. Established global distribution networks and long-standing relationships with healthcare organizations, dental laboratories, and medical device manufacturers support recurring demand and long-term business growth. Strong research and development capabilities, intellectual property portfolios, clinical validation experience, and integrated hardware-material ecosystems provide significant competitive differentiation while accelerating adoption of personalized healthcare solutions.
- Dependence on specialized medical-grade polymers, advanced resin chemistries, and high-performance thermoplastics exposes manufacturers to elevated raw material costs and supply chain complexities. Significant investments are required for research and development, clinical validation, regulatory approvals, quality assurance systems, and production infrastructure, increasing operational expenditures. The market is also influenced by stringent healthcare regulations, lengthy product qualification cycles, reimbursement uncertainties, and increasing competition from emerging material developers and regional additive manufacturing suppliers, which may impact profitability and commercialization timelines across certain medical applications.
Established Players (Apium Additive Technologies GmbH; Proclaim Health)
- Focus on strengthening their position in medical 3D printing plastics through advanced additive manufacturing solutions for patient-specific implants, surgical guides, anatomical models, orthopedic devices, dental applications, and healthcare research. Emphasis is placed on developing high-performance medical-grade polymers, particularly biocompatible and implantable materials, while enhancing printing precision, process validation, and regulatory compliance. Strategic collaborations with hospitals, medical device manufacturers, research institutions, and healthcare providers support technology adoption and commercialization. Continuous investments in high-temperature printing systems, material innovation, clinical workflow integration, and quality assurance capabilities further reinforce market leadership in advanced healthcare applications.
- Strong expertise in medical additive manufacturing, regulatory-compliant production processes, and high-performance polymer technologies supports participation in complex and high-value healthcare applications. Competitive advantage is enhanced through specialized knowledge of medical-grade materials, patient-specific manufacturing, and integration of advanced imaging with additive manufacturing workflows. Established relationships with healthcare providers, research organizations, and medical device companies support product validation and market acceptance. Their ability to deliver customized solutions with high accuracy, biocompatibility, and clinical reliability further strengthens competitiveness in the rapidly evolving personalized medicine market.
- Exposure to stringent regulatory requirements, lengthy product qualification cycles, and evolving medical device standards can increase operational complexity and commercialization timelines. Dependence on premium medical-grade polymers such as PEEK and specialized photopolymers may result in higher production costs and margin pressures. Compared with large multinational healthcare technology companies, limited scale and geographic reach may restrict access to broader healthcare networks and large procurement contracts. In addition, high capital requirements for advanced printing systems, ongoing research and development investments, and reimbursement uncertainties may create challenges for sustained growth and profitability.
Recent Developments
-
In June 2024, Arkema showcased its commitment to sustainability and industry partnerships for 3D printing at the RAPID+TCT 2024 event in Los Angeles. The company highlighted innovative materials, including medical 3D printing plastics, designed for various applications, from dental to industrial uses. Arkema's focus on bio-based materials and enhanced recyclability aligns with its sustainability goals, aiming to improve the performance and environmental impact of 3D-printed products, thereby supporting advancements in healthcare and manufacturing sectors.
-
In January 2024, Proclaim launched its innovative Custom-Jet Oral Health System, designed to eliminate harmful bacteria in the mouth in just seven seconds. This groundbreaking system features a custom 3D-printed mouthpiece with patented water jets that clean effectively between teeth and gum lines. Clinically proven to significantly reduce gum disease indicators, this system underscores the importance of oral health in preventing systemic diseases.
Medical 3D Printing Plastics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 858.8 million
Estimated market size in 2026
USD 1,086.8 million
Projected market size by 2033
USD 4,983.8 million
Growth rate
CAGR of 24.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, form, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S., Canada, Mexico, China, India, Japan, Germany, UK, France, Italy, Brazil, Argentina, Saudi Arabia, and UAE
Key companies profiled
3D Systems, Inc.; Apium Additive Technologies GmbH; Arkema; DSM; ENVISIONTEC, INC.; Proclaim Health; Evonik Industries AG; SABIC; Solvay; Stratasys Ltd.; Victrex plc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical 3D Printing Plastics Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and analyzes the latest industry trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global medical 3d printing plastics market report based on type, form, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
ABS
-
PEEK
-
PETG
-
Photopolymer
-
Polyamide
-
Polylactic Acid
-
-
Form Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Filament
-
Powder
-
Ink
-
-
Regional Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The medical 3d printing plastics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical 3d printing plastics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
ABS (Acrylonitrile Butadiene Styrene)
Revenue is captured through the production and sale of ABS-based medical 3D printing plastics utilized in surgical planning models, anatomical visualization tools, medical equipment prototypes, and educational applications. Demand is driven by its durability, impact resistance, ease of processing, and cost-effectiveness, enabling healthcare providers and manufacturers to produce accurate and functional medical models while supporting rapid product development and clinical training activities.
PEEK (Polyether Ether Ketone)
Revenue is captured through the commercialization of PEEK-based medical 3D printing materials used in orthopedic implants, spinal cages, cranial implants, trauma fixation devices, and other long-term implantable applications. Growth is supported by its exceptional mechanical strength, biocompatibility, radiolucency, and resistance to sterilization processes, making it a preferred material for high-performance medical devices requiring long-term clinical reliability.
PETG (Polyethylene Terephthalate Glycol)
Revenue is captured through the supply of PETG medical 3D printing plastics utilized in surgical guides, dental models, diagnostic devices, protective medical equipment, and healthcare prototypes. Demand is driven by its transparency, chemical resistance, dimensional stability, and ease of printing, enabling manufacturers to produce precise medical components while maintaining cost efficiency and operational flexibility.
Photopolymer
Revenue is captured through the production and sale of photopolymer resins used in dental aligners, temporary crowns, surgical guides, hearing aids, anatomical models, and patient-specific medical devices. Growth is supported by superior printing accuracy, smooth surface finish, high resolution capabilities, and compatibility with stereolithography and digital light processing technologies, enabling the manufacture of highly detailed medical components.
Polyamide
Revenue is captured through the commercialization of polyamide-based medical 3D printing materials utilized in prosthetics, orthotics, surgical instruments, medical device housings, and customized healthcare products. Demand is driven by its excellent mechanical performance, flexibility, wear resistance, and suitability for complex geometries, supporting the growing adoption of personalized medical devices and functional healthcare components.
Polylactic Acid (PLA)
Revenue is captured through the utilization of PLA medical 3D printing plastics in anatomical models, surgical planning tools, educational applications, disposable medical components, and rapid prototyping activities. Growth is supported by its ease of printing, biodegradability, low processing temperature, and cost-effectiveness, making it widely adopted for non-implantable healthcare applications and clinical training environments.
Segment - Form
Revenue capture definition
Filament
Revenue is captured through the sale of filament-based medical 3D printing plastics used in fused deposition modeling systems for manufacturing anatomical models, surgical guides, prosthetics, orthotics, and customized medical components. Demand is driven by the widespread adoption of desktop and industrial 3D printers, cost-effective production capabilities, material versatility, and growing utilization of point-of-care manufacturing within hospitals and healthcare facilities.
Powder
Revenue is captured through the commercialization of powder-based medical 3D printing materials utilized in selective laser sintering and other powder bed fusion technologies for producing orthopedic implants, prosthetic devices, surgical instruments, and patient-specific medical components. Growth is supported by the ability to manufacture complex geometries, superior mechanical properties, high dimensional accuracy, and efficient production of customized healthcare solutions.
Ink
Revenue is captured through the production and supply of ink and resin-based medical 3D printing materials used in stereolithography, digital light processing, material jetting, and bioprinting applications. Demand is driven by increasing requirements for high-resolution printing, detailed anatomical models, dental restorations, surgical planning tools, and patient-specific medical devices that require exceptional precision, surface quality, and biocompatibility.
Estimation Model
Layer Name
Key Question
Description
Top-Down Medical 3D Printing Plastics Demand Scan Layer
What defines market boundaries?
This layer begins with global demand for medical 3D printing plastics used in the production of patient-specific implants, surgical guides, anatomical models, prosthetics, orthotics, dental devices, and medical equipment components. Demand is filtered based on healthcare expenditure, adoption of additive manufacturing technologies, surgical procedure volumes, prevalence of chronic diseases, dental treatment demand, and investments in personalized medicine and advanced healthcare infrastructure.
End-Use Application Validation Layer
Where is demand generated?
This layer evaluates demand distribution across orthopedic implants, dental devices, prosthetics and orthotics, surgical planning models, cardiovascular applications, cranio-maxillofacial implants, and customized medical equipment components. Market revenue is aligned with key performance requirements such as biocompatibility, sterilization resistance, dimensional accuracy, mechanical strength, patient-specific customization, regulatory compliance, and compatibility with various medical 3D printing technologies.
Product & Material Conversion Layer
Who captures market revenue?
This layer converts application-level consumption into medical 3D printing plastics revenue by applying material mix ratios across PEEK, photopolymers, polyamide, PETG, ABS, PLA, and other specialized medical-grade polymers. The analysis incorporates material certifications, biocompatibility standards, printing technology compatibility, mechanical performance requirements, manufacturing efficiencies, post-processing requirements, and supplier pricing structures throughout the healthcare value chain.
Regional Commercial Cross-Check Layer
How are assumptions validated?
This layer validates demand concentration by comparing North America's advanced healthcare infrastructure and strong adoption of patient-specific medical devices, Europe’s focus on regulated medical manufacturing and personalized healthcare solutions, and Asia Pacific’s expanding healthcare investments, dental care services, and medical technology adoption. It also evaluates emerging opportunities in Central & South America and the Middle East, driven by healthcare modernization initiatives, increasing surgical volumes, improving access to advanced medical technologies, and growing investments in additive manufacturing capabilities.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Regional Segmentation
Detailed market sizing, growth analysis, demand assessment, and forecast breakdown for North America, Europe, Asia Pacific, Central & South America, and Middle East & Africa. Country-level analysis can be provided for key markets including the U.S., Germany, U.K., France, Italy, China, Japan, South Korea, India, Brazil, Mexico, Saudi Arabia, and UAE.
Enables identification of high-growth healthcare markets, regional investment priorities, regulatory environments, healthcare infrastructure maturity, and adoption trends for medical 3D printing plastics across developed and emerging economies.
Cross-Segmentation
Comprehensive cross-analysis of Type (ABS, PEEK, PETG, Photopolymer, Polyamide, PLA) by Form (Filament, Powder, Ink), and Region.
Helps identify the highest-value market pockets, emerging application-material combinations, technology adoption patterns, and revenue concentration areas for targeted business expansion and product development strategies.
Opportunity Assessment
Identification of emerging growth opportunities across patient-specific implants, orthopedic and spinal devices, dental aligners and crowns, maxillofacial reconstruction, biocompatible materials, point-of-care manufacturing, and hospital-based 3D printing facilities. Includes analysis of technology adoption trends and unmet clinical needs.
Enables prioritization of high-growth investment areas, new product development initiatives, market entry strategies, strategic partnerships, and long-term revenue generation opportunities aligned with evolving healthcare and personalized medicine trends.
Frequently Asked Questions About This Report
Some key players operating in the medical 3D printing plastics market include 3D Systems, Inc.; Apium Additive Technologies GmbH; Arkema; DSM; ENVISIONTEC, INC.; Evonik Industries AG; SABIC; Solvay; Stratasys Ltd; and Victrex plc.
Key factors that are driving the market growth include rising demand of medical 3D printing plastics in the manufacturing of various products such as mask, face covers, surgical gloves, and protective gowns.
The North America medical 3D printing plastics market accounted for the largest share of 45.2% market size in 2025.
The Asia Pacific was the leading medical 3D printing plastics market and is expected to grow at a compound annual growth rate of 25.3%.
Based on form, the filament segment accounted for the largest share of 75.6% market size in 2025. Growing demand for customized, cost-effective, and rapidly manufactured medical devices is driving the adoption of filament-based medical 3D printing plastics.
The PEEK segment based on type is expected to grow at a CAGR of 25.2% for the forecast period.
The global medical 3d printing plastics market size was valued at USD 858.8 million in 2025 and is estimated at USD 1,086.8 million for 2026.
The global medical 3d printing plastics market is expected to grow at a CAGR of 24.3% from 2026 to 2033, reaching USD 4,983.8 million by 2033.
The photopolymer led the medical 3D printing plastics market in 2025 with a 47.2% share. Growing demand for highly precise, patient-specific, and clinically validated medical devices across dental, orthopedic, surgical planning, hearing aid, and healthcare prototyping applications is driving the adoption of photopolymer-based medical 3D printing plastics.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


