
- Home
- »
- Catalysts & Enzymes
- »
-
Metal Carboxylates Market Size & Share Report, 2026-2033GVR Report cover

Metal Carboxylates Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Primary Drier Metals, Through Drier Metals, Auxiliary Drier Metals), By End-use (Catalyst, Lubricant Additives, Plastic Stabilizers), By Region, And Segment Forecasts
Market Size, 2025
$6.0BMarket Estimate, 2026
$6.3BMarket Forecast, 2033
$9.1BCAGR, 2026–2033
5.4%Metal Carboxylates Market Summary
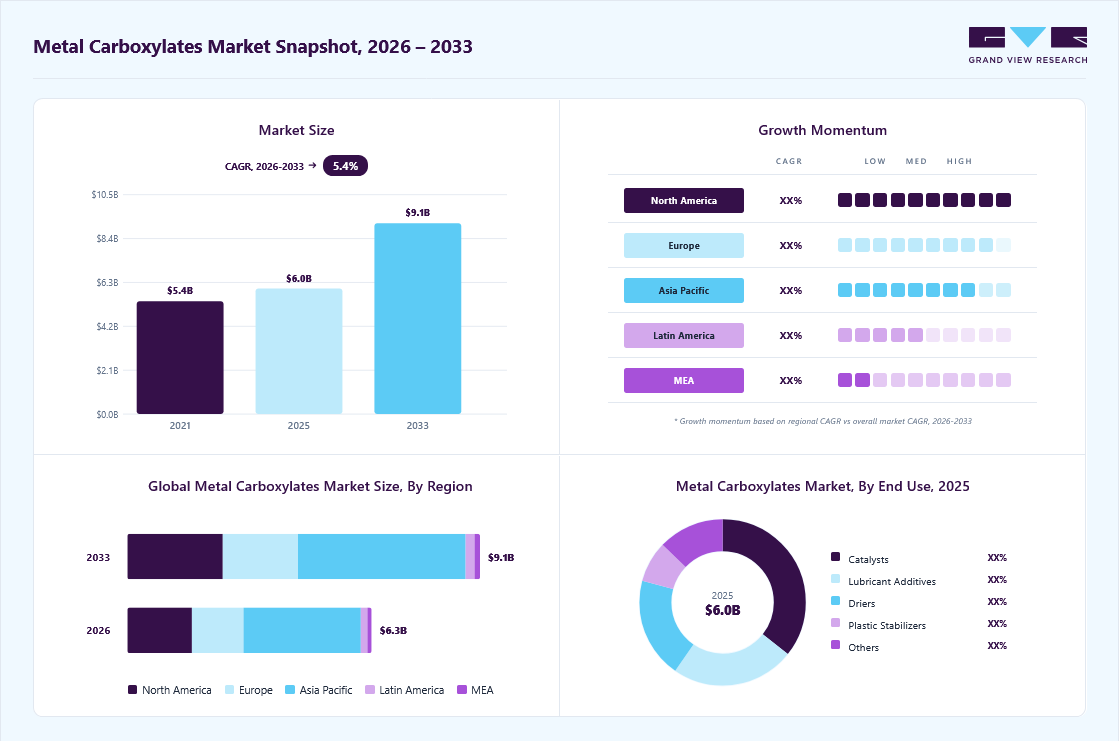
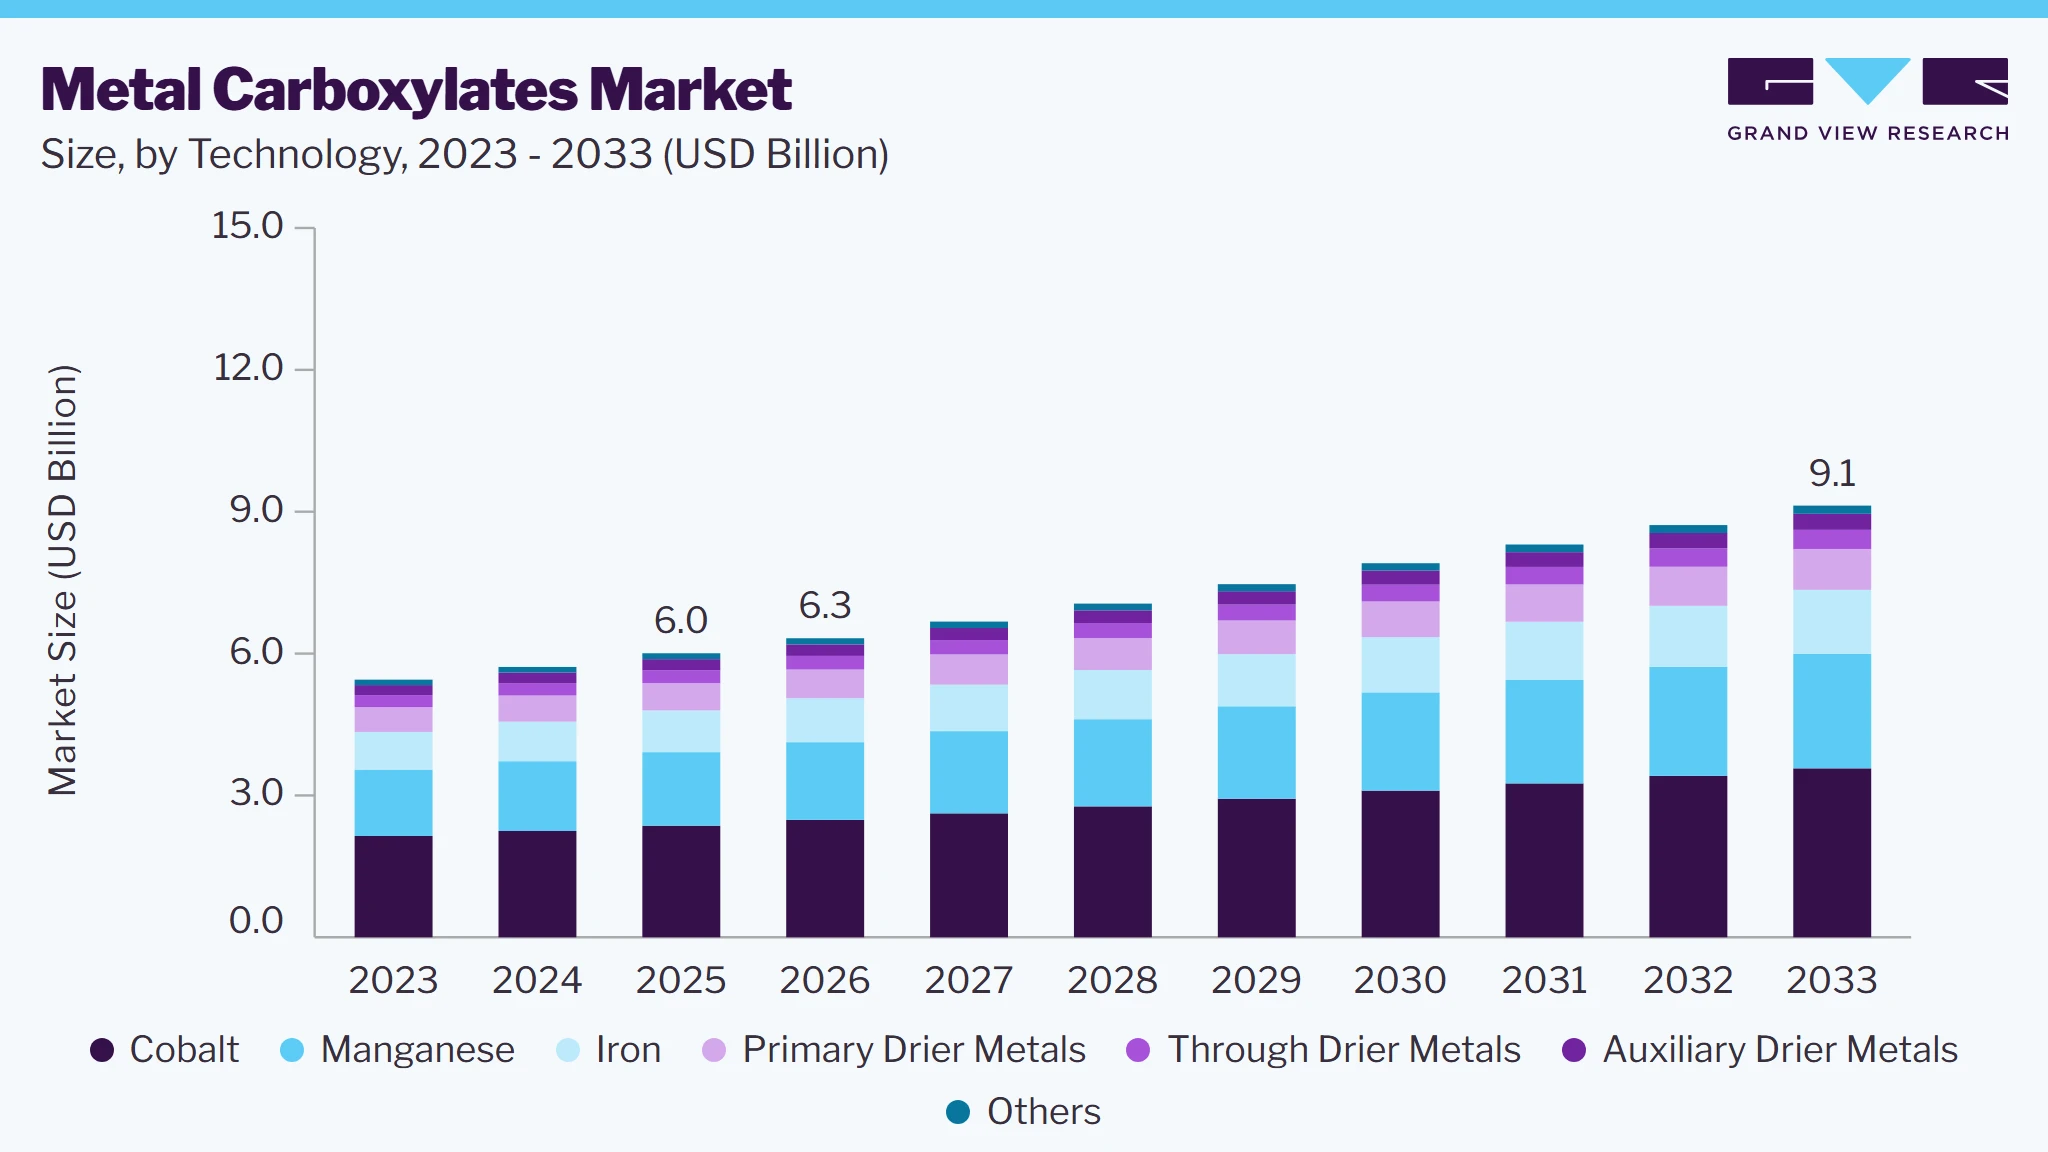
The global metal carboxylates market size was valued at USD 6.0 billion in 2025 and is projected to grow from USD 6.3 billion in 2026 to USD 9.1 billion by 2033, at a CAGR of 5.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 48.1% in 2025. Metal carboxylates have significant applications in the building and construction industry, where they protect structures from external damage.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Cobalt segment accounted for the largest share of the metal carboxylates market, representing 39.3% of total revenue in 2025.
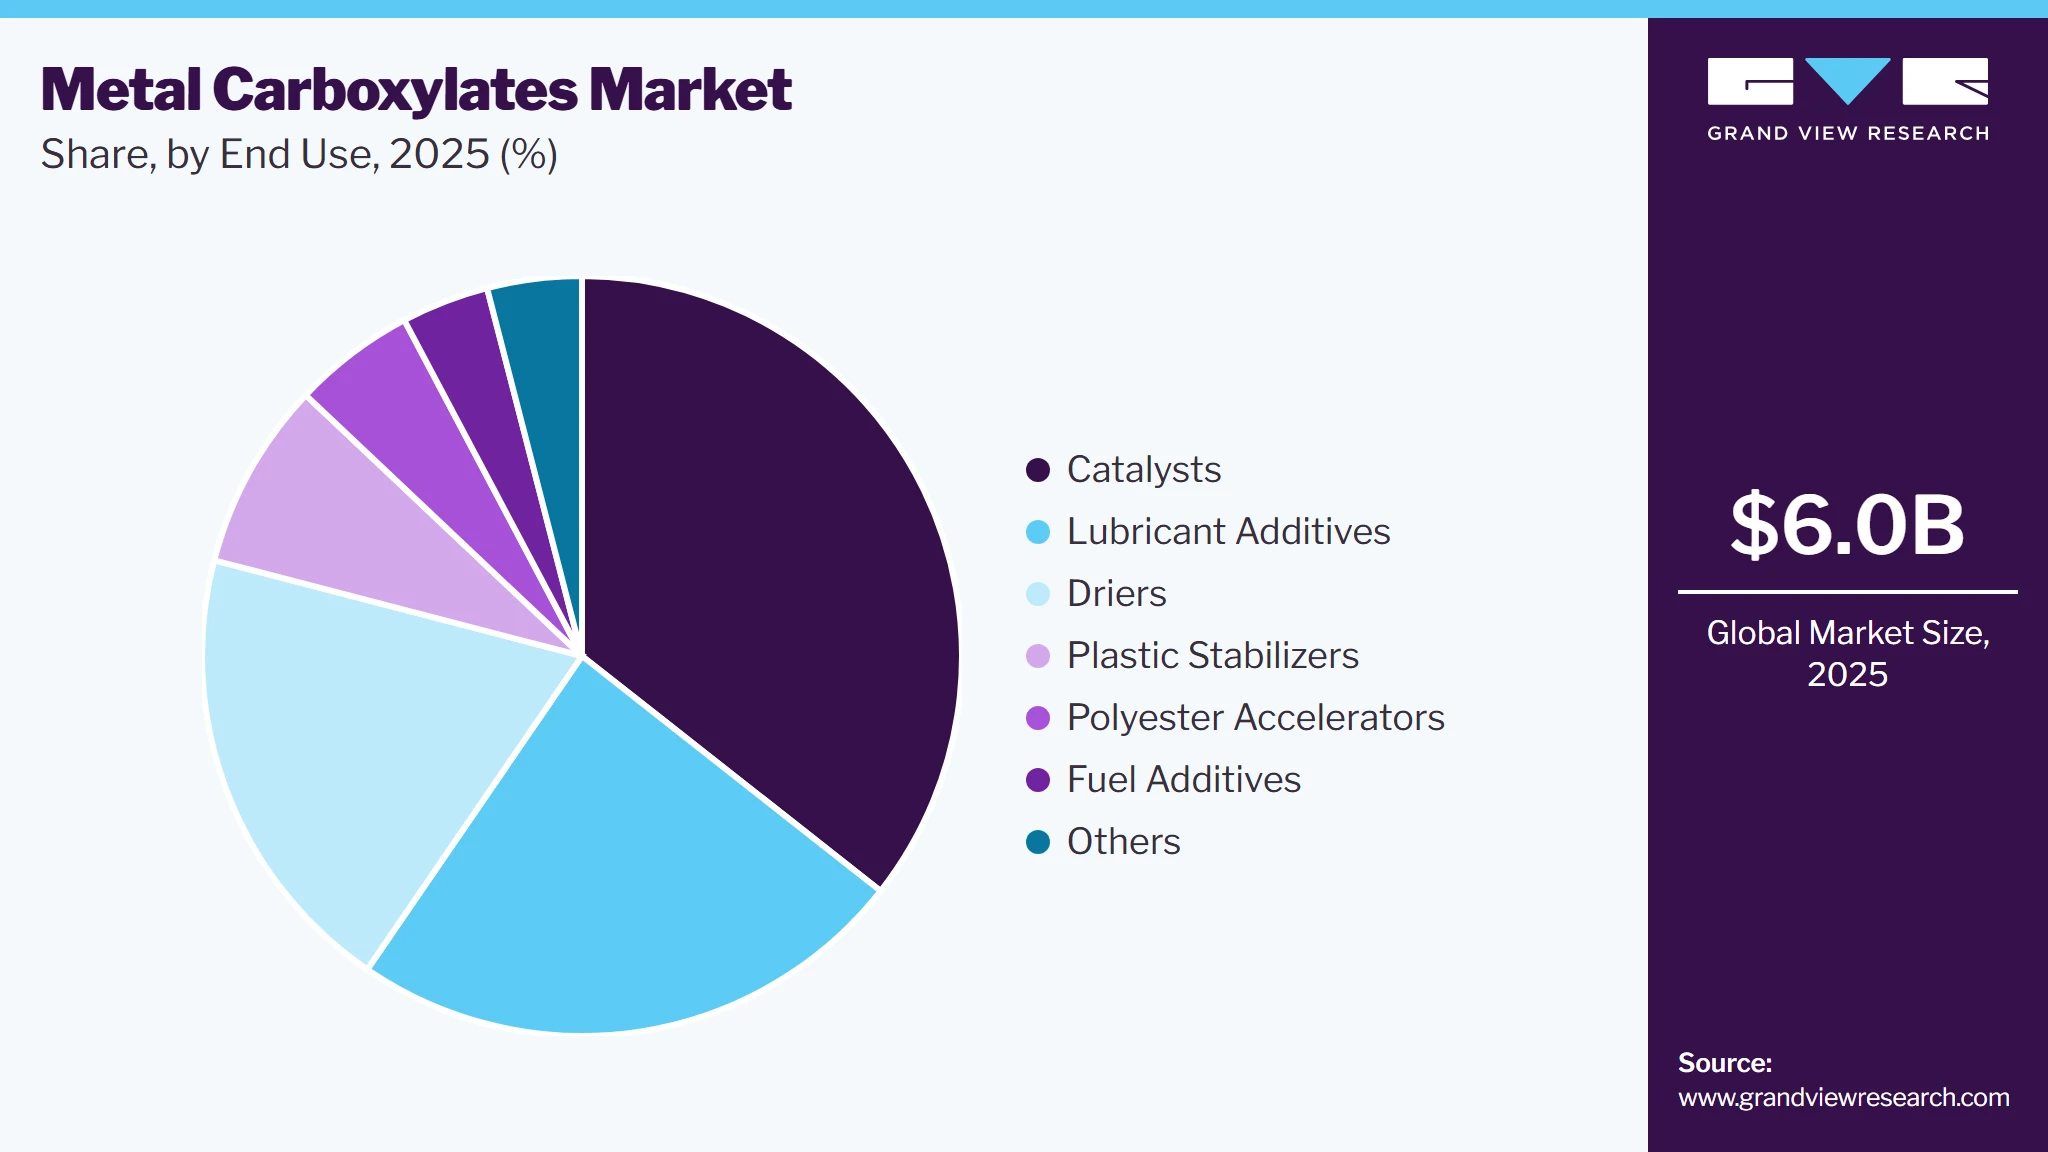
- By end use: Catalysts segment accounted for the largest revenue share of 35.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (48.1% revenue share, 2025)
- Fastest-growing regional market: (highest CAGR, 2026-2033)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.0 Billion
- Estimated market size in 2026: USD 6.3 Billion
- Projected market size by 2033: USD 9.1 Billion
- CAGR (2026-2033): 5.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The demand for industrial coatings is experiencing the most substantial growth in China and India, with moderate growth in Europe. This surge in coating demand, in turn, enhances the need for metal carboxylates. Additionally, additives improve performance and address deficiencies in fuels or lubricants used across various applications. Manganese and iron metal carboxylates are commonly utilized as fuel additives.
 To learn more about this report, Download Free Sample Report
Metal carboxylates are essential for various industrial processes, including producing plastics, coatings, lubricants, and catalysts. The rising demand for high-performance materials in sectors such as construction, automotive, and aerospace have significantly increased the need for these substances. Metal carboxylates offer distinctive advantages, such as improved performance in manufacturing processes, high-temperature resistance, and exceptional stability.
A significant market segment is utilizing metal carboxylates as catalysts in various processes. These compounds, particularly those based on zinc, copper, and cobalt, enhance the speed of chemical reactions, increasing their application in catalytic processes. One notable trend in this field is the growing use of metal carboxylates in Ozone Catalytic Oxidation Solutions, driving advancements in green chemistry. These catalysts support the industry's demand for economic and energy-efficient solutions due to their effectiveness at lower temperatures and reusability.
Market Dynamics
The metal carboxylates market is growing due to rising demand for coatings, catalysts, polymer additives, and specialty chemicals across industrial applications. Increasing consumption of paints, adhesives, and plastic products requires efficient additives that improve durability, drying performance, and processing efficiency. The expansion of automotive, construction, and manufacturing sectors increases the need for high performance materials. Growing research into advanced chemical formulations is encouraging the development of improved metal carboxylate solutions. Manufacturers are focusing on sustainable and efficient production methods to meet changing regulatory and industrial requirements.
The increasing use of metal carboxylates in paints and coatings is creating strong demand across various industries. These compounds act as effective drying agents and catalysts that enhance curing speed, surface quality, and durability of coating materials. Automotive, construction, and industrial equipment manufacturers rely on high performance coatings to improve protection against corrosion, weathering, and chemical exposure. As these industries expand, the requirement for efficient coating additives continues to increase.
Metal carboxylates help manufacturers achieve better product performance while reducing processing time and improving production efficiency. The growing preference for advanced protective coatings in infrastructure projects, vehicles, and machinery is encouraging wider adoption of these chemical additives. This demand trend is expected to support market growth as industries continue seeking reliable solutions for improved coating performance and longer product lifespan.
Environmental regulations related to the use of specific metal-based chemicals can restrict the growth of the metal carboxylates market. Some metal carboxylates containing heavy metals may face limitations due to concerns regarding toxicity, disposal issues, and environmental impact. Regulatory authorities are implementing stricter guidelines for chemical manufacturing and industrial applications, requiring companies to modify formulations or develop safer alternatives. These compliance requirements can increase production costs and create difficulties for manufacturers dependent on restricted metal compounds. The need for regulatory approvals and continuous reformulation efforts may slow adoption in certain applications where environmental standards are becoming more stringent.
The development of environmentally safer metal carboxylate formulations presents growth opportunities for manufacturers in this market. Industries are increasingly seeking chemical additives that provide high performance while meeting sustainability requirements. Manufacturers can focus on producing low toxicity and eco friendly metal carboxylates using alternative metal sources and improved production processes. Demand for sustainable coatings, advanced polymers, and efficient catalysts creates opportunities to introduce innovative solutions with better environmental profiles. Companies investing in research and product development can expand their application areas and address changing customer preferences. The shift toward greener chemical products allow manufacturers to strengthen their market position while supporting industries that require safer and more efficient additive technologies.
Technology Insights
The cobalt segment accounted for the largest share of the metal carboxylates market, representing 39.3% of total revenue in 2025 and is expected to continue to dominate the industry over the forecast period. The cobalt technology segment in the metal carboxylates market is driven by its critical role as a drier in coatings, inks, and paints, enhancing oxidative curing and film formation. Cobalt-based carboxylates are widely used in alkyd resins for improved drying efficiency and durability. Growing demand for high-performance coatings in the automotive and construction industries is a key driver for this segment. However, increasing regulatory pressure on cobalt use is pushing manufacturers toward sustainable and low-toxicity alternatives.
The manganese technology segment in the metal carboxylates market is gaining traction due to its effectiveness as an eco-friendly alternative to cobalt-based driers in paints, coatings, and inks. Manganese carboxylates offer excellent oxidative curing properties while meeting stringent environmental regulations. The primary driver for this segment is the growing demand for sustainable and low-toxicity solutions in the coatings industry, particularly in Europe and North America.
End-use Insights
The catalysts segment accounted for the largest revenue share of 35.6% in 2025. The catalyst segment in the metal carboxylates market is driven by its critical role in polymerization, oxidation, and other chemical synthesis processes across various industries. Metal carboxylates, such as those based on cobalt, manganese, and zinc, enhance reaction efficiency and selectivity in industrial applications. The increasing demand for high-performance catalysts in petrochemicals, coatings, and pharmaceuticals is a key driver for this segment. Additionally, the push for sustainable and energy-efficient catalytic processes is further fueling market growth.
 To learn more about this report, Download Free Sample Report
The lubricant additives segment in the metal carboxylates market is driven by the growing need for high-performance lubricants in automotive, industrial, and machinery applications. Metal carboxylates, such as calcium and barium-based compounds, enhance lubrication, reduce wear, and improve thermal stability. Rising industrial automation and stringent regulations on fuel efficiency and emissions are key drivers to boost demand. Additionally, advancements in lubricant formulations for electric vehicles and heavy-duty machinery further support market growth.
Regional Insights
North America metal carboxylates market is experiencing growth due to the rise in construction activity, increasing automotive production, and demand for products in the metal carboxylates market.
U.S. Metal Carboxylates Market Trends
The metal carboxylates market in the U.S. is expected to grow during the forecast period. This growth is attributed to the increasing automobile production, general industry, construction, and oil & gas industries this is expected to positively impact the metal carboxylates market.
Asia Pacific Metal Carboxylates Market Trends
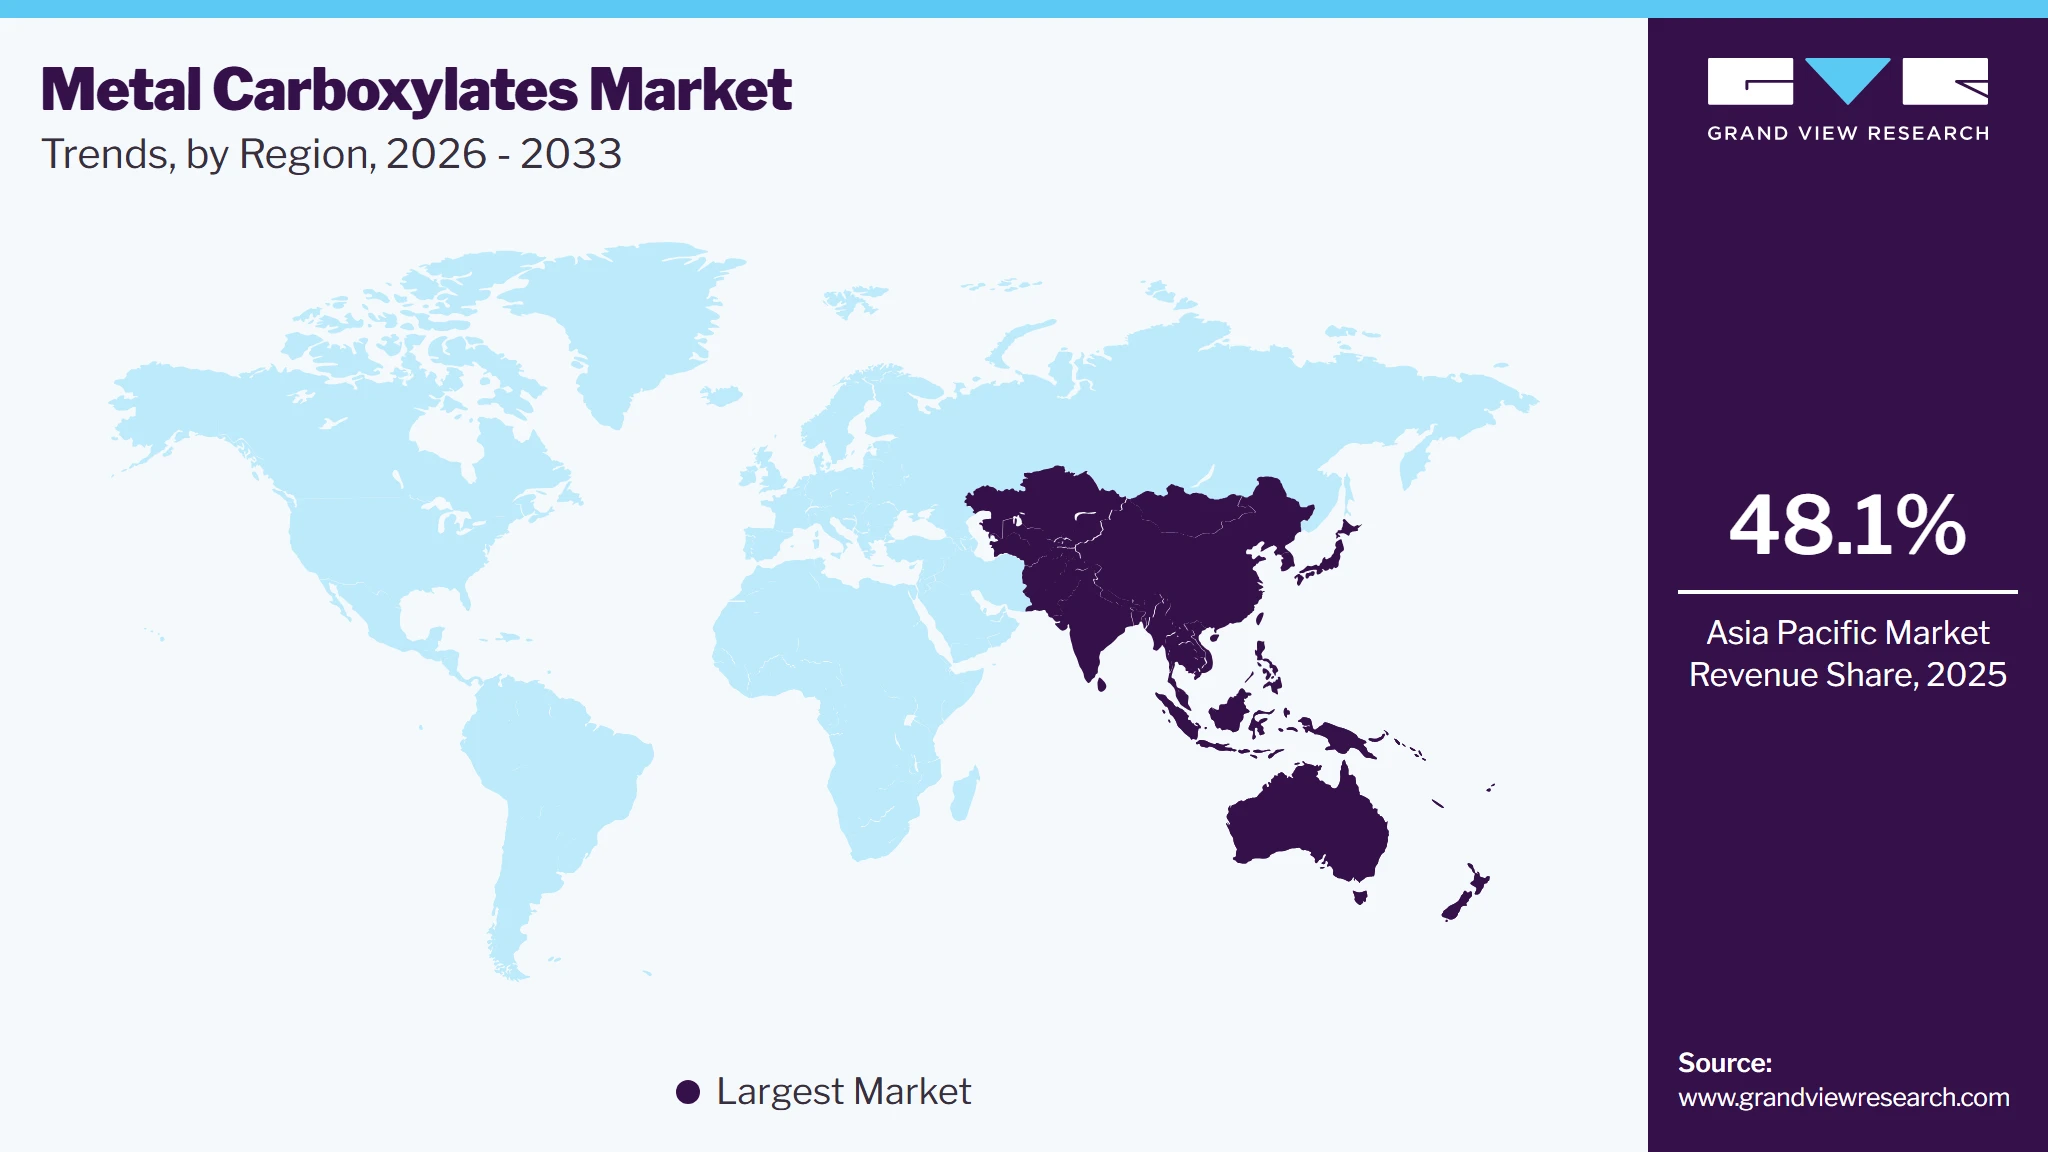
Asia Pacific accounted for 48.1% of the metal carboxylates market revenue in 2025, making it the largest regional market. The metal carboxylates market in Asia-Pacific region dominates the metal carboxylates market due to rapid industrialization, growing automotive production, and expanding construction activities. The rising demand for high-performance coatings, lubricants, and polymer stabilizers is a key driver fueling market growth. Additionally, increasing investments in manufacturing and infrastructure development further supports the region’s strong market expansion.
 To learn more about this report, Download Free Sample Report
China maintained a leading position in the Asia Pacific metal carboxylates market. China metal carboxylates market is expected to grow during the forecast period. This growth is attributed to the increasing manufacturing activity in the region and has led to increased demand for products in the region.
Europe Metal Carboxylates Market Trends
The metal carboxylates market inEurope is expected to grow over the forecast period. This growth can be attributed to the increasing product demand from various end-use industries such as the general industry, power generation, aerospace, and automotive and vehicle refinishing. The regional market is also expected to grow due to the increasing automobile production, construction activity, and the growing aerospace sector.
Latin America Metal Carboxylates Market Trends
The metal carboxylates market inLatin America is expected to witness steady growth over the forecast period. The rising product demand from the general, automotive, aerospace, and marine industries is anticipated to positively influence market growth in the region. Furthermore, the presence of automotive production plants and oil & gas-producing countries in the region, including Brazil, Colombia, and Venezuela, is projected to fuel the demand for metal carboxylates over the forecast period.
Middle East & Africa Metal Carboxylates Market Trends
The metal carboxylates market in the Middle East and Africa is expected to witness steady growth over the forecast period due to increasing oil production in the region. The region is the global leader in terms of oil production. The presence of major oil-producing countries such as Saudi Arabia, Kuwait, Oman, Bahrain, Libya, Iraq, Angola, and Iran in the Middle East & Africa is expected to create high demand for metal carboxylates in the region
Key Metal Carboxylates Company Insights
Some of the key players operating in the market include BASF SE and Arkema Group
-
BASF SE is a globally recognized German chemical company and the largest chemical producer in the world. The company operates through six primary business segments: industrial solutions, chemicals, materials, surface technologies, agricultural solutions, and nutrition and care. Its diverse portfolio encompasses various chemical products, such as performance, plastics, and functional solutions. One of the company’s key areas of expertise is the production of carotenoids, including beta-carotene and related products, which are utilized in the food and beverages, pharmaceuticals, and animal feed industries.
-
Arkema manufactures specialty chemicals and advanced materials. It operates through three segments: high-performance materials, coating solutions, and industrial specialties. The company sells its products to end-use industries, including construction, electrical and electronics, food and agrochemicals, health, hygiene, beauty, oil and gas, paper and packaging, renewable energies, sports, and transportation. The company has 151 production plants in 55 countries.
Key Metal Carboxylates Companies
The following key companies have been profiled for this study on the metal carboxylates market.
-
BASF SE
-
Dow
-
Elementis plc
-
Organometals
-
Arkema Group
-
PMC Group, Inc.
-
Valtris Specialty Chemicals
-
Penta Manufacturing Company
-
DIC Corporation
-
Ege Kimya San. ve Tic. A.S
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF SE, Elementis plc, Arkema Group, Dow, PMC Group, Inc., Valtris Specialty Chemicals)
- Focus on broad specialty chemical portfolios, advanced metal carboxylate formulations, and long-term relationships with coatings, plastics, and industrial manufacturers.
- Invest in research capabilities, sustainable chemical solutions, and global expansion strategies to strengthen market presence across diverse applications.
- Strong technical expertise, established customer networks, and extensive distribution capabilities support market penetration across major industrial sectors.
- Diversified product offerings enable customized solutions for coatings, catalysts, lubricants, and polymer applications.
• Large-scale operations may reduce flexibility in responding quickly to niche application requirements and regional customer demands.
- Compliance with evolving environmental regulations can increase formulation costs and require continuous investment in product development.
Emerging Players (Ege Kimya San. ve Tic. A.S, Organometals, Penta Manufacturing Company, DIC Corporation)
- Focus on specialized metal carboxylate solutions, customized formulations, and targeted applications across coatings, catalysts, and industrial chemical markets.
- Expand through regional partnerships, application focused innovation, and customer specific product development strategies.
- Greater flexibility allows faster adaptation to specific formulation needs and customer requirements.
- Specialized expertise in metal-based chemicals enables focused solutions for selected industrial applications and regional markets.
- Limited global distribution networks and smaller operational scale can restrict expansion compared with multinational chemical suppliers.
- Lower investment capabilities in research and sustainable product development may affect competitiveness in evolving chemical markets.
Recent Developments
-
In October 2023, Arkema announced a significant capacity expansion at its Nansha site in China. The expansion will aim to increase the production capacity for high-performance materials, specifically for high-temperature-resistant polymers and advanced coatings. This move also aimed to meet the growing demand for coatings in various sectors, including automotive, electronics, and renewable energy. The company planned to invest in new facilities and upgrade the existing ones to enhance production efficiency and support its strategic growth objectives in the Asian market. The expansion aligns with Arkema’s broader strategy to strengthen its global presence and cater to the regional market needs.
-
In September 2022, Eastman acquired Taminco, a leading producer of alkylamines and metal carboxylates, for USD 2.8 billion. This acquisition aims to enhance Eastman's position in the specialty chemicals market, particularly in high-performance metal carboxylates for industrial and agricultural applications.
Metal Carboxylates Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.0 billion
Estimated market size in 2026
USD 6.3 billion
Projected market size by 2033
USD 9.1 billion
Growth rate
CAGR of 5.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Brazil; Argentina; Saudi Arabia; South Africa;
Key companies profiled
BASF SE, Ege Kimya San. ve Tic. A.S, Elementis plc, Organometals, Arkema Group, PMC Group, Inc., Valtris Specialty Chemicals, Penta Manufacturing Company, Dow, DIC Corporation.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Metal Carboxylates Market Report Segmentation
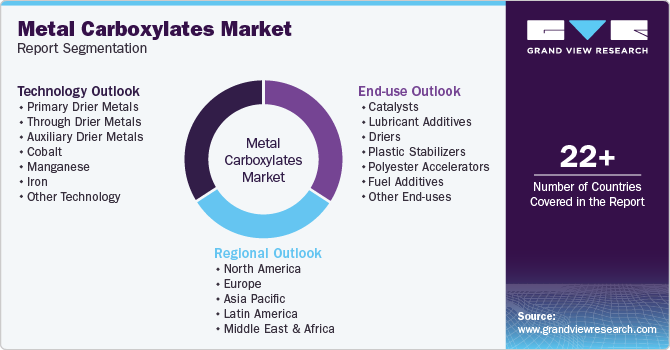
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global metal carboxylates market report on the basis of technology, end-use and region.
 To learn more about this report, Download Free Sample Report
-
Technology Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Primary Drier Metals
-
Through Drier Metals
-
Auxiliary Drier Metals
-
Cobalt
-
Manganese
-
Iron
-
Other Technology
-
-
End-use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Catalysts
-
Lubricant Additives
-
Driers
-
Plastic Stabilizers
-
Polyester Accelerators
-
Fuel Additives
-
Other End Uses
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The metal carboxylates Market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each metal carboxylates Market segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Technology
Revenue Capture Definition
Primary Drier Metals
Revenue is captured through the sale of metal carboxylates containing primary drier metals that initiate oxidation and accelerate drying in coating formulations. Manufacturers generate income from recurring demand by paint, ink, and coating producers requiring improved curing efficiency, faster drying rates, and enhanced surface performance.
Through Drier Metals
Revenue is generated through the supply of metal carboxylates that enable uniform drying across coating layers. Chemical manufacturers capture value by providing solutions used in industrial coatings and specialty formulations where complete curing, improved film properties, and consistent coating quality are required.
Auxiliary Drier Metals
Revenue is captured through sales of supporting metal carboxylate additives that enhance the effectiveness of primary and through driers. Manufacturers generate revenue from coating producers using these compounds to optimize drying balance, improve formulation stability, and achieve better performance in finished coating products.
Cobalt
Revenue is generated through cobalt-based metal carboxylate sales used primarily as high efficiency driers in paints, coatings, and printing inks. Manufacturers capture value from demand for faster curing solutions that improve coating productivity, surface finish, and durability across automotive, industrial, and decorative applications.
Manganese
Revenue is captured through the supply of manganese-based metal carboxylates used as drying agents, catalysts, and performance additives. Manufacturers generate income by serving industries seeking effective alternatives for coating formulations and chemical processes requiring improved reaction efficiency and reduced dependence on cobalt-based additives.
Iron
Revenue is generated through iron-based metal carboxylate solutions used in catalysts, coatings, and specialty chemical applications. Manufacturers capture value by supplying cost effective additives that support oxidation processes, improve formulation performance, and meet specific requirements across industrial manufacturing sectors.
Other Technology
Revenue is captured through other metal carboxylate technologies, including zinc, calcium, zirconium, and other metal-based compounds. Manufacturers generate income by supplying specialized formulations for coatings, plastics, catalysts, and industrial applications requiring customized performance characteristics and functional improvements.
Segment - End use
Revenue Capture Definition
Catalysts
Revenue is generated through the sale of metal carboxylates used as catalysts in chemical reactions and manufacturing processes. Manufacturers capture value by supplying additives that improve reaction efficiency, support polymer production, and enhance performance in specialty chemical applications.
Lubricant Additives
Revenue is captured through the supply of metal carboxylates used as lubricant additives to improve stability, wear protection, and operating performance. Chemical manufacturers generate income from demand across automotive, industrial machinery, and manufacturing sectors requiring enhanced lubrication solutions.
Driers
Revenue is generated through metal carboxylate sales used as drying agents in paints, coatings, varnishes, and inks. Manufacturers capture value from recurring purchases by coating producers requiring faster curing, improved finish quality, and enhanced durability in finished products.
Plastic Stabilizers
Revenue is captured through the sale of metal carboxylates used as stabilizing additives in polymer processing. Manufacturers generate revenue by supplying solutions that improve thermal stability, processing efficiency, and durability of plastic materials used in industrial and consumer applications.
Polyester Accelerators
Revenue is generated through the supply of metal carboxylates used to accelerate polyester resin curing processes. Manufacturers capture value from demand by composite and resin producers seeking improved processing speed, productivity, and performance characteristics in polyester-based materials.
Fuel Additives
Revenue is captured through the sale of metal carboxylates used in fuel additive formulations to improve combustion performance and operational efficiency. Manufacturers generate income by supplying specialized chemical solutions for fuel processing and related industrial applications.
Other End Uses
Revenue is generated through specialized metal carboxylate applications in adhesives, sealants, coatings, and specialty chemical formulations. Manufacturers capture value by providing customized additives that improve product performance, stability, and processing efficiency across niche industrial applications.
Estimation Model
Layer Name
Key Question
Content
Industrial Application Base Layer
What forms the demand base?
Identify the global demand base across industries using metal carboxylates, including paints and coatings, plastics, lubricants, catalysts, polyester production, fuel additives, and specialty chemical applications. This layer establishes the overall industrial consumption landscape that creates demand for metal carboxylate compounds.
Technology Adoption Layer
Where are metal carboxylates consumed?
Estimate the adoption of different metal carboxylate technologies, including primary drier metals, through drier metals, auxiliary drier metals, and specific metal types such as cobalt, manganese, iron, and other formulations. Demand is assessed based on performance requirements, formulation needs, and application suitability across industrial sectors.
Consumption Intensity Layer
How much metal carboxylate is used?
Analyze consumption rates of metal carboxylates based on application requirements, formulation concentration, production volumes, and performance specifications. Usage intensity varies depending on coating formulations, catalyst efficiency, polymer processing requirements, lubricant performance standards, and the functional properties required in final products.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of metal carboxylate compounds supplied to manufacturers of coatings, plastics, lubricants, catalysts, polyester materials, and fuel additive solutions. Revenue is generated through recurring chemical purchases by industrial users requiring performance-enhancing additives, drying agents, catalysts, and stabilizing solutions across global manufacturing operations.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Customization
Customization Delivered
Value Added
Regional Segmentation
Additional regional analysis covering countries beyond the standard scope, including Vietnam, Indonesia, Egypt, UAE, with assessment of application demand, regulatory environment, and industrial adoption patterns for metal carboxylates.
Provides deeper visibility into emerging regional opportunities and helps identify countries with increasing demand for coatings, specialty chemicals, and industrial additives.
Competitive Benchmarking
Detailed comparison of manufacturers based on product portfolio, application expertise, sustainability initiatives, customer reach, innovation capabilities, and strategic positioning within the metal carboxylates industry.
Enables better understanding of competitor strengths, differentiation strategies, and market positioning to support supplier evaluation and strategic decision making.
Opportunity Assessment
Evaluation of future opportunities arising from sustainable coating additives, low cobalt formulations, advanced catalyst applications, polymer processing solutions, and increasing demand for high performance specialty chemicals.
Helps identify attractive growth areas and supports investment planning by highlighting application segments with strong future potential and evolving customer requirements.
Frequently Asked Questions About This Report
The cobalt segment held the largest market share, accounting for 39.3% of total revenue in 2025, due to high effectiveness as a drying agent in coatings and inks drives widespread industrial adoption.
The catalysts segment accounted for the largest revenue share, representing 35.6% of the market in 2025, due to growing demand for chemical processing catalysts increases consumption across industrial applications.
China accounted for the largest market share in the Asia Pacific region, due to strong coatings, manufacturing, and specialty chemical industries support higher metal carboxylate consumption.
The lubricant additives segment is expected to register the fastest growth during the forecast period, due to increasing demand for high performance lubricants enhances adoption across automotive and industrial sectors.
The global metal carboxylates market size was estimated at USD 6.0 billion in 2025 and is expected to reach USD 6.3 billion in 2026.
The global metal carboxylates market is expected to grow at a compound annual growth rate of 5.4% from 2026 to 2033 to reach USD 9.1 billion by 2033.
Asia Pacific dominated the metal carboxylates market in the food & beverages market with a share of 48.1% in 2025. The Asia Pacific region is dominant in the metal carboxylates market, Rapid industrialization in the region is anticipated to increase the demand for metal carboxylates market.
Some key players operating in the metal carboxylates market include BASF SE, Ege Kimya San. ve Tic. A.S, Elementis plc, BASF SE, Arkema Group, PMC Group, Inc., Valtris Specialty Chemicals, Penta Manufacturing Company, Dow, Ege Kimya San. ve Tic. A.S, Oriental International (Pvt) Ltd., and CarboTech.
This growth is attributed to the expansion of the transportation sector, especially in automotive and aerospace, is fueling market growth. The increasing preference for eco-friendly waterborne metal carboxylates is another reason for the growth of the market
About the Author(s)
Catalysts & Enzymes Research Team
Specialty & Chemicals · Catalysts & EnzymesThis report was authored by the catalysts & enzymes research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the catalysts & enzymes segment of the specialty & chemicals industry. All findings are based on proprietary specialty & chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


