
- Home
- »
- Advanced Interior Materials
- »
-
Metal Forging Market Size, Share & Growth Report, 2033GVR Report cover

Metal Forging Market (2026 - 2033)
Size, Share & Trends Analysis Report By Raw Material (Carbon Steel, Alloy Steel, Aluminum, Magnesium), By Application (Automotive, Transportation, Aerospace, Oil & Gas, Construction), By Region, And Segment Forecasts
Market Size, 2025
$39.4BMarket Estimate, 2026
$43.0BMarket Forecast, 2033
$72.8BCAGR, 2026–2033
7.8%Metal Forging Market Summary
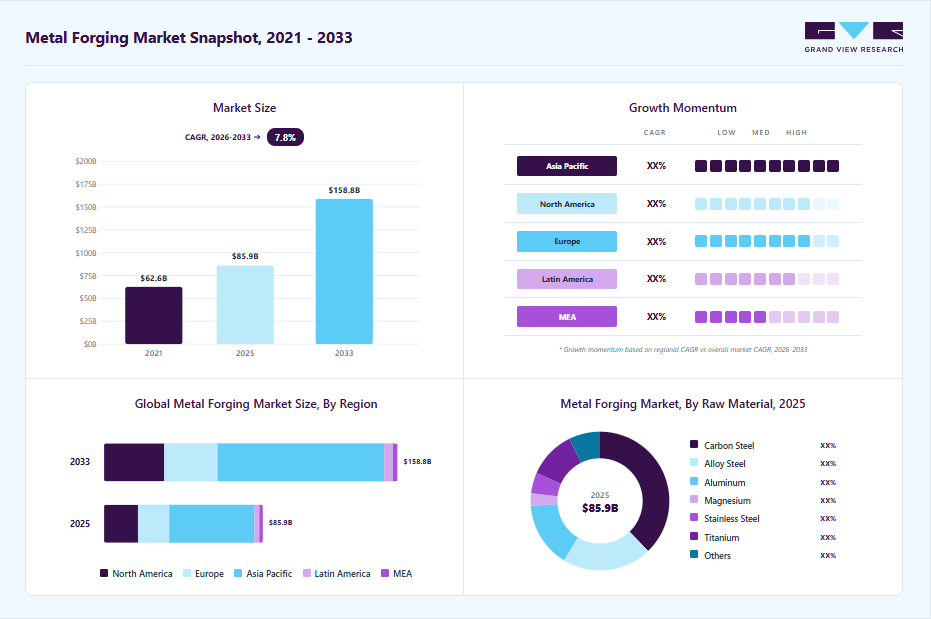
The global metal forging market size was valued at USD 39.4 billion in 2025 and is projected to grow from USD 43.0 billion in 2026 to USD 72.8 billion by 2033, at a CAGR of 7.8% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 53.6% in 2025. The market is expected to witness steady growth, supported by its essential role in producing high-strength and high-reliability components across key end-use industries such as automotive, aerospace, oil and gas, and heavy equipment.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By raw material: Carbon steel accounted for the largest market revenue share of over 37.0% in 2025.
- By application: Power generation segment is anticipated to register the fastest CAGR of 10.1% from 2026 to 2033.
Regional Highlights
- Largest regional market: Asia Pacific (53.6% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 39.4 Billion
- Estimated market size in 2026: USD 43.0 Billion
- Projected market size by 2033: USD 72.8 Billion
- CAGR (2026-2033): 7.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Forging processes enhance mechanical properties, including fatigue resistance, grain structure alignment, and overall durability, making them highly suitable for critical applications where performance and safety are paramount. Growth in industrialization and infrastructure development, particularly in emerging economies, continues to drive demand for forged components in construction equipment, railways, and energy systems. In addition, the increasing focus on product quality and lifecycle performance is reinforcing the adoption of forging over alternative manufacturing methods.
 To learn more about this report, Download Free Sample Report
The evolving automotive sector remains a significant contributor to market demand, particularly with the transition toward electric vehicles. While the shift reduces demand for traditional internal combustion engine components, it creates new opportunities for forged products in structural and safety-related applications such as chassis systems, suspension components, and transmission parts. Furthermore, regulatory pressure related to emissions and fuel efficiency is encouraging the use of lightweight forged materials such as aluminum and magnesium. The aerospace industry also supports market growth through consistent demand for high-performance forged components used in aircraft engines and structural assemblies, where precision and material integrity are critical.
In November 2024, Schilling Forge, a precision forging supplier based in Syracuse, New York, expanded its operational capabilities by installing a new electrically heated Gasbarre car-bottom furnace, increasing its annealing capacity by 67% to better serve high-precision medical applications such as surgical and dental tools. In addition, the integration of simulation tools and data-driven optimization is reducing design cycles and improving production planning. Sustainability initiatives, including energy-efficient equipment and metal recycling practices, are also gaining importance as manufacturers align with environmental regulations and corporate sustainability goals.
Market Dynamics
The expansion of automotive, aerospace, energy, construction, and industrial machinery manufacturing is driving demand for metal forging. Forged components offer high strength, fatigue resistance, and structural reliability, making them suitable for critical applications such as engine components, gears, shafts, axles, landing gear, and industrial machinery parts. Increasing production of vehicles and industrial equipment is supporting market expansion.
The growing emphasis on lightweighting, component durability, and manufacturing efficiency is further supporting the adoption of advanced forging processes. Manufacturers are increasingly using precision forging, closed die forging, and automated forging systems to produce complex components with improved material utilization and reduced machining requirements. Advances in forging technology and high-performance alloys are expanding applications across the transportation, energy, and defense industries.
Metal forging requires substantial investment in forging presses, dies, heating systems, automation, and other specialized equipment. High energy consumption during heating and forming operations can further increase production costs, particularly when electricity and fuel prices are volatile. The requirement for skilled labor and periodic die replacement can add to operating expenses and create challenges for smaller manufacturers.
The expansion of electric vehicles, aerospace programs, renewable energy infrastructure, and advanced industrial equipment is creating opportunities for high-performance forged components. Demand is increasing for lightweight alloys, high-strength steels, titanium, and aluminum forgings that can improve efficiency while maintaining structural performance. Investment in automated forging, near-net shape manufacturing, and advanced materials is expected to further expand the application scope of metal forging.
Analyst Perspective
The market is positioned for strong growth, supported by rising demand for high-strength, durable, and lightweight components across automotive, aerospace, construction, energy, and industrial machinery applications. The transition toward electric vehicles is creating new opportunities for forged chassis, suspension, drivetrain, structural, and other high-performance components, while investments in aerospace and renewable energy are supporting demand for precision forgings. At the same time, high capital requirements for presses, dies, furnaces, automation, and inspection systems, along with energy-intensive production and volatile feedstock prices, remain key challenges for manufacturers.
Raw Material Insights
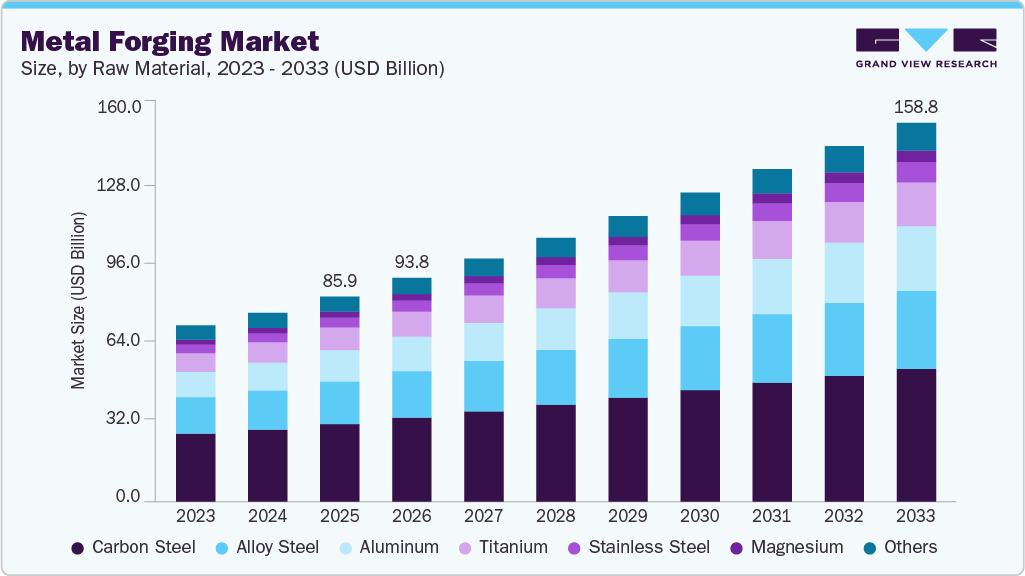
The carbon steel accounted for the largest market revenue share of 37.8% in 2025. Carbon steel is the most extensively utilized raw material in the market due to its optimal balance of mechanical strength, ductility, and cost efficiency. It is widely deployed across open-die and closed-die forging processes to manufacture high-load, fatigue-resistant components such as crankshafts, connecting rods, gears, shafts, and fasteners. The material’s broad carbon content range allows manufacturers to tailor properties from high ductility in low-carbon grades to superior hardness and wear resistance in high-carbon grades, making it suitable for diverse end-use industries, including automotive, construction, oil & gas, and industrial machinery.
Aluminum is a key material segment in the metal forging industry, primarily driven by its lightweight characteristics, high strength-to-weight ratio, and excellent corrosion resistance. It is extensively used in forging applications where weight reduction without compromising structural integrity is critical, particularly in automotive, aerospace, and transportation sectors. Forged aluminum components such as suspension parts, wheels, aircraft structural elements, and engine components offer superior mechanical performance along with improved fuel efficiency and emission reduction benefits.
Application Insights
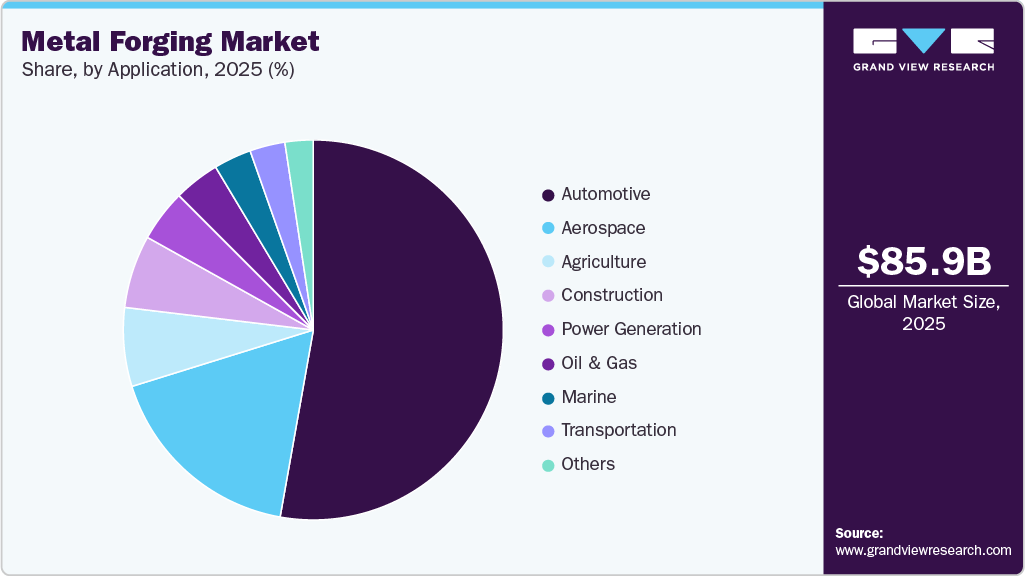
The rapid expansion of electric vehicle production is a major factor accelerating growth in the automotive segment. Global EV sales surpassed 20 million units in 2025, reflecting a strong shift toward electrified mobility. This transition introduces entirely new vehicle architectures that rely on highly specialized components, many of which are best produced through forging. Unlike internal combustion engine vehicles, EVs require parts such as motor rotors, inverter housings, and battery enclosures that must endure intense thermal fluctuations and mechanical stress.
 To learn more about this report, Download Free Sample Report
The power generation segment continues to be a major market driver due to the rapid scale-up of renewable energy capacity worldwide. According to the IEA Renewables 2024 Electricity report, global annual renewable capacity additions are projected to increase from 666 GW in 2024 to nearly 935 GW by 2030. Solar PV and wind alone are expected to account for about 95% of these additions, primarily due to their lower generation costs compared to both fossil fuel and other non-fossil alternatives, along with continued policy support. This large-scale expansion directly drives demand for forged components such as turbine shafts, flanges, and structural rings used in wind and solar infrastructure.
Regional Insights
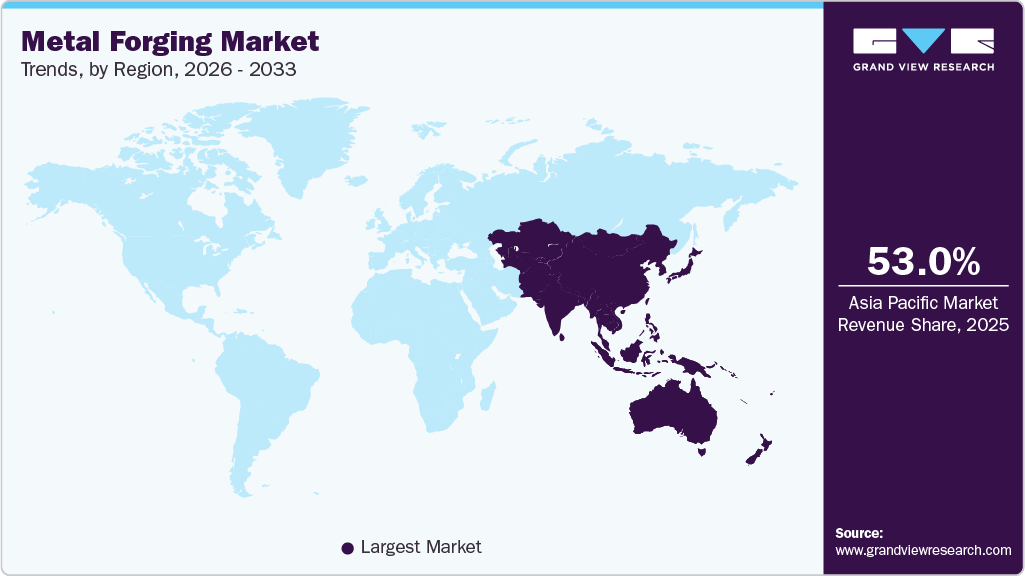
The Asia Pacific dominated the market with the largest revenue share of 53.6% in 2025. The region represents one of the most dynamic growth hubs for metal forging, driven by rapid expansion in renewable energy, particularly in wind and solar power. Countries such as China and India are aggressively increasing their installed renewable capacity, with China alone exceeding 400 GW of wind power capacity and continuing to lead global additions. This large-scale deployment is generating strong demand for forged components such as turbine shafts, bearing rings, flanges, and gear systems that are essential for high-capacity wind turbines. In parallel, rising investments in solar energy and grid infrastructure upgrades across the region are further supporting demand for forged products used in power transmission and distribution equipment.
 To learn more about this report, Download Free Sample Report
China Metal Forging Market Trends
The metal forging market in China is being driven by the expansion of automotive, electric vehicle, aerospace, heavy machinery, and energy industries, which require high-strength, lightweight, and durable forged components. In 2025, China’s automobile production reached a record level, while new energy vehicle production increased 29% year over year, supporting demand for forged drivetrain, suspension, chassis, and other structural components.
North America Metal Forging Market Trends
The metal forging market in North America is currently experiencing a robust period of growth, primarily fueled by the accelerating transition to EVs and the revitalization of the automotive supply chain. Forged components are indispensable for EVs because they provide the high-strength, lightweight properties necessary to offset heavy battery packs and improve driving range. As of 2026, manufacturers in the U.S., Canada, and Mexico are increasingly utilizing advanced aluminum and titanium alloys for critical parts such as suspension arms, steering knuckles, and motor housings. This shift is bolstered by the USMCA (United States-Mexico-Canada Agreement) trade provisions, which mandate high regional content and North American-sourced steel and aluminum, incentivizing domestic forging facilities to scale up production.
The U.S. metal forging market is being propelled by robust demand from the aerospace and defense sectors, which are seeing unprecedented levels of investment. The recently authorized nearly USD 900 billion FY2026 National Defense Authorization Act (NDAA) explicitly identifies castings and forgings as priority components for national security, creating a multi-year business opportunity rather than a series of short-term contracts. This funding ensures predictable volume for manufacturers producing everything from submarine structural forgings to aircraft landing gear and propulsion systems.
Europe Metal Forging Market Trends
The metal forging market in Europe is undergoing a structural transformation driven by the EU's Green Deal and the "Circular Economy" initiative. As of 2026, forgers are facing intense pressure to decarbonize, leading to a widespread shift from traditional blast furnaces to Electric Arc Furnaces (EAF) and the adoption of high-quality recycled scrap. This transition is being accelerated by the full implementation of the Carbon Border Adjustment Mechanism (CBAM) in January 2026, which effectively places a carbon price on imported steel and aluminum.
Latin America Metal Forging Market Trends
The metal forging market in Latin America is witnessing steady expansion, driven by rising oil and gas activity, strong mining output, and increasing renewable energy investments across major economies such as Brazil, Argentina, Chile, and Peru. Brazil remains the primary growth engine, with its offshore energy sector reaching a historic milestone in 2025 as total oil and natural gas production climbed to 4.89 million barrels of oil equivalent per day, marking a 13.3% increase compared to 2024. Pre salt reserves now contribute close to 80% of this output, highlighting the growing importance of deepwater exploration.
Key Metal Forging Company Insights
Some of the key players operating in the market include Arconic Inc., Bharat Forge Limited, and others.
-
Arconic Inc. operates as a specialized manufacturer of aluminum-based engineered products, catering to industries such as aerospace, automotive, and construction. The company’s business model is centered on producing high-performance, lightweight metal solutions for structural and architectural applications. It was previously known as Arconic Rolled Products Corporation and was renamed Arconic Corporation in 2020 following corporate restructuring.
-
Bharat Forge Limited represents a fully integrated forging specialist with a strong global footprint across automotive, industrial, aerospace, and defense sectors. As part of the Kalyani Group, the company has evolved into a high-volume and high-precision forging manufacturer with diversified end-market exposure. The company’s strength lies in its extensive forging portfolio, which includes crankshafts, connecting rods, chassis components, oil & gas forgings, and aerospace-grade parts such as landing gear components.
Key Metal Forging Companies
The following key companies have been profiled for this study on the metal forging market.
-
Arconic Inc.
-
Allegheny Technologies Incorporated
-
Bharat Forge Limited
-
Bruck GmbH
-
China First Heavy Industries Co., Ltd.
-
ELLWOOD Group, Inc.
-
Jiangyin Hengrun Heavy Industries Co., Ltd.
-
Nippon Steel Corporation
-
Precision Castparts Corp.
-
Larsen & Toubro Limited
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Arconic Inc., Allegheny Technologies Incorporated (ATI), Bharat Forge Limited)
- Mature players in the metal forging industry generally operate highly integrated manufacturing facilities covering billet preparation, heating, open- and closed-die forging, heat treatment, machining, surface finishing, and inspection.
- The key competitive advantage of mature forging companies is their extensive metallurgical expertise and ability to produce complex components at consistent quality and scale. Established forging capabilities allow them to handle large components and demanding alloys while maintaining tight dimensional tolerances and controlled grain flow.
- Mature forging companies typically operate capital-intensive facilities requiring substantial investment in presses, dies, furnaces, heat-treatment equipment, machining systems, and inspection infrastructure. High energy consumption during heating and forging makes operating costs sensitive to electricity and fuel prices, while fluctuations in steel, aluminum, nickel-based alloys, and other feedstock prices can pressure margins.
Emerging & Regional Players (e.g., Bruck GmbH, Jiangyin Hengrun Heavy Industries Co., Ltd.)
- Emerging players in the metal forging industry generally pursue specialized and flexible manufacturing strategies, focusing on high-value components, regional customers, and applications with increasing demand for lightweight or high-performance parts.
- Emerging forging companies benefit primarily from manufacturing flexibility and their ability to respond quickly to customer-specific requirements.
- Emerging players generally have smaller production capacities, limited financial resources, and weaker purchasing power compared with established forging manufacturers. This can increase their exposure to fluctuations in raw materials and energy costs and restrict their ability to absorb large investments in forging presses, dies, heat-treatment systems, machining equipment, and testing infrastructure.
Recent Development
-
In July 2025, Bharat Forge Limited completed the acquisition of AAM India Manufacturing, strengthening its automotive forging capacity and expanding its manufacturing footprint in India. This move enhances its position in drivetrain and component manufacturing.
-
In June 2025, ATI Inc. expanded its production focus on high-performance titanium and nickel-based alloys to meet growing aerospace forging demand, particularly for jet engines and structural applications.
Metal Forging Market Report Scope
Report Attribute
Details
Market definition
The market size represents the total annual consumption of forged metal components across end-use industries such as automotive, construction, aerospace, energy, etc.
Market size in 2025
USD 39.4 billion
Estimated market size in 2026
USD 43.0 billion
Projected market size by 2033
USD 72.8 billion
Growth rate
CAGR of 7.8% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Volume in kilotons, revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Volume & revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Raw material, application, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK, Germany; Italy; France; Spain; China; India; Japan; South Korea
Key companies profiled
Arconic Inc.; Allegheny Technologies Incorporated; Bharat Forge Limited; Bruck GmbH; China First Heavy Industries Co., Ltd.; ELLWOOD Group, Inc.; Jiangyin Hengrun Heavy Industries Co., Ltd.; Nippon Steel Corporation; Precision Castparts Corp.; Larsen & Toubro Limited
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Metal Forging Market Report Segmentation
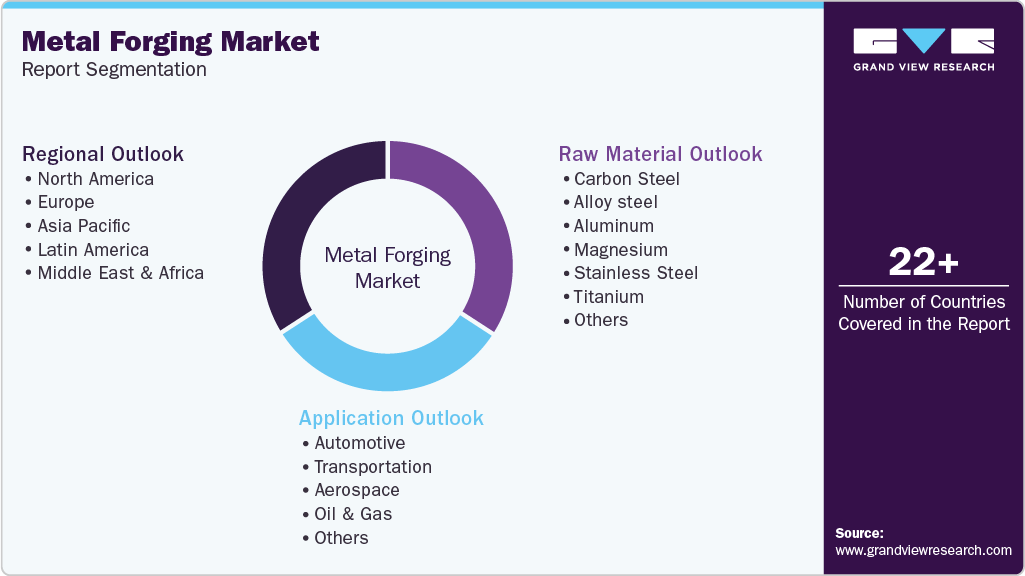
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global metal forging market report based on raw material, application, and region:
 To learn more about this report, Download Free Sample Report
-
Raw Material Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Carbon Steel
-
Alloy steel
-
Aluminum
-
Magnesium
-
Stainless Steel
-
Titanium
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Automotive
-
Transportation
-
Aerospace
-
Oil & Gas
-
Construction
-
Agriculture
-
Power Generation
-
Marine
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Italy
-
France
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Middle East & Africa
-
Research Methodology
The metal forging market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each metal forging segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Raw Material
Revenue Capture Definition
Carbon Steel
The carbon steel segment captures revenue generated from metal forgings manufactured using carbon steel as the primary raw material.
Alloy steel
The alloy steel segment represents revenue generated from forgings manufactured using alloy steel containing elements such as chromium, nickel, molybdenum, and manganese to enhance mechanical and performance characteristics.
Aluminum
The aluminum segment includes revenue generated from metal forgings manufactured using aluminum and aluminum alloys as the primary raw material.
Magnesium
The magnesium segment captures revenue generated from forgings manufactured using magnesium and magnesium alloys.
Stainless Steel
The stainless steel segment represents revenue generated from metal forgings manufactured using stainless steel grades as the primary raw material.
Titanium
The titanium segment includes revenue generated from forgings manufactured using titanium and titanium alloys.
Others
The others segment captures revenue generated from metal forgings manufactured using other raw materials and specialty alloys, including nickel alloys, copper alloys, cobalt alloys, and other non-ferrous materials.
Application
Revenue Capture Definition
Automotive
The automotive segment captures revenue generated from metal forgings used in engine, transmission, steering, suspension, drivetrain, and structural components.
Transportation
The transportation segment represents revenue generated from metal forgings used in railway, heavy-duty vehicles, commercial transportation equipment, and related components.
Aerospace
The aerospace segment includes revenue generated from metal forgings used in aircraft engines, landing gear, structural components, flight control systems, and other critical aerospace parts.
Oil & Gas
The oil and gas segment captures revenue generated from metal forgings used in valves, flanges, drilling equipment, wellhead components, pressure-containing parts, and pipeline systems.
Construction
The construction segment represents revenue generated from metal forgings used in construction machinery, cranes, excavators, loaders, structural equipment, and heavy-duty components.
Agriculture
The agriculture segment includes revenue generated from metal forgings used in tractors, harvesters, tillage equipment, plows, cultivators, and other agricultural machinery.
Power Generation
The power generation segment captures revenue generated from metal forgings used in turbines, generators, shafts, valves, flanges, pressure equipment, and other power plant components.
Marine
The marine segment represents revenue generated from metal forgings used in ship engines, propulsion systems, shafts, propellers, valves, marine equipment, and offshore structures.
Others
The others segment captures revenue generated from metal forgings used in industrial machinery, mining equipment, defense systems, medical equipment, rail components, and other specialized applications.
Estimation Model
Layer Name
Key Question
Description
Industrial Manufacturing Demand Base Layer
What forms the demand base?
Identify global demand from major metal forging consuming industries, including automotive, aerospace & defense, oil & gas, construction, power generation, machinery & equipment, and marine. Assess vehicle production, aircraft manufacturing, energy infrastructure, industrial equipment output, and heavy machinery production to establish the total addressable demand for forged metal components.
Metal Forging Application Penetration Layer
Where are forged components utilized?
Estimate the penetration of forging across key applications, including engine and drivetrain components, structural and chassis components, aircraft landing gear and structural parts, valves and fittings, gears, shafts, flanges, bearings, and heavy machinery components. Analyze the adoption of open-die, closed-die, and seamless rolled-ring forging across end-use industries and regions.
Forging Consumption Intensity Layer
How much metal is processed through forging?
Analyze forging intensity based on vehicle production, aircraft build rates, industrial machinery output, energy infrastructure, and heavy equipment production. Evaluate forged metal consumption per component or end product according to component weight, material grade, dimensional requirements, forging ratio, and production volumes. Consumption intensity varies according to component complexity, material type, manufacturing technology, and required mechanical performance.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of forged components manufactured from carbon steel, alloy steel, stainless steel, aluminum, titanium, and other metals using open-die, closed-die, and seamless ring forging processes. Revenue generation is driven by automotive, aerospace & defense, oil & gas, construction, power generation, machinery, and marine industries. Market value is influenced by metal prices, component complexity, forging capacity, energy and labor costs, production volumes, and regional industrial activity.
Delivered Customizations
We have successfully delivered the following deep-dive customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed regional analysis of the metal forging industry across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Included evaluation of automotive production, aerospace and defense manufacturing, industrial machinery, construction equipment, energy infrastructure, shipbuilding, and investments in advanced forging facilities.
Identified major manufacturing hubs, high-growth consumption markets, and emerging forging centers. Enabled strategic expansion planning based on automotive production, aerospace manufacturing, industrial development, and regional manufacturing capacity. Supported regional demand forecasting and supply chain optimization.
Opportunity Assessment
Identification of high growth opportunities across electric vehicles, automotive lightweighting, commercial aerospace, defense equipment, renewable energy systems, wind turbines, power generation, industrial automation, oil and gas equipment, construction machinery, and advanced precision forging.
Enabled prioritization of high-return growth segments and emerging regional opportunities. Supported long-term capacity expansion, advanced forging technology adoption, product innovation, strategic partnerships, and business development initiatives aligned with lightweighting, electrification, advanced manufacturing, and industrial modernization.
Cross Segmentation
Comprehensive cross-segmentation analysis by material, forging process, application, end use, and region, including carbon steel, alloy steel, stainless steel, aluminum, titanium, and other metals across open die forging, closed die forging, and seamless rolled ring forging.
Enabled identification of the most attractive material, process, and application combinations. Supported product portfolio optimization, customer targeting, production planning, technology selection, and investment prioritization strategies.
Frequently Asked Questions About This Report
Asia Pacific dominated the market with revenue share of 53.6% in 2025.
Power generation is anticipated to register the fastest CAGR over the forecast period.
China dominated the Asia Pacific market with revenue share of 52.5% in 2025.
Automotive accounted for largest revenue share of 52.8% in 2025.
The global metal forging market size was valued at USD 39.4 billion in 2025 and is estimated at USD 43.0 billion for 2026.
The global metal forging market is expected to grow at a CAGR of 7.8% from 2026 to 2033, reaching USD 72.8 billion by 2033.
The carbon steel segment dominated the market with a revenue share of over 37.0% in 2025.
Some of the key players operating in the metal forging market include Arconic Inc.; Allegheny Technologies Incorporated; Bharat Forge Limited; Bruck GmbH; China First Heavy Industries Co., Ltd.; ELLWOOD Group, Inc.; Jiangyin Hengrun Heavy Industries Co., Ltd.; Nippon Steel Corporation; Precision Castparts Corp.; and Larsen & Toubro Limited.
Key factors driving the metal forging market include growing demand for high-strength and lightweight components across automotive, aerospace, construction, and power generation industries.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


