
- Home
- »
- Medical Devices
- »
-
North America Pre-clinical Scientific Research Medical Device Market Report 2033GVR Report cover

North America Pre-clinical Scientific Research Medical Device Market (2026 - 2033) Size, Share & Trends Analysis Report By Product, By Animal Model (Rodents, Rabbits, Non-human Primates), By Application, By Customer, By Country, And Segment Forecasts
North America Pre-clinical Scientific Research Medical Device Market Summary
The North America pre-clinical scientific research medical device market size was estimated at USD 14.9 billion in 2025 and is projected to reach USD 23.4 billion by 2033, growing at a CAGR of 5.9% from 2026 to 2033. The market growth is mainly due to rising pre-clinical R&D spending by medical device companies, stringent regulatory and safety requirements, technological advancements, and shift toward translational research models.
Key Market Trends & Insights
- U.S. pre-clinical scientific research medical device industry held the largest share of 88.3% in the region in 2025.
- Canada pre-clinical scientific research medical device industry is expected to grow significantly over the forecast period.
- By product, the pre-clinical IVD systems & reagents segment held the largest market share of 23.6% in 2025.
- Based on the animal model, the rodents segment held the largest market share in 2025.
- Based on application, the oncology segment held the largest market share in 2025.
Market Size & Forecast
- 2025 Market Size: USD 14.9 Billion
- 2033 Projected Market Size: USD 23.4 Billion
- CAGR (2026-2033): 5.9%
- U.S.: Largest market in 2025
- Canada: Fastest growing market
Prism AI by Grand View Research Free to tryAsk a question about the north america pre-clinical scientific research medical device marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
North America's pre-clinical scientific research medical device industry is expanding rapidly, driven by rising R&D investments from medical device manufacturers, particularly in the U.S., which leads the global spending. Besides this, strong venture capital, private funding, and NIH grants support innovation. For instance, in January 2026, WashU Medicine reported USD 1.7 billion in startup funding, supporting the commercialization of diagnostics, therapeutics, and medical devices and potentially strengthening demand for pre-clinical research infrastructure. These investments enable the rapid development of diagnostics, therapeutics, and medical technologies that require advanced imaging, monitoring, and in vitro diagnostic tools. In addition, the NIH’s USD 47 billion 2024 budget supports translational research, reduces financial risk, and boosts adoption of specialized pre-clinical instrumentation, driving market expansion.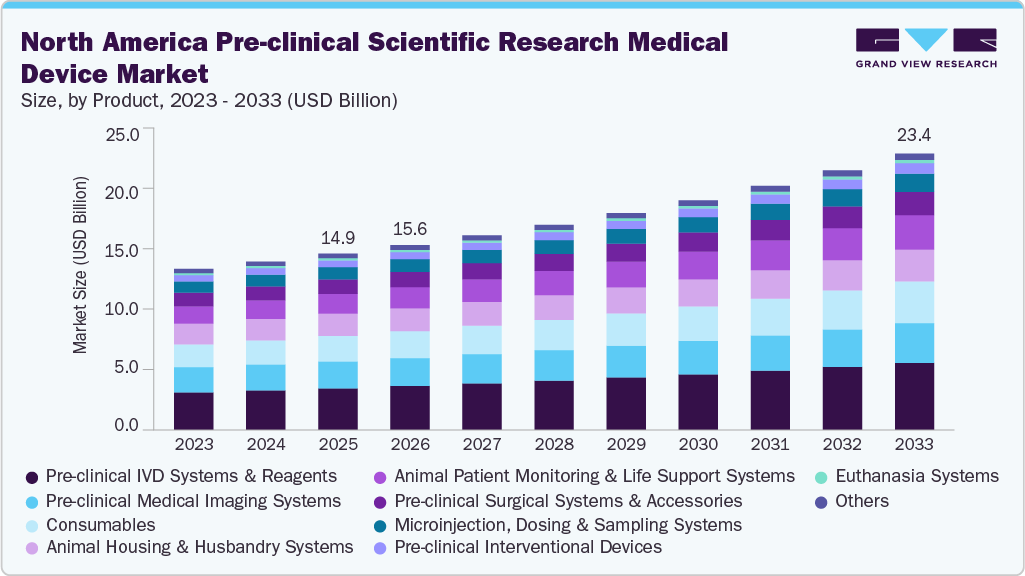 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
In addition, regulatory authorities, particularly the U.S. FDA, require comprehensive preclinical evidence to demonstrate safety, functionality, and biocompatibility before clinical trials or market approval, especially for high-risk and AI-enabled devices. These stringent standards compel companies to invest in advanced imaging systems, monitoring platforms, dosing equipment, and validated IVD tools to generate reliable, regulator-acceptable data. For instance, in April 2025, FDA introduced a roadmap promoting New Approach Methodologies alongside animal studies, further elevating expectations for data quality and reproducibility. Similarly, manufacturers are adopting sophisticated preclinical technologies, positioning regulatory compliance as a key driver of market growth and innovation.
Furthermore, technological advancements in imaging, analytics, automation, and data integration are transforming pre-clinical research workflows and driving demand for advanced scientific research devices. In addition, high-resolution small-animal imaging, automated monitoring, precision dosing systems, and integrated IVD tools enhance accuracy, reproducibility, and longitudinal data generation. As devices grow more complex, multifunctional and AI-enabled platforms support deeper biological insights and faster regulatory decision-making. Besides this, leading companies are accelerating innovation. For instance, in 2025, Revvity launched Living Image Synergy AI software to streamline multimodal imaging analysis, while Thermo Fisher introduced award-winning analytical technologies that improve precision, throughput, and automation. These innovations are expanding investment and adoption across research institutions and industry.
Opportunity Analysis
The expansion of translational research and precision medicine initiatives is creating strong growth opportunities for the pre-clinical scientific research medical device industry. Besides this, government and private funding programs aim to bridge laboratory discoveries and clinical applications, driving demand for advanced preclinical tools that generate human-relevant, regulatory-ready data. In addition, large-scale precision medicine initiatives support disease-specific models, biomarker validation, and targeted therapy development, requiring high-resolution imaging, automated monitoring systems, molecular diagnostics, and precision dosing platforms.
Furthermore, medical device companies are aligning R&D strategies toward precision-based and AI-enabled technologies, increasing the need for robust pre-clinical validation. Similarly, the integration of 3D cell cultures, organ-on-chip platforms, and hybrid in vitro-in vivo workflows is expanding instrumentation intensity. In addition, regulatory support for New Approach Methodologies further encourages parallel testing strategies. As institutions and biopharma firms invest in predictive, data-intensive research infrastructure, demand for integrated imaging, analytical, and monitoring systems continues to accelerate.
Technological Advancements
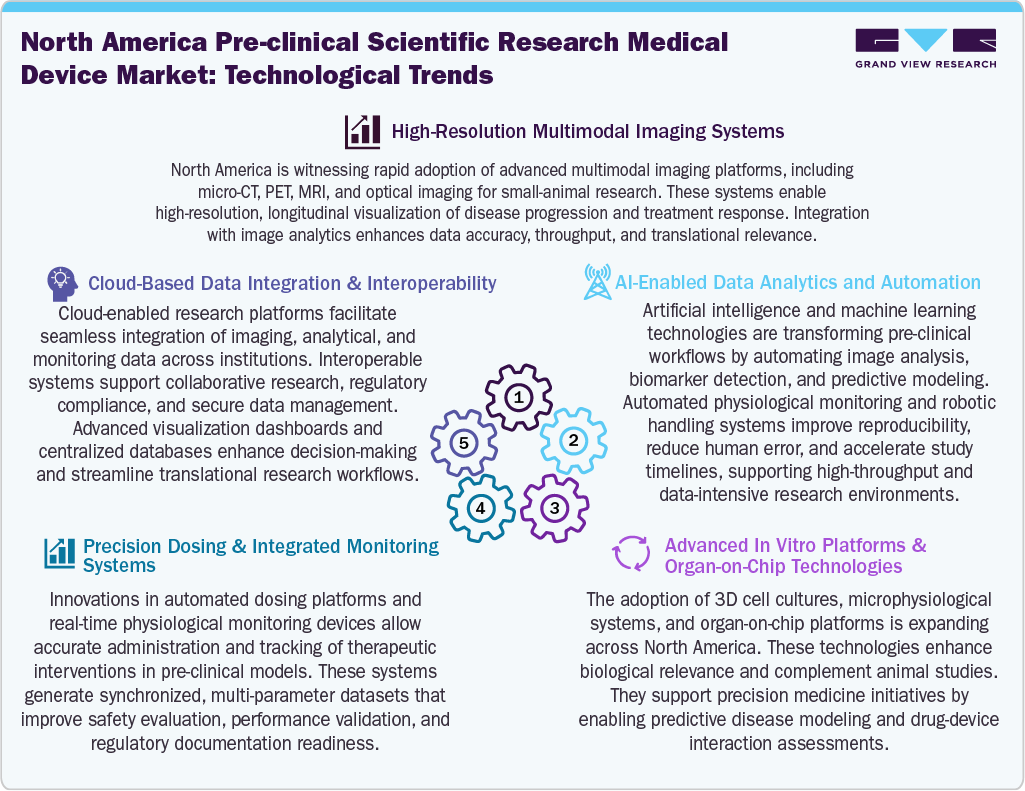
Technological advancements are significantly shaping the North America pre-clinical scientific research medical device industry. Similarly, high-resolution multimodal imaging systems, including micro-CT, PET, MRI, and optical imaging, enable detailed longitudinal studies of disease progression and therapeutic response. Besides this, artificial intelligence and automation enhance image analysis, biomarker detection, and workflow efficiency, improving reproducibility and accelerating timelines. In addition, advanced in vitro platforms such as 3D cell cultures and organ-on-chip technologies complement animal studies by offering more predictive and biologically relevant models.
 To learn more about this report, Download Free Sample Report
Furthermore, precision dosing systems and integrated physiological monitoring devices generate synchronized multi-parameter datasets that strengthen safety and performance validation. In addition, cloud-based data integration platforms improve interoperability, secure data sharing, and collaborative research across institutions. Thus, these innovations enhance translational relevance, support regulatory submissions, and drive capital investment in sophisticated pre-clinical research infrastructure across the region.
Pricing Model Analysis
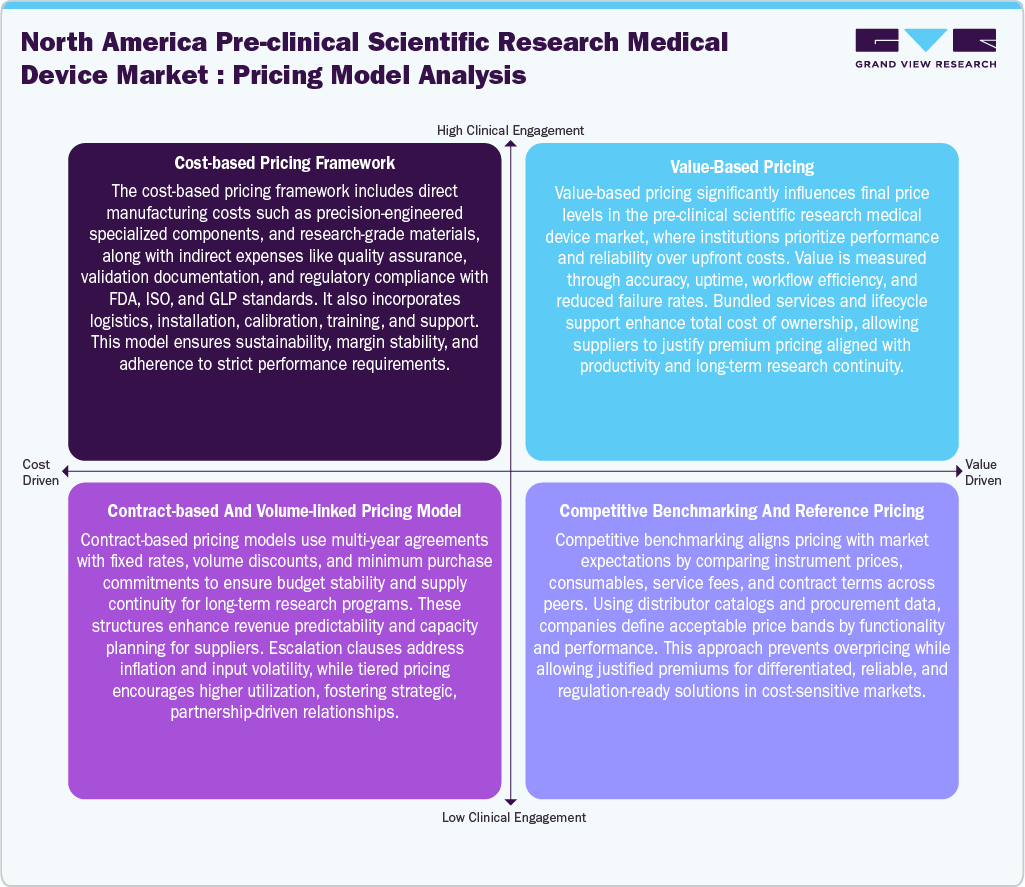
The pricing framework in the North America pre-clinical scientific research medical device industry integrates cost-based, value-based, competitive benchmarking, and contract-driven models. The cost-based pricing accounts for direct manufacturing expenses, regulatory compliance (FDA, ISO, GLP), quality validation, and post-sales services, ensuring operational sustainability and margin stability. Besides this, value-based pricing builds on this baseline by incorporating performance metrics such as accuracy, workflow efficiency, system uptime, and reduced experimental risk, enabling suppliers to justify premium pricing based on measurable productivity gains and total cost of ownership.
 To learn more about this report, Download Free Sample Report
In addition, competitive benchmarking aligns pricing with market expectations through structured comparisons of instruments, consumables, service contracts, and technical capabilities, ensuring defensible, differentiation-driven price positioning. Furthermore, contract-based and volume-linked models further enhance commercial viability through multi-year agreements, fixed pricing structures, volume discounts, and escalation clauses.
Market Concentration & Characteristics
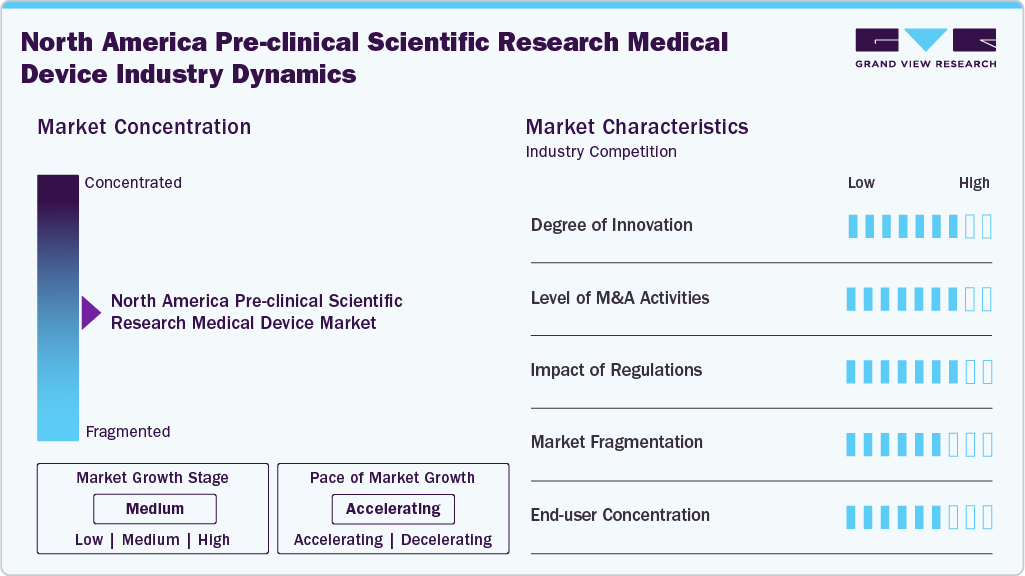
North America pre-clinical scientific research medical device industry growth stage is moderate, and at an accelerating pace. The market is characterized by the degree of innovation, level of M&A activities, regulatory impact, service expansion, and regional expansion.
North America exhibits considerable innovation in the preclinical medical device research sector, fueled by substantial R&D funding, advanced academic resources, and partnerships between original equipment manufacturers (OEMs) and biopharmaceutical firms. For instance, in December 2025, Mediso installed the first nanoScan 7T PET/MRI system in the U.S., significantly advancing North America’s preclinical neuroimaging capabilities with simultaneous ultra-high-field molecular, functional, and structural imaging.
 To learn more about this report, Download Free Sample Report
Regulatory oversight plays a crucial role in transforming market dynamics, with compliance standards aligned to FDA, GLP, and ISO requirements affecting product design, validation, and documentation practices. Besides this, stringent quality and performance criteria increase development costs but improve reliability and acceptance globally. The rigor of regulations also increases the need for validated, trackable, and audit-ready systems, creating higher barriers to entry and supporting premium pricing strategies.
Mergers and acquisitions remain active as key players aim to expand their portfolios, integrate technology, and consolidate geographically. Some of the players are purchasing specialized technology providers in fields such as imaging, bioanalytics, and automation to bolster their comprehensive pre-clinical capabilities. For instance, in February 2024, Bruker acquired Spectral Instruments Imaging, expanding its optical imaging portfolio and enhancing the availability and competitiveness of multimodal preclinical imaging for North American disease research laboratories.
The market displays moderate fragmentation, with large multinational original equipment manufacturers (OEMs) operating alongside specialized regional and niche technology companies. The well-established firms lead in high-value instrumentation sectors, and smaller enterprises drive innovation in particular applications such as small-animal imaging or physiological monitoring. Competitive differentiation largely relies on performance, compliance readiness, integration capability, and robust long-term service support.
The concentration of end users is quite high, primarily driven by prominent pharmaceutical companies, biotechnology organizations, contract research organizations (CROs), and major academic research institutions. Significant procurement volumes come from large research centers and federally supported institutions. In addition, purchasing decisions are typically centralized and focused on value and compliance, granting major buyers considerable power in negotiations over pricing and long-term supply contracts.
Product Insights
Based on product, the pre-clinical IVD systems & reagents segment held the largest market share of 23.58% in 2025, due to their crucial role in animal research, aiding in disease characterization, biomarker identification, safety evaluations, and the validation of findings before progressing to human trials. The hematology analyzers, clinical chemistry systems, immunoassays, and molecular diagnostic tools facilitate ongoing assessments of organ function, immune activity, and metabolic changes in laboratory animals. Some of the companies, such as Revvity, offer comprehensive solutions that include cell analysis devices, innovative imaging technologies, and bioanalytical tests that improve efficiency and data accuracy. The market is also fueled by significant investments in biotechnology and pharmaceutical research and development, especially in the U.S., where advancements in gene therapy and immuno-oncology are particularly pronounced.
The animal monitoring is the fastest growing segment over the forecast period, 2026-2033, in North America, and it is fueled by the demand for accurate and continuous observation of vital signs such as heart rate, respiratory rate, blood pressure, oxygen levels, and temperature in research animals. Some of the sophisticated systems that utilize telemetry, wireless technologies, and minimally invasive sensors facilitate automated data collection, enhancing workflow efficiency, animal welfare, and the reproducibility of studies. Additionally, companies such as Harvard Apparatus and Kent Scientific provide modular monitoring systems, while BIOPAC Systems caters to specialized research in cardiovascular health. In addition, life support solutions from VetEquip and RWD Life Science combine anesthesia management, ventilation, temperature regulation, and fluid management.
Animal Model Insights
Based on the animal model, the rodents segment held the largest share in 2025. Rodent models, such as mice and rats, play a vital role in preclinical biomedical research, allowing for the assessment of disease mechanisms, the functionality of devices, and the long-term effectiveness of implantable devices like stents and catheters. Their genetic resemblance to humans, consistent disease profiles, cost-effectiveness, and short lifespans make them suitable for early-stage evaluations of safety, biocompatibility, and device performance. These models facilitate iterative design processes, material optimization, and examination of device-tissue interactions prior to clinical trials. Besides this, in North America, enhanced surgical methods, imaging technologies, and bioengineering tools improve translational precision, research infrastructure, and alignment with regulatory standards. For instance, in July 2025, Scintica collaborated with Sentinel Nord AS to introduce sterile, preclinical catheters that are compatible with MRI, PET, SPECT, CT, and ultrasound, thereby enhancing small-animal imaging and driving innovation in preclinical device development.
The non-human primates (NHPs) represent the fastest-growing segment, consisting of monkeys, apes, and prosimians that play a crucial role in the research of medical devices due to their close anatomical, physiological, and genetic resemblance to humans. They are especially significant for investigating intricate systems such as the nervous and immune systems, where smaller animal models fail to provide accurate predictions. The regulatory agencies frequently mandate strong pre-clinical evidence for implants, neurological devices, and combination products, highlighting the necessity for NHP models that are relevant to translation. Additionally, species such as the African Green Monkey (Chlorocebus sabaeus) are commonly used in research on infectious diseases and neurology. The increasing dependence on NHPs is anticipated to drive ongoing growth in the market.
Application Insights
In terms of application, the oncology segment captured a considerable share in 2025. The leading cause of death globally is cancer, with over 10 million fatalities and nearly 25 million new cases annually. In North America, particularly the U.S., rising incidence rates and stringent regulatory expectations are increasing demand for robust preclinical scientific research. Preclinical studies evaluate the safety, performance, targeting efficiency, and toxicity of oncology devices before clinical trials, supporting innovations in biopsy tools, implants, and drug-delivery systems. Besides this, advances in 3D tumor models, organoids, and precision animal models enhance validation accuracy. Furthermore, growing investment in cancer research and regulatory scrutiny drives the adoption of sophisticated testing platforms, improving clinical trial success, reducing risks, and accelerating the development of safer devices.
The neurology segment is expected to be the second fastest-growing segment, due to the rising burden of neurological disorders, an aging population, lifestyle changes, and improved diagnostics across North America. Some of the neurological conditions, such as stroke, Alzheimer’s disease, Parkinson’s disease, epilepsy, and multiple sclerosis, are driving investments in early detection and specialized care. In addition, growing emphasis on neuroimaging, biomarkers, and digital health tools is strengthening research and preventive strategies. Some of the neurological devices, including neurodiagnostic, neurointerventional, and neurostimulation systems, are supporting preclinical research. For instance, in November 2025, InnoSer and Carthera’s partnership around the SonoCloud ultrasound platform advances CNS-targeted therapeutic research, further accelerating innovation in neurological medical device development.
Customer Insights
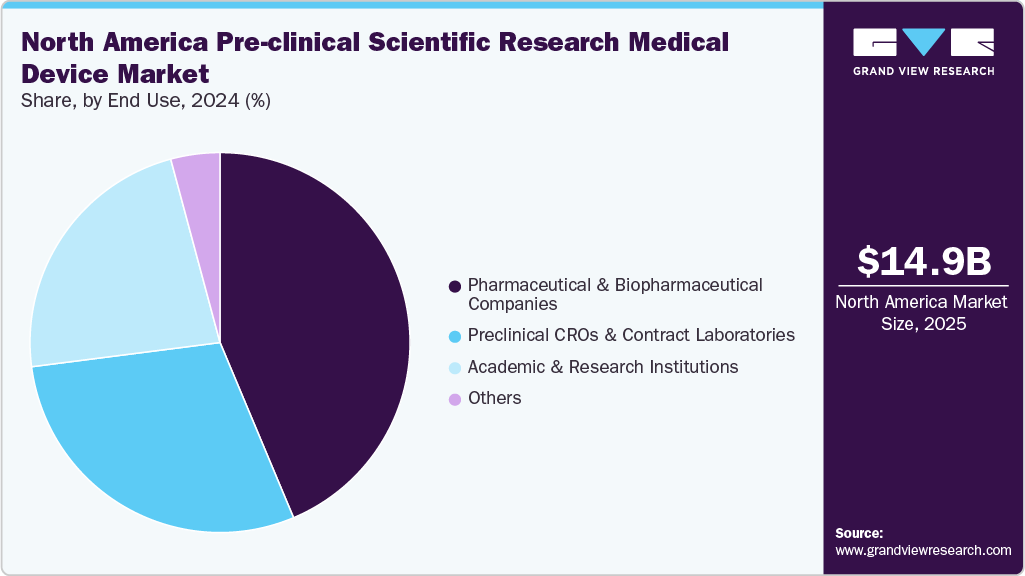
By customer, the pharmaceutical & biopharmaceutical companies segment captured a considerable share in 2025. The medical devices are integral to pharmaceutical and biopharmaceutical operations, supporting diagnosis, monitoring, treatment, and prevention across a broad spectrum of healthcare applications. In addition, ensuring device safety and efficacy is critical, supported by strong regulatory frameworks that emphasize compliance and risk mitigation. The region’s robust ecosystem, comprising advanced laboratories, experienced CROs, and academic-industry collaboration, facilitates extensive preclinical research for device validation, particularly for drug-device combination products and delivery systems. In addition, stringent FDA standards strengthen study design and data quality. Rising investment in biologics, personalized medicine, and advanced delivery technologies further drives demand for preclinical research.
 To learn more about this report, Download Free Sample Report
The preclinical CROs and contract laboratories segment is the fastest-growing segment over the forecast period, as it plays a critical role in advancing medical device research by providing comprehensive in vivo and in vitro testing, biocompatibility studies, toxicology assessments, and performance validation services. These organizations are equipped with advanced infrastructure, scientific expertise, and strict regulatory compliance, which support the evaluation of device safety, functionality, and biological performance prior to clinical use. Besides this, the increasing complexity of implantable and combination products is driving demand for specialized preclinical capabilities. Furthermore, medical device manufacturers are outsourcing research activities in large numbers to reduce development timelines and operational costs.
Country Insights
U.S. Pre-clinical Scientific Research Medical Device Market Trends
The U.S. pre-clinical scientific research medical device industry dominated the North American region, supported by advanced infrastructure, strong funding, and a robust FDA regulatory framework. Preclinical studies emphasize safety, biocompatibility, performance, and functional efficacy before clinical evaluation. Besides this, activities include bench testing, materials characterization, mechanical and electrical assessments, and in vivo studies.
In addition, a well-established ecosystem of device manufacturers, pharmaceutical companies, academic institutions, and government organizations strengthens market growth. Innovations in digital and combination devices further expand research demand. For instance, in 2025, Revvity launched Living Image Synergy AI software, enhancing multimodal in vivo imaging analysis, workflow efficiency, reproducibility, and early-stage device validation.
Key Pre-clinical Scientific Research Medical Device Company Insights
The key players operating across the market are adopting strategic initiatives such as service launches, mergers & acquisitions, partnerships & agreements, and expansions to gain a competitive edge in the market. For instance, in September 2025, ZEISS partnered with Concept Life Sciences to advance automated spatial imaging workflows, thereby enhancing market growth by improving scalability, reproducibility, and throughput for translational research applications.
Key Pre-clinical Scientific Research Medical Device Companies:
- Bruker Corporation
- Revvity, Inc. (PerkinElmer)
- Rigaku (MILabs B.V.)
- Thermo Fisher Scientific Inc.
- Agilent Technologies, Inc.
- Molecular Devices (Danaher)
- Carl Zeiss Microscopy
- Nikon Instruments
- Olympus / Evident Scientific
- CytoViva, Inc.
- FUJIFILM VisualSonics
- MBF Bioscience
- Mediso Ltd.
- MR Solutions
- Siemens Healthineers
Recent Developments
-
In December 2025, Thermo Fisher partnered with AIM Biotech on microphysiological systems, advancing North America’s preclinical device market by accelerating the adoption of human-relevant microphysiological systems and expanding complementary in vitro approaches in preclinical research.
-
In November 2025, Agilent partnered with NHCS to advance cardiac organoid metabolic analysis, reinforcing the market by driving demand for real-time metabolic platforms supporting 3D organoid and translational research workflows.
-
In March 2025, Nikon opened a Center of Excellence at the University of Arizona Cancer Center, which boosted the market growth by expanding access to advanced microscopy, intravital imaging tools, and researcher training programs.
North America Pre-clinical Scientific Research Medical Device Market Report Scope
Report Attribute
Details
Market size value in 2026
USD 15.6 billion
Revenue forecast in 2033
USD 23.4 billion
Growth rate
CAGR of 5.9% from 2026 to 2033
Historical Year
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, animal model, application, customer, country
Regional scope
North America
Country scope
U.S., Canada.
Key companies profiled
Revvity, Inc. (PerkinElmer); Rigaku (MILabs B.V.); Thermo Fisher Scientific Inc.; Agilent Technologies, Inc.; Molecular Devices (Danaher); Carl Zeiss Microscopy; Nikon Instruments; Olympus / Evident Scientific; CytoViva, Inc.; FUJIFILM VisualSonics; MBF Bioscience; Mediso Ltd.; MR Solutions; Siemens Healthineers; Bruker Corporation
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to the country & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
North America Pre-clinical Scientific Research Medical Device Market Report Segmentation
This report forecasts revenue growth at the regional and country levels and provides an analysis of the latest industry trends across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the North America preclinical scientific research medical device market report by product, animal model, application, customer, and country.
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Pre-clinical IVD Systems & Reagents
-
Hematology Analyzers
-
Clinical Chemistry Analyzers
-
Immunoassay Platforms
-
Molecular Diagnostics
-
Others
-
-
Pre-clinical Medical Imaging Systems
-
Optical Imaging
-
Magnetic Resonance Imaging (MRI)
-
Positron Emission Tomography (PET)
-
Single Photon Emission Computed Tomography (SPECT)
-
Computed Tomography (CT)
-
Ultrasound Imaging (US)
-
Photoacoustic Imaging (PAI)
-
Hybrid Imaging Systems
-
Imaging Microscopes
-
Endoscopes
-
Others
-
-
Animal Patient Monitoring & Life Support Systems
-
Multiparameter Monitoring Systems
-
Physiology Monitoring Devices
-
Anesthesia Machines & Vaporizers
-
Ventilators & Respiratory Support
-
Infusion, Syringe & Precision Pumps
-
Temperature Management Systems
-
Data Collection & Acquisition Systems
-
Others
-
-
Animal Housing & Husbandry Systems
-
Housing Cages
-
Watering & Feeding Systems
-
Rack & Cage Ventilation Systems
-
Others
-
-
Pre-clinical Surgical Systems & Accessories
-
Stereotaxic Surgery Systems
-
Surgical Instruments & Toolkits
-
Surgical Lasers
-
Surgical Microscopes & Magnification Tools
-
Surgical Tables & Stabilization Systems
-
Optical & Illumination Systems
-
Warming Plates & Heating Pads
-
Others
-
-
Microinjection, Dosing & Sampling Systems
-
Microinjection Pumps & Osmotic Pumps
-
Sampling Devices
-
Valves, Tubing & Precision Delivery Accessories
-
Vascular Access Devices
-
Injection Systems (Manual, Automated)
-
Others
-
-
Pre-clinical Interventional Devices
-
Catheters & Microcatheters
-
Guidewires
-
Minimally Invasive Surgical Tools
-
Balloon & Vascular Tools
-
Others
-
-
Euthanasia Systems
-
Consumables
-
Others
-
-
Animal Model Outlook (Revenue, USD Million, 2021 - 2033)
-
Rodents
-
Rabbits
-
Non-human Primates
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Oncology
-
Neurology
-
Cardiovascular Diseases
-
Infectious Diseases
-
Metabolic Disorders
-
Others
-
-
Customer Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceutical & Biopharmaceutical Companies
-
Preclinical CROs & Contract Laboratories
-
Academic & Research Institutions
-
Others
-
-
Country Outlook (Revenue, USD Million, 2021 - 2033)
-
U.S.
-
Canada
-
Frequently Asked Questions About This Report
The North America pre-clinical scientific research medical device market size was valued at USD 14.9 billion in 2025 and is projected to reach USD 23.4 billion by 2033.
The North America pre-clinical scientific research medical device market is growing at a CAGR of 5.9% from 2026 to 2033.
Some of the key players include Revvity, Inc. (PerkinElmer), Rigaku (MILabs B.V.), Thermo Fisher Scientific Inc., Agilent Technologies, Inc., Molecular Devices (Danaher), Carl Zeiss Microscopy, Nikon Instruments, Olympus / Evident Scientific, CytoViva, Inc., FUJIFILM VisualSonics, MBF Bioscience, Mediso Ltd., MR Solutions, Siemens Healthineers, Bruker Corporation.
The growth of the market is mainly due to rising pre-clinical R&D spending by medical device companies, stringent regulatory and safety requirements and technological advancements and shift toward translational research models.
By product, the pre-clinical IVD systems & reagents segment held the largest market share at 23.6% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


